Small Cap Value Report (Fri 27 Jan 2023) - WJG, STRX, PFG, RNK, OTB, HSP, SDRY, TET, MOTR,SRAD, AVON

Good morning! I'm joined by Roland today, who's come in to help with some backlog items from yesterday, thanks Roland!
Today's report is now finished. Have a lovely weekend!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda/Summaries
We managed to cover everything today!
Paul’s Section:
Watkin Jones (LON:WJG) (I hold)
110p (last night)
Market cap £281m
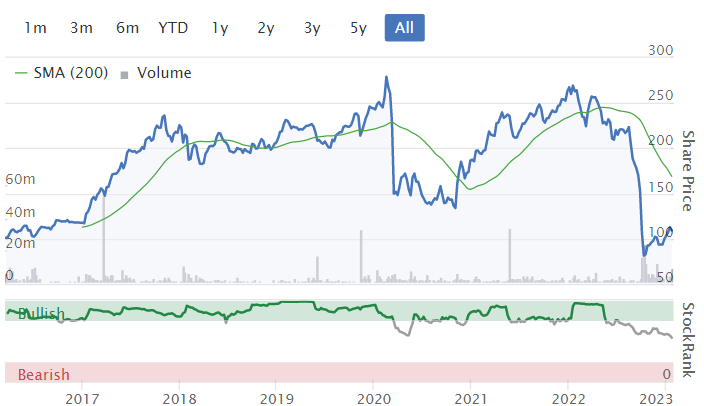
Graham reviewed the nasty profit warning here in Oct 2022, which clobbered the share price to an all-time low of 82p. It’s since bounced to c.110p, but remains well below the pandemic 2020 low point of 134p (in Nov 2020). Note that WJG has not diluted shareholders, with a share count almost static at c.256m shares, since it floated in 2016 - a common trait of family-owned/controlled companies, which tend to jealously guard themselves against dilution, and tend to also operate with a long-term focus, and sound balance sheets - which are good reasons as to why many value investors congregate in family/founder-run companies. They often out-perform, although that’s subjective, I don’t have any data to prove it (maybe we should do a study of this, if anyone has a few hundred hours of spare time?!)
Share price since it listed on AIM, plus there have been decent divis on top -
Anyway, I scraped up some cash, and bought a few near the recent low, and have since topped up to, so I’m declaring my interest because that’s bound to not be unconscious bias, but conscious bias - I think the company is good, and the shares good value, so that's why I put some of my own money in them recently.
On to the most recent news -
Results FY 9/2022 (announced 25 Jan 2023)
The profit warning in early Oct 2022 was due to the impact of higher interest rates making institutional clients more cautious, and political/economic turmoil causing the sale of 2 projects to be delayed. It also reported “some pricing and margin softness”. Guidance was revised from adj PBT of £55m, to £49m - hardly a disaster, and the share price plunge looks overdone.
WJG sold 8 developments last year, so this business model of big, lumpy projects, is always going to come with some risk of project delays around period ends, investors just have to accept that, and management need to maybe be more prudent in their assumptions at a time of increased uncertainty & higher interest rates (which have changed the economics of property investment projects for the institutional buyers).
WJG mainly builds student accommodation, but also build to rent (BTR) projects for wider occupation. These are pre-sold to institutional buyers, thus nicely lowering risk compared with many other construction companies.
Actual results now show £48.8m adj PBT, so that’s in line with expectations, near enough. Although note the statutory PBT figure is much lower, at £18.4m, due to a £30.4m exceptional charge for remedial work under the new Building Safety Act, which seems to particularly apply to tall, residential buildings (which is what WJG builds), in response to the Grenfell tragedy.
The worry for shareholders might be that further increased provisions might be needed - it seems to be the case that initial estimates for complex liabilities generally, are usually too low. That’s a bear point for this share. Notes 4 & 12 give more detail, and worry me considerably. An initial estimate of a liability arising from 30 years’ building projects, where the situation is complex and fluid - sounds like a can of worms to me. But the costs will be spread over probably many years, so I doubt this would prove an existential crisis, but might limit the future ability to pay generous divis, if the situation does deteriorate. Something to keep an eye on, for all builders that are impacted by the new law.
Using the adjusted numbers, EPS is 14.8p, and the divis are 7.4p for FY 9/2022 (policy is 2x earning cover), so that’s a PER of 7.4, and yield of 6.7% - very attractive valuation metrics, but it stands to reason that we’re likely to see lower earnings/divis in the new year, and possibly in 2024 too? I’m generally assuming that peak earnings have passed for cyclical companies, and investments have to stack up on reduced earnings. Although it’s always worth remembering that we’re not just buying 2023 earnings, we’re buying all earnings forever. So a low PER, on low earnings, could be a long-term bargain, as the future earnings, and the multiple they're valued on both improve. That's what always happens in bull markets.
Balance sheet - looks really healthy to me.
NAV is £177m - down nearly £8m on LY, mainly due to the big increase of £21m in “Provisions” within non-current liabilities - this will be the bulk of the remedial work required by law, referred to above. There’s also a smaller element of this in current liabilities.
The only adjustment I would make to the balance sheet, is to remove £12.2m of intangible assets, which gives us NTAV of £165m. This includes net cash of £82.5m (cash: £110.8m, less £(28.3)m interest-bearing loans).
The market cap is £281m, so this means NTAV constitutes 59% of the market cap, which is decent tangible asset backing. Not as good as the housebuilders, but that’s fine because WJG has a different business model, which places less reliance on a big land bank, and its projects are forward-sold to institutions, rather than being sold piecemeal to the public.
Overall then, this is a very safe balance sheet, in my view.
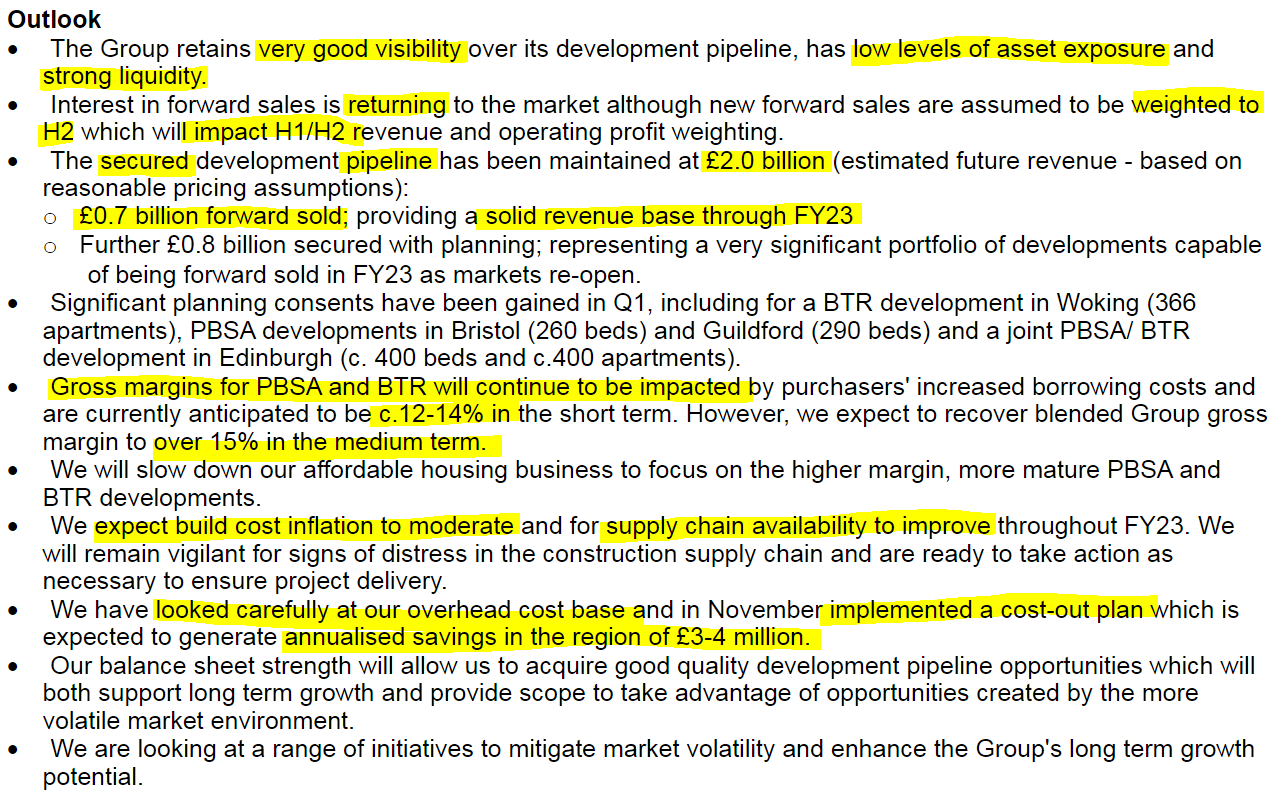
Outlook - there’s so much useful detail, I’ve taken a photo and made it more colourful -
Broker forecasts - nothing available on Research Tree unfortunately. Management needs to address this, as private investors need some help with research notes, and we’re the people who create the market liquidity, and hence set the share price.
EDIT: a new note from Progressive has just come through. Jolly good.
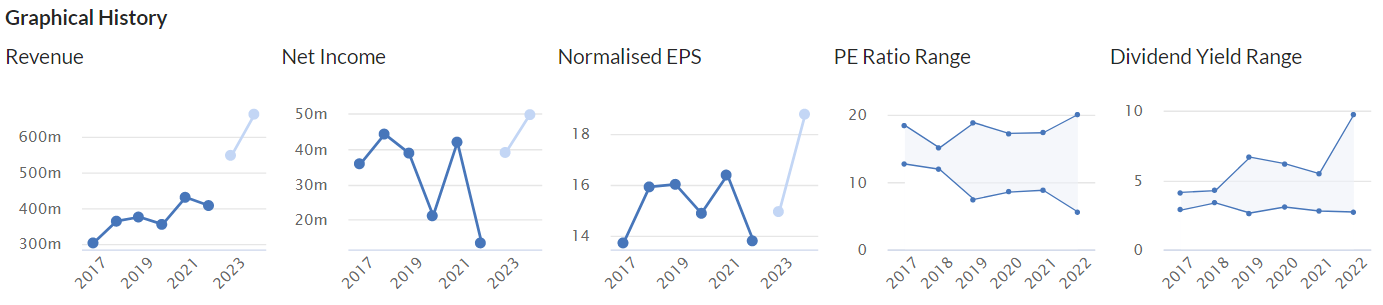
Stockopedia’s wonderful little graph shows us the trend below, with 5 brokers contributing -

I’ve sense-checked these forecasts, and I’m worried they’re possibly not cautious enough yet, given that historic EPS was 14-16p (based on the same number of shares, there’s not been dilution remember) see below -
There’s a recording of the video (with slides) results webcast here.
My opinion - I’ve bought some shares outright (am not using gearing any more for my main portfolio), hence am happy to just keep them for the duration - ie. several years. I think the current price looks attractive based on current fundamentals, taking a longer term view. The facts will change over time of course, as with everything. The period of zero interest rates would have undoubtedly stimulated demand, which might permanently reset at a lower level, thinking through the downside risk.
Also, I think it’s prudent to assume that legal provisions are more likely to increase, than decrease.
Overall though, I think the share price has already factored in so much downside, that it’s probably overshot too low. Hence there’s the chance of a shorter term recovery in price, plus a longer term re-rating once the economy is improving again. Plus there’s always going to be demand for this type of accommodation, due to the structural shortage of housing in the UK. I would like to see many more co-living spaces, for younger, and single people, which are much more social ways to live, eg in city centres. WJG has great experience & expertise, relationships with many institutional investors, etc, which give it a big advantage, and a barrier to entry for competitors.
Thumbs up from me, but it could be a bumpy ride, with another profit warning distinctly possible as 2023 develops.
On Beach group (LON:OTB)
190p (up 9% at 09:45)
Market cap £317m
We were discussing this online holidays company back in the autumn, with readers and I agreeing that it looked cheap at 95p. Here we are just a few months later, and it’s doubled, which is a considerable surprise! (well done to holders).
Holiday shares seem to be very strong at the moment, and I noticed that easyJet (LON:EZJ) recently announced strong trading too. Cruise operators have also been announcing strong bookings lately, helping to drive a strong recovery in share price at Saga (LON:SAGA)
OTB gives us an update for FY 9/2023 so far.
Key points -
Q1 (Oct-Dec 2022) - bookings up on prior year
Q2 so far - bookings “materially increased”
Overall bookings up 68% against last year - that is impressive, although I’m not sure how that would translate into revenues.
Higher costs (now known as “investment”) to drive sales growth.
Claims to have a strong balance sheet (checking the last one, it’s pretty good, with NTAV of £82.5m, and I like that client cash is held separately in a trust account).
The glaring gap in this announcement is obviously nothing said about what matters most (profitability). So investors are left scratching our heads, is this in line with expectations, or are they avoiding saying that for a reason? A badly written trading update then.
I can’t find any broker notes either.
Looking at consensus forecasts, they were reduced last autumn, so with bookings up so strongly, it looks as if the market might be expecting a beat against these forecasts below? -

My opinion - neutral, as I don’t have enough information.
Although given very strong bookings growth, it seems reasonable to assume EPS might end up nearer the 20p level that was being forecast before the cost of living crisis began. If that’s right, then 190p share price looks good value still, at 9.5
It might not get there in one go, but even if broker consensus of 12.2p is achieved for FY 9/2023, then the PER would be 15.6 - probably priced about right.
So valuation depends on whether you think it’s likely to meet, or beat forecasts. Either way, the doubling of share price in the last few months looks a fairly solid move, backed by fundamentals, although some people are bound to start banking their profits I imagine.
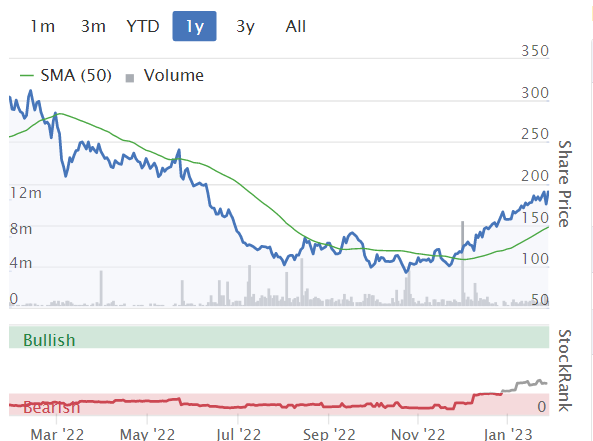
Superdry (LON:SDRY)
121p (down 19% at 12:02)
Market cap £99m
I need to get up to speed on Superdry, in time for the IMC webinar, which starts shortly at 13:00. Although what I have learned from previous webinars, is to take the permanently upbeat commentary with a pinch of salt. It seems to be more about what they want & hope is happening, rather than necessarily what is or will actually happen!
Superdry announces its Interim Results covering the 26-week period from 1 May 2022 to 29 October 2022 ("H1 23") and a trading update covering the 9-week period from 30 October 2022 to 31 December 2022.
H1 results look poor - some key numbers -
Revenue up 4% to £287m
Weaker gross margin, at 52.1% vs 55.2% LY. This seems low, but bear in mind that it’s a mix of retail (high margin) and wholesale (lower margin). Stores generated a good 68% margin in H1. Online was 58%, and wholesale 31% (down heavily from 38% LY).
Adj loss before tax was £(2.8)m in H1 LY, and worsened to £(13.6)m this year’s H1.
The statutory H1 loss was £(17.7)m.
Under-performance in H1 blamed “mainly” on wholesale (revenues down 18% YTD, and down 57% in the most recent 9 weeks). It’s strange to see product that’s selling well in the stores, not selling well to wholesale customers, so I’m perplexed by this. Although wholesale orders would be for the next season, so maybe that’s not resonating with customers - which could be an advance warning of softer retail sales in the spring of 2023 maybe?
Wholesale has proved more challenging with revenue down 18.0% year-to-date, in part driven by the impact of shipment timings, some of which will reverse in the second half. However, there is still a Covid-related confidence lag in Wholesale, which we expect to close as our partners see how successful our AW221 range has performed through our own channels, giving them confidence to buy for future seasons.
“Adjusted other gains and losses” stands out, at a large £23.4m overall gain, of which £17.2m is a forex gain. This seems to be telling us that excluding these gains (assumption being that they’re one-offs) would have meant an underlying trading loss of £37m in H1, which is rather alarming. Forex gains seem to have heavily cushioned a bad performance in H1.
Outlook - guidance for FY 4/2023 is lowered to a small loss -
...we are mindful of the challenges facing the consumer as we head into 2023 and remain very cautious about the potential for a soft spring. s a management team we are taking action to seek costs savings initiatives to support our performance. When combined with current margin run-rates and the underperformance of our Wholesale division, we believe it appropriate to amend our adjusted profit before tax guidance to broadly breakeven (previously £10 – 20m).
Balance sheet - is burdened by a large deficit on IFRS 16 lease entries, suggesting that SDRY still has plenty of serious problems in its store estate, with loss-making sites. That could be a tailwind though, as those leases gradually disappear on expiry. But for now, it will be a nasty headwind on trading and cashflow.
Inventories & receivables have gone up, and look too high to me, but the balance sheet is at Oct 2022, which would be when inventories were high for seasonal peak trading season ahead..
Net debt was £38.0m at Oct 2022, but has since reduced to £9.8m at Dec 2022, the usual seasonal pattern.
SDRY came close to the edge when its existing bankers didn’t want to renew the facilities, but it managed to replace them with more expensive specialist debt providers. A close shave for sure, but at least that issue was resolved satisfactorily.
Accounting problems - as mentioned here in the past, SDRY’s Annual Reports are dripping with problems going back years re its accounting department, which seems to have been a complete shambles. To see what I mean, check the archive here, or have a look at the Annual Reports (which are full of useful info that most investors never look at!)
My opinion - there’s no sign of Dunkerton’s brand reset delivering tangible results in the numbers. There are red flags with SDRY, in particular - multi-year negative disclosures in the Annual Reports re sloppy accounting. Also the underlying H1 loss (excluding forex gains) seems to have been much worse than the headline loss. H2 guidance reduced to breakeven, but stripping out the forex gains, it’s actually a significant loss. Big deficit on the IFRS 16 lease entries, which indicates there are heavily loss-making stores in the estate.
Overall, I’m on the fence. This share could go either way - it wouldn’t completely surprise me if the business were to go under at some stage. It’s incredibly difficult to make any money in the mid-market fashion sector, unless you’re Next (LON:NXT)
If Dunkerton does pull off his brand reset, then this share could be a good riser. At £99m market cap currently, the upside could be a 2-3 bagger perhaps? The trouble is, today’s update doesn’t give me any confidence the upside case is likely to play out any time soon, but who knows - it all depends on the product - it’s fashion, so the fashions have to be right every season. I’m still scarred from Joules, which showed that a couple of bad seasons can bankrupt the company, even when it has only a little bank debt. Hence I don’t really want to get involved in any fashion businesses right now, unless there’s a bulletproof balance sheet with plenty of net cash.
It might be far less glamorous than SDRY, but little Quiz (LON:QUIZ) is performing better than SuperDry, and has half its own market cap on the balance sheet as net cash.
The only other small cap fashion retailer that strikes me as any good is Sosandar (LON:SOS)
In this sector, I’d be more inclined to go mid-cap, with JD Sports Fashion (LON:JD.) And Next (LON:NXT) standing out as particularly good, and reasonably priced. Frasers (LON:FRAS) is another one to consider.
EDIT: a very interesting webinar was held. Worth a watch.
Roland’s Section:
Strix (LON:KETL)
100p (+10% on Thursday)
Market cap: £218m
Shares in kettle control manufacturer Strix bounced 10% after yesterday’s trading update. This company makes the component that ensures kettles switch off automatically when the water reaches boiling temperature.
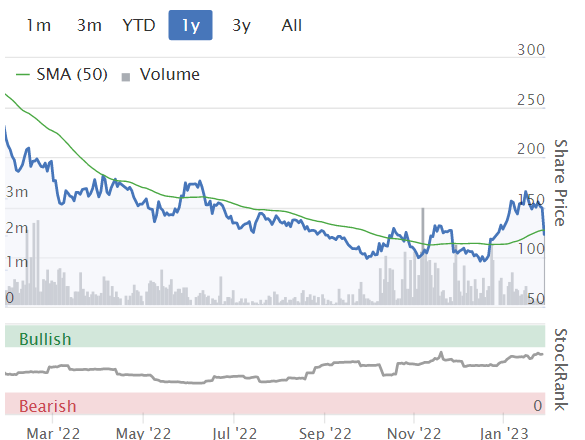
The shares have now risen by 25% since November’s profit warning (which Paul covered here), but on a one-year view the picture is still pretty bleak.

2022 results guidance: Management expects to report an adjusted after-tax profit of £23m for 2022. That’s in line with the guidance given in November, when Strix said that China lockdowns and wider geopolitical uncertainty had caused significant disruption to sales.
To put the scale of this drop in context, previous years’ profits were £31.4m (2021) and £29.5m (2020).
This week’s update implies a P/E ratio of around nine times 2022 earnings. That could offer value, if the company’s recovery proceeds as expected.
Profit margins: I’m concerned that Strix’s formerly strong profitability may have suffered a lasting hit. Using the firm’s past results and consensus forecasts, I’ve calculated Strix’s adjusted net profit margin from 2020 through to 2023:
2019: 29.8%
2020: 31%
2021: 26.3%
2022(fc): 20.7%
2023(fc): 17.2%
However, gross margins have remained fairly stable at around 40%, so my guess is that this falling trend reflects the expansion in the group’s cost base – probably due to acquisitions and the construction of a new factory.
Acquisitions: One problem with Strix’s core kettle control business is that with a global market share of over 50%, growth prospects are limited. To try and overcome this issue, Strix has been diversifying into areas such as hot water taps and water filtering.
What’s not yet clear to me is whether these acquisitions will be able to deliver the kind of steady profitability and cash generation that I’ve admired in the core kettle controls business. I’d like to see a bit more segmentation in the firm’s results so that we can understand this.
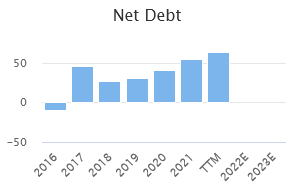
Net debt/leverage: This acquisition spree has taken place alongside the construction of a new factory in China. This combination has had a predictable result. Debt has risen and the dividend has no longer been covered by free cash flow.
Management say that net debt reached £87m at the end of December, up from £61.3m at the half-year mark. This means that net debt/EBITDA leverage has now risen above 2.0x.
This trend has been clear to see for some time now. Essentially, the dividend has been supported by borrowed cash – never a good thing:
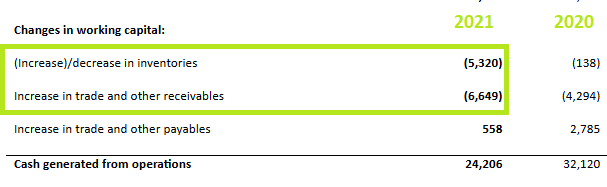
Elevated inventories and receivables have also eaten into the group’s operating cash flow. With supply chain conditions now normalising, I’d hope to see this start to reverse. This could release a useful amount of cash for debt reduction.
Dividend: Back in November, Paul commented that the dividend could be at risk because of declining free cash flow.
The company now confirms this, saying that the final dividend payout is being reviewed in light of the need to prioritise debt reduction.
Outlook: Strix says that it will not be making any more acquisitions and will now focus on “returning to its core operating model of behind highly cash generative with no further M&A activity or investment into new factory builds”
Capex will be significantly reduced and the firm will work on reducing inventories to free up cash from working capital.
The firm’s latest acquisition, hot water tap firm Billi, is said to have a strong pipeline of orders and be “highly cash generative”.
My view: Strix’s core kettle controls business has a dominant market share and high profit margins. Given the safety-critical nature of the product, I think this position is fairly safe.
Before its 2017 flotation, this was a conservatively-run and very profitable business. If the current management can return to this mindset and achieve good results from the acquisitions of recent years, then I think Strix could be an attractive turnaround play at current levels.
However, given the level of debt involved and the apparent likelihood of a dividend cut, I’m still cautious here. My inclination would be to wait for the company’s full-year results in March before deciding whether to invest.
Provident Financial (LON:PFG)
233p (+9% on Thursday)
Market cap £596m
Q4 trading update & name change
This sub-prime lender has closed down its doorstep lending business and is now focused on credit cards, personal loans and motor finance for the “mid-cost and near-prime parts of the market”.
Last year’s half-year results showed significant progress versus 2021 and the company has now reported a solid end to the year, suggesting full-year results should be in line with expectations.
Trading update: the group saw “strong momentum” across its credit card, vehicle finance and personal loans businesses during the final quarter of the year.
Management are keen to emphasise the group’s strong capital position. No numbers were given, but Provident reported a Common Equity Tier 1 ratio (CET1) of 27.3% in its half-year results, which is nearly double that achieved by most mainstream UK banks. The balance sheet does appear to be quite healthy, in my view.
Asset quality is said to have “remained high”. Bad debt trends were said to be stable and consistent with the earlier part of the year.
The firm’s product lines include retail savings accounts under the Vanquis Bank brand. Access to this cheaper source of funding (versus wholesale markets) remains a key differentiator, according to management.
New product: a new second-charge mortgage product is being trialled. These loans are being bought in at the moment, but the company plans to start originating them if this pilot phase is successful.
Outlook: 2022 results are expected to be in line with expectations. That prices the stock on six times forecast earnings, with a prospective dividend yield of 5.7%.
However, broker forecasts suggest earnings are expected to fall by around 35% in 2023, pricing the stock on 10x forward earnings. I assume this reflects the risk of increased bad debt levels during a recession, given the firm’s exposure to below-prime borrowers.
While this isn’t expected to impact dividend growth, I think it’s worth considering when valuing the shares:

Strategy update/name change: the company is aiming to move away from its sub-prime roots and reinvent itself as a near-prime lender.
The Provident brand was mainly linked to the doorstep lending operation, so the firm has opted to rebrand under its existing Vanquis Banking brand, which is already used for credit cards and loans.
New CEO: There’s a new chief executive to go with the new name. CEO Malcolm Le May is stepping down, having overseen the group’s turnaround since 2018.
The new boss will be Ian McLaughlin, who has a track record of senior positions in mainstream banks including Bank of Ireland, NatWest (I hold) and Lloyds.
Mr McLaughlin appears to be highly experienced, with past involvement in consumer and motor finance, SME finance and mortgages. His appointment seems logical, given the group’s intention of moving up the credit quality curve to near prime.
I’ll be interested to read his initial thoughts on the business after he takes charge this summer.
My view: It’s a little hard to believe that Provident Financial was once a FTSE 100 member with well over £1bn in annual revenue.
However, the business looks in decent shape to me today. The strategy of moving up the credit quality curve makes sense, given tougher regulation around high-cost lending and the problems suffered by the company in the recent past.
My main concern is that the firm’s client base are presumably more likely to suffer financial problems during a recession than those higher up the credit spectrum.
I think it’s possible that we’ll see bad debt losses spike over the next year. However, broker forecasts already appear to reflect this risk, pencilling a 35% fall in earnings.
I don’t think this is likely to be an existential issue for the firm, given the strength of the balance sheet.
Based on consensus forecasts, my sums suggest the group could achieve a return on equity of c.15% in 2022. That’s attractive, in my view, and suggests that the 5.7% dividend yield should be comfortably affordable.
While I’m not a massive fan of this sector, I think Provident shares could be a reasonable purchase at current levels.
Rank (LON:RNK)
92p (broadly unchanged on Thursday)
Market cap: £422m
This gaming group operates the Grosvenor Casino chain and Mecca Bingo, together with a number of online gambling properties. It’s delivered a string of profit warnings over the last year, as rising costs and weaker consumer spending have hit earnings.
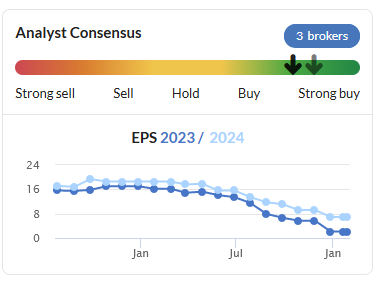
For more background on these issues, I’d suggest a look at the SCVR updates from October and December.
This week’s half-year results suggests that performance may have stabilised – or at least that expectations have been cut to a more realistic level.
Trading: Underlying like-for-like net gaming revenue rose by 2% to £337.4m during the six months to 31 December. This was driven by a 9% increase in online revenue (£100.8m), offsetting a 1% fall in venue revenue (£236.6m).
Underlying operating profit for the half year was £4.2m, 83% below the £24.9m reported for the prior year.
At a statutory level, Rank reported a pre-tax loss of £107.1m for the half year, reflecting £95.4m of impairment charges. These primarily relate to soft trading at its Grosvenor and Mecca venues.
The dividend remains suspended.
Balance sheet: available cash and bank facilities stood at £148m at the end of December. Rank says net cash was £10.9m, excluding lease liabilities.
Including lease liabilities, statutory net debt was £158.3m at the end of the year, up from £142.7m one year earlier.
While I sometimes agree with the exclusion of lease liabilities from net debt, in this case I think there’s a case for including them. If the performance of UK venues doesn’t recover, then some of these leases could become onerous and need renegotiating.
More generally, the balance sheet doesn’t seem that strong to me. Tangible net asset value is negative and there is c.£78m of financial debt, in addition to £169m of lease liabilities.
I’d want to do further research into the group’s financial liabilities, before considering an investment.
Outlook: full-year operating profit guidance of between £10m and £20m is unchanged.
My view: Rank’s well-known brands and decent market share will probably support a recovery over the medium term. This business has generated double-digit returns on capital employed in the past. I’d imagine its hybrid mix of online/offline venues should continue to deliver results.
However, net debt looks high to me and I think trading could remain tough in 2023, given the macro backdrop. Regulatory risks are always a concern in this sector, too.
Rank shares have already staged a substantial recovery from their October lows.
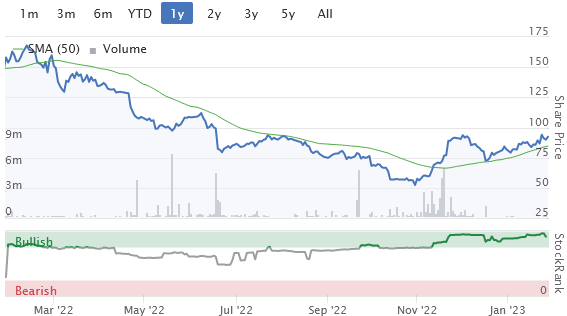
On balance, I would be inclined to wait for another market dip before considering a purchase, given the risks involved.
Hargreaves Services (LON:HSP)
Share price: 430p
Market cap: £144m
This industrial services group operates land development and earthmoving businesses in the UK, together with a coal-focused commodity business in Germany.
Results from the six months to 30 November seem encouraging. Revenue rose by 53% to £116.5m, while pre-tax profit for the half year rose by 80% to £18.7m.
Hargreaves reported net cash of £18.1m (excluding leases) and a net asset value of 603p per share, up from 462p one year earlier. This increase appears to reflect a rise in the value of certain joint ventures and investments.
Earnings per share rose by 68% to 52.2p per share, while the interim dividend has been increased by 7% to 3p per share.
Segment performance: Revenue growth has been driven by contract work on the HS2 high-speed rail project. However, the largest profit contributor remains the group’s HRMS trading business, which is based in Germany.
Here’s how the different parts of the business contributed in H1 2022 (“Services” represents earthmoving/construction):
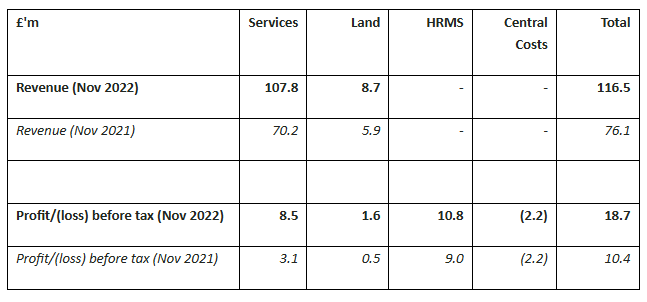
Outlook: the first half of the year included some one-off benefits. Management warns that this year’s results are likely to be weighted to the first half. In other words, second-half profits are likely to be lower.
This already seems to be reflected in consensus forecasts, which suggest full-year earnings per share of 71.7p, versus H1 eps of 52p.
The board is confident full-year results will be in line with market expectations, suggesting the shares remain reasonably valued at a 20% discount to book value, with a useful dividend yield:

My view: I’ve always had an interest in this business, but it’s been a complex investment over the years.
One attraction for me is that long-time CEO Gordon Banham is an 8% shareholder, so has a strong motivation to maximise the value generated by the group’s assets and protect against dilution.
I’ve only had a quick look at these half-year results, but they look fairly reassuring to me. However, I can see some risks on the horizon that could impact performance over the next 12 months.
Visibility on profits from the German HRMS business is poor, as much of this division’s income comes from commodity trading. However, the company has warned that its steel recycling business will generate less profit than expected this year due to higher maintenance and energy costs.
The UK-based earthwork and construction services business appears to be performing well, but this is a lower-margin and fairly capital-intensive operation (lots of leased equipment).
Hargreaves’ land bank remains a valuable asset. The firm has made good progress selling permitted building plots for residential developments in recent years. However, most major housebuilders appear to be cutting back on land purchases at the moment. I think it’s prudent to expect Hargreaves’ land sales to slow, also.
I think this business remains interesting and could be attractively valued, at a discount to book value. However, I’d need to do more research to understand the valuation of each segment of the group, plus the likely impact of macro conditions over the coming year.
Broker forecasts suggest some caution might be warranted, guiding for a 12% fall in earnings in the 2023/24 financial year:

On balance, however, my view is positive.
SCVR Summary spreadsheet - I'm updating this every day - please don't share this link, it's for Stockopedia subscribers only please!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Hi Paul, Great work. Just flagging up the mystery shares like this is a good option. Thanks
Hi Paul. I was wondering if I could provide a suggestion after listening to your podcast. Would it be possible if you could have your mystery share highlighted as a different colour or border in your SCVR spreadsheet so we can easily identify it? No worries if not. Hope you're well.
Hi Caduceus - it's probably easier if I just put the mystery shares here in the comments to each Firday's SCVR.
This week's podcast mystery shares are -
Best Of The Best (LON:BOTB) (I hold) - see Thursday's report here. I think risk:reward still looks good, even after a sharp rise in price this week, on a reassuring update. I think future upside could come from a deal (if agreed) with GIL, the 30% shareholder owned by Tedi Sagi. Sagi wants to expand BOTB internationally, but mgt is being cautious about the pace of change (as always), and doesn't want to rush into anything (something I gleaned from a call with mgt). So it's slow & steady under existing mgt (with good divis, specials, and buybacks) at a modest valuation now. The upside is a re-rating to international expansion, if GIL gets its way. Also upside from GIL deciding to bid for the whole thing, although mgt still have significant shareholdings.
hVIVO (LON:HVO) - I'm a recent convert here, but think it looks very interesting - see Wednesday's SCVR here. Mainly due to a series of big contract wins, having a breakthrough year into profit in 2022, strong pipeline so 2023 looks already in the bag & should beat forecasts, plus amply cash and maiden divi on the way. Good upside on this one I think, providing nothing goes wrong. So I've picked up an opening position in it myself, and will continue researching & monitoring.
As always, these are just my views, some of which will turn out to be wrong, and some right. So always vital to do your own proper, more detailed research.
Thanks, Paul.
Thank you buddy, replied on a sunday as well! BZ You clearly love it!. Very much appreciated. It helps to narrow down my left and right of arc of focus/prioritisation to look at things you talk about. Hope you're well and having an enjoyable weekend.
Earning interest on cash balances in ISAs and SIPPs.
I currently have my ISA with IG and my SIPP with AJ Bell. Neither offer interest on the cash balances (that I know of). I am planning to keep a substantial float of cash that I'm not sure I will deploy over the next few months.
Are there any "safe" type of cash/money-market funds that I can buy, on either platform? Any recommendations, and is it worth it if I only hold for a few months, given the trading fees and any other fund fees? (I am aiming to put in high 5-figures, maybe low-6 figures).
I'm aware its not going to be as safe as FSCS protection on savings. But I don't want to withdraw my ISA, and I can't withdraw from my SIPP.
Alternatively, is there an ISA or SIPP provider that pays market competitive interest on cash balances (say 2.5%+ currently) that I should consider moving to?
AJ Bell pay 1% on cash balances above £10k and 0.5% under that amount in an ISA and 1.75%/1% on a SIPP
https://www.ajbell.co.uk/isa/c...
ii pay 0.4% on the first £10k and 1.25% above £10k
https://www.ii.co.uk/our-charg...
Ah wow, thanks! I didn't realise AJ Bell paid interest on cash balances! That's awesome.
And... I'm with IG, not II. Looks like IG doesn't pay interest on cash balances. Maybe I should move ISAs...
Could Lyxor Smart Overnight Return - IE (LON:CSH2) be something to look at for this purpose?
Also, if you have a view on FX relative performance, some of the wisdom tree currency funds may also be of interest such as: Wisdomtree Foreign Exchange (LON:SJPY) , Wisdomtree Foreign Exchange (LON:SGBP) , Wisdomtree Foreign Exchange (LON:SEUR) . I used these at periods in 2022 when I had excess cash on account. These ones are x1 so fairly calm in terms of volatility, there are also instruments available offering x3 leverage but of course these are riskier!
Yes, thank you Forbsy! The Lyxor Smart Overnight Return looks like what I'm looking for. Money market fund, super low risk (I think?) but earning some decent amount of interest, similar to what I could get in a cash savings account. Looks like about 3-4% annualised, so not too shabby?
But guessing there is the black swan counterparty risk, in that they are lending to large corporates, and if one of them suddenly went....
However, the Lyxor fund you suggested is in USD. Are there any money market funds in GBP, and also no currency risk?
Thanks for the suggestion of currency funds too, but at the moment just sticking to UK exposure for now (except for my S&P500 short!)
Just found this: Xtrackers Sterling Cash Swap UCITS ETF 1D
Looks like fairly accurate tracking over the last few years, tracking the SONIA rate. Which is close enough to what I am looking for. 0.15% TER, which sucks on a 3%+ return, but ah well, no choice, there doesn't looks like there are other ETFs out there that are similar?
The problem though is that it is all synthetic - it is just a derivative with Deutsche Bank. So 100% counterparty risk to DB. Not really doing any underlying SONIA lending itself. So somewhat of a risk?
The Lyxor seems to be in £ but I can't buy on IG within an ISA. Can buy on HL I think, seems to about 2% but maybe more in the next year with rising interest rates?
Interactive Brokers (IBKR) pay interest about 2-3% depending on currency and amount but not sure if that is within an ISA.
Preference shares maybe worth considering but capital can fall, I do have a few.
Hi Boon
HL also offer decent interest on ISA/SIPP cash balances, including on balances <£10,000.
https://www.hl.co.uk/charges-a...
A
Interesting, I wonder when they pay this interest, can't find any payment on my ISA. Have monthly fees.
If HL do pay 1.5% on cash over £50k, then not much point in some of these low paying funds, which carry more risk?
I have sent HL an email about where my interest is. Will update.
Hi Rusty2
I've seen interest from HL in an ISA and a SIPP for quite some time now, usually around the 9th of the month.
Hi Abtan, I have checked again and there are some payments, I was looking under income as that is where other payments and fees are but they are under transactions. But they don't seem tie up with the interest rates, unless they have got up nearly x3. Do you know what the rates were last December?
HL bumped their rates up in the first week of January I believe.
The December rates were much lower but I'm afraid I can't remember what they were.
Thanks! Looks like I might have to give in to expensive fees, now that the interest earned balances it out...
The VIX has now dropped below 20. Above 20 is fear territory, above 30 is panic.
Paul, thanks for all your work. Interesting you mentioned family owned businesses as a potential investment case, not sure if you are familiar with the Pictet family fund which tries to do a similar thing on a global basis, launched in May 2020.
Links here to the Pictet family
Link to a Fund fact sheet
Thanks
Alb
That's an interesting idea for a fund (invest in family businesses) and not heard of it before. Performance looks pretty miserable unfortunately (appears to be bottom quartile agaisnt its sector over all key periods!)
Hi Paul, hope you're well. Question please... Should the MOTR PW be on the PR warns tab of the SCVR Spreadsheet Paul? I couldn't see it on there and didn't know if it was missing for a specific reason? In other news... I left Stockopedia... lasted 2 months, got withdrawal symptoms and returned to being a subscriber! I'm weak!
Conscious bias here Paul, thank for the excellent analysis on WJG, we hold (again).
57,900,000 block gone through in N Brown (LON:BWNG) !
Alliance family?
Looks like Frasers (LON:FRAS) has taken a 17.9% stake in N Brown (LON:BWNG) according to the RNS this afternoon.
Who sold them the block I wonder?
Interesting news, given the Alliance family own so much of the company Frasers would need them on board if they were looking to takeover the company.
Today folks on 'Frivolous Friday' Hostmore (LON:MORE) surges to a two month high and smashes through the 50 day moving average. I'm telling you, the sky's the limit with this one, (although a hard landing remains just a fraction below my cockpit). I continue to hold and suffer, but only for my general amusement and as a warning to myself lest I ever forget :o)
Many thanks for your useful and detailed update on Watkin Jones (LON:WJG). My father worked for the firm as a joiner in the 1950's when you could probably put all the employees in a single car.
Paul,
A note on Watkin Jones (LON:WJG) from Progressive Equity landed in my email about an hour ago. I'm not sure if they are on Research Tree, but it's free to read anyway.
EDIT, the note is on Research Tree, that email just landed a few minutes ago.
Cheers.
Hi Graham.
Many thanks for your balanced view on Strix (LON:KETL) . Good to see the annual Net Profit %ages. By the way as one suggestion for improvement to Stockopedia I asked for such profit %ages to be included in the Income Statements as it would be so useful and save having to manually calculate them.
We can't deliver everything you need, but I hope you find some of the financials included here on Strix (LON:KETL) of use: https://www.equitydevelopment....
On the beach On Beach group (LON:OTB) (I hold) is up 8% following on yesterdays big drop why this volatility
On Beach group (LON:OTB) has been one of the least volatile shares in the last month or so. Put an 8 day moving average on the chart and apart from 1 day in early December its been a stress free gentle rise since 100p.
Yesterday selloff just people banking profits as they knew an update was coming this morning. Have to remember lots of people will be sitting on 50%+ paper profits.
Can feel some of the steam coming out of this 4 month everything rally. Maybe S&P breakout, if it happens, will give it another push. Personally been the best trading period since covid vaccine announcement in 2020 so have been banking profits along the way.
Looks like a really good performance from On The Beach. I am kicking myself for not buying, but as I work in the travel industry, I'm already very exposed to the industry, financially.
They took a big gamble by investing heavily in headcount, marketing last year. And this looks like it's going to pay off handsomely. If the consumer demand stays buoyant, they'll be one of the strongest players, having made that investment, and grab more market share.
If I wasn't already so financially exposed to the travel industry, OTB would be one of my top shares to consider buying.
On Beach group (LON:OTB) have made the point over many months that this year will be much more of a level playing field because many other companies had been issuing vouches for cancellations / postponements. They didnt do that, so their last year's figures were arguably artificially low, and therefore perhaps the increase this year vs last is perhaps artificially high?
On the other hand Michael O'Leary recently said the previous weekend was the best Ryanair flights / holidays had ever had and that people now regarded foreign holidays as a necessity not a luxury. He also made the point that with forecast flight and holiday prices to rise still further, advance bookings were likely to be higher than normal.
On Beach group (LON:OTB) are at the cheaper end of the market so may well be well positioned to do well, especially if O'Leary's forecasts turn out to be right. There are still many people with savings according to the banks and, with that in mind, perhaps many people will say 'we''re off' rather than buying carpets, settees or even nothing at all. 'Put it on the card' is also another option for the many who are feeling down in the dumps!
Following Wednesday's positive year end trading update from (LON:XPF) there are a couple of short CEO interviews for anyone wanting to explore further.
The £28m market cap will be too small for some, but XPF ended the financial year with net cast of £3m, a revenue run rate of £33m pa and the broker forecasting FY23 EBITDA of £6.1m, based on the up and running estate. The lions share of capex was in 2022 so they are profitable, cash generative and appear well capitalised.
That said FY22 success means there will be share dilution to settle the outstanding Boom Bar acquisition earn out liability. So it's important to bear this in mind for the per share calculations!
Nevertheless I think the CEO speaks well, obviously talking his own book but offers some good insights into the leisure sector for those interested.
https://www.voxmarkets.co.uk/m...
https://www.directorstalkinter...
I hold.
Hi Cuddlesticks,
Yes, I'm pleased with how XP Factory (LON:XPF) is progressing (I hold personally).
My view is that just going to a bog-standard bar is so boring, when you can get quietly sozzled at home for a fifth of the price, and not have to worry about anti-social louts, or screaming hens.
So experiential leisure is far better, where people go for a group night-out, and have activities that are fun to engage in, and create a really nice atmosphere. Boom Battle Bars does that very well I think. It might have a few rough edges, but it's a really good format, that they're constantly tweaking.
XPF is the only way to play this sector trend in the stock market, and I think it could be a multibagger. Although there's considerable execution risk, building a business that fast, and the cash position is a little too tight for my liking. That said, as you state, the existing sites are now nicely cash generative.
Promising I think! DYOR as usual.
Regards, Paul.
Watkin Jones (LON:WJG) Graham, was quite negative last October: "Watkin Jones is sensibly expecting this softness to continue, as there is no reason to believe that borrowing costs are going to reduce in the year ahead. The business model of forward sales and high visibility has served the company well over the years but I’m taking a neutral stance due to the risk that interest rates continue to increase and given the fact that Watkin Jones shares still trade at a high premium to their balance sheet value."
Re Watkin Jones (LON:WJG) I didn't read the forecast in such a positive way, and I was taken aback to see the forecast for remedial work to be £50m over the next 5 years. That's around 20% of profitability this year which is quite a chunk.
Also, although they have good levels of land with planning permission and are going to forecast on the higher profitability areas of buy to let and student accommodation, there are still higher interest rates to be borne by their customers which may dampen down orders in the short term.
I would not be surprised if there were a bumpy ride as he predicted in the short term. Nevertheless, he has bought at current prices 'to have and to hold', so who knows?
I enjoyed yesterday evening webinar with Ed Croft. He managed to cover one day seminar in one and half hour. Well done Ed and may we have more of such webinars please.
Morning all - apologies if its already been mentioned but I enjoyed the GMO piece from J Grantham - tempering my temptation to take some risk off the table, for a month or two at least.
Just a follow up from my earlier comment re Sherborne Investors (Guernsey) C (LON:SIGC) and Navient (NSQ:NAVI. Navient (NSQ:NAVI) results were Tuesday after the close and the call was the following morning. Its a pretty hard business to understand because its a student loan business in wind down and the management are looking to transition into growth areas. They have an activist, Sherborne, on the board, who think this is likely to fail and would prefer them to slash costs and retire capital. Lots of moving parts with most areas of business in retreat not helped by COVID...but costs also been attacked aggressively and stock being retired at a pace that, give or take, is preventing NAV dilution ( from the shrinking business).
Navient (NSQ:NAVI) shares trade at a 20% discount book. The pressure from the activist means the co have upgraded return targets for 2023...but this remains a transition year. The co DID NOT announce a major cost plan which I think the activist is pushing for. Somewhat to my surprise the shares have reacted well ... rising 6% Wednesday and 4% yesterday. Having an activist in the background is no guarantee of success but at least you know management is under pressure. For now it remains a wait and see.
For Sherborne Investors (Guernsey) C (LON:SIGC) their shares are also at a discount c37%...and are therefore under pressure themselves. With a little more progress the NAV will be back to 100.... which is helpful. Sherborne Investors (Guernsey) C (LON:SIGC) also have cash....from memory I had this at £60-70m....would help them further increase their stake in Navient (NSQ:NAVI) or just buy back their own stock once Navient (NSQ:NAVI) is on the right path.
All in all, it wasn't the unequivocal news I was hoping for this week....but the story seems to be moving forward and as I have highlighted previously ...a decent return if Sherborne Investors (Guernsey) C (LON:SIGC) can get back to NAV approaching 100. I am of course talking my own book and continue to hold. DYOR.
Have a great weekend and hope you enjoyed this rather positive start to the year.
Awful looking update from Motorpoint (LON:MOTR)
Shore reduced EPS for 2023 and 2024 to 0.1p and 0.5p. PEof 1025x and 286x. They expect headwinds to remain into 2024.
Ive opened a short position.
With Motorpoint (LON:MOTR) there is lots of reverse operational leverage going on at the moment. They obviously take a time risk with when they buy used cars, and when they manage to sell them. So in a declining market, they take a hit on the price, but also it might take longer to sell a car.
Obviously benefited from an expansion of margins over the last two years as used car prices rose, and customers were desperate to buy and not haggle.
Now the reverse is happening, this looks like a classic falling knife - unless you really know where used car prices are going to bottom out at, its almost impossible to tell where the new equilibrium state will end up as.
However, the silver lining is that I think they will emerge stronger than ever before. They have had to deal with thorny competition from the likes of all the online car dealers, burning money and offering cars unprofitably, over the las two years. Now they are largely gone or a shadow of their former selves, Motorpoint have an opportunity to capture the void left behind by them.
Looking forward to Roland's thoughts on Hargreaves Services (LON:HSP) . Lots of moving parts and lots to like in my view.
The possible disposal of pension liabilities, Blackwell contract with Balfour Beatty for the substantial Road of the Thames project, minimal debt, most service contracts include inflation protection, trading at a significant discount to NAV with land in the books at cost and the potential for gains from the company's nascent involvement in renewables and energy from waste venture.
As with most investments there are some negatives, land sales are likely to slow in the short term. Also there is the uncertainty regarding the future profitability of HMRS, the company's German venture
Have been in and out of Hargreaves Services (LON:HSP) since the share price was £2 or thereabouts, recently bought back an opening position.
Hi Jonno
I have a small position in Hargreaves Services (LON:HSP) and concur, a lot of the price rise has been driven by the outstanding returns on the German JV in the last 12 months which have gone straight to the bottom line.
Working in construction I was personally never too sure about the Blackwells purchase, yes there are a lot of jobs right now think A14, HS2 Phase 1 / 2a / 2b but then it depends on the structure of the contracts, do they get paid on material placed and certified or cost plus e.g. what happens when it rains a lot in June, as June is now typically wetter than December, which is peak muck shift season. A lot can go right and a lot can go wrong in these contracts. Did anyone mention a shortage of qualified drivers for the various categories of machines? They have the same challenges of Wincanton (LON:WIN) with a smaller labour pool.
With regards to land, we are not building any more land in this country, compared to say Hong Kong or Singapore, so there are a number of brownfield site owners who I feel are going to benefit in the longer term as what were marginal or too difficult sites then get given the necessary catalyst to start, such as government funding support, rezoning etcetera and I think they are well placed to gain from these. For example Harworth (LON:HWG) or Henry Boot (LON:BOOT) .
Then there are a number of longer term service contracts within a very specialist niche, dry bulk storage for example, which are sticky as there are only a few operators in both installation and maintenance of these, again there not a lot of operatives suitably qualified and experienced. Not massive, but just a nice thing to have in the background ticking over onto the bottom line each year.
So in the longer term I feel they will continue to be a part of my portfolio, never going to shoot the stars out, but just a solid return most years, adding that I am currently dividends reinvested as returned to work this month.
Tommy
ps. I hold Hargreaves Services (LON:HSP)
pps. Sorry didn't realise that I had not posted this several hours ago!
Cheers Tommy
You have certainly added a few more aspects to consider. Longer term I think Hargreaves Services (LON:HSP) will do well.
There is also the Tungsten West project that I forgot to mention for which I seem to recollect Hargreaves Services (LON:HSP) receives £1M annually for 8 years plus first dibs at engineering works once the mine is operational
All the best
What Hargreaves Services (LON:HSP) have done with Blackwells, after a lot of pain over several years which I'm sure that they didn't anticipate when buying them, looks about right to me, as someone who knew Blackwells for many years. Blackwells used to act as a subcontractor to the big contractors on motorways etc and as a main contractor to local authorities on pure muckshift jobs such as regrading old colliery waste mountains. But the ethos of the organisation was originally formed when Chris Blackwell took on the main claims QS from I think it was Laing after the original M1 contract. They became infamous for their claims culture and ability to take advantage of clients with poor understanding of the various "Methods of Measurement" applied to contracts, and believe me there are many such clients.
Eventually they found many local authority clients preferred to exclude them from tender processes and main contractors, apart from those such as BB who were just as contractual as Blackwell, preferred other subbies. Gradually they then moved into becoming a main contractor on jobs which were much more than muckshift, which was their downfall, imo, despite having good claims people. Enter HSP, buying a company with a huge "work in progress" book, ie lots of outstanding claims which Blackwell had confidently put into their books, and then came the pain.
But what HSP have done is stop all the "main contracting" rubbish and restrict Blackwell to subbie roles in the major civils contracts, which are all awarded on ideal forms of contract for Blackwell. These contracts are based on one of the Civil Engineering forms of contract, which although their are about half a dozen varieties, are more than fair to the contractor and usually guarantee cost plus for most of the contract period. This usually leaves the risk of breaching a target cost late in the project, after which things become painful for the contractor, but along the way the Blackwell contractual expertise, assuming they have saved most of it, allows them to identify contract changes that enable them to negotiate increases in the target figure, so I personally would expect them to never have a problem in that respect. In fact that form of contract can end up with a bonus at the end if you can keep raising the target and end up below it on completion. So well done HSP for steering Blackwell into the correct niche, now all they need is continuity of major projects.
Hi Jonno,
Thanks for your comment on Hargreaves Services (LON:HSP). I agree that there's plenty to like, but the number of moving parts (and cyclical risks) do create some complexity/uncertainty.
I've not been able to do an in-depth report, but my impression is favourable, albeit with similar caveats to those you mention.
Regards,
Roland
Worth saying how good Ed Croft's 2023 NAPS Webinar was yesterday. He is such an inspirational presenter. Always thought provoking. Thanks to Ed.
Superdry (LON:SDRY)
What a dreadful update today - top dog seems happy and he seems to think there is an underlying recovery within the business whilst at the same time the numbers have taken a material turn for the worse . They did amazingly well to get financing away - guess it’s lucky for them that they didn’t know how bad it was until after they had the new facility. Only surprise is it wasn’t all royal mails fault
You can see from the Superdry (LON:SDRY) how the markets seem to have gotten ahead of themselves in the past month. From 100p to 150p, with what was an in-line trading statement and just a renewal of a working capital style financing facilty.
This morning back to 120p, and possibly back to 100p or lower next week.
I fear that too many shares have seen an indiscriminate rise whether or not their prospects have actually gotten better, and am doing two things. I've been reducing my holdings this week, and being very selective of my purchases.
(edited to correct that there was an update between the 100p and 150p rise)
Yes, I completely agree Boon. This has indeed looked like an indiscriminate rally since Oct 2022 lows. I've been putting my BUMP proceeds to use (have sold most in the market), but am only buying things that have issued a decent, recent trading update.
I suspect that some of the big jumps in share prices of late could be more selling, than buying opportunities, where there hasn't been any news to justify a re-rating. SDRY certainly looks like that, as you say. Although I find Dunkerton far too promotional. His webinars & updates seem to be more about what he hopes will happen, than what is actually happening! Hence I'm disregarding pretty much everything he says now.
It's worth saying Boon, that in some cases the market had/has gotten ahead of itself. There have been plenty of examples over the last ten days/2 weeks of shares reacting very positively to their Jan trading update/results. I've been surprised at the large % jumps in a lot of share prices, potentially showing the market had not got ahead of itself, in fact the market was lagging behind itself (if that is the opposite).
The only point to arise from this is that I hope you haven't been reducing your holdings indiscriminately, as you're just as likely to be doing yourself out of some good future returns, as saving yourself from bad ones.
If I've learnt one thing over the past year to eighteen months (and I'm sure it's a lesson I'll un-learn/re-learn in the future), it is that in uncertain and unpredictable markets, doing nothing is a not a bad strategy. If there is no discernible negative change in the operation/financial position of a company, you can just ignore the share price.
Good luck and good weekends to all!
Chris
P.S. - Please Paul, could you take the weekend off, not podcasts, no additional research, just relax. Put on some Chaka Khan and think about something else. You've been pumping out prolific levels of work recently, you need some time off.
Agree Boon. I think this year the asset allocation decisions are the key to success. Company updates are fine but there are a lot of extraneous factors applying themselves at this point. I think you need to decide if you are going to see recession and if so many updates now are irrelevant. In my view capital is still being taken from the global economy, Russia/Ukraine is likely to continue through 2023. On top of this everyone seems to think inflation is solved, it isn't. Yes the highs are gone but I believe we will now see bursts of inflation. That's a difficult environment when running companies.
My morning smallcap tweet: Winter's Fail. Dunkerton hangs holders out to, er, dry.
Superdry (LON:SDRY) Amigo Holdings (LON:AMGO) Motorpoint (LON:MOTR) Stelrad (LON:SRAD) Avon Protection (LON:AVON) On Beach group (LON:OTB) Actual Experience (LON:ACT), Treatt (LON:TET)
◄Superdry (SDRY)► H1-Oct profit short of expectations mainly due weak Wholesale. But in the H1 trading stmt CEO founder Dunkerton said “I’m pleased with the performance of the business over the half". Adj pretax -£13.6m (-£2.8m). Cuts FY adj pretax guidance to broadly breakeven. [SP=149.2 Cap=123m]
◄Amigo (AMGO)► not enough support for needed fundraise yet. Deadline 26 May. Return to lending - volumes have increased substantially during Jan. [SP=2.88 Cap=14m]
◄Motorpoint (MOTR)► warns " recent reductions in finance commissions and lower gross margin, largely due to the well documented fall in electric vehicle values" will hit profit for the foreseeable future. [SP=147.5 Cap=131m]
◄Stelrad (SRAD)► guides FY-Dec broadly in line with its expectations with rev up c.15% and 3% LFL. Adj op profit c.34m. [SP=118.3 Cap=151m]
◄Avon Protection (AVON)► AGM stmt - sounds in line. [SP=1019.57 Cap=307m]
◄On the Beach (OTB)► AGM stmt - Oct to date TTV up up 68%. In line? [SP=175.77 Cap=291m]
◄Actual Experience (ACT)► FY-Sep rev in line. Outlook: advanced discussions with a large UK central government department two leading professional services firms but says sales cycles are in general lengthy. [SP=1.08 Cap=2m]
In line: TET