Small Cap Value Report (Fri 28 Feb 2020) - Carnage, VRS, FOXT, NCYT, AVAP, VTC

Good morning!
I hope everyone is ok out there.
As I type, FTSE futures are changing hands at 6550.
It has been an extraordinary week in the stock market.
In the immortal words of Clive Dunn, "Don't panic!"
In today's article I'll be taking a look at the newswire, as usual, and talking a little about what's going on more generally.
Some small-cap announcements today:
- Foxtons (LON:FOXT)
- Novacyt SA (LON:NCYT)
- Avation (LON:AVAP)
- Vitec (LON:VTC)
Rightmove (LON:RMV) has published results, too. I have a long position in that one, and it's relevant to OTMP, so I might say a few words on it.
Finished at 13:30. Got as far as VTC.
Carnage
I should address the fact that the FTSE is down by 800 points, or over 11%, in the space of five trading sessions.
What I've been doing - very little!
As long-time readers will know, I don't trade very often. I can go many months without buying anything new, or selling anything.
It is true that since December, I disposed of around 1/4 of my entire portfolio, to help fund a house purchase. Yesterday, I got rid of my tiny stake in Property Franchise (LON:TPFG), to help fund this purchase.
The rest of the sales took place in mid-January, long before the panic over the coronavirus.
So my share portfolio has not been reacting to this news.
If I had been more clever, I would also have sold my entire stake in Burberry (LON:BRBY) last month, when it was trading at £23 (now £16). But selling and buying back cheaper is not a game that I play.
The total returns for my largest holdings so far in 2020 are:
- Volvere (LON:VLE) (+6% YTD) (21% of portfolio)
This is a cash-rich, counter-cyclical holding which would benefit from a recession. It's been holding up as I hoped it would in these circumstances.
- Burberry (LON:BRBY) (minus 27% YTD) (12% of portfolio)
Burberry has heavy exposure to China and Chinese tourists around the world. If I had more cash lying around, I'd consider topping up on this at a PER of 18x (granted that major earnings downgrades are likely for the current year).
- H & T (LON:HAT) (minus 2% YTD) (12% of portfolio)
This issued a positive, "top-of-the-range" trading update at the end of last month, but has now given back those gains. With the gold price currently very strong and the stock sitting at possibly 7x earnings, it looks too cheap to me.
- Berkshire Hathaway ($BRK.B) (minus 8% YTD) (11% of portfolio)
Jack covered Warren Buffett's annual shareholder letter here. Like Volvere, Berkshire is cash-rich and would benefit from the buying opportunities which a market crash would present.
- IG Group (LON:IGG) (minus 4.5% YTD) (9% of portfolio)
The market volatility will throw up plenty of trading opportunities for IG's customers. Again there is an element of counter-cyclicality, since customer activity is tied to volatility rather than the economy (and volatility is especially pronounced in bear markets!).
Even if you aren't interested in my individual holdings, hopefully this helps you to see that I am not actually very worried about their share prices. I'm more worried about whether they are going to be reasonably successful companies over the long-term. I don't think that the Coronavirus changes this, even if it causes a lot of disruption in the short-term.
Buffett gave us a nice quote about this:
In investing, just as in baseball, to put runs on the scoreboard one must watch the playing field, not the scoreboard.
In other words, it's what your companies are doing that counts, not their share price. If they are doing well on the pitch, then the scoreboard will follow.
Market dislocations such as we are currently experiencing do bring harm to investors, in the following two major ways:
1. Forced sellers
Those who have used leverage are particularly vulnerable in times such as this.
If the leverage is long-term and can't be called in by the lender (e.g. mortgage debt), then leveraged investors have a better chance of survival.
If the leverage is in some form of a margin loan, then market volatility can quickly wipe out accounts, unless bets have been sized appropriately.
I actually consider this to be a cardinal sin, when it comes to investing. It might be the worst mistake that an investor can make.
What's so disastrous about it is that the losses it brings are permanent. They can't be recovered, except through starting again and investing with fresh money.
Forced sales are to be avoided at all costs, in my view.
2. Excessive trading
This is a less serious problem than forced selling, and you may disagree with me on this point. But I do consider excessive trading to be a real problem for investors, and a drag on returns.
There are some examples of investors who timed the market spectacularly well, and whose trading served them. I think Leon Boros falls into this category: selling out of the stock market before the 2008 crash.
But for every Leon Boros who sells out in advance of a market crash, I think there are far more people who sell out, and then miss the subsequent recovery.
Beating the market is very hard, and I think that beating it is even harder if you're not participating in it sometimes, and if your transaction fees are multiplying thanks to huge trading activity.
Of course this isn't advice. This is just a point of view.
"I couldn't resist"
One trade which the recent market movements did trigger me into making was a long position in the FTSE Index, using a put option.
I did this on Monday, when the FTSE was at 7180. I had good data for all my FTSE trading activity from last year, and the pricing on Monday was back around the levels which I traded before several times, and made money from each time.
So far, this trade hasn't done anything for me yet (this is an understatement). The FTSE is at 6540, so it's down by 640 points.
But the option doesn't expire until September this year, and my breakeven level is 6420, i.e. I won't lose any money from the trade unless the FTSE is below 6420 in September. And if the FTSE is below 6420 in September, I intend to fill my boots with UK equities.
What's crucial about this trade is that I again traded in very small size. Being greedy with leverage is the root of so much disaster in life and in the stock market. On the other hand, taking small regular profits over a long period of time is an honourable way to make money, in my view.
All of that having been said, I can't deny that there are real psychological reasons for people to behave the way that they do. I'd be lying if I said that I didn't get a kick out of participating in the movements of the FTSE, or taking big-sized positions in the companies I admire.
The trick is to stay in control, and stick to your plan, regardless of what the market throws at you.
Right, on with company news...
Versarien (LON:VRS)
- Share price: 39p (unch.)
- No. of shares: 154 million
- Market cap: £60 million
Paul seems to have missed Tuesday's bombshell announcement from Versarien, which is a market-leading supplier of RNS announcements to the London Stock Exchange.
Or is it?
According to Tuesday's announcement:
Going forward, the Company intends to use its interim and full year results announcements to provide updates on the status of various collaborations and will not make announcements between these unless a disclosure obligation arises.
But if it doesn't make lots of announcements, what exactly will the point of the company be?
It turns out the VRS was only teasing us. Today we are reassured that content will continue to flow, albeit in the form of web presentations and "Q&A" rather than RNS announcements:
Versarien has adopted a new communications platform called Investor Meet Company... Through live, interactive presentations, as part of the investor roadshow, all investors can now have the same opportunity for two-way engagement regardless of the number of shares they own or where they are located so they can come to an informed decision about the Company.
Alongside the published Q&A from the live presentations on the Investor Meet Company platform, the Company will seek to publish a Q&A each month addressing these shareholder questions...
My view
I was worried for a day or two, but today's announcement is very comforting. Versarien will continue to publish lots and lots of material for investors to consume. At the end of the day, that is what matters.
Foxtons (LON:FOXT)
- Share price: 74.75p (-5%)
- No. of shares: 275 million
- Market cap: £206 million
As flagged by Paul last month, Foxtons is trading "around breakeven, in lousy market conditions".
The statutory pre-tax loss for 2019 is actually £8.8 million, so there's a bit of work to do, to get back to breakeven on a statutory basis.
We are presented with a pick-n-mix of earnings measures.
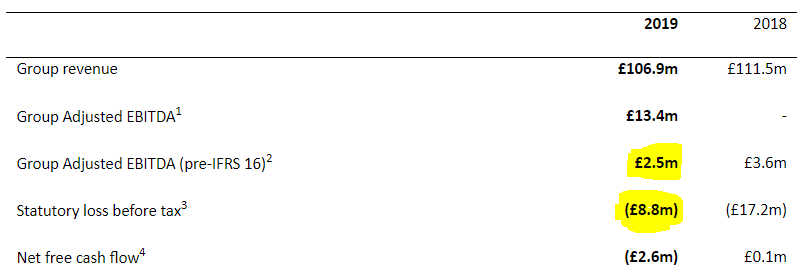
I tend to look immediately for the statutory result. Companies earnings statutory profits are what I'm looking for.
If you're in a forgiving mood, the pre-IFRS 16 adjusted EBITDA might also be worth a look.
But like Paul, I can categorically rule out using adjusted EBITDA in a post-IFRS 16 world. The £13.4 million number shown above is meaningless.
In this particular instance, net free cash flow offers a halfway house between the two measures. In both 2018 and 2019, it's not too far off breakeven.
Key points:
- lettings revenue down 2% (hurt by the tenant fee ban) (£65.7 million).
- sales revenue down 10% (£32.6 million).
- cash of £15.5 million, no borrowings.
I note that the decline in sales revenue was driven by a decline in units sold and a decline in revenue per sale. It's pretty hard to put a positive spin on that.
Market share did grow in both sales and lettings - but at the expense of pricing. Competitors increased their prices to landlords, in the wake of the tenant fee ban.
Dividend is still cancelled. Seems reasonable to keep cash in the company, for now, while it waits for a recovery in the London residential property market.
CEO comment - "pleased with our resilience in this prolonged downturn".
And regarding the future:
...with the uncertainty of the general election removed, early signs are that the sales market may improve during 2020. Our sales pipeline is currently ahead of last year, however we are well prepared for further challenging conditions in the sales market in the run up to Brexit and will continue to build our lettings business and manage our cost base in line with trading conditions.
My view
It's a very reasonable statement and a reasonable strategy. Foxtons is focusing on the more stable lettings business while it waits for the sales market to pick up.
It doesn't pass my quality filters (too labour-intensive, too hard to generate a competitive advantage). On the other hand, there is clear scope for recovery when the cycle turns.
If you are close to the London property market and can time this one, it could turn out to be a winner. But for most of us (myself included), timing its recovery is likely to be too difficult.
Novacyt SA (LON:NCYT)
- Share price: 148.5p (+29%)
- No. of shares: 37.8 million
- Market cap: £56 million
This is a clinical diagnostics company, dual-listed in London and Paris. You can find the French shares on Stockopedia here.
A few weeks ago, it announced that it was in the final stages of developing a test for the coronavirus, as a "research use only test".
It then announced that it had launched a "CE-Mark" test, which it said could be used by labs and hospitals without the need for further validation.
Today it releases a gangbusters statement:
- €1.1 million of sales so far from these Coronavirus tests.
- high levels of interest, and the value of customer quotations has grown "significantly".
- "in active discussions with representatives from a number of countries".
- "major distribution agreement" with a "global life sciences company", to supply two Asian countries (not China). This is forecast to generate sales of €2.5 million in the first six months.
- agreement with US healthcare group to manufacture and sell its research use only test.
- In contact with US FDA as it reviews the test for use in the US.
Excerpt from the CEO comment:
We believe the Primerdesign test remains among the quickest and most accurate tests available for COVID-19, as well as being stable for long distance shipping without the need for specialist cold-chain shipping. It is also designed to run on multiple molecular testing platforms commonly used around the world.
My view
This is beyond my area of expertise - I can't judge whether the Novacyt tests are superior to others already available.
I do think it's interesting that there is one company set to directly benefit from responding to the Coronavirus problem.
Stock market investors may feel desperately in need of a "hedge" against the spread of this disease, and NCYT shares promise to provide it, at least in the short-term.
Avation (LON:AVAP)
- Share price: 254p (-1%)
- No. of shares: 63 million
- Market cap: £159 million
This is an aircraft leasing company, based in Singapore.
As foreign jurisdictions go, Singapore is one of the safer ones (in my humble opinion).
Avation has been around for a long time, and has a good track record of building shareholder value.
It started a "formal sale process" last month, saying that it was in talks with someone about the potential sale of the company.
Today's update:
Since the date of the announcement, a number of parties have expressed interest in the Company and certain portfolios of aircraft. The strategic review and formal sale process is being undertaken in response to an unsolicited approach to purchase the Company. The purpose of the review is to establish what path would represent best value for shareholders.
They go on to say "Avation's value is above the net asset value of the company".
That NAV, for the record, is $4.29 per share.
At latest exchange rates, that is £3.33 per share.
Results - are excellent, boosted by the once-off $37 million recognition of value in aircraft purchase rights that it no longer needs, and will sell off in due course.
Excluding those gains, PBT is up 10%. Not bad.
My view
Over the long-term, Avation has earned a decent return on equity (high single digits or low double digits) and grown its NAV while also paying dividends to shareholders (current yield 3.8%).
On that simple basis, and on the assumption that aircraft leasing is likely to remain a stable business, I would therefore tend to agree with management. A share price closer to NAV would make more sense.
Vitec (LON:VTC)
- Share price: 832.8p (-9%)
- No. of shares: 45.6 million
- Market cap: £380 million
Purchase of shares by Executive Directors
This is a new one for me. It has been listed for a long time but escaped my attention until now.
Its products "typically attach to, or support, a camera" - supports, accessories, bags, power, etc.
The results are a bit uninspiring, as expected. It issued a profit warning in November.
Net debt increases to £96 million, but it would have fallen in the absence of IFRS 16 impacts. Fair enough.
Covid-19 - Vitec has employees in China and Italy. Together, China and Italy account for 9% of turnover.
Sites in these countries are open again, but there is still some everyday disruption, supply chain issues, and a reduction in demand. The current estimated hit to operating profit is up to £5 million - no big deal for a company of this size. Of course this estimate is subject to change.
Outlook
Order visibility is "limited", and the eventual impact of the Coronavirus is unknown. Based on H1 so far, Vitec expects the financial year to be "more H2 weighted than usual".
An H2-weighting can generally be interpreted as a semi-profit warning.
My view
I'm out of time for now. For what it's worth, my initial impressions of this company are pretty good. I'm tempted to say that it's heading into value territory at a P/E multiple of 10x. But I would need to study it in more detail, to be able to say that with any conviction.
The CEO and FD have bought some shares this morning, to try to show some conviction. They have not quite done so in the sort of size that would make me sit up and take notice.
For me, a Director purchase needs to be at least a month's pay, to be of any major significance.
Going to hang up my pen there as I've covered a lot of ground already and it's time for lunch.
Have a great weekend, everyone. I think we all deserve a rest.
Best regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Err, that's fine.
There was recent comment here about the financial problems at the family-run Cordant Group, and comparison was made with Staffline (LON:STAF) . I have received an e-mail telling me Cordant has just been taken over by Twenty20 Capital, a private equity crowd. Read into that what you will.
I think you can take some notice of director buying at Vitec (LON:VTC), Graham. The Chief Exec has just spent £128,000 on shares. I would hope that this is rather more than one month's salary, or else he is being overpaid for a company with a £380m market cap!
I checked his pay from the most recent annual report (2018).
And it was? Surely less than £1.5m per year?
I presume this is Stephen Bird you're on about. The annual report for 2018 shows the following for him:
Base Salary £451,758
Benefits £33,212
Pensions £90,352
Annual Bonus £377,925
Long Term Incentive £1,383,287
Total £2,336,534
And what about his "Expenses"?
Hi Graham,
Can i ask why you do a spread on an option on an index (i think thats what you are doing) rather than a cfd/spread against the index?
Both show real-time P&L so i just would like to know your thinking?
Thankyou
J
It's a bit complicated to explain but I prefer the flexibility in options. With options, I can decide which level I want an outright position at.
No need for any additional superlatives on selling .... In looking for "bargains" it is often wise to buy strength rather than bottom fishing the weakest. I've written a short note on my site with an interactive data report of indices, commodities and sectors/shares YTD.
Some notes below
only 89 Mid/Large Caps still in the Green in 2020 YTD.
There are 412 small caps still in the green YTD with the likes of Citigroup Q Ord (LON:CGP) (+160%), £EUA (+92%) £GFRD (+153%) and £SLP (+57%): the below are small caps over £100m
in terms of red, here's an overview YTD ....
I've posted an interactive report on my site which gives breakdowns by cap and individual sectors allowing customisable research
https://runprofits.com
Graham - based on the below - how much have you got invested on the stock market to the nearest 100K pls?
It is true that since December, I disposed of around 1/4 of my entire portfolio, to help fund a house purchase. Yesterday, I got rid of my tiny stake in Property Franchise (LON:TPFG), to help fund this purchase.
The rest of the sales took place in mid-January, long before the panic over the coronavirus.
So my share portfolio has not been reacting to this news.
.......excessive trading ..... a real problem for investors, and a drag on returns.
There are some examples of investors who timed the market spectacularly well, but there are far more people who sell out, and then miss the subsequent recovery.
... if the FTSE is below 6420 in September, I intend to fill my boots with UK equities.
What's crucial about this trade is that I traded in very small size. ... taking small regular profits over a long period of time is an honourable way to make money, in my view.
Well said.
To put some perspective on the present situation. All my largest positions are index shorts. Most are ETFs without leverage. Today and yesterday are good pay days for me. Nevertheless XUKS is lower than it was in Dec 2018 when I decided to hold for a bear market. The opposite happened! A hedge fund does the leverage for me and their results last year were terrible. The Central Banks financial engineering is suspect but....
Markets only crash downwards. However at some point there will be a 'dead cat' bounce, Gold was down yesterday. So reducing some positions seems prudent.
Avation (LON:AVAP), no thoughts on the results released this morning?
Great overview Graham. Sage advice if you pardon me borrowing from Warren Buffet.
I am convinced that the virus has been in the UK for a couple of weeks but has been dealt with normal remedial treatments without being picked up on as being on Chinese/E.Asian origin.
There were approx 4m people travelling from Hubei in China and probably also in Europe. I was in Europe during the Chinese New Year, and there were plenty of E Asian tourists. It is hard to imagine that places that were visited won't have impacted on their fellow tourists, many of whom will have been in the same transit terminals.
There have been plenty of responsible health warnings, which will hopefully slowed any spread down, but we can expect as the testing criteria is changed to be anyone suspected of symptoms, and not just having been in China, that more cases will discovered.
I suspect we are in for 2 to 3 weeks of media headlines, so expect this to impact on Stock Markets.
Graham, am I reading you right on Versarien that you are "comforted ". the shares are a hazard of note to put it mildly in my opinion. Are you sure?
Will Marsh
It seems you’ve misunderstood. Graham’s comments on Versarien were tongue in cheek. If you read his previous update on Versarien it will probably make you laugh. A joke Company (though some on other bbs seem oblivious). So you agree with Graham.
Re Versarien (LON:VRS)
To quote Dick Emery :
(Younger readers may need to consult google)
Avation (Avap) the aircraft leasing company issued remarkably good headline H1 results. PBT +218%. However this was the result of recognising gain on ATR options of $37m. Roughly $0.59 per share.
Stripping that out, results were pretty much in line with my expectations (and can anyone notice the two Thomas Cook aircraft repossessions? Got to look hard; something that PI's were saying would be a disaster for the company).
Previously most of the ATR options value were not included in the results as they were so far in the future that auditors disallowed them. Now, a portion of these are up for sale hence their valuation is now on the balance sheet.
The real reason/interest to be in AVAP now is the strategic review and I suspect AVAP included the ATR options valuation as part of that process and used the argument of selling 'some' of of them as an excuse to get them on the balance sheet. Nevertheless AVAP does have a history of selling the occasional option for a profit. So in summary I don't believe the inclusion of this asset is for nefarious reasons.
I would however question how they derived the actual valuation (Note 3 in the interims) as to whether they are worth that much. But that's a discussion for another day
They also outline additional hidden valuations in the company which I mentioned on TLF a few weeks ago. You may laugh at me but if a sale was to occur I see 500p or more. However the value is in the personnel so I still think a M&A is more likely. Either way best part of a 100% gain on the cards.
Have to remind yourself that aircraft leasing companies and associated financing looks long term.. Decades ahead.
As for COVID-19 I think you have to look at the type of aircraft they have etc . Basically mostly domestic flights. Small operators or government funded airlines practically speaking.
Previous shocks to the airline industry have been relatively short lived. Think 9/11 and Sara etc. However there are real survival implications for major international carriers and consolidation is likely. Does not really affect AVAP's customers though. Am not saying its impossible but I am saying the risk for Avap is low and if a few ATR's get repossed then remember a few are unencumbered and per aircraft loss of revenue is small.
Furthermore US Fed seem likely to reduce rates three times this year all of which reduces finance cost for Avation and makes an M&A even more attractive as they would have access to even cheaper finance than Avap could ever hope to get.
Potential downsides to me seem to be either credit rating agencies making life more difficult to raise fresh cash for future business or the company goes into private hands and a potential exodus of shareholders bringing the share price down as many current investors would not want to hold shares outside a trading exchange.
Undoubtedly there will be a lot more negative news regarding airlines over the rest of this year and AVAP share price very likely to be depressed as a result.
There is supposed to be a Roadshow to institutional investors about now regarding strategic review. It would therefore suggest to me that any positive corporate action will not be announced for perhaps another 4-6 weeks at the earliest. This would suggest to me that any new investors or those wanting to top up may find a better price this time next month.
Given current markets, I would prefer to be holding shares in companies with potential major corporate activities.
BTW. Web presentation later today by Avap. See their website for details.
I wouldn't laugh at you, Carcosa. I'd buy you a beer, as this is my third largest holding right now, I was hoping for a take-out at around 380p, and your 500p would make up for my hopeless performance on what used to be my largest position. I have read your previous, nicely considered, posts and also think it is well positioned to see out the COVID-19 episode for the reasons you describe. But will you really hold on for 500p? Did you listen to the webcast?
Hi Carcosa, great comment as always. Would it be fair to suggest that selling the options at a premium is a safe way of ensuring investors that repossessed planes are in high demand, therefore are likely to be taken up quite quickly?
thats the only recent concern I have regarding current conditions.
£Avap the aircraft leasing company issued remarkably good headline H1 results. PBT +218%. However this was the result of recognising gain on ATR options of $37m. Roughly $0.59 per share.
Stripping that out, results were pretty much in line with my expectations (and can anyone notice the two Thomas Cook aircraft repossessions? Got to look hard; something that PI's were saying would be a disaster for the company).
Previously most of the ATR options value were not included in the results as they were so far in the future that auditors disallowed them. Now, a portion of these are up for sale hence their valuation is now on the balance sheet.
The real reason/interest to be in AVAP now is the strategic review and I suspect AVAP included the ATR options valuation as part of that process and used the argument of selling 'some' of of them as an excuse to get them on the balance sheet. Nevertheless AVAP does have a history of selling the occasional option for a profit. So in summary I don't believe the inclusion of this asset is for nefarious reasons.
I would however question how they derived the actual valuation (Note 3 in the interims) as to whether they are worth that much. But that's a discussion for another day
Volvere (LON:VLE)
Fairly restrained price drop this week, likely due to the large amounts of cash on the balance sheet. So I took the opportunity to top up today at this lower price. Hopefully this asset price disruption gives them something to buy.
Morning Graham. I like the idea of buying a FTSE index call option, and wondered if you could recommend a company to buy these from. (Its going to be a fairly infrequent event for me).
I cannot recommend dabbling in options to anybody, as they carry an extreme risk of capital loss and should only be used by financial professionals.
I trade options using IG Group (LON:IGG), which I own shares in. G
I trade options using IG Group (LON:IGG), which I own shares in.
That's got to be one of the strangest hedges I've ever heard of :-)
Thanks for your soothing voice of sanity today. If you'd told me I'd be beating the All-share by 7% at the start of the year I would have expected to be happy and not quite the way I feel right now! A strange week. However, I am reminded of a Buffett saying:
"The stock market is a device for transferring money from the impatient to the patient."
All the best, Si
If you'd told me I'd be beating the All-share by 7% at the start of the year I would have expected to be happy and not quite the way I feel right now!
Which is, of course, an excellent way of viewing the situation. My portfolio is back to where it was last August, the current correction is just a blip so far, and is beginning to throw up some value - although some extremely overpriced stuff is now just very overpriced. But falls in H & T (LON:HAT) , Ig Group (LON:IGG) , Cmc Markets (LON:CMCX) and even Plus500 (LON:PLUS) look wrong. Ramsdens Holdings (LON:RFX) not so - a 50% fall in FX revenue would pretty much wipe out profits (I own all of those apart from Plus500).
If we end up with Covid-19 lockdowns in the UK you'd imagine it would impact anything that involves social gatherings - so airlines, hotels, travel companies. restaurants and probably most of the high street and their suppliers are at risk. As always in a downturn the key thing is to avoid total capital losses - balance sheets are critical and heavily indebted companies in those areas ought to be avoided, even if you're brave enough to try and trade the downturn. Even the survivors will take a hit - and in areas where they can be substituted by online competitors its likely to accelerate the move to digital so investing in those areas is very much a stockpicker's game.
Hans Rosling identified a flu pandemic as one of the five real threats we face and it's important to contain it, if only to prevent the economic issues that will follow if we don't. But as fear, uncertainty and doubt take hold it presents proper long-term investing possibilities. I'm hopeful we'll see 2008 style prices at some point - although hoping for quality companies on PERs of under 10 and yields of over 5% is probably a wee bit greedy :-)
The fat pitch may not be upon us, but if the current contagion of markets continue much longer it can't be far away ...
timarr
The fat pitch may not be upon us, but if the current contagion of markets continue much longer it can't be far away ...
Yep. In a low interest rate environment my yardstick would be Unilever (LON:ULVR) on a > 4% yield. That would tell me to go all in. How do you measure the fat pitch?
All the best, Si
Yep. In a low interest rate environment my yardstick would be Unilever (LON:ULVR) on a > 4% yield. That would tell me to go all in. How do you measure the fat pitch?
Hi Si
Not so far away then ... I keep track of a basket of companies but I also keep an eye on the drawdown of the FTSE 250. If that gets to 20% then I'm a net buyer but I'm greedy enough to want to see it down 30% before going all in. Currently only down about 12% since January so we have a way to go before I go all in.
Roughly we see that kind of fall about once a decade, and normally it takes about 2/3 years to see a full recovery. So, in general, there's no hurry ...
timarr
Hi Si
Not so far away then ... I keep track of a basket of companies but I also keep an eye on the drawdown of the FTSE 250. If that gets to 20% then I'm a net buyer but I'm greedy enough to want to see it down 30% before going all in. Currently only down about 12% since January so we have a way to go before I go all in.
Interesting. I'm down 5.4% on a total return basis. I'm not an income investor but I still find it comforting that even in such a bad week I've received £600 in dividends, mainly Ig Group (LON:IGG) . I've topped up a couple of positions today and will look to add some stuff on a daily basis for the next few weeks. Unilever (LON:ULVR) is only down about 4% YTD but when it tanks I think it's a pretty good indication that people are capitulating. Then I'm going to get fat! :-)
All the best, Si
Hi Timarr
I haven't done the maths, but as you say a substantial fall in FX revenue would certainly hit Ramsdens Holdings (LON:RFX) profits, which I also hold. On the plus side a strong gold price and sound balance sheet of £12m cash at the interims (about 40p per share) help. At some point the current apocalyptic view will lighten and share prices start to recover, how much damage will be inflicted in the meantime, no one knows.
I should have top sliced Ramsdens Holdings (LON:RFX) a few weeks ago, but too late now.
All the best
I should have top sliced Ramsdens Holdings (LON:RFX) a few weeks ago, but too late now.
IMO this is time to keep your hindsight glasses in their case and look forwards. If we'd all sold everything a few weeks ago we'd all be better off. There's no point beating yourself up about the past - nothing would've told you even this time last week we'd be where we are now!
When this virus is out of the way, people will still go on holiday. The bigger worry for Ramsdens Holdings (LON:RFX) is whether they will use cash rather some form of card or app rather than this short-term turbulence. In the current climate, there are companies in far worse shape than Ramsdens Holdings (LON:RFX)
All the best, Si
IMO this is time to keep your hindsight glasses in their case and look forwards. If we'd all sold everything a few weeks ago we'd all be better off. There's no point beating yourself up about the past - nothing would've told you even this time last week we'd be where we are now!
Absolutely correct.
In terms of Ramsdens Holdings (LON:RFX) there's no particular concern - the company is in good financial shape and the pawnbroking and gold components of value will likely do well in a downturn. My point was that the price fall is somewhat rational because of the near 40% of gross earnings from FX and that the read across to H & T (LON:HAT) isn't really valid, even though the two companies are often grouped together.
In terms of the future for Ramsdens Holdings (LON:RFX) - yes, increasingly we'll see people shifting to cards but Ramsden's particular customer demographic aren't likely to be big credit or debit card users. They already offer a prepaid Mastercard and adding an app isn't hard either so I doubt that will be a major impact in the near future.
timarrTimarr & Si
Regarding Ramsdens Holdings (LON:RFX) thanks for restoring a sense of perspective.
On the question of physical cash versus the use of cards/apps, my view is similar to Timarrs'. Ultimately there will be a commission/transaction cost that will accrue to the provider, so I don't think that the gradual migration from cash to cards will have a major impact on Ramsdens Holdings (LON:RFX) or £HAT.
All the best
On the question of physical cash versus the use of cards/apps, my view is similar to Timarrs'. Ultimately there will be a commission/transaction cost that will accrue to the provider, so I don't think that the gradual migration from cash to cards will have a major impact on Ramsdens Holdings (LON:RFX) or £HAT.
Yes, fair point. Quick anecdote... I was recently in Chile and Argentina and met a couple of Brits who were having untold problems with Fair Fx cards and the app. I think they got the problems sorted in the end but it's not the kind of hassle you want when you're trying to enjoy a holiday. Neither were impressed. In Argentina at least, nothing talks quite like a $50 or $100 bill :-)
Don't know about you but I'm off for a stiff drink or several in an hour or so...
All the best, Si
Thank you Graham
This is macro so look away now if you don't want it....plus perhaps a bit too crazy for some ;)
The most remarkable thing is that the dollar has weakened. Add to that I think the fall in yields for 10 treasuries (the safety asset) is predictable but unremarkable.
Obvs, we are not not rerunning 2008 and its fast systemic financial system / balance sheet crisis. But we are running a sharp panic. Simplest to call it a growth re-rating…and that is maybe an interesting thing to ponder…
US is where we have had western world growth. The rest of the world bar bits of Asia have struggled and been somewhat anaemic or choppy. US stock prices reflect this -> they are priced very high across the board as they are ‘safe’ and have sound economy.
UK and Europe much more modestly price arguably cheap. Market wisdom (of recent years particularly) says that UK and Europe catch a cold if US sneezes. Does that still hold? (beyond the grip of panic obvs). Note, that US budget deficit is out of control relative to UK/Europe…and a recession or at least short term emergency and extra counter measures are going to push it more negative.
Another US point, it is economically and politically much more dependent on its stock market. Capital gains and stock options contribute very meaningfully to tax take in US. A lack of them is widening the deficit. If the virus sustains impact the US faces a choice of 1) large tax hikes, 2) big spending cuts, or 3) very rapid increase in debt issuance to fund deficit. Obviously, 3 is what happens (both Trump and Dems will agree that).
Now normally during stress moments there’s a big safety bid for US assets and absorbing extra issuance is possible. That doesn’t seem to be the dynamic right now. Important to note that pre-COVID19 there already appeared to be a problem absorbing US debt issuance as shown by repo market stress and the Fed transacting massively in that market which effectively meant that the Fed was indirectly monetising Treasury issuance (even if this was unintentional byproduct its still important to see that this avenue is open). If US budget deficits grow and the RoW doesn’t rush to fund it (a la 2008/9) then they are going to monetise….the Fed might resist a bit but the politicians are ready to demand it.
The above means probably a systemically weak dollar in a crisis…it could be strong if Fed neglects to have funding open for global eurodollar markets but that seems unlikely as self-harm to have overseas financial collapses blowback into US through trade and balance sheets…everyone very well trained on fixing this problem given 2008-2012 (ie inc euro crisis).
Perhaps, just perhaps, the lack of extreme overvaluation in UK and Europe may begin to insulate a little bit from the US growth de-rating?
The production heart of the world is China. All the potential actions of the west will not hold back the tide and the tide will become a tsunami if China cannot re-float its production. Xi made it very clear on Sunday this week that this is no 1 priority and indications are that China is slowly normalising outside of still quarantined Hubei. Obvs this could fail if the virus establishes virulence around rest of China. However, China seems to recognise the rock and hard place of economic heart attack or epidemic and its choosing the latter risk. It could be that either fail as the regime itself falls…but its likely that people pull together in time of emergency (there is an underlying very high patriotism and sense of greater good).
Now I’m going to sound a bit crazy…what if we are seeing the end of dollar hegemony? Obviously we know that global trade and balance sheet flows need USD (or more accurately eurodollars) so we ain’t saying goodbye to the dollar as a global necessary currency. But if its weak and not a safe haven its systemic importance is very changed. What happens in its stead? Is perversely China looking strongest? Is this China’s moment? Like the 1920-40s when US and USD replaced UK and GBP through a period of much strife? There’s a problem with the Chinese Renminbi as its not open enough globally with only the linked HKD as an open window and HKD is too small. Well, thinking a bit crazy…could China make the HKD its currency? But still its not an open enough economy and faith of the world in the Party to honour HKD liabilities would be low and take a long time to build….but China does have the most gold in the world (not official holdings but across population) and is the biggest yearly producer as well. Could China have some form of gold backed RMB or HKD….a bit mad I know….but China does want to be kingpin and this may be the move. Overall, the world would welcome the leadership (with equivocations obvs)
I wont go into much detail on COVID19 itself but it seems to me that it is probably much more prevalent outside China than reported. Also, note that Hubei province where it ran amok for over a month has a population not far short of UK (and much more densely packed than us). The nos for infections and deaths are not nearly as bad as the imagined potential nos currently driving western markets down. I’m not saying don’t worry, I’m just saying that fact and feeling are not matching up yet.
Anyway, enough for now…back to watching the red
PS its quite likely that something meaningful or signalling meaningful will come out over weekend and probably quite globally coordinated.
Obvs, strong dollar financial contagion kicking in would maybe invalidate the above. This may be just what's about to happen?....in which case dust down your eurocrisis playbook too
Love this line: 'economic heart attack or epidemic'. This is the key decision for governments going forward.
HKD Hongkong dollar is officially linked to USD US dollar. Not going to look up the ratio but there is a band, not free floating.
I hold but have reduced in recent years over concerns like this; plus securities and 'wayfoong' gold certificates in Hongkong.
Nevertheless an interesting and thought provoking post.
Yes, I know. The link has been under duress for a while. China/HK would love a way to rejig....and China would prefer a strong currency as that deflates dollar liabilities and reduces the drag of some old and increasingly defunct export infrastructure. Plus they are very reliant on imports of resources so maintaining strength good. In the current dollar hegemony world that is proving super tough...
...opportunity for a move now...with some global support? Its not a forecast just thinking
Nice piece Mojomogoz but the Hong Kong Dollar is still pegged to the US dollar
Mentioning Hong Kong, theyre looking vulnerable and will be in a particularly bad position with a strong dollar
bellow video is a bit over done and out of date but interesting
Hello Ambrosia, I know Kyle Bass (a little from past)...he's been saying this for a long time. I met a spin out investment business from his about 8+ years ago and one of their funds was out of the money options on HKD breaking peg. That fund had a 5 years life before it burned thro their capital....which it must have done! I also know a HK based short seller (mainland Chinese so always amazed that he short sells) that has been betting on this for best part of a decade....
So, I am very well aware there is a peg...and that is partly my point...it served a purpose once for HK but not so much now particularly to fulfil Chinese desires of more fulsome integration.
In history pegs don't last when big stuff changes. I'm not saying its the end if USD hegemony...I'm not that mad....but it could look a bit like this
https://viewpoint.bnpparibas-a...
Thank you Graham for your sage words.
I have not been through anything like this before (I have been investing for about 8 years) and it is pretty scary but so far mentally containable. I had gone to about 10% cash before COVID19 because I was uneasy about valuations in the US market and any big sell off there causing a ripple effect over here. That 10% is now 13% (I sold a bit at the beginning of the week and the falls in my holdings). 4.5% in gold.
My other supposed “hedges” were Anglo Asian Mining (LON:AAZ) and £RRE. The former gold and the latter trading at below cash. These have not worked out and not only are they my largest fallers they are my largest holdings. Still I am not interested in the price the market attributes to them today (I am as certain as one can be in this game that the market is wrong) but what I think they will be valued at one, two or three years from now. Anglo Asian Mining (LON:AAZ) has been utterly destroyed over the past week.
Finally one of the columns I have to track my portfolio is percentage increase since December 12th (the GE) 11 of my holdings are still up one marginally down and three down 11% 16% and 17% (Arcontech (LON:ARC) Anglo Asian Mining (LON:AAZ) Rockrose Energy (LON:RRE)).
This might be a form of price anchoring? But for me at least it helps put some perspective on this week’s falls. That said in the month of February I am down 14%.
Have a good weekend.
Many thanks for the Versarien (LON:VRS) comments Graham!
On the same subject I think they could perhaps learn from the marketing campaign of Stella Artois, “Reassuringly Expensive”. But in Versarien’s case the strap line would be “Graphene so good nobody buys it”.
Maybe graphene is a snob good?
Hi Graham i note that Record (LON:REC) is down 25% this week. Do you have any idea why? I would have thought it would benefit from uncertainty, similar to IGG. Thanks
Good to see you have Avation (LON:AVAP) on the list. Good interims out this morning even without the huge boost from from an unrealised gain of c.$37mm from their purchase rights for ATR72's. There was also a huge jump in the tax bill to $7,015 mm from $ 0.583mm the year before. Is this a result of recognising the $37mm which is as yet unrealised? Also no mention of the impact of the 2 aircraft repossessed (and now re-leased to VietJet) or did the lease continue to be paid by Thomas Cook in the interim? I am a happy holder but keen to see the outcome of the strategic review and sale process. Tempted to have another nibble but haven't.
Graham
I share you view that going long of FTSE is not going to a bad call if this carnage continues much longer. I maybe naive but at some stage you need to call this as enough. Of course my history of timing is littered with a variety of calls on macro events but all the right things to stop this virus seem to be being taken and it is a loss if confidence driving this fear. Do others share my view? I am also a fan of Avon Rubber but not sure its products are likely to benefit?
It strikes me that there are a number of popular, cash generative shares that must be considering buy backs right now. I'm thinking of the likes of Anglo Asian Mining (LON:AAZ), Sylvania Platinum (LON:SLP), Rockrose Energy (LON:RRE), all of whom have large cash piles, pay big dividends, and could spend a small amount of money to increase long term value massively. Anglo Asian Mining (LON:AAZ), for example, has around $25m in cash and 114m shares in issue, so spending $6m could buy back at least 4m shares and increase long term rewards for shareholders by 3.5%. Sylvania Platinum (LON:SLP) could do similar: instead of the 16c that Liberum forecast for this years dividend, if they spent half of that on share buybacks they could reduce their shares in issue by 10-12%, boosting future returns.
If nothing else, it shows how cheap things are looking if you assume the end of the world isn't imminent.
Donald,
Sylvania Platinum (LON:SLP) has already announced that they propose to buy-back up to 12M shares and I would be happy that they brought back more whilst the basket metal price is soo high.
I have a concern that the UK is going to suffer further unwarranted downward corrections as the overinflated US market adjusts. A future buying opportunity for those with cash.
Alternatively, in the immortal words of Dan Ackroyd ( Trading Places the movie ) "Buy low, sell high,-Fear is the other guys problem!"
I had a look at Stockopedia's FT100 chart for 5 years. The RSI(14) is currently at 19.3. That's an extreme low (anything under 30 is considered oversold territory). It's difficult to tell exactly, but the only other time it was at this level was in 2018Q1. The market rebounded sharply after that.
Looking at the FT100 chart for 2018, I would say it recovered up to May and then there was a long decline until the end of the year, 2018 was not a good year. So I don’t agree with rebounded sharply.
That's right, January 2019 was awful.
Morning Graham
I would be interested in your thoughts on Vitec (LON:VTC) that released prelims this morning. The results were a little downbeat, perhaps as expected.. Like many companies there will be an impact, as yet not fully quantifiable from the Coranavirus, although credit to Vitec (LON:VTC) they have made a good go of doing so. Medium to long term I think that Vitec (LON:VTC) operates in an exciting market with good growth potential. In the short term the situation is less enticing.
I hold, albeit a smallish number of shares and will continue to do so. With few exceptions I see this as a time for buying rather than selling shares, but at present we have I think some way to go to the bottom of the market.
All the best
Hi Jonno, good suggestion - I'll add Vitec (LON:VTC) to the list. G
Rightmove (LON:RMV) results today. Hardly a smallcap but it does get covered here from time to time particularly in respect of its relation to Onthemarket (LON:OTMP) . These appear to show a marked decline in the number of agencies using their service but they are successfully squeezing the juice from those that have stayed. Revenues and underlying profit both up 8% at £289.3m & £219.7m respectively with ARPA up £83 to £1083 from a declining agency base of 16347 (this decline appears to be accelerating: 17328 last year and 17626 in 2017). Another metric that really caught my eye was the employee engagement figure which has consistently been over 90% since 2015 dropped to 81% in 2019. Still high but a worrying drop in morale for some reason. I still hold although considerably fewer than I held before my pre-emptive Covid-19 sell off.
Thanks John, I planned to cover Rightmove (LON:RMV) so will indeed say something on it. Thanks for sharing your thoughts on it. G
If you're looking for a distraction from these torrid markets, piworld have just published a charming interview with The China Dolls Investing Club:
https://www.piworld.co.uk/2020/02/28/the-china-dolls-investment-club/
The China Dolls were 'discovered' by The Share Centre, for their winning performance. They'd achieved a return of over 121% from 2010 to 2018, (it's since slipped back a little ... probably even more after this week!). They are a group of retired ladies in Bournemouth. Here, they share with us their club and what it means to them. It's a thoroughly engaging 40 minutes.
St James House (LON:SJH) Renold (LON:RNO) Gulf Marine Services (LON:GMS) McColl's Retail (LON:MCLS) Avon Rubber (LON:AVON) Foxtons (LON:FOXT) Benchmark Holdings (LON:BMK) SIMEC Atlantis Energy (LON:SAE) Novacyt SA (LON:NCYT), STM (LON:STM), Surface Transforms (LON:SCE)
St James House (SJH) trading: vague. "Working capital remains constrained and an area of focus, however the Board believes the improving operating performance will alleviate the position gradually." I note SJH offers "Banking As A Service". What the hell have I been using for 40 years then?
Renold (RNO) mkt still tough in H2. Covir-19: "Chinese factory has reopened, staffing levels are not yet fully recovered due to continuing limitations on the movement of employees. In addition, the extensive disruption and the limited visibility of third party supply chains into both the Chinese factory and our Australasian Chain business, means that there remains uncertainty as to the performance of these business units over the coming months."
Gulf Marine Services (GMS) another month's covenant waiver as it talks to lenders.
McColl's (MCLS) bank facilities have been amended and extended to May 2022.
Avon Rubber (AVON) wins $21m US defense order.
Foxtons (FOXT) FY. Outlook: "early signs are that the sales market may improve during 2020. Our sales pipeline is currently ahead of last year," I'm short.
Benchmark Holdings (BMK) Q1 rev-cont down 15% but guides FY in line. Covir-19 minimal impact so far.
SIMEC Atlantis Energy (SAE) CFO stands down but remains on board. He is thanked. Internal non-board appointed as CFO. Odd.
Novacyt (NCYT) covir-19 test sales going well.
In line: STM (LON:STM) Surface Transforms (LON:SCE)