Small Cap Value Report (Fri 30 Aug 2019) - SHOE, G4M, CLG, LGRS

Morning folks,
Today we have a profit warning from Shoe Zone (LON:SHOE) and an update from Gear4music that is in line with expectations. We also have results from Clipper Logistics (LON:CLG)
After that, I may look at a few stories that I missed earlier in the week.
Cheers
Graham
Shoe Zone (LON:SHOE)
- Share price: 134p (-30%)
- No. of shares: 50 million
- Market cap: £67 million
Board changes and trading update
The 30% fall in share price today looks reasonable after a dire update.
The CEO has tendered his resignation, "in order to leave Shoe Zone and pursue other business interests". He leaves immediately.
I always hate seeing an abrupt departure like this. To me, it suggests that there was a falling out or some other sort of conflict at the top of the company. If you're leaving a company you care about, and if you've done a good job as CEO, why wouldn't some form of transition be arranged, some period of time in which the company can think about finding a replacement?
The two brothers who have managed Shoe Zone together for the past 20 years clearly feel that they are up to the task, and won't be seeking a replacement. Instead, one of the brothers returns to his original role as CEO, and the other will remain as COO.
Trading update - it's hardly a coincidence that the CEO is leaving on the same day as a nasty profit warning.
This year will be below expectations (not quantified).
The "tough high street trading environment" is blamed.
Shoe Zone stood out as a share which was seemingly immune to high street conditions. As a provider of very cheap footwear, some of us thought that its business would stay firm even as other retailers struggled. Now we know that this isn't quite true. Perhaps the declining footfall has finally started to take its toll?
There is a property writedown of £3.1 million, to £5.3 million. Freehold properties on the high street simply aren't worth what they used to be. The flipside of declining property values is that Shoe Zone is able to negotiate rent reductions at many stores.
Finally, there will be no special dividend this year. The special was worth 8p last year, 8p in 2016 and 6p in 2015.
The update ends on a positive note:
"While we therefore face a short-term impact on our balance sheet [due to the freehold property writedowns], we do not anticipate any change to our dividend policy, reflecting our confidence and excitement in the long-term growth opportunities through the Big Box roll-out, continued operational improvements and our multi-channel proposition."
My view
I summed up my views on this share back in October 2018 and to be honest, nothing has really changed since then.
It still looks like a clothes retailer that is capable of generating lots of cash (and paying it out to shareholders). The historical track record is excellent.
On the other hand, it probably still has little by way of an economic moat around it. It competes primarily on price, not on quality. As I said before, I doubt that the brand has any value.
So this share is primarily a bet on management, and they have done a good job in recent years. Dividends have been very healthy and impressive quality metrics have been achieved:
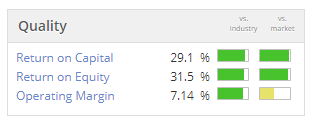
So where does it go from here? If forced to go long or short, I would go long of this one.
The two brothers at the top of the company own a huge chunk of the shares between them, and are highly motivated to make it work. So I would be inclined to bet that they will figure out a way to preserve value and restore earnings, over time. But of course this is not easy to predict. All I can say for sure is that they are highly incentivised to succeed!
Updated forecasts
It's a shame that the company didn't include any updated forecasts in this RNS - I don't see why it can't do this.
The broker Finncap has published a note on Research Tree, cutting this year's PBT forecast by 14% to £9.5 million.
And FY 2020 forecasts have been withdrawn, leaving investors without any official guidance for next year.
With a 14% cut in the official PBT forecast for the current year and suspension of next year's forecast, combined with the abrupt CEO change, a share price fall of 30% today seems fair.
Summary
Last night, Shoe Zone passed two stock screens for value on Stocko, and enjoyed a high Value Rank. It is even more "value" now, probably.
It doesn't tick enough of the qualitative boxes for me but I think this one should survive and could do well for patient shareholders.
Gear4music (LON:G4M)
- Share price: 199p (+6%)
- No. of shares: 21 million
- Market cap: £42 million
AGM Statement and Trading update
Very little info given in the AGM statement, but trading is in line with expectations.
"The specific actions that we have undertaken to improve gross margins and ensure that the Group is operationally robust ahead of our peak trading period continue to yield positive results. As such, we remain confident that the Group is well-positioned to grow revenue and improve profitability."
The share price rising 6% in response says that investors were braced for more bad news, in advance of this statement. Since there wasn't any bad news, we get a small relief rally.
The G4M chart has been a disaster on a 12-month view, down from 620p a year ago.
The two-year picture is also very rough for shareholders:
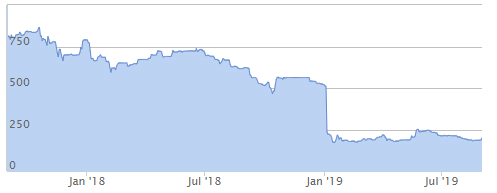
It's amazing what a change in sentiment can do.
Looking forward, the company is forecast to make EPS next year (FY March 2021) of about 11.7p. So we could see G4M "growing into" its valuation over the next two years, if all goes to plan. And if the market gets excited again, perhaps the shares can return to their former peaks?
My view
The StockRanks are cautious, giving it a score of just 35, and that's in the ballpark of where I would rate it, too. After producing a loss in FY 2019 and seeing its gross margin crumble, it still has a lot to prove.
Personally, I need to see G4M's own brand of instruments gain real traction.
Until then, it falls into the same category for me as AO World (LON:AO.), which is a share that I'd want to strongly avoid (though I acknowledge that G4M's gross margins are better than AO's).
Clipper Logistics (LON:CLG)
- Share price: 220p (+3%)
- No. of shares: 102 million
- Market cap: £224 million
Final results for year ended April 2019
We knew this was coming out, thanks to a trading update on Tuesday.
By the way, this was Clipper's deadline day for the results, wasn't it? Companies on the main market have four months to publish their annual report, and Clipper has done it in the nick of time.
Profit from logistics activities (i.e. excluding Clipper's property-related profits) increased by 18% to £17.1 million.
It mentions new contracts with PrettyLittleThing (owned by £BOO) and other "major multinational customers".
And among many other operational highlights, I see that it's doing a robotic trial for Superdry (LON:SDRY).
The outlook sounds good:
Recent contract wins, together with a strong pipeline of new business activity and the further evolution of our Click and Collect proposition, place the Group in an excellent position to achieve further growth both in the UK and internationally. Indeed, Clipper's approach of adopting a hands-on, long-term and pro-active relationship with its retail clients allows it to continue to support its clients during these changing retail market conditions, and the uncertain political and economic landscape.
The reference to an "uncertain political and economic landscape" is echoed here:
"We are conscious of the challenging market conditions facing UK retailers and the macroeconomic uncertainty within the UK economy; this may well have some impact in the year ahead, but we remain confident in our ability to continue the momentum in the business and are well-positioned to continue to deliver strong returns to our shareholders."
Fresh macroeconomic data was released this morning on consumer confidence, suggesting that the consumer is currently very weak.
What I find interesting is that it's not just physical retailers (e.g. Shoe Zone (LON:SHOE) ) who are finding it tough right now. The dour sentiment has spread to such an extent that even online retailers are potentially vulnerable.
Since Clipper is at the heart of the online trade, its performance might be a useful measure of activity in the sector. It reports today "some organic revenue decline with certain of our customers", but predicts organic growth in the current financial year "particularly with those customers in e-commerce who will benefit from market growth".
Overall, Clipper's positioning seems ok. E-commerce is still growing and taking market share from the high street, and that's where Clipper's services are key.
Net debt was £46 million at year end, driven primarily by "assets acquired on HP and finance contracts".
The overall result for the year was net income of £13.4 million, down from £14.3 million the prior year.
My view - no change to my stance on this one. It looks and sounds like a decent logistics company that is performing well. With net income forecast to increase to £21 million in the current financial year, it might offer value at current levels.
Loungers (LON:LGRS)
- Share price: 200p (-2%)
- No. of shares: 92.5 million
- Market cap: £185 milion
Final Results for the 52 weeks ended 21 April 2019
Two days ago, Lounders confirmed that it is trading in line with expectations and is "outperforming the wider hospitality market".
Eight new sites are open with the target being 25 for the full year.
The total number of sites now is 150+.
Adjusted EBITDA rolled in at £20.6 million, after excluding £8 million+ in depreciation expense.
My view
As Paul noted on Wednesday, many people focus on EBITDA for a stock like this.
While that is true, it's also true that a company isn't worth anything unless it generates positive free cash flow. EBITDA doesn't help us to understand cash generation.
For example, Loungers spent £18.6 million on capex in FY 2018, and then spent £22.6 million on capex in FY 2019.
This expenditure (i.e. cash outflow) was higher than its adjusted EBITDA in each respective year. Adjusted EBITDA was £16.6 million in FY 2018, and £20.6 million in FY 2019.
This doesn't prove that the company is a poor cash generator. To examine that, we need to think about how much of the capex spend in recent years was "maintenance" and how much of it was "growth".
The number of sites increased by something like 22% in FY 2018, and then increased by a further 21% in FY 2019.
It's safe to assume (and it's probably not too hard to find the precise answer) that several million pounds of capex in each of the last two years was growth capex. So on an underlying basis, looking at the core estate in each year, I don't doubt that the company is cash-generative.
But is it sufficiently cash-generative to deserve a valuation of nearly £200 million? I don't know. Each site is currently being valued at over £1 million.
A more fundamental question that I have over Loungers is its competitive positioning. It says that it offers "something for everyone regardless of age, demographic or gender". In other words, it wants everybody to visit. It's open all day. It competes with all other establishments for all types of business. To me, this sounds like a difficult way to make money - we shall see!
Signing off there for the week, but thank you for dropping by. Paul makes his return on Monday.
Have a fine weekend.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Shoe Zone (LON:SHOE)
I always get twitchy when a CEO suddenly departs. With recent events at other companies my first thought is always accounting "issues", but I would also expect (hope?) any suspicions of that nature to be announced at the same time as the departure. Time will tell.
Looked in yesterday's report for something on Amigo Holdings (LON:AMGO) but was wondering if anyone had opinions on it.
On paper, it looks extremely cheap relative to earnings.
Their operating cashflow does not stack up, with a large 'interest receivable' item making this negative. Is this an effect of booking profits on loan contracts issued before the loan is fully repaid?
I can understand that the rate of defaults may be set to increase, perhaps sharply so but unclear on how this may affect profits. From the share price reaction it seems that an increase of a few percent might be pretty bad for profits.
Amigo Holdings (LON:AMGO) is looking like a perfect storm - they're setting aside more cash as the number of customers in arrears rise and they're seeing a rise in customer complaints. A regulatory clampdown on guarantor loan companies is expected to arrive soon which will likely force them to focus on new customers rather than recycling existing ones - a more difficult and expensive proposition.
Far too hard to value. Another Woodford stock as well.
timarr
Snoo, Woodford is invested in Amigo - that should be enough of a red flag to avoid it like the plague! :)
On a more serious note be careful. "Cheap relative to earnings"? They made reference to regulatory changes/issues which are obviously going to result in lower earnings going forward.
Yes, that is a worrying sign. How could it all go wrong for Woodford, so many investments that seem to have no rationale at all, and concentrated in property.
One thing that is noticeable for me is how these guys (and Funding Circle) seem to have trendy head offices, seemingly staffed by casually dressed 20-somethings who can enjoy a bit of pool or table tennis while quaffing free beers after work.
Probably fine in the good times, in the bad times it'll be these people responsible chasing the increasing pile of defaults.
I have to agree, after reading a bit more it doesn't seem very good. Thanks for your (and timarr)'s input.
I would suggest with companies such as this, you are better of looking at the price to tangible book ratio as opposed to PE, and the company is at 1.4x per stocko (certainly not what I would call extremely cheap).
As a sub-prime lender one might argue a higher multiple to book since they get a more attractive return on their assets than vanilla banks and in theory carry less debt, but then again they do need to hold more capital for risky lending, so that higher income is held on the balance sheet as opposed to paid out.
In my simple brain, people who can actually afford to pay 50% of the principal in interest are unlikely to need to borrow, with or without a guarantee.
As far as accounting, not straightforward but will try and answer - please note I am simplifying the matter a lot:
they have to account for the interest on an accrual basis, ie a receivable (similarly any upfront fees are liabilities, released to P&L over the life of the loan),
I expect if customers are defaulting they will default on the interest and the loan principal, especially if interest at the end of year one represents 50% of the principal.
Loan losses will be charged to P&L - a deduction in profit and the hit will be accelerated since the entire amount will be written off, even though the asset was initially anticipated to be realised over several years (non cash item of course, but then again cash left the door and is not going to come back, so I would suggest it is a cash item).
Don't know about Amigo itself (beyond the ads) and what their impairment policies are, but anything at 3 months arrears, I would expect specific provisions / impairments against and then a general level of provisioning based on the economic cycle and their own history.
Cynical perhaps, but financials tend to be slow in recognising provisions / impairments, often because they are trying to sell loans / assets before buyers realise they are impaired (I know - that is so 2008) unless they are having a good year, in which case, it is nice to have something to write back and show how low your loan losses are in a downturn because you happen to be so good at analysing credit risk.
Wameja (LON:WJA) (formerly £ESG), released H1 results earlier this week, and a KPI update last week. The figures represent the historic business, the model changes going forward, with a large cost base removed and HomeSend being scalable.
Here's John Conoley the Exec Chairman giving an update on where they're at, and how he views the future.
A slightly wry smile from me when I saw the statement from Shoe Zone (LON:SHOE) this morning - commiserations to holders, it is not your pain I am smiling at.
I was discussing only yesterday my brief holding earlier in the year when I bought at 215p and sold a very few days later for a c. 7% loss. I was just about feeling vindicated when I discussed yesterday that despite the price rising in the meantime it was now back below my sell price. I am feeling much more vindicated now!!
Back at the end of May, Damian Cannon described his decision not to buy as a "lucky escape" I bet that feeling is somewhat reinforced now Damian? Luck or skill - its results that count!
Anyway I will leave comments on the trading element for now (I cannot add anything to Graham’s write up).
I just a have a bit of a thought on the write-down of freeholds.
The true economic value of the freeholds to the business as a going concern is related to the rent they would otherwise pay if they were leasing the property.
As rents have come in general, the “value” of these assets has therefore decreased.
In that sense I don’t really see these write-downs as a bad thing as such. Similar to when companies with a US presence had to write-down the value of the retained tax losses, because the payable/avoidable taxes had reduced.
On the other hand, this valuation should also be closely aligned to the capital they could raise in a Sale & Leaseback. That could be a negative.
At face value I would not see this business as cash constrained. I would note though that they have rundown their cash-pile via the special dividends, now suspended. If trading is really bad, those previous special dividends could end up looking reckless.
I have no idea what the freehold properties are, but the perhaps could be in an upside if they could be sold at a higher value with change of use planning consent. I wouldn’t want to count on that, but it might be an area for investigation if there were other attractions here.
In the short term though, I would look for a turn on their trading news-flow (and clarity on how big a miss this year will be) before considering a purchase.
"Back at the end of May, Damian Cannon described his decision not to buy as a "lucky escape" I bet that feeling is somewhat reinforced now Damian? Luck or skill - its results that count!"
Well remembered Gromley. Definitely some luck involved there...
I can't quite remember the name of the presenter who waxed lyrical about Shoe Zone (LON:SHOE) but it just goes to show that even the smartest investors can get things wrong.
On a side note I know that some private investors see illiquidity as somewhere smaller investors can gain an edge over institutional investors. I can understand the logic but this kind of situation gives me the willies. After all if I can't buy or sell easily, even with my small trade values, when market conditions are kind then just how bad will it be when conditions become unsettled?
Damian
I bought Shoe Zone only last Tuesday at 200 pence, I doubt if I was on my own and now feel somewaht chagrined. It was a toss up between that and United Carpets but had I gone the other way UCG might be next to drop 33%. It is a long game anyway unless you have a supercomputer and algorythms to match.
£G4M - I've said this before but I think it's worth repeating. G4M's products are something I've had a personal interest in for years. I don't buy music gear so much these days but I still browse for those 'fantasy' items I'll purchase when the time is right, of late this has been Midi Keyboards and Active Monitors (speakers).
When searching for prices on these items I started to include G4M along with my usual resources:
1. GAK (Guitar Amp Keyboard)
2. Amazon
3. Any other source as reference, could be Thomann.de, eBay or a London based Retailer
4. + G4M
I usually end up ruling £G4M out, it's products can be found anywhere else and it rarely seems to compete well on price. Sources 1 & 2 usually trump every time. So for that reason alone I'm not interested in G4M as a share holding, it has no discernible moat so it's buisness appears to hinge it's success as an online retailer that manages to capture a decent share of a popular market. But it's certainly not unique in it's offering.
To G4M's credit it has a large and comprehensive product range and it's website is well presented, it's easy to find what you're looking for.
It's unique offering is own brand products, these may sell well in the large and growing amateur market but these are cheaper items (not sure what their margin is). I imagine professional musicians will largely ignore these.
LeeWilliams. I think the “...2 usually trump everytime...” could allied to almost any product, with the exception possibly of clothing (I hold £BOO). Also if you want something that you are happy to have second hand or is a bit obscure then eBay.
I find shopping such an unpleasant experience (I have just spent a mind numbing hour wondering around B&Q) that using Amazon (unless you need it instantly) is just so much easier. And returns are a doddle.
For this reason anything bricks and mortar retail is un-investable for me.
Hopefully Clipper Logistics are moving vast and ever-growing amounts of Sosandar products...
The forecasts for G4M looks very challenging, but the AGM RNS says trading is expected to meet the Board's expectations. Does that mean they expect the consensus forecasts to be achieved?
The Treasury 2030 index linked gilt seems to be saying something about market inflation expectations.
Looking at Index Gilt price changes (or the real yield reciprocal) in isolation won't tell you about inflation. For this you should be looking at the "breakeven" inflation derived from its relationship with a Conventional Gilt as well. If the former is rising in price strongly, without similar moves in the latter, then you can be sure inflation is a driving factor. Moving together, or even lagging the latter, then it is a falling yield (or deflation) story you are witnessing in the main, despite Inflation Linked Gilts "showing" price rises.
SHOE: it is interesting to note that SHOE will be writing down the value of their freehold property £3.1m which is a third of their previous valuation. SHOE have depreciated their freehold properties. In effect, they are either saying the depreciation charged has been understated, or the market value is significantly lower than the carrying value.
Whilst it is stated there is no cash impact (which is true), there is a write-down in valuations to the effect that market valuations that could be achieved are significantly lower. Therefore, if the property was to be sold, then it would result in a cash impact.
There is also a wider point: investors will look at balance sheets for potential hidden value and one of these areas is within the Fixed Assets and property holdings. The market value has normally been assessed to be greater than the carrying value. However, with the excess capacity on high streets and pressure on rents, perhaps caution should be applied.
Reacher --- some good points there but the benefit of declining property values is that Shoe Zone (LON:SHOE) is effectively "short" property at the many sites it rents. Declining rents will flow through to the income statement over time.G
there is a Shoe Zone outlet near me on a small retail park ( they seem neither fish nor fowl I.e. not cheap nor obviously catering for the higher end) and the store nearly always empty . I have always thought the company seemed to be defying gravity with its outcome and whilst the yield looked good I had several reservations, so left alone. I agree that the write down in freeholds could be seen as a write across to retail values with the proviso that many are hardly in what I would see as ‘ quality’ locations. I commented previously in the value of retail property not having found the bottom yet and the write down here is an obvious example. I see Clark’s are also seeking rent reductions from Landlords so this may be yet another challenge from on line. In the light of the latter is poor trading at SZ actually a surprise?
Sounds just like Brantano................always empty when i purchased my £40 pair of shoes every 6 months..................now long gone...............although i can't see why anyone would buy shoes online...................surely you need to try them on ?!
I buy mine online regularly, if they don't fit just send them back, most retailers are fine with returns, it is probably cheaper than renting a premises.
once you find the brand you like, then it's just a reorder.
Interesting..................although i think that the 'returns' aspect for a lot of online companies will change in the future................
Hi Covkid
“the 'returns' aspect for a lot of online companies will change in the future”
Could you explain?
Thank you.
PS
As margins get squeezed the focus on costs will highlight what the cost of returns really is & whether it can be sustained. I think that most on-liners will start to either charge for or limit the amount of returns accepted.
There was a big fire in Whirlpool's trailer park yesterday, wouldn't have expected trailers to burn quite so fiercely. I don't suppose they were full of returns by any chance?
The renewables' acquisition - albeit related party, owned by CEO's wife! - at Parkmead (PMG) is interesting though I'm chiefly baffled as to how ever Stockopedia manages to rate it a 'super stock' based on PMG's overall financial profile!
I'm finding a lot of "superstocks" baffling, so many seem to have negative growth forecasts. I don't fancy investing in many of them at the moment.
herbie47: Aren't Superstocks Superstocks because they are up there? 'Way I see it the only way next is down, the question is when.
Do you mean share price? Well XLMedia (LON:XLM) is certainly not up there. Quite a few seem to struggling, only one in the top 10 that is of interest to me is Mission Marketing (LON:TMMG) but that is down about 25%. Yes I have feeling that some may well be going down soon. Note Shoe Zone (LON:SHOE) is superstock.
Clipper Logistics (LON:CLG) looks way more interesting than Shoe Zone (LON:SHOE).
With the growth, Clipper has a more attractive PEG.
First time I have looked at this company, so am currently reading through the report trying to figure out what is wrong with it*.
Please could you consider this one Graham ?
*Edit:
Current ratio =0.89
Trade receivables increased by 31%, compared with just 15% for revenue. ~£8.1 million past due date, up from £2.6million last year.
In an ideal world I would know more about accounting in order to figure out if the figures are acceptable for this type of business ! Still working at it.
Hi jonesj, thanks for pointing that one out. I will be taking a look. G
Weekend watching, here's the much awaited Part 2 of the interview with Lord Lee. This veteran of stock market investing, continues to impart his wisdom. The interview includes his reflections of stock market cycles, and some of the companies he’s buying into after his windfall from Tarsus.
If you missed it, here's Part 1. This interview covers his recent book, written for his grandchildren, with the hope they will follow in his footsteps: Yummi Yoghurt - A First Taste of Stock Market Investment! Plus, sage advice for all investors.
Enjoy the weekend!
Graham
Please will you cast an eye over the half year results from £EMIS ? I don't know what to make of them.
FREng, I appreciate the request as always but unfortunately this is above my market cap limit and is not a share I know much about. G
Shoe Zone (LON:SHOE)
Property write-down is a bit of an eye-opener:-
"The Board has also undertaken a review of its freehold property valuations and has concluded that it will be writing down the value of its 17 freehold properties by £3.1m to £5.3m."
The accounts at Sept 18 show these at a NBV of £7.7m - so the suggested revaluations are between 40% and 70% down.
Had been looking at Newriver Reit (LON:NRR) - I'll be pondering on that one a bit longer after today.
Phil
No positions
(P.S. - Shoe Zone may regret not putting any numbers to its profit warning)
I read that differently. I think the old value was £8.4m and the new value is £5.3m so a £3.1m or 37% write down. But I can see why you interpret it the way you do.
That’s still more than the 23.5% reduction in rents that they are achieving on renewals. I think I read that Next are targeting 30% reductions but I guess it’s a function of the starting point as well and Shoe Zone seem to occupy cheap sites on short leases anyway. So for them to get further big reductions isn’t a good sign for landlords.
I think the writedowns are on their freehold properties, so not impacted by rent reductions on their leasehold properties.
But it is the reason they give:
"The pressure on the retail property market has enabled Shoe Zone to achieve an average 23.5% fall in rents on renewal and average outstanding lease length of only two years. As a consequence of this and the tough freehold property market, our freehold assets had to be revalued to represent fair value and give us future flexibility."
There could be a read-across to other businesses operating from a mix of leasehold and freehold property, especially retail.
Shoe Zone (LON:SHOE) is going to be interesting, coupled with the CEO exit I can see a large fall today.
Longer-term I had a positive view of this company, although clearly it has reached maturity. Longer-term I still think these will turn out to be a good investment.
There is no real moat around their business, but it would not seem very lucrative for a new entrant to take them on.
Ownership structure is interesting, with the founders probably carrying more influence than the CEO anyway, probably apt that one of them steps up.
Hoping for a large discount today.
My morning smallcap tweet: SHOE down at heel, CEO runs for it
Jaywing (LON:JWNG), Shoe Zone (LON:SHOE)
Jaywing (JWNG) FT results delayed by up to a month as co negotiates funding with bank and shareholders. "Trading has improved since the end of June [when it was 'very weak'] but conditions remain challenging with client activity adversely impacted by the uncertain economic and political outlook."
Shoe Zone (SHOE) warns FY will be below its expectations. CEO resigns. He is thanked.