Small Cap Value Report (Fri 6 July 2018) - Carluccio's, FFX, IGP, IPX, Hipgnosis, CBOX

Good morning!
A slow start this morning.
I was out last night in Carluccio's in Dublin.
This restaurant chain has been in the news in recent months, as creditors agreed to a CVA. 30% of UK sites are closing while the rest will benefit from an investment programme. I have read that £10 million is being ploughed in by its majority owner, the Dubai-based Landmark Group.
Nothing was out of place last night, however - apart from a very loud fire alarm, which caused patrons to run for their lives (just kidding, nobody panicked).
It was a great value menu, very flavourful and authentic, reflecting well on this medium-sized chain sticking to its roots. I had olives, calamari and chicken saltimbocca. A large photograph of a romantic Italian town served as the backdrop to our seating.
It's a shame that so many restaurant chains are struggling, even those providing such an excellent service to customers. Reading around some commentary on Carluccio's closures, it's clear that the pain is also being keenly felt by smaller chains and independent restaurants who lack the resources of the larger groups.
Things will remain desperate until supply matches demand. There is no other solution that I can think of, apart from fewer restaurants. There are still too many empty chairs at empty tables.
The RNS wire is a bit quiet today.
I am planning to take a look at:
- FairFX (LON:FFX) - Half-Year Trading Statement
- Impax Asset Management (LON:IPX) - AUM Update
- Hipgnosis Songs Fund - Result of Issue
FairFX (LON:FFX)
- Share price: 129p (+13%)
- No. of shares: 155 million
- Market cap: £200 million
This is an international payments group, serving both retail and corporate customers. I last covered it at its full year results in April.
Foreign exchange is a gigantic industry and an exciting place for new entrants at the moment, due to the complacency of high street banks.
Banks know that most people won't shop around, so their rates tend to be uncompetitive.
More and more people are shopping around, however. Consider the increasing popularity of the services provided by pawnbrokers Ramsdens Holdings (LON:RFX) and H & T (LON:HAT) (in which I own shares), for example.
Targeting the both the consumer and the SME/corporate segments, FairFX has plenty of business to compete for.
Its pre-tax profit (PBT) was negligible last year. The hope for investors is that this year, top-line growth combined with fixed costs can lead to some scale efficiencies. Broker forecasts suggest that PBT could surge to £7.7 million.
Today's update is in line with expectations:
The strong first half gives the Board confidence that the Company will achieve market expectations for the full financial year.
Organic turnover growth comes in at 23%, led by growth in international payments (39%).
Including acquisitions, growth is 146%.
FairFX is combining its pre-existing FX capabilities with the digital banking offer from CardOne (which it acquired last year) to launch a range of new products for SMEs.
I continue to think that this looks interesting.
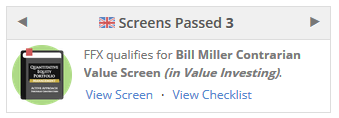
It passes a couple of momentum screens, including the Value Momentum Screen, while also passing Bill Miller's Contrarian Value Screen (you can find these below the chart on the StockReport).
So there looks to be a healthy dose of both value and momentum with this stock. A nice combination.
This section is written by Paul Scott (in response to reader requests). Paul owns shares in Intercede (IGP)
Intercede is "the leading specialist in digital identity, credential management and secure mobility."
Intercede (LON:IGP)
- Share price: 28p (unch.)
- No. of shares: 50.5 million
- Market cap: £14 million
Intercede (LON:IGP) is rather speculative, but the reasons I've picked up some shares personally are;
Quality of customers - outstandingly good, e.g. Governmental bodies around the world, major defence & healthcare companies, etc, including USA & M.East. If you can sell encryption technology to organisations like that, then these tend to act as reference sites, and can sometimes result in a snowballing effect on future sales. Clearly the company has an outstanding product, or it would not have won all these contracts.
New CEO - with a background in sales/marketing in IT. The company's focus seems to have previously been on product development. If the new CEO can turn that into rising revenues, then the operational gearing here could be exciting (as gross margin is 99.6%)
Cost-cutting - the recent results statement indicated that overheads had been slashed by £3m p.a. When you take into account R&D tax credits, I reckon this means the company is probably now at or near breakeven. Hence cash burn should (hopefully) no longer be a problem - but that's dependent on sales being maintained at a minimum of previous levels of around £9m. This excerpt from the 7 June 2018 results statement is the key bit, which is what induced me to buy the shares;
A cost-cutting exercise removed significant costs from the business without impacting operational capability. Intercede started the new financial year with an operating cost run rate that is more than 20% lower (approximately £3m per annum) than at this point last year.
Takeover potential - with a world-class product, and a market cap of only £15m, a larger IT group might decide to buy Intercede.
Cash - looked tight at £2.3m at last year-end of 31 Mar 2018, but rose to £4.7m as at 30 Apr 2018, after significant orders received.
Convertible loan notes - this is a bit of a nuisance. The company has c.£5m convertible loan notes in issue, which carry interest at 8%, so costly, at c.£400k p.a.. Interest is payable quarterly, so £100k per quarter cash outflow. The conversion price is 68.8125p, which is well above the current share price of 28.3p, so dilution on conversion doesn't look a problem. Final redemption date is 29 Dec 2021 - so not a problem for the time-being - the company has 3 years to come up with the money to redeem these loan notes (if they're not converted beforehand), and actually it currently has roughly that amount of cash on hand anyway. So this doesn't look like a problem to me - unless trading deteriorates, when it would become a problem.
Paul's opinion - the company has been a serial disappointer in the past, which is why the market cap is so low, at only £14m. However, the way I look at things, risk:reward looks asymmetric - in that the upside, if sales accelerate, could be very considerable - after all, this is a very sexy sector, and this company clearly has an outstanding product (evidenced by its major customers). It's possible to imagine that this could be a 5-10 bagger (£75-150m market cap) if sales accelerate (which has happened before - look at the chart), and drop through into decent profits. Obviously that upside case may not materialise though, and there have been false dawns in the past.
If the company does even half well, then a £14m market cap could potentially double or triple. There are lots of other far more speculative companies around, with nothing like this company's quality of customers, on higher market caps.
It all hinges on what progress (if any) is made on new contract wins. The recent newsflow has been good - with major contracts secured just after the 31 Mar 2018 year-end.
I'm inclined to sit tight for a year or two, and wait to see what newsflow emerges. It may work, or it may not, I don't know. It might have been more sensible to wait and see, then buy shares if & only if the newsflow is positive, and a chart breakout occurs (which would be the Minervini approach). Personally though, I tend to prefer buying ahead of the crowd, because that way there's plenty of liquidity, and I can get into a micro cap in decent size. The risk of my approach is that the company continues to under-perform, and it becomes difficult to impossible to exit, even at a lower price.
This one won't appeal to most people, as it's rather speculative.
Impax Asset Management (LON:IPX)
- Share price: 202.5p (-1%)
- No. of shares: 130 million
- Market cap: £264 million
A standard quarterly update from this environmentally-focused asset manager.
AuM are up 7% quarter-on-quarter for Q2 2018, to another all-time high.
The share price might be a little soft today as group net inflows fell to £200 million, not helped by a £100 million net outflow at its acquired US-based business.
It's the smallest inflow for Impax since Q3 2016, when AuM was only about a third of its present level.
So this update could be seen by some as a slight loss of momentum and raise a yellow flag about US progress.
On the other hand, it's only one quarter and inflows remained positive, so it's hardly the end of the world. The CEO refers to "a healthy pipeline of new business".
Market movements picked up the slack, raising AuM by over half a billion pounds. The overall AUM movement was from £11.0 billion to £11.75 billion.
As regular readers will now, I like the fund management sector and have written favourably about this company on many occasions. I remain open to the possibility of adding shares in this to my portfolio at some point in the future.
Hipgnosis Songs Fund
This fund has released a string of announcements since last year, when it first attempted to float. After several delays, the IPO was aborted.
Today, it announces that it has successfully raised just over £200 million in gross proceeds.
I am keen to figure out if this might be worth buying shares in, when it finally lists.
It plans to buy catalogues of songs containing "proven, evergreen Songs from award winning songwriters". It is hoping to get "more than 10 number 1 hit songs in the UK and US", from at least 8 songwriters.
Collecting royalties is not entirely straightforward these days, given the proliferation of illegal downloading.
The fund is obviously bullish on this point, seeing improved monetisation from legal streaming services (e.g. Spotify) and less piracy in emerging markets.
Compound returns
The basic concept sounds attractive to me. It comes down to the yields achieved and the safety of its portfolio in terms of its diversification.
Copyright lasts for 70 years after the death of the artist (in the UK). I suppose that's another important consideration - how long will be left on the catalogues of songs it purchases?
Not all of the fund's earnings will be distributed as dividend, so there is the potential for compound returns. Hipgnosis is targeting 10% per annum total return on NAV over the medium term, net of fees. That would be a fine result
There is a 182-page prospectus on its website, if you are at a loss for things to do this weekend!
Cake Box Holdings (LON:CBOX)
- Share price: 164p (+2%)
- No. of shares: 40 million
- Market cap: £66 million
This is a new issue, only listing on June 27. See announcement. Thanks to Edinburgh Investor for suggesting that we take a look. It's still too early for it to have any Stocko metrics.
No new money was raised at IPO. Existing shareholders sold about 3/8ths of the company at 108p.
It has generated a bit of a buzz, and its share price is now more than 50% higher than that Placing price.
What it does: egg-free cake shops! Some people don't want to eat eggs for religious reasons, while others are still free to enjoy and appreciate the taste of egg-free cakes.
It has a franchise model. Most revenues are derived from cake and sponge sales to franchisees. I like this model, as it is often associated with very high returns on capital.
I've been reading some research which suggests that Cake Box might earn about £3 million in net income during the current financial year. If that's true, the corresponding P/E ratio at the current share price is c. 22x. Not cheap, but understandable in the context of the rating attached to Patisserie Holdings (LON:CAKE).
All done for today, and for the week.
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Intercede (LON:IGP) looks like its going to break out.
Interesting spot, it has just about reached the high point from mid July - could do with more volume, worth watching tomorrow.
Cake Box Holdings (LON:CBOX)
FWIW I wrote a little piece about Cakebox here.
Hi Paul,
Don't worry Paul, I see nothing but total integrity & honesty with your input. Some of us recognize good character.
I'm just genuinely astonished at this stock moving so far on microscopic volume.
I suspect my portfolio is a fraction of the size of yours, but even I would not be interested in some of the small trades that apparently moved the price of this stock up so ffar.
Jeff
Sold out of FairFX (LON:FFX) at a tiny profit after looking at it and considering FX can only be a race to the bottom of decreasing margins really. And given I sold out of Ramsdens Holdings (LON:RFX) due to the strengths of transferwise...
Not sure where that leaves my SafeCharge International (LON:SCH) position, hmm...
[Incidentally, if anyone else wants to use Transferwise, they have a referral scheme where you get one free transfer & I get an incentive after 3 transfers. PM me if interested]... ;-p
Re: Intercede (LON:IGP)
Wow, how about that for the Paul Scott effect!
He posts about his investment case at 11.39am today and at 11.45 the SP starts moving up. At one point this afternoon it was 26% up, all before I had even started my research on them.
Have a great weekend, especially tomorrow afternoon. Perhaps if Paul comments about the bull case for England's footballers, great things will also happen for them (and us)...?
Cheers
Francis
The "Paul Scott effect" seems to be on quite tiny volume.
Paul's post is timed at 11:39.
There are approximately £25k worth of buy trades since then, spread over 15 trades.
Approx £24k worth of sells, over 4 trades..
Hi jonesj,
If your numbers are correct it’s a very good example of why price is so arbitrary, and probably why prices often make little sense, 26% movement on £25k is nuts.
Hi jonesj,
The big price move on Intercede (LON:IGP) on low volume, on Friday was nuts, I agree.
If the market makers see a flurry of buying in a micro cap, they just jack the price up, because usually they run a neutral book, so don't want to be short after a flurry of buys. It's a pity if people then buy on such a spike up in price, as more often than not, the price comes back down again within a few days.
I hate it when this type of thing happens - the last thing I want to do, is to move share prices with my comments. That just ends up causing grief for everyone - people accuse me of manipulating the price, and blame me when it drops back down again, leaving the eager beavers who bought the spike up out of pocket.
There's nothing I can do about this. If people want to rush in and buy things that I comment on, then there's nothing I can do to stop them. It just goes with the territory in small caps.
The one thing I can reassure on, is that I have never, and will never, post a positive comment about any company, and then sell into any subsequent spike. To me, I've always seen that as crossing a line. I know plenty of people who do exactly that, but it's a red line to me.
Also, these days my position sizes are too big to be able to trade in & out of micro caps, so I don't even try. All my micro cap positions are conviction buys, which I hold usually for at least 6 months, and usually for several years - as you can see from BMUS - which is a distilled version of my real portfolio small caps. Although holding period is dependent on newsflow - if something goes wrong, then it gets ditched - e.g. with one of my failures, recently Connect (LON:CNCT) .
Anyway, time will tell if IGP becomes a success or failure - it's all dependent on the company's ability to win increased (lumpy) sales - so it's clearly a speculative & high risk share.
Regards, Paul.
I'm really interested in Hipgnosis, it reminds me a little of Burford Capital. Investments in non traditional assets which shouldn't be affected by the market cycle, run by people with very credible backgrounds in the industry.
The promised 6.5% annual dividend as well as 10% NAV return looks good. I assume this is 10%, with 3.5% retained as capital instead of 16.5% total return? I also believe the affordability and quality of streaming services has completely disrupted illegal downloading. All my friends used to download songs illegally circa 2006, even as early as 2012 everyone I knew was signed up to some sort of subscription service when I was at uni. Admittedly this could be driven by age.
Never forget to consider the competition to FairFx.
After my supposedly mutual nationwide building society charged me 3% to transfer money to Singapore, I started shopping around for better deals.
I now use Transferwise, who charge me about 0.5% total (total loss measured against XE mid-market rate). The money can also be there within 30 minutes. [That's less time than it would take Jeremy Corbyn to get from Buckingham Palace to no 10, if thinking of scenarios where speed matters]
FairFX do not seem to offer transfers to Singapore, so that's loss of competitive edge #1.
If I transfer £10,000 to Euros, FairFX give me Eur 11,160
For the same transfer with Transferwise, I get Eur 11246, at the same point in time.
Loss of competitive edge #2.
I wouldn't use FairFX to move money. Why would anyone else ?
So, as an investment, where is their moat & competitive advantage ?
[Incidentally, if anyone else wants to use Transferwise, they have a referral scheme where you get one free transfer & I get an incentive after 3 transfers. PM me if interested]
BTW Transferwise is privately owned but Draper Esprit (LON:GROW) own a slice. It's an interesting service where the match bank transfer going in both directions - a bit like the gambling sites that match opposite bets. Works well but would only use it for small regular transactions. Increasingly small business are using it.
Hi HDO, interesting suggestion Draper Esprit (LON:GROW), interesting portfolio, thanks.
An FX company to also have a look at is Alpha FX (LON:AFX) , they are corporate fx brokers. Very strong SME management & this is an area the banks make a fortune but offer a poor & expensive service.
Hi Graham, I was interested in your positive experience in Carluccio's of Dublin. The branch in Durham that my wife and I visited was, on the other hand, awful - a very long way indeed from our expectations of the standard of food and service we would receive. I wonder whether other readers have had experiences more similar to yours or mine at this restaurant chain? If the latter, this could be another reason for the overall problems experienced by this company. Regards, Clive
I have not been to Carluccio's since they opened in my south midlands town some years ago. I thought it was over priced for what it was. Occasional glances at its menu in passing since has not indicated any change in the pricing. My wife visited with a friend for a coffee and a cake a year ago. The place was half empty but that did not stop a waitress putting a bill on the table unbidden. My wife resolved to never go there again
Carluccio has suffered by the owner not caring a s''t. Last time I was in, none of the staff was Italian, the food that was supposed to be fresh was at least yesterdays and when I challenged the staff on this, I was told that it was sent out from central processing and just got delayed by a day sometimes.... Booze prices hiked to up to try and make a profit out of the low levels of demand. I was with an Italian and as each dreary dish was presented it just got funnier and funnier to the point that we had to walk out. The staff kept interupting our meal with nonsense questions. It has lost its way and needs to be shot to leave space on the high street for sensible restaurants.
Many thanks Graham.
Here's the Impax Asset Management (LON:IPX) presentation from ShareSoc April
http://www.piworld.co.uk/2018/04/23/impax-asset-management-group-ipx-sharesoc-presentation-april-2018/
Quite a good overview of the fund.
Thanks for Ffs Graham. Anyone used FairFX (LON:FFX) 's cards? Any good? Bread4business are appalling - huge fx commissions & often declined.
As a side note, is this site misquoting FairFX (LON:FFX) revenue?
In their 2017 annual report "Gross value of currency transactions sold" is £937m but revenue is at £15.5m. I find it odd that the company exchanges "Gross value of currency transactions sold" with turnover in its statements.
Nice 'Les Mis' reference. You can have a like just for that alone Graham (the report is worthy of one too, thanks for the great work).
Matt
Thanks Matt, glad you noticed :)
Good morning,
Intercede (LON:IGP) is rather speculative, but the reasons I've picked up some shares personally are;
Quality of customers - outstandingly good, e.g. Governmental bodies around the world, major defence & healthcare companies, etc, including USA & M.East. If you can sell encryption technology to organisations like that, then these tend to act as reference sites, and can sometimes results in a snowballing effect on future sales. Clearly the company has an outstanding product, or it would not have won all these contracts.
New CEO - with a background in sales/marketing in IT. The company's focus seems to have previously been on product development. If the new CEO can turn that into rising revenues, then the operational gearing here could be exciting (as gross margin is 99.6%)
Cost-cutting - the recent results statement indicated that overheads had been slashed by £3m p.a. When you take into account R&D tax credits, I reckon this means the company is probably now at or near breakeven. Hence cash burn should (hopefully) no longer be a problem - but that's dependent on sales being maintained at a minimum of previous levels of around £9m. This excerpt from the 7 June 2018 results statement is the key bit, which is what induced me to buy the shares;
Takeover potential - with a world-class product, and a market cap of only £15m, a larger IT group might decide to buy Intercede.
Cash - looked tight at £2.3m at last year-end of 31 Mar 2018, but rose to £4.7m as at 30 Apr 2018, after significant orders received.
Convertible loan notes - this is a bit of a nuisance. The company has c.£5m convertible loan notes in issue, which carry interest at 8%, so costly, at c.£400k p.a.. Interest is payable quarterly, so £100k per quarter cash outflow. The conversion price is 68.8125p, which is well above the current share price of 28.3p, so dilution on conversion doesn't look a problem. Final redemption date is 29 Dec 2021 - so not a problem for the time-being - the company has 3 years to come up with the money to redeem these loan notes (if they're not converted beforehand), and actually it currently has roughly that amount of cash on hand anyway. So this doesn't look like a problem to me - unless trading deteriorates, when it would become a problem.
My opinion - the company has been a serial disappointer in the past, which is why the market cap is so low, at only £14m. However, the way I look at things, risk:reward looks asymmetric - in that the upside, if sales accelerate, could be very considerable - after all, this is a very sexy sector, and this company clearly has an outstanding product (evidenced by its major customers). It's possible to imagine that this could be a 5-10 bagger (£75-150m market cap) if sales accelerate (which has happened before - look at the chart), and drop through into decent profits. Obviously that upside case may not materialise though, and there have been false dawns in the past.
If the company does even half well, then a £14m market cap could potentially double or triple. There are lots of other far more speculative companies around, with nothing like this company's quality of customers, on higher market caps.
It all hinges on what progress (if any) is made on new contract wins. The recent newsflow has been good - with major contracts secured just after the 31 Mar 2018 year-end.
I'm inclined to sit tight for a year or two, and wait to see what newsflow emerges. It may work, or it may not, I don't know. It might have been more sensible to wait and see, then buy shares if & only if the newsflow is positive, and a chart breakout occurs (which would be the Minervini approach). Personally though, I tend to prefer buying ahead of the crowd, because that way there's plenty of liquidity, and I can get into a micro cap in decent size. The risk of my approach is that the company continues to under-perform, and it becomes difficult to impossible to exit, even at a lower price.
This one won't appeal to most people, as it's rather speculative.
Best wishes, Paul.
Paul - many thanks for the very full and helpful explanation.
Martyn
I notice Finncap have initiated coverage of Tracsis (LON:TRCS) with a target of 700p. Nice
I wonder if this explains the recent strength, even though it shouldn't?
It has crossed my mind whether Tracsis (LON:TRCS) might bear some responsibility for the recent problems with rail travel, schedules etc. Or alternatively, whether these problems might drive some customers to their door for help? Does anyone have any knowledge of their involvement?
Regarding Tracsis (LON:TRCS) sounds good that a broker is increasing the forecast price, but last month or so the price had already pushed to over £600, so I doubt this broker forecast has directly influenced this, but all good news helps buying sentiment, I guess.
Its quite an illiquid share with a fair spread on the price. This makes for some very sharp movements either way on the share price.
They did change broker this year, so may have been looking for more active institutional support?
They were reasonably positive in their last 1st half trading statement for the 2nd half, and I think their
year end is July. So hopefully something good to report in due course. I believe they did their year-end trading statement in August last year, and they tend to be fairly consistent.
Zoo Digital (LON:ZOO) Just posted the FY18 results presentation:
http://www.piworld.co.uk/2018/07/06/zoo-digital-group-zoo-preliminary-full-year-results-presentation-july-2018/
Very comprehensive overview. Great explanation how the convertible loan not affects the EPS. All sounds very positive.
Hi Graham
If its a quiet day it would be greet to get your views on Cake Box Holdings (LON:CBOX) Its a new issue, sells a niche product on the high street. It makes cakes without using eggs or something along those lines.
I have seen a lot of positive comments in the media.
EI
Hi EI, nice request re: Cake Box Holdings (LON:CBOX). I haven't looked into it in great detail yet but it sounds good. Thanks. G
Intercede (LON:IGP)
Looking at the IGP results on 7th June, it seems reasonably clear they have done the necessary and taken the Hatchet to their fixed cost base, so hopefully they will be much closed to being cashflow positive which would reduce the downside risk somewhat. I am guessing the upside here is probably potentially unlimited with the sexy (investor viewpoint) nature of their work.
I went straight to the outlook bit of this announcement and my positive thoughts towards this being a nice turnaround situation where somewhat dashed.
Outlook per the announcement
P1
Cyber-threats, whether driven by individuals, organizations or nation states are increasing in sophistication and the economic and reputational cost is growing exponentially. Intercede's MyID continues to enable our customers to eliminate reliance on the use of potentially insecure passwords for secure authentication. In doing so, they become increasingly resistant to social engineering and other cyber-attacks based on compromising employee (or end customer) login details.
Huh - i guess if you can't find something positive write any old crap to fill up some space.
P2
The investment in new formats and components of MyID puts Intercede in a strong position to provide the market with reliable Digital Trust. Intercede experienced a strong end to the financial year which included the receipt of a large US Federal Government license order on 28 March 2018. License orders relating to this deployment have historically been received every 12 months or so and therefore the revenue for the years ending 31 March 2019 and 2020 is particularly sensitive to the timing of future orders. Following reviews, the cost base has been brought back in line with future revenue forecasts and the Board are confident that Intercede will grow and return to profit within the next two years.
Ok it will take them 2 years (June 2020? -ye 2021?) to get back to profit possibly, if things go right. Nice to have such a top notch customer.
So are they just being very conservative here in what they say?, what about new business contracts are they not hopeful of signing some decent new clients in under 2 years ?- if they are it would have been nice to give some hope in this regard in the outlook statement. Hopefully the return to profit bit isn't akin to Tesla's ability to churn out Model 3's at 5k per week (one week only?)
Morning guys,
FairFX (LON:FFX) is certainly on the menu today.
News looks a bit dead apart from that.
G
FairFX (LON:FFX) also please. I looked very closely at this company and it ticked all the boxes for me but 1, and the most important one for me, their main product FX is always some way off the transferwise price, today FFX £100 = €110.6, Transferwise £100 = €111.8, a big difference and their customers are internet savy. I did get a detailed response from the COO but it didn’t really address the difference, different customers/value offering etc. All well and good but fx is the main driver for many fx customers.
So it sits on my maybe list so would appreciate other views.
From a Lynch perspective, the retail shop by Liverpool Street (that they have recently bought) always had massive ques, so fx for a lot is also convenience driven over price, however there was little competition for the city outlet.
Graham
If you have time, I would really welcome your view on the financial strength of Intercede (LON:IGP) which publlished its results on June 7. I'm interested in it because Paul Scott bought a small position for his fantasy portfolio BMUS yesterday and the Stockopedia computers clearly think he's bonkers! But we know him better than that ...
(If Paul is reading this then obviously I'd lbe grateful for any explanation you are willing to give of your reasons for the purchase, to help me to improve my own trading performance - which is far worse than yours!)
Hi FREng
You'll find Paul reviewed Intercede (LON:IGP) last in November 2017
https://www.stockopedia.com/content/small-cap-value-report-tue-7-nov-2017-trcs-igp-fevr-bltg-jpr-idea-ctp-upgs-237398/
I too take notice of Paul's BMUS buys and sells but amongst other things, I also look at signal pages like this http://www.ichimokutrader.com/ to help me decide when to buy a share. A reader here mentioned it a while ago and I've found it very helpful although it's taken me a while to get to grips with the system. For what it's worth, the signals here indicate caution as the price recently crossed below the Tenkan.
cheers
Francis
Thanks, Francis. Yes, I read Paul's November review. It's one reason why I'm interested in the thought processes that led him to change his mind about Intercede (LON:IGP) - especially as it's loss making and has negative book value.
Intercede (LON:IGP) is a turnaround play. They look to have a good product and impressive customers together with a new management team with strong CVs who seem to be doing the right things.
It’s the sort of interesting situation where I would want to know more than I do about the new management team before buying.
Third line support on FairFX (LON:FFX) please
TT
FairFX (LON:FFX) seconded, also Alliance Pharma (LON:APH) which is a Naked Trader favourite and has just got permission for a remodelled pregnancy anti-nausea drug. I bought starter positions in both this morning.
Morning Graham.
Seems rather quiet today so perhaps if you don't get too many requests you could revisit FairFX (LON:FFX) (I hold).
Trading Update is in-line and looks quite good if it can hit forecasts - I note your comment from your most recent coverage "I do think this is worth putting in the 'interesting / do more research' category. Important-sounding developments are taking place, in particular the new permission from Mastercard to issue its own cards".
Thanks, as always, for any valued comment.
Hey Matylda, thanks as always for your contributions & requests! FairFX (LON:FFX) was included. Cheers. G
Much appreciated comment Graham - Thanks - Have a great weekend Sir!
My morning smallcap tweet: Rev wilting warns WIL.
Wilmington (LON:WIL), Integumen (LON:SKIN), Bcre Brack Capital Real Estate Investments NV (LON:BCRE)
Wilmington (WIL) guids FY adj pretax broadly in line with market expectations. "This level of profitability has been achieved despite revenue being lower than previously expected at around £122m, with cost reduction actions offsetting the impact of the revenue shortfall. Certain of these actions were one-off in their nature and are not expected to benefit the current financial year." Guides this FY rev growth of low single digit % and profit down by high single digit %.
Integumen (SKIN) won't proceed with the reverse takeover of Cellulac. Instead discussing buying a minority stake in Cellulac. Shares still suspended.
Brack Capital Real Estate Investments (BCRE) proposes delisting then listing on Euronext Access. €2m max buyback. "In line with the revised strategic plan, the Company will consider distributions to shareholders, by way of share buyback, dividend or otherwise."