Small Cap Value Report (Fri 9 April 2021) - SRT, LGRS, NCYT

Good morning, it's Paul here with the SCVR for Friday.
Timing - with it being a quiet Friday, I'll take my time, and hope to finish by 1pm. Today's report is now finished.
StockSlam recording
These are quick fire shares investor evenings (online at present). If you missed it, here is the recording for the most recent one. They're good fun I think. Here is the video, let's see if I can embed it below...
.
Boohoo (LON:BOO)
(I hold)
Jack and I agree that BOO is cluttering up the comments in the SCVRs, and it's not a small cap any more, so we want to move it onto a separate thread. Here is the new BOO thread - where I comment on today's news re its warehousing update, pointing to strong growth. NB - please leave your comments about BOO on the new thread, not in the SCVRs any more. Many thanks.
Srt Marine Systems (LON:SRT)
31.75p (up 2% at 08:29) - mkt cap £53m
SRT Marine Systems PLC (SRT), a global provider of maritime surveillance, monitoring and management systems, today announces a trading update for the year ended 31 March 2021.
The Company expects to report revenues of approximately £8.2 million* and loss before tax of £5.8 million* with gross cash as at 31 March 2021 of £5.3 million*.
The asterisk says “subject to audit”.
Clearly another grim year. This is a stark statement -
… because of Covid lockdown related implementation delays, no invoice milestones were completed and thus no revenues recognised during the year.
That relates to new projects. Existing projects & sales of hardware generated the £8.2m revenues.
Funding - a CBILS loan of £2.5m was due for repayment in April 2021, but has been extended to quarterly repayments from July 2021 to April 2023, giving some breathing space on cashflow. Note the £5.3m quoted above is gross cash, so we would need to deduct the £2.5m CBILS loan from that, plus any other loans.
The interim results as at 30 Sept 2020 show the £2.5m bank loan, but also “Other loan” of £5.99m. This is a £10m secured loan note programme provided by LGB Corporate Finance. This is expensive debt, costing 8-10% p.a. interest cost. A covenant was breached on this loan, subsequently a waiver was provided by the lender.
Overall then the funding position is clearly precarious, and another equity fundraising is needed, in my opinion. Unless it can actually land some of the enormous pipeline of new orders that rarely actually materialise.
Jam tomorrow - as always with this company. The share price is supported by dangling the prospect of large contracts in front of us -
As of this statement, based upon customer guidance, we expect three of the Asian opportunities and one of the Middle East opportunities, with an aggregate value of approximately £71 million to commence during the first half, a further one in Asia worth approximately £14 million at the beginning of the second half, with the other two Middle East contracts , with an aggregate value of approximately £40 million, to commence later in the second half. The implementation and therefore revenue profile of each project differs, ranging from 9 months to 24 months to complete and therefore the revenues associated from these projects will be spread over a 24 calendar month period against delivered milestones…
We now have seven new system contracts worth a total of £125 million which are pending commencement as the respective countries relax restrictions and contracting processes catchup and normalise. Five worth £85 million are of primary short-term focus for us given customer guidance regarding their contracting processing status. These systems are vitally important to our customers and we maintain very close liaison with them whilst we both wait for the relevant government contracting agencies to normalise operations.
Diary date - 29 July 2021, for FY 03/2021 results.
Apology from management - this is a nice touch -
… to our shareholders who I know, like me, expected and hoped for a great financial result this year, but will today be disappointed. I am very sorry for this disappointment and would like to personally thank you for your support and patience which I expect to be rewarded in the coming year as our system customers are able to proceed as planned with the implementation of these essential systems."
My opinion - you can’t help but like, and believe, Simon Tucker, the immensely affable CEO of SRT. However, the reality is that this business has almost no visibility over sales even in normal times. Add covid lockdowns into the mix, and performance is almost random.
I’ve followed this company since it listed in 2005. Performance over that time has been highly erratic. It’s probably not the company’s fault, it’s the result of relying on Governments around the world moving at glacial speed to implement projects that are clearly not essential - if they were essential, they would be implemented with more vigour by customers.
The investment case here is always the same - look at the gigantic pipeline, if only a few of those contracts come off then profits will soar. The pipeline seems to get bigger & bigger, yet in 15 years we’ve never had a sustained breakthrough in revenues or profits - instead just seeing one-off bumper years occasionally.
To me that just doesn’t seem a very good investment case. I don’t want to invest in things where the result is essentially down to guesswork, and luck.
Plus it clearly needs another fundraising, and all that debt will need to be paid off at some stage. So perhaps a funding requirement of £10-20m, to add onto the £53m market cap, doesn’t exactly leap out at me as a bargain.
We’re in a bull market, where punters are happy to chase after jam tomorrow stocks. If that happens to coincide with some belated good news on contract implementations, then there could be upside here, who knows?
I’ve got absolutely no idea what is likely to happen, nor what the share price is likely to do.
The shareholder base looks very fragmented, with hardly any institutions over 3%, and management also only having small shareholdings.
.

Good luck to holders, but there’s too much guesswork here to interest me. I’d have a punt on it, if the market cap was say sub-£20m, with plenty of cash in the bank. But at £53m market cap, with net debt, and clearly needing another equity fundraising, then it’s not of interest.
I think today’s RNS is misleading, by quoting gross cash, and not net debt.
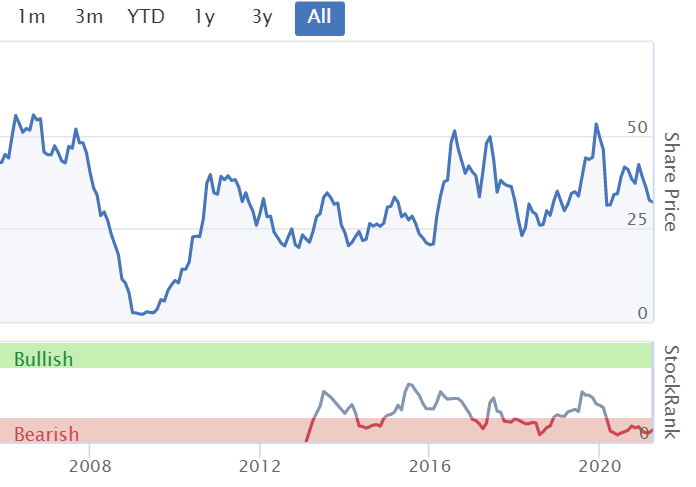
Looking back at the AIM admission document from 16 years ago, it floated with 69m shares in issue, at 35p. The share price today is slightly below that, and there are now 164m shares in issue, which actually isn’t too bad considering the company has never achieved a sustained breakthrough into profitability. Plenty of AIM shares are far more profligate in new share issuance.
.
.
Loungers (LON:LGRS)
(I hold)
262p (down 1.5%, at 10:43) - mkt cap £268m
There are hardly any trades printed so far today, so the price movement is irrelevant really.
This was a badly floated share - the broker just placed blocks of shares with institutions (thus earning big fees for doing the least amount of work), resulting in a concentrated shareholder register (see pie chart below), and hence terrible after-market liquidity.
.

.
Bank facility extension and re-opening update
Loungers, the operator of 168 neighbourhood café / bar / restaurants across England and Wales under the Lounge and Cosy Club brands…
Bank facility extended - to Oct 2022, total £25.0m Revolving Credit Facility (RCF).
Covenants waived/amended - enabling full resumption of new site roll-out programme.
Re-opening - 47 sites opening on Monday (12 April) for takeaway and outside trading. All sites (apart from Wales) should be open by 17 May.
New sites - 4 new sites opening by 26 May, taking total to 172.
We are approaching re-opening with enthusiasm and optimism, encouraged by how strongly the business traded last Summer and Autumn… We remain confident that Loungers is well-placed to emerge strongly as the country comes out of lockdown…
"We expect to trade well once the estate is fully re-opened, particularly with our strong coastal presence as we look forward to a summer of staycationing.
Judging from evidence about bookings for bars & restaurants that I've seen, I think we’re about to enter a bonanza for this sector in the coming months, but time will tell.
Roll-out - LGRS was a fast-expanding & successful roll-out prior to covid. This should be an excellent time to be opening new sites, as there are such attractive deals available from landlords -
We anticipate - and are ready to return to - a run-rate of 25 new site openings per year during the course of the year ending April 2022, assuming no further Covid interruptions. The pipeline of new sites is exceptionally strong and we continue to see a large number of attractive opportunities in the locations which we are targeting…
"The most recent lockdown has given us a real opportunity to build a fantastic pipeline of new sites in what is undoubtedly a tenant-friendly environment. We will approach the coming months cautiously but are very keen to get back to opening 25 sites a year at the earliest opportunity with such excellent properties being presented to us, and we are grateful to Santander and Bank of Ireland for their continued support."
My opinion - my sector expert who I consult from time to time has always said that LGRS is the pick of the bunch, in terms of operational excellence.
I bought a small amount for my SIPP about a year ago, but the lack of market liquidity in the share has put me off buying any more.
I’d say it’s almost a certainty that trading should be strong once the sites re-open.
The risk is obviously that covid rears its ugly head again in the autumn/winter, or worse still if a mutated form emerges that gets round the vaccines. Every investor has their own ideas on what the most likely outcome is, and that drives our decision-making. Nobody knows for certain.
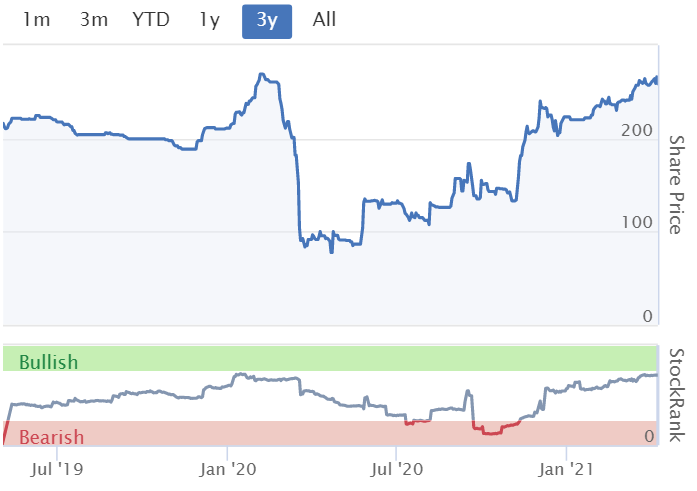
Maybe the share price has already factored in the upside from re-opening? Hence I’m not convinced that risk:reward is particularly attractive to buy any more at this stage.
.
.
** BREAKING NEWS **
Novacyt Sa (LON:NCYT)
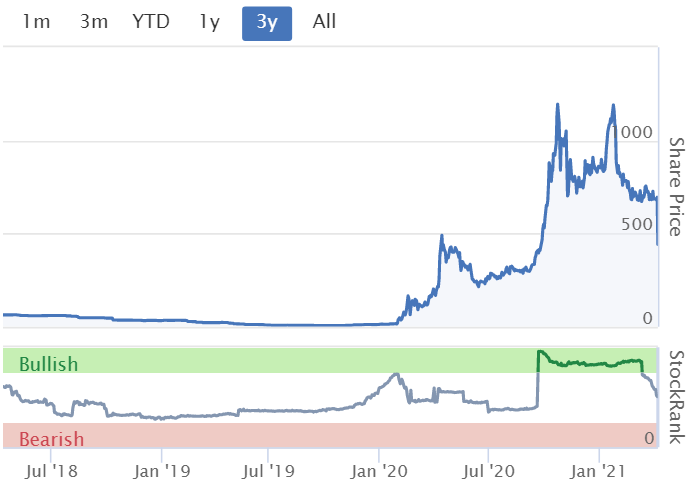
470p (down 32% at 12:53) - mkt cap £331m
Trading Update (profit warning)
Bad luck to holders here, of this covid testing bonanza company.
I’ve got the live price chart on my other screen, and it’s in freefall at the moment, hasn’t bounced at all, and in the time it’s taken me to write this, it’s dropped further to 455p.
What’s gone wrong? - a contract extension being negotiated with the UK Department of Health and Social Care (DHSC) has not been agreed. Worse, it is now in dispute -
Regrettably, the parties are now in dispute regarding the contract, which may have a material impact on Q4 2020 revenues. However, the Company has taken legal advice and believes it has strong grounds to assert its contractual rights.
Current trading - the DHSC contract was half of Q1 sales, so this issue looks very serious -
Novacyt delivered revenue for Q1 2021 of €83.0 million (£72.6 million). Approximately 50% of Q1 revenue was driven by sales to the DHSC, predominately PROmate™. The remaining c.50% of Q1 revenue was driven by continued growth of international sales and expansion of the Company's private sector testing operations…
Given the ever-changing nature of the COVID-19 pandemic and diagnostic testing demands, the Company continues to have limited visibility over future sales.
Profit warning for 2021 -
Whilst the Directors are confident new contract wins will continue as Novacyt expands international sales and into private sector testing, they believe revenue and profit for 2021 may be lower than current market expectations due to the absence of the DHSC contract extension.
Novacyt expects PROmate™ to continue to be rolled out in hospitals, private sector settings and international markets for the foreseeable future, although the Company believes that Q1 PROmate™ sales may be sufficient to support the NHS current roll out plans for the remainder of 2021.
Positive noises are made about new products in development.
My opinion - neutral. It’s a boom time company, which hit the jackpot with a covid testing product that has produced spectacular, but short term profits.
Today’s update sounds a serious one, given that the biggest customer has not extended its order, and is now in dispute with the company.
It’s anybody’s guess how this works out.
It’s a pity the update doesn’t tell us what the current cash position is. With the market cap now down to c.£330m, there could be an angle on this re cash & profits even at a reduced rate?
There are probably lots of spread bet punters in this share, who will have been stopped out by now, and could be scrambling to buy back in? Which may not necessarily be a good thing, given that the fundamentals have seriously deteriorated by the sounds of it.
There’s such a great concentration of risk here - a product dependent on a pandemic, lots of competing products being developed all the time, the pandemic itself is likely to have relatively short shelf life (we hope), and now the loss of the biggest customer by the looks of it.
How on earth do you put all that together to value the share? I’ve got no idea! It will be interesting to read subscriber views in the commments below, which is why I'm mentioning it, as I know there is considerable interest in this share in our community.
This is one for traders I think. Or it could be an interesting special situation if you’re able to accurately work out the cash position, and buy at a favourable price. It could be strongly profitable even after losing the biggest customer, who knows? Good luck whatever you decide.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

109 comments
Deffo not long dated Government ones Bob though a 1% increase on their rates would probably knock 10-15% off your portfolios value madness that long dated investment grade now higher risk than a global equity tracker fund.
I’m sure I’ve heard on numerous educations from Tom Bennett at Killik (ex Moneyweek editor) that the problem with market time is close clustering of worst and best days.
He’s cited a JP Morgan study a number of times (I don’t know the citation) which supposedly shows that the best days tend to happen immediately following the worst days, without there being a clear bottoming out stage before the resurgence happens.
He’s cited a JP Morgan study a number of times (I don’t know the citation) which supposedly shows that the best days tend to happen immediately following the worst days
Correct.
Overall, timing the market hurts returns through the worst and best days clustering together. This has been true historically and as Katherine showed even as recently as March, when the market was very volatile. Overall, the worst and best market days are just like rain and rainbows. Generally a rainbow appears only after a thunderstorm. While intentions to miss the rain are valid, we will likely miss the rainbow that follows.
https://am.jpmorgan.com/us/en/...
timarr
Ah...Friday night and all is well......Regular readers may recall the discussion on £TMO a couple of weeks ago. Very pleasing movement at present
Redde Northgate (LON:REDD) - I know Paul and others hold this share. It was announced this afternoon that Richard Griffiths, who is a very substantial investor based in Monaco, had increased his holding from 4.46% to 5.08%. This is good news for me as I have followed him into other profitable trades in the past. 5.08% of Redde Northgate is a good sized investment.
Novacyt Sa (LON:NCYT): The Novacyt Share Price is an interesting one and as Paul mentioned above, a tough one to value. The NHS contract provided a steady stream of income however the price paid by the NHS was much lower than any private market ask.
The UK Government is keen to move testing away from a centralised NHS offering to a private market as outlined in this recently released publication - Private COVID-19 testing validation - GOV.UK (www.gov.uk).
PCR vs LFT
PCR testing is here to stay due to two main characteristics: Accuracy & Variants. As quicker tests commonly referred to as Lateral Flow Tests become more popular, these will allow us to return to some sort of normality - mass testing. However these tests have faced a considerable backlash over accuracy and concerns around efficacy against specific variants. In settings where variant screening and accuracy are of paramount importance, PCR will continue to dominate. This includes hospitals, travel and care homes to name but a few.
Market Trends
Novacyt has placed a big bet on rapid PCR testing outside of the lab. Through the introduction of VersaLab, PROMate, Q-Machines, Rapid HT-PCR tests and VariPlex, Novacyt has produced a service that enables people to conduct a PCR test outside of a lab with results available in 60-90 minutes. This is quite simply an unrivalled user experience and means the company is well positioned to capitalise on a decentralised diagnostics market going forward. It is also important to remember that Novacyt have over 550 tests allowing individuals to test for far more than just COVID-19.
Unfortunately I think the COVID-19 pandemic is very similar to the way the market views technology trends. People over estimate the initial power of technology and significantly underestimate the power in the long term. In my opinion this can be applied to the pandemic: People overestimate how quickly it will subside and underestimate the longevity. Unfortunately as a result, testing could be here to stay for a significant period of time especially as variants continue to mutate as the virus comes under increasing pressure.
Financials
Based on 2020 figures and not taking into account the current DHSC dispute, Novacyt produced £277 million in revenue and £187 million EBITDA (margin of c.68%). EBITDA is then converted into cash at an 80% rate.
Using this ratio, revenue of £72 million in Q1 2021 gives an EBITDA of c.£48 million resulting in cash of c.£38 million. This would put Novacyt's cash position at an eye watering £130 million.
With the current market cap of £330 million, Novacyt would be valued at c.X2.5 cash position which seems incredibly cheap given the recent hiring spree, world class R&D, continued revenue production and consistent demand for their services. Sentiment is at an all time low with this stock however peers in the industry continue to be valued on X10 revenue as seen by recent M&A activity.
There are definite headwinds for the company to deal with and their PR strategy has resulted in a number of disgruntled shareholders, however very few companies in the world have a gold standard product, operate at 80% margins, are completely debt free and sit on c.£100 million cash.
Novacyt SA (LON:NCYT) - That's a bullet (hail of) some of us have dodged. What a scary price drop for those caught in loss or caught big!
The Novacyt Sa (LON:NCYT) rns was a disaster. It also was very instructive. The company had a fantastic run from a few pence to over £12 by being first on the scene. That was superb management. Having got there and making a fortune for investors, I sense they struggled somewhat to push on. They could have raised cash or used highly rated paper to buy in their sector. They did neither and as vaccinations increased at a significant rate, the share price fell away. The smart money sold at over £10 and cashed out of other Covid testing stocks such as the very poor £GDR I have a saying for this....all the way up the mountain, all the way down the other side. Very difficult to understand when to sell except with hindsight. FOMO kicks in I guess.
We do not know what the true cash position is. We do not know whether a lot of cash was spent on new products in anticipation of the new Government contract ....which failed to materialise. It might be that staff were hired in anticipation and the costs of all this will lead to a large write off. The World is currently awash with testing products. There is now pressure on price.
Either way, the bubble has burst for the moment. The share price closed at about the lows and without a lot more clarity I see little reason to buy (although at much lower I might be tempted by a trade). The Covid stocks have been fantastic for many of us (me included) but a profit warning is a profit warning
Bought Novacyt Sa (LON:NCYT) last week for a punt, then did not see any price action and moved on a few days ago....indeed missed a bullet ! Sorry for existing shareholders.
Hi Barnetpeter, you wrote:
"The Novacyt Sa (LON:NCYT) rns was a disaster...."
This article has a different view on Novacyt (which I hold):
https://www.powerof78.com/2021/04/11/ncyt-blackbird-investing/
I would be interested in other people's thoughts on these two alternative views.
Hi pka,
I know little about NCYT in truth , but citing that "article" - really?
I was tempted to rant on an extreme level about it, but perhaps that would be unfair - people should read it and make up their own minds.
But seriously, people need to test the 'arguments' being made in any article (to be generous they are shaky in this case) and also perhaps do a bit of due diligence on the author if there are any doubts about the logic of the article.
@BlackbirdInvest Appears to have been on Twitter since January & doesn't appear to have contributed anything to man-kind other than Uber positive views of NYCT.
So on balance I will retain my scepticism.
Off topic but
RIP HRH Prince Philip.
A great man, war hero, patriot, national treasure, sportsman, and spouse to HM The Queen.
What a sad day for the Royal family and nation.
$DOCU :DocuSign - Started buying this stock in early February as was impressed by the Tech and the growth in the business. The price at the time was on the up and bought mine at c. $256. The price plummeted to $192 in February and early March like all Tech and is now around $212 today and rising. Today for first time used DocuSign via email for Commercial Legal docs as work in the area of General Legal Counsel. Impressed with the ease of use but the signing pen use was poor but you can use two other options. This will take off as a Legal option once the "Solicitors" and Courts/Judges get their fingers out and come into the next century and accept that everything does not have to be paper based to believe it!!!!
The product is great and integrated with other systems. The SME I work for has just increased contract size and it is very sticky, we will never go back to life tech. I can't comment on valuation though.
Have got a small stake in $DOCU that I bought during the QQQ correction in March. It's used extensively by top tier law firms I I instruct (deputy general counsel) and agree I can't see there being a reversal of the trend.
Novacyt Sa (LON:NCYT) trading update:
"REVENUE AND PROFIT FOR 2021 MAY BE LOWER THAN CURRENT MARKET EXPECTATIONS DUE TO ABSENCE OF DHSC CONTRACT EXTENSION."
30% down at the moment...
Novacyt Sa (LON:NCYT) seems to be settling around 470p (not sure of the technical term). I hold and have just topped up to average down a little
"Novacyt Sa (LON:NCYT) seems to be settling around 470p (not sure of the technical term). I hold and have just topped up to average down a little"
I think I've had to use rounding down on many of my big winners ( Plus500 (LON:PLUS) EVRAZ (LON:EVR) XLMedia (LON:XLM) International Personal Finance (LON:IPF) ).
Some say this is a bad strategy,
If you are buying a quality and valuable stock after some short term bad news, you could potentially be setting up a great winning hand if the company later delivers.
The long term exposure gives one time to learn the idiosyncrasies, timings and behaviour of a stock, and you get to remember the StockReport card and metrics off by heart.
Good luck Mr Kevin101.
So I've lost a largish sum today on Novacyt Sa (LON:NCYT) but I have made a huge amount on the way up (I have held since Xmas 2019) and have luckily sliced as it went up so overall this share has been very positive for me.
It seems to have POTENTIALLY lost 50% of its revenue from UK, but still has great opportunity for overseas sales as it seems to be amongst the few "gold standard" PCR tests. It also has some diversification in other testing areas. So it remains very cash generative and we have not been told how much cash it has generated so far in 2020.......so where the price goes I am not sure - I suspect I will keep my holding for now (depending if there is a bounce).
What hurts is that I invested a small amount on my wife's ISA last year in NCYT so though it is only a loss of a few hundred pounds for her my life will not be worth living for a while!
I’ve got a wife like that, ignores the multi-baggers and points to the share that has lost a few pence that day!
But she still looks after me
Blimey! You mean you actually tell your wife what shares she owns/buys/sells?
Good job there's no thumbs down button any longer :0
She basically leaves it to me to choose the shares / funds she invests in.......and as soon as there is a gain (which there have been many over the last couple of years) she withdraws the gain. Not a long term investor!
Novacyt Sa (LON:NCYT) tanking
Paul comments on the price change of Loungers (LON:LGRS) 262p (down 1.5%) as being irrelevant. I would call it misleading.
The fact is that afaics the official spread was 252-266 from just after noon on Tuesday to close yesterday. Then TWO shares changed hands at 266p in the closing auction so that becomes the closing price as deemed by the LSE. Today the price has been 256 - 268 from open until 15 minutes ago. So the mid has risen from 259 to 262 so in my book the price is up 1.2% not down 1.5%. One or two shares in the closing auction often happens with small caps and I suspect that some of this may be blatant manipulation of the official closing price.
Stocko is now showing it as 168 +2 but that of course is due to using the last trade (being a buy) as the price. If the next is a sell at 256 it will suddenly change to -10. Grrrr.
This has happened to me getting a partial fill of a very few shares in the closing auction. In that case it was certainly not manipulation and is an expensive way to buy as you get charged for a virtually irrelevant trade. The cause is that there were only a few shares on offer during the close to partially fill my order.
No it could be a partial fill of an order, I had one share sold recently, at the price I wanted. It does happen on some platforms. I sometimes put in ambitious order prices, surprising when they get partially filled and my fees are low, so it does not matter that much, but some platforms don't do partial fill orders.
A great many thanks to those who provided the solution to my query about finding previous reports on SCVR. The suggestions worked like a dream, and the subsequent research turned out to be remarkably useful.
How lucky we are to have this wonderful resource of SCVR. Not only is it so useful, but it has a level of humanity that is quite rare in the digital world.
Apart from Paul's wisdom and dedication to helping us, he sets a splendid maverick tone. And provided the comments don't get too venomous, I greatly look forward to the occasional dust-up over Boohoo.
We are fortunate that discussion on Stocko has not yet become the preserve of the flamers and pedants that can inhabit discussion areas. Long may this continue.
Thanks nettle! You're one of my favourite subscribers now! ;-)
(my cheque is in the post)
Nettle can I ask that you share the solution for finding previous reports on SCVR please?
many thanks
Loungers (LON:LGRS) - I like to buy shares in companies whose products I like. We have been in one branch of Loungers near to where my son lives on several occasions. In normal times it was busy all day with a good choice of menu and drinks. I spent no time looking at accounts as I was just impressed by the business and the intention to grow. I don't know what sort of quantities Paul is interested in buying but I didn't find any difficulty in building up a holding by investing £5,000 at a time. Maybe the difficulty would be to sell everything quickly in the event of bad news but it is one I am very happy to hold at present.
It has a pretty wide 500bps avg spread according to Stocko.
Although liquidity seems OK? avg daily volume of 100k shares, £260k value. So if you only had say £20k-£50k in your portfolio, it should be relatively easy to sell if needed.
A solitary thought for all:
I was in a spin class, hot has hell, "eye of the tiger" and all of that, and as the final cool-down track began, the bloke next to me literally keeled over on his bike, legs still spinning even though he was passed out.
The bloke died in hospital. 40-50 something years old. No one, not even he, saw it coming.
Life is short. We are held together simply because blood and oxygen pumps through fragile pipe works without something leaking.
There is only now... and it can end in a blurred flash. And when its over, all these numbers, all the B.S. that bothers us day to day, is gone, and what's left is passed over to HMRC, loved ones, or those close to us.
Just broke a new all time high.
I think of the three folios I manage, my sisters and mine are now at or around highs, my mum's is still about 4% down from January 2020 (low point was July 2020 as I went back in, but obviously the wrong things as this is me we are talking about after all).
But a lovely moment today, I went round to give my mum's with the year end report as we go on tax year. Start with you never need to do a tax return again as everything is finally in ISA...I could kill her Financial Manager of 20 years...maximizing his own finances the beep, if anyone ever needs a recommendation for someone they do not like please let me know!
So yes you are down still from January 2020, but you are up from this time last year and back within 4%.
But the best part was being able to say that your folio is now structured so that your basic needs (including state pension) are now covered from the dividends from 50% of your investment
The other 50% is in "growth" shares to pay for the fun things in life, yes you are 79 this June and waiting to be able to book a flight to Australia to see your nieces again without 2 weeks in a hotel at either end, but it will be business class both ways with a 5* stop over wherever, thinking Singapore Airlines!
Sorry all very random
I hold, I sold, I am totally FOMO
Tommy
Well said @UK_Investor_8888
With it being a quiet Friday it has given me a little bit of time to do some thinking....
With the UK coming out of lockdown and some pubs are partially reopening next week, which is obviously good news for pub shares, it occurred to me that....
If the government was to put the vaccine into beer and immediately reopen all the pubs,
the whole country would be vaccinated within a week!!!
Just a thought :-)
Thanks for your write up of SRT Marine Systems (LON:SRT), Paul [I hold]. You state that it "clearly need[s] another equity fundraising". I disagree. £4.5m of non-revenue cash flowed in from projects in H2, with a further £5.7m due in the current financial year from existing projects. With the very substantial cash flows "expected" from the new projects over the next few years, it would be a great surprise to me if further equity was issued. The visibility of capital flows should make it relatively easy to raise debt to bridge any short-term capital issues.
Hi EC,
I'm not sure about that. It's all very well quoting cash inflows from customers of Srt Marine Systems (LON:SRT), but that ignores the operational cash burn.
Some figures from the H1 (6m to 30 Sept 2020) results below - as you can see, a huge reduction in receivables was mostly offset by a reduction in creditors - [course: note 6 of interim results]
.
Then if you look at the cashflow statement which links to this note above, it shows a cash outflow of £1.5m capitalised R&D in H1, and that the cash pile actually came from a £2m equity raise, and £3.5m drawdown on the loan facility. Hence how it ended up with a £5.0m gross cash pile at 30 Sept 2020.
Overall it's in a net debt position, with expensive 8-10% p.a. interest costs. And as I mentioned above in the main article, it breached a covenant on that, and was able to get a waiver.
So we have a loss-making, cash burning company, reliant on expensive debt, having breached a covenant. That is very far from a comfortable financial position.
Although I do take your point that if the huge orders do roll in, with cash up-front, then that would take the pressure off. If the repeated delays which have dogged the company in the past happen again, then I'd say another equity raise is looking very likely.
What terms would investors demand if the company had to put out the begging bowl yet again?
I'm just flagging the risks. You could be right that it might be able to manage without another placing, if things go well, but what if things don't go well? This share is quite risky you know.
Regards, Paul.
Thanks for your response, Paul. To add a bit more info, this is extracted from the finnCap broker note on SRT Marine Systems (LON:SRT) this morning:
Comfortable cash position
To set against the £8.5m debt, we have clear visibility on £15m of cash:
- From guidance we expect £5.7m cash from delivery of the existing system contracts in the year ahead and the Transceivers business should generate at least £4.0m of cash from its profits. With the current £5.3m, that is a total £15.0m cash from the existing business alone for this year.
We note that SRT will have invested in equipment for some of the pending projects as part of the preparation process, given the expected aggressive implementation schedules.In my view, this supports the argument that there is adequate cash plus visible cash flows to see the business through 2021 without a further equity raise. Of course, absent the new contracts, that position would change in 2022.
This remains, as you say, a high risk, "jam tomorow" share. What does seem to have changed in today's update is that management is now able to be much more specific about when they believe that jam will arrive and in what quantities. If they deliver, it is undervalued, if they don't, it is overvalued.
Thanks EC, good points.
If they deliver, it is undervalued, if they don't, it is overvalued.
Yes, I completely agree with your conclusion! :-)
Best wishes, Paul.
Excuse what is doubtless extreme ignorance . I want to look up Paul's words from the pulpit on a company, which he made a few months ago. Indeed I foresee that I may well want to do the same in the future. How do I do a search for these?
When on the company's Stockreport, click on the "Discussions" tab.
I usually start via the "Discussions" tab on the main stockreport page for a particular share I am looking at. This would typically list all the historical SCVR entries, however, as noted in the thread below, this is not 100% fool-proof as it relies on the epic being included in the title (I think). So if the author does not explicitly list it in the title, it will not be included in the search results ... nevertheless, it is usually a very good start I find.
Alternatively, one could of course go directly to https://www.stockopedia.com/co... and then just manually scan through the headings.
I don't see myself as ever being in a pulpit. More like propping up the bar, droning on about shares to anyone who'll listen! ;-)
Explains why the communion wine has gone missing!
Hi Berksbee,
Explains why the communion wine has gone missing!
Ha! Good one!! :-D
Which reminds me, in my latest delivery from Parsley Box (LON:MEAL) this week, I tried out a half bottle of Cabernet Sauvignon. It was bloody lovely! Seriously, one of the nicest mainstream red wines I've ever tried (am not a connoisseur I should emphasise).
I'm not comfortable with the valuation for a loss-making company , but there are aspects of MEAL's products which do intrigue me.
Regards, Paul.
nettle - as gwilli68 says, first port of call is the discussions tab on the SR. However, I see that like myself you have been here long enough to be able to use the old site. Be aware -the discussions list on that site has been appallingly maintained and using the discussions tab is one of the occasions when I use the new site. Take Boohoo, which Paul has started a special thread for today: if you look at the old site it has appeared in the SCVR twice since the beginning of last year - 14/1/20 (Paul) and 28/5/20 (Graham). Switch to the new site and you will find quite a few more!
Any Second Now for the Grand National. Nudge nudge, wink wink.
Here are my SCVR heat maps for today (prices as at ~9:45am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
I have added a MarCap category to the heat maps, along with a high spread indicator. The key to the symbol heat maps is now:
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
More than happy for Boohoo (LON:BOO) to have it's own thread - lots of us who got on this ship early appreciate ongoing commentary from the captain.
Is there though an argument for all shares to have their own thread and and comments anywhere that include the £ plus ticker automatically get copied to that shares discussion thread. Wouldn't that make searching for input on individual shares that much simpler.
It could well be me being stupid but I often vaguely remember some interesting comments on a share but can't remember where and searching the site seems very hit and miss. For example - I've just searched on the Discussion page for SAGA and come up with only 1 hit and that from a Graham Neary SCVR dated 19 June 2019.
Same search for BooHoo gives the top Discussion as again being a Graham Neary SCVR report from December 3 2019;
What am I doing wrong?
Hi Laughton.
In the absence of an effective Stocko search function for company comments that are not specifically tagged, I’ve found a reasonably effective way of finding relevant comments. Firstly, assuming you know the company you’re looking for, go to it’s Stock Report and look at the news flow. Identify when it has issued an earnings report or other newsworthy item from the headlines. Then look at the SCVR report for that particular date (there is an index for all of these under “Blogs” under the “Discuss” header). Trawl through the comments thread at the bottom of the article and you will often find what you’re looking for. As a general rule most company’s only get commented on when prompted by results or other significant news.
By no means fool proof - please can we have a decent Search Algo built into Stocko?
Gus.
I am not sure what is going wrong for you but if I go on to the stock reports for Boohoo or Saga and click on discussions I get a long list of SCVR's where they have been discussed. Perhaps something with your computer settings?
Hi Laughton,
Sounds like something is going wrong for you. If you go to the StockReport for any company, then click on "Discussion", it brings up all articles where the author tagged that company.
In the example you give, Saga (LON:SAGA) (I hold), this is what you should get when you follow the above simple procedure - a long list of all my (and others) articles on SAGA, providing we remembered to tag SAGA in the article. Sometimes the tags do disappear, and I might forget to put them back in, but that should be rare:
(the screenshot below is a clickable link to that page) -
Paul, that does not work on the old site, it does not select the more recent posts, ie in the last 18 months approx.
Hi Herbie 47,
Paul, that does not work on the old site, it does not select the more recent posts, ie in the last 18 months approx.
Ah, OK, I think we might have worked out what the problem is. I've been writing the SCVRs in the new site for maybe a year or two? So it looks like the old site doesn't pick up articles that I've written in the new site. Sorry about that.
I've just messaged Jack, so he can run it past the tech team next week, to see if they can suggest a solution.
Have a lovely weekend.
Best wishes, Paul.
One tip where the company is mentioned in the comments is to use the search facility built into your web browser. I use Chrome, CTL+F brings up the search box, I then input the ticker, hit return and can scroll through the comments.
A bit cumbersome but quicker than reading through all the comments if you know which shares you are researching.
I note you are using the old site, if you go to the new site, then it will locate the more recent posts.
I share your nervous sentiments, have taken some of my 2020 profits and parked them in less racy stuff. preference shares, tobacco, REITs, cheaper markets e.g. Jpmorgan Russian Securities (LON:JRS)
Hi Momoko
I had been increasing in British American Tobacco (LON:BATS) doing exactly what you had said of just going solid, sensible, profit making
Then JP Morgan through a brick at it! But still it is ok I can sleep and things will be ok
Tommy
British American Tobacco (LON:BATS)
SR87 Q80 V93 Magic Formula 98% Yield 7.76%
As much as I find their product distasteful, those metrics and that chart make it a pretty safe play compared to the peaky miners. Government and The Law permits British American Tobacco (LON:BATS) to trade. The Public voluntarily buy their products.
No 4 on my Magic Formula screen with the highest Value choice except for Lenta (LON:LNTA) .
Pesky miners on PE of 4-5. Magic Formula is 98% for Sylvania Platinum (LON:SLP) British American Tobacco (LON:BATS) may look good value but is loaded with debt and is almost bankrupt according to Stockopedia. Cigarette sales are falling as people switch to vaping. Why pay out such a large dividend when debt is so high?
Sorry, herbie ... maybe it's just getting late. But I honestley haven't a clue what you are trying to say.
Re British American Tobacco (LON:BATS)
Apart from the Altman-Z, how does Stocko show British American Tobacco (LON:BATS) as almost bankrupt?
Net Debt is reducing, Book Value and Cash is increasing. Dividend is covered 1.5x.
Although cigarettes kill end-users, the net population of the client base is rising. :-)
I still regret selling EVRAZ (LON:EVR) back in February... I had a really nice holding with safety... but it was necessary almost. I'll be back after my tax is paid.
alternatively, buy right and hold.
100 baggers!!
Chesnara (LON:CSN) I posted some detailed thoughts on the SCVR on the 12th Feb. re the share price being due a catch up and the research I had done re their solvency ratio still likely to be robust enough to still allow a 3% increase in the final div. with the numbers on the 30th March. That was duly delivered on the day and the shares went XD 14.29p yesterday. That will be a four figure sum coming into my account on the 24th May. Adjusting for the XD yesterday the shares were still a share price gainer on the day. All the shares I have accumulated are still showing a capital gain even on the XD share price. The thing I like about this one is that you can do your own research and it had been neglected but the market cap was still £400m plus so you could buy as many shares as you wanted. WheelieDealer prompted me to look at it and then looked at my research. Only a few investors took any notice (Peter Higgins, Tmjdr Rhmn, Tim Wheet, DH2, Harvey John, Privateer, Specter, McWall etc.) which did not disturb the share price. It still looks like they will increase the current year dividend by another 3%, so even after a bit of the share price catch up we have seen the shares are still likely to pay you 7.5% to hold them.
My morning smallcap tweet: Jam on radar for SRT. CEO scrapes it off with a knife
Gresham House Strategic (LON:GHS) Versarien (LON:VRS) Wameja (LON:WJA) Alpha Growth (LON:ALGW) Ramsdens Holdings (LON:RFX) FIH (LON:FIH) SRT Marine Systems (LON:SRT) Star Phoenix (LON:STA) Good Energy (LON:GOOD)
Gresham House Strategic (GHS) NAV at end March 1,515.4p/sh. [SP=1436.88 Cap=50m]
Versarien (VRS) £1.93m strategic investment at 45p (17% premium) by Graphene Lab, a South Korean based company specialising in chemical vapor deposition. Agreement to advance both Versarien's and Graphene Lab's proposed activities in South Korea. That Neill Ricketts is so persuasive. [SP=38.5 Cap=73m]
Wameja (WJA) Sunset Date for the Mastercard takeover extended to 24 May. No material change to the status of the Potential Indemnity Claims that are causing the holdup. [SP=NA Cap=NA]
Alpha Growth (ALGW) Black Oak Alpha Growth Fund AuM $25.5m. Co confident of strong growth prospects. [SP=NA Cap=NA]
Ramsdens (RFX) guides H1(Mar) 'resilient' with small loss but still cash positive. In line? [SP=NA Cap=NA]. I hold.
FIH (FIH) guides FY(Mar) breakeven. Falkland Islands operations traded well. [SP=NA Cap=NA]
SRT Marine Systems (SRT) guides FY(Mar) rev c. £8.2m, pretax -£5.8m. Lockdowns resulted in no systems invoice milestones completed and no revenues recognised during the year. Expected Middle East orders delayed. "Four system opportunities in Asia worth approximately £50 million have developed more rapidly than expected and are now pending their contract processing." CEO "very sorry for this disappointment". Again. [SP=NA Cap=NA]. I hold.
Star Phoenix (STA) to pursue arbitration proceedings re $10.2m bad debt. [SP=NA Cap=NA]
As its fun Friday I thought I'd go a little off small stock topic. What a week so far for me and I guess others as well. My portfolio is up nearly 6.5% this week and about 25% for year. At the moment I'm only 5% cash but am getting more and more nervous about the situation and have the internal conflict of not wanting to miss out but also not wanting to be fully invested when this goes pop, what's everyone else thinking /doing?
Sell sell sell
Buy buy buy
In case you thought I was being flippant, pleaase read my post to see why I posted the above
s now the right time to Buy Buy BUY ?
If you are 50% cash and 50% stocks, you can only be 50% wrong. - I am 33% cash currently.
I have just gone from 100% invested to 25% cash, but I needed to as I was holding a fair bit of US tech (all sold now) I think UK has some way to go yet, and the dilemma of holding too much cash with inflation around the corner is real
Morning Brookeda,
Sitting on 20% cash at the moment, like you had a cracking start to year!
Fearful this will not last much longer...
Cash/Stock split.This is always a dilemma but obviously depends very much on individual circumstances. I always try and have room to trade so my cash holding fluctuates quite a bit, generally average around 75% stock to 25% cash. always good to have available cash to invest. I like Edmund Shing's week end column. Really good ideas on sectors and vehicles to invest in ETFs etc. Obviously not too risk averse. How else can you make money? Jim Mellon is quite visionary. Read a lot, also remember too nobody is infallible.
100% stocks. But I do hold other investments that I could liquidate to provide cash if required. The whisky market keeps rising and I am considering taking skin out of the game there to provide more liquidity should I need cash - all current sentiment seems to be that markets will be bigger than they were pre covid - even the IMF have recently alluded to this.
I'm not saying a word in case I "jink" it:-
On paper (screens), I've made £100K and 10% in the past week or so.
(Full balance of new house sitting in cash.)
Few of us can predict the spasms, surges and droops of The Markets.
We are probably limited in our clairvoyance to the long term probability only.
UK_Investor_8888, you may not wish to jinx it, but you are regularly one of the exceptionally few posters that feels the need to boastfully declare your gains in £ value terms regardless... or at least that's the way you come across.
Nearly every other poster (plus SCVR authors etc) seems content and modest enough to detail % terms where appropriate for the thought process/rationale.
Shoe-horning in your personal £gains and £cash hoard sufficient for your new house is not necessary, rather it severely detracts from any of the interesting input you might otherwise make?
I’m up 30% or about 30 pence innit
Any insight into why an online broker cannot provide a live price to buy physical stock? I have found this recently with ACSO and ELCO. I can get a live price to sell but not to buy. Is this a sign of lack of liquidity, lack of stock available to buy or do the market makers remove the ability to buy off the electronic order book while large orders are being worked in the background? What’s the best way to buy physical stock in this scenario (other than open a position as a spread bet). Should I place a limit order, place a trade at ‘market best’ or phone them? I don’t have Level 2 access. Any advice appreciated.
I can buy accesso Technology (LON:ACSO) with IG at 715p. You could try reducing your order size, that may work or place a limited order.
Probably just a temporary issue.
Just put the order through with a limit price. The dealing desk will find the shares as long as the price doesn't move above your limit price. It happens to me with some shares.
maillot,
My advice would be to get Level2 , you will get the cost back in no time and it will help you understand a current market for a stock , it certainly helped me. It can help to alter the size of your order , up and down, persevere too because the market position changes regularly or place a limit order for all or maybe half of your requirment and try and buy the rest as a normal trade. It is not always a sign of a lack of liquidity but it can be in smaller Cap stocks.
Richard
I am similar, well up this week. Only about 7% cash, but I get the feeling there is a positive vibe at the moment with the country slowly getting back to normal. I have taken some profit from lockdown tech type stocks and switched to a few recovery stocks, and looking to ride it out for a while. After reading 100 Baggers, I do have a few that I intend to keep forever. Good luck to all, whatever you decide.
Hi Brookeda
I have also been fortunate this week., not to the tune of 6.5%, but good nevertheless. For what it is worth, I intend to do very little in terms of selling/buying, although I have added to one holding. I think that the recent success, which of course might be next week's disaster is due to the fact that my somewhat concentrated portfolio is focussed on UK small caps that are cash positive or have little debt and are in the main modestly rated, helped by the market commentary of rotation from growth to value.
I tend to remain fully invested and my portfolio like many was rescued by the arrival the vaccines, although in fairness, as is my approach I sold very little last year, but admit to some tinkering around the edges. My personal rules are:
To focus on the individual company, not the market and run one's winners, the caveat being that no one stock is allowed to exceed 10% of the portfolio.
To sell on a profit warning, although there the occasional exception, such as when Creightons (LON:CRL) issued a profit warning two years ago on the basis that it didn't have the capacity to meet demand and had to outsource production at increased costs.
To sell when the story has changed, or I got it wrong, or management does not do as it said it would. Regarding the latter, I sold Venture Life (LON:VLG) as I felt somewhat uncomfortable with the recent large fund raising, director selling and very large orders for a Chinese client. Also some four months on from the fund raise the mooted acquisitions are yet to materialise. I may off course be wrong on Venture Life (LON:VLG), time will tell.
Good luck in whatever you decide
"To focus on the individual company, not the market and run one's winners, the caveat being that no one stock is allowed to exceed 10% of the portfolio."
I am totally in breach of this rule.
The dilemma is when to cut the winners.
Its also a major problem selling large positions and getting the timing anywhere near right, and realising the imagined quote price.
At the moment, I am just holding everything with a "Joan of Arc" style delusion in my head saying "God has sent this, merci beaucoup".
However Stockopedia's dataset appears to be the instrument of The Almighty in what the numbers foretold. Thank Stockopedia!
Likewise but concerned about a possible retrenchment and so trying to hold a selection of uncorrelated assets that should do well in a downturn. Picked up some Begbies Traynor (LON:BEG) on their recent placing, hold both Manolete Partners (LON:MANO) and Litigation Capital Management (LON:LIT) whose business models I don't think are well understood and went into Alpha Growth (LON:ALGW) recently which is offers a most interesting investment proposition and has spiked up this morning on results.
As ever DYOR
Hi Brookeda,
I'm 4.3% cash and 15.3% up ytd, most of it in the last three days. I do look at some of my holdings and feel that their valuations are pushing it a bit now, but I have not been selling for two main reasons.
Firstly, I believe that most of my companies are approaching the post-COVID opportunity as leaner, more efficient businesses than they were pre-COVID, and anticipate seeing some real benefit from this in future numbers compared against historic numbers. I do not believe that these improvements are baked into market expectations yet.
Secondly, taking a longer term perspective, my portfolio has only this month moved ahead of its previous high in January 2020. My 12-month returns are spectacular, but my 14-month returns are poor and with that longer term view, my holdings do not seem over-valued.
Brookeda – thanks for raising this as it’s been on my mind too. We can be 100% certain there will be a crash sometime soon – we don’t know whether it’ll be 6 weeks or 6 years out however! The difficulty with a daily blog such as this, to which I am glued, is that one tends to get sucked into the noise, whereas what I’m really interested in is getting my pot to a meaningful size to convert to a steady income stream in retirement in maybe 7-10 years…..
Obv. Its all about risk / reward management and my approach is to have 3 pots – divided roughly equally into 1. small caps, 2. ITs (covering sectors I can’t research such as Asia small caps / biotech etc) & 3. since December reflation stocks such as banks, housebuilders & fund managers. I don’t shoot the lights out with this style, but it’s served me really well over the last 3 years since I started investing seriously & beaten Fundsmith which is my personal benchmark.
I have a rule that I always sell or top slice on a 10% pullback, which means I frequently sell my winners too early, but equally it’s got me out of some stinkers too. Luckily, I bought back in again in April last year. I hate seeing my hard-earned dosh going down, so really shouldn’t look every day and I do try and time the market by increasing cash when it feels toppy to me. Right now, I think there’s plenty left in the tank for the reflation stocks, commodities and sensibly priced quality small caps, but the highly rated mega growth stocks will continue to pause for breath due to the impact of higher inflation & growth rate assumptions. I’m enjoying William O Neill’s How to Make Money in Stocks: A Winning System In Good Times And Bad which has plenty to say about calling the top.
Would be really interested in other’s views.
TJ
Hi Jack, my rationale for doing this is exactly the same as yours but I'm 55 in 18 months time and completely unexpectedly I'm now near the lifetime limit and having to read up on 'benefit crystallisation events'. Hopefully you get that problem too! As I manage both mine and the wife's pension I need to start swapping risk from mine and move more into hers which has been quite averse for the last year or two. But what is risk? I left my small SIPP with just big divi ftse payers alone during the pandemic (which then elbowed/shrank divis anyway) and it took a year to get back to where it was. I was wildly trading my main sipp during this time full of all sorts of stuff and that lost 40% in Mar/April but was back above by end of June and has gone on to play a blinder for me. I know someone a lot older than me who went 100% cash in february 2020 but was so frozen with fear that they never went back in and so consequently have effectively lost a once in a decade/century/lifetime opportunity to make some serious money. I haven't got a clue what the right thing to do is but I know I'm not buying crypto, tesla or non-fungible artworks though.
With a much larger portfolio than usual, but many of the holdings with smaller stakes than usual, and with remarkable well over 90% of them profitable, and portfolio almost doubling from the nadir in March 2020, I’m creaming off some of the gains on many of them now. It raises significant cash but still leaves (sometimes a lot) more left than I originally invested.
I’m under no illusions. Unless totally incompetent it’s exceptionally easy to invest successfully in this market as even a lot of rubbish is going up, so anyone half competent should have a winning current portfolio. It can also make unskilled investors think they are very good. They’ll find out the reality when this fun bull market ends!
I’ve bought a few rubbish shares and fun punts like KR1 (tripled) that I would never even think about buying in normal times because they attract mug punters. But rather than cream off the profits from those I tend to sell while well ahead. And any I hold that don’t join in this bull market, or go wrong or issue iffy news I sell immediately. It’s pointless holding them when so much is doing so well.
Quality holdings and Investment Trusts I prefer to cream than sell. And big dividend payers I’ve held for years I tend not even to cream as long as news is good and dividend to be held or increased.
I never try and second guess the market. Did that In my early days of investing. It didn’t work. Markets surprise us. Who would have thought this time last year that we were at the start of an extraordinary bull market for example. So I react to what markets are doing and at present it is a buyers market.
Some sectors and some markets are clearly very fully valued (e.g tech shares and US markets) ) and even in bubble territory and shares here like ITM and CERES with tiny revenues and big losses, but lots of hope, are worth almost as much as Marks and Spencer!
But here in the UK a lot of shares are still very good value with PE ratios sometimes in low single figures and paying dividends as high as 10% even after soaring. e.g insurers like Aviva and Legal and General, Kazakhstan cement producer Steppe Cement (99 Stocko rating) paying over 10%, and mining shares like Ferrexpo, Evraz and Rio Tinto all paying huge dividends (and Stocko ratings in the 90s) even after trebling sometimes since this time last year. For those of us buying those shares near the lows, the 20% and more annual return from the dividends alone make shares like that worth holding, at least until there is clear bad news from the sector or Company to suggest otherwise.
Finally note that even now the FTSE100 is only at the level it was at the end of the last century! So not all markets are expensive and for all we know the good run could last for ages.....or end next week!
First time I've seen someone mention Steppe Cement (LON:STCM), which I am considering for yield (and Guaranty Trust Bank (LON:GRTB)). Feel comfortable with Kazakhstan as a jurisdiction?
Hi something to remember about Guaranty Trust Bank (I hold) is the conversion into US dollars. So the share price might rise but this gets eaten into if the dollar stengthens against the Nigerian currency. Also a large spread and can be volatile. Very good dividend yield.
Ideally, I like to be like the Cockney Rebel if a crash comes around. From what I heard from an interview with him, he mentioned he went into hospital (hope he's recovered from it!) pre-Covid crisis so liquidated most if not all his shareholdings into cash and when released from hospital, the market had crashed, so he was managed to pick up shares on the cheap. Good on him.
Do I have the discpipline to sell up the shop and sit around until a pending storm is over? Probably
What about the idiom "time in the market is better than time out of the market" - To that, I would say - no, not when your wealth in the market is getting slashed by a half.
Last year taught me that I do not have to run a portfolio of stocks, I could just as easily focus on a few stocks with a pending TU that I feel is undervalued and trade short term.
Will I be able to get out if there is a pending crash. Probably not!
But surely the market is not schizo. At the beginning of a crash - it can not just go up 5% and then next day fall by % as well...or can it? I do not have sufficient exposure to have witnessed prior crashed besides the recent one. Surely there are manifestations of an imminent crash before the crash? High Vix, S and P futures looking increasingly glum, commentators opinions converging towards a common negative market sentiment? During October 20, when Trump had Covid, I thought armageddon was around the corner and nearly sold up shop entirely only to find he recovered and the market bounced back (Lol - crazy weekend I recall where he later pulls off his mask in defiance!)
And should these warning indicators, if heeded, not tell you to bottle it before all doom and gloom arrives? Easy said and done but if me and my whole family's finances are in this, I'd rather sit it out rather than to take an opportunistic view in times of any high uncertainty.
Maxistaxis
Good points made but:-
If someone authoritatively said:-
You give up £10,000 today.
In 2022 it will be worth £7,000.
In 2023, it will be worth £13,000.
What would you do?
A. You invest. You lose your money today, and next year, but in 2023, you get back £13,000 worth roughly 15% per annum return.
B. You wait until 2022, and you think to yourself "holy crap, I nearly lost £3,000... and if I invest again, I could lose another £3,000... This is terrifying. The rest of The Market can't be wrong. I'm out".
C. You wait until 2023. At Inflation of (argumentatively only) 3%, your £10K is now worth £9,409
Spread your money.
Diversify.
Drip feed.
Buy only quality.
Tax plan.
Why not try the Stockopedia NAPS strategy where fine minds and algorithms have done their best probability?
Interesting comments 8888, Love your daily blogging BTW. Just remembered you hitting 1mn a few months ago and now you are 25% on that! Congrats!
I get it. Currently I am all in, but if there is any sniff of what I experienced in late Oct 2020, I'm out. I'd rather be fully cashed up ready to pounce on any dashed for cash stocks rather than be long any stocks.
Of course, if unforseen factor leads to market crash, that's nothing I can do, but if it is in my hands not to be at the mercy of the market, then I'd rather sell off early and dive in again hopefully +/-5 % at the market trough.
Believe the idiom is "Time in the market, beats timing the market" think there is another one around if you miss the best 10 days over a 20 year period, your overall returns are halved, but happy to be corrected.
Black Swan events on average only occur every 7 years, so hopefully we have 6 more years before the next one.
Besides my "coffee can" shares, mainly based on the "Jim Slater screen" with a few tweaks, everything else in my portfolio has a strict 20% sell based on its highest position, removes all attachment. This worked well during last year with close to a 40% gain on portfolio, however my coffee can Sylvania Platinum (LON:SLP) went from 60% profit to 20% loss, but now sits at 173% profit, so looks like both strategy's worked.
Maybe with only a year to go before I may retire, I should put it all in bonds, but where is the fun in that.
"if you miss the best 10 days over a 20 year period, your overall returns are halved"
I've heard this as well ....... however, no-one seems to comment (or have studied?) on what happens if you miss the 10 worst days. Wonder if it's out there to serve the vested interests in the city?
Think you have to find the system you're comfortable with, really don't think there is a right or wrong answer.
Phil
Looks like someone has, and if you can miss both the good and bad days, your onto a winner, but how will you know which days are which?
https://www.barrons.com/articl...
They also say most people lose money by not being in the market and I think that is true, especially in the US, I have held off investing much in the US because the markets looked too high but look what happened last year, some US funds were up over 100%.
But if you invest in the FTSE100 then that has not gone up in the last 20 years, so it is really only dividends that you are getting and those probably are not much more than inflation.
The best days often follow the worst days?
It is easy enough to get the weekly ftas values from
https://uk.investing.com/indices/ftse-all-share-historical-data
They provide 2009 on.
Order by the abs
calculate the product
Counting all weeks I get 1.753 which happily matches the site (Change %: 75.33)
Removing the 62 largest changes (10% of the data) I get 2.01.
so about 15% better.
Removing the 10 best days I get 92.3%
so about 47.4% worse
The saying may well be right.
The corollary that you should buy&hold because otherwise you miss out is not there really.
The FTSE All share has not performed well, probably because it's a weighted index, which is heavily influence by out largest companies. How about on the FTSE250 or the S&P500?
We have not really had a crash since 2008 as well so that may influence those results.
Good point - also - after March 2020 crash - going into April - there were tons of cheap stocks around. ...and if one were to have missed e.g. 24th March and other good days,I would expect the ROI would still have been hefty.
I've heard this as well ....... however, no-one seems to comment (or have studied?) on what happens if you miss the 10 worst days. Wonder if it's out there to serve the vested interests in the city?
Hi Phil
It has been studied, and has been commented on before here. Sadly the utterly crap Stockopedia search function makes it impossible to find.
However the 10 best days occur during bear markets, as do the 10 worst days. And they occur in close proximity.
If you can be in the market for the former and not the latter you're not just an investing genius, you're an immortal trading legend. In fact, being out of the market consistently during the 10 best days (and therefore the 10 worst days) leads to better performance.
https://seekingalpha.com/artic...
Like most stockmarket aphorisms the "10 best days in the market" is a complete and utter load of <expletive deleted > nonsense. But, hey, fact checking is so last century.
timarr
Fantastic article Timarr!
I would never seek to be in the best 10 days or even try. All I am trying to do is avoid a catastrophic loss. If I can do that - this means I will have sufficient bullets.
I invest with Buffett's "don't lose money" principle on my forehead. if that means I have to jump off a profitable ship..i.e. at an early stage and even if it means that it could be a complete false alarm .....I rather do that than to suffer the consequences of a sell-off where everything is NTs and u get completely shafted by the MM.
The pain of foregoing profits by far is less than the pain of seeing your investment being underwater bigtime, particularly when me and my family's money - everything that we have is in there.
Each to their own. My "twitchy" perspective will only be switched on when there are big dark clouds on the horizon (for those events that lead to crash which I could not have foresee ...since I can not do anything about them - I do not worry about them).
Hi maxistaxis
Buffett's "don't lose money" aphorism is about value investing - if you invest in things that are cheap then, over time, you won't lose money. It's nothing to do with avoiding temporary losses.
The full quote is:
"The first rule of investment is don't lose money. And the second rule of investment is don't forget the first rule. And that's all the rules there are. If you buy things for far below what they're worth and you buy a group of them you basically don't lose money".
Buffett is, of course, a proponent of long-term buy and hold investing - he and Munger are quite clear that in a lifetime of investing people should expect very serious drawdowns at points. Those "losses" are temporary as long as you're invested in sound companies with good business models and some form of competitive advantage.
If you invest long enough you'll end up suffering profit warnings - I hold Novacyt Sa (LON:NCYT) and that wasn't much fun on Friday. But risk management is about portfolio management as well as individual stakes and the 0.5% drop in overall net worth is something I can live with.
Everyone manages risk differently, of course, but anyone who invests in shares over a long time will either see very significant losses at some point or will forgo very considerable gains in order to avoid the losses. Stocks are volatile, if they weren't there wouldn't be any reason to buy them.
timarr
Don't forget the compisition of the ftse 21 years ago though. Lots of dotcom and related stocks