Small Cap Value Report (Mon 15 July 2019) - Tablets, GOCO, BPM, DPEU, TMMG, SWL, NTBR, INS, AMO

Good morning!
A very busy morning in RNS-land, with a lot of "small" updates, including 3 relating to my own portfolio holdings.
This list is final:
- Goco (LON:GOCO)
- B.P. Marsh & Partners (LON:BPM)
- DP Eurasia NV (LON:DPEU)
- Mission Marketing (LON:TMMG)
- Swallowfield (LON:SWL)
- Northern Bear (LON:NTBR)
- Instem (LON:INS)
- Amino Technologies (LON:AMO)
Tablets
It's that time of the year for me to take my main holiday, so I'll be jetting off to Italy soon and you'll be in Paul's capable hands again for a while!
That's not investment-related, but perhaps of more interest is my research into the Tablet market. The only one that I have ever owned is an iPad from about 2012, possibly the iPad 3. It barely works any more (though perhaps I should be glad that it works at all, due to its age!)
I've been looking at some of the models currently for sale, with a view to finding one that I can bring to Italy. It's for light work purposes - I need to log in occasionally while I'm away to do a few small tasks, which should only take a few minutes. What I'd like to do is leave my laptop at home more often, and just bring a tablet instead.
It's easy to forget about the tablet market, since phone screens have become so big in recent years that the need for a mid-size device has diminished. But there is still a market for multi-functional devices with a screen size of 7"-12".
Anyway, despite being a huge fan of Apple ($APPL) when it comes to phones, there is actually no chance of me buying an Apple tablet. The choices available from Samsung, Huawei and Lenovo seem to be more than sufficient, and at very attractive price points. There's also the interesting possibility of the Amazon Fire HD 10. Or if I was going for a more expensive, heavy-duty device, I'd be inclined to go for the Microsoft Surface Pro.
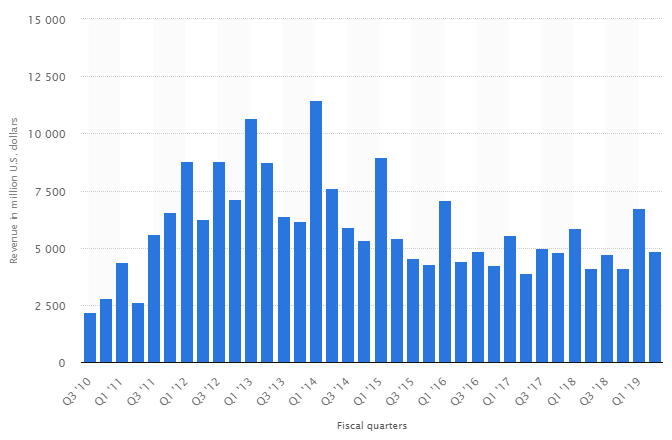
This is a long-winded way of saying that I'm contributing to the trend whereby iPad sales were stronger in 2012 than they are today:
(Source)
And if I have a good experience with a non-Apple tablet, does that mean I'll be more likely to buy a non-Apple phone next time? iPhone revenues haven't been on a positive trend, either. Once we escape the Apple ecosystem with one device, maybe we are more likely to escape it with another device, too?
Goco (LON:GOCO)
- Share price: 86.5p (+0.4%)
- No. of shares: 418.5 million
- Market cap: £362 million
(Please note that I currently have a long position in GOCO.)
This is pleasant news for Goco (LON:GOCO) shareholders. We have a tie-up with B, the digital banking service from CYBG (LON:CYBG). A new service will allow B customers to:
"...quickly and easily find and switch to better energy deals, all within the B mobile banking app. As the GoCompare energy switching service is integrated with B, their customers' details are used to pre-populate a lot of the questions needed to carry out an accurate comparison, making the process as hassle-free as possible."
Comment from CYBG:
Having been early adopters of Open Banking, our new partnership with GoCompare has launched the first energy comparison and switching service for bank customers in the UK.
The financial value of the deal is unclear. In simple terms, we have 300,000 B customers who are now more likely to use Goco to switch their energy service, as it will be very convenient for them to do it on their phone. That can't hurt!
I also think it's encouraging to see external validation, from CYBG, of Goco's technology platform.
This has been a pleasant, small position for me since I bought it late in 2018. I reckon the most likely outcome is that it will get gobbled up by someone else in the next few years, hopefully at a generous premium.
It deserves a better rating, in my view (but I would say that!).
B.P. Marsh & Partners (LON:BPM)
- Share price: 287p (+1%)
- No. of shares: 37.5 million
- Market cap: £108 million
(Please note that I currently have a long position in BPM.)
This is an investor in the insurance sector.
As mentioned last month, I increased my position size here on the back of its final results. I'm attracted by its long track record, portfolio diversification, management style, financial position and share buyback policy. NAV per share is 350p.
Over the past month, there have been several small share purchases by insiders. There has also been a very small repurchase of its own shares, at 291.5p. It can buy back its own shares at a >15% discount to NAV, so it can buy back anywhere below 297.5p.
Today's news relates to an £800k investment, with contingent consideration of a further £600k. So it's a fairly small piece of the entire portfolio.
BP Marsh, via a holding company, will own 36% of Ag Guard, an Australian insurance services provider.
Note that there is an Australian theme at BPM, which is 20% owned by the Australian insurance company PSC (ASX:PSI).
My view - when I'm investing in an investment company, I tend to think much more about the quality of the people running it, rather than attempting to copy the due diligence that they are doing on their investees.
I was delighted to have a meeting with BP Marsh recently, which helped to cement my view that they are running the organisation with a strong sense of stewardship and with a very long time horizon.
This is one of my favourite types of investment, and I'd put it in a similar category to Volvere (LON:VLE).
DP Eurasia NV (LON:DPEU)
- Share price: 86.7p (-2%)
- No. of shares: 145 million
- Market cap: £126 million
(Please note that I currently have a long position in DPEU.)
Yet another company of mine has made an announcement this morning. Very unusual!
Full-year adjusted EBITDA at this Dominos business is in line with expectations.
We have like-for-like sales growth of 7.7% in Turkey, when measured in Turkish Lira. The problem is that this is not keeping pace with the depreciation in the Lira, in terms of the local inflation rate and the value relative to GBP.
However, I note that there are signs the Lira is firming up. It is currently not far from the levels seen before the savage sell-off in mid-August 2018.
While the collapse in the Lira was very distressing for this share, I took the view that currency movements would eventually wash themselves through the system and that a fair equilibrium would be reached again. It was not DP Eurasia's fault that the currency value had fallen, and indeed DPEU's results have been quite reasonable, when you put that issue to one side.
To give you an idea about what happened:
- 6 August 2018: DPEU share price 148p
- 13 August 2018: DPEU share price 91p (loss of 39% in a week)
- 6 August 2018: one Turkish Lira is worth 14.7p
- 13 August 2018: one Turkish Lira is worth 11.3p (loss of 23% in a week)
The Turkish Lira is currently worth 13.9p, so you can see it's not that far from those levels in mid-2018. Turkey's main interest rate is currently 24% and even though President Erdogan wants to see this reduced, it's likely to remain at extremely high levels as the central bank seeks to preserve the value of the currency.
So I'm sort of bullish on the possibility that the Lira can recover. Even at its current levels, I don't think that the DPEU share price reflects the recovery it has made or the progress at the company itself.
DPEU's Russian sales are up 63% (including sales at owned and franchised stores). And like-for-like sales in Russia are up 4.7%, measured in Russian Roubles. This is despite the previous period including the World Cup, hosted in Russia.
The Russian business needs a new CEO, as I've mentioned before - a new appointment is sought before the end of the year.
Online deliveries continue to improve for the entire group, and are now at 67.5% of total (versus 59.3% last year).
CEO comment:
We remain on target for store openings for the full year in both our main markets and the Board expects the full year Adjusted EBITDA(5) for 2019 to be in line with expectations."
My view - this remains my smallest holding, and an extremely risky one at that, but I remain hopeful! It hasn't put a foot wrong in terms of the growth strategy, and I view the collapse in the share price as being almost entirely macro-related.
Looking forward to next year, analysts are targeting EBIT of 102.7 million Lira, which is worth about £14.3 million at current exchange rates. The following year, if growth targets are hit, it is looking for 131.9 million Lira, which is worth £18.3 million.
It is carrying some debt which needs to be serviced, and the uncertainties are many, but I continue to like this as a small, speculative position.
Mission Marketing (LON:TMMG)
- Share price: 85.5p (-6.6%)
- No. of shares: 85 million
- Market cap: £73 million
This is a network of marketing and advertising agencies, created via a series of acquisitions.
Today's H1 update makes no reference to market expectations, only to KPI targets, making my job slightly harder.
However, I have checked last year's H1 update and it did not refer to market expectations either, so at least the company hasn't changed its format in that regard.
The Board is pleased to report that the Group expects to report results for the first half of the year in line with its KPI targets of revenue growth of 5% and profit* growth of 10% from continuing operations**, continuing the Group's track record of growth over the past eight years.
A note published by Edison last month forecast that revenue would increase by 5.6% this year, and PBT would increase by 7.4%. So the numbers presented above look ok, in that context.
Debt has been a hot topic with this share and it sounds like progress is being made in terms of develeraging. Net debt at the end of the period is £5.2 million, and the company thinks that its net debt/EBITDA ratio is only 0.5x, before making adjustments for the new lease accounting rules.
There will be "a significant bias towards the second half", which the company says was true in previous years, too.
Checking the archives, the company did indeed say almost exactly the same thing in 2017 and in 2018, too.
Since it has been consistent, I wouldn't punish it for repeating what it has said before.
My view - this update seems fine to me, but judging by the share price it is clear that some shareholders were expecting more.
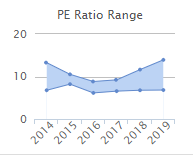
Historically, this has been valued at cheap earnings multiples. As of last night, the PER was 9.4x. Perhaps it is headed back to the 6x-8x range where it has often traded before?
You can see from this Stocko graphic that the PER has been unusually high in 2019:
Swallowfield (LON:SWL)
- Share price: 230p (+19%)
- No. of shares: 17 million
- Market cap: £39 million
Proposed Disposal of Manufacturing Business
Terrific news for Swallowfield shareholders, as it proposes to change from a manufacturer and brand developer to being a pure brand developer. Its manufacturing business will be sold for £35 million (subject to some adjustments), and the name of the remaining group will be renamed "Brand Architekts".
Readers will know that I'm a shareholder in Creightons (LON:CRL), another cosmetics manufacturer. The quality metrics at Creightons have been excellent, reflecting (in my view) the skill of its managers and its operational efficiency. But the deal today by Swallowfield suggests that even a modestly profitable manufacturing business can still command healthy disposal prices.
Swallowfield acknowledges that its manufacturing business has not done terribly well:
Over recent years significant volatility has been experienced in the Manufacturing business, of late due to the impact of material cost inflation, weaker product mix and the prevailing external environment.
Core financial metrics for the manufacturing business:
- Revenue for 53 weeks to June 2018: £31 million
- Operating profit for 53 weeks to June 2018: £2.6 million
- Value of assets being sold: £23 million
So the premium to book value of assets is >50% and the multiple being paid relative to trailing operating profit is 13.5x.
The deal will benefit the manufacturer, by putting it in the hands of a larger organisation that can manage it without being so sensitive to short-term volatility.
It also benefits SWL by achieving a sale price in excess of its total market cap, and still leaving it with ownership of its Brands business!
Note however that SWL does not expect that it will be sitting on £35 million of cash. There is some debt to clear:
Following completion of the Proposed Disposal, the Directors expect the Group's net cash position will be approximately £23 million, after taking account of deductions and the expenses of the transaction. The Board intends that these funds should be retained by the Group to fund investment to drive organic growth and to pursue future earnings accretive acquisition opportunities.
Payments to executive directors: there are large bonus payments being proposed for SWL's three executive directors in relation to the deal, adding up to almost £600k. They seem to be designed as a thank-you for getting this deal done, but are they perhaps a bit generous?
My view - Swallowfield looks like it might be priced at bargain levels at the moment, seeing as this deal could leave it sitting on £23 million of cash, leaving the Brands business theoretically valued at £16 million at the current share price.
The Brands business generated £2.6 million of underlying profit in H1, before central costs and exceptional items. Central costs and exceptional items should surely reduce now that the manufacturing business is leaving?
In the prior year, the Brands business generated underlying PBT of £4.8 million (over a 53-week period), again before central costs and exceptional items.
Today's trading update says that there are still some pressures on Brand sales:
As highlighted previously, the pace of growth has slowed in the Brands business with revenues declining by 3% over the prior 52 week period (5% on 53 weeks). This is a result of lower UK consumer confidence and pressures within the retail environment which have led to a softening in demand and retailer reductions in category space and promotional activity.
Even with these headwinds, the market cap looks possibly too low to me.
Northern Bear (LON:NTBR)
- Share price: 66.7p (+8%)
- No. of shares: 18.5 million
- Market cap: £12 million
This building services provider has produced good numbers for FY March 2019.
The cash generated from operations is unusually large at £5.1 million, helping the company to increase its regular dividend and declare a special divi of 0.75p (though I note that this is lower than the special divis in 2017 and 2018).
The Chairman's statement, in response to feedback from shareholders, includes a few paragraphs to explain why the company's results are "very difficult to predict".
This share nearly always looks dirt-cheap but this is for all the right reasons, in my view. Building services are a tricky place to build a sustainable business and the Chairman himself rightly states that there is little or no visibility when it comes to results in any given period.
I will give full marks to NTBR for stating their lowest, highest and average net cash or net debt position during the year. That is the best way to disclose net cash or net debt, and not enough companies do it.
Outlook - not worth the pixels it's printed on, probably, but here it:
The Group continues to hold a high level of committed orders although, as stated in the Trading section, we have limited short term visibility as to when these orders will be realised.
My view - it doesn't interest me, as I try to avoid small, order-driven B2B businesses, and I don't invest in building services. This cheap stock is reserved only for those who have the stomach for it.
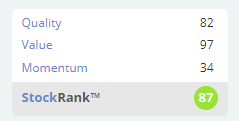
Fittingly, Stocko categorises it as Contrarian:
Instem (LON:INS)
- Share price: 360p (+1%)
- No. of shares: 16 million
- Market cap: £59 million
Instem plc (AIM: INS), a leading provider of IT solutions to the global life sciences market, is pleased to announce a trading update for the six months to 30 June 2019 (the "period").
I'm afraid that I'm not familiar with this software company. But for what it's worth, today's update sounds fine, and is in line with expectations. Sell-side analysts have made no changes to their estimates as a result.
- 10% year-on-year revenue growth
- SaaS revenue is replacing perpetual licenses
- Good macro conditions wiith R&D pipeline growing
CEO comment:
"...it was particularly pleasing to see a faster rate of transition than anticipated from perpetual software licensing to SaaS subscriptions. We believe our SaaS value proposition offers both Instem and our customers enduring benefits and increases shareholder value as the visibility of our revenue continues to improve."
Outlook
Checking the analyst forecasts, I see that the company is supposed to generate adjusted PBT of £3.6 million this year, rising to £4.4 million next year.
Stockopedia likes it, calling it a High Flyer:
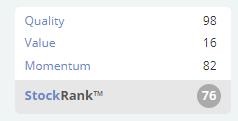
I was chatting with Ed recently, and he reminded me that the Momentum Rank includes earnings momentum, so it's not just a technical tool based on share price movements. It also has an important fundamental ingredient. Something to bear in mind!
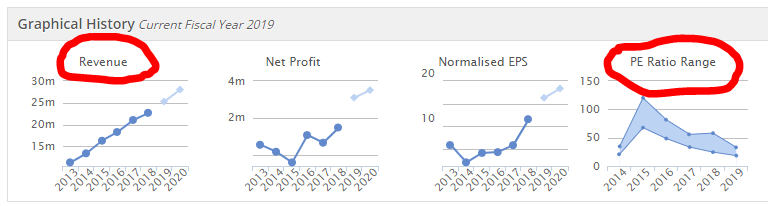
Checking the progress of revenue and the historic P/E ratio range, I see very encouraging lines of progression. Revenues have been on the march and the company has been growing into its valuation - the P/E ratio has declined even as the share price has increased over the past few years:
It all adds up to a nice set of indicators.
Amino Technologies (LON:AMO)
- Share price: 121p (+2%)
- No. of shares: 73 million
- Market cap: £88 million
Acquires 24i to accelerate online video strategy
I'm running out of steam now, but let's take a quick look at this one, which has been mentioned in the comments. It makes TV-related technologies - software, hardware, and cloud solutions.
Paul and I have generally made positive noises about this company, without claiming to bring any particular sector expertise to the party. See Paul's comments on it in June. I've only covered it once before, and that was last year.
Today's update is significant: Amino is making a €21.4 million investment in exchange for 92% of 24i, an international business with its HQ in Amsterdam.
24i makes "TV apps for every screen". Its apps can be used on all sorts of TV devices and on games consoles, tablets and phones.
The valuation is a bit punchy, as you might expect. 24i's revenue last year was just €7.1 million, and the Amino deal gives it an implied enterprise value of €27.5 million. So the implied Price to Sales multiple (trailing) is in the region of 4x. As regards profitability, 24i has been trading close to breakeven.
Rationale - the two companies share a vision of the future, and their customer bases and product suites are described as "highly complementary".
24i shares Amino's vision of where the modern TV industry is heading and, like Amino, recognises that the industry is at the beginning of the curve of disruption. This is a fundamental shift from broadcast and hardware to streaming and hosting video platforms in the cloud. Like Amino, 24i has an agile culture of innovation and is focused on capturing this market opportunity.
The Acquisition will enable Amino to deliver full 'end-to-end' and on-demand personalised content solutions to its customer base. It will also build momentum in Amino's software and services revenues, as well as its recurring revenues.
This is not the takeover of a competitor, in other words - it's designed to increase the overall product offering at Amino.
My view - it sounds logical, so hopefully it will create value for everyone concerned.
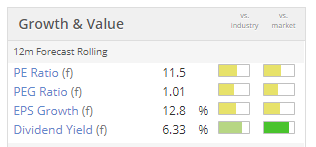
Amino is yet another Contrarian share on our list today, and it pays out a surprisingly high dividend yield for a tech stock. Might be worth looking into:
Ok, that's it for today! Thanks for all your feedback.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Hi Graham; Late in the day but for vacations i use the Samsung Galaxy Tab 10.5 in conjunction with the Mobile S6 Both very reliable and useable. The Samsung folding carry case is a must, beautifully designed. For both when typing a lot i use a Bamboo stylus. And thanks for all your reports which i find particularly helpful. Have a great vacation.Chow.
I have an Amazon Fire and it's basic in the extreme. OK for web browsing and emails viewing and books reading and Readly. But for anything at all 'business like' is a disaster. I thought I could use it to store meeting packs before a meeting but I found it hard to get Documents organised. It can open Words reasonably well but fails on pdf's - each screen seems to show 4 pages, which makes it illegible. Maybe there's a Setting some where I haven't sussed? Also found it hard to download ordinary Android apps - Amazon's library seemed too restrictive though I gather the techies can 'jailbreak' into it.
For any tablet, you need to decide whether to have a SIM card for 3G or rely on external WiFi (or hotspot from your phone).
That said, the Amazon is cheap as chips and the pop-up advertising on the login page easy to gloss over.
There used to be something called a Hudl which had a good reputation but I think it's been discontinued and the versions available on eBay will be pretty manky by now.
Sports Direct International PLC -
Just noticed Sports direct delayed releasing their results today blaming auditing delays - it would be funny if it was the newcastle* branch of Grant Thornton tasked with doing the audit - i guess that would be a by the book nice comprehensive list questions and answers before everything is signed off :) * substitute similar location of your choice where Mr Ashley has rubbed up bods the wrong way.
I am glad i sold this share when he tried to morph a successful cash cow of a business into something less successful but more trendy. Price is down nearly 75% from its peak and they aren't exactly brimming with confidence today that things will pan out in line with how they previously guided the market.
I have a iPad mini, it is good for travelling, not too small, about 7" screen, last time I looked you could get them for about £250.
Hi Bob! I'll be in central Italy (Naples region) and Rome, but thanks anyway! Enjoy the summer. G
Thank you Graham. BTW w are in Italy remote part of northern tuscany until mid august.....if you are in reach let me know and maybe swing buy for lovely home cooking and tranquility
Best
Bob
Thanks for mentioning B.P. Marsh & Partners (LON:BPM) again Graham. This time I'm interested in digging further.
Positives: Low PE, management skin in the game, clear rules about share buybacks at only discount to NAV and a commendably prominent warning about JSOP shares on the font page of their website.
Negatives: Share price CAGR since listing appears to be only just over 5% per year & that hasn't been compensated for with a large dividend. I need to look into this further.
the Amino acquisition looks expensive at Eu21mn but if it works will give a mighty boost to RoCE in about a year's time. They have been sitting on a load of cash and seem to be sorting out problems. The company has a clear strategy on moving away from set top boxes and more into varied media streaming/software so this is in the direction indicated.
On Northern Bear it is worth mentioning that the prelims release is accompanied by some clear and useful statements regarding (especially) average net debt (rather than just period end which they concede can be very misleading) and treatment of longer dated receivables. Generally management is acknowledging that outside shareholders deserve a bit more handholding than has been forthcoming to date. This is welcome. I would rather be in here than Sosandar any day of the week (famous last words!).
Nice trading update from EKF Diagnostics Holdings (LON:EKF) today. It includes the following:
"Net cash and marketable securities as at 30 June 2019 are also slightly ahead of management expectations and were approximately £15m. This figure includes approximately £3.25m of Renalytix AI plc securities (2,677,981 shares) held at cost price. These shares have a value of c. £8.7m at the last practicable date prior to this announcement, giving cash and marketable securities at current market value of over £20m."
In other words, they have chosen not to mark their Renalytix AI (LON:RENX) shares to market, meaning that there is £5.45m of value lurking within this asset alone. (Renalytix AI (LON:RENX) was spun out of EKF Diagnostics Holdings (LON:EKF) a few months ago and has since risen by 220%)
Not surprisingly, the share price is up a bit today.
I hold both EKF and RENX. Both have Christopher Mills as a Director.
Ricardo
It's a busy day for announcements, but one more I would flag up is an acquisition for Amino Technologies (LON:AMO) taking the company further into "higher margin software and recurring revenues".
The rather enthusiastic RNS is here. The CEO believes this is "moving us closer to a decisive market leadership position".
As a result finnCap has increased 2021 EPS from 15.5 to 16.1c and target price from 185 to 215p.
Regarding BPM does anyone know why the stockrank and qvm scores are all 0? Is this a quirk of the stockopedia system or does it genuinely regard BPM so unfavourably?
Thanks.
BPM isn’t ranked because it is classed as a collective investment. Stockopedia doesn’t rank funds etc.
Thanks!
Re: Goco (LON:GOCO)
I don't understand this, really. Under Open Banking there's no requirement to have a partnership with the bank at all, the APIs are available to any registered, authorised third-party and there's nothing any bank can do to stop access as long as customers give consent.
The only advantage to this I can see is that it allows the bank to market the service directly to their customers - so maybe it gets them over the hump of getting accountholders to sign up. But the real opportunity here is for Goco (LON:GOCO) or one of their competitors to integrate to all of the banks and start offering switching services to all UK accountholders.
timarr
If someone made a slightly smaller & sensibly priced Windows clone of the lightest Apple macbook, I might be a customer, but nothing suitable exists. So I stick with the tablet for now.
I have a rather long in the tooth Asus T100 Transformer 2-in-1. It runs Windows 10 and came with Office 2013 loaded for just over £200. When I go away I just take the tablet half and leave the keyboard at home. I guess it's similar to a Surface Pro but much cheaper and much less powerful. I'm not sure if Asus still make them, but if they did....
EDIT: it looks like they do: https://www.asus.com/2-in-1-PCs/ASUS_Transformer_Book_T100TA/
All the best, Si
On tablets, for what it’s worth...
For me, the ecosystem (Apple in my case but the google ecosystem would work in a similar way) is important. The things that work for me are:
* documents, spreadsheets available on my iPad, my iPhone or my Mac to pick up where I left off
* all SMS and iMessages available on my iPad, Mac and iPhone
* Tap Forms database (used to record my investing analysis...) synced between devices
* website reading list etc.
* similar ways of working
Looking forward to hearing your choice and how it works out.
Hi Graham
One small piece of advice if you do get a new one, don't leave it on the plane. I've never left anything behind until last weekend getting back from my holiday, let alone a brand new ipad pro! Luckily the Easyjet (LON:EZJ) aircrew went back and got it for me as I only realised at passport control (great customer service by them!). On the topic of tablets I must say I have never purchased any devices that expensive before I felt uneasy paying for it, but its been great and have no regrets now..
Cheers
Re tablets, it will be interesting to see how you get on. I don't think you'll beat the current basic iPad at £319. But you can be a guinea pig for us finding out how difficult or worthwhile it really is to leave the Apple ecosystem.
https://www.techadvisor.co.uk/test-centre/tablets/best-tablet-3265725/
Thanks John! I look forward to reporting back. Basic iPad is at a reasonable price, agreed. G
Preferring something compact, I bought a £300 Samsung 8" tablet a few years ago and it's fine for holidays. The cheaper ones tend to be too slow, particularly after the software is bloated via updates. [I gather Apple do this as well & am waiting for class action or regulators to act]
Using spreadsheets is slightly more difficult than with a laptop, but it's tolerable for very minor edits.
If someone made a slightly smaller & sensibly priced Windows clone of the lightest Apple macbook, I might be a customer, but nothing suitable exists. So I stick with the tablet for now.
I went Amazon Fire HD 10. For the price it has been really good. You are a little more tied to amazon in that you do not get the range of Android Apps (amazon have their own subset) But has all I need. (and they are on sale at the moment on prime day (only £95))
Lloyd
You can load the Play Apps store onto the Fire HD - just google it fairy straightforward and that gives you full access to all the Android Apps.
The Swallowfield (LON:SWL) disposal of its manufacturing business has seen share price rise 15% (at time of writing) and Market cap rise to £38m. Pro- forma the disposal, the group will be left with £23m net cash and a brands business (which in FY19 saw sales of c£20m ). This brand business has been the main contributor to profits £4.8m in FY18 - but to estimate profits going forward you need to be clear how many group overheads can be eliminated by the sale.
But on this analysis, the pro-forma company looks cheap.
But there is also the DB pension scheme that will remain with Swallowfield. The accounting deficit on this is £6m (Dec 18) and the total PV of the fund liabilities is around £29m. One option, for the cash balance might be to seek a buy-out of the pension fund by an insurance company - but I guess (only a guess) this would use up approximately half of the £23m cash balance. The pension scheme, I suspect, will remain an important drag on the valuation of the company.
Portmeirion (LON:PMP)
Seems like a sensible acquisition anything that adds to their us presence and adds cross selling abilities seems like sensible use of their cash/available financing - the following text is always comforting to see in relation to acquisitions.
Northern Bear (LON:NTBR)
Decent results announced today - slightly ahead of the trading update on 11th March - although probably inline with what most shareholders were expecting to to 10th March due to prior updates.
Per march update (memo ye 31/3)
and per results today
Note the update in March spooked the market and the shareprice has remained depressed since that time - so despite the rise this morning the shares are still behind where they were despite the decent figures. EPS of 13.5p puts them of pe just over 5 - so the market simply doesnt rate this company at present.
The company doesn't really give meaningful outlook statements in that there a lack of broker forecasts - they refer to April-September 2018 results being exceptional and q1 this year was poor so at best one would hope that this year will be broadly in line with last year. Unless there are material changes we are unlikely to get any confirmation in that regard to this time next year when the final numbers come in :(
Todays outlook
ref the cheap as chips shareprice - its a micro cap and the company doesn't really do much by the way of investor relations - it works in construction and the balance sheet is a bit light - there are high payables and receivables - note the balance sheet is improving naturally ignoring acquisitions each year so that is a plus. Liabilities down £1.3 million - and current assets and debtors due over 12 months has increased by 600k - so decent natural progression being made as earnoings in excess of dividends feed through to the balance sheet.
Instem (LON:INS) if you have the time please Graham. They have been sitting on my watchlist for long enough that I can’t remember much about them but today’s RNS and the stock report both encourage further research..
Would like to second this suggestion of Instem (LON:INS). The steady revenue growth is attractive. The ratio of capitalised development costs looks a bit high.
Thanks, I will get there a bit later. Breaking for lunch now. G
Hi Julian/ST, I've had a look at Instem (LON:INS), it's not one I've looked at before but thanks for flagging it! All the best. G
Slightly surprised no-one is interested in Finsbury Foods, a bread and cake maker I used to own. It looks very cheap and the update though not startling sounds reasonable. Anyone have a view here?
I'd love a slide of the rule over Mission Marketing (LON:TMMG) please Graham - has hit targets this year but uh oh - what's that Sooty? 'H2 weighting'?
I'd like Mission Marketing (LON:TMMG) too please - "results for the first half of the year in line with its KPI targets of revenue growth of 5% and profit* growth of 10% from continuing operations** " does not sound like it can support the current share price; we're back to single digit revenue growth again.
Hi rtj / andrea, yes, TMMG is on the list. G
My morning smallcap tweet:
Mobile Streams (LON:MOS), £GAME, Swallowfield (LON:SWL), Actual Experience (LON:ACT), Spectra Systems (LON:SPSY), Portmeirion (LON:PMP), Northern Bear (LON:NTBR), EKF Diagnostics Holdings (LON:EKF)
Mobile Streams (MOS) dismal FY trading with rev-cont £1.3m (£3.1m). Rationalisation "had a significant impact on the Company's cash balances and, as a result, the Board is considering a number of financing options."
Game Digital (GAME) Sports Direct will take it over as it exceeds 75% of shares
Swallowfield (SWL) sells manufacturing business for £35m. Cap is £33.1m at 193p. Owned Brands business become the entire focus of the Group.
Actual Experience (ACT) bookbuild to raise £3m min at 135p/sh min, an 18% discount.
Spectra Systems (SPSY) wins $1.1m order over about 5 years for lottery security.
Portmeirion Group (PMP) buys Nambé, a premium, branded US homewares business, for $12m. It is expected to be earnings enhancing in the first full year of ownership.
Northern Bear (NTBR) FY rev up 6%, adj EPS 13.5p up 8%. Final div + special div 4p total (4p). Op profit slightly better than guided. No F/C. Outlook: Q1 slow due to a number of contract delays but "majority of these contracts have now commenced and trading should be much stronger in the second quarter." Outlook for the financial year remain good. I hold.
EKF Diagnostics (EKF) H1 trading: rev in line but adj EBITDA ahead of management expectations.