Small Cap Value Report (Mon 5 July 2021) - FRAN, IGP, RST, TRT, PRV, TPX

Good morning, it's Paul & Jack here with Monday's SCVR.
Timing - today's report is now finished (15:15)
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Agenda -
Paul's Section:
Intercede (LON:IGP) (I hold) - a reassuring, rather than earth-shattering Q1 trading update. Gives us more colour on the reseller partner programme called "Connect". £600k new contract wins in Q1. Long tail (c. 10-20 years typically) of recurring revenues. Things are going well. Valuation looks about right to me, for now. Long-term upside I hope, as this is a core "coffee can" holding in my portfolio.
Restore (LON:RST) - upbeat trading update, restoring divis, and confident-sounding outlook. The valuation doesn't look stretched. Could be worth a closer look maybe?
Transense Technologies (LON:TRT) (I hold) - in line with market expectations for FY 06/2021. Not enough hard numbers to form a firm view either way. Small, speculative, but looks OK. Not burning cash, so dilution risk seems low.
Porvair (LON:PRV) - solid interim results. As usual when I report on this company, I struggle to understand why it's worth a PER of almost 25? Lacklustre outlook comments too.
Panoply Holdings (LON:TPX) - I've been sceptical about this acquisitive software group in the past. Looking at it with fresh eyes today, a lot of my concerns have now been addressed. Strong performance, and good outlook. The valuation looks expensive, but if high performance and growth are maintained, then it could be justified.
Jack's Section:
Franchise Brands (LON:FRAN) - fast-growing franchise owner posts an in line update. Share price back up near to previous highs might limit short term upside, but there is ambition here.
Paul's Section
General market comments
It's certainly felt a lot more cautious in recent weeks, with lots of shares succumbing to profit-taking, after a truly spectacular run from the announcement of the vaccine roll-out last Oct/Nov. Also, as mentioned here almost every day, lots of shares now look fully valued, or even maybe over-shot on the upside. So I see a pullback as being very healthy actually.
I do think companies need to produce positive newsflow (not just in line with expectations) to drive further re-ratings in share prices. Things don't keep going up in a straight line, after all. In line with expectations isn't good enough, for shares which are on stretched valuations.
Within my own portfolio, there's very little on stretched valuations, but the one that did look a bit toppy at 395p ( D4t4 Solutions (LON:D4T4) ) (I hold) was clobbered when it put out in line results recently, together with a reduction in profit forecasts for the new year. That's a tricky one, because the company has made a policy decision to spend more ("invest" in today's parlance) on sales & marketing, to drive expansion. That hits short term profitability, but should increase medium to longer-term profitability. So should that really hit the share price? Arguably not. You could argue that, if a company has a great product, with blue chip existing clients, then pushing it more aggressively to new customers is absolutely the right thing to do, irrespective of the short-term impact on profits. Anyway, I had already decided that D4T4 was a "coffee can" holding for me, to hold long-term, and ignoring short term share price volatility, so none of this really matters. I've not sold any, and don't intend to.
News over the weekend re covid/re-opening sounded positive for the markets. The re-opening trade has gone stale in recent weeks (after a great run), but I wonder if it could come alive again? The new Health Secretary (and please let's not stray into a political debate, that's not for here!) is talking very much in terms of re-opening as the priority, and learning to live with covid, now that the vaccines appear to have broken the link between cases and hospitalisations/deaths. That makes sense to me. After all, what's the point of vaccinating anyone, if we're going to have perpetual lockdowns? The whole idea of vaccinations is to make this a less serious illness, a bit like seasonal flu, which of course kills several thousands of people each year, but we don't have daily updates on the news about flu cases, and don't have lockdowns over flu either.
Anecdotally, it was busy here in Bournemouth over the weekend, despite dreary weather. Plenty of people clearly want to get out and about again, socialise, and spend. So I'm looking again at my portfolio, and thinking about buying more of my favourite rebound stocks like Saga (LON:SAGA) (I hold) , Revolution Bars (LON:RBG) (I hold), and a few others. There's got to be upside though. I can't see the point in buying rebound stocks that are already priced to anticipate a return to peak 2019 earnings. Unless they've stripped out loads of costs, such that profitability could not just rebound, but exceed previous peak earnings.
Broker forecasts - in some cases, these are still way too low. But they're starting to catch up. This is the best opportunity at the moment I think - identifying companies where we can work out from good trading updates that current broker forecasts are way too low. Hence all the forward-looking valuation metrics are wrong in those cases, and the share prices could have plenty of further upside, once analysts finally produce realistic forecasts later on. A good example of this last week was Headlam (LON:HEAD) (I hold), where the broker update even said that its own forecasts were too low, but they wouldn't be updating until September! How ridiculous is that? Deliberately leaving woefully pessimistic forecasts out there seems wrong, because it misleads investors who are not able to source the note to read the text which puts the low forecasts into context. It does remind us that there's no substitute for DYOR (doing your own research)! Broker forecasts are often wildly wrong, especially so at the moment, so should not be relied upon as anything more than a complete guess.
Supermarkets - I'm also tempted to pick up a few Tesco (LON:TSCO) and J Sainsbury (LON:SBRY) this morning, given that Americans seem to think UK supermarkets are cheap (Bid for Wm Morrison Supermarkets (LON:MRW) announced). Although MRW had a particularly large freehold property portfolio. I don't believe the assurances given by the buyers that they won't plunder the property asset base of MRW to help pay for the acquisition.
Takeover bids are coming thick & fast, hence why I want to remain fully invested in decent companies on reasonable valuations. Reviewing my portfolio over the weekend, I'm very happy with the positions I hold, and the position weightings (lots in the best ones).
Intercede (LON:IGP)
(I hold)
108p (up 6% at 08:10) - mkt cap £61m
Connect Partner Programme & Q1 Contract Wins
Intercede, the leading specialist in digital identities, credential management and secure mobility…
Summarising the key points in today's update -
- “Connect” partner programme is going well
- Q1 (Apr-Jun 2021) - 6 new contracts (a record) signed - £600k revenues (mostly for FY 03/2022)
- Tailwinds - work from home (WFH), and frequent data breaches driving demand for improved network security
- Important point - partners have existing clients that would benefit from buying Interecede’s software
- Last year 90% of new business wins came via Connect partner programme
List of example partner names is given -
Building on the launch of the Connect Partner Programme in February 2020, new and enhanced relationships have been formed via both Technology Partnerships with organisations such as Aware, Yubico, Utimaco, Primekey, Sailpoint, Feitian, Authentrend, GoTrustID and Entrust as well as Reseller Partnerships, including but not limited to CertiPath, Altron, Guidehouse, Expisoft, eSysco, ASKON, Cryptas, WidePoint, TSM and Nevo Technologies.
My opinion - I’m reassured by this update, that the strategy of selling via partners appears to be working.
£600k in new contract wins may not sound a lot, but remember that most of IGP’s revenues come from recurring & repeating revenues. Clients are typically very sticky - think 10, even 20 years of annual maintenance & support fees, plus upgrades, and customisation work, all high margins because IGP’s software is very stable and requires little support. It obviously works very well, otherwise many major clients wouldn’t be so sticky.
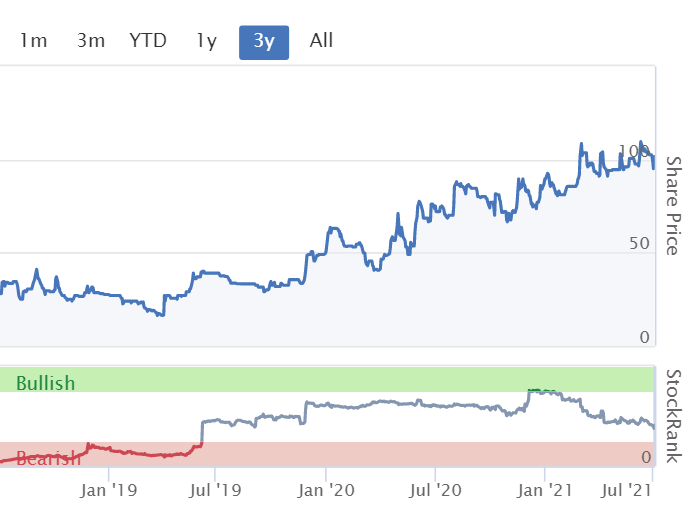
Valuation - I think the rise to 100p is fully justified, and overall I’m comfortable with the current valuation. The company is profitable, cash generative, and now has a bulletproof balance sheet with lots of net cash, following conversion of the loan notes recently.
Liquidity - IGP shares are tightly held, so it can be fiendishly difficult to buy shares, especially when the newsflow is good. Hence why I'm not interested in trying to time the market here. I'd rather just hold long-term, and accept that the price is likely to be volatile. The danger is that if we try to be clever by selling, then it could prove impossible to buy back in, in any decent size. The opposite of that is obviously that if the company disappoints, then the price plummets. That's the deal with small, illiquid shares, hence why some diversification is very necessary. I try not to have too many small illiquid things in my portfolio these days, having come a cropper in a spectacular way in 2008, with a gigantic, geared position in one micro cap. It did not end well.
I’ll be sticking around here, because I think there’s scope for a decent flow of new business, through the partner programme, which creates an operationally geared potential for much higher profits. Last year was held back by the pandemic, although growth in the main USA market was still good.
The company recently indicated it’s on the acquisition trail. Management are very grounded here, so I think they’re more likely to get acquisitions right than wrong. Note that a NED holds almost 30%, so is likely to keep a watchful eye on things.
I’m still amazed that this little company in Lutterworth provides the network credentials management software for sections of the US Govt, and numerous huge multinationals (e.g. Boeing, Airbus). Not just a few parts of those organisations, but some licences are for hundreds of thousands of users.
Could IGP become a bid target? It's possible, but the buyer would obviously need security clearance from the US, so Chinese companies: probably best not to apply!
(As an aside, for people writing RNSs, it's best to avoid abbreviations, because readers might not know what they mean. Intercede today refers to "IDAM offerings". If abbreviations are used, it's best to provide a footnote, explaining what the abbreviation actually means!). People reading the RNSs are not going to be sector experts in everything. If I had to guess, I'd say IDAM probably means Identity Accreditation Management, but that's a complete guess). Oh, I've googled it, and I was close, IDAM means Identity & Access Management. There we are).
.
.
Restore (LON:RST)
408p (up 4% at 09:30) - mkt cap £558m
Trading Update & Dividend Restoration
Restore plc (AIM: RST), the UK's leading provider of integrated information and data management services, secure technology recycling, and commercial relocation solutions, today issues a trading update for Q2 2021, ahead of its Half Year results on 27 July 2021.
PR titles -
Trading above expectations in Q2…
In addition, as a result of the strong first half performance and continued confidence in the Group's outlook, the Board confirms its intention to reinstate its progressive dividend and pay an interim dividend payment for FY21.
That’s a nice summary actually.
Other points -
- All business units showing strong revenue growth
- Run rate of revenues is >£250m (partly driven by acquisitions)
- Cash generation strong
- Net debt in line with expectations at H1 end
- Recent acquisition (called EDM) has performed ahead of expectations so far
- Two larger, previous acquisitions performing “well above expectations”
- More acquisitions in the pipeline for H2 - over 100 potential target companies! Active discussions with over 25. Blimey. Several expected to close in H2.
Operational improvements have -
… created a stronger organisation, capable of generating sustainably higher returns.
Dividends - intends to return to previous progressive dividend policy. Level of interim divi will be set at 27 July 2021 H1 results
My opinion - I’m certainly impressed with this update, and it sounds like this share could be worth readers taking a closer look.
The breakneck pace & quantity of acquisitions does alarm me somewhat. How can so many acquisitions be integrated & managed? That does introduce risk. EDIT: the company's advisers have pointed out to me that it has 3 divisions, each with management teams experienced in M&A. Hence the workload is spread. End of edit.
The last reported balance sheet looks quite top heavy, with £247.4m in intangible assets, which is inevitable when companies do lots of acquisitions, as goodwill mounts (businesses are nearly always acquired for more than their NAV).
Stockopedia is showing the forward PER as 16.6 before today’s positive trading update, so the actual PER is probably likely to be lower. I can’t find any broker updates today.
Trading ahead of expectations, combined with what looks like a reasonable valuation, is a good combination, and can be a precursor to further share price rises, providing nothing subsequently goes wrong, and in a recovering economy, why would it?
Looks potentially interesting I reckon, although not really the sort of share that I would invest in, because I find highly acquisitive groups difficult to understand and value.
Note it’s still well below the pre-pandemic peak.
.

.
Transense Technologies (LON:TRT)
(I hold)
91.5p (up 4%, at 10:47) - mkt cap £15m
Very small & illiquid, so let’s keep this brief.
Trading update - for FY 06/2021.
- In line with market expectations (upgraded Feb 2021)
- Revenues c. £1.8m
- Profitable (no figures provided) at EBITDA and Profit After Tax (PAT) level - hence by implication I assume it must have made a small loss at the Profit Before Tax (PBT) level.
- Net cash of £1.04m (down slightly from £1.19m a year ago)
- Q4 royalties not paid until after year end, which should boost cash (again, no figure given)
- Most interesting bit - royalties run rate is up 80% since the business pivoted to a licensing model.
My opinion - a bit too much PR spin, and not enough numbers in this update!
It’s only a small, speculative position for me, as I liked the move to the licensing model.
There’s enough in this update to keep me interested, but not enough to make me want to buy more.
.

.
Porvair (LON:PRV)
582p (down c.1%, at 09:58) - mkt cap £270m
Porvair plc ("Porvair" or "the Group"), the specialist filtration, laboratory and environmental technology group, announces its half year results for the six months ended 31 May 2021.
These figures are tricky, because the prior year comps would have been impacted by lockdown 1 (the worst one). Hence trading this year should really show an improvement, which it doesn’t.
Profits are roughly flat against H1 LY, on revenue down 5% (down 2% at constant currency).
The aerospace division has been hit by the aviation sector near-shutdown. Therefore I imagine future profits should rise.
Net cash of £6.2m seems healthy.
Balance sheet overall strikes me as strong. Although note the pension deficit, shown as £10.87m
Outlook - a bit mixed, and doesn’t sound madly exciting to me -
Looking ahead, the underlying drivers of growth for Porvair all remain in place: tightening environmental regulations; the need for clean water; expansion of analytical science; the drive for manufacturing efficiency; the replacement of steel and plastic with aluminium; and the development of carbon-efficient transport.
The order book for the second half looks healthy and whilst the currently high levels of demand in Laboratory are likely to dampen as the pandemic eases, there are signs that activity levels in aerospace are starting to rebound."
My opinion - I’m always left wondering why this share attracts a premium rating, when it hasn’t really delivered anything much in organic growth in recent years.
It’s a nice enough company, generating good profit margins, and cashflows. Why would I want to pay a forward PER of almost 25 though? I suppose holders must believe that the future is much brighter than current forecasts suggest. In which case I would have expected a more bullish outlook section.
On balance then, I can’t see any particular attraction to this share at the current valuation. It’s a decent enough business, but the share price seems a bit toppy in my opinion. Maybe better value & growth elsewhere?
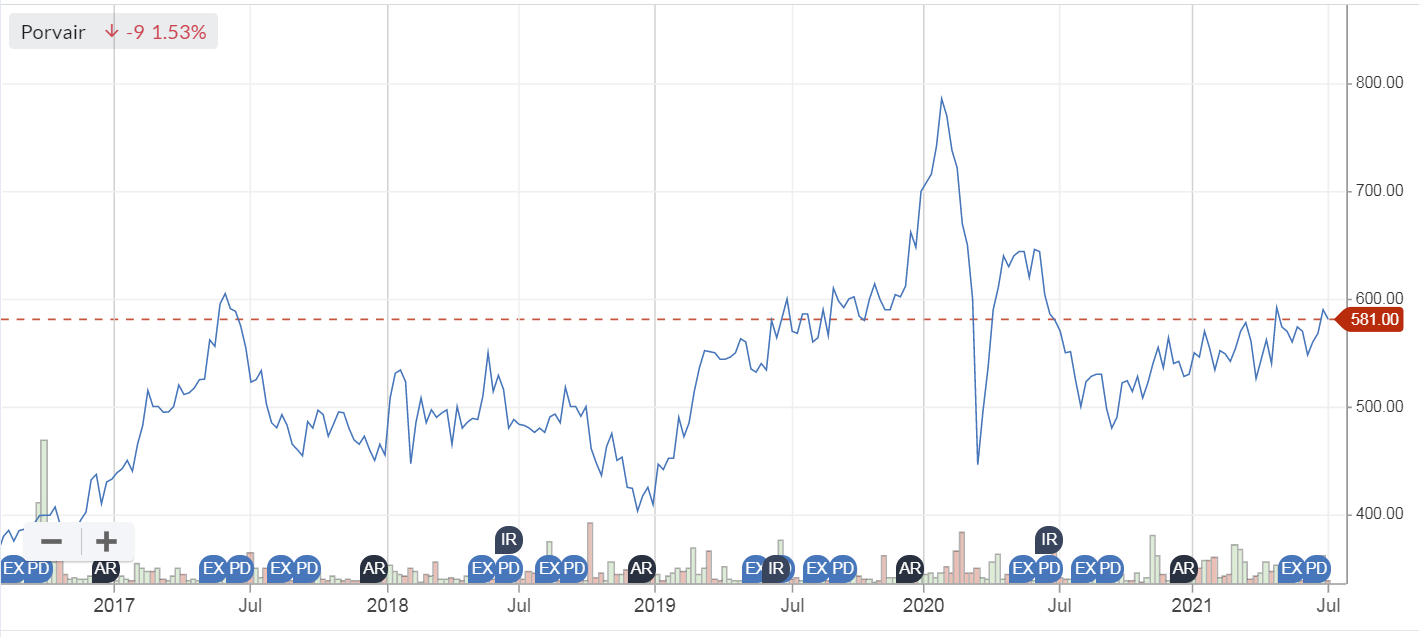
The chart below is 5-years - the trend being sideways, and with no divis over that time too. Not great. The opportunity cost would bother me, if I held this share.
.
.
Panoply Holdings (LON:TPX)
285p (up c.1%, at 14:17) - mkt cap £232m
These are quite complicated accounts, because the group is growing rapidly through acquisitions. These deals have earn-outs, so if they perform well post-acquisition, the consideration payable can increase. This created a situation where the potential dilution to existing holders could have been very large - e.g. see this explained on page 25 of the 03/2020 Annual Report - a massive increase in share count from 48.16m to 74.82m seemed to be on the cards, which put me off at the time -
.

.
However, it looks as if the dilution risk has been managed well, by getting the share price up strongly - which reduces the number of new shares that need to be issued, to satisfy the contingent consideration.
The number of shares to be issued now has fallen drastically from the position a year ago above, as follows;
As a result of the strong performance of Group companies during the current and prior period, further consideration is payable and will be satisfied through the issue of new ordinary shares. As at 31 March 2021, the total value of consideration that is payable based on FY2021 accounts is £10.9m, resulting in maximum further shares to be issued totalling 13.7m which reduces to 3.8m based on the closing share price as at 2 July 2021.
In this respect, it reminds me of M&c Saatchi (LON:SAA) - where a potentially horrible level of dilution from an options scheme was largely negated by the share price rising strongly.
It’s worth bearing in mind though, that shareholders at TPX do still face some risk - if for any reason the share price were to fall sharply, then there would be an increase in the dilution risk from new shares. Hence before buying this share, people really do need to properly understand this issue by doing your own research.
If the share price stays at or near the current share price, then issuing another 3.8m new shares really isn’t a problem any more, as that’s only modest dilution from the 81.38m currently in issue - dilution of 4.7% of the existing shares, which looks fine to me.
Therefore I think it’s fair to conclude that the dilution risk has been skilfully handled by the company, and is no longer a problem.
The other accounting issue which needs a look, is the weak balance sheet. As it’s an acquisitive group, then intangibles are piling up at the top of the balance sheet - this is almost all the premiums over NAV paid for acquisitions, so intangibles have no actual resale value as such - they don't turn into cash, like inventories or receivables do.
If we write off the £82.7m intangibles (goodwill of £53.3m, plus Intangible assets of £29.37m), then NAV of £60.65m turns into negative NTAV of £(22.1)m - i.e. weak.
Although as the commentary from TPX explains, the deferred consideration liabilities totaling £12.2m are payable in shares, not cash. Therefore it makes sense to adjust out those liabilities, which reduces the NTAV to negative £(9.9)m - still not great, but probably adequate for a capital-light business model, and a decently profitable & cash generative business.
Overall then, I’ve seen better balance sheets, and would prefer NTAV to be positive, rather than negative, but the weak balance sheet is not a deal-breaker because the group is trading well.
Trading - has been very strong for FY 03/2021 -
Revenue up 62% to £51.1m, most of the increase is from acquisitions, but within that 62% total growth, 19% is organic - impressive
Adjusted profit before tax is £5.9m (up 103% on LY)
Adjustments - are they reasonable? Mainly, yes, in my opinion. The big adjustments relate to a £4.26m charge for higher contingent consideration, and £2.46m amortisation of intangibles, which seem to relate to acquisitions. Both are legitimate adjustments, to arrive at the true underlying trading picture, in my view. There’s also a £746k restructuring provision (relating to acquisitions again), and a not unreasonable £294k share based payments charge. Put that lot together, and the statutory profit is actually a loss before tax of £1.8m - but I think the adjusted profit of £5.9m is a better figure to value the business on.
So the profits are real. I’ve looked for funnies, but it does all stack up, in my view.
Cashflow statement - similar thing. Everything looks fine to me, it’s a genuinely cash generative business. The increased borrowings were used to pay for most of the cash paid on acquisitions of subsidiaries. A tiny dividend was also paid.
Valuation - adjusted EPS is a solid number, as footnote 4 shows that it takes into account maximum potential dilution. This dropped out at 6.1p, giving a PER of 46.7 times - very expensive! Although earnings growth of 69% does seem to justify a punchy rating.
This is forecast (by Dowgate, thanks for providing forecasts, which are on Research Tree) to rise further to 8.7p this year FY 03/2022, dropping the PER to a still punchy 32.8 times. So make no mistake, this is an expensive share, but performance has been excellent, so it looks justified. Providing the strong performance is sustainable.
Outlook - again, sounds strong -
Our trading momentum has accelerated further into the current year, and we are delighted to have signed approximately £18.6m in new contracts in Q1 FY2022. This is a record quarter for the Group and this performance, together with the existing sales backlog we had built in FY2021, means we now expect revenue and EBITDA for FY2022 to be significantly ahead of current market expectations and to deliver analysts' expectations for FY2023 a full year early.
Note that the Dowgate forecast of adj fully diluted 8.7 EPS for FY 03/2022 was issued this morning, and does already include a 19% upgrade to reflect today’s strong trading update.
My opinion - taking a fresh look at Panoply, I feel much more comfortable with the numbers. The dilution risk has now drastically reduced, to a level where it’s no longer a problem. The balance sheet isn’t great, but is adequate.
Trading remains strong.
I like the niche this group is targeting, especially public sector work, which as we’ve seen with other software companies, can last for years, and be very lucrative.
There’s a video presentation from the company here.
Overall, my view is turning positive. The valuation looks a bit stretched, and everything hinges on the group being able to maintain and further grow the increased profits. Although so far, so good.
.

.
Jack’s section
Franchise Brands (LON:FRAN)
Share price: 150.5p (pre-open)
Shares in issue: 95,758,470
Market cap: £144.12m
As the name suggests, this company specialises in acquiring and building various franchises, with a combined network of 400 franchisees across five brands. B2B brands are Metro Rod, Metro Plumb, Willow Pumps, and B2C are ChipsAway, Ovenclean, and Barking Mad.
It’s growing revenue fast, with a compound annual growth rate over five years of some 62.3%, but the share price is up around 50% in 2021 alone. It’s now more or less back to all-time highs.

The forecast PE ratio is up to 26.2x and the forecast PEG is 1.1 though, so even accounting for the strong growth you might argue the shares are fairly priced at these levels. That said, it has often traded at high multiples in the past as well, and share price has appreciated regardless.

Trading update for the six months to 30 June 2021
Record-breaking system sales at Metro Rod
System sales at Metro Rod have returned to pre-COVID growth levels, up 21% compared to H1 2020 and 17% compared to H1 2019. That makes for record system sales of £23.8m (H1 2020: £19.7m; H1 2019: £20.2m). Franchise has benefitted from released pent up demand here, with record system sales in June of £4.3m - an increase of 41% on H1 2020 and 26% compared to H1 2019.
Willow Pumps (acquired in October 2019), has a greater exposure to hospitality and was more impacted by lockdown. Franchise was unlucky with its timing here.
Invoiced sales still increased by around 9% compared to H1 2020, however, and it continues to facilitate the growth of pump-related work within Metro Rod. Pumps system sales by franchisees have increased 159% to £0.7m (H1 2020: £0.3m).
The B2C division has also performed strongly, and 40 new franchisees have been recruited taking the number of B2C franchisees to 393.
Overall, the Group's trading in the first half gives the Board strong confidence in delivering a full year performance at least in line with market expectations and it will provide a further update on current trading and outlook at the time of the half year results.
The interims are expected on 22 July.
Conclusion
Franchise ownership can be a robust and cash generative business model when there are the correct brands and franchisees to back it up, so a high multiple can be justified.
But, as above, it does seem as though the shares are up with events for now.
There is a degree of shareholder dilution over time but earnings per share have been increasing. The balance sheet is in decent shape, cash generation is increasing, and growth rates across the board are encouraging. It looks like a well managed company.
The only real sticking point is valuation. It’s not eye-wateringly expensive, but it does suggest upside in the short term could be limited - unless the group can surprise the market with good organic growth (continuing beneficiary of pent up demand?) or negotiate a good acquisition.
Franchise certainly has growth ambitions. It has said before that it continues to look for acquisitions and might even create a third division. Back in March, it set targets of a £100m revenue run rate and adjusted EBITDA of £15m, all to be achieved by the end of 2023.
That would be close to double the current rates of revenue, so it remains a stock to watch. Directors have also made purchases recently at close to the current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Paul , many thanks for your general market musings. It is always good to see your general views along with specific company thoughts.
I see that the love affair with Best of the best is over and the shares have abated by one third because the owners unloaded a chunk of stock a short time before a profit warning.
Lorenz Hart (partnered with Rogers before Hammerstein). Hart sadly drank himself to death. He was a great song writer. He summed it up”
“ when love congeals, you can small the odour of performing seals, the double crossing of high heals. I wish I was in love again.”
it will take some time.
Paul, I found your opening comments on D4T4 interesting.
Seems you accept the investment in new customers for them but not for Naked Wines.
Just an observation as when I was reading it it made me think of the Naked Wines model.
I hold Naked and have had D4T4 on my watchlist. I am tempted to buy in at this lower entry point.
Panoply Holdings Panoply Holdings (LON:TPX) - I hold.
Further to Paul's note - the biggest adjustment is a £4.26m charge for higher contingent consideration - having watched their presentation they say that this method of paying for acquisitions is not going to be used going forward - there is one that rolls up in the first half of this year and one in the second, but after that it is cash/ debt and shares, which does of course bring the prospect of some further dilution. They have headroom on a facility with HSBC, and are generating good cash, which should hopefully keep the dilution under control, and they do point out that acquisitions should be earnings accretive immediately.
I'm reluctant to buy shares on fancy multiples - I could never bring myself to buy Kainos as they always looked 'too expensive' but they kept growing and the share price kept going up, and I'd take another look and they still looked 'too expensive'. I bought this six months ago, it has already done quite nicely, and I plan to hold tight for a while.
Paul,
I admit I don't understand your comments on D4T4. This is a company that has just reported for FY21 the lowest net profit and operating margin since it's records on Stockopedia started (2016). And yet supposedly the change to a recurring revenue model is progressing smoothly?
It's barely, increased revenue in that time either and still relies on lumpy one-off licenses for 53% of sales. This means it always appears to be scrambling to close sales in H2 every year to meet numbers, and yet it's on a PER of 48. It makes no sense to me and I can only conclude the share price is held up by"Greater Fool Theory". Not what I'd be looking for if I had a coffee can...
I wish you luck with it!
All the best, Si
Just to add to Simoan's comments on D4T4, I was also a bit concerned to see that some of the company's most experienced management are retiring at similar times, although they are being replaced by experienced personnel. Also, I notice that the company's Celebrus product already included some fraud protection capability as early as 2019 but I guess they must have developed it further to justify the more recent annoucement that they are moving into this market.
Paul, could you comment on The Panoply's results published today? There is a PI World webinar with them today too. Thanks, Chris
Hi Chris,
Yes, I'm looking at Panoply Holdings (LON:TPX) now actually! The section should be up here by about 2pm, as I'm taking a break first to rest my eyes from staring at a computer since 06:30, and have some lunch.
Regards, Paul.
It was worth waiting for - really useful insights that I hadn't fully considered before. Thanks Paul!
Here are my SCVR heat maps for today (prices as at ~9:55am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Hi Paul,
I'm surprised you're not a little more bullish re Intercede (LON:IGP) update this morning but maybe my calculations are overly optimistic. Given the vast majority of their revenue is recurring, and their high operational gearing levels mean most of the 600k drops to the bottom line, I calculate a forward PBT of £2m+ for Y22 with 3 quarters of the year to go. Assuming some further sales this year then the forward PE could be as low as 20. Am I being widely optimistic?
All the best and thanks so much for all your analysis
Intercede (LON:IGP)
Kouremenous
"I'm surprised you're not a little more bullish re Intercede (LON:IGP) update this morning but maybe my calculations are overly optimistic. Given the vast majority of their revenue is recurring, and their high operational gearing levels mean most of the 600k drops to the bottom line,"
How do you know these revenues are not already baked into current/next year company expectations?
If they are then they don't really tell us anything today that we didn't already know and expect previously.
Note the company has not updated expectations as far as i can see ref sales or profits so i am kinda presuming these signed contracts are part of what they previosuly expected to arrive at some stage or not material enough to change the picture ref expectations.
This being the case only very modestly positive news at best.
Note if expectations have now changed and they are giving nudge nudge wink wink to brokers and are telling us nothing in official release - this isnn't exactly creating a level playing field for pi's and brokers and their best buddies - unless you are a best buddy.
Thanks for the reply rmillaree. Perhaps that's what I am missing!
However in the past updates on contract wins have included statements such as;
"The contract was included within the directors' expectations for the current financial year ending 31 March 2021."
Ever hopeful I read these as in addition to expectations :-)
Intercede (LON:IGP)
However in the past updates on contract wins have included statements such as;
The contract was included within the directors' expectations for the current financial year ending 31 March 2021."
Ever hopeful I read these as in addition to expectations :-)
Ok thats good to know i see you logic here - however they have gone from being clear and transparent to opaque and obtuse in that regard now
Hey ho - if it aint said i wouldnt presume it other than we are forced to presume way to much trying to work out what companies say (or aren't saying but mean) most of the time nowadays.
all good fun and games.
Just heard on Ian King - SkyNews - that Hypnosis Songs Hipgnosis Songs Fund (LON:SONG) are about to launch a dividend next yr after a rise in profits. The Stock Rank and previous commentary has leaned toward avoid. Wonder if this thing will go anywhere. I don't hold. The catalogue looks like songs I would never listen to......B Manilow, 10cc!
It holds an incredible catalog of songs most of which were initially modern artists or producers like Mark Ronson / Timbaland / Poo Bear (don't) - it's incredibly diverse. You need to take a better look!! I used to hold but not sure that the business model stacks up long term as they paid a lot of money for these rights,
Just heard on Ian King - SkyNews - that Hypnosis Songs Hipgnosis Songs Fund (LON:SONG) are about to launch a dividend next yr after a rise in profits.
They already pay a dividend. The problem is that while they're in build out mode they're raising far more in new money than they're paying out in order to buy song portfolios. They pay a dividend so they can be picked up by income funds, but in investing terms it's pointless, they'd be better off retaining the dividend cash and buying more tunes.
The other imponderable here is what the actual value of these songs is and to what extent valuations are being bid up by competition. Who knows what the royalty will be on one of these songs in a decade? You can imagine that if a small number of these companies control a significant portion of the catalogues then they'll be able to push prices up. Or maybe not.
In the fullness of time - when they've stopped buying portfolios and the valuations have normalised - then this will probably be a very useful alternative asset class. But at the moment it's guesswork.
timarr
I think I heard they were paying around 16x earnings for the catalogues (on average, some will be more expensive) which doesn't seem excessive as they are also seeing good growth from increased streaming. I think the older catalogues should provide a very reliable income stream for many years, but not sure about newer songs. They have been increasing exposure to older catalogues though with around 60% held in 10y or older vintages. Overall worth holding I think for its non-correlated qualities and prospect for valuation gains.
I think I heard they were paying around 16x earnings for the catalogues (on average, some will be more expensive) which doesn't seem excessive as they are also seeing good growth from increased streaming. I think the older catalogues should provide a very reliable income stream for many years, but not sure about newer songs
Although it's been a very peculiar year the eps has dropped from 8.13c to 4.73c - putting Hipgnosis Songs Fund (LON:SONG) on a P/E of 35. A big jump is forecast next year, but I'm not really sure why.
The proposition is good, I'm just not convinced by the timing as an investor. Shares in issue have more than doubled in two years and Merck Mercuriadis has indicated that the pace of acquisition will carry on for at least five years. Obviously the money is being spent on assets - songs - and those generate earnings. I'm just not sure how anyone can know what the value of those earnings will be in five years time.
The whole thing, including the prices paid and the valuation of the portfolios, is very opaque. I'd rather sit on the sidelines and see this develop - hopefully it'll turn into a proper alternative asset class, but the evidence so far is decidedly mixed.
timarr
Hi timarr,
I bought a few Hipgnosis Songs Fund (LON:SONG) in March 2020, mainly because I couldn't understand why it had fallen in-line with the market when its source income was clearly uncorrelated, and as we have subsequently found out, I assumed people would listen to even more music during the lockdown. I also took part in a C share placing via Primary Bid which made a small return but I have offloaded those.
Although it's been a very peculiar year the eps has dropped from 8.13c to 4.73c - putting Hipgnosis Songs Fund (LON:SONG) on a P/E of 35. A big jump is forecast next year, but I'm not really sure why.
I'm not sure P/E is a useful valuation metric for these strange types of investments; it's a bit like all those infrastructure funds. Although on any valuation metric it looks expensive!
The whole thing, including the prices paid and the valuation of the portfolios, is very opaque. I'd rather sit on the sidelines and see this develop - hopefully it'll turn into a proper alternative asset class, but the evidence so far is decidedly mixed.
I agree, and I'm a pretty weak holder of the stock I bought last year - I'm not an income investor! However, it does seem that they actively manage the songs in a way the original owner would never do i.e. they have a team actively placing songs in films, ads and encouraging new cover versions by major artists to increase the income streams. So I believe longer term there is scope for them to add value by increasing revenue and profit (which should be very high margin) through more active song management.
BTW I watched the film "Yesterday" on iPlayer last night - typical Richard Curtis script, directed by Danny Boyle, interesting premise with a few laughs but otherwise turgid! - and noticed that they had to pay $10 million for use of the Beatles songs in the film. I Imagine a biopic of Neil Young, or one of the other artists whose catalogue they own, would generate a really nice little earner!
All the best, Si
I've held Song now for a couple of years now and have got a total return of 28% so far so I am reasonably happy with what should be a strong performer over time, with compounding.
It is an unknown to a degree but I am hopeful it'll continue to do a reasonable return over time. The only thing I would add as a concern as there's new music created every week so I am not sure they will ever stop needing to raise money to keep buying new songs. It should hopefully slow down over time but the need to raise money might never end.
Also worth checking out Round Hill Music Royalty Fund Lp (LON:RHM) which is arguably a more interesting opportunity than Hipgnosis Songs Fund (LON:SONG) as it is much more heavily tilted towards older catalogues (60s-80), and the team has more of a proven track record (they run some private music royalty funds and have generated some very good returns over past decade).
If you are one of the many Stockopedia fans who are, like me, interested in investment trusts, such as SONG, you might like the free weekly Money Makers investment trust podcast I record each week with Simon Elliott, head of investment trust research at Winterflood Securities. We cover all the major announcements of the week in an hourlong podcast and currently have 1300+ regular listeners, including many professionals..https:/money-makers.co.
Talking of being happy with current holdings Paul, would love to see the Part 2 of your top holdings you hinted at. It puts a lot of context behind your SCVR writeups.
Morning Liquidium,
Talking of being happy with current holdings Paul, would love to see the Part 2 of your top holdings you hinted at.
Ah yes, I'd forgotten about that! Will add it to my To Do List.
Regards, Paul.
Hi, does anyone have a link to the article for part 1 of Paul's top holdings? I must of missed it.
Thanks
Tom
here you go: https://www.stockopedia.com/co...
Wm Morrison Supermarkets (LON:MRW) Morrisons (no holding) another example of a non disclosed bid which has been mentioned on here before. "said an initial unsolicited proposal was received
from Fortress on May 4 at 220 pence a share. This offer was not
made public."
Completely agree on the Bournemouth busy comments, first time I've been down there in a while, mid week Mudeford was packed with staycationers lapping up the sunshine, and with some of the holiday caravans being put on the market for 700k (which is madness) and beech huts @ 250k, the midweek age range seemed to be seniors and queues forming at cafes all day long, says to me, that money is being spent in large quantities, I just picked up a few Revolution Bars (LON:RBG) backing up my feeling about a surge in recovery, certainly for the sunny couple of months ahead of us, with the head wind of potential future restrictions
Good morning Paul, and Jack. Loving the general market commentary. Things aren't quite as busy here in Manchester, I am not sure people can be bothered with the queues, booking for drinks, and some people don't like ordering over an app. Young people take this in their stride, they are desperate to get out, but I thought it was missing some people from an age group of around 50 years of age. When full restrictions lift I think you will see another ramp up in socialising. Also on the subject of "Coffee Can" stocks Intercede (LON:IGP) looks good this morning, with more positive news, so would appreciate your thoughts. Thank you.
Hi Paul, could you please have a look at TRT? 80% growth in royalties is significant. Thank you.
Good morning Naan Deal,
Yes, I'll put up a brief comment on Transense Technologies (LON:TRT) (I hold) a bit later. Very small mkt cap though, so I should probably prioritise bigger, more liquid things first.
Regards, Paul.
Thank you very much
Panoply Holdings (LON:TPX) FY21 results interview: strong with revenue up 62%, 19% organic. Sales order backlog £39m to be generated by March 22. For FY2022 both revenue and EBITDA will be significantly ahead of market expectations and they expect to deliver analysts' expectations for FY2023 a year early. Video & podcast.
There is a Panoply Holdings (LON:TPX) results webinar with management at 12 noon today. Register here.
Separately if you haven't seen Stuart Widdowson's interview: Investing with a rivate equity lens, it's excellent. Video & podcast.
And, there's two webinars this week and next week where Listed Private Capital cover funds which give PE and credit investments exposure where they will outline the investment case and opportunities. Register here.
My morning smallcap tweet:
Intercede (LON:IGP) Eden Research (LON:EDEN) Batm Advanced Communications (LON:BVC) Restore (LON:RST) Franchise Brands (LON:FRAN) Lokn Store (LON:LOK), Transense Technologies (LON:TRT)
Intercede (IGP) Q1 sees orders from 6 new customers worth over £600k. [SP=102.48 Cap=59m]
Eden Research (EDEN) bionematicide, Cedroz, authorised in Morocco and biofungicide, Mevalone, authorised in Romania. [SP=10.9 Cap=41m]
BATM Advanced Communications (BVC) $10m defence order for an advanced cyber security solution; expected to complete in 2023.. [SP=92 Cap=407m]
Restore (RST) trading continued to strengthen in H1. Q2 ahead of mgmt expectations. Will resume progressive dividend policy. [SP=391 Cap=534m]
Franchise Brands (FRAN) guides FY(Dec) at least in line with market expectations . [SP=149 Cap=143m]
Lok'nStore (LOK) Significant development of new store pipeline, will result in 51 stores. Will be funded from revolving credit facility, operating cash flow, and proceeds of sale of surplus land. [SP=650 Cap=193m]
In line: Transense Technologies (LON:TRT)
Morning chaps, it would be great to have your insight on the Panoply Holdings (LON:TPX) results this morning. Current trade is expected to meet 2023 forecasts a year early. I hold.
Hi Leebod, do you think liquidity in Panoply Holdings (LON:TPX) may present problems for PI's? I do not hold.
Silver
I've never had issues buying and selling before but I've only been dealing in smallish quantities upto £10k but that was a year ago. The spread used to be horrendous but as it's price has moved its now more reasonable. Cheers.
Thanks Leebod.
Hi Leebod,
Strange, Panoply Holdings (LON:TPX) didn't come up on my usual scan of the RNS first thing, so thanks for flagging it. Yes, I'll take a look at the numbers & report back later this morning, or early afternoon.
I've not been convinced by TPX in the past, but will approach if with fresh eyes today.
Regards, Paul.