Small Cap Value Report (Thu 1 Feb 2018) - IGE, COM, SPSY, CTO, ALU

Good morning, it's Paul here. I have a lunchtime meeting in London, so will only be able to rattle out a few sections early. I'm hoping that Graham might then be able to add a bit more this afternoon.
I added more sections to yesterday's report last night, so here's the link to that.
Let's start with a profit warning;
Image Scan Holdings (LON:IGE)
Share price: 4.25p (down 38.2% today, at 08:21)
No. shares: 136.0m
Market cap: £5.8m
(at the time of writing, I hold a long position in this share)
Trading update (profit warning)
Image Scan (AIM:IGE), the specialist supplier of X-ray screening systems to the security and industrial inspection markets provides a trading update for the year to 30 September 2018 ("FY18").
This is a tiny company, below our usual market cap size. However, 2 readers have already mentioned it this morning, and I hold personally (more's the pity), so I naturally want to look at it, and see what's gone wrong.
The company made a series of positive updates over the summer, which drove the share price up substantially. This also allowed a big holder to exit, via a discounted secondary placing done through the house broker. I took part in that placing, thinking I was getting a bargain. They tried first to sell at 10p, then reduced the price to 8p, when the market price had been around 11-12p. So an apparent bargain. Since then, the share price has dropped by almost two thirds.
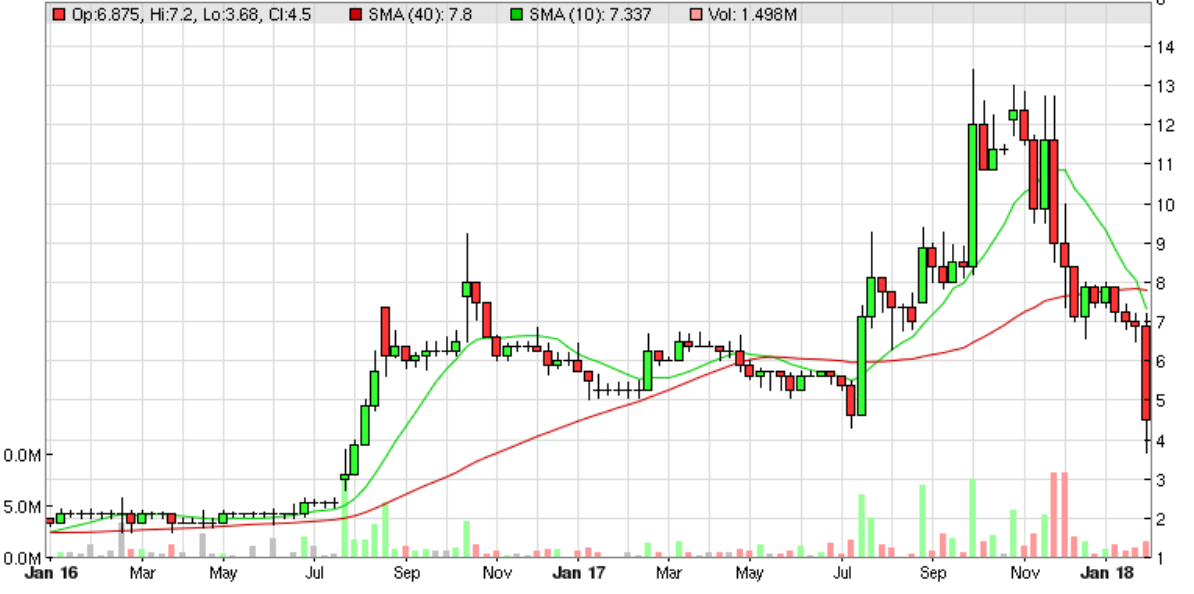
There was the first sign of trouble, which I mentioned here on 6 Dec 2017, with the company referring to delivery dates not yet being finalised on a proportion (not stated) of the order book. A reader mentions in the comments that he sold out at the time, sensing trouble ahead. That was a great move. Sadly I didn't have that option, due to my having a position size that's too big to sell in the open market. So I'm in for the duration here.
Profit warning - today the company drops a bombshell, that a £1m order is likely to be cancelled (on unknown terms). That's a material figure - the company did £5.0m revenues last year, and £3.3m in 2016.
Here's the key bit in today's announcement;
The order was made up of largely standard portable X-ray products and, though the Board is confident these units can be sold to other customers, this may not occur in FY18.
Whilst the Board expects FY18 sales to be weighted towards the second half and the Company to remain profitable for the financial year, given this development the Company now expects its trading performance for FY18 will be materially below current market expectations.
The dreaded H2 weighting - so that means interim results are probably likely to be poor. Although remaining profitable for the whole year suggests that this is a setback, but not a disaster.
In terms of financial impact, this means inventories are likely to be increased, and that's bound to put a strain on cashflow.
Balance sheet - is quite strong. By my reckoning, I don't think this issue is likely to trigger a financial meltdown. Inventories were already quite big (probably including some or all of the disputed order), and the company had £1.25m in net cash as at 30 Sep 2017. The current ratio was 1.81, with a working capital surplus of £1.8m (i.e. current assets exceed current liabilities by this amount).
Therefore it looks to me as if today's setback probably won't trigger any financial problems. The balance sheet looks strong enough to absorb the loss of this contract.
My opinion - incredibly disappointing. I thought it was strange that the company did a series of positive updates in the summer. It's difficult to shake off the feeling that those of us who took part in the 8p secondary placing were stitched up!
That said, the share price has fallen so much now, that I think risk:reward is looking favourable again. It expects to remain profitable this year, and has interesting new products which had been selling well until today's bombshell. At this price, I certainly won't be selling, and could even be tempted to top-up.
That said, the lack of liquidity means that anyone holding more than a small scrap of shares is locked in for the duration, whether they want to be or not. I very much dislike tiny, illiquid shares, for this reason. You buy them in the hope that the odd one will be a multi-bagger, but given that you can't exit when something goes wrong, risk:reward can actually be very poor with the smallest shares on the market.
Comptoir (LON:COM)
Share price: 19.5p (up 2.6% today, at 08:52)
No. shares: 122.7m
Market cap: £23.9m
Comptoir Group plc, the owner and/or operator of Lebanese and Eastern Mediterranean restaurants, is pleased to today announce a pre-close update for the 52 week period ending 31stDecember 2017.
I'm not a fan of this small restaurant group. The format seems to me like a glorified kebab shop. There's one at Gatwick Airport, and the rest are mainly in London.
I was expecting another profit warning, given how dire the casual dining sector is at the moment - due to over-supply, and cost pressures. However, this is surprisingly good;
Despite a difficult market backdrop, the Directors are pleased to report that trading for the 52 weeks to 31st December 2017 was above market expectations. The Company had a strong trading performance during the second half of 2017, ending in a busy December.
As announced within the interim results of the Company, published in September 2017, the Company has focused on controlling its costs and improving its operational efficiencies and margins where possible. The Directors expect this focus to continue throughout 2018.
Now the difficult bit - what are market expectations?! Since the regulators (may their headphones snag on every door handle) imposed MiFID II, we can't get hold of much broker research. For this reason, I implore companies and their advisers to clearly state in every trading update what they believe market expectations are (in a footnote). Some companies already do this, and there's no valid reason why it cannot be done. Without this crucial information, many investors are left in the dark, and are therefore not likely to buy the shares.
Stockopedia (whose data comes from Thomson Reuters) shows a forecast net (i.e. after corporation tax) loss for 2017 of -£0.7m. So beating that number (by how much, we're not told) doesn't necessarily mean the company is profitable.
Still, at least things haven't got any worse.
New sites - 3 more were opened in H2 of 2017. Given that the company is struggling to reach profitability, is it wise to roll out a format that isn't really working very well? If they're getting amazingly low rent deals, then maybe, but we're not told rental terms. It now operates 26 restaurants, with another 3 franchised sites. Two more new sites are planned for 2018.
Sale of CPU - I think they mean a building, not a computer chip. Central processing unit, is my guess for the meaning of CPU in this context. Companies & advisers should avoid abbreviations in announcements, since not all readers will necessarily know what they mean. This has raised cash of £2.6m.
EDIT: I've just looked back at the announcement of 19 Oct 2017 which says that;
Completion of the sale is expected before the end of the current calendar year.
Therefore it looks likely that the £4.5m net cash below includes the proceeds from this disposal.
Net cash was £4.5m at 31 Dec 2017. It is not stated whether this includes the £2.6m from the CPU sale, or not. Why introduce such an ambiguity? Does nobody sense-check these announcements before they're published? (see edit above)
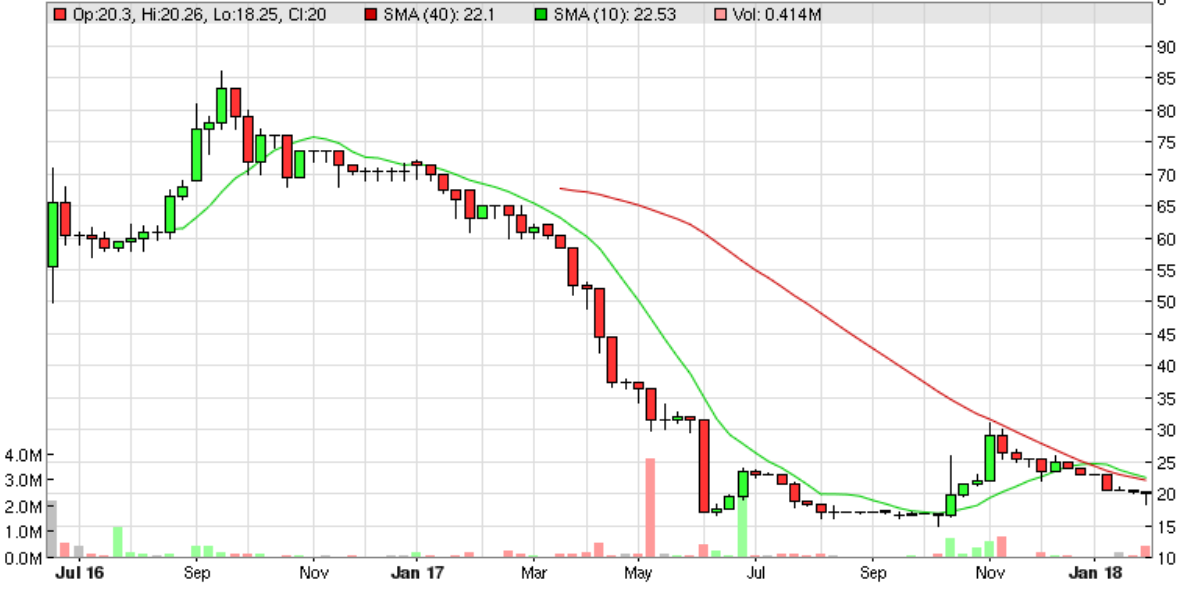
My opinion - if you fancy buying into a small restaurant chain that's struggling to operate at breakeven, then this could be your chance! Valuations in the sector have come down to more reasonable levels, although the £23.9m market cap here values the business at about £824k per site. This seems way too high to me, given that the business doesn't make a profit overall. Maybe things will improve in future, and its financial position looks fairly sound. I'm not interested.
Not a very successful float, since June 2016;
Spectra Systems (LON:SPSY)
Share price: 123p (up 18.8% today, at 09:40)
No. shares: 45.4m
Market cap: £55.8m
Spectra Systems Corporation, a leader in machine-readable high-speed banknote authentication and brand protection technologies...
There's more good news for shareholders here, this company seems to be on a roll;
... announces that it received confirmation yesterday from its licensee for covert materials supplied to 18 central banks that the royalty component of the licensee's payments will be higher than previously expected for 2017.
As a result, Spectra estimates that its profits for the year ended 31 December 2017 will exceed market expectations.
No indication of the amount is given, so we're left in the dark, to guess at the financial benefit of this good news.
Broker update - thankfully the house broker is on hand to give us some guidance. House broker notes are treated as commissioned research, hence can still be distributed under MiFID II (may the regulators' socks rotate just enough to be uncomfortable)
Estimated profit for 2017 is increased by 18% to $4.0m, 8.6 US cents EPS. That's 6.0p EPS for 2017, and the same forecast for 2018. At 123p that looks like a PER of 20.5. To determine whether that's a reasonable price or not, we would have to find out whether earnings are sustainable, and likely to increase further, or not? I haven't looked at the company closely enough to form a view on its future prospects.
Balance sheet - is excellent, with plenty of cash.
Dividends - nothing as yet, but I see that quite generous divis are forecast to start shortly.
My opinion - this looks an interesting company, worth a closer look. The key issue is understanding its products & markets, and determining how well they are likely to sell in future. Although reading that back to myself, that's the key issue with every share!
Spectra seems to be generating out-performance at the moment from one key customer, which is obviously more risky if something were to go wrong. It sounds like a big customer too, supplying 18 central banks. I wonder if it's De La Rue (LON:DLAR) ? Major customers like that can act as very good references for selling to other customers. All in all, it looks intriguing.
T Clarke (LON:CTO)
Share price: 78.4p (down 6.0% today, at 10:11)
No. shares: 41.8m
Market cap: £32.8m
TClarke plc ("TClarke" or the "Group"), the Building Services Group, announces a year end trading update for the financial year ended 31st December 2017.
This business specialises in complex electrical & IT installations, e.g. for office blocks under construction or refurbishment.
This is how trading updates should be done by all comapnies:
The Board is pleased to report that the expected outcome for the year is in line with current market expectations, which are an underlying profit before taxation of circa 6.5m and revenues in the region of 310m.
It's so simple, why can't all companies do this? I wish they would. Tell us how you've performed versus market expectations, and then tell us what those expectations are. Simple, clear, everyone can understand it, and we don't have to struggle to find broker forecasts, which are often now unavailable.
Cash position looks good;
After an aggregate 3m investment in the ETON acquisition and at our manufacturing facility at Stansted, the Group's cash generation remains robust with the year end net cash position improving by 27% to 11.7m, the strongest closing balance recorded since 2009 (31st December 2016: 9.2m).
Order book - down slightly, but I like the comments about tendering sensibly. We don't want the company to "do a Carillion" and get into bother from under-pricing contracts;
Our forward order book as at 31st December 2017 has strengthened to 337m compared to 330m at 31st December 2016. This has eased back from the record high reported during the course of 2017, a reflection of our selective approach to tendering rather than lack of opportunities.
My opinion - I don't touch any contracting businesses any more, so it's not for me.
Right, I have to dash, for a lunchtime meeting in London. Hopefully Graham might be able to add some extra section(s) this afternoon.
Regards, Paul.
Hi, Graham here picking up the baton to add to Paul's article.
Alumasc (LON:ALU)
- Share price: 159p (-8%)
- No. of shares: 36 million
- Market cap: £57 million
We've occasionally written on this supplier of premium buildings products before.
The operations are split in the following categories: Solar Shading & Architectural Screening, Roofing & Walling, Water Management, Housebuilding.
A year ago, at 175p per share, I said the stock was in value territory at a PE ratio of c. 9x.
Offsetting this was a £33 million pension deficit, requiring annual payments of £3.2 million - quite a lot of forecast earnings.
Overall, I was reasonably impressed with the company's performance.
Fast-forward a year, and the numbers have deteriorated a bit:
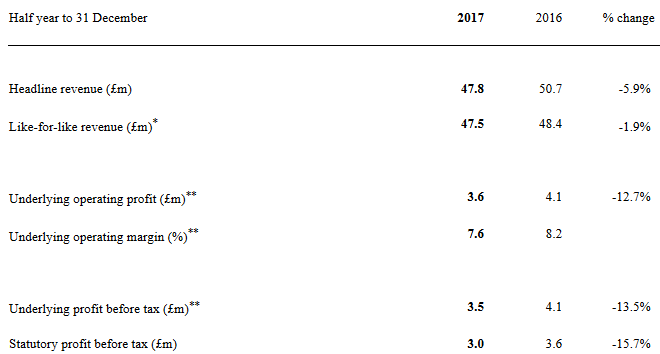
Like-for-like revenue excludes revenue from a division which was sold in July 2017 - fair enough.
Underling profit excludes some "one-off" costs and gains - these seem like reasonable adjustments to look at the underlying business, but you'll see from the above table that they amounted to negative £0.5 million both this year and last year. They were negative £0.6 million the year before that. Perhaps we should just leave them in, since they tend to crop up most years?
Alumasc describes the performance as "satisfactory" versus a flat UK construction market and input cost inflation.
We are guided for a second half weighting. Checking last year's interim results, this was promised last year too!
Checking what happened last year, the promised second-half weighting did indeed materialise:
- H1 underlying EPS 9.1, PBT £3.6 million.
- Full-year underlying EPS 20.1, PBT £8.1 million.
So when Alumasc guides for a better second half this time around, due to "large project phasing", I'd say this is quite credible.
On that basis, maybe PBT will again approach £8 million for the full-year?
Brokers were previously forecasting PBT of £9.5 million, which looks a bit aggressive to me at this stage.
UK revenues are up 1% versus a flat market, so maybe there has been a small increase in market share. Revenues are a bit lumpy, so we can't expect market share to go up strongly every period.
In terms of the operating divisions, the biggest contributor to profit is water management
This division's revenue are up 4% year-on-year, with slightly reduced operating profit thanks to lower sales of its higher-margin drainage products and higher input costs.
Order book is down by a few million to £25 million.
Acquisition
There's an £8 million acquisition of a drainage business, paid from existing banking facilities (Alumasc is actually paying £14 million, but will benefit from the target's £6 million in net cash).
The target made £1.4 million in PBT from capital invested of £3.2 million. Not only does this sound like a good deal in terms of the earnings multiple, it also sounds like a high-quality business - check out that ROIC!
Outlook - the outlook is in line with previous expectations. Which suggests that £9.5 million in PBT is still on the cards.
My opinion
I had a positive impression of Alumasc the first time I covered it, and I still do.
I like its intense focus on margins. Though margins aren't very high, it has nevertheless achieved good returns:
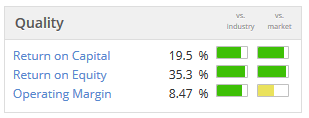
With this acquisition, it has found a productive way to use its cash balance. The new company also earns great returns on capital, and hopefully the combination with Alumasc can be even better than the sum of its parts!
You have to add about £30 million to the market cap to account for the pension deficit, so the valuation is not that cheap. And revenues are bit lumpy, leading to this last reduction in half-year sales. But it looks like a decent company all the same, so maybe there is room for it re-rate higher over time.
I'm not seeing too much other news to comment on, so I'll call it a day there.
Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Apologies for the off topic question, but does anyone have experience investing in North America, i.e. nasdaq?
There don't seem to be equivalents of "trading updates" that I can find. I searched various company documents on sadar.com but can't find any commentary on how companies are performing against expectations, which I find to be of enormous value.
@TomJoons
This has been asked before and there doesn't appear to be a direct equivalent. The best way I know is to open an account at seekingalpha.com and set up a portfolio there with e-mail alerts. The transcripts of earnings calls will then get e-mailed to you along with other articles.
I find those transcripts very helpful - you get to hear directly from management and see the Q&A from the analysts on the calls. Or if you want to listen in directly then the time difference sometimes helps. For example the Apple call will be here in 40 minutes:
https://www.apple.com/investor/earnings-call/
Thanks for the suggestion, will look into it!
Spectra Systems (LON:SPSY) Paul , thanks for your reports as always.
Does the broker forecast same for the yr 2018 of EPS 6p , ie Flat growth for that yr or a repeat of an 18% gain. Your far better at interpreting broker results than I am.
The CPU referred to by Comptoir will be there Central Production Unit. Presumably a sale and leaseback to help cashflow. I actually like this brand as providing a reasonable combination of value and quality but doesn't look investable at a PE of 66.7.
Deltex Medical (LON:DEMG) Anyone else hold? I have just sold at 1.3106p and taken up the subscription offer at 1.25p in the hope of replacing shares just sold, and I should get a tax refund under EIS of 30% so effective cost of the replacement shares to me is just 0.875p. If I have the wrong end of the stick let me know, but if I am holding both wrong ends please keep very quiet!
Regards,
Seadoc
PS Not suggesting this is a buy, just for info if you already hold.
Hi Paul,
SPSY has paid a dividend of 5c in June 2017. The following is from the Preliminary Results RNS in March 2017 :
"With the Company having reached sustainable profits and having sufficient resources to execute on its growth plans with its existing cash reserves, the Board is delighted to start paying dividends. It intends to pay an inaugural annual dividend of USD 0.05 per share in June of 2017 and thereafter to pay the dividend in June after the audited close of each fiscal year."
With the constant increase in forecasts - which are probably still short of what will be reported - I would be surprised if the dividend is not increased this year.
The Image Scan Holdings (LON:IGE) announcement has raised a more general question for me. For companies that have long, international order books, how do they handle contractual agreements to deliver beyond March 2019? Is it possible contractually to agree to deliver products to non-UK markets with the present level of uncertainty?
Re exports beyond March 2019 (and, nominally, Image Scan Holdings (LON:IGE) ): Do you expect an impact on deliveries to non-EEA countries?
It probably depends on who you listen to. An excerpt from http://www.cer.eu/insights/transition-and-trade-deals . It's two weeks old so maybe it's changed but it suggests some level of legal uncertainty in the absence of new agreements.
"While the transition agreement is still subject to negotiation, the Commission’s draft proposal states that once the UK has withdrawn from the EU it will “no longer benefit from the agreements concluded by the Union”. This is not pernicious, simply a statement of fact: the UK will no longer be an EU member, therefore the EU’s international treaties will no longer apply to it. The proposal further specifies that the 27 will only assist the UK in finding a way to extend the agreements during the transition period if it is deemed to be in the interest of the EU.
As well as binding the UK to the EU’s single market and customs union, the draft proposal seeks to ensure that the UK continues to apply the bloc’s external tariff rates and performs the same border checks with non-EU countries.
This could easily result in a scenario in which UK exporters are no longer able to take advantage of the EU’s existing free trade agreements, but exporters located in countries with EU FTAs would continue to benefit from preferential access to the UK market on the same terms as now. To give a practical example: during the proposed transition, Korean car exporters would still be able to sell cars into the UK without being subject to border tariffs under the provisions of the EU-South Korea free trade agreement. UK car exporters selling into Korea, on the other hand, would no longer be covered by the agreement and would face Korea’s tariffs of 8 per cent."
Re: export arrangements beyond March 2019 - thanks for your views. My own expectation is that the current status quo will persist during any transition period (I cannot see even our government agreeing to abide by all the requirements of the EEA single-market and customs union without access to its benefits, even temporarily) and for the period beyond any transition, for pragmatism to hold sway in any trade beyond the EEA (the government have been finding their proposal to extend the agreements we have with 3rd party nations under existing EU agreements to be extended on an interim/emergency basis till they are superseded by bespoke bilateral FTAs have been well received by 3rd-party nations - reference Liam Fox/ Theresa May racking up the air-miles; the EU's stance on our trade with the EEA however is quite another matter). However things develop, you point to uncertainty beyond March 2019 and clearly, there is uncertainty over future arrangements and associated risk.
Paul,
Thanks for covering Spectra Systems (LON:SPSY), much appreciated.
Love the digs at broker coverage.
How much did you spend in Revolution Bars (LON:RBG) - Up 2.76% as I write!
Enjoy the meet and thanks again for the coverage.
Tracsis (LON:TRCS) has announced two small(ish) acquisitions today. The announcement reveals revenues and profit before tax, but nothing about how much the company paid for the two businesses (and whether it was cash, debt or equity).
To me, this is worse than useless as we have no basis to value if this is a good deal or not.
Re: Tracsis (LON:TRCS). Yes, a curious omission by a company that espouses the openness of its transactions, and its acquisition model. Perhaps this doesn't quite fit the constraints they have previously set themselves.
In recent times they have made a few 'investments', rather than acquisitions. Perhaps this is one that straddles the criteria. There are only totally exempt filings for the accounts of the companies -all of which are relatively new incorporations.
Maybe because they are separate companies, with separate owners, they don't want to show their hand at the individual acquisition pricings, in case it sets off bad feeling?
Trident,
I hope that my last note to Ramridge clarifies but if not let me know. We will always wish to be open and transparent with investors but this obviously has to be balanced with commercially sensitivities.
TCS and DRS are 100% acquisitions but under the AIM class tests their relative size meant we didn't have to RNS anything whatsoever but thought shareholders would like to see progress on the M&A front.
Best
John
Ramridge,
We deliberately didn't announce the consideration details concerning these transactions as under AIM rule 12 they were not significant transactions and there was no reason to do so.
I appreciate you might find this 'worse than useless' but given the choice I would sooner not have to always announce the exact specifics of a deal for 2 main reasons which I hope you will understand:
1) Given we are a company with a stated strategy of accretive M&A these details do end up acting as a precedent which other target companies try to use for their own ends i.e. our 'best' transaction will be used as the template on which to build when negotiating a deal with Tracsis which doesn't help.
2) With acquiring very small companies it can be controversial with staff and management when they suddenly realise the boss/bosses have become fairly wealthy overnight! This can also be true with clients/customers of the respective business.
As I have repeatedly said on this forum if shareholders wish to discuss specifics not disclosed within our annual report or an RNS they are welcome to contact me directly.
Best regards
John
Hi John -
I said this in the past and I make no apology for repeating it. It is very refreshing to see a CEO engage directly with private investors through the medium of a bulleting board. Others should take note and follow your lead.
I take your point that strictly speaking you didn't have to RNS. But there is a difference between what is legally permissible and what is good for corporate governance and good for management.
And so for the reasons you have stated, you saw fit to provide some of the acquisition details but withhold others, such as the purchase prices.
As a shareholder, I am left with the choice between trusting you that the deals are good ones, or upping sticks and selling my shares. Fortunately I know your excellent track record when it comes to acquisitions and the meticulous process your team follows in sifting potential candidates. So in your case I have no hesitation in trusting your judgement.
But I will say that there has been at least one occasion in the past with a larger plc, when my vote went the other way.
Best wishes, Ram
Re. Tracsis (LON:TRCS)
Good morning John
Your RNS this morning " Additional information regarding acquisitions" : a big thank you.
Best wishes, Ram
We aim to please! In future please don't hesitate to contact me directly.
Things withheld from an announcement are unlikely to be price sensitive (as otherwise they would need included) and therefore we can often share additional information directly with shareholders even if it is not disclosed via RNS.
Hope this helps.
Best regards
John
Thanks for the write up on Spectra Systems (LON:SPSY) . Graham has mentioned this company previously. It has been highlighted that customer information is closely guarded and somewhat mysterious.
However, in previous announcements the company made reference to significant prospects in China and also being able to use its technology for real-time fraud control and risk management systems for gaming operators which could potentially be a big market.
Finally, there was mention of being able to use its technology on smartphones to verify products.
I'm sorry to ask this question again, but I'm just out of hospital after major op and don't have access to all my usual links that I use at work - please can someone tell me good sites to view (1) most shorted stocks, and (2) free tools for momentum stock analysis?
Hi andrea34l - hope you’re feeling better soon. Link below to Short Tracker to get you started ...
https://shorttracker.co.uk
Gus.
Hello andrea34l
I also hope you recover well and soon. On your question about momentum stock analysis you could try:
* the various momentum screens offered on Stockopedia. Stockopedia is great in that it gives the performance of all these screens so you can assess which ones to use. Just click on Screens at the top of the Stockopedia page. There is a whole section on momentum screens
* Paul Scott's SCVR of yesterday (good timing for you) talked about the momentum screens he uses and gave details of a screen that Paul has created following the momentum indicators favoured by Mark Minervini (whose book is great by the way). Here is a link to Paul's Small Cap Value Report that includes his discussion of momentum screens.
https://www.stockopedia.com/content/small-cap-value-report-weds-31-jan-2018-botb-joul-bst-sat-rnwh-306923/
I hope that helps
Good suggestion Julianh and they are tools I am looking at. However the original poster asked for "free" screens and to access the momentum screen in Stockopedia you need a paid subscription. I know this because I recently moved from being a free user of this site to being a paid subscriber.
The suggestion on the short tracker is a good call. As for "free" momentum screens online I'm not sure where these can be found and would be interested if anyone has any suggestions.
Bachart.com has some free tools that do a portion of this.
But you get what you pay for as the adage goes....
Thanks Julian & Gus for both your kind good wishes and advice; the shorting site is the one I used before, though the site I used for momentum indication (which allowed filtering by all sorts of different criteria) is not one mentioned.
ADVFN?, Moneyam?, Interactive Investor (iii.co.uk)?
The Google stock screener lets you screen on price change % over 13, 26, or 52 weeks as well as other common metrics.
http://finance.google.com/finance/stockscreener
Well above the normal market cap threshold here, but I wonder if today's report from SIG (LON:SHI) of Historical overstatement of profit is worth a review as to any learn-able lessons.
A quick précis of the announcement :
The issues were found :
(Beware companies like Barclays (LON:BARC) who believe that attempts to persecute whistelblowers are only a minor misdemeanour.)
The issues were around :
Further the investigations
This last part confuses me as they also say :
How can this be so?
Certainly the prior year adjustments will not form part of the "underlying" numbers, but the £2.5m overstatement in H1 and I would guess a £2.5m+ overstatement in the assumed run rate into H2 will certainly have to come out of the underlying - to me that points to a near 10% miss on the projected £57m Net profit expectation - so unless they have found a completly different £5m down the back of the sofa - I don't see how they can hit expectations.
The shares are 'only' down around 5% so far this morning, although the shares also fell nearly 4% after 2:30pm yesterday afternoon.
I wonder what time that board meeting finished? Not a happy coincidence for a company impacted by potentially fraudulent behaviour by its employees!!
Anyway, given the level of forensic investigation Paul & Graham often offer up, I wonder if there are any lessons to be learned - could we have seen this coming?
Stocko Earnings Manipulation Risk indicator would not have helped in this case - ranking the likelihood of manipulation as low.
" Does nobody sense-check these announcements before they're published? "
"Sense-check", nice term, Paul, I'll use that.
Hi Paul Re Image Scan Holdings (LON:IGE)
You wrote "At this price, I certainly won't be selling, and could even be tempted to top-up "
Before you or others are tempted to buy, it might be worth reviewing Ed's excellent study "The Profit Warning Survival Guide".
- Within the last 6 months, IGE's SP fall from peak to yesterday was -46%
- At the time of writing, the SP has fallen some 30%
- You can make up your own mind about the likelihood of the last two future events
As usual, DYOR
Just seen your earlier comment so perhaps Alumasc (LON:ALU) instead?
A bit over the cap limit but RPS (LON:RPS) please Paul
T Clarke (LON:CTO) if possible would be appreciated Paul. First time I have come across - thanks Matylda.
Like the management commentary around discipline which seems to be backed up with a normal revenue growth path and seems like good visibility.
Balance sheet looks good pension aside, which given poor op margin could be problematic. That said, would expect an improvement on the next report.
Decent Divi covered by free cash - think there is a fair whack to like in this company
Certainly a contrarian sector at the moment.
Maybe I should learn from my holding in Capita (LON:CPI) - ouch! (Sorry - still hurting - problem shared and all that!)
Can you please cover T Clarke (LON:CTO)
Thanks
Good morning - A request for Spectra Systems (LON:SPSY) here please Paul.
Lack lustre half year report from Alumasc (LON:ALU) this morning and the announcement of a smallish (£8m) acquisition. Still pushing the “in line with expectations” mantra but reliant on improved H2 performance. Slightly nervous holder ......
Gus.
I know what you mean Gus. I keep looking at Alumasc in so many ways it looks like a good investment. Strong balance sheet , good divi well covered. Low PE ratio and so on. The chief black mark as far as I can see is the huge pension fund deficit, but I can't help feeling interest rates are only going one way which should see this reduce over time. I can appreciate it is not a growth business any longer but the construction industry always offers up cheap opportunities by its very nature. Erm....... will continue to sit on the fence if only because in short term cannot see anything which will drive share price and I feel shares are a bit toppy anyway.
My morning smallcap tweet:
Imaginatik (LON:IMTK), T Clarke (LON:CTO), Palace Capital (LON:PCA), Image Scan Holdings (LON:IGE), Comptoir (LON:COM), Spectra Systems (LON:SPSY), Connect (LON:CNCT)
Imaginatik (IMTK) puts up For Sale sign. - "the Company's share price does not reflect either the value of the highly scalable platform itself, or the growth prospects available to the Company. Additionally, the Board is mindful that shareholder value may be maximised by a sale of the Company to a larger organisation that can accelerate growth..." Not to do with funding loss after loss. Cap £1.7m. Stockopedia "Sucker Stock".
Clarke T (CTO) trading in line. FD leaving "after a short handover period to a newly appointed Interim (1 year) FD who joined today. No kind words. Where was the RNS announcing the FD's resignation? Are nomads telling companies not to bother?
Palace Capital (PCA) sells 3 houses for £1.2m at 14% over book and has more to sell. Is that really worth an RNS?
Image Scan Holdings (IGE) warns it expects FY will be materially below current market expectations - a £1m expected order now not happening.
Comptoir Group (COM) guides FY trading above market expectations.
Spectra Systems (SPSY) FY17 will exceed market expectations due to royalties from banks being higher than previously expected. This two weeks after saying FY will significantly exceed market expectations.
Connect Group (CNCT) buyer of books div fails to pay by deadline. Prev RNS said buyer admitted it didn't have the wherewithal to pay.
Mr Contrarian
Re Spectra Systems (LON:SPSY) - I am a holder so watch their announcements. They are almost as though they forgot their previous updates, but at least they are all on the right side! Ian
Today… year ended 31 December 2017 will exceed market expectations.
Jan 18… year ending 31 December 2018 will significantly exceed market expectations.
Dec 17… the Company continues to trade in line with market expectations.
Oct 17… year ending 31 December 2017 will significantly exceed market expectations.
It might just be me but I am hoping the broker estimates are on the conservative side given there have been a series of positive updates. I suppose final results will show how accurate they are
I mis-read £SPSY's prev RNS. That was flagging a beat for 2018.
Also T Clarke (LON:CTO) did thank the leaving FD.
Good morning Paul, assuming you didn't fall ill from the Revolution Bars (LON:RBG) bar tender's cold, another request for Image Scan Holdings (LON:IGE) please (I still hold, duh) and Spectra Systems (LON:SPSY) update (I hold, yeah).
cheers
Francis
Morning Paul
I'd appreciate your thoughts on Rank (LON:RNK) half year results please
Thanks
Morning,
Rank (LON:RNK) is £875m market cap, so is above my usual c.£400m market cap threshhold.
I'm confused as to why people keep asking me to cover mid to large caps, when this is a small caps report?!!!
Regards, Paul.
Understood. Thanks Paul
Paul,
Every day you get new readers who don't know what is reviewed here. I would suggest adding a standardized note in each daily template at the top indicating what shares you review and at your discretion. Otherwise its newbies unaware that will continue to request other shares.....
Re: Requests for reviews of non-smallcaps, one would think the name Smallcap Value Report ought to be a sufficient clue, but apparently it is not!
Nasty little profit warning from Image Scan Holdings (LON:IGE) one of the contracts for which a date was still to be agreed at the last statement, will now be cancelled. Current year performance will be materially below and 2018 will be H2 weighted (meaning imho that results could be even worse than they were saying).
There were hints in the last few statements that a miss could be on the cards, so I'm happy to say that I took those hints and sold out a few weeks ago.
I realise now that my last sentence (re Image Scan Holdings (LON:IGE) ) on having sold out before this warning sounds a little smug.
That wasn't the intention at all, but I have been putting a lot of focus recently on when not to buy (or hold) stocks even if I believe(d) the longer term story. This has been a very valuable exercise and IGE is just one case in point. On the flip side as I'm not seeing too much that I do want to buy at the moment so if this carries on I'll be out of the market altogether! (But maybe I'll look back and realise with hindsight that is not a bad place to be!)
Anyway, I just wanted to highlight a couple of points that tell me that there is room for further caution here :
I read the first part of that statement (and statements like it) as saying we don't know how yet, but we 'intend' to over-perform our previous expectations in the second half in order to (somewhat) offset the poor H1.
And if that first part does not come to fruition, then "remain profitable" is clearly also in doubt.
Secondly :
I don't really know the pace of technological development here, but I one would have to wonder what level of discounting may be necessary in order to sell the 2017 model in 2019?
So the clear risk here is that not only do they lose the margins they would have made on 20% of their expected revenues - having already manufactured some/all of the kit - they also face write downs in stock.
Hopefully some of this can be recovered from the prospective customer, but as they are "currently negotiating terms for the cancellation of that order. " , that cannot be taken for granted.
In the past, if I still believed the longer term story (I'm not sure now in this case), I would have been very tempted to think that the price fall represents a great opportunity to buy for the longer term.
Now, I am more than happy to wait and possibly buy at a higher price, if the path to the promised land becomes clearer.
Hi Gromley,
FWIW I certainly didn't see your initial post as smug, and I think this follow up is well worth reading, for those interested. As mentioned on twitter, today, my sympathies to all holders. As the old addage goes: "If in doubt, Get out!"
I, like Gromley, used to hold a significant percentage of my portfolio in Image Scan Holdings (LON:IGE) I sold my entire position 2/1/18. Like all my buys & sells, I reported this on Twitter.
Why did I sell?
I was asked this by Conkers on Twitter, today. Good question. When I go back to review my trade, I made a mistake - I held on too long, when I knew something wasn't right, and took a loss of ~15%. If I had have been more decisive, I could have exited my position sooner - perhaps even in its entirety on 6/12 when the prelims came out at ~8.6p rather than ~7.8p in Jan.
That said, the decline in the SP made up my mind, and it was gone.
Thanks,
IG
@InvestedGeordie on twitter
Hi IG,
On Image Scan Holdings (LON:IGE) , what did you know wasn't right? And do you normally view a decline in the SP as a sign to sell?
I try to assess how much something is worth, and pay less than that, so would generally be keener to buy / less keen to sell if the SP has declined without a change in the actual assessment of value.
Do you think it's worth more or less than the current price? If less, then presumably you think the company's situation has changed drastically, given how much less you can buy the company for now.
Thanks.