Small Cap Value Report (Weds 31 Jan 2018) - BOTB, JOUL, BST, SAT, RNWH

Good morning, it's Paul here!
To get you started today, here is the link to yesterday's completed report. I added new sections on Filtronic (LON:FTC) and NWF (LON:NWF) in the evening (EDIT: extra bits added re NWF, after talking to an adviser to the company, who helped me with understanding the business model)
On to today. I see that yet another outsourcing company has run into trouble. Capita (LON:CPI) this time. The RNS today says that it needs to raise c.£700m in a Rights Issue, has suspended divis, and is to make non-core disposals, and cost savings. It's become too big & complex. I don't know the company at all well, but it seems to me there are 5 clear lessons to be learned from Carillion, Capita, and previous failures in the outsourcing & support services area;
- It's a lousy area for investors, unless the business is focused in a specialist niche area, and is very well managed.
- Operating a group with a weak balance sheet, loaded up with debt from acquisitions, is very often an accident waiting to happen.
- Contracting businesses often mess up contracts in one way or another. This is bound to happen, as offering to build something large, or provide a complicated service for multiple years, is fraught with risk. Yet contractors often under-estimate the risks & costs, in order to win the contract, sometimes at an uneconomically low price.
- Investors are often sucked into shares in this sector due to a high dividend yield. Companies with weak balance sheets, lots of debt, and paying big divis are an accident waiting to happen. I only go for high yield shares if the balance sheet is bullet-proof.
- The accounts in this sector cannot really be relied upon. Reported profits often turn out to be illusory, once problems with contracts later emerge.
Overall then, my resolve is stiffening to avoid this sector like the plague.
Best Of The Best (LON:BOTB)
Share price: 255p (unchanged today, at 11:31)
No. shares: 10.12m
Market cap: £25.8m
(at the time of writing, I hold a long position in this share)
Interim results - for the 6 months ended 31 Oct 2017
Best of the Best runs competitions to win cars both online and at retail locations
This is the well-known supercar competitions company, which has been operating from UK airports for many years. Its business is now mostly online, at 82% of revenues. Total revenues are only flat vs H1 LY, at £5.54m. Although reduction in airport revenues has masked an increase in online revenues of 6.8%, to £4.44m.
I'm rather disappointed with this pedestrian rate of online growth. The reason I hold this share, is because I think it has an excellent product, which has the scope to be many times larger. However, management seem to prioritise profits over growth. That has resulted in a nice stream of special divis, but I can't help feeling that a big growth opportunity is not being suitably developed. Hence why I don't see PER as a particularly relevant way to value the share - it has considerable latent value, and many years' reputation, which could be worth multiples of the current valuation, if better exploited.
Other points;
- Strong profit margin - £0.95m H1 profit, on £5.5m revenues, is 17.1% net margin
- Cash of £2.05m (no debt)
- Another special dividend (hoorah!) of 7.5p
I'm pleased to see that the company is spending more on online marketing - but is it enough? There's a strong argument to really go for it, and stimulate strong growth. That would send the share price into orbit, then a say £5-10m fundraising could be done, to turbocharge the next phase of growth.
Growing investment in online marketing to increase player acquisition, with encouraging numbers of new customers
Valuation - H1 EPS is 7.67p (up only 2.3% on H1 LY). We cannot simply double that figure to get a full year estimate, as there's a complicating factor here. This is the change in tax status of the company, which was explained in this RNS on 13 Dec 2017. Instead of being subject to VAT, the company will now pay Remote Gaming Duty.
The company very helpfully spelt out the impact this would have on future profits, in its Dec 2017 announcement;
The payment of RGD, as opposed to VAT will result in the payment of higher taxes and will negatively affect the Company's operating margin. The impact on profit in the current financial year is expected to be mitigated by the old tax regime's ongoing application in H1 and a solid start to H2 and therefore the Company confirms that it expects to report profits before tax of not less than 1.4m (2017: 1.5m). The impact on FY19 is expected to be more pronounced with forecasted profits before tax of not less than 1.2m.
Therefore, if we are to be conservative, we should probably value the company on a run rate of £1.2m PBT, which would be roughly £1.0m after corporation tax, divided by 10.12m shares = 9.9p EPS.
The house broker is a bit more conservative (and dilutes for share options, which I haven't done), and forecasts 9.3p EPS for 04/2019. That's a PER of 27.4 - which looks expensive for a company which is not generating much growth at all. Although as explained above, I think there's considerably more latent value in the company's future, so a PER valuation basis looks too simplistic to me.
If the company hits on an effective digital marketing strategy that stimulates growth, then (in a bull market) we could see the rating double, and earnings forecasts double - that's the type of situation I look out for - and it's exactly what happened at Gear4Music, for example, proving very lucrative. That's the upside potential anyway, but I'm not totally convinced that it's likely to happen. A more sedate pace of growth seems to be the plan;
We have continued to grow our investment in all forms of marketing which has helped drive revenues and increase awareness of the BOTB brand and the Dream Car competition. It is our intention to gradually accelerate the rate of this investment to build on these results.
VAT reclaim - this is still up in the air, but the house broker reckons that BOTB's £4.5m (before costs) VAT claim is strong, and likely to succeed. If that happens, then I imagine the company would probably pay another special dividend. Although my preference would be for the company to instead use any such windfall as a big new marketing pot, to be focused on (hopefully greatly) scaling up the business, using predominantly digital marketing. That's where the opportunity is, in my view - same with all online businesses.
Outlook - management seem happy with performance, so I wonder if there might be upside potential on the forecasts?
The business is well placed for future growth and is trading in line with management expectations. We look forward to updating shareholders on progress in due course."
My opinion - as you can probably tell, I'm somewhat frustrated that a big opportunity has been created here, but isn't being pushed forwards as aggressively as it could be.
Joules (LON:JOUL)
Share price: 324.5p (down 0.15% today, at 12:57)
No. shares: 87.5m
Market cap: £283.9m
Interim results - covering the 26 weeks ended 26 Nov 2017.
This is a distinctive fashion retailer/wholesaler/online - website is here.
It's good to see the interim figures from this company today, as its trading updates are almost completely useless - failing to provide the key information that investors need. I explained my complaints about badly-written & confusing trading updates here on 12 Dec 2017, and again here on 9 Jan 2018. The company tends to just talk about revenues (which are obviously going up, because it's opening new shops). However, it often fails to state how it is trading relative to market expectations. That's the vital information, so to omit this renders trading updates largely useless.
I'm pleased to say that the interim results provide a much better indication of how things are progressing, with this clear outlook statement today giving us some of the information we need;
The Board now anticipates that full year profit will be slightly ahead of the range of analysts' expectations
I say "some" of the information we need, because the company has failed to state what it believes the range of analysts expectations actually are. Companies & their advisers need to remember that, post MiFID II, many investors are no longer able to access analysts' notes.
Reuters website shows a range of EPS estimates from 11.0p to 12.67p for 05/2018. Although my worry is whether these estimates might start to dry up, if brokers stop providing their figures to financial websites? So I'm treating all forecasts with great caution at the moment, and am sense-checking them myself.
This seems to me to be suggesting that full year EPS of c.13p seems likely. That works out at a current year PER of 25. Not cheap, but not outrageous either, for a decent growth company, in a bull market. Although I have to say that UK small caps are feeling more like a bear market at the moment, with lots of things selling off quite badly.
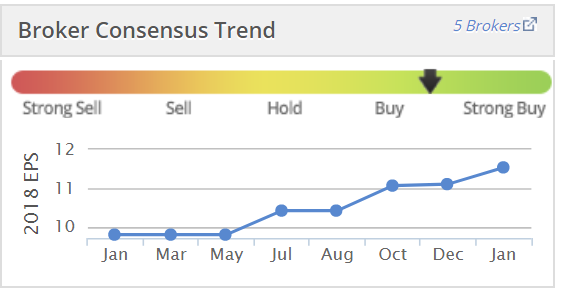
House broker notes for JOUL are available on Research Tree. They've upgraded forecast earnings by 3% today, on top of a 6% upgrade after the Christmas trading statement. I think it's often worth paying a highish PER for companies which have a track record of beating estimates, as this one has. The actual PER in 12 months time ends up being cheaper than you thought at the time of purchase - because the forecasts were too low.
This effect has been shown dramatically with both Boohoo.Com (LON:BOO) and Fevertree Drinks (LON:FEVR) which have established remarkable track records of thrashing original forecasts. So when they looked so expensive during the rapid growth phase - actually they were cheap! The lesson I've learned from that, is to stop treating analyst forecasts as fact, and instead remember that they are just one person's best guess. They are often very considerably wrong. Predicting the future is not easy, especially when profit is a leveraged number. So profits can swing up & down a lot, on fairly modest changes in sales, at many companies.
The earnings upgrades at JOUL are not quite so dramatic, but they're worthwhile, and repeated;
Balance sheet - I would say is satisfactory, but not strong.
My opinion - overall, I like the good track record of profit growth that JOUL is establishing. It's a fashion business, with a very distinctive look, so it carries a heightened risk of going out of fashion, compared with other retailers.
I think the current price can be justified, based on strong growth. I don't see enough short-term upside to want to buy any shares myself though.
Stock screens based on earnings momentum
I've focused on earnings momentum a lot over the past 2 years, with excellent results. The stock screening section of Stockopedia is very useful to find potentially good shares. This section shows a couple of screens which I follow, that have performed very well over the last 5 years. You can click on this picture to go to the relevant page;

I often find that stocks I like appear on Tiny Titans, based on James O'Shaughnessy's investment approach. It's also a near shortcut to find new stock ideas. Although having a look at its latest selections, there are not many that I rate.
I create lots of screens on Stockopedia, and see which ones work best. Most don't work consistently. However, one screen that I created a year ago does tend to come up with some smashing stock ideas. It's based on Mark Minervini's approach, and looks for shares with moderate to good share price momentum, with good sales growth, and (crucially) forecast upgrades in the last 3 months. People have asked me for the criteria in the past, so here you are;
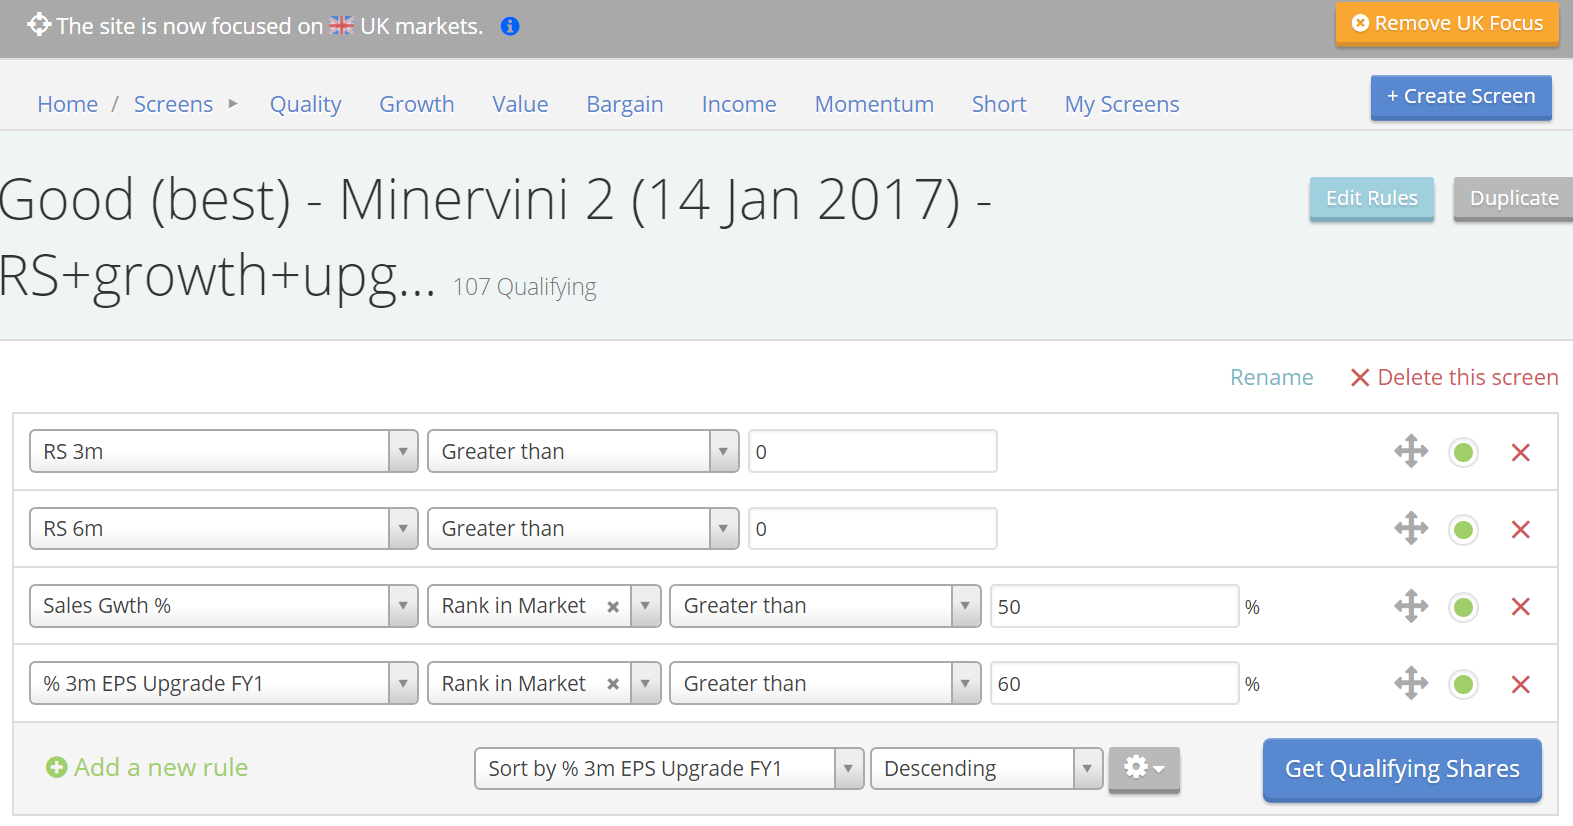
I'm not sure that a Minervini style approach will necessarily work in more bearish-feeling UK small caps at the moment. In a bull market though, it worked a treat - helping me to identify some cracking risers last year.
Big Sofa Technologies (LON:BST)
Share price: 13.97p (down 3.7% today, at market close)
No. shares: 65.1m
Market cap: £9.1m
Trading update - for calendar 2017. I didn't realise the market cap was so small, but as Magnus Magnusson used to say, "I've started, so I'll finish".
Big Sofa (AIM: BST), a fast-growing international video analytics provider to consumer brands and market research agencies, is pleased to announce a trading update for the year ended 31 December 2017.
It's a jam tomorrow company, so not really my kind of thing at all.
Revenues in 2017 were up 72%, but were still only £1.3m.
The narrative today is mainly about big name clients, and future potential.
However, it seems to me that the apparently positive update today seems to be glossing over very poor financials. Here is a summary P&L from H1;

Full year revenues are £1.3m, so that means £0.8m revenues in H2. If the cost base remained the same as in H1, then this suggests an operating loss of a whisker under £2.0m in H2, for a full year loss of over £4m.
Cash position - looks extremely precarious. As at 30 Jun 2017, the company had only £397k in cash, less borrowings of £628k, so net debt of £231k. It raised £1.4m after costs in a placing at 18.5p in Aug 2017. Given the likely cash burn in H2, I reckon that by now the company must be running on fumes - i.e. it probably needs an urgent, immediate cash injection to keep trading.
Outlook - jam tomorrow basically;
"We have begun 2018 with an established client base that has already extensively stress-tested and validated Big Sofa's technology in 2017 and is poised to increase spend in the current year. The board is highly encouraged by the progress demonstrated in 2017 and the platform Big Sofa has established for material revenue growth in 2018."
My opinion - there's only one thing I dislike more than jam tomorrow companies, and that's jam tomorrow companies which have run out of cash. So personally I'll be watching from the sidelines, and waiting for the company to;
- Get proper funding to take it through to profitability
- Demonstrate that it has a viable business model.
I don't see either of those things yet. So it's extremely high risk at this stage, and hence best avoided, in my view.
Should the company have issued such a bullish-sounding update, yet make no mention of its cash position and cash burn? If a placing is done at a significant discount, then I think people who bought on the basis of this trading update would have serious grounds for complaint against the company.
Trading updates should not be ramping exercises. They should instead give a balanced and informative view of the company's position. I can't see anything like that in this update. It might be worth a closer look, if and when the company raises enough cash to give it c.2 years' breathing space, and if/when the promised increase in customer spend really does happen.
Satellite Solutions Worldwide (LON:SAT)
Share price: 8.56p (up 1.3% today, at market close)
No. shares: 682.6m
Market cap: £58.4m
Satellite Solutions Worldwide Group plc (AIM: SAT), the global leader in the delivery of alternative super-fast broadband services, announces its unaudited trading update for the 12-months to 30 November 2017.
I remember talking to the CEO of this company a couple of years ago, and being struck by what a good business model he seemed to have come up with. This company is buying up lots of little satellite broadband companies, which are uneconomic as standalone businesses. Put together, they do become viable. Margins increase as the cost of satellite data transmission reduces, but customers are charged fixed monthly fees.
From tiny beginnings, it's starting to look like a sensible business, with recurring revenues, emerging;
Like-for-like organic revenue1 increased 12% during the period, with total revenue, including acquisitions, increasing 104% to around 44m (FY16: 22m). Recurring revenue2 increased 119% to around 40m (FY16: 18m), representing 90% of total revenue, providing improved visibility of earnings for the coming financial year.
However, there are 2 problems which make it uninvestable for me;
1) It doesn't really make any money. EBITDA sounds good, but most of this is consumed by depreciation & amortisation;
Gross profit margin expanded to 36% (FY16: 34%) with EBITDA3 expected to be above 4.5m (FY16: 1.2m) despite continued investment in the Company's products and services to underpin future growth.
2) The balance sheet is pretty awful. Although it did do an £8m placing, announced in July 2017. Despite this, net debt rose to £12.8m. The last published balance sheet at 31 May 2017 is one of the worst I've seen for a while.
My opinion - I can't make the numbers stack up here at all. Having said that, it's possible that the company could grow its way into decent profits. The current valuation seems to already factor in a lot of future success. It's not for me - I can only base my opinion on the numbers as they are today. What happens in the future? Who knows?
A few quick comments to finish off;
Renew Holdings (LON:RNWH) - down 7.8% to 415p today. The Q1 (Oct-Dec 2017) trading update is in line with expectations.
This bit might have rattled some investors today?
The Group's term loan will be fully repaid by 31 March 2018. A slower than usual payment profile with certain customers in the public sector has led to an increase in work-in-progress in the first half. Nevertheless, cash balances as at 30 September 2018 are forecast to be broadly in line with the previous year end.
Renew has no financial exposure to Carillion's insolvency.
This does lead me on to the sector - engineering support services. Who would really want to invest in this sector, given all the bad news for other contracting companies?
My opinion - In fairness, Renew seems to have navigated the pitfalls very well, and has a good track record. It seems to be more of a niche business, rather than a sprawling & out of control group like Carillion or Capita.
However, Renew's balance sheet is awful - with negative net tangible assets, and the whole business is financed on advance payments from customers. Therefore I see this as a high risk share, with the potential for big problems at some stage, if any large contracts go wrong. And/or if customer up-front payments dry up. It's not anywhere near as safe as bulls imagine it to be, in my reading of the balance sheet. So considerable caution is needed. It might all turn out to be fine. However, my job is to flag up risks when I see them.
SCS (LON:SCS) - in line H1 update.
Run out of time, sorry.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Capita (LON:CPI) Woodford never really had much of an overall approach. He didn't distinguish between quality and non-quality well and didn't identify risks well. I also think that the cult of one person isn't great. At Fundsmith there is a proper team but at Woodfood it all seems to be about Neil.
Neil Woodford's approach was obviously lacking in a few areas. Shame to see him fall like this but he has made self-inflicted errors. He is meant to be preserving and growing capital but got the former wrong.
On many of Neil's investments he "tried to be clever." He is not an early stage investor and he shouldn't try to be. Investing in tobacco and early stage stocks doesn't fit together well. He let his clients down.
Interesting how Hargreaves Lansdown (LON:HL.) hyped him up significantly. Many their clients should ask why exactly. This is why I don't think I would ever want to be an HL client. Always hyping fund managers who are often of dubious quality.
BOTB. I used to have a punt on their site until they changed their website. Previously one picked - say- 10 cars then went in to play spot the ball and after 10 x's it told you. You then paid - all done. Now it allows you to carry on putting x's so you can't delete the x's so they want you to pay more. At this point I just left the site. Can't believe that I am alone. I did email them but bot no reply.
Hi Paul, I appreciate you have a long list of companies to comment on today, but if time permits I wonder whether you maybe able to briefly run your 'slide rule' over the results from Ashley House (ASH). Thanks to you and Graham as always for a top class service.
DH2.
Can anyone explain the dip in Patisserie Holdings (LON:CAKE) please.
It reached highs of about 405p two days ago.
Thanks
re Patisserie Holdings (LON:CAKE) I can see falls in EPS forecast for January on the Broker Forecasts on the main Stocko page . Sorry don't know how to copy the images. May be the reason.
Paul - I note your comments on Best Of The Best (LON:BOTB) and frustration with regards their current strategy.
What are your views on shareholder activism and is this an approach you have considered?
I guess now that you are committing larger chunks of capital into fairly small businesses, a greater say in how they are run in order to help drive shareholder returns could be a valid investment approach!?
As an aside, I'm sure if you add up the Stockopedia community's holdings in some of the more popular small caps, we'd have a real presence on the shareholder register!
N
Re shareholder activism and Best Of The Best (LON:BOTB) Only 15.4% of the issued shares are in free-float, and since the founders can do what they want if they control or influence at least 75% of the shares, there is no threat of activism stopping them from doing whatever they want.
(I have no position in Best Of The Best (LON:BOTB) )
Paul,
Thanks also for the screen, hope the Doc found it :)
Paul
Many thanks for the Minervini screen
Re Best Of The Best (LON:BOTB)
Issue re 'pedestrian' online growth of 6.8% YOY is linked to the ownership/Board. Son and founder (William Hindmarch) is backed on the Board by his Dad and (I think) a friend from college albeit one with a city education. This is therefore now a lovely lifestyle business for the owner and mates/family that will probably continue to make very good money. So hats off - I wish I had done something like this. The combination of salary and dividends must create a very comfortable life for the Hindmarch crew.
However, for real growth they need more expertise and attitude on the board especially on a commercial side.
There must be any number of ex gaming site Directors who would like to have a role in the BOTB fancy car business. The basic business model is now largely proven.
The business should i) (as Paul says) be pushing more money into online Marketing to drive growth and ii) be looking to replicate the model in other jurisdictions and ii) looking to replicate the model overseas. But I fear the marketing results to date will not inspire confidence in the Board. Scattergun approach to Marketing eg No mention of TV advertising this time (which IMHO was a another plaything for Mgt to discuss at dinner parties), new low cost to enter games are a good idea but are presented on the website in a dull way with no focus. They now have a good sized marketing budget and could really accelerate with a better commercial strategy.
Perhaps Paul can somehow communicate that an even nicer lifestyle awaits if the current owners sell out but retain a decent share (say 25%) with some professionals to run it day to day. Otherwise expect otherwise happy holders like me to exit when and if there is a spike up.
Paul, As someone who works in the hard facilities management part of outsourcing and construction projects sector, can I just say your analysis of the sector from an investment point of view is very succinct and spot-on !
Quite apart from a diversification of income point of view (as I work in it), I find it uninvestable !
What's happening at Bioquell (LON:BQE) ? Down 17% in 5 days despite announcing that y/e pre exceptional pbt will be significantly ahead when results are announced 0n 7 March.
I hold - have I missed something?
Michael
Paul would be very interested in your thoughts on FLYBE Q3 Trading .
This has been my worst ever investment in 14 years trading.
Best Of The Best (LON:BOTB) The results today talk about their strategy of reducing ticket sales to bolster sales and increase their target market. This may be a key reason for growth being lower than hoped. Directors do seem upbeat about the impact this is having.
Talk of moving into other areas - eg motorbikes or simply just cash lotteries.
Growth not firing as we'd hoped, but lots of positives. Picture could look once again exciting in 6/12 months.
hi paul, please review Best Of The Best (LON:BOTB) if you can - a nice special div when we thought they had stopped ! (due to the buy-back announcement they made before)
Flybe (LON:FLYB) Q3 trading statement today:
https://www.investegate.co.uk/...
May actually be finally showing progress on the turnaround. Q3 has normally been loss-making for Flybe (LON:FLYB) but if I have got my maths correct Q3 may be profitable. This augers well for a full year result. If they can keep cost per seat similar in Q4 results could look something like this:
This is probably too optimistic for Q4 but shows that this may not be the basket case that is being priced by the market.
Nice analysis. I like this and useful. Own them higher myself but as a turnaround I think they may have legs.
Circa £120m of cash I believe so unlikely to go bust aka Monarch or Air Berlin and the departure from the market of those two appears to have been net positive for pricing across the market.
With a NTAV of £155m (accounting for debt) vs a market cap of £75m this is priced at 0.5 * assets. Only £11m of intangibles so nothing too goodwill related sitting on b/s.
If they can start making £25-30m p/a PBT consistently from next year you can see them 3 or 4* higher from here at £300m mkt cap. (£150m nav + 7* earnings)
or am I missing something (other than obvious health warning attached to airlines in general :)
The cash is upfront payments by customers so while it provides a good liquidity barrier it can't be paid out to shareholders so I don't think it should be counted in the EV.
That said I think £30m PBT is conservative if load factor continues to improve as routes mature & fleet growth moderates. On the majority of their routes Flybe (LON:FLYB) are not competing against the jets of Ryanair Holdings (LON:RYA) & easyJet (LON:EZJ) but road and rail. So as more people decide to avoid the clogged roads or expensive trains the better it is for Flybe (LON:FLYB). They just have to get their costs under control to fully capitilise. So overall I agree a 3-4x medium term upside is possible.
NTAV is the owned planes so even if Flybe (LON:FLYB) fail to turn it around it is not inconceivable that a player like Stobart Air would want their slots & their planes to try to make a go of it. This provides some downside protection.
So overall there is a decent upside if they execute well and a limited downside if they fail.
Agree - I don't think all cash is upfront payments as they were always well "cash" funded since the last bail out placing xx years ago to repair the b/s. However, I share your view that downside should now have some protection (possibly around this level) with a successful continued turnaround offering good upside. Certainly feels as though risk / reward ratio is finally skewed favourably.
Be interested in any other knowledgable Flybe (LON:FLYB) investors views too. I am leaning towards a small position.
I'm afraid I still take the bear view on Flybe. Only reason IMHO Q4 looks much better is the Monarch capacity was taken out of the UK market.
All that will happen is RYA and EZJ will keep up the pressure on the rest.
Can't see any way for Flybe to find a niche.
Not looked at the numbers in detail though - just taking a macro view of the sector.
Hi Paul,
I was wondering if you had any thoughts on Capita (LON:CPI) and the outsourcing sector as a whole.
I know Capita is too big to warrant a full blown section but i like the paragraphs you do on bitcoin and other more macro items and also considering the substantial coverage carillion and capita are getting in the press recently would probably be of interest to some people.
However if you're already busy enough with the smallcaps no problem.
KR
James
Looking at the reader requests, I'll try to cover most of them.
So far, I have a list of 8 companies to try to cover today, so will do as many as I can, which are:
Best Of The Best (LON:BOTB) (which I hold)
Joules (LON:JOUL) - interims
Big Sofa Technologies (LON:BST) - trading update
Satellite Solutions Worldwide (LON:SAT) - trading update
Renew Holdings (LON:RNWH) - AGM statement
SCS (LON:SCS) - trading update
Real Good Food (LON:RGD) - profit warning (another one?!!!)
Low & Bonar (LON:LWB) - final results
Thanks for SAT
Would really welcome your comments on Satellite Solutions Worldwide (LON:SAT) . Interesting "binary" situation, with what looks like an impossible debt load, but they could just be reaching the point of generating some real profits for the first time. I don't own, though have in the past, but sold after reconsidering the risk.
Hi Paul.
Thanks for the review of Satellite Solutions Worldwide (LON:SAT) .
I agree with your view that the balance sheet is lousy, although given the annuity nature of their subscription income stream I think their business model is akin to that of a utility capable of supporting quite high leverage (though not as high as it is at the moment). One thing in their favour is that so far they appear to have been able to source fresh capital with apparent ease from both shareholders and banks and also the BGF (Business Growth Fund). Over time they will hopefully reach the critical mass necessary to support the central overhead while generating sufficient cash to deleverage.
Given the importance of broadband access, I think they also have the benefit of being in good odour with the governments of the countries they operate in for providing essential infrastructure to remote areas. In due course this could give them a seat at the negotiating table over subsidies etc..
One possible concern is that if the company is ultimately successful the PI’s may get stitched up by the management and Harwood Capital taking the company private at a negligible premium.
Gus.
Oh quiet possibly! Thanks for your reply and understood.
Paul
I've been following Wincanton (LON:WIN) and see it going up and up. Your valued thoughts if possible. Thanks
Hi mercury61,
I've been following Wincanton (LON:WIN) and see it going up and up. Your valued thoughts if possible.
You must have been looking at the chart upside down, as it's been trending down over the last year!
I can't see any results or trading updates from WIN today, so there's nothing for me to comment on. I don't generally comment here on day-to-day share price movements. This column is all about giving analysis & views on the day's trading updates & results.
Here's the archive for mine & Graham's previous comments on WIN (which you can access for any company by going to its StockReport, then clicking on the "Discuss" tab).
Regards, Paul.
Wincanton (LON:WIN) As I read the chart , the main trend has been UP sinceOct.2013 and the current trend from June 2017 is a retracement leg which is just about to come off the bottom of the channel , so could be about to turn. Apologies for the intrusion.
Paul, many thanks for your excellent analysis and comments.
I just can't resist pointing out that even if you were to take a chart of share price with a downtrend and look at the chart upside down it would still show a downtrend.
Sorry! Thanks again for everything.
Re. Burford Capital (LON:BUR) Please note that Burford issued a late RNS yesterday. It has raised $180m in a US bond issue. Market reaction seems to be positive.
Just to clarify Burford Capital (LON:BUR) raised the $180m in London - the first ever $US bond issue on the LSE's Order Book for Retail Bonds (ORB).
Discoverie (LON:DSCV) if time permits ( previously ACAL )
Hi Paul, any thoughts on Satellite Solutions?
Thanks,
SCS (LON:SCS) have a new trading update. Could be worth a look at.
I just thought that I would point out (as I see two comments have fallen foul of this), that when using the £ symbol before the EPIC code you must not put a punctuation symbol straight afterwards, otherwise it confuses it and the link doesn't take... so leave a space after the code. As an example:
Any thoughts on £DOTD?
Change to:
Any thoughts on dotDigital (LON:DOTD) ?
Hi andrea
If you look at my post #4, I followed the rules and the system didn't like it?
Ramridge, you've used the £ symbol, which is good, but what you have done (as per the reason for my post) is that you have put the apostrophe straight after WSG where as you need to put a space between WSG and '. So, in the below, the first one is the way you have written it and the second one is where I have applied the space rule:
News of £WSG's results...
News of Westminster (LON:WSG) 's results...
Hi Paul,
I hope you don't mind but... I attended the Shares magazine Growth and Innovation forum event in London yesterday and thought that readers who couldn't attend might like to get a flavour of the event. So i've written up my notes and posted them here: https://www.stockopedia.com/content/report-on-the-growth-and-innovation-forum-30th-january-2018-307038/
Personally, I thought it was well worthwhile, with interesting speakers and lots of small cap companies presenting and exhibiting. And it was very well attended by some 300+ private investors
cheers
Francis
Thanks fwyburd for your synopsis , far more efficient than myself; I too attended and it was the one point that Gervais Williams made with regard to Fund Managers now starting to get really into AIM stocks to give them an edge over otherwise rather mundane performances; which made the most impression. The price of those stocks, of sufficient size for funds to buy a reasonable amount, will be well supported through any downturns.
Of the Small Caps; The Chargemaster CEO gave an excellent presentation, word perfect, he clearly knows his subject and previously created a successful startup. I put my name down for info when they have their IPO.
The only other one of interest was CML Microsystems (LON:CML) ; had a long discussion with the CFO who was appointed after the 2014 downturn; they have reorganised , spend far more on R&D, massively improved the products & gaining good customers. The price chart is just about to break out , so will be watching.
Good morning Paul
Any thoughts on the new CFO appointment at £DOTD? I really like the company but appointing a Chartered Financial Analyst with a lot of Fund Mananagement experience as chief financial officer really worries me. He may be great at raising funds and making acquisitions but will he have the right experience and understanding to maintain financial controls and make sure that the accounts don't get inflated with non-tangible assets to boost profits and raise the share price? Yes, our Graham is (if my memory is correct) and FCA but I imagine that Graham's cautious approach and focus on solid balance sheets is an exception in the FCA world.
Any thoughts?
*CFA not FCA.
The CFA exams teach a very disciplined approach, cover large amounts of topic material and has very little to do with raising funds or making acquisitions. I'm not quite sure where you got that from.
It's major sections are accounting (FRA), equity valuation and fixed income. Graham's approach is the one very much championed by the CFA institute with a focus on careful analysis. I would learn a bit more about the topic before slandering it.
As a CFA charterholder myself (since 2001) I think you have the wrong impression of what they represent from an analytical perspective.
I've got my gripes with the CFA Institute (and I have a general dislike for professional organisations generally due to lobbying activity) but one of them is not that it teaches corporate finance dark arts as part of the curriculum. If you want a platform to build analytical knowledge then its great.
Ciao
Interesting points. Usually accountants have specific accountancy training. CFA covers accounting but is not a professional accountancy qualification. So there are pros and cons. On the one hand having a CFA as the CFO helps to give an understanding of the investment side. On the other hand it means a lack of a specific accountancy background. So it could be a positive or a negative.
On face value it does seem unusual to appoint a CFA as the finance person. Usually the post does go to a qualified accountant as far as I understand. However, the ambition of Dotdigital may make this a positive and probably the accounting for a small company like this isn't too complex. I.e. it isn't exactly a global bank. As stated a CFA will be able to judge shareholder value enhancements better than an accountant.
For disclosures sake I have a CFA qualification. It is an ok qualification but quite theoretical and all driven by multiple choice exams. Tough to pass or at least you have to give up a lot of weekends to study like mad.
Not sure why a few people gave a thumbs down to your post!!! Seemed like a fair comment to me. Or at least raised a point that should be considered. I don't think you were criticising the CFA qualification (fair enough if you were) you were just asking if it was suitable for an FD role.
I agree that the CFO does not need to be a qualified accountant.
Interestingly, at Staffline (LON:STAF) , which for a small cap gets its numbers out really quickly, the CFO for the last two years, Chris Pullen (last week promoted to CEO) left school at 18 and joined the army - got an MBA (I think) but had no formal accountancy qualification. Pullen’s replacement as CFO, Mike Watts, is a chartered accountant (ex PWC).
Also on Staffline (LON:STAF), the outgoing CEO, Andy Hogarth, who at last week’s private investor presentation emphasised his confidence in the company going forward has sold two-thirds of his shares (late evening announcement yesterday).i
Sorry Paul, created 2 posts in the interests of potential thumbs up - Your thoughts on the SCS (LON:SCS) Net Cash position and potential for it to sustain that Dividend in the event of a downturn.
Thanks in advance if you get the time.
https://www.stockopedia.com/content/scs-sofa-so-good-baby-302388/
https://www.stockopedia.com/content/armchair-ageddon-at-dfs-194239/
IMO (and that can be misguided!) I think the net cash position is fairly bullet proof at the moment. The SCS (LON:SCS) business is set up to be quite resilient to downturns. Yes it will challenge short term earnings but it should not cause a drastic erosion in cash position. They had trouble back in 2008 caused by too rapid expansion in 2005-7 and then a technical catch in the credit crisis when providers withdrew credit insurance (I say 'technical' as pre 2008 it is the kind of thing that people did not understand...their fault for getting caught with it but so would most smid cap cos).
The issue going forward is what will they do with so much cash? Four choices:
1) Acquisition
2) Buy back stock or special dividends
3) Lot more new stores/ other investment
4) Buy out Sun Capital who own 40% (private equity)
Perhaps it is clarification on the cash pile that leads to stock re-rating.
I think they hope for a chance at 1. Based on mgt approach and discipline I think they will do this very cautiously and not force it so its a case of whether the opp comes.
On 2 they just bought back 1.2% of stock the other day which was really aimed at a bit of 4 above (as bought off of Sun).
On 3 they have a target of 30 store locations that would suit a SCS (client base). They will only open if the circumstances are right which for them is mainly destination retail parks with other furniture and housing related stores. An other investment could be starting their own furniture production capability as this would allow them to move closer to DFS Furniture (LON:DFS) margin...but would introduce greater cyclicality and downside too.
So at the moment, if I am correct on the security of their cash position, then they can either fully buy out Sun Capital or fund the whole 30 stores they want to open (at £1m per store, their normal costing for opening). That's quite a buffer...and decent armageddon proofing (a little too much).
IMO they should get on with a very significant share buyback program. At least 20% of outstanding stock.
Most grateful for that, that Dividend is looking quite attractive!
Morning Paul, Best Of The Best (LON:BOTB) (a site I have an occasional, usually late night after some drinks with friends, punt on) is not an eventful update but it does seem to demonstrate a lack of ambition...
"Special dividend of 7.5 pence per share (£0.74 million) to be paid on 23 February 2018"
Would it not be better spent on advertising and generating new customers?
I don't hold but would be tempted if there was a sign of ambition.
Appreciate your thoughts.
News of £WSG 's massive contract has disappointed again, not to any surprise to many.
To add insult to injury, they are also raising equity funds as the coffers are near empty.
Hi Ramridge,
I don't usually bother looking at RNSs from Westminster (LON:WSG) . The company has been such an abject failure for so many years, that I'm amazed it still exists. Fundraising after fundraising. Who are the masochists who pour money into rubbish like this? Fastjet (LON:FJET) is another one in a similar vein. I think we can be pretty certain that the investors are using other peoples' money!
Regards, Paul.
Agree on that. Not point looking at the dogs. Every dog may have its day but good quality companies deliver the strong long-term returns. Waiting for a dog to turnaround is usually a fools errand. Fastjet was such a dumb idea I was amazed that it got going. Low cost carriers worked in Europe because the EU got rid of national protection for flag carriers. African countries are not likely to do the same and it is a tough continent to operate in.
Re Westminster (LON:WSG) Agreed. No position long or short, and no intention to ...
Last mile satellite broadband provider Satellite Solutions Worldwide (LON:SAT) gives a trading update this morning.
https://www.investegate.co.uk/satellite-solutions--sat-/rns/trading-update/201801310700054049D/
Bullish statements about growth (has passed its 100,000 subscribers target) and now EBITDA positive although still a long way to go. As noted recently, occasional small cap predator Harwood Capital/Chris Harwood have rolled up about a 17% stake in the company. Like many start ups, very much “Sucker Stock” territory at the moment.
Gus.
Low & Bonar (LON:LWB) may be of interest. Revenue is up, but so is debt (c15%), and the company seems to have turned in a loss on the year. Unfortunately there was also a fatal accident at one of the plants. Perhaps the new CEO can turn this around.
My morning smallcap tweet: zzz
Joules (LON:JOUL), People's Operator (LON:TPOP)
Joules Group (JOUL) H1. Outlook - guides FY profit slightly ahead of the range of analysts' expectations.
The People's Operator (TPOP) Deferrs £1m bank loan repayment from July to 2020 "following analysis of the Company's new business plan and the successful fund raising".