Small Cap Value Report (Thu 12 Jan 2023) - MEX, BWNG, PMP, TRST, HFD, XAR, ASC, GYM, XPP, MCL, DIS, VINO

Good morning from Paul & Graham!
Today's report is now finished.
Very very busy for news today, so we're doing lots of smaller sections again, to cover as much ground as possible. Please feel free to add your own comments too, especially if you spot something good that we haven't noticed, explaining why it's good.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
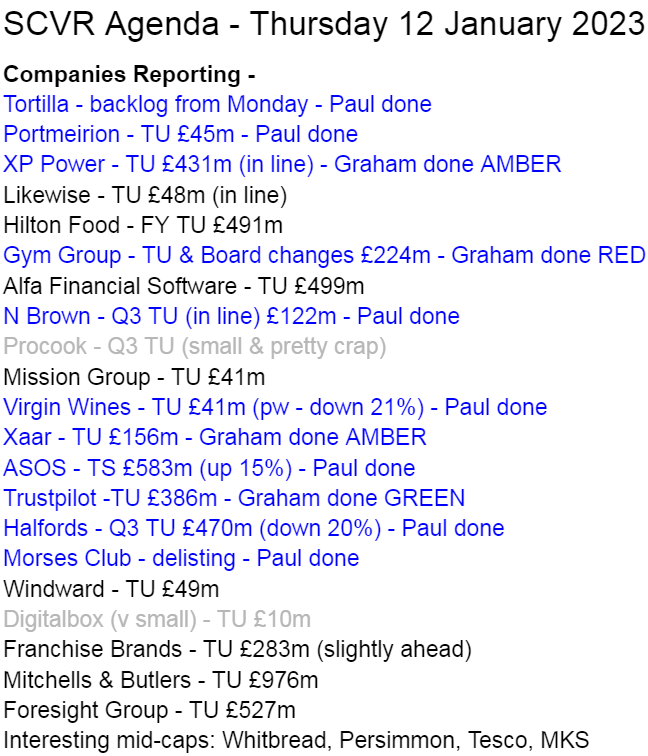
An absolute avalanche of news today - here's our initial agenda, we'll try to work through as much of this list as we can. Also we'll pick up on the big % movers at about 9am, and prioritise accordingly.
Here's the final list, showing what we did & didn't manage to cover. I think we caught all the main stories today (in terms of price moves) -
Paul's Section:
Tortilla Mexican Grill (LON:MEX) - 101p - mkt cap £39m
Trading update on Mon 9 Jan said FY 12/2022 performance in line with market expectations (footnote: £58.4m revenues, adj EBITDA £4.0m). H1 was £2.5m adj EBITDA, so H2 must be lower at £1.5m. Decent growth from site roll-out, and acquisition of Chilango. Impressive LFL revenue performance at +16.4% vs 2019 - it needs to be at this sort of level to absorb all the extra costs. Although note it was +19% in H1. Says it can self-fund further new sites, and good deals available. Confident in outlook.
My opinion - I’m warming to MEX shares, and mystery shopped it again this week - the food is always good, and fairly priced, and healthy-ish compared with other fast food. But beware the £4m EBITDA number - it’s only really trading around breakeven, once you include depreciation and interest costs. Incredibly difficult sector, so I wouldn’t chase this share price too high. Although I see MEX as a long-term winner, likely to expand into a decent-sized national chain, if management can stay in control, which isn’t easy. Overall then, I'll give it a thumbs up due to the growth potential, and solid trading in a tough macro situation. (no section below)
N Brown (LON:BWNG) - 27p pre market - mkt cap £123m
Trading update - Q3 (ish) update says trading to end Dec 22 was “solid”. In line with market consensus outlook for FY 2/2023. Expecting market to be soft in FY 2/2024. Emphasises strong balance sheet (which is true, and the mkt cap is at a deep discount to NTAV - pretty much the only positive thing about this share). As we mentioned recently, the legal dispute with Allianz has been settled, but at a heavy cost of £49.5m. Seems to have ample liquidity, providing banks are comfortable with the big securitised loan.
My opinion - I don’t like the business model, and on current forecasts, it’s only trading around breakeven. No divis forecast either. The bull case is that the huge discount to NTAV might narrow, and self-help measures could see a turnaround (no sign of that happening yet though, with forecasts repeatedly falling). Also chance that controlling family might take it private. Could be a rebound trade in this current slightly mad market? (no section below)
Portmeirion (LON:PMP) - 323p pre market - mkt cap £45m
FY 12/2022 Trading Update - strong H2, with Christmas trading ahead of expectations. H2 is where almost all the profit is made historically. Revised guidance - revenues £110m (4% ahead of both guidance, and LY). PBT guided in line with market expectations, and 10% ahead of LY, has also exceeded pre-covid 2019 level. Pity they couldn’t just give a number, as I’m struggling to reconcile those statements. FY 12/2021 was £7.2m headline PBT, so this implies about £8.0m for FY 12/2022. That’s about 45p EPS, which is what the StockReport shows (EDIT: now confirmed these numbers to a note just out from Singers). So a PER of 7.2 - which looks very cheap. Energy costs are hedged into Q1 2024.
Outlook - cautious about macro, but expecting improved margins from efficiency gains. Margin target (long-term) is c.13%.
My opinion - thumbs up, this looks dirt cheap, and is overdue a strong bounce I think. (no section below). One of my top picks for 2023.
Halfords (LON:HFD) - 173p (down 20% at 08:28) - mkt cap £378m
Around £94m wiped off Halfords market cap first thing today. Q3 update for FY 3/2023. Strong sales in motoring, but softer than expected in cycling, and tyres. Struggling to recruit 1,000 more technicians (mechanics) for autocentres. Revised guidance: underlying PBT £50-60m for FY 3/2023. The last update on 23 Nov 2022 guided “at the lower end of our £65m to £75m range”, so this looks a 15-20% profit cut today.
My opinion - Halfords seems quite a good business, albeit low margin, and has diversified into car servicing & repairs. After today’s fall, the valuations is probably about right, so I can’t see any reason to get involved here. It could do well when the economy recovers and consumers feel more flush, but in the meantime it looks as if discretionary spend is being cut back. Overall, I'm neutral - amber on my spreadsheet.
ASOS (LON:ASC) - 673p (up 15% at 09:05) - mkt cap £674m
Has the long-awaited rebound started in the bombed out fashion eCommerce sector, or is this a dead cat bounce?
Trading Statement - is the 4 months to 31 Dec 2022, of FY 8/2023.
This sounds good -
Confident in outlook, with significant improvement in profitability and cash generation expected in H2 FY23
Q1 revenue down 4% vs LY. Reckons it can make profit improvements of >£300m, more than offsetting inflationary headwinds & higher returns rate. FY guidance is cash outflow of £(100)m to zero range - doesn’t seem very good, despite the upbeat commentary. Expecting an H1 loss, with significant improvement in H2. Stock write-off was previously c.£90m, now increased to c.£130m, buried in footnote 2. Low gross margin of 42.9%, and only 36.1% after including stock write-off. Says this will improve, it needs to! So the H1 numbers are likely to look awful, but we're served jam tomorrow for H2 & beyond.
My opinion - I’ve heard for years that Asos grew exponentially fast, but was a shambles internally - as people, systems, processes, didn’t change with the growth. Today’s indication of £300m+ cost-savings and profit improvements shows that they’re at last taking decisive action to make this a profitable business (it’s never really made any sustainable free cashflow [just a blip in the pandemic], and has never paid divis). Massive £4bn revenues means that every 1% of extra margin puts c.£40m onto the bottom line. Gross margin has always been far too low at Asos. Reduction in costs could further improve profits. So I can see there’s a decent opportunity here, it could be an interesting trade, but it's too early to judge whether it will make a good long-term investment or not.
Morses Club (LON:MCL)
Announces it’s to de-list. It says the listing is not economic, as doesn’t provide access to fresh funds, and inadequate liquidity. Hopes to keep going with private funds. Down 65% as I type this. It’s been a basket case for a while, so I don’t suppose it will be missed.
Distil (LON:DIS)
Another nano cap that's dropped 43% this morning on a hopeless update for FY 3/2023. Revenues will be "significantly below market expectations", and a EBITDA loss of £(0.6)m, in line with previous guidance. It's only got £277k cash left from a £3.2m fundraise in Aug 2021, so looks like another fundraise is needed (if possible at all) or a delisting is the next most likely step. I'll be steering clear of this one, for sure.
Virgin Wines UK (LON:VINO) - down 26% to 54p at 11:44 - mkt cap £30m
Trading Update - for H1 (6m to Dec 2022) has disappointed, causing shares to give up most of the recent rather indiscriminate small caps market rebound.
Profit warning today due to various operational problems, including new warehouse computer system disrupting/delaying dispatches, and problems with couriers. It also incurred extra costs to deal with the problems. H1 revenue fell £6.8m (down 17% on LY) to £33.7m. About half due to operational problems, the other half just reduced demand, presumably as some customers cut back.
FY 6/2023 guidance revised to £63m revenues, EBITDA margin 4-5%. Cash position is fine.
My opinion - disappointing, but not disastrous. Revised PBT forecast (Liberum) is only £1.8m for FY 6/2023, down from £5.3m LY. It’s fundamentally a nice little business, that should be fine long-term. Although shares likely to languish for a while I’d say, so I can’t get excited about it for now. Hence I’m neutral. The strong balance sheet means there’s not much risk here, and it remains profitable at a lower level, so sitting tight for the long-term recovery is probably just as sensible as ditching it and moving on. Your money, your choice.
Graham's Section:
Trustpilot (LON:TRST) (£386m pre-market) [quick comment] - I covered Trustpilot’s interims in some detail here. Today it updates the market with news that adjusted EBITDA for FY 2022 was ahead of expectations. Revenues of $149m look to me below expectations ($153m) after a huge currency headwind that reduced revenue growth by c. 10%. Huge dollar strength in 2022, on the back of hawkish Federal Reserve policies, will have made Trustpilot’s non-dollar earnings less valuable. However, the company’s revenue growth at constant exchange rates was in line with expectations and additionally they have adjusted their costs lower in response to the economic environment. Or in their own words, “given the uncertain market backdrop we have actively managed our business to deliver operating leverage in H2”.
I remain a fan of the story here. Trustpilot has a huge warchest of $73.5m in net cash, has seen annual recurring revenue growth of 20% (using constant exchange rates) to $162m, and enjoys a 100% net dollar retention rate - this means that there is no loss of business from the existing customer base. The valuation has increased since the last time we mentioned this, with the cash-adjusted price to sales ratio rising from 2x to 2.5x (using ARR as the measure of the sales). So it’s not as cheap as it was the last time we looked at it, but I still find it interesting at this level.
One final point is that the former CEO of Future Plc is now the Chair Designate at Trustpilot - hopefully she has learned from some previous investor relations difficulties.
Xaar (LON:XAR) (£137m) (-13%) [quick comment] - this inkjet technology share has spent many years in the doldrums after briefly making it into the FTSE-250 back in 2013. Since then, financial results have been erratic and it looks like 2023 could be another year to forget for the company’s shareholders. Performance in 2022 was at least “on track”: revenues of c. £74m (up from £59m), including organic growth of 9% plus acquisitions. But according to analyst estimates, Xaar’s adjusted profits for 2022 will be minimal (around £1m).
A factory reorganisation should help in 2023, and there are no problems reported from recent acquisitions. The company’s current difficulties instead relate to “uncertainty in China, which is expected to continue in the short term as Covid cases increase. At this stage it remains unclear when normal levels of business will return.” Analysts at Progressive have slashed their adjusted PBT estimate for 2023 from £4.4m to just £2.5m. Perhaps the reopening of China can reverse this bad news? But the truth is that Chinese demand for Xaar’s products has always been volatile and unpredictable. Ultimately, I doubt whether anyone can predict this company’s fortunes. And it doesn’t have the balance sheet it used to have, with its cash balance now only around £9m.
GYM (LON:GYM) (£218m) (-4%) [quick comment] - this low-cost gym operator has decided that it agrees with the views expressed in the SCVR, and has decided to slow the pace at which it opens new sites (see our November article here). Instead of opening 25-30 sites in 2023, it now expects to only open 20 new sites. Total site numbers are currently 229 and personally, I would be fine with site openings falling to the single digits at this point. My reasoning is that the company has a rising net debt level of £76m (this excludes rents) and I fear they may regret funding a roll-out in a year or two when their energy hedges expire and as consumer behaviour remains unpredictable. Gym memberships are of course one of the easiest things for consumers to cut in a cost-of-living crisis. A like-for-like comparison of revenues at mature sites versus 2019 shows that GYM’s site revenues are still only at 90% of pre-Covid levels, and it looks like the post-Covid recovery bounce is now over. Work-from-home/hybrid working has left some of their more mature sites without the local footfall they need to make a full recovery.
Remember that like-for-like revenues need to increase, just for the company to keep pace with inflation. The company reports that January member acquisition is in line with expectations, and they do plan to self-fund their site openings this year (i.e. without any need for further shareholder dilution). But they will do so without their current CEO, who is stepping down, and they are now searching for someone to fill that role. I can’t help the feeling that this change reflects a realisation that prior growth plans were too ambitious. With uncertainty around future leadership and an indebted balance sheet, I would be inclined to avoid these shares for now.
XP Power (LON:XPP) (£430m) (+2%) [quick comment] - 2022 adjusted operating profits will be in the middle of the range of market expectations (£41 - £46m, so I guess that’s £43.5m). This developer and manufacturer of power components had a dreadful H1 but thankfully reports that H2 performance “improved significantly”. The full-year revenue performance is up 5% organically at constant exchange rates.
Looking ahead, order intake has been soft in Q4 compared to last year but the company is still happy with the overall size of the order book and claims to have good visibility for 2023, particularly in H1. The cash performance has been very poor, due to a lawsuit the company lost in the United States, and net debt is now £152m. Inventories are also still draining more cash than expected, and the company has received covenant flexibility from lenders - a red flag that the company is under some financial stress (though it claims it will be able to stay well inside the new covenants). Based on its long prior track record of success, I think investors can probably still have faith in this company, despite the various problems it has had in 2022. Deleveraging needs to be its top priority in the short-term.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
There should be an investigation into the conduct of Paul Smith, the former CEO of Morses Club (LON:MCL), who somehow managed to dump £200,000 worth of shares prior to it being public knowledge that there was a huge spike in claims from Claim Management Companies. This is an open goal for the FCA - will they pull their finger out? Probably not, if history is a guide.
There is a need for short term lending providers but given the tribulations that Wonga, Morses Club (LON:MCL) and Amigo Holdings (LON:AMGO) have had / are having, it seems wise to avoid investing in that industry for now.
I am surprised that this saga has happened with Morses Club (LON:MCL) because I presumed there would be a greater need for short term lending providers given the devastating impact of lockdowns on lower income families. It seems that any momentum that they did have has been eaten up by CMCs.
I also found the comment about Halford's struggling to recruit mechanics interesting. In my very limited experience, it seems that auto mechanics are grossly under-paid relative to the costs of their tools, the technical and physical challenges involved and the increasing difficulty due to the ever changing technology in cars. I hope that the trade gets a bit of a makeover and is seen as more respectable and lucrative. If the salaries and earning potential was higher and not dampened by the 'fix price per hour' model, then presumably their would be more interest in the trade.
I just want to offer admiration and thanks for this heroic shift.
thanks Paul for your great analysis on GYM (LON:GYM) (I hold) all seems very reasonable other then 'Gym memberships are of course one of the easiest things for consumers to cut in a cost-of-living crisis' which I'd disagree with, I think gym membership (especially with the young and retired) is quite sticky and offers great time to expense value, granted the user could join a cheaper gym (or workout at home, run in the park etc.) but this may benefit GYM as they're at or near the budget end.
also, and I hope you don't mind me saying, I was quite surprised you sold out of Saga (LON:SAGA) (I hold) as you always seemed quite optimistic on their long term potential.
finally, I caught quite an interesting little segment on the local news this morning, there was a shopkeeper (I didn't catch which town she was in but it will be South West) and she was enthused about her business and footfall in the area - she put it down to more people working from home and saving money on the commute and other associated costs. I prefer to go in to work but I'm definitely in the minority, there must be a lot of people saving money this way to offset the current cost of living headwinds... just thought the shopkeepers theory was quite an interesting positive if it were to be true.
davidjhill I read your post today on Avation (LON:AVAP) with interest. I bought an opening position on 11 Nov last at 115p as previous resistance was 110p. I sold on 22 Dec at 93.5p as it kept dropping. If it breaks 120p I will be a buyer. Michael Taylor wrote a good article in the IC in November and he clearly thinks the business model works.
thanks portugall - hadn't seen the Michael Taylor piece. on Avation (LON:AVAP) in Nov.
It definitely had a bit of a false dawn in Nov/Dec as they had some delays to finalising the sale of a couple of aircraft from the old Virgin Australia administration and that seemed to lead to a lot of twitchy sales which never helps in a poor market.
As I understand it no further delays were expected though and the company has plenty of liquidity anyway so I'm not really sure why the angst at that time. As you say could have been more related to a technical resistance point. Volume wasn't particularly high.
They have some of the best aircraft to lease though - highly fuel efficient, so as long as there is decent demand for air travel then given the relative low supply of new aircraft second hand asset values should hold up well and increase from here post pandemic. Certainly we've seen that already starting to occur.
Rule of thumb in aircraft leasing used to be around 1.1* NAV as a share price or slightly higher for a takeout of a company with good assets. That would stick them at something over 300p but whether we revert to the historic mean remains to be seen I guess.
The fact that they survived the pandemic, are profitable and have retained most of their asset value from 3 years ago pre pandemic does suggest that there is decent resilience in the business model over black swan type events. Investor confidence returning is something else of course.
Avation (LON:AVAP)
Hi David
I must admit to not fully understanding the story here.
As far as I can make out:
Add those up and it comes to a very large negative number.
What am I missing?
(*the capital repayment figure is an average over the lifetime of the 2 different forms of debt currently being used by the company and based on the last published maturity dates, which are between 2023 and 2031.)
---
I can see that the latest value of planes on the balance sheet is c$813m.
Net debt was $793m.
= c.$20m net asset position
The current market cap is $90m.
I'm not sure that I can see the value that others can see, so any insight would be much appreciated.
Cheers
A
Tangible Assets $1.22bn
Liabilities $990m
= $230m of tangible assets approximately
As at 30th June Company stated the below. nb: NAV doesn't include any goodwill. (basically Planes, Cash and receivables minus debt and maintenance reserves & def tax)
Calculated at $1.22 / £ so same exchange rate. After write down of 2nd hand plane values coming our of pandemic though I believe 2nd hand values have also now risen so I expect an uplift.
Note also that the business model has basically almost no interest rate risk. They fix interest rate and tie the lease duration to the plane finance such that once the lease finishes the plane is basically theirs and then they sell or re-lease. (thats not completely true any more as they did issue a bond but remains predominantly the case)
Key risk as they found during the pandemic is credit risk of airlines and 2nd hand asset values. Generally there are less planes made globally on an annual basis than demand so 2nd hand values hold up well and often increase as planes have a long lifespan if well maintained. Clearly that hypothesis was tested during the pandemic when there was no flying and airlines were going bust.
Hi David
You are missing the elephant in the room on Aviation plc.
Thanks
Assume you mean Avation.
Will you tell us what you are referring to rather than just drop a meaningless comment?
Hi Westway001
Avation that’s the one ( sorry it’s a bit late now! ).
I was referring to the small issue of the bond holders that they actually own this company. If anyone can tell us how all these millions can be repaid without diluting existing shareholders it will be helpful and much appreciated. We are talking here about yearly interest payments that are not far from its market cap and half of their revenues.
Have a good evening.
clearly you know very little about the business then alas and didn't bother to read about it before posting!!!
That’s a great response David , answering my concerns.
Avation (LON:AVAP)
Thanks for the response David.
Yes, I can see their stated £2.68 net assets per share, but as far as I can tell this doesn't include the sizeable interest payments that are coming over the next 8 years ($243m by my calculations.)
That wipes out quite a lot of the $230m tangible asset you mentioned in your previous post.
Incidentally this value looks like it includes $100m of aircraft held for sale, which surely means even less revenue in the future if any of these are currently leased out.
I have no problems with the aircraft valuations on the balance sheet - I'm sure the company know more about this than me.
--
Returning to my earlier post on annual cashflows, I still don't really understand how they're going to afford paying loan capital ($165m pa) and loan interest ($47m pa) and admin costs ($13m pa) until 2026 given their expected annual revenues of c$104m.
Surely refinancing on aged aircraft in a few years won't be easy either?
A
Morning abtan ,
They will clearly have to dilute the existing shareholders or go bust. This company offers no investment case scenario ( at least for me ) as it is too risky with a debt that is tremendously too high in relation to its revenues and market cap.
Thanks
A good CPI read bang on forecast stateside should now calm nerves and mean a 0.25% interest rate increase from the Fed seems very likely odds on.
It does make me feel more bullish about not heading back to the 2022 share price lows, and also blows my FTSE100 hedge out the water, but up or even a consolidation from here is good news for us bottom feeders, and my hedge thank goodness is hardly balanced.
The swift reduction of inflation really will unlock the next bull run IMHO, and combine that with China getting control of COVID, perhaps a settlement in Ukraine and you could see a string of good News stories in 2023....time will tell.
On the shares front I notice Polar Capital Holdings (LON:POLR) RNS on AuM was by no means glowing, and yet up its gone, so I do feel more and more is now being costed in to current SP's.
Thanks entirely to Graham I am in some of these fund managers, and they seem to have terrific potential, and will be buying more on dips in my two holdings Polar Capital Holdings (LON:POLR) and Jupiter Fund Management (LON:JUP). Thanks Graham!
CPI met consensus but actually beat forecast of 6.7%. MoM actually came in negative which is clearly good news.
Anecdotally even here in the UK I have started to see emails from certain suppliers actually reducing costs and working with suppliers to reduce further. Obviously this has to work its way to the consumer but strikes me that inflation could be rolling off quite quickly, particularly supply led inflation. Energy costs are forecast to actually fall now (below energy cap) so in the coming few months I think the consumer could well be feeling more positive, particularly as food inflation backs off.
With a forward view of 6 months I'm feeling more optimistic - the question will be how hard / soft the recession ends up looking and for that we need central banks not to over egg the interest rate pudding. Particularly in the US as they have a dual mandate of inflation and growth.
Jupiter Fund Management (LON:JUP) own 20% of Chrysalis Investments (LON:CHRY) and worth around 10% of JUP market cap.
CHRY have stakes in a few fast-growing non-listed cos inc. Starling Bank etc. Worth having a look - up a lot today and breaking out ...
You're welcome TFI but it's your own decision to invest or not so well done yourself! G
Interesting that Avation (LON:AVAP) is waking up. NAV should be circa 280 - 300p. Broker note out this morning that points out compared to peers they should be trading at 180p+ on a comparative NAV basis.
Business is profitable again and expect 8c of eps next year so that allows them to start growing again. Aircraft usage is significantly up in the industry which has tightened aircraft availability (particularly as a lot of aircraft were decommissioned during the pandemic) and lease rates are going up.
They've jumped about 10% in last couple of days. I'm long anyway but mulling buying some more. Anyone got any other interesting insight?
Thank you eParo for your post on the Cruise Industry which I guess explains why the Saga (LON:SAGA) SP has gone from 99p on 1st Dec to 152p today a 53% jump.
Hi Paul
With regard to your point in your ASOS (LON:ASC) coverage.
Has the long-awaited rebound started in the bombed out fashion eCommerce sector, or is this a dead cat bounce?
Looking at comparisons of on-line retailers UK versus Europe based, it seems an upward trajectory is occurring. The European retailer Zalando SE (ETR:ZAL) seems to have taken an upward trend earlier than the two UK based retailes ASOS (LON:ASC) and Boohoo (LON:BOO) .
I don't hold any of these but have n the past.
Regards
Howard
Langton Capital:
Cruise specialists have reported a significant upturn in demand in recent weeks. Cruise Circle managing director Jason Daniels revealed he was forced to temporarily pause some marketing channels because his sales team ‘could not cope’ with a surge in demand. Cruise365 managing director Anthony Blackmore said ‘Cruise is going through a very big renaissance. December was much stronger than in the previous three years.’
Good read across for Saga (LON:SAGA) and others.
Langton Capital a couple of days ago:
The Advantage Travel Partnership and the CAA are predicting bookings to ‘soar’ over last weekend as it featured ‘Sunshine Saturday’ - the first Saturday after Christmas and new year and typically the most popular day of the year to book a foreign trip…
And, with the weekend now behind us, Travel Weekly writes ‘Hays Travel claimed a fivefold rise in holiday bookings on Sunshine Saturday against the same day in 2022 as customers prioritise holidays in the face of cost of living pressures…’
On Beach group (LON:OTB) has climbed over 70% since the lows. They are getting prime time exposure through sponsoring 'The Masked Singer' on ITV. Should be doing brisk business imo.
Also Hostelworld (LON:HSW) reported a good forward visibility of bookings in its trading update this week. So travel demand seems to be holding up strongly!
I'm trying to build up a position at the moment in an overlooked company in this sector; proving difficult with the low trading liquidity, so don't want to reveal it yet in case the price moves away from me before I build my entire position.
Without any constraints, I think I would be building a much larger portfolio position of travel shares, as I think the signs now are looking they're going to be alright for this summer. But I work in the industry, so already have a lot of my financial "prospects" tied up in the fortunes of the sector...
I also quite like On Beach group (LON:OTB) , been on my watchlist since before COVID.
I was in Thailand recently and there were a lot young people travelling, probably back to pre Covid levels, for young westerners, which is Hostelworld (LON:HSW) market. Many Hotels I stayed in were full or almost full., I stay in cheaper Hotels around about £20.
https://www.stockopedia.com/co...
For anyone interested in Chapel Down (OFEX:CDGP) I have just posted the attached article.
Hi Paul,
I think your new spreadsheets (top 20's and quick ref summary) are great and I find myself referring to them quite a bit.
I wondered if it would be possible for you to add the links to the daily reports as a permanent entry (like the explanatory notes appear daily). So they are easily available for reference?
Thanks again to you and Graham for your insightful commentary.
Andy.
Hi Andy,
I wondered if it would be possible for you to add the links to the daily reports as a permanent entry (like the explanatory notes appear daily). So they are easily available for reference?
I'm confused as to what you mean? I already put the SCVR daily report links in column A of my spreadsheet - here's a screenshot - so if you click on any of the blue dates in column A, that opens up a new window with that day's SCVR in it.
I meant just adding the link to the spreadsheets in you daily report, somewhere at the bottom. So just a easy way to get access to the summary report so we can access content.
On your top 20 spreadsheet, I know I will want to reivew this regularly to look at shares and the share performance, so rather than having to look up the daily report you did in Jan, a link to it would be easier.
Just a thought.
Andy.
bookmark it in your browser?
I really should have worked that out myself!!!
I will do that.
Wynnstay
Following the sell off getting strong support now.
Reckon the “10% off sale” is coming to an end .
Looks like there was a decent seller into a thin market, maybe one of the institutions that backed the 550p raise 6 months ago .
Pretty bad form if that was the case but just speculation and hopefully they would have been locked in .
Not going to multi bag but it’s dividend record of increasing dividends every year and it’s asset backing make this a good bedrock share .
Glad I had this when the market was under huge pressure as it hardly budged (it was a benefactor actually )
My guess is it’s going to bounce straight back to the 600 level so last few days of the 10% off sale .
Wynnstay (LON:WYN) - Appreciate the tip but I think this is the third time in a few days. It’s beginning to sound a little rampy when I don’t think that’s your intention, having been such a big proponent of Crestchic (LON:LOAD) to many members’ benefit.
Not rampy at all everyone on here hopefully can make up their own mind .
I have a very focussed group of companies I follow and spend a lot of time understanding them in great detail including direct conversations with them .
Most readers won’t have that understanding or knowledge so I think it’s relevant .
But no problem to just do my own thing but please do me a favour and don’t take this as ramping that is not my style and I find the comment a bit disrespectful .
Ps - I’m a buyer not a seller so price drop is good for me, that’s the exact opposite of ramping .
My hunch too. Top sliced at 630 and bought back at 536 so my money is where my mouth is. Very solid business and a keeper for me. Also largely inflation proof, but like many has had to adjust to price changes.
https://ahdb.org.uk/cereals-oi...
https://www.cips.org/supply-ma...
I believe much of Wynnstay (LON:WYN) profitability and margin can relate to the price of wheat. London futures are now back pretty close to where they were a year ago near the £200 mark but in the period after Putin invaded Ukraine they shot up to over £300 and averaged near that mark for much of 2022. Fertiliser prices also went up massively and Wyn have profited from maintaining margins at much higher selling prices.
While full year 22 should be a record breaker for them, it is possible that future sales will revert to the levels of previous years. Other headwinds in the animal feed industry as explained in the cips article where farmers are reducing herd/flock sizes knowing that current input costs will make their produce unprofitable.
Hopefully not the case as a holder of Wynnstay but this coming year could be very tricky for the agriculture sector.
I would concur that agriculture is going to be very hard, this is a farmer rather than an agribusiness perspective.
That is a personal view coming from a small farm upbringing, a tenant farmer heritage.
We are addicted as a population to low prices, why pay someone local a good price where you can see them looking after crops or animals well, you can ask what they put on them, feed them, see how they treat them. We take our daughters to see the local organic dairy where we buy our milk from each year! When you can get them from Brazil, or whoever for a 1/10th of the price, including Tesco (LON:TSCO) mark up.
Rant over
Tommy
Hi Planetx
I know we had a discussion off the back of the first fall, as this triggered my "10% off peak" sell rule and I personally was not sure as it was such a low volume, and with everything else I was in the quandary about sell and buy back cheaper. Double up, or just sit tight.
We all have our holdings which are core to our beliefs, that do not let us corner you in a coffee shop or bar as we will bore the item of clothing off you going on at length about it.
I have chosen to increase my stake, not at the lowest low, but taking from a 1% to 2% holding, and that is just me being honest, having looked through last night I still feel the fundamentals are there, I should talk to some of the farmers in the school playground as 25 years since my folks sold up and divorced, but is my blood.
I am also very honest and say yes I am nervous, but that is a lot of things, like a 3rd redundancy in 7 years last September, loss of both the in-laws in Covid who were younger than my 3 olds, and various other stuff in life, and I can afford to be cash for a year or two...
Anyway, this is not rampy, ok there is not a detail analysis within this, it has had a drop without any real reason coming to light, so would not appear inside sellers ahead of a profit warning, well I hope not.
Keep talking.
Tommy!
ps. I hold Wynnstay (LON:WYN)
Any thoughts on perennial disappointed Xaar (LON:XAR) trading update this morning. Revenue appears to be on target vs. forecast but little guidance on ‘adjusted profit’ . Claims ‘strong balance sheet’ - another red flag for Paul. Given that they burnt through £12m cash in 2021 the fact that they only have £8m cash at end 2022 must be a worry in terms of potential refinancing. Perhaps the factory rejigging will generate cash savings but jury must be out on that. Comments about macro headwinds and difficulties in China now and into future don’t inspire confidence either. Hardly surprising that shares down c. 13% this morning. Have held Xaar (LON:XAR) for many years buying at £5.00 after fall from dizzy heights of £11+ in the hope that their technology might attract an acquisitive printing technology buyer (Danaher (NYQ:DHR), Dover (NYQ:DOV, Illinois Tool Works (NYQ:ITW) ) but seems a forlorn hope now!
Halfords / Tandem
Not surprised on Halfords cycling market is in a very bad way and I’d be pretty confident tandem are really struggling to maintain margin and sales.
There is huge oversupply and weak deman, brands massively over ordered based on covid run rate and those orders are now ready .
I have heard from my old suppliers that Taiwan bicycle factories are totally jam packed with orders that brands are delaying / cancelling .
With no pick up in demand it is going to take 12-24 months for this to clear through so that’s 2 years of underperformance to come .
Long term of course ok for tandem who have cash.
Could be some nice acquisition opportunities for anyone looking to pick up some famous cycling brands that don’t make it through the sticky period .
Be warned on tandem .
Portmeirion (LON:PMP)
Pleasing that there is no profit warning here - albeitan incredibly annoying update nonetheless.
Perhaps its my grasp of the english language that is poor (it aint great for sure) but i simply cannot work out what they are saying with the all important cut to the chase comments ref profits.
Ignoring the hyperbole at the top of the anouncement and the flattering comparisons against earlier years i would be grateful if other peeps can advise whether the following text should be read as "profits in line with expectations" or whether it should simply be read as commenting that margins are in line with expectations and zilch narrative as to where profits are compared to expectations?
We expect FY22 profit before taxation to be 10% above the prior year and now ahead of pre-Covid 2019 levels, with improved operating margins and in line with market expectations.
Personally i can only read above text as saying that profits are in line with expectations - this being the case i am confused as the hyperbole at the top of the announcement says the following.
Strong second half and Christmas trading ahead of expectations
Ok its possible they needed a strong second half to meet expectations and the fact that xmas is ahead of expectations doesnt really give much away (xmas alone could explain the strong second half) - so its technically possible these comments could be fcatually correct when they are only in line with expectations.
Is it really that hard to provide crystal clear not "fluffed up" guidance when we are past the end of the year - not even a mention of what current market expectations are. This company gets a 0/10 mark from me with regard to this outlook - thats annoying as i am happy with profits being in line with prior expectations.
It gets a BBB from me.
(Bullsh!t Baffles Brains)
Hi rmillaree,
You could insert a comma and get it to make sense: "...margins, and ...".
Or is that confirmation bias?
Is it that bad? As a matter of normal English usage, the phrase "in line with market expectations" applies to the increased PBT, and cannot apply to "improved operating margins". Whether the sentence is true or not is another matter - just what is the point of referring to market expectations without telling the reader what the writer thinks they are?
Portmeirion (LON:PMP) (I hold) rmillaree yes I share your concern that the trading statement is less than helpfully clear. I get that its serving at least 2 audiences, firstly the financial press that will restate the fluff without looking too closely under the covers and [2] actual shareholders. Unlike the institutions - that have their own analysts and detailed forecasts to refer to - a lot of PI's won't and will likely just go with the fluff. The rest of us, trying to be both analyst and fund manager are wandering around holding our heads and trying to work it out!
FWIW - this is my interpretation.
Strong H2 and Christmas ahead of expectations - no reason not to take this as it seems.
Except that we learn that Revenue is £110m ahead by 4% and also 4% ahead of expectations.
So thats the ahead bit?
Whereas Profit before tax is up by 10% on FY21, but despite improved operating margins (and the beat on revenue) its only in-line with expectations? How does that work?
Short answer: I don't know.But the CEO does state that : 'The sales outperformance benefits from the retranslation of US dollar sales at a lower rate (which benefits revenue but not profitability)'
Which seems to be saying that the sale outperformance is an accounting artifact - and in constant currency they are both in line? Which seems ok? Except that putting that as the headline would have not generated the same fluff in the media reports?
I tend to put this kind of thing down to the brokers, advisors and corporate comms over-ruling the management. Perhaps they need to put their foot down harder? A clear note to define the expectations at the bottom would save us all a lot of headache?
Really must remember to put this in FULL CAPITALS in the comments on the next IMC presentation. Perhaps we should all coordinate that? Please remind me!
Anyway - aside from that. An in-line statement with some tail-winds from the USD is no mean feat? A bit less than I'd hoped for but it does set up well for 2023?
Without the £1m restucturing charge (pretty please!!!), improved margins, productivity gains and much reduced freight costs - shoud be a big rise in H1 figures to help keep the share price rising?
Can't help comparing with Churchill China (LON:CHH) and thinking that there is a long way still for this to rise - particularly if they start to seriously move margins towards their declared >13%,
cheers
Mark
Franchise Brands (LON:FRAN) seems to be doing very well, especially after the acquisition of Filta, a company that recycles commercial cooking oil. Demand for that has increased with higher prices for virgin oil. Hopefully Paul will have time to comment on this one.
Franchsie Brands (LON:FRAN)
Yes, Filta grew revs from $51m to $90m in 2022
MetroRod and MetroPlumb grew 19%
Whilst B2C struggled. B2C has become a very small part of the group as B2B done fantastically well.
Stephen Helmsley CEO and 17% shareholder:
"I am particularly pleased with our performance in 2022 which has been another year of strong growth for the Group. The Filta businesses have been integrated faster than expected and have made an excellent contribution in the year, with many more opportunities identified for development in the future. It is a credit to the team at Metro Rod and Metro Plumb that they have now achieved £60m in system sales in 2022, up from £50m in 2021, together with significant growth in profitability."
"Following the successful integration of Filta, our B2B businesses offer a significant opportunity to capture an increasing share of their large, fragmented markets where scale and our ability to serve customers through our one-stop range of services is becoming more of a competitive advantage. In the B2B markets we are also able to leverage our core central services, in particular technology, increase our international footprint and selectively acquire businesses that extend and complement our existing portfolio."
I hold
My morning smallcap tweet: The Big Sweep. 23 shares covered.
GYM (LON:GYM) ASOS (LON:ASC) Ince (LON:INCE) Morses Club (LON:MCL) Franchise Brands (LON:FRAN) Portmeirion (LON:PMP) Distil (LON:DIS) Woodbois (LON:WBI) Plant Health Care (LON:PHC) Digitalbox (LON:DBOX) Windward (LON:WNWD) Xaar (LON:XAR) Trustpilot (LON:TRST) IQGeo (LON:IQG) Mission (LON:TMG) Virgin Wines UK (LON:VINO) Alfa Financial Software Holdings (LON:ALFA), Dechra Pharmaceuticals (LON:DPH), PROCOOK (LON:PROC), N Brown (LON:BWNG), K3 Business Technology (LON:KBT), Likewise (LON:LIKE), XP Power (LON:XPP)
◄The Gym Group (GYM)► guides FY-Dec rev up 63%. In line? Outlook "intend to take a more measured approach to our new site openings in 2023" due to macro. Jan new members started in line with expectations. [SP=125.6 Cap=226m]
◄ASOS (ASC)► guides Sep-Dec rev down 3%, broadly in line with expectations, "reflecting challenging trading conditions and prioritisation of structural profitability improvements". Adj gross margin broadly flat with encouraging progress through the period. FY cssh outflow in line. [SP=580.3 Cap=580m]
◄Ince (INCE)► regustory approval for sale of Arden which is expected to complete on 16 Jan. [SP=4.95 Cap=19m]
◄Morses "it's not a" Club (MCL)► proposes delisting. "Trading on AIM no longer sufficiently provides the Company with the advantage of providing access to capital in the medium to longer-term, nor, in the opinion of the Directors, provides significant liquidity to investors". [SP=1.22 Cap=2m]
◄Franchise Brands (FRAN)► guides FY-Dec rev and adj EPS slightly ahead of recently-increased market expectations of £98.75m and 7.7p. [SP=219.64 Cap=286m]
◄Portmeirion (PMP)► guides FY22 rev £110m+, 4% ahead of market expectationa. Margins in line. [SP=321.75 Cap=45m]
◄Distil (DIS)► guides FY-Mar significantly below market expectations but EBITDA loss in line. Blames one-off reduction in stock availability during key Christmas trading period within a major retailer. Q3 rev down 48%. [SP=0.9 Cap=6m]
◄Woodbois (WBI)► Q4 rev up 32% and FY22 EBITDAS (bullshit earnings before share based payments) >$3m. In line? [SP=1.69 Cap=38m]
◄Plant Health Care (PHC)► distribution agreement of Harpin ab for use in sugar cane production in India with commercial sales beginning 2023 H2. [SP=11.09 Cap=34m]
◄Digitalbox (DBOX)► warns FY-Dec rev below mkt exp but EBITDA broadly in line. Blames economy. [SP=8.59 Cap=10m]
◄Windward (WNWD)► guides FY-Dec rev up 23% and EBITDA loss c. $12.2m ($8.6m) "reflecting investment in headcount to support R&D and sales and marketing". Sales weak except in US. [SP=58 Cap=50m]
◄Xaar (XAR)► guides FY-Dec rev up 24% and adj profit in line. Outlook "Sales volumes in the Printhead business continue to be affected by the uncertainty in China, which is expected to continue in the short term". [SP=202 Cap=158m]
◄Trustpilot (TRST)► guides FY-Dec rev in line and adj EBITDA ahead of expectations. [SP=93.35 Cap=389m]
◄IQGeo (IQG)► guides FY-Dec ahead of expectations with rev up 88% and adj EBITDA £1.8m. [SP=193 Cap=119m]
◄Mission (TMG)► guides FY-Dec rev up 10%, slightly ahead of expectations (whose?). [SP=46.2 Cap=42m]
◄Virgin Wines (VINO)► warns FY-June rev only £63m EBITDA margin 4% to 5%. Blames some one-off factors, particularly over Xmas. [SP=75 Cap=42m]
◄Alfa Financial Software (ALFA)► hikes FY-Dec rev exp by £1.5m all falling through to operating profit.. [SP=169 Cap=502m]
In line: DPH, PROC, BWNG, KBT, LIKE, XPP
Morses Club (LON:MCL) delisting from AIM to save costs stop going under and attract private finance. I don’t know what holders get - zero or some holding in a private co.
PIs retain their shares in the private company. MCL proposes to establish a 'matched bargain' facility. It still means they will be worth 3 fifths of 7 eighths of b****r all!
Morses Club (LON:MCL)
Needs 75% shareholders approval / shares remain trading prior to cancellation due close 12 Feb / assetmatch.com to facilitate an electronic off-market dealing facility for the Ordinary Shares.
Presume they are mopping up any shares on sale (recent spike) so the free float has gone and only die hards left.
What happens if they don't get 75% - clearly fold the company but presume there is some disadvantage in doing that - maybe directors on the hook with the FCA or suchlike, so taking it out of public eye.
So maybe the auction would give a good deal to mop up the diehards?
Don't understand how have shares in a private company - would that not be good?
Complete newby on this so more a learning exercise. Investment reduced long ago, just a small holding to keep watch. Not sure why I got suckered in, probably the SR99 back in 2021.
Is anyone else having issues with Investegate this week? It's unusually slow.
Yes its been in and out all week
Yes, it takes ages to login.
It is worth asking what Investegate does (or how it does it) that Stocko doesn't.. I mean, we should be able to get the news we need, as we need it from Stocko right, but I too find myself always opting for Investegate in the mornings. Neither sharpad or stocko have a contender in news feed yet..?
Stocko’s news feed does not generally seem available before at least 7.10, so if your window is between 7 and 7.10 Investegate is the alternative. I do find the latter a bit clunky (and slow to load), however.
Any thoughts on IQGeo (LON:IQG) ? Fabulous growth, but valuation is very high (160m mc for 2m of EBITDA)
Our latest research on £BRK following this morning's update (link here: https://www.equitydevelopment....)
Brooks Macdonald (BM) continued to build momentum in Q2 of FY23 (to 31 Dec 22), with FUM increasing by 4.5% (+£0.7bn) over the quarter to £16.2bn (end of Q1: £15.5bn). BM chalked up its 7th consecutive quarter of positive net flows of £156m, an annualised rate of 4% of opening FUM. Investment performance contributed £546m to the FUM increase (3.5% of opening FUM, in line with the benchmark MSCI PIMFA Private Investor Balanced Index - capital only).
Management have confirmed that underlying profit and margin are running in line with expectations, and our forecasts remain unchanged, although our fundamental valuation ticks up to 3000p per share, which is 44% above the current share price, with the increase due to a reduction in the UK 10-year gilt yield (the risk-free rate used in our DCF valuation). We also highlight that BM’s PER of 14.0 is significantly below a peer group median of 17.3 which doesn’t look justified. We will revisit our forecasts & valuation when H1 results are released on 2 March 2023.
Our latest research on Polar Capital Holdings (LON:POLR) following this morning's update (link here: https://www.equitydevelopment....)
AUM fell 1.6% over Q3 of FY23 (to 31 Dec 22) to £18.47bn. Over the first nine months of the FY the AUM fall totalled 16%, although this was heavily impacted by the significant sell off in technology stocks in Q1 (Apr – Jun 22). Net outflows totalled £304m during the quarter, lower than the £529m recorded in Q2 and the £316m of Q1. Market movements and investment performance contributed +£19m over the quarter (Q2: +£342m; Q1: -£2,393m). The closure of Phaeacian mutual funds in Q1 resulted in a -£469 impact on AUM.
The lower net outflows of the latest quarter and two consecutive quarters of positive investment performance suggests a degree of positivity in some of the major sectors Polar is exposed to, and perhaps some stability in the most significant technology sector. More specifically, Polar has reported:
• continued demand and inflows into the Global Insurance, Healthcare Blue Chip, Smart Energy and Emerging Market Stars funds, with combined net inflows of £190m in the quarter;
• a continuing decline in the rate of outflows from its open-ended Technology funds, with £217m of outflows in Q3 compared to £252m in Q2 and £380m in Q1.
This latest AUM update suggests Polar is on track to meet our previous FY23 forecasts, which remain unchanged (we will revisit forecasts & valuation with the Q4 AUM update in April), as does our fundamental valuation of 600p per share (20% above the closing 11 Jan 2023 share price). We also highlight that Polar’s PER of 9.8 is significantly below the 12.2 median PER of a UK-listed active fund manager peer group.
I note the Persimmon (LON:PSN) trading statement today, following Barratt Developments (LON:BDEV) yesterday, with recent home reservations well down, and a comment on how mortage costs for some first time buyers have roughly doubled. Hopefully these comments are 'in the price'.
Persimmon (LON:PSN) Private sales down by over 50%. I agree with Paul that at some point the housebuilders will be a great buy. Perhaps not yet.
RNS
The change in market conditions gathered pace in the final months of the period, with private net sales reducing to 0.30 per outlet per week in Q4 (Q4 2021: 0.77), with the last 7 weeks of 2022 at 0.19 per outlet per week (2021: 0.61). The trading performance weakened across all geographies with the biggest impact on sales seen in our Southern regions. We saw a particularly sharp fall in demand on those sites where Help to Buy was more widely used once the scheme in England closed for new applications from 31 October.
Political comment: I regard Help to Buy as a policy error. It was a significant cause of large increases in house prices while it was running. I don't think excessive rises in house prices help our society very much in the long run and I speak as someone with a substantial amount of net equity invested in UK residential properties (not including our home).
Current forward sales position
£1.0bn
£1.6bn
-36%
Of which private forward sales
£0.5bn
£1.1bn
-56%
Completely agree . Help to Buy has encouraged many young people to take on debt and given the market downturn, many will struggle.
Houses are generally not selling where I am in the midlands and until house prices return to actual market values (Pre Covid ?) the sector looks to be in for a rough time
Agreed. I think you can argue that the housing recession is mostly in the price, especially given the good balance sheets this time round. The elephant in the room is the stopping of Government distribution of free money, aka Help to Buy. How much this adds to a housing recession and for how long, is anyone’s guess.
Also there is political risk to the upside, Government seems addicted to being the answer to any problem and spending any amount of money despite deficit and national debt figures, so there is always the possibility of the announcement of a son or daughter of Help to Buy, especially prior to a GE. Although I don’t think that would be a good idea, I do think it would mark an upturn in housing stocks’ share prices.
+1 ref housing being way to expensive and help to buy being ouit of control - unfortunately the mass nimbyism , over protection of our greenbelt (have you seen how much green there is when you have a long train drive) , woeful strategic planning and woeful planning permission processes ensure we build a fraction on the new homes we should do each year. We get the hype from every government that they want more new homes being built and it never happens. Its a national disgrace that every couple that is working and earnings the minimum wage not living in london doesnt have some affordable housing within a reasonable commuting distance of where they were born and brought up. Ok we will never get perfect in that regard but the lack of any effort to help provide affordable houses en masse is super frustrating to me - and i dont even have any kids to feel sorry for !!
Ok second rant for the day over and out
[EDITED] @GreyInvestor - Looks like your hope is being fulfilled, the update was in the price, Persimmon is up, nearly 5% as I type. And so are all but 4 of the shares on my folio of businesses connected to the UK housebuilding sector:
https://www.stockopedia.com/po...
(I hold MJ GLEESON (LON:GLE) and Wickes (LON:WIX)
Persimmon's RNS says nothing about cutting the dividend. If this is held it could provide a return of 17% (it was 18% earlier before this morning's sp increase). If it's held the dividend isn't going to be covered but even so.....
If you look at all the builders, all above their lows and any bad news is being easily absorbed in either flat or higher share prices!