Small Cap Value Report (Thu 16 Feb 2023) - IHC, CKT, HOME, CREO

Good morning from Paul and Roland!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Roland’s Section:
Inspiration Healthcare (LON:IHC)
51p (pre-open)
Market cap £35m
This company provides medical technology for critical care, with a focus on neonatal intensive care. Inspiration Healthcare’s own-branded solutions include non-invasive respiratory management and thermoregulation, while its UK distribution business supplies solutions for surgical procedures and infusion therapies.
Graham covered November’s profit warning from this medical equipment manufacturer here. To recap, the company said that problems in China meant that a number of orders would slip back into the following financial year.
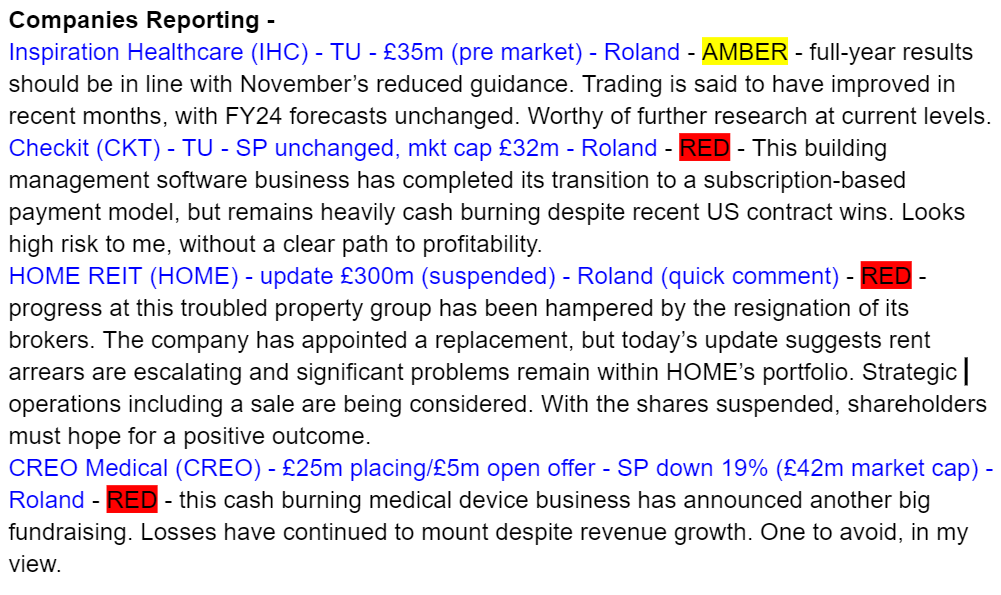
Results guidance: Today’s full-year trading update confirms results for the year ended 31 January should be in line with revised expectations from November.
“following the close of the financial year ended 31 January 2023, the Group is expecting to report revenues of approximately £41.2 million representing an increase of 0.4% compared to the prior financial year and in line with market expectations. Adjusted EBITDA* is also expected to be in line with market expectations.”
An updated broker note from Cenkos is available on Research Tree this morning. Cenkos analysts estimate EBITDA of £3.8m for the current year, valuing the business at around 10x EBITDA.
Cenkos forecasts are consistent with the consensus estimate on Stockopedia for adjusted earnings of 0.7p per share for the year ended 31 January.
Current-year trading update: Chief executive Neil Campell (who is a 6% shareholder) says that recent months “have seen increased order flow” and “a high level of interest in our products”.
Mr Campbell says that external disruption effectively stalled the group’s growth last year, but he now believes the group is well placed to return to growth.
Cenkos analysts remain positive and have left their FY24 forecasts unchanged. These align with those on Stockopedia, suggesting revenue could rise by 10% to £45m this year, supporting earnings of 3.6p per share.

These estimates price the stock on 14 times FY24 forecast earnings, which does not seem too unreasonable to me.
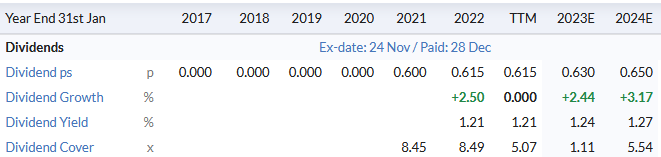
It’s worth noting that the group has minimal debt and is expected to pay a (slightly) increased dividend of 0.63p per share this year.
My view: I’ve followed this company intermittently for a number of years, after being impressed by management at a ShareSoc presentation. I think it’s fair to say that progress has been a little frustrating and inconsistent, but in my view this remains an interesting business, with strong management ownership and support from some leading small-cap specialist fund managers.

Acquisitions in 2019 and 2020 resulted in some dilution for shareholders, and it’s disappointing that this has not yet translated to a consistent step up in profits. However, the circumstances around the pandemic were exceptional. I don’t see any obvious reason why a more stable performance won’t now follow.
One area I’d like to understand more about are the profit margins on different product ranges. According to previous broker notes, November’s profit warning had such a severe impact on profits (88% eps reduction) because it related to the loss of higher-margin sales.
At current levels, Inspiration is trading on a price/sales ratio of less than one, with minimal debt and a track record of reasonable profitability.
This situation isn’t without risk, but my feeling is that the stock could offer value at current levels and is probably worthy of further research.
Checkit (LON:CKT)
31p (+4% at 08.30)
Market cap £32m
Company presentation: Checkit’s CEO and CFO are giving a presentation on the Investor Meet Company platform at 12pm today.
This software business helps monitor the productivity of “deskless workers” in sectors such as hospitality and healthcare, by monitoring their interactions with “critical equipment and buildings”.
Growth took a hit during the pandemic when many such businesses were closed. However, Checkit is now back in growth mode and expanding into the US market.
Trading update: the company has been converting its customers to a subscription model and says this process is now complete. Full-year revenue is said to be slightly ahead of expectations:
Annualised recurring revenue (ARR): £11.5m (+28%)
Revenue from continuing operations: £10.3m (+22%)
Net cash at 31 January 2023: £15.6m (31 July 2022: £19.5m)
Checkit is expanding into the US market and says that ARR from US clients rose by 91% to £2.8m last year. Recent wins include “biopharma customers and a new contract with a large resort and casino operator”.
The US business is said to be on track to be the largest revenue contributor to the group. Given that US ARR only accounted for 24% of ARR last year, this seems to suggest either that US growth remains very strong, or that declines are expected elsewhere.
Cash: Checkit’s post-pandemic growth may be encouraging, but I’m more concerned about the group’s continued high cash burn rate.
Net cash fell by £3.9bn in six months between July and January. Today’s statement does not provide any fresh guidance on a pathway to profitability, although a further update is promised for April.
At the current rate of cash burn, I’d say that Checkit would need to raise funds in the next 12-18 months, to avoid a cash crunch.
Broker forecasts from Edison (paid research) are unchanged today and suggest an aggregate pre-tax loss of £12.8m for FY23 and FY24.
My view: I’d be interested to learn more about the size of the market opportunity here and about potential competitors.
However, until Checkit’s management can provide clear guidance on a pathway to profitability and cash flow breakeven, this business remains too speculative and high risk for my appetite.
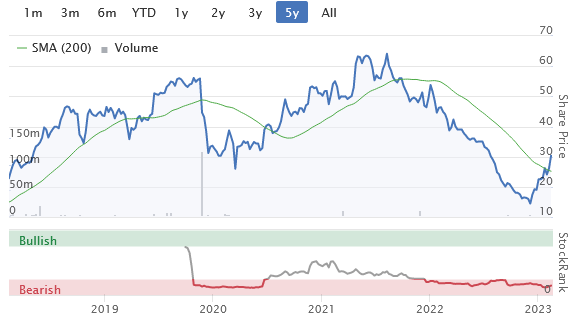
Stockopedia’s algorithms concur, awarding a Sucker Stock classification and a StockRank of just 14.

Creo Medical (LON:CREO)
23p (-18% at 09.15)
Market cap £43m
Placing and subscription to raise a minimum £25m
Creo Medical is focused on the “emerging field of surgical endoscopy”.
This loss-making business has announced a £25m placing and £5.2m open offer today. That’s a fairly hefty level of fundraising, for a business that had a market cap of £50m at last night’s close.
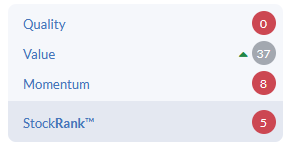
The StockRanks are highly sceptical of this business, highlighting its speculative status:
Fundraise: £25m of shares are being placed with institutional investors at 20p. Existing shareholders will also be able to apply to buy new shares at this price through a £5.2m open offer.
Share price spike: the 20p placing price is broadly in line with the level the shares have been trading at over the last month. But the stock spiked up by around 40% yesterday, which looks a little odd to me. Perhaps news of the fundraising leaked?

My view: Paul warned about the worrying rate of cash burn at this early-stage medical device business in January and August. The need for a fundraise was also flagged in a recent broker note from Edison (paid research). Hopefully no Stockopedia subscribers have been caught out by today’s news.
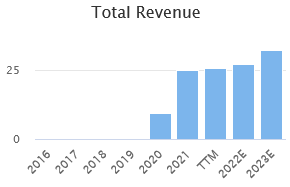
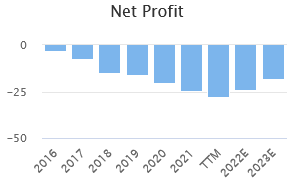
Creo Medical’s revenue has risen from £0m to £25m since 2019, suggesting the company is selling growing quantities of product into its target markets. However, there’s no sign yet of this growth converting into profits. Losses have ballooned during this time.
The share count has risen too, due to repeated fundraising:

I don’t have any insight into the potential size of the market for the company’s products. But shareholders who have stayed loyal to this story have paid a high price. The shares have lost 90% of their value over the last two years:

From an equity perspective, Creo remains uninvestable in my view, until the company can demonstrate profitability and positive cash flow.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
I want to say on Creo that surgical endoscopy is not an emerging field. Developing perhaps as yes the number and scope of procedures are increasing, but broadly, snaring polyps is surgical endoscopy and that's been happening for decades. The company is guilty of some fairly questionable promotional material which has hoodwinked a lot of people for example this chap: https://www.fool.co.uk/2022/11... who championed the company twice and seemed to be convinced that endoscopy was only diagnostic before Creo.
Creo Medical (LON:CREO) From other comments you appear to have some insight into things medical. I am quite swayed by the £2m of director investment at the raise. This is much higher than they have previously put in. The sales have gone from £13k to £27m in 3 years. I See the issue about profitability, but maybe the directors know what's coming? The issue about training people during the pandemic would appear from the outside to be genuine. What is it you see in this that makes the claims questionable? Not attached to this and very keen to learn about the negatives from a functional and potential sales perspective.
Hi Roland, regarding Checkit (LON:CKT) their current cash is sufficient to get them to break even at the current and historical ARR growth levels (30%). There was a lot of supporting information given in the Investor Meet presentation.
£18m - £20m ARR needed for break even (expected FY25) - ARR currently at £11.5m
Projected cash at end FY24 £9.5m - Analyst estimate (£6m burn / 500k per month, down from £660k per month FY23, which was down from £800k per month HY23)
Projected Cash end FY25 £3.5m - My estimate (then break even)
Year end 31 Jan
So we have visibility on profitability, it's just 2 years away (at current growth rate).
Sounds like you heard my question on todays Checkit (LON:CKT) webinar Scoobydoit ;-)
Cash burn is certainly key for them right now so let’s hope their forecasts are correct and no raise is required. I was impressed that they (as far as I could tell) answered ALL the questions they were asked. In my experience, companies using InvestorMeet are inclined to cherrypick those they prefer to answer over more tricky ones. So credit to Checkit
I believe the Edison note is also on the CKT website so that’s my next stop
Hi Scoobydoit,
Thanks for the clarification and extra info re. Checkit (LON:CKT). I wasn't able to make the IMC presentation.
Hopefully the company will be able to meet its forecasts and avoid the need for a further raise. Good luck to holders!Regards,
Roland
Except, H2 growth rate at Checkit (LON:CKT) was weaker than H1, and if that continues, they'll fall short of the 30% growth rate. Not far off though.
However, what if the softer H2 growth rate in ARR, is symptomatic of further growth slowdown? And then we start to see like 15%-20% annual growth rate in ARR, and suddenly the break-even horizon slips too far into the future.
Up for everyone on their own to judge the cash runway, and the growth momentum with Checkit...
Hi Roland
Is Paul ok or just having a well deserved rest?
James
Avingtrans taking a right kicking the past week .
Plenty to buy in the 360s and hard to sell indicating going to go a bit further.
Not too much volume and seems to be a bit of a possible bear trap .
Seems to be sone nervousness about their investment into Adaptix /Magnetica digital imaging system (seems to be like Polarran)
Daily volume is pretty low and it’s dropped from 440 to 368 .
I’m nibbling away on the drops down .
Going to recheck the fundamentals as I’m starting to question it .
They post half year results on 22nd.
The spread is quite wide at the moment on Avingtrans (LON:AVG) , buy price of 375p, is not much lower than the other day, even though the share price is down. Will see if it drops below 360p.
Hi planetx
You beat me to it! I was going to post on Avingtrans (LON:AVG) as it is my largest holding just. Average in price 258p. The recent share price weakness has perplexed me. I added at 347p in November or thereabouts and added a few more recently at 400p
I am, as best can be, familiar with the company and keep on asking myself have I missed something? The newsflow and other factors that are summarised below are all positive.
I could go on. Avingtrans (LON:AVG) operates in regulated industries where the barriers to are high. The obvious example is nuclear where its subsidiary Metalcraft manufactures high integrity storage boxes for nuclear waste. There are to my knowledge no other UK companies accredited for this work. Again from the last prelims:
"During the period, Metalcraft and Sellafield Limited entered into the second phase of the contract to provide high integrity stainless steel storage boxes for Sellafield. The 3M3 ('three metre cubed') box contract is now worth up to £70m, being a £20m uplift to the original contract awarded in 2015. In the year, the division's nuclear credentials were enhanced by the strong recovery of Booth Industries, which also broadens our market reach into Critical National Infrastructure (CNI). Booth's multi-year contract with HS2, worth £36m, is progressing well."
If you haven't already done so I would suggest watching the video interview that Paul Hill did with Steve McQuillan, CEO and Stephen King CFO in September following the company's prelims. Also there is a further video interview that Paul did with Christopher Mills of Harwood Capital last December in which Avingtrans (LON:AVG) is discussed. Both are available on VOX Markets.
Apologies for the length of this post but it has helped me go through my reasons for investing and continuing to hold. I would conclude by referencing broker research from FinnCap published on 17 Jan that confirms its forecasts of adj eps of 22.8 and 24.4 for years to May 2023 and 2024 respectively. On this basis and given the ungeared balance sheet the shares are hardly expensive, plus there is the potential cherry on the cake of Adaptix and Magnetica.
Difficult for me to avoid bias and there are always the potential for the 'black swan' event, but all the know facts indicate that Mr Market has got it wrong. Fingers crossed!
All the best
hi Jonno
‘There are to my knowledge no other UK companies accredited for this work’
..a small point but Goodwin (LON:GDWN) are also accredited for this work & share this contract with Maloney Metalcraft, they also do a wide range of other more complex contracts for Sellafield in part because they are a foundry as well as a machine shop with nuclear accreditation
I’ve held Avingtrans before but currently my largest position is Goodwin…incidentally Carr’s mentioned some lower margins in their engineering division which is also a Sellafield supplier but akin to Avingtrans has no casting capability in house, it’s my understanding that the 3m box contract design has evolved over time & might now be sporting a rather advanced cast lid designed/produced by Goodwin
Cheers Rhomboid,
I wasn't aware of Goodwin's association with Metalcraft. The more information the better as it helps my understanding of Avingtrans (LON:AVG) . There must be IP associated with the design of the nuclear waste containers? I assume that this resides with Metalcraft as they hold the contract with Sellarfield?
Certainly provides the basis of a few questions for Avingtrans (LON:AVG) management team who have to-date proved themselves to be adept and alert to opportunity.
Carr's appears to be in a state of flux at present in that their prelims have been delayed due to audit complexities. I have occasion whimsically thought that their engineering division with its remote handling capabilities would be a good fit for Avingtrans.
All the best
This is a link that describes some of the background
https://www.gamechangers.technology/static/u/GC%20Challenge%20Statement%20Magnox%20SL%20-%20Monitoring%20Waste%20Packages%20web.pdf
I believe the IP is likely held by the NDA but I’m not entirely certain…it has certainly been a long process getting into series production…reading between the lines I believe the 3m box contract is not terribly high margin compared to other products (eg the 30 tonne SSB’s or the can racks that Goodwin supply) but obviously it’s high volume long duration work & there’s plenty to go around .
Thanks Rhomboid
Have opened the link and will have a read to see what can be gleaned.
Hi Jonno
Further reading suggests I may be mistaken & Goodwin perhaps don’t share this contract ..at least currently https://www.gov.uk/government/...
I think the confusion on my part is around discussion I’ve had with them about various waste recycling containers they are involved in supplying…sorry for adding additional confusion
cheers
Morning Rhomboid
Thanks for the update regarding Goodwin and the earlier information on "Monitoring of waste packages". Happy to hear that Avingtrans (LON:AVG) subsidiary Metalcraft are likely to be the only UK company involved in the supply of the 3M nuclear waste containers to Sellarfield.
They certainly have have plenty to go at.
I know of Goodwin, a successful family owned niche engineering company, but know little about them. Shall have to do some homework.
Best wishes
Well Im with you, even with a black Swan event it is pretty well diversified with the separate divisions.
The magnetica / adaptix is going to burn a bit of cash Im sure but thats a big win if/when it comes off .
I think there has been a few sellers moving funds out of Avingtans into some of the speculative dross that has had the strong "everything bounce".
Now my biggest holding too and just got to sit tight .
Very thin trading at the moment.
As Warren Buffet says "we like it when prices go down " so we can buy more and whilst Im not quite as comfortable in my skin as that I think we just need to chill out here .
Looking forward to the interims and post results videocast on VOX Markets that Paul Hill has indicated he will try to make happen.
Hopefully I have read the runes correctly. Based on the know facts and looking forward to the rest of 2023, I am of the opinion the risk reward is very much on the upside.
As an afterthought I wandered whether an equity raise might be in the offing to fund an opportunistic acquisition, hence the share price weakness, but have dismissed that idea as it tends not to fit with the Avingtrans (LON:AVG) approach, which is to avoid overpaying by acquiring businesses that have potential but are in a mess.
Good luck with your investment.
Avingtrans (LON:AVG)
Interesting discussion. I've held for a number of years and did venture down to Birmingham for the agm just after they acquired Hayward Tyler.
The nature of the business (PIE strategy) means material events arrive out of the blue (acquisitions, sales etc).
I believe Booths is close to being ready for sale, it's been re-incorporated as a standalone unit and has an attractive orderbook.
Magnetica is being targeted for a float in 2024. Be interesting to see how the product is received later this year on launch.
Regards the 3m3 boxes Metalcraft are the only current provider (after Darchem dropped out/were dropped) but management expect future contracts to be shared due to their size. Hopefully Goodwin (LON:GDWN) will pick up some business as I also own them :-)
Nice post, has encouraged me to research further, thanks
Checkit (LON:CKT)
Today's trading update says they are substantially (my definition) ahead of expectations, however, these expectations were downgraded at the interim stage in September and these results are still below the previous ones - see Singer and Edison reports. Also they say cash ahead but the burn is still substantial.
No position, ex holder.
Investegate |Checkit PLC Announcements | Checkit PLC: Trading Update and Notice of Results
Urgh..... I hate the fact Hargreas Lansdown don't let you set buy limit orders or edit stop loss levels! Grrrrr
I can set buy limit orders?
I have no problem setting buy or sell limits orders on HL. It's an option on the same page where you specify the deal you are looking to place.
You can only do it for lower prices? Not for when the price to buy is higher, for breakouts?
Yo can do both to be fair.
I ditched HL though as their fees are too high, especially for overseas equities. I use Interactive brokers these days... far better
You can't edit orders, you have to cancel them and then redo the order.
What are II fees? Is there a custody fee?
Agreed. Interactive Brokers (IBKR) are great for overseas equities. They cover a very wide range of international markets and their charges are reasonable. Another reason for ditching Hair Grease Pants Down is their history of recommending the Woodford funds despite:
1. their poor long term performance
2. the incompatibility between their name - Equity Income - and their portfolio make-up - too many illiquid, early stage companies that didn't pay dividends
IG are also good for for UK and international equities.
'C' I believe you are wrong on HL and buy/stop loss limits. If you go to do a trade on a company ,just above the trade details you will find stop loss/buy limit . I am doing this from memory if you have any further trouble, please contact,and I will make sure Tony
I think you misunderstand. Can you buy shares at a price higher than the current price with a buy order, say you want to buy BP (LON:BP.) @ 599p?
You can only do, Buy limit for price below current price, if I put in 599p, the order will fill straight away.
Upper limit to sell and Stop loss also.
Hi Rusty2,
HL do not offer buy-stop orders which is what you are referring to. I swapped to IG Index, only to discover that they only tend to offer buy-stop orders on the larger or more liquid companies.
That's what I was saying.
Good morning, Graham. Would be most appreciative if you would cast your expert AM eye over Assetco (LON:ASTO) 's results today. Thank you kindly in advance,
Tricky one Dojosan - I've been watching them for a while considering a purchase but held off so far. They have net cash of £40m+ versus a market cap of £100m. The Parmenion stake is valuable. The two of those assets alone are probably worth the market cap.
The River and SVM acquisitions : I was surprised not by the losses, but by the current run rate loss of circa £5m after they've already stripped out £10m+ of annual costs. That business needs to move into b/e quickly and I had expected that to be early 2023 which it seems it won't.
If it drifts back towards 60p I may pick some up for a longer term asset play (ie sum of parts worth more than market cap) but have to say was a little disappointed with the trading update.
I share the same sentiment, David. Having been in it at 59.6p when it just about bowled upwards, I sold my remaining at 73.6p about a month ago. Results were a bit of a shocker, today. Very surprised at how the market has bought back in so fast. Couldn't pick out any big positives besides the wad of cash + annualised cost savings. Agreed, sum of parts > MV. So, there's your margin of safety. Re-entry for me c60p .
Boohoo (LON:BOO) The ‘Growth Share Plan’ RNS this morning is worth a read
It prompted me to tweet ‘If at first you don’t succeed, try, try again” as it’s the 3rd incarnation after the 2019 & 2020 ones were not achieved
Directors look to be both very well paid & incentivised, I’m clearly in the wrong game
My first FD used to say "we are defined by our actions"
Boohoo management not fit for purpose and clearly see it as their gravy train t to ride.
Run a mile from any management that does this on principle.
Its like being 2-0 down after 80 minutes of a match and asking for the match to be restarted 0-0.
Just corporate arseholes really, we can do better as shareholders.
On the other hand, if Boohoo (LON:BOO) management do achieve all the hurdles, I will be quite happy with the share price at £3.95
Are you preferring the board of Boohoo (LON:BOO) to fire management en-masse instead and start with a completely new clean slate?
Compensation needs to be market competitive. Which at the senior exec level includes a share based incentive plan.
Pick your poison.
Agree the issue of incentive plans is not straightforward, but if, as with Boohoo (LON:BOO), they have massively underpformed the requirements of existing plans, then to simply create a new, rebased and potentially very generous, one, does tend to undermine the "incentive" argument
Creo Medical (LON:CREO) got a rapid bump in share price yesterday from 19p-26p. Today are doing a discounted placing back at 20p . Price higher than it was two days ago!
That looks really strange. Opportunistic - but surely they can't initiate a placing so quickly?
As MrC says - it's to keep the lights on
There does seem to be a lot of trade around 20p - so someone is dumping and someone soaking it up.
same as Sosandar (LON:SOS) the other day. You get a rise ahead of the placing - placing then done at a discount and institutions look like they are getting at a discount and can then often place the stock with retail ahead of the placing price. Happens quite a lot.
Hi Wolfspirit, I'll be covering Creo Medical (LON:CREO) in this morning's report.
Regards,
Roland
Bank of Georgia and by extension Georgia Capital look to have produced stellar results .
There will be the usual negative views on geopolitical risk. Bigger risk in UK or USA from any highly leveraged derivative risk lurking like an iceberg (as Liz Truss discovered )
Georgian economy seems to be doing very well and bizarrely a beneficiary of Ukraine war .
Share buybacks continue reducing share count .
Can’t fault it really and if you can rationalise geopolitical factor and offset it by the fact this is actually a growing not declining economy I think it’s a decent place to have an allocation of your portfolio .
I’d split 50/50 between bank of Georgia and Georgia capital if anyone thinking about it .
I'd take a close look at TBC Bank (LON:TBCG) too...Many similarities with Bank of Georgia (of which Georgia Capital (LON:CGEO) is a large shareholder)...So may be better to hold CGEO and TBCG to gain exposure to the inevitable growth prospects in this West-leaning country. I hold shares in all 3 and have done for some time.
NAV of Georgia Capital now 1997p compared to share price of 777p
Superb results again for Bank of Georgia (LON:BGEO) I have to say. Ignore the 300m GEL (circa £100m one off gain) but excluding that EPS now equates to around £7.5 p/s so a PER of less than 4! Has a book value of £30 p/s too.
Dividend even after the rises remains at 8% too which is great. The large share buy back will further enhance EPS too.
Key watch metrics for me though are CET at 14.7% versus reg minimum of 11.6% so comfortable above - I consider +2% prudent so +3.1% is conservative. Cost/income ratio down around 31% which is excellent if you compare against UK banks that are closer to 70% (a reason I also like Osb (LON:OSB) btw, as it too operates around the 30% mark)
Cost of risk at sub 1% is fine.
Happy with macro environment in Georgia with inflation rolling over there too, good strength in GDP growth and tourism accelerating with capital inflows from Asia.
Can't quite remember but Georgia Capital (LON:CGEO) current share prices is probably just the NAV related to its holding in Bank of Georgia (LON:BGEO) and cash so very little attributable to its other businesses in healthcare, pharmacy, utilities. Given the strength of the Georgian economy can only see those being worth more than their existing values on the B/S so NAV should be north of £20 which really does make a £7.7 share price look a bit derisory.
Did look at TBC Bank (LON:TBCG) and agree they look interesting too. Buying those may give me a bit much Georgia exposure though.
And one of the few countries where rugby is the national game!
Completely agree, I have added a comment on their pages. I do have holdings in both Georgia Capital (LON:CGEO) and Bank of Georgia (LON:BGEO) .
The reality is that the geopolitical aspects are working to Georgia's benefit at present, all that skilled immigration from Russia is helping.
Good morning Paul. Your comments on MJGleeson's results (LON:GLE) would be welcome.
My morning smallcap tweet: You have won first prize in a mug punter contest. Collect 100 worthless shares.
Chill Brands (LON:CHLL) Home Reit (LON:HOME) Boohoo (LON:BOO) Libertine Holdings (LON:LIB) Jaywing (LON:JWNG) OnTheMarket (LON:OTMP) Checkit (LON:CKT) t42 IoT Tracking Solutions (LON:TRAC) Creo Medical (LON:CREO), Inspiration Healthcare (LON:IHC)
◄Chill Brands (CHLL)► co's website selling its first 3rd party product, Mad Tasty drinks. Mad Tasty was founded by the lead singer of OneRepublic, Ryan Tedder. Like we give a shit. "We are thrilled to be joining the Chill.com marketplace" whoops a clearly overstimulated President at Mad Tasty. I guess passengers were thrilled to step aboard the Titanic and the Hindenburg, [SP=NA Cap=NA]
◄Home REIT (HOME)► sinking ship hoists For Sale flag. Only 23% of rent has been collected in Q-Nov. Serious challenges in rent collection for Dec and Jan. C.25% (by beds) of properties require at least some level of refurbishment. Considering all strategic options. [SP=NA Cap=NA]
◄booHoo (BOO)► new Growth Share Plan since last one isn't paying out. "The introduction of the Growth Plan will drive long-term sustainable growth" just like the 2019 one, er, didn't. 6% max dilution. Hardles based on SP alone, from 95p. [SP=NA Cap=NA]
◄Libertine (LIB)► signs Term Sheet with Azelio AB to jointly integrate and licence Libertine's HEXAGEN platform for energy storage applications. [SP=NA Cap=NA]
◄Jaywing (JWNG)► warns FY-Mar rev only £22-£22.5m, with adjusted EBITDA ahead of last year due to cost reductions, but below market expectations. "Jaywing has seen a softening of demand over the past two months with certain clients seeking to defer their marketing spend." [SP=NA Cap=NA]
◄OnTheMarket (OTMP)► secondary placing of 3.1m shares at 76p, 2% below mid. [SP=NA Cap=NA]
◄Checkit (CKT)► guides FY-Jan rev up 22%. ARR up 28% vs 20% expectations. So total rev in line? "Non-recurring revenue declined compared to FY22 as planned." [SP=NA Cap=NA]. I hold.
◄t42 IoT Tracking Solutions (TRAC)► guides FY-Dec rev c.$4m. In line? Sales from Openbox, the new distributor in the USA, disappoint. Co "focusing on the need to accelerate upfront cash payments to suppliers to shorten the supply chain period and ensure delivery preference". Or they could just do it. [SP=NA Cap=NA]
◄Creo Medical (CREO)► £25m placing and £5.2m OO at 20p, a 28% discount, to keep the lights on. [SP=28 Cap=51m]
In line: IHC
Love these crisp snapshots with your sometimes pointed colour added. Thanks
MrC's laconic "Like we give a shit" made me smile again this morning. When you've read as many RNSs as he has, you develop a fine instinct for PR guff.
Chill Brands (LON:CHLL) - very spicy Mr Contrarian :)
Annual report from Herald Investment Trust (LON:HRI) where Katie Potts' review of the year of small cap tech investing is never less than interesting. A couple of snippets about the UK caught my eye:
Due to liquidity it has become increasingly challenging to reduce positions at the larger end, and we realise there is now a structural issue exacerbated by MiFID (Markets in Financial Instruments Directive) and other recent regulation. I find that smaller company investing is now a separate world from large company investing with different brokers and different analysts, so companies can no longer seamlessly transition their shareholder register to larger investors as they grow. As successful small caps outperform, they are left with overexposed shareholders, who struggle to sell their holdings and are constrained from providing further capital. It is therefore more difficult for companies to raise additional capital.
And:
The UK has a creative and entrepreneurial spirit, with many interesting investment opportunities. However, we feel the risks of investing in early-stage loss makers in the quoted market has risen. We have experienced situations where we alone have provided follow-on funding, and others where we would have provided funding but found there were insufficient co-investors. We expect to continue to support existing investments, and remain open to new ones, but I expect the UK to diminish as a percentage of the assets of the Company unless there is a political will to redress the regulatory burden and improve liquidity.
https://www.londonstockexchang...
timarr
I hope ShareSoc and Lord Lee are on top of these issues.
Is this an argument for extending a Stocko subscription beyond the UK?
Is this an argument for extending a Stocko subscription beyond the UK?
I am 80% invested ex-UK. There simply isn’t a wide enough choice of high quality and growing businesses to suit my investing style. Value investors are far better provided for. But that tells its own story about our economy.
However, if you’re interested in researching companies beyond the UK, Stocko is not the tool for it, IMO.
What is the tool for it in your opinion? Interested
What is the tool for it in your opinion? Interested
I use a combination of:
Sharepad pro c£800 pa for live prices, level 2 access, financial data and RNS-type US news from MTN - This might be purely personal preference but I find Sharepad’s customisable data presentation, from charts to financial tables, much clearer and, well, customisable! The basic version is half the price and provides most of the functionality without the real time data.
Seeking Alpha £300 pa for semi professional investment analysis of global stocks albeit with a strong US bias - no bad thing. Also comes with the option of news feed via email inbox, almost exclusively US
Morningstar c£150pa. They offer a range of regional subscriptions but the US one gives full global analyst coverage of thousands of well established companies once you work out how to access “foreign” (to a US investor) securities. For a longer term view on companies that focuses on moats instead of short term fluctuations I find it an invaluable resource. My experience over the last five years has been that my Morningstar-denominated wide moat stocks in aggregate have outperformed my narrow moat stocks which in turn have outperformed my no moat stocks. A valuable lesson - although my quality growth investing style might have a bearing on the outcome. For reasoned and unemotional analysis of global stocks with a clearly defined valuation mechanism based on cashflow analysis this is an absolute bargain resource. Start here!
I also have a Refinitiv Eikon feed via an obscure US software company £1500 pa. On top of providing a second - and sometimes different - view of the same financial data this gives me an enhanced news service plus an options price feed. It supplements the above services with coverage of companies in China, Japan, Australia etc. Essentially it’s a “cheap” Bloomberg terminal.
Obviously, how many inputs and how much to spend is a product of one’s portfolio size and the amount of time one has to devote to investing activity. There’s also the question of what one is saving in custody and management fees by taking on the work. This is a key justification for the Eikon terminal but I also write a lot of options and hold a substantial number of Japanese names for which accurate and timely data is hard to come by. But I would not think it remotely cost-effective for someone branching out into a few US companies.
Ultimately, away from UK small caps, where Stocko rules, you are fine with a basic Sharepad account £350 pa plus Morningstar US subscription (global anyway).
I am considering moving from Stocko to Sharepad for the same reason. I am no longer interested in Aims and Microcaps. They have caused me lots of financial damage for very little gain.
Most of my holdings are in Mid to large caps.
Daily coverage in discussion section hardly covers that section though I find occasional articles in regarding these sectors interesting.
BnB,
Thanks, that's useful.
What's the name of the software company that provides your Refinitiv Eikon feed ?
The company is Metastock and the product is XENITH. Interested in what you make of it.
I certainly don’t feel a Bloomberg terminal at 15x the price would be any more valuable. On the other hand, for a pure buy and hold approach, who needs all that live-ish data?
However, I write a A LOT of options, so having options prices with minimum delay is a plus, and comparing them instantly to the latest analyst views - in order to set optimal strike levels - definitely helps.
For US stocks, I use TipRanks free service, lots of information that is not on Stockopedia, can also set up folios. They have a subscription level also. Seeking Alpha is also worth considering but I found TipRanks free one suited me better. It is surprising how much information you can bet free for the US markets.
Not convinced Stockopedia rankings work in the US markets.
I use Stocko for UK, US and CA stocks. I supplement it with Seeking Alpha and used to also use Zacks, but I developed a hate of Zacks over time and will not be renewing it. I do think Stocko is worthwhile for US/CA stocks though and I avoid most of the small-cap/AIM stocks dicussed here with a passion.
Agree, much better selection of companies elsewhere, but as I just don't have time to start analysing US and European markets I get most of this exposure via funds (specifically investment trusts). There are some good quality funds on very wide discounts right now, especially in the private equity space abrdn Private Equity Opportunities Trust (LON:APEO) ICG Enterprise Trust (LON:ICGT) Oakley Capital Investments (LON:OCI) are my top picks. Also very good value in Pershing Square Holdings (LON:PSH) the Bill Ackman vehicle on a 35% discount - rumours he may try to move the listing to the US which would see the discount disappear pretty quickly in my view given its superb performance.
My choice in the private equity section is 3i.
3i has hardly been is such a discount as the present time.
I hold £iii too and has actually been my best performing position recently - but it's effectively a play on Action (two thirds of NAV) so don't really see it as a private equity play (certainly not a well diversified one!).
without doubt IMO
but really it will come down to what exchanges your broker offers - no point in buying a stocko subscription for e.g Australia if your broker doesn't offer ASX/Sydney for example!
Some excellent comments there and chimes with my own view that UK small caps are stuck in a bit of a rut of persistenty low valuations, and difficult to see this changing anytime soon. Increasingly moving my portfolio into larger caps (oil majors and banks have done very well for me but still cheap) and overseas stocks.