Small Cap Value Report (Thu 16 Jan 2020) - RBG, Macro, Ed's webinar, CALL, PMP, QRT, JDG, HEAD, BWNG, KIE, XAR

Good morning, it's Paul here with Thursday's SCVR.
Estimated time of completion is: 3pm - because there are absolutely masses of updates to cover today, so I'll probably do briefer sections on each company to get through them all.
Update at 14:58 - today's report is now finished.
Please see the header for the updates I'm hoping to cover today (i.e. no need to request anything if it's already on the list!).
First, a few thoughts to get you started (I wrote this first bit on Weds evening).
Revolution Bars (LON:RBG) - in which I have a long position.
A post-script to yesterday's detailed coverage. I added this late to yesterday's report, and am copying it here too, so that everyone sees it.
Expansion - once the basics of the business have been sorted out, and debt reduced, then the roll-out of new sites could resume. This presents an opportunity, in that in future this share could re-rate back to being a growth company.
Property deal - some of us baulked at RBG signing new 25 leases (announced today) on 4 of the sites that it is retaining with a landlord called Aprirose. It's just dawned on me that RBG already occupies these sites (hence knows them inside out, and what level of rent is affordable), and RBG is already committed to occupying these sites for another 12 years from now, on the existing 25 year leases signed in 2007. Therefore it is actually only committing to another 13 years on these sites, over and above what it was already committed to. And the rents have come down, albeit described as only by a small amount.
Macro comment - Inflation, unemployment, & interest rates
Inflation - an interesting article in the Telegraph flags up that inflation has fallen to 1.3% for calendar 2019. Clearly that's good news for living standards. I'm trying to track down source data for macro topics, and making diary entries to check it each time it's released in future.
The inflation data comes from the Office for National Statistics (ONS), here's the link in case you also want to bookmark it.
Incidentally, I'm listening to the audiobook of Ed Balls memoirs (don't laugh, it's actually quite good, after a slow start), and he mentioned that one of the things New Labour did was to make the ONS completely independent (as well as the Bank of England). Whereas previously the ONS had been under a Govt Minister. Hence the data it puts out should be reliable, and not subject to tampering by dodgy politicians!
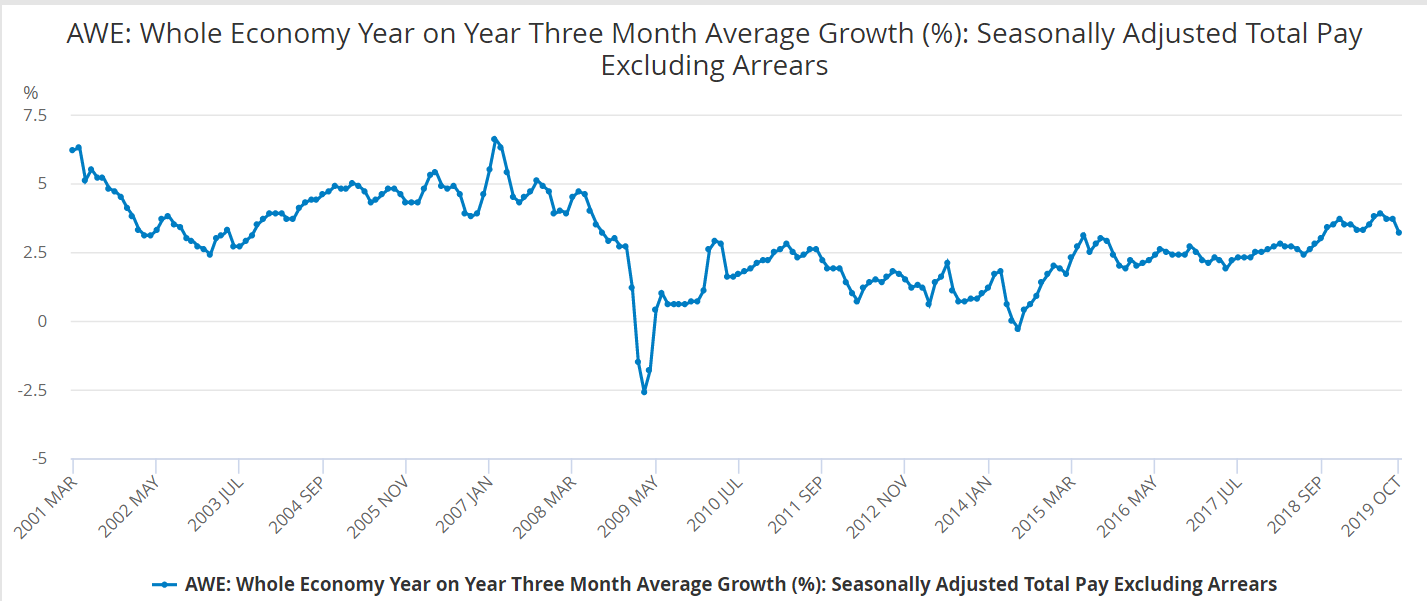
Rising wages - the ONS data on earnings is here (most recent data is Oct 2019).
Annual pay rises peaked at 3.9% in July 2019, and has since slipped back to +3.2% in Oct 2019. However, it's the difference between pay rises, and inflation that matters ("real terms" wage rises), and this is currently running at 3.2% pay rises, less 1.3% inflation = +1.9% real terms increase in average earnings. That's a healthy position, and means that people on average have more money in their pockets. Sooner or later, that tends to find its way into increased consumer spending. Although if consumers are nervous, they do sometimes use extra earnings to pay down debt, rather than consume more.
Overall though, the data suggests that we should be feeling bullish about consumer spending prospects in 2020, and which companies might benefit from this increased spending power.
Rise in Living Wage - the stage seems set for a really large increase in real incomes from April 2020. For over 25's, the Living Wage is set to rise +6.2%, less 1.3% inflation, becomes a massive +4.9% real terms increase in earnings for the lowest paid, from April 2020.
Higher paid workers demand pay rises too, in order to maintain differentials between each rung of the hierarchy. Therefore we can expect to see large upward pressure on wages generally in 2020.
So I think we're on the brink of an explosion in earnings, and consequently consumer spending.
However, that's also likely to put tremendous pressure on businesses large & small where employee costs are a high proportion of total costs. I think supermarkets, and other low margin retailers, are probably going to suffer considerably from higher costs. Competitive pressures mean that many retailers have been unable to pass on price increases to consumers, squeezing their margins, and eventually causing the weakest to withdraw from the market (e.g. look at all the Dept Stores that are closing).
It might get to a point where the Govt has to put a brake on, or pause further increases in Living Wage, if it causes too many companies to go to the wall.
Low unemployment has fallen from a recent peak of 8.5% in late 2011, to only 3.8% today - pretty much full employment, as there will always be a small level of frictional unemployment, as people are fired or made redundant, then get another job a few weeks or months later.
As you can see, this is a historically very favourable position - although the rules are stricter now on who qualifies to be counted as unemployed (i.e. have to be actively seeking work to get JSA)
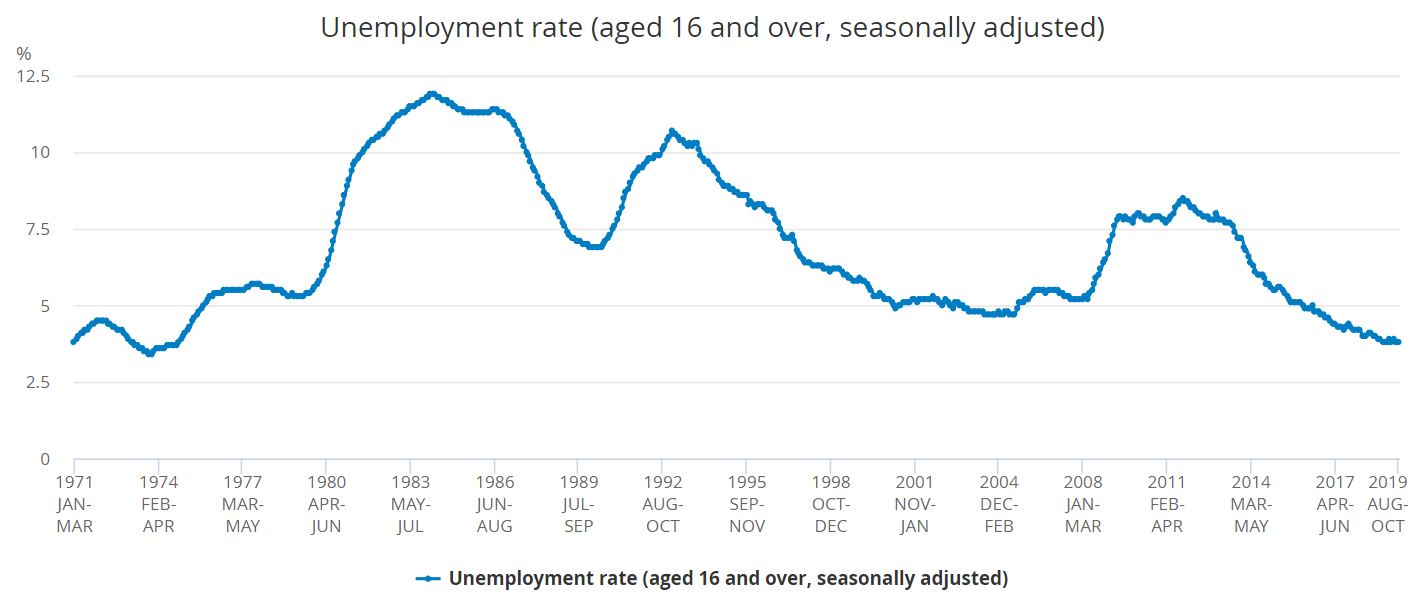
This low level of unemployment means there are labour shortages in some sectors. This adds more pressure on employers, who are forced to increase wages offered, in order to fill vacancies.
Conclusion - put all that lot together, and I think 2020 could well be a crunch year, where many retail and hospitality businesses come under intolerable pressure, and are forced into insolvency. That leaves more market share for the stronger players, and frees up resources for new entrants.
Higher wages are also likely to feed through to higher inflation, as companies are forced to raise their prices to survive. Finding cost savings, and raising productivity will be key themes for employers. Cheap labour is becoming a thing of the past.
Remortgaging - I was stunned to see an advert today in Nat West's window, offering a 5-year fixed rate mortgage at 1.59%, maximum LTV of 60%, for remortgages only, with a £995 fee. This is stunningly cheap, barely above inflation. Given that inflation is probably going to rise due to the factors noted above, then this looks a golden opportunity to remortgage on amazingly good terms.
Therefore, I'm flagging it to readers, as this is probably your best opportunity ever to remortgage on amazingly attractive terms.
With mortgages this cheap (for the lucky people who can come up with 40% deposits), and nearly as cheap for 25% deposits, then there's only one way house prices are likely to go - upwards. Good for shares in housebuilders, and companies in their supply chains.
There is talk of base rates being cut from 0.75% to 0.5%, due to sluggish GDP growth & low inflation under-shooting the 2% target. That seems pretty crazy to me.
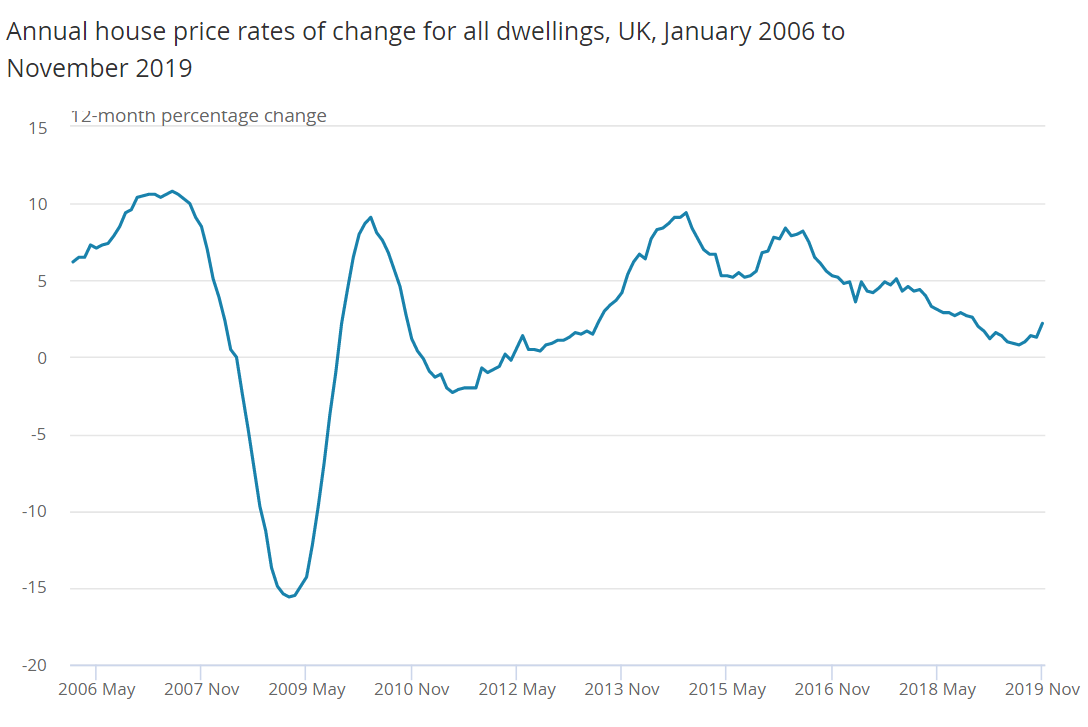
House prices - talking of which, I've just spotted another ONS set of statistics on house prices, here. The most recent figures (Nov 2019) show that average house prices (compiled from HM Land Registry data) grew by 2.2% in the year to Nov 2019. This is up from 1.3% in Oct 2019. Note that this is before the election result, so we could see this trend accelerate after, possibly.
Within the +2.2% average for the UK, England was +1.7%, and the stand out number is Wales +7.8%. Within England, London managed only +0.2%.
Here is the context of house prices since 2006;
Ed's webinar - 2020 stock picks competition
A staggering number of people (over 1,000!) tuned in to Ed's webinar last week.
The topic was Stockopedia data analysis of the 10,765 share picks, of 5 per person from the 2,153 people who entered the 2020 stock picking competition here.
If you missed it, you can watch the webinar video recording here. The competition leaderboard is here. Scanning through the leadersboard, I can see some names that I recognise from regular commenters here at the SCVR, so a shout out to;
- Howard Marx in 4th place, whose portfolio is up 35.4%
- Edward John Canham, in 44th place, whose portfolio is up 15.1%
- peterthegreat in 56th place, up 14.1%
- Andrew Mitchell in 68th place, up 13.4%
- Gostevie in 81st place, up 12.7%
Sorry for anyone I've missed. It's part fun, but part serious, as Ed wanted to analyse the data from a smart crowd (62% of entrants are Stockopedia subscribers), and see if, over a year, we really are smart, and beat the market. Or not.
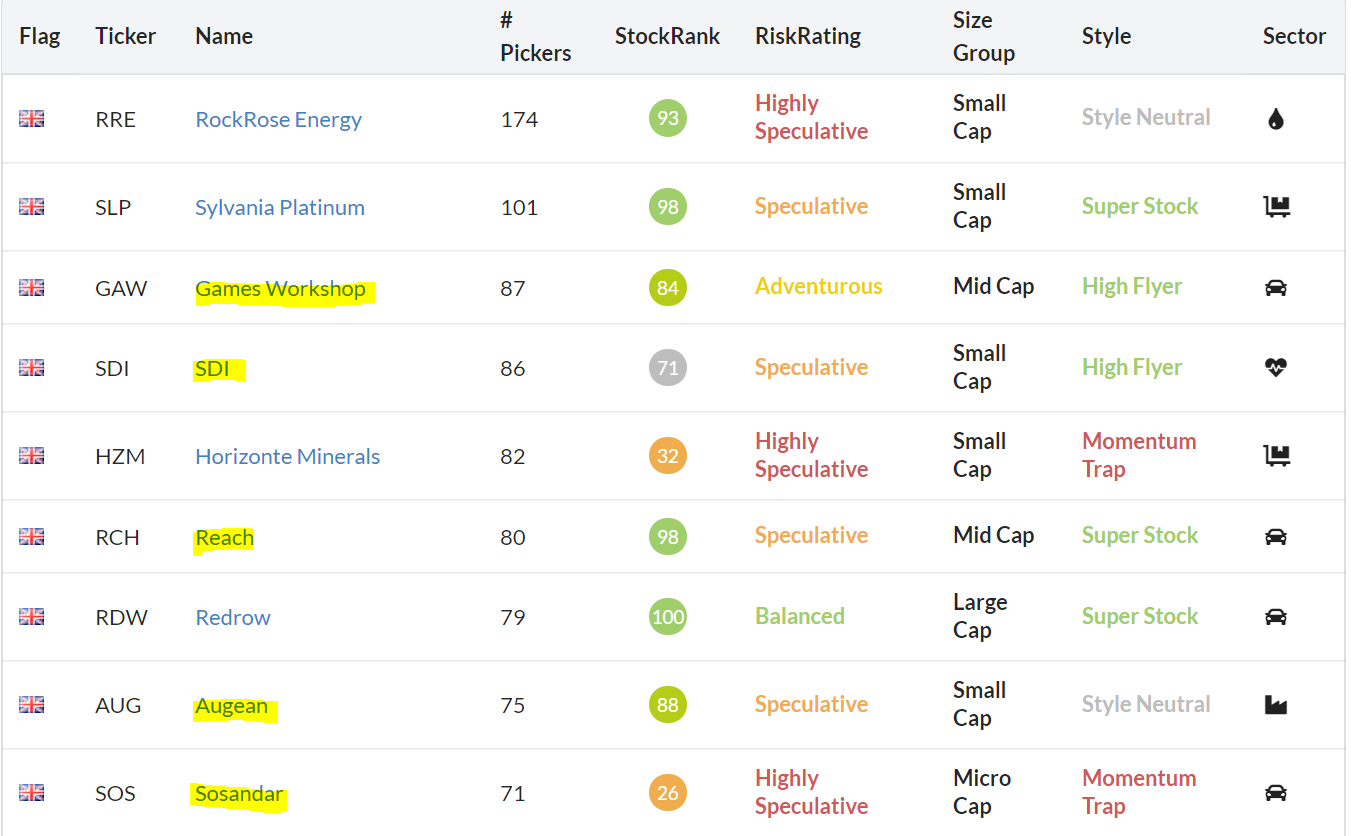
Top picks - it will be interesting to see if the stocks that competition entrants have bunched into turn out to be good or bad. The top pick, RockRose Energy (LON:RRE) has been picked by a staggering 174 entrants (out of 2,153 - 8.1% of everyone in the competition picked this one share). I'm not an expert in resource stocks, but can see that its super-low PER of 2, and cash-backed balance sheet look appealing. Jack Brumby dug a bit deeper, and in this recent article he flags the huge importance of future decommissioning costs, which is the biggest issue to understand.
Here are the top 9 picks, I'm amazed to see Sosandar in there at no.9 with 71 entrants having picked it. I didn't realise it was that popular. I've highlighted below the companies that I'm familiar with.
The stock selections include a lot of shares from USA.
The only problem with share competitions, is that there's no downside risk, and only one winner, so many of us just tend to pick highly speculative shares that might shoot the lights out, but probably won't!
On quiet news days, I might dip into the stock picks list, and do some research on things I'm not familiar with.
OK, on to today's trading updates - lots of them!
Cloudcall (LON:CALL)
Share price: 99.5p (up 1.5%, at 08:13)
No. shares: 38.7m
Market cap: £38.5m
(at the time of writing, I hold a long position in this share)
CloudCall (AIM: CALL), the integrated communications company that provides communications and contact centre software that integrates with Customer Relationship Management ("CRM") platforms, announces the following trading update for the year ended 31 December 2019.
This is a slight miss on revenues, because the forecast was for £11.7m, so a £0.3m shortfall, or just under 3%. I can live with that, because it's still a very good (purely organic) growth rate, up 30% on 2018.
The Group is pleased to confirm that revenues, cash and losses before tax are all expected to be broadly in-line with market expectations, subject to year-end financial close and audit procedures.
Run rate at year end for revenues is over £13m
Recurring & repeating revenues are 89% of the total (and on a high gross margin)
Customer churn rate is low
Put that lot together, and it's a compelling business model, or will be, once growth has passed the tipping point to break into long-awaited profits. That's not happened yet because the company repeatedly increases its cost base, to drive growth. There are two ways to look at that;
- Exasperation at repeated failure to achieve breakeven, let alone profits, or
- Recognition that the growth opportunity is far more important than short-term profitability
Very much a glass half full, or half empty stock then. I'm very much in the half full camp, because I'm more interested in the company maximising the long-term value of the company, than chasing short term profitability and missing a bigger opportunity due to under-funding growth.
Growth in the USA is a stand out positive;
US revenue up 55% year-on-year, with US revenue now approximately 40% of total Group revenue
I reckon a takeover bid from the USA is a possible outcome here. They value tech growth companies so much higher over there, so there could be Americans looking at this and regarding it as cheap. This is evidenced by there already being 2 American institutional investors with disclosable stakes (e.g. Kinderhook 2 LP has 12.1%).
The two standouts for the year are the quantum increase in interest from enterprise companies and the over-50% growth we delivered in the US.
It is worth noting that the US is now responsible for approximately 40% of our total revenue and with nearly half of the total funds raised in the recent placing coming from US investors, I have little doubt there is a huge, largely untapped, opportunity for CloudCall in the US and this is a key focus of our sales and marketing expansion.
Cash - is fine now, as a big placing of £11.3m was done in Oct 2019. It had £11.4m in cash, and an unused £2m debt facility at year end.
Enterprise customers - a key target area for growth is attracting much larger deals. Positive commentary is given on this.
Bullhorn relationship - very important, and is deepening. Improved sales pipeline due to directly incentivising Bullhorn staff to sell the CloudCall add on.
Asia expansion is now underway - important because some larger customers or potential customers want this.
My opinion - I understand & sympathise with the bearish view on this share (repeated failure to meet targets, repeated fundraisings, etc), but that's the past, and it should be the future that we concentrate on. After all, that's how shares are valued. Past mistakes are soon forgiven once a company starts delivering better results.
My view is firmly bullish on CloudCall. The downside risk has now largely gone, due to the big recent fundraising - driven by American investors who want the company to get on with it, and go for the growth opportunity, instead of penny pinching. For what it's worth, that's my view also.
Upside potential looks good, particularly if more enterprise customers sign up. The key thing is that the product is superb - I've been using it for years, and it works superbly. The recruitment sector niche that CALL targets can achieve excellent performance improvements by using CloudCall. There are many other sectors where this product would also add value. Plus it's moving towards being a global service.
Investors here have had to be very patient, but I reckon this share could be a lot more valuable in say 5 years' time, hence I'm happy to keep mine tucked away for the long-term.
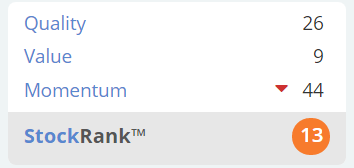
Definitely not a share for value investors though. Stockopedia reminds us of the high risk of failure with this type of share, with a dismal StockRank. I like this, as it's a sense check. Investors in CALL have the be very sure that this is going to work, to overcome the warning flag of such a low StockRank;
I've moved this one up the priority list, because it's today's largest % faller -
N Brown (LON:BWNG)
Share price: 106.4p (down 25% today, at 09:41)
No. shares: 285.2m
Market cap: £303.5m
Trading Statement (profit warning)
N Brown Group Plc today announces the following trading update covering the 18 week period to 4 January 2020.
This update relates to FY 02/2020. The year end date changes slightly each year, as it accounts for 52 or 53 week periods, instead of 12 monthly periods.
This is an unusual retailer. It seems to have closed nearly all its shops (only £6.9m revenues last year), and says today that 87% of product revenue is now online.
The other unusual thing, is that a large proportion of the business is financial services. I think this is high cost instalment credit for customers - if any readers know more about this part of the business, then please post about it in the comments. Revenue from financial services last year FY 02/2019 was £298.6m, almost 33% of total revenues. That obviously brings with it regulatory and balance sheet risk, so I'm not very keen on that aspect of things.
Profit warning - top marks here for clear disclosure (well done MHP Communications!), in particular these 2 key boxes are ticked;
1. Quantifying the revised profit guidance (instead of the bad way of reporting, using ambiguous wording, like materially below, significantly below, etc);
... we now expect FY20 adjusted profit before tax to be in the range of £70m to £72m 5
2. Footnote showing previous guidance, enabling us to instantly see the extent of the profit shortfall vs expectations;
5 Current range of consensus FY20 adjusted profit before tax forecasts is £78.0m to £84.1m
If we take the mid-point of each range, this gets us to;
Old profit guidance: c. £81m
New profit guidance: c.£71m
That's a £10m profits miss, or 12%. That's clearly not good, happening so late in the year, but operational gearing can have that effect.
Reasons given -
- Predominantly due to a lower than expected benefit from the IFRS9 non-cash provision estimate
- combined with lower Financial Services revenue and
- a highly promotional market
What the hell is IFRS9? I hear you cry. Well that was what I cried anyway. Googling it provides the answer, that it concerns rules on how to measure financial assets & liabilities. This seems to relate to BWNG's bad debt provisions against its consumer debtor book.
This extract contains some important points, and seems to be saying that tightening up on its consumer credit offerings is likely to hurt profits. I'm assuming this is driven by regulatory pressure?
Improved credit quality will feed into a reduced IFRS9 bad debt provision; our IFRS9 bad debt provision ratio declined to 11.9% as at H1FY20. This compares with a 17.9% provision when IFRS9 was first introduced. We believe that while further impairment improvement can be expected, the pace of improvement will slow.
In addition, changes to our policies and procedures, specifically the embedding of new measures around affordability and the introduction of new rules concerning credit limits - effective March and December 2019 - and persistent debt, which is due to take effect in March 2020 and December 2020, will have a significant influence on the size and shape of our debtor book.
The Group continues to assess its strategies to mitigate the impact of these changes, including the phased introduction of new financial products and further reductions in its operating cost base.
I've split it into two sections above. The first one sounds positive to me. Surely a reduced bad debt provision is good news? I don't fully understand all of this, but the last section talks about looking for ways to mitigate the impact, which clearly means that the impact of these changes is bad for profits.
Revised guidance for FY 02/2020 is given in a very detailed table - again, excellent transparency. This should enable broker research teams to come up with accurate models.
One stand out item, is that group operating costs are forecast to reduce by approximately -6.5% (mid point of the range given), revised from -4.5%. This demonstrates the advantages of selling online - namely that marketing spending is a major outlay, and can be dialled up & down to suit the circumstances. In this way, profit can be protected (albeit at the expense of growth). That cost flexibility should make successful online retailers far more resilient in a downturn, than traditional retailers which are being killed by fixed, high cost occupancy costs (rent & rates, but also cost of minimum staffing levels).
Outlook - this sounds concerning, as it seems to be saying that the lucrative financial services side of things is going to shrink;
We are making good progress with our ongoing strategic review and look forward to providing further details at our full year results in April. Our work so far has highlighted the need to have a tighter brand portfolio, a sharper focus on product and a cost base appropriate for delivering sustainable digital growth.
At the same time, we will continue to proactively address the accelerating and cumulative external factors which are anticipated to reduce the size of our Financial Services business over the next two years.
These will significantly influence the way we will operate our Financial Services business and we are taking proactive measures to ensure that the change is managed appropriately. This is in line with our strategy of becoming a digitally focused, retail-led business.
Our expectations remain that the retail market will continue to be challenging and promotional, but we are focused on our clear strategy of delivering profitable digital growth."
My opinion - I've read enough to completely put me off delving any deeper into this.
So it's not something I would touch - too complicated, and it sounds like there are significant problems ahead.
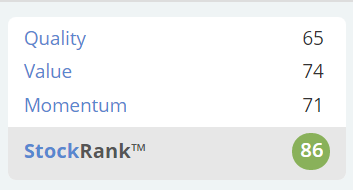
The StockRank is high, at 86, but I imagine that is likely to fall, as reduced broker forecasts feed through the system after today's update.
Portmeirion (LON:PMP)
Share price: 805p (unchanged, at 11:23)
No. shares: 11.11m
Market cap: £89.4m
Portmeirion Group, the designer, manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Wax Lyrical, Nambé and Pimpernel brands...
I've traditionally liked this group, but performance of late has been rather lacklustre, which has made me wonder if it's perhaps not as good as I thought?
... pleased to announce that it expects revenue and profit before tax for the year to 31 December 2019 to be in line with revised market expectations.
It's an in line update today, but look how much broker forecasts have been reduced;
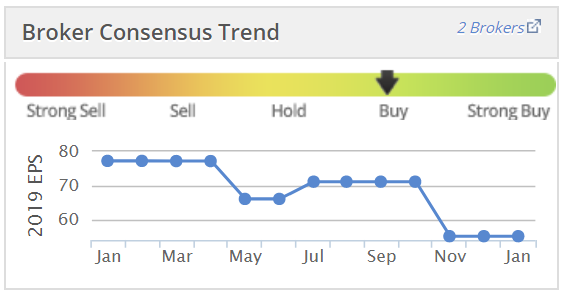
Or to put it another way, the group has given up all the profit growth from 2013 to 2018, despite having acquired other profitable businesses during that time. This suggests to me that there might be some deeper underlying problem here.
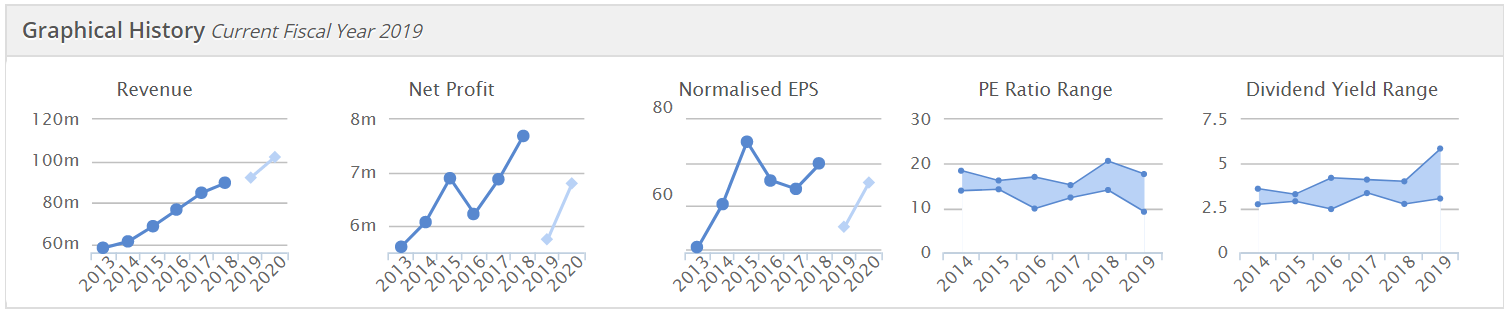
At the moment, brokers are expecting profit to partially recover in 2020, but how much reliance can we place on that, given that 2019 has been so disappointing? The key question then, is whether 2019 was a blip, or if profit is now trending down?
Other points in today's update;
- Revenues up 3% to at least £92m, but driven by an acquisition (Nambe)
- LFL sales declined 5% - driven by poor sales of Botanic Garden range
- South Korea is the problem market (which is PMP's 3rd largest market, after UK & USA) - making good progress to stabilise this market
- Pleased with other markets & subsidiaries
- UK grew 5% despite "tough economic backdrop"
- Online sales growing (I like this bit);
Our migration towards online continues with total online sales in our core UK and US markets growing by 17% year on year. We now estimate that 30% of our total UK/US sales are made through online channels reflecting the strong progress we have made in the transition to online. Sales from our own ecommerce platforms grew 16% year on year and are expected to continue to grow strongly in 2020. Online sales remain a key area of strategic focus for the Group.
A lot of PMP's products are ornamental, collectable items of pottery, or consumable (candles). Therefore knowing who your customer is, and having the ability to contact them directly through digital marketing, cutting out resellers, has obvious attractions - much higher profit margins, targeted special offers, stimulating demand by suggesting items which match what customers have previously bought, building brand loyalty, promoting new product ranges, etc.
Outlook - the way I read the below excerpt, it seems to be guiding us towards continued soft profitability in 2020, and hoped-for better profitability longer term;
We are confident in our strategic plan and the long term opportunities to grow our business. In 2020, we intend to further increase investment behind key strategic areas such as driving online growth and brand marketing including campaigns and product launches to celebrate the 250th anniversary of Spode. The integration of the Nambé business continues to go well and we look forward to seeing the anticipated benefit in future sales growth. "
My opinion - I think the long-term picture looks good, particularly with online. However, I don't see any rush to buy now, because of the hesitant outlook for 2020. It could have another profit warning in it for 2020, perhaps?
On the upside, it pays a decent divi of 4.8%, and there's always the takeover potential for a more highly rated group (e.g. from USA) to buy this in order to bolt on growth at a modest outlay (the forward PER is only 12.3 - although maybe that's because the uplift in profit for 2020 may not happen?)
Overall, revenues are growing, but profit isn't, therefore I'll probably just keep it on my watchlist for now.
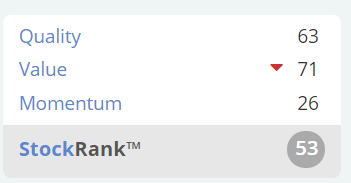
Stockopedia's computers are sitting on the fence next to me!
Brief sections now, due to time constraints.
Quarto Inc (LON:QRT) - this is an illustrated books publisher. It changed broker, to Finncap, in Nov 2019, which can often be a precursor to a fundraising.
Today Quarto announces a rather interesting fundraising, in that it's just an open offer (no placing element). i.e. only existing shareholders are participating in the fundraising. This is excellent, as nobody can complain about being diluted. It's just like a rights issue, except that there's no facility to buy or sell entitlements to new shares. With an open offer, you either take up your entitlement, with the ability to apply for excess if you wish, or just let it lapse. Or partially take it up.
Open offer entitlements for existing shareholders are 1 new share for each 1 existing share. The market cap is tiny, only £15m, I hadn't realised it had fallen that low.
Divis stopped in 2016, which is a clear sign of financial stretch whenever it happens.
I've never liked the balance sheet here, so it's a good thing that it's being strengthened with fresh equity.
Price is 68p, about 10% discount to the 75p prevailing price beforehand - which is fine - it needs a discount to nudge people to take up the open offer. Actually, the price could have been set lower, to provide more of an incentive for people to take it up.
Underwriting - 2 existing shareholder groups are underwriting the whole open offer. So it's going to happen, it's just a question of which shareholders take up the new shares. That seems a very fair way of doing things - i.e. giving smaller shareholders the option to put in more money, but without any consequences if they choose not to. That's far preferable to a deeply discounted placing, as happened yesterday with INCE (LON:INCE) .
Clearly this is happening at the insistence of the bank;
The Group has also been in discussions with its banking syndicate to extend the final repayment date of its existing facilities agreement and to extend certain of its covenants. Such amendments would be conditional on completion of the Open Offer. Furthermore, the Group intends to use the net proceeds of the Open Offer to reduce the Group's existing bank debt.
My opinion - I think small shareholders in this have been very lucky!
Large shareholders have bailed you out, basically. This could have very easily been a wipe-out.
Trouble is, it only partially fixes the problem. Net debt was last reported at $65.0m at 30 June 2019. The $16.7m being raised (after costs) in this open offer, only reduces bank debt by about a quarter, quite appropriate for Quarto! My worry is that, if the bank has cold feet, then it might want to ultimately pull out altogether. Therefore this could be the start of a series of fundraisings, maybe? For that reason, personally I wouldn't take up my open offer shares if I held, and would ditch my existing holding in the market, and count it as a lucky escape.
Judges Scientific (LON:JDG) - what an amazing share this has turned out to be! I remember attending a Mello presentation given by David Cicurel many years ago, when this share was about £1, and we all agreed what a clever & charming (and very amusing) chap he was. Little did we know it would turn out to be a 50-bagger!
It's proof that a buy & build strategy can work, if it's done in a disciplined way - buying good, niche businesses cheaply (e.g. when owners want to retire), and using cashflows from acquisitions to pay for themselves over a few years.
Today it says 2019 EPS will be slightly ahead of market expectations (upwardly revised in Sept 2019). Good demand, and favourable exchange rates, are mentioned.
I'm neutral on this one. The market cap is not huge at £309m, so if more shrewd acquisitions are bolted on, then who knows where it could end up? That said, it must be tempting to bank some profits after such a stunning rise?
Headlam (LON:HEAD) - floorcoverings distributor - 2019 results will be marginally ahead of market expectations but down on 2018. Divi maintained. Cautious outlook for 2020, and £10m more capex in 2020 to finish new distribution centre.
Footnote included - bravo Buchanan Communications!
¹Company-compiled consensus market expectations for 2019 revenue and underlying² profit before tax are £705.5 million and £39.3 million respectively (mean), with the expectation for underlying² profit before tax given prior to the adjustments due to the adoption of IFRS 16 'Leases' accounting standard which came into effect on 1 January 2019. The Company currently anticipates, subject to completion of the 2019 audit, that underlying² profit before tax will be impacted by a reduction of £0.8 million due to the adoption of IFRS 16 and that 2020 underlying² profit before tax will be impacted similarly.
My view - a nice company, and looks good value, even after strong rise in the last year. Yield of nearly 5% - worth a closer look.
Kier (LON:KIE) - in line trading update today, from this embattled contracting business.
There's no new bad news.
I have to file this in the "too difficult" tray. I've covered the detail before here on 17 June 2019. There are so many moving parts, and uncertainties, that it's impossible for me to value this company.
Although it looks dirt cheap, and the balance sheet isn't too bad, the potential for a 100% loss scares me off. Why risk my capital on something that could go under if any more serious problems emerge?
Xaar (LON:XAR) - this previous tech star, making innovative print heads, looks a busted flush these days. I can't see anything in today's update to change that view.
It's got cash in the bank though. Doesn't interest me.
That's all I can manage for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Thanks for a great report. Always love your macro commentary. On the wages front there is a short article on Yahoo on Haldane’s comments on productivity or the lack thereof and how higher wages can actually leader to higher productivity.
https://money.yahoo.com/econom...
Re N Brown (LON:BWNG) Paul said
Not in any great detail, but I think you are essentially correct, as far as I understand it there are essentially like a digital version of the old catalogue operators (anyone remember Great Universal Stores? Were it not for their payment plans I would have probably been turning up for work naked at the start of my career!)I cannot now find the reference, but somewhere in the past 2 or 3 years I commented on the SCVR about their (back to N Brown) cunning plan to reduce their "overdue debt" levels by increasing everyone's re-payment period.
I'm sure I made some very restrained comment about this not being especially prudent. (Or just maybe I used stronger language?)
Without looking in too much detail it reads as though they are being forced to lend more responsibly, which may include reversing some their extended payment periods.
I started writing all of that with very negative frame of mind, but I'm now not so sure.
Their sales growth rates actually look pretty good and they may well be more impressive than apparent if they are now increasingly shipping goods to people that can actually pay for them.
I'm quite time poor just at the moment (and allowing myself to spend too much time on distractions) otherwise I might be tempted to have a more detailed look. There's a lot of "baggage" so it wouldn't necessarily be straightforward research, but I think this could develop into an interesting proposition.
I have added it to my watchlist, but the complexity may mean I never get around to having a proper look.
I will probably eject it from my watchlist in a couple years time with either a smug - "yep I was right not to put any effort in there" or a "hey-ho - I've agreed not to beat myself up about the ones that get away".
Would like to add my belated thanks to Paul for another amazing effort. I find the mix of macro and company analysis extremely educational. It's also a reminder of how clueless I am when it comes to investment compared to the expertise here !!!!!! Being a teacher, every day is a school day in more ways than one.
It's crazy to think these reports used to be free, and sit outside the Stockopedia subscription! What a quality SCVR. Many thanks Paul.
many thanks for an excellent report.I am new to your daily analysis and I am finding it a valuable source of market information as well a great learning tool for me.Wonderful resource Thanks
Re Resources which I know is a bit shunned in the SVCR so mea culpa in advance
, oil and gas was one of the biggest laggards in 2019 and was Yin to the Yang of Alternative Energy which was the brightest star in 2019 .. the Thunbeg effect and a souring of sentiment towards the dirty oilers?? (counter-intuitively crude was up 21% on the year so not a demand/supply issue)
In a Dogs of the Dow fashion, some of the oilers should play catch up in 2020 not least Royal Dutch Shell (LON:RDSB) and BP (LON:BP.)
Many of the oilers are off to a good 2020 not just £RRE (see plot below) .... John Wood (LON:WG.) is popping today on favourable guidance (and short covering) so Services should catch a bid too
That said 2020 so far shows Alternative Energy still to be a star in its own galaxy ..up 13% so far in 2020 some of the performances below which are ......well, stellar
Ilika (LON:IKA) up 60% , ITM Power (LON:ITM) up 50% etc
Well said, Beermonster and FREng . I was soon voting up this morning, even before the companies review.
I notice M&S are on about closing a food store in Spalding, Lincolnshire. I thought that their idea was to close their big in town stores and open up these smaller food stores ? When I have been in this Spalding store, it always seems busy. They closed their Skegness & Grantham in town stores a long while ago, then opened food stores in those locations further out of town. Perhaps they are going more on line now than what I thought.
Like many others here probably, I’m very keen to know the date for Sosander’s trading update.Eventually managed to get a sort of answer but agreed not to say how I found out.
It seems very likely to be tomorrow.
Maybe Paul if you happen to see this, you might be able to confirm for sure. I was asked not to disclose how I got the date, but can’t really see what the problem is, as Companies often give a date for post Christmas trading updates.
Agree btw with other comments about the exceptional quality, even by Paul’s incredible standards, of his recent updates, including today. But also fear that it will be impossible to keep up this level as it would be so exhausting to do do, so please don’t overdo it.
Thanks Ken re Sosandar (LON:SOS) - I'll set my alarm clock and keep fingers crossed.
Paul
Today's report again went above and beyond anything subscribers have the right to expect. Please be careful to keep your effort here to the companies that interest you and the amount of analysis that you enjoy. We would hate to lose you!
Best wishes and thanks
Martyn
What a fantastic report once again. The coverage here is second to none.
Macro musings; Coverage of a large number of updates; Review of the competition; Combined with exceptional contribution and debate from/with the subscribers.
Brilliant - Thank you to Paul & Graham and everyone else involved.
With N Brown (LON:BWNG), I do think there is the case that the market is undervaluing some brands like Simply Be/Jacamo which have niche positions in the larger size markets which are not that well contested.
It is surprising how much money is made on the finance side: finance revenues: £298.6m. That appears to be more than Next, (which has around £1bn average debtor balances earning around £250m before expenses) - is that correct?
It seems to me that something like JD Williams is a bit of a marginal business on its own but is reliant on the financial side to become profitable. That might also be the case for the other clothes businesses but I sense their figures will be more in line with other smaller retailers.
Don't quite fancy the price at the moment but at lower levels I would. The plus-size brands seem to be a good fit for Boohoo who could operate them separately but improve their logistics.
Snoo,
I bought into N Brown (LON:BWNG) focus on the underserved niches story.....when N Brown (LON:BWNG) was at 320p in 2015 (having come down from over 500p in 2014!) and the business was all about getting 'Fit for the Future' ie digital, focusing on 3 brands: Simply Be, JD Williams and Jacamo whilst improving the Quality of its Financial Services all coming from a heritage of Catalogue - an advantage in a new digital world. I still think at that time they had a shot.
But fashion is brutal and, expensive learning later, the other brands have proven so weak as to be worthless and the underserved market spaces easy to copy. All retailers now seem to have 'Curve' Petite and Senior sub ranges and everyone is digitally savvy ! Only Simply Be seems to push on but I think is not needed by BooHoo and is about to be run down by it
The tightening of the Financial services regulatory regime has restricted their ability to make money there and if there is a recession even for a short period then I think impairments will rocket. Clothing debt is last on the list of priorities for people to pay if cash gets short.
The continued payment of high divis until last year has weakened the balance sheet. Net from being a cheerleader disputing wiser heads on this site, and waiting patiently for a turnaround, I have now given up on it and and sold out. Good luck! Maybe now is the moment.
Capital Drilling (LON:CAPD) (I hold and intend to continue to do so) A request for comments from readers, rather than Paul (given area and volume of other announcements today!). CAPD is a drilling contractor who get most of their revenue operating rigs for gold miners. So a real picks and shovels business, rather than a resource company. SR of 98.
TU today is bang in the middle of consensus forecasts at revenue of $115, and to me reads well. Good growth, with EPS Growth of 29%, a PE of 11 and therefore a PEG ratio of less than 0.5.
Also interesting to see that they seem to have addressed one of the risks that Roland highlighted in his recent review for the SIF portfolio, in that they have now signed Barrick Gold in a new contract following their purchase of a previous customer, Acacia. I'm also reassured by the continued strength in the gold price, meaning that miners should be well incentivised to continue exploring.
The market completely disagrees, and this is down ~7-9%. I guess expectations were for revenue at top of forecasts, or for a beat. Any other holders, watchers or commentators have an opinion on this one?
Capital Drilling (LON:CAPD) drop is due to a major new contract slipping
‘Capital Drilling’s first mining services contract at Allied Gold’s Bonikro Gold Mine (Côte d’Ivoire) as announced in October 2019:
- Contracted to provide a full range of mining services including drill and blast; load and haul; grade control; and dewatering;
- Contract to transition to comprehensive Schedule of Rates Contract (subject to agreement of rates), on confirmation of long-term mine plan, with an interim mine plan to December 2020 now in the process of implementation;
- Delivery of long-term mine plan now scheduled for Q3 2020, current services contract to be extended ahead of delivery of final plan”
Thanks rhomboid - seems they've shaved $10-15m off 2020 estimates from that contract, with the market discounting the price accordingly.
I don't want to be a killjoy, but that stocko competition should come with a wealth warning. The thought of newbies looking at the list for ideas makes me very uneasy. That's the kind of mistake I would have made 30 years ago when I first started.
To win that competition, you need all-or-nothing type stocks that will return +200% or -100%. In many ways, it's the opposite of what you should do in real life where steadily compounding gains and avoiding big losses will win you the prize (i'm not just talking mathematics, I'm talking about real life behavioural finance too).
Overall, Stocko does a great job of steering people towards succcessful type stocks e.g. in showing the history and research that supports low volatility investing as one successful strategy. The competiton seems to do the opposite.
Having said that, the most popular stock RockRose Energy (LON:RRE) has multi-bagged in to being one of my largest current holdings, so there appears to be a glaring inconsistency in my thinking. My take on that is that while RRE may be flagged as "Highly Speculative" it is in fact lower risk than that. Consequently, while I expect it to do well, I doubt that it will be part of the winning portfolio in that competition.
I guess it all depends upon one's definition of 'risk.' there's a whole literature on the topic
Cmpeckham
I would agree very much with your sentiments. That is my reservation about the competition:
Personally I see it as a bit of fun.
I entered but I don’t think I would use the list as a source of ideas. That said I look forward to any analysis Paul does of some the stocks.
Portmeirion (LON:PMP)
Reassuring update today from Portmeirion (one of my major laggards this share is) - the quick collapse in their growth story and decent into lower profits has been a bit of a disaster as i thought this looked a reasonably safe company.
Anyway the past in behind them and they seem confident that they "are on the way back" - nice comments ref online sales - not sure how much they are simply taking away from their non online sales in that regard though.
Our migration towards online continues with total online sales in our core UK and US markets growing by 17% year on year. We now estimate that 30% of our total UK/US sales are made through online channels reflecting the strong progress we have made in the transition to online.
shareprice is is now up 20% plus from the recent lows so anyone doing some bottom fishing may have missed the boat - the share looks about the right price where it is being honest - im happy to hold but i don't think i would be investing (other than bottom fishing) new funds until they get back to proven sustainable growth - perhaps that ship has sailed permanently who knows.
well at least it passes the Geraldine Weiss Lite Dividend Screen test so perhaps that's a good sign as geraldine seems to be on a bit of a tear at present
oh dear on the history it says the following Exited 2020-01-16- does that mean geraldine is saying sell today - doh! if that is the case.
Really good that more small caps are stating consensus expectations in their trading updates, including Headlam (LON:HEAD) for example this morning. I am sure Paul and Graham can take a lot of the credit for this as Paul in particular has been campaigning for this for ages. There is more campaigning to do, though, as Cello Health (LON:CLL) for example refers to consensus figures in their update this morning but does not state what the figures are.
Cloudcall (LON:CALL)
davidjhill
Looks to me like cash burn in 2nd half was also down to around £1m.
I came up with a total of £1.5 mill cash burn - note this is potentially slightly flattering in that they banked a 600k r&d refund in the period - although i am guessing the r&d freebie is likely to repeat.
Note i haven't factored in or adjusted anything for placing costs (i used 12.08 mill raised as being cash in - so knocking £0.5 mill of cash burn is probably reasonable as i am guessing the one of costs in that regard will possibly be that high - that being the case your £1 m may be more accurate than my calc.
this cash burn was slightly better than i expected and is positive if it suggests there isn't an over excess amount of intangible capitalisation going on that would flatter the (loss)/profit situation.
They are in a very strong position in this regard - in some respects its what use do they put all the money too? I guess the sensible thing is to leave £6-7 mill + safety net so they prove to markets they won't be (again) "forced" into raising funds when the shareprice is week. so it's all about the topline growth - i would be most interested in 2021 sales projections - can they get to £20 mill that year - i would certainly think the run rate at ye 31/12/2021 should be £20 + mill minimum.
My one worry here is the question if their product is unique and cheap enough to scale with sufficient margins. Could it be that practicably speaking bullhorn are pimping them to maximise their cut whilst ensuring that Cloudcall are selling everything at cost price - lets be frank the product has been around long enough know that one would hope the margin explosion would be imminent on the extra sales - the reality is that the company is saying a higher cut is now going to bullhorn.
It's a tricky binary bet this one as to which way it will go ref future shareholder gains - i would say have turned more positive now than at any time since i half previously despite my niggling concerns - just not positive enough to splash the cash. Perhaps the first trading update of 2020 will be the time when things start to look ultra rosy again.
rmillaree
I've been going back through a few of the older announcements and I don't think they are necessarily paying Bullhorn more, just that it was restructured such that the sales team were more directly incentivised. Couldn't find any details mind - that was reading between the lines so if you saw something specific would be good to see.
A lot of expenditure has been going into development and scale. They are also referencing spend on getting AsiaPac ready. So I wouldn't necessarily say they are selling at cost (though I understand why you put it like that) more that they are investing in scale. This is fine for me as long as profits then ramp up significantly after the investment phase.
I'd like to see the impacts of the strategy in a presentation but haven't found one yet so still trying to get me head around the ultimate profit trajectory.
Cloudcall (LON:CALL)
I've been going back through a few of the older announcements and I don't think they are necessarily paying Bullhorn more, just that it was restructured such that the sales team were more directly incentivised.
It was certainly a presumption of mine when they said t"he sales team were more directly incentivised." - that i i took this to be extra costs - it may very well not be though if you think otherwise - i presume alot of stuff and plenty of it ain't correct.
One plus point is it appears they have excellent visibility with regard to 2020 sales if the following broker comment is to be believed. I don;t know how long it takes for orders to turn to revenues (i am guessing lead time is getting longer) - but if they only need £1mill booked contracts to hit 2020 goals there is room to surprise on the upside - with this company that's a confilct of what seems logical ideas in that the company never surprises on the upside.
I couldn't see any mention of 2020 revenues yet unfortunately
Broker comment from random third party website so don;t rely on info below being correct
Based on management comments, our analysis on page 2 suggests that CloudCall may already have good visibility on >90% of our £15m sales forecast for 2020 (+30% yoy). This takes into account the 2019 exit run-rate of £13m and adds £1m in contribution from already signed deals. The resultant ~£14m in sales implies only £1m in new sales are needed to deliver our £15m expectation. Such good visibility at this early stage in the year is, in our view, highly encouraging and underpins our estimates.
Yes - but the fact that, as investors, we are unclear on something as fundamental as margins is a bit of a worry as it suggests the company has been vague, leading us to form different conclusions from the same statement.
However, I'm with you on the potential to actually exceed expectations for a change in 2020. My calc is £1.4m to £1.5m of additional revenue required to hit targets and that looks very achievable to me.
Hi Paul, Really excellent reports last few days, really appreciate all the effort, for me it’s a reason to subscribe in itself, now don’t you and Graham go getting any ideas. On Ed’s risk list I’m sure.
And Mr Contrarian , same gratitude to you, always essential reading.
Thumbs vertical
I fully endorse Paul's pleas for announcements to spell out the market expectations against which they are in line or not and his praise for those that do. One of the best this morning from John Wood (LON:WG.) :
Adjusted EBITDA of $850m to $860m and operating profit before exceptionals of $410m to $420m, in line with current market expectations4
4. Company compiled, publicly available consensus comprises 12 analysts who have published estimates since our November 2019 trading update and includes forecasts that reflect both changes to our reporting metrics and the impact of IFRS 16: Bank of America Merrill Lynch, Barclays, Berenberg, Citigroup, Exane BNP Paribas, Goldman Sachs, Investec, Jefferies, JP Morgan Cazenove, Morgan Stanley, Numis and UBS.
Consensus 2019 Adjusted EBITDA, including the impact of IFRS 16 is $864m (Range: $850m-$879m), Consensus Operating Profit (pre-exceptional items) is $418m (Range: $387m-$448m) and Consensus AEPS is 46.6c (Range: 41.2c-53.0c).
N Brown (LON:BWNG) with finance, they actually default you to this when you sign-up, you have to opt-out and it is a buy now, pay next month sort of arrangement. Boohoo (LON:BOO) has just added this with 'clearpay'. Personally I don't like it as it just creates operational gearing but I guess the sales benefits must outweigh the added risk.
Cloudcall (LON:CALL) I agree with Paul that I think the market is looking at this with the wrong lens. In the UK we are so fixated on short term profits and multiplying that by a PE ratio, irrespective of business type, that it is no wonder most tech stocks disappear off to the US! Our stockmarket mentality is a very challenging one to attract capital to build a global growth story from. I'm sure there are reasons for this but getting my crystal ball out I am also in the camp that Cloudcall (LON:CALL) will end up getting bought by the US. Something tells me probably for around £2 p/share, at which point it will be re-listed on the US market at £4 p/share and someone else will take the lions share of any capital appreciation alas!! Anyway rant over :)
The revenue forecasts for this year are £15.4m. The ARR exceeds £13m and the new enterprise deals add £0.6m so £14m is already visible. The additional £1.5m to meet revenue expectations equates to 50,000 months of new subscribers at £28 arpu. If we assume a net 1000 new users per month that actually equates to £2.2m and this number ignores any new enterprise deals signed through the year. Thus targets don't seem massively challenging to me.
A 30% revenue growth is actually phenomenal on a compound basis so I'm not unhappy with this. Looks to me like cash burn in 2nd half was also down to around £1m.
I'm comfortable holding, but mildly irritated this isn't US listed.......
Cloudcall (LON:CALL) Davidjhill Good rant and very true ! (Long Cloudcall (LON:CALL) from 2015)
Brilliant macro comment Paul. Thanks. Was particularly interested in your comment about big increase in living wage leading to increased inflation. That seems a very likely outcome to me. So not sure about your house prices rising prediction. Yes, if inflation modest, but any sign of a return to the wage price spiral that lead to runaway inflation in the 70s and interest rates will have to go up. And except for those on fixed mortgage rates at very low interest rate their monthly payments will rocket, and that could put a break on house price rises AND consumer spending too. Also the likes of that Nat West bargain mortgage are going to be a real burden for the banks and building societies that offered them. So are we seeing clear signs now of real problems ahead?
Thank you Paul for putting so much informative information and thought out there, it’s really, really appreciated. I’ve been putting some thought into the crystal ball and worry about how much debt is being carried by Britains, how expensive renting has become and how priced out not just young people but single people and women are from the buying a home.
It is also worth barring in mind that in 2022 the first interest only mortgages are going to be up, this will probably be fine for a couple of years probably, but many self certified interest only mortgage takers from slightly later, stretched themselves to the limit and beyond, are not going to have the money saved, which could lead to a big sell off of houses. I worry that will take everything down. The government have put too much effort into keeping the housing market accessible to those that couldn’t afford it with various schemes and not allowed it to naturally rise and fall, keeping debtors on the edge too I can’t see how this imbalance isn’t going to bring down the whole pack of cards. Sorry quite long winded and not very cheerful.
Paul
Hope you make the most of the lie in - A full days reading already for us to wake up to with your usual great insight If I could a double thumbs up from me once you get onto today's news!
PS single thumbs up already
It's interesting that the Stockreport of $ CALL does not reflect the £13m cash balance. Something to be aware of in other potential 'sucker stocks'.
It's interesting that the Stockreport of $ CALL does not reflect the £13m cash balance. Something to be aware of in other potential 'sucker stocks'.
Stock reports are only updated following half and full year results. As the equity fundraise took place after the former and the latter hasn't yet happened it's not reflected at the moment. But that's the case for all stocks - it's why if you're using Stock reports for stock picking they can only be a starting point. You always need to go back to the company's own numbers to make sure there's been no significant events in the meantime.
timarr
It looks like Cloudcall (LON:CALL) has again failed to get their gross sales up to the level of their fund raising and promises of future investment in Asia suggest that there are no plans to do so in the near term. The market continues to indulge this company to an extraordinary extent with no mention of profit or even a misleading EBITDA in today’s RNS.
Some day this may come good but what a long wait it will have been
Any chance you could look at Non-standard Finance (LON:NSF) . Good results (inline) with impairments below expectations across their 3 divisions and loan book growth slightly ahead at 2. Big news though is the expected new financing arrangements which will reduce borrowing costs. If this lands it is a bit of a game changer. RNS of two substantial new holders. Div yield is circa 14%. Risk for me is the regulator otherwise there should be a substantial rerate soon.
Hi greagatr0n,
Sorry I won't be looking at Non-Standard Finance (LON:NSF) - because I've already got so much on my plate, and also I rarely cover finance companies. If it had been a quiet day for other news, then I would have looked at it for you. Sorry about that.
I like your summary though, thanks for posting that.
Regards, Paul.
I'd appreciate any thoughts on Quarto Inc (LON:QRT) - I hold but didn't average down, because I was almost certain that they'd need to raise money given the balance sheet...Particularly after appointing a new broker at the end of last year.
I think there's a good business in there, once the balance sheet has been sorted out. I know it's heavy on intangible assets ($78m of goodwill and intangibles).
But the intangible assets / Intellectual Property does have value - it generates revenue. So I'm planning to back the capital raising, but happy to hear contrary thoughts.
One point with thumbs down Paul. I very nearly gave you one (for the first time) this morning. I have to add unintentionally. The ticker is at the top I read the article so came from the bottom and as I brought my mouse up it went through the down tick first, and held the down tick indicator. Fortunately I wasn't in the rush I normally am so spotted it and removed my arrow and entered from the top. Just saying.....
My morning smallcap tweet: Fourteen smallcaps covered today. Phew!
Lamprell (LON:LAM) Xaar (LON:XAR) Judges Scientific (LON:JDG) Headlam (LON:HEAD) N Brown (LON:BWNG) Hydrogen (LON:HYDG) Prophotonix (LON:PPIX) Quarto Inc (LON:QRT) Digitalbox (LON:DBOX) VR Education Holdings (LON:VRE) Moss Bros (LON:MOSB) Gulf Marine Services (LON:GMS) Cloudcall (LON:CALL) Works co uk (LON:WRKS), Spire Healthcare (LON:SPI), MySale (LON:MYSL), Kier (LON:KIE), Bakkavor (LON:BAKK), Cello Health (LON:CLL), Allergy Therapeutics (LON:AGY), Portmeirion (LON:PMP), Finsbury Food (LON:FIF), Non-Standard Finance (LON:NSF), Brooks Macdonald (LON:BRK)
Lamprell (LAM) guides FY rev $276m at the bottom end of previously guidance. Guides FY20 rev $350-450m. A year ago FY19 guidance was $250-400m. Net cash reduced to $41.5m ($80m). "The Company has secured an extension to its debt facility until April 2020 as we continue to negotiate a new facility, as well as considering other debt options, for future working capital requirements."
Xaar (XAR) guides FY rev £46m with H2 trading broadly in line with H1. F/C is £56.5m but that looks wrong since XAR guided H2 rev similar to H1 (£22.5m).
Judges Scientific (JDG) guides FY EPS slightly ahead of market expectations despite a weak Dec.
Headlam (HEAD) guides FY marginally ahead of market expectations (U/L pretax £39.3m). Guides a modest improvement in this FY.
N Brown (BWNG) guides FY adj pre5ax only £70m to £72m. Blames a lower than expected benefit from the IFRS9 non-cash provision estimate, lower Financial Services revenue and a highly promotional market. Also guides FY21 adj pretax flat due to "reduced scope for bad debt provision improvements, combined with industry-wide regulatory changes."
Hydrogen Group (HYDG) guides FY net fee income only £29.4m. US strong but "some reduction in quarter-on-quarter growth rates as recent investment in both new staff and physical infrastructure was onboarded and bedded in." Nevertheless guides U/L pretax broadly in line with current management expectations.
ProPhotonix (PPIX) guides FY rev $14.9m down 9% (they don't say so but highlight H2 orders up 30%, rev up 9%). F/C $19.1m yet "The Board is pleased with the rebound in business in H2".
Quarto Group (QRT) Open Offer to raise £13.9m at 68p, a 10% discount, to cut debt.
Digitalbox (DBOX) The Daily Mash publisher guides FY adj pretax ahead of market expectations, and revenue slightly ahead.
VR Education (VRE) sees FY rev only €1.02m, below market expectations. Blames delayed launch and shortage of mobile standalone headsets from hardware providers. Supply problem has been resolved. EBITDA -€1.49m better than mkt expectations.
Moss Bros (MOSB) guides H2 LFL broadly in line with the Board's expectations, FY adj pretax -£1m. Blames more intensive discounting from competitors and a materially lower level of footfall on high streets and shopping centres. Expects challenging year "until we see an improvement in consumer confidence."
Gulf Marine Services (GMS) sees FY EBITDA at upper end of $48-50m guidance. Guides FY20 $57-62m.
Cloudcall Group (CALL) H2 rev up 18%, FY 30%. Rev cash and pretax expected to be broadly in-line with market expectations.
Theworks (WRKS) CEO scarpers. He is thanked. CFO made CEO.
In line: Spire Healthcare (LON:SPI) MySale (LON:MYSL) Kier (LON:KIE) Bakkavor (LON:BAKK) Cello Health (LON:CLL) Allergy Therapeutics (LON:AGY) Portmeirion (LON:PMP) Finsbury Food (LON:FIF) Non-Standard Finance (LON:NSF) Brooks Macdonald (LON:BRK)
Thanks MrC!
How you managed to cover all those updates in your post just before 8am, I have no idea! Respect!
Also many thanks for posting your daily early snapshot here every day, it's very much appreciated.
Regards, Paul.
Good morning Paul
Any thoughts on the Cloudcall (LON:CALL) trading update.? You said (at the start of the year) that this is one of your holdings.
This is a "broadly in line" announcement. Lots of growth and encouraging signs for the future but (by the sound of it) not quite keeping up with market expectations. And actually I am not sure how much the slight miss matters. It may just be a sign that Cloudcall (LON:CALL) have not learned how to manage City expectations. 30% year on year growth may be good enough to build a successful business though, maybe, not as quickly as the company and investors would like
I am happy to continue holding but not yet encouraged to top up.
And thanks again for your insightful, in depth and truly independent and honest commentaries
Cloudcall (LON:CALL)
And actually I am not sure how much the slight miss matters.
One slight miss matters not a jot - its when the company continually misses and drags out expectations that one should worry - and Cloudcall certainly has form in this regard.
I used to hold - sold at a loss and and happy remaining on sidelines until they convince me they have a very near term clear path to profits and being cash flow positive - whilst keeping reasonable growth.
To be fair to the company progress isn't terrible and the numbers are reasonably clearly laid out.
Note the company had advised previously they had a 1k + per month new user target for 2019- so the H2 number of 902 is 10% shy of this target (nice simple one to follow) - so looking at this stat it seems slightly worse than "broadly inline" - although this stat probably matters more to next years turnover/profits outcome i would guess - so technically i guess they can ignore this future slippage - with high upfront costs i guess slower than expected growth could actually help the numbers perhaps.
In July their said
Whilst I am obviously pleased to note sales are growing strongly, and that we tracked above our target of 1,000+ net new users per month
Hi Paul,
Will you cover CALL trading update today? Thanks.
The webinar was a fascinating analysis of the competition entries. There has been quite a debate on both tactics and rules on a thread started by our friend Gromley that you can find here: https://www.stockopedia.com/content/stockopedia-2020-challenge-enter-before-midnight-31st-december-541031/
I know we don't normally discuss oil companies in the SCVR but they have been among the favourites of the all-or-nothing entrants to the competition so I would like to share this particular story here. The leaders for the first week had all chosen Lekoil (LON:LEK) . Now you could not make this up: on the 2nd the company announced a funding deal causing a massive rise in share price. On Tuesday, following a brief suspension, it announced:
"....the loan agreement announced on 2 January 2020 by the Company, purportedly with the Qatar Investment Authority ("QIA") (the "Facility Agreement" or the "Transaction") seems to have been entered into by the Company with individuals who have constructed a complex facade in order to masquerade as representatives of the QIA (the "Counterparties")."
see https://www.stockopedia.com/sh...
So - closing prices 31/12 4.65p 6/1 10.5p today 2.91p.
Can you imagine the outcry if the first announcement had been made just before the end of the competition and the second after the announcement of the winner, who had included this share!
Hi sharw,
I know we don't normally discuss oil companies in the SCVR but they have been among the favourites of the all-or-nothing entrants to the competition...
Just because I don't report on resources sector companies, that's no reason why readers can't discuss them here if you wish to.
Regards, Paul.
Two days' reading matter for the price of one!!
No thumbs down allowed.
Hi Laughton,
Well, I thought if I put up some macro stuff tonight (weds), then I can have a bit of a lie-in on Thurs morning, it's been a stressful week!
Regards, Paul.
looks like I'm the first to give Paul a thumbs up!