Small Cap Value Report (Thu 18 May 2017) - CHH, IND, STAF, ITQ, BMY, MTC

Good afternoon! It's Paul here.
I had another second wind in the evening last night, and added more sections to yesterday's report, which now comprises comments on;
- Patisserie Holdings (LON:CAKE) - decent interims
- Foxtons (LON:FOXT) - trading update
- Altitude (LON:ALT) - results & placing
- Zotefoams (LON:ZTF) - trading update
- Ideagen (LON:IDEA) - trading update
On to today, the header above shows the companies that I'm aiming to report on today.
Obviously the backdrop this week is a bit of a market wobble in the USA yesterday, driven by political events surrounding Donald Trump's chaotic presidency. I think a stock market correction is overdue, so sometimes the market just looks for any excuse to sell off.
Personally, I've de-geared, and opened some shorts in my spread bet accounts. However, I've not made any significant changes to my ungeared, long-term portfolio.
Churchill China (LON:CHH)
Share price: 1068p (up 1.2% today)
No. shares: 11.0m
Market cap: £117.5m
AGM Statement - covering the first 4 months of the current financial year (ending 31 Dec 2017).
This is a UK-based manufacturer of crockery, mainly for restaurants.
Today's update is short & sweet!
"I am pleased to report that we have made further progress against our objectives in the first four months of the year. We have continued to benefit from strong export demand and our new product launches have been well received.
As a result we continue to anticipate that we will meet our target performance levels for the year."
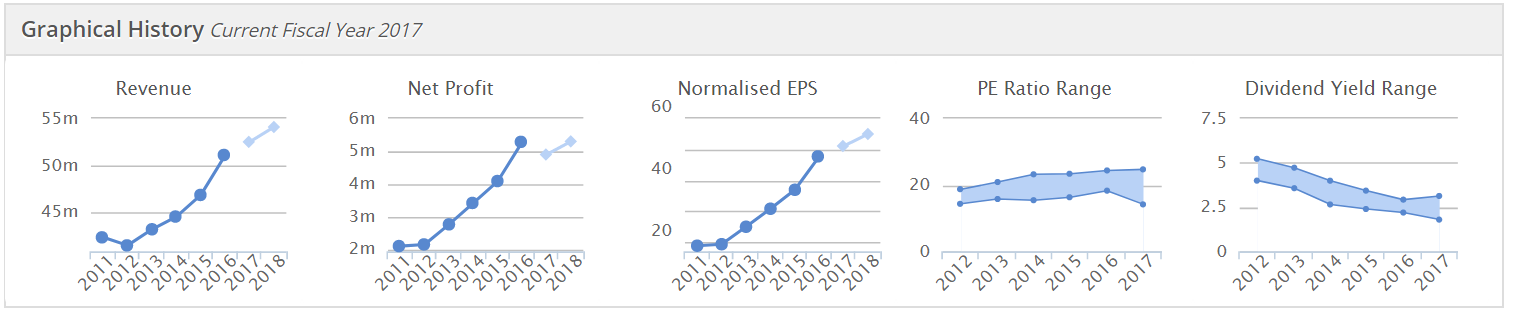
Looking at the Stockopedia graphical history (which is my shortcut for getting a handle on how any company has performed), we can see that there is a steady progression of revenues. Plus there seems to be good operational gearing, as profits & EPS have risen considerably more in % terms, than revenues;
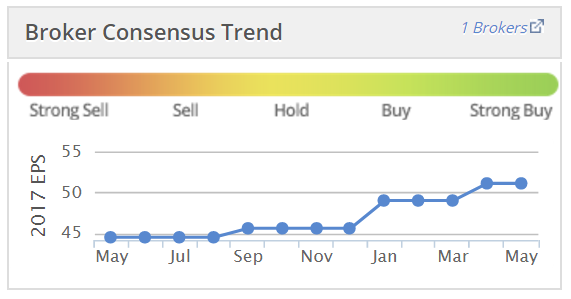
There's also been a positive move in forecast EPS in the last 12 months, which is another thing I like to see. Companies which are seeing earnings upgrades are usually on a roll, so there's probably less risk of a profit warning;
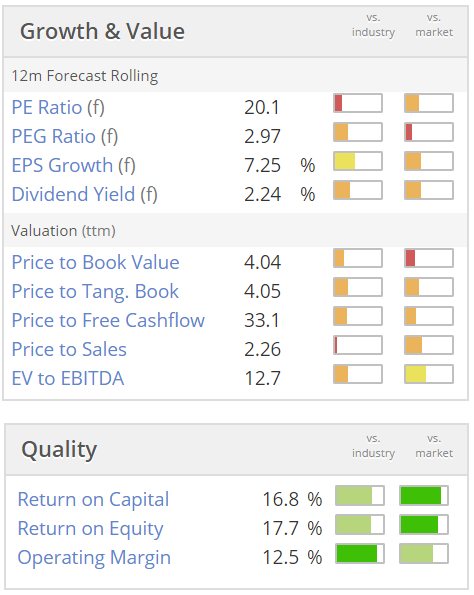
So far so good. However, as regards valuation, it's certainly not cheap;
Hospitality sector - there's been tremendous growth in the UK hospitality sector in recent years. The problem is that many operators are now reporting more difficult conditions. Therefore, some are shelving expansion plans. Weaker players could go bust.
Skimming through the last results statement in Mar 2017, the company does indeed reporting softening demand in the UK. Although exports seem to be taking up the slack - driven by weaker sterling.
My opinion - this is a good quality company, which seems to be well-run. It also has a strong balance sheet. The products are widely used, and seem attractive & stylish.
The trouble is, I think the UK hospitality sector has peaked, and could struggle for the foreseeable future.
Although the company's growth seems to be coming from export markets. Whilst thumbing through the most recent Annual Report, I came across this interesting little graphic;
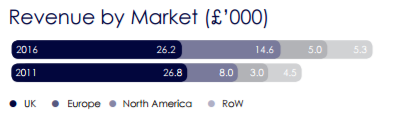
Look at how UK sales have slightly shrunk in the last 5 years, but exports have grown strongly.
So it seems to be the export growth which is justifying the rather toppy valuation. So shareholders will need to keep an eye on sterling exchange rates, as it's creeping back up against the dollar for example.
Overall, I like the company, but feel the valuation is too warm for me, given that earnings growth seems to be slowing.
Indigovision (LON:IND)
Share price: 211.9p (up 17.4% today)
No. shares: 7.6m
Market cap: £16.1m
(at the time of writing, I hold a long position in this share)
AGM Trading Update - covering the 4 months to end Apr 2017. The company now has a 31 Dec year end, having changed it some time ago.
This is an Edinburgh-headquartered mid to high end digital CCTV company. It sells products globally, and was an early pioneer in developing digital CCTV systems.
I've held this share continuously for 13 years now, and can tell you that positive trading updates are extremely rare. So what a pleasure to read this update today, which sounds a lot more encouraging than news for several years.
Summary of main points;
- Software licence & camera sales have shown decent growth in volumes
- Camera prices have stabilised (previously falling)
- Modest growth in overall revenues
- Good (over 10%) growth in Latin America, Europe, M.East & Africa
- N.American sales "well below potential"
- US sales teams have been restructured (yet again)
- New product called "CyberVigilant" detects if CCTV system has been hacked, and is patent-protected
Outlook/current trading - sounds encouraging;
May started well. In the first 19 weeks of 2017, overall revenues were ahead of the corresponding period last year.
The immediate outlook is more positive than it has been for some time, and the medium term prospects are promising.
The Board continues to expect that 2017 as a whole will see improvements over last year, with both sales and profits, as in recent years, second-half weighted, and the latter part of the year also benefitting from higher revenues in North America.
My opinion - as I am painfully aware, this company has little visibility over earnings. This is because just 1 big contract can make a massive difference to the overall results. So there's not really much point in looking at measures like forward PER, because nobody knows what the E is going to be.
That said, after years of disappointments, the company does seem to be getting its act together. I know that management have tried incredibly hard to rebuild profitability. There's plenty spent on R&D, which has enabled the company to keep innovating on product.
The balance sheet remains strong. Note that the company has hardly issued any new shares over the years, so there's good discipline there.
Perhaps this is the start of IndigoVision's renaissance? Time will tell.
Staffline (LON:STAF)
Share price: 1238p (down 1.0% today)
No. shares: 27.8m
Market cap: £344.2m
AGM Trading Update - the company updates us today on performance to date in this financial year (ending 31 Dec 2017).
This is a group which provides contract staff to customers (mainly food producers & retailers). Plus, it is a leading provider of UK Government welfare to work programmes.
Main points;
- Continuing to make "excellent progress" in 2017, after "record year" in 2016.
- Staffing division continues to grow - no impact from Brexit vote, on either demand for, or supply of workers.
- Employability division - "new business pipeline remains strong". "Continue to bid for and win new contracts".
Overall - this sounds reassuring;
As a result, we are pleased to confirm that current trading is in line with market expectations and the Board remains confident of the Group's growth prospects with the "Burst the Billion" £1 billion revenue target still very much on track."
Broker comments - there are two update notes available on Research Tree today, which I've had a quick look at. Both analysts sound encouraged by today's update, and think the shares are good value.
Valuation - Stockopedia shows the forward PER as 10.6 - which I think looks good value for a company with a track record of strong organic growth.
StockRank is excellent, at 97.
Note that the Stockopedia computers have also put Staffline into one of the winning investing styles;
My opinion - I've been positive on this share for years.
It's a well-run, entrepreneurial business. It looks reasonably-priced, in my opinion.
Interquest (LON:ITQ)
Share price: 47p (down 3.1% today)
No. shares: 37.6m
Market cap: £17.7m
Cash offer for Interquest - I mentioned this situation 2 days ago here. The Chairman, CEO & CFO of Interquest indicated they might bid for the company at just 42p per share. They issued another RNS today saying they are going ahead with a derisory 42p offer.
What complete scumbags! The way I see it, they've under-performed, and the share price has reflected that, plunging on a series of profit warnings in the last year. Now the company is cheap, management have decided to try to buy it on the cheap, at what is clearly an under-valuation.
The NEDs and broker (Panmures) have publicly said this offer undervalues the company.
The statement today from management is a joke. They complain that the low share price is damaging the business, and it would be better off privately owned. Yet the low share price is their fault - for their lamentable performance.
When a company under-performs, management has a duty to improve performance, and over time market confidence returns. Only a bunch of spivs would try to buy the company on the cheap, leaving shareholders with crystallised losses. It's clearly unethical. Meanwhile the performance of the company will no doubt improve, and greedy management will receive all the future benefit.
I suppose there's a chance this is a stalking horse bid, designed to smoke out higher competing bids?
Personally, I ditched my shares in disgust this morning at 46.6p. The problem is that the Chairman, Gary Ashworth, holds 33.3% of the equity. Together with others, this means there is already 42.2% support for the derisory 42p bid. So it might be difficult to stop.
I keep a black list of Directors that I won't ever get involved with again, who shaft outside shareholders. A good example was FDM (Holdings) (LON:FDM) - where (years ago) Rod Flavell forced out other shareholders, taking the company private at a laughably low price. Of course it re-floated a few years later at a massively high valuation. So for me, that one's a bargepole job. Perhaps a pity, as the shares have done really well, but if you can't trust management...
InterQuest now falls into the same bracket. So I'll certainly be avoiding any other companies these Directors get involved with.
A few snippets to round off with.
Bloomsbury Publishing (LON:BMY) - audited preliminary results - for the year ended 28 Feb 2017 - from this book publishing group.
Profit before tax and highlighted items is down 7.7% on last year, at £12.0m .
Although the company says this is above market expectations.
Divis of 6.7p are up 4.7% on last year, and provides a yield of 3.8% based on the current share price of 177p.
Balance sheet looks excellent, very strong, and includes £15.5m in cash, with no debt.
Cashflow also looks excellent, although of the £19.8m operating cashflow, £7.3m came from an increase in trade payables. That could reverse next year. However, cashflow still looks pretty good, and comfortably enough to finance the divis.
Note that this company continues to publish Harry Potter books. It would be interesting to find out what proportion of profits comes from those?
StockRank is exceptional, at 97, and this is classified as a "Super Stock" in the new styles classifications.
My opinion - it looks OK. The price seems about right to me - 15.3 times forward earnings.
Where's the profit growth going to come from though? Normalised EPS has been fairly flat in the last 6 years, so I'm not sure I'd want to pay 15 times, for a company that seems ex-growth, in a sector that's declining.
It's good to see that conventional books still have a future. Although it's not something I would want to invest in.
Mothercare (LON:MTC) - full year results for the 52 weeks ended 25 Mar 2017 are out today.
This is the third year of the company's turnaround, and to my mind, it's fairly unconvincing. I've had a quick skim of the figures, and am not particularly impressed.
The UK is still loss-making, at £4.4m underlying loss, on £459.4m UK sales. So a lot of work, for no return. What's the point?
International has always been the better part of the business, but underlying profit there is down 13% to £35.2m.
Underlying EPS is up a smidge, at 9.7p.
PER is 12.8, at the current share price of 124p (down 3.5% today).
My opinion - I can't see much in the outlook comments to give me confidence that future performance might radically improve. That's the only reason most people would invest here - i.e. if profits say doubled in the future, then the shares would do very well. How likely is that though? I don't know.
This seems to me a company that is maybe running to stand still. Internet disruption means margins are going to be under relentless attack. So this strikes me as a typical older-style retailer that may never return to the glory days of higher profits before the internet came along and messed everything up.
All done for today! Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
I see one of the NEDs that wouldn't recommend the ITQ offer has been voted off the board at the AGM!
FREng
I would imagine Paul is reeling at the shock. Quite late in the day for Revolution Bars (LON:RBG) to say that matters which have been on the horizon for quite some time i.e min wage, apprentice levvy and business rates have affected them. Actually the rates haven't gone up yet have they?
I though re the minimum wage was countered by the argument that Revolution Bars (LON:RBG) paid above average to managers etc.
Anyway look forward to Paul's take
Yes, eagerly awaiting Paul's thoughts on this. As a holder, I'm tempted to buy this morning, but not sure the stomach is strong enough.
Revolution Bars (LON:RBG) please, Paul!
Probably also worth mentioning that Indigovision don't have any R&D capitalised on the balance sheet and they had quite a lot of cash so whilst trading is erratic the balance sheet is strong. Company has historically paid dividends including a special dividend to return surplus cash to shareholders during the last 5 years
Paul; With regard to IND , I trust you top sliced in 2007 but curious to know why you did not pull out altogether in say 2011 whilst still in profit and reinvest in a growth company , as you so often do. Just attempting to learn what successful investors do at such times. Cheers.
Thanks Paul ; enjoyed the report, as usual.
Do you have any input as to why Revolution Bars (RBG) has been fading ever since the Sharescope negative report ; is it just that or more to do with returns on new bars.
Hi
Anyone got a view on why Somero Enterprises Inc (LON:SOM) dropped to 283.5p (down nearly 10%) on early trading this morning. It's recovered somewhat and now only down circa 2.4%?
Might this be the Trump issues worrying investors about US sales?
Ideas welcome. (I hold)
Regards
Howard
I doubt there's a logical reason. I also hold. The market is going through a bout of jitters.so things go down
Yes I think it was to do with Trump, the US market was down heavily yesterday evening, so on opening I guess Somero Enterprises Inc (LON:SOM) was marked down. Ashtead (LON:AHT) which also has high exposure in the USA was another heavy faller this morning but has recovered since.
Yes I think it was to do with Trump, the US market was down heavily yesterday evening, so on opening I guess Somero Enterprises Inc (LON:SOM) was marked down. Ashtead (LON:AHT) which also has high exposure in the USA was another heavy faller this morning but has recovered since.
Yes, Keller (LON:KLR) also dropped 3%+ too, early doors. Somero Enterprises Inc (LON:SOM) is my largest holding so I watched the drop in real-time with morbid fascination while downing my first mug of Yorkshire Tea of the day. I was only really looking at real-time data at the open to see the reaction to Burberry (LON:BRBY) FY numbers having accumulated a fair lump of them recently. Must admit they had not been on my radar before so I'd like to thank Graham for mentioning them here and bringing them into my (to quote Terry Smith) "Investible Universe"
All the best, Si
Hi Si
See my comment #14, building on your insight about Keller (LON:KLR).
Regards
Howard
Hi Si
What do you use to watch in real time?
Thanks
Michael
Hi purpleski,
I use MoneyAM: http://www.moneyam.com/ because it meets my very limited needs for real-time prices. Registration is free. I find that generally watching prices is not helpful as I'm not a trader by nature. However, it can be interesting to watch price action of companies that have released news at the open on occasions.
All the best, Si
Thanks. No I am not a trader either (13 buys/sells this year) but I think it would be good to have a source.
I will take look.
Best Michael
Hi Herbie
Thanks for the insight about Ashtead (LON:AHT), and Si's comment #12 about Keller (LON:KLR). Both are Industrials as is Somero Enterprises Inc (LON:SOM). I note that other Industrial sector shares are also quite down today.
Maybe a Trump/US thing plus an Industrials thing in combination.
Regards
Howard
Yes I think Trump issues. I sold Somero Enterprises Inc (LON:SOM) recently when the pound strengthened after the election announcement, which is another factor. I think it's fundamentally a very good company that was being undervalued, but the recent increases were driven by expectations of a Trump construction boom that now look less likely than his impeachment.
I never thought that Trump boom would help Somero much as I think their kit isn't so relevant for big civil infrastructure projects as opposed to high bay warehouses, but that was the reasoning being expressed here and elsewhere.
mainly because Somero Enterprises Inc (LON:SOM) is pretty illiquid with around 81K shares traded a day, it doesn't take much selling to push that around. If you believe it was a good share last week then media hysterics on Chump's future doesn't make a damn difference. Last week's good share just got better
net-net the Houses run the US and not the POTUS, it doesn't matter if it is Chump, Pence or a Cat-in-a-Hat once both houses are dominated by republicans who are business friendly.
GPB strength may revalue the SP based on USD denominated earnings but not 10% in one morning
The reality is most likely profit taking and over anxious selling... looks like some people were buying too,
Well I think it could have an effect if Trump goes then the US spending could well change, Trump is the one who is promising all this spending on construction and infrastructure. It's a bit like if Labour win the election in June, the future for many companies will change, some may even be nationalised.
John
Thanks for the comments. I also think it is a good company and looking now at the days recovering SP movement it seems the market is also comfortable with it. I guess it's a big trader doing something 8am to 8:30am not entirely related to the quality of the SP and stock.
Regards
Howard
I guess it's a big trader doing something 8am to 8:30am not entirely related to the quality of the SP and stock.
Of course it would not be the first time this has happened... I remember buying Somero Enterprises Inc (LON:SOM) at 120p or thereabouts a while back when an institution was constantly dripping shares. What a bunch of muppets!! I think there's money to be made buying good quality companies when an institution is getting out. It happened with Lavendon (LON:LVD) too. If anyone sees this happening, please let us all know as it's proved a lucrative approach to date :)
All the best, Si
Hi Howard
I think others have answered your question.
I hold as well and only wish had been able to see the early trading, I would have definately bought some more if I had know they were on sale at a 10% discount. I suspect in 10 years (when Trump is long (8 years?) gone) this will have prooved to be a lovely investment.
My 6th largest holding 7.2% of folio.
Kind regards
Michael
Thanks for the assessment of Churchill China Paul. Yes, UK revenues have stagnated for quite a few years but they are still greater than sales of all other contries combined so I am hoping that there is still be plenty of scope for international growth to drive the company forward. I also like to conservative and experienced management of this company.
Any chance of having a gander at Safestyle Paul in line with management expectations but looks like market was expecting better. Thanks
I believe Safestyle UK (LON:SFE) is down is because of this : "2017 started positively with robust order intake in the first quarter, however recent trading has been weaker than expected reflecting the latest FENSA statistics which have shown a significant contraction in the overall market in the first quarter of 2017. As a result, compared with an exceptionally strong equivalent trading period last year, the Group has seen more modest overall growth of 2% in order intake for the first four months of 2017. The Group expects to grow revenues in the first half of the financial year, but anticipates profits in the first half will be lower than the comparative period last year due to a combination of lower than planned volumes and some parallel running costs following investment in our new production facilities, as previously outlined."
There's a decent [if somewhat downbeat] article on Safestyle by Richard Moore on Shareprophets.
Steve Moore - apologies.
it amuses me when mainstream media try to find a narrative for market moves after they happen and not before. Markets have been well extended, volatility has been artificially suppressed by premium selling in options and huge ETF buying programmes. Gold has been signalling a pullback for the past few days (and a very nice trending trade too).
As you say, well overdue and healthy, time for wishlists and dry powder. Given the rapid drop-off yesterday in the main US indices, I'd be unsurprised by a 10% pullback. Yesterday the S&P tore through its 50 DMA on volume like a knife through butter. That moving average had been in play as support since last November : the 200MA is about 8% off the highs and hasn't been checked by price action since Nov 4: I'd favour price having a look at that for support and then a rally when tested. Loads of leveraging in these markets which can unwind very fast . As the S&P does so the world follows.
Just my hypothesis, always good to create one's own narrative and then allow facts to prove or disprove otherwise.
June swoon looms
Yes it is laughable how mainstream media like to interpret moves in the indices. On the BBC news at lunchtime today the newsreader suggested that the weak performance of the US market was because the likelihood of Donald Trump being impeached was rising sharply, as reflected by bookmakers odds. I wonder how the BBC knows that this was the reason - just a guess I suppose.
Hi Paul
Looking forward to the report as ever. I'd be interested to hear your thoughts on the placing / acquisition RNS from 1pm (LON:OPM) today. I'm a bit peeved at the discount, and pondering how to respond to the open offer. A fairly minor holding for me, and an under-performing one at that, so far.
Cheers!
Same for me, small holding, but I am wondering how to interpret this. My current take on this is that a 20% discount means they were not able to generate a lot of interest from Institutions, which is not a good sign I guess... Also the raising was leaked and the company had to release a statement to confirm the rumour yesterday. Paul, in your experience would that also indicate that the discussions were taking too long because of too little interest? Great case study anyway!
Thanks as always for the great job!
Thomas