Small Cap Value Report (Thu 20 Jan 2022) - RBG, WIN, G4M, WIX, TIME, SDRY

Good morning, it's Paul & Jack here with Thursday's report. Today's report is now finished.
Agenda -
Paul's Section:
Revolution Bars (LON:RBG) (I hold) - festive season was hit by pandemic issues, as we've heard from other bars. It's still in line with full year expectations though (set low). I see a very positive second half (Jan-June 2022) being likely, and explain why.
Gear4music Holdings (LON:G4M) (I hold) - peak trading Q3 (Oct-Dec 2021) has gone OK in the UK, but sales are well down in Europe- Brexit challenges being blamed. We're told to expect a recovery in EU sales, due to 2 new distribution centres ramping up. Overall, G4M reassures, with EBITDA guidance in line with market expectations. Some good catalysts for growth - e.g. acquisition of AV.com. Share price looks about right to me.
Superdry (LON:SDRY) - I have a good rummage through interim results, and for the first time see signs of a potential turnaround. Management seem to have stabilised the business around annualised breakeven. Solvency looks OK. Might be worth a punt, if you think management can recover former glories, but that won't be easy with big cost headwinds coming in 2022.
Jack's Section:
Wincanton (LON:WIN) - FY profit to be ahead of expectations. Good control over costs and new contract wins, so the group is executing well. Financial risks remain though, which is a shame, as the valuation here is modest and the shares could well rerate at some point. So we have to consider the potential risks against the likely reward.
Wickes (LON:WIX) - Q4 sales down -5% on tough comps, but up 14% on a 2Y basis. It’s the cheap valuation that has attracted me to this recent demerger, which used to be a part of Travis Perkins. There’s a lot of competition, so the group needs to prove it can defend and grow market share.
Time Finance (LON:TIME) - modest levels of growth here but the shares offer good value, so not much is currently expected from the market. The new CEO has been in place since June 2021 and the strategy has shifted from buy and build to organic growth. It’s a micro cap now, but one in which the investment case is beginning to look more favourable.
Market comments from Paul
I've been following US markets a lot more closely of late, and it seems distinctly bearish at the moment - in particular for tech stocks. Many former tech darlings are now down hugely in the last year, many by more than half. That's been disguised by the mega techs doing well, but even those are coming under pressure now.
Commentators blame it on rising interest rates, the perception is the Fed is likely to raise 3-4 times in 2022. Each raise is only 0.25%. So even after these increases, interest rates would remain incredibly low by historic standards. Will the Fed actually go through with it? Remember that a couple of years ago, when rising interest rates spooked the markets, it reversed course. It seems to me we're addicted to permanently low interest rates, and QE.
In recent Q&A to Congress, Fed Chairman Powell indicated that the Fed would react to the next proper recession (i.e. not a specific crisis, like 2008 or covid) with "asset purchases". I.e. more QE, and super-low interest rates.
Whatever the reason, I welcome the scrubbing off of excessive valuations, and the unwinding of highly speculative activity (e.g. many IPOs, the nonsense of SPACS - premium prices for blank cheque companies, influx of (millions of) naive speculative traders through platforms such as Robinhood, Bitcoin mania ["crypto" currently valued at around $2 trillion! Just worthless pieces of code, whose sole real world function is financial speculation], traders chasing momentum and ignoring fundamentals & valuation). Maybe the bear market in speculative tech shares is a good thing, which is scrubbing off excess, thus making the market more stable going forwards, instead of risking a sudden crash?
Whilst in UK small caps, it strikes me how many companies are exceeding expectations. We had 5 such companies beating expectations yesterday alone (SIS, Midwich, PCI-Pal, Christie, and Centaur). Plus 6 companies that were in line, with only 1 profit warning (BOTB - I hold).
My style of value/GARP investing feels like it's coming back into fashion. Hence I think it's good to focus on decent, reasonably priced companies, and be more resistant than ever to story stocks, and growth priced for perfection.
The big UK retailers reporting so far, have generally done well.
Supply chain costs/delays are an ongoing issue, but it generally feels as if companies are adapting, and coping. The cost headwinds & delays in 2021, could turn into the tailwinds of reducing transport costs & easing of supply chains in 2022, who knows? Many companies have increased inventories, and brought them in earlier - thus compounding the overall pressure on supply chains. But again, stocking up is something that only happens once, then eventually reverses when supply chains normalise. Someone on CNBC was saying that semiconductor chip shortages now, are likely to turn into a glut in future, once production has increased, which takes time apparently. That's certainly the pattern in the past.
Years ago (late 90's, early noughties) there were shortages of electronic components, I've mentioned this before here. My neighbour Steve used to tell me about it down the pub. He described his job as moving from selling, to allocating limited production to key customers (similar to what's happening at the moment). A couple of years later, he was unemployed, because new Chinese factories had flooded the market, and there was now over-supply, and greatly reduced prices.
The same thing happened with solar panels - remember all that kerfuffle with PC Crystalox, which along with the rest of the sector, was forced to pretty much shut down, because China made so many solar panels, and so cheaply (dumping at below cost apparently, to ensure full employment), to destroy the industry everywhere else and corner the market. I seriously worry about how dependent we've become on China - a hostile, dictatorial regime, that doesn't operate to the same rules Western companies do (i.e. subject to scrutiny, and needing to seek profits due to shareholders wanting divis).
Best Of The Best (LON:BOTB) - thinking about eCommerce companies, what struck me about BOTB's profit warning yesterday, is that its business model is so dependent on online marketing. Players churn constantly, although they do have some "whales" - i.e. longtime customers who play every week, regular as clockwork. Other players see an ad online, have a punt, then lose interest. So the company has to constantly advertise to generate replacement players, let alone growth.
The cost of that online advertising has shot up, thus greatly reducing BOTB's profits. It's now having to scale back marketing quantity (for the same cost), and hence the H2 guidance provided yesterday was for a sharp slowdown in revenue & profit, since the marketing spend now delivers less bang for the buck. This problem shows that purely online businesses are lambs to the slaughter for Google & Facebook/Instagram in particular - who set the prices at whatever they like, because they dominate online advertising so much. Many companies have told me that these 2 companies control the most effective marketing, so companies are effectively forced to use them. Rather than looking for growing eCommerce businesses, maybe we should just buy & hold shares in Alphabet and Meta? They're not expensive, and have stunning growth, and completely dominate online advertising. There's regulatory risk though.
Are all eCommerce businesses doomed then, to suffer falling profits, as the mega tech US companies price-gouge their captive customers, and remove their profits? It looks a big threat for companies that have to constantly generate new customers. But there are better online business models, e.g. -
Sosandar (LON:SOS) (I hold) uses a variety of marketing approaches, split equally between online, TV, and printed magazines posted out. All are effective. Moreover, once they've acquired a customer, then they can communicate for free using email. Customers also tend to be sticky, and loyal to the brand, as it has a distinctive product, and brand. This strikes me as a very much better business model than others. The cost of customer acquisition has roughly halved, as the company becomes more savvy about what works.
Next (LON:NXT) and Shoe Zone (LON:SHOE) (I hold) - what both these companies seems to have achieved, is to reap the benefit from having both online operations, and physical stores. I'm coming round to the view that this could be the optimum business model. SHOE for example recently said that its growing online operations have a low returns rate (about 11% from memory), and that the bulk of these customer returns are taken to a physical store - hence no postage costs for SHOE. How good is that? It's fantastic, I think. Hence why I dipped my toe in with an opening size stake recently.
Next is just a superb operator, as we've been saying here for years. It seems to be using the stores as mini warehouses. I really like this approach, as it would allow an advanced IT system to fine-tune the stock holdings in the physical stores. So if a particular store is over-stocked, then online orders for those particular lines could be routed to the store which has excess stock. Staff are then utilised at quiet times to fulfil online orders. Plus there's less terminal stock at end of season in the stores, to clear at a discount. There's so much potential in that approach I think, but the challenge would be merging the IT to be capable of handling the stock in this way.
Other eCommerce businesses might need to grapple with the problem of customer returns by analysing every customer's activity, and just closing the accounts of people who constantly return lots of items. Is free postage for returns viable? Could customers with low returns rate be rewarded with discounts, points, etc? I think companies will need to innovate in these areas, to gain a competitive advantage in a very crowded sector.
Meanwhile there's the looming threat of Chinese competitors trying to harvest our data, and offering product at uneconomical prices, because they don't actually need to make a profit. The same is true of venture-capital backed speculative new entrants into markets like BOTB's, and the online car retailers new entrants like Cazoo, Cinch. They're not viable business models (heavily loss-making), but have a ton of marketing money to rapidly gain market share, in the hope that they can scale up and become viable in future. That's obviously unfair competition, but nothing can be done about it.
Lots to think about, as always!
Inflation - Chairman Powell made an interesting point about the reasons for higher inflation (recently hit 7.0% in the USA). He said that supply chains have faltered because of covid, but also because demand for physical goods rose by 20% in the pandemic. That's because people diverted spending from holidays/leisure activities, into buying physical goods (e.g. home improvements). That's the main reason supply chains can't cope - excess demand, a lot of it fuelled by Govt stimulus. We saw a similar thing in the UK, with the Bank of England saying a lot of stimulus money piled up in household bank accounts.
Hence I remain of the view that what we're seeing is a mixture of supply chain disruption, but also excessive demand. Maybe that could sort itself out in 2022, as conditions seem to be returning to normal, with us now having achieved herd immunity, and the pandemic almost over?
As long as companies can raise their selling prices, then they should be able to protect profits. That's the main issue that I'm focusing on, and always asking management when I speak to them. Companies with low margins (gross and net) are just best avoided I think, as if they don't have pricing power, there will always be a delay in them passing on costs (as we've seen with Accrol Group (LON:ACRL) ). Companies locked into long-term supply contracts could be disastrous, so that's another good question to ask companies.
OK, on to today's news...
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Revolution Bars (LON:RBG) (I hold)
23.4p (y’days close) - £55m market cap
Revolution Bars Group plc ("the Group" or "the Company"), a leading operator of 67 premium bars, trading mainly under the Revolution and Revolucion de Cuba brands, today announces a trading update for the 26 weeks ended 1 January 2022.
Overall trading - still in line with (modest) full year expectations, despite taking a hit from covid disruption over the festive period -
Despite the government's response to Omicron, which in our view was overly cautious and caused a substantial loss of trade during the important festive season, the Board remains confident of achieving its full year expectations assuming that the Covid landscape does not significantly deteriorate.
We are encouraged by the strong performance pre Christmas and yesterday's welcome announcement from the Government about easing all restrictions but are nonetheless alert to and monitoring closely the inflationary pressures building across all elements of the supply chain and are taking action to mitigate these where possible.
Disruption over the festive period wiped out the previously strong growth from July-Nov, which is a pity, but a problem for the whole sector -
As previously reported, LFL sales for the majority of the half, from 19 July 2021, when restrictions were relaxed in England, to 13 November were very strong at +14% versus the comparable period two years ago. Overall, 2-year LFL sales for the period from 19 July 2021 to 1 January 2022 remained positive at +1.4%, with the business performing as well as could be anticipated given the additional restrictions imposed on our guests in the Christmas period…
LFL sales for the 6 week period ending 1 January were -23% when compared with the same period 2 years ago, the last unaffected Christmas period.
Corporate bookings - as other operators have indicated, covid disruption caused the cancellation of many office parties. However, as Nightcap (LON:NGHT) said recently, many are being rescheduled, which should give a boost to spring 2022 trading -
The impact of the Government actions was most felt in the cancellation of office parties. Pre Booked Revenue, an indicator of Corporate Christmas parties, was -39% for the 6 week period to the 1st January 2022 when compared to 2019/20. However, the total number of bookings during the 6 week period was at +19% highlighting that our young guest base were still keen to go out and enjoy themselves. Both of these metrics were significantly higher earlier in December before the Omicron variant and negative government messaging took hold. Pleasingly, many of the corporate parties have already been rebooked for early in 2022.
Net cash was £4.7m as at 19 Jan 2022 - very healthy indeed, so the company is fully funded to refurbish existing sites, and open new ones. It has large unused borrowing facilities too, so tons of liquidity for expansion - at a time when they should be spoilt for choice when the rent moratorium ends, and lots of vacant sites become available on attractive rents.
Refurbishments - 6 have been done already, “pleased with their early performance”, and 13 more to be done over the next 5 months to year end 30 June 2022. That means 28% of the bars being refurbished over a 6 month period - which should drive decent revenue & profit growth.
Too many bars became tatty, and this was the main problem RBG experienced before the pandemic - previous management focused too much on short term cashflow, and opening new sites, instead of properly maintaining the existing sites.
Late night bars have to be in tip-top condition, or the customers drift away to fancier competitors. Hence I see the refurb programme this year as being key to restoring shareholder value.
On my way home from mystery dining at TGI Fridays, I always check on Bournemouth’s “Revs”, and am pleased to see it is being refurbished as we speak. I’ll mystery drink the refurbished site once it opens, and Dry January is over. Peering through the window, work is underway, and I could see a builder wandering around -

.
A refurb should put at least 10% onto LFL sales, so that should be enough to mop up inflationary pressures.
Diary date - 1 March 2022 for Interims to 1 Jan 2022.
My opinion - the hospitality sector has a lot of cost headwinds coming through - higher wages, general cost inflation on ingredients, VAT returning to 20% (although limited impact on wet-led operators like RBG), and business rates resuming.
On the positive side, RBG has restructured its estate, ditching the loss-making sites, securing rent reductions on a consensual basis, and a CVA to eliminate the handful of landlords that refused to co-operate. A deal was also done to ditch the onerous 25-year leases on closed & loss-making sites. So it goes into the post-pandemic period with a clean estate, and with 19 refurbishments underway between now and June 2022, everything is lined up to deliver very good trading updates in 2022.
There are also deferred Xmas parties mentioned today, and pent-up demand, likely to provide months of positive, and highly profitable trading.
Forecasts are currently set ridiculously low (around breakeven) for FY 6/2022, so I’m expecting them to smash forecasts.
New sites, and new formats are also being created, e.g. the Founders & Co format which has been trialled in Swansea. There’s another new format, a retro-gaming themed bar that is in the pipeline.
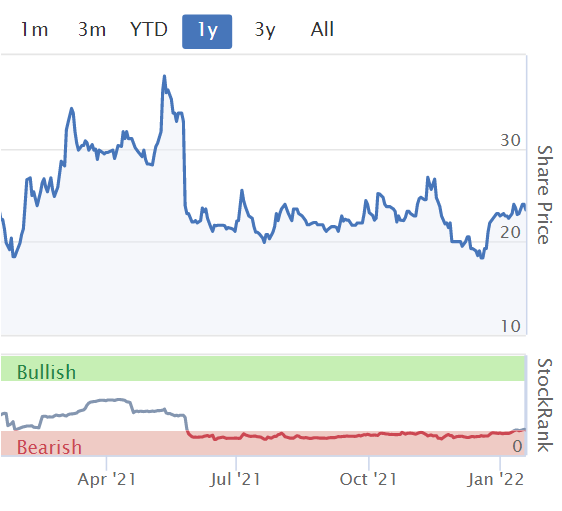
Obviously the last 2-3 years have been really painful for anyone who just held this share, and did nothing. Whereas loading up at the lows proved lucrative. So maybe it’s more a share to trade, than buy & hold?
My price target remains 30-40p (I sold in that range previously), so at 24p currently, the share seems attractive to me. Everything is now sorted out, and it’s set up really well to generate good profits again, in my view. Both the CEO & CFO are highly regarded, hands-on, experienced, capable people.
There are other expanding bar groups, but they’re too expensive (e.g. Nightcap (LON:NGHT) ) with a premium for newness. Whereas RBG has a discount due to historic problems. If like me, you think the problems have been resolved, then it could be a good recovery share.
The re-opening trade is a key investing focus for me at the moment, now we seem to be genuinely at the end of the pandemic. There could still be very good upside on shares which have not yet properly priced-in a full recovery in profits. I see lots of opportunities out there at the moment, and RBG is one of them.
The chart won't get back to previous highs, because the share count has risen from 50m pre-pandemic, to 230m now. But obviously I have a much larger number of shares personally now, so only need a rise to 30-40p to recoup previous losses. Averaging down does work sometimes, if the fundamentals & outlook justify buying more shares. It's mindless averaging down that is disastrous - i.e. ignoring poor fundamentals, anchoring to the previous highs, and buying more for emotional, not rational reasons. Time will tell, but I think RBG looks like a sensible average down, not a mindless one! We'll see.
.
.
Gear4music Holdings (LON:G4M) (I hold)
690p (per market open) - mkt cap £145m
I should add (for full disclosure) that I’ve down-sized my G4M position from medium to small. That was partly due to another large founder CEO share sale, and also worries about the cost of online marketing, and supply chain. It’s a good company though, so I’ll be looking to increase my position size potentially in future, depending on newsflow. I can’t afford any more profit warnings, hence down-sized a few things late last year, also pushed by margin calls on my geared account, as mentioned previously.
G4M has been very open about benefiting in particular from lockdown 1, and it managed investor expectations well, with broker forecasts showing a big reduction in this year’s forecast profits early on. Hence the share price has held up quite well, since expectations were managed realistically, as opposed to hitting us with profit warnings, as other eCommerce businesses have done.
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces a trading update for the three months to 31 December 2021.
The current financial year ends 31 March 2022, so today’s update is for Q3 (Oct-Dec 2021).
Q3 revenues - down 10% on 2020, but up 17% on 2019 (pre pandemic) - OK I suppose, but not madly exciting.
Geographic split is striking - Q3 revenues up 13% for the core UK market, but down -27% for Europe & RoW. The commentary explains this is due to “short-term Brexit-related challenges”, which surprises me given that G4M has had 2 distribution centres in the EU for several years now (Sweden & Germany). This issue has been mentioned before, so is nothing new. A fix is already happening, which could explain why the share price has not been punished for disappointing EU sales -
New European distribution centres are scaling up well to address post-Brexit challenges, which as previously reported have impacted European sales…
We are continuing to make good progress in scaling up our new European distribution centres in Ireland and Spain to strengthen our European customer proposition, and we expect European revenues to regain momentum as we head into FY23.
Gross margin - is just as important as sales growth, but often overlooked by investors. Note that the 2-year comparison is sales +17%, but gross profit +27%.
Gross margin of 28.4% is lower than last year (29.9%), but up on 2-years ago (26.2%). The company’s turnaround has been mainly based on improving gross margins, instead of chasing market share at any price. That’s the right strategy.
Profit guidance - annoyingly, the company quotes EBITDA, like so many other companies, which is not real profit. Note that £12.0m EBITDA becomes c.£5.7m adj PBT, so a big difference there. Hence why I dislike EBITDA so much. It's one measure of profitability, and does have some uses, but it shouldn't be the only profit measure disclosed in trading updates.
G4M does provide a footnote on market expectations though, which is important, and gets a round of applause from the SCVR -
FY22 EBITDA continues to be in-line with consensus market expectations*
* Gear4music believes that consensus market expectations for the year ending 31 March 2022 are currently revenue of £149.2 million and EBITDA of £12.0 million.
Summary/Outlook - there’s enough positive in here to keep me interested -
"We are pleased to report that financial performance during the FY22 peak seasonal trading period was in line with the Board's expectations, demonstrating good progress when compared with the same period in FY20.
UK sales growth continued to be robust against what were exceptional revenues last year, and as previously reported, European growth has been restricted due to short term Brexit related challenges. We are continuing to make good progress in scaling up our new European distribution centres in Ireland and Spain to strengthen our European customer proposition, and we expect European revenues to regain momentum as we head into FY23.
Following the successful acquisition of AV Distribution Ltd in December 2021, we were very pleased to have successfully launched AV.com as scheduled on 13 January 2022. AV.com is currently focused on retailing Home Cinema and HiFi equipment and accessories and significantly increases our addressable market size.
We have a strong pipeline of new products, e-commerce system developments and new website features due to be launched throughout FY23, and as such, we remain confident in our long-term profitable growth strategy."
Broker updates - we’ve got Singers and Progressive updating us today, many thanks.
FY 3/2022 EPS forecast is only 18.6p, way down on prior year’s lockdown-boosted 60.4p
FY 3/2023 EPS forecast is good growth, to 29.8p - a PER of 23 times, which looks about right to me, in an era where eCommerce companies are no longer attracting a large premium valuation.
My opinion - the disparity between UK sales growth, and EU sales contraction makes me wonder if UK sales might be gaining from a reduction in European competitors in the UK market? Musicians tell me that there are delays on product ordered from market leader Thomann (Germany), so they now order everything from G4M instead, for reliable next day delivery. The same could be working against G4M in Europe. So that would explain why the UK is doing so much better than Europe, maybe?
If European growth does resume in the new financial year (starting in April), then that could be a catalyst for the share price to rise. Plus the acquisition and relaunch of AV.com, bolts on more business.
In the meantime though, overall, I think the current share price looks about right, considering risk:reward.
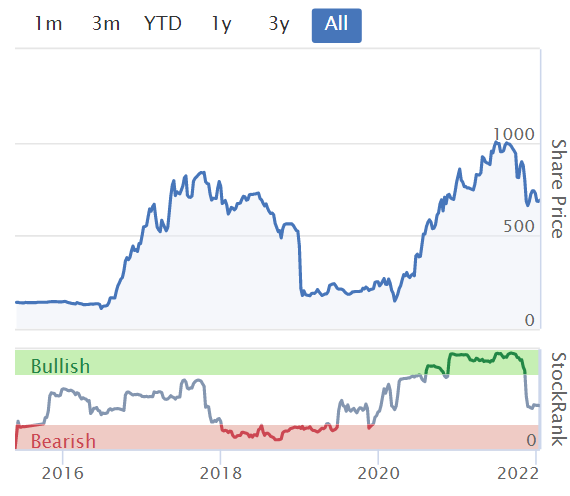
It's certainly been a rollercoaster ride since G4M listed in June 2015. Are we plummeting at high speed on the current downward leg, or about to pull several G's as the rollercoaster does an abrupt turn upwards? Or maybe coasting towards a gentler plateau, and the restraining bar lifting? Do we stay on, and go around again? (OK that's stretching the analogy too far).
.
.
Superdry (LON:SDRY)
240p (down 3% at 10:34) - market cap £198m
The share price here is all over the place today - earlier it was up 8%, now it’s down 3%.
I’ll try to be impartial, but my existing view is that the company’s management have been trumpeting a turnaround which has so far delivered absolutely nothing in the reported numbers.
They’ve ramped it like an old hand on advfn, saying net margins will be better than ever. I don’t see anything at all to justify their optimism in previous reported numbers, so let’s have a look and see if the green shoots (facts, not aspirations) are coming through in today’s numbers?
Remember SDRY was in a mess before the pandemic struck, and has a legacy store estate which is a heavy burden.
Superdry announces its Interim results covering the 26-week period from 25 April 2021 to 23 October 2021 ("1H 22") and a trading update covering the 11-week period from 24 October 2021 to 8 January 2022. Where relevant, given the disruption to trading from Covid-19 and to provide more meaningful analysis, we have provided comparisons on a two-year basis.
PR summary -
Clear signs of brand and financial recovery
Oh yeah? I’ll be the judge of that, given the track record of overly bullish commentary.
Revenues - no sign of recovery here, £277.2m in H1 this time, down 2% on H1 LY, and down 25% on H1 2 years ago.
Stores revenue in H1 was up 21.5% on LY, and Ecommerce was down a very disappointing -30% - although this is explained as being due to more full price sales, instead of discounting. It’s still really poor though.
Gross margin - a good improvement against H1 last year, at 55.2% (LY H1: 51.7%). Getting close to pre-pandemic 56.3%. The commentary says sell-through was good, and there was no need for an end of season sale, which bolsters the company’s credibility in focusing on full price sales. My worry was that they would seek full price sales, but then be forced to discount to clear slow-moving stock at season end. I’m encouraged that has not come about.
Note that the stores gross margin is exceptionally high, at 71.7%, but further on in the commentary, it says stores gross margin is 69.6%, so not sure what the difference is, but they're in the same ballpark - very high.
Still loss-making, despite business rates relief, at £(2.8)m - better than the more heavily disrupted H1 LY loss of £(10.6)m
Note that the loss would have been worse by £8.1m due to a £2.0m gain from releasing a provision against trade receivables, and a £6.1m “Other gains” - what’s that for, I wonder? Possibly releasing lease provisions? These items were not adjusted out. Ah here we are, it is to do with leases -
Other gains and losses reflect modifications on IFRS 16 leases and royalty income and this net credit has reduced £(2.0)m year-on-year to £6.1m.
Whereas £6.8m gains on forward contracts (forex?) & £0.6m gain from founder share plan, were adjusted out. Hence the statutory pre-tax result was a £4.0m profit.
Net debt is negligible at £3.9m, but the net cash from last year has gone, as I suspected, as it came about from stretching creditors last year.
Current trading - this covers the peak trading period, and looks good - in particular a very strong improvement in stores performance -

.
Outlook - reassuring I think -
Our performance over the peak trading period has given us confidence that we will achieve current market expectations for FY22 adjusted PBT.
In line with the rest of the sector, we expect to be impacted by inflationary cost pressures. However, we expect to fully offset these headwinds through further gross margin improvement (via a reducing mark-down mix), together with some price realignments in selected categories and markets.
Annoyingly, I can’t find any broker notes. Stockopedia shows £670m revenues, and a tiny net (after tax) profit of £7m for FY4/2022. That’s 10.4p EPS.
With £277m revenues in H1, this implies £393m revenues in H2, a 42% uplift.
There’s a neat function here on Stockopedia, which splits historic results into H1 & H2. Pre-pandemic, SDRY achieved an H2 uplift over H1 of +17% in FY 4/2018, and +10% in FY 4/2019. This shows that the +42% forecast uplift this year for H2 over H1 seems very ambitious, and I don’t imagine that uplift is achievable.
Given management over-optimism in the past, I remain to be convinced that it actually will hit forecasts for FY 4/2022. There again, a loss of £(2.8)m in the seasonally slower H1, and FY forecast of £7.0m post tax, so maybe £9m pre-tax, needs a profit of £11.8m in the busier H2, so that’s possible I suppose. Maybe forecasts are achievable? The jury is out.
Going concern note - worth a read. The company gives itself a clean bill of health for going concern (12 months from signing the accounts is standard), but it’s would be sailing close to the wind in 2022 if trading were to deteriorate-
Under the reverse stress test, which tests for the breakeven point against our borrowing facilities, the October 2022 (Q2 23) covenant test would breach first. However, management considers the revenue shortfall required to cause this breach to be remote. The directors are confident that under the mitigated reverse stress test there is sufficient liquidity headroom over the going concern period.
If this scenario was to occur, management would approach lenders for a covenant waiver. Whilst there would be no guarantee that such a waiver would be made available, in making their assessment management notes that it currently has a good relationship with the Group's lenders and has held positive discussions throughout the year. These lenders have been made aware of all key inputs into the Base Case Plan, as well as the implications of the short-term disruption, and have agreed to re-gear the covenants on several occasions, to reflect the unforeseen duration and magnitude of the impact from Covid-19.
Balance sheet - overall it looks OK, not financially distressed.
The stand-out items are the large lease liabilities, which dwarf the Right of Use Asset, indicating that the company still has a lot of heavily loss-making physical stores, which will take time to dispose of.
Working capital has deteriorated, but not disastrously - a year ago SDRY had net current assets of £77.5m, and a current ratio of 1.32 - reasonably healthy for a retailer/wholesaler. A year later, at end Oct 2021, net current assets had reduced to £51.3m, a ratio of 1.19
My opinion - having had a good rummage through these figures, for the first time, I can see in the numbers some evidence that a turnaround is starting.
Although to keep things in perspective, even if the company does meet current market expectations, that’s only for a tiny profit, and I reckon all of that profit is probably coming from releasing onerous lease provisions through IFRS 16. That’s something to carefully check for all retailers at the moment - as they slashed the Right of Use Asset during the pandemic (effectively a provision against future losses), they are now releasing some of those provisions as trading improves. It’s easy to bury that (non-cash) benefit in the reported numbers, and not many people will notice!
So as things stand, I reckon SDRY is operating around breakeven on a cashflow basis for FY 4/2022.
The question is, can it improve on that performance? There are big headwinds coming - 6.5% minimum wage increase from April 2022, and business rates relief disappearing. So SDRY will need to improve sales, and gross margins, to just mop up those additional costs.
So far, returning management seem to have stabilised things, and halted the decline. It remains to be seen if they can make Superdry decently profitable again? If you think they can, then at £198m market cap, it could be worth a punt.
Overall then, I’d say my stance has moved from negative, to neutral, as the fundamentals seem to be improving.
EDIT: The InvestorMeetCompany presentation by Julian Dunkerton today was hugely impressive! I can see how persuasive & convincing he is - well worth watching the recording, as there's lots of useful background about Superdry in his comments. Think I might have to dip my toe in here, with a small initial purchase. End of edit.
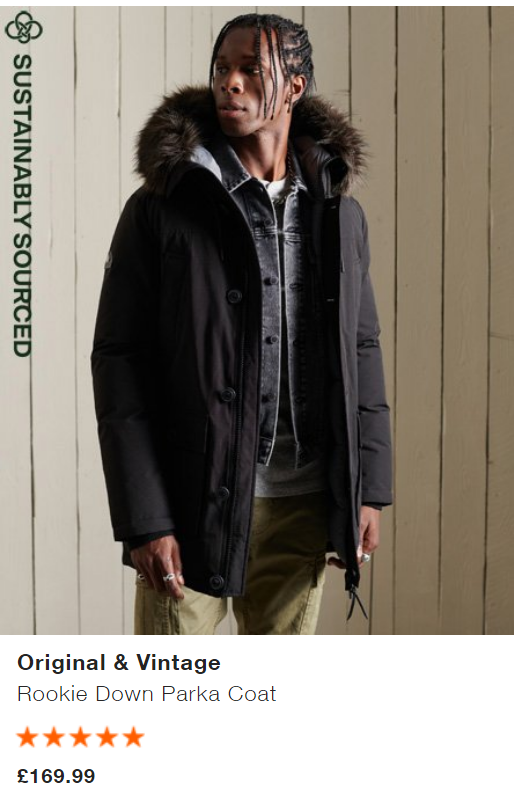
If you're prepared to pay £169.99 for a Parka coat (below), then would (say) a 5% price rise to £178.50 deter you from buying it? I'd say probably not. That's the advantage of a brand with high margins - they're already charging almost 4 times cost, so the customer wants the product a lot, is not value-focused, and is prepared to pay up. Hence I suspect SDRY might be able to push through price rises, if they get the product designs right.
There are 10 customer reviews, all 5 star.
.
Jack's section
Wincanton (LON:WIN)
Share price: 376.7p (+7.93%)
Shares in issue: 124,543,670
Market cap: £469.2m
Wincanton delivers strong trading performance; upgrade to full-year profit
Strong demand across all four business sectors, with high demand for its services and revenue growth of 15% in the quarter (14% excluding acquisitions and disposals). Given the result, and greater certainty around cost pressures, Wincanton now expects to exceed current market expectations.
Digital and eFulfilment revenue increased by 51%, thanks in part to the acquisition of Cygnia. Excluding Cygnia, sector revenue rose by 22%. Wincanton's Customer Fulfilment Centre for Waitrose.com executed the successful delivery of its first Christmas peak trading period. The two-person home delivery business contributed another quarter of strong performance, although volumes were down slightly.
The integration of the Cygnia business is progressing well, although online volumes for some customers were impacted by a higher-than-expected proportion of high street sales around Black Friday.
Operations ran smoothly in the group’s Grocery and Consumer sector, delivering 25 million cases of food and drink in the week before Christmas. Revenue was up 19%. General Merchandise sector revenue grew by 9%.
Wincanton's Public and Industrial sector revenue rose 5%, primarily driven by the growth of Public Sector business.
Driver and labour shortages are a challenge but have been managed well with no disruption to operations. The group has secured some ‘significant contract wins and extensions’ as well, including a new contract with the Department for Environment, Food and Rural Affairs (DEFRA).
Wincanton is also extending its partnership with DFS to manage deliveries that go directly from suppliers to customer. New services for The Range, MGA Entertainment, Lakeland and Department of Health and Social Care (DHSC) were implemented in the period, as the group saw strong take-up for its collaborative warehousing services.
It is also on track to deliver its previously announced five-year contract with Primark for the provision of transport services to all its UK stores, commencing in February.
Conclusion
Focusing solely on trading, the shares seem to be the wrong price. Wincanton is ahead of expectations, is successfully managing challenges, and is winning new contracts with big customers including the government. The latter two points suggest to me a competent management team.
All this for a forecast rolling PER of 9.7x (after this morning's rise).

Debt ex-leases has fallen somewhat (the financial summary figure adds in £94.3m of capital leases in FY20 and £113m in FY21). Here’s long term debt ex-leases.

Net tangible asset value is still negative though, with £469m of tangible assets set against £563m of total liabilities resulting in -£94m. And there’s also a pension scheme to consider, so overall the financial health leaves a little to be desired.
On that last point though, an improved actuarial valuation would reduce cash contributions in future. In general, deficits are improving at the moment so that is a potential boost (although for now it’s a drain on cash)
The financial health remains an important issue to consider, but I can’t fault the operational performance here. Good control over costs, a raft of new contract wins and extensions, growth across all business segments, and profit ahead of expectations, with a single digit PE ratio.
Wickes (LON:WIX)
Share price: 215.8p (-1.46%)
Shares in issue: 259,637,998
Market cap: £560.3m
(I hold)
Wickes is a spinoff from Travis Perkins. Anyone that’s read One Up on Wall Street by Peter Lynch will know will know that these can be attractive opportunities, with newly incentivised management and greater freedom now decisions are not tied to the agenda of a larger corporation.
The shares look cheap on a forecast PER of 8.9x, and the management team sounds competent, so I’ve taken a smaller holding here to see how it plays out. It’s a newer listing though and I’m keeping the position flexible.

Note the high levels of net debt on the StockReport - likely responsible for one of the two ‘Z-Score’ fails. This is mostly capital leases, so ex-leases the group was actually around £127m net cash as of June 26th 2021, although this is set to come down in the second half due to a combination of capex, IT separation costs, and dividend payments.
Q4 Trading Update for the 13 weeks to 25 December
As expected, Core sales moderated against the toughest comparatives from 2020, but were strongly ahead on a two-year basis. We continue to expect to report adjusted PBT* of no less than £83m.
- Core Q4 sales -6.8% year-on-year, +35.7% over two years,
- Do It For Me (DIFM) sales +1.6%, -13.5% over two years,
- Total sales -5%, +14% over two years.
FY figures show Core sales up 14.2% (one year) and up 35.7% (two years). DIFM is +9.7% and -20.9%, meaning Total sales are +13.3% and +18.9%.
Core sales in Q4 were supported by continued strong performance in local trade, where home renovations continue to drive robust order books for trade customers. TradePro membership and associated revenue continue to grow strongly, driven by Wickes’ digital capability.
DIFM delivered sales were strong in October and November, as we progressed through the elevated order book, but weakened in December from a higher incidence of Covid disruption and self-isolation ahead of the holiday period. As a result, the DIFM year-end order book has more than doubled on a two year basis. This, plus an encouraging lead and order profile from the winter sale, will support DIFM sales in the current year.
The group launched its DIY app successfully in November, with strong conversion rates. The Google Play Store rating is 3.9 from 15 reviews, with downloads in excess of 10,000. A respectable start, although I note the Wickes TradePro app has had its fair share of criticism and has a lower rating of 3.5 compared to others such as B&Q (4.4) and Toolstation (4.7). So perhaps more work needs to be done here.
Inventory levels have increased as a result of cost price inflation and the recovery of stock levels from the prior year. Wickes has also invested to protect the business against the risk of any future supply chain disruption.
Refitted stores continue to perform very well, with a strong returns profile as we work through the estate and we therefore plan to accelerate the pace of major store refits from 2022 onwards. We will provide further detail on our investment and broader capital structure as part of full year reporting.
The group announces a new CFO today as well: Mark George, to replace Julie Wirth who plans to retire. He’s the CFO of The Gym Group, also reporting today.
Conclusion
This is a recent demerger on a modest rating with a fairly low risk growth opportunity in the form of ongoing store refittings. That won’t continue indefinitely, but it could be a nice tailwind over the next couple of years.
Q4 sales are down against tough comps, but the group reaffirms its FY profit before tax guidance of not less than £83m. Stockopedia shows fluctuations in the tax rate, from 45% in FY19 to 9% in FY20. Assuming a notional 20% charge this year would give a minimum profit after tax of £66.4m and earnings per share of 25.6p, which is in line with the consensus forecast.
This is set to fall slightly the following year, but there has been a general rising trend in consensus estimates.

Wickes remains a bit of an unknown entity as a listed company, so the jury’s out for now, and for all its talk of a strong market position this is a competitive sector with some very good operators. Management has referred to the ‘dynamic’ market environment over the Covid period, so it’s a particularly hard time to understand how various players are performing on an underlying basis.
Has there been a temporary, unsustainable revenue boost over the Covid period? I think that’s possible, as is a more sustainable opportunity should people end up working from home for longer than expected. Rising costs such as wage inflation could potentially become an issue though.
Ultimately I come back to the valuation, which is undemanding. If the group shows it can defend and grow market share or revenue then it might not take too much for the market to rerate the stock.
Time Finance (LON:TIME)
Share price: 25p (-0.99%)
Shares in issue: 92,512,704
Market cap: £23.1m
This was pitched by twitter user JimTech at last night’s StockSlam as a value play. That video should be out later today. I’ll link to it later so do check it out if you want a three-minute ‘slam’ of the company from an existing shareholder.
It’s very small, a micro cap, so won’t appeal to all, but the value is pretty clear.

Time Finance's core strategy is to focus on providing or arranging funding finance for UK SMEs, primarily from its own book. There are four divisions: Asset Finance, Invoice Finance, Vehicle Finance, and Loan Finance.
Half year results for the six months ended 30 November 2021
- Origination +3% to £58.1m,
- Revenue +1% to £11.8m,
- Gross profit +3% to £7.6m,
- Profit before tax +1% to £7.6m,
- Net assets up from £57.1m to £58.2m (against a market cap of around £24m),
- Net tangible assets up from £28.4m to £29.6m,
- Net deals in arrears down 26% to 9% of the gross lending book, with no deals in forbearance.
Covid is still having an impact on trading activity and normal business has yet to be fully resumed. This is hitting the non-core brokerage arms more.
Investments have been made in sales resource across Asset, Invoice Finance and Commercial Loans. The lending portfolio performance was better than pre-pandemic levels and continues to improve. UK SMEs have remained resilient during the pandemic, with borrowers missing payments reducing.
The group had £9.6m of cash, cash equivalents and convertible 'paper' at period end, leaving it well placed to capitalise on future opportunities.
Conclusion
Again, a stock that doesn’t have to shoot the lights out in order to justify a rerating. Covid is still having an impact but trading figures are modestly positive. Time Finance is listed as a ‘Super Stock’, but it’s probably more ‘Contrarian’ in spirit.
It’s all about the value here, and whether or not the new CEO (appointed back in June 2021, and with previous experience working at the company) can arrest what has been a long, slow share price decline.

Looking back, I actually wrote up some notes of a meeting with the CEO (Ed Rimmer) back in September 2021, which are worth going over.
Companies change all the time, and investment cases improve and deteriorate. Time Finance could well be getting its house in order and so it is worth looking at more closely in my view. Drawing a line under the ‘buy and build’ strategy to focus more on organic growth strikes me as a positive step.
I think shares could potentially double if we see sustained signs of improvement. Things do seem to be slowly moving in the right direction, and the valuation is supported by £28.4m of net tangible assets. Meanwhile, debt in arrears has declined and there are no deals in forbearance.
Equity Development follows the company and calculates a fundamental valuation of 45p per share for the group. Here are the notes. We’re going through a busy patch at the SCVR with lots of updates, so heading over to ED to see what a dedicated Time Finance equity analyst makes of the stock is a good move I think, if the valuation piques your interest.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
We were engulfed by a huge number of trading updates today, and I had several webinars to listen to this afternoon, so we didn't get round to covering many of the in line updates, sorry about that.
Here's today's list -
The boss of Superdry Superdry (LON:SDRY) has said that customers can expect price rises and no sales in its shops as the business tries to combat the increased costs it is facing due to runaway inflation.
Julian Dunkerton told the PA news agency that the company will hike prices by around 2% due to rising costs.
But it will also be able to offset the cost hikes by slashing the number of items the retailer has on sale, something that has been part of the Superdry plan since before Covid-19.
“No stores will ever have a sale again … and discounting is limited to a shorter period online and very limited,” Mr Dunkerton said.
“So patently we are less affected because of that margin shift internally by the headwinds of inflation.
“We’re an affordable brand and we will remain so, and it’s very important that we do.”
Superdry (LON:SDRY)
Great comments Paul cheers - this one has been on the knife edge since Tyrion oops i mean Dinkerton has come back on the scene. To date the action plan has not really borne any fruit. However superdy seem to have got it so wrong prior to him coming back and the leases must be such a noose around their neck its a not a complete surprise its such a long haul back (if they ever make it back - jury must still be out) . What is extra frustrating is that before things went wrong the wholesale side of things was going great guns - i thought that side of things would have bounced back quickly - perhaps they have the covid excuse there if their customers shops have ben closed - so maybe there is some hidden potential there. Personally i am hanging on through laziness more than anything else but my confidence they will regain past glories is very low - i do think the worldwide brand does have the potential to be lucrative though.
I haven't read the results, but saw the BBC news article that they're going to reduce promotional activity, removing all sale from stores, and reduce the discounting online.
This usually infers that management believe the Brand is in danger. Many a C-Suite have been tempted to pull the discount/sales lever often, and Superdry (LON:SDRY) have been guilty of that for the past few years. Almost perpetually on discount. However, this damages brand equity; and you also are then pressured to lower clothing quality, because margins are always never at full-fat.
I think maintaining quality, and staying full-price is a good strategy for Superdry long-term. Bring them back into the mid-premium market, where they originally saw good success, rather than the mid-bargain market they seem to find themselves in now. Too many others doing the same thing, and not very profitable, especially given their huge expensive store estate (that was leased with the mid-premium strategy in mind. Think expensive Oxford and Regent street stores, and airport concessions).
However, increasing prices and reducing discounting.... hardly good for short term sales volumes and revenues. Customer brand perception takes quarters, if not years, to shift. Also when trying to re-acquire customer segments (eg mid-premium) that have abandoned the brand. For that reason, I think the next few quarters of trading is going to struggle; and there will be time to pick up the shares cheaply from jaded, frustrated shareholders unwilling to wait. But I see tentative shoots that Dunkerton is making the right decisions for Superdry, medium-long term.
I suspect Dunkerton has an eye of doing this Brand turnaround, in time for a blockbuster 2022 Christmas...
Took a good look at my local Superdry store yesterday. Looked like a cross between a jumble sale and Sports Direct. Stock piled high and didn't seem to be anything special interms of quality or design. Nothing new to catch the eye. Main point though, was that there were absolutely no customers in a very big store.
Heavily branded clothes are now dated. The Superdry brand is tired and has lost its mojo. The core customers of yesterday have outgrown the brand. They are now 30 and 40 somethings. Superdry has no appeal to the current generation who are buying clothes. In short, I think it is dead in the water.
Re: Adobe. I think they just tried to charge me to rotate a pdf from horizontal to vertical. Ridiculous.
I do believe Adobe are living on borrowed time - they are generating quite a bit of ill feeling with their price hikes from their user base, certainly at the smaller end of the spectrum (photographers, graphic designers etc), if not the larger corporates. Anecdotally I hear of people being prompted to investigate alternatives.
It is not difficult to do much (but not yet all) that Photoshop/Lightroom does with freeware (e.g. GIMP). More reasonably priced competitors such as Affinity are emerging as well to reclaim the "one-off purchase" value territory. Of course it is a mere annoyance to experienced users who value the speed of familiarity, but younger generations coming through will have started on cheaper alternatives and realise they aren't that bad.
There is a limit to what functionality is left to add - the software is quite mature. There are also complaints about the performance of some Adobe products - they are getting sluggish and re-coding from scratch is a major expense for no additional revenue.
Even Microsoft isn't immune - I do keep an eye on Google sheets as a challenger to Excel, now that they've added scripting it starts to get interesting, and Google sheets does some things far better than Excel. Compatibility issues are becoming less and less of a barrier - I now regularly mix & match from both, which is not what I was expecting only a year or two ago.
However, the timeline for change here is years, not months.
Hi Paul
I don't think the topic of EBITDA vs PBT is straightforward and really needs to be looked at on a company by company basis.
1) A company that has invested into growth can be punished at a PBT level and the PE ratio may look high despite it starting to generate strong cash profitability. If investors wait to get onboard until the depreciation disappears and the PE looks good value then they have usually missed the growth. A good example of this is Tremor International (LON:TRMR) who are trading on roughly 4* cash profitability or EBITDA. But here they have a massive cash pile (so positive interest) and no debt. So really the sunk cost invested capital causing the depreciation should be of little interest to current shareholders as all that matters is the cash profit going forward.
2) Other companies use EBITDA to mask high debt costs and corresponding interest charges. This is of course a sleight of hand as the interest costs are a very real drag on the cash profitability of the business and therefore the forward value to shareholders and this will appear in the PBT number.
3) and then other companies will invest but amortise as much as they possibly can to appear to have much better PBT now but are really mortgaging the future where there may be no guarantee of that investment generating the right returns. Cashflow should catch this.
As investors what we really want to find is a company that has already invested and is beginning to see the fruits of that investment. Ie The invested capital hasn't been wasted on frivolous projects but is now generating expected returns. That gives us comfort that management have a good handle on how to generate appropriate returns from invested capital. A PBT only approach will probably get you in at the wrong time whereas an EBITDA approach is more likely to see you catch the wave at the right point.
I always try and take an EBITDA number in conjunction with the PBT and work out which scenario I am seeing. I then want to see how that is translating to actual cashflow so that I can try and avoid the scenario 3's of this world.
The relative shifts in P/E vs EV/EBITDA can also catch people out - if the share price doubles the P/E doubles, no so with EV/EBITDA if debt is a large proportion of the EV....
Paul - will you be commenting on Smiths News (LON:SNWS)
Hi TheGob (LOL!! :-)
Paul - will you be commenting on Smiths News (LON:SNWS)
Run out of time today unfortunately. But I did read the announcement (business update) and it all looks fine - in line with expectations, and confirming the turnaround case I think. So reassuring, rather than earth-shattering!
Regards, Paul.
thanks
should have said TheGob! is my nickname from my days as a football commentator / terrace God
Really excellent ramble this morning.
Surprised that Time Finance (LON:TIME) was not picked up by anyone today, including MrContrarian's summary! It's a value share, as well as financial services, which is coming into vogue these days.
My highlights from today's HY results:
- COVID impacts still masking growth/recovery, which really only took off halfway through the HY period.
- Deep value. Trading at 25p vs NTAV of 32p
- New strategy of increasing own book loans that started just before COVID, has yet to show the positive impacts due to COVID disruptions, but will over the next 6 months
- Play on value shares macro re-rating. Play on financial services shares macro re-rating.
- If labour shortage / wage increases become quite entrenched, more SMEs will be forced to invest in capital expenditure to automate/replace labour. TIME addressable market will increase.
- Negative is that they might see an uptick in bad debts, as some hospitality SMEs go into administration not having survived the Omicron Christmas. Also rising inflation means more SME in distress as well, over the next year.
There's an IMC presentation today at 1pm.
(I hold)
Time Finance (LON:TIME) (no position)
Hi Boon
Thanks to you and Paul for your thoughts on this one.
I've been a fan of this company in the past though I've continued to remain on the sidelines. After today not much has changed my thinking.
I thought the improvement in gross profits was a big positive, highlighting the reduced bad debts/arrears in H1.
There were, however, a few negatives:
I like seeing this as it gives me an idea of expected return on the cash that has been lent out.
I can make a reasonable guess of this by deducting Total Receivables (from the balance sheet) from the Gross Lending Book (which the company usually states in their commentary.)
However, there is often an adjusting item to make the above calculation work (it's not that big and I've simply assumed it's something to do with bad debts), so without the company explicitly stating what the unearned income is I can't work out the % return they are expecting.
If I forget the unknown adjusted item, it looks like the order book is growing, but that the % returns are decreasing, which obviously wouldn't be good. All guesswork though without an actual Unearned income number.
---
The business continues to look good value and I can see the appeal. Hopefully there will be more granular detail in the full year results.
Cheers
A
Great points on £TIME abtan! I haven't had the time yet today to go through the numbers myself in detail, nor the IMC presentation... will pick them up over the weekend when I've got a bit of time.
My overall sentiment is that the business is OK. Not the highest quality available. But they are decent, and the valuation is abnormally low, so there's potential for a re-rating, either with improving performance and PE expansion, or there's a bit of market story potential to come (FS sector interest, value shares, SMEs investing in capex vs opex).
(I Hold)
Demand for total physical goods has risen 20% since the start of the pandemic?? Not true. The world has been short of demand for 12 years, hence the historically low interest rates over that period. If there was now massive demand with supply unaffected we would see much higher levels of output. Instead the world is still below the pre-pandemic path of GDP. Of course there has been displacement of demand from services to goods as people have spent on their homes instead of going out etc. that's been well understood for a long time now. But there is no strong evidence of excessive aggregate demand (you're right to say that cash has been building up in household bank accounts - that's because people have chosen not to spend it). Meanwhile there is ample evidence of shortages of energy, labour and other capacity as the workforce has been absent.
My expectation is that 2022 will be the big year of reopening when supply will finally become unstuck. If I'm right to say that this is the issue driving inflation, then this will have a big impact and there would be no need for dramatically higher interest rates (2% or so would still be healthy). Instead, if inflation is primarily due to demand not supply, then we will need much higher rates to bring it down and that will be a big problem for stocks. The market would then have to be much lower to be consistent with historical norms.To me, anyone who is fully invested in the stock market but believes inflation is primarily due to excessive demand is thinking inconsistently. It means accepting that we will be stuck with low growth (there is no dramatic improvement in supply available) and that there will be much higher interest rates .... but somehow the stock market will move higher?? I can't see the logic in that but each to their own.
Thank you Paul for your market musing, it was enjoyable and insightful reading!
I was wondering if there was a general concern about Russia and Ukraine or is this just something investors have no control over, think will be localised and will deal with it when or if it happens?
Getbusy (LON:GETB) ( I hold)
Decent update from Getbusy (LON:GETB) today. Things that caught my eye.
Numbers are ahead despite some FX headwinds. Broker numbers look too cautious. Extremely high recurring revenues-94% with little churn. Over 70k customers now, some of whom are older and on cheaper pricing which are now being transitioned to current pricing. Credit Vault a new product has picked up $200k ARR in 6 months, signs that they are looking to monetise their customer base with adjacent revenue streams. Cash is significantly ahead though this looks temporary. They are still investing in the Getbusy product which is gaining traction though perhaps slower than they had initially hoped.
Shares have been dull for a while. Fidelity has been selling and just generally leaning on them for a while so it doesn't feel like they'll race away yet. I think patience will be well rewarded in this one. Its effectively on about 2x sales which is very low for a software business. Management still has significant skin in the game.
Serica Energy (LON:SQZ) Update from this modest company, which now provides 5% of UK gas from the North Sea which, as they point out ,is much greener than imported LNG and beneficial to the UK.
One point that I did not not understand is why they have such large amounts of cash tied up as margin (£115m vs £1.8m).....may investigate further unless anyone can enlighten me ?
re Serica Energy (LON:SQZ), they have historically hedged a part of their production (from memory, about 20%) which would obviously require some margin to be lodged. At current prices, it would be logical for them to have sold forward much more of their production, and I believe margins have been raised in current conditions. Unusual for a trading update to mention cash lodged as margin, but in the circumstances I would have thought it makes sense.
Basically, they have hedged about 15-20% of their production out to 2022/23 in order to protect the downside and ensure capital for investment (they do this on a rolling basis as a matter of course). These hedges range from 31.4p to 57.4p per therm (there's a full list in the presentation), so at the Dec 31st spot price of around 170p per therm they are at a huge loss (they're effectively a short), and hence they have to put up a shed-load of margin.
However, if the gas price does stay this high for the next 18 months until all the hedges expire, then the hedging losses will be massively covered by outsized profit on the remaining 80% of gas production, or alternatively if the price does come back down to nearer the hedge prices then the margin requirement will unwind.
So it's not a bad thing, although clearly it would have been better if they could have hedged at a higher price. However, either in the update or the presentation, they state that they simply couldn't arrange forward puts recently due to the massive volatility.
I think it's an excellent company, I have a fair value based on a DCF of their remaining 62mmboe of reserves of around £3 per share, at a discount rate of 12%, and assuming 125p/therm average this year falling to 75p the next, then 60p, 50p. However, that assumes that they spend £45m on a duster at N.Eigg, and get no return for £25m of intervention capex in Bruce/Keith. So there is clear upside to this if either of those work out.
£SQZ Thanks ISA for that very detailed reply. Your DCF modelling seems very conservative I do not see why prices should fall so far, and as you imply if they can lose that much on selling 20% of their production should make 4 times more on the 80% they have not sold forward !
The return of inflation creates uncertainty. Will inflation retreat once supply chains sort themselves out, or will inflation march on as wage reviews and forward supply chain prices factor in long term price growth? It seems that older, more experienced economists, who actually remember inflation, fear the latter scenario.
Tech mega caps. They generate between 0% and just over 3% tangible surplus for shareholders relative to MCap. That leaves them all between over priced and highly over priced. Further growth from here could be hard to find. The available world is only so big, unless they can generate inter galactic sales.
A GARP investor, really! Well, ScS, GARP for sure, just look at that monster tangible surplus relative to MCap. Bohoo! GARP, you are kidding, right!
The point about inflation being that, in the event of an economic slow down, the Fed and BOE will be very reluctant to return to more QE and ultra low interest rates while inflation remains high, to do so could stoke much higher inflation.
The point about inflation being that, in the event of an economic slow down, the Fed and BOE will be very reluctant to return to more QE and ultra low interest rates while inflation remains high, to do so could stoke much higher inflation.
This is certainly a conundrum even if, bar a supply shock - eg 70s oil crisis - recessions are typically disinflationary. For the current macro regime, tightening is appropriate - but sorting out supply chains and reopening economies so that consumers can spend on services (foreign holidays!) instead of goods should have a more significant impact - if it finally happens. It's a delicate situation.
I agree that if we enter inter a full blown mid strength recession, i.e. not 1981 or 2008/09 but say a 3% to 3.5% GDP fall, then that would likely quash inflation in itself. But, central banks like to dive into QE as growth slows, let alone flatlines of falls. This is the option that will be off the table. Bear in mind we are likely to go through several periods of weakening or potentially flatlining growth before the next real recession. These are the occasions when central banks would have turned to QE bit will no longer have that option.
I do agree with you that the QE get out of jail card since 08/09 will be difficult to play whilst inflation is so high.
I think at some point there will be a global debt reset and the trillions will all be wiped off and then the governments of the west can start running them up all over again from a zero base.
Tangible surplus on tech stocks????
What????
That’s a measure basically for the banking sector ( used a lot during the 2008 financial crisis )
Wrong. Tangible surplus is not the price to book value, but the growth in tangible wealth that the business generates relative to its MCap. If a business does not generate tangible wealth for its shareholders then what exactly is its function?
What?????
Who said anything about price to book value????
You are in another world, one of your own.
It’s like a religious for you this tangible surplus.
Anyway , how much of that was created by Apple over the years?
SEC published its report on GameStop
"The SEC published its report on GameStop $GME this Monday, which focuses on the January 2021 trading activity of GameStop Corp (GME), the most famous of the "meme stocks." Because the meme stock episode raised several questions about market structure, the staff report also provides an overview of the equity and options market structure for individual investors."
A review of the report on Youtube.
I know not a small cap, but having been badly burnt with Thg (LON:THG) over the past few months, after averaging down I’m still around 30% down and the SP is continuing to fall. There seems to be a big gap between broker recommendations, target SP and market view. I’d be very interested in what other holders views are? Is this oversold?
My feeling is that brokers got the original price targets horribly wrong and have been steadily trimming rather than slashing their PTs in order to hide their embarrassment. Even at these levels, THG is slightly overpriced on an EV/revenue basis relative to its projected growth rate and other e-commerce businesses. But all e-commerce is noticeably down on a rotation into value stocks, so there is some hope of recovery, though not to post-float levels IMO.
Not a holder, but the business is based locally to me (Cheshire) and I know some people who are connected both through work and shareholders who query some business practices by the company. I was only discussing this week that selling large sections of their property portfolio to Moulding and then leasing them back now appears to be questionable in the very least.
I also query the intrinsic value of Ingenuity which provides back end services to other big corporations. I remember a late party soon after Softbank made a large investment. To say that managers were surprised in an understatement - reminds me of the goings on with Autonomy and Mike Lynch with HP....
Thg (LON:THG) has unfortunately kept me out of IPO (and Primary Bid) and on advice here wait for a year or two till actually goes into profit. Not great to be negative and a lot of companies will benefit from the inflow of cash but Mr Market needs to be aware - you reap what you sow.
SEC published its report on GameStop
"The SEC published its report on GameStop $GME this Monday, which focuses on the January 2021 trading activity of GameStop Corp (GME), the most famous of the "meme stocks." Because the meme stock episode raised several questions about market structure, the staff report also provides an overview of the equity and options market structure for individual investors."
A review of the report on Youtube.
Hi Paul. Something on the horizon, but not quite a Black Swan, as we sort of know about it, is the Russia/Ukraine situation. This could have ramifications for Europe, given the rather foolish dependency on Europe on Russian Gas Supplies.
I am not going to ramble on about it, because the politics, military, diplomatic, and economic implications are all quite difficult to rationalise, but it broadly falls into the 'not good' pot of potentialities.
I'm looking at Prospex Energy (LON:PXEN) which I hold. Of course, if Nordstream2 is accepted by Germany for its supply of Russian gas then my hopes and those of many others unconnected with Prospex Energy (LON:PXEN) go out of the window.
Battered by Ferrexpo (LON:FXPO) but as so many Russians on the LSE can't see it actually affecting the business long term so holding on. But agree I don't think Putin is going to reverse the tanks anytime soon especially when our interest is did they serve canapes.
Anybody on 5G affecting low visibility flights into airports. Sorry missed it with the expensive hoody coat noise.
Vertu is taking a battering past few days following the rise after excellent update .
Anything untoward ? Or simply some profit taking combined with worries about how long the motor industry bonanza will last ?
Excellent pre-amble Paul. Thank you.
Regards
Michael.
Paul, I think you are spot on with the view that a mixed online/physical store approach may be the winner here. I can’t help think that once people feel able to go out freely it will bring a big boost for the hospitality centre but also retail and especially destination malls. BTW I’m also a big user of TGI and I have to say even during the lockdown periods,when we could go out of course, they seemed to do reasonable business.
Hi Paul, really interesting commentary today. The reason Chinese company DJI is dominating the drone market is down to them selling their units for less than cost to knock out any competition that wouldn’t sell up to them. We lost some fantastic companies and all the competition in the market. DJI completely dominate the market now and churn out new products while running down ‘old’ product not ever for filling the promoted potential… not only that all their drones are collecting and sending masses of data, photos and coordinates probably sound tracks too of every place they’re flown. As someone in the industry I’m totally tied to them. China play by their own rules and have been playing the long game. They’re on track for world domination until we stop valuing everything with our wallets.
Very interesting and readable pre-amble Paul. Very well done, as someone has already commented you must be up early or in bed late, or both!
Regarding this morning's announcements, re-assuring updates from Avingtrans (LON:AVG) and Smiths News (LON:SNWS), both of which I hold. Thank you the overview of Wincanton (LON:WIN) Jack. It is operating in a great space, but some of the financial metrics are unattractive. I can't help thinking that there must be better ways to play the ecommerce space.
All the best
It was a positive surprise to see Luceco (LON:LUCE) reporting in line today (I hold). This is an example, to Paul's earlier point, of the ability to price up. I confess that I totally doubted their ability to offset a whopping £25m of cost inflation, whilst trying to ensure product availability, without impacting demand, and whilst integrating the latest acquisition. It seems I was wrong to doubt management on this - clearly their vertically integrated supply chain has been a differentiator, as well as pricing discipline. They now seem to be lapping very strong comps in 2022 so we will see if they go ex-growth.....or manage to maintain mid-digit organic growth + acquisitions to maintain momentum and gain a potential re-rating.
The US “tech wreck” has certainly been severe for buy and hold investors like me. I’m down 50% on some holdings - and these are companies with positive cash flows, not meme or story stocks. Certainly valuations had got ahead of themselves but falls have been indiscriminate, taking companies with very high cash generation down along with the jam tomorrow names.
Paul, you are spot on with FAAAM; these are the most powerful companies the world has witnessed since Standard Oil, more so I’d wager. So far they’ve held up but a deeper correction cannot be ruled out. I’d be a buyer today but would load up on a bigger correction. I favour Alphabet and Microsoft, which are two of my biggest positions, but Meta (Facebook) is cheap!
Moving down the scale, ignore PERs as the best companies plough cash straight back into growth, look for tech names with high gross margins and cash generation in segments showing powerful growth - that means cyber security, automation and digital transformation. Gross margins indicate the presence of a moat and cash flows are a proxy for profit.
My bank recommends Palo Alto Networks as the stock with the best combination of PER and growth and its fundamentals are only mildly intimidating to value oriented investors. But I also have large positions in ServiceNow, Dynatrace, Crowdstrike, Zscaler, Atlassian and several others. The first two have the most attractive balance of growth, margins, cash generation, profit and moat and are good models for a top tech growth stock. I’ve been rolling several of my riskier holdings in biotech into tech names with these characteristics.
If anyone is interested in researching fundamentals, look for revenue growth of over 25% combined with a cash flow margin over 20%. This is known in software investing as beating the Rule of 40. Any company whose combined score of cash flow margin + revenue growth rate exceeds 40 passes the test of quality. You can have 60% growth with negative 10% cash flow margin and that is still a pass, eg Snowflake, or high cash flow margins with lower growth, eg Adobe. They just need to exceed 40 to be considered top grade.
Alternatively, there are low growth, high free cash flow generators like VMWare and Dropbox - but these are really value stocks that have not sold off. Good for a solid sub 10% annual return and probably a better bet in the short term but not really a way of capitalising on the sell-off. Much more comfortable to research and own but there’s a reason the PER is low.
Very interesting, thanks BnB.
What I didn't realise (until researching it last year) was that apparently expensive mega tech companies (e.g. Amazon) are actually making way more money than the reported figures, because they expense so many growth initiatives for new products, even new verticals. The odd one pays off big time, e.g. most of Amazon's reported profits now come from AWS. But I wonder what else they've got under the radar making loads of profit, that is recycled into funding loss-making speculative growth areas?
Google, Facebook, Microsoft also seem to do this, so the core profit-making businesses might actually be cheap, once growth projects are stripped out. I'm not sure if this is itemised in the accounts, as I'm only at the fairly early stages of researching US companies, focused on reading the quarterly financial reports, which are remarkably easy to digest actually.
Apart from mega-tech, which I think are uniquely good companies, I've also bought some £WGO - which looks a cracking share: PER of 6.2, broker forecasts constantly rising, OK balance sheet, well-known brand name, etc. Downside risk is that sales/profits might fall once pandemic has gone, and people return to international travel? But a PER of 6.2 already factors in a more than halving of profitability. It has a StockRank of 98 too.
Right, back to small caps, I need to get stuck into SDRY's interims next...
Regards, Paul.
Alphabet/Google has a whole series of "other bets", also know as moon-shots, most notable of which is its Waymo autonomous driving business, itself valued at $30bn or so. But you won't want to buy shares in the company that literally (or is that virtually?) forms the gateway to the entire digital universe and which utterly dominates the digital marketing industry with one of the most powerful moats in history because its tangible surplus indicates that it is significantly overvalued. When you look at the egregious PER of 23x for a business that has only managed to grow its astronomical revenues by 400% in the last ten years you can see why Doug is so dismissive. Avoid.
Hi Paul
Welcome on board the £WGO wagon, where I am a fellow holder. I would strongly encourage you to get out there and hire an RV for a month or two - it is another world and I am not aware of anything on the planet that can match the grandeur of the National Parks north & south of Salt Lake City (i.e. Yellowstone down to the Grand Canyon)
I'm not overly concerned about the return of international travel, although of course it will have an impact at the margin. Winnebago (and especially recent acquisition NewMar) are at the "luxury" end of the spectrum. They are not really rentals - people buy them with their retirement pots. The rental end of the market (Four Winds etc) are made by Thor, and if you hire from the likes of Cruise America that is what you will be rattling along in.
The RV market is immense, and people book well ahead to secure their slots in the prime locations. If you want to overnight on the edge of the Grand Canyon then availability is probably next year. It is also a lifestyle - many spend months on the road in their "homes from home", complete with giant TV etc.
When Europeans deride the Americans for not having passports they miss two things - you don't need them on some cruises, and why travel overseas when the US has so much variety to to offer at home (in terms of the great outdoors)?
MC
$WGO, what happened, shares are down over 10% today, can’t see any news. Some other CC stocks such as $BOOT are down heavily as well.
Phew it’s BOOT shares getting the BOOT today not BOOT shares - panic over - back to my fork and peas
BnB I totally agree with you and Paul about FAAAM. They are for the most part astonishing companies.
I started buying Alphabet last year, at an ATH. I don't normally buy at ATH's, but I realised this is a different animal. For me it's not how they are valued now or the growth over the past years, although that is reassuring.
What turned me on to Google is how it is being used by children, who are the future for any company. In Latin America, North America, the UK and so on, Google classroom has become part of many children's daily routine. My children included. They and their school use google drive as the place where they store all their schoolwork. They upload their completed school tests and projects to google drive and give access to the teacher to mark it, and this is at a school which is fully open everyday. They Google when searching the internet. Google is a massive part of their lives and the kids don't think twice that Google is a commercial company, as they have grown to trust it. Which is more than can be said for Facebook. I don't know any child that uses Facebook. It's not of interest to them at all.
The more I looked at Google, the more I liked it. They invest in the future, not just in how they have helped schools and become indispensable for the kids of today, but they are at the forefront of AI, car automation, and so on. If they have to, they buy and support the companies that may provide them with another tentacle, years down the line. These buys tend to be the best in class.
I have a good friend in the USA, who is a lot older than I am. He told me that many years ago he had some excess cash and he asked an old school friend, who was then a stockbroker, where he should put the money and was told to just buy Apple shares. My American friend told me, 'so that is what I did, I just bought Apple shares whenever I could', he bought nothing else. He now has a few modest houses where he spends part of the year, moving from one to the other, with the weather. He sold some Apple shares to buy some of the houses and the dividends provide his very comfortable life style.
Alphabet is my Apple.
Hi Paul,
Thank you for the extended preamble. Your thought provoking comments are a good way to start to the day. You must get up very early, or work late? Its obvious that you enjoy what you do.
Smiths News (LON:SNWS) (I hold) reaffirmed their strategy is on course. No significant new news (excuse the pun) but they are clearly confident going forward and hinted that they are looking for other opportunities.
"we are pursuing a structured exploration and review of organic opportunities that can provide
for new and incremental revenue streams in the longer term."
It's no insignificant achievement to run "one of the world's fastest physical
supply chains" You'd assume there is opportunity here. Perhaps there is synergy with the online/physical store retailers that you talk about above?
I'm interested what you think the following comment might mean for shareholders:
In recognition of this significant progress, in December 2021 the
Company's banking facilities were favourably amended, extending the term by
1.75 years to August 2025 and allowing for a greater share of free cash to be
distributed to shareholders.
Higher dividends going forward is the obvious assumption? Very attractive in an environment where cash holdings are being devalued by inflation.
Have a good day.
Revs8 - I assume you saw the recent RNS confirming that the dividend cap has now been raised to GBP 10m? This is what they refer to. Chunky yield going forward. I hold
Epwin (LON:EPWN)
Solid update today slightly ahead is fine. Their niche has probably been buoyant but they must have had supply chain nightmares like everyone else so great outcome. Expectations for 2022 are for ramp up in profits so more work to do but no reason to believe they are not on track. In some respects if they have standard markups they apply a higher sales price should mean more for the bottom line. Debt down faster than expected so another happy hold here with this company at current prices.
Wow Mr C! So that’s less than 2 minutes for each of the 26! Amazing! Have you done a speed reading course?
Mr C has done a computer programming course (or taught himself), I believe - for which we are all grateful.
I do have a Google spreadsheet to help but it is overwhelmed on the days I need it most, like today. So 90% of it is done manually. I have learnt to skim RNSs very fast.
MR C
I always appreciate your work, thank you.
Richard
Double thanks then, Mr C - we marvel at your skills, benefit from them daily, and chuckle at your barbed observations.
Thank you for your comments on LON:BOTB which, painfully, I still own. You rightly suggest that others may also be in the firing line as a consequence of more expensive online advertising (S4 beneficiary?) but BOTB is also a warning to other 'new world' stocks pumped up to unsustainable multiples which suddenly are perceived to have gone ex-growth. How quickly the party fades, especially on AIM. In the case of BOTB the two aspects that keep me involved are the FCF generating capabilities of the business model and the optionality around use of their customer base. Had they not taken large money off the table at £24 the CEO would surely feel more compelled to communicate - a charm offensive is required to settle this one down. As a regular user of the platform, I would suggest a new game should also be considered - Spot the Ball is getting a bit dull and I don't get any better at it !
Terrific commentary Paul. Good stuff.
Revolution Bars (LON:RBG) in-line trading update today. Nothing unexpected, not a beat & not a disaster. Hopefully Paul may add his views.
D.
The lack of any details on profitability concern me with the £RGB statement.
They give cost inflation a passing mention (the old management were blindsided by this) but without details you wonder whether or not they have it under control.
Call me a sceptic, but I’m reading the lack of details here as a likely future miss on profits.
(No position)
Revolution Bars (LON:RBG)
GrahamF
The lack of any details on profitability concern me with the £RGB statement.
Surely thats covered by the section below - ie they are on target to meet profit expectations.
Despite the government's response to Omicron, which in our view was overly cautious and caused a substantial loss of trade during the important festive season, the Board remains confident of achieving its full year expectations assuming that the Covid landscape does not significantly deteriorate.
Maybe.
But they are not clear. Are they talking about sales revenue expectations or profit expectations or both? To be confident in meeting profit expectations they must have the most recent profit figures available so why not provide them to us?
Revolution Bars (LON:RBG)
Are they talking about sales revenue expectations or profit expectations or both?
I can see why you are worried but i would be amazed , gobsmacked and angry if they are not saying they expect to meet current profit expectations with what they have written. Sales to me are always the minor party in this equation - so i would be confident any company that is simply referencing turnover would at a minimum make it at least half clear that is the case.if its not totally clear the clue would be there thats what they are saying. Always the chance i could be wrong though so please don't put any trust in my comments as you seem to rightly be doing by querying why i am so confident here.
It’s good commentary in line with the general improvement in research coverage at Stocko.