Small Cap Value Report (Thu 22 July 2021) - SOS, KETL, MGP, AUG, BOOM, RST, GOOD

Good morning, it's Paul & Roland here with the SCVR for Thursday. Thank you to Roland for helping out in a really busy week, very much appreciated.
Timing - TBC. We did our best with yesterday's deluge, focusing on what we thought was most interesting. Let's see what happens today.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker.
Agenda -
Paul's Section:
Sosandar (LON:SOS) (I hold) - here are my unstructured notes from yesterday's webinar. Typed up in the glorious sunshine, whilst fending off aggressive herring gulls (pluses and minuses of living in a penthouse in Bournemouth)
Takeover situations - I review 4 companies in bid situations with news out today.
Roland's Section:
Strix (LON:KETL) - this manufacturer of kettle safety controls has some attractive characteristics in my view, but I’m unsure about the quality of growth here.
Medica (LON:MGP) - demand for routine elective scans in hospitals is back to 75% of pre-Covid levels in NHS hospitals. Company says it is “well placed to continue our ambitious growth trajectory”.
Paul's Section
Here’s something I prepared earlier -
Sosandar (LON:SOS)
(I hold)
28p (up 10% yesterday) - mkt cap £62m
My notes from Sosandar webinar yesterday - as usual, these are just my personal notes, not a comprehensive account of the webinar.
Fastest sell-through ever of new products in Q1 (Apr-Jun 2021)
Year-on-year % growth will be highest in Q1 due to soft prior year comps
3rd party sales (J Lewis, Next, MKS) “going from strength to strength”
Q1 gross margin up strongly to 56% (double check this, as I couldn’t see screen closely)
Only selling in the UK, not EU, so no impact from Brexit
Clear path to profitability
Customer loyalty good - repeat orders gone up from 3 times per year, to 4
Product categories - “barely scratched the surface” of new categories, huge opportunity to expand range further
Flex products to customer needs - diverse product (e.g; pivot to casualwear in lockdown)
Concession model - online only sales through the big 3 (J Lewis, Next, M&S) - they approached Sosandar, happy to engage. They distribute the product & handle returns. Revenue & gross profit are the same. There’s a commission charge lower down the P&L which contains all the costs, which the 3rd parties absorb. Profitable from day 1. Close relationship between inventories supplied, and sales by 3rd parties - supply more stock, sales go up, linear relationship. Going to double stock in autumn/winter 2021 - greater depth & breadth of product coming. Selling out v quickly in key styles. Larger order quantities means lower prices from suppliers.
Marketing strategy - refined in the last few years. Split between TV, glossy brochures, and social media. Learnings from data, much lower cost of customer acquisition now. TV drives traffic to website, leads to email signups, which then allow free customer contact. Website conversion rates spike up when glossy brochures land on doormats. Social media is all about engaging with customers & keeping them interested. Email is lifeblood of the business, like a daily newsdesk, producing relevant, daily contact. Very high open & conversion rates for emails.
Celebs/influencers - great since day 1. We don’t pay them anything, unlike other brands. They wear Sosandar because they like the product. Icing on the cake, not dependent on it.
Database 100k-400k, includes prospects.
Mgt option pool c.11% - 30 institutions were consulted, they all agreed
CAC - big decline in cost (customer acquisition)
ESG - main suppliers are China, India & Turkey - close relationships with suppliers, independent audits done, have to check what suppliers are doing what they say they do, ultimately based on trust.
Q&A - repeat orders? 70% of the total.
Addressable market? 12 million women in the UK, international markets are huge. Barely scratched the surface. Sky's the limit. We see ourselves becoming a major eCommerce business, same opportunity as Boohoo and Asos, in an older customer demographic.
EBITDA margin in future? Not a short term issue long term in double digits?
Stock turn with 3rd parties? Very fast - typically 3-4 weeks stock turn. Very good, very efficient way of selling.
My opinion - this is looking exciting. I should probably not write up anything within a 48 hour cooling off period of a webinar, and I do like Julie & Ali very much - you see, calling them by first names is a clear warning sign I’m emotionally involved!
Make up your own mind! For me, the Q1 growth means they’re now near breakeven, have plenty of cash, are scaling up the 3rd party sales, I like it a lot. This is now a coffee can stock for me personally - buy and hold forever. Is it cheap? No - £62m market cap looks pricey for where the company is now. That’s always the difficult choice isn’t it, with growth companies - how much to pay up-front for future growth?
There's a point of difference here - SOS is an older demographic, and understands it/ serves it well.
15p float price. Now close to double that - it's going well. Yes, needed a bit more funding, but I'm fairly comfortable I was right abut this from day 1. The key is passionate, committed management. Starting a new fashion brand from scratch is almost impossible. Julie & Ali have done it. Sit up & take notice. I think this could (not will!) be a good investment from here. Make up your own mind.
.
.
Takeovers
As mentioned before, these are coming thick & fast, especially from overseas buyers, which is one of the reasons I generally feel bullish about the UK market right now.
Augean (LON:AUG)
An ongoing situation first announced on 27 May 2021, almost 2 months now. Augean says today that it is continuing to have discussions with Morgan Stanley Infrastructure Inc. , certainly a credible sounding name as a bidder. The PUSU (put up or shut up) deadline from the Takeover Panel has been extended again to 19 August 2021.
My view - it’s currently rated at 17.2 times forecast earnings for FY 12/2021, which personally I thought looks a fair price, so I sold my small position here in the market at around 300p, which had been in the back of my mind as a sensible price target when I bought at around 200p. I wasn’t particularly interested in speculating on whether a bid may or may not happen. There’s also a large ongoing dispute for allegedly overpaid landfill tax. Good luck to holders, I hope you get a satisfactory outcome.
Audioboom (LON:BOOM)
A much less credible bid approach was announced on 19 July - I covered it here. Audioboom has issued its response today, which rejects the approach. Reasons given are: undervalues the business (that’s arguable!), unattractive structure of deal (true, as mostly payable in toilet paper - no, not Accrol (!), I mean shares in suspended AAA), and no strategic reason for the deal.
Well said BOOM, this was a fairly daft approach, so best kicked into touch.
Note there is an InvestorMeetCompany presentation today at 15:00 which I'll be attending. Will report back if anything of interest is said. Growth has been very good lately, but still not profitable, so I don't know how to value BOOM.
Restore (LON:RST)
Announced today, Marlowe (LON:MRL) has said that it has made 2 possible takeover approaches for Restore, but both have been rejected. The latest offer was 530p, a 26% premium to last night’s close - not bad. Although the catch is that it’s only 71p in cash, and the remainder in new Marlowe shares. I’ve had a quick look at Marlowe, and it looks a decent company, about the same size as Restore. So there could be a benefit from a larger, combined group maybe? Restore shares are up 16% today to 489p.I thought Restore looked good, and reasonably priced, so have a call with management booked in for next week. Pity I didn’t pick up any shares, but never mind.
Restore put out its own announcement at 08:41 today. It says Marlowe offered 515p initially, mostly in shares, which was considered and rejected due to undervaluation, and poor structure (mostly in shares, with only 71p in cash). That was then raised to 530p, rejected by Restore on the same basis.
Restore management says they remain highly confident in its standalone prospects. Presumably they also want to keep their jobs!
I can’t see any new trading information, it reiterates the key points from the positive trading update on 5 July 2021, which I covered here, and was impressed, awarding it the coveted SCVR “could be worth a closer look” status An adviser did come back to me with my concern about the rapid pace of acquisitions at RST, by pointing out that it has 3 divisional teams, all of which are experienced in M&A, so it can cope with a considerable flow of deals..
Diary date - 27 July for its interim results.
The share price of 489p indicates that the market doesn’t see a deal at 530p happening. Could be worth top-slicing a bit of the profit maybe?
Good Energy (LON:GOOD)
I’ve never heard of this green energy company, but it’s received a cash 340p per share offer from its largest shareholder, Ecotricity. It’s only a paltry 10.6% premium. Looking back at previous announcements, on 12 July 2021 the company previously rejected a 340p approach from Ecotricity - saying it’s a highly opportunistic offer by a competitor, and undervalues the company.
This looks like a hostile takeover bid, with Ecotricity by-passing management of Good Energy (which they don’t seem to rate too highly judging from the comments in today’s announcement). It will be interesting to see how this pans out.
Roland’s section
Strix (LON:KETL)
316p (pre-open)
Market cap £652m
Strix is an AIM-listed firm whose main product line is kettle safety controls - that’s the part that makes your kettle switch off when the water boils. In western markets this is a regulated component, for obvious safety reasons.
Strix is the world’s largest manufacturer of these controls and says its products are used by 10% of the world’s population. I know my kettle has a Strix control.
Of course, kettles are fairly cheap and most people who want a kettle (in developed markets) already have one. Finding new areas of growth has become a key focus for Strix since its IPO in 2017. Areas being targeted include instant water heaters, baby formula makers and more lightly regulated markets.
So far, I think it’s fair to say that Strix’s share price has performed more strongly than its business. Operating profit has been broadly flat since 2017, but the shares are up by 140%.

Is the current valuation justified? Let’s take a look at today’s update.
“Revenue growth of circa 50%”
The tone is bullish. The company says that the kettle controls category is performing strongly, especially in the regulated sector (i.e. developed markets, excluding China). The order book is said to be “positive”. No numbers are given but I guess this might mean that the order backlog has risen since the 2020 year end.
Here are the financial highlights:
- Revenue growth of 50% in H1 versus the Covid-affected prior year.
- Full-year revenue growth in 2021 expected to be 30% - this appears to be in line with consensus forecasts
- Gross margins are said to be in line with expectations - more detail promised with H1 results
- Price increases pushed through on some products to minimise the impact of cost inflation.
Full-year revenue growth of 30% sounds very impressive, given that average annual revenue growth between 2015 and 2019 was c.5% per year.
The main reason for this leap forwards seems to be last year’s acquisition of water purification appliance company LAICA. This business generated revenue of €20m in 2019. Sales are said to be up by 20% in H1 2021 -- assuming a similar full-year performance, I estimate this could add around 20% to Strix’s 2020 revenue.
This suggests to me that organic revenue growth, including in-house product launches, might be about 10% in 2021. Not bad, but not as impressive as the headline figures suggests.
One other area of interest for some investors will be Strix’s HaloPure technology, which it acquired in 2019. This is currently being used to sterilise water feed lines in industrial pig farms. It’s still in the early stages of commercialisation, working with some large Chinese companies.
I’m unsure about this - I’d be more encouraged if Strix was working with - say - Danish pig farms.
My view
I have mixed feelings about this business.
Positives: Strix has consistently generated operating margins of 25% or more since 2015. The group is a market leader and I believe its core products have some moat-like qualities, due to regulatory hurdles.
Negatives: In developed (regulated) markets, it’s not clear to me how much scope for growth exists. In less developed (lightly regulated/unregulated markets), the opportunities are greater, but so too is the scope for intellectual property infringements. China is the obvious example here. No doubt it’s a big market, but I struggle to believe that the Chinese can’t design and produce this technology domestically.
Strix is introducing new product lines and making acquisitions to try and stimulate growth, but I think it’s too soon to know how successful this strategy will be. The 2021 results may give a fairer idea - 2020 was disrupted, after all.
Balance sheet/cash flow: Strix has historically generated strong free cash flow, but this has weakened over the last few years, while net debt has risen.

Today’s update shows that net debt excluding lease liabilities has risen to £51.6m so far this year, up from £37.2m at the end of 2020. This increase isn’t explained, even though it’s fairly sizeable.
I appreciate that last year was difficult. The company has also been spending money on a new factory in China. But I’m not sure why cash generation hasn’t been a little stronger during the first half.
After recent gains, Strix is trading on around 20 times forecast earnings. The dividend yield is down to around 2.6%.
I’m not tempted to buy at this level, but I’ll await the H1 accounts with interest.
.
Medica (LON:MGP)
160p (+4.9% at 0930)
Market cap: £198m
Medica provides outsourced teleradiology and imaging services. In short, it employs qualified medical practitioners to interpret and report on scan results from home-based workstations. The NHS is the biggest client, but the group is expanding in other English-speaking markets, including Ireland, Australia and the US.
Demand for Medica’s services was hit last year as hospitals suspended a lot of elective activity to free up capacity to handle Covid-19 patients.

Today’s update tells us that a recovery is underway. NHS demand has returned to 75% of pre-Covid levels (Jan/Feb 2020). However, the company warns that the impact of the removal of Covid restrictions on hospitalisations has yet to be seen.
Looking beyond the pandemic, the backlog of NHS elective activity is expected to combine with structural growth in elective scanning to support strong demand in 2022 and beyond.
The firm’s emergency out-of-hours service, Nighthawk, is also said to be performing well.
Financial outlook: The financial guidance in today’s update seems somewhat nuanced to me.
An increase in gross margins during H1 may be offset by the effects of contract wins and changing case mix in H2. My reading of this is that gross margins may be lower in H2.
Gross margin for the full year is expected to be “at least in line with 2020 levels”.
However, revenue is expected to recover strongly this year, rising from £36.8m to £60.3m. To put this in context, 2019 revenue was £46.5m.
My sums suggest this should report a strong recovery in operating margins, to around 20%.

My view
I’ve had a favourable impression of Medica’s business since its 2017 flotation, although I’ve been unsure about the scope for growth outside the core NHS market.
That question remains, in my view, especially as regards US ambitions. As investors in Tristel (LON:TSTL) have found (see yesterday’s report), breaking into the US healthcare market is not easy for small, non-American companies.
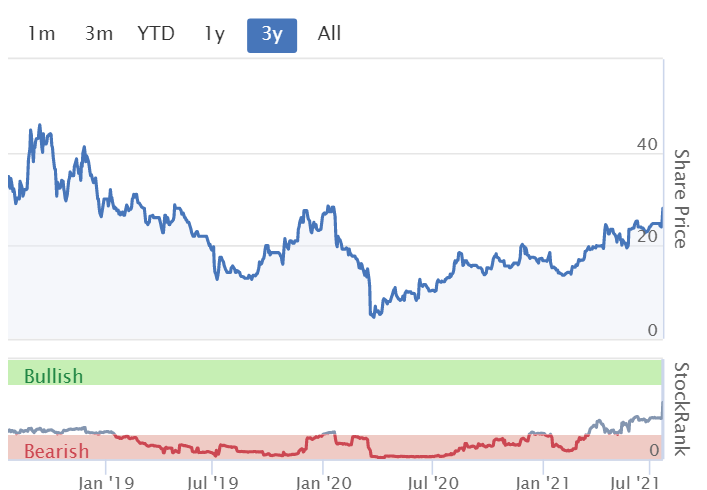
Medica’s shares have had a strong run so far this year:

This has left the stock trading on a rolling forecast P/E of around 20, according to Stockopedia.

Today’s update does not refer to market expectations. My reading of it is that results are expected to be broadly in line, with some room for uncertainty on both the upside and downside.
I don’t see anything in today’s update to change my view on this business. I think the share price is probably up with events, but I don’t think the stock is obviously overpriced. If I held the shares, I’d continue to do so.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

100 comments
The 400p offer looks even better now!!
It took a bit of time for the fall back to happen, but it certainly seems to have done so now! Is it a buy for the brave or a sell for the faint hearted! I have a small holding and will probably act as a rabbit and stare at the lights!
Well the CFO of Good Energy (LON:GOOD) seems to think 335p is a good price to sell. Doesn’t inspire confidence in his bean counting if he thinks 335p is a good price when 400p wasn’t. Nowt queer as folk and all that …
Gus.
Hi Gus, if I held Good Energy (LON:GOOD) (which thankfully I don't hold) I would be selling as well when you consider the amount of debt it has. Also, Good Energy (LON:GOOD) supplies gas to around 28,000 homes, not a good time to be suppling gas, in my opinion, unless the company bought in advance and locked in at a low price. I see another energy provider, Goto Energy, went into administration today. I think that makes an unlucky 13 so far this year.
Does it look like the 400p offer isn’t going to succeed. How bizarre!!
Indeed. Offer for Good Energy (LON:GOOD) has officially lapsed:-
https://www.investegate.co.uk/...
Presumably the shareholders that rejected the offer and supported the incumbent board will be delighted … at least until the opening bell on Monday when the share price falls back towards the pre bid price. Meanwhile Good Energy (LON:GOOD) gets on with business as before other than it now has an openly hostile and presumably slightly p***sed largest shareholder. Watching with interest. No position.
Gus.
It’s been bubbling along in the background for a while, but Ecotrcity have just increased their unsolicited offer price for Good Energy (LON:GOOD) by 60p to 400p this morning.
https://www.investegate.co.uk/...
Gus.
Augean (LON:AUG) competitor bid to the Morgan Stanley backed 280p plus 20p contingent announced at 325p this morning. I’ll add to today’s SCVR when it’s published in due course.
https://www.investegate.co.uk/...
Another financial buyer consortium with 54% irrevocables in their pocket so a done deal unless a higher offer comes in. Over to you Morgan Stanley …..
Gus
Hello Paul…I think it’s unfair that the moderator blanked out your comments..I want to read whatever you write.
We live in an age of PC and I have lived in an age of BBBS( Bullxxxx Baffles Brain Syndrome..I used to work in banking and have met countless directors of small private businesses making millions. I have invested in companies who make diddly squat ,but as we are in the silly season, it amazes me how the regulars here have the time to write about all subjects covered here..
But my point is , whatever Paul has written we should be allowed to read it as many of the companies I have shares in or considering investing in have directors who are overloaded or medically diagnosed with BBBS…and surely Our Paul does not yet suffer with BBBS…?
Paraphrasing Paul‘s blanked comment, he was suggesting via slightly opaque beer goggles that Strix (LON:KETL) wasn’t necessarily the best ever investment with the suggestion that it might go the same way as some of the other fraudulent Chinese companies that listed on AIM such as Camkids . (See posts from 2015).
https://www.stockopedia.com/co...
Not sure whether he stands by this opinion in the cold light of day.
Gus.
p.s. just read Paul‘s original commentary on Camkids in the link above. I don’t think he needs beer goggles to express a strong opinion very well ….
Having seen the comments, I think they are best deleted, I think even Paul may agree on that.
Some words should never be used on here, IMO.
Yes best deleted.
BSV
As one of the number of people who was targeted by Paul's now deleted comment I agree the comment should be deleted. After reading it this morning and seeing the time of the comment I put two and two together which has since been confirmed in Paul's SCVR report today.
What I like about Stockopedia is that discussions and differences of opinion can be shared in a civil manner. Leave the name calling to ADVFN and other boards, it is not welcome here.
Do you think you will get chance to look at Dotdigital (LON:DOTD) tomorrow Paul?
Do you think you will get chance to look at Dotdigital (LON:DOTD) tomorrow Paul?
Sorry will, I got sidetracked onto Supreme (LON:SUP) webinar -which looks more interesting - see tomorrow's SCVR. Apologies! Today was a day when I just got overwhelmed with newsflow. I can't cope with it sometimes, and need to have a lie down.
Best wishes, Paul.
Hotel Chocolat (LON:HOTC) £40m equity issue announced this evening at 355p (low or nil discount) including a retail issue on PrimaryBid. Not sure that level of discount is a particular sweetener to the offer (coat please) although suggests confidence on the part of the brokers that there is plenty of demand at this price level.
https://www.stockopedia.com/sh...
Gus
Why does Hotel Chocolat (LON:HOTC) still need funding to do expansions? Don't they already have enough shops generating FCF to self-fund growth?
And does that point to a flawed business model, that they're not making enough profits that they need to still be raising funds for expansion of production capacity at this size?
Very clever for Hotel Chocolat (LON:HOTC) to raise a load of money at a peak valuation! Smart move! This one looks to me a bit like Naked Wines (LON:WINE) - not sure if they're good companies, or promotional BS. Time will tell.
Hi Roland, I'd like to suggest that the comparison between Tristel and Medica is perhaps a bit tenuous owing to their completely different areas of work. Medica will not experience the same barriers to exploiting the US market as, generally speaking, most of its services will not need the FDA/EPA approvals which Tristel is seeking for its products. Medica will need licences to provide its teleradiology reporting service in the US but the requirements for these, whilst not trivial, are very unlikely to be as onerous as for an FDA approval of a product. However, there will certainly be plenty of competition in the US but I think the size of some of the companies working in this sector in the US indicates the potential for growth if Medica is good enough. Geographic expansion is one growth channel for Medica to grow but there are other medical sectors for it to exploit its expertise in remote diagnosis and analysing medical images, including through the use of artificial intelligence. I was interested to read that, despite the shortage of radiologists in the UK, Medica offers flexible hours and an ability to work at home which makes it easier to attract staff.
I absolutely agree re Medica (LON:MGP) and global expansion, including the US Peter. However they don't need to recruit in the UK but anywhere on the globe where the skills are to be found and particularly other time zones (Australia, India etc) which reduce the cost of providing the service in our night time as these countries are in their daytime - neat! I think outsourcing appropriate medical services remotely is a massive opportunity including operations in time, particularly as the technology for this develops. Also paying per job as opposed to having someone on the payroll internally is massively more cost efficient and predictable too.
Hargreaves Services (LON:HSP) lovely phrase in today's trading update released at 1315. ' the Board now expects that the Group results for the year ending 31 May 2022 will materially exceed market expectations. Up 11% after the update, I hold.
https://www.londonstockexchang...
I added to my Hargreaves Services (LON:HSP) after a recent tip in Small Company Share Watch highlighted the value in their German business so that's working out well so far. Unusual time for a trading update but easier to forgive when it's good news.
I read Roland's report on Strix (LON:KETL) Strix ( I hold ) with interest and I cannot agree with his conclusions . As far as i can see he raises 3 issues : 1: free cash flow declining in the last two years 2: intellectual property 3: growth and where it is going to come from
1. I would refer you to the last annual report
"Tangible assets had additions to net book value of £17.2m in 2020, compared to £15.4m in 2019. This includes £9.1m of new factory construction (2019: £6.0m), plant, machinery and tooling £3.9m (2019: £3.4m), and LAICA's addition of £3.7m."
This equates to 8.08 pps and 8.45 pps in the last two years compared to an average of 3.16pps over the previous 4 years ; the new factory in China which is the bulk of the capex is due on stream in August 2021 so I do not see this level of capex continuing . This and the acquisition of Laica is where the cash has gone
2. Intellectual property : again I would refer you to the annual report
"Defence of intellectual property and regulatory enforcement remain core activities of our business and there have now been 57 in total since 2017."
Having operated in China for years and invested in a new factory there over the last tow years I find it difficult to accept that IP is vulnerable in China - if it was going to happen it would have happened by now . The Strix IP is the bedrock of the company and one of the main reasons why I have invested in them - it is a substantial moat.
3. Growth
"At the recent Capital Markets Day in November, the Group outlined its medium-term strategy stating that the Group aims to double revenues over the next five years, primarily through organic growth in its water and appliances categories. Strix continues to actively seek opportunities that will add value across the Group through niche acquisitions or technologies"
With Return on Capital 31.5%, Return on Equity 216.2% , Operating margin 27.95% , PE : 20 i can't see how you can' t come to the conclusion that this is a fantastic investment opportunity
And to add to what you say re Strix (LON:KETL) (I hold) this morning's TU specifically says "Strix has also successfully implemented price increases
on some of its legacy products in both kettle controls and water
categories..." so they seem to think they have some pricing power in the face of rising costs.
They've also said in the past that kettles typically last three years before requiring replacement, so the fact that 'everyone' already owns a kettle doesn't mean they won't have to buy a new one in a few years.
The share price has risen a lot in the last twelve months so is maybe a bit on the high side, but I see this company as a longer term investment.
Excellent response on Strix (LON:KETL) fred9566. I've been a holder of Strix for about 2+ years now and vouch for what you've said. Comments like this justify why it is so important to do your own research if you are interested in a company before diving in.
As the disclaimer on this report says, Paul and Roland are not giving tips, they are just giving their impressions on the companies. With so many companies in their universe to report on they can often only touch the surface in their review and that is 100% not a criticism of these reports, it is an acknowledgement of the task they are undertaking. I think just a couple of months ago Paul raised the same concerns as Roland over Strix.
Having said all that, this really doesn't diminish the value of these daily reports. It is reader comments like yours which adds more valued detail to the companies under review and completes the value of these reports.
Having said all that the SCVR can for me be an initial screener for stock ideas. If there is a negative write up here on a company then I'm less inclined to research further, unless there are reader comments which actively challenge the reports with hard facts.
On a different topic but relevant to today's report, when it comes to Medica (LON:MGP) I researched the company about a year ago and was tempted. What held me back is thinking if their service is time limited and not much of a moat. Maybe people more knowledgeable in this area can explain to me if this business is at risk from Artificial Intelligence developing which can perform this work, with minimal error rate and a lower cost?
RE: Medica (LON:MGP)
Maybe people more knowledgeable in this area can explain to me if this business is at risk from Artificial Intelligence developing which can perform this work, with minimal error rate and a lower cost?
As I understand it, at least at the moment, teleradiology can't be fully implemented using AI due the huge diversity in the input data. However, increasingly it's being supported by machine learning programs such as Medica's own augmented reality software. To the extent that reduces the reliance on trained operators and improves performance that ought to be a boost rather than a problem.
In the long-run, of course, AI will probably provide better results than humans - but that's true in a host of applications, and trying to predict which will be impacted and when is a hopeless task. Medica is a decent business, well run by competent management and clearly has short term opportunity as the NHS tries to deal with record waiting lists.
Meanwhile the US acquisition of RadMD is both an opportunity and a risk - but again the recovery in elective scanning ought to provide a tailwind over the next two or three years.
Overall, it still seems like reasonable risk reward to me, for the time being. But I'm quite bullish on UK companies in the area of telehealth so maybe that's my preferences overcoming my analytics. Wouldn't be the first time (or the last).
timarr
There are two hurdles for AI in medicine.
The first is, the technology needs to be almost 99.999% accurate. Even a little off, there will be uproar. Think drugs, and the stringent new hurdles they go through.
The second is, once the technology reaches that 99.999%, it will need regulatory approval. Which is a very slow, multi year process.
In the next 5-10 years, I predict we will see AI-assisted radiography, where a radiologist still needs to sign off. But it will be more accurate and faster. So from that perspective I don't see AI being too disruptive to Medica (LON:MGP) area in the short-mid term.
Thank you both for your views on AI and Medica. Very much appreciated.
just to add to this, I imagine having a huge data set to train AI on is a valuable asset in itself!
Re your comments on Strix (LON:KETL) Fred, from the several interesting and convincing webinars I have listened to recently, I couldn't have put it better myself. I was really surprised how embedded they are in China, and not just as a source of production. That doesnt mean they are immune from changes in the attitude of the totalitarian governing party nor worsening relations between the West and China that seem likely, in the meantime it is a fact nevertheless.
Razor sharp analysis on Augean (LON:AUG) sharw - thank you!
I agree, hold and will be very disappointed if the final bid is £3.
FR
Augean (LON:AUG) - Paul mentions the landfill tax dispute. It was announced on June 24th that the First Tier Tax Tribunal had found in the company's favour. HMRC can appeal this decision within 56 days. I make that August 19th - which also happens to be the new PUSU deadline. I have a hunch (no more) that two prices are on the table (depending on whether HMRC appeals or not) ready to be announced when that is known.
well given that they have paid all the tax claimed up front to HMRC including penalties and interest there mightily well should be two different prices, otherwise they could get taken out for a song with the offeror pocketing all the proceeds.
I'm a bit irked at any bid around 300p as I had this as a long term hold for me from around 200p. I think Augean (LON:AUG) has some very strong moats around waste management, particularly being about the only owner of landfill in the UK that can be legally expanded. Given landfills are reaching capacity that should come with a hefty premium in my view and I'm not convinced it will be priced correctly alas.
Just listening to the Supreme (LON:SUP) results presentation - CEO and CFO come across well to me. They are a new holding for me - I read the IPO docs and found them convincing.
@Paul: I realise a very busy week for you but suspect they are exactly the kind of share you are interested in: maybe if Friday is quieter?
Would be interested to know Paul's views on Loopup (LON:LOOP) LoopUp. Thanks!
Why? This is an investment website. To regain investor confidence would be like ..... answers on a postcard.
Dear Paul, You mention that you might cover Judges Scientific. I hold quite a lot of shares, and they have more than doubled. Needless to say, I would be interested!
The company seems to have an excellent niche (how I love that word), and the management is highly regarded, and they seem to do all the right things like sailing through the Pandemic, and increasing their divi each year.
But they have a very low StockRank, in part because they are very expensive. My own gut-feel is that such a good company is worth this value - there aren't so many companies like this about. However, your views would be more worthwhile and grounded than my touchy-feely opinions!
Nettle
SDI has a not dissimilar business model to JDG, but it is at an earlier stage in its development. You might be interested in looking at it. They have sound management with a good track record and to me are even more attractive now that they are not longer funding acquisition by shareholder dilution. (Declaration of interest : I’m a long term holder).
Dear Timeoteo,
Many thanks for this helpful advice. But for the reasons you give, I also have shares in SDI!
incidentally, I sent an enquiring email to both companies before investing, and had a prompt and intelligent reply. That is always a good sign! Many companies don't bother.
Yes, I’ve always found them very responsive. I prefer investing in companies which communicate well if possible : I always think that companies who do that are less inclined to drop nasty surprises!
Hi Timeoteo and Nettle. I too hold shares in SDI and Judges Scientific and I would agree with Paul's previous comments (if I remember correctly) of Judges Scientific being the type of company which could be a hundredbagger. It has careful, conservative management with a proven track record and I don't think there is much chance of it running out of decent, profitable, small tech equipment companies to buy in the forseeable future so it just has to continue to do what it has always done. It even has a decent ROCE despite being an aquisitive company. SDI is at an earlier stage and, I would suggest, a little more aggressively run, but I reckon it also has some of these characteristics so let's hope we are all right!
Re Judges Scientific (LON:JDG) I am late to the party, but I was impressed recently by the comment that they had opened up much more capital availability, seemingly ready for a spate of additions to their stable during 21-22? Am I reading more than I should into this?
Judges Scientific (LON:JDG) - with £15m cash not going to buy much. But a large capital raise will mean they have a good story / pipeline - but can't give that story away - a problem.
Hi Paul, were you the Board of Ecotricity wouldn't you want to buy Good Energy (LON:GOOD) just for its name? I hold.
Thanks for all your hard work,
Silver
Hi Paul, was going through SCVR for recent Begbies Traynor (LON:BEG) update which you usually cover. Any thoughts on the recent final results ?
On Begbies Traynor (LON:BEG) there was nothing new-new in the latest update. I think the key variable is whether their acquisitions can bed in and can they extract either operating synergies, or leverage their greater size now to win more (or larger) insolvency deals.
Then there is the question of the macro environment - will the UK see a surge of insolvencies later this year or will the economy do a V-shaped recovery, or the government yet again does massive relief loans?
On the commercial property side, that should fare rather well as volume picks up due to distressed portfolios and sellers. There must be lots of covenant holidays coming to an end, and with rents now looking way below pre-COVID, many landlords might be forced to liquidate their properties, forced by lenders.
Once Stocko updates the data with the latest results, I suspect the Quality and Value ranks will increase quite a bit, and therefore I'm expecting overall SR to be in the 80s, from 50 currently.
(I Hold)
Hi Investor_AD,
I've got a standard-sized long term personal holding in Begbies Traynor (LON:BEG) but haven't yet got round to looking at the recent results. It's probably alright, or the price would have moved. I really like mgt there - Ric Traynor is a class act, see my .
So no opinion at the moment. I love it when readers give ur views - esp when I'm busy - what do you think?
Many thanks Roland for your thoughts on Medica (LON:MGP) (I hold) and remain ‘Humming along’. No not me making my morning coffee, but the headline of today’s Liberum broker note on Medica (LON:MGP) flagging up the fastest growth in its sector. ‘Disruptors’ is overused and only a few companies truly deserve this epithet including I believe Medica with their remote outsourcing of radiography stepping up a pace as NHS radiographers have their summer holidays by providing overnight processing through southern hemisphere reporters. I hold two other disruptors Auction Technology (LON:ATG) connecting global cloud buyers with county auction houses in the lower value Arts, Antique and Collectables market and Motorpoint (LON:MOTR) challenging the physical motor dealers with online sales, whilst also retaining a significant physical presence, unlike many of their online competitors. No idea if these three will eventually dominate their sectors and as usual DYOR. BTW where is Mr C this morning – I really miss his daily results summary.
In regard to Medica (LON:MGP) (I hold) I think that the performance is very solid given the enormous drop off in elective surgeries. The data is a bit hidden and lagged but here if you are inetrested in taking a look: https://www.england.nhs.uk/sta...
The data is now coming though up to May 2020 and shows that total elective surgeries in England dropped from around 6-700k per month to just 180-220k in Mar / April 2020.
Hello, re Medica (LON:MGP), I am late in the day to the party. No mention by anyone of the detail of the US company taken over and the growth potential there. Am I missing something?
On Medica (LON:MGP) I think they provided an update that the latest elective volumes (presume latest month June) at 75% of Jan-Feb20 volumes. Presume Nighthawk now running at 100%.
Its tricky to try to come up with one's own EPS estimate given the two acquisitions, but IMO the £60m rev and £8.8m Net Profit broker forecast currently looks a bit too high now. Especially when you compare to 2019 levels, and assume 75% elective revenues for the year and 100% Nighthawk, and some extra for new acquisitions. The unsaid thing in the Trading Update is that the recovery is slower than probably what was expected at the start of the year.
And then there is the risk of Elective volumes going into reverse in the second half of the year. Already, some NHS trusts in June and July have had to cancel elective surgeries. There was another comment further up that hospitals are prepping for influx of more covid patients over the next few weeks. Then there is likely to be a winter wave again Nov-Dec.
Ireland will face similar issues. USA operations, should be OK as they do clinical trials, not elective surgeries.
At the current 22x PE for FY21 it just seems fully valued, given that there is downside risk to that 6.9p EPS.
I'm keen to buy back in (held in the past) but for me there only looks to be value sub-120p.
Medica offer teleradiology services not radiography services. There are major risks to investing in Medica namely IR35 and the formation of regional NHS reporting co-operatives/networks. It was a great idea and kudos to Simon Raslingham for starting Medica over 15yrs ago. I can’t see Medica gaining much work outside of the NHS. The recruitment of radiologists must have almost reached saturation in the UK?
https://www.rcr.ac.uk/posts/of...
Medica (LON:MGP) (I hold)
Hi maillotàpoisrouges
Interesting IR35 comment there.
I have thought about this before too, but my belief was that contractors won't all be based in the UK, so in many cases tax compliance will be up to the contractor themselves to sort out.
For example, I believe shifts between radiologists in the UK and Australia/New Zealand are arranged so that they work each other's night hours, which makes sense given the time difference.
So for sure changes to IR35 is a risk for the business, but it might not be too bad even if major changes do eventually come about.
Cheers
A
Hi Roland. Good, balanced view on Strix (LON:KETL) . In terms of future growth prospects, as a practical matter I would suggest that electric kettles are one of the least „durable“ durable goods and as such there is a good chance of a high churn rate from the existing customer base. We probably replace ours every two to three years as and when something goes wrong (usually starts leaking water or the switch/heating element goes on the blink) and given the relative low replacement cost vis having a repair done we simply buy new. A 33% pa repeat order from a growing customer base as they expand outside of established markets makes the growth story a lot more credible IMO.
Gus.
Strix (LON:KETL) I hold and agree about durability of kettles and would suggest that most peoples kettles around the world have seen more use in the last 15 months than ever before .
Thanks for the write up Roland.
Richard
Hi Gus, good point about the regular replacement cycle for kettles. Ours usually seem to last a bit longer, than 2/3 years, but they certainly aren't as long-lived as most other kitchen appliances.
I want to be bullish on Strix (LON:KETL) but I can't get completely comfortable. I think this year's results should answer some questions, for me at least.
Roland
There had been discussion previously about the Americans buying kettles. Apparently they don't use them much at the moment.
Americas use kettles, just not electric kettles.
I must have been lucky as my kettles always last donkeys years, even in a extremely hard water area. Even the £5 one from Wilko lasted many years.
Loop Up is in freefall this morning, its technology and services should be doing really well in the current environment, yet they keep disappointing. I thinking it might be time to give up on this stock.
On another subject, a bit of insider information from the NHS. Their forecasters think we have another covid surge coming in the next few weeks, all the managers have been told to prepare. My missus is currently having to cancel leave for people in certain areas and isnt granting leave to any new requests.
Apparently next week is key, if the numbers match the predictions we're in trouble
No surprise on the NHS front - they are covering the worst potential issues seen in the modelling (from SAGE). R is 1.2-1.4 but its a lagging indicator so is likely to be nearer 1.6-1.8 across the country. Bear in mind last wave was 4000+ hospitalisations a day during Jan. Last data was 750.
Key take from this - if everyone behaves like the pandemic has gone expect the red line or above. You listening kids?!
Hospitalisations are down. Those that are hospitalised are having shorter stays. Deaths are down.
Covid is now endemic. We need to be mindful of the impact on health services but, ultimately, control of the virus is lost and we need to focus on broader health and economic issues to maximise health outcomes across the board, not just Covid outcomes. The vaccines, and staying on top of variants is an important management element going forwards.
I expect we'll see some return to a dedicated facility for covid a bit like we used to have dedicated TB hospitals.
Just my opinion, others may vary.
Just to be clear, its not endemic until its classified as such by people far better qualified than you or I.
I broadly agree with your point but its we shouldn't trivialise the situation.
"Just my opinion. Others may vary".
There are plenty of scientists stating it is endemic including articles in respected publications like "Nature". The WHO may not have declared it as such but the consensus is heading that way.
The coronavirus is here to stay — here’s what that means (nature.com)
Yes and 50% of the hospitalisations are from the 10% of the adult population who are not vaccinated. 92% of all deaths have been from people with a co-morbidity.
As the CDC said in the states "It is only a pandemic amongst the unvaccinated.
Recent edition BBC R4 More or Less with Tim Harford is worth a listen.
As the CDC said in the states "It is only a pandemic amongst the unvaccinated.- What a great line to take away from ALL this Covid-19 reporting . Perhaps the most important statement to be repeated to every unvaccinated person until they get it !
That is certainly what I feel.
The other good line put out by the CDC is:
“If you are fully vaccinated, you can resume activities that you did before the pandemic without wearing a mask or physically distancing, except where required by laws, rules, regulations, or local guidance”
https://www.cdc.gov/coronaviru...
Not sure why the states are more pragmatic about it?
Perhaps because infection rates in the US are about 20% of the level in the UK?
Interesting insights from Ambrosia and Leebod on Covid forecasts and planning. Personally I think that very little changes from 19 July - nightclubs being the main area of concern and community pubs allowing punters back to the bar. The note under the graph from Leebod suggests expectations of a step change in transmission. I think this has already happened, facilitated by the stupid behaviour at/around the Euros, especially in the pubs and by travelling fans (Scotland coming to Wembley/London for example).
The need for face masks on pubic transport in London were already being ignored by about 30% of those travelling from what I saw last week so things like this already in the numbers. And most pubs will keep table service for the forseeable for staff safety. Will be the only way they stay open!
Bigger concern for me is the pingdemic and impact on supply chains through staff absences, ability of the NHS to keep functioning, etc until next stage of not isolating everyone pinged.
I think we should also be planning future firebreaks in now - Autumn half term for 2 weeks perhaps and January full shut down again, unless we are on top of this by then. Freedom being the reward for good behaviour! I expect the winter to bring a next wave, maybe of a different variant, though hopefully not of the current scale.
Just thinking ahead to possible ructions this might cause markets in coming months. Certainly don't expect the travel sector to get the green light they are shouting for until next spring. Why do their spokespeople think it is acceptable for us to export our high levels of infection to other countries? As a third country I would have the UK on the banned list til September at least already. And generally I look on the bright side!
I suspect the 'Pingdemic' may die down as more people delete the app - although i can see many people keen on receiving these notifications as it is 10 days paid off work.
I cant speak for London, but up here in Newcastle we have had a huge change. from ym experience. The majority of people are maskless - all ages, not just the young. the only place I have seen enforce continued mask usage was my NHS dentist this morning.
In addition, i visited a fair number of pubs/bars last night and table service was only running in one of them. I did ask one of the bars why they removed table service and they said they NEED to get back to normal service; the majority of their staff HAVE NEVER SERVED/MANAGED QUEUES. they've only dealt with app/table service orders. This was quite apparant as i waited at the bar for 5 minutes listing to the three co-workers chat without as much as a hello, let alone take my order haha.
I really dont like the idea of forcing people to be double jabbed to enter a nightclub. seems forced and targeted at the young who generally have a lower uptake of this vaccine. Are we really going to allow 50k people in to sports/music venues without any dose, but turn away the minority who want a dance in flares?
thank you Ambrosia. Forewarned is forearmed.
My understanding is....
Something is Endemic when it only affects a certain place, ie, a country.
It becomes Pandemic when it involves more than one country, ie, worldwide.
When coronavirus initially broke out in China it was described as endemic but as it spread around the world it became classed as a pandemic.
Thanks for the free education lesson. I learnt something new :)
Interesting that Nature took it to mean what I thought it meant, ie widely circulating, not located to a specific geography or some other characteristic - but that's not what the dictionaries say. I guess you *could* say, it's endemic in human populations, but we probably need a better word as endemic doesn't scale well.
Apologies for off topic waffle.
Regarding the definition of endemic, Wikipedia tends to agree with the sense of IGotPoesJacket. Strictly speaking it would have to be at a steady state with R0 at 1 but I would say the description fits in that the disease is established in the population and will be sustained without external inputs.
https://en.wikipedia.org/wiki/Endemic_(epidemiology)
The covid surge is well under way.
https://coronavirus.data.gov.u... has the grisly details.
Any elective surgery is fast being put on the back burner.
How similar are Boohoo (LON:BOO) and Sosandar (LON:SOS) ?
Tempting to think of them as similar because they are both clothing companies that sell on line in the UK.
But, the ‘secret sauce’ is very different. In one case you have a business model that has driven success I.e. launch lots of products in small quantities at very low prices then quickly restock what sells and drop the rest. In the other case you have two fashion gurus who appear to have identified an underserved sector of the market that with their eye for what this sector wants can come up with a product that better fills this sector’s needs.
BOO have done an incredible job with their international expansion and acquisitions which really does look like a very solid platform for growth.
SOS on the other hand have stumbled rather on their path to break even (as most young businesses do) but are achieving that significant milestone so good on them for getting there. And they do appear to have a lot of momentum. But, and this for me is a big but, does their secret sauce of a certain type of product in a certain market scale into other product categories in the same market and does their understanding of what this UK sector wants mean they also understand what this sector in other countries want?
While I wince at the environmental impact of fast fashion, BOO feels to me like an investment in a company going from great to greater whereas SOS feels like its gone from wobbly to good with a fair deal of uncertainty still about whether it will go on to become great.
(BOO - I hold through a collective investment; SOS - no position so far)
Re Sosandar (LON:SOS) I agree they started from a different place but I think online market forces tend to drive them all to become alike in terms of business model.
I was surprised to see just now they have 353 items listed on johnlewis.com so that has really grown strongly. The headline prices are the same but the Sosandar website is offering me 20% off everything and promoting Klarna for buy now pay later.
I expect that research will mean I'll be seeing online adverts for leopard print clothes for the next few weeks....
Re Sosandar (LON:SOS)
“ I expect that research will mean I'll be seeing online adverts for leopard print clothes for the next few weeks....”
Well I think you need to follow through then, John, and buy one of said items, in the name of research of course. You can then post a pic modelling it!
Phew, I think the heat must have gone to my head!
Thanks for sharing that Paul, appreciate it. I had my eye on SOS for a wee while but hesitated. They are now firmly on my 'to buy' list but I am hoping for a drift back to do so. That may well be a fool's errand as I think the company looks like a fantastic growth proposition - I just feel the current valuation is a tad high for where the company is at and there still needs to be flawless execution. I like the management too. So am torn. Good luck to you and all holders!
Hi drobs, I agree with this to a certain extent. you say -
I just feel the current valuation is a tad high for where the company is at and there still needs to be flawless execution. I like the management too. So am torn. Good luck to you and all holders!
Spreadex allow me to put £100k underlying on anything I like, up to about 40% margin. So SOS is up to about that. Beyond that, it's 75% if I want to exceed that size. A good discipline.
Am scrabbling around to find margin to buy more SOS and QUIZ at the moment on 75% margin? No. Make up your own mind. 75% margin is fine - it drops, and your cash supports it, so whats the problem?
Recent gyrations show that we should keep speculative things on 75% margain. No issues with drawdowns.
Regards, Paul.
Jarvis Securities (LON:JIM) - application for Capital Reduction to release reserves not previously legally distributable - sorry have no clue or comment. SP taking a negative view at the off.
Re: Jarvis Securities (LON:JIM) - the news you mention is from last week which concluded with them announcing a special dividend of 8.5p. The share price is flat today and up since the special was announced, so not sure what you mean by a negative reaction.
Cheers
Simon
RE: Jarvis Securities (LON:JIM)
Capital reduction is purely technical to allow special dividend to be paid.
timarr
Jarvis Securities (LON:JIM) shares are now up 4% today. Shares did not fall on opening either, where are you getting your information from?
Could you look at Dotdigital (LON:DOTD) ?
Really strong trading update from Dotdigital (LON:DOTD) with a 23% increase in revenues, 93% recurring revenues. Strong partnerships, a competitive moat, significant growth in both the America’s and AP.
Paul and Roland would really appreciate your thoughts on this company whilst it’s still a small cap.
Like dotDigital (LON:DOTD), there are a number of software companies around with an excellent record, growing strongly, and rated on what to me are quite ridiculous PERs. If the Fed and the BOE really pull the plug on QE, I would have thought these highly rated stocks would drop sharply. I hold dotDigital (LON:DOTD), so do I sell or hold? I will probably hold, as I try, not always successfully, to sell my worst performers, not the best. But the market feels to me distorted.
OK, I'll make a start on Dotdigital (LON:DOTD) next, looking interesting.
After that I'm hoping to look at Loopup (LON:LOOP) (looks bad) and possibly Judges Scientific (LON:JDG)
Regards, Paul.
Good man Paul! Responsive, knowledgeable, entertaining and on the ball as usual - what a treasure. Hopefully a nice cold beer on Bournemouth prom for you at the weekend!
Strix (LON:KETL) Pre close trading update. 'We anticipate delivering revenue growth of circa 30% for the Group in 2021'. Let's hope that profits go with this. The Stock Report shows they have good margins.
https://www.londonstockexchang...
Franchise Brands (LON:FRAN)
Strong revenue recovery and record profits give confidence in a full year performance ahead of expectations
· Revenue increased by 18% to £28.6m ( H1 2020 : £24.2m).
· Adjusted EBITDA* increased by 50% to £4.2m ( H1 2020 : £2.8m).
· Statutory profit before tax increased by 200% to £2.6m ( H1 2020 : £0.9m).
· Strong cash conversion of 84% (H1 2020: 38%).
· Net cash of £5.2m at 30 June 2021 (31 December 2020: £4.9m).
· Adjusted EPS** increased by 46% to 2.70p (H1 2020: 1.84p).
· Basic EPS increased by 143% to 1.63p (H1 2020: 0.67p).
· An interim dividend of 0.60p per share declared (interim 2020: 0.30p per share
These Interims look pretty good to me and Stephen Helmsley (Exec Chair) and substantial shareholder said:
"We look forward to the second half of the year and beyond with great optimism. We are confident that the full year performance will be ahead of current consensus market expectations."
The expectations are spelled out in the RNS which is good.
IMO at a time when many people are looking for a new career, becoming a franchisee must be quite appealing which could be quite good for Franchise Brands.
I hold
Investegate |Franchise Brands PLC Announcements | Franchise Brands PLC: Interim Results
Good morning Paul - Thanks for the swift SOS write up - Much appreciated.
Tough one, yes - But, on a coffee can approach, if you had to bet the house, would it go to BOO or SOS?
I suppose it's more appropriate to ask - What split would you use, 50/50, on a BOO/SOS basis.
Thanks again as always for your constant commitment.
Wishes.
I hold £boo (top 3 holding 11%+ of pf) but do not hold £sos.
In my opinion, for what it is worth, an allocation between the two will depend on many factors: time frame, risk tolerance, stage of life etc. But personally any allocation to Sosandar (LON:SOS) on a Kelly principle would have to much less than an allocation to £boo
I think it goes without saying that if £sos achieves even a 10th of £boo ‘s revenues (and remember it is not even selling outside of the U.K. yet) at similar profitability to Boohoo, competition does not crush them (there is Boohoo (LON:BOO) with its multitude of brands and Paul mentioned Stein yesterday) and they do not dilute existing shareholders significantly this will be seen as having been cheap today but I would imagine volatility will be pretty gut wrenching for a number of years.
Sosandar (LON:SOS) is not for me at my stage of life or the current market. If it was to sell off in the next market correction (whenever that maybe) back to the mid-teens then I might revisit. I like online retail a lot.
Not sure I would call it a coffee can stock though. There is still too much uncertainty.
Apologies to Paul for jumping in here.
Regards
Michael
:) I disagree Michael. Go back 6 months and I would have concurred, but they've hit inflection for me. I hold both Boohoo (LON:BOO) and Sosandar (LON:SOS) but they are different beasts and business models targeting different demographics. I doubt there will be much more volatility in this stock now than we currently see with Boohoo (LON:BOO) !
Hi David
Takes two to make a market :-) but are you saying you would allocate more to Sosandar (LON:SOS) than to $BOO or vica versa. I would just see more risk in because it is early stage in Sosandar (LON:SOS) than in £BOO.
I am not adverse to it at some point but just not at the current double what it was in February price but may be I am price anchoring!
Maybe I will bung a few into my son's JISA. That usually seems to do wonders for the share price. Everything I buy for him goes up and to the right and everything I buy for my own account (Best Of The Best (LON:BOTB) Boohoo (LON:BOO) Anglo Asian Mining (LON:AAZ) Games Workshop (LON:GAW)) flounders around going nowhere..
Regards
Michael
Hello Michael, I hold both Boohoo (LON:BOO) and Sosandar (LON:SOS), unfortunately more of Boohoo (LON:BOO) than Sosandar (LON:SOS). I used to be a fan of Boohoo (LON:BOO) but i have gone off them and I looking to reduce my holding without losing money. I also hold some ASOS (LON:ASC).
Maybe more risk at Sosandar (LON:SOS) but also more potential but I would not hold a large amount. Also looking to get out of Anglo Asian Mining (LON:AAZ).
Herbie47, re"looking to reduce my holding without losing money."
It souldn as though that money has already been lost. The decision now is surely whether you think Boohoo (LON:BOO) will go up or down from here on the timescales that are important to you, and if the answer is "up", whether the money you have in BOO would have a better risk/reward if invested elsewhere.
Hi Michael - I know the feeling!
I'm about 50/50 allocated to Boohoo (LON:BOO) and Sosandar (LON:SOS)
I like both and see Boohoo (LON:BOO) as an ambitious long term winner in their demographic and new marketplace platforms so am happy to hold that for the next few years on the basis I am anticipating the price to double or treble. That obviously comes with some market angst about the company but I offset that by my regard for the strong ambitious management and an already well established business.
But Sosandar (LON:SOS) I see no reason why they can't be a £500m - £1bn business in the next 5-10 years if they continue to execute. Thats 10-20 times the current share price potentially. Admittedly there is no guarantee they will execute to anywhere near that level but given the current state of trading and clear market appeal (likes of Next/ John Lewis demand for stock etc) I now view the downside as much more limited than say 6-12 months ago.
Hence when I give them both a risk/reward rating I come out about equal, slightly on the side of Sosandar (LON:SOS) (but I think that's a personal bias towards higher reward). They appear expensive now but I think that will change quite rapidly. At just £2m ebitda they would be on an EV/EBITDA of just 25. No longer feels like a stretch to get there any more to me so I feel quite comfortable with my holding. I may well add more at some point soon.