Small Cap Value Report (Thu 22 Mar 2018) - CVR, SFE, KETL, COG, VLG

Good morning!
There is no shortage of company announcements today, so I'm going through them personally at the moment. As usual, I'm happy to take requests in terms of which ones to cover here.
My final list is as follows:
- Conviviality (LON:CVR)
- Safestyle UK (LON:SFE)
- Strix (LON:KETL)
- Cambridge Cognition Holdings (LON:COG)
- Venture Life (LON:VLG)
Also, Paul updated yesterday's report with more sections. You can read that here.
Cheers,
Graham
Conviviality (LON:CVR) (suspended)
Update on progress and potential equity fundraise - Conviviality, the alcohol wholesaler and retailer produced an update at 6pm last night.
In short, it looks like a horror show for existing shareholders. The only ray of hope is that we still don't know at what price the new money will be raised, so there is still a chance that the forthcoming dilution will not be too severe. But it is now inevitable that those who take part in the forthcoming fundraise will end up owning the majority of the company.
If you remember the recent timeline, Conviviality discovered a £30 million tax payment coming due shortly and that it hadn't made provision for. This came after an error had led to the company miscalculating its profit forecasts, and trading margins had weakened. The shares were suspended and the CEO stood down, though staying on to help with the transition.
Originally, I thought that the company might only need to raise £30 million, plus a little bit more for extra comfort. After all, there was no clue up until recently that it had any short-term funding requirement. The balance sheet wasn't pretty and its lending facilities were maxed out, but it was thought to be profitable.
It turns out that the company needs to raise far more than £30 million. It is looking for £125 million, for the following purposes:
· "Resolve overdue payments with its creditors and return them to normalised trading terms;
· Settle payments with HMRC;
· Repay the Company's £30.0 million revolving credit facility in its entirety; and
· Provide working capital headroom and fund costs associated with the work undertaken to recapitalise the business."
So perhaps the funding requirement looks something like this:
- £30 million HMRC payment
- £30 million to pay back the RCF (I'm assuming the bank has indicated it is withdrawing this facility)
- About £6 million in fees associated with the funding (this remains to be seen)
That leaves £59 million to normalise relationships with creditors and its working capital position.
The company is also trying to raise another €5 million on top (the maximum allowed under EU rules) in an Open Offer. This is a token gesture to private shareholders and others who find themselves shut out of the Placing.
I also wonder about trading losses which might need to be funded.
Let's review the EBITDA timeline:
- 8 March: "Following a review of current year projections, the Company now expects that adjusted EBITDA for the current year will be approximately 20% below current market expectations." (forecasting error and weaker wholesaling margins)
- 13 March: "Further to the Announcement, the Company can confirm that the prevailing market expectations for adjusted EBITDA at the time of the Announcement were a range of £69.1 million to £70.5 million. Based on the guidance provided that the Company expects adjusted EBITDA for the current year to be approximately 20% below market expectations, the Company confirms an expected range of adjusted EBITDA of £55.3 million - £56.4 million."
- 14 March: "The Company's announcement on 13 March 2018 confirmed an expected range of adjusted EBITDA of between £55.3 million and £56.4 million. To the extent that the current situation creates operational difficulties, this may negatively impact the adjusted EBITDA range."
- 22 March: "Assuming the Placing is successful, the Board would expect that the adjusted EBITDA* for the year ending 29 April 2018 to be in the range of £45.5 million to £46.0 million and net debt to be below £100.0 million."
This means that it has taken just 16 days for the current year's expected financial result to worsen by £10 million, having already reduced by £15 million against previous expectations. It sounds like the company is making big sacrifices with customers and suppliers, to keep their business during this period.
With a much lower adjusted EBITDA, the net profit result will be that much lower.
The final sentence is no surprise:
If the Company is unable to raise funds by way of the Placing or otherwise, it is unlikely to be able to trade on a going concern basis.
My opinion
Those who take part in the Placing, presuming that it goes ahead, will end up owning most if not the vast majority of the company. The market cap closed at £185 million on the day before suspension, i.e. before market participants knew about the problem with the tax payment, and before EBITDA was downgraded again.
The Evening Standard (external link) reported 2nd-hand information that brokers were talking about a 10p placing price. That would produce 1.25 billion new shares and reduce the existing shares to a 13% ownership interest.
I'm glad to have covered this stock over the last couple of years - it has been a useful exercise. On my twitter feed, you'll find links to the original articles I wrote about it back in 2016.
If the Placing does go ahead, and if it returns from suspension, I will probably remain sceptical in the short-term. One reason for this is that we will need clarity on new management and a new strategy.
Another much simpler reason is that it will remain debt-laden: the £125 million placing will reduce covenant debt by just £30 million. As of a week ago, the company was forecasting covenant debt of £113 million and total net debt (including its invoice discounting facility) of £150 million by the end of April.
As in the case of Accrol Group (LON:ACRL), I think the initial placing won't be enough to produce a very sound balance sheet, and more funding rounds might be required in due course.
Alternatively, it's possible that new managers and shareholders might decide to reverse out of the previous strategy and start disposing of some subsidiaries, and break up the group. That might be the most sensible thing to do.
Safestyle UK (LON:SFE)
- Share price: 92.4p (+3%)
- No. of shares: 83 million
- Market cap: £77 million
This is a manufacturer and retailer of double-glazed windows and doors.
Its share price was around 300p this time last year, as it has suffered a series of nasty profit warnings over the past 12 months. Competitive forces and fragile consumer confidence have combined to produce a continuously deteriorating outlook. You can find our coverage of Safestyle's profit warnings in the archives.
Paul covered it again in some detail last month (link), and reckoned that earnings would be permanently lower from now on, due to the difficulty of maintaining a competitive advantage in double-glazing. He has been consistently cautious towards the stock, so all credit to him for that.
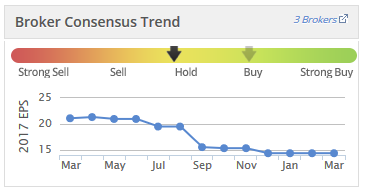
This Stockopedia graphic helpfully shows the effect of new entrants and weakening demand on Safestyle's earnings forecasts:
Thankfully, it's not all doom-and-gloom. The company is still profitable, even if this is at a lower level. And it has historically had a very strong balance sheet. Net cash sat at £11 million at December 2017.
I've added my own market to the financial highlights below:
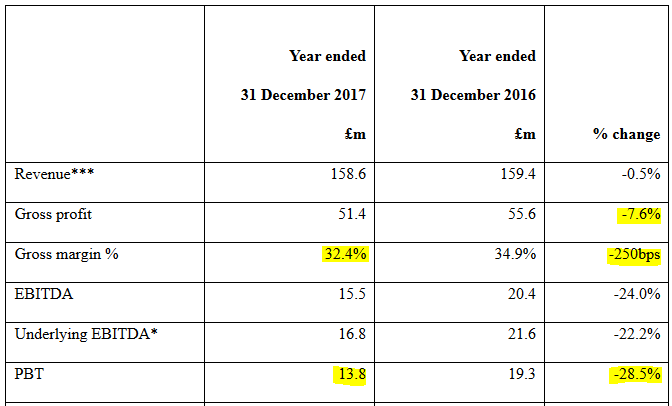
As you can see, revenue is about flat but the gross profit takes the hit with a lower gross margin. That would be consistent with lower pricing power in a more crowded industry. The company has made generous consumer finance offers to keep business flowing.
The effect of operational leverage then produces a much larger % fall in EBITDA and PBT as compared with the % fall in gross profit.
Scrolling down to the operational highlights, the company interestingly claims to have increased market share by 50bps to 10.7%. I guess there most likely has been been a big sacrifice in terms of pricing in order to achieve this.
Consumers haven't exactly been benefiting either, though. Sales prices have actually risen due to, among other things, raw material prices increasing. A combination of higher prices per unit sold and lower volumes has resulted in the flat revenue result.
Volumes are probably still falling, and were falling at a rate of c. 10% for the market as a whole during the latter part of 2017.
Dividend - the company is ploughing ahead with the same final dividend as last year (7.5p), even though this means that annual dividend cover falls to just 1.2x. I suppose this is one of the benefits of the strong balance sheet - it can afford to pay all profits as dividends, if it wants to.
If earnings fall again this year, as they are forecast to, I wonder if it will plough ahead with the same dividend? Analyst forecasts currently forecast that it will.
Outlook - not good. But the company has extended its factory in South Yorkshire and is determined to keep competing:
As a result of the deteriorating market conditions and the activities of the aggressive new competitor, the Group's order intake in 2018 to date has been weak and our market share is under pressure...
We are well invested in our manufacturing facilities and are focused on enhancing our operations, particularly through the effective deployment and utilisation of technology. Although 2018 is likely to be a year of significant challenge for all market participants, with our leading market position we are determined to participate strongly in a smaller more competitive marketplace.
My opinion
The stock has some positive characteristics - good cash flow generation, financial strength and a strong chunk of market share.
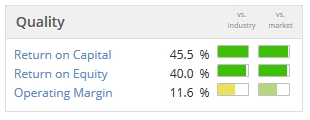
The algorithms are picking up on its positive characteristics, and give it a Quality Rank of 94.
But it sounds like the competition is increasingly eager (or desperate), using aggressive door canvassing operations to snap up leads and heap the pressure on Safestyle.
My personal view is that this is getting into a broad range where I'd consider the shares to be reasonable value. While dividends shouldn't be chased for the sake of it, it's probably worth mentioning that this dividend yield is approaching 13%.
My approach to stocks in highly cyclical and competitive markets such as this is that if I do start snapping them up, I want the market to be experiencing peak gloom when I do.
Some people might believe that we are already at peak gloom now, but I would respectfully disagree. We aren't even in a recession yet!
Strix (LON:KETL)
- Share price: 128p (-1%)
- No. of shares: 190 million
- Market cap: £243 million
This is still a fairly recent float (August 2017). It develops and produces commonly used safety controls in kettles, for which it owns the patents. HQ is on the Isle of Man, and manufacturing takes place in China.
It's numbers are in the billions. Today it reports that it sold its two billionth product late last year. Previously, it reported that its products were being used around the world over a billion times each day.
Its valuation has seemed pretty reasonable and I've been kept back from buying the shares only because 1) it has a modest debt load (probably no big deal); 2) the expectation that something will "go wrong" as it sometimes does for recent flotations; and 3) not yet having an annual report for it, as a publicly listed company.
The third of these worries will soon be out of the way, as we now have preliminary results.
And apart from those concerns, the business model is hard to fault. The main ongoing risk is that copycats, particularly from China, take a bite out of its 38% market share.
Today's numbers are in line with expectations. Revenue increased by nearly 3% and gross margin was up 120 bps to 40.7%.
Market share in "regulated" markets, i.e. those markets which protect intellectual property in the way that a western country might do, is flat at 61%.
In the "less regulated" markets, market share grew to 19%.
In both segments, the overall size of each market is growing and this growth is particularly strong in the less regulated markets, which increased by c. 12% (Strix grew by 16%).
The company does not appear to be resting on its laurels, either. A new range of controls was launched last year, which will therefore be included within a wide spread of new appliances this year.
A table illustrating Strix's controls can be seen here (external link).
Dividend - final divi declared. 2.9p is being paid for the first five months since flotation, and brokers have apparently penciled in 7p for next year.
Balance sheet - net debt is now at £46 million. The financial review says this is set to decline during 2018.
My opinion
As you might have guessed, I'm increasingly warm towards this share. Stockopedia also reckons its above-average, giving it a StockRank of 73. Check out these value stats:
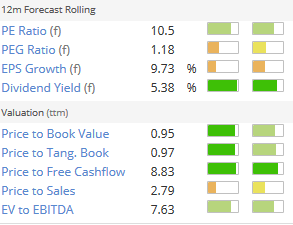
Having said that, I'm not sure I agree with the price to book value calculations above. The company has been reorganised, so the stats might need be updated with these latest figures. One of the advantages of looking at newly-listed companies is that there can be a delay before the computers figure out exactly what is going on!
I'm tempted to buy a small, starter position in this to get my feet wet, as I build my familiarity with its operations.
Cambridge Cognition Holdings (LON:COG)
- Share price: 97.5p (-14%)
- No. of shares: 21 million
- Market cap: £20 million
This stock is new to me, so I can't pretend to have any prior knowledge of it whatsoever.
It is a "neuroscience digital health company specialising in improving brain health by developing & marketing near-patient cognitive testing technologies for pharmaceutical and healthcare industries worldwide." Simples!
Paul has occasionally covered it in the past. He first covered it in late 2013. He said:
The company is currently loss-making, so is really a punt on their product taking off. It's a computerised testing system for early detection of dementia, so sounds an interesting product. The outlook doesn't sound immediately exciting.
The share price has risen in the four+ years since he wrote that, but not by an exciting amount (from 61p to 97.5p).
Also from that 2013 report was a management quote:
I believe that following our review of the business, and a refocused commercialisation strategy, we are far better positioned to deliver significant revenue growth and to move the Company towards a breakeven position in the next financial year, with significant future successes thereafter.
Unfortunately, profits have been infrequent and small so far.
Today's results for 2017 show that revenue declined marginally to £6.73 million and the company made a pre-tax loss of £284k (last year: £116k pre-tax profit).
I don't feel qualified to judge the potential for Cambridge Cognition's products and services, but I do see that reported profits might be less lumpy from now on.
The new accounting standard IAS 15 requires companies to allocate contract revenue to particular performance obligations associated with each contract. As a result, software revenue will recognised over the period of time during which a customer uses the company's software, not at the start of the contract. This does not affect cash flow.
In the company's words:
In previous years, there have been fluctuations in results from one year to the next dependent on whether a year includes a large contract win or not. We believe this new standard will result in a smoother spread of revenue over the life of a contract.
And here's how the change would have affected previous years. While there would have been less revenue from 2015-2017, the missing amounts would gradually show up in future years.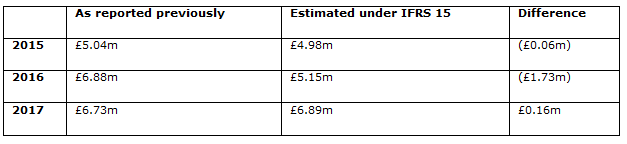
This is to be welcomed, I think. It's a more conservative revenue recognition policy, with less revenue recognised up-front but with more of the company's total revenue being recurring in nature.
Outlook - in Paul's words, the outlook comment is not "immediately exciting". Growth is signaled, naturally. Brokers, for their part, are forecasting an 18% increase in revenue this year to £7.9 million, and a modest profit result of £0.5 million.
The products and technologies developed by the Group over the past five years to supplement the core technology have seen a gradual progression of our offering in line with customer needs. With a clear focus on the needs of patients and healthcare providers in our four core disease states, we have driven testing closer to the patient using wearable and voice activated technologies. This provides a data rich assessment of brain health and provides a detailed assessment of pharmaceutical and non-pharmaceutical intervention in these complex disease areas.
Balance sheet - looks ok. No borrowings.
My opinion - I don't know enough to give a sensible view on whether this might be a good investment or not. I will say that I've seen plenty of early-stage companies which I've felt were almost certainly going to result in wipeout for investors, and this isn't one of those.
It has a particular focus on supporting drug development companies in their search for treatments for Alzheimer's disease, Parkinson's disease, schizophrenia and depression.If you have some money to spare, and want to do something which might improve general mental health, maybe that's enough reason to support this company, regardless of the investment merits?
Venture Life (LON:VLG)
- Share price: 45.5p (+6%)
- No. of shares: 37 million
- Market cap: £17 million
This is another company which is usually unprofitable, as you can see from this chart showing negative EPS:
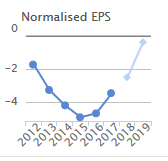
Today's results show that the company made another loss in 2017, but this was rather unlucky. It actually made a pre-tax profit of £63, but then got clobbered by a £430k tax charge.
Higher revenues and margins resulted in an 18% in gross profits to £6.5 million, which sounds encouraging to me.
I have looked at this company once or twice before. It owns UltraDEX (external link), whose flagship product is a mouthwash that's supposed to be exceptionally effective. I've tried it myself, and had no complaints about it at all, but ended up going back to the more well-known brands.
Venture Life is an active developer of its own products while also being a contract manufacturer for various customers. Contracted products are sold either under the customer's brand name or under a Venture Life name.
The nice thing about owning UltraDEX is that it puts Venture Life in contact with a lot of major retailers, both in the UK and internationally. That gives it a platform from which it can try to sell its complete range of products (food supplements, cosmetics, etc.)
And UltraDEX sounds as if its doing really well, with the "widest distribution in the UK for over 5 years", and "new listings in UK market with important pharmacy chains, to take effect in 2018." Its revenues increased 24% in 2017, and profitability multiplied four-fold.
In terms of the big-picture view, Venture Life's revenue line has made great progress:
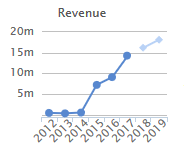
The CEO's comments are what I would hope for, based on my initial skimming of these results. He thinks the company will be "sustainably profitable going forward", as larger revenues will feed through the income statement and produce a positive net income result from now, thanks to operating leverage.
Total manufacturing capacity has increased and is now double 2017 output, so the company is ready for its next growth phase.
Dividend - it pays a very small, flat dividend, which is unchanged this year.
Balance sheet - the investment case weakens a little when you look at the balance sheet. Net tangible assets are minus £2 million, and net debt finished the year at £6.3 million. The company thinks net debt/EBITDA will fall to 2x this year, as revenues grow.
Some of this debt is quite expensive, in the form of a convertible bond with a 9% coupon attached, and needs to be refinanced next year.
My opinion - overall, I have a positive impression of the company and its prospects. There are still at least a few years to wait until the share starts to look "value" relative to earnings, but my view at this time is that the company has a bright future ahead.
The algorithms remain sceptical, only awarding it a StockRank of 17.
That's it for today! If tomorrow is quieter, I will circle back to some of today's results that I missed.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
1 Paul & Graham should write about what they want to cover. That way, we keep the quality up.
2 Allowing free access to their reports is an excellent marketing channel for the subscriptions to the paid for service.
The current business model works just fine.
For me it’s not about whether one is a subscriber or not, it is about bringing an end to readers requests. I thought Lion Tamer put the point across very well, I agree with everything Lion Tamer wrote.
Graham
The subscription pays for access to the Stocko data, not for exclusivity into Paul and Graham's opinions.
It's been said before, but it's probably worth saying again - many people here started as non-subscribers and only became subscribers after participating. So I can't see why Ed and the team would block off their own best marketing channel.
And quite why subscribers would want to deny themselves a constantly interesting and often knowledgeable set of non-subscribing posters a platform here is a mystery. The minor downside that you get occasional spam and the odd idiot posting is offset by the fact that some subscribers are sometimes idiots and that we all occasionally generate spam of our own.
Frankly, this is just about the best moderated and most polite set of investing boards around. All making the boards exclusive will do is allow people to give free reign to their feelings - there's lots of research showing that people feel that paying for something gives them the right to abuse it. As it stands a subscriber can be blocked for being abusive just as much as a non-subscriber - and quite rightly so.
Keep the boards free, minds open and conversations flowing. It benefits us all.
timarr
I don't see the need to know whether a contributor has paid or not while reading their post. If i feel there's an ulterior motive click name, click view profile, are they premium? if no, when did they sign up and latest comments. This forum is the most polite and pleasant place i have ever been online, the regulars point things out to new people without the need (very often) for moderators and administrators, i love it.
Further votes on community maters
1. Paul/Graham to write as they wish - I liked comment from someone that good quality commentary from the balance community likely to get them to write about the company (maybe on the news cycle)
2. Comments by subscribers only - reward for paying my money and best posters are likely to be more experienced/larger shareowners and thus willing to invest in Stockopedia (I think Stockopedia ethos is DYOR first and education/community/bulletin board second).........personally I enjoy both and read all comments every day but it is the data provision I buy!
3. Stockopedia mgt to think perhaps about other 'channels' than SCVR - eg employing weekly column commentator on popular areas (eg have suggested Retail/F&B in the past; others could be Large Cap focus, Financials and Resource stocks ie those NOT so often covered here..
I disagree with the above few posts. I first started contributing to Stockopedia when it started and was not a subscriber. I picked up a huge amount of information with many others, some subscribed and some didn't. The problem with subscription only contributions is that you limit very good information being passed on through the forum. The whole point of Stockopedia is to enlighten and educate those who have an interest in share ownership and it should not matter if the odd contributor comes across as less insightful than the volume posters.
I think this report is wonderful! We would all miss it....
Would like comments on the mkt in general myself; ftse breaking down through 7000 now and Dow down another 700 points plus. Could be a stampede soon to dump stock I think.
Paul and Graham are great, and I think they should just write about whatever takes their fancy including large cap, macro and even crypto!
Let's all be more tolerant, after all it's easy to just ignore any comments you don't like. No point replying in a negative manner.
Let's keep it positive and learn from each other.
Hi Graham
I really enjoy reading the reports by Paul and yourself. The insightful analysis gives me the tools I need to evaluate other shares that might not be covered by the column. I really hope you and Paul are both able to continue to contribute in this way.
Previously I've also enjoyed reading well structured and considered input from the community in the comments below each article, and occasionally when feeling brave enough that I can add something of actual value I've contributed myself. The contributions in the comments have previously alerted me to things I've missed in my own research on companies, or opened up new avenues for potential investments. The net result of yours and Paul's columns and previous comments have enriched both my understanding and pocket.
Unfortunately the trend over recent months is for the comments to become a list of demands in the general format "analyse this share for me" (notice the absence of "please", and more importantly the absence of any contribution of value to other readers). For me, this trend plus the occasional incidence of uncivil conduct (no specific reference to today's comments, this is a more general observation) have significantly reduced the value of the comments. I don't know if I am alone in this view or not, and I certainly would not want to discourage people for contributing with views and insight. Nevertheless I've found I'm more often skipping the comments as I simply can't be bothered.
My suggestion on how this could be improved, is to suggest (as Paul said on one of his columns recently) that you should write about whichever companies you want, and not ask for reader requests. If readers want their favourite share included in the column, then they should earn the coverage through adding value to their request with their own views and analysis, in the hope (rather than expectation) that they arouse your interest. However, the bottom line (for me at least) is the column is about education and insight into how to do a good analysis, rather than simply company coverage (which is probably best left to buy/sell type tip sheets).
I expect an avalanche of red-flags on this comment, but so be it. Preserving the long term value of these columns is worth that risk!
Thanks again for the outstanding quality of your coverage, and thanks for the profits I've made from your coverage (and that from Paul). I remain your avid and loyal reader.
I fully agree with you Lion Tamer 100% with all your points , the Stocko community is great and have a wealth of knowledge we should be working together to learn from each other (ultimately making us better investors) therefore there is no need for people getting involved in petty squabbles there are other sites for that !
Hi Lion Tamer,
I agree with your comments and doubt you will get any down thumbs. I think the opening up of the report to 'what do you want covered' was a mistake and has contributed to Paul's disillusionment in writing.
I agree there have been a couple of widos (https://www.urbandictionary.com/define.php?term=Wido) recently and no one wants this to turn into ADVFN. I think Stocko should seriously consider restricting comments to those who have subscribed. At least by that time you will have gauged the lie of the land before they start to contribute.
Agree with you Banzii too many people thinking their gallus !!
Even though I have been party to suggestions since it was introduced, I too would vote to go back to Paul and Graham doing what they are interested in instead of reader suggestions. I actually found more insight and satisfaction from this, opposed to looking for positive confirmation why I am right about shares I already own.
It's ok to realise the idea didn't manifest into something better and go back
Hi
I thought all comments were from subscribers only .If not what are the criteria, if any, for non members to comment. Maybe this could be flagged up as member/non member? Just a thought.
Only members can comment.
I think use of the word 'member' is ambiguous. Comment is open to anyone who has registered whether they have paid a subscription or not. Those who have paid a subscription are labelled 'Premium' on the profile page.
Aha - Was not aware one could register for free to comment - That in my opinion should be changed.
Yes indeed, that’s why there is spam sometimes, I agree think this forum should be for subscribers only. Certainly there would be more control.
That is the point I was trying to make. Comment for paid up subscribers only. OR one could show premium member status and those that have registered and are not paid up ....
Maybe a different colour for subscribers and non-subscribers, everyone is blue currently, maybe green for non-subscribers? Then is would much easier to see their status.
Lion Tamer- you have articulated my view of how the SCVR has changed, far better than I ever could.
I think it's time to stop reader requests and let Paul and Graham do what they want. Nothing wrong with readers discussing among themselves though.
Also, having to set up the template the night before must be really irritating. It's not exactly laborious, but it stops Paul and Graham from ever being able to entirely switch off. Could this not be automated by the Stocko team?
sharmvr I wouldn't bracket Strix with Accrol (I hope!) I never really got Accrol whose main supply was of the supermarkets/discounters own label products. I have connections with a company supplying supermarkets and it is alright giving some customers own label product but you really need a strong brand of your own if you are going to survive. Otherwise you are just going to get continually squeezed.
Fair point - to be honest I was more concerned about Zeus Capital! Will wait for now and do more research/follow price - maybe one for new ISA season
Striz I hold and they seem a very promising small company. They have patented products and seemingly an international market. Good forecast dividend for next year and prospects of growth..
Agreed - Strix has a lot to like and am looking forward to Graham's thoughts on the company.
Value, market leadership,
I have it on my watchlist - sub 130, but am having doubts mainly because of Accrol and the balance sheet / cash flow is not the easiest to follow (which is due to reorganisation post IPO, doesn't look dodgy to me at least).
Given market conditions, perhaps an extra dose of cynicism / scepticism is useful.
My main concerns are:
Listed by Zeus Capital (Accrol) and their prospectus mentioned how China had a strong year due to a health scare (fortunate timing) - there were some related party transactions that were cleared as a result of the fund raising.
High dividend IPO at a time when growth was good (in prospectus and trading updates)and a rather famous income oriented manager (who's flagship income fund is no longer in the Equity income sector) has a piece - nothing against him but the guy can't seem to catch a break at the moment!
Welcome the views from the esteemed participants in the forum.
I hold a very small amount of Strix however I noticed on the update today the following paragraph
''Legal actions have been initiated in relation to c.20 appliances within China that infringe our intellectual property rights. We will continue to defend our intellectual property rights, following on from the success of our previous legal actions.''
In terms of legal costs not sure how much it will cost the company as no mention on report I thought I would bring to people attention and would welcome any thoughts I hold for the moment.
Re: Strix -
''Legal actions have been initiated in relation to c.20 appliances within China that infringe our intellectual property rights. We will continue to defend our intellectual property rights, following on from the success of our previous legal actions.''
It's a bit disconcerting. But on the other hand is there a better endorsement for their products?
Good point !!
Safestyle I had at one time but wouldn't touch now. It seems that personnel have left and set up Safeglaze almost around the corner. The TV adverts in the north-west which were often by Safestyle and now Safeglaze with Safestyle seemingly having gone quiet. Unless they can get a grip I can only see lower profits and big risk of further downside
Re: Safestyle commented on by doublelutz.
Yes I also once held Safestyle but my impression is that there is still plenty of scope for Safeglaze to take business from them and the competitive landscape has changed fundamentally and possibly permanently since I invested. I thought Safestyle's marketing spend on TV adverts would provide better protection from competitors but it seems that consumers of double glazing just look at the price. It has to be said that the internet must also make it easier for small competitors to market effectively. I also feel a bit uncomfortable about the number of Safestyle employees or contractors who have been in trouble with HMRC including the person fronting some of their TV adverts. Safestyle's web site also reveals that it seeks "self-employed" people to work for it and I wonder if it may be at risk from HMRC or employment tribunals who might claim that some of these workers are actually employed. This area has been in the news quite alot lately from the likes of Uber.
I have followed Safestyle for a few months now and thankfully never taken the plunge.
Other than sector and so on, I thought the value was their strong balance sheet allowing them to consolidate much smaller companies and run them more professionally and take advantage of operating leverage and better efficiency.
It seems to me that once acquired, the sellers start back up, with presumably deeper pockets.
At current prices, would say it is certainly getting interesting but would like to see how the next results pan out and in particular the margins side of things.
Thanks for another great review.
I'd love to read your views on Sopheon which reported this morning. I'm already a holder and the results look extremely encouraging - but I would welcome a more professional assessment.
Produce Investments (PIL) has never been looked at on this site. Why?
Mkt Cap £44M P/E 7 Has Debt but solid looking balance sheet. Well covered 5% divi.
But neither Paul or Graham have ever looked at it. Potatoes too boring probably!
Probably never will be either if you use that approach.
What do you mean by "use that approach"? I'm willing to learn from your obvious superiority.
It has been actually: https://www.stockopedia.com/share-prices/produce-investments-LON:PIL/discussion/
Thanks for the link. Not much use to me as its 3+ years ago.
Think 3 years ago is still a shorter period than never, but as always DYOR and RYOC!
Personally a big fan of boring products - but ideally dividends be covered by free cash, not just profits. Further, they seem to have no control over their business (Tesco tells them the sale price, weather tells them supply).
Given earnings volatility, this is not the kind of boring company I would like, but appreciate the suggestion and will look into.
Not sure potatoes are a big growth area - sweet potatoes maybe (prefer the regular myself)
On a separate note, your comments (or specifically the responses to others) come across a little patronising / flippant (my interpretation) - There were no down votes on your very first comment.
I think Paul's comments are well worth reading and I can see why it has not been discussed on the SCVR since. Actually the last 2 posts were last year but did not generate any interest.
My opinion a few things I don't like about Produce Investments (LON:PIL), supermarkets, weather and debt. Also momentum is negative. I tend to avoid these type of companies because sooner or later there will be another profit warning.
Congratulations Mathew, I saw less red thumbs during my recent attendance at the 'Blind Cobbler's Convention'
Wow. My first comments on this site and I get a "reported for disruptive behavior". Trouble is I still don't know what matylda meant by "Probably never will be either if you use that approach." To my request for Graham to look at a stock.
Anyway sorry if I upset you all. I'll not post anymore. I think I'm a bit too thick.
Matthew - you say "My first comments on this site" but your profile suggests otherwise. It shows 11 comments here in 2013 which, at a quick glance, look like useful contributions with a good number of 'thumbs up'. If you could revert to that style I don't think there would be a problem.
Sorry, I should have put "My first comments on Grahams site".
Regarding matylda comment to me "Probably never will be either if you use that approach" in reply to asking for Graham to look at PIL. I would like to apologize. I thought she/he was laughing at my rather basic company analysis. Reading it back I now realize it was probably because of the rather crude and abrupt manner of my post.
Sorry to Graham and Matylda. Too much much time reading dodgy posts on ADVFN is my only excuse.
Quixant (LON:QXT) please Graham
Seconded. A super high growth stock. PEG<1
Thanks for all the suggestions, I will update my list of stocks to cover. G
Hi Graham
If you get a chance to look at Sopheon (LON:SPE). Final results today, reflecting their previous trading update showing strong Q4 growth.
Best wishes
Greyster
VLG looks interesting if you have time to review the company:
· Maiden profit before tax of £0.1 million (2016: loss of £1.1 million)
· Adjusted earnings* per share of 0.66 pence (2016: loss per share of 1.28 pence)
· Cash positive H2 2017
· 'The net debt to EBITDA multiple sat at 3.5 times at 31 December 2017, but we expect this to fall significantly during 2018, to much closer to 2'.
As Utilitywise (LON:UTW) was released from suspension at 9:00am any remaining shareholders (and surely there can't be many on here) are now able to sell and replace with Inspired Energy (LON:INSE).
There are a couple of interesting questions which I shall be pleased to have the teams thoughts on-
- At a price of 35p is UTW, having now put revenue recognition on the basis it should have been all along, no longer a value trap but a company with a future?
- If the communists take over the assylum and renationalise everything what happens to the INSE and UTW business model with only a single energy vendor in McDonnell Plc?
I am a long term holder of one of the above shares having never touched the other but due to EU privacy rules can't reveal which one I hold.
Cambridge Cognition Holdings (LON:COG) just released final results today for FY2017.
Very much jam tomorrow promise, with lumpy sales and lack of profit. One of the highest gross margins I've ever seen!
Simon Thompson is a strong bull on this share, having tipped it a few times over the last year.
For me they might be doing exciting things academically and scientifically, but not focused on extracting maximum profits and returns for shareholders. Lifestyle business run for the benefit of the directors?
I had a quick look at Cambridge Cognition Holdings (LON:COG) but could not see the gross margin, what is it? Bioventix (LON:BVXP) has a operating margin of 78.9% which the highest I know of in that sector, Burford Capital (LON:BUR) is higher at 79.8. I would beware of ST tips, use a stop loss. Does not look attractive to me.
Cambridge Cognition Holdings (LON:COG) - GM 91%
Bioventix (LON:BVXP) - GM 93%
Big difference is Cambridge Cognition Holdings (LON:COG) has an operating margin of 1.7% - and the market seems totally underwhelmed with today's results.
BTW herbie - any thoughts on Monday's interims for Bioventix (LON:BVXP) ?
Phil
Hi Phil, thanks for those figures. Craneware (LON:CRW) is also higher at 94.3 and a few others as well. But it's the operating margin that counts.
Re Bioventix (LON:BVXP) I'm really not sure, I'm hoping they will be up on last year and I expect them to beat the forecasts.
Bioventix (LON:BVXP)
Yeah, sold out after last years finals after watching them drift for a bit.
Key seems to be the Seimens Troponin project and that seems to be in the lap of the gods. Can't decide whether to get back in or not. Believe they will beat forecast this year, but info. on future growth a bit opaque.
Phil
"Key seems to be the Seimens Troponin project and that seems to be in the lap of the gods"
I don't think that Troponin is as key as is sometimes assumed. There is an excellent post by VegPatch after he met management on a thread here: https://www.stockopedia.com/content/bioventix-fy-results-v-strong-look-how-fast-the-core-is-growing-to-offset-loss-of-nt-probnp-229328/#comments
(Post 12). He (VegPatch) is quite clear that they are his estimates/guesses, not managements words, but they look sensible to me and show potentially 3 income streams having the potential to grow individually to replace NTproBNP (1m lost from FY18 onwards) by FY21 - drugs, Progesterone and Troponin. Any one of them meeting those estimates would be +1m from today individually.
As for the upcoming results, I've no idea what they will be like, but I know what I'm looking for. Bioventix (LON:BVXP) did 3.12m in H1 2017, and 4.12m in H2 (+32% HoH). Assuming 0.45m and 0.55m for NTproBNP for H1 and H2 respectively, and assuming no NTproBNP royalties in H1 2018 (there may still be some), then zero growth in everything else from H2 '17 to H1 '18 would see +15% (sales) H1 '18 vs H1 '17. I would regard that as a poor result. 20% growth from H2 '17 to H1 '18 in everything else would see +37% H1 '18 vs H1 '17. I would regard that as an outstanding result. 10% growth H2->H1 would see +26% H1->H1, that's what I'm realistically hoping for.
Bioventix (LON:BVXP) is one of my 3 largest positions (the others are Burford Capital (LON:BUR) and £ACSO), so hoping for a good update!
Hi
Bioventix (LON:BVXP)
Many thanks for that.
Phil
Hi Phil,
Thanks, but in hindsight the only useful part of my post was the link to VegPatch's post.
My musings about upcoming results completely neglected to consider currency effects and seasonality (shouldn't post at 23:45!). Looking though Bioventix (LON:BVXP) last 3 years I see:
Revenue
H1 2015: £1.93m
H2 2015: £2.40m
H1 2016: £2.37m
H2 2016: £3.15m
H1 2017: £3.12m
H2 2017: £4.13m
So there appears to be some significant seasonality in favour of H2. In light of that, I won't be panicking if H1 2018 revenue comes in similar to H1 2017, given that it won't include much NTproBNP.
(I've used H1 to refer to the interim results half, Bioventix confusingly seem to refer to this in H2 in the interim statements since it falls in the second half of the calendar year).
Hi
Bioventix (LON:BVXP)
I picked up the seasonality when I looked into further after your post - and I did put my toe into the water on Friday.
Interims look good to me. Have grown from H1 2017, ignoring the back-dated royalties following audit, which implies the existing core antibodies etc have grown by 20%+ to replace and more the lost revenue. Would have preferred some more detail on Troponin but I guess it's still early days.
I think a big plus for me was the update was remarkably upbeat compared to their normally cautious statements. I guess I should beware reading between the lines but it is somewhat reinforced by the 20% increase in interim dividend.
Phil
Hi Graham,
Not sure you’ll have time for this one but maybe others are interested. Venture Life (LON:VLG) released final results this morning. They are in the space of making supplements, cosmetics and devices aimed at the aging market (so potential growth area). Very small at just 16.4m market cap.
They have been loss making up till now but have just managed to scrape a profit. This and 1.6 million in the bank should hopefully stave off any need for a placing just to survive.
Currently up 16.3% today so the market seems to like it. I hold a very small position which I bought after seeing a video of the founder at the UK Investor Show a couple of years ago.
re: Venture Life (LON:VLG),
Thanks for the suggestion Banzii. I'm working on this one now. G
Strix (LON:KETL) please. Floated on Aim last August so results to Dec represent 5 months trading. Revenue up 2.9%, profit after tax up 10.8% gross margin up1.2%. Net cash up, net debt down. Dividend equates to annualised yield of 5.4%. Market leaders in kettle controls with approx. 38% of global market supplying most well known brands and cumulative sales exceed 2bn products. Within market for regulated products STRIX have market share of c61%.
"Healthy start" to current year's trading.
Any chance of a look over Safestyle UK (LON:SFE) and £STRIX both in line but in construction and retail which have been poor sectors to be in currently just wondered if you thought any value at current prices with either stock.
Nice suggestions, thanks clarea.
Inspired Energy (AIM: £INSE), a small cap and "a leading UK energy procurement consultant to UK
and Irish corporates and SMEs, announces record final results for the year ended 31 December 2017" and yet Profit Before Tax has gone down to £3.55m from £4.02m (minus 12%) and Basic EPS down to 0.48p from 0.71p(minus 32%). The other numbers look more positive. A second RNS released at 7.05am concerns Inspired Energy acquisitions of SystemsLink & ECM and the follow on Issue of Equity. Thoughts? In the same field are Utilitywise plc their Questions And Answers For Shareholders RNS is interesting.
re: Inspired Energy (LON:INSE).
Mercury, I'm not too familiar with that company but I'll see if I can do something on it later. Cheers.