Small Cap Value Report (Thu 23 Sept 2021) - BEG, FNX, XLM, DFS, FCCN, VLG, EVE

Good morning, it's Paul & Roland here today. Today's report is now finished.
Agenda -
Paul's Section:
Begbies Traynor (LON:BEG) (I hold) - AGM trading update says the company is confident about delivering market expectations for FY 04/2022. Acquisitions are going well. This share looks good value to me, and should benefit from the withdrawal of Govt support measures. Hence I'll be buying any dips in the coming months, to add to my position.
Dfs Furniture (LON:DFS) - sparkling results for FY 06/2021. The balance sheet is still weak, but has improved a lot. Clear guidance given for the current year. Obviously supply chain problems are an issue for everyone, so a range of profit guidance is provided. Given the significant improvements, I'm happy to turn positive on this share.
French Connection (LON:FCCN) (I hold) - announces (without their consent) that a consortium of investors is mooting a cash bid at 30p/share. Let's hope this smokes out a more generous bid.
Venture Life (LON:VLG) - a poor market reaction to interim results, with the shares down 14%. As mentioned in my last review of this company, it's difficult to value now, because 2 material acquisitions are not yet bedded in. Let's see what the numbers look like in future. For now, I'll continue to steer clear.
Eve Sleep (LON:EVE) (I hold) - a quick look at its interim results. Outlook comments give me some hope. This is a special situation, value share, not a regular type of investment, so won't interest most readers.
Roland's Section:
Fonix Mobile (LON:FNX) - a strong set of figures from this mobile payments specialist, but I have some concerns about long-term growth and the risk that its technology could become redundant.
Xlmedia (LON:XLM) - the renewed management team is doing all the right things to turnaround this digital marketing business, in my view. But I remain concerned about the underlying durability and quality of its earnings.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Begbies Traynor (LON:BEG)
132.6p (last night’s close) - mkt cap £202m
Begbies Traynor Group plc ("the group"), the business recovery, financial advisory and property services consultancy, is today holding its Annual General Meeting...
The current financial year is FY 04/2022.
This is the most important bit, on current trading & outlook -
In the first quarter of the new financial year, commencing 1 May 2021, we have achieved double digit growth in revenue and profit reflecting the benefit of our recent acquisitions and the bounce back in activity from last year's lockdowns. At this early stage of the financial year, we remain confident of delivering market expectations* for the full year.
* current range of analyst forecasts for adjusted PBT of £17.0m-£18.5m (as compiled by the group)
Note the shareholder-friendly footnote, many thanks for this.
Other points -
- Acquisitions doing well.
- Since May 2021, insolvencies have been rising, expected to continue as Govt support measures are phased out.
- Diary date - interim results due out in Dec 2021
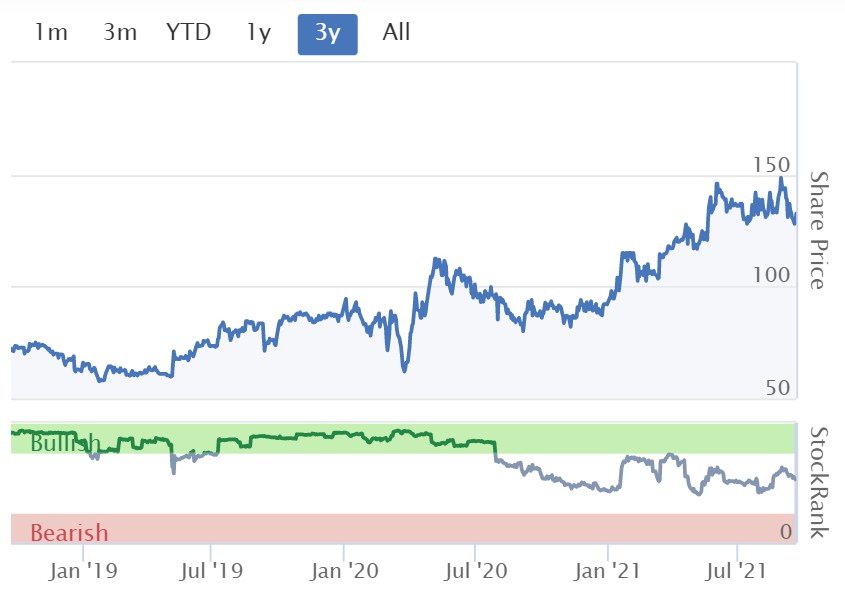
Track record - an impressive track record is being built up, which I think has not yet been properly reflected in the rating given to BEG by the market. This is an impressive growth business, which has made a series of canny acquisitions. But it’s still being rated as a value share -
Over the last four financial years, we have delivered compound annual growth in adjusted earnings per share of 20%, including 10% organic growth. Over the same period, we have moved from net debt of £10.3m to net cash of £3.0m at the year end, whilst making value-enhancing acquisitions and delivering 8% compound growth in dividend per share.
Valuation - many thanks to Shore Capital for issuing an update note this morning. It’s pencilled in 8.5p EPS for FY 04/2022, which is consistent with the 8.86p EPS consensus forecast shown on the StockReport. I’ll push the boat out a bit, and say I reckon a more realistic figure is probably 9-10p EPS for this year, so that’s what I’m going to use for valuation.
With a share price of 132.6p before the market open today, that gives us a PER range of 13.3 to 14.7.
I think there’s scope for this share to re-rate to a PER of 15-20, which implies a share price target of 135-200p. Hence decent upside. Also that’s only based on this year’s earnings, and doesn’t factor in any future growth or more acquisitions, which would add further to this price target range, longer term.
EDIT: an update note has just come through from Equity Development, which forecasts 9.2p EPS, higher than Shore Capital's 8.5p, and more in tune with my 9-10p range. End of edit.
My opinion - this share looks attractively valued to me. It’s a growth company, priced as a value share, which seems anomalous. Hence I see scope for a decent re-rating, if we’re patient.
The core insolvency practice business is very specialised, and high margin work (c.30% profit margin). So it’s strange to see a high quality business on a low rating. Maybe the market has not yet cottoned on to the fact that the business is growing well now? It did go through a bit of a flat patch a few years ago, and investor perceptions persist. Here are the SCVR, we're eager to change our minds, once the figures/outlook change, that's why we turned positive on this share in early 2021, when it became clear that stronger growth was coming through.
There are likely to be many companies requiring restructuring services, as furlough & business rates support are phased out.
Personally, I picked up some shares in early 2021. Based on revisiting the figures today, I’ll be buying some more when funds permit.
.
.
Charity pledges
Just before I get on to looking at Dfs Furniture (LON:DFS) next, I wanted to share some wonderful news with you.
Renowned investor David Stredder (who also founded Mello Events) came up with a great charity fundraising idea a while ago, where investors set a price target for a share we like, and then pledge a charity donation (free to choose the charity, and the amount), if the share price target is hit. This makes charitable donations fun, and self-funding! More details are here.
The list of investor pledges to charities is here.
One pledge astonished me for its generosity, a £25k pledge to my favourite African humanitarian aid charity, ZANE, from an investor who wishes to remain anonymous, using the psedonym Investore1. I did wonder if it was pie in the sky, but the wonderful news is that Investore1's chosen share, Polarean Imaging (LON:POLX) (I hold) smashed through its price target yesterday, and the £25k has been received by ZANE, with thanks.
Even better, investore1 has pledged another £25k to ZANE, if Electra Private Equity (LON:ELTA) (I hold) gets to 700p by the end of 2021.
It's a fun thing, and I'll give some thought to putting in some more pledges myself soon. I can't get anywhere near to investore1's level of generosity, but every pound counts, so size doesn't matter. Thanks again to investore1 - that donation will literally save & greatly improve many lives out in Zimbabwe.
Right, back to shares...
Dfs Furniture (LON:DFS)
266p (down <1% at 08:45) - mkt cap £689m
DFS Furniture plc (the "Group"), the market leading retailer of living room and upholstered furniture in the United Kingdom, today announces its preliminary results for the 52 weeks ended 27 June 2021 (prior year comparative period is the 52 weeks ended 28 June 2020, non Covid-19 disrupted comparative period is the unaudited pro-forma 52 weeks to 30 June 2019(2)).
MARKET OUTPERFORMANCE DRIVEN BY OUR SCALE AND INTEGRATED RETAIL MODEL,
CREATING A SUSTAINABLE BASE FOR FURTHER GROWTH
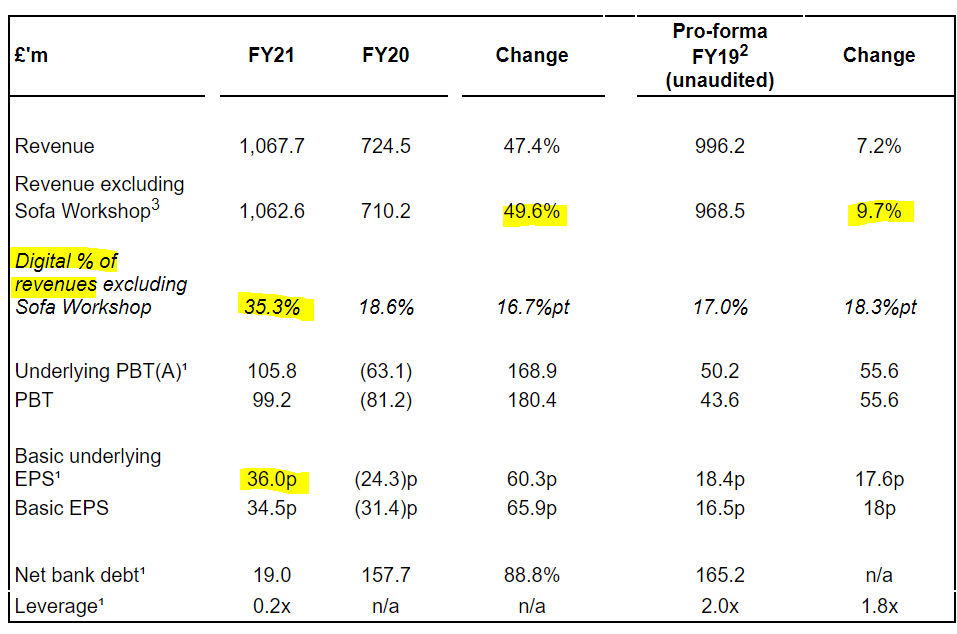
The highlights table is very good - giving 3 years, so we can see the changes both from last year, and from pre-pandemic trading. Very clear, and informative - all companies should be reporting like this.
The numbers look fantastic, and profit/EPS seems to be way ahead of the consensus forecasts shown on the StockReport -
.
Also note how the % of sales done through the internet has almost doubled to 35.3% - which calls into question the uniqueness of Made.com (LON:MADE) and its premium price. If DFS is achieving similar sales online, and rapid growth, then maybe we should be piling into DFS, instead of paying a premium for MADE (which doesn’t make much profit yet)?
Adjustments to profit are small this year, so I’m happy to rely on the adjusted numbers.
High order bank - that will be recognised in H1 of the new year, FY 06/2022.
Strong consumer demand continues to be experienced over the first 12 weeks of FY22 with the current order bank at a record high, providing further resilience.
Supply constraints - the well-publicised problem area for all companies that move physical goods around -
Current trading
As detailed in our year end trading statement, strong customer demand in the final quarter of FY21 was already expected to underpin revenues and profits in the first half of FY22. Order intake has also remained strong in the current financial year to date, well ahead of our previous scenario of +7% growth on FY19, resulting in an order bank that continues to grow and which in absolute terms is very significantly ahead of normal levels.
This order intake provides significant resilience, and confidence in our outlook. However the constraining factor on our reported short-term financial performance will be our pace of conversion of the order bank, which depends on both our supplier partner manufacturing capacity and also the capacity of our proprietary logistics operations.
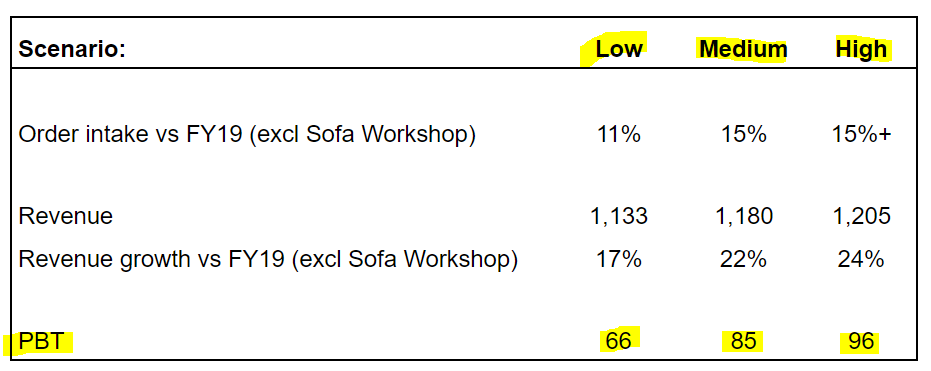
We believe the Group is well placed to achieve the medium scenario of our range of FY22 profit outcomes identified back in June.
We already have increased output capacity significantly in FY21. We continue to strengthen our operations, increasing warehouse capacity and resourcing levels, to meet customer demand. Notwithstanding this, it should be recognised that the short-term operational environment continues to be exceptionally uncertain and difficult, given well-reported logistics disruption, cost inflation pressures and unplanned Covid absences.
We believe that we have the right plans in place to mitigate these impacts, underpinned by our scale, operating experience and long-standing relationships, and we are focused on delivering good customer service, protecting our colleagues and creating long-term value.
Balance sheet - is still weak, but getting less bad.
NAV: £284.5m. Intangible assets are £535.4, which gives us a very weak NTAV of negative £(250.9)m.
However, I would improve that by stripping out the IFRS 16 lease numbers, which are not of any importance at such a profitable company. That removes £345.1m right of use assets, and liabilities of £88.1m, and £366.0m. That means we can add back £109m onto the balance sheet (since IFRS 16 liabilities exceed assets by that amount), which reduces the deficit of NTAV to £(141.9)m. For the first time, I now see this improved situation as being tolerable. It’s far from good, but the big profits of FY 06/2021 have gone some way to repairing the balance sheet.
Also, we have to take into account that furniture retail has a lovely reverse working capital structure - customers pay up-front, so DFS benefits from sitting on the customer cash before the product has even been made. Then after a time lag (as most things are made to order), DFS is paid in full, and pays the supplier some time later.
As we’ve seen, even during lockdowns, there are enough orders in the pipeline to continue deliveries to customers. Then when lockdowns end, pent-up demand causes a surge of new orders. Along the way, more sales have been moving online too.
What’s even more remarkable, is that a combination of factors have combined to almost eliminate the previously heavy interest-bearing bank borrowings.
This is a very much improved position.
Guidance - wonderful clarity is provided, as usual - this low, medium, high range of guidance is absolutely spot-on, and really should be standard practice for all companies. It helps investors, but it also tells us that the company is in control of its business, and finances, thus giving me confidence.
.
My opinion - this is very encouraging. For the first time, I would consider investing in DFS, because the risks have now reduced to a level that is acceptable to my (admittedly quite strict) criteria.
Supply chain issues are only temporary, so long-term investors shouldn’t really be worrying too much about such short-term, fixable issues.
Remember also that furniture retailers actually benefit from supply chain delays - more delays and a longer order book, means more cash in the bank. When supply chains ease, and order backlogs reduce to normal, then the cash pile would reduce, or rather net debt would increase.
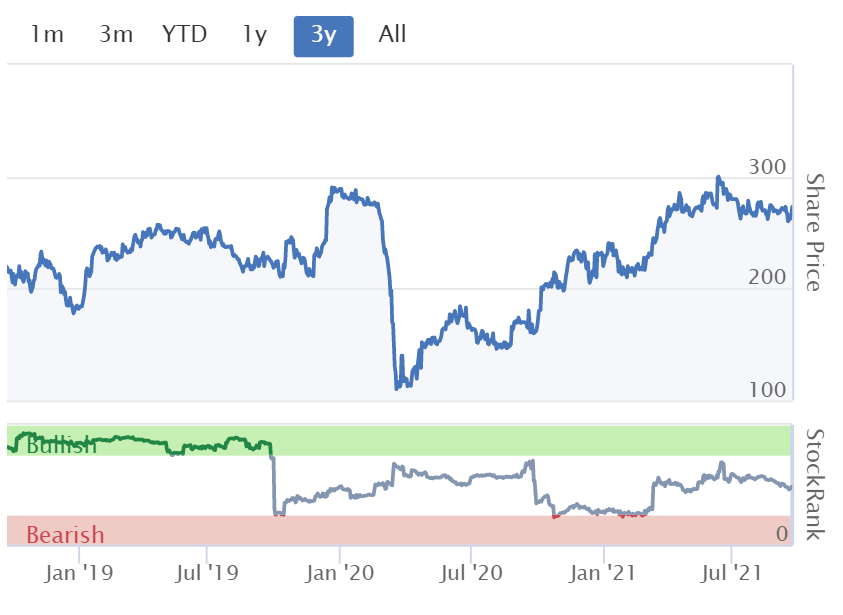
My sector favourite remains Scs (LON:SCS) and these strong figures from a larger competitor augur well.
.
.
French Connection (LON:FCCN)
26.5p (up c.15%, at 11:24) - mkt cap £25m
Statement re Share Price Movement
A possible bid approach has been received at 30p cash -
... it has received an approach from a consortium of bidders including the Company's second largest shareholder Apinder Singh Ghura, Amarjit Singh Grewal and KJR Brothers Limited (the "Consortium") as a potential offeror for French Connection Group Plc, which may or may not result in an offer for the Company. The indicated offer price is 30 pence per share in cash.
Discussions with the Consortium remain ongoing…
This announcement has been made without the consent of the Consortium.
My opinion - I’d be surprised if the founder is willing to sell up for only 30p.
However, the fact that the company has put out this announcement, without the consent of the consortium, and is continuing to discuss it with them, does suggest we might be nearing the end game maybe?
FCCN probably wants to smoke out other potential buyers.
I remain of the view that the brand is well-known internationally, generates significant profits from wholesale & licensing, hence is clearly a valuable brand. That’s been obscured by the retailing division losses, as we’ve discussed here many, many times over the years!
I’ve still got just over 1% of the company, so will sit tight and see what happens. Personally I’d be happy to accept any offer of 50p+. Stephen Marks, the founder, will be making the decision, as he has a near-controlling stake.
.
Shorter sections now, to rattle through a few more companies.
Venture Life (LON:VLG)
Down 14% to 56p - mkt cap £71m
I've just re-read my notes here on VLG’s profit warning on 13 August 2021.
Skimming through its interim results out today (which the market clearly doesn’t like, with the shares down 14% today), and there’s not a lot more to add.
H1 adjusted profits halved to £1.3m. Last year benefited from one-off sales of hand sanitiser. H1 statutory profit is about breakeven.
The cash pile has mostly been spent on 2 acquisitions, as planned.
Balance sheet looks OK overall, although I think the £50m bank facility for acquisitions looks excessive & risky.
Personally I would attribute little value to the existing businesses, with the main value probably coming from recent acquisitions, which will materially increase the size of the group’s revenues & profits.
My opinion - I don’t want to guess what profits the recently acquired businesses might achieve, that just seems a risky approach to investing. For me, the less guesswork, the better. Hence why I’m happy to sit on the sidelines, and watch. I’ll be happy to review the numbers next year, once the acquired companies are bedded in.
For now though, I’ll neutral/avoid this share, because I don’t know how to accurately value it.
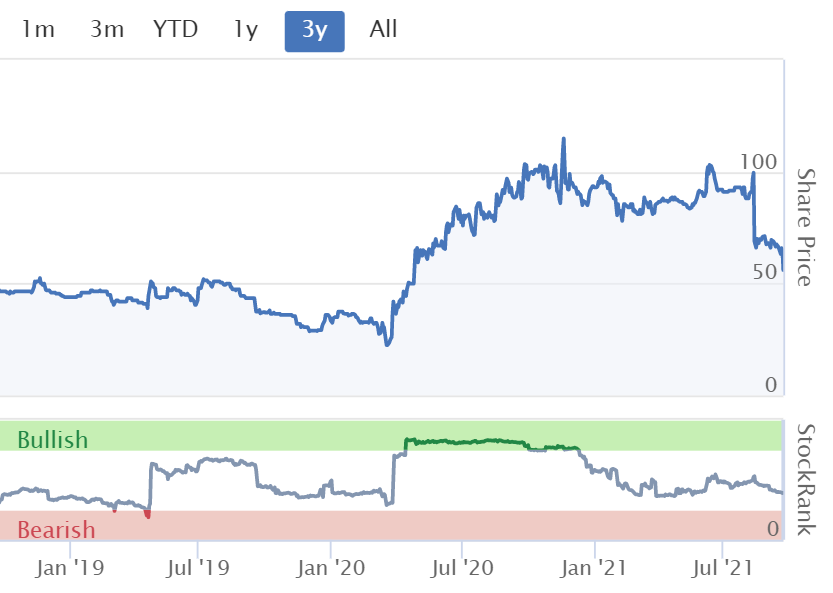
It's interesting to see from the chart below that, like many other companies which had a speculative boost from the pandemic, a lot of that froth has since blown away.
.
Eve Sleep (LON:EVE) (I hold)
3.8p (up about 5% at 12:58) - mkt cap c.£10m
eve Sleep, the direct-to-consumer sleep wellness brand operating in the UK, Ireland (together the "UK&I") and France, today issues its results for the six months ended 30 June 2021 (the "Period").
I’d describe this as a special situation - where the original high growth business model hasn’t worked, but there’s plenty of cash left, and still a potentially viable business.
Somebody might buy it, given the low valuation, even if it’s just to take out a competitor.
So I’d be happy with a potential exit at say double the current price, but don’t have any expectations beyond that.
H1 numbers look poor at first sight -
Revenues up 13% to £13.9m - not too shabby this bit
Loss before tax of £2.3m
Cash pile sharply down from £8.4m to £5.2m in the last 6 months - this is a worry, as the cash pile was my main comfort (weighted!) blanket. It’s still about half the market cap, but will it be burned through in continuing marketing spend?
The commentary reassures me on the main issue, cash burn -
The company remains on-course to deliver the Board's previous full year expectations, with the strength of the UK&I trading expected to offset any variability in the French market. Marketing investment which was up £1.4m year-on-year in the first half, was front loaded, and is expected to be broadly flat in H2. The cash outflow in the first half of the year exceeded the operating performance by some £1.2m reflecting £0.9m for the timing of payments to HMRC and higher stock levels, as well as £0.3m for additional working capital movements.
Net cash at the end of August increased to £5.9m, from £5.2m at 30 June, with the cash outflow over the remaining four months of the year expected to be minimal.
Supply chain has “held up well”
There are some positive elements in the current trading section -
Trading in the UK&I in July and August has been above the Board's expectations, driven by ongoing strength in eve's ecommerce channel. While the comparatives in the prior year were very strong, eve's UK&I sales in July and August increased 46% on 2019 pre-Covid equivalents. The new sleep away range has been a standout performer, and has surpassed all expectations with its early sales, though demand has also been strong for the rejuvenated bedding range and the premium 'spindle' bedframe.
My opinion - it’s obviously a fairly low quality business, so not something I would normally touch. However, for me this is a potentially interesting value special situation, with half the market cap in cash, and some signs of life with current trading, and new products.
At £10m market cap, I think there might possibly be a value situation here? It’s not a high conviction one though so I’ve only sized my position quite small (under 1% of my portfolio).
.
Roland's Section
Fonix Mobile (LON:FNX)
Share price: 150p (pre-open)
Shares in issue: 100m
Market cap: £150m
This mobile payments and messaging stock floated in October 2020. The company’s core business is allowing consumers to make payments that are charged to their mobile bill through carrier billing or SMS billing. The main client sectors are media, charity and gaming.
Despite my general caution about recent IPOs, Fonix appears to be highly profitable and growing fast. Checking back through the archives, Fonix’s half-year results were covered here by Jack in February. They showed a fairly solid picture - let’s see how things have changed in the six months since then.
“Strong earnings growth and momentum”
Today’s full-year results cover the 12 months to 30 June. They show continued growth in client numbers, revenue and profits.
- Total Payment Volume (TPV) +10.3% to £233.4m
- Revenue +19% to £47.7m
- Adjusted pre-tax profit +14.6% to £8.3m
- Adjusted EPS +14.7% to 7.0p
- Final dividend: 3.53p
- Unrestricted cash balance +158% to £5.0m
The company says that all three of its business segments have performed in line with expectations since Fonix’s IPO in October 2020. Today’s results are indeed very close to the consensus figures shown by Stockopedia.
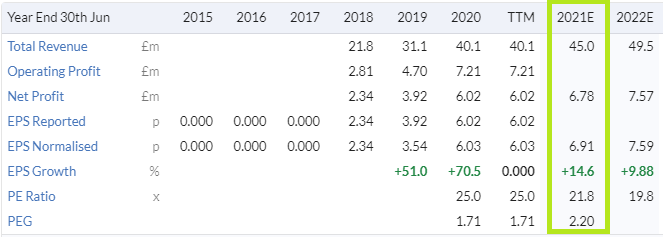
Profitability remains strong. My sums indicate:
- Operating margin: 16%
- Return on capital employed: 134%
These are slightly below last year’s figures, but I suspect that reflects costs and changes connected with Fonix’s IPO. In my view, Fonix still boasts very attractive levels of profitability.

The company’s operational metrics also show progress.
- 34 new customer contracts signed, increasing customer count by 13% to 111
- 18m unique mobile users made 628m interactions with Fonix’s services
- Record £32m payment volume processed in a single month
- 50% increase in number of charity clients
- 100% client retention, with over 99% of income of a repeating nature
Customer numbers: Growth in new customers and 100% client retention sounds impressive. But the numbers don’t quite add up for me.
Today’s results show that 34 new contracted customers were added last year, lifting the number of active customers by 13% to 111 last year. The comparable number of active customers at the end of FY20 is given as 98.
Fonix defines an active customer as one that has generated at least £500 of gross profit over the last 12 months. So today’s active customer numbers appear to imply that 21 customers have become inactive (given that the company reports 100% client retention).
In fairness, I’d guess that some inactive customers may be new customers who have signed up, but not yet activated their services. But I suspect that there may also be some previously active customers who have become inactive.
If a customer has not generated £500 of gross profit in 12 months, I think we might question how valuable their business is to Fonix.
Outlook: Fonix reports a
“positive start to FY22, with trading in line with the Board’s expectations”.
The company says it is building the foundations for international growth and has won its first international payments contract. Management says that a number of existing multinational clients are looking to expand Fonix’s services overseas. International markets are expected to provide “a meaningful contribution to growth” in the years ahead.
By leveraging existing customer relationships and technology, Fonix expects to incur minimal costs and benefit from a high degree of operating leverage as it expands.
House broker FinnCap has left its FY22 forecasts unchanged today, so for now I think we can rely on the consensus figures in Stockopedia. These show earnings growth of 10% this year, putting Fonix on around 20 times forecast earnings, with a 3.5% dividend yield. That doesn’t seem unreasonable to me for a growing, profitable business.
My view: Fonix has an impressive roster of clients, including ITV (I hold), Bauer Media and Children in Need. My feeling is that the key attraction for clients is that Fonix’s services facilitate impulse/emotional transactions by making them seamless and removing the upfront payment process. This isn’t true with other payment methodologies.
The key question for me is whether this service is a stopgap that will eventually be made redundant by (future) payment functionality in Apple Pay and Google Pay. I’m not an expert in this area, and it may be that Fonix offers additional functionality that’s not available elsewhere.
Another potential attraction is that Fonix’s solution is guaranteed and universal - it does not depend on whether users have configured card payments through their phone.
On balance, I’m impressed with Fonix’s continued growth and profitability. I think the shares could be attractively valued at current levels. But I do have some reservations about the longevity of its technology. I’d also like to know more about customer activity levels.
.
Xlmedia (LON:XLM)
Share price: 49.9p (-6% at 09:00)
Shares in issue: 262.6m
Market cap: £128m
Half-year results & Acquisition of BlueClaw Media
This Israeli digital marketing company has made and lost fortunes for shareholders since it joined the AIM market in 2014. This business makes money by publishing informational websites which generate new customer sign ups for casino, sports betting and personal finance businesses.
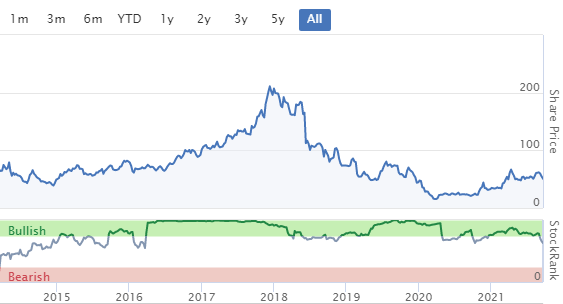
When I last looked at XLMedia in May, I took a cautious stance and explained my reservations about this business model.
Today’s half-year results have again received a cautious reception from the market, sending the stock down 5%.
Financial highlights
The headline figures for the six months to 30 June look strong, but profitability is suppressed due to “transformational activities”. In other words, this is a turnaround situation.
- Revenue +16% to $32.2m
- Adjusted EBITDA +29% to $6.6m
- Transformation costs of $1.0m (H1 2020: $1.5m)
- Reported pre-tax loss of $0.4m
- Cash and short-term investments of $36.9m (31/12/20: $13.9m)
Divisional results show progress with diversification, but the vast majority of revenue still comes from gambling of one kind or another:
- Sports: $11.7m revenue, split roughly equally between EU and US markets
- Casino: $12.5m revenue
- Personal finance: $6.6m revenue- this US-focused business is being built around the Money Under 30 site, which XLMedia acquired in 2017. MU30 Founder David Weliver is leading the business and editorial activities.
Transformation programme
XLMedia’s transformation programme is focused on building portfolios of fewer, higher quality websites. The company aims to cut its portfolio from more than 3,000 websites to “fewer than 100”.
More emphasis is being placed on quality content and site structure. In my view, XLMedia is now focused on building genuine editorial-led websites, rather than thinly-disguised advertorial. I would say this is an essential - and overdue - change.
However, costs seem to be high. Today’s report shows just $1m of transformational expenses, but the cash flow statement shows $11.9m of spending on websites, domains and software. This follows on from $12.8m of such spending last year.
Acquisition: XLMedia has acquired Leeds-based SEO agency BlueClaw Media for up to £1.8m. BlueClaw has been working for XLMedia over the last eight months, so presumably this deal is designed to bring a valued service provider in house.
Outlook
The outlook for the full year is unchanged, with revenue guidance of $65-$70m. However, costs are expected to be higher this year than previously guided, as the company accelerates its pace of change.
House broker Cenkos is forecasting adjusted earnings of 3.3 cents per share in 2021, rising to 6.6 cents per share in 2022. These are slightly ahead of the consensus figures shown in Stockopedia.

My view
I think XLMedia CEO Stuart Simms is doing all the right things to improve this business. He may succeed in creating good quality editorial brands, which generate reliable web traffic and thus sustainable revenues.
This, for example, is the model that’s being successfully pursued by £FUTR.
However, I’m not enthusiastic about a business that relies so heavily on gambling, through its sports and casino operations. To me, these are sectors that will always attract aggressive competition and be at risk of harsh regulation.
XLMedia’s turnaround may deliver, but there are too many risks and moving parts here for my liking. This isn’t a stock I’d be interested in buying.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Thought this might amuse you! I was so desperate to get online, this was the only way I could find power, wifi, and a workstation, on arrival at our Madeira villa!
That’s hilarious. Well done Paul
Best possible use of an ironing board, a technology which has now clearly been consigned to history with everyone working from home !
Time for another "holiday" snap - or rather WFV (working from villa) - amazing sunset over our infinity pool & jacuzzi LOL here in Madeira. I've been glued to my laptop, with so many stimulating things going on with the markets & my portfolio.
Paul - I'd stay there if I were you. It turned quite wintry/autumnal today and I know where I'd rather be.
Enjoy, it looks fab.
Still very pleasant in London - walked the dog at 8:30 pm in tee and shorts and I was not cold / chilly at all. Friday meant to be 23 which is great for this time in Sept.
Your dog wears tee shirt and shorts??
still like mid summer here in Suffolk, where are you living?
Paul/Jack
Interested in your thoughts on the compare function under the tools tab. Stocko clearly picks a winner when you compare but I've no idea what it gives weight to the winner, perhaps uber simple point a section ???
Have you do you ever use it ??
I've never seen anything on it, it might be of interest to many ? Its plainly there for a purpose
Mike
Where is the tools tab ? not showing on my laptop version of stocko !
I get to it from a company page ie one you want to compare to another, you will see tools drop it down click compare enter the company you can look at up to 5-6. But I have no idea what the weighting is to arrive at the winner, it plainly says "winner" you would think its aimed at stock selection, I just don't know hence question. Perhaps one for Stocko back room team
Re. the background to the Compare Function, this explanation from the Learn Section on Stocko might be helpful:-
https://www.stockopedia.com/le....
Gus.
I just tried this. I put in 3 with SR of 99, Royal Mail (LON:RMG), Gattaca (LON:GATC) and Firstgroup (LON:FGP), Royal Mail (LON:RMG) was the winner. However when I swapped Firstgroup (LON:FGP) with Marshall Motor Holdings (LON:MMH), Gattaca (LON:GATC) became the winner.
I expected Marshall Motor Holdings (LON:MMH) to be the winner as it had SR of 100.
How can Gattaca (LON:GATC) be the winner now? Nd why are lower ranked stocks higher than higher ranked ones?
Nd why are lower ranked stocks higher than higher ranked ones?
If it was as easy as identifying the company with the highest Stockrank it would hardly require a comparison tool ...
As far as I can see the "winner" is the one that "wins" most comparison categories - e.g. Stockrank only counts as one category, Market Cap is another, etc.
For instance if I compare Marshall Motor Holdings (LON:MMH) with Somero Enterprises Inc (LON:SOM) then MMH wins as it has most category wins. If I add Gattaca (LON:GATC) to make a three way comparison then SOM wins because GATC takes away more category wins from MMH than from SOM.
So basically the "winner" thing is useless as a stock selection tool.
timarr
Thanks Tim, that explains it.
So as you say not that useful for selecting stocks.
Without being able to delve into the mechanics of the comparator it’s hard to be sure. I suspect it’s a function of the relative (as opposed to absolute) merits of each company when compared to your other selections as opposed to its score when ranked against the entire universe of stocks.
It’s a bit like trying to pick your favourite fruit. Say I offer you an apple, an orange, a plum and a mango (in a world of say 1,000 different fruits). Each fruit is scored against all the other fruits in the universe and given a relative ranking say based on sweetness (Q), cost (V), and popularity (M). These are then totted up to give an overall fruit score relative to all other fruits (analogous to a company Stock Rank). For sake of argument, let’s say the plum gets the top fruit score against all other fruits. If you then change the universe of fruits from 1,000 fruits to just 3, (say an apple, a plum and a mango) the relative scores of just these three fruits will change and you could well end up with a different winner. If you keep two of the three and add a different fruit, the relative rankings may well change again and the addition of a new fruit/loss of the original fruit could well affect the relative ranking of the two original fruits. (For example if you go from comparing an apple, a plum and a mango to comparing an apple a plum and an orange the substitution of a high sweet/Q scoring mango with a sour/lower Q orange might jumble the relative rankings of the second selection such that the apple now comes out on top).
I suspect the peer group comparison is especially sensitive if you are trying to compare companies with similar ranking scores (in your example it looks you’re looking at companies all with a SR of 99/100).
Then again, there may just be a bug in the algorithm ……
Gus.
If I remember correctly, Fonix's technology is well suited to impulse donations because it allows mass payments to be processed in a very short space of time and this is where some of its competitive strength arises. This technology is proprietary, but I guess alternative versions could be developed by competitors if they thought this payment processing niche was sufficiently valuable, but I'm not sure it would be.
Any views on Venture Life (LON:VLG), which published its half-year results this morning? SP has taken a further hammering today.
Came out of this one after the claim that thier mouthwash has a special ingredient that kills covid. Someone on Mello pointed out the ingredient can be found in toothpaste aswell!
Yes, although that type of practice is rife. I recently picked up a pack of sausages which claimed 100% British Pork. On further inspection...100% British but 45% pork!
hahaha
or should that be AHA !
Venture Life (LON:VLG)
Unless i have missed it i can see no confirmation of how "In line" they are with regard to existing expectations with regard to ye 31/12/2021 bottom line numbers - specifically profit.
If they have not specifically updated in that regard i would ask why no update? if thats unexplained as to why there is no update thats good reason for shareprice being hammered IMHO. If they had said we are on track to hit current expectations of £5.04 net profit for the current year i i would guess sharepirce may have reacted not nearly so badly.
My final question is presuming there was no specific update is this a back door profit warning that will only be communicated to shareholders via two third party sources - one being them giving the nudge to the broker and the broker giving the nudge to the "press" or "chosen select few that can affod to get broker notes" - if this is the case surely what they have done aint right or proper?
Apologies if info was in plain sight and i missed it.
They came out with a profit warning in July in a TU. I think todays HY (formal update rather than a TU) numbers was just conforming what they said in July which in itself resulted in a major drop in SP.
I would've hoped this hadn't resulted in their 14% drop, but it has so now time to decide to get out on the assumption that they normally come in three's, or hold on believing the two new acquisitions will deliver.
I do wonder if the comparisons between Dfs Furniture (LON:DFS) and Scs (LON:SCS) are warranted. My wife refused to even walk into SCS, I went in alone and didn't like one sofa (rather keep my kids vomit stained old ones tbh). Compared to DFS or Sofology (I think this is owned by DFS) we were spoilt for choice. Just my opinion here...(I used to hold SCS before checking out the store in Croydon with all its sale signs up).
You're obviously too posh for Scs (LON:SCS) (I hold) ! :-)
ScS caters for people on a budget, who don't have very good taste in furniture. Further evidence of this is they've got Lawrence Llewelyn Bowen advertising things on their website. For younger readers, he's a designer who used to secretly go into people's houses, and totally destroy the interior, in a mad rush, being filmed for a TV programme.
PP.
Happy common-as-muck SCS sofa buyer here! Has held up pretty well through young kids and young dogs, was good value, and had a good finance scheme. I'll happily buy my next sofa from them.
Scs (LON:SCS) was super cheap as its council house chic and posh aspirant shareholders don't get it ;)
I like they way they run their established biz. The quality of what they do has been severely under appreciated. I was a shareholder for few years until approx 2 years ago - from sub 150p and very fat dividend to c.220p and still plump dividend. Quite nice but I was a little disappointed it didn't get more recognition. However, despite being good value now I wont buy back as my concern is that management are looking for investment opps outside of or stretching their current model. That sounds like a capital allocation problem in the making. I'd be enthusiastic if they were focused in slow very value adding additions to current estate and returning larger chunks of capital through a buyback (could easily add 5%pa eps growth that way, probably more)
Hi mojo,
I chatted to new management at Scs (LON:SCS) (I hold) quite recently, and think they don't really know what to do with all the surplus capital on the balance sheet. As you say, capital allocation is the issue here. I got the impression the new CEO wants to focus on running the business, not doing anything too ambitious (e.g. acquisitions), but who knows what the future holds?
It looks such a blindingly obvious candidate for a private equity bid - when you compare the balance sheet structure with DFS, the opportunity is so stark. The whole cash pile could be removed, plus some debt introduced. That's what DFS did, and it runs fine with a massive negative NTAV balance.
Maybe SCS is too small for private equity?
It needs someone like Geoff Wilding of Victoria (LON:VCP) to come in, and shake things up, and use SCS as a starting point for good acquisitions. It's too sleepy as things stand.
Or failing that, a massive special dividend will do.
Regards, Paul.
Hi Paul, if Scs (LON:SCS) return excess cash through buybacks then I'll be sad I didn't hold as I think the sustained upside to high dividend and earning growth through buyback and modest growth would be pretty considerable over 5-10 years. When I spoke to management they had a very defined model for new stores and had a list of 30 specific locations they want to open in....given that they have been slowly killing off the bad sites they opened in the mid noughties expansion rush that are a drag on performance there's a nice potential growth inflection in that too. However...
I'd worry about acquisitions as I think their model is so niche and honed that they would best maximise the return from that model...but then maybe I lack retail imagination. A misstep on capital allocation see this turn into a value trap
Eeeeek - He was on the telly last night channel 4 and he is still destroying homes
Paul late news £mcls director share award based award nice freebees?
Hi davidallen77,
Paul late news £mcls director share award based award nice freebees?
Thanks. I ditched all my supermarket shares (TSCO, SBRY, MCLS) when the National Insurance rise was announced by the Govt. Just seemed to me it was the last straw in terms of headwinds for the sector, on top of supply chain problems, wage inflation, HGV driver shortage, very low net margins, etc.
Regards, Paul.
He's still doing it!
Just a bit more on Dfs Furniture (LON:DFS) working capital model - I'm not sure the pay upfront is 100% of the value as with my "posh" sofa's from Sofiology, I paid £300 upfront and the £1.7k last week - they were delivered yesterday after I kept pushing out the delivery (I didn't want to buy new sofas till the kids were at least 5yrs old ,but the wife got her way!)
Agree. I am a holder and went to visit my local Scs (LON:SCS) for some market research. I think the share price may be held back because it simply dosent have as good a product as the likes of Dfs Furniture (LON:DFS), Sofology. The other shops in the same retail park were much busier and the Scs (LON:SCS) store itself was bland and uninviting.
I am however interested in the financials which are appealing from a value perspective but think their product offering is not what would make this a great business. Maybe that’s the opportunity!
Re Fonix Mobile (LON:FNX) and its counterparts Boku Inc (LON:BOKU) and £BGO. It’s important not to see these as cutthroat competitors of each other. They each occupy and thrive within their own separate niches, from broadcast charity or gaming payments to online payments for the underbanked of Africa and Asia to telco-bundled media subscriptions to data monetisation. I see each as a play on DCB (direct carrier billing) as a viable mobile payment channel and choose to hold equal quantities of all three in a combined holding that then matches in scale my other, better known e-payment names like Square, MasterCard etc.
Finally, French Connection (LON:FCCN) bids coming in. Announcement that a significant shareholder has preliminary indicated a 30p bid. Looks like from someone with deep experience in the UK fashion industry.
Don't forget earlier this year they had 3 interested parties too, which may come back with counter offers.
I think it would be scandalous if they got FCCN for 30p. My personal valuation is 50-60p within the next 12 months.
(I hold)
Paul - as a holder I’d be interested in your thoughts on the offer please
Hi Paul following your review of Pennant Pennant International (LON:PEN) yesterday, 5 Directors bought about 80,000 shares between them yesterday - not massive but a positive. Additionally IC published a positive update this morning. I hold and added this morning.
Rob
Quiz (LON:QUIZ) 26p today seem to be having a good run Is anything happening?
Quiz (LON:QUIZ)
Benson
"Quiz (LON:QUIZ) 26p today seem to be having a good run Is anything happening?
Its simply playing out exactly as mystic Pauly predicted (that a joke peeps Paul doesnt predict anything in real life)
Few bits of idle speculation
Good internal news may have leaked out to the market in advance of that news being announced. We are due an update 29th September which is very soon and i am guessing we will have update on the all important current trading.
Good external news ref trading is filtering through - as we all know know external parties have much useful "indictive current trading data" - whilst shgareholders have nowt to go on since last update.
If the expectations for ye 31/3/2023 are materially higher than for ye 31/3/2022 the closer we get to those expectations being "near to current year" i would expect the sharepice to have moved towards a fair and reasonable level based on those better expectations - the sharepriced was very depressed so if its good news in that regard stong rebound should kind of be expected. I havent topped up here as i only ever wanted a small holding here and my initial punt before the dipped down below the 25p level on the way down was enough for me. Shame i didnt have an extra short term bet in hindsight though - sometimes doubling up can be a disaster and the actual news up to now ref trading has not been great - but there are known reasons for that so that was to be expected. Even now market cap here is only apprOx £30 mill - one would hope there is scope to make £5 mill plus if they can do £100 mill plus of turnover "medium term" so no reason why market cap couldnt be back at £50 mill+ at that time. Note my own expectations here being honest are that getting their mojo back will be hard work - but for now i am happy to hang around and see how the mop flops.
Perhaps there are other factors at play here -perhaps simply more buyers than sellers at present. As we wll know shares to often be moving in one direction or another so perhaps the momentum/charting bods have joined the party.
Cheers for your thoughts on Quiz The market has been putting silly prices on shares so as a holder I am trying to work this one out
The silly price for Quiz (LON:QUIZ) (I hold) was the starting price, not what it's since risen to recently. It's actually a nice business, as I've been saying here for a while, but nobody was interested when it was 8p! The retail store portfolio was rationalised through a pre-pack administration, so all the loss-making stores have gone. The rest are on turnover rents, which means they should be profitable in future. It has an established internet operation. The founding family still own about 50%, and there's been no dilution throughout the pandemic. Plus the balance sheet is strong, with net cash (rising recently). And the market cap is still peanuts!
I like it a lot & still hold about 2% of the company (haven't sold any).
Regards, Paul.
Worth noting the Begbies Traynor (LON:BEG) chart.
Previous ATH was around 200p, which is at the top end of the target SP range identified by Paul and c.40% updside to current price.
I often look for significant historical levels as they can act as 'magnets' for the SP to return to.
Since early 2020 there has been significant volume on this share with respect to previous years.
I'm happy to hold as I think - in time and assuming favourable conditions and momentum continue - 200p should be visited again.
Hi Roland
Thanks for the write up on Fonix Mobile (LON:FNX) (I hold) which I think covers the bull and bear case well. On the subject of Apple and Google, an alternate view is that their app stores will be opening up to alternative payment methods and Fonix suggest on their blog that carrier billing will become part of the mix https://blog.fonix.com/apple-a...
The other aspect that appeals to me is that they are a platform business and the platform has already been built. This should mean that operational leverage kicks in as new customers and channels are added to the mix. But, they have to win the customers and open the channels first, hence the investment in their sales team.
Cheers
Simon
On the subject of Apple and Google, an alternate view is that their app stores will be opening up to alternative payment methods and Fonix suggest on their blog that carrier billing will become part of the mix https://blog.fonix.com/apple-a...
That's not what's happening, but to be fair it's not what the article says either.
Firstly, it makes no difference to Google, their model is funded on advertising, as you'd expect.
The Apple model currently requires any app bought through the App store to pay Apple up to 30% of any subsequent purchase of digital content (not physical goods). That isn't changing - so Apple don't have to offer other payment methods in the store. However, companies are now allowed to offer their own payment methods off store and to tell their customers about it - and that will make a difference because you can (for instance) choose to use carrier billing to pay for in-app purchases.
So it's not bad news for DCB payments but it's not game changing either.timarr
Paul that is amazing news about Zane. Like you say donations of the magnitude made by Investor1 will make a material difference to the work Zane are able to do.
I have been impressed with their regular communication since I signed up for a Monthly Bankers Order.
Begbies Traynor (LON:BEG) (i hold)
I wonder if Begbies will get any of the business from the 7 failed energy companies ??
Richard
Fonix Mobile (LON:FNX) : I have a very small starter position here and I'm pleased with the results today which look like a very slight beat to me with plenty of positive sounding narrative. Plenty of impressive operational improvements (34 new customer contracts signed, active customers increasing by 13%, record £32m Total Payment Volume in one month, 50% increase in the number of charity clients, 100% client retention, 99% repeat income etc. etc.)
Future growth and expansion plans sound positive: Fonix won "its first international payments contract" and "several.. multinational customers look to expand our services overseas" also discussion on new opportunities in the dating, gaming and e-scooter hire spheres.
My question would be around the defensibility of the moat (or even if there is a moat). The issue was addressed to some extent by the CEO noting that:
"For the majority of our customers, deploying Fonix's payment solutions has largely shown to reduce checkout abandonment and provide incremental revenues rather than cannibalizing existing transactions, as demonstrated by the box office pay-per-view payment solution used for BT Sport. For this reason we do not consider ourselves to be in direct competition with traditional payment methods, such as credit card or ApplePay, but offering an alternative to consumers who would otherwise forgo purchasing."
Obviously this doesn't address the issue of competitors in the exact same space from undercutting Fonix.
I don't know enough about the industry or the competition to be certain of how strong Fonix's moat is but for now they seem to be progressing nicely and perhaps might become a bolt-on acquisition target for a larger player in the not too distant future given their relatively undemanding valuation.
Fonix Mobile (LON:FNX)
RE technology. Personally I think that carrier billing has an advantage over Apple pay and Google pay (which I have used exclusively where possible for a few years now) particularly when it comes to media campaigns etc. I haven't seen use of Google pay etc on a TV campaign personally and would imagine that an app would have to be downloaded to facilitate such a payment. So things like This Mornings competitions for a Carribean holiday etc or the charity campaigns are reasonably safe as I can't see too many people downloading an app to just to enter into a compition- there would have to be an added benefit for mass download. It also takes away the impulsively a text message offers as Paul indicates.
re: competitors : Boku Inc (LON:BOKU) and IMI mobile Imimobile (LON:IMO) are highlighted as their key Competitors. I suppose the fact that they've retained their key clients 5.5 to 6 years long must mean that they can ward off competitive threats but I share your concerns here and will earmark them for future research. I do hold a small position here and it is very much my more research required list.
On another note: I like to see tangible workings and evidence of companies I'm interested in day to day in the environment I live and work in. A couple of weeks ago I was walking through a local park which has long been neglected and recently redeveloped funded primarily via local community fundraising, when I saw a number of fundraising signs stapled to variouse trees. They each had a phone number on them for donation and all had the sky logo emblazoned on them but down in the small print Fonix Mobile was the provider. I can't imagine it being a hugely successful campaign for them in the grand scheme of things but I imagine that it may be just as successful as fundraisers out with a bucket.
Fonix Mobile (LON:FNX)
RE technology. Personally I think that carrier billing has an advantage over Apple pay and Google pay (which I have used exclusively where possible for a few years now) particularly when it comes to media campaigns etc. I haven't seen use of Google pay etc on a TV campaign personally and would imagine that an app would have to be downloaded to facilitate such a payment.
Correct, about the X-pay app download. The underlying issue is regulation which is pushing carrier billing companies the same way because of the limits on payment values before you have to step up to use a separate electronic money account (which needs a separate app). That's currently only in the EU and the UK but the trend is in that direction globally.
There's an ongoing battle between security and convenience in the world of payments. What consumers really want is convenience right up until something goes wrong and then they expect to be compensated for said problems. Carrier billing is no different. If you use it check your bills carefully.
timarr
Fonix Mobile (LON:FNX) great set of results from these guys who appear to proving consistency. 7p EPS should grow to 8p+ this year. Like the 100% client retention and international expansion plans where there is plenty of scope to grow the business. Decent initial dividend of 2.5% to boot. Outlook from management sounds confident. Probably not a million miles away from fair value, maybe 160-200p but seem like a decent business to hold medium term.
Not something typically covered around here, but if anybody is interested in Caledonia Mining (LON:CMCL) they have acquired an additional exploration project as per this morning's RNS release.
Mark Learmonth (CFO) always comes across as very prudent and thoughtful, so I would think they have not gone into this without feeling very comfortable about the prospects.
Commenting on the announcement, Steve Curtis, Chief Executive Officer, said:
"We are delighted to enter into this agreement to purchase the claims over Maligreen, one of the more significant exploration opportunities in Zimbabwe. The property has significant potential and has benefitted from many years of exploration activity. Initial evaluation of the inferred mineral resource by our own team and by independent consultants indicates the potential for a significant mining operation with a NI 43-101 compliant inferred mineral resource of almost one million ounces at a grade of 1.88g/t, an acceptable open pit grade. Moreover, our understanding of the grade tonnage curve indicates that the deposit is likely to offer a high level of mining flexibility although much more work is needed in this area. We believe the property also offers significant upside exploration potential at the north-west extensions to the existing inferred mineral resource and at additional exploration targets in the northern part of the property.
"This transaction is an important next step as Caledonia pursues its strategy to become a multi-asset gold producer in Zimbabwe, one of the last gold frontiers in Africa."
https://www.investegate.co.uk/...
Caledonia Mining (LON:CMCL) - not a stock that'll be covered in SCVR as not its area.
The claim over Maligreen acquired for $5m looks a good option. If the project pans out then it'll be reasonably quick and simple to put into life and low development cost as open pit - approx $50-60m. 940k oz at current cut off grade gives 1.88g/t which is pretty good for open pit. And mgt hint that they may increase the cut off grade to push average grade up (>2.5 g/t whilst only reducing resource to a little below 800k oz).
Assume they produce 30k oz pa and have $800 per oz op cash flow and that's $24m pa cash flow to company. Factor in reduced recovery to refactory ore milling process and crudely/conservatively assume that 600k oz recovered over c.20 years.
Numbers all made up and I'd guess they'd go for higher annual production and better recovery. Plus there's upside to further exploration potential in area too -> this may turn out to be good proof that CMCL have upside by being able to develop abandoned brownfield sites in Zim. Then Zim risk turns into quite a good 'moat' and generator of opportunity. Of course...there is always Zim risk.
Royal Mail (LON:RMG)
Bit outside the scope of this place normally but this share is showing up as p/e of only 7.8 on stocky so i have had a bit of a punt recently while shareprice is below 500p. There may be read across to other shipping firms on todays news - so interesting to see how volumes are margins and holding up in their varrious segments.
Balance sheet seems fine.
Currently they are doing two monthly updates and today is one such day.
The market has presumably been predicting dropoff in parcel volumes as covid tailwinds turn to headwinds - the company seems confident now in this regard that there is a re-basing going on which is good news here.
"In Royal Mail, we are increasingly confident that domestic parcels are re-basing at a significantly higher level than pre-COVID and believe we are maintaining our share of the market. Domestic parcel volumes are up around a third compared to pre-COVID.
current ye expectations per stocky are for 640 mill net profit this year and 650 next year.
per trading update today - note reasonably high % of profit is NOT actuallyfrom Royal Mail unit.
Group adjusted operating profit for the first half of 2021-22 is expected to be £395 to £400 million, with at least £230 million from Royal Mail.
400*2*80% = 640 mill so on track in H1 ignoring anything seasonal - it looks like H2 is seasonally stronger that would make sense with H1 ending 30/9 and xmas and black friday and the like falling in H2.
So certainlly no signs here that the the good sweet spot they are exepriencing in their business will drop off soon. Note i suspect there could be operational gearing at play here so it could be dropoff in revenues would unduly impact profits. On what they are doing right now though this company seems cheap as chips.
Todays update seems nicely positive and the market reaction here is zlich.
Agree re RMG. The other thing worth keeping in mind in the substantial and undervalued property portfolio.
One other point: Czech investor, Daniel Kretinsky - the “Czech spinx”…- has been building a stake and following a recent buy is now up to about 18%.
Begbies Traynor (LON:BEG) Trading during the first quarter (May to July 2021) was in line with expectations. BEG remains on track to achieve our revenue and adjusted profit forecasts, which are unchanged. As anticipated, the components of forecast double-digit percentage growth in revenue and profits this year are internally driven, rather than market related: specifically recent acquisitions and the bounce back from 2020’s lockdowns.
The two business and financial recovery acquisitions completed last year, CVR Global (January 2021) and David Rubin & Partners (March 2021) and another, MAF Finance Group (May 2021) post the year-end are all performing well. BEG reported successful integrations, identification of synergies and cross selling opportunities.
We have held our forecasts and 165p/share fair value estimate, equivalent to a 17.9x FY22e PER and a 1.9% prospective yield (2.9x covered by adjusted earnings).
https://www.equitydevelopment....
Dfs Furniture (LON:DFS) this morning
"Order intake has also remained strong in the current financial year to date, well ahead of our previous scenario of +7% growth on FY19, resulting in an order bank that continues to grow and which in absolute terms is very significantly ahead of normal levels."
This should be a good read across for Scs (LON:SCS) ( i hold).
Richard
Re. Dfs Furniture (LON:DFS) , I don't have a position in this or Scs (LON:SCS) but thought I would share an anecdote to give a data point of one: Last week I ordered a bed frame from one of the big sheds - the frame was from a large company (Ercol) and is physically on display in at least three stores that I visited. However when I placed my order, I was told delivery would be February 2022 and when the assistant phoned Ercol to query this, he was told it was correct and due to supply issues. The assistant also told me that they had millions of pounds of stock stuck in warehouses unable to be despatched due to driver and delivery staff shortages. He described the situation as an absolute nightmare and expressed the view that next year would be extremely difficult.
I also wonder, if when the reality of the scale of energy price increases hits consumers this winter (gas prices up 70% in August alone), whether discretionary furniture purchases might abate rapidly. I cannot see how 2 million energy customers learning that their supplier has gone out of business would instill consumer confidence.
I reckon we could be in for a bumpy ride this winter.
I for one like anecdotal input, especially from retailers. With this in mind I rang SCS a couple of weeks ago to get an idea of order lead times, delivery issues etc and spoke to an extremely helpful sales guy who told me that the only issues they were having were on products coming from China , mainly Lazy Boy chairs and sofas, which i think made up 20- 25% of their offering but for the rest, that were put together in the UK, they were quoting 6-7 weeks delivery. I was fairly happy with this.
I was thinking exactly the same about energy prices hitting consumers, many don't realise that their bills could go up 50%+. The quotes I've had to renew my energy supply are eyewatering, some are up 100% on what I'm paying now and they are going up again in October.
Of course the energy costs will be hitting companies also, some have closed down already, as the costs are too high to make a profit, this may have knock effects, such as lack of CO2 for example.
I have been looking at buying a new sofa, reading the reviews many of the negatives are about late deliveries or no deliveries. Told 8 weeks and still waiting 6 months later. The ones I was looking at in Oak Furniture Land were around 14-16 weeks although some could be supplied within 1 week.
Good read across to French Connection (LON:FCCN) too which makes licensing income from DFS selling their branded sofas.
(i hold)
Cvs (LON:CVSG) FY CEO overview. Strong results. Sales +19.2%. Adj EBITDA +37.3% Adj EBITDA margin 19.2%. 3.2m homes acquired a cat/dog during CV19! Video & podcast. A recording of the analyst presentation will follow.
Attraqt (LON:ATQT) H121 CEO overview. Rev+10%. 7 upsells in period. AI search functionality ahead of targets. Some key hires. Video & podcast. A recording of the analyst presentation will follow.
Property Franchise (LON:TPFG) The Property Franchise Gp H1 21 investor presentation from last week. Superb results obviously estate agency market is very strong. Outlook ahead of expectations. Strategy update on online, Hunters & financial services with Mortgage Genie and partnership with LSL. A great presentation with an excellent Q&A. Video & podcast
Personal Group (LON:PGH) interim results webinar tomorrow 24th September, 2pm. Deborah Frost, CEO and Sarah Mace, CFO will present followed by Q&A. Hit by CV19 but making a good recovery. (They are an digital provider of employee benefits etc, they tie up with Sage who will make an appearance tomorrow.) Register here.
Finally, we have a Stockopedia/PIWORLD StockSlam on 27th October, 6pm. Does anyone feel like Slamming? Please contact me here. It's obviously the Slammers that make this event. Speaking from experience, it's great fun and good to give back - I've got a lot from other Slammers. It's always very popular with thousands registering and watching afterward. Register to get your place to watch here, we know it will be a great evening.
We are hosting two webinars today for private investors.
The first one is at 9am with Mirriad Advertising (LON:MIRI) Stephan Beringer CEO and David Dorans CFO will present the HY results released yesterday and the outlook. Register here
The second webinar is at 12pm with Crossword Cybersecurity (LON:CCS) Mary Dowd CFO will give an introduction to the company. Register here
Plenty of time for Q&A at both sessions or send them in ahead of time to info@yellowstoneadvisory.com
Also:
Fonix Mobile (LON:FNX) in line.
Chill Brands (LON:CHLL) Tobacco-Free Nicotine Flavour Pouches in US shops in Q4. Will pay "renowned rodeo athletes" to puff this stuff. Don't all stampede at once. I'm short.
Augean (LON:AUG) TOP auction yesterday evening resulted in a 372p all cash bid from Eleia being successful. Decent outcome for shareholders, not least in light of initial 280p per share (with a conditional extra 20p available) from Morgan Stanley managed fund.
https://www.investegate.co.uk/....
Gus.
Augean (LON:AUG) certainly a good outcome for those of us who got in at 40p Gus. (Always loved the Classical name although that wasn't reason for investing.)
Allergy Therapeutics (LON:AGY) Final results. Pre tax profit 95% ahead of forcast due to lower overhead costs but still down on last year. Finncap have released a note raising their target price from 45p to 50p.
£FNX announce a 19% increase in revenue and a dividend of 3.53p. There was a stock pitch for the Investment Club in March 2021
I am an holder and see this one as a longer term hold. Growing steadily, paying a nice dividend and generates a good amount of cash. 100% customer retention rate is also super impressive. The risk with this is if mobile payments get superseded by some other technology
Begbies Traynor (LON:BEG) announce in line update = 5% fall in s.p. probably