Small Cap Value Report (Thu 24 Mar 2022) - BKS, SPE, SCE, MCLS, KCT, AOM

Good morning, it's Paul & Roland here today. Today's report is now finished.
Agenda -
Paul's Section:
Beeks Financial Cloud (LON:BKS) (I hold) - another big (for the small size of company) contract win. This quarter has now delivered record contract wins, of 3 times the previous record quarter. Something big is happening here, so despite it being difficult to value, BKS is becoming a top conviction holding for me, as a long-term investment.
Surface Transforms (LON:SCE) - a large increase in its contract with (possibly) Tesla, for ceramic brakes. This looks like a genuine game-changer for the company, although at nearly £100m market cap, a lot of the upside is already priced-in. In more bullish market conditions, I could see this share going higher. Execution risk is considerable, going from negligible revenues, to mass production.
Mccoll's Retail (LON:MCLS) - as mentioned before, I think existing equity is now almost certainly worth nothing. Departure of the CEO today looks like it's imminently game over for existing shareholders. The business looks likely to survive, but with new owners, and reduced debt, I imagine. Please don't buy these shares, imagining it might multibag! You'll almost certainly lose all your money within days or weeks.
Activeops (LON:AOM) - my first look at an AIM float from H1 of 2021 (a terrible period for over-priced, opportunistic floats). Today's trading update for FY 3/2022 looks OK, in line with expectations. The 17% drop in share price seems harsh, with only a couple of minor negative comments from the company. Trouble is, it floated at a gross over-valuation. So I think it's likely to continue falling, because the starting point was so high. A loss-making, moderate growth company, valued at £70m, is not going to appeal to many people right now.
Roland's Section:
Sopheon (LON:SPE) - Software group Sopheon has delivered another year of revenue growth and reports some promising KPIs. But profits continue to fall despite strong cash generation. I’m not convinced the pace of growth justifies the valuation here.
Kin And Carta (LON:KCT) - strong organic growth, with half-year revenue up 59% like-for-like. However, this pace is expected to moderate in future years and I have concerns over the quality of profits and cash generation. I’m struggling to see much value here.
Spring Statement & Market Comment (from Paul)
I quickly looked through the detail of the Chancellor's Spring Statement from yesterday. It seems to alleviate only some of the squeeze on household incomes. A big rise in the NIC starting threshold seems to offset about half of the total cost of increased NIC rates previously announced. 5p off fuel helps a bit too. Although with inflation + higher taxes now looking to increase household spending by say 8-10%, and incomes only rising say 3-5% (depending on peoples' circumstances), there's no doubt that millions of households are heading into a period where disposable income is squeezed hard. That's why consumer-facing shares have dropped so much. Does it then trigger a downturn in business confidence, and even a recession? It's possible, for sure. It seems strange to me that Sunak did such massive intervention to prop up the economy (very successfully) during the pandemic, yet now seems almost blase about letting the economy wilt - which of course runs the risk of tax revenues drying up, making the situation worse. A reputation for competence seems to be ebbing away.
Anyway, how should that affect our investing? I feel that many of my small caps have fallen so much already, that it's probably too late to think about selling. I'd rather push through, and await a recovery for my core holdings. That means accepting the risk of further losses, which for me personally is fine, as I take a long-term view, and am happy collecting in divis. Others however tend to be much more short-term, and less able to cope with financial pain. So people need to make difficult decisions on whether to continue holding, or to run for cover and see how things pan out. Your money, your decision.
There was an interesting bar chart shown by the BBC news last night, indicating that the squeeze on real incomes this year (with inflation way above rises in wages/benefits) is the worst for 30 or 40 years. However, what struck me is that all the previous negative bars only lasted one year, and then saw big positive bars either side. Hence this is a temporary issue. So should we really be pulverising share prices just because a company is likely to have one bad year, due to temporary factors? Probably not, but markets look to be driven by fear & flow of money at the moment, so are not necessarily making logical prices. At some stage that market mentality suddenly changes, and investors snap up cheap shares with a view to recovery. I've no idea when that change in sentiment will happen. That creates lots of buying opportunities for investors with strong stomachs, who can tolerate short term losses. Or if you think you can time the market, and buy back in at the optimum time (which will be before the economy actually recovers, remember markets anticipate events that are likely), then sitting in cash is not a bad idea, if it's only for a few months.
Obviously I'm kicking myself for not moving into cash myself, when things were spectacularly rosy in my portfolio last autumn, what a missed opportunity. Another one to chalk down to experience, not that I ever seem to learn from experience - making the same mistakes over & over again. Although as mentioned in my last annual portfolio review, I don't have the right personality to manage money. It's the analysis of individual companies that I enjoy, and over the long term do at least manage to make a decent living from my portfolio, and the long-term returns aren't bad too.
Although year-to-date so far in 2022, my SIPP is down 22%, and my geared accounts a lot more - as I didn't reduce my gearing enough, or fast enough, and my hedging strategies failed. So if you're having a bad year, hopefully it might reassure you that most of us are in the same boat, or doing even worse.
What to do? I think it's key to put emotions to one side, and just try to make rational decisions as things stand today. We can't wind back the clock, or change anything in the past, so best to just accept the current situation, and manage it as logically as we can. Markets always recover, if you're invested in decent businesses with good management.
.
Paul’s Section:
Beeks Financial Cloud (LON:BKS) (I hold)
146p (y’days close) - market cap £83m
£4.4m Private Cloud Contract Win
- 5 year contract total £4.4m
- European tier 1 client
- Won via a partner
- Q3 (Jan-Mar 2022) contract wins now c.$15m (3 times previous record quarter)
The latest contract is testament to the strong sales momentum across the Group, now successfully targeting the world's largest financial services organisations and exchanges. Both the Private Cloud and Proximity Cloud Offerings have significantly contributed to Beeks' record third quarter of trading, with c. $15 million in total contracted value during the period, representing a three-fold uplift on our previous record quarter of Q1 FY22.
Gordon McArthur, CEO of Beeks Financial Cloud commented:
"Successfully securing a further contract of such significance reinforces our belief that the prospects for Beeks have never been stronger, as financial services organisations accelerate their cloud strategies.
Alongside other recent wins we have announced, this latest contract contributes towards underpinning our FY23 expectations.
A substantial pipeline continues to build across our Private Cloud and Proximity Cloud offerings, and we are confident in our ability to further increase our market share."
My opinion - another very encouraging contract win. It’s becoming increasingly obvious that BKS has passed a tipping point, where its cloud-based connection services for financial markets are being more rapidly taken up by big clients, globally.
Therefore an exciting future is on the horizon, as those recurring revenues build.
I reviewed Beeks interim results earlier this week here. Although the numbers at this stage are barely above breakeven, that’s missing the point. It’s the very rapid organic growth, of recurring revenues, which is laying the groundwork for a much bigger, and potentially highly profitable company in future.
This is generally a bad time to be investing in growth companies, so there is that strong market headwind, but when growth is this strong, with big contracts rolling in faster than ever before, it’s time to sit up and take notice.
For that reason, and despite it being difficult to value, BKS is fast becoming a high, maybe even highest, conviction holding for me. I need to just ignore market sentiment, and buy more (as a long-term hold).
I think this is probably the best reasonably-priced, high organic growth company on the UK market right now.
InvestorMeetCompany webinar from Beeks is today at noon.
.
.
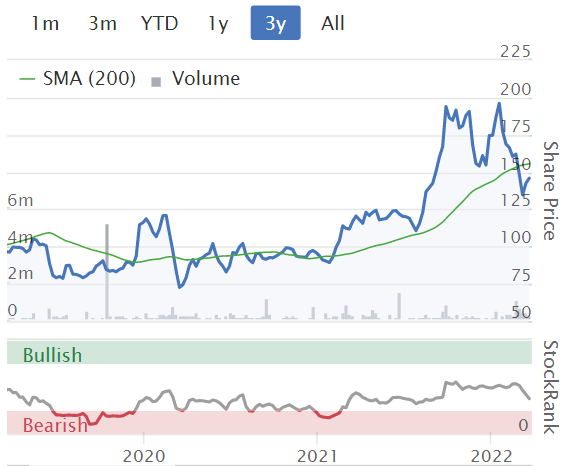
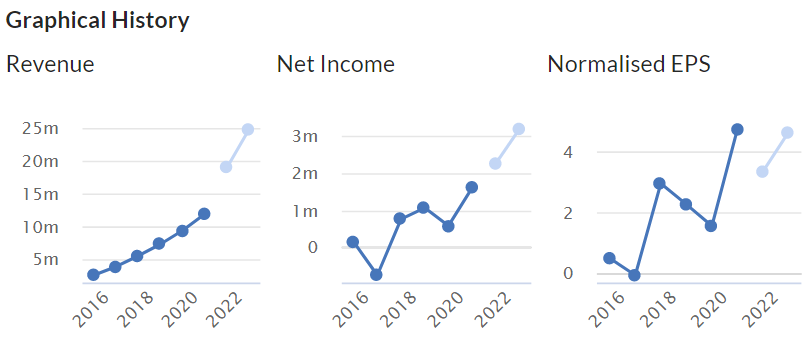
The share price over three years has not properly reflected the acceleration in growth you can see below. Although bear in mind the company is not chasing profitability at this stage, but instead re-investing revenue growth into further expansion.
.
Surface Transforms (LON:SCE)
51.0p (up 21% at 08:21) - market cap £99m
SCE produces specialist brakes, made from carbon ceramic, for high end sports cars.
This follows on nicely from Beeks above, in that SCE is another small company which seems to have reached an inflection point, after many years of losses and negligible revenues, is now transforming with big contract wins, into something that could be exciting. Providing management can execute well, and turn contract wins into real profit & cashflow, which is not always as easy as it sounds. There are so many micro caps which always seem on the cusp of great things, but never quite get there.
Capital Market Day - the company is providing a tour of its facility in Liverpool on 27 April. Do we have any subscribers in the area who could maybe ask if they can join the meeting? It doesn’t sound as if private investors would be excluded, which we often are for this type of meeting -
… for investors, media, analysts and other interested parties
Some big numbers here, this looks really impressive -
Surface Transforms plc (AIM:SCE) is pleased to announce that it has signed a new contract with its existing customer, OEM 8 with a contract value of approximately £100m. This contract replaces the previously announced contract from September 2020 which was valued at approximately £27.5m. This increased contract value of over £70m is driven by both significantly increased demand for this particular model of OEM 8 and the contract being extended to 2027.
The contract remains priced in pounds sterling and increases the Company's sales forecast by £4m in 2023, £11m in both 2024 and 2025 and by £20m in both 2026 and 2027, taking the Company's overall lifetime order book to over £180m.
Delayed production hasn’t started yet, but sounds imminent (“now scheduled for spring 2022”), but orders for the vehicle (Tesla, people seem to think) are ahead of plan, hence this contract being revised up.
SCE needs to increase its overheads by £2.5m this year FY 12/2022 to cope with the extra demand & production.
My opinion - this looks very interesting indeed. There’s still execution risk, and it remains to be seen what profits will be generated. However, I particularly like the massive % increase in contracted revenues. Let’s hope the company can cope, and is able to deliver such a large increase in production/delivery without hitches.
Zeus (many thanks for an update note today) reckons the company might make a 20% margin on £38m of revenues by 2025, so about £7m.
That means the current market cap of almost £100m is probably pricing in the next 3 years’ growth already.
Hence investors have to hope that SCE can win a load more contracts, and scale up into a much bigger business. Or that a bigger automotive group might buy it.
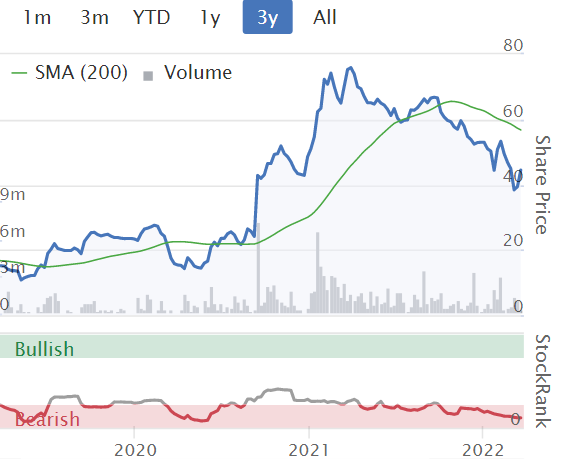
Given that we’re in a bear market for small caps, this might struggle to go a lot higher for the time being, despite the good news, simply because it’s already priced-in.
If markets become more bullish again, then at some stage this is the sort of share that people might chase up to a higher valuation. So it could be interesting. Certainly it seems a lot more credible now, than it has done at any point over the last 20 years that I’ve been following its progress as a listed company!
The automotive and health sectors are both areas where innovative small caps often find it a painfully long process to commercialise new ideas, if they manage it at all. Remember Torotrak, whose gearboxes were meant to be the next big thing, but never got anywhere beyond lawnmowers!
Then of course there’s Seeing Machines (LON:SEE) which has raised money so many times, that it now has billions of shares in issue, diluting away the commercial progress (and it’s still loss-making).
So these innovative companies are tricky to invest in, as they nearly always take far longer, and consume way more cash, than originally planned.
That said, SCE is clearly now in a potentially very good position, with this huge revised order. So it certainly looks an interesting share, with a decent bull case. If the company executes well, then the valuation would be justified, and I could see it potentially doubling in a bull market, maybe more, who knows?
.
.
£MCLS **Warning**
c.1.9p - market cap £5m
The CEO has stepped down, with the Chairman taking over in the short term.
The purpose of this brief comment is to try to dissuade readers from punting on this share, imagining that it might recover.
As I mentioned here on 28 Feb 2022, the signs are very clear now that the existing equity is almost certainly worthless. A clear distinction has to be drawn between the survival of the business (which is quite likely, once a deal has been done with banks & other creditors), and what happens to existing equity. Due to the perilous financial position, lenders will now be calling the shots, hence existing equity has little to no say in what happens next, unless they’re prepared to stump up a lot of fresh equity, which would result in massive dilution to existing holders, probably at a huge discount. It's too late for that, I think.
In all likelihood, in this type of situation, the holding company goes into administration, then the business is sold off quickly to a buyer, with a deal being done with the debt holders maybe taking a partial haircut.
Today’s news that the CEO has gone, who was trying his best to find a solvent solution, and had injected c.£3m of his own cash into last year’s equity raise at 20p, suggests to me that we might now only be days away from administration. Hence shares almost certainly worth 0p. Please don’t buy any, imagining that they might multibag, because the chances of that happening are pretty much zero.
Note this wording today, which again talks about “stakeholders”, and doesn’t mention shareholders -
The Group remains in ongoing dialogue with its lenders towards a longer-term agreement in relation to the balance of its existing facility and continues to believe that a financing solution will be found that involves its existing partners and stakeholders. As previously announced, a further update will be made as and when these discussions conclude.
The outgoing CEO does mention his personal shareholding, but I imagine he’ll probably now be more interested in funding newco, rather than pouring more money down the drain into oldco (but that’s guesswork on my part of course) -
"I remain a significant shareholder, and I leave confident that, with its clearly defined, convenience-led strategy and strong partnership with Morrisons, McColl's will continue to play a vital role at the heart of local communities across the UK."
My opinion - super high risk - almost certainly going to zero, probably imminently.
.
Activeops (LON:AOM)
97p (down 17%, at 10:36) - market cap £70m
This is a new company to me. Jack wrote a useful briefing on the company here in Oct 2021, questioning the valuation, and pointing out this SaaS company is still loss-making.
Jack also reviewed interim results here in Nov 2021, and again questioned the high valuation. Since then the share price has almost halved, so is this now a buying opportunity? Probably not, because AOM was floated on AIM in H1 of 2021, which seems to have been peak tech mania, when all sorts of wildly overvalued companies were floated. A lot of which have not only turned out to be over-priced, but also opportunistic, as rather poor businesses hit a growth spurt due to lockdowns, and persuaded fund managers to extrapolate out that growth forever.
It might sound like I’m being a smart Alec after the event, but we’ve always been sceptical about IPOs here at the SCVR. Not only because they’re usually over-priced, and opportunistically timed, but also because brokers execute new floats so badly - bagging their excessive fees for the least amount of work, which results in a large, lumpy shareholder base, and little aftermarket liquidity - which begs the question, why bother floating, if there’s no market liquidity? All too often it's so controlling shareholders can cash out at an inflated price.
It’s much better to reverse into a cash shell, with a ready-made small shareholder base, which results in much better market liquidity, in my experience.
On to today’s update -
ActiveOps plc (AIM: AOM), a leading provider of Management Process Automation (MPA) software for running hybrid and global back-office operations, today provides an update on trading as it approaches its financial year end on 31 March 2022.
A year of growth and positive outlook
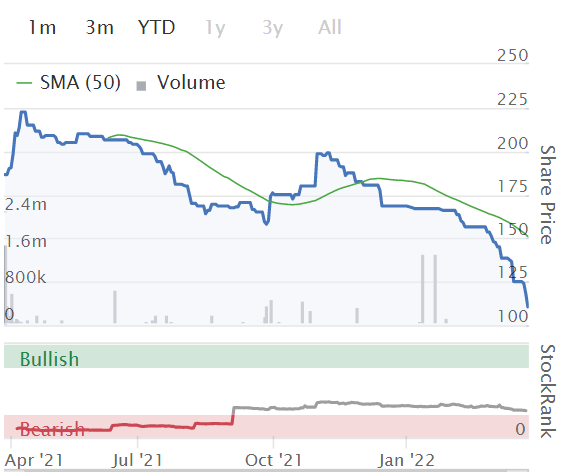
Shares are down 17% today, so the market doesn’t share the PR person’s sunny disposition.
It starts off well -
The Board is pleased to confirm that trading is in line with previously upwardly revised management expectations…
This is more mixed, so can be read either way, but overall sounds OK to me -
Trading has been particularly strong across EMEIA and Australia versus management expectations, offsetting slower than anticipated US growth and some softening of retention rates, reflecting the ongoing impact of COVID-19. The US region is however, the fastest growing region versus the prior year with a strong and growing pipeline.
Cash is "comfortably ahead" of mgt exps (no figure provided)
AOM claims to have a strong balance sheet, which is an amber flag to me, so I’ll have to check now… it’s OK actually, NTAV of £4.4m is adequate for a software company, because they get paid up-front by customers. Hence the £10.9m cash pile is actually almost entirely represented by customer advance payments (see note 8 to interims, showing £10.6m deferred income creditor). So it’s not as strong as management seem to think, but not a cause for concern either.
Outlook -
Looking forward, the Board is confident in the Company's outlook, as a clearly defined list of target customers feed into an existing and robust pipeline. The impact of COVID-19 on global operations and the still evolving requirements for hybrid working is driving new levels of demand for better data and operational control. The value of sales opportunities in the Group's pipeline at formal proposal stage or later is 60 per cent. higher than in February 2021.
ActiveOps product release pipeline is equally strong with a number of major advances in AI and data driven management process automation due for release this year. Adoption of ControliQ is accelerating clients' capabilities to evolve and adapt new hybrid operating approaches, providing managers with the data to control and releasing time to implement agile operations post COVID-19.
Our high levels of recurring revenue and gross margin provide us with a strong basis as we look ahead, and while we see some ongoing disruption in the US market from COVID-19, the successes in EMEIA and Australia, combined with a considerably elevated sales pipeline, provide us with confidence in our ability to successfully execute on our growth strategy."
My opinion - it’s not a bad update by any means. Also the pipeline suggests growth should continue.
The trouble is, this share was floated near the peak of a tech/small caps boom (as we now know), and the market has since turned markedly bearish. Hence this share was bound to drop, largely regardless of newsflow & performance.
Performance for FY 3/2022 is in line, and they say expectations were previously upgraded. So we’re being offered shares in the same company, which has performed OK, at about half the previous peak price. Is that an attractive proposition? It doesn’t float my boat personally, as I’d need to see performance at or near breakeven, and much faster organic growth (which for a similar market cap, I can get at Beeks Financial Cloud (LON:BKS) [I hold]).
Another issue we have to consider, is that small cap fund managers who buy these new floats, may be seeing investors wanting to pull their funds out, due to poor performance of pretty much all small cap funds, unless they’re heavily overweight in sectors like natural resources, which are doing well at the moment.
Therefore, the knock-on impact of fund inflows turning into fund outflows, could worsen and prolong this small caps bear market, as some fund managers are likely to be sellers of their lower conviction holdings, in order to raise cash to meet redemptions. Also, they might want to get their mistakes off the books, especially over-priced IPOs. But with little market liquidity (as mentioned above), who will the buyers be? There could be an absolute gulf between what new buyers are prepared to pay, and the current market price, leaving shares like this to continuously drift down until there’s a catalyst to bring in lots of buyers.
I remember back in the bear market of 2000-2003, how a lot of newly floated tech junk (and it was real junk back then, a lot of it total blue sky, zero turnover rubbish) kept falling in price, and many shares lost 90% of their value over time. Then it got worse! Before long, there were plenty of small caps down 99%, falling to well below their own cash balances, if they were loss-making and had little prospect of commercial success.
Hence it seems to me to be too early to catch the falling knives, unless they’re proper businesses, making profits/cashflow, cheaply priced, and preferably paying divis.
AOM is a proper business, with recurring revenues, and real services, big clients, etc. How do you value it though, given that it’s still loss-making? I would say forget about multiple of sales, or EBITDA - those are silly, top of the bull market valuation metrics. To entice me into any share, I want to see at least the prospect of decent profits, and cashflows. AOM is not at that stage, so it’s not much more than a punt at the moment. So maybe 20-30p might be the share price level where I’d be tempted to have a small punt, but I cannot see any reason to even consider it, at 97p per share (£70m market cap). Growth is pedestrian, and it’s loss-making. So it’s not worth anything like £70m to me.
The market is being brutal at the moment, and throwing lots of babies out with the bathwater, so we can be really picky. If something still looks expensive on fundamentals, then why chase the price down? I'd rather sit back and wait for it to get ludicrously cheap, and only then consider buying.
.
.
Roland’s section
Sopheon (LON:SPE)
Share price: 650p (pre-open)
Shares in issue: 10.6m
Market cap: £69m
“Revenue ahead of market expectations”
Sopheon is an international provider of software and services for Enterprise Innovation Management solutions. This includes solutions to help manage corporate processes, products portfolios and internal planning. Market sectors covered include aerospace and defence, automotive, chemicals and consumer goods.
Today’s results cover the year to 31 December 2021.
Sopheon has been a big faller this year, losing more than 30% since the start of January. However, today’s results strike a positive note and appear to be ahead of broker forecasts. So is there hope of a recovery?

Let’s take a look.
Financial highlights
The company has delivered revenue growth “in the face of continued COVID challenges” but did not manage to increase its profitability. However, a strong balance sheet removes any near-term concerns.
- Revenue: +15% to $34.4m (2020: $30.0m)
- Annualised recurring revenue (ARR): +15% to $20.7m
- Gross [revenue?] retention: 95% (2020: 91.5%)
- Adjusted EBITDA: +5.1% to $6.2m
- Pre-tax profit: -29% to $1.2m
- Earnings per share: -47% to 7.83 cents (2020: 14.68 cents)
- Net cash: $24.2m (2020: $21.7m) - no debt
- Dividend maintained at 3.25p per share
Today’s results are consistent with the upgraded guidance provided in January, when management said that revenue would exceed $34m and adjusted EBITDA would be over $6m.
Forward revenue visibility for the current year has also improved since January, rising from $23.4m to $25.1m today. However, profits have fallen once again, continuing the trend of recent years:
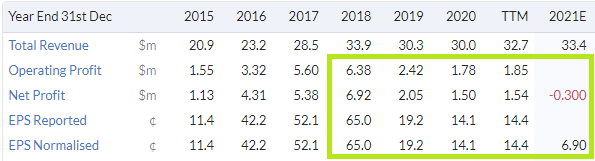
Increased spend: Sopheon’s management say that lower profits are the result of increased spending on R&D and marketing, along with “higher amortisation and share based payments”.
The income statement shows us that operating costs rose by 23% to $23.6m last year:
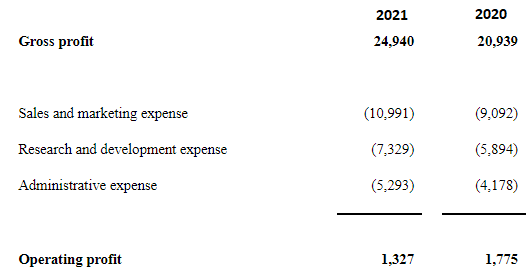
Cash flow: Reassuringly, cash generation remains strong. My sums suggest free cash flow of $3.9m last year, up from $2.6m in 2020.
Balance sheet: Net cash increased from $21.7m to $24.2m last year, which seems to support my view on free cash flow.
Operational highlights
Management reported 10 new customer wins in 2021, of which nine were SaaS( software as a service), so will contribute to ongoing growth in annualised recurring revenue. This is the holy grail for Sopheon and most other software businesses these days. No one wants to sell licences anymore.
The new customer pipeline is said to be “approaching 90% SaaS”, suggesting that this transition will continue.
One attraction of the SaaS model is that it should provide terrific operating leverage. Incremental sales cost very little to fulfil, so as revenue rises, operating margin should also rise.
Clearly that’s not happening yet at Sopheon, making me question the group’s scale and pace of growth.

However, the company says it saw an increased volume of smaller new orders last year. Management says this supports the view that Sopheon’s products are gaining traction and should provide upselling opportunities in the future.
Outlook
Today’s outlook statement is positive but vague. However, brokers FinnCap have provided an updated note today that’s available through Research Tree.
FinnCap’s analysts expect to see revenue climb 7.5% to $37m this year, but are forecasting a further decline in profits before a return to earnings growth in 2023.
My view
I quite like the look of Sopheon, which seems to be making some progress under its new (2021) CEO. The balance sheet looks sound and cash generation seems good, despite disappointing profitability.
The shares look very expensive to me on c.110x 2021 earnings, given that earnings per share are expected to fall in 2022.
However, comparing the company’s £68m market cap to last year’s free cash flow gives a more reasonable multiple of 23x trailing FCF.
I can see some potential here, but I’m not yet convinced the pace of growth is fast enough to justify the stock’s high-tech valuation.
Kin And Carta (LON:KCT)
Share price: 289p (unch)
Shares in issue: 174.3m
Market cap: £504m
“On track to meet recently raised guidance for the full year”
Kin and Carta is a digital transformation company. It uses data and technology to help clients conceive and develop new digital products and services.
Today’s half-year results cover the six months to 31 January.
Checking back in the archives, Jack covered Kin and Carta in February, when the company upgraded its FY22 guidance. The shares have performed well since then, gaining around 25%, so it will be interesting to see if today’s numbers justify continued confidence.
Financial Highlights
Today’s numbers show a decent return to (adjusted) profitability after the challenges of the last year.
- Net revenue from continuing operations: +63% to £85.6m
- Adjusted pre-tax profit (continuing): +682% to £5.0m
- Adjusted operating margin: 6.7%
- Adjusted eps: +821% to 2.3p
- Interim dividend: nil
- Net cash: £5.4m (H1 FY21: net debt of £22.6m)
When I see such a heavily-adjusted set of numbers, my first instinct is usually to check out the statutory figures and reconcile the two.
Here are the equivalent set of reported figures from today’s half-year accounts:
- Revenue: +59% to £89.3m
- Pre-tax profit: -£3.1m (H1 21: -£8.1m)
- Basic earnings per share (continuing operations): –1.94p (H1 21: -3.85p)
There are a lot of adjustments here, but there are only three I think we need to consider. They’re all quite commonly seen in the accounts of services and software businesses:
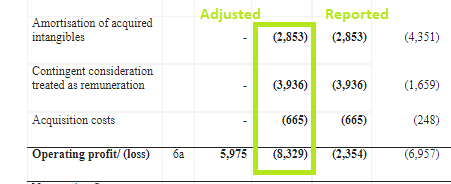
The argument in favour of ignoring the amortisation of acquired intangibles is that it’s a non-cash cost that doesn’t affect cash generation, and wouldn’t be incurred if the acquired assets had been developed in-house.
That’s true, but on the other hand, the amortisation charge represents past cash outflows on acquisitions. Said differently, the amortisation charge represents capital employed by the business.
For this reason, I generally include it in calculations such as return on capital employed, so that I can gain an accurate view of the returns being generated by the business. Kin and Carta’s ROCE has been negative in five of the last six years:

Contingent consideration is also another cost I prefer to include, especially when it’s a regular occurrence - as it is here. The footnotes to today’s accounts show that Kin and Carta has up to £52.9m of outstanding commitments on past and committed acquisitions, including £23.7m in cash.
Cash generation: The other test I like to apply to adjusted profits is to compare them to a company’s free cash flow. With Sopheon (above), I found that cash generation was stronger than profits. With Kin and Carta, the picture is less encouraging, in my view.
Including £33.2m of proceeds from disposals gives a positive half-year free cash flow of £26.6m.
However, if I exclude profits from disposals and acquisition spending, my sums suggest the business saw a free cash outflow of £6.6m during the half year, due to some sizeable working capital movements.
For comparison, I’ve taken a quick look at the FY21 numbers. I estimate that Kin and Carta saw a free cash outflow of £1.5m last year, excluding disposals and acquisitions.
Outlook
Trading is said to be strong, with “robust demand and a record backlog entering H2”.
Management reiterated February’s guidance for revenue growth of 35%-40% and an adjusted operating margin of 10%-11% for the full year (ending 31 July).
This rate of growth seems to reflect a degree of pandemic recovery. Medium-term guidance is for annual revenue growth of at least 15% and incremental operating margin improvements.
My view
There are quite a lot of moving parts here, as Kin and Carta is continuing to evolve. I have some sympathy with the transformation story, but I’m concerned by the weak cash generation and rather average profitability. This might explain the continued lack of a dividend.
Today’s results don’t include any further updates to guidance, leaving the stock trading on 40 times FY22 earnings, falling to 28x earnings for FY23.
I’m struggling to see much value here, given my concerns. After making strong gains over the last year, I’d argue that the shares are up with events.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Really great overview Paul.
This is what I really like about Stocko. Wise, sensible words. Humility and intelligence at the same time. I haven't found this culture anywhere else in this world.
I have copied and pasted some of your words to remind me of the fundamentals : I spend far too much time worrying about short term performance whilst being perfectly happy with their medium/long term prospects. I should stop wasting my time, leave them well alone and put in some alerts in case management start to balls it up, get too greedy or power crazy.
Brandshield Systems (LON:BRSD) 2 directors have been selling significant volume of shares at a knocked down price. Not the actions of directors confident of the company’s future share price.
Looks like some institutional movement in Beeks today; two big trades, for over a million shares each trade. Combined, that's about 4% of the mkt cap, so I'll keep an eye out for an announcement of who it might have been over the next couple of days.
Cheers
Chris
£KCT
Paul - you are ignoring the acquisitions in your cashflow analysis.
What you need tor remember about this share is that it was previously an underperforming business that needed a big shake up. It has spent the last couple of years disposing of non core and moving itself to a pure DX play. It has removed a large pile of debt to a net cash position and this year is really the first year you are seeing the impact of that transformation. The company is now growing at 35-40% revenue with 10-11% adj operating margins. Net cash inflows will be strong going forward now.
Hi david,
It was Roland who looked at £KCT just so you're aware.
Paul.
EDIT: I think Roland's logged off for the morning, but will flag up to him tomorrow about your comment, so he might respond, I'm not sure.
:) I do beg your pardon
deleted
At a Macro level there are a few things worth pointing out that aren't quite as forlorn as people seem to be making out.
1) The level of household savings is proportionately very high, so actually whilst there will be an income squeeze some of the impact of this (both psychologically and financially) will be dampened, so I doubt demand will drop off a cliff - particularly for leisure activities where people are prepared to spend savings for holidays/experiences.
2) The reason the Chancellor doesn't want to do too much more than he did in the budget is house prices. Unfortunately in an inflationary environment what you want to do is dampen demand to force companies to keep selling prices as low as possible. If you just put more cash in peoples pockets the effect is the opposite. That then just leaves you with one tool - interest rates. If you put those up too much to combat inflation the effect is much worse on mortgages and thus potentially house prices. This effect is a worse shock for the economy.
So in my view Sunak is relying on weak labour bargaining power (a big diff to the 1970's by the way) to mitigate wage inflation to the 3-5% level in the knowledge that this will squeeze middle incomes temporarily and constrain demand without annihilating it. Companies will thus pass on some, but not all of the inflationary effects, keeping any potential spiral under control and the BoE can then raise interest rates up to maybe 2% without collapsing the mortgage market. The threshold NI rise is just there to try and counter the impact on the very low earners to avoid too many people getting into poverty traps.
That is all predicated on a slow down in energy price rises and much more stability in that market. The UK wholesale prices were hit particularly hard this year for 2 reasons (1) a lack of input from renewables (significantly less from the wind farms) and a broken electricity cable to France. These are likely to be temporary and given a renewed focus on national security of energy capacity should be growing in the coming year.
Unfortunately in an inflationary environment what you want to do is dampen demand to force companies to keep selling prices as low as possible
According to Next (LON:NXT) today demand isn't the problem:
The disruption to global supply chains along with chronic labour shortages in many parts of the UK economy, mean that there are simply not enough goods, energy and skilled workers to maintain living standards at the levels we have become used to. It is important to understand that the cost of living crisis is a supply side crisis; the inflation we are experiencing is a symptom of underlying constraints in the supply of goods.
And:
The good news is that there is much the Government can do to increase supply. It can reverse the self-defeating barriers it has placed on overseas workers supporting our economy and accelerate, simplify and reform the planning process to increase the supply of desperately needed housing
Given those measures seem unlikely from this government we can probably expect more economic pain ahead.
Digging into the detail Next expects selling price inflation at 8% in the second half of the year, which probably gives an indication of the level of price rises we should expect. Companies will be faced with higher interest rates and wage rises at the same time as consumers are experiencing a drop in disposable income. It will be hard to push through price rises in that environment.
https://www.rns-pdf.londonstoc...
None of this looks particularly positive for the stockmarket but in this environment exogenous factors probably matter more than what companies actually do.
timarr
Some what ironic the comment by £Next regarding overseas worker shortages. I recall that Sir Simon Wolfson was one of the cheerleaders for Brexit claiming it wouldn’t be an issue at all!
You identified 2 very good reasons to expect some weakening of UK energy prices by next autumn (normal wind for renewables and the interconnector from France), helping cut the inflationary burst.
I think 2 further under-remarked offsets will be i) energy reduction through efficiency and energy demand mgt and ii) subst and workaround effects. Within a year we can, install a lot of room temperature regulators or work out how to import gas from elsewhere. These might shave a few % only off the demand / supply figures but it was the sudden increases that really hurt.
We thus likely end up with energy costs higher than before but perhaps not quite so bad as is thought now. Like with shares, we get herd actions and overshoot.
How do you know it will windier this year? It has been windy this February/March but the average has not increased much over the last year and today wind only produced around 2.7% of our electric. Electric demand is going up as some people switch to EVs and heat pumps. One nuclear power station is due to close this June and a coal one in September, I don’t think the French link will make much difference, we import from 7 different ports, there is Norwegian hydro now. Gas prices are key, I don’t think switching to another supply will make much difference. Around 38% of our electric comes from gas. We import around 9% of our electric. People will cut down on gas, I think it’s more difficult to cut down on electric. Prices have already doubled or will next week for many and may go even higher in October. Pity VAT was not scrapped on energy bills, that would have helped a bit.
Rustbucket - A few responses:
1. I do not KNOW wind will blow more this year - I just know that is was well below average last year and is mean reversing (with a climate change bonus on top). So likely to be more. (There will also be a bit more capacity as the investment of the last few years ramp up. I overlook the Solent and see the boats full of blades going out to offshore windfarms all the time).
2. I think (from memory) the specific interconnector that went down delivered around 7% of UK's electricity. It will still not be fully up until 2023 I think but it is the marginal power that really causes prices to spike.
3. I agree electricity demand is harder to cut down on than gas where dropping the thermostat 1-2 degrees, wearing warmer clothes/rugs in the evening etc is possible for most working and middle class families in work. (The truly poor are being screwed but lets not get political here!). On gas on a 6 month basis, we can import from new places and re-build stocks. All at higher than 2020 prices but helping control the high point in 2022/23 winter.
4. But even on electricity, much can be done in the 6 months before next winter - millions have yet to switch to LED bulbs or insulate their loft. These are significant and big savers domestically, industry 'tiger' teams will be out in force in businesses as every CFO/business owner will be really inspecting their energy use plans.
5. If the govt were competent and focused, it could even do some imaginative and highly targetted green schemes, way beyond zero rating solar panels. Genuine low cost loans for energy efficiency schemes (solar, insulation etc). They cannot be taken from the house and with with the right regulation could be a made a priority to re-pay if the person moves home.
Even the dreaded heat pumps would have a role. Not the nonsense that Boris spouts but highly targetted at the up to 1mn, largely rural homes with gardens with high energy demand and currently using oil fired boilers. For these homes, even a £10-15,000 investment would pay back in 5-7 years - they may just may need cash upfront support. So low cost govt backed loans against the property. These installations would then build the technical capability and scale to do more later ie a practical route forward. (In contrast, where I live in crowded Portsmouth heat pumps will never be a good a solution - such details matter in the real world!)
The problem is the government are just stumbling into problems with no long term strategy. They bet on always low spot prices and availability - closing the Rough storage facility etc, failing to 'get on' with nuclear and dragging on other efficiency measures to be 'populist'.
If the fuel duty escalator had been retained, the price signal for efficiency would have given us so much more efficiency in place by now. On cars for example, all those people in gas guzzling SUV's will be regretting their choice and deserve little sympathy. The govt should have been promoting fuel sipping urban cars etc for years - and are still not doing it even as we transition to electric, the perfect time to do so. I despair sometimes.
Returning to investing, those companies lucky or sensible enough to have hedged energy out for another 12months ie through to spring '23 are likely to be fine and the rest will probably do better than current commentary suggests. None of this means that this is going to be anything other than a very tough year.
Thanks for all that info. I agree with most of it. Do you know what wind will produce if the wind speed is average over a year? I don't have any figures for that. This year the average, over the last year, went up from 19.9% to 20.1% but after a few calm days is now back down to 19.9%, these are based on £NG figures. Yes there is more wind capacity coming online later this year. It needs to because we are losing Hinkley nuclear power in July which is about 2% and demand is increasing.
Re imports, I understood even if the French link is full capacity, we would not be importing much more, already at around 9%, we do have the new link to Norway now which came in at the end of last year. Do you have any prices for imported electric? Last year there was various problems with cold spring, nuclear power plants closed down for maintenance, some of which over ran by months as at Sizewell, link to France down. Worldwide shortages of gas pushed prices up. Now we have the problem with Russia and sanctions, which has pushed gas prices up even more as supply is restricted, so getting gas from other sources will be very difficult.
I agree the Govt. could do far more, grants only seem to be available to those on benefits. I would consider solar panels but I'm considering moving in a few years time. Looking at cavity wall insulation but difficult to get at the moment.
I'm all in favour of renewables but my concern is, if there is no wind then where will all the power come from? Yesterday wind produced only 2.5% of our electric. Nuclear power plants take around 10 years to build and the current ones being built, are only replacing what is closing down, Hinkley C won't be open for around 4 years.
Helpful thoughts, Paul. The thing that worries me is whether I'm wasting too much time on the wrong asset class. UK small caps are beset with appalling liquidity, enormous spreads and barely any institutional support especially given regulator imposed liquidity constraints post-Woodford.. Katie Potts at Herald recently said that reduced weightings in the UK was a trend in her fund that would continue despite finding good companies to invest in because of those factors. Disclosure and behaviour is variable (CEO of Morses selling his shares ahead of a profit warning is a good example) and since MiFid, research is scant, paid for and descriptive at best. If there is market failure here, good companies could remain cheap for a long time. As you can tell I've had a bad start to 22 as well! Time for a walk in the sunshine I think and maybe dust off that Seeking Alpha subscription and spend a bit more time looking over the pond.
Good thinking. What is happening here isn't happening over there.
We often forget that the price of an equity is set by the marginal buyer/seller - the price often diverges significantly from the opinion of the majority of shareholders. Even Blackrock can't influence the price once their portfolios bump up against max position costraints. The marginal seller is often forced to sell for practical reasons that may not reflect their investment opinion - margin calls, the need to deleverage, fund outflows, compliance constraints, index constituent changes, pension outflows etc.
The market is efficient in reflecting the equilibrium between buyer and seller, not the equilibrium between valuation opinions. Therein lies opportunity, and also much pain.
I find that regularly reminding myself of two analogies can be helpful:
I did stick some more detailed thoughts down on structuring your portfolio to survive the ups and downs of markets in the Discuss section under Folio Management around October last year (so has now dropped off the bottom), which garnered some good comments:
Portfolio Diversification
Beeks Financial Cloud (LON:BKS) completely agree on this Paul. The key is not to look at this years earnings too much as a valuation metric as they are largely irrelevant due to the level of investment going into the business. The revenues they produce are annually recurring so as that investment starts to wind down profits go up very very rapidly.
Momentum in this type of business is key and really shouldn't be underestimated - financial institutions behave very conservatively initially and then herd for safety in numbers. IF (and many fail) you can break into the preferred supplier/ MSA then you can sell a lot into them quickly. The hard part is getting enough to form that initial herd. That has now happened with Beeks Financial Cloud (LON:BKS) so I expect continued rapid contract wins.
The value of a business that has those type of contracts with tier 1 financials is very high. My suspicion is they will ultimately get bought out. Multiples are often in the 40* earnings range. The reason being the level of cross sell and credibility you get with a trusted incumbent provider. I've held this share from 60p despite the volatility and am not selling any. In the absence of any new black swan type events I can see this doubling/trebling from here, and maybe much more. Private cloud and Exchange connectivity to an underserved and captive audience of the top financial institutions globally.....a lot to like.
I am also long Beeks Financial Cloud (LON:BKS) as the recent orders have been really impressive. As well as all the positives, which you and Paul have very expertly highlighted, I think there are two words of caution that need to be mentioned.
Beeks is effectively an infrastructure business, despite some small bits of software Beeks is currently looking at protecting the IP in its Exchange Cloud and Proximity Cloud offering. It is difficult to see gross margin % going much above the 40s. So to ever earn £10m of post tax profit, revenues need to be a many multiple of current levels. How many multiples depends on what assumptions you want to make on how much administrative costs need to grow as the top line grows. Cannacord recently introduced FY24 forecasts - even with £30m of revenue forecast then,Cannacord is seeing no real feed through to the bottom line or cash generation.
In addition as management were very open about on the Investor Meet Company call today, the balance sheet needs strengthening.
Therefore, I am keeping some spare cash for a possible future equity raise. But I do like the story and the momentum is fantastic.
My guess is that they don't really want to do an equity raise. I sensed a lot of hesitancy when management skirted that topic. I think they are more focused on asset financing which, given the capital required is upfront against material contract wins probably makes sense. If they do an equity raise it will be because they can't get good terms on asset financing in my view. Though that said if they do I will support it and buy some more.
Whilst they invest heavily it doesn't drop straight through to the bottom line - depending on how well the business performs it could be 2 or 3 years before you see it coming through. But the point with this type of business is if you try and value it on PE then by the time you spot what you consider the opportunity the market has already priced it.
The revenue they generate is very sticky and long term annually recurring and that's key.
The CEO also said that whilst £30m is out in the market they hope to do considerably more so I think the broker revenue expectation is deliberately set at a low bar.
Well done Paul, on giving us the bare facts on Mccoll's Retail (LON:MCLS) in which I gave up my holding last June at 36.8 pence after buying at 200 pence in 2017. The writing was already on the wall but my sentimentality was keeping me invested.
Glad to be longer keeping this dog.
Kin And Carta (LON:KCT) results out this morning look very strong. Digital transformation is the place to be! They are guiding to 35-40% organic revenue growth this year on 10-11% adj operating margins. Medium term guidance of +15%CAGR with mid teens operating margins so suggests they will be trading at around an eps of 8p on a PEG ratio of 0.9
Moved from £22m of debt last year to £5m net cash so highly cash generative too now.
Judging by momentum looks like they will be trading around 20* next years numbers but with revenue growing as it is and margins due to move up 40% over 3 years they still look decent value to me.
It would be great if there was some coverage of energy companies (oil, gas, etc).
I'm mostly invested in Canadian oil and gas companies, which have no Stockopedia commentary. It's a shame, because there are lots of high quality companies in this sector that have done fantastically over the past year, are still good value and have strong momentum.
Another area that could be of interest to readers is resource companies. e.g.
I agree, it would be good to have access to similarly expert/informed analysis on resource stocks and have commented to this effect before. But I think this should be quite separate from SCVR, which focuses on a well-defined niche and is clearly highly valued by a large number of Stocko subscribers.
I also think that any similar coverage of resources stocks should not be restricted to small companies.
I agree with you. I am 60% long energy - O&G and Uranium. Both are quite technical areas and need a good understanding of valuation and macro. O&G holdings in the US: Range Resources, Matador, Sandridge; in Canada: Tourmaline, Baytex and CNQ and in the UK: Serica and IOG. The best European large cap play is probably Equinor (I don't hold) and Uranium: Energy Fuels, Dennison, Nexgen, UR Energy and I also use the UK listed Geiger Counter Investment Trust. I also like copper and nickel and have a small position in Li/Sn company European Metals. I don't hold Kenmare or Atalaya. Kenmare looks very interesting and Atalaya has a first rate CEO. The 10% I hold in European small caps has not done well this year although we have enjoyed a nice recent bounce which I fear is of the dead cat variety. The best trade has been puts of Ark Innovation and out of the money calls on oil. Personally, I think we will be faced with several years of stagflation and I think we are at the early stages of a major bull run in all commodities. The astonishing feature is that almost all commodities have risen together apart from coal which led first. many coal stocks are up 400%.
Many Canadian oil & gas companies are up more than 400%. Here's a list of some of the big risers over 3y. About half of these are classed as SuperStock:
You'll find a good commentary of most of these stocks by Eric Nuttall of Ninepoint Partners, who manages the world's best performing energy fund. I think there's still another 2x from the current prices in most of these if oil/gas prices stay elevated.
Thanks for mentioning the other stocks, which I'm researching.
Forgive me for I must be missing something here. I have traded in and out of some of these Canadian O&G plays over the past couple of years and I cannot see where you are getting the returns you quote from.
For example, just three names I have recently sold:
Cardinal went from CAD2.51 to CAD7.72 in 3 years
Enerplus from CAD11.01 to CAD16.72 in 3 years
Crescent Point from CAD4.25 to CAD 9.41 in 3 years
Do you mean from their lows?
Eric has certainly done well out of some of these plays in his energy fund. Other folk worth following in the O&G space are Josh at Bison Interests and Adam and Leigh at Goehring & Rozencwajg.
Another UK listed O&G company I am looking at is Seplat who are buying the Nigerian shallow water assets of Exxonmobile. I can cope with the jurisdictional risk, but am not yet sure of the quality of the assets being purchased. It is noteworthy that Exxonmobile are retaining their deep water Nigerian assets.
On the subject of whether or not oil and gas prices remain elevated, I think we will see US$185 WTI by Q4, 2022. As such I am holding in the money and out of the money oil call options. The IEA figures are just plain wrong and far too optimistic. The oil market is self sanctioning Russian oil and we are in deep merde unless the Iranians are permitted to release oil onto the market (which of course they will be ..... what else do we think the UK paying its old debt of £400m was all about? Does anyone seriously think it was to secure the release of the deeply impressive and indomitable Nazanin Zaghari-Ratcliffe?). OPEC do not have the capacity to ride the West's rescue this time.
re Surface Transforms (LON:SCE)
Ceramic brakes are terrific as they are considerable lighter than the metal equivalent and with superior heat management, ie they don't fade. But the real benefit is a complete absence of brake dust meaning no wheel-cleaning.
But when one cracks, or even just chips, the replacement cost of a disc is horrendous, easily north of £5k EACH - eek!
I like BEEKS (LON:BKS) have added this morning - I have quite a chunky position in these! Definitely seem to be on a roll
Hi Paul, Thanks for the commentary on your personal financial performance. Makes me realise that I'm not the only one in the position you describe.
Sureserve (Sur) looks a cracking buy at current levels .( I hold )
Good fundamentals already with 16.5 million cash, 8.2 eps .
And a player in what is becoming a rising tide red hot sector which Sunak gave more budget support to yesterday - heat pumps , insulation , heat exchangers .
Christopher Mills is a big fan, and share price has come off its highs .
Share price currently bouncing between 80 and 85, anything around 80p or below looks just plain wrong .
It’s one of a small group of bulletproof shares that look to be cash generative, and should be impervious if not benefitting from recession.
Total no brainer compared to some of the dross companies that are going to get found out in the inflation headwinds .
Have these alongside following for bulletproof portfolio anchors
Bloomsbury - there’s only one Harry Potter !
Somero - great technology and ability to produce perfectly flat warehouse floors is a golden ticket .
Northbridge - load bank power supply going to be very important.
Completely agree regarding Sure Ventures (LON:SURE), current share price looks too cheap...
Actually should be Sureserve!!
I agree with others Paul, making a living from investing isn't easy, esp when things turn against you. These are the hard miles so wishing you a strong recovery.
I own a couple of "reopen " plays...Hostmore (LON:MORE) being the one under most pressure. On the face of it the pressure on disposable inc is not great.... but during the virus quite the opposite was true. The argument goes that after two years of little discretionary spend there is pent up demand and the surplus will be spent. Whilst some of this budget is being taken by fuel bills etc Just looking at 2022 does paint a particularly gloomy picture. The prospects for big tickets like housing and cars may be under pressure as these are long term budget decisions. For casual dining and more short term expenditure I would argue prospects may actually be better than assumed. The mkt has moved rather quickly to discount a very disappointing summer .... which could well be far too gloomy. I expect people will want some relief from all the doom and gloom .... and eating out, bowling, shopping and going to the pub all qualify. As the sun shines I expect that desire to get out and have a little fun is still there.
For sure I take on board the threats higher wages, staff availability, and food costs represent but still think prospects could be better than somewhat gloomy expectations .... and with valuations so low.... it wouldn't take much for an upturn. Fingers crossed.
Re Hostmore (LON:MORE) - I own some of this, I think the key thing for them will be that they are already premium priced and focused on above average income clientele. For these people, 1 big decision (eg continuing to NOT have a long haul family holidays) pays for a an awful lot of Friday's visits and they have built reserves in P2Yr.
In contrast, brands selling to average joe punters face much more challenging times.
"consumer-facing shares" Please explain; don't understand what you mean.
Companies that sell consumer products/services. i.e. a B2C rather than B2B
Without getting into an argument about Brexit, I do feel that there's not enough of the can do, entrepenurial spirit that can create wealth and confidence in the economy and should be more achievable without EU constraints. Getting rid of red tape, making the public sector leaner and more responsive would make it more cost effective but there seems to be a hopeless acceptance of 'that's how it is'
I'm old enough to remember the I'm Backing Britian campaign of the late 1960s. Something that unifies and energises the UK is needed.
Thanks for sharing your politics - what rubbish
There's one of them ;-)
I'm old enough to remember the I'm Backing Britian campaign of the late 1960s. Something that unifies and energises the UK is needed.
Unfortunately going for a hard Brexit after a referendum result that left the population split nearly down the middle, wasn't a great start towards national unification, or for our economy.
"always with the negative waves" Who said that?
On a plus side people have been saving more money during covid, so that may help cushion the blow of inflation for a while, unless they have blown it already.
I hit an all time high in January but I am now 7% off that high. I'm feeling that when you hit an all time high with so much bad news around that maybe that's an indicator to sell off.
Hi Paul
Thank you for another candid commentary. For what it’s worth the SCVR is my most valued financial reading of the day.
If you were able to call the market tops then you’d be so rich we wouldn’t be able to afford to read your opinions! ;)
If I’ve understood the squeeze comment correctly:
There was an interesting bar chart shown by the BBC news last night, indicating that the squeeze on real incomes this year (with inflation way above rises in wages/benefits) is the worst for 30 or 40 years. However, what struck me is that all the previous negative bars only lasted one year, and then saw big positive bars either side. Hence this is a temporary issue.
This is the rate of change. It means that people will still have less disposable income the year after “the big squeeze” , the pressure only eases over a longer time. It will take a few years for salaries to catch up (or prices to reduce, recession is very possible).
My pots of money are in different categories. The long term pension is still invested, the medium term is half cash and the short term trading account (that I might need sooner) is almost all in cash.
As the saying goes. It’s madness to risk something you need for something you don’t need!
£CVSG, CEO overview of interim 2022 results by Richard Fairman. Video and podcast. Demand for vets is strong.
The revenue benefit of extra pet ownership during lockdown comes in the future, as pets get older they need more medical intervention. (Like us all!). Good growth and strong margins. We should have this morning's analyst presentation in due course.
At 1pm today (24.3.22) Pebble (LON:PEBB) management will present full year 2021 results, which were announced on Tuesday. The share price is up over 20% since the announcement. The Facilisgroup is the most exciting, imho. A SaaS platform to help their customers automate the purchasing process from conception to delivery. They are in the promotional products industry like 4imprint (LON:FOUR) & Altitude (LON:ALT). Register for the webinar here.
Other results webinars coming up below, register for all here:
Personal Group (LON:PGH) Full Year 2021 results: Friday 1st April, 12 noon (In a hot space of employer benefits for employees, during the current talent war).
Property Franchise (LON:TPFG) Full Year 2021 results: Wednesday 6th April, 12.30pm (A franchise estate agent, an excellent business model, similar to Belvoir (LON:BLV)).
Tracsis (LON:TRCS) Interim results: Friday 8th April, 1pm (The last trading update guided EBITDA +10%, with Events & Traffic Data recovery, and, we'll hear more about the North American Rail Acquisition.
And, the Stockopedia/PIWORLD StockSlam: Wednesday 6th April, 6pm. Where 10 private investors 'slam' their best stock idea in 3 minutes (with a pitch by the one and only Paul Scott!), followed by Q&A. Register to attend live, here.
Atalaya Mining (LON:ATYM) released a strong set of results showing a quadrupling of post tax profits and declaring an inaugural dividend.
I run a pretty diverse share portfolio of 40 companies and a few ETF's which I hope stops huge swings either way as frankly I don't need the stress and need a good nights sleep. I actually hit an all time high just before the end of the year but have seen my shares go down about 10% this year with most things off their highs with the exception of Bae Systems (LON:BA.) I suffered a big loss on Polymetal International (LON:POLY) which I have since sold but it was about 2% of my portfolio at the end of the day.
Everything else I am happy with and the results still look good overall so I am optimistic long term with my holdings. As I still work full time I have excess income which I will invest if the markets go down more (I added at the start of March some.) With inflation and the war I am hesitant to add more at the moment to what I did at the start of the month.
Overall I am not feeling so depressed as I was a couple of weeks ago, probably as there's been a notable uptick in the last 10 days or so but I'm also aware the next 12-18 months could be very bumpy
I can confirm that holding Polymetal International (LON:POLY) does not contribute to a good night's sleep!
Paul, in response to your imprecation to think long term, an investor is a business owner, whether they think like one or not. And having been of an entrepreneurial persuasion for much of my working life, I can add these thoughts.
Owners of businesses don’t go round all day wondering about the price someone will pay for their company. They concern themselves with the performance of the company and appoint representatives to devise strategies to maximise revenues, to develop a loyal and competent workforce and to deal with issues as they arise.
When the GFC and pandemic came along, owners didn’t rush to the nearest business broker to ask what their company was worth or fret about selling their stake. They knuckled down and made sure the company would survive any existential threats and be best placed to capitalise on any rebound.
Eventually, for every business there is a point where the owner’s state of mind or stage of life coincides with a period of very strong trading. Only then does the owner seek a buyer. Up to that point, the exercise is purely academic.
Paul I think most of us really appreciate your honesty above everything else. Of course we really appreciate your forensic analysis of so many companies , but only a naive fool would expect you to call the market and anticipate the future. You have always told us to do our own research, but I suspect many just follow you blindly, and now feel somehow let down!!
FWIW, I am in exactly the same position as you, and hence am happy to keep all of the stocks in my portfolio, and will enjoy the dividends and wait for market sentiment to improve .
Keep up the fine work.
Thanks Caper4!
I think it's important to own bad patches, not just brag about the good patches. Sadly, so many Twitter people & other commentators like to do the bragging bit in the good times, then just go strangely silent in the bad times, then claim afterwards that they sold at the top, and bought back at the bottom. All nonsense usually of course, but their fragile egos don't allow them to do anything else.
I know many super successful multimillionaire investors, who I've watched make serious money over the years. They share one common trait - they never brag about performance, because they don't need to.
Also, they get plenty of shares wrong, and are open about their mistakes. But usually they hit a handful of major big winners, and run them, which is where most of the money comes from - just a handful of key winners, over a whole career, very often.
Regards, Paul.
Ian Cowie’s column in the Sunday Times Money fits the bill! Always buying ahead of a rise and selling before a fall. Occasionally admits to a minor error but much, much less than claimed successes.
Ian Cowie's columns are also incredibly superficial - his buying rationale is usually along the lines of 'people are always going to like Magnum ice cream so let's buy Unilever' - I don't think he even considers valuation and definitely never looks at the balance sheet or generally looks under the bonnet. He does have a pretty good record though so perhaps he's got the right approach.
I am perhaps going over old ground from yesterday but I think this is important for Saga (LON:SAGA) I have reposted some comments from yesterday:
Is this not a concern for everyone?
"The reported loss before tax for 2021/22 of £23.5m was materially better than
the £61.2m loss in the prior year, mainly due to significantly lower
restructuring costs, as well as the £59.8m goodwill impairment included in
the 2020/21 results."
Does that actually mean that the trading results for 21/22 are worse than 20/21?
Yes, if you look at the underlying numbers, the PBT has swung from a £17.1m profit to a £6.7m loss, largely due a downturn in the Insurance business.
Yes thank you, we saw this comment yesterday, I don't think there is any valid reason to repeat it today.
Short-term results for Saga (LON:SAGA) are not what it's all about, since the important travel division was shut down or heavily restricted by covid. So the above is not really relevant to the performance of the business in future, when travel is fully recovered (probably FY 1/2024). That's what it's all about - recovery from covid.
P.
Paul, fair enough. My wife tells me I am like a dog with a bone.
rmillaree thanks for your input. Yes, that makes sense.
I have another question about Saga. I'll save that one for tomorrow. :-)
Just kidding.
£saga
CamRaid
I have another question about Saga. I'll save that one for tomorrow. :-)
Now a dog with a bone wouldnt be looking at its bone for 24 hours before attacking it - fire away with your question before we all pack up and depart outdoors for the weekend.
I don't know if this was picked up earlier in the week but the FT reported that Saga (LON:SAGA) had hedged all of this years fuel costs and could hedge next years at current prices for a cost of £3.0M.
Yes it was on yesterday's investor presentation available on the website. I'd also point all holders to the slides qs there are some interesting insights particularly around cruise where they have restated how the ebitda of 40m is derived. They've also reduced their pbt yield to 18m from 20m per ship. Lots of moving parts.
Saga (LON:SAGA) correction pbt adjusted to 16m per ship
Saga (LON:SAGA)
Camraid
"Does that actually mean that the trading results for 21/22 are worse than 20/21?"
Yes but that fact was flag up months ago that an underlying loss was expected (certainly that position was re-confirmed in january trading update) - so it was fully expected that this would be the case - so its no new news yesterday in that regard - ie a non event.
Note it would probably make sense that for ye 31/1/2021 there would be "bumper insurance profits" from peeps paying full years car insurance but driving much less - that seems to be the main differentiator looking at the two years- probably more freebie handouts from the government too that prior year (overheads materially lower).
Both these years have huge travel losses so the investment case is still pretty obvious that in normal year those travel losses should be replaced by profits - so in some respects both years are equally unrepresentative of what they can acheive in normal year - it is the outlook as to where they are going to and that is what we need to concentrate on rather than either of these two years figures.
Obviously the not so good news was the flagged up ref expected reduction if insurance profits this year and next and the slower than i would have liked bounceback ref the travel side of things (it very early in year to judge here though) - I very much agree with Paul though that travel this year will certainly not be up to full speed - its just a question of how much progres they can make towards normality - it looks like we may have to wait for next year to see "good profits" presuming nothing goes wrong in the meantime (full on irony mode here !)
Keep in there Paul. Most investors are in the same boat and it’s easy with hindsight.
Jack told me stockopedia are looking for someone who can do a similar job to Paul, but for the Precious metals market. This is really needed now imo. So if anyone knows someone who could do this, ask them!
Your honesty and balance sheet skill is an important part of my day Paul. I was an over leveraged inexperienced Put Option writer in October 1987, you can guess the rest but the capital losses came in handy for years afterwards. Enjoy your day.
Momentum keeps building at Beeks Financial Cloud (LON:BKS) :
... cloud computing and connectivity provider for financial markets, is pleased to announce the signing of a multi-year Private Cloud contract. The contract , worth £4.4 million over five years, is for a new European Tier 1 client, and was secured via a partner.
"Successfully securing a further contract of such significance reinforces our belief that the prospects for Beeks have never been stronger, as financial services organisations accelerate their cloud strategies. Alongside other recent wins we have announced, this latest contract contributes towards underpinning our FY23 expectations. A substantial pipeline continues to build across our Private Cloud and Proximity Cloud offerings, and we are confident in our ability to further increase our market share."
https://www.investegate.co.uk/...
(There is also an Interim Results presentation hosted on Investor Meet Company at 12h00 today. )
I've been in Beeks Financial Cloud (LON:BKS) for a few years and bought in at about 98p a share so am very happy with holding this and continuing to do so. To me this is operating in a very niche space where economies of scale will kick in and they should overtime generate a good profit of between 20-30% (the giants like AWS manage about 35% so I am assuming Beeks won't get quite the same scale.) I do believe at some point this is going to get taken over but I hope its a few years from now and the share price is significantly higher than it is now
Very excited about this one