Small Cap Value Report (Thu 28 July 2022) - HOTC, APTD, RST, HEAD, SRT, TWD, INCE, EPWN, VINO, FORT, FNTL, DSCV

Good morning. Paul & Graham are here today.
Agenda -
Paul's Section:
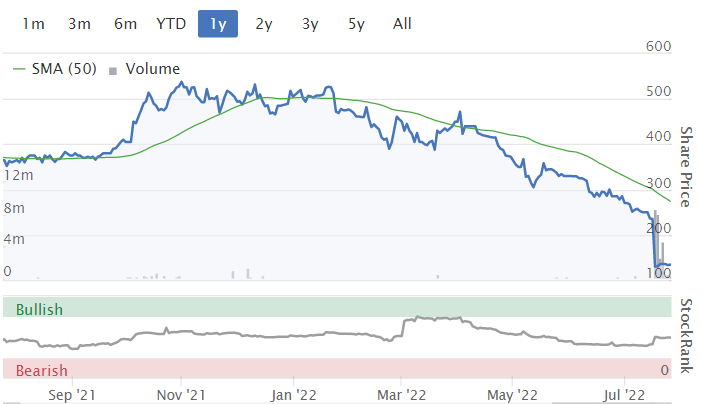
Hotel Chocolat (LON:HOTC) 134p (unch.) (£184m) - confirms today that its Japanese JV has entered court protection to restructure. Hence a c.£30m hit to HOTC - as indicated 9 days ago in a bombshell announcement, so today is really just confirmation. I question how management allocated capital so badly - spending about £1m per shop in Japan, for just 20% ownership of the JV? Despite crashing by about 80% this year, HOTC shares still don't look cheap yet, given it's now really just a UK business, and faces plunging profits in 2023 from cost headwinds.
Headlam (LON:HEAD) 307p (down 1%) (£257m) - a surprisingly good trading update, with self-help measures absorbing costs & reduced volumes, to still report increased profit in H1, and in line with expectations for FY 12/2022. Very good balance sheet, although cash is down a lot, partly due to generous shareholder distributions. A very nice value share, thumbs up from me.
Ince (LON:INCE) 5.6p (down 53%) (£5m) [No section below] - this one continues to be a disaster, we’ve been warning against it here for years, due to a diabolical balance sheet, with all sorts of nasties in it - e.g. large deferred consideration, excessive debtors, bank debt, and deeply negative NTAV.
INCE did a deeply discounted fundraise once before, and it’s now announced another one! 5p placing, a 58% discount. I wouldn’t pay anything for INCE equity personally. Although occasionally things like this can be speculative multibaggers, but a more likely outcome seems to me that it gets taken private for tuppence, or goes bust. It’s amazing to think these are lawyers & financial experts, yet are utterly incompetent at managing their own finances (although to be fair, the same accusation could be levelled at me! LOL!). INCE equity is therefore uninvestable at any price, in my view. For gamblers only - you never know, occasionally these things do pay out, although not often in bear markets. At least the risk of insolvency might have reduced somewhat, given this latest emergency fundraising.
Epwin (LON:EPWN) 76p (down 1%) (£110m) [No section below] - A solid H1 trading update. Trading has “moderated slightly” in June & July, but it “remains confident of achieving expectations in 2022”. H1 revenues up 13%, mainly due to price rises - good that it can pass on cost inflation. Managing OK with supply chain issues. Modest net debt of £7.3m, 03.x EBITDA. Tons of headroom (£65m) on bank facilities. Last balance sheet (at Dec 2021) was OK, at c.£20m NTAV, worsened by net lease liabilities. Overall - looks reasonable, although I’d be worried it might see business turn down once current shortages & premium prices for building products normalise, possibly? Generous divis, with a 6% yield, twice covered - not to be sniffed at, if that’s sustainable.
Virgin Wines UK (LON:VINO) 67p (down 8%) (£37m) [No section below] - FY 6/2022 results. Revenue down 6% on last year, to £69m, as the pandemic boost wore off. Although still up 63% on a pre-pandemic basis. Plenty of cash. EBITDA £6.3m, which Liberum converts into £5.3m PBT, and EPS of 7.5p = PER of 8.9 - starting to look attractive value (at a third of IPO price!). Forecast balance sheet is OK, and has about £11m NTAV. My view - I was expecting to dismiss this, but actually it’s now looking sensibly priced, for quite a decent, profitable small business. Lots more detail in the RNS. Worth a closer look, to put it on the possible buys list for later, I think. I don’t see any rush to get involved here.
Forterra (LON:FORT) 296p (up 2%) (£646m) [No section below] - very good interim results from this brick maker. I like the strong profit margins too. Positive outlook, FY 12/2022 profits to be “slightly ahead” of expectations. I like the balance sheet - dominated by huge fixed assets, but all bought & paid for, with no net debt (net cash actually, at £24.1m). Decent divi yield of 4.7%. Looks a very nice value share, if you think strong demand is likely to continue. High StockRank of 92. Thumbs up from me.
Fintel (LON:FNTL) 200p (down 1%) (£207m) [No section below] - a trading update for H1 of FY 12/2022. “Core” numbers strip out the effect of disposals - H1 revenue up 9% to £27.1m, adj EBITDA up 5% to £8.7m. Zeus (many thanks!) forecasts FY 12/2022 EBITDA of £19.0m, which is 12.0p adj dil EPS. So a PER of 16.7 - looks a bit pricey in a bear market. Although much revenue is recurring. Last balance sheet at Dec 2021 looks thin, with negative NTAV of £(8.1)m. Although plenty of liquidity now, with cash of £7.6m, an undrawn RCF of £45m at June 2022. Small divis. My view - looks a decent business, with nice recurring revenues. A bit pricey for me though, in current market conditions.
Discoverie (LON:DSCV) 738p (up 8%) (£705m) [No section below] - A good Q1 (Apr-Jun) trading update, with strong organic revenue growth of 17%, with another 10% on top from acquisitions. Profits are ahead of expectations. Record order book (up 40% organically in a year) at June 2022, but expected to “begin to normalise” as the year progresses - have customers been building up inventories maybe? Margins resilient. Chip shortages have improved, but “remain tight”. Sri Lanka is 6% of group production - OK so far, but contingency plans made. Acquisition is on track. “Well positioned” overall. My quick view - looks a good business, performing well. Priced accordingly at a PER of c.20.
Graham's Section:
Aptitude Software (LON:APTD) (£198m) - The full-year outlook is unchanged at this enterprise software group. Organic growth is reported at 10%, and total growth is much higher after an important acquisition completed late last year. The company has an impressive cash balance but the overall balance sheet strength is limited. Operationally the company appears to be performing well with good momentum. Valuation remains a niggle for me but I can’t deny that much of the air has already come out of this stock.
Restore (LON:RST) (£613m) (+0.9%) [no section below] - this is a group of five support services businesses. Jack last covered it here. Today’s half-year results show 32% revenue growth, of which 19% is organic and 13% relates to acquisitions. I suspect that these results still include an element of recovery from the Covid-induced downturn. Adjusted PBT increases by 36% to £21.2m and the company includes a helpful bridge to show how this was achieved: price increases mostly offset cost increases, and there was a huge bounce in activity levels compared to last year. Net debt is now over £100m and more acquisitions are coming in the pipeline. I agree with the StockRanks which argue that there’s limited value on offer here (PER 16x) but potentially this is compensated for by a lower risk profile than most small-caps.
SRT Marine Systems (LON:SRT) (£51m) (-4.5%) [no section below] - this is a company with a long track record of promising investors the world, and delivering very little. It describes itself as “the global leader in maritime surveillance, security, management and safety products and integrated systems”. Revenues and cash flow are lumpy and unpredictable, as large contracts are negotiated in far-flung parts of the globe.
Today’s results show a £6m loss on £8m of revenues. The poor performance necessitated an equity placing during the year. But it’s not all bad: there’s a £600m “validated sales pipeline” (?), and the long-standing CEO says he has “started to see strong demand return for our products… which I expect to be reflected in next years (sic) financial results”. Plus ça change.
Trackwise Designs (LON:TWD) (£15m) (-10%) [no section below] - this company releases its 2021 results very late: the delay was previously blamed on “the cumulative impact of Covid-19, including related staffing absences”. The results show revenues up 32% to £8m and a small adjusted operating loss (excluding share-based payments and new facility set-up costs).
Balance sheet - the 2021 Auditor’s Report will include a Going Concern warning. TWD already raised £7m in early 2022, but the net debt position still rose to nearly £8 million by the end of June. The outgoing CFO Mark Hodgkins, says that in a “severe but plausible downside scenario”, in which it failed to secure the facilities it is currently negotiating, the company would face a fresh shortfall of £6.8m.
Profit warning - revenue from TWD’s most important customer has been “delayed” and brokers have this morning slashed their FY 2022 revenue forecast by 53% to £10.5m. They forecast year-end net debt of £14.5m, which looks very dangerous to me in these circumstances. I consider this stock uninvestable.
[Paul adds: Thanks for this Graham! I was warming to TWD as a speculative punt, but your update today has put me off. Looks more risky than I suspected when I looked at it here in June. Interesting new products, but I'd like to see more secure finances before investing here.
EDIT: Also note there is an InvestorMeetCompany webinar which is available as a recording, which I watched over the weekend. Management say the audit disclosures were required, but that they believe they can plug the funding gap mainly with new borrowing facilities which are in negotiation, e.g. for HP on capex, (£4.4m), a £1.9m trade finance loan, and £1.4m from improved payment terms from their nickel supplier from 2023)]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Hotel Chocolat (LON:HOTC)
134p (pre market open)
Market cap £184m
Has gone into Court protection, whilst it tries to restructure & raise more capital.
HOTC’s exposure -
- Loan of £23m outstanding,
- Guarantees of up to £5.8m re leasing company loans.
My opinion - this is really just confirming what was said 9 days ago, which I covered here, when HOTC indicated a full impairment against the JV loans was necessary. The £5.8m loan guarantees in addition are new to me though.
There’s not really anything to add from today’s announcement. If anything, it might be a positive, to draw a line under a disastrous overseas expansion strategy. What I don’t understand, is how has HOTC managed to squander c.£30m on a JV that it says today is only 20% owned by HOTC (I had assumed it was a 50:50 venture), and yet which produced only £5m retail sales in H2 of calendar 2021. Even allowing for some impact from the pandemic, this seems a massive investment for 20% ownership of only 31 stores, about £1m each! How is that even possible? Management seem to have made extraordinarily bad capital allocation decisions. They’re not going anywhere though, with controlling combined shareholdings.
If you’re thinking about buying/holding this share, Roland’s recent article is a must-read.
Overall, my view is unchanged after today’s (predictable) update. Management have made some terrible mistakes, and I have to question their competence. But, they’ve built an impressive brand, and the UK operations seem to have good potential still.
The other thing to consider is the big cost headwinds, that have caused FY 6/2023 forecasts to be slashed. The consensus figure on Stockopedia of 8.9p EPS could come down, as one recent broker update I saw was just 5.6p. At that level of earnings, a share price in double digits would make more sense than the current 134p.
It’s tempting to have a nibble here, but there could well be disillusioned fund managers dumping their holdings, now the big growth dream of international domination has evaporated. I see that recent TR-1 forms have been disposals by abrdn, which has reduced from 7.1% to under 5%, so presumably they’ll still be selling in the market for a while.
I’m not convinced it has de-rated enough, and with no particularly compelling reason to buy, think I’ve persuaded myself to sit on the sidelines here for a while.
The good thing, is HOTC can absorb the hit from Japan failing, because it’s mainly a write-off of a balance sheet (non-cash) asset. The £5.8m loan guarantees would be cash outflows, but that’s affordable within existing resources. Hence risk of dilution from a placing, is close to zero, in my opinion, nothing to worry about there (assuming there's no more material bad news yet to come).
There is de-listing risk though, given management controlling shareholdings, and after the humiliation of screwing things up badly, they might decide to take the company private. I don't trust their judgement, so think I'm talking myself out of wanting to invest here. Let's see where the dust settles.
.
.
Headlam (LON:HEAD)
306p (down 1% at 08:46)
Market cap £257m
Headlam Group plc (LSE: HEAD), the leading floorcoverings distributor, is providing a Pre-Close Trading Update in respect of the first six months of the year to 30 June 2022 (the 'Period') ahead of announcing interim results on 6 September 2022.
Company headline - is a concise and accurate summary -
Improved profitability despite economic backdrop
My summary -
H1 revenue £323.8m down 1.9% on H1 LY (that’s OK, as the StockReport shows forecast revenues for FY 12/2022 are flat vs LY)
UK revenues down 2.9% (weakness in residential), with the small France/Holland division up 5.1%, partially offsetting UK weakness.
Underlying PBT improved, at £17.3m for H1 (up 3.6% on H1 LY)
Operational efficiency & cost control drove the profit increase.
Believed to have increased market share.
Prices increased, driven by manufacturers - helped to offset operational cost inflation. (This must mean volumes dropped more than the 1.9% drop in revenues, given that prices increased)
Outlook - strikes me as good, in the current tougher macro conditions -
Currently, the Company remains on track to meet market expectations4 for the year, although the marketplace will undeniably continue to present weakness on the residential side and operational cost inflation headwinds remain.
4Company-compiled consensus market expectations for revenue and underlying profit before tax, on a mean basis, are available on the Company's website at www.headlam.com.
This link is better, as it takes you to the actual page you need, instead of wasting time looking through the website trying to find it!
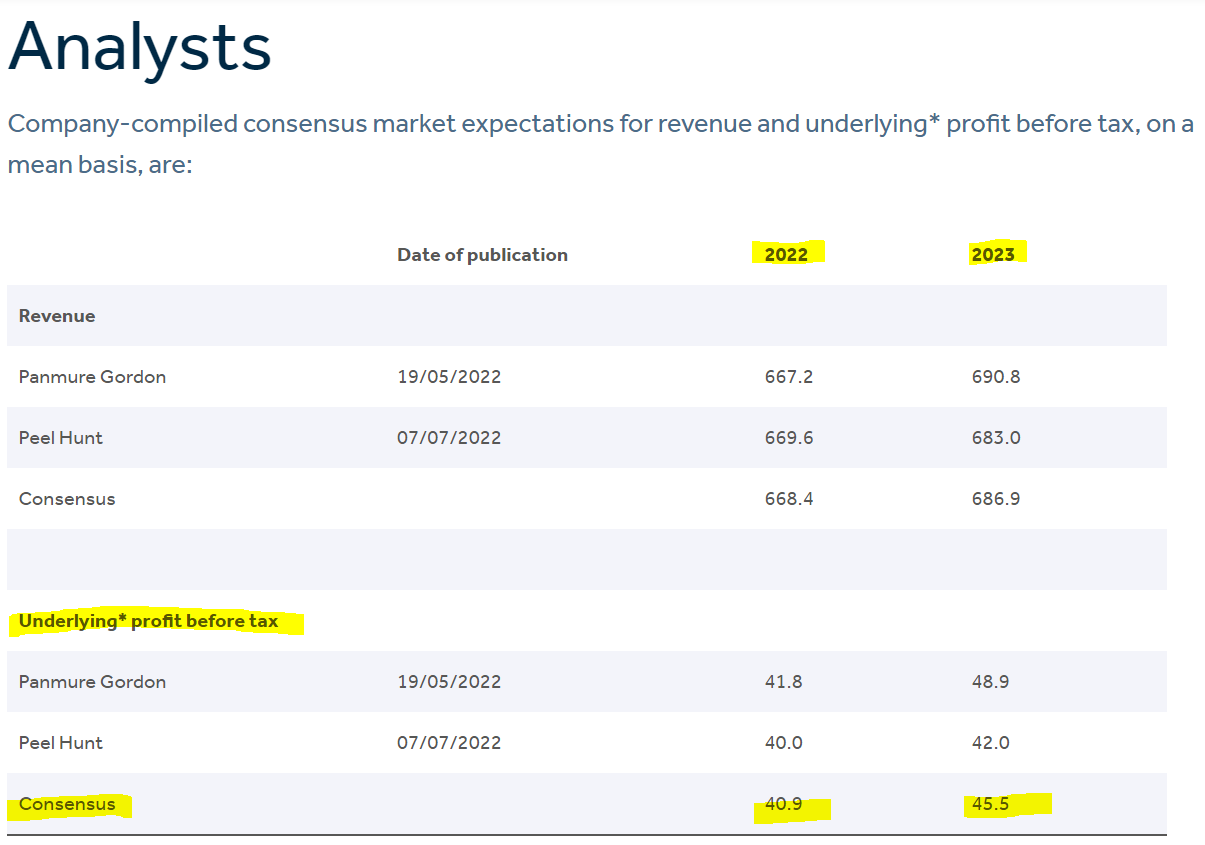
This is great info (copied below).
If HEAD can publish broker forecasts on its website, even for a shy one like Peel Hunt, why can’t everyone else? Maybe companies need to insist on being permitted to publish this info on their investor relations websites, when signing up with a new broker?
.
These numbers look consistent with the broker consensus figures on Stockopedia (which are different, because they’re post-tax, and EPS).
That means the current year PER is about 8.4, dropping to 8.0 next year. That seems cracking value to me. Maybe the market is worried that consumer food/energy squeeze might trigger an H2 profit warning? That’s possible I think, so some allowance probably should be factored in for weak macro.
The CEO says -
"We are pleased with our performance thus far in 2022, particularly given the economic backdrop.
Profitability has been improved, market share gains made, and our strategy is proving to provide a countermeasure and protection against a weaker underlying market.
We believe we are set fair especially for when headwinds ease."
Net cash/ Balance sheet - Net cash has dropped a lot, it was £53.7m at Dec 2021 year end. That has now dropped to only £6.0m at end June 2022. How come? £25.8m has been paid out to shareholders, including both last year’s final divi, plus a special divi, and it’s also doing daily buybacks too.
Other reasons given for cash falling - stocking up ahead of busier season & new product launches, and capex for expanding the trade counters side of the business.
I don’t think this is a worry, as HEAD is very soundly financed, with a lovely balance sheet. As the company points out today, it owns freehold property in the books (2020 valuation) at £110m - amazing really, for a £257m market cap company with no debt.
Hence shareholders here do not need to fear either solvency, or dilution, even if the economy deteriorates.
My opinion - the share price has fallen a lot, which is nothing to do with the company’s performance, which remains good.
This is an excellent value share, in my opinion. You’ve got the safety of a really strong balance sheet, no debt, loads of freeholds, and a twice-covered divi yield of 6% protecting you against inflation, and/or providing an income.
Sure, there’s a risk of an H2 profit warning if consumers switch off discretionary spending in the autumn, which is probably why the share price is on the floor. But it’s becoming more obvious by the day that Governments will have to take more decisive action to mitigate soaring energy costs later this year. Plus plenty of households have savings, and so can afford to replace carpets regardless.
The commercial sector declined during the pandemic, whilst residential did well. That’s probably reversing somewhat now.
HEAD has a really good business model - selling a wide range of large, bulky products, which customers couldn’t realistically stock themselves. So customers need HEAD, and the wide range & bulk buying power creates a barrier to entry for competitors. There's also a longer term opportunity to maybe even sell direct to consumers?
I wouldn’t normally be interested in buying this type of cyclical share in an economic downturn, but HEAD is doing a lot of self-help stuff, to make the business more efficient. Hence why it has been able to absorb a downturn in revenues, whilst still reporting increased profits. That protects profitability now, but also gives a springboard for future growth when the economy has calmed down, and inflation falling. Also, it's all about valuation - I think the share price has overshot on the downside, for investors taking a longer term view.
A solid thumbs up from me. I’ll be buying back into this share later this year. It’s tightly held, so surprisingly difficult to deal in.
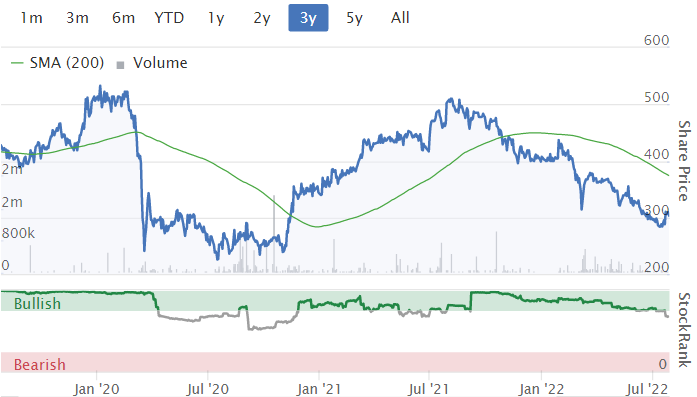
It got irrationally cheap during the pandemic too, then recovered strongly. I imagine, at some unknown point, we're likely to see a repeat of that in future -
.
Graham’s Section:
Aptitude Software (LON:APTD)
- Share price: 345p (pre-market)
- Market cap: £198m
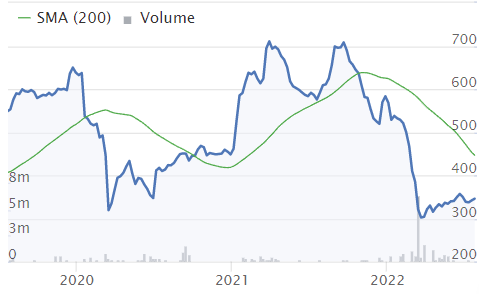
Looking deep into the archives, I previously thought that this enterprise software provider was overvalued at 544p.
It has been a bumpy ride for shareholders:
Today’s interim results benefit from an October 2021 acquisition that was described by Jack here.
Strip that out and the organic growth rate at Aptitude is around 10%. Which is perfectly good, but not enough on its own to justify a very high rating for the stock.
Aptitude tends to enjoys a high rating and this remains the case today, even after stock has deflated so much:

Some key points from the interims:
- Annual Recurring Revenue £49m (up 10% organically, at constant currencies)
- Total revenue for H1 2022: £36.1m, of which £24.4m was recurring in nature.
- Cash £23.6m, net cash £13.5m after subtracting financial liabilities.
- Balance sheet equity £59m, but negative net tangible asset value.
- Outlook for 2022 is in line with expectations.
The balance sheet doesn’t give any cushion in terms of NTAV and while the cash balance is impressive at nearly £24m, some of this may be required to help deliver £30m of deferred income (products paid for upfront by customers, and delivered over time - this is normal in software businesses). The company says H2 is seasonally stronger for cash.
While this balance sheet doesn’t worry me, I don’t think it offers much of a buffer and I wouldn’t say that it’s a positive factor when it comes to valuing the business as a whole. Aptitude used up its previous balance sheet strength to get the 2021 acquisition done.
Operational highlights - lots of positivity here. It’s not hard to imagine the value of Aptitude’s solutions in the subscription-based world we live in. So hopefully the company can keep going on this positive trajectory. I also note Aptitude’s launch of Fynapse, its new finance management platform for CFOs.
From the statement:
The Group is confident that Fynapse will accelerate the Group's growth in the medium and long term whilst also generating higher gross margins due to the cloud native technologies on which the platform is built. Fynapse provides differentiated finance digitalization capability to a market in which the Group already has outstanding credentials with the successful Aptitude Accounting Hub.
My view
For this type of software company, I tend to check the market cap as a multiple of recurring revenues. In this case, the multiple drops out at 4x.
I’ve seen many examples of companies trading higher than this - e.g. Quartix Technologies (LON:QTX) which trades on six times recurring revenues.
Of course margins and profitability should also be taken into account, and if there are any other risks such as customer concentration. According to the most recent Annual Report, Aptitude did not have any customers accounting for more than 10% of total revenue. So I’m going to assume that customer concentration is not a factor here.
Given the modest organic growth rate of 10%, I still find it difficult to get on board with the market’s valuation of Aptitude.
But when I looked at this company two and a half years ago, it was trading at more than 10x recurring revenues, not 4x.
At 4x, it makes much more sense, especially for someone who thinks that organic growth can accelerate from the current level.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
M&C Saatchi (LON:SAA)
Artisan Partners increasing their position and the SP drifted up a bit yesterday - possibly as a result of a trading update. I wonder if somebody knows something?
https://www.londonstockexchang...
Hi Paul, Graham,
Excellent short/summary commentaries today. I am a definite fan of them and just loved the "are utterly incompetent at managing their own finances (although to be fair, the same accusation could be levelled at me! LOL!)" comment!
Hi Paul ,
A brief comment on your comments regarding Reach plc. This was one of my biggest investments and having exited between £2.80 and £3.20 , I have decided to reinvest again under 90p.
The actuarial valuation of the pensions assets is nothing else than an appraisal of extreme economic conditions. It’s exactly the same thing as the BOE tests carried on the banking sector and based on violent and unfavourable economic conditions , in Reach’s pension deficit case a stock market collapse and 0% interest rates. I believe that this deficit will disappear with another 1.5% increase in interest rates. Then the board will have the option of buying an annuity.
On your comment regarding the declining newspaper and printing sector I have to agree with you , but also emphasise that the expected revenues are just the same as the 2014 revenues and there was a £100 debt also at that time!
In addition there seems to be an 8p yearly dividend based on my calculations , that is about 9% and plenty of cash and future cash flows for acquisitions and perhaps buybacks.
Buying an annuity is also based on an actuarial valuation which is appraised on even more extreme conditions.
I don't think that's the case for a pension buyout with an insurance company - they would base it on more realistic assumptions, not the ultra cautious assumptions used in the actuarial model. If interest rates rise a bit more, they should be able to easily offload the pension to an insurer.
Exactly this is what I was trying to say in a nice way.
Absolutely not. The liabilities on a buyout valuation will be much higher than on an actuarial valuation.
This is not right. The insurance company base their calculations on far more conservative investment assumptions than the average actuarial valuation, and then add their profit margin on top. A pension scheme might typically need to be something like 120% funded compared with the 'technical provisions' used in their actuarial valuation, never mind the IAS19 fantasy numbers in the accounts.
A buyout is a very lengthy process - a couple of years, not weeks or months - and needs clean member data including wonderful things like GMP equalisation which most schemes have not yet completed. There is nothing easy about a pension scheme buyout!
I'll stop there, because any commentary on the farce that is company pension accounting and comparison with other valuation bases runs the risk of ending up longer than War & Peace...
My comment was in response to Bouden, not shopoffrogs, who is absolutely spot on.
That’s why the market fluctuates on a daily basis. You and 12barblues say this , Paul says another thing , and Bouden54 and I offer a completely different opinion based on how we understand things and probably how we have experienced similar situations in the past.
The question is simple , since I started this conversation:
Is Reach plc a good investment under 90p in the foreseeable future? I strongly believe based on the figures that I have in front of me , and the guidance from the company , that it is a good investment.
Well , at the end of the day Mr Market is going to decide and prove who is wrong and who is right.
Hi yiannos1,
To be fair, I did say in the main article that valuation of Reach (LON:RCH) shares rests very considerably on how the pension deficit actually pans out. The existing agreed cash payments are just over £300m to 2027. It has not been able to agree updated deficit recovery payments with 3 of the 6 pension schemes trustees, which doesn't suggest to me the problems are going away any time soon.
I don't have a strong view either way, because I don't know how the pension scheme will end up getting resolved. As said in the main article, if you think (as you seem to) that the pension scheme liabilities will disappear quite soon, then RCH shares could indeed be very cheap. That's a perfectly rational view, if you turn out to be right re pension scheme liabilities.
I wouldn't bank on interest rates continuing to rise though (thus reducing scheme liabilities). As we saw last time the Fed (which indirectly drives (or at least influences) the UK & Europe) tried to tighten, it stalled the stock market, and they were worried about the economy going into recession, so the US reversed back to near-zero interest rates, causing pension deficits to shoot back up again.
This week we've had news that the US has entered a technical recession, so why would the Fed keep raising rates, and crash the economy? I just don't see that as likely at all. Particularly where the causes of inflation are already peaking, or sowing the seeds for lower inflation (e.g. falling commodity prices, supply chains beginning to ease), all combined with a squeeze on consumers, meaning that sales volumes are already falling at many companies (e.g. Headlam (LON:HEAD) yesterday).
Some of my more knowledgeable City friends think we could even go into a glut for many products next year, bringing inflation down very rapidly, and with it interest rates, as the Fed/BoE decide the economy needs boosting to get it out of recession, rather than more tightening.
On the question of buyouts of pension schemes, I don't know a lot about this, but do recall a question I asked mgt of Norcros (LON:NXR) a few years ago. Why don't you just hive off the pension scheme to an insurance company, or similar? He sighed, and said it's a 30-year liability. If we sell it on to someone else, they'll want belt & braces calculations, and add their profit margin on top. Why would we give away all that money to someone else, when we can manage it ourselves?
Another thing he pointed out, is that a lot of the pensioners might be elderly, but when they die, there's a continuing liability to pay a widow's pension. In some cases, the widow can live another c.20 years.
Hence I remain of the view that we shouldn't just dismiss the RCH pension scheme liabilities & cash contributions, which are currently consuming about half profits. As profits (inevitably) fall in the coming years, then that could end up at three quarters, or even all of the profits. Who knows?
As I say, no firm view from me either way, because I don't know what will happen. But I think it's right to flag the issues, which the company tends to gloss over I think.
Regards, Paul.
£INCE Paul, classing lawyers as financial experts is a major misnomer. All too many partners in law firms start from the premise of " What do I need the firm to pay me in order to support my lifestyle ?" rather than " What can the firm afford to pay me?" and as for sums sitting on the balance sheet as debtors - the accounts should be nominated as a contender for the Pulitzer Prize for fiction. Not that I'm bitter or anything!
£HEAD Whilst I think this is a good company that has delivered over the years and should go on doing so, I wonder from the last two updates whether they are just optimistic about avoiding a profit warning. In May they said 'broadly' in line with residential down 0.5% and Commercial +5.8%. In two months this has become residential -5% and Commercial only up 4.9%.
Again, going back to May they said Commercial had been poor for the last two years and they were expecting a pick up from the education sector but no specific mention in todays update. I was also concerned that they gave their strategy then as to 'capture market share in underweight customer segments' which seemed to imply they were finding things hard in their traditional sectors.
I would quite happily own this share because of strong management who seem to make long term decisions but not convinced now is the right time to do so.
I agree that Headlam (LON:HEAD) is a 'good' company. I hold and have added a few today. They have a suite of self help measures in place and the balance sheet is sound. I especially like the value of its freehold property, cited at £109m in the trading update. I assume that Paul arrived at his figure of £120m by including the book cost of the new Ipswich distribution centre that was completed in July 2020.
My best expectation in the short term is that the company will tread water. I am conscious of the potential for a profit warning, but if one can be avoided that would be a great result in my view. On a medium term view I think that the shares are great value. In a 'normal' market with a reasonable economic outlook they have historically traded on a PE of 14 or thereabouts. Hopefully I am laying the groundwork for good future returns, but accept that I have to be patient.
All the best
Liontrust Asset Management (LON:LIO) one of the 2022 Naps now yielding 8%. Clients need money managed. Maynard Paton covers here:
https://knowledge.sharescope.co.uk/2022/07/27/screening-for-my-next-long-term-winner-liontrust-asset-management-lse-lio/
Epwin (LON:EPWN)
Epwin may be worth some comment - albeit "in line" news doesnt really say much new does it (net debt update is appreciated) ``- pleasing half year update confirming everything on track - per stocky this is trading on p/e of 8.5. Probably to be expected if peeps are factoring in a recession or drop off in business that the company doesnt see coming as of yet??
I would say epwin is now in rude health (good) compared to where it has been in the recentish past. Debt down to modest levels so they have some scope for inorganic exapansion if needs be. For once the "strong balance sheet" comment isnt a complete lie as is often the case - net debt at end of 2018 was £25 mill and they mention covenant net debt as only being £7 mill now - slightly sketchy comparison but it does look to be fair comparison as ye 31/12/2021 net debt was down to £9 mill - only modest increase in share count since 2018 too. So they are providing they are making real profits and have very sensibly been reducing debt (UK PLC take note).
Per company today
"I am pleased to report a good trading performance in the first half. We
remain confident of achieving our expectations in 2022, underpinned by ongoing
proactive management of the raw material cost. Looking further ahead, the
medium and long-term drivers for the Group's products remain positive."
The Group retains a strong balance sheet to support its strategic objectives,
including value enhancing acquisitions. Covenant net debt at 30 June 2022
has reduced to £7.3 million (31 December 2021: £9.4m) which is 0.3x adjusted
EBITDA, providing the Group with in excess of £65 million of headroom on its
facilities.
I would be interested if anyone has a view Completion of Convertible Loan Note Fundraising of £1m by LON:BYOT (I hold). The summary of the RNS is below. Is it just me or is there something odd going on here?
They have adequate cash on the balance sheet so is it a method of tying in good management, a sign of optimism or something dodgier? Normally Director buying is a good thing. Maybe I've woken up half-empty for once.
The Loan Notes carry a coupon of 9% per
annum, payable quarterly in arrears.
Based on the issue size of £1,000,000, the Loan Notes would, if converted,
represent approximately 30,769,230 Ordinary Shares, amounting to 6.8% of the
current issued share capital of the Company. The "shares equivalent" represent a premium to the current price.
Over half of the funds raised have been taken up by Directors/NEDs
Whilst sometimes Directors purchase shares and it doesn't prove to their advantage, I would have to say this is positive, but mainly for those Directors that have participated. They are getting circa 9% for their risk, and they can convert to equity later (within the five year term) if the prospects are good.
I guess the note will allow either for the 9% coupon to be paid by the Company annually (which is 9% of the rough historic operating profit that seemed to be in evidence) or accumulated if the Company doesn't want to pay out the cash in a financial year?
This is less risk to the Company, arguably, than a Bank loan. But their cash balances didn't seem to warrant a cash raise, though they seem to state that the extra £1m raised will help them improve /meet regulatory requirements, though of course those regulatory costs will be generally deductible from profits anyway.
I think we have to accept there is a fine balance here, but my amateur view is that participating Directors have done quite well out of this, as the Company seems to say it takes a positive view of prospects.
I imagine if they had the normal annual resolution to disapply the rights of shareholders to participate in share issues up to a certain %, this was an easy raise with the City boys, and mostly ordinary shareholders would not have had much of a sniff (unless someone corrects me).
I don't hold
Thanks Trident. Reassuring and a very useful second perspective.
Please can someone comment on this mornings RNS by PHOTO-ME LON:PHTM ? I have just started a new thread on this which contains further details.
Airea (LON:AIEA) Interim Report (I hold)
Mcap 11.4m sp 27.5p
The traditionally brief, to the point, no-nonsense, caution interim statement from this Yorkshire based carpet tile manufacturer now known as AIREA which some may remember as Sirdar. You might be forgiven for thinking that times are hard in Yorkshire, but at least its not trouble ‘t mill? Quite the reverse – these results are good progress and I might even venture reasons to be cheerful!
The ‘BRIEF’ feed that I see on my stocko portfolio made me smile as its one-liner on these results is ‘Airea says Co will not be proposing interim dividend at this time’. Maybe I’m wrong and perhaps there is trouble ‘t mill? But then a brief glance at the stock report dividend summary shows that Airea has rarely paid an interim dividend over the last decade – and has just returned to paying a final dividend. Maybe its the all pervading gloom that causes the financial media to seek out the most negative statement they can find? We’ll see.
Onto the figures.
Revenue 8.6m (7.4m) up 16% on prior year and up on the previous 6 months – which is good as there is some seasonality in their results.
Operating Profit 0.756m (0.574m) up 31% - but let’s not get carried away its still 25% below pre-pandemic levels – but under the circumstances with supply constraints, raw material, energy and labour cost increases that’s a good result and perhaps indicates some price setting ability.
Profit of 0.611m gives eps 1.58p (1.14p) up 38%
Net cash increased by 0.3m as operating cashflow of 0.717m also paid back 0.569m of the cbils loan.
To say the balance sheet is bullet-proof is probably understating it. Net cash of 2.5m is accompanied by a 4m investment property. The defined benefit pension scheme is in surplus but this is not accounted for as an asset as the company does not have an unconditional right to the surplus.
EV is £4.9m
It’s trading on EV of 4.7x previous year profits and EV of 4x current year profits based upon 2x the interim figure – which is conservative given continued growth and seasonality in Airea’s figures.
Reasons to be cheerful continued. During the pandemic the company has continued to invest in more efficient and productive plant (£1.2m) capable of producing the new products being launched – into the mid and premium ranges, rather than the cheap carpet tile market, and sell into the primarily commercial market. This is likely giving the company its ability to pass on the price increases – though I estimate that the operating margin has been compressed in the current results by around 15% - as freight costs subside, raw material and energy costs stabilise if not weaken I anticipate margin to be regained through current price increases and premium product launches.
With all value shares the question is always – how long will it remain a value share and is it a value trap? In this case I expect their investment in the business to generate growth and out the value in a two year medium term. Should be worth at least 2x and quite possibly a multi-bagger if they get these products right and the risk seems limited by the balance sheet. In the meantime like the chairman I cautiously expect a dividend to keep me alivem if not the style to which I am becoming accustomed.
Should the current gloom cause the sp to slip at all I shall be pleased to tuck away a few more,
Cheers
Mark
Airea - the inventory level seems very high here at £6.1m. In the FY 2021 accounts the cost of inventory passing through the P&L was £6.4m.
So they have nearly a year's worth of stock on the balance sheet. How does that compare to other floor covering sellers?
Shipoffrogs,
Airea (LON:AIEA) - Inventory is a good question. Thanks for bringing it up - it had been in the back of my mind. Yes it does seem high. I think you've may have put your finger on a risk that this tiny manufacturer runs. Or its another source of stored up profits. But I don't think there is a single answer.
Don't think its a year's worth ? Revenue is around £17m annually at current sales - likely £18m by year end. Though it depends upon how conservatively they've valued inventory.
Inventory of £6.132m is stable on the £6.150 of 6 months ago and up slightly on the £5.877m of 12 months ago. Looking at the inventory in note 14 of the last accounts over £1m is raw materials and the rest finished goods. The increase in inventory is probably more than accounted for by the increases in raw materials to counter supply delays and price rises?
Other than that it seems to be supported by the level of trade payables? Though I hasten to add I am not an expert.
I notice that there is also a figure for provisions in note 14 of £0.354m up from £0.144m last year.
But it still looks high? AIrea is probably not a just in time manufacturer? Which under current circumstances might actually be a good thing? Airea is a manufacturer rather than a distributor and often selling directly into commercial projects (hospitals, schools, offices) much less into retail (via distributors like Headlam). There is an argument for higher stock levels to support lumpy sales profile - and they have previously stated that they are building inventory for new product launches.
Another thought I had is that carpet tiles don't seem to go out of fashion at the same rate as clothes do? I suspect that they have to keep stock of old designs to allow for continual replacements around the coffee machines? In addition I think these new mega-looms only work efficiently if the production quantities are high enough - chopping and changing designs leads to more downtime and lower efficiency?
So I'm satisfied, but I accept that other might not be - there has to be a risk that despite the provisions its too much stock to carry?
Sorry for all the waffle,
cheers
Mark
PS - when Airea shut down their last loss making carpet factory the unwinding of the inventory led to a massive cashflow, profit, special dividend and share-buybacks. Not saying its the same here - but they do have form on managing inventories well.
Mark - comparing inventory with revenue won't give you the run rate, especially where there are high margins.
The cost of inventory sold last year was £6.4m (it is stated in the accounts), so they are holding stock nearly equivalent to the amount sold last year.
Airea (LON:AIEA)
inventory - Shipoffrogs,
apologies for not being clear - too much waffle. I did not mean to compare inventory directly with revenue - except as a guide to how much they might need to hold as stock against future orders.
Just to be clear - where are you getting the £6.4m of inventory sold in last years accounts?
I can't find it, probably just my ignorance,
must try to waffle less in future,
thanks
Mark
It's in the short narrative under the numbers in note 14 on Inventory (in last year's annual accounts):
"The consolidated income statement includes £6,384,000 (2020: £5,937,000) as an expense for inventories".
Airea (LON:AIEA)
Inventory - Shipoffrogs
"The consolidated income statement includes £6,384,000 (2020: £5,937,000) as an expense for inventories".
Ah thank you. I found that statement to be less than clear.
Going back to your original question 'So they have nearly a year's worth of stock on the balance sheet.'
No I don't think that they do.
Making carpet tiles, even for the premium market is not high margin. Admittedly I am not an expert but it seems very unlikely that £6,150m of stock at cost would generate anything like revenue of £15m? If that's what you mean?
Or looking at it another way - in 2021 they spent £6.849m on raw materials, adding on a high proportion of the labour and overheads for the cost of a years product gives something like £11m to £12m quite possibly higher.
So the £5m in note 14 as finished goods probably represents less than 6 months of output. Does seem high as I said, but then margins might be lower and there could be good reasons for holding stock - which makes my guesstimate less than accurate and holding less than 3months stock would probably be too risky?
Which means I am not clear what the reference in Note 14 means. But based upon my limited industrial experience I'd think it was the value of goods held in inventory that was taken out for sale during the year?
Hoping I've not managed to further confuse things, and apologises for all the waffle,
cheers
Mark
(LON:HOTC) Hotel Chocolat: I am yet to meet anyone who actually enjoys their chocolate. I think their chocolate tastes extremely sub-par vs. pretty much every other brand out there. A similar box of Thornton's is cheaper and tastes far superior. Perhaps the SP is finally reflecting the poor quality of it's product and if that is the case, there is a long way to go.
Its a 'story' stock. A fun interesting industry, usually means a poor investment. As Buffett says, invest in boring overlooked companies.
Airea (LON:AIEA) Decent interim figures this morning. Market cap a little over £11M. Very solid balance sheet (net cash £2.5M) plus freehold investment property valued at yield over 9% and nice to see a set of numbers not adjusted for plethora of items. Profitable and cash generative. Sadly CEO passed away earlier this year and yet to be replaced. I have held a number of years and one day hope patience will be rewarded.
CMC Markets (LON:CMCX) announces income in line with last year but a 5% increase in costs. Share price falls 19%.
Sigh.
timarr
That seems to be an over reaction. I was in 2 minds prior to the update, I didn’t think they would be doing too well in the current market but then why do a share buy back of £30 million prior to an update unless it was going to be positive. So I sold half on Tuesday.
Robert Walters (LON:RWA) posts half year results - a “record first half performance”
19% jump in profit and “Looking ahead, we are yet to see signs of any slowdown in job market activity”
Re Robert Walters (LON:RWA) promising results market not impressed if SP change is anything to go by.
Empresaria (LON:EMR) also issued a TU today. In line, and SP no change. Even now that they have come down to reality, they are off my list anyway.
Hi ridavies, Robert Walters (LON:RWA) share price has increased today by 2 or 3% - were you expecting greater? Or is it the low volumes?
I forgot to say: I hold.
I don't get some market reactions sometimes. Airtel Africa (LON:AAF) put out what I thought were good numbers today but the share price has plummeted.
As mentioned below, a good update from Headlam (LON:HEAD) given the current economic winds. No surprise regarding the anticipated weakness in the residential market. Headlam (LON:HEAD) is a financially sound and in my view a well managed company. The market mood is unforgiving at present but therein lies he opportunity.
Foxtons (LON:FOXT) interims appear somewhat underwhelming on first reading. I have a small holding. Will wait to see how the market reacts.
In addition to both of the above I hold Forterra (LON:FORT) and £ITV. Interims from Forterra (LON:FORT) read very well, with full year expected to slightly exceed current market expectations. Also having skim read the ITV (LON:ITV) interims I thought that they were positive with ITV Studios performing especially well, whether the market will think so is another matter. Given the share price one would think the company is on the brink of administration. In my view ITV (LON:ITV) Studios alone is worth more that the current market cap. One day it will have its day in the sun, as to when who knows. I certainly don't.
Paul/Graham any views on the above excluding ITV (LON:ITV) which is clearly not a small cap, greatly appreciated,
Keep up the great work..
All the best
Hi jonno,
Yes, I'll certainly be looking at Headlam (LON:HEAD) and Foxtons (LON:FOXT) today.
We've got a huge list of announcements to work through though, so will have to prioritise the more important ones. Here is our to do list as things stand now, just FYI -
Cheers Paul
To reiterate what others have said I really like the bite size overview of company announcements that you and Graham have introduced recently. Also the in depth commentary is excellent, where else would one get such insight into company accounts for the Stocko subscription price. I would also add a further plaudit for your weekly small cap summary which I enjoy listening to.
Flattery? No just well deserved recognition.
Well done to both of you and the Team at Stockopedia.
Best wishes
Re Trackwise Designs (LON:TWD) looking forward to Graham's comments. There is something good dangling out there, but I'm a lousy fisherman and have been burned on a number of occasions......but still, the bait put out there by the management outlook summary is very tasty!!!!
If Trackwise Designs had a little more headroom in their finances, I'd agree with you. However finances are so dependent on their largest customer coming through that a fund raise looks almost inevitable. Seeing all the provisos in today's accounts, makes this one uninvestable, IMHO. It might just be best for $Arrival to take them out, and reduce their liabilities on their balance sheet in the process. Such a shame, if only they had raised more money when they could have. But that's just true of so many companies of late.
While Trackwise may not make it, I think there's a lot of value in similar situations. I'm putting quite a bit of research into companies with upcoming results, in preparation that if the results are on the right side of solvent, some of the very beaten down prices can prove to be some real bargains. But it does really mean understanding the company's various skeletons before the accounts are published. Any ideas for upcoming results for the unloved due in the next few weeks?
Hello Jonno, Re Forterra (LON:FORT) yes and Ibstock (LON:IBST) yesterday the brickies have the market by the balls. Combined SP rise for the latter of around 11% in 2 days and close to best for the year. Just so long as they can keep the price rises up to the minute, to match the high rising energy costs, they should continue to do well. These two especially.
Michelmersh Brick Holdings (LON:MBH) and Marshalls (LON:MSLH) and Brickability (LON:BRCK) have shown less promising SP movements since the end of March at least when I added them to my Watch list.
I bought into MBH recently, I do believe that it is a sound company. I worried about the energy costs (I imagine that it is a significant proportion of production costs), from one of their presentations MBH do hedge this cost - but I wonder if the market wonders for how long.
Foxtons (LON:FOXT) (I hold)
Hi Jonno
I thought the results today were excellent.
Some thoughts, with a focus on Lettings + Sales (though I remain a fan of the financial services business too - it's small, but it is profitable.)
LETTINGS
Lettings revenue of £39.4m (+20% YOY) was excellent and if pre-2020 is anything to go by, then there will be a H2 weighting.
The increase was driven by a 32% year-on-year increase in Revenue/Let (£3,284 --> £4,330.)
I'm not entirely sure why there has been such a drastic increase, even in the current climate, as average weekly London rents have only increased 23% year-on-year (£412 --> £506.)
Foxton mentioned longer contracts, so maybe this is pulling forward future revenues?
On a similar note I just discovered this Foxton Lettings Reports today, in case anyone fancies a read:
https://www.foxtons.co.uk/pres...
SALES
Sales revenue looked "okay" though of note was the long backlog of transactions waiting to be completed. £19m of commission is apparently in the queue with a c.3months wait time.
For context H1 revenues were £20.8m.
Given the above backlog I am assuming the normal drop in revenues in Q4 won't happen this year.
PROFITABILITY
I prefer to look at Adjusted Operating Profit of Sales + Lettings combined given that central costs are allocated based on headcount.
Total Sales + Lettings Adj OP in H1 = £6.6m
This is nothing special by itself, but for H2 if one assumes:
then Adjusted Operating Profits in H2 alone could be as high as £20m.
That might seem farfetched, but I keep going over my numbers and I can't see what I'm missing. For clarity, all the H2 growth is coming from Lettings.
To add weight to the above projection, there appears to be real operational leverage here too as fixed costs have remained relatively stable for a while now.
The £0.9m increase in costs from NI, business rates, etc... was offset by £0.9m of savings. Annualised cost savings are £3.0m, so any further operating cost rises in H2 will hopefully be mitigated.
---
NEXT YEAR
Of course next year I am expecting operating profit to drop, but not by much.
The full year affect of acquisition will feed through and I imagine there will be more acquisitions on the way.
The company has been on a sales recruitment drive in H1 - which is how they explain the Sales Operating loss in the period (-£0.6m)- and they expect the benefits of this will come through over the following 12 months.
I'm also wondering whether there will be surprise interest income. There is £113m of client monies lying around and the Foxton T&C's confirm that all interest income is due to the company.
---
In conclusion the company is:
At the current valuation, the downside seems limited with a lot of upside if things progress as the company seems to imply they will.
Fingers crossed I haven't missed anything.
A
no numbers, but interesting announcement from Cambridge Cognition Holdings (LON:COG) this morning:
"Cambridge Cognition wins PTSD trials with top 10 pharmaceutical company
and the United States Department of Defense
Cambridge Cognition Holdings Plc (AIM: COG), which develops and markets digital solutions to assess brain health, is pleased to announce two agreements in a new therapeutic area for the Company, post-traumatic stress disorder ("PTSD"). Most recently, a research agreement was entered into with the with the United States Department of Defense, following on from a contract secured earlier this year with a top 10 pharmaceutical company. Approximately 20 PTSD treatment trials run every year1, demonstrating the potential for further sales in this therapeutic area."
https://www.investegate.co.uk/...
Unbound
Just read the RNS about the launch of the third party website .
Ive read it twice and unless I am totally stupid at no point does it actually give the website ?
When I owned an online business generally it is a good idea to tell your readers where to visit !
Maybe stock market RNS rules don’t allow this ?
I see they are still pedddling the 4.5 million customers claim which just goes to show what a total set of clowns they are .
The corporate BSspeak of these guys is off the scale. I noticed it on their website presentation and it was jarring for me. Someone needs to remind them that they are selling comfy shoes to old people...
Hello cheeky. 'Older people' please!
cheeeky by name.. sorry about that !
Unbound (LON:UBG)
Anyone buying their bargain basement offer of shares?? I nearly had a fit when it appeared on my broker account website - until I saw it was Zero amount!
"Just read the RNS about the launch of the third party website .
Ive read it twice and unless I am totally stupid at no point does it actually give the website ?"
I have an interest in this company but my current stake is of the same order that I would be prepared to risk on a 20:1 outsider at Aintree...
unbound.com or unbound.co.uk takes you to a crowdfunded book publisher.
unboundgroup.co.uk seems to be the live website. It does appear to work although the Modern Slavery and Gender Paygap statements are missing and the unboundgroup.com domain is still available to purchase, so I don't think they are taking this project as seriously as they should.
Unbound (LON:UBG) - also, if you try to email them.... their email link within the investor section of the corporate website pops up a personal email address. Typing the "correct" one in produces an undeliverable bounceback - as it does with the personal one.....
A complete shower......
I sold on Monday
unbound.com or unbound.co.uk takes you to a crowdfunded book publisher.
I know it is a little off topic but the crowdfunded book publisher is (disclaimer I hold and am a customer) rather good.
Give them ~£25 and some time later you get a hardback with your name in the back with all the other book's crowdfunders.
Good for presents if you are willing to wait (lead times are long). Got my dad "empire of booze" - a history of the british empire through the lens of drink with his name in it,
(recommend the book too)
Unbound (LON:UBG)
And having a quick google doesn't find it either..... Nor the article in Drapersonline - a rag trade website.
I sold my few shares on Monday - can't see any reason to invest in such a poorly run operation
Who on earth chose unboundgroup.co.uk as the website address?
Do they even have anyone with some marketing experience?
I managed to find the link by clicking through to a blog link at the bottom of the Hotter shoes page and scrolling all the way to the bottom of the blog.
I think it's fair to say that "high profile" isn't on their agenda. As someone else said, what a clown show.
Having said that, the website looks good, is fast and responsive. So not a complete washout....
Who on earth chose unboundgroup.co.uk as the website address?
Most likely because unbound.co* was/were taken?
Right, but unbound group? has all the charisma of a mouldy banana.
I'm no marketeer but surely liveunbound or anunboundlife or something would be more memorable / tell a story.
Ince "delivers legal advice, strategic guidance and business solutions to clients". [SP=12 Cap=12m]
Mr C,
“wince at INCE shareholder rinse” - you are a master of the one liner, and regularly make me laugh. Thank you.
Ricardow
SRT Marine Systems (LON:SRT) Don’t drive! That jam has been in the cupboard for so long it will be 50% proof.
I am still new to this game and I did Google this but it blew my little mind. In simple terms what is a block listing return, and is it considered good or bad for current investors?
Polarean Imaging (LON:POLX)
Block listing example
In simple terms what is a block listing return, and is it considered good or bad for current investors?
It's a very boring administrative procedure that allows companies to issue small amounts of shares, usually for share option schemes, without going through an incredibly complex regulatory process.
I've never known one of these be of any interest whatsoever.
timarr
Thanks for clearing that up. I see lots of these and I have always wondered.
Headlam (LON:HEAD) Trading update.
"Total revenue was £323.8 million (H1 2021: £329.9 million), with a 5.1% uplift in Continental Europe (France and The Netherlands) helping to offset a 2.9% decline in the UK related to weakness in the residential sector. Manufacturer-led price increases helped offset operational cost inflation during the Period. This, and the Company's continued focus on operational efficiency and cost control, led to an improved underlying profit before tax performance of £17.3 million (H1 2021: £16.7 million).
While residential sector revenue declined 5.0% in the Period, the commercial sector increased 4.9% as it showed recovery from mainly COVID-19 related issues in the prior two years, with the ongoing summer months being an important trading period."
Very solid update in the circumstances from Headlam (LON:HEAD) Also very strong asset backing with a small net cash position and "£148.1 million of
inventory and a £109.5 million nationwide freehold property portfolio"