Small Cap Value Report (Thu 29 Oct 2020) - HRN, FOXT, BEG, PHD, CTG, REDD

Good morning, it’s Paul and Jack here with the SCVR for Thursday.
Please bear with us this week, as we’re experimenting with new ideas for how to seamlessly contribute sections into the same article. Yesterday seemed to work out well. I enjoyed having a good rummage into the weird put options at M&c Saatchi (LON:SAA) which turned up a potentially nasty dilution situation. So be careful with that one. If anything looks odd, in the accounts, it really does need to be properly checked out.
Timings - Jack did an early section, many thanks for that. Now I'll be producing the usual 4 or 5 sections throughout the day. Likely to be finished late afternoon, as some of these sections take a long time to dig into, and write up! Let's aim for 4pm finish. Update at 16:26 - the main sections are now done, but I'll do a bit more to look at one or two more companies. Extended finish time now 6:30pm. Today's report is now finished.
Agenda - these results/trading updates have caught my eye;
Foxtons (LON:FOXT) - Trading statement
Begbies Traynor (LON:BEG) - Red Flag Report
Proactis Holdings (LON:PHD) - Final results
Christie (LON:CTG) - Interim results
Redde Northgate (LON:REDD) - from yesterday, several people have asked if I’d look at it
.
** This first section contributed by Jack Brumby **
Hornby (LON:HRN)
Share price: 37.4p
Shares in issue: 166,927,838
Market cap: £62.4m
(Jack writing)
This developer, producer, and supplier of hobby products probably has some goodwill with certain investors who have used Airfix and the rest before.
Long-suffering shareholders might be less fond of the company as a listed entity, however.

It’s a potentially interesting case here.
What some once assumed to be the likely fate of Games Workshop (LON:GAW) has happened at Hornby: from 2015, Hornby (LON:HRN) has reported declining financial results due to a sustained fall in collecting customers and the rise of video gaming.
A brief summary of recent trading:
Shares dropped by more than 50% in a year in 2015/16 and Hornby announced it would cut more than half its less profitable toy ranges. In the year to 31 March 2017, revenues fell further to £47.4m from £55.8m, while underlying losses widened to -£6.3m from -£5.7m.
In July 2017, its largest shareholder Phoenix Asset Management (PAM) bought 17.6m shares for 32.375p for a 55.2% holding. This triggered a mandatory takeover offer of valuing Hornby at £27.4m and led to the resignation of Chairman and CEO later that year.
PAM then brought in a new management team to oversee the turnaround. Since then, the shares have been stubbornly range-bound despite (presumably) ongoing operational progress.
PAM picks up some interesting companies. Another one that comes to mind is Stanley Gibbons (LON:SGI) , the antiques and coins dealer.
Neither share price has come good as of yet, but PAM is a dedicated deep value investor so I do keep checking in on progress. Today Hornby releases its interim results.
Highlights:
- Group revenue +33% to £21.1m,
- Operating PBT has swung from a loss of £2.5m to £0.2m,
- The group has gone from net debt of £8.4m to net cash of £4m
The soundbite from Lyndon Davies, CEO, runs:
Hornby has moved into profitability, the growing sales and margins built on the back of the introduction of some fantastic new products, new technology and the changing environment.
And, later on,
...we have not only weathered this shattering storm [the pandemic], our sales have increased by 33% in the first half of 2020 (compared to prior year), moving Hornby back into profitability. The growth built on the back of the introduction of some fantastic new products, new technology and the changing environment. And this was in the 'quieter' half of the year; traditionally 55%-60% of our sales fall into the second half.
This sounds surprisingly upbeat and the headline figures look really positive.
The statement also reads like quite an engaging and characterful update.
Turnarounds rarely turnaround, and the ones that do often take longer than expected. This is proving to be the case here but the company has now registered a small profit, which could be an important psychological milestone.
What’s important here is the strategy, and this is ticking some boxes particularly with a planned migration to online:
No-one could have foreseen the acceleration in online shopping that took place this year. We want to engage more with our existing customers and to recruit new ones, and we all know that retail will never be the same again. We need to create 'Community' and have more direct engagement, where customers come to us to learn about our products... over time each of the brands will develop their own identity and will move in the direction that best suits their needs. As we move forward our website will feature rich content with images and videos generated by ourselves and our customers, a place where we can interact.... Foremost in my mind is 'Community'.
If Hornby really can accomplish this and use its brands and IP to create an engaged and loyal online community, then there might be life in the old dog yet.
Directors have been buyers over the past couple of years, which is encouraging.
Conclusion
Hornby has net cash and solid liquidity scores. There are no huge flags in its balance sheet but the group continues to bleed cash on the cash flow statement. It looks like it has had to go, cap in hand, to shareholders fairly consistently to fund its turnaround.

The group has many years of losses so the track record is pretty dire - but no brokers are following it, so if the group really is turning around then that could present a substantial opportunity for retail investors.

The shares are very illiquid though, so you’d have to do your research and be sure of your convictions before building a stake as I imagine it’s very easy to get trapped here if trading heads south.
The two figures below suggest a buy or sell of around £4k but this could easily change if everybody starts buying or selling at the same time.

In all though, this is an interesting case and probably worth following in more detail. Timing could be key - if you’re too early then you’re just another long-suffering shareholder funding a turnaround that is - surprise, surprise - taking longer than expected.
The risks are pretty clear but there are some promising signs that Hornby is approaching some sort of inflection point. ‘The boy who cried wolf’ and all that, but the stocks that get it right can observe a dramatic and material rerating.
So on that basis, it’s probably worth further investigation.
.
Foxtons (LON:FOXT)
Share price: 32.3p (down 6% today, at 10:04)
No. shares: 275.0m
Market cap: £88.8m
(I do not currently hold)
Disclosure: I previously had some FOXT in my spread betting account, but had a margin call earlier this week, so had to cull one or two lower conviction holdings, including this one. Therefore I do not currently hold any position in Foxtons. At some stage I'll probably buy back in, when funds permit, as I continue to like this share for its recovery potential.
Foxtons Group plc (LSE: FOXT), London's leading estate agency, today issues its trading update for the third quarter ended 30 September 2020.
It looks as if there’s been a strong bounce-back in Q3 (July-Sept 2020), after the lockdown period ended;
Business activity significantly increased in the third quarter with valuations, instructions, applicant numbers and viewings all considerably up on last year across both Lettings and Sales. The business returned to full capacity by the end of September, with no use of the Coronavirus Job Retention Scheme (CJRS) in October.
That’s encouraging, although of course with the sales department, it takes time to rebuild the pipeline of transactions. Therefore actual revenues are down on last year;
Group revenue for the period was £28.5m, down 10% on the prior year (Q3 2019: £31.7m1), and over the first nine months of the year was £68.9m, down 18% on the prior year (2019: £83.5m1).
Lettings department - this is quite interesting;
Revenue for the third quarter was down 8% to £19.5m (Q3 2019: £21.3m). Whilst volumes in the London lettings market over the summer months returned to close to pre-pandemic levels, average revenue per tenancy was lower due to fewer high value short-term lets and a significant reduction in the number of overseas student tenants and corporate relocations.
I’ve heard that rents are coming down in London, often quite substantially, due to some people relocating to the countryside, given that working from home has become so much more prevalent, and could be semi-permanent in future, who knows?
Sales department - encouraging signs here;
Revenue for the quarter was £6.9m, down 18% (Q3 2019: £8.4m) due to depressed levels of exchanges, a hangover from the spring lockdown. However, sales activity, including the number of instructions and number of offers accepted, has been significantly higher than the same period last year, driven by pent-up demand post lockdown and Stamp Duty relief. This started to convert into revenues in September, which were up 9% on prior year.
At the end of the quarter, the sales commission pipeline, based on the value of properties 'under offer', was up around 30% on the same time last year. However, as has been widely publicised, transactions are taking longer to move through to exchange and the economic uncertainty is also driving higher than normal transaction fall-through rates.
That’s a bit mixed. I’ve heard that there are bottlenecks with local authority searches, causing long delays. This is apparently causing some buyers to pull out, if they don’t think they can complete by the end of the reduced Stamp Duty period. Sounds like Chancellor Rishi Sunak needs to extend the Stamp Duty discount - or make it permanent even. My perception is that he seems to do the right thing, but only at the last minute, after a public outcry, and when some damage has already been done. Let’s get those letters rolling into our MPs!
Liquidity is excellent. Remember Foxtons did a placing earlier this year, to eliminate its bank debt, so it’s in a comfortable position;
At the end of the period, the Group's cash balance was £43.2m, benefitting from VAT deferral of £3.5m and lease deferrals of £3.2m, part of which will be repaid in the remainder of the financial year. The Group has no external borrowings.
I’ve just had a quick look at the last reported balance sheet, and it’s fine overall. There’s a lot of goodwill/intangibles, and a large deferred taxation creditor (which might relate to intangibles, I’m not sure, I tend to just ignore deferred tax).
Outlook comments - here are the key points;
We have successfully re-built the sales commission pipeline to its highest level in 3 years, delivered a resilient lettings performance and progressed our lettings book acquisition strategy.
Although the London residential market has gained momentum, we remain cautious as economic uncertainty causes more sales transactions to fall through and is putting downward pressure on rents.
My opinion - I like this share, for a future recovery, and it’s resilient enough to survive. Lease liabilities are quite high. The problem is that reduced Stamp Duty is the key driver for the London property sales market, and that could be withdrawn fairly soon. Hence the risk is that Foxtons could face a bleak 2021. We do have a highly interventionist Government though, so there is probably a decent chance that Stamp Duty reductions may be extended. It would be worth doing some googling on that.
The shares are hitting new lows, which seems at odds with a relatively perky Q3 update today. Hence a cautious thumbs up from me, for the long term recovery potential. Although I don’t know how the shorter term outlook will pan out.
.
Begbies Traynor (LON:BEG)
Given the circumstances, I’m actually quite surprised these figures are not far worse;

.
Clearly Govt support measures, unprecedented in their scale, are keeping many businesses afloat which might otherwise have failed.
Although this is ominous, and suggests the underlying picture is a lot worse than the figures suggest;
... backlog of court action preventing many CCJs and winding up petitions being issued…. The rise could have been much higher, were it not for reduced court activity due to the coronavirus pandemic, which has limited the number of CCJs and winding up petitions being issued against indebted companies and the ban on winding up petitions for Covid related debts.
Data shows there were 26,244 CCJs lodged against companies during July, August and September in 2019, with only 10,045 lodged during the same period in 2020, a fall of 62%. The situation is even more acute with regard to more serious winding up petitions. During July, August and September 2019, 1,019 were lodged compared to 101 during the same period in 2020, a fall of 90%.
With so many businesses limping along there could be a flood of insolvencies when the courts do get back to anywhere near normal capacity and attempt to clear the backlog of pending cases. This in itself, combined with the end of the furlough scheme and other government support measures, is likely to have a material impact on the UK business failure rate.
There’s more of the same in the rest of the report. It paints a very gloomy picture, which won’t be a surprise to any of us.
My opinion - what I’m seeing almost every day, when writing these reports, is that most companies do seem to be recovering. Generally speaking most UK listed small caps seem to be surviving, and recovering, and not under insolvency pressure. Therefore I feel the Begbies report paints a rather skewed picture, it’s important to remember that Begbies focus just on companies in financial trouble, not the economy as a whole. Hence it might be overly gloomy.
I think we’re likely to see continuing forms of Govt support. Maybe not on the huge scale of the schemes launched in the spring/summer, but it wouldn’t make sense for the Govt to switch off the taps, and stand back whilst large numbers of companies go bust.
Casting my mind back to the 2008/p financial crisis, I recall that a huge wave of insolvencies was predicted then too, but actual insolvencies were far less than expected. This was because interest rates were cut to near-zero, which meant that banks were often prepared to be lenient with problem borrowers, since the cost of keeping borrowings static was so low. As long as borrowers could pay the modest interest charges, then it made sense for the bank to wait for better times, rather than foreclose and sell off assets in a fire sale. Many "zombie" companies survived against the odds, and did manage to gradually reduce debts in subsequent years.
Whereas in the 1990-93 economic downturn, interest rates were sky high, causing banks to be brutal in forcing many businesses into unnecessary insolvencies. I worked for PWC at the time, in a junior role in the insolvency department, and I saw many businesses destroyed which would have survived, if interest rates had been low. The banks got often very poor recoveries on their debts by using expensive insolvency procedures, and I think they learned from that, and have been very reluctant to pull the plug on companies unless they're complete basket cases.
Overall then, I’m not convinced the outlook is necessarily quite as gloomy as Begbies suggests. Although it very much depends on what support measures the Govt implements. Time will tell.
.
Proactis Holdings (LON:PHD)
Share price: 31.8p (down 1% today, at 14:00)
No. shares: 95.5m
Market cap: £30.4m
Proactis Holdings PLC, the business spend management solution provider, today announces its audited results for the financial year ended 31 July 2020.
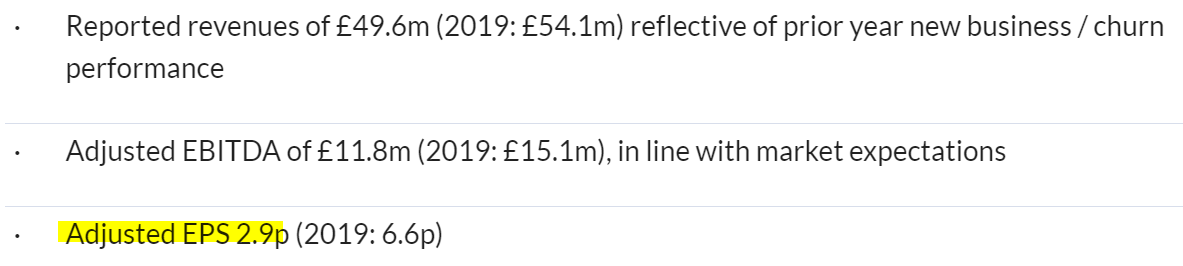
The company highlights positive KPIs, but the key results figures are poor. This included the covid/lockdown period, but software companies should have done better than most, due to having recurring revenues. So I’m not impressed with these numbers. In particular, the 56% drop in adj EPS;
.
It’s a £19.3m loss before tax at the statutory level, which includes a large £14.8m impairment of intangibles, and £10.7m regular charge for amortisation of intangibles.
Note that the impairment charge is not a one-off, there was an even bigger £27m charge last year. People say, oh it’s non-cash, but I challenge that. This was money that had previously been paid out for supposedly valuable acquisitions, which have now turned out to be not so valuable. So it’s still cash down the drain, just old cash, not new cash!
Debt - is much too high, in my view;
Net bank debt of £37.1m (31 January 2020: £35.6m) | |
· | Reset banking facilities with HSBC in order to support the Group's current business plan for the mid-term |
Outlook comments sounds quite upbeat overall, mixed with caution about the macro/covid situation, which is fairly standard stuff that most companies are saying.
Despite these challenging market conditions, we are prudently managing our costs such that the Board continues to expect to meet our earnings forecast for FY21.
[Paul: what are management's earnings forecasts? We're not told!]
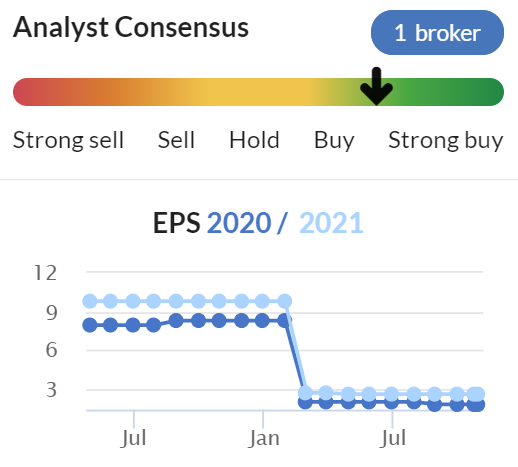
Brokers consensus (if these are up-to-date, guidance might have been withdrawn?) shows little improvement for the new financial year;
Notwithstanding this, the Group's new business performance is encouraging and combined with our return to organic growth in underlying ARR are material indicators of our progress.
Our business has proved to be robust through this extraordinary period and our pipeline and forward revenue visibility positions us well for the future. We're in an exciting growth market and are poised to accelerate our growth, earnings and cash flow over the coming years."
Balance sheet - looks awful to me. This is definitely a deal-breaker, and to me, it makes this share uninvestable.
NAV is £51.8m, but this includes £118.8m intangible assets, so NTAV is heavily negative, at £(67.0)m. It needs a big placing to fix that, which would involve heavy dilution for existing holders.
See note 6 - the £118.8m intangibles mainly relates to premiums over NAV paid for acquisitions. Hence it’s not really worth anything. Only about £20.0m relates to previous development spend, and software for own use, which I would argue are the only intangibles that justify a place on the balance sheet. An identical imaginary company that had grown solely organically, would not have £98.8m intangibles on the balance sheet, therefore why do we consider that this is an asset for Proactis?
Cashflow statement - again very revealing. This shows net cashflow of £8.0m. However, further down, £8.5m of development spending has been capitalised. Therefore, the company is not actually cash generative at all! This demonstrates what nonsense EBITDA is at software companies, as I frequently point out.
My opinion - this looks a precarious situation to me - way too much debt, and no genuine cash generation. That doesn’t usually end well. The company needs to drastically improve performance, and make a serious dent in the bank debt, before I would consider this share to be investable. As it stands, I think this needs a high risk warning to existing, or potential investors.
Also note that there were no takers when the company put itself up for sale.
The way I look at things, the equity probably has little to no value as things stand. You may disagree, but I’ve set out above the reasons that brought me to that conclusion.
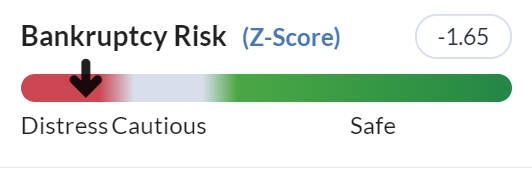
Altman Z-score confirms financial weakness;
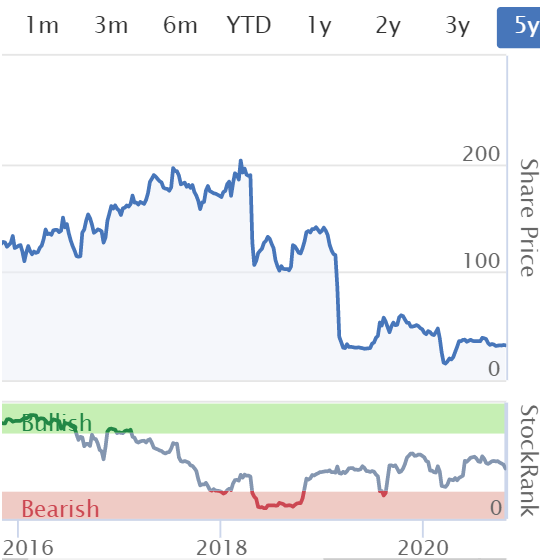
Poor 5-year track record, as you can see below;
.
Christie (LON:CTG)
Share price: 71p (down 11% today, at 15:32)
No. shares: 26.5m
Market cap: £18.8m
Christie Group plc ('Christie Group' or the 'Group'), the leading provider of Professional & Financial Services and Stock & Inventory Systems & Services to the hospitality, leisure, healthcare, medical, childcare & education and retail sectors, is pleased to announce its interim results for the six months ended 30 June 2020.
Clearly the company will have been hit hard by covid/lockdown over this period. These figures are ugly;
· Revenues amounted to £18.8m (H1 2019: £38.1m)
· Operating loss of £5.5m (H1 2019: £1.5m profit)
· Prudently foregone an interim dividend this year (H1 2019: 1.25p per share)
Liquidity looks good though;
· Strong cash balance at 30 June 2020 of £13.4m
Outlook sounds more encouraging for H2;
...all businesses have resumed to the extent now possible. Our third quarter trading has been encouraging and, if it continues, should lead to a much improved second half."
Balance sheet - a loss on the P&L has a knock on effect in reducing net assets. In this case, NAV has fallen to negative £(8.8)m at 30 June 2020, from only £(0.3)m 6 months earlier. Why such a large drop? The pension deficit has grown from £12.0m to £16.7m in the last 6 months - that’s not far off the market cap of the whole company, of £18.8m, so the pension deficit is a major issue here.
I’ve checked the 2019 Annual Report, and discovered that the pension deficit recovery payments are £1.47m p.a. That’s about a third of the typical £4m profit which the company makes in an average year. Hence it’s something that needs to be adjusted for, when valuing the shares - i.e. this share should probably be on a low PER, to take into account the reality that a lot of its cashflow is being sucked out into the pension scheme, hence not available to pay divis. That’s a long-term problem, made worse by low interest rates.
Also the heavy trading loss in H1 has dented the balance sheet further.
Take off the £3.0m in intangible assets, and NTAV looks weak at £(11.8)m. However, if we strip out the pension deficit, a manageable long-term liability, then the rest of the balance sheet looks OK.
The cash pile of £13.4m is a bit of a mirage though. That’s because lower trading means receivables have unwound, boosting cash generation in the short term. As business recovers, then receivables rise again, and the cash pile will reduce. Therefore I would regard the unusually high cash figure as a temporary aberration, so not something to use for valuation purposes. Enterprise value is a particularly dangerous concept at the moment, when companies are hoarding cash, and squeezing cash out of their working capital in the short term.
My opinion - pretty awful H1 figures, due to covid/lockdown, so not the company's fault, but it’s now recovering in H2.
Of all the shares on the London market, I don’t really know why anyone would choose this one. It’s an OK business, that makes about £3-4m profit in a good year, and pays reasonable divis. But there’s not really any growth, it’s cyclical, and obviously is operating in a difficult sector at the moment.
The broker forecast figures are old, pre-covid ones, so ignore those.
Once everything has returned to normal, in maybe late 2021, or 2022, then I could see earnings returning to c.10p. The share price could recover to say 100p, but is that interesting enough to make me want to invest now? Not really, and divis have been cut too, so there’s no income whilst waiting for the share price to recover.
Overall, it looks OK, but with little prospect of growth, and an expensive pension deficit to service, I can’t see much attraction to buying the shares now. It’s probably priced about right.
.

.
Redde Northgate (LON:REDD)
Share price: 178p
No. shares: 246.1m
Market cap: £438.1m
This was released yesterday, but I ran out of time, so am circling back to it today, as several readers said it looks interesting, and I have to agree!
The group calls itself a “leading integrated mobility solutions platform”!
I prefer to describe it as a merger of Redde (which provided rental cars for no fault accidents, to insurance companies), and Northgate, a company that hires out vans.
The merger only happened in early 2020, so we don’t yet have any full year results to go by. I suppose you could go back and manually combine the two companies’ results prior to the merger. Or use broker forecasts, if they are available and accurate. Obviously covid/lockdown is muddying the waters considerably, as with everything.
The market didn’t like yesterday’s update, and the share price has fallen about 10% in the last 2 days.
This is what it said yesterday;
In the first five months of FY2021 the Group has seen sequential monthly improvements in trading, with a recovery in VOH to slightly above pre-COVID levels, strong used vehicle prices and disposal profits, but slower recovery than expected in Redde volumes due to several factors including local and regional lockdowns.
Absent a deeper or more prolonged impact of COVID-19 than currently expected, the Board is comfortable with the consensus of FY2021 analyst forecasts that have been updated since April 2020.
A footnote would have been helpful to specify what earnings forecasts are. But it's really useful guidance, as I can value the share with this information. See the brokers consensus graph below, the FY 04/2021 EPS figure is 27.34p (the darker blue line)
.

.
A share price of 178p, divided by 27.34p EPS forecast, gives us a current year PER of 6.5 - which looks very cheap. There must be something wrong then. If there is, I’ve not found it!
Usually shares this cheap on a PER basis have poor prospects, are in structural decline, and/or have weak balance sheets, often with big pension deficits. I can’t find any such problems with REDD, but do please bear in mind this is the first time I’ve looked at this merged group, so I might have missed something. Let me know if I have please.
Dividends - are being maintained, and are large (Redde was a high yielding share when it was a standalone company);
Shareholders are being asked today to approve a final dividend of 6.8 pence per share, which will be paid on 3 November 2020, to those shareholders on the register at close of business on 25 September 2020. This dividend, if approved, will result in a total ordinary dividend payable in respect of the year ended 30 April 2020 of 13.1 pence per share.
To be maintaining a big divi during current conditions, says a lot about the strength of the business, in my view. So this gets a big thumbs up from me.
13.1p divis, divided by 178p share price, is a yield of 7.4% - that’s very attractive for income seekers, if it can be maintained.
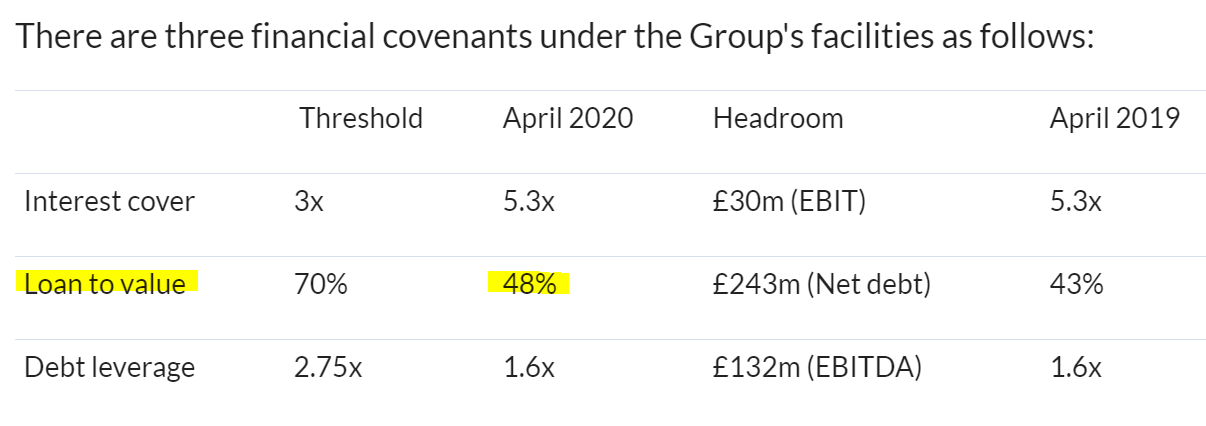
Balance sheet - I’ve reviewed the preliminary results for FY 04/2020, which are post-merger, hence the balance sheet is reliable as being for the merged group. Overall, I’m happy with the figures. As you would expect from a vehicle hire business, the vehicle fleet results in very large fixed assets at the top, financed by long-term borrowings at the bottom. I won’t go into all the detail now, but to my eyes it looks fine. Debt is manageable, and there’s good transparency about debt covenants, with good headroom, and the debt is very cheap too, costing around 2.0-2.5% p.a.
I like the capital banking, with a loan to value of only 48%, i.e. the vehicles are roughly half owned by REDD, with debt funding the rest, a comfortable position;
.
What’s interesting, is that the commentary says that the company is moving towards financing vehicle purchases in future on contract leases. This would remove some or all of the need for bank debt, thus making the group far more secure. It would simply sit between the manufacturers and the end user, matching monthly cash income with cash outflows, and making a similar profit margin as if it owned the vehicles. That appeals to me a lot, as it de-risks the business (not that risk is high anyway).
Negatives - obviously it’s not all rosy. Profits at Redde (the accident management business) have been hit by reduced journeys travelled, although that’s improving with more journeys now occurring, which sounds ghoulish to be seeing more profits from other people’s misfortune having accidents, but that’s life.
Further covid lockdowns, could cause some damage, and the current second wave that’s engulfing the UK and Spain, being the countries REDD operates in (Spain is very profitable, incidentally, at about 17% profit margin, vs c.10% in the UK). Yet I think white vans would still be in strong demand, given the upsurge in internet shopping, and need for a multitude of delivery drivers, who need vans.
If economies go into recession, then that could lead to bad debts, and abandoned vehicles maybe? Plus potentially lower resale values. Although there's no sign of that at the moment.
The other threat to the original Redde business, is insurance companies shopping around, and moving their business to cheaper competitors. I recall that was an issue a while back, with some uncertainty over large contract renewals.
My opinion - thanks to the readers who nagged me to look at this, I think it looks an excellent investment proposition - a very low PER of 6.5, based on confirmed forecasts for this year. A decent balance sheet, debt that looks fine, a lovely dividend yield which is being maintained - this strikes me as exactly the type of thing I like to invest in. So when funds permit, I’ll probably be picking up some stock myself.
I’m just a bit worried that it looks too good to be true. Have I missed anything? I’m worried that might be possible. Therefore if you think I’m too bullish on this, please post negative comments for balance!
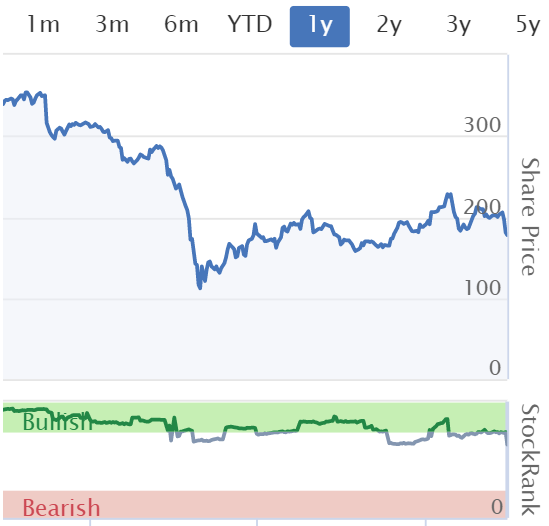
Why is the share price continuing to fall? If it’s such good value, surely buyers would have overwhelmed sellers by now?
Stockopedia likes it too, note the high StockRank below.
.
.
All done for today!
Best wishes, Paul & Jack.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
hi Paul
Redde Northgate (LON:REDD) is also a holding of mine. It is worth noting that second hand values are actually increasing so this is likely to have a positive overall effect on earnings. As you say it has decent cash generation, good dividends and much room to grow. Analysts expect 36p of earnings next year which puts it on a PE of 5.
However, during this year they have achieved £14m of annualised run rate savings with a bit more to come. This upcoming year should be when they see those realised (note : the cost reductions were put in place between merger in Feb and August y/e so there is probably only 3 months worth in this years numbers ). Therefore I can see £10m+ dropping straight to bottom line that wasn't there in this years 30.8p eps on underlying earnings. Thus I think the business only has to stand still this coming year to achieve the 36p eps on analysts radar and as a consequence I can see upgrades on the horizon.
Further lockdowns could clearly have an impact but this years numbers include the whole Mar-July initial shutdown. In my view any subsequent lockdowns will be shorter and less onerous in nature but more importantly are now less of a shock to people and businesses, so in theory at least, should be a little less disruptive.
All in all I can see this years eps expectation of 36p as being comfortable, even given the current environment, and there is strong free cash generation so don't forsee too much risk to dividends. But on the other side of the Covid crisis I can also see strong growth.
best
David
A bit of nostalgia there with Redde Northgate - I learned to drive on that industrial estate in Darlington 40 odd years back, cant believe they are worth half a billion now. Just across the road is the remains of the old MFI - now Howdens Joinery.
Shall take another look - thanks Paul
many thanks for your review of Redde Northgate Paul. This is my second largest holding after Boohoo,and I intend to keep onto both for a few years
again, completely disagree with adding a ticker on replies to OP's. I don't believe in clutter. People should use 'threaded' & 'latest' filters. Who jumps into a book at page 10 for example? I also hate clutter and a ticker on every post is silly. Stocko should simply add a hyperlink on the linked thread posts and if people are curious or want to know more about that conversation then click it. Otherwise ignore it and jog on.
Great work chaps. Thank you.
A suggestion for the powers that be. How about adding a box at the top of the Comment Now box - in which to put the ticker of the relevant share? That would then appear when you submit your post, so that the top line could show "in reply to post #xxxxxxxx re "name of share".
If you are replying to a previous comment then the box could be automatically filled with the ticker from the post you are replying to. Can't be impossible, surely.
If your comment is just a general comment on the market for instance then you could enter a simple symbol (an asterisk, for example).
Gfinity (LON:GFIN) final results today look like BIG decline in revenues and huge losses much bigger than current CASH but under the bonnet there is a much different picture.
i have calculated back from last year results and this year H1 results.
the new CEO (Mar 2020 cut the run rate of costs by 65%) and they have stated regularly before about reaching profitability for Q1 2021. so my calcs for Q1 2021:
t/o = 1.8m
GP = 1.1m
admin costs = 1.0m
profit = 0.1m
so this means that turnover is possibly growing from
< 0.5m in mar to june (albeit in heavy lockdown)
to 1.8m between jan and mar 2021
i.e. huge growth rates
and using Q1 2021 turnover rates implies annual turnover (run rate) of 7m
so at the current 4p giving MV of 32m the valuation is 4.5 times
but obviously this is reducing rapidly as the growth rates kick in
they have 1.6m of net CASH, and warrants that will give a further 2m CASH.
given the valuation of comparable companies seems to support the rising chart to me, and of course like many others they have enough CASH and will be profitable soon.
the key for me is that > 3.8p seems a very clear chart break out confirming a chart bottom after years of company poor performance from the previous management .
disc: GFIN is in my portfolio. i am low risk investor
When I look at Begbies Traynor (LON:BEG) and Frp Advisory (LON:FRP) I think there was anticipation of a blood bath in the SME - Mid Market space. Their close relationships with lenders would see a string of insolvencies where they could make good money.
The government support and the supportive attitude of the banks has meant this has not happened.
It is a question of whether casualties have been avoided through this support or whether the can has merely been kicked down the road.
Q1 - Q2 2021 will be key. HMRC arrears will need repaying, rants will be due, staff support will be withdrawn. The perfect storm could impact on many SME's cash flow.
The comments seem to sliding here again with many not including a company name or code. Please do include this in any comment
Thank you
As penance for this slightly critical note I would like to bring up Orchard Funding (LON:ORCH) which reported last week and for which a favourable report by Liberia has been published ( house brokers so not by any means unbiased).
The on again/off again banking license and poor growth justify the disappointing share performance but the upside from here would appear to be relatively straight forward. The business is simple ( short term lending for insurance premiums and professional fees ). Bad debts are minimal and the cost base - excepting the Chairman (and main shareholder ) remuneration - seems very manageable.
I hold, with regrets for past performance but if I can avoid looking back it appears to have promise.
One can switch back and forth from the new site to the old quickly and easily. If you're experiencing difficulties following the thread, instead of expecting everyone else to meet your exacting requirements, you could be the one to go the extra 10cm and use the new site for the report then flick back to the old for the stockreports etc. :)
Lots of newer members can't access the old site. Older members still can but it takes about 1 minute as it's slow. I use the old site, I find it much easier to follow the SCVR comments.
Is there an issue on the new site with £share, many don't seem to producing the link.
The format is £SHARE in caps with no special characters in the string. For example £SHARE. wouldn’t work.
Test iPad, Safari Boohoo (LON:BOO)
That's just not so! Subscribers after, I believe, c. Jan 2020 have no 'old site' accessible. Anywhere.
So please, girls and guys, have the courtesy to say what you're banging on about!
For those who are confused by this the comments on the old site are in time order oldest first.
On the new site you have 6 choices - combinations of oldest first/newest first/most popular and threaded/unthreaded so anyone chosing oldest first with unthreaded on the new site has the same experience as those on the old site in not knowing what share some people are talking about.
Comments have suggested that it is on mobiles that there is difficulty with the £ sign but if it just comes across as "£foxt" at least we know what you are talking about.
I think the irritation that began this came from people ignoring Paul's very clear plea at the top of Tuesday's SCVR:
Good morning, it's Paul here with the SCVR for Tuesday.
Reader comments - can I echo a repeated request here from other readers. If you're going to comment on any company, please include the ticker, or company name, in every post. Otherwise some readers won't know which company you're talking about, hence your comment is pointless to many readers. It depends which version of the site & comments layout people are using.
It's all a bit rubbish in my view to give users half a dozen different ways of viewing comments and then expecting us to format our comments for people using one of the other five methods. But yes being a polite chap I do try to remember.
Exactly, it’s unreasonable to expect everyone else to take an action because one person doesn’t want to thread the posts. Tail trying to wag the dog.
"Exactly, it’s unreasonable to expect everyone else to take an action because one person doesn’t want to thread the posts. Tail trying to wag the dog."
Or, looking at it another way - if you take the trouble to post something do you want to make it as easy as possible for someone to know what it is you're talking about?
God knows how you guys cope with Reddit.
When you use unthreaded, it even gives you a click saying “one reply” or “two replies”.
As I have hopefully just demonstrated.
oh look, in unthreaded I can see I have three replies.
Guess this one makes it four.
Right, but it’s only the old site that had the issue.
If you’re using the new site the comments can be threaded.
Not a problem on the old site it was clear who he was replying to and what the share was.
Surprisingly positive (or less worse than expected) update from Malvern International (LON:MLVN) today. Interesting prospect given the potential increase in online education in a covid world.
thoughts on Foxtons (LON:FOXT) this morning gentlemen?
Trading statement:
https://www.foxtonsgroup.co.uk...
Business activity significantly increased in the third quarter with valuations, instructions, applicant numbers and viewings all considerably up on last year across both Lettings and Sales. The business returned to full capacity by the end of September, with no use of the Coronavirus Job Retention Scheme (CJRS) in October.
Lettings:
Revenue for the third quarter was down 8% to £19.5m (Q3 2019: £21.3m). Whilst volumes in the London lettings market over the summer months returned to close to pre-pandemic levels, average revenue per tenancy was lower due to fewer high value short-term lets and a significant reduction in the number of overseas student tenants and corporate relocations.
Sales:
Revenue for the quarter was £6.9m, down 18% (Q3 2019: £8.4m) due to depressed levels of exchanges, a hangover from the spring lockdown. However, sales activity, including the number of instructions and number of offers accepted, has been significantly higher than the same period last year, driven by pent-up demand post lockdown and Stamp Duty relief. This started to convert into revenues in September, which were up 9% on prior year.
Balance sheet:
cash balance was £43.2m, benefitting from VAT deferral of £3.5m and lease deferrals of £3.2m, part of which will be repaid in the remainder of the financial year. The Group has no external borrowings.
CEO says:
"...We have successfully re-built the sales commission pipeline to its highest level in 3 years,..."
I own shares here. They are currently 34p, versus the pre-lockdown price of 95p. In the years before Brexit the company was reporting over £30m of net profit per annum. Today's market capitalisation is £94m.
I may have been hasty in buying as a recovery play. I couldn't find a reference to market expectations in today's statement so perhaps management has 'withdrawn guidance'.
Asagi (long FOXT)
It seems positive, but the market seems to have interpreted it as bluster.
I don't own, but last time I had a look, it seemed that they have a decent lettings product, but a bad sales one. Turnover from sales reduced from £69.8m in 2014 to £32.6m in 2019, and that part of the business was loss making even on an adjusted EBITDA level.
By contrast mortgage broking revenues actually increased in the same period from £6.26m to £8.53m. Either they are getting more money per customer on this side, or more likely, the average commission per property has fallen quickly over that period. The rapid increase of London property values from 2014-2018 I think has seen agents happy to accept a decreased percentage as it still means more money. Some places may have gone up 50% in that time.
Lettings is by far the most important part of the business, but I feel there are substantial headwinds. The market for short-term lets is surely smaller now and more competitive. The ban on fees also makes it harder to squeeze tenants, and a more competitive rental market may see landlords go towards cheaper agents. Margins seem to have fallen away.
I don't feel the market conditions which saw them make the big profits are likely to return for some time.
Foxtons (LON:FOXT) I think this statement looks very fair. No debt, a 52 week high of 98p and a placing earlier this year at 40 pence. So below 33p seems fair. A lot of London offices will be transformed into residential in time and although lettings may be cheaper, agents tell me tenant turnover creates the biggest profits. Definitely on my buying list but I think markets are heading down to lower levels so just watching at the moment.
Foxtons (LON:FOXT)
Many sales and chains are falling through because mortgage companies will not lend money on a property that does not have an EWS1 certificate, it is not possible to re-mortgage either (i.e. convert a normal mortgage to a buy to let mortgage as this is considered a new application) https://www.theguardian.com/mo...
The Sunday Times has had several articles about this too. London and other urban areas are obviously at greater risk because of the relatively high number of flats.
Begbies Traynor (LON:BEG)
Issued its Q3 red flag reprot today. Worth a read.
"Julie Palmer, Partner at Begbies Traynor, said:
"It is noteworthy that the number of businesses in significant distress have grown substantially in the last three months, even with court capacity significantly reduced due to the pandemic. With so many businesses limping along there could be a flood of insolvencies when the courts do get back to anywhere near normal capacity and attempt to clear the backlog of pending cases. This in itself, combined with the end of the furlough scheme and other government support measures, is likely to have a material impact on the UK business failure rate.
"Unfortunately for the many zombie companies in existence across the UK, a perfect storm is on the horizon. A combination of a grim economic backdrop and very poor trading conditions, particularly in the most vulnerable sectors, such as hospitality will take its toll and this is expected to feed through to Q1 2021, particularly when the government ends its high profile corporate life support measures."
Even though all 22 sectors measured by the Red Flag Alert, research showed an increase in significant distress since the start of the year, some sectors have experienced a harder fall than others in the last quarter, including those which have been thriving since reopening;"
Phil
Agree - had a browse myself - the bit that surprised me was food and drug retailers struggling - but it makes grim reading.
Its also worth noting the definition of distress and significant distress; the former a CJJ <£5k the latter >£5k
I'm not so sure about the value of those definitions. It must be more likely with all the disruption due to the lockdowns and working from home that small claims and disputes get missed and claimants get automatic judgements. Not a good thing of course but perhaps a sign of the general disruption.
Surely Begbies would benefit from this. Surprised they are still valued at similar levels to pre lockdown
Problem is that Begbies Traynor (LON:BEG) has been crying Wolf for many many quarters, look at past Red Flag reports. Yes, there has been revenue growth but not at rates to justify its high valuation IMO.
would be grateful Paul if you could have a quick look at Redde Northgate (LON:REDD)
Redde Northgate (LON:REDD) - I don't think Paul will comment as I can't see any news today and it has been covered in the past. It continues to pay an attractive dividend and is in my view an excellent turnaround situation. That hasn't stopped a fall in the share price from around 220 to 180 over the past few weeks. There has been good discussion on PI World by Richard Leonard on a couple of occasions and he describes himself as ultra bullish on the stock.
There was an AGM update from Redde Northgate (LON:REDD) yesterday but Paul didn't get to it before he ran out of time.
yes thanks. I am aware of the PI world conversation with Richard Leonard and bought on the strength of it. Be good though to get Paul’s view,if he has time .
I thought one of the attractions of Redde Northgate (LON:REDD) was the pedigree of the new Chair, Avril Palmer, who made a mint at BCA/WeBuyAnyCar https://www.thisismoney.co.uk/...
Might be worth casting an eye over Hornby (LON:HRN) - which back in TMF days, at the turn of the century, was a private shareholder favourite. Been through hard times but the new CEO seems to understand the value of their roster of brands and was quick to spot the opportunity that the marathon staycation we're being encouraged to take would offer them:
Back in profit, debt gone and lots of opportunities to exploit. There's a temptation to read across to what's happened at Games Workshop (LON:GAW) although think I this isn't quite the same. But often in these situations it's the CEO's language that tells - this kind of stuff:
I haven't looked at the accounts in any detail as I'd never anticipated being even mildly interested so this is purely superficial. But - at that surface level - it looks worthy of a deeper dive.
timarr
Hi Timarr
Thanks for the heads up on £HRN. I passed over the RNS thinking that the company continues to be the proverbial basket case, but just maybe the new CEO will be able to revive the company and its historic brands. If he has an impact anything like Kevin Rountree at Games Workshop (LON:GAW), time studying the recent RNS and accounts will be well spent.
Jonno
Thanks Timarr I own this as one of my highest conviction shares. I think it is a highly credible turnaround story and would encourage anyone to read their results as an illustration of both clear vision and a laser focus on the right strategy to get there.
After a very quick look at the interim release at Hornby two things stood out. Firstly operating cash flow in the first half was positive. True that after a doubling in fixed investment (sounds like more modern machinery mostly) cash was down compared to March year end (i.e. net cash flow was negative) but this was an encouraging revenue recovery. There was a substantial fund raise (40 odd mn shares at 36p to raise £15mn) in February. Most of the debt was eliminated and this also allowed an invetory build ahead of H2. . Phoenix and Artemis were the main backers. They are obviously hoping for a decent H2 towards which the company is very heavily weighted.
Secondly, if you brush through the product range description, it is quite clear that Hornby went on a huge brand buying binge in 2004. It looks insane in hindsight but growth worshippers pushed the stock up from 30p to 250p over a couple of years. Currently net equity is £37mn against a market value of £57mn and though there is goodwill and intangibles of aggregate £7.5mn some value must be attributable to the brands - Hornby itself, Scalextric, Airfix and so on.
I have no idea whether these brands appeal to the current generation of younger children but I do know my grandson (5) has a huge collection of toy cars and plastic dinosaurs but spends a fair amount of time playing games on his tablet. Will he graduate to Hornby railway models (basic set at about £80), collectors' locomotives (starting at around £100 up to £500 for limited editions) or Scalextric car racing (basic sets start at £65)? Each brand seems to have a unique website and some (anyway) are on ebay.
Fascinating but no idea.
Hornby (LON:HRN)
I have no idea whether these brands appeal to the current generation of younger children but I do know my grandson (5) has a huge collection of toy cars and plastic dinosaurs but spends a fair amount of time playing games on his tablet.
Hi WDWombat
Yeah, I don't know either. The trouble with this sort of stock is that you can create opportunities out of thin air.
For instance, it wouldn't be hard to imagine creating a hobbyist brand that doesn't require kids to buy the stuff - there's probably enough people around who remember the brands from our childhood to create some kind of business. Alternatively the new Nintendo Mario Kart game - using real toy karts - shows the kind of mixed media ideas that you can come up with if you're inventive:
But opportunities aren't cashflow and without cashflow you can't grow the business without diluting the shareholders.
Anyway, having skimmed the numbers I decided to dip a toe in the pond. But at this stage I wouldn't want to put my foot in it ...
timarr
I haven't had time to look properly at Hornby (LON:HRN) (and tbh I'm not sure it will be a priority at this time).
Superficially though, the thought that crossed my mind on the improvement in performance - parents locked in at home for weeks on end with their kids - what would they do - buy more toys! Also as he's going to have to play with it as well, perhaps dad would buy something he enjoyed in his youth - a Hornby trainset maybe?
For me, I would want to see this improved performance sustained in more normal circumstances to be confident enough to invest in the 'turnaround'
I have three young kids myself and this comment struck a nerve. My sister and her husband both tested positive for COVID last week and as a good brother I wondered what I could do. So I headed to the local Smyth’s superstore and put a bag of “time stealing” toys together for each of their kids. They are all too young for Hornsby brands but it made me think that if this company is at the right price it has massive potential both for parents trying to introduce the new generation and parents trying to relive a lost youth. The parallels with Games Workshop (LON:GAW) aren’t valid as they have already created a younger demographic following from their older following which is obviously attractive but it seems reasonable to me that Hornby (LON:HRN) could do the same with effort and with a range of brands that have a much greater potential for mass market. I also note Dogon’s fervent support for the management team above - that I think will be my avenue for research - do these guys have experience in creating a brand or community? If I can see that, I think I’ll be a buyer. Michael C’s negative comments below are also interesting - more research needed here !!
As an aside it also struck a cord with me that I had very little worries for either my sister or husband’s health - they are both younger middle aged, my sister lost sense of taste, her husband was symptom free, neither has any related health condition. For the majority of the country, this isn’t the life threatening condition we were worried about (although as investors we really need to be concerned with what the government is actually doing, not what we think they should be doing - don’t want to restart that debate).
It is important to remember that model railways are still a very important part of Hornby's business and the models with the best margins are expensive items sold to adults, not trainsets sold to kids. The hobby is very lively at the moment, with everyone seeming to be very busy, and there are quite a lot of collectors. Anyone following £hrn could usefully follow the leading enthusiast forum, RM Web, where there is a sub-forum for Hornby (LON:HRN) https://www.rmweb.co.uk/commun... and a thread with intelligent comments about today's RNS: https://www.rmweb.co.uk/commun...
However I am not convinced by Hornby's new Steampunk line, where I think the design work is amateurish. If you are trying to appeal to a very specialised market you need designers who are totally immersed in the genre, and you need some powerful social media influencers on board. When a new consumer product catches my interest the first thing I do is look at Youtube. A search for Steampunk videos produced in the last month has the two leaders with 931k and 837k views, both about a week old - no mention of the Hornby range. The highest viewcount for the Hornby steampunk range is 30k views after 4 weeks. The majority of the comments on all the Youtube reviews of the Steampunk line are critical and many are utterly scathing.
Diversified Gas & Oil (LON:DGOC) (Diversifed Gas and Oil) has reported another set of strong results this morning in their Q3 update. This is a company with an excellent management team that has produced consistent delivery and exemplary execution. Key is management’s ability to manage their wells (co is 99% gas) more efficiently than previous owners and industry peers. Careful stewardship extends the well decline period so that the wells produce for longer and on average their wells have a life of over 50 years. They are also one of the lowest cost producers and take a sensible/conservative approach to hedging production. This translates into better financial metrics
Q3 results this morning report Adjusted EBitda of $75m +10% and EBITDA margin 52%. Production increased to 107 MBOEPD +7% vs Q2 and 17% vs Q3 2019 and at the same time they have maintained low production costs at $1.18/Mcfe inline with previous quarter ($1.17).
The company policy is to distribute 40% of FCF to shareholders and today they have announced another increase in the quarterly dividend to 4cents, an increase of +7% on Q2 and +14% on Q3 last yr. The stock now yields over 10%.
The balance sheet is in good shape with Net Debt of $730m, equivalent to 2.2x ND/EBITDA.
Natural gas prices for 2021 continue to improve and the company has increased its hedging position for 2021 to 80% of production at a floor price of $2.66 MMBTU giving improved confidence in future cash flows.
Management will discuss these results at a webinar on 3 Nov at 1pm. Register here
Re Diversified Gas & Oil (LON:DGOC), which I hold, it’s also worth noting their recently announced JV with Oaktree Capital who are providing $1bn of capital over 3 years.
My morning smallcap tweet:
Hornby (LON:HRN) Kape Technologies (LON:KAPE) Kromek (LON:KMK) Filtronic (LON:FTC) Tiziana Life Sciences (LON:TILS) Foxtons (LON:FOXT) MTI Wireless Edge (LON:MWE) OTAQ (LON:OTAQ) Magnit PAO (LON:MGNT), Biome Technologies (LON:BIOM)
Hornby (HRN) H1 rev up 33%, pretax £17k (-£2.5m). Outlook 'hard to tell'. [SP=33 Cap=55m]
Kape Technologies (KAPE) £89m raised in oversubscribed placing last night at 150p, a 1.6% discount. [SP=152.7 Cap=246m]
Kromek (KMK) CFO scarpers. He is thanked. [SP=12.2 Cap=42m]
Filtronic (FTC) delivery delays mean rev broadly flat. "Slow order intake has been experienced in the public safety market as our lead customer continues to experience in-field rollout constraints. New business acquisition remains a challenge as opportunities for customer engagement remain constrained." [SP=9.35 Cap=20m]
Tiziana Life Sciences (TILS) confirms Accustem Sciences demerger timetable. Ex-entitlement date 2 Nov. [SP=155 Cap=300m]
Foxtons (FOXT) Q3 rev down 10%, sales commission pipeline highest in 3 years. "Remains cautious as economic uncertainty causes more sales transactions to fall through and is putting downward pressure on rents." [SP=34.3 Cap=113m]
MTI Wireless Edge (MWE) wins $1.5m follow-on order in Russia. [SP=43 Cap=38m]
OTAQ (OTAQ) guides H1(Sep) rev and EBITDA up by unspecified amounts. Guides FY rev up c. 17% and EBITDA up c.11%. ""Trading in this period however has been challenging and has resulted in the expected timescales for our growth ambitions being extended due to limitations in our ability to engage with new customers." [SP=37.5 Cap=11m]
Magnit (MGNT) Q3 rev up 12%, LFL up 7%, in Roubles. Confirms store opening and redesign guidance but cuts capex. [SP=NA Cap=NA]
In line: Biome Technologies (LON:BIOM)
Proactis Holdings (LON:PHD) results overview by Tim Sykes. EBITDA in line with expectations.
Video & Podcast
Further, PHD's Tim Sykes, CEO & Richard Hughes, CFO, will give an hour's FY20 results presentation/webinar with Q&A, this Friday 30.10.20 at 12.30. To join register here.
Separately, next week, 5th November 1pm, we have another piworld interview/webinar: An hour with Paul Jourdan, from Amati Global Investors. Paul will give an insight to his winning formula, how he selects companies and sectors, and how his strategy has evolved over time. To join register here.
Scott Brumby sounds like some dodgy 80s Radio DJ, but yesterday's report went straight to the top of the charts, well done gents, feels like a winning formula.
Just to echo your comments - the mix of companies covered was very helpful.
Good morning! Below covers today's regulatory and potentially price-sensitive announcements.
Thank you Holland Smith.. very useful!
I really appreciate yesterday's deep dive into £SAA. The warning signs were all there after the accounting shenanigans. Unfortunately I took up a full position following Vin Murria's buy-in to the company, but I guess there's no better way to learn a lesson than learn it the hard way.
What initially attracted me to M&C Saatchi (LON:SAA) was its decentralised structure encouraging an entrepreneurial spirit in an industry that thrives on creativity. What I failed to understand was that this model required enormous attention to detail and excellent internal controls. This was not the case. The Board had titled Directors and an award-winning media banker. This meant nothing. With hindsight, in my view, it was simply not up to the job of managing what became a very complex enterprise. It may have needed a more grounded and practical team with a complete focus on the job at hand and an absence of external interests. Crude possibly but a Board of the "great" and "good" may look impressive in an annual report but could be awful for investors. I was relieved to have got out of this disaster some time ago albeit at a substantial relative loss.