Small Cap Value Report (Thu 3 May 2018) - TNI

Good morning, it's Paul here!
We're up-to-date! Yes, Tuesday's report now includes a rather sceptical commentary on Connect (LON:CNCT) (in which I hold a long position, but am pondering whether to sell or not) here.
Wednesday's report was updated last night, to include six companies in total, so the link for that is here.
Leon Boros - half marathon
ISA millionaire, and all round decent chap, Leon Boros is running a half marathon on May 20th. Leon is always generous with his time, helping to educate and enrich other people through talks at investor shows, etc. His investment track record, based on a clear focus on high quality companies, is extraordinarily good. Stunning actually. So he's very much a person to follow.
Here's a link to Leon's eBook and articles about his highly successful strategy. If you're looking for a proven strategy to adopt, then I think Leon's approach is second to none.
The fundraising cause is for ShareSoc, which as many of you know, is a not-for-profit organisation which campaigns for private investors on numerous topics. The Directors & other supporters are unpaid, and put in a tremendous amount of work on our behalf.
I feel that we should do more to support ShareSoc, and hence it's a good thing to become a paid member. Also, if you can spare a bob or two to sponsor Leon run for ShareSoc, then I know he would appreciate it very much indeed. Here's Leon's sponsorship page.
Trinity Mirror (LON:TNI)
Share price: 84.7p (down 2% today, at 12:43)
No. shares: 299.3m
Market cap: £253.5m
This newspaper group updates us today;
Trinity Mirror plc is issuing a trading update for the 4 month period from 1 January 2018 to 29 April 2018 ('the period'), ahead of its 2018 Annual General Meeting later today.
A reader left a very interesting comment here yesterday, suggesting that newspapers might see a resurgence because people are becoming disillusioned with all the lies on social media. That's a nice idea, although newspapers don't exactly have the best of reputations for accurate reporting! It's more about reflecting the prejudices of the readership, sadly. Although that's less the case with local papers.
Also, Facebook seems to be doing a great job of trashing its own reputation, because it happily collects in the advertising revenues, but seemingly does not adequately vet the advertisers, let alone all the nonsense that people post on their timelines. So could we have reached peak social media? I find that quite a compelling argument, and am considering whether or not to place a short on Facebook shares.
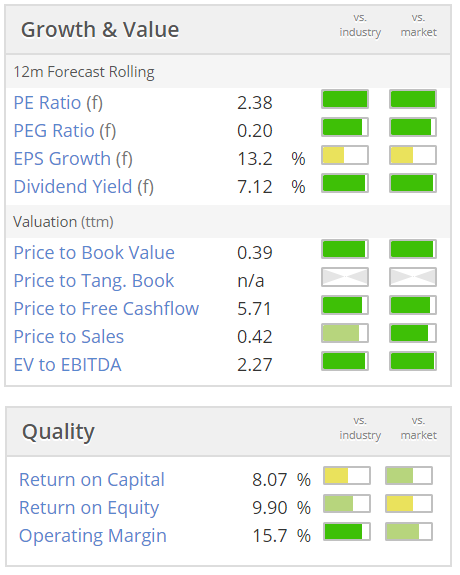
Trinity Mirror could possibly surprise everyone, and see its advertising revenues go up, maybe? On a PER of just 2.4, and with a dividend yield of about 7%, I am wondering whether this share might do what it did back in 2009 - it bottomed out at 25p, then rose to about 173p within 6 months. Sentiment has radically changed towards this share in the past - could it happen again, I wonder.
A well-crafted statement today starts with the key information;
The Board anticipates performance for the year to be in line with market expectations*.
Ooh, there's an asterisk! Hopefully this will tell us what market expectations are - because post MiFID II many private investors no longer have access to broker notes (well done regulators, great work, muppets!)
* The market consensus range for adjusted PBT for the 52 weeks ended 30 December 2018 is £131.7 million to £133.9 million.
This range only includes estimates from analysts that have updated forecasts since our annual results announcement on 5 March 2018. Adjusted PBT excludes operating adjusted items (costs in relation to restructuring charges in respect of cost reduction measures, pension administrative expenses, amortisation of intangible assets and transaction costs in relation to the acquisition of Express and Star) and the pension finance charge.
Fantastic stuff, well done to TNI & its advisers. This is exactly how all companies should report.
Other points in today's update;
Acquisition of Express & Star (a Midlands-based local newspaper group) has been referred to competition watchdog & Ofcom. Board confident that there are no competition issues.
Like-for-like group revenues down 9%
Revenue trends are still grim, so any hope of stabilisation looks way too optimistic;
Publishing revenue for the period fell by 9% on a like for like** basis, with print declining by 11% and digital growing by 2%.
Publishing print advertising revenue fell by 17% and circulation revenue fell by 7%. Improved national advertising performance over Easter resulted in print advertising revenue falling by a reduced 15% in March and April.
We continue to grow digital display and transactional revenue which grew by 7% during the period. Digital classified advertising, which is predominantly upsold from print, fell by 16% during the period.
Net debt - for a business in (arguably terminal) decline, it's astonishing how cash generative TNI still is;
The Group continues to generate strong cash flows with net debt at the end of April estimated to be £85 million. This is after payments of £88 million in relation to the acquisition of Express and Star and increased pension contributions but before the payment of the 2017 final dividend of £10 million.
My opinion - unfortunately, I can't see any signs of the business stabilising, so am reluctant to punt on a recovery in share price. If these declines in revenue continue, then it's only a matter of time before profitability collapses - costs can only be cut so far.
The elephant in the room is the gigantic pension funds. Although the prodigious cashflows generated by the business have, so far enabled it to reduce debt, pay decent divis, and service the pension scheme. The deficit could reduce once interest rates begin rising.
I'll keep a watching brief, but at the moment, I can't see any reason to invest here.
On paper this share looks stunningly cheap - high quality scores, and a dividend yield over 3 times the forward PER! I can't recall ever seeing such a situation where the yield is that much higher than the PER.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
"I'd've thought that ShareSoc would have enough tech experts/professionals as members to be able to get volunteers. Employing outsiders to do it can be a road to endless expense or problems."
Agreed.
Maybe I am worrying about nothing though. Some further thoughts:
1) I recall Roger has run a software company (see this old thread: https://www.stockopedia.com/content/small-cap-value-report-30-apr-2015-cct-ope-ubi-gbo-97917/?comment=33#33). So there is some real-life expertise involved here.
2) I gather some ShareSoc directors are active on social media. No doubt calls for tech/CRM experts would have been made though that channel.
3) ShareSoc and UKSA have been in merger talks. UKSA.org.uk runs on Drupal, so perhaps the eventual plan is to integrate CiviCRM with that website (although that leaves a question about the £6k WordPress site).
I know Drupal. A bit.
But I'm not volunteering.
I wouldn't choose to use it on my own sites. so don't know (or want to know) it well enough to use it for anyone else.
And don't know CiviCRM, though understand that it should support Wordpress as well as Joomla!.
I'd've thought that ShareSoc would have enough tech experts/professionals as members to be able to get volunteers. Employing outsiders to do it can be a road to endless expense or problems. And stuff often needs acting on immediately - as in the recent Drupal vulnerability.
“I feel that we should do more to support ShareSoc, and hence it's a good thing to become a paid member.”
Well... according to Leon’s sponsorship page:
“The money raised will be used to help ShareSoc install an up to date membership database and online member support forum and to further its educational work.”
And according to ShareSoc:
https://www.sharesoc.org/servi...
https://www.sharesoc.org/servi...
“Over the last two years, Mike Dennis and I, with input from Roger, have examined how best to achieve this. Fortunately, we have established that we can develop the facilities we need using open source software: WordPress and CiviCRM, so there are no software costs as such. However, to create a website of a professional standard, professional input is required. After an extensive competitive process, we have identified expert contractors able to assist us with this, though much of the work to transition to this new site and system will be performed by ShareSoc’s own staff.”
“Firstly, the cost of contractor effort to conduct the first phase of the project was ~£6,000, below the original budget. Subsequent phases are expected to cost us a further £18,000. “
£18k to implement what is free CiviCRM software does sound rather a lot.
And poor old Leon will have to run a few more half marathons to pay for the expert contractors :-(
If I were a ShareSoc member (or Leon!), I would be asking what alternative and cheaper CRM packages — or combination of membership/event/forum packages — could be considered instead.
Perhaps the tech aces at Stockopedia and SharePad could provide some advice?
For what it is worth, I have downloaded the CiviCRM software, installed it into a localhost WordPress set-up and found it does not integrate well with the page-builder (WP Bakery/Visual Composer) used to develop the ShareSoc website. The problem I encountered was CiviCRM displaying confirmation pages using the active WordPress theme and seemingly ignoring the style of the pages created using the page-builder.
https://docs.civicrm.org/sysad...
And it seems CiviCRM was developed primarily for Drupal and not WordPress. Anyone know Drupal?
Hi Paul,
Thanks for your observations on Trinity Mirror (LON:TNI) - I always value your views.
I should point out that I wasn't intending to suggest a resurgence for the papers, but rather that there is some evidence of a change in the (down) trend having actually happened in the short term at least. As it turned out Trinity Mirror (LON:TNI) 's take on this was less bullish than that of Johnston Press (LON:JPR). I note though that Johnston Press (LON:JPR) referred to the regionals whereas Trinity Mirror (LON:TNI) did not give the national / regional split - the lack of that split may of course mean that they saw no significant difference. On the subject of trust that you raise I do agree that the "red tops" are probably not much more credible that Facebook - people do though I think have a warmer feel about the regionals.
Anyway albeit a with a less bullish tone than Johnston Press (LON:JPR) (and one that did not 'surprise' the market as I conjectured it might) Trinity Mirror (LON:TNI) did report some improvement in print advertising.
This is important in two ways I think. Firstly because existing valuations are predicated on all of the traditional business areas continuing to decline aggressively; if even temporarily the decline abates then this increases the profits and cash that can be thrown off during the death spiral.
More significantly perhaps it also creates the possibility of a change in sentiment in the near term. I made a bit of a joke of the fact that TNI's outlook statements have been incredibly boring in the last three years - always "in line" - but this underwrites the fact that the earnings trajectory has not really changed over the recent years (taking aside the recently announced tie up with Express & Star that I will mention later). So the story has not really changed in three years, yet the price wiggled between c. 190p and c. 60p so imho sentiment is a big factor here imho.
Anyway I can absolutely understand the 'Marmite' taste of TNI as an investment, but for me the "run down" value of the traditional business more than supports the current valuation.
You made an important point though that I believe is transferable to other situations :
This actually comes with the territory and is the counterpoint of the oft heard complaint about growth stocks - that they generate great profits but no cash as it is all invested in growth - on the wind down these businesses throw off super levels of cash as capex falls.
As an aside, I used to run the operations for a business unit that was barely washing it's face ; "the seniors" then decided to take a massive write down on our assets (potential resale value was virtually zero). Although we were still doing exactly the same business, I cannot recall now how many calls I had to field over the next year from the heads of other divisions wanting to know what they could do to achieve our levels of return on Assets. (They were by and large not impressed at my suggestion of becoming "old school" and "redundant".
Anyway, back on topic - Trinity Mirror (LON:TNI) should probably now go back into the "too boring" bucket until we learn what the regulators think about the proposed tie up with Express and Star (incidentally these are the national titles not the black country regional of that name)
Personally I think it would be perverse for the 'merger' to be blocked by the regulators, but nevertheless this would be my major caution here.
Tni has lots of property and office space. I would think they will morph into more of a reit as the decline happens
Hi Paul
I'd just like to thank you, Graham and the Stockopedia staff for your hard work, insights and analysis, particularly the recent feedback and videos from Mello. By far the best investment I have made was to subscribe to Stockopedia. I'm sure it must be very hard work and tedious at times churning out the SCVR so keep up the good work and I hope you'll return refreshed and renewed after your sabbatical. I really appreciate your efforts, erudite analysis, humility and honesty.
Cheers.
jim knight
Paul,
Re Trinity Mirror (LON:TNI) you mentioned "... a dividend yield over 3 times the forward PER! I can't recall ever seeing such a situation where the yield is that much higher than the PER."
As a quick job, so no checking data, or the quality of the companies, and E&OE etc. (Think that's all the disclaimers out of the way !)
Here's a list of companies who's Divi is >= (current) PE. I did leave out Carillion (LON:CLLN) ! lol who's figures came out as PE:0.49 Div:129.93 Ratio:265.16
Still trying to work out what, if anything, this means, but do recognise some of the names as being mentioned in SCVR in the past.
Pan African Resources (LON:PAF) PE:0.06 Div:4.58 Ratio:76.33
Aberdeen Private Equity Fund (LON:APEF) PE:2.62 Div:47.06 Ratio:17.96
Accrol Group (LON:ACRL) PE:2.00 Div:33.33 Ratio:16.67
Safestyle UK (LON:SFE) PE:4.43 Div:19.40 Ratio:4.38
Barloworld (LON:BWO) PE:0.76 Div:2.83 Ratio:3.72
Connect (LON:CNCT) PE:5.00 Div:17.82 Ratio:3.56
Gattaca (LON:GATC) PE:5.88 Div:16.73 Ratio:2.85
Caffyns (LON:CFYN) PE:2.28 Div:5.29 Ratio:2.32
Debenhams (LON:DEB) PE:6.17 Div:13.90 Ratio:2.25
OPG Power Ventures (LON:OPG) PE:2.28 Div:5.09 Ratio:2.23
UP Global Sourcing Holdings (LON:UPGS) PE:5.76 Div:12.34 Ratio:2.14
Trinity Mirror (LON:TNI) PE:3.70 Div:6.82 Ratio:1.84
Urals Energy PCL (LON:UEN) PE:2.42 Div:4.46 Ratio:1.84
Hansteen Holdings (LON:HSTN) PE:3.45 Div:6.27 Ratio:1.82
Galliford Try (LON:GFRD) PE:6.36 Div:10.36 Ratio:1.63
Centaur Media (LON:CAU) PE:3.55 Div:5.56 Ratio:1.57
NAHL (LON:NAH) PE:5.88 Div:8.55 Ratio:1.45
Marshall Motor Holdings (LON:MMH) PE:2.65 Div:3.79 Ratio:1.43
PayPoint (LON:PAY) PE:9.93 Div:13.81 Ratio:1.39
Northern Investors (LON:NRI) PE:9.78 Div:13.39 Ratio:1.37
Conviviality (LON:CVR) PE:9.37 Div:12.45 Ratio:1.33
National Grid (LON:NG.) PE:4.09 Div:5.22 Ratio:1.28
Prime People (LON:PRP) PE:5.71 Div:6.67 Ratio:1.17
Income & Growth VCT (LON:IGV) PE:25.45 Div:29.58 Ratio:1.16
British & American Investment Trust (LON:BAF) PE:9.89 Div:11.47 Ratio:1.16
Ferrexpo (LON:FXPO) PE:4.74 Div:5.21 Ratio:1.10
Cenkos Securities (LON:CNKS) PE:7.92 Div:8.61 Ratio:1.09
PCI- PAL (LON:PCIP) PE:2.69 Div:2.86 Ratio:1.06
Mobeus Income & Growth VCT (LON:MIX) PE:24.60 Div:25.81 Ratio:1.05
Panther Securities P L C (LON:PNS) PE:3.13 Div:3.20 Ratio:1.02
U and I (LON:UAI) PE:7.38 Div:7.54 Ratio:1.02
Not sure how good your data is - just looked at National grid, the PE ratio is 14, and div is 5.28%. Appreciate the effort all the same.
Re the PE/Divi data.
I should have pointed out it wasn't from Stockopedia, and the figures were from another site's financials. Perhaps I should have worked them out from the underlying numbers too, to check their headline figures were correct.
My investment performance has improved markedly since subscribing to Stockopedia, with Paul and Graham’s daily small company reports a key reason for that success, both big winners I would not have invested in (e.g BOO 7 bagged) but for their expertise, but also when their excellent analysis reveals shares not to touch with a barge pole.
One concern though is burn out risk. Their updates are so detailed and thorough that they must take hours to do. e.g Yesterday was a marathon marathon effort from Paul. If they are both happy to continue to put in so much effort that’s great. But if (or perhaps more likely, when) it becomes too much strain then would it be a good idea to reduce the detail on shares where they are feeling neutral at best, and focus more on shares they like a lot and any obvious stinkers. I look at all their information when they are very positive or negative about a share, but tend to skip some of it when it is far less clear cut. IF others do the same it questions whether it is worth their doing it in such detail.
Also I’m happy with most of my portfolio and tend to hold the quality investments that are doing well for years sometimes, and so have to be selective with new buys. And the updates I really really like are the ones on shares I currently hold or are on my watch list, and the new ones that look must buys. Hence why I sometimes skip some of their information on shares they are ambivalent about.
I hope this isn’t out of place, but it just seems that sometimes they are working TOO hard for our benefit, and we’ll all lose out if their enthusiasm wanes.
On Trinity Mirror (LON:TNI) I ask myself when was the last time I interacted with a product from them and I have my answer whether to invest or not. (in my case not)
On Facebook shorting, I wouldn't personally do it - they own Instagram which has a huge and increasing take-up and are getting into dating, which I think they will do well from. They have fingers in so many pies - VR through their purchase of Oculus Rift etc... that should the Facebook part of it wane, another part of it might boom.
On Trinity Mirror (LON:TNI) one key trend that is happening is media accountability - big brands are coming under increasing pressure to know where their ads are shown, and against what type of content.
Social networks like Facebook, Youtube, and display networks like OpenX cause this issue, because its a "network buy" for ad space. Against user generated content.
We are probably going to see marketing spend shifted to "walled garden" closed networks, sometimes known as premium networks, like Trinity Mirror (LON:TNI) or selective premium video & display networks.
If you're Unilever's CMO, why risk your job chasing ad impressions on open networks when you can spend your money in the many closed networks available, and sleep well at night knowing there won't be any public backlash looming?
Therefore I see digital ad revenues on newspapers increasing in the future, as companies stampede to secure the limited but safe ad environment.
It would be interesting to hear readers thoughts on Van Elle Holdings (LON:VANL)
I don't currently hold but they are in my potentially interesting pile. This is based on the fact that they seem to have a moat (good quality scores) and are trading at a low valuation. Impact of Carillion (LON:CLLN) seems minimal and they are giving guidance of a £10.5m profit before tax.
Cheers.
@BenSharman
A positive AGM statement from Johnson Service (LON:JSG) today:
Following substantial growth in 2017, year to date trading has been strong reflecting both an encouraging underlying performance together with the benefit of acquisitions over the last twelve months. We expect the full year results for 2018 to be slightly ahead of current market expectations.
Mello Derby
Beeks Financial Cloud (LON:BKS) presentation just posted:
http://www.piworld.co.uk/2018/05/03/beeks-financial-cloud-bks-presentation-at-mello-derby-2018/
Also posted yesterday, Xpediator (LON:XPD) presentation:
http://www.piworld.co.uk/2018/05/02/xpediator-xpd-presentation-at-mello-derby-2018/
Both recent IPOs, so great to have the opportunity to hear management to explain the whole story.
Thanks Tamzin
I will watch soon just to make sure that my initial impressions (I was there) were not too overly enthusiastic. My view on Beeks Financial Cloud (LON:BKS) after their presentation was:
* a niche operator with no like for like competitors
* strong barriers to entry - it would be difficult to come in and steal their clothes
* great return on their investment - every server pays for itself x 8 before it needs replacing
* a big market still open to them
* they provide an essential service to their specialist customers. Customers will stick around and won't quibble about the price
* overall a very high quality business just in the early stages of its growth
I hope I am right on this. As always, do your own research.
At Mello Peterborough (2015, I think) I bought one share - Bioventix (LON:BVXP) now +247% since my first purchase. My fingers are crossed that this one will do the same
Disclosure (if not already obvious) - I hold
This morning's AGM Trading Update from Trinity Mirror (LON:TNI)
Had I not read the Johnston Press (LON:JPR) update of a couple of weeks ago then I would have taken this as the most positive statement for some time.
On the Mirror Group side "Print advertising trends were marginally better in March and April" and "Improvednational advertising performance over Easter resulted in print advertising revenue falling by a reduced 15% in March and April."
On the Express and Star front "Revenue trends since completing the acquisition on 28 February 2018 are estimated to be better than the trends for the period pre acquisition."
Not a mention of challenging or volatile trading conditions anywhere, but perhaps they have finally decided that we take that as read!
"The Board anticipates performance for the year to be in line with market expectations"
Always.
However having read JPR's more positive take on print advertising, this more muted statement is mildly disappointing. With regards my "coin toss" position of yesterday, it rather feels like the coin has landed on it's edge.
Will continue to hold my main position, but will review my fun trade after seeing whether there is any further movement after the AGM itself closes.
If you're after suggestions Paul I wouldn't mind your opinion on Irish hotel chain Dalata Hotel (LON:DAL) reporting slightly above today, tipped in SHARES, but down 3% on open, maybe missed expectations. Have stayed in the Maldron hotels quite often and like them and I know from experience how full hotels in Ireland are right now. And everyone else of course. Ta.
I'm currently a fan of this company. I think management really know what they are doing and communicate their strategy really effectively.
It has a strong asset backed balance sheet through direct ownership of it's hotels giving good downside protection and room for expanding their growth through further borrowing to increase the number rooms available. They have consistently high occupancy across the group and modern well appointed rooms. They all have received good reviews in both brands 3.5-4 for all Maldron hotels and 4-4.5 for the more premium Clayton brand.
Their strategy of going after the 3-4 star market in provincial cities is a smart play in my opinion as the competition in these markets is very fragmented and the hotels are typically older than the the budget hotel segment. This update seems positive and leads me to believe they continue to execute their strategy effectively.
This presentation given in January I think outlines their strategy pretty well.
http://dalatahotelgroup.com/wp-content/uploads/2018/01/Investor-Presentation-January-2018-FINAL.pdf
My morning smallcap tweet:
Charles Taylor (LON:CTR), Van Elle Holdings (LON:VANL), Midatech Pharma (LON:MTPH)
Charles Taylor (CTR) major contract win. Acquisition for $22.5m + $28m earn out. Placing of £17.6m by book build.
Van Elle (VANL) [edit] guides FY pretax £10.5m due to weather (natch'), Carillion, weak piling mkt. F/V £10.4m. Bad debt charge will be £1.0m (rather than £1.6m guided). New CEO from Balfour Beatty in Oct or sooner. Previously RNS'd CEO leaving.
Midatech Pharma (MTPH) not aware of any reason for the price spike. Reiterates previous guidance on funding and R&D.
The Van Elle Holdings (LON:VANL) FY profit would be in line/slightly above expectations (10.5 vs 10.4).
Thanks. Have corrected.
not sure I ike the way they call it 'adjusted' pbt
Depends how you see it; one of the better adjustments imo as it is a true one off.
And I think I'm correct in concluding that the broker forecasts were also pre-adjustment (given that the actual bad debt is .6m better than predicted).
But maybe I'm wrong given the market reaction.
Though it got Luceco very wrong initially.
Re Van Elle Holdings (LON:VANL) I think you are not comparing like with like. The £10.4m forecast as shown on the stock report was net profit whereas the £10.5m is pretax so assuming approximately 20% tax this is surely a big miss?
Re Van Elle Holdings (LON:VANL)
Its strange because I made this point this morning...
Year End Trading Update (To End April 2018) – This looks like a miss (PBT to be £10.5m) by I reckon, about 25% (based on Stockopedia 2018E £10.4m Net Profit (my rough calculation being, add 25% for 20% Corp Tax).
With little movement in the SP today not sure what's going on - Can't find any broker notes.
Re Van Elle Holdings (LON:VANL)
Sorry Matilda I missed your comment earlier (so did xcity obviously!). Like you not sure why SP not reacting much
Van Elle Holdings (LON:VANL)
I always go on the EPS forecast.
10.1p x 80m shares is essentially £8m net income - extrapolating from this, PBT would be about £10m - so I think the forecast is PBT and therefore it's a slight beat.
One of the problems I have with Stockopedia is quite often the net income forecast is actually PBT, or adjusted PBT or .......
Phil
Thanks all - Will be interesting to see if Paul can pick up on this, perhaps he has access to some broker info (can't find anything on Research Tree myself).
That would certainly explain the otherwise strange relationship between predicted net profit and predicted EPS.
You're quite correct, though that then leaves me baffled as to how broker expectations could have been that high after the warnings in the interim statements. Tax unlikely to be as high as £2m. But need to look more closely at the broker predictions in future to make sure I have the right line. That said, I don't completely understand the figures - estimated profit up and EPS down. Sharepad had the predicted pre-tax (normalised!) as 10.7.
I had been hoping to pick up a few today after poor results but discounted it after the statement only to see that someone did manage to pick some up in the mid 70s. :( Price back over 80 again now.
Maybe when the results are actually out.
Wannabe acquisitive start up Gloo Networks (LON:GLOO) announces it has given up looking for viable targets and has announced self liquidation at not less than 47p per share.
https://www.stockopedia.com/share-prices/gloo-networks-LON:GLOO/news/gloo-networks-plc-update-on-acquisition-strategy-urn:newsml:reuters.com:20180328:nRSb1958Ja/
Not really newsworthy, but couldn’t resist the strap line “Gloo comes unstuck”. Coat please ......
Gus.
I note zero acqs in 3 years but BoD paid £4.3m in salary, bonuses (!) and pension funding. Two of the dirs are Marwyn people, FYI.