Small Cap Value Report (Thu 4 Oct 2018) - ABDP, EHG, IGP, DFS, BOOM, VLE

Good morning!
Please see the header above for the shares that have caught my eye this morning.
CEO interview - Best Of The Best (LON:BOTB)
In case you missed it yesterday, here is the link to my audio interview with William Hindmarch, CEO of BOTB (in which I have a long position).
Sorry if this project rather curtailed yesterday's report. I've decided that it's too much to write a SCVR and do an interview on the same day. So in future, I'll only do interviews when Graham is writing that day's SCVR.
FinnCap research
Excellent news for private investors. FinnCap tweeted me last night, to say that all investors, including PIs, can now access their research. The website is here. I've just registered, and it works! So that's a very handy initiative to widen the distribution of research notes - something that I'm very keen to encourage.
Ab Dynamics (LON:ABDP)
Share price: 1472p (up 14.8% today, at 11:08)
No. shares: 19.5m
Market cap: £287.0m
AB Dynamics plc (AIM: ABDP), the designer, manufacturer and supplier of advanced testing systems and measurement products to the global automotive industry, is pleased to provide a trading update in advance of the publication of its final results for the twelve months ended 31 August 2018.
A very nice update today;
The Group has performed well through the year and the Board expects both revenue and profit before tax to significantly exceed market expectations.
Most of the growth has come from track testing products, used for autonomous vehicle development.
My opinion - I'm not sure how to value this share, as I don't have any updated forecasts. So I'll have to use some guesswork.
Stockopedia shows broker consensus of 34.0p EPS for y/e 31 Aug 2018. What does "significantly exceed" mean? Maybe c.40p EPS? At 1472p per share, that would be a PER of 36.8 - expensive.
Maybe the market thinks the company will achieve more than 40p then? And/or that the new year might deliver say 50p EPS? That would move the PER down to a still expensive 29.4.
As you can see from the Stockopedia graphs, this company has an outstanding track record, and the light blue forecast blobs & lines below are based on forecasts that we now know are too low. Once the data has updated then, these graphs will look even better.
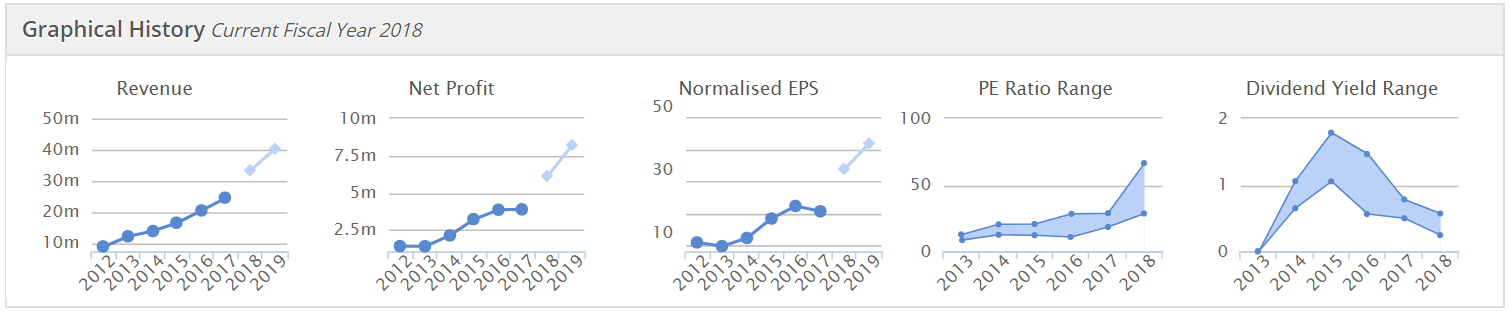
Overall, this is a terrific little company, performing very well indeed. The share price reflects that, so it can't afford to put a foot wrong.
Elegant Hotels (LON:EHG)
Share price: 68p (up 3.7% today, at 11:30)
No. shares: 88.8m
Market cap: £60.4m
Elegant Hotels Group plc ("Elegant Hotels", the "Company" or the "Group"), the owner and operator of seven upscale freehold hotels and a beachfront restaurant on the island of Barbados, issues the following trading update in relation to the year ended 30 September 2018.
H2 trading is in line;
Trading since the interim results in May has remained in line with market expectations.
Current trading - up;
In addition, bookings for the year ended 30 September 2019 are currently tracking ahead of the same period last year.
Barbados tax changes - sounds like there isn't a problem as yet, but there might be in future? That's how I read this anyway;
The Group notes the recent changes to taxation implemented by the newly elected Government of Barbados and, in line with its initial assessment, can confirm that it has not seen a material resulting impact on the results for the year ended 30 September 2018.
Moreover, while the Board continues to monitor the matter closely, at this point it does not expect these changes to materially affect expectations for the year ended 30 September 2019.
More generally, the Group welcomes the Government's plans to invest both in the Barbados tourism industry and in the wider infrastructure of the island.
My opinion - I've reported favourably on this share before. I like the asset backing of freehold properties. Although the big discount to NTAV suggests that the stock market thinks the property valuations are too high.
The shares have slipped down in the last year, like many other small caps, so could be worth a fresh look perhaps, especially that we now know that current trading is up on last year. Quite interesting. It pays out decent divis too, with a yield of over 4%.
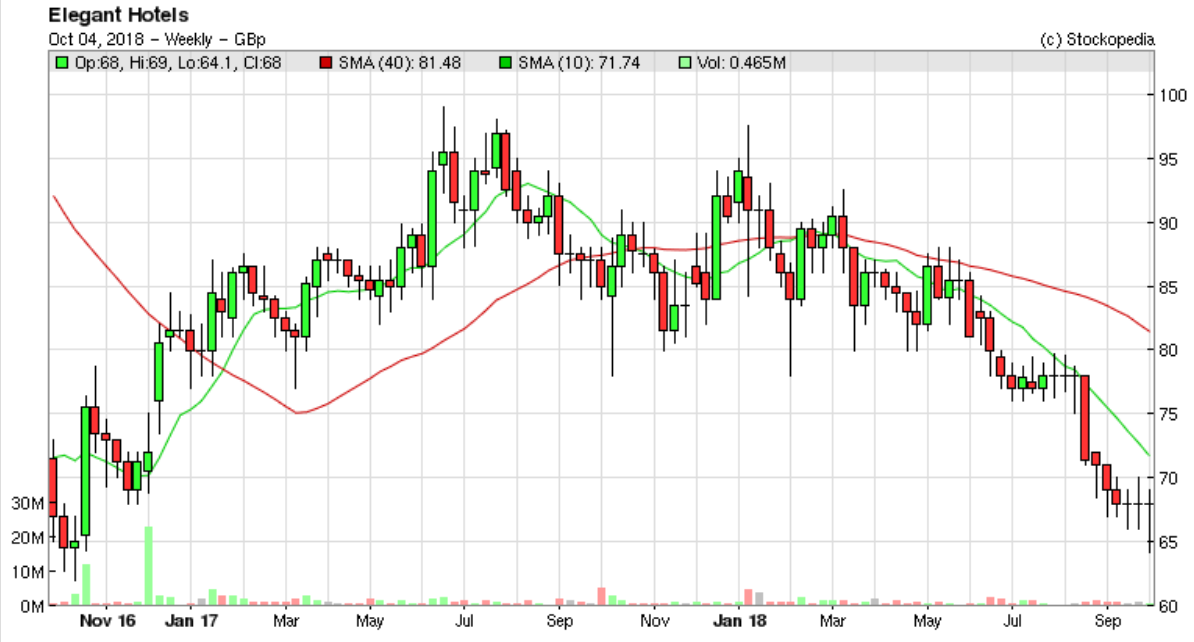
With solid current trading, and the chart showing we're near 2-year lows, then this could be an interesting entry point perhaps? Obviously your research process would need to include doing some googling on the tax changes in Barbados.
Luke Johnson is a NED here, and owns 12.5% of the company - a (probably) bullish sign.
Intercede (LON:IGP)
Share price: 31.5p (up 5% today, 11:50)
No. shares: 50.5m
Market cap: £15.9m
(at the time of writing, I hold a long position in this share)
Intercede, the leading specialist in digital identity, credential management and secure mobility....
H1 revenues (6m to 30 Sep 2018) are up over 10% to £4.1m - in line with expectations. This is a useful improvement, but still very small numbers. A strong end to H1 is noted.
Cost-cutting - deep cost cuts were announced some time ago, which combined with a more sales-focused new management, is what prompted me to buy some shares here. So the operating losses have been substantially reduced;
Coupled with action taken to reduce the cost base prior to the start of the financial year, operating losses for HY2018 are substantially reduced to less than £1.0m (2017: £3.1m).
That's really good news, in my view. With a much lower cost base, sales growth (at very high gross margins) should have a dramatically geared impact on the bottom line. The tricky bit is actually delivering much higher sales.
Cash - this (below) is also good news, and it confirms my view that the company should hopefully be able to avoid tapping shareholders for more funds;
Cash balances as at 30 September 2018 totalled £3.6m, compared to £2.3m as at 31 March 2018 and reflect a positive operating cashflow during the period, plus the receipt of £1.0m from HMRC in respect of the 2017/18 Research & Development Claim.
Convertible loans - opinions differ on this issue. Here's what I wrote about them on 6 July 2018;
Convertible loan notes - this is a bit of a nuisance. The company has c.£5m convertible loan notes in issue, which carry interest at 8%, so costly, at c.£400k p.a.. Interest is payable quarterly, so £100k per quarter cash outflow. The conversion price is 68.8125p, which is well above the current share price of 28.3p, so dilution on conversion doesn't look a problem. Final redemption date is 29 Dec 2021 - so not a problem for the time-being - the company has 3 years to come up with the money to redeem these loan notes (if they're not converted beforehand), and actually it currently has roughly that amount of cash on hand anyway. So this doesn't look like a problem to me - unless trading deteriorates, when it would become a problem.
My opinion - I was drawn to this company by the amazing quality of its client base, which include Governments, other large public sector organisations (worldwide), and major corporations. So clearly it has an excellent product (secure ID software).
If sales can be driven strongly upwards, then this share would in all likelihood become a multibagger, as the growth feeds through to a move into profits. The market cap is peanuts right now, so clearly sentiment is still very much against the company.
That's no wonder, when you look at its historic track record, which is lamentable.
I completely understand why the stock market is sceptical about this share. The company has promised jam tomorrow over many years, and simply didn't deliver on the potential. However, it has new management now, which have stripped out costs, and focused on driving sales.
The jury is out on whether this turnaround will work or not. However, I'm encouraged by today's announcement that risk:reward is looking quite good. I.e. big upside if it works, and probably not much downside if the company continues trundling along at the £8-10m p.a. level of revenues that it has done over the last 5 years.
Stockopedia hates it, with a StockRank of 6, and "Sucker Stock" classification - a reminder that this is high risk. There again, the Stockopedia computers don't know that it has new management, and that cash burn has been slashed! So they're not necessarily right.
Note that a fund connected with one of the NEDs bought 1.5m shares this year, and now holds 26.4% of the company, which I see as a bullish sign.
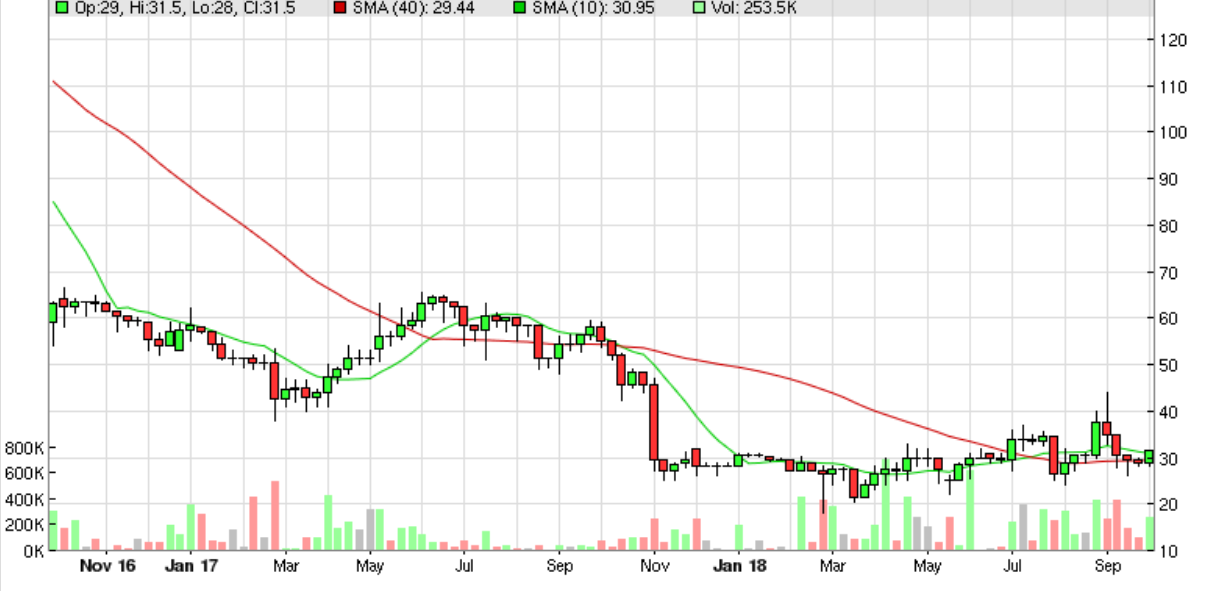
The chart seems well underpinned at c.30p
DFS Furniture (LON:DFS)
Share price: 201.5p (down 4.1% today, at 12:44)
No. shares: 211.7m
Market cap: £426.6m
DFS Furniture plc (the "Group"), the market leading retailer of living room and upholstered furniture in the United Kingdom today announces its preliminary results for the 52 weeks ended 28 July 2018 (prior year: 52 weeks ended 29 July 2017).
A few brief points;
Underlying EPS down 25% to 14.0p - this seems to be a miss, against the 14.4p consensus forecast shown on Stockopedia
DFS blames exceptionally hot weather in Q4 - strange, as that didn't seem to affect competitor SCS (LON:SCS) which reported strong results earlier this week, see my comments here in this Tuesday's SCVR
Dividends - the yield here is attractive, at over 5%. Final divi maintained at 7.5p, giving total divis for the year of 11.2p (same as last year)
Outlook - more positive, with positive (no figure given) LFL sales in the first 9 weeks of the new financial year
Balance sheet - ridiculous, with large negative NTAV. This is only possible because customers pay up-front
My opinion - SCS looks a far better investment proposition than DFS, in my view. I'm basing that on the fact that SCS has a strong balance sheet with pots of cash, whereas DFS has a debt-laden, weak balance sheet. SCS pays a higher divi yield. Finally, SCS is trading well (earnings rising), whilst DFS is trading poorly.
So if I wanted to hold shares in a furniture retailer, then right now SCS would be the obvious pick.
Audioboom (LON:BOOM) - another poor update. Sales have risen quite a lot since I last looked at it, but the cash burn & losses continue. Looks like it will need to refinance again. I don't see a viable business here.
Volvere (LON:VLE) - an interesting special situation, where the largest investment is being sold for a huge profit. This leave cash above the market cap. Management have an excellent track record. I had this on my watchlist after Graham mentioned it, but the stock was too illiquid for me to buy a meaningful position, so I didn't. Well done to holders.
That's it for now. Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Maybe it's upper case O rather than 0?
tried finncap.
it wont accept my password - along the lines of Eabcde01x[
There is a definition of "sophisticated investor" and I will be surprised if many people qualify:
Sophisticated investors
23.—(1) “Certified sophisticated investor” means a person—
(a)who has a current certificate in writing or other legible form signed by an authorised person to the effect that he is sufficiently knowledgeable to understand the risks associated with participating in unregulated schemes; and
(b)who has signed, within the period of twelve months ending with the day on which the communication is made, a statement in the following terms:
“I make this statement so that I can receive promotions which are exempt from the restriction on promotion of unregulated schemes in the Financial Services and Markets Act 2000. The exemption relates to certified sophisticated investors and I declare that I qualify as such. I accept that the schemes to which the promotions will relate are not authorised or recognised for the purposes of that Act. I am aware that it is open to me to seek advice from an authorised person who specialises in advising on this kind of investment”.
Does anyone know who would issue such a certificate?
www.legislation.gov.uk/uksi/20...
And a supplementary question to John's (re the definition of "sophisticated investor"):
I notice the definition of a Certified high net worth individual is on this page:
http://www.legislation.gov.uk/uksi/2001/1060/article/21/made
It states a number of conditions (basically you've got either an annual income of over £100,000 or net assets after house, potential insurance benefits & pension etc. £250,000 or more). However the copy/paste certification text also has to be signed by the recipient’s accountant or by the recipient’s employer. Well I've got neither an employer or an accountant, as I'm early retired and do my own accounts / tax returns (always have done, which may be why I could afford to retire:)). So although I meet the conditions, I'd be unclear how to arrange the certification.
For the record, this is a rhetorical / academic question, since I took the pragmatic approach of clicking "High Net Worth" on the FinCap registration page and signed up anyway. Let the authorities come looking for me if they've nothing better to do!
The FinnCap category is "self certified sophisticated investor", so the question of who issues a certificate doesn't really arise.
I think I can work out who would issue it for a "self certified sophisticated investor".
Isn't this all about shifting any liability for bad decisions on to the investor (where it should be)?
Thanks for the comments on Intercede Paul as the company does look interesting. I went to the company's web site to find out more but found it quite difficult to evaluate the company. A key strength promoted on the web site appears to be that the company's "team of experts has deployed millions of identities to governments" and other organisations which sounds impressive but I haven't a clue how you measure the significance of this. Also I found that the video on the web site explaining the "PSD2 Hub" does not exist so I am none the wiser on what that is. I then clicked on the link on the web site "rapid.intercede.com" to find out about the company's RapidID technology and the link did not work! If Intercede can't even get their web site up to standard I wonder how they manage with more complicated tasks?
Hi Paul
Many thanks for the heads up re FinnCap
Best Regards
Martin
Hi Paul
Any opinion on £TED? I know it's not a small cap but you have commented on it before ... Is today's drop an overreaction?
thanks
Mick
I hadn't looked at Ted Baker (LON:TED) for ages and my recollection was that in stockrank style terms they were a High Flyer (high Quality and Momentum but little by way of Value credentials).
But no longer, the momentum has gone and they are now considered as a Falling Star.
And it is not just the shareprice that has lost momentum , earnings forecasts have been consistently downgraded throughout the year.
Not a happy picture.
I have hardly even skimmed the surface of the results, but I do note that Stock are showing a forecast 7% increase in revenue for the year but for the half year they are +3.5% (+5.5% at constant currency) .
With no obvious reason why H2 will be any better I would expect further downgrades to come.
On this basis I didn't look any further.
Three cheers for FinnCap (and thanks for flagging it Paul).
Hi Paul
Out of interest, when did you sell EHG?
On 12 Oct you said you were long:
https://www.stockopedia.com/content/small-cap-value-report-thu-12-oct-2017-ehg-nxr-rno-rbg-227808/
Back on 9 Jan you said you were happy to hold:
https://www.stockopedia.com/content/small-cap-value-report-tue-9-jan-2018-ehg-tpt-joul-nexs-tast-gaw-294743/
One caveat to the finnCap research is that you do have to tick a qualification box the minimum for which is High Net Worth Individual. I have found that defined as:
If you earn at least £100,000 a year or have net assets excluding property and pensions of at least £250,000, you can self-certify yourself as a high net worth individual (HNWI) or a ‘sophisticated investor’.
from https://www.nelsonslaw.co.uk/h...
Why not "self certified sophisticated investor"?
I managed to sign up to Finncap as a 'sophisticated private investor', and so far they have totally failed to spot that I'm an idiot.
Re EHG and Barbados tax changes:
Effective July 1, 2018, the highest rate of corporation tax would rise from 25 percent to 30 percent.
Effective October 1, 2018, a health service contribution will be introduced at a rate of 2.5 percent on incomes, with 1.5 percent payable by employers and one percent by employees.
The incidence of the above will fall on EHG (and employees).
VAT on hotel accommodation will double to 15 percent from January 1, 2020, with a per night hotel room levy applying in the interim, which will range from USD2.50 to USD10 per night. In addition, a 2.5 percent product levy will be imposed on all direct tourism services. This will be collected by the providers of these services.
A 10 percent tax on all sharing economy transactions, such as those provided by Airbnb, Homeaway, Expedia, and others, will be imposed from August 1, 2018.
An airline travel and tourism development fee will be introduced from October 1, 2018. Passengers flying to destinations outside the Caribbean Community will pay USD70, while those flying to destinations within the Caribbean Community will pay USD35. This fee will be in addition to the departure tax.
The incidence of the second group will be on tourists rather than hotels, but may reduce demand for tourism.
Source: https://www.tax-news.com/news/Tax_Regime_Overhaul_Announced_In_Barbados____76835.html
I hold EHG.
Thanks Paul, I have already registered with finncap and am busy investigating
You really are worth your weight in gold (or your favourite share of the moment)
Lets hope others catch on and do the same
The best place for Broker research in my opinion is Research Tree that includes many brokers to small/medium cap companies.
It is an aggregator of most research houses and Edison, FinnCap, Liberum, SP Angel, Zeus, N+1 Singer, Cenkos, Capital Network. WH Ireland are all on there.
I subscribe and if you haven't already taken a look I think they do a 30 day free trial from memory.
ps edit : I was just looking and I see 2 notes on Elegant Hotels (LON:EHG) for example so you can compare what different brokers think/say.
Yes, I agree, Research Tree is a fantastic service. I'm a big fan.
It's very handy to have things in one place, and the £25 pm fee is insignificant, compared with one losing trade, if you didn't have important information. A lot of people tend to be pound stupid, but penny wise, in my view - re scrimping on important services such as Stockopedia & Research Tree.
I listened to the botb interview yesterday which sounded great had a look at stockopedia, and it sounded great, I had a look at the stocko page and it predicts falling eps this year and next, 3% and 11%, not the impression I got from the interview at all. Is this wrong or am I looking at the wrong thing, or have I gone a bit mad ?
K
As already mentioned today, Volvere (LON:VLE) has rocketed today. Up 16% on the sale of Impetus which the company bought 3 years ago for £1.25m and have just sold for £31m (£23m net). Good for Graham who has told us Volvere (LON:VLE) is one of his largest investments.
But the two businesses the company has left do not seem to be that good: Shire Foods that still makes a loss, and Sira Defence & Security that broke even in the Interim results. So I’m not sure what the future for the SP is after today.
Volvere (LON:VLE) always has a huge (now monumental) cash pile but seems to do very little with it. They have said they have no intention of paying a dividend any time soon.
(Disclosure: I have sold half my long holding this morning.)
ELTA worth following with interest, post special dividends in January the main asset will be TGI yielding 5% and sub 8x EBITDA with most likely next news...more cost to be cut. With numbers moving the right way Im sure it wil attract interest.
There's a lot of clearly written financial detail in the Electra Private Equity (LON:ELTA) strategic review RNS today. I would welcome Paul or Graham's views if there's time to cast an eye over it - there seems to be value and a decent management team here.
News that Volvere (LON:VLE) has disposed of its Impetus Automotive holding just released.
https://www.investegate.co.uk/volvere-plc--vle-/rns/disposal-of-impetus-automotive-limited/201810040930059737C/
£23m of net consideration in the context of a £34m market cap at last night’s close. Shares up over 20% at the moment.
Gus.
Volvere (LON:VLE)
Also worth noting that prior to the transaction Volvere (LON:VLE) 's NAV was £26.9m of which Impetus was £3.6m
Not one of my bigger positions (sadly) but a big thank you to Graham, had it not been for the mentions in this column, it's probably not the kind of business I would have spotted. (Although I do note that it was a suprise inclusion in this year's NAPs selections.)
My guesstimate would be an increase to NAV of c600 ...takes int to 1260 and we can wait for new investments to get excited about. Great deal from Lander and Lander....
Thoughts on Electrocomponents (LON:ECM) anyone? Seems to be chugging along ok.
Morning Paul
I note that you intend to cover Elegant Hotels (LON:EHG) and await your views with interest. Given the recent share price weakness I was expecting a profit warning, but pleasantly surprised that it is trading in line. The stock is inexpensive on on a number of metrics, but as is usually this comes with caveats, the most obvious perhaps being the £:$ FX. I continue to hold.
On Elegant Hotels (LON:EHG), there was also a preliminary bid approach from the Accor Hotel group. So that's another consideration, that they could become a nice acquisition for one of the large chains, all who have been doing well recently and probably hungry for some growth in their portfolio.
Paul
I just wanted to say thanks for the super interview yesterday with Best Of The Best (LON:BOTB).
They were very clear and look like having some interesting plans in the pipeline even though they couldn't talk too much about it.
I hold and may add to my position. Looks like a nice one to lock in the drawer for a long time.
Dave
Hi Dave (Brookeda)
re Best Of The Best (LON:BOTB) (in which I hold a long position) interview yesterday - you're welcome, it was my pleasure.
I thought the answers from the CEO to our reader questions were very interesting. In particular the key points for me were;
- he sounded firmly committed to retaining the AIM listing, and said they run it very lean (on costs & mgt time) so I think there's little to no risk of it going private (which is good)
- I hadn't realised that the marketing budget is being increased so much, from £1.7m pa to £3.0m pa. That should drive accelerated online growth, which could trigger a re-rating of the shares at some point in future
- overall, it sounded as if mgt are more ambitious than I had thought - they clearly want to grow the business, and are not sitting on their laurel bush
On the downside, it's clear that the share will remain extremely illiquid, due to the tiny free float. But that works to the advantage of existing holders, once decent newsflow comes out.
All in all, could be interesting longer term.
Regards, Paul.
Good Morning Paul,
A view on the Intercede Group Trading Update would be much appreciated. I note (from your header) that it's already on your radar so i look forward to reading any comments...update copied from FE Investegate below...
"Intercede, the leading specialist in digital identity, credential management and secure mobility, is pleased to report that revenues for the six months ended 30 September 2018 (HY2018) are more than 10% higher than last year.
This is in line with expectations and reflects a strong end to the half with orders received from both new and existing customers resulting in revenues for HY2018 of £4.1m (2017: £3.65m).
Coupled with action taken to reduce the cost base prior to the start of the financial year, operating losses for HY2018 are substantially reduced to less than £1.0m (2017: £3.1m).
Cash balances as at 30 September 2018 totalled £3.6m, compared to £2.3m as at 31 March 2018 and reflect a positive operating cashflow during the period, plus the receipt of £1.0m from HMRC in respect of the 2017/18 Research & Development Claim."
Regards,
Andrew
Market inefficiency =>
Valuation of DFS Furniture (LON:DFS) versus SCS (LON:SCS)
Interesting update from Thalassa Holdings (LON:THAL) this morning.
The results of the trials is welcome but I can't understand the issue of preference shares, and can't find anything about it in the last reports.
If I've understood it right, they've issued one preference share per ordinary. These are non transferable and have 10 votes.
There's no explanation as to the benefit of issuing these, and I don't understand it. Can anyone illuminate me?
https://www.stockopedia.com/share-prices/thalassa-holdings-LON:THAL/news/thalassa-holdings-issue-of-preference-shares-amp-amendment-to-articles-urn:newsml:reuters.com:20181004:nRSD9126Ca/
Doug
Re the Thalassa Holdings (LON:THAL) issue of preference shares.
This seems to have no effect until the ordinary shares are traded, at which point the preference shares are cancelled. So the voting power will move to the benefit of those existing shareholders who keep their shares. It will also prevent option holders and any convertable bond holders (if such exist) from gaining proportionate voting power.
I'd guess that the answer lies in the capital structure of THAL or in the trading activity, though I haven't bothered to look into either as I have no position.
https://twitter.com/MrContrarian
A succinct explanantion by one wiser than me.
My morning smallcap tweet: Swinging BOOM hits passengers again. What a voyage.
DFS Furniture (LON:DFS), Audioboom (LON:BOOM), Clear Leisure (LON:CLP), Premaitha Health (LON:NIPT), Crawshaw (LON:CRAW), Ab Dynamics (LON:ABDP)
DFS Furniture (DFS) FY rev up 14%, organic rev down 2%. Pretax down 49%. Underlying EPS down 25% to 14p. FY div unchanged at 11.2p. Recent trading: LFL order growth across all brands. "We believe however, we are benefiting from deferred purchases in the prior financial year and overall we expect the market to remain subdued into 2019." I'm short.
Audioboom Group (BOOM) Guides FY rev below current market expectations, material impact on EBITDA.
Clear Leisure (CLP) loses appeal. You can say that again. Court throws out attempt to reverss Mediapolis’ land auction and the decision of the auctioneer to reject the Company’s request of assignment.
Premaitha Health (NIPT) collaboration agreement to provide genetic testing based on next generation sequencing for oncology. The initial phase is worth $1m over the next 6-12 months.
Crawshaw Group (CRAW) Nomad Peel Hunt resigns, 1 month notice. That's a bad sign. Appoints WH Ireland as Joint Broker (but not nomad).
AB Dynamics (ABDP) guides rev and pretax significantly exceeding market expectations.
Morning all.
Ab Dynamics (LON:ABDP) pre close trading update makes good, if brief, reading.
https://www.investegate.co.uk/ab-dynamics-plc--abdp-/rns/pre-close-trading-update/201810040700039015C/
Revenues and PBT to year end August 18 “significantly ahead of market expectations”. Share price had a wobble mid August but seems back on track now.
Gus.
Ab Dynamics (LON:ABDP) up 11.5% as I write. As you say wobble in August which according to Stockopedia chart saw c. 20% fall between July 24th & August 17th 2018. However, this wasn't as bad as the c. 30% fall from January 3rd to February 13th which resulted in my stop loss kicking in at £9.22 - very frustrating and reinforcement for my negative view on stop losses. Leaving aside my personal frustration this is a highly rated share with a PE in excess of 30 (value rank of 5) and as a consequence any small negative or even a lack of positive newsflow seems to hit the share price hard. With autonomous vehicles as flavour of the month and a trading update 'significantly ahead of expectations' the news is good at the moment and the share price has reacted accordingly. I will be interested to hear what Paul has to say - valuation too rich for him or significant future potential enabling it to grow into the valuation?