Small Cap Value Report (Thu 9 Nov 2017) - SWL, QRT, GATC, DVO, TRCS

Hi, it's Paul here.
This is initially a placeholder article, ready for your comments from 7am onwards.
To get you started today, please note that I updated yesterday's report in the evening, with some new sections. So it now includes additional sections on;
- Stadium - profit warning
- Snoozebox - it's gone bust
- Tracsis - results for y/e 31 Jul 2017
See you in the morning!
Good morning, it's Paul here.
No larger cap preamble today, as it takes up too much time, which is limited today.
Swallowfield (LON:SWL)
Share price: 390p (down 1.3% today)
No. shares: 16.9m
Market cap: £65.9m
(at the time of writing, I hold a long position in this share)
AGM Statement (trading update) - this company has a June year end, so this update covers the first 4 months of its 06/2018 year. Description;
... a market leader in the development, formulation, and supply of personal care and beauty products, including its own portfolio of brands
The key sentence is reassuring;
"The Board is pleased to report that trading in the first four months of the year is in line with expectations.
Outlook for the full year is also reassuring;
While we remain conscious of the continuing macro uncertainty both in the UK and internationally, overall we expect to maintain our positive progress and are well positioned to deliver against our expectations for the full year"
The following comments might have spooked some investors (the H2 weighting), but it sounds fine to me;
Our manufacturing business is also performing steadily against strong prior year comparators. As previously indicated we are seeing volumes normalise against the significant new products launched in the first half of last year. Pleasingly, there is a fresh wave of new product launches and contract wins that will contribute to our full year performance and bode well for future momentum. This is likely to give a second half bias to the year in this segment of the business.
New product launches is a good reason for an H2 bias, and might even trigger out-performance, who knows? Christmas ranges have seen "another year of growth".
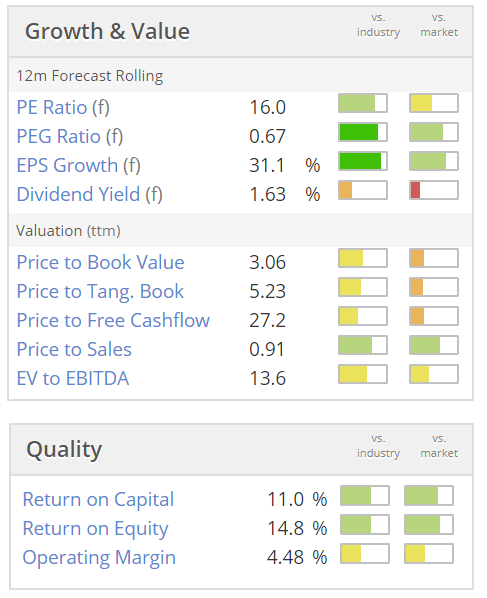
Valuation - on the face of it, the PER looks about right;
Although digging a little deeper, the earnings growth really has been excellent, as you can see from the Stockopedia historic graphs;
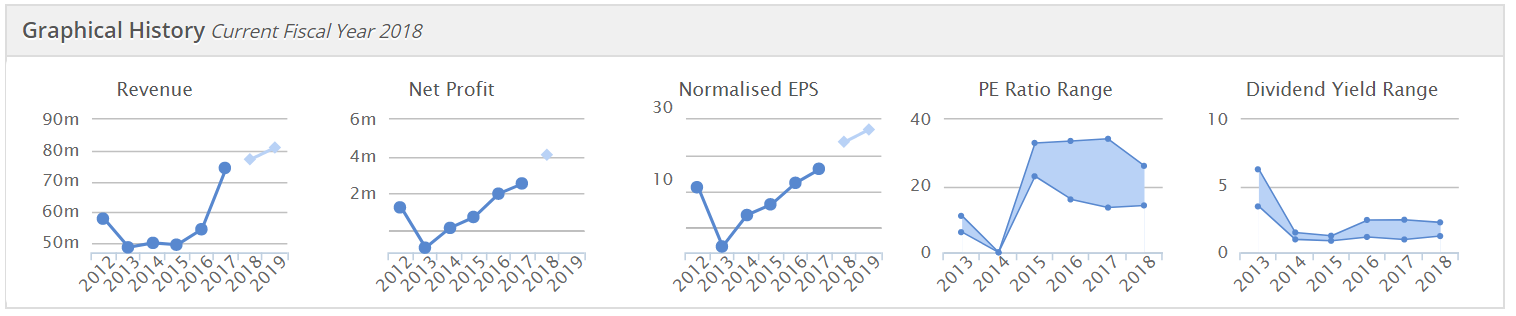
Broker comments - One broker this morning has kept their forecasts unchanged, at 23.8p EPS for 06/2018, and 27.2p for 06/2019. It says that the update today provides a reasonable level of visibility for the full year.
My opinion - I hold a few of these in my personal portfolio, and may use any further price weakness to top up.
This to me looks like a quite nice GARP share (growth at reasonable price). The shares have rallied strongly since an unusual, and unjustified dip in Sep 2017. In my view it's reasonably priced, and worth a closer look.
Quarto Inc (LON:QRT)
Share price: 122.5p (down 16.4% today)
No. shares: 19.7m
Market cap: £24.1m
Trading update (profit warning) - bad luck to holders of this illustrated book publishing company. This piles more misery onto shareholders after previous profit warnings. I reported on its profit warning on 4 Jul 2017 here. Then there was a spike up on news of a potential bid for the company, which fell through in Aug 2017.
What's gone wrong today then? This relates to the current financial year, ending 31 Dec 2017.
Strong publishing list drives solid H2 trading performance to more than recover the H1 loss but will not be enough to meet Board expectations for full year profits.
This is a very heavily H2 weighted seasonal business, so more than recovering the H1 loss is an absolute must.
It gets worse;
Full year adjusted profit before tax now expected to be significantly lower than Board expectations.
That leaves us in the dark. Why can't they just give an estimated range of PBT expectations? I've sought out a broker update, which just says that they're withdrawing estimates, and working on revised figures.
Unfortunately, that leaves me in a position where I cannot value the share.
Looking back at the interim results, they were awful - an adjusted loss before tax of $8.7m (prior year loss of $1.6m). So it looks to me as if this year may not be much above breakeven? The current forecasts look way too high, so that's why the forward PER of 2.51 shown on the Stock Report is a red herring. That PER will go up considerably when revised, more realistic forecasts flow through.
Dividends - sensibly, the company has decided to cancel any final dividend. This makes complete sense. The company tried very hard to continue paying generous divis, but that really isn't realistic any more. This could trigger an exodus from the share, from people holding it for income? With debt very high, I wouldn't expect divis to resume any time soon, unless there's a dramatic improvement in financial results next year or beyond.
Net debt -
Year-end net debt expected to be lower than net debt at 30 June 2017 [Paul: $75.8m] but to increase year on year. [Paul: $61.9m at 31 Dec 2016]
I think it would be sensible to try to find out what the position is wrt bank covenants. Nothing is said in today's announcement about that, but it could be a risk.
The Directorspeak suggests to me that a placing could be on the cards, to strengthen the balance sheet & reduce debt?
"In 2018 we have two clear objectives - more granular asset management particularly in our Adults publishing portfolio, brought about by enhanced financial systems and control, as well as looking at all options to reduce our debt and strengthen the balance sheet."
My opinion - as I've repeatedly said here before, over several years, the indebted balance sheet is the deal-breaker for me. I think there's a quite good business here, but personally I wouldn't touch it unless & until the balance sheet is strengthened considerably with fresh equity.
Gattaca (LON:GATC)
Share price: 309p (down 0.3% today)
No. shares: 31.6m
Market cap: £97.6m
(at the time of writing, I hold a long position in this share)
Preliminary results - for the year ended 31 Jul 2017. This company is;
... the specialist Engineering and Technology (IT & Telecoms) recruitment solutions business
Underlying diluted EPS has come in at 34.3p, which seems to be slightly ahead of 33.8p broker consensus. Although I'm not sure whether the broker consensus figure is basic, or diluted (which makes 1.0p difference to EPS). This is a PER of 9.0
Note that EPS is 22% down on last year, so things are not going particularly well.
Divis - this is the main reason to hold this share. Pleasingly, the generous payout is maintained, at 17.0p final, giving 23.0p for the full year - a yield of 7.4% . The fact that the divis are static, not increasing, suggests that the company might be struggling a little to maintain the payout - increasing the risk that it might be cut in future, if trading deteriorates further.
Net debt has risen from £25.0m a year ago, to £40.3m. This looks a bit too high to me. Although with recruitment businesses debt is par for the course - to fund the big receivables book (debtors). In this case debtors is huge, at £115.0m, so actually having net debt of £40.3m is fine in that context.
Balance sheet overall is fine.
NTAV is £32.9m.
Working capital - the current ratio of 1.85 looks very healthy, although note that there are also £26.0m in non-current liabilities. So if we move them into current liabilities, then the current ratio including all liabilities would be a still-healthy 1.32 .
Therefore there are absolutely no worries with this balance sheet, or the level of debt. I saw some commentary a while back arguing that the company was dangerously over-geared. That was wrong, because the writer had not looked at the balance sheet as a whole.
Outlook - light on specifics, but sounds generally positive;
We will continue to position the Group to maximise growth opportunities both in the UK and internationally. We believe the investments we have made during the year, will deliver good returns in 2018 and beyond. We are now well placed strategically to take advantage of the increasing convergence between the engineering, IT and telecoms skill sets, and to grasp the opportunities presented by infrastructure investment commitments around the world, particularly those made by the UK and US Governments.
While we continue to monitor uncertainty in the wider economy, we will invest selectively in strengthening the business to support our medium and longer-term performance.
They've been saying that kind of stuff for a while, and it hasn't paid off yet.
My opinion - whether you like this share really depends on your macro view. Personally I see bumpy, but not catastrophic times ahead. We'll muddle through with Brexit, and a wobbly Government, probably.
Therefore, for me, I'm happy to hold for the generous divis. Although if the economy does go into a proper recession, then I'd want to exit from this probably.
Devro (LON:DVO)
Share price: 239.5p (down 0.5% today)
No. shares: 166.9m
Market cap: £399.7m
Trading update - readers have asked me to look at this update. The company calls itself;
... one of the world's leading manufacturers of collagen products for the food industry
Looking at Devro's website, the products page is all sausages - Devro makes the sausage skins it seems.
The company has a 31 Dec year end, so it's updating today on Q3 performance. Things sound fine;
Trading for the period was in line with the Board's expectations, with total sales volumes ahead of the equivalent period last year, continuing the momentum delivered in H1...
The Board's expectations for the year ending 31 December 2017 remain unchanged.
Cost savings are going to plan.
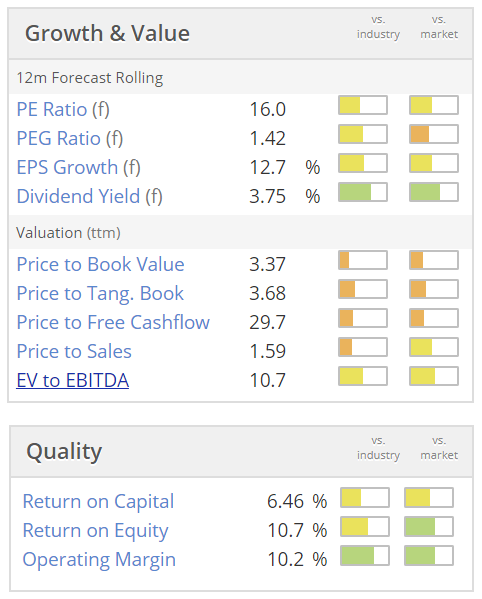
Valuation - looks reasonable, in a frothy market;
My opinion - I don't really have an opinion on this. It looks quite a capital-intensive business, and looking back at the history, something seems to have gone wrong in 2014, and the overall record of EPS is not very good;
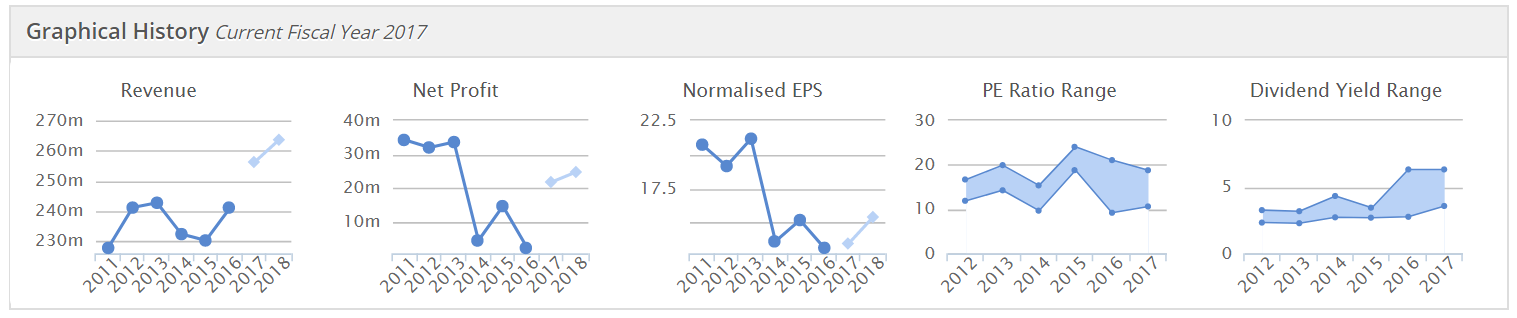
On an admittedly very superficial look, I can't really see what the attraction is here? Brokers are forecasting 14.4% EPS growth in 2018, which is respectable (if the company achieves it). The PER on 2018 forecasts is 15.7 - which looks about right. Divis of 3.7% are reasonable.
Is there something more exciting in the pipeline that I've missed? I assume the company will face a lot of competition for what seems a fairly generic product. So my worry would be that its margins might be eroded over time. It's not for me.
Tracsis (LON:TRCS) - CEO/CFO interview
I put yours & my questions to the CEO & CFO of Tracsis today. Here is the link to the audio recording (apologies for the background beeping). They sounds pretty happy about how the year ended, and the prospects for the future.
I reviewed the accounts for y/e 31 Jul 2017 in yesterday's SCVR here.
I'll probably have to leave it there for today, due to needing to prepare for my CEO interview with Tracsis (LON:TRCS) imminently, then travelling to London. If I can grab some time later today to add some more, brief comments, then I will do.
Graham will be looking after you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Regarding debt and as a follow up on the comments from Ramridge and Damian I note from the stock report that Devro's debt is about 5 times forecast pretax profits to end December. On this basis alone I would steer well clear.
Devro (LON:DVO) also has a pension deficit, I agree I would stay well clear.
With regard to Quarto QRT, it's as well to observe that it's in an industry suffering from declining sales.
Many of its peers over the past few years of this bull market have share price performances that have been disappointing.
It's seems difficult to make money here, a good example being Jon Moulton's Better Capital BCAP purchase of Reader's Digest in 2010 for £14M, the subsequent investment of £9M and its sale in 2014 for £1. IMO any business that puts ink on paper is nowadays swimming against a very strong tide.
Four key sentences there.
1. At the current level of business (without any further growth) we'll hit the target.
2. But it's not out of the question that something could wrong.
3. But if growth continues as it has been we'll beat the target.
4. We'll let you know when we pretty much have all of the numbers together.
I wonder if their business is really that unpredictable in the short term or whether they are being overly reticent? As I understand it a certain "leading global consumer electronics company" seems to be pretty bullish about things.
I know what you mean. I would suggest though that it's not so out-of-place to be cautious - some companies are as they want to cover themselves just in case. As they say, it is also early in the quarter. They presumably do expect and are reasonably confident that the demand from the "leading global consumer electronics company" will increase, but feel it's inappropriate to guide for that outright because based on the actual rate of orders received so far they are only heading for "in line". So in my opinion they are probably being what you call "overly reticent" rather than anything to worry about.
I read it differently, as 'uncertainties' referring to upside risk. So I read it as them saying they would hit expectations as a minimum but with a decent chance of a beat. I think it's a bit disingenuous to claim it's "early into the final quarter" given that we are nearly half way through it, so I think they will have a pretty good idea of the final outturn for the year relative to market expectations. A steep ramp up in VCSEL activity isn't suddenly going to reverse itself in the remaining 7 weeks of the year.
I actually tend to agree with Gromley's interpretation. If the uncertainties refer to the potential upside beat then it wouldn't make sense that the upside potential is only referred to in the next paragraph and begins with "However". Although I still think the update is not so unreasonable as I mentioned in post #34.
I think the issue around the "steep ramp up" is not that they are so worried that present levels will reduce (although to be cautious they don't want to exclude it). Their main point is that it may continue to improve further in which case the results would be ahead, and about that prospect they are more cautious as it is just a projection of an increase from current levels based on the assumption that since it has been increasing it will probably increase further. This is inherently somewhat uncertain.
Taken literally, I agree that the word 'however' tends to support yours and Gromley's interpretation, but given the mood music from their customers and everything else we know about their markets right now, I just think it makes more sense to read 'however' as 'therefore'.
The VCSEL ramp is a broad secular trend. They wouldn't be splurging on all this capex and doing the placing at all if there was a material risk of that trend suddenly reversing.
IQE (LON:IQE) are doing a placing at the market price of 140p, they want to raise £95m for investment. Sounds interesting. Presumably they are confident they can raise the funds and I would imagine this will draw more attention to the company and its potential. (I hold). The company says:
Rationale for the Placing and use of proceeds
IQE is seeking funding to enable it to scale the business to capture multiple high growth mass market opportunities.
This placing will allow IQE to expand its capital expenditure programme in its new foundry, with the purchase of up to 40-60 new MOCVD machines over the next three to five years.
The additional capacity should enable IQE to address multiple mass market opportunities, including its leading position in the production of VCSEL wafers for use in 3D sensing consumer electronic applications.
IQE is enjoying material demand for its VCSEL wafers from a leading global consumer electronics company for use in one of its mass market consumer products. In conjunction with multiple other customer engagements IQE expects this demand to increase as its technology is applied across multiple consumer applications and platforms.
This placing should also enable IQE to accelerate the development of new products and technology; whilst protecting and enhancing its current positioning in a fast-moving marketplace.
This placing will allow the company to de-gear and should enhance IQE's financial strength and ability to supply global Tier 1 OEMs; both existing and new customers.
This placing in conjunction with the "Cardiff City Deal" should allow IQE to generate incremental sales.
Current trading
On 20 October, IQE confirmed that it had enjoyed a strong Q3 with continuing growth driven largely by the ongoing strong VCSEL ramp for a mass market 3D sensing technology.
The Board remains confident that at current trading levels, the Company is on track to achieve market expectations. Given it remains early into the final quarter, there are inevitably a number of uncertainties between now and the year-end close.
However, should the VCSEL ramp continue along its current growth curve during this quarter, then there is potential for FY17 earnings to exceed current expectations. The Board will continue to monitor current trading and plans to provide a pre-close trading update no later than the end of the year.
Interesting RNS from IQE (LON:IQE) about a placing. Would be great to your thoughts on this, Paul or Graham
Quarto Inc (LON:QRT) Also is in NAPS 2017. I generally agree with that rule but prefer no debt, sometimes I make the odd exception such as Rentokil Initial (LON:RTO) last year.
Re. Quarto Inc (LON:QRT) One of Robbie Burns hard and fast rule is never to invest in a company where the ratio net debt/ profits exceeds 3.
If you look at this ratio for Quarto over the past 3 years, it has been around 4. A clear and strong red flag.
I think its one of Lord Lee's investments.
Yes Quarto Inc (LON:QRT) is still listed as one of Lord Lee's. http://www.parliament.uk/biographies/lords/lord-lee-of-trafford/1132/register-of-interests
Sounds like a fine rule. Normally I stick with companies that are net cash or nearly so. It's surprising how many companies are in this happy state...
That and the chart being in a clear downtrend...
Quarto Inc (LON:QRT) is definitely an object lesson in selling on the first profit warning. I bought twice about a year ago (at 299.5p and 318.5p) as things seemed to be heading in the right direction. Sold everything in March at 257p for a 17% loss. If I sold now that would be a whopping 61% loss! Lucky escape. However it looks like my second buy was literally at the top of the market. There must be some sort of lesson there. :-)
Damian
Hi Paul,
I used the Stocko compare facility for Swallowfield (LON:SWL) and Creightons (LON:CRL) and on the vast majority of metrics Creightons came out the better. Do you have a view on the respective merits of the two companies,
Thanks, Dave
Hi Dave,
The trouble is that there aren't any forecasts for Creightons (LON:CRL) - so Stockopedia isn't able to compare the most important numbers - forecast earnings growth, forecast PER, etc.
On the historic figures, CRL does indeed come out best when compared with SWL, but CRL is a bit too small & illiquid for my taste. The 03/2017 figures for Creightons were excellent, I covered them positively here.
Regards, Paul.
Sorry to go off at a large cap tangent but having read the results RNS from Burberry (LON:BRBY) this morning before the open I was left bemused by the share price reaction. The results looked great with 4% LFL growth and very good cash generation.
Unfortunately, I didn't see the the new CEO's manifesto in a separate RNS - Lord help us! Burberry are going to give up growing because they will stop selling stuff to Chavs from retail outlets. The world must officially be coming to an end :) Not good in the short term but probably a good thing for the brand in the long term. I'll probably buy some more along the way...
All the best, Si
Generally speaking, I like to invest in companies that have good and sustainable growth in both revenue and profit (that is cash-generative in the long-term). I don't see how DVO is capable of achieving significant growth in what IMHO is an unexciting product market. Looking at H1 2017, it looks like much of the revenue growth was down to exchange gains, but pre-ex operating profit was almost static while both pre-tax profit and eps were down and the dividend was unchanged. To me it looks a pretty dull investment proposal.
Re QRT, I think this is a prime example of profit warnings occurring in multiples!
I wonder why, despite saying what the final div will be, Gattaca have not stated when the exdiv date is, normally around mid November? Is this at all significant?
Thankyou Paul and daveinthelakes for your comments, I bought in this morning, it looks like a game changer for city, hopefully it is .
And MWE looks interesting.
Hi Paul
Hope you enjoy your busy day. I'd be very interested in your views on Eagle Eye, if you can find the time. On the plus side - it looks to be growing very fast with plenty of big contracts and new contracts with tier 1 clients (google, Sainsburys, Mitchells & Butler...). But, it is still very much loss making and expensive too. My temptation would be to follow Minervini on this one and hold off until momentum and volume confirm that it is being picked up by the institutions. Or maybe put a toe in just to keep it in full view.
Thanks as always.
Hi paul could you look at cityfibre, link up with vodafone. Thankyou in advance.
Hi frank341,
I only really cover trading updates & results statements in these reports, and occasionally other things.
So I'll be happy to look at results from Cityfibre when they are published, but their contract announcement today is not something that I can add any value to. You're best off trying to track down some broker research comments on it. To point you in the right direction, there are 2 new broker notes this morning, available to subscribers of Research Tree, from Liberum & FinnCap.
Regards, Paul.
Hi Frank,
I watched the Leon Boros video last night and amongst other wise advice he said do not sell if the investment case has not changed. How prophetic that CityFibre Infrastructure Holdings (LON:CITY) made the announcement this morning as having bought around a year ago at 52p and doubled up at 42p when the price collapsed a few months back I sold over 60% of my holding at 49p a couple of weeks ago.
I was influenced by the negativity in the market highlighted by Numis producing a very downbeat analysis and a price target of 30p. My view on the company had not changed but I bottled it!
However Mr Boros also says do not be afraid of reinvesting at a higher price if you realise that you may have made a mistake. I have just added to my holding.
The Vodafone announcement is the game changer. This provides the certainty of the base revenue stream for the CityFibre Infrastructure Holdings (LON:CITY) fibre roll out which it already has the cash to pay for. The point is Vodofone only gets exclusivity to market for a period up to and shortly after construction. City can then sell to the market and this at a gross profit of around 85%.
As a rule I hate investment in providers of new infrastructure but faster fibre is the future, supported by Government initiatives with an almost guaranteed take up providing long term highly profitable revenue streams. City got it's current main inter city fibre routes on the cheap off KCOM (LON:KCOM) who didn't have the vision to see the goldmine they were sat on. At the time this was viewed by the market as a great deal for the vendor but I saw it as an even better deal for City.
Have we missed out following the 25% share price increase today? I don't think so because the company raised £200M in an institutional placing four months ago at 55p ie the current share price.
We may have to wait two or three years for the profit streams to flow but I have now decided to put these away and ignore the market noise. I think there is a fair chance that a foreign infrastructure provider or private equity will bid for the company. I do not hold for this reason but it will always be there in the background.
Good luck if you hold or decide to invest, Dave
Morning!
I'm really pushed for time today (have a CEO interview to do at lunchtime, then have to jump on a train to London).
As regards reader requests above;
Swallowfield (LON:SWL) - yes I will report on this
Devro (LON:DVO) - I'll try, but it it might have to be this evening
Gattaca (LON:GATC) - yes I'll cover this one
MTI Wireless Edge (LON:MWE) - looks rather small, and is overseas/AIM, so low priority - will cover it if I can find time
Flybe (LON:FLYB) - crappy business, so low priority. Will try to find time, but won't be until this evening, if at all.
Others I will try to fit in;
Quarto Inc (LON:QRT) another profit warning
Wincanton (LON:WIN)
Prime People (LON:PRP)
Eagle Eye Solutions (LON:EYE)
Lookers (LON:LOOK)
Right, I'll crack on & see how far I get by lunchtime! No large cap preamble today, as there isn't time.
Regards, Paul.
Supergroup's closing update looks fine to me. Why do you think the market doesn't like it? I hope you'll comment in line with your usual practice on big clothing retailers
I agree that the SuperGroup (LON:SGP) update looks good. One potential negative I'm seeing is the decline in gross margin mostly driven by the sales mix including more wholesale but also some input price pressures.
It's had a good run up in the last six weeks so perhaps there is some profit taking but I'll continue to hold.
To me it looks as though SGP have seen quite a drop in LFL growth between Q1 and Q2...? Perhaps this is the reason for the fall - as you say, they've had a good run recently.
Hi Paul. Time permitting - would it be possible for you to look at Gattaca (LON:GATC) and Flybe (LON:FLYB)
Thanks,
Ben
Gattaca (LON:GATC) results are inline with the mild profit warning issued at the end of the period. Weighted outlook reads as negative to me. Dividend maintained, but given declining profits I think it should be cut to reduce debt, which would of course remove the main reason for holding. Medium term performance has been poor, there are worries about the contracting (self-employed) market and we may be near a peak in the labour market.
Things aren't much worse that when I bought in May, but I no longer understand what I was thinking at the time. Therefore I have sold at a small loss.
Following on from Paul's excellent point about Gattaca (LON:GATC) debtors, this should mean that if revenue continues to decline then working capital will be released which provides a very good measure of protection. Contrast with car dealerships where if new sales decline then this causes a nasty cash outflow as VAT due on sales exceeds VAT reclaims on new stock (the cars are effectively lent by the manufacturers), or if a retail concept stops rolling-out the reverse lease premiums stop.
Having delved into their accounts further (in particular, note 19) I understand Gattaca (LON:GATC) have an invoice factoring facility at 1.1% over base and with £50m of headroom. Their overall rate is about 2% over base (in theory and practice). All good, as Paul said.
Having delved into their accounts further (in particular, note 19) I understand Gattaca (LON:GATC) have an invoice factoring facility at 1.1% over base and with £50m of headroom. Their overall rate is about 2% over base (in theory and practice). All good, as Paul said.
The main problem with Gattaca (LON:GATC) that is not shown in the accounts is that the management are just not very good. They keep making acquisitions that do not add any shareholder value. Contrast the performance of the company with similar listed recruiters, and the fact is, they are poor. I don't believe their excuses, it's probably just that they are being outperformed by the competition.
All the best, Si
Morning Paul!
Time permitting, wondering if you could look at the following...
£SWL
AGM Statement – Trading in the first 4 months of the year is in-line with expectations. Generally expecting to maintain positive progress and deliver against expectations for the full year. Quite like the look of this and its on my Watchlist around the 300p area.
£MWE
Results For The 9 Months Ended September 2017 – Slightly below my usual Mkt Cap but this just caught my eye this morning. YoY Revenue up 12% ($19.6m), PBT up 54% ($1.2m), EPS up 47% (1.63 US cents) and Cash at end September 2017 was $5.35m. On a PER of 10.8 this looks like decent value here - I have started opening an initial long position here this morning.
Thanks in advance!
Quite a few to review today. If you have time, please could you take a look at Devro (LON:DVO) who issued an in line trading statement this morning. Not sure what to make of this share. Strong M and decent Q so overall a good stock rank but seems very highly leveraged which is compounded by a large pension deficit.
Thanks.
gus,
Devro (LON:DVO) I used to hold a quite a few going back perhaps 15 yrs but they were serial disappointers so I sold out at 187p in March. Had I not sold could have got a bit more now and it remains on my watch list. I am afraid that I have not reviewed the numbers recently, was tempted because I thought the fall was terminal and yet it continues upward. But FWIW this is one not to be holding when the music stops, well I had problems in March selling into a rising market. I would be interested in a forensic snapshot of where they are today.
Regards,
Seadoc
Edit, I mean that I think we are near a peak in the market as a whole, not specifically Devro (LON:DVO) . and I am looking to sell almost anything that I think could bomb in next sell-off.
Thanks for the feedback on Devro (LON:DVO) Seadoc. I wasn't aware of the thin market issues (it has a reasonable market cap at £400m+) but it came up on one of my screens as a possible shorting candidate (like you I'm mildly bearish and thinking about opportunities to look at if there is a sell off) due to the very high leverage which I found hard to reconcile with the decent Q score. I'll be interested to hear Paul's view if he has time.
Gus.
My morning smallcap tweet:
Countrywide (LON:CWD), Quarto Inc (LON:QRT), Agriterra (LON:AGTA), St Peter Port Capital (LON:SPPC), Independent News & Media (LON:INM), Prime People (LON:PRP), £FLY
Countrywide (CWD) Q3 rev down 7%. Guides FY towards lower end of forecasts. I'm short.
Quarto (QRT) FY trading. Warns rev down YoY. Adj pretax sig. lower than board exp.
Agriterra (AGTA) FD resigns but stays as non exec!
St Peter Port Capital (SPPC) Conclusion of Strategic Review - no viable offers received. Will "continue to seek opportunities to realise its investments in its remaining assets in an orderly manner."
Independent News & Media (INM) warns material reduction in expected FY pretax. Blames challenging market conditions and "higher once [sic] off legal costs, than previously envisaged."
Prime People (PRP) to buy back up to 300k shares. Starts 20 Nov.
Flybe Group (FLYB) H1 adj pretax £8.4m (£15.9m) "largely due to the previously announced one-off onerous IT contract provision and the impact of increased aircraft maintenance costs. This adjusted profit before tax is towards the upper end of the range of £5m to £10m [guidance]." Q3 sales continue to be encouraging with rev up 9%. Outlook: "The European aviation market continues to be challenging, with many airlines impacted by excess seat capacity in the short-haul market, a weaker pound and both business and consumer uncertainty. Within this market, the Board believes that Flybe offers a differentiated regional business model and has clear plans to deliver a sustainable profitable future helped by the plans to reduce capacity and cost."