Small Cap Value Report (Thur 11 June 2020) - CMCX, OTMP, CHH, MIND

Good morning!
Graham here. Paul is taking a long weekend for his birthday.
Markets continue to act in all sorts of surprising ways - the NASDAQ has returned to all-time highs and the FTSE climbed back to 6500 as of Monday before retreating 300 points (6200 in the futures as I type).
Reflecting the uncertainty, the Volatility Index (VIX) has found strength again and is now around 30 - a historically very high level, although we've been much higher than that in 2020.
I hope you are all managing to navigate these conditions - it's not easy! I have taken the 'easy' option of trading virtually not at all, and simply watching the value of my accounts gyrate.
Today I'm looking at:
- CMC Markets (LON:CMCX)
- Onthemarket (LON:OTMP)
- Churchill China (LON:CHH)
- Mind Gym (LON:MIND)
Finished c. 2pm.
CMC Markets (LON:CMCX)
- Share price: 217.5p (+9%)
- No. of shares: 289.1 million
- Market cap: £628 million
Spread betting companies are a very lazy way to invest - compared to having an active spread bet account.
Why bother with all that trading, when you can sit back and make money from everybody else's trading?
Why bother trying to make money in blackjack and poker, when you can simply own the casino?
I should have held on to the CMC shares I bought last year. The share price has more than doubled since.
Instead, I focused on my shareholding in IG Group (LON:IGG) - one of my top 5 holdings. IG is in my view likely to be the lowest-risk share in the spreadbet industry, with CMC coming in at second place.
This entire industry has enjoyed a bizarre windfall from the Covid-19 pandemic. Government lockdown policies crashed the Western economies which in turn sparked stock market chaos and drove traders (both old and young) to churn their accounts like never before.
Let's see how CMC did for FY March 2021:
- net operating income +93% to £252 million
- PBT explodes to £98.7 million
- EPS explodes to 30p
It almost sounds too good to be true, and I am nervous that it is.
Last year, as flagged in my analysis of CMC's interim results, the company changed its risk management strategy.
Risk management at spread bet companies should be simple, in my view: client trades should be hedged by default, except where the exposure is so small as to be immaterial.
IG Group (LON:IGG) does that, and it publishes a chart every year showing the residual market risk (almost zero).
Plus500 (LON:PLUS) doesn't do that. That's why, a few days ago, it reported that its customers had made $150 million at its expense.
In November, CMC announced that it was now hedging less often, leaving only a "significant" amount of risk hedged with its prime brokers.
This decision was made, according to CMC itself, because of the collapse in trading activity after strict leverage limits on retail traders were imposed by the EU regulator, ESMA.
The November report disclosed that retail client trading activity had reduced to just 30%-40% of previous levels.
My fear is that CMC decided to take on a somewhat riskier business model, as a way to make up for the business that was crushed by the leverage limits.
From today's update. I have added the bold:
Following implementation of ESMA regulations, which resulted in a material change in client trade duration, the Group refined its risk management strategies in the final months of our prior financial year. As a consequence, this year the Group internalised more client flow than previously, particularly in the more highly traded and liquid instruments, which resulted in lower hedge costs.
The change increased the daily revenue ranges and market risk exposure, which was supported by the Group's strong regulatory capital ratio, and yielded higher net trading revenue
It's there in black and white: increased market risk exposure. It would help if it quantified this (e.g. by telling us what percentage of risk is unhedged, or gave us the daily revenue range).
But investors can't complain that they haven't been warned.
CMC has been honest. It is hedging less, it has more market risk, and it now has a wider daily revenue range.
This is the context in which we need to understand the near doubling of CFD net trading revenue (to £214.5 million), despite CFD gross client income increasing by only 11% (to £240.6 million).
Net trading revenue includes "risk management gains and losses", while gross client income does not.
CMC describes this result as "greater retention of client income".
You can see it in this chart from the Analyst Presentation. You can see net trading revenue jump sharply, despite only a modest increase in gross income:
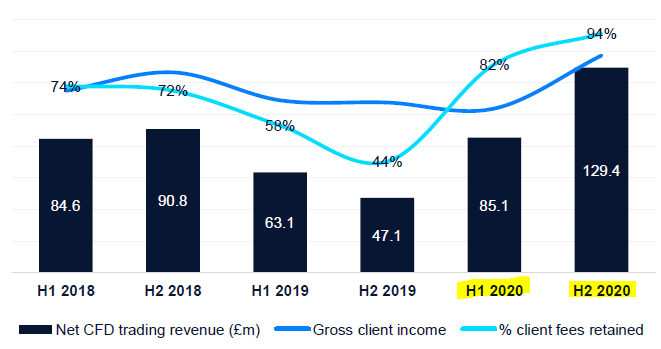
In this presentation, we learn that Hedging costs declined from £35.6 million in 2019 to just £23.3 million in 2020.
And "Risk Management Gains/Losses" swung from a £49.5 million loss to a £13.7 million profit.
That's a good thing. But what I really want to know is what sort of a loss CMC could face, if its customers made winning bets? I think it's safe to presume they could win a lot more, at the expense of CMC, than they could before.
To me, there are only two possible explanations. Either CMC's previous hedging strategy was very expensive and wasteful, or its current hedging strategy is very risky.
I really, really hope that it's the former, not the latter.
In the Risk Management section, CMC says that its team runs stress scenarios on their "residual portfolio", modelling various market movements and how they would affect the company. Why not simply hedge?
Balance sheet - taking a leaf out of Plus500's book, CMC points to its strong balance sheet as a justification for taking on market risk exposure.
Equity is £382 million, of which cash and broker balances add up to nearly £220 million.
Similarly, the company's "own funds" (its primary liquidity source) have bounced sharply higher to £238 million.
Client moneys are segregated and held separately.
The minimum capital requirement is £81 million, so there is indeed plenty of headroom above that.
My view
There are very impressive results but I am now firmer in my belief that CMC is appreciably riskier than IG.
I would still doubt that CMC's riskiness has reached the level of Plus500 - CEO Peter Cruddas, owning 57% of CMC, has too much to lose.
OnTheMarket
- Share price: 57p (+8.6%)
- No. of shares: 71.2 million
- Market cap: £40.5 million
Final Results to 31 January 2020
It's not often that myself and Paul end up on opposite sides of the exact same trade. But Paul has been short of Rightmove (LON:RMV) in recent months (I'm long) and had a long position on OTMP (I've been sceptical about this one for years).
See the comments thread, the last time OTMP was discussed.
OnTheMarket IPO'd at 165p in early 2018, and I've been consistently worried about the business model.
The basic idea is to bribe estate agents to use the portal, by giving them lots of free OTMP shares.
Great for the estate agents, but not so great for other OTMP shareholders.
In the end, it's the general public who will determine the winner. As of FY January 2020, Rightmove's market share of viewing time was 75% (2019: 76%, 2020: 73%).
Long-term, I imagine that there will continue to be space for two profitable property portals. If anybody should be worried about OnTheMarket, perhaps it is Zoopla.
FY January 2020
OnTheMarket has generated a 32% revenue increase and reduced losses:
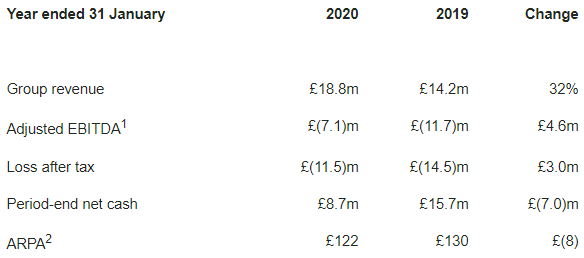
As you can see, the cash balance has dwindled to £8.7 million, down £7 million on the year despite equity issuance during the period. A further equity raise appears likely.
KPIs
- Traffic (measured by site visits) up 49% to 237 million.
- Average monthly leads per advertiser up 75% to 96
- Branches on paid contracts are now 9,000 as of May, up from 8,000 as of January.
There should be good scope for further revenue growth this year, from contracts signed during the previous year.
The consensus forecast is that revenue will hit £27 - £28 million in FY January 2020, but I don't think this reflects the impact of the pandemic.
Trading update
February and early March was in line with expectations, pre-lockdown. The property market was then effectively suspended.
From May 11th, there was some recovery in traffic and instructions.
The good news is that traffic in the first week of June was up 15% versus the first week of March. And new instructions are now back at early March levels.
The key takeaway is that we have a quick recovery to pre-Covid activity levels.
Outlook
There is no guidance - not very helpful, but this is a common stance taken by companies.
Agent recruitment has been slowed down by the pandemic, and revenues have been hit by a 33% discount offered to agents from April (for three months).
Finishing on an optimistic note:
"...the recent uplift in activity, which reflects increased brand awareness, is encouraging and we remain confident that we have the right strategy to support our longer-term vision to become the portal of choice for agent customers and property-seekers alike,"
CEO
Remember that the CEO got the boot in March, very abruptly, without any proper explanation being given.
The acting CEO (formerly CFO) remains in charge.
My view
I don't see any reason to change my view on this today.
There is some improvement in the financial performance, and I do expect that it will continue to improve, but at the end of the day, I'm not sure if there is space for a third mass market property portal.
If there isn't, then it will have to topple Rightmove or Zoopla - not exactly an easy task.
And from a shareholder perspective, I think that dilution could be heavy - not just on an ongoing basis to get agents to sign up, but also because the existing cash balance looks a bit thin, relative to recent losses and its growth ambitions. It might not immediately be forced to raise, but it might want to raise. Pedestrian growth using its now rather limited resources will hardly satisfy anyone.
Churchill China
- Share price: 1068p (-3.3%)
- No. of shares: 11 million
- Market cap: £117 million
This is a "manufacturer of innovative performance ceramic products serving hospitality markets worldwide".
Its customers have been smashed by the lockdown policies, and its share price has duly halved (vs. February levels).
It confirms today that trading in April and May was "well below normal levels".
Furthermore, CHH guides that monthly revenues will "remain below 2019 levels for some time as hospitality market activity re-adjusts".
This is despite European markets re-opening (with restrictions) and the UK beginning its exit from lockdown.
There will be an unknown number of redundancies (you can find the number of employees on the StockReport - at CHH there are over 600).
We have commenced a process to adjust costs across our business consistent with these lower levels of activity and as such we have entered into a consultation period with our employees in relation to the potential reduction in the size of our workforce.
There is not much else of interest in this statement.
My view
It's rare that a good company becomes a bad company overnight. I doubt that it has happened, in this case.
Net cash at year-end (Dec 2019) was an encouraging £15.6 million, and cash generation was healthy.
Unfortunately, the company hasn't quantified the impact on trading so far, there is no guidance, and forecasting is pretty much impossible.
Gross margins
I wanted to look into the company's operating leverage, to hazard a guess at possible outcomes, but neither Churchill nor Portmeirion (LON:PMP) publishes gross margins. Which makes it even trickier to do the operating leverage calculation.
At least we know that the final operating profit margin was very good last year, at 17%. This does provide a baseline margin of safety, so that small revenue declines won't automatically lead to large losses.
The revenue decline is unlikely to be small, of course.
I'm inclined to think that by cutting costs (e.g. via the redundancies, and elsewhere), and using its cash balance if necessary, Churchill will be able to navigate this difficult period and come through in good shape on the other side.
It's just very hard to do any calculations right now. At times like this, we are left with guesswork and instincts.
Mind Gym
- Share price: 105p (-8.7%)
- No. of shares: 99 million
- Market cap: £104 million
Full year results for the year ended 31 March 2020
This training business joined AIM in 2018.
Pre-pandemic, the shares were around 200. So it's another one whose valuation has roughly halved.
Today's results show revenue of £48 million (up 15%), of which "digitally enabled revenue" (yuk!) is £14.5 million.
That means 70% of revenue wasn't digital, and therefore I guess has complications in a socially-distanced world.
The company discloses that 40% of pre-Covid revenues were from live, face-to-face sessions.
Pre-tax profit for the year came in at £7.4 million (+44%).
Covid-19 impact:
Mind Gym's clients were thrown into crisis mode as entire industries slowed down and like so many others we were confronted with a sudden drop in revenue.
Staff have accepted reduced hours, salary cuts, and a few have been furloughed.
"People-related overheads" have been reduced by 19%.
The company notes that some salaries for the digital development team will be capitalised, not expensed - this will require monitoring.
Dividend - not happening. But balance sheet cash is impressive at £16 million.
Outlook:
Despite the short-term impact of COVID-19 and an unsurprisingly slow start to the year, the Group is well positioned to respond to the new market needs.
My view
This probably suffers from many of the same uncertainties afflicting the hospitality/leisure industry.
But unlike a rollercoaster ride or a relaxing hotel stay, at least it is possible to get training online. Mind Gym has other ways to sell and deliver its expertise.
This one could be worth researching in greater detail.
I'm out of time there, thanks everyone. See you tomorrow!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
The On the Market website is a bit of a cheap knock-off the Rightmove site. It is puzzling why it should be so unappealing, there are many quick fixes it could make, and it should seek to differentiate itself a bit. Any agent that made the brave jump to ditching Rightmove would save money in the short-run but in the long run lose money as people get dissatisfied with their visibility stats. If there was an industry-wide pact, this could work but I feel it is way to much dog-eat-dog for that type of co-operation.
I do believe there could be room for disruption, basically Rightmove has changed little in the last 10+ years. The network effect means that getting agents on board gets easier if you get the buyers on board. But how would that happen? Maybe people could be incentivised. None of the portals have built any form of community, which could be really powerful. A site combining Rightmove, Houzz (interior design), CheckaTrade, conveyancing services would have some synergies between them.
Yet I feel Rightmove has become a cash cow, simply returning profits instead of seeking to build their moat further. That's not necessarily a bad thing and is ideal for certain types of shareholders.
But could an innovation be replicable without them copying it? It seems unlikely.
OldFitMan, your argument that 90% of clients lose 90% of their account in 90 days could be correct (At least for private clients) but I suspect that a good proportion of Cmc Markets (LON:CMCX) clients are simply hedging rather than trading. In which case, why should they be any more likely to make a profit than someone taking out an insurance policy?
Regarding the debate between Onthemarket (LON:OTMP) and Rightmove (LON:RMV) Stephen English is negative on the latter in his webinar with Tamzin - the Who will be the losers? section starting 39:29 in.
https://www.piworld.co.uk/2020/04/10/stephen-english-webinar-a-plague-on-all-our-houses-how-to-repair-some-of-the-damage/
He cites the website:
https://www.saynotorightmove.co.uk/
re Onthemarket (LON:OTMP) - the upside case here is all about risk:reward. The business is growing, and can dial its marketing spend up or down, in fact most of its costs are variable. Therefore, it can continue growing without being forced to raise funds. I think it probably will raise more funds at some point, to accelerate growth, once it has a new CEO. That's why I have held back on buying more shares in OTMP, it's only a small, entry level position for me.
I wish we knew why the old CEO left, he seemed a safe pair of hands to me, but something obviously went wrong behind the scenes.
Going back to risk:reward, if OTMP does manage to topple Rightmove, then this share could be a 100-bagger. So even if you think that there's a more than 1% chance of this happening, it justifies having a punt on the shares.
Remember that Rightmove is hated by its customers, since it price gouges them, making absurdly high profits. Therefore it stands to reason that estate agents would jump at the chance to usurp Rightmove with their own portal, and OTMP is majority earned by estate agents. I think it's surprising this hasn't happened yet. IF it does, then OTMP likely becomes a a big multibagger. That's the attraction of the £40m mkt cap, which could potentially become billions.
Hence I recognise it's speculative, but the upside potential is so large, I think it's worth a punt.
Regards, Paul.
When we used to go into a pub many months ago, and order a coke for the driver. It's expected that the cola drink you are given is Coca Cola. Other Cola based drinks are available but I think you'd be put out with "Nobby's Cola" on your glass. Same thing with RMV.
I am a regular property investor and RMV is my 1st port of call. There are a few skinflint agents who insist on using Zoopla, but I don't have the time to use a 3rd and a 4th provider. I know that anything that I'm likely to be interested in will be on that.
I'm not defending RMV.....far from it. They just don't seem to like their customers, but I can't see OTB seriuosly challenging.
Thats a fair assessment but if you rewind 10 + years or so, who would have thought there would be room for 2 extra supermarkets competing with Tesco, Sainsbury's, Morrisions & Asda?
Even though their margins are wafer thin, the shrewd Germans have come along and taken even more market share.
Brands and trusted names are a powerful thing, but so is heard mentality. No one likes being the first to try some thing, but once there is a following, they can catch on pretty quickly.
I see the upside here, maybe one to tuck away long term, but for that to happen management really needs to crack why estate agents should change to them, I am not sure manipulating them with shares will win long term. But one ill start watching this one more closely.
That's not a good analogy. You're comparing supermarkets who operate physical locations, to property portals online.
This is why Google, Apple, Facebook, LinkedIn, Amazon, eBay.... all online marketplaces... have dominant positions. Unlike supermarkets where its almost impossible to get 60%, 70% of a market.
Why? Because people are only willing to travel X miles for supermarket shopping. But there's no such concept of "distance" in online - everyone can access a website, easily. So it is a very much winner takes all in online.
Hi Paul - "it stands to reason that estate agents would jump at the chance to usurp Rightmove with their own portal, and OTMP is majority earned by estate agents. I think it's surprising this hasn't happened yet."
I expect the reason estate agents are proving v.slow to shift from Rightmove to OTMP despite hating the former is that their customers like/love it and have never heard of OTMP. If estate agents tell all their potential customers that their house is going to be marketed on a site they never heard of, rather than the one they are undoubtedly using themselves to search for their new house (i.e. Rightmove) - they might end up with no houses to sell rather rapidly... I own neither so no pony in this race.
Cheers
Steve
thanks
The results from 1spatial (LON:SPA) today should be reassuring for shareholders. The acquisition seems to have gone well, the turnaround is said to be complete, they are confident in their financial position and have a "strong" but unquantified order book (forward guidance withheld). The Chairman, Andy Roberts (ex TIG) is a competent manager in my opinion, and significant director share purchases at 21p in early April give me some confidence.
(no position, but on my watchlist)
Graham: " Why not simply hedge?"
It makes sense that CMC Markets (LON:CMCX) are looking at the residual portfolio rather than hedging every trade. If they didn'y they would be throwing away money. They must pay bid/offer on their hedges so every time they do it, they reduce margin. It also makes sense that they would partially match related trades, so for example, they would nett off individual stock trades against index exposure, stock index exposure against interest rates, or maybe gold stocks against gold bullion trades, or sterling long and short against different currencies (not just the same one). There are obvious ways of doing this that any of us could tell them about and I'm sure there are more intelligent ways that they don't want to talk about. Trouble is, if they don't talk about it, we can't be sure.
So, simply hedging every trade would be sub optimal and I wouldn't want them to do that, or even get close to that. But I would share your concern about how far they take this. We can be sure that, at some times, clients will be overall winners.
Also: great analysis Graham, insightful and concise.
Thats not hedging though is it? You're still leaving basis risk, e.g by hedging gold stocks with bullion.
Thanks cmpeckham. I totally agree that it's not necessary to hedge every single trade. There are so many ways to manage risk.
I just hope they aren't trying to be too "smart", and don't get too used to the idea that clients can't trade well! Cheers. G
CMCX - great analysis Graham. The way that you decode the way the results are written makes them so much easier to understand
Yes - Look historically for a rush to shave beards and brick up windows when both (Bizarrely ) were hit with a "windfall" tax
Really interested to hear what you have to say on Churchill China (LON:CHH) as it seems a strong company that is just waiting for the lockdown to ease across Europe which we are beginning to see. It has already started right-sizing the business which must be a good thing.
Really interested to hear what you have to say on Churchill China (LON:CHH) as it seems a strong company that is just waiting for the lockdown to ease across Europe which we are beginning to see. It has already started right-sizing the business which must be a good thing.
Not really sure the AGM statement said anything to be honest - no numbers whatsoever. Although for such a well run and conservative company to be considering redundancies would tell me things are pretty dire and will likely extend beyond the government furlough period. NB. we are now approaching the time when any company looking beyond the furlough scheme will have to start considering layoffs.
I guess we'll have to wait for the trading update at start of July to see some numbers but given they recently mentioned costs had been reduced to less than £1m per month and they had £15m of cash in the bank, for them to be considering layoffs, things must be pretty grim.
All the best, Si
Thank you - very clear
worth a read investment managers take on lockdown - blue planet monthly report
bryaz. A link to the report would be helpful.
The fund produced a total return of +11.3% during the month of April against the benchmarks +3.9%.
When so-called medical “experts”, led by Neil Ferguson, once again came forecasting death on an apocalyptic scale, just as they did with
BSE, Aids, Ebola, SARs, Swine Flu, Asian Flu and MERS, all of which turned out to be greatly exaggerated and whereas in the past their
predictions have been treated with scepticism, largely because on every occasion they have been proven wrong, this time gullible
politicians fell hook line and sinker for their prophecies of doom. Essentially, they faced two simple choices:
1) let the virus run its course, as has been customary up until now, and provide the necessary resources to the health service to deal with
it. That would have had little, if any, impact on financial markets, the economy, jobs, civil liberties, the public finances/government debt
and our children's education and future prospects.The economy would have remained strong and growing, well able to fund any extra care
required for the very small subset of the population that was at risk from covid-19, or;
2) Shut down the economy. Wipe trillions of dollars off people’s savings. Spread undue panic throughout the population, creating its own
problems for the NHS and lasting damage to our economy. Throw millions of people out of work. Destroy very large numbers of
businesses, large and small alike, in every sector of our economy that have taken years to build. Introduce martial law, stripping citizens of
their most basic civil liberties and effectively imprisoning them in their homes. Deny our children their education. Deny seriously ill
patients, such as those suffering from cancer and heart disease, the medical care they need and deter others who need care from
attending A&E. Borrow gigantic sums of money to try and mitigate the wholly unnecessary and self-inflicted economic damage done by
those policies, at a time when public sector debt is already at irresponsibly high levels and the tax burden is at a 50 year high. Additional
debt that will require very large cuts to public services and yet more tax rises to service it, which will further reduce our already anaemic
rate of economic growth, burden our children with a mountain of debt to pay off and severely damage their future prospects.
Our politicians chose option 2. Undoubtedly, the dumbest most damaging decision ever taken by a Conservative government.
Not a single person need have lost their job, not a single company need have been forced into bankruptcy, not a single child need have
been deprived of its education or its future prospects, not a single penny need have been added to the national debt, no tax rises or cuts
to public services would have been required and no one need have been stripped of their civil liberties had our country been run by
intelligent, able people. Sadly, it is not and the full extent of the damage done by gullible and utterly incompetent politicians is going to
become all too apparent in the coming months. They have destroyed millions of people's livelihoods and future prospects, although most
don't yet know it, for a ludicrously exaggerated and largely unreal threat. We are now, as a result of their stupidity, barrelling towards an
economic catastrophe and the wholesale collapse of entire sectors of our economy, including car manufacturing, airlines, restaurants, oil
exploration and development, retail shopping, cafes, bars, hotels, theme parks, entertainment, housing, shopping malls, airline
manufacturing and quite possibly our banks as bad debts skyrocket. If ever there was a time to rethink how we select the people to run
our economy it is now. We need a system based on merit that ensures only our best, properly qualified and most able people get to do so
and that excludes virtually all current politicians.
Concerning the CFD companies and spread betters.
I do not understand why the government effectively subsidises the CFD companies by not charging clients who use them stamp duty. It would raise more money for the government if stamp duty was reduced to 1/2% and levied on all share trades whether CFD or not. This would also be beneficial to most punters as they would be much safer with most stockbrokers.
It seems to me that the tax subsidy the government gives to the CFD industry is like encouraging people with a drink problem not to go to the pub where people might keep an eye on their alcohol consumption and into a crack house where they can obliterate themselves in private.
Surely it would just stop people using CFD's at all so less stamp duty would be collected. I don't know what the average buyer does with a CFD but I would have thought many would be looking at very quick trades for small margins and duty of 0.5% would kill it. Not really CFD's but my son traded in currencies and a trade could be held for seconds and I wonder if some may trade CFD's similarly.
I understand that CFDs don't attract stamp duty, because the buyer does not own the shares - they enter into a contract to exchange the difference in the price of shares.
Also, it would only apply to shares. FX is currency - not taxable - stamp or capital gains - people would just to spread betting or a different product.
There is enough government / institutional interference in the function of markets and the economy (to the detriment of both in my humble opinion) and it is getting enhanced by the day.
If the government needs more tax, I suggest they just increase tax rates as opposed to trying to play all these games, where anyone reasonably informed will be able to avoid the tax.
I dare say, high tax rates with a bunch of deductions or the use of transaction taxes just make the tax system regressive
HMRC can try to tax FX as trading gains if carried on in a significant manner. In fact, there was one case where the trader having lost a lot of money argued in Court that it was trading in his particular case which he won and was able to set the losses against his other substantial income! There are many arguments that can be put forward for and against treatment as trading by both by HMRC and the trader. Clearly, as you say, no stamp duty applies which if it did would make such trading impossible.
I was under the impression that because it is classified as legal tender, it is not taxable. Then again a market maker doesn't pay stamp duty but pays tax on profits/deducts losses (although I don't think that extends to currencies).
Guess they can always change the rules based on which assets Dominic Cummings decides to trade. :D
There are a lot of things to take into account but just one point, if it is your main activity and you are making money you can expect HMRC to say it is taxable. If it is just a few trades before you go to work then it is not likely to be taxable. So a market maker with an organisation trading in currencies would certainly be taxable. If you lose money, of course, HMRC will say you are not carrying on a business of trading in currencies!
There is no practical difference between owning 1000 shares of Vodafone and a CFD for 1000 Vodafone shares.
CFDs were invented to avoid tax and that is what they continue to be used for.
Whether there is a practical difference or not, there is a legal difference and that matters for tax purposes. You still pay income and capital gains tax. If the objective is to avoid tax, I suggest using a spread bet, unless you are trying to make losses to protect gains elsewhere.
Leveraged products in general and CFDs are very useful and cost effective risk management tools. They serve that purpose for those who choose to use them as such. Hold IGG
Just as a minor point, I don't believe that you pay income tax on CFDs. As I understand it, dividend adjustments to CFDs are regarded as a capital adjustment rather than income, and hence the CFD is only potentially liable for capital gains tax when sold, never income tax.
Of course I am a layman not a tax expert and may be wrong, but this is my understanding of the situation after looking into it for my own interest.
that makes sense - your trade is based on change in capital value, and this is an adjustment for the capital value - as per stamp duty, you didn't purchase the shares so didn't receive the dividend.
If you wanted Vodafone shares to hold I think you would buy the shares and pay the stamp duty. If you wanted to hold them for a very short period for a small potential profit then you may decide to use a cfd or the completely tax free spread bet. There must be a vast number of transactions that would not take place with a stamp duty charge.
I doing know if you've seen what is happening in the US where there is no stamp duty. Some brokers have gone for zero transaction fees which has led to an explosion in day trading of penny stocks, including some that have said they are going into bankruptcy like Hertz. Others use the options market which seems more developed than over here.
I don't get the human psyche - remove a $10 fee, I am willing to risk thousands of $ . Guess if Sir Isaac Newton struggled with the madness of men, what chance us mere mortals!
I sincerely hope I am not one of the people I denounce!
I guess it encourages small trades in penny stocks. A lot of CFDs are small trades too.
Boo!
All investing is done on already pre-taxed funds, and then the profits are taxed too.
There's too much taxation and government meddling in peoples' lives already.
Apart from Flutter who have the leading sports betting exchange in Betfair I do not see what the competitive edge is between either the various spreadbetting firms CMC,IG ,Plus etc or between the gambling companies GVC,William Hill etc
On a personal level I have to say a lot of online gambling firms have either closed my betting account down with them or reduced my ability to place bets with them to very small stakes. because their software has clearly identified me as someone who places my bets with whichever firm is offering the best odds or have special offers
When John652 writes GVC has an excellent business model i'd say it is a short term too greedy by half business model relying on having an endless supply of mug or desperate punters as clients.
It is terrible PR and the original founders of the gambling firms Cyril Stein ,William Hill ,Victor Chandler etc would be turning in their graves as to what has been done to their firms..They were originally gamblers themselves who understood the spirit of gaming markets.Todays gambling executives are to quote Oscar Wilde 'accountants who know the price of everything but the value of nothing'
Personally I have found the privately owned firms bet365 and Betfred to be much more customer friendly and I would urge recreational punters to place their bets with private listed companies rather listed gambling companies (unless of course they own shares in a listed company)
I’m also wary of regulation for the likes of IG Group (LON:IGG) and Plus500 (LON:PLUS) and the gambling stocks such as GVC Holdings (LON:GVC), i think they have excellent business models, and for GVC Holdings (LON:GVC) etc the sports betting opportunity in the US is huge but... we have just had the worlds governments shutdown the economy, the ‘capitalist’ engine of functioning society, be it for the right reasons or not, i think the risk for these stocks & tobacco etc has grown enormously.
Given big state had no issues locking us all in and creating a subsequent economic, social and health crisis i see it a very small step to smash gambling, tobbaco, sugar companies for ‘your own good’ . With the general state of fear in the population that is likely to have a long residual tail, how much opposition would there be? Easy target for tax revenue, and my gaud will they need it ( or maybe G20 c19 perpetual zero coupon bonds, say 10 Trillion should do it).
I digress, so for me they are all, as single stock investments, off the list unfortunately. I did weigh up IG Group (LON:IGG) & CMC Markets (LON:CMCX) but to be a proper hedge id need say 20% in and that was just too much, so good stocks for now, but the £ commitment for a hedge & reg risk doesn't work for me.
..." i see it a very small step to smash gambling, tobbaco, sugar companies for ‘your own good’"
The government netted £2.9 billion in gambling duties during 2017/18.
https://www.casino.co.uk/guides/gambling-and-taxation/
Hi
..." i see it a very small step to smash gambling, tobbaco, sugar companies for ‘your own good’"
The government netted £2.9 billion in gambling duties during 2017/18.
Smash them as in now its £6 billion of tax
For those not following, California voted two days ago on whether to allow sports betting in the State. This is expected to be a huge market and bigger than all of Europe combined. The Covid issue has decimated tax take and billions of revenue per year is thought possible in future years. A lot of "under the counter" sports betting takes place in the State but with no tax being collected.
The vote was passed and now proceeds to a second stage next Thursday and there is likely to be a lot of discussion and debate before then. If that is confirmed and there is no guarantee of that, then there is a public ballot in November. If passed then I suspect nearly all of the US states will vote similar. The potential for spread betting and betting companies in general over the next few years in the US is stunning .....but there are some major hurdles yet before the legislation is all in place.
I don't know who the potential listed winners might be of this. Companies will need a licence to operate and these may be restricted. Tiny market cap company Webis Holding (LON:WEB) has a licence as it operates a racetrack in California and huge resources as it is majority owned by a holding company with billionaire investor Jim Mellon at the helm. It is a very risky and highly volatile stock at the moment as you might imagine with only a small public float (disclosure: I hold WEB). I do wonder if BET365 could list in the US later this year if the California vote is yes.
Remarkable how CMC and IG continue to boom, when supposedly the bulk of clients lose money - i.e. higher levels of turnover should if the claim/theory is correct, hasten their departure/demise, and a revenue slump in due course. Barring fresh victims recruited, of course.
"Barring fresh victims recruited, of course. "
If you take a look at the US you will see that growth of new participants into the market is a little mind blowing. According to Bloomberg, small trader call buying made up more than 50% of total volume last week, the highest since 2000
These traders are probably still ahead, which of course further encourages new entrants. It has all the hallmarks of a speculative bubble – but who knows when it will end.
If you are interested in in a humorous and informed take on the new American lockdown pastime of leveraged speculation, then it’s worth giving Matt Levine a read. It might require a Bloomberg subscription; otherwise you can get his email.
Its the old 90/90 senario. 90percent blow their account in 90 days. Most of the money for these firms seems to rely on FX wannabe traders chasing the dream and online course guru sellers recommending their systems, so that there is an ongoing stream of "clients" coming forward.
There are a few videos on YouTube covering how it all works and it is the CFD scandal 2 in the making. The companies make more money on the lossing clients than the profitable ones due to capital holdings they have to take out on positions.
think Bookmakers ??
Same scenario
Cmc Markets (LON:CMCX) full-year results
With CMC Markets reporting today, what is next for this online financial trading company.
YTD both Cmc Markets (LON:CMCX) and Ig Group (LON:IGG) have acted as a useful hedge against turbulent markets, with FY2020 revenue growth of 93% and 32% and share price growth of 36% and 10% respectively. This recent growth only recovers revenues to the long-term growth trend. (see below graph). The dip in 2019 was due to New UK and EU regulation to protect retail investors/traders. With markets still uncertain does Cmc Markets (LON:CMCX) and Ig Group (LON:IGG) have further to go?
I suspect revenue growth is strongest during and just after recessions for these two companies. I have included IG Group numbers after the last recession, suggesting double-digit growth for quite a few years after the last recession. (Sorry no numbers for CMC Markets pre-2011)
IG Group (2008-2013)
CMCX valuation
Assuming growth will continue (7%), my valuation model suggests Cmc Markets (LON:CMCX) & Ig Group (LON:IGG) has the potential to re-rated over the next few years and provided a useful hedge if markets remain unstable. (see graph below)
Note (I have long positions for both Cmc Markets (LON:CMCX) and Ig Group (LON:IGG))
As always DYOR.
Assuming growth will continue (7%), my valuation model suggests Cmc Markets (LON:CMCX) & Ig Group (LON:IGG) has the potential to re-rated over the next few years and provided a useful hedge if markets remain unstable. (see graph below)
I also hold both. With the ever present risk of further regulation they're unlikely to rerate hugely. But while markets are volatile they're a very good place to keep your cash.
Thing to watch out for is the hedging policy - Plus500 (LON:PLUS) got caught out by this, as flagged in their recent announcement: they don't hedge and their customers guessed right.
timarr
"With the ever present risk of further regulation"
"Thing to watch out for is the hedging policy"
I'm always surprised the regulator hasn't stepped in and mandated the firms hold near 100% hedging positions, so they don't have any incentive for their customers to lose, rather they need them to survive, keep trading and earn spread commission.
I suspect if this was in place, their sites would transform with position and risk mgt tools, similar to what a prop trading firm does with its traders, to stop people blowing up their accounts.
I do not follow these stocks. But I would be surprised if the high % of clients who lose money is predominantly because they make bad bets (i.e. that the reverse bet would have been profitable). I would assume it is much more likely due to clients overtrading - and paying high bid-offer spreads as well as the high finance charges.
Hi Timarr,
Yes, I agree with everything you say. That's why I have a preference for Cmc Markets (LON:CMCX) and Ig Group (LON:IGG) as they do hedge client positions to some degree and are not dependent on clients losing money.
I like both IG Group (LON:IGG) and CMC Markets (LON:CMCX).
I think the probability of another round of regulation is low. They've just been through a massive amount of regulation and re-writing of the rules. Surely human nature of the regulators will lead them to step back and admire their work for a decent period of time (10 years would be nice) rather than be hugely self critical, admit their mistakes and get back involved.
Add to that that the government is probably relieved to see at least a few companies in the economy thriving and making a profit - it will help the tax take to fund the Covid bills.
I think the probability of another round of regulation is low. They've just been through a massive amount of regulation and re-writing of the rules. Surely human nature of the regulators will lead them to step back and admire their work for a decent period of time (10 years would be nice) rather than be hugely self critical, admit their mistakes and get back involved.
That was just Europe. Both Australia and the Bahamas are expcted to annnounce new regulations on CFDs this year.
timarr
Fair enough. But there is a good chance that they will take their lead from UK/Europe and implement similar measures. I think both CMC Markets (LON:CMCX) and IG Group (LON:IGG) have proved competent at dealing with regulation changes.
Thing to watch out for is the hedging policy - Plus500 (LON:PLUS) got caught out by this, as flagged in their recent announcement: they don't hedge and their customers guessed right.
Is this correct? I have always assumed that they hedge but not exactly. For example if a customer goes long on a FTSE 100 company, they would buy long FTSE100 index. The spread on the individual company is much larger than the spread on the index hence where they scrape their margin. However there is always the risk that the individual company does not follow the index and so is not a perfect hedge, so herein lies the risk. Over the long term this risk tends to zero (as born out by Plus500 (LON:PLUS) stating that over 6 years their trading gain/loss has been 1%) but over a 3 month quarter, the hedging gain/loss can be large. In Q1, they made a $82M trading gain and in 9 wks of Q2 they made a 146M trading loss. Over the entire year, the trading gain/loss will probably be small.
cmcx also fste250 candiate in september or top of reserve list?!
The results video presentations on Ig Group (LON:IGG) website are worth watching. In particular (as a holder) I would highlight that they are investing very heavily in geographical growth and providing brokerage services, ISA’s, etc so IMHO not the one trick pony people sometimes appear to suggest.
Almost bought Churchill China (LON:CHH) yesterday but price was falling slighly so I left it... Interesting to see what happens today - I might get a better price...
My morning smallcap tweet: Angling for cash
Angling Direct (LON:ANG) McBride (LON:MCB) Churchill China (LON:CHH) ADES International Holding (LON:ADES) Share (LON:SHRE) Open Orphan (LON:ORPH) Diaceutics (LON:DXRX) Brave Bison (LON:BBSN) Woodbois (LON:WBI) 1Spatial (LON:SPA) R.E.A Holdings (LON:RE.) Cohort (LON:CHRT)
Angling Direct (ANG) £5.5m placing at 50p, a 15.3% discount. Needed for working cap, balance sheet and possible acqusitions.
McBride (MCB) CEO scarpers, replaced by CFO. He is thanked.
Churchill China (CHH) AGM stmt. Expects mkt recovery but still expects overall monthly revenues to remain down for some time. Possible job losses.
ADES International (ADES) Q1(Mar) rev up 22%. Guides FY EBITDA flat.
Share (SHRE) FCA approves takeover.
Open Orphan (ORPH) major contract with a leading vaccine developer "to obtain and support market access of newly developed vaccines into the EU and US markets until the end of 2020." Not sure what that means.
Diaceutics (DXRX) £20.5m placing at 145p, a 1.4% premium. "Will strengthen the balance sheet in readiness for new growth opportunities."
Brave Bison (BBSN) CEO scarpers, replaced by chmn as exec chmn. She is thanked.
Woodbois (WBI) recommenced some harvesting in Gabon but sawmill & factory still idle. Talks with lenders to restructure debt.
1Spatial (SPA) FY(Jan) rev slightly up on guidance at £23.4m. EPS -1.37 (-1.65[cont]). Current trading in line.
R E A (RE.) FY(May) harvest yp 7%. Covid-19 has not had a significant negative effect on the operations. Crude Palm Oil price bounced from low of $510/T to $595/T.
Cohort (CHRT) wins €7.5m contract for Air Guard Counter-Unmanned Aerial Systems.
CMCX gave a very uplifting trading update. Awaiting your view on it in anticipation Graham
those cmcx results are pretty much caused by the march just gone with covid even 2 months of market madness will see better results for 2020, summer fallout?