Small Cap Value Report (Thur 13 September 2018) - FTSE, SCH, DPEU

Good morning!
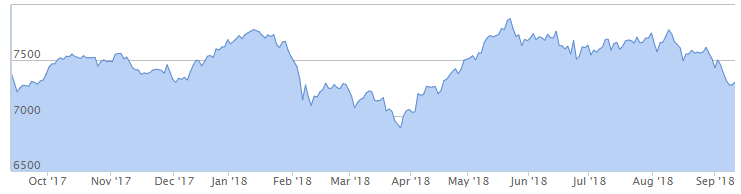
While I was away, the FTSE (UKX) dropped by 2% in a week. That will teach me!
The biggest faller was WPP (LON:WPP), which had a profit warning. Other big fallers were Ocado (LON:OCDO) and Just Eat (LON:JE.), and most of the big mining companies.
Mainstream media has been pointing out that the index is now around its five-month lows.
Taking a slightly longer timeframe, we can see that it basically hasn't gone anywhere over the past year (before dividends):
in currency terms, GBP has at last found some strength over the past few weeks. That is perhaps the most obvious headwind to explain the recent weakness. But it only partly explains the move.
Buying opportunity? This situation has certainly caught my attention. As regular readers will know, I am short FTSE puts. I am committed to buy a decent chunk of shares at 6,000 if the FTSE falls below that level by next March.
Aside from that reason, there are also a few tempting shares in the big-cap space to look at. British American Tobacco (LON:BATS) for example (where I already hold a long position) has been extremely weak and I am thinking about increasing my position size in it. I also have more highly rated companies like Unilever (LON:ULVR) and Experian (LON:EXPN) on the watchlist. Unfortunately, their share prices have remained very strong.
In some ways, it could be argued that the FTSE going flat for a while is a benign situation.
For those people who are worried about a general overvaluation, it gives the market a chance to grow into its valuation. And it does that without causing any of the panic you get with a very sharp sell-off. Instead of panic, it merely causes boredom and melancholy among the impatient.
And for people like myself who are buying equities from time to time, it means we still have lots of opportunities.
I've noticed a really mixed bag in terms of sentiment expressed on twitter and in casual conversations this year. Investors I've spoken to are happy with a flat or small gain this year, given the soggy performance of the index. It's completely different to last year, when lots of people said that investing had been made easy!
Away from the FTSE, the AIM All-Share Index (AXX) has outperformed the big-cap indices.
I do question the usefulness of this index when it comes to measuring small-cap and micro-cap performance. It includes ASOS (LON:ASC), Fevertree Drinks (LON:FEVR) and Burford Capital (LON:BUR) - these collectively are worth about £13 billion and dwarf the vast majority of other constituents.
As far as my own portfolio performance is concerned, with a mix of big-caps and small-caps, the total return year to date for my top equity holdings is as follows. They've done much better as a group than my smaller holdings:
- Burberry (LON:BRBY): 19%
- Volvere (LON:VLE): 5.5%
- H & T (LON:HAT): minus 4%
- PCF (LON:PCF): 48%
- United Carpets (LON:UCG): minus 9%
- IG Group (LON:IGG): 22%
- Creightons (LON:CRL): 20% (purchased in Feb, March & June 2018)
I don't know what the aggregate portfolio performance is at this stage, but I know I'm satisfied with how these companies are doing.
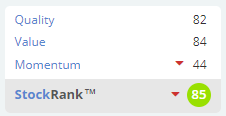
Indeed the main point of weakness among my top holdings, H & T (LON:HAT), is a stock where I've been seriously considering adding to it at current levels.
It gets a big thumbs up from the StockRanks, too:
In summary: we have a soggy main market index, which is nice for those of us who are net buyers.
As I've said before, I don't consider current valuation levels in the UK to be extreme, as long as the FTSE is within a 7000-7500 range. We have a forecast P/E ratio of 13.3x and a forecast dividend yield of 3.7%.
The thing to do then, as always, is try to drown out the noise and find some good companies.
I hate this phrase, but it's a truism, so I'll say it anyway since it applies:
"this is a stock picker's market!"
SafeCharge International (LON:SCH)
- Share price: 319.6p (+5%)
- No. of shares: 148 million
- Market cap: £473 million
This isn't one we usually cover here. It was mentioned in the comments, so I thought I'd give it a quick look.
SafeCharge (AIM: SCH), a leading payments technology company, is pleased to announce its interim results for the six months ended 30 June 2018.
One of the first things I do when I look at a company for the first time is check its historical share count. This lets me immediately categorise it as financially stable (share count is flat), mature (share count is falling) or growing/speculative (share count is rising).
SafeCharge's share count has been flat, and its revenues have been rising every year. It has been profitable most years, though the path of profitability has been irregular.
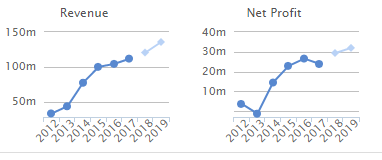
This gives us some context with which to look at today's results.
- revenue growth +26%
- adjusted EBITDA +15% (this is framed as "excellent" but why doesn't it at least match revenue growth?)
- net income falls marginally to $11.9 million (this is after some currency effects. Profit from operations increased to $13.8 million.)
Operationally, signs are positive as processed volume is up by a whopping 59% to $6.7 billion. The CEO says "we are only at the beginning of our journey".
Outlook - it's in line with market expectations, with revenue at the top end of expectations.
Location - one curiosity is the company's location. The address is given as Guerney. Fair enough, but where are the employees (of which there are nearly 400)? I believe the management team is in Israel, and its website shows office locations around the world (London, Hong Kong, USA, etc).
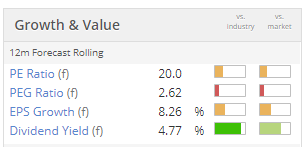
The above-average P/E rating says that investors trust the company. A hefty dividend doesn't hurt in this regard (and it's being increased by 15% today):
The core of the business is a payments platform offering a complete payments solution for merchants, and compatibility with other technologies they might like to connect to it.
This type of product is not to easy for the average Joe to test, compared with a consumer-facing product (e.g. we all have direct experience of PayPal ($PYPL), and know when we are using it).
As recommended by a reader in the comments thread, I have looked for user reviews for SafeCharge. Here is a page showing a mix of comments, including five reviews from 2018. The overall score is 7.5/10.
Scalability - this word is music to investors' ears. SafeCharge's platform can allegedly accommodate transaction volumes 10x greater than it currently processes. This could mean huge operational gearing, as increased revenues could be achieved without much additional capex.
In the short-term, however, EBITDA margin weakened and this was attributed to lower gross margins (as the company entered new markets and focused on lower-risk customers, who presumably have greater negotiating power?) and on recruitment for sales and marketing.
My view - it looks solid, it sounds promising. I wouldn't mind holding a few shares in this.
We aren't short of companies offering payment solutions, however. I wonder how we might predict which ones will win in the end, or even in the medium-term?
Though I'm a fan of the financial sector, I typically invest in lenders and other types of investors. Lending is a predictable activity with predictable returns (some of the time).
This stock falls instead into the fintech category, that hybrid category halfway between financials and technology. The rewards are huge for those who succeed (PayPal) but it's a fast-moving sector which is tough on those who fail. Reaching critical mass is key.
Besides the difficulty of predicting who will win, this sector has also been (in my opinion) the recipient of vast quantities of speculative money in recent years.
I'll keep an eye on this share, although I'm unlikely to buy it at current levels.
DP Eurasia NV (LON:DPEU)
- Share price: 89.45p (+3%)
- No. of shares: 145 million
- Market cap: £130 million
(Please note that I hold DPEU shares.)
There's not much else I want to talk about from today's RNS, so here's a story from Tuesday.
The share price for this Domino's Pizza business has approximately halved since I first covered it - in July!
It's my worst performing share. In total, it has fallen by more than 50% since I purchased it a year ago.
My July article summed things up as follows:
There's a lot that could go wrong, either with execution of its strategies or with the macro/political situation in the countries in which it operates.
A war of words between Trump and Turkey is what happened, tariffs were increased by both countries, and the Turkish lira collapsed in value.
A year ago, a British pound was worth about 4.5 Lira. Today, it is worth 8 Lira.
It's a disaster in terms of the value of DPEU's Turkey earnings. That country is where DPEU's business is considered mature.
Micro vs Macro
Leaving the macro picture to one side, DPEU is doing reasonably well. The market responded well to Tuesday's results.
The outlook for full-year adjusted EBITDA is in line with expectations.
Some highlights:
- revenues up 32%
- adjusted EBITDA up 8% to 40 million Lira, or GBP 5 million. Held back by central overhead growth and recruitment for growth in Russia (where food sales were up almost 70%)
- online sales increased from 50% to 59% of total sales
- like-for-like growth of 10.9% in Turkey and 18% in Russia (we already knew this from the trading update)
The performance in terms of operating profit is disappointing: it reduces slightly to 15 million Lira (approx £2 million).
Below that line in the income statement, foreign exchange losses and higher interest costs in Turkey contributed to a meaningful deterioration in PBT, from breakeven to a 10 million Lira loss.
Flipping back to the macro, I note that the Turkish central bank has increased interest rates today by 625 basis points (!) to 24% (!).
That means DPEU needs to avoid borrowing in Lira. It has refinanced most of its debt from Euros to Russian Roubles.
It also means we might be due for a correction in the value of the Lira. If the Lira somehow recovered to its previous levels, with the help of a 24% interest rate, and if DPEU continued to perform roughly in line with expectations, then perhaps the DPEU share price is due for recovery? A man can dream!
The CEO has reassured investors that prices are being increased to customers in Turkey, and this is not having any noticeable impact on volumes. He continued:
Historically, the business has been relatively robust in challenging economic conditions... This is my third such experience at the helm of DP Eurasia during a difficult macroeconomic environment in Turkey and on each previous occasion we have come through stronger relative to the competition due to our market leadership position, focus on value and service to the customer and resilient franchise partners.
My view
Ever since buying into this company, I've known it was my riskiest position. Not much has changed, except I guess this has been proven to be correct (sadly!)
I'm planning to hang on to it, partly out of stubbornness. But if I hadn't bought it a year ago, and was looking at it today, I think I would have the same positive reasons to buy into it now (with the discount in the share price being adequate compensation for volatility in the Lira).
It's probably beyond the risk tolerance of most investors, even for a small position. And I can easily sympathise with that perspective.
Calling it a day there. Thanks for dropping by!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Graham, I bet you wished you used a stop loss on DP Eurasia NV (LON:DPEU) :P
Well it's easy to determine which positions need a stop loss in hindsight! You'd need to work out how Graham's entire portfolio would have done with a given stop loss to determine whether he'd have been better off with or without, not one individual holding.
Thanks for your review of SafeCharge International (LON:SCH) Graham, it is one I hold a modest amount of (c3% folio position). I have a couple of things to add which might provide some additional colour.
1. The reduction in margin is a result of the company de-risking away from over reliance on the gambling sector, from which it was borne.
2. There is a dominant shareholder situation. Overall, this adds an element of risk, including low liquidity (although volatility is not high).
My personal view is that the endgame here will be a takeover as part of industry consolidation (they have had sufficient cash to be an acquirer for a while but I think that boat has sailed), the price of which will be determined by the dominant shareholder. I wouldn’t want overweight exposure but with a decent yield, it has held its own in my folio for a couple of years now.
Cheers
Simon
SafeCharge International (LON:SCH) The dominant shareholder is said to be Teddy Sagi through Northenstar Investments, with 67+%. I can't find proof of this as Northenstar doesn't list directors on Bloomberg, but Sagi founded or was one of the founders of SafeCharge International (LON:SCH), and was in control of the company in the past.
Sagi has a criminal record, and has served time for securities fraud/bribery/deceit.
There was a period in Playtech (LON:PTEC) 's history, before Sagi's stake was reduced to 6ish%, that Playtech was buying Sagi's startups.There were serious questions at the time concerning the prices Playtech (LON:PTEC) was paying for these companies.
Rumour has it that during the attempt by Playtech (LON:PTEC) to buy Plus500 (LON:PLUS), UK regulators were concerned about Sagi being in control of the combined group.
There was some questionable behaviour involved with the Playtech (LON:PTEC) / William Hill (LON:WMH) joint venture.
Do google 'Teddy Sagi fraud' , etc., so that you can make an informed decision. My comments are based on articles read on the web; I can't vouch for the accuracy of anything above, but the sources are normally reliable (FT, etc.).
[disclosure- a tiny recent long position in PTEC]
From the Safecharge website:
http://investors.safecharge.co...
timarr
Graham,
I hold two from your portfolio:
Volvere (LON:VLE) - currently my largest holding, and have held for 8+ years now, without top-slicing or topping-up.
Duke Royalty (LON:DUKE) - a recent purchase (Jun 18) and have a note to top-up when/if I think it's worthwhile.
The one surprising (to me) holding of yours is Distil (LON:DIS) . Seems to be very diversified in comparison to your 'folio. It has been on and off my watch list. I suppose many people enjoy a beverage (stock?) ! lol. I wonder if Wetherspoon cutting/replacing their European-based drinks would benefit non-Euros (Distil perhaps ?).
I've not long pruned my folio (to 17 stocks), and have 3 main categories:
1) Top - 5 shares accounting for 53%
2) Middle - 8 shares for 37%
3) Punts - 4 shares for 7% - This area is where the pruning took part, else would have been 15 shares for 16% !
Leaving 3% for cash.
Market caps range from £2.8m (one of the punts) to £2.7b (a bank that's likely to be sold when/if funds needed). The average Market Cap over the 17 stocks is exactly £500m !
Hi Graham,
Time allowing, would appreciate if you could take a look at Medica (LON:MGP) half year results out yesterday.
If I remember, on your last look, you were quite positive about the company.
My personal view - high quality business with a solid balance sheet (assuming goodwill carrying value is not impaired) and given it represents some 37% of the capital base, and the company generates roughly 25% ROC (assuming last 6 months doubles), I would suggest it is fair.
The not so good - revenue growth seems to be slowing - roughly 18m generated in H2 17 and 18.6m in H1 18, which would imply revenue run rate is not growing.
They note in the financials reduced gross margin (due to lower prices from increased competition and stingy trust) - and results support that with "transaction" volume growing faster than revenue and.
I guess a 50% gross and 20 - 25% operating margin is going to attract competition and if I read correctly, they do not expect it to impact operating margin.
My worry is more that they do not seem to be growing customer numbers.
This might be due to NHS trusts being busy with whatever the next NHS crisis happens to be (Brexit / No deal preparations perhaps) or whether that is due to competition or an ineffective sales force - they seem pretty quiet on the "new business" front - it would be helpful if they disclosed the number of trusts they work with.
I expect the customer base is quite sticky, given that selling to public sector is not easy and I imagine (shameful bias against the public sector) that they are not the most dynamic of customers, but whether that qualifies as a moat I am not sure?
From looking at the services, they do not seem that entrenched, unless they substantially expand the offering and become the one stop shop for all remote medical scanning
Would appreciate any thoughts especially those who might have experience of selling to the NHS / other public sector trusts.
Many thanks
Hi Sharmvr
(Disclosure I hold Medica (LON:MGP) )
I’m sure there’s lots of comments others can make around the half year results, so I’ll keep to giving some thoughts around selling to the NHS and public sector – which is what my own business does, albeit in a different segment of services.
The NHS and local government are going through a major crunch, which is well documented – an aging population (with proportionately greater health and social care needs), but dwindling and more costly labour pool. The simple economics of this are that it can not afford the projected cost, without a major transformation in funding, which politicians have repeatedly failed to address (it doesn’t win votes).
With this backdrop, our experience is that procurement within trusts is a slow moving ship, and so whilst you don’t see an increase in trusts using Medica (LON:MGP) services, it does explain why the number remains stable. The growing revenue (albeit growth slowing?) from this stable customer base suggests the service offers value for money, which is pretty much the main focus for any trust.
Pros:
• The selling point of Medica (LON:MGP) services is cost saving – which trusts will focus on
• Limited pool of skilled radiologists and higher productivity per headcount
• Flexibility – 24/7 service, without relying on costly incentives for employed radiologists
• Remote working – a big incentive for a radiologist to work for Medica (LON:MGP) rather than his/her local trust
• I’ve not researched the market, but am not aware of much competition for this service?
• Radiology is not a service likely to decline, and very far from automation of any sort!
Cons:
• The focus on costs – in our experience public sector bodies are slow to adjust fees to meet rising costs, so potential margin pressure
• Although they have multiple customers, really in the end it is just one – the NHS, so very sensitive to government whims, funding decisions etc
• NHS procurement – very lumpy and often delayed in getting to any sort of outcome
I hope these general comments help – obviously they are my thoughts, and a ‘read across’ from my business, but not specific to Medica (LON:MGP)
ppdrs
PPDRS - interesting insight - thanks, just one small point - you say that radiology is very far from automation of any sort. I thought that AI was already performing better than humans in this field.
Shipoffrogs
I don't have any specific expertise in radiology. My understanding is at a basic level (e.g. X-ray), there might be some automation (although anecdotally I have heard that skilled clinicians have missed fractures on occasion!), however my views about automation are more around complex imaging especially oncology, where it might be some time (but never say never) before humans can be replaced.
ppdrs
Morning ppdrs - re Medica (LON:MGP)
I'm no oncology or IT expert either, I am a bit of a google researcher however
One search and...... Article in last months science daily about AI and oncology
https://www.sciencedaily.com/releases/2018/08/180822114436.htm
some time?
ppdrs,
I hold Medica (LON:MGP) too.
Thanks for this - great insight and exactly the kind of thing I was hoping for - mostly confirms my view.
Accepted re customer concentration and politics, but I would say that has to be a risk of investing in such a business.
Would tend to agree with Shipfrogs that basic radiology (eg recognising a common fracture such as hairline) lends itself to automation, although I would suggest part of the Medica (LON:MGP) investment case is that opportunity and an area they are looking to develop.
That said, something being ready for automation and actually being automated are two very separate ideas in the real world, especially when you are dealing a parent worried about their child.
Personally, I liked this company at the outset and sadly overpaid - at current valuations, I would suggest this is an attractive long term compounder (politics notwithstanding) - added to the holding a few months ago. If I see same operational performance and balance sheet, with a growing customer base, I would add, especially if the valuation stays as now - something to watch for in the next couple of updates I think.
Microcap Malvern International (LON:MLVN) reported its Interims today. I would be grateful if Paul would be willing to comment, as it's a BMUS stock.
Hi Graham, 3 of my shares had results today, Ricardo (LON:RCDO) SafeCharge International (LON:SCH) & Amerisur Resources (LON:AMER), it would be good to get your views on each.
SafeCharge International (LON:SCH) looks decent and as expected albeit with expected lower margins
Ricardo (LON:RCDO) took a bit of a dive on the recent trading update and I felt it was overdone (so I bought) especially as it was only one element (auto) that had underperformed and they say they have put right, they now have a record year end order book and the future looks bright to me
Amerisur Resources (LON:AMER) looked good to me with impressive increases in revenue and pbt, and a current seller holding the sp back imo
Hi Threeputt, I appreciate the requests. I don't cover every sector, however - Amerisur Resources (LON:AMER) is a resource stock and Ricardo (LON:RCDO) is a consultancy. So they're not on my radar. Apologies. G
Performance of the FTSE 250 is probably a better view on the domestic situation given the currency exposure of the FTSE 100 it is, as you say, an inverse dollar correlation based on multinational's repatriated GBP-denominated earnings. In the plot below the out-performance of cable on the right mirrors the under-performance of FTSE 100 on the left
AIM has outperformed this year and over the summer
Below are relative performances using an RSI based on the FTSE All-Share for 1 month vs 3 month timescales. Good to keep an eye to top-down while mining the bottom-up in my view . Tobacco has had a bad run .... not a sector I know much about but have seen concerns over vaping legislation, sector is down over 27% ytd so technical bear territory
Hey, thanks for the useful graphic and the insights. G
Re: the forecast dividend yield of 3.7% of the FTSE 100 - I presume this is the median yield of the index (not taking into account market cap). FTSE 100 trackers currently yield over 4% and this is because some of the big beasts (e.g. RDSB, HSBA, BATS, BP, GSK) yield more than the median FTSE 100 yield and are ~31% or so of the index.
Anyway, I do think the FTSE 100 is quite attractively valued. However, I think one of the reasons for the low valuation is that a number of companies (particularly the larger constituents) appear to be stagnant companies. E.g. RDSB, HSBA, GSK and BP havent really had much earnings growth relative to a decade ago.
Interesting market view Graham thanks for that. Much as I'm trying hard to become less of a stock-picker and more of a "top-down" investor using the excellent tools here at stockopedia, I have to agree that it does fell very much a stock-pickers market at the moment.
I was I surprised therefore that you mentioned your smaller holdings. I thought from previous comments that you only had a concentrated portfolio of large positions? Performance in your top positions look very impressive, if the smaller holdings are doing less well, is this because they were less convincing to you in the first place?
I'm just musing therefore on the merits of having different position sizes (unless risk adjusted) versus just concentrating on "conviction" plays. (Personally I'm doing the opposite and trying to become more evenly diversified, but that's just my way of tackling my monkey mind.)
As my portfolio has gotten a bit bigger over the past year or two I decided to allow myself to diversify a bit, to reduce the concentration risk somewhat. I'm still quite concentrated: Burberry (LON:BRBY), Volvere (LON:VLE) and H & T (LON:HAT) account for one third of everything, for example.
Also, I wanted to try investing in a few companies which I wouldn't normally invest in, but which I thought were interesting. Diversification has enabled me to invest in DUKE, DIS and DPEU. If I only owned 7 stocks in total, I might not be able to bear the risk of owning them.
My other equity holdings are :
Of course, you had actually mentioned some (probably all) of those additional positions, but I hadn't joined the dots.
I can certainly relate to the soothing effect of having a bit more diversity. In fact contrary to what you've seen so far this year, I have found that my "brilliant" ideas have not disproportionately out-performed my "good" ideas, but they do create disproportionate "stress". Hence my move towards having more even position sizes (at least at the point of initial purchase). Most soothing of all though this year has been building up a diversified hedge portfolio of shorts, that also being the best performing part of my portfolio thus far.
Would you be able to look at Sirius Real Estate (LON:SRE) please Graham? There is a positive update on letting 11,000sqm of lettings. They are focussed on property development and letting in Germany.
Interesting general market commentary. I bought Ashtead (LON:AHT) the other day after very good Q1 results with pre-tax profit+23% and commentary indicating the FY outcome will be ahead of expectations. This is helped by Sterling weakness, as most of the business comes from the States via Sunbelt and, more recently, in Canada; therefore I see next to no Brexit impact.
Hi andrea, I'm not too familiar with Sirius Real Estate (LON:SRE) to be honest. I see that its EPRA NAV was recorded at 64c (about 57p) for March 2018. That means the shares are only trading at a small premium, or maybe even a discount compared to whatever its live EPRA NAV might be.
That's a good start. I like buying property companies at NAV or lower. But I don't have specific information about SRE. Cheers, G
First time I have posted on hear and the comment I made earlier about the Google search related to SafeCharge International
Good Morning Graham,
Please can you take a look at today's late announcement of an acquisition by Scapa (LON:SCPA) ?
Morning rtj. Thanks for the suggestion. I'll take a look. G
It is worth doing a Google search on the company and looking at the reviews. The results are very mixed. Many of the staff sound disgruntled and critical of the management. On a review of the product one person gave it a score of 0 out of 10 though several gave 8 out of 10.
Good morning Graham & folks, being a financial services person Graham I'd appreciate your views on SafeCharge International (LON:SCH) this morning, although it's a £452.5m mcap so slightly over. Strong in-line but overall profits down 2%, possibly due to its big dividend and a recent acquisition. Income, payments etc all up & outlook strong but the Non-Exec Chair has left. Would that put it in play? Has recently slumped 350p-300p so someone knew something was up. I hold a small stake for a t/o. Been waiting a while! Cheers
Thanks for the solid views on SafeCharge International (LON:SCH) Graham, much appreciated!
You are very welcome rtj! G
My morning smallcap tweet:
Debenhams (LON:DEB)
Debenhams (DEB) [last night] Sports Direct confirms report that it does not intend to make a bid for Debenhams.