Small Cap Value Report (Thur 16 August 2018) - VLG, OTB, 7DIG, RNK, ASH, FTC, TRB

Morning all,
Things I've noticed today:
- Venture Life (LON:VLG) - trading update
- On The Beach (LON:OTB) - acquisition and trading update
- 7digital (LON:7DIG) - preliminary results
- Rank (LON:RNK) - final results
- Ashley House (LON:ASH) - preliminary results
- Filtronic (LON:FTC) - final results
- Tribal (LON:TRB) - half year report
Venture Life (LON:VLG)
- Share price: 47.8p (+3.5%)
- No. of Shares: 84 million
- Market cap: £40 million
We covered this when it did a £19 million placing last month, to acquire Dentyl mouthwash and generally strengthen the company.
It already has the UltraDEX mouthwash brand.
We have 6% organic revenue growth in H1 to £8.3 million and a full-year outlook in line with expectations.
The order book is up 20%. I'm not sure how much to read into that - we don't know how long it will take to realise these revenues. Still good news, though.
UltraDEX is entering Spain, Portugal and Belgium from Q4 2018 and is set to enter Austria and the U.A.E by Q1 2019. The total number of markets where the brand will be "partnered" is set to double from 15 to 30 by the end of 2020.
My view
I wish there were fewer moving parts, as a little bit of guesswork and maths is required to figure out what is going to happen next. We have UltraDEX and Dentyl now and will probably soon have more acquisitions. It's impossible to have much of a clue about whether a future acquisition will work out or not.
Using back of the envelope figures, I think VLG might have c. £10 million of cash left from the placing, after paying down debt and buying Dentyl.
So let's estimate the current enterprise value at £30 million (market cap £40 million minus £10 million cash).
- UltraDEX made operating profit of £600k last year and this is presumably going to show a nice increase.
- Dentyl made PBT of £1.2 million. This has been trending lower but of course VLG's plan will be to turn this around.
If you think about what the combined operating profit of these mouthwash brands could be and compare this to the current enterprise value of £30 million, VLG shares seem to me like they could be reasonable value at current levels.
The brands don't strike me as high-grade, though. Personally, I don't think I would buy UltraDEX or Dentyl mouthwash. I've tried UltraDEX before. Has anybody tried Dentyl?
Also, the 6% organic revenue growth from UltraDEX is good but not exactly earth-shattering. The increased distribution channels should accelerate this, however.
I think I'll sit on the sidelines, as there's not quite enough for me to get overly excited about this yet.
On The Beach (LON:OTB)
- Share price: 479p (+16%)
- No. of shares: 130 million
- Market cap: £624 million
Acquisition and Trading Update
Fantastic share price reaction to this update.
Acquisition
On The Beach is an online travel company that helps people to find holiday flights and hotels. It has been a big success for investors since the company listed in 2015.
Today it announces a small-ish acquisition (£20 million), with a smidgen of dilution for OTB shareholders. The target company packages luxury holidays and sells them via offline travel agencies.
Among other plans, OTB will help its new subsidiary to build an online portal for travel agents to use.
It sounds like a useful little bolt-on acquisition, and OTB's technology will be used to significantly improve its new subsidiary. I approve!
Trading update
Despite the positive acquisition news, I don't think a £20 million acquisition is sufficient to improve a market cap by c. £85 million (that's approximately how much OTB's market cap has increased by today).
We have an accompanying trading update:
As has been widely publicised, the exceptionally hot UK weather that has been prevalent over recent months, combined with the football World Cup, has suppressed holiday demand. This has impacted our headline revenue growth during the period, but the weaker demand has driven a significant reduction in the Group's marketing spend, ensuring growth in revenue after marketing costs has remained strong.
So revenues are down but marketing spend is down too. Adjusted PBT will be broadly in line with expectations.
That would normally be considered a mini-profit warning by me and by others, as "broadly in line" translates to "a slight miss".
It is evident that the market had already priced in a serious profit warning, however. The shares have been drifting lower for months, as the heatwave has persisted. Today's bounce recoups much of these losses.
My view
I maintain my positive view of this company and I don't think it is trading at a terribly expensive price, either. The StockRanks give it a poor rating which I think is due to things like its low dividend yield, high price to book value and high price to sales ratio:
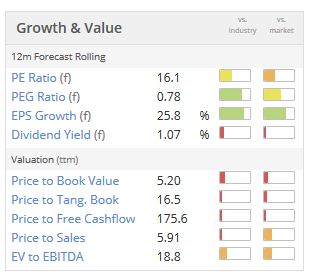
I think there may be legitimate explanations for all of these issues.
For example - it's a website, it doesn't need many assets and therefore if people value it on earnings then the price to book value ratio is inevitably going to be expensive.
Similarly, it earns a very high operating margin (24%) so a high price to sales ratio can be justified.
So I can look past the low Value Rank in this case.
The point about the StockRanks is that they work on average. But for any particular stock, there are reasons why it might do a lot better (or a lot worse) than its StockRank suggests.
This is on my watchlist for a purchase, if I can ever find a spot for it in my portfolio.
7digital (LON: 7DIG)
- Share price: 4.5p (-1%)
- No. of shares: 400 million
- Market cap: £18 million
I missed the fact that this stock got suspended last month, for failing to publish 2017 accounts.
The company said that the audit process had been complex because of its rapid growth.
Not sure I can abide that excuse. If the accounting is out of control to such an extent that it takes eight months to report numbers, I would be a bit concerned that other things were out of control, too.
The Chairman apologises for what happened. 7digital has a new, interim CFO who is interested to take the role on a permanent basis and is implementing the recommendations of its new auditors, BDO. So maybe it can put the issue behind it now. The stock is back trading today.
As I described in February, 7digital provides a range of music and audio-related services to businesses.
It has been unprofitable for almost the entirety of the 21st century, and raised nearly £11 million (net of expenses) from investors last year. The CEO promised that it had "the right foundation for full year profitability in 2018".
It does sound like it should be valuable:
7digital is one of only two companies in the world to be able to provide full white-label streaming services to businesses who want to use music as part of their offering. Our product is sought after because of our catalogue of 60m licensed tracks and our platform on which new music services can be built quickly.
I'm looking for some reassurance in today's statement that profitability will be achieved this year.
The CEO says "the Board remains committed to being profitable at PBT level during the second half of 2018" - i.e. we will probably have a full-year loss. This is a downgrading of expectations compared to what the Chairman promised in February.
There has been a big transaction with a big German company called "MediaMarktSaturn" (MMS), with the result that MMS becomes 7digital's largest shareholder. MMS had previously been described as a client.
This means we are going to have a lot of related-party activity. Sometimes that's no problem, but I consider it a source of risk.
I don't feel comfortable yet in terms of my understanding of what 7digital is doing. It is classified as Highly Speculative by the algorithms and has a StockRank of zero. I also think the inability to meet profit forecasts is quite disappointing. So I won't be putting any funds into it at this time!
Rank (LON:RNK)
- Share price: 171p (-3%)
- No. of shares: 391 million
- Market cap: £668 million
We rarely cover this one as its market cap makes it a bit too big for us. I occasionally look in on it to see how it's doing.
It operates bingo halls ("Mecca") and casinos ("Grosvenor") in the UK, having both a physical and online presence.
Bingo halls are considered old-fashioned and indeed are in steady decline as the pool of older women who are interested in them diminishes.
Casinos at Rank aren't doing terribly well, either. They've had a "challenging" year due to "low win margin, enhanced due diligence and extreme weather".
So even though digital revenue is up, total revenues are down.
Adding to shareholder woes, there are £22.6 million of exceptional items taking a huge bite out of profits in FY 2018.
Let's dig in to these exceptionals:
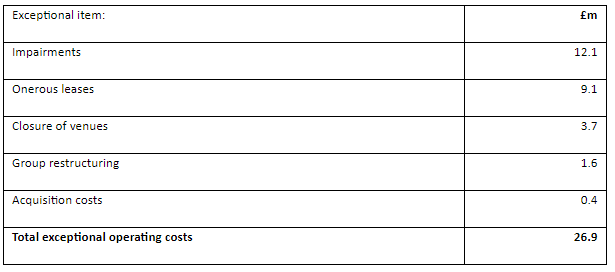
Considering them in turn:
- Impairments of £12.1 million. It's fair enough to add this back in to operating profit in my opinion.
- Onerous lease costs of £9.1 million. I would allow this (i.e. I would ignore this cost), but I would also ignore all future releases of this provision, which will be used to increase future net income. I hate these lease provisions - they always feel to me like they are a way of managing the profit figures, rather than reporting them in a straightforward manner.
- Closure of venues, restructuring and acquisition costs. Mixed feelings about this. Aren't these likely to be regular events?
In summary, I am inclined to agree with the majority of the exceptionals as being "exceptionals" which should be added back in to operating profit. So the adjusted operating profit figure of £77 million is not too far from what I would use.
Good value?
It looks superficially cheap:
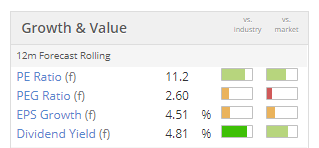
We need to decide how bad are the prospects for bingo halls and casinos,
Together, these accounted for £77 million of adjusted operating profit, compared to just £21 million from the company's digital activities. So they are still very important to the value of the entire group.
The outlook is in line with expectations. Stocko shows forecast net income for this year of £57.5 million.
I don't hate the idea of owning shares in this business, but I'm not exactly in a rush to buy them, either. Will continue to monitor sporadically.
Ashley House (LON:ASH)
- Share price: 15.3p (+11%)
- No. of shares: 60 million
- Market cap: £9 million
I no longer analyse this type of business. It doesn't strike me as an attractive type of investment, so I'd prefer to just ignore it and focus on sectors I find more promising. So I won't be analysing these results. Ashley House is a niche property developer and property manager working in partnership with local governments and others.
I won't deny that some of them may make for good investments at the right price. If there are enough people like me who aren't studying them. they might end up being completely mispriced from time to time.
Our resident expert on Ashley House, "drvodkaquickstep" (not his real name) has penned some analysis of its FY 2018 results as a comment (#23) on his own Stocko article. So I'd recommend heading over there if you are interested in this share. He own ASH shares, as you might expect.
Filtronic (LON:FTC)
- Share price: 13.125p (-5%)
- No. of shares: 207 million
- Market cap: £27 million
I didn't have much nice to say about this share when I covered it in December (at 10.25p).
Let's remind ourselves what it does:
Filtronic plc is a world leader in the design and manufacture of a broad range of customised RF, microwave and millimetre wave components and subsystems.
The company's products are used in wireless communication equipment, point-to-point communication systems and adjacent defence/security sectors.
Thursday's results aren't bad in historical context. Profits have always been a bit patchy. Operating profit comes in at £1.8 million, beating last year's (2017) £1.7 million.
There is a strange currency effect which then costs the company £0.5 million, thanks to "a US dollar denominated intercompany balance". It has a loan out to its US subsidiary, and the value of this loan has fallen because of the weaker dollar against the pound during the reporting period.
It seems fair enough to classify this as an exceptional item, so long as we do it every year.
The Wireless business has deteriorated, but the Broadband business swang into a profit. From now on these will trade and report as a single entity, as their technologies have converged.
Outlook
The outlook statement affirms the reason why this is too high risk for me. Plaudits to management for being so up front about it:
Whilst progress has been made in diversifying our customer base our sales remain highly concentrated and are still exposed to fluctuations in demand due to the nature of our business and the significant size of projects we supply into.
So while there are positive noises made, it's still very much dependent in the short-term on the outcomes from of a small number of customers and contracts.
Good luck to them.
Tribal (LON:TRB)
- Share price: 91.6p (+2%)
- No. of shares: 196 million
- Market cap: £180 million
Tribal provides "software and services for education management".
It's a successful turnaround story which has been brought back to life by a new management team.
Even though they have concluded their cost reduction program, they are forecasting more cost savings in 2019 to further improve margins for the business.
Today's results show a £1.7 million reduction in central overheads - not a huge sum in comparison to the market cap but it makes a huge difference to operating profits.
Operating profits increase from £5 million to £6.3 million, i.e. the improvement is more than fully accounted for by the reduction in central overheads.
It's a spectacular improvement and there may be more to come. I'm not familiar enough yet with the company's activities to buy into it, but I do recommend it for further research.
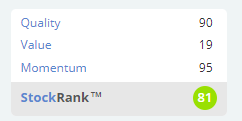
It is a bit pricey now at 23x forecast earnings:
Finally made it to the end of today's list! Thank you for your patience.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
I’ve been wondering for some while why I can’t find dental ph in any of the supermarkets any more. We had taken to stockpiling some of it on the basis we thought it was being phased out.
The idea of it is that when you use it no spit out the mouthwash you can supposedly see the stuff it’s cleared out of your teeth. To me that seems like a gimic but to some people (my wife) that’s apparently a good thing.
Given its almost impossible to buy the stuff at the moment, getting it to turn around shouldn’t be that difficult....just get some super markets to stock the stuff again!
I've tried Dentyl. Its major selling point is that it is PH neutral.The trouble with that is that it doesn't really make your mouth feel fresh in the way that most flouride mouthwashes do. I'm guessing that that may be an inevitable downside of it being PH neutral [neither acid nor alkaline].
Thanks for the insight. UltraDEX also doesn't leave you with the buzzed up feeling of Listerine and others. G
Yes I found exactly the same disadvantage with Dentyl, it doesn't make your mouth feel fresh so that is why I did not buy it again and perhaps why its previous owner wanted to sell the brand.
"...so that is why I did not buy it again and perhaps why its previous owner wanted to sell the brand."
Crikey... better not tell Diageo that I've stopped drinking Guinness!! :-)
All the best, Si
For accuracy; pH and fluoride.
A valuable lesson from Graham is the skill to read in between the lines. Something many of us (me including) at times forget.
The CEO says "the Board remains committed to being profitable at PBT level during the second half of 2018" - i.e. we will probably have a full-year loss. This is a downgrading of expectations compared to what the Chairman promised in February.
What does On The Beach do that other websites like Expedia do not?
I liked this one:
"Our resident expert on Ashley House, "drvodkaquickstep" (not his real name) has penned some analysis ..."
Hi,
My favourite line in today's SCVR about £7DIG
It has been unprofitable for almost the entirety of the 21st century ...
Love it! I like the way you manage to be scathing about lousy companies, whilst still sounding very polite (I never quite mastered that, lol)
Best wishes, Paul.
Thank you Sir!
Graham Nearly Jacob Rees Mogg!
RE: VLG : I think the recent placing (see Aug 7 2018 RNS) at placing of 40p for a net £17.5Mn to i) fund acquistion of Dentyl £4.2Mn (2nd mouthwash brand to Ultradex) ii) pay off £3.7Mn of (director) loans and give combined with this update are very positive indeed. Future is brighter than current numbers show.
1. The marginal profitability of extra mouthwash sales is likely to be very high indeed. So assuming the extra UK listings work out on UltraDex plus help support the (re-)introduction Dentyl to a wider distribution, we can think of PBT of Mouthwash going from say 0.6(Dentex 2017) +1.2(Dentyl 2017) = 1.8Mn PBT to say 1.6 +1.7 = 3.3Mn + sachets 0.3Mn = 3.6Mn. This compares to 0.6Mn for UltraDex alone last year.
Both brands bring distinctive benefits/propositions to the category in the UK and are always going to be niche segments but are probably sustainable and growing with some love and effective targetted marketing.
The extra Euro/ROW sales on mouthwash will probably generate a benefit big enough to pay launch costs in first 1-3 years since I doubt there will be big TV supported marketing plan any launch but growing from current 10 markets to 15 (Q1 19) and 30 promised by 2020 will be a big increases in scale and probably permit the profitable in sourcing of mouthwash production already owned Italian manufacturing site. Euro/dollar-sales also provide some more natural currency hedging (plus again help in manufacturing efficiencies). A useful additional benefit given brexit risk to pound
Overall, the extra sales will also help spread fixed OH since very limited additional staff required given manufacturing already set up with account handlers in UK in place and distributors used in overseas mkts.
2. Financial savings from less interest costs (est at 0.3Mn pa) plus the elimination of the bonds/loans cleans up the balance sheet to look better as well as be stronger. Balance sheet on Stockopedoia will not update to reflect this until interim results in Sept
3. As Graham says, the residual 10mn provides for extra acquisitions or to fund marketing to drive sales faster (or resilience if all goes to pot for a period!).
The shares IPO'd in 2014 at 100p so at 48p are half the price with the business much better defined. Each year there has been a positive strategic move. I think it worth opening a position. Risk is now move of it moving sideways than falling sharply (famous last words!). Looking to buy.
This blog has previously discussed how one of the benefits of online businesses is that they can reduce their marketing spend (often their main cost) in response to falling demand or a poorer economic environment. The On The Beach (LON:OTB) update this morning was evidence of that. Unsurprisingly they have seen a fall in revenue due to world cup and hot weather but they are not changing their expectations for the full year as they have reduced their marketing spend in response. "Whilst August and September are important trading months for the Group, the Board continues to expect that adjusted PBT for the financial year will be broadly in line with management expectations." I hold and took the recent dip as a buying opportunity as there is nothing fundamentally wrong with the business.
I would be wary of thinking this way. Yes, marketing spend can be cut back to meet financial targets. But that marketing wasn't planned as meaningless entertainment. The act of cutting back has just made next year's sales targets more of a stretch. If the company choose to spend more at some future point, cash needs to be deployed into less effective channels, since your original plans always cover the most cost-effective ones. It's a slippery slope.
Anyway, good luck with the holding.
Jon (ex holiday co marketing director)
On The Beach (LON:OTB) is an interesting company and today's announcement was twofold: a trading update which was cautious due to the hot weather and World Cup, and more importantly the acquisition of Classic Collection Holidays.
I found this to be interesting: the acquisition price of £20m is 7.7x EBITDA in 2017 and 2.4x NAV seems very reasonable. Looking at what Classic offers is an expansion of OTB's offerin. Classic focus on luxury beach holidays and these are sold via travel agents with no online offering to the consumer. OTB intends to leverage its technology to make this better. It provides them with access to the 5 million short-haul beach holidays booked offline. Therefore, Classic is not a direct competitor of OTB but will allow OTB access to new markets.
It seems an astute acquisition.
If I have correctly recalled Paul's previous comments (as alluded to by paraic) about marketing costs being dialled back for high growth, online businesses, it's that there is a difference between marketing spend in absolute terms and in relative terms (i.e. as a percentage of revenues).
On The Beach (LON:OTB) is a good example of this: in absolute terms, marketing spend has been increasing year on year since well before it listed. However in relative terms, marketing spend peaked at just over 50% of revenue in FY14 and has been declining ever since, to just over 40% in H1 2018:
Granted it sounds like On The Beach (LON:OTB) has reduced marketing spend in absolute terms over the last 19 week period, but it wouldn't surprise me if for the year as a whole the trend of the last few years remains intact, i.e. increased or similar marketing spend in absolute terms but lower spend in relative terms.
What I found more interesting in today's announcement is what looks to me like an anomaly between what they said about demand and marketing spend at the last interims and what they said today.
When the interims were issued on 10 May they said this:
and today they said this:
No expertise in marketing but could it be that they invested in marketing (i.e willing to pay a lot for the word beach), but then low demand met the customer did not click so therefore they spent less on clicks than anticipated??
Would explain the cost/revenue remaining constant from 2017 but the absolute amount being lower???
At the risk of overcomplicating, OTB will almost certainly be bidding on '000s of search terms. When you cut back your spend a typical result might be to fall from first or second in the search results to a lower position - generating less click-throughs. Many of those people who didn't click might have been early in the holiday planning process, which is why their absence doesn't become apparent until much later.
HTH, no position.
Hi Graham,
A general question: How many firms make a market in a given stock? It does not seem to be given on Stocko nor on the public pages of the London Stock Exchange. Do you or any of your readers have a link?
Thank you, in anticipation, Seadoc
Hi Seadoc
https://www.londonstockexchange.com/products-and-services/trading-services/registered-market-makers-by-security.xls
..Gives you the info..but obviously any L2 provider does too
Rhomboid, thanks.
I also thank rhomboid! G
Hi Graham,
I would second the request for ST Ives (LON:SIV) if you can fit this in please and am also keen in hearing your thoughts regarding £7DIG.
Thanks, James
Ashley House (LON:ASH) request seconded please.
DrVodkaQuickStep is our resident expert on this stock, I defer to him. I will link to his article. G
St. Ives ST Ives (LON:SIV) if possible please Graham.
Ashley House (LON:ASH) if you have time please Graham...!
I wish I bought this after reading your report on it a while back, I watched it for ages when it dropped to 8p but never took the plunge.
Mercia Technologies (LON:MERC) looks interesting please if nothing else grabs you Graham!
My morning smallcap tweet:
Infrastrata (LON:INFA), Petards (LON:PEG), Mercia Technologies (LON:MERC), ST Ives (LON:SIV), Sinclair Pharma (LON:SPH), Ab Dynamics (LON:ABDP), Abzena (LON:ABZA)
Infrastrata (INFA) CEO and COO play musical chairs.
Petards Group (PEG) contract win - £2.7m. Starting January 2019, expected to be completed in 2020.
Mercia Technologies (MERC) 46% owned investee co nDreams wins multi-million dollar contract with "one of the world's foremost virtual reality technology companies." It's the most significant (biggest?) contract win to date.
St Ives (SIV) Guides FY pretax at the upper end of market expectations.
Sinclair Pharma (SPH) extends PUSU deadline again, by 7 days.
AB Dynamics (ABDP) director and 6% holder dies. She was married to a founder director, also deceased. Will the holding need a new home in due course?
Abzena (ABZA) recommended of of 16p, a 167% premium. SP has crashed in last year as it seeks funding and starts firesale