Small Cap Value Report (Tue 13 June 2023) - CMCX, TAM, IOM, DRV, VNET

Good morning from Paul and Roland! (Graham's on holiday this week)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.

Summaries of main sections
CMC Markets (LON:CMCX)
Down 5% at 160p (£449m) - FY23 results, in line - Roland - GREEN
A solid set of numbers from this financial trading group, reflecting the impact of reduced market volatility and increased investment in IT and headcount. I think the fundamentals of this business remain strong and suspect the shares offer good value at present. (more detail below)
Tatton Asset Management (LON:TAM)
Up 1% at 460p (£276m) - FY23 results, in line - Roland - GREEN
A strong set of numbers for this asset manager and IFA support services business. Continued AUM growth in last year’s more difficult market suggests the group has a well-targeted offering and good distribution. My view remains positive.
iomart (LON:IOM)
Up 1% to 166p (£187m) - Final Results - Paul - AMBER
In line results for FY 3/2023 are out today, so I have a good rummage below. This looks a fairly decent company, with nice recurring revenues, and good cash generation - funding decent divis and acquisitions. I've moved from green to amber, because the valuation has shot up in the last 2 months, from when we flagged it as a bargain here at 121p in April.
Driver (LON:DRV)
Up 1% to 32.7p (£18m) - Interim Results - Paul - AMBER
There's lots to like here - very good balance sheet with £5m net cash, divis of c.5%, improved H1 results, continued turnaround potential, an I'd say Driver could be a takeover bid target. So I would have gone green, but the weak outlook comments have put me off for now, suggesting a profit warning and reduced forecasts are in the pipeline probably.
Quick Comments only
Vianet (LON:VNET)
Up 1% to 85p (£25m) - Final Results - Paul - RED
Care is needed with these numbers, as I’ve mentioned before, the company is a heavy capitaliser of development costs (£1.7m this year, £2.0m last year), which means that EBITDA and operating profit numbers are meaningless, and don’t reflect reality.
I suggest reading the cashflow statement, rather than the P&L, because it makes starkly clear that Vianet has not generated any cash this year, or last year. It was all spent on development spending, which is just payroll, so I regard that as an ongoing operating cost.
Balance sheet is adequate, with c.£3m NTAV. A smallish debt position seems OK.
Cenkos (many thanks) slashes EPS forecast today from 5.3p to just 1.86p for FY 3/2024.
Paul’s opinion - the recent rise looks unjustified, and the current year forecast PER is now 46x, which looks way too high. It’s not a very good business in my view, and the share price looks well overvalued. Sorry if that upsets anyone, but it's what the numbers are telling me.
Paul’s Section:
Driver (LON:DRV)
Up 1% to 32.7p (£18m) - Interim Results - Paul - AMBER
This is a global construction consultancy, that (from looking at its website) seems to be focused on dispute resolution/prevention.
The company had some problems, with an onerous contract I seem to recall, and was a possible turnaround share. I’ve not looked at it for about a year, so let’s see what the latest results are like.
H1 revenue down 1% at £24.2m, so close to a £50m annualised run rate - which seems quite good for a company only valued at £18m.
Profit is low though, at only £508k (or £710k if you ignore the share options charge), but this is a useful improvement of 378% on H1 2022.
Big reduction in headcount after restructuring in the M.East and Asia.
Outlook - sounds like a profit warning to me -
While the second half of the year for Driver has been shown historically to be strong. April was slower than expected owing to the timing of the Easter weekend and a succession of public holidays, which affected utilisation. The Board is currently considering its policy on forward guidance, which will reflect the short-term revenue visibility.
Balance sheet - is excellent, with NTAV of £12.7m, including £5.3m of cash (no bank debt). This is a very comfortable position, and nicely protects downside risk - even if it generates more losses in future, I don’t see any risk of dilution, or insolvency, providing nothing gigantic goes wrong.
Segmental performance - note 5 is interesting, showing that the Europe & Americas business is quite good, generating 79% of total group revenues, and a nice profit of £2.9m. Whereas M.East and Asia are very small, and making small losses. Which makes me wonder why don’t they sell, or close the small divisions, and focus on the main profit generator? Although this argument falls over when you consider the large £2.2m of central, unallocated costs, which gobbles up most of the divisional profit.
As mentioned before, I don’t understand why this company is stock market listed. It could probably eliminate maybe £500k pa in costs if it went private, which would materially improve profitability.
Paul’s opinion - potentially interesting as a turnaround, although the wobbly outlook statement today suggests to me that another profit warning is gestating. For that reason I’ll watch from the sidelines for now.
I really like the excellent balance sheet, which supports most of the market cap, giving lovely downside risk protection for investors, and leaves management free of funding issues, hence able to focus on turning the business around.
At this stage it’s difficult to see much immediate upside though, other than the potential for a takeover bid, which looks high to me. Consultancy companies often seem to attract bids, often quite highly priced.
Overall then, I quite like risk:reward here. I would have gone green, had it not been for the weak outlook comments today, so it has to be AMBER for now.
I almost forgot, the divis are quite generous, with a yield of about 5%, nice to be paid whilst you wait for a takeover bid or a turnaround.
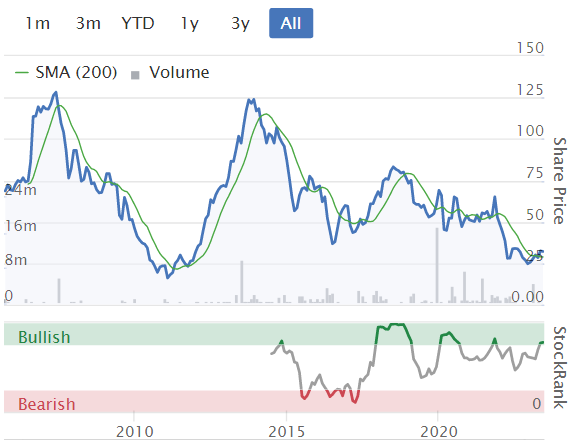
The long-term chart is sobering -
iomart (LON:IOM)
Up 1% to 166p (£187m) - Final Results - Paul - AMBER
My notes from reviewing its trading update on 14 April 2023 are useful as a quick way to get up to speed. I liked the value on offer at 121p, with a PER of only 11.2, a good yield of 4.6%, and a decent outlook. Also lower energy costs should help profits considerably, as the £7m cost headwind of FY 3/2023 should be reversing now, at least partially. Downsides were the lack of tangible asset backing (only £4m), and worries over the dominance of Amazon in cloud computing.
The share price has risen strongly in the last 2 months, so is it still good value?
iomart (AIM: IOM), the cloud computing company, is pleased to report its final results for the year ended 31 March 2023 (FY2023).
Strong increase in revenue and positive M&A activity
Some key numbers -
Revenue up 12% to £115.6m (a very impressive 92% is recurring)
Half the revenue growth came from an acquisition (Concepta)
Another (small) acquisition was done recently, post year-end.
Adj profit before tax (PBT) down 13% to £14.8m - a healthy margin of 12.8%
Adj diluted EPS down 9% to 10.9p - giving a PER of 15.2x - not such a bargain as last time I reviewed it.
I’m ignoring EBITDA as a nonsense number, because it ignores capex (£8.9m), depreciation (£16.5m), amortisation (£6.4m), finance costs (£2.9m), lease costs (£4.9m), development spending £(£1.9m), so you can see what a ridiculous number it is!
The company says these results are in line with market expectations, with this footnote providing some clarity -
Market expectations based on known sell-side analyst estimates for the full year ended 31 March 2023, established in or around 11 October 2022
Cost headwinds are mentioned, particularly energy, staff costs, and finance charges.
Sales pipeline improvement noted in H1 converting into stronger order booking levels in H2
Energy costs - I wonder if hedging might now be a negative, given that wholesale energy costs have fallen so much?
The data centre sector has had to navigate the significant challenges in the energy markets and during the year the Group's electricity costs increased by approximately £7 million. iomart's robust business model and customer arrangements have ensured this additional energy cost has been appropriately passed through to the customer base. While electricity costs remain high, the energy markets appear less volatile as we enter the new financial year. We have a proactive hedging strategy in place for the next two years and expect this matter to be less of a distraction for our team and customers going forward.
Net debt of £39.8m looks alarmingly high, but they’ve included lease liabilities in the headline number, which is a presentational own-goal. I had to search through the results to discover that of this, £19.2m is lease liabilities, so net bank debt is a much more acceptable £20.6m.
Outlook - is in line, but only for the first 2 months (April & May 2023). I would have preferred a more clear comment about FY 3/2024 expectations -

Balance sheet - is dominated by £113m intangibles, mostly from acquisitions, but also quite hefty £65m fixed assets (PPE) - although £20.6m of this is leases, which I would much prefer to be shown separately on the face of the balance sheet. Note there is a handy £6.9m freehold property asset, which I like. Data centre equipment and computers are £37m.
NAV is £120.6m, with NTAV being only £7.6m - so there’s little asset backing.
Overall though, for the type of business, I think the balance sheet stacks up OK (note there aren't any inventories, as it's a services business, which helps), but I wouldn’t want to see it increasing bank debt in the current macro uncertainty.
Broker note - thanks to Finncap for making its update note available to us. It confirms results are as expected. For FY 3/2024, it’s estimating adj PBT rising from £14.8m to £16.0m, but flat EPS at 10.9p. The culprit is higher corporation tax, and a slight increase in shares issued, which together absorb all the increased profits. The 6% hike in corporation tax is an important negative factor which is detrimental for company valuations, and it's curtailing earnings growth - negative, but it could also mean future earnings growth might be better, once this one-off factor has washed through the figures.
Paul’s opinion - this looks a fairly decent company, nothing special, so I can’t see why anyone would particularly focus on investing here, when we have so many other options? The PER is now 15.2x, which seems up with events now. I liked this share when it was cheaper in April, when I went GREEN on it. However, now the price has risen from 121p then, to 166p now, I think it’s going to have to be AMBER now, as the price looks up with events for the time being.
The key area to research in more detail, would be the services it offers, customer relationships, competitive landscape, and ultimately whether profits are likely to grow, or contract. Same as with any company really! At least it's genuinely cash generative, and has nice recurring revenues, so it can pay decent divis, and self-fund modest acquisitions. I also like that the founder has plenty of skin in the game, holding 15.7%, which is a very good vote of confidence in the company, and the new management. since he retired a couple of years ago it seems.
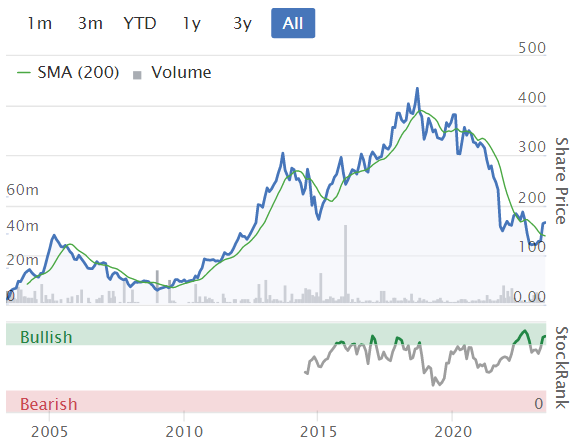
Long-term, this has been quite a rollercoaster ride! Note the high StockRank -
Roland’s Section:
CMC Markets (LON:CMCX)
Share price: 160p (-5% at 08.30)
Market cap: £475m
Net operating income a new record high outside of the pandemic period, in line with guidance
This financial trading group is run by founder-CEO Lord Peter Cruddas, who has a 59% shareholding. CMC has looked like a possible value play to me for a while, after a series of downgrades.

I have an interest in this sector as I’m a shareholder of CMC’s larger rival, IG group (LON:IGG)
Today’s results are in line with guidance, but flag up a big increase in costs and an uncertain near-term outlook.
Let’s take a look.
Financial highlights: CMC’s claim to have achieved “new record” net operating income “outside of the pandemic period” seems slightly disingenuous to me. I think it only serves to highlight the operating leverage that’s inherent in the business model.
When leveraged trading activity rises thanks to volatile markets, profits tend to soar. But the reverse is also true, and that’s what we’ve seen over the last year.
I’ve pasted in the financial summary from today’s results as I think it highlights some interesting trends:

Net operating income rose by 2% to £288.4m. For context, this figure peaked at £409.8m in the (pandemic) year ended March 2021.
Net operating income represents revenue less commissions and levies. But CMC does not hedge all of its clients’ leveraged trading positions and takes some risk exposure itself.
These “risk management gains or losses” are reflected in trading net revenue, which rose by just 1% to £233.1m last year. This figure peaked at £349m in FY21.
Revenue from CMC’s non-leveraged stockbroking business was down, but this was offset by a sharp rise in interest income to £13m. CMC earns interest on its own funds (FY23: £310m) and on segregated client cash, which totalled £549m at the end of March.
However, a 26% increase in operating expenses to £217m (excluding bonuses) meant that pre-tax profit for the year fell by 43%. This sharp rise in spending represents additional headcount and investment in IT as the group develops new services and infrastructure.
Operationally, we can see that active client numbers fell by 9%, but revenue per active client rose by 11% to £3,968. To me, this suggests CMC’s lower-value pandemic clients are thinning out, but its higher-quality long-term clients are remaining active.
Profitability: last year’s slump in profits has had a big impact on CMC’s reported profit metrics. I calculate an operating margin of 17.5% and a return on capital employed of 14.2% from today’s accounts. Both are well below the recent average from this business, according to Stockopedia metrics:

Balance sheet/cash: CMC’s balance sheet looks in good shape to me. The company ended the year with £326.8m of capital, giving a coverage ratio of 369% of its Own Funds Requirement (OFR) of £88.6m.
Dividend: a final dividend of 3.9p per share gives a full-year payout of 7.4p (FY22: 12.38p per share). Although this is a cut, the FY23 payout appears to be ahead of consensus estimates of 6.5p per share.
Outlook: I think this is probably why the shares are down 5% in early trading.
CMC warns that “quiet market conditions” so far in the company’s Q1 have resulted in “client trading activity being down 15-20%”. This is expected to “negatively impact Q1 2024 net operating income”.
The company doesn’t mention full-year guidance at all. My guess is that it’s too soon to be sure if full-year forecasts will need to be cut. Market conditions can change quickly.
For what it’s worth, the company maintains its guidance for “underlying 30% net operating income growth from 2022 to 2025”.
My view:
I’m slightly biased towards this sector as I’ve found it a good way to hedge market volatility. When most of my stocks are crashing, I can usually be sure that IG (and CMC) will be enjoying bumper trading conditions.
During the pandemic, operating profit tripled from previous highs and the shares topped 500p – they’re 160p today.

The picture is more subdued at the moment, but I still think the fundamentals of this business are attractive.
I’m also encouraged by the speed and ambition of CMC’s expansion into stockbroking and institutional offerings. CMC now earns more from non-leveraged trading than larger IG.
The company is now in the process of launching a new retail investing platform in Singapore and an expanded institutional offering in Dubai.
Heavy IT investment should also pay off in the future, according to the company. CMC says its new API (effectively a standardised interface to connect into CMC’s core systems) will allow for easy bolt-on additions of new products and markets.
I know from past experience in IT that a good API can be a powerful tool, but I don’t have any insight into how good CMC’s technology is versus that of its peers.
I’m tempted to give an amber view here in recognition of the uncertain near-term outlook. But on balance, I don’t see this as a big concern – profit volatility is an inherent part of the business model.
My view remains that CMC is in sound financial health and offers good value at current levels, so I’m going to award a green view.
Tatton Asset Management (LON:TAM)
Share price: 460p (+1%)
Market cap: £276m
“It is fitting that in this 10th anniversary year, we have raised the bar further, delivering our best performance to date with record net inflows of £1.8bn, AUM/AUI of £13.9bn and involvement in lending through Paradigm of £14.5bn.”
I’ve admired the progress of this asset manager and IFA services provider since its flotation on AIM. I have previously owned the shares, but I don’t currently have any position.
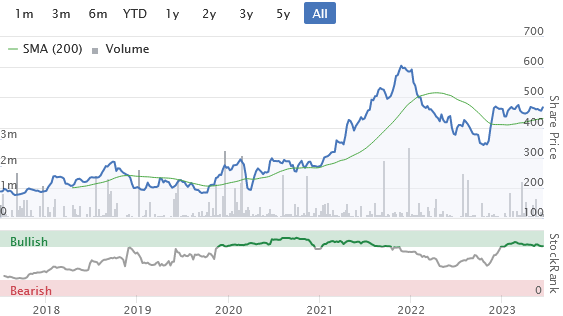
Given the pressure on most asset managers over the last year, we might have expected a slowdown for Tatton. But today’s results seem to suggest that its business model is still performing well, with growth across all key metrics.
Financial highlights: Tatton provides a range of support services for IFAs and also runs its own asset management arm, providing a logical and complementary set of services.
Last year showed continued top line growth and stable margins:
Revenue up by 10% to £32.3m
Adjusted operating profit up by 12.9% to £16.4m
Adj. operating margin: 50.7% (FY22: 49.5%)
Adjusted eps up by 10.7% to 20.6p
Full-year dividend of 14.5p (+16% vs FY22: 123.5p)
Net cash of £26.5m (FY22: £21.7m)
This strong performance reflects a positive operational performance:
Assets under management up 12.3% to £12.7bn
AUM at June 2023 c.£13.2bn
Organic net inflows of £1.8bn, an increase of 15.8% on opening AUM
Acquisition of 50% of 8AM Global Limited added “assets under influence” of £1.136bn
Number of IFA firms served rose by 16.5% to 869, with the number of client accounts up 19.2% to 107,010
Paradigm Mortgages business generated a 10.3% in completions to £14.5bn
Outlook: there’s no specific financial guidance for the year ahead, but CEO Paul Hogarth says he remains “optimistic about the group’s prospects”.
Broker Singer has a new note today (available on Research Tree) which leaves FY24 earnings forecasts unchanged.
Consensus forecasts on Stockopedia suggest earnings could rise by 4% to 20.9p per share, putting the stock on a P/E of 22.
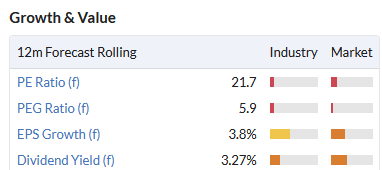
Roland’s view: although Tatton looks pricey compared to many asset managers, I think its high margins and continued growth may justify a stronger rating.
As with CMC, this business benefits from founder management – the CEO remains its largest shareholder:
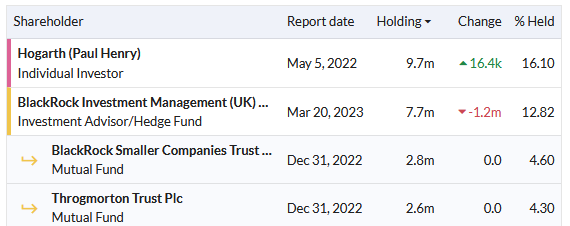
Stockopedia classifies Tatton as a high flyer and I would agree with this view. If performance disappoints, the shares could re-rate sharply. But if the company can continue expanding, then the shares could still be fairly priced at current levels.
On balance, I remain impressed by the company’s good progress and execution. I think Tatton is well positioned in the market and could continue to do well. My view remains green.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Plus500 (LON:PLUS) showing how you clear an overhang. £101million buyback this morning from Odey (8.2%)
They have a separate £70million buyback ongoing too. Sharecount has gone from 109m in 2019 to 82m today. Helps when you have an enormous cash pile.
Odey appear to be forced sellers in a number of companies. Frasers purchased an 18% holding in AO World (LON:AO.) from Odey on Friday.
Probably holding back a few others like Jet2 (LON:JET2)
Plus500 (LON:PLUS) well spotted, thanks Wolf of Small Street. Isn't there a concern that the purchased shares are not cancelled but held in Treasury?
That's an interesting question I don't know the answer to. Anyone have thoughts on this?
I have had a thought on this, as it has been concerning me a little too. The one benefit of keeping them in the treasury I guess would be to prevent a potential hostile takeover. Will be useful too if they ever need to raise capital. Just hope they don't use them to pay employees or executives as part of a compensation plan.
Can a company vote its shares held in Treasury? I had thought not.
Hmm, true. Hope they will just cancel them eventually. At least the management team seem to know what they are doing and buying them back at very good prices.
To provide for boardroom share options perhaps? Certainly this happens quite a lot here and there but maybe should not be leveled at the Plus500 (LON:PLUS) management. The share count is reducing on the balance sheet and time will tell if these share buy-backs are of benefit to the shareholder, I hope so as I do hold.
I see there is a very large cross in Conduit Holdings (LON:CRE) (Odey holding) today. This stock has been under pressure since the Odey news broke.
Tatton Asset Management (LON:TAM) - here's our detailed research report from this morning (free & accessible) : https://www.equitydevelopment.... Brief summary: "Forecasts exceeded in FY23, strong start to FY24 *** In FY23, Tatton (once again) grew much faster than peers. AUM was up 12% y-o-y excluding acquisitions (peer group median: 0%) to £12.7bn on 31 Mar 23 (31 Mar 22: £11.3bn). Assets Under Influence (AUI) reached £13.8bn (including 8AM Global: 50% stake acquired in Aug 22). In just over two months post year-end, AUI has grown another 3% to £14.3bn. The bulk of growth in FY23 came from exceptionally strong net flows of +£1.8bn (FY22: +£1.3bn); 16% of opening AUM (FY22: 14%) compared to a peer group median of 4% (FY22: 6%). Tatton’s ability to attract and retain assets has been far above peers for some time now. It has clearly designed, and is delivering, an outstanding proposition to clients. Tatton has exceeded our previous revenue and profitability forecasts for FY23 and we think its differentiated offering within a market sweet-spot (on-platform Model Portfolio Services growth rate: c25% p.a.) will fuel continued strong growth. We increase our FY24 forecasts: revenue from £35.0m to £35.9m; adjusted operating profit from £17.9m to £18.2m. Our fundamental valuation rises from 560p to 580p.
Metro Bank ! Bosh ! Crispin Odious looks like he's having to close his shorts ...tee hee
Meanwhile over at Oxford Biodynamics (LON:OBD) the SP has tanked from c14p to 9p, as Odey is the largest shareholder with 18% and as a micro-cap the market will be so thin if he needs to sell. Also a company that is running out of cash and needs to do an equity fundraising in the next few months IMO.
I still hold, now 70%+ loss but such an insignificant part of my portfolio that I haven't sold. I wrote a short summary of my thoughts on OBD in my latest Boon Fund journal.
(I hold in the Boon Fund)
70% - do you not use stop losses?
Nope, stop losses are not part of my strategy.
I do keep track of SP movements and if there is a sharp movement downwards, then I see if the facts and my understanding have changed, and make a decision. As information evolves, so does my thinking of whether a certain price is undervalued, fair, or overvalued.
The story with Metro Bank Holdings (LON:MTRO) isn't just about Odey's shorts.
It is also that mortgage rates have now shot up, given that Gilts and BoE rates expectations have also shot up in the last week.
A few points on Metro:
The shares reached a high of 150p before SVB, and I can easily see them returning to those highs, and also surpassing. On valuation metrics (P/B, P/S) they trade at a massive discount to UK bank peers. And once we see profit numbers in the HY report, we will probably see undervaluation in the traditional PE metric too.
(I hold in the Boon Fund)
Hi Roland, thanks for the write up of CMC. I think you've incorrectly tagged a Hong Kong listed company called IGG Igg (HKG:799) rather than the UK listed IG group (LON:IGG) .
From my point of view it is interesting to read of other spread betting companies for market conditions as I am also a holder and customer of IG group (LON:IGG) . I feel more comfortable to hold and be a customer of IGG since it looks to hedge the customer trades and so is less exposed to wild swings in market but more reliant on trade volume. Having been a customer of the former World Spreads which got found out for not hedging their customer trades I steer clear from companies who don't hedge the trades. Why take the risk, it maybe more profitable 9 times out of 10 but there is the risk of the whole house of cards coming crashing down like it did with World Spreads (and a few others whose names escape me).
Hedging every single position is very expensive and probably wipes out half their profits. Prefer the approach of CMC and PLUS to partially hedge - you will get more volatile earnings but they tend to even out over time and in the long run be much more profitable (especially PLUS)
Importantly both these companies have robust risk management procedures in place, so they will never allow unhedged exposure to grow so large that it could lead to catastrophic losses. More likely you'll just have a weak quarter every so often when trading goes against them, but personally not too worried about that.
Hi Paul,
Does Peter Cruddas' 59% holding not concern you?
It was Roland who discussed CMC Markets (LON:CMCX)
Hi mjfgs,
Re. Peter Cruddas and his 59% shareholding - my view on this is that it's generally a positive factor -- Cruddas should clearly be incentivised to create value and rebuild the CMC Markets (LON:CMCX) share price.
I understand that investors are nervous about sudden delistings after iEnergizer, but CMC is listed on the main market (FTSE 250), not AIM, so I believe shareholders should have more protection.
More broadly, I think the benefits of owner-management generally outweigh any risk that they will act unilaterally to the disadvantage of shareholders.
For a mid-cap like CMC with a main market listing, it's not something that would concern me at all.
Roland
Dear Roland,
Thank you for your detailed reply and explanation (and sorry for attributing your piece to Paul - I was using the tiny screen on my mobile!)
Would you be concerned if CMC Markets (LON:CMCX) was AIM listed?
Other than doing an internet search, is anyone able to list the main differences between a Main Market listing Vs AIM Vs Aquis etc, particularly with regard to shareholder protection and similar please?
Hi Mjfgs - no problem!
I'm afraid I can't answer your second question without some detailed research.
But in answer to your first question, no. Speaking personally, I wouldn't be too worried if CMC Markets (LON:CMCX) was AIM listed.
Having said that, opportunistic de-listings of even mid-size businesses can happen occasionally - FDM (Holdings) (LON:FDM) is an example where the founders took it private opportunistically and then relisted a few years later.
Ultimately, you pays your money and you takes your choice.
In my experience, the benefits of owner-management generally outweight the risk they will act unfairly towards minority shareholders. But there are always exceptions and risks. That's part of the nature of stock market investing.
Roland
Thanks Roland...I asked ChatGPT and here is his/her/its/their answer:
The **Alternative Investment Market (AIM)** is a sub-market of the **London Stock Exchange (LSE)** that is designed to help smaller companies access capital from the public market. AIM allows these companies to raise capital by listing on a public exchange with much greater regulatory flexibility compared to the main LSE stock market³.
Some key differences between AIM and the Main Market (Premium segment) include:
- No minimum number of shares to be in public hands on AIM, while there is a minimum of 25% shares in public hands on the Main Market¹.
- No trading record requirement on AIM, while there is normally a three year trading record required on the Main Market¹.
- Prior shareholder approval is required only for reverse takeovers and fundamental disposals on AIM, while it is required for significant transactions, including significant acquisitions, disposals and related party transactions on the Main Market¹.
- Admission documents are not pre-vetted by the Exchange on AIM. The FCA will vet an AIM admission document where it is also a Prospectus under the Prospectus Directive. On the Main Market, a prospectus is pre-vetted and approved by the UKLA¹.
- A nominated adviser and broker are required at all times on AIM, while sponsors are needed for new applicants and significant transactions on the Main Market¹.
- There is no minimum market capitalisation on AIM, while there is a minimum market capitalisation of £700,000 on the Main Market¹.
Some other differences between AIM and the Main Market (Premium segment) include:
- Compliance with a recognised corporate governance code or explain why not on AIM, while compliance with UK Corporate Governance Code or explain why not on the Main Market.
- The role of the nominated adviser on AIM is to ensure that the company is appropriate to be quoted on AIM and to advise on, and to ensure that the AIM Rules for Companies are complied with on admission. The nominated adviser can be the same entity as the company’s broker (who encourages trading of the shares in the market) – and so it is important to carefully consider their selection. As required by the AIM Rules for Nominated Advisers, the nominated adviser must undertake extensive due diligence, advise the company of its primary or secondary market disclosure requirements, be available to advise and guide AIM Companies for which it acts at all times and liaise with the Exchange and the company’s other advisers.
Most of it fairly obvious I suppose.......
We dare not ask it what our so called conservative government has done for our country over the last 12+ years. Best not go there.
iomart (LON:IOM)167p +2.36% up on open. Results out today. In line with forecasts except fcf is higher than expected. There is a free broker report out by fincapp who have a tp of 260p.
Technically it is looking promising. Trading above the 50 and 200 MA. Golden Cross formed recently. Cup and handle pattern created which in theory should give a target of about 256p which coincides with the broker target. A safe entry would be a break above the 183p recent high with a safe exit of about 230p.
In response to Paul's request in the podcast for more posters I thought I would do a little writeup to hopefully encourage a few others to get involved. I was always too shy to post for fear of sounding out of my depth, however I recently decided to do a writeup about the use of AI to research how busy Revolution Bars (LON:RBG) sites might be. The positive response from the community gave me confidence to write on the board more frequently. I want to start by saying - I am very new to the world of investing, having bought my first ever share on 4th January 2022 (impeccable timing I am sure you will all agree). I do not have a business background of any form, I actually work as part of the Leadership team in a Secondary School. I am currently 34, so hopefully have a lot of time ahead of me to make/lose money!
Like many others I feel a combination of awe and intimidation reading some of the comments around company analysis. Personally, I would not know where to start with the finances, but it is important to note that I feel comfortable with this. It is okay for others to know more than you and for me personally, I am content to rely on the experience and expertise of others. The SCVR is a goldmine for company specific information and unlike boards like ADVFN and London South East, is not full of people trying to ramp or short specific stocks.
My short time investing has been a bit of a rollercoaster and I hope one day to see one of these bull markets that get talked about so frequently. I have managed to just about break even since Jan 2022 (although down compared to if I had stayed invested in cash) mainly thanks to a handful of US stocks (Alphabet (NSQ:GOOGL) , Crispr Therapeutics AG (NMQ:CRSP), Crowdstrike Holdings (NSQ:CRWD)) and a lucky Seraphine bid (cheers Paul).
I wanted to use this post to make one key point that I feel is rarely mentioned, maybe due to a historical consensus of buy and hold. As small investors we do not have many advantages compared to the big boys, but there seems to be one standout - we are nimble. I don't think this gets discussed enough. Being able to read an RNS in the morning and bail out bang on 8am if there is even a hint of negativity regarding guidance has saved me a small fortune this year. Recent examples include On Beach group (LON:OTB) which I was able to sell at the open for 124p, it dropped to 109p by the close. Pan African Resources (LON:PAF) and Gulf Keystone Petroleum (LON:GKP) were similar stories. I just wish I had followed my own guidance with Watkin Jones (LON:WJG) a few weeks back. I recognise I won't always benefit from this approach but it has been crucial in protecting me from some big drops this year.
So my one tip for other new investors: Sign up for the Stocko RNS alerts for all the stocks you hold. Give them a read in the morning and don’t be afraid to be nimble and get out if needed, the market is unforgiving!
Another great post. I look forward to more like this.
"the market is unforgiving" probably the wisest part of the missive, and at the moment especially so, and on any good news it's like trying to get blood out of a stone from the market. Good times will come
Well done Ben, you seem wise beyond your years. Have you used the RNS to try and buy in at 8am? Btw I might add we hold Watkin Jones so probably bought your shares!
I have actually, I did this with Cleantech Lithium (LON:CTL) after seeing Simon Thompsons list of share picks this year. I tried to buy a position in about 4 of his 8 suggestions at the open with the goal of selling them the next day after people had finished buying the tip. I had zero interest in holding the company but made a nice little 20% profit on it which was fortunate. I also bought into Volex (LON:VLX) at the open after Reading Pauls Stockreport that he kindly posted in advance of the 8am open, which moved upwards nicely after purchase.
Cleantech Lithium (LON:CTL) - selling a tiny, non producing, soon to be nationalised, Chilean brine miner was probably a good call.
Hit the lithium bug with Albemarle (NYQ:ALB) currently hopefully oversold but will move on when I can (don't have your selling mentality unfortunately) but at £20bn it should be ok longer term - has Aussie operations so some diversity. Maybe longer term will sell Chilean operations to a nationalised Sociedad Quimica Y Minera De Chile Sa (NYQ:SQM RT) - who knows, it's mining.
If ok with riskier space then Andrada Mining (LON:ATM) could be interesting. Revenue from tin but has found lithium and needs a funding/partner for developing. Put £200 worth in the ISA for a laff.
Albemarle (NYQ:ALB) is one of my largest holdings and my largest US share, I am currently about 10% up with them having bought when Lithium sentiment was in the toilet a few months back and then the Chile news. I do see this one as a long term hold for the next few years minimum. I agree it should be much safer holding than a lot of the more speculative options around lithium.
ALB is perking up today I think UBS positive. Also looking at Global X Lithium & Battery Tech ETF (PCQ:LIT) and Sprott Lithium Miners ETF (NMQ:LITP) who probably hold it among others - useful to track the market and if don't have time to research.
Seems motor manufacturers are funding miners to secure supply. And America ramping up its own resources so not reliant on imports. Hot and moving space.
Keep eye on Lithium Americas (NYQ:LAC) (General Motors) American Lithium (NAQ:AMLI) Amplify Lithium & Battery Technology ETF (PCQ:BATT) and someone Ford is sponsoring but lost the note.
As with all 'hot' markets "warning - danger Will Robinson". But you want your EV then it don't grow on trees.
Nice post Ben and best of luck.... having worked in private client and institutional fund management I can tell you there is a very wide spectrum of knowledge out there. Be curious I say... you don't have to be an accounting expert...some people do great reading other signs. Common sense above all else .... and "try" to stay in your lane...ie develop fields of competence. Embrace your mistakes as good decisions of the future... I remember an older senior colleague once saying to me, "I think you are going to make a great fund manager because you have now made every mistake there is"! Which I find amusing... enjoy the journey. It's the best computer game ever invented.
PS use limits if trading in the auction, weird stuff can happen otherwise.
Thanks RDHowarth, there is so much to be learned from others with experience such as yourself - so thank you for regularly taking the time to share your insights with everyone on the SCVR. I totally agree about embracing mistakes, it is how we all learn after all! Nice reminder about always using limits, I am forever fearful of being that tall candle of regret for everyone to see on a share chart.
Hi Ben, how do you sign up to the Stocko RNS alerts?
I find on the today screen, there are far too many news items, on shares in my folios, this has been discussed before, there is no way to turn them off for certain shares, such as Barclays (LON:BARC), who issue numerous RNS each day.
You do this on the stock report of the stock that you are interested in, click on Alerts (top right) then Tick News announcements also top right, hope this helps
Thanks Pmollycule for the explanation - I personally don't turn them on for a couple of my megacaps like Alphabet, or as you say Rusty, they can have multiple daily emails coming through. I feel it is invaluable for my Micro-Mid cap stocks though.
Thanks, I see where you mean now. How quick are these alerts, as I've had some price alerts , very late. I tend to use the Today screen but trouble is that picks up everything in my Folios, around 10% of the whole market.
There should be a box to deselect which alerts you don't want shown on the Today screen.
They arrive in my inbox as an email almost instantly after being posted on Stockopedia.
I believe it picks up whats in your FOLIOS.
Agreed. I put all our stocks in Folio and the RNS/RCS have been very reliable and on time over the past year.
Looking at the Today screen, this morning, I'm getting RNS for stocks I've sold but also for stocks I have never held in my folios. No wonder I get so many.
As small investors we do not have many advantages compared to the big boys, but there seems to be one standout - we are nimble.
Of course, we have one other great advantage - we're not constrained by the corporate requirement to meet targets, so we can be patient and not react to every bump in the road.
timarr
Thats a great post Ben, I had a similar thought to yourself when Paul mentioned encouraging others to post.
Ive been trading since around the dotcom bubble. left school at 16 with no qualifications, worked as a labourer on a building site and other various crappy jobs for a few years.
I only had £500 when I started, made all the usual mistakes of buying tips etc but just loved the mechanics of the market and eventually found my own style. It took 1000's of hours but after 17 years I was a able to buy a house with profits Id made. I now work part time, making more trading than I do from work. If I can do it anyone can, just have belief in yourself, stay level headed and keep buggering on as Churchill said.
Ive enjoyed (almost) every day trading. To me its a modern version of panning for gold
Apart from the basics I know very little accounting or in depth balance sheet analysis (why I love SCVR) Thankfully it isn't necessary , as the lack of Ferrari driving accountants show. Common sense and passion for markets helps paper over most cracks. Oh, and stop losses. I must have a stop loss. As the saying goes "Avoiding stupidity is easier then seeking brilliance"
One other thing Id say to anyone starting is ignore media coverage of economics as theyre almost always wrong. 'Trading economics' have a fantastic app now, info and news are all facts, not Robert Pestons opinion.
Vertu Motors (LON:VTU) this morning announced a further £3m share buyback programme - repurchased shares will be cancelled. An encouraging sign given the current macro uncertainty and I like it when companies cancel shares rather than hold them in treasury.
(I hold)
Vertu Motors (LON:VTU) gave me an online quote to 'buy my car'. Drove to a huge impressive site where the manager said "thats below average" and knocked me down £600.
Not happy but respect car dealers to be "meaner than a scrap yard dog!" or should I say "commercial", which bodes well for the outfit.
Motorway quoted higher (but it is auctioned which came in a lot lower duh!). Impressive website and mobile app - upload loads of pictures etc so all upfront other than mechanicals, which presume you have some liability for post sale).
Sold it privately on Auto Trader (LON:AUTO) in the end - selling personally is hassle, granted, but with email can send all the info and answer questions honestly so the deal is done, including the haggling, so just leaves the personal trust, read the documents and a short test drive.
65p breakout or maybe 70p for Vertu Motors (LON:VTU) but not expecting a bull market in the UK for a long time, sorry. And Mr Bean doesn't like electric vehicles - certainly not my next car.
"And Mr Bean doesn't like electric vehicles - certainly not my next car."
I think he is typical of most celebrities who are fickle with what they like and what they don't - albeit his recent guardian article does raise some issues worth looking at. As a reasonably unbiased spectator i can't see how he has been "duped" in any way - is he simply writing this article to pimp up his own celebrity and max his fees. To me none of the story of electric cars has changed much - so not sure why he has got the hump "now" about them when the evolution has been fairly successful - perhaps his orignal research was lacking perhaps ?. Hmmm looking at his article that has already been updated twice to remove some original "inaccuracies" spouted by him.
I don’t understand your post or logic.
Vertu Motors plc needs a bull market to go up?
Food, variable rate mortgages, govt control on what vehicle you can own, what the hell do you buy that has some future proofing other than the white elephant old tech expensive lump plugged into a lamppost but ticks your "vertu" box and keeps Chinas lithium producers in business. Ask how many battery factories they have over UK's er zero.
But sure if breaks out then were 'off to the races' and will follow with interest.
I haven’t got a clue what you are talking about (I have but they all have nothing to do with Vertu’s balance sheet or business-you are just talking daft basically).
Have a look at Chrysler’s price during the doom and gloom years!
Vertu Motors is returning about 10% p.a. to its shareholders through buybacks and dividends. The share count will be below 280m in three years time , meaning that £2 is still cheap.
The yearly free cash flow is over 15% of its market cap!
They have recently sold a property over 50% of its book value , so the NAV of 65p is way too low in real terms.
Good luck with your investments.
Interims from Driver (LON:DRV) this morning. A good increase in the Europe/Americas business with reduced losses in the Mddle East an APAC. If the latter two can be sorted this could take off.
Equity Development have increased their TP from 49p to 56p (not from the 0.49p shown by Stocko). ED have not reinstated forecasts. The ones shown by Stocko are those from before the suspension over a year ago.
Paul - you last covered in May last year https://www.stockopedia.com/co... - worth an update?
Good morning Paul and Roland. Interesting update from Mercia Asset Management (we hold) on their mobile and gaming portfolio, with 33% of their portfolio in that section it so far seems a well placed bet. Also Vertu (we hold) announce yet another £3 million share buy back and intend to maintain dividends and acquisition strategy. What's not to like? Almost forgot, Driver's interims, back on the road although hardly out of 3rd gear (we hold).
Impressive results from B.P. Marsh & Partners (LON:BPM) . Sensible, well honed long term strategy. Confirms new dividend and buy back proposals subject to receipt of funds following the agreed sale of its 18% holding in Kentro for £51.5m . Diluted NAV 518p versus share price of 348p
I don't hold but would like to.
I think that this is in Graham's sweet spot. But would welcome the views of Paul or Roland.
B.P. Marsh & Partners (LON:BPM)
I have held for a while and am a happy holder - through covid its kinda been a sea of calm compared to some (or most?) of most other holdings. Management seem very safe pair of hands here.
As you say a discount to NAV should be expected but their track record is very consistent - albeit who knows what the future may hold.
Have held B.P. Marsh & Partners (LON:BPM) now for 7 years nearly and have a total return of about 65% and its a steady as you go investment company.
They have started to realize a few of the investments lately and hopefully that might bridge the gap between the SP and NAV. The additional dividends over the next few years will help given the meagre dividends before but the interesting one is how the 6m share repurchase program will work given they have a major shareholder. I am thinking they can only do this with a voluntary share sale for existing holders.
Driver (LON:DRV) - The interim results from Driver Group were ahead of the profits guidance provided during the pre-close update in late April. Progress on costs has been made as the rationalisation programme has kicked in. The EuAm (Europe & the Americas) region has generated a strong performance, with revenues and profitability at record levels and there is further scope on margins and utilisation levels. The smaller regions produced an improved performance, with expectations of delivering profits for the full year. Cash generation remained positive, with net cash amounting to over 30% of the market cap and NAV. Despite the ongoing suspended estimates, the Group is on the path to recovery from FY22. We think the discount to the forward price/book ratio of its peers is too high, particularly in view of the cash. Link to note here: https://www.equitydevelopment....
My morning smallcap tweet: Rubbing sleep from the eyes of opportunity
Cambridge Cognition Holdings (LON:COG) Pennant International (LON:PEN) Windar Photonics (LON:WPHO) Roquefort Therapeutics (LON:ROQ), iomart (LON:IOM)
◄Cambridge Cognition (COG)► £2m contract for a 'pivotal' cancer therapy trial. [SP=99.7 Cap=35m]
◄Pennant (PEN)► wins A$6.4m of contracts, 5 yr terms. Two smaller contracts. [SP=35.22 Cap=13m]
◄Windar Photonics (WPHO)► FY-Dec. Going concern: board 'convinced' co will have has sufficient cash flow for FY23. "However, as the Company foresee and plan for substantial growth in both 2023 and 2024 the cash flow projections rely on the precise execution of logistical plans within the entire supply chain." So how convinced is the board? Outlook: H1 production capacity was fully booked booked at start of yr, focused on increasing capacity by at least 100% to be implemented mid-year 2023. [SP=22 Cap=15m]
◄Roquefort Therapeutics (ROQ)► positive results from in vitro studies for its anti-cancer mRNA therapeutic in breast and liver cancer. [SP=6.42 Cap=8m]
In line: IOM