Small Cap Value Report (Tue 14 August 2018) - CGS, MUBL, HAT, MMH, FCCN, D4T4

Good morning!
Today we have interim results from H & T (LON:HAT), so that's top of my agenda seeing as it remains one of the larger positions in my portfolio.
On the list today we have:
- Castings (LON:CGS)
- MBL (LON:MUBL)
- H & T (LON:HAT)
- Marshall Motor Holdings (LON:MMH)
- French Connection (LON:FCCN) (comment by Paul Scott)
- D4t4 Solutions (LON: D4T4)
Castings (LON:CGS)
- Share price: 402.5p (-5%)
- No. of shares: 44 million
- Market cap: £175 million
This heavy industrial stock reports continuing strong demand from its main customers, but the machining part of the business needs more time to recover to profitability. It's going to move into the company's main headquarters, rather than having is own location. Shares are down 5%.
My view -I'm worried that machining is never going to fully recover from the loss of a big contract in 2017. Return on capital for the group as a whole has deteriorated and may only be restored through some shrinkage as part of the restructuring process.
All of that having been said, the company remains profitable and financially sound. The foundry business is still doing well. This could be worth a look.
MBL (LON:MUBL)
- Share price: 3.75p (-17%)
- No. of shares: 17 million
- Market cap: 650k
AIM Notice and Update on Proposed Cancellation
Thanks to MrC for pointing this one out. I would probably have missed it, as the RNS was published after 6pm yesterday evening. MBL is being fined £125k (reduced to £75k for early settlement) for breaches of the AIM rules by previous members of the Board.
MBL is now a cash shell after its last operating subsidiary appointed administrators (from Begbies Traynor (LON:BEG) ) in June. It proposes to delist and then, as a private company, return cash to shareholders via an orderly winding up.
I dabbled in these shares about five years ago, when I was doing the "deep value" strategy.
I'm glad I quit the stock, as it has achieved very little for shareholders since then.
It reported balance sheet cash of £1.35 million as of September 2017, and disposed of its other operating subsidiary in March 2018 for cash consideration of £0.8 million. I have no real insight into what the current cash balance might be.
I think the market cap at the current offer price of 4p is something like £0.7 million.
That could be very cheap compared to its cash balance, but you have to be willing to go through a delisting and then hope to get paid out from a private company - lots of hassle.
H & T (LON:HAT)
- Share price: 319p (+3%)
- No. of shares: 38 million
- Market cap: £120 million
(Please note I currently own HAT shares.)
I have held shares in this continuously since 2013. So far, so good.
H&T is Britain's largest pawnbroking group, operating 182 stores.
It has much in common with Ramsdens Holdings (LON:RFX), a popular holding among readers of this column. Their differences are mostly around geographic concentration (the two firms rarely compete with each other over the same turf) and product emphasis.
H&T, despite growing its other products, remains at its core a traditional pawnbroker. I am keen for this part of the business to remain strong, because it's what sets it apart from other alternative credit providers. It's the platform from which it can engage in other services: jewellery retail, personal loans, etc.
So it's pleasing to read that the pawnbroking pledge book continues to make steady headway, up by almost 9% to £48 million. There are certain periods when it is necessary to shrink the book - thankfully, this does not appear to be one of those times.
The main driver of growth, however, is the personal loans segment. These have increased by 78% since June 2017, or 19% since December 2017.
One nice little factoid in today's results is that only half of H&T's personal loans now fall under the FCA's definition of high-cost credit. Customers who pay back their high-cost loans may be able to access the lower-cost loans.
Its nice to see this improvement in the mix of credit quality. Loans with longer maturities to customers with better creditworthiness make for sturdier business. And the regulatory threat should be lower for these loans, too.
The overall performance of the personal loan book during these six months didn't achieve quite the same margin as it did last year: risk-adjusted margin falls to 37.5% from 44.5%.
That's still a very strong margin, in my book. I'll make sure to keep a watchful eye on this indicator in future periods.
Balance sheet - net debt increases from £11.5 million to £16.8 million. The covenant test says that net debt/EBITDA must remain below 3x. The actual value for this ratio at June 2018 is 0.97x.
It has happened before that people think an increase in debt at H&T is bad thing. It's actually a very good thing, when it is the result of increased lending (assume that credit risk has not deteriorated).
Growing the personal loan book and the pledge book means more debt is needed to fund these loans. There is nothing wrong with this in principle!
Gold purchasing - a relatively minor operation, it also sees a little bit of growth, thanks to increased volumes.
Fx/Other - H&T hasn't made huge headway into FX yet, but it is improving and it made £1.6 million of gross profit from this service. Other services were flat or lower.
Regulation
This might be the primary risk faced by shareholders, since I think that management and the company's reputation are both extremely strong. Regulation is the thing that could come out of nowhere to dent profits.
The FCA is consulting with the industry at the moment, seeking clarification on various matters. It sounds like H&T are closely monitoring the situation and are well-placed to respond proactively.
Outlook - there is good demand for loan and trading is in line with expectations.
Dividend - the interim dividend increases from 4.3p to 4.4p.
In summary, we have continued progress at H&T.
I've been thinking about topping up recently, in fact. The share price has been a bit soft, perhaps due to weakness in the Sterling gold price.
I like to have some long gold exposure in my portfolio, and that's one of the reasons I've been holding H&T for so long. So it would make sense for me to top up when the gold price is weak.
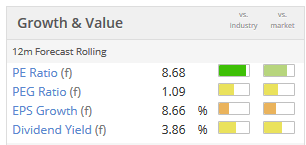
And the valuation does look unduly pessimistic to me. A cheap rating is one of the reasons H&T has a huge StockRank of 97:
The one thing holding me back from buying more shares is that H&T's return on capital is not overly high.
It's much higher than a high street bank, naturally, and is not bad for a financial stock, but it has only very rarely achieved ROCE of 20%+ (and that was when the gold price was enjoying a bull market).
So in the absence of further news I have no plans to buy or sell. A happy holder!
Marshall Motor Holdings (LON:MMH)
- Share price: 156p (-1%)
- No. of shares: 78 million
- Market cap: £122 million
I've only covered this car dealer once before (in March 2017). At the time, the share price was 170p and I said that value investors should be taking a look.
Not much has changed! I can see why readers have been taking an interest in it. The StockRank is 97 and the forecast P/E ratio is only 6.5x (Stocko data).
Checking back to my previous article, I noted that it had completed a very large acquisition and was carrying a big debt load as a result.
But since then, MMH has made a big disposal. It got rid of its leasing division for £42.5 million, making a handsome profit in accounting terms. The rationale was to focus on its retailing activities, strengthen its balance sheet and reduce its indebtedness. Sounds great - I like it when companies are focused on their core activities, without distractions.
So let's take a look at MMH's highlights for the latest period, now that we've caught up with where the company is! All numbers relate to continuing operations:
- underlying PBT up 1.2% to £16.4 million on slightly reduced revenues. The closure of six underperforming sites has played a big role in this.
- like-for-like new unit sales to retail customers down 5.9%.
We would expect the trend for new vehicle sales to be downwards. Compare with Pendragon (LON:PDG).
- like-for-like used unit sales down marginally but revenues up 5.2%. Gross margin improvement. This is attributed to a better management information system and the support of PCP financing, which accounts for most of the company's sales.
PCPs (personal contract plans) may bear some regulatory risk, as they remain somewhat controversial. According to this legal analysis published in April, there is the chance of a fresh mis-selling scandal around how car dealerships and finance companies have sold PCPs to customers. Just something to bear in mind.
- aftersales revenue up 3.2%. This is by far the most high-margin activity, so it's good to see it having a robust performance.
Balance sheet
This is much less complicated than it was when I looked at it last year. We nowhave equity of £200 million, of which tangible equity is £80 million.
There is a small net cash position, rather than a huge debt load.
But MMH has retained its £120 million revolving credit facility until June 2021.
So we could have more acquisitions before too long.
Outlook
The outlook for the rest of the year remains unchanged.
The BoD expresses caution while also arguing that the group is well-positioned for the future.
My view
I can see the attractions to this stock in quantitative terms. It's a straightforward value play: the earnings multiple is exceptionally cheap, and yet the outlook does not immediately appear to be disastrous.
And the balance sheet is sound so there is no reason to use that as an excuse to shy away from it. Although more acquisitions may see debt levels rising again soon.
Personally, I find it hard to differentiate between car dealerships. I have difficulty finding reasons why a customer would prefer to use one over another, apart from price.
For that reason, I am not terribly comfortable investing in the sector. It's sort of the same as with recruitment companies. They are providing a service that many other companies can offer, too.
On the other hand, there is no doubt that MMH's earnings are real and it does throw up an interesting value opportunity.
I think in the end it comes down to economics. A rising tide will lift all boats in the sector, and it's possible that investors are being unnecessarily gloomy about prospects for car sales. I do have a financial interest in the vehicle market through my holding in PCF (LON:PCF).
Even if car sales do keep trending downwards, there is still plenty of aftersales revenue for MMH to generate.
It will be interesting to see what transpires over the next 12-24 months.
Comment by Paul Scott, who owns FCCN shares.
French Connection (LON:FCCN)
- Share price: 48.1p (+0.4%)
- No. of shares: 96 million
- Market cap: £46 million
A brief comment from me on the situation re French Connection (LON:FCCN) and its exposure to House of Fraser. This has been a known issue for some time, for people who understand the business.
FCCN has concessions (a store within a store) in department stores, including House of Fraser. These are typically small operations, with minimal staff and little stock. The way concessions work is that all sales are "banked" through House of Fraser's EPoS system. HoF then sits on the money for, I am told, about 2.5 months.
As HoF has been on the brink of going bust for some time, it was worth working out the potential liability to FCCN. Thankfully, a retail FD friend of mine worked out the figures some time ago. He reckoned there was a potential bad debt to FCCN of about £2m (probably less), if/when HoF went bust.
Since HoF went into Administration, then that crystallises the loss for FCCN and other concessions. Mike Ashley would not be paying those debts as part of his acquisition, as pre-Administration trade payables are unsecured creditors, hence usually are paid nothing in this type of insolvency.
How is the £2m estimated bad debt for FCCN worked out?
Estimated 40 concession sites within HoF stores.
Estimated annual turnover per concession of £200k
Giving £8m estimated annual revenues for FCCN from its HoF concessions.
Assume the bad debt is perhaps 3 months takings, arriving at an estimate of £2m bad debt for FCCN.
That's not material, since FCCN has a market cap about £46m, and has substantial net cash - so it can afford to write off a £2m bad debt without any consequences.
FCCN will also have to write-off fixtures & fittings related to its HoF concessions, or at least the ones that are to be closed. This again will not be material, and is non-cash, so not a problem.
The inventories within HoF stores remain FCCN's property, and if necessary can be moved to other FCCN sites, so there should not be any write-offs relating to inventories.
Going forwards, this might prove a nice opportunity for FCCN to accelerate the reduction of its heavily loss-making retail division. So I feel that, once the dust has settled, the market might actually see this as a positive.
To reiterate, the sooner the FCCN retail stores are closed, the better, as they lose money hand over fist! The value in the business is the profitable wholesale & brand licensing divisions. It amazes me that this is so obvious, yet "the market" seems oblivious to it.
There was a takeover approach last year, which must have been serious, since the board apparently spent several months assessing it & allowed the potential acquirer to do due diligence. It's only a matter of time before the business is sold, because the founder/chairman is into his 70's now, and must be looking for an eventual exit (otherwise he wouldn't have engaged with the potential acquirer last year).
I've worked out that FCCN has several stores which are literally black holes for cash, in terms of losses. The leases on these should soon expire. That means that profitability should make a step change upwards. That's what's interesting about this cash-rich company. The brand is still very valuable, and I'm hoping for an eventual payout here of 100-200p, on a trade sale.
This special situation is certainly one for patient investors only! I'll be insufferable when the payday does finally come, lol!
The recent share price softness, presumably on worries over HoF, looks overdone to me, so if it goes much lower, I'll be topping up. But it's already one of my biggest long positions, so maybe it's not wise to tie up too much cash in this one?
I imagine there is likely to be an RNS from FCCN very soon, detailing the cash losses due to HoF insolvency. It should also give us some detail on the non-cash write-offs (e.g. F&F), plus an update on what's happening going forwards. I imagine this is likely to say that some HoF concessions will continue, but some will be closed. They'll obviously only keep the profitable ones, and this is a nice opportunity for FCCN to re-negotiate terms with Mike Ashley, on a take it or leave it basis (giving him a taste of his own medicine!). Therefore FCCN should emerge with a more profitable concessions operation after this process has been completed. Hence I'm rather looking at this as glass half full, rather than glass half empty.
This section written by Graham.
D4t4 Solutions (LON: D4T4)
- Share price: 168p (+13%)
- No. of shares: 38 million
- Market cap: £64 million
Five contracts announced by this data analytics company.
Numbers aren't given. They sound impressive. The word "global" is used four times!
In addition, we learn that a £19.5 million debtor balance has been paid off.
CEO comment:
In the year to date, and in line with management's expectations, we have been successful in converting a number of significant opportunities from our strong pipeline. This puts us on track to return to more normalised levels of business weighting for the first half of this financial year, against the comparable period last year."
Results have been a bit lumpy thanks to the contract-oriented nature of sales.
I tend to steer clear of anything too lumpy/order-driven these days, preferring a simpler life.
Also, having skimmed D4t4's website a couple of times, I think it would take me a lot of effort to properly understand what it does. I only have time to analyse so many companies.
So I wish everyone the best with this one, but I don't think I'll cover it again. It's in my personal "too difficult" tray.
It does have a good track record of profitability, dividends, etc so it could be worth looking into if you are confident enough to analyse it.
Calling it a day there. Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Re FCCN , it does look as if Stephen Marks is at least open to a sale of French Connection (given serious due diligence last year, sale of Toast) but I think his ego will require the business to be restored to profit first. Rationally, the business should already have been re-sold/restructured otherwise
So we have a schedule that says - next 6 months kitchen sink all bad news outstanding (store closure costs, concession write offs etc), next 6 months show a clear profit, next 6-12 months find a buyer.
Thus, whilst opportunity is there we are still likely at least 1.5 to 2 years off an end game (unless something exceptional occurs (eg crazy offer, Marks heart attack).
Furthermore, what will fill the gap in his life if French Connection goes - currently it is a hobby that generates $500K pa plus salary other lifestyle benefits. Could go on a few years yet.
.......But you need to be innit, to win it.
Graham - great report - thanks for covering Marshall Motor Holdings (LON:MMH)
Really appreciate the value perspective you give on all companies even when value might not be the primary consideration.
Is STAR every going to be covered? Very large link with a major European company being announced end of this month!
There appear to be divergent views on Debenhams at present. Another profits warning on the way and back towards 10p OR part of the great new High St game which is being played out?!
Hi!
A brief comment from me on the situation re French Connection (LON:FCCN) and its exposure to House of Fraser. This has been a known issue for some time, for people who understand the business.
FCCN has concessions (a store within a store) in department stores, including House of Fraser. These are typically small operations, with minimal staff and little stock. The way concessions work is that all sales are "banked" through House of Fraser's EPoS system. HoF then sits on the money for, I am told, about 2.5 months.
As HoF has been on the brink of going bust for some time, it was worth working out the potential liability to FCCN. Thankfully, a retail FD friend of mine worked out the figures some time ago. He reckoned there was a potential bad debt to FCCN of about £2m (probably less), if/when HoF went bust.
Since HoF went into Administration, then that crystallises the loss for FCCN and other concessions. Mike Ashley would not be paying those debts as part of his acquisition, as pre-Administration trade payables are unsecured creditors, hence usually are paid nothing in this type of insolvency.
How is the £2m estimated bad debt for FCCN worked out?
Estimated 40 concession sites within HoF stores.
Estimated annual turnover per concession of £200k
Giving £8m estimated annual revenues for FCCN from its HoF concessions.
Assume the bad debt is perhaps 3 months takings, arriving at an estimate of £2m bad debt for FCCN.
That's not material, since FCCN has a market cap about £46m, and has substantial net cash - so it can afford to write off a £2m bad debt without any consequences.
FCCN will also have to write-off fixtures & fittings related to its HoF concessions, or at least the ones that are to be closed. This again will not be material, and is non-cash, so not a problem.
The inventories within HoF stores remain FCCN's property, and if necessary can be moved to other FCCN sites, so there should not be any write-offs relating to inventories.
Going forwards, this might prove a nice opportunity for FCCN to accelerate the reduction of its heavily loss-making retail division. So I feel that, once the dust has settled, the market might actually see this as a positive.
To reiterate, the sooner the FCCN retail stores are closed, the better, as they lose money hand over fist! The value in the business is the profitable wholesale & brand licensing divisions. It amazes me that this is so obvious, yet "the market" seems oblivious to it.
There was a takeover approach last year, which must have been serious, since the board apparently spent several months assessing it & allowed the potential acquirer to do due diligence. It's only a matter of time before the business is sold, because the founder/chairman is into his 70's now, and must be looking for an eventual exit (otherwise he wouldn't have engaged with the potential acquirer last year).
I've worked out that FCCN has several stores which are literally black holes for cash, in terms of losses. The leases on these should soon expire. That means that profitability should make a step change upwards. That's what's interesting about this cash-rich company. The brand is still very valuable, and I'm hoping for an eventual payout here of 100-200p, on a trade sale.
This special situation is certainly one for patient investors only! I'll be insufferable when the payday does finally come, lol!
The recent share price softness, presumably on worries over HoF, looks overdone to me, so if it goes much lower, I'll be topping up. But it's already one of my biggest long positions, so maybe it's not wise to tie up too much cash in this one?
Regards, Paul.
EDIT - I imagine there is likely to be an RNS from FCCN very soon, detailing the cash losses due to HoF insolvency. It should also give us some detail on the non-cash write-offs (e.g. F&F), plus an update on what's happening going forwards. I imagine this is likely to say that some HoF concessions will continue, but some will be closed. They'll obviously only keep the profitable ones, and this is a nice opportunity for FCCN to re-negotiate terms with Mike Ashley, on a take it or leave it basis (giving him a taste of his own medicine!). Therefore FCCN should emerge with a more profitable concessions operation after this process has been completed. Hence I'm rather looking at this as glass half full, rather than glass half empty.
Hi Paul,
Good to hear from you again. A couple of questions occur to me:
Does FCCN have similar exposure to Debenhams? What's your view if any on the speculation about a "House of Debenhams" merger?
And IF reports are to be believed, Philip Day offered more for HoF than Mike Ashley without insisting on putting it through administration. How could that offer not have been accepted?
Edit: If I was running FCCN I would only re-commit to run concessions in HoF if the money owing pre-administration was made good. Hardball time as you say.
I could easily be wrong but I think Philip Day's proposal involved more store closures and job losses in the short-term than Mike Ashley's.
Hi John,
Does FCCN have similar exposure to Debenhams?
Good question. I looked up the store locator page on FCCN's website, and it helpfully set out which stores are within a House of Fraser, by noting "HOF" next to the store location. It turns out that there are 40 FCCN concessions within HoF stores. So my friend's estimate was exact.
I can't see any reference to any concessions within Debenhams. So perhaps (hopefully) Debenhams might just be a wholesale customer of FCCN? If that is the case, then I hope FCCN is insisting on securing trade credit insurance, to protect against any possible bad debt from Debenhams too.
What's your view if any on the speculation about a "House of Debenhams" merger?
It makes a lot of sense, but only if Ashley can buy Debenhams out of Adminstration, in the same way he has done with HoF. Otherwise it would make no sense at all, for Ashley to take on Debenhams' awful lease liabilities, which are around 18 years remaining on their leases, I seem to recall.
I cannot imagine that anyone else would want to take over Debenhams as it stands, for the same reason. This realisation is why I recently sold my (very briefly held, and small) long position in DEB - because I cannot see a solvent way out of things for the company, longer term. It could survive for some time to come, especially if it sells its Danish business, Magasin du Nord, which is up for sale now.
The only way I can see Debenhams surviving longer term, is if it goes through some kind of restructuring to shed its increasingly onerous lease commitments - so a CVA, or a pre-pack Admin. The catalyst could be withdrawal of trade credit insurance, which seems to be hanging by a thread already.
EDIT: so the risk is that the existing equity in Debenhams could well turn out to be worth nothing, or very little, in a restructuring. That's why I've decided that, for me, the shares are now too risky.
And IF reports are to be believed, Philip Day offered more for HoF than Mike Ashley without insisting on putting it through administration. How could that offer not have been accepted?
No idea, you'd have to ask the Administrator. It was a pre-pack deal. There must be some reason why the Administrator went with Ashley as opposed to Day. Administrators are not always interested in maximising the proceeds, they often just want the quickest possible deal, and to not expose themselves to any potential liabilities. Every case is unique though.
Regards, Paul.
Thanks Paul - I'm a bit surprised but looking further it seems Debenhams don't stock any French Connection items. At least I don't see them on the Debenhams brand directory.
https://www.debenhams.com/content/brand-directory/brand-directory-womens#F
I think principle an administrator cannot favour one debtor over another. Otherwise it could be a bit dodgy for the administrator legally. But no doubt there are many ways to skin that particular cat!
They do like to make sure they get paid :)
Apologies in advance for the flippant comment - you are of course right (in principle!)
Hi Paul,
Just wondered if you have any idea if the cash is in the bank yet re the sale of Toast earlier in the year.
Thanks
Hi Paul, thanks for your efforts on French Connection (LON:FCCN) a very valuable understanding from one of the complexity's within the retail sector.
I couldn't help but notice this comment...
"...because the founder/chairman is into his 70's now, and must be looking for an eventual exit..."
What does this say about J.Murry the chairman of Andrews Sykes (LON:ASY) who is pushing on 100? Would this be a candidate for a bid in the future, or would it just be tightly held within the family and passed down another generation?
Its a very sound company overall so its not a high risk stock for me by any means, the biggest problem is getting a good price on the shares as its very illiquid and the current spread is huge at 580 - 630.
The bad debt that French Connection has is probably going to be £2m at the very least and I'd be stunned to find out if it was anything less, it's extremely unlikely that House of Fraser were sitting on 2.5 months of creditors when they were on the brink of administration. The FD would have done everything possible to prevent any cash whatsoever leaving the bank account over the last few months. Cash for staff wages would have become a priority.
Extract from BBC website re HoF creditors - think the exposure to FCCN might be less than stated above as presumably it would have special mention.
Mulberry (LON:MUL) holders might be interested - no position - but the exposure is 60% of anticipated profit and more than 1% of revenue for a business with a sub 5% operating margin. Although I expect at least some of this was already provisioned / insured.
Good luck all
This morning, administrators EY published a huge long list of all the hundreds of suppliers that are still owed money by House of Fraser since it collapsed.
Total liabilities stand at £753.6m, while unsecured non-preferential claims will be about £484m.
Here is a list of some of the largest creditors:
• British luxury fashion company Mulberry is owed £2,411,570.17
• UK fashion retailer All Saints is owed £1,776,969.87
• Italian luxury fashion house Giorgio Armani is owed £1,590,849.62
• British women's clothing retailer Karen Millen is owed £957,320.10
• UK luxury clothing retailer Jigsaw is owed £440,471.25
CGS grew its machining business with just one customer who walked away, it made the mistake of needing to be customer focused when it is process focused and a good cost controller. Basic divergence of direction between a very conservative board and an entrepreneurial outwards facing add on business. Was never going to do well.
On this occasion the ultra-conservatives on the board have won out. Pity as the business strategically cannot grow into SG castings anymore (it is the European centre for this technology) it doesn't want to get into say steel castings (which is could do by buying a few companies) so back to dull stuff. In fact it is so conservative it could be German. One to buy on the dips and just take divis
MBL (LON:MUBL) - is a situation I would normally be very interested in, but this one looks far too risky. From what I can tell from the RNS the plan does not seem to be to vote on self liquidation at the same time as the delisting vote. The circular, once published, might contradict that assertion so I'm not presenting it as fact. Not to vote on voluntary liquidation whilst the company is public leads to a possibility for such a proposal never being presented to members at all, even ignoring the risk of a vote not passing.
Hi Andy, re: MBL (LON:MUBL) I can only agree! Horrible outcome for minority shareholders. G
Whenever I'm tempted by Marshall Motors I'm put off by the free float of only 23% and the consequent low trading volumes.
It's results day today but as I write not one share has been traded.
Cannot see anything on the horizon which is going to change this.
Phil
Marshall Motor Holdings (LON:MMH) also please, looks solid
Marshall Motor Holdings (LON:MMH) Director's Talk interview with CEO on today's results available here -
https://www.directorstalkinterviews.com/interview-marshall-motors-deliver-robust-h1-profit-growth/412756638
Sharmvr - I think the answer is actually in your question. They are "after sales". Vast majority of new car buyers return to original sales outlet for servicing, extended waranties etc. so Marshalls need to be selling new cars to garner this "after sales" turnover and, as you say, that's where the real profit margins are.
Sure, I'll look into that after HAT. Cheers. G
Second the request for Marshall Motor Holdings (LON:MMH) please.
Tangible Asset backing equal to market cap with a profitable/cheap business attached and a 4% dividend. Margin/return on capital are weak but c'est la industrie!
Looks good - not sure I have room as already hold Vertu Motors (LON:VTU) and there are quite a few cheap dealerships around - probably for a good reason
On a separate note and stupid questions, in this industry, after sales generate 10% of revenue but 40% of profit - why don't they just do after sales
Selling customers cars on tiny margins is the best way to get them to come back to you for an overpriced service!
Hi Graham - it looks like you have your hands full with results today but at some point in August I would love to hear your wider macro/stock market views. I find these very helpful as an amateur investor with a full-time job which prevents me from properly studying the market.
I've noticed a lot of retail shares have come off over the last couple of weeks and some predominately online businesses have also taken a knock over the last week. I assume the latter is related to the Treasury airing the idea of some kind of online sales tax if they can't secure international agreements on multinational tax payments, but I am wondering if it is also a sign of investors reducing risk appetite?
Hi paraic, yes I would like to write some macro commentary - stay tuned. I'll do it when I get the chance! Best wishes. G
Morning Graham - if you have time then some words re: the Contract Wins and statement from £D4T4 this morning would be great.........nothing to do with it being my No1 holding.... thanks!
Marshall Motor Holdings (LON:MMH) interims look solid, with net cash and freeholds.
H & T (LON:HAT) - Interim results. Profit before tax up, basic EPS up (to 13.51p, h1 17 11.7p), large increase in net debt to fund personal loan book and other capital spend but balance sheet looks good (0.97x Net debt/EBITDA)
Reported all segments are up, Prawn broking, scrap, personal loan, fx, retail although reduced margin on scrap (gold price) and retail.
Interesting that FX was up slightly. Will this read across to Ramsdens Holdings (LON:RFX) where the share price has fallen recently.
Hi... Ramsdens Holdings (LON:RFX) is up by 3-4% today so perhaps it is reading across! G
Hi Graham, Re Ramsdens Holdings (LON:RFX). I think that guy from Investors Chronicle tipped it today.
PLP please
My morning smallcap tweet: Rare public censure from LSE for MUBL.
Phaunos Timber Fund (LON:PTF), £D4T4, React (LON:REAT), PHSC (LON:PHSC), Castings (LON:CGS), MBL (LON:MUBL), French Connection (LON:FCCN)
Phaunos Timber Fund (PTF) rejects firm offer of 49c. Is selling off assets, guides realisation of 54-60c within 6 to 9 months, which would cover 92% of the Portfolio Value. Will all sales proceeds from the Asset Realisation Process as they are received, after allowing for cash reserves to wind-down the Company.
D4T4 Solutions (D4T4) contract wins. "D4T4 has record bookings in H2 In the year to date, and in line with management's expectations, we have been successful in converting a number of significant opportunities from our strong pipeline. This puts us on track to return to more normalised levels of business weighting for H1."
React Group (REAT) keep the lights on placing of £420k at 0.3p, a 21% discount.
PHSC (PHSC) finals. Lots of detail on subsidiary trading but I can't fathom if group result is OK. Q1 trading: rev £1.56m (£1.82m), EBITDA £121,815 (£121,351), which included results for ALS (discontinued). "Highly encouraging growth in revenue and profit from QCS gives us an expectation that overall and on a consolidated basis, 2018/19 will see an improvement on 2017/18."
Castings (CGS) AGM stmt. Demand from main customers remains strong but "the level of reorganisation at CNC Speedwell is such that we do not foresee it returning to profitability during this financial year."
MBL Group (MUBL) RNS late last night. Public censure for failing to report poor trading in Sept 2017 www.londonstockexchange.com/co... Also will shortly publish Circular and Notice of General Meeting re mooted delisting. This has been a massive crock, with late-as-possible results only the tip of the iceberg of contempt for holders.
French Connection (FCCN) Times says Mashley won't pay HoF concession debts. He'll only pay for sales since Friday. There was wishful talk of pressure on him to pay. Ha! I hold.
Thanks for pointing out MBL (LON:MUBL). Looks like a grim end to its stock market presence. G