Small Cap Value Report (Tue 16 June 2020) - macro, IND, DLAR, RNO, ECK

Good morning, it's Paul here with the SCVR for Tuesday.
Estimated timings - I have to stop by 1pm, because the XJS is going in for its MoT.
Edit at 12:49 - today's report is now finished.
I've got a bit more material left over from my weekend preparation session. Some of this is probably already out-of-date;
Commentator snippets
I like to review many sources of information & views, and have CNBC audio running in the background on my computer, during the afternoons, as there are often good interviewees (when they can get a word in edge-ways, as Joe Kernan’s questions are more like speeches, then he interrupts them within seconds of them starting to reply! Dreadful).
Plus some of the women have voices like an angle-grinder running at maximum rpm. And don’t even get me on to Jim Cramer. Hence the mute button needs to be kept close to hand.
In between those annoyances, there’s often some terrific commentary, from high profile guests. When I hear something interesting, I jot it down on my pad. Recent snippets;
Nikola - this seems to be a zero turnover US listed company, currently valued at c.£20bn. It is hoping to make electric cars at some point in the future. The share price has been a multi-bagger lately, as punters pile in, speculating that it’s the next Tesla (I’m short Tesla - yes, again! Glutton for punishment springs to mind). The name of the company is a hat tip to Nikola Tesla, the inventor & electrical engineer from history.
This was cited as an example of market mania, or “mass psychosis” as one commentator put it, which is currently gripping the US markets. His stance was that millions of “clueless retail investors” were chasing up junk shares (including essentially insolvent companies) using a platform called Robin Hood. They are often trend following, and using stop losses, therefore this is sowing the seeds for explosive boom & busts in many share prices. A very interesting point I think. Last week’s large & rapid pullback in the US markets (which spilled over into the UK market) seems to validate this view. With valuations so high, despite dire economic news, I think we should therefore work on the basis that there’s an elevated risk of more sharp pullbacks.
Automobiles - Jim Cramer pointed out that the public may be reluctant to use public transport. He therefore thinks that there could be pent-up demand for cars. Therefore we might see a surge in demand for new/used cars, as people shy away from both public transport, and ride-sharing schemes, possibly? That makes sense to me, hence why I’ve recently gone back into Vertu Motors (LON:VTU) on a small scale.
Carl Quintanilla made a good point, saying that whilst there seems to be pent-up demand as the economy re-starts, this could be a short-term boost only. How long will it last? Another good reason why I’m leaning towards banking gains on the re-opening trade, if such gains materialise.
Net debt - the brilliant, and hilarious, Mark Brumby of Langton Capital made an excellent point in one of his daily emails (highly recommended) last week. Namely that the net debt, and cash burn figures being reported by many companies, are not reliable. This is because other creditors are building up - such as withheld rent payments, trade creditors not being paid, plus of course large liabilities backing up with HMRC for deferred VAT & payroll taxes. None of these liabilities are included in reported net debt figures - which are only for interest-bearing debt.
Once businesses resume trading, and Govt support schemes begin to unwind, then these backlogs of creditors will need to be paid. This could be problematic. Therefore I think we would all be well-advised to not take reported net debt figures at face value. They could be the tip of the iceberg when other liabilities are included. A great point, thanks Mark! He also points out that auditors may refuse to sign off accounts, which is another point to watch & be aware of. Hence I think general solvency issues could well take centre stage again in the coming months. How many more placings can the market absorb, I wonder?
Mergers & acquisitions - accountancy giant PWC is apparently predicting a boom in mergers & acquisitions, due to private equity and sovereign wealth funds having so much available cash. It makes sense for the cash-rich to pounce, when assets are on offer at distressed prices. Trouble is, the massive & rapid action by central banks & Govts has caused markets to rebound so much, that it’s difficult to see many bargains around. It is noted that Warren Buffett has not been out shopping, which he did back in 2008-9.
Fed speech - I was listening to Powell of the Fed, give a speech last week, and it sounded distinctly gloomy in tone. This is what triggered the big sell-off in the US markets late last week. You could see the market searching for positives, realising there weren’t any, and then a fall started & seemed to gather pace with every sentence Powell uttered. The crux of his speech, is that interest rates will stay low into 2022.
I don’t see how interest rates can possibly rise now, maybe ever? Govts have too much debt, and need to keep the cost of servicing & rolling it over, as low as possible. If bond markets don’t want to buy the newly issued Govt bonds, then they just hit the QE button to create guaranteed, and potentially unlimited bond buying. Where does it all end? Nobody knows, but vast money printing historically has always ended in disaster, with debasement of currencies & hyper-inflation. Anyway, Powell said that the recession underway is likely to be worse, and last longer, than people might think. Clearly that’s taken some of the froth out of the markets, rightly so.
US Presidential election - CNBC said a few days ago that Democrat Joe Biden had inched ahead in the polls. He favours higher taxes, which would be negative for share prices - maybe a catalyst for a 10-20% market fall, if he looks like he might win?
My opinion - make of that what you will. I'm just reporting interesting things that caught my eye from the numerous news & views that cross my desk every day.
.
Re-starting of non-essential retailing
These days, I live in a slightly down-market suburb of Bournemouth, when I'm not in London.
Curiosity got the better of me yesterday, and I walked into the town centre, to see what the re-opening of non-essential retailing looked like. Would the town centre be thronged with shoppers?
It was, what I can only describe as, a damp squid. Mid-to-late afternoon on a Monday would never be busy, but it was not exactly thronging. Importantly, only a few, large, shops had actually opened - JD Sports, Zara, River Island, Primark, Debenhams, plus of course Boots & Superdrug had already been open for a while. Apart from that, most of the smaller shops, building societies, and of course all the restaurants, cafes, and bars, were shut. Hence there was little point going into the town centre at all.
Maybe Bournemouth is a secondary, or even tertiary town (dunno, who makes these things up?), but the grand re-opening was completely devoid of fizz. In fact, it reminded me how incredibly annoying youths on skateboards are, making that loud clattering noise, over & over again. Why would I want to share space with them, and hobos asking me for money? Buying stuff online is easier, and means that I don't have to rub shoulders with people I would rather completely avoid & pretend don't exist. Sounds harsh, but that's the reality for most of us.
Maybe things might improve in town centres, once the office staff come back, and populate the space in their lunch breaks, etc. But will they come back? Isn't it easier to work from home, and maybe have the occasional day in the office, until the lease runs out & it's vacated completely?
As it turned out, I bought a £3 meal deal from Tesco, and sat on a wall, feeding myself, and people watching. I noticed lots of other people enjoying (as I did) the town centre beginning to come alive again. But as we sat around on walls, I reckon many other people were probably thinking the same as me - what is this town centre actually for, when we can buy stuff online?
Possibly it might be better once the bars & cafes re-open? You can easily see which ones are preparing to re-open, and which ones have owners that have given up, and won't be re-opening. The ones that survive should have more market share.
Overall, I reckon it's likely to be a real challenge to get many smaller towns working again. V-shaped recovery? I don't think so.
IndigoVision
AIM - Suspension
I must mark the tearful passing of IndigoVision from the stock market. It's a Scottish digital CCTV company. It has been taken over, by Motorola, at a reasonable price of 405p per share, which was a very good 129% premium to the prevailing market price. The deal's gone through now, so the shares are being suspended forever.
My involvement here was interesting. I spotted the company's potential back in 2002, when many small technology shares that floated in the tech boom of 1998-2000, ended up crashing as much as 99% in value, from the dizzy speculative highs. Some of these shares saw the market cap drop below their own bank balances. I came up with the idea of agitating, as a shareholder activist, to persuade such companies to distribute cash back to shareholders, rather than continue burning the cash on a hopeless business model.
This worked very well. I set up 5 shareholder action groups, attracted a lot of attention from the press, and set up websites where other shareholders could pledge support, and discuss the situation. All 5 action groups worked well, and we achieved over 100% gains on all 5, over an 18 month period in 2002-2003. This was what convinced me to give up my FD job, and instead become a full-time shareholder activist in Sept 2002.
IndigoVision was next on my list, as it was only valued at £2m, but had about £10m cash in the bank! So I bought about 8% of the company, then flew up to Scotland to meet management & discuss what could be done to unlock shareholder value. The meeting went well, and I became convinced that the company's leading-edge digital CCTV systems, were the future. Management's revised, lower cash burning business model seemed to make sense, hence I swung behind management and supported them, rather than trying to oust them.
Business took off, and the shares 30-bagged, from 30p to £10. I made about £5m profit on it, but then lost the lot in the 2008 financial crash, due to having foolishly geared up too much in illiquid positions totalling well over £10m underlying. Unfortunately, my financial demise at the time also blew a £2m hole in Spreadex's balance sheet, which I feel very sorry about. Fortunately, they were very reasonable about it, and over the next few years we worked out a payment plan & haircut, and the matter is now fully resolved on a solvent basis. I made the last payment about 5 years early, since my new portfolio really took off in 2016 & 2017 onwards.
Hence why IndigoVision is seared in my memory, as the share that made me a millionaire originally, but then dragged me all the way back down again, when it crashed in the 2008 crisis (along with everything else). It's a good story, to remind people;
- Not to combine gearing with illiquidity - a toxic mix, and
- Try not to fall in love with a share that makes you a huge profit - this is very difficult to do, as many multibaggers fall most of the way back down again, hence being disciplined about selling, to bank the profits, is vital.
- Don't let success go to your head - as the hubris that sets in, sows the seeds of future disaster.
It's a good story, so thought I'd repeat it here for any newer subscribers who don't know about my previous successes & failures!
.
De La Rue (LON:DLAR)
Share price: 157p (up c.8% today. at 10:25)
No. shares: 104.0m
Market cap: £163.3m
(I have a long position, at the time of writing)
Good news here - the Serious Fraud Office has decided to discontinue its investigation that started in July 2019. It is taking no further action.
I did wonder why this share price was zooming up yesterday, when everything else was collapsing. Clearly someone knew something - possibly it might have been announced elsewhere?
My opinion - I bought some of these shares, after a very bullish update recently. There seems a convincing turnaround underway. The balance sheet will need to be fixed at some point, but that doesn't bother me, because institutions seem happy to support fundraisings for companies which have a good recovery story.
I think there could be further upside here, if nothing else goes wrong. Hence I'm just running the position, and we'll see what happens next.
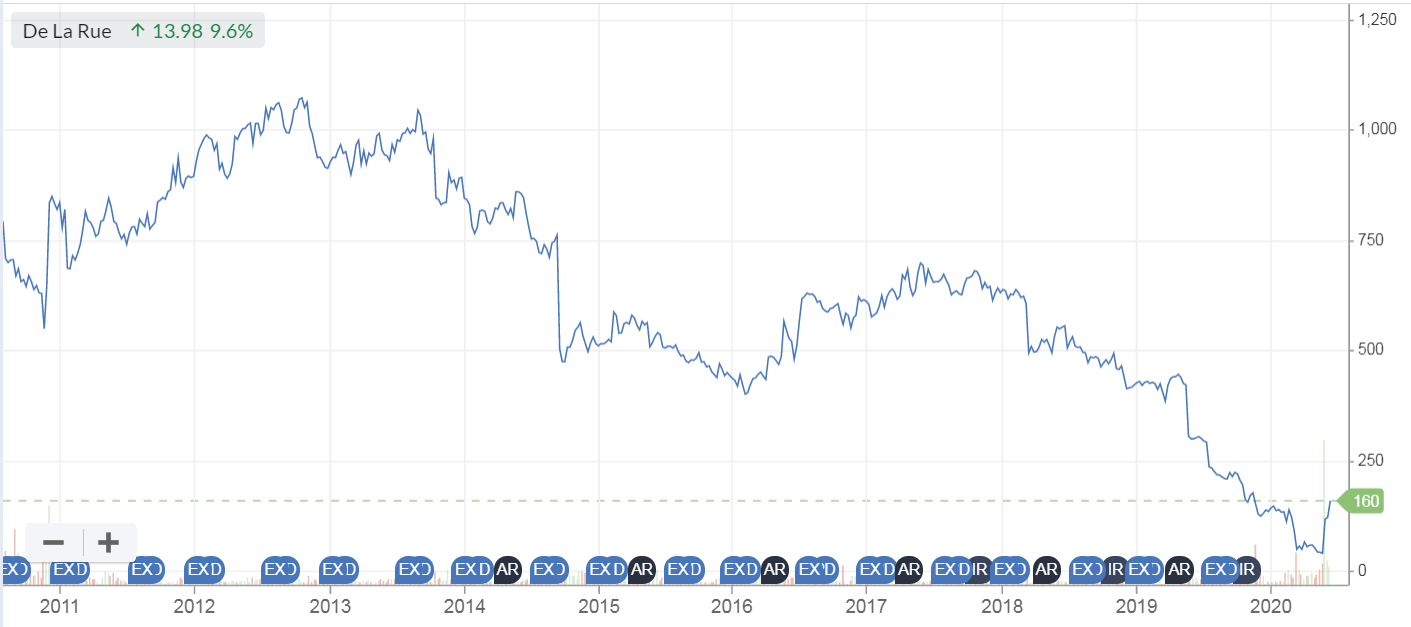
The recent share price recovery looks little more than a blip on the 10-year chart of shareholder value destruction;
.
.
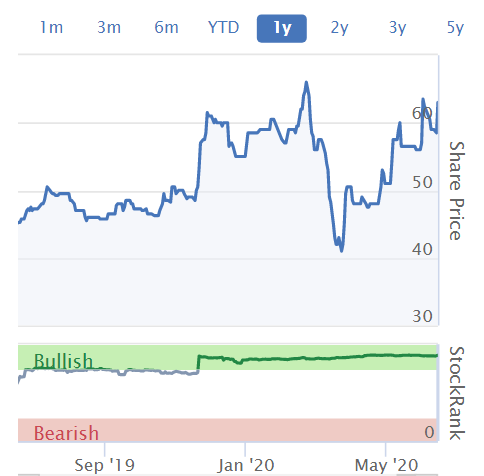
However, if we zoom in to the last 6 months chart, you can see what a spectacular recovery there has been. Mind you, anyone who bought at the lows was taking a big risk, as the company looked precarious at the time. It's since pulled a rabbit out of the hat, with some good contract wins, so is now lower risk, hence the big share price rise;

.
Renold (LON:RNO)
Share price: 9.8p (up 36% today, at 11:16)
No. shares: 225.4m
Market cap: £22.1m
Renold, a leading international supplier of industrial chains and related power transmission products, today announces its preliminary results for the year ended 31 March 2020.
This share is top of the leader board today, and it's a company that I've previously seen as having potential.
FY 03/2020 figures look a bit lacklustre - adj EPS is down from 3.1p LY to 2.9p TY (this year) - a PER of only 3.4
- Significant impact from covid-related factory closures in "final months" of FY 03/2020
- Operational efficiency improved in Chinese factory
- Torque Transmission division has traded well, profits up
- Restructuring successfully completed
- Bank covenants amended, increased flexibility to Sept 2021
- Key point - cash generative & profitable in the first months of FY 03/2021 - very important, and reasssuring
- No guidance given - due to uncertainty & volatile demand
- Confident it can manage through current period of disruption
- No divi due to covid
Balance sheet - this is the main problem. It's got too much debt in my opinion, and also a huge pension deficit. This is shown as a £97.6m liability on the balance sheet. However, with interest rates now effectively at zero for the foreseeable future, that increases the valuation of pension scheme liabilities. This means that shareholders probably won't be getting much in dividends in the future, as the company mainly exists to service the pension schemes & repay debt.
I can see possible upside on the equity, because the share price is now so low, that the equity is almost an option on the company surviving & recovering from covid disruption. The commentary today suggests that it should survive, and might be able to do so without diluting existing equity holders with a fundraising, possibly?
Overall then, looks to have speculative upside, in my view. But be aware of the risks from its weak balance sheet. Worth a closer look.
.
Eckoh (LON:ECK)
Share price: 63p (up 8% today, at 12:24)
No. shares: 253.9m
Market cap: £160.0m
Eckoh plc (AIM: ECK), the global provider of secure payment products and customer contact solutions, is pleased to announce unaudited results for the twelve months to 31 March 2020.
The summary of these results is;
Results in line with market expectations; strong revenue and profit growth
Earnings - financial highlights look impressive. Adj diluted EPS is up 62% to 1.75p - a PER of 36.
Recurring revenues are 79% of the total - giving good visibility
Balance sheet - fairly good. Note that the cash pile is offset largely by creditors - i.e. Eckoh benefits from receiving cash up-front from its customers.
Outlook - sounds good;
· New financial year trading is encouraging, with Group revenue and profit comparable to the previous year
· Notwithstanding the disruption relating to COVID-19, the Board remains confident of the future prospects for the Group, underpinned by balance sheet resilience, high recurring revenues, excellent sales pipelines and the long-term market opportunity
My opinion - I've followed this company for many years, and it seems to at last be delivering on the potential.
If earnings growth continues at such a strong level, then this company could rapidly grow into its valuation. Therefore, looks potentially interesting, worth a closer look.
.
.
That's it for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

100 comments
Activist fund Crystal Amber Fund (LON:CRS) should take a lot of credit for the turnaround at De La Rue (LON:DLAR) they managed to replace the awful previous management after taking a 19.2% stake
Superb story Paul - that keeps you feet on the ground as they say
Agree with some of the other posters Paul write that book not another how to buy stocks effort but your real life adventures reckon you would have a lot of sales on Stocko subscribers alone.
Hope this time round your hanging onto the millions
Idox (LON:IDOX) H1 20 results presentation to analysts, given yesterday 15.6.20, including Q&A, view the video or listen to the podcast.
The new management team, headed up by David Meaden, CEO, seem to be doing a good job. Highlights: Revenue up 13%, including 10% organic growth. Recurring revenues 53% of total revenues. Revenue visabiity strong, with 90% FY20 contracted. EBITDA increased 133%.
Separately, piworld webinars coming up. This Thursday 18th June, 1pm, we have ex bond trader, Paul Hawkins, telling us Everything you wanted to know about Corporate Bonds. Having just run through the content with him, I know it's going to be superb. Register here.
The following Thursday, 25th June, 12.30pm, Codemasters Group (LON:CDM) CEO, Frank Sagnier & CFO Rashid Varachia will present the groups results for FY20. There will be the opportunity to ask questions. Register here.
Fantastic report Paul.
Fascinating story r.e Indigovision! WOW
What a great story on IndigoVision Paul!
You really add a lot of value and also colour to the SO site and I constantly come back during the day to see if there have been any updates by yourself or Graham to this section.
Dexamethasone - a cheap steroid found by UK scientists to cut covid death rate by 30%. Quite a significant discovery.
Great news !
Thanks for the pre-amble. Very interesting.
“I don’t see how interest rates can possibly rise now, maybe ever? Govts have too much debt, and need to keep the cost of servicing & rolling it over, as low as possible.”
What happens when or if we get inflation due to the amount of extra money being pumped into this system but then maybe for some reason this won’t feed through into inflation?
As for the high street, I really think it would be for the best if it was put out of its misery as soon as possible. What use it will be put I am not sure.
PS Paul please write that book!!
I think thats the point of the zero interest rate. Financial repression - deliberately keeping the interest rate below the rate of inflation to inflate away government debt. As all countries are doing it there is no hoped to be no impact on the exchange rate.
”Estimated timings - I have to stop by 1pm, because the XJS is going in for its MoT.”
I hope it passed! I had one (V12) over 30 years ago the most beautiful car I had ever owned and the most expensive, under full acceleration you could watch the needle on the petrol gauge move. The affair with the car lasted 6 months.
Are there any (many) MOT stations open? I thought there was a 6 month extension to MOT's expiring after March? ie Only vehicles with their MOT already expired before March need to get one if they are to be put back into use. Maybe this is the case with your XJS Paul? I am an interested party as I have an MOT station tenant in a property.
Joules (LON:JOUL)
I was intrigued by the +40% e-commerce demand the company mentioned this morning.
The revenue figures up to 2 weeks ago show something completely different.
---
The only way the +40% demand figure makes sense is if one includes marketplace revenues, which look to have grown about +67%...but only from £1.8m in FY19 to £3.0m in FY20.
Retail e-commerce revenue for H2 (for a year which ends May 31st) is up only 0.3% Year-on-Year, so essentially flat at £42m.
I would have expected this latter figure to rocket over the last few months and it must surely be a concern that it hasn't.
It's also worth noting that the +40% demand figure the company mentions includes VAT and does not allow a provision for returns, so essentially meaningless as far as I am concerned.
No position, and no plans to have one at this stage, though if the 40% demand growth turns into 40% e-commerce revenue growth then I plan to investigate further.
Hi Paul
Thank you for the comments on Renold (LON:RNO). To me this is a case of a good business being buried by the pension deficit - i.e. yet another casualty of QE - and so not an investment proposition. Maybe I am giving too much weight to the pension problem.
Hi Paul,
Re: Nikola
I've been playing around in this as I came across them at a hydrogen conference last year. I no longer have a position. A few random points, currently there is only 6% of the equity floated, a lot of the equity will come on to the market shortly. There is a warrant that I am trying to understand better but theoretically may get you into the shares at a 50% discount. The borrow with IG is currently 500%!!!!!!!!! so i can't actually hedge it out.
They have a commitment from AB Inbev to move their whole fleet of trucks to Nikola, so they theoretically have 10bn of forward orders. They also gave a big order to Nel in Norway( hydrogen infrastructure play).
There is a lot going on in this space and this will be a stock worth watching but it will be crazy and I have no idea how it ends. This one is way less crazy than Hertz :), at least it won't be bust next week!
"...what is this town centre actually for, when we can buy stuff online?"
Paul, this seems to me a question which is important and almost never asked.
There are repeated studies and initiatives to preserve/restore/ rethink our high streets, but rarely, if ever, is it doubted that we must do some such thing.
If, as seems to be the case, the high street is largely redundant, it seems to make sense to let it die a peadceful death. If it has value, it will survive anyway.,
I wouldn't rubbish the robinhood movement completely: rather than naive retail investors it is more of a crowd-sourced market manipulating machine led by the likes of Dave Pourtnoy, a US internet phenomenon with a huge following : they revel in trolling Wall Street professionals and lampooning "the pinstripes". While it may well be gambling, it is not without method in its madness. These are "smash and grab" day traders who rapidly cycle through their targets as they cynically poke fun at their nay-sayers.. much use of "ok boomer" and other millennial @ phenomena
Pourtnoy has dubbed Buffet "washed up ": His Twitter timeline makes hilarious reading and he has over 1.5 million followers so he/they can move prices in their social media coordinated buying and selling ( he was a buyer even as Berkshire was a seller of airlines right at the lows)
These may well be pandemic "flashes in the pan" but equally disruptors do tend to be disruptive and are often dismissed at first. The deficit of sports gambling during lockdown does seem to be instrumental in providing some of this liquidity... along with the other numerous tidal waves of liquidity from multiple sources .
On macro, the FED announcement of broadening their buying of corporate bonds is significant and likely was instrumental in yesterday's dramatic intraday reversal : does look like stock markets are effectively being nationalized
I find CNBC to be full of noise and hysterical attempts at market narratives but do listen to the Fast Money podcast which aggregates a lot of the sense and removes the dross. It's also EOD so less likely to skew biases intraday.
Robinhood is the new algo trader....they trade with matrix powers making the data, rather than chasing the data
current markets seem to more like The Matrix: "red pill or blue pill" being an apt metaphor for participation
Hussman believes that the FED's buying of corporate bonds is illegal.
One of the insidious risks that the Fed has taken during this downturn has been to violate Section 13(3) of the Federal Reserve Act. While the Fed has the authority to buy Treasury bonds and other securities that are guaranteed as to principal and interest by the U.S. government, 13(3) requires it to take collateral when it buys corporate debt, or otherwise lends to corporations, and that collateral has to be “sufficient to protect taxpayers from losses.”
See, if the Fed did not require sufficient collateral to prevent losses, and the Fed was to actually lose money as a result, it would have actually engaged in fiscal policy – effectively granting public funds to the corporation, or to the investor that sold the bonds. Of course, the Constitution vests sole fiscal authority in Congress, so transactions by the Fed having fiscal effect would be unconstitutional, which is why the Federal Reserve Act (as well as section 4003(c)(3)(B) of the CARES Act) prohibits this sort of transaction.
Treasury may use a portion of its $500 billion in support to eligible businesses, States, and municipalities, under 4003(b)(4)(B), for the purpose of “purchasing obligations or other interests in secondary markets.” But the Fed claims it has the authority to “leverage” CARES funds by a factor of 10-to-1 to make secondary market purchases of corporate debt, including junk bonds. Even members of Congress have asked Jay Powell to identify why the Fed believes it has that authority.
The moment the Fed purchases corporate bonds beyond the amount of CARES funds directly provided by the Treasury, without taking collateral, it violates explicit “requirements relating to loan collateralization, taxpayer protection, and borrower solvency” that the CARES Act emphasized like a children’s book – using the phrase “For the avoidance of doubt.” The moment any of the Fed’s purchases generate a loss beyond CARES funds directly provided by the Treasury, it will have extended this violation to include Article 1 Section 8 of the U.S. Constitution.
Someone needs to take it to the supreme court. That's probably unlikely as no thanks will come for doing it (at least not until after corporate bond buying were to blow up)
FDR went thro many constitutional battles particularly around his revaluation of gold relative to USD (ie depreciation of dollar) and the severing of the gold clause common in all bonds issues (public and private) after the Civil War promising to repay in either dollars or gold coin at the price fixed at issue. FDR administration won the case by 5 to 4. Historically they are considered to have lost the argument but won the day as realpolitik prevailed. Note this was just the beginning of series of battles with the court many that FDR lost but he won this one as to overthrow FDR's action would have bankrupted US overnight.
There was great moral outrage from financial and legal industry and many politicians (at the time that included a lot of Southern Democrats as well as Republicans). It was the end of US, moral bankruptcy, the whole system would collapse, etc....but markets loved the change and it helped begin the very slow process of stopping the huge deflationary pressures (I view FDR as villain in many regards too so I'm not a pure fan boy...but to his credit he took some leaps in the dark that very few experts supported).
Hussman and others in finance who complain about Fed actions remind me of the above. He seems like a good guy and I think his analysis is well worth reading....but on stuff like this along with other Wall St talking heads he's talking his book and layering on a immorality/illegality angle to fluff it....he doesn't like that the game has been changed on him and that he missed it in his analysis. Be careful the models and the data.
Like i said yesterday:
Option 1 = debt deflation driven depression
Option 2 = something else
https://www.stockopedia.com/content/were-all-fomosapiens-now-621583/
We are going option 2...good luck working it out....be careful of being sucked into intellectual robust and beguiling option 1
So we're cheering on pumping and dumping? It's just a bucket shop - sure it uses social media, but it's just the same old techniques, front runners leaving the gullible holding nothing of value. I recommend @bagholderquotes on Twitter
Not sure I'm permitted participation, but what the hell...
I've got a new one for Mr Contrarian...Checkforshit
I had a look at Checkit (LON:CKT) results today and I found it hard to unpick. I'm not expert and didn't spend a lot of time but here's my quick reccy:
1) They seem to use different approaches to accounting for disposal within income and cash flow statement. Income statement implies a hefty loss which includes £5m of operating loss. CF statement implies positive operating CF. Income statement is after disposal but CF statement includes disposal in operating cash flows. On net basis it seems they really burned about £5m op cash.
2) It seems year to date this c.£1.2m for 4 mths so a reduction on last year....but hard to know the extent to which this could be working cap positive (they are working with govt which has made a point of being early payers recently) and then there is the C19 slowdown, support and any furlough to consider. All could really help cash position for a pre profit company
3) They fully wrote down the value of last years acquisition (Checkit!). Ie they have decided the cash generation for their new enterprise is effectively zero. This seems unlikely to me and its kitchen sinking. If they do believe it then holders look out. Whatever it is it feels like a warning light to me. Either there's trouble or mgt are aggressively manipulative of financials (see 1 above!). The positive is that if the business is real in 2-3 years time then the earnings are higher as no amortisation or later write down of goodwill. You may like this and see it as 'cleaning'...but its not really playing by the rules...it leads me to look back at the big disposal last year and think that accounting during year was fudged to maximise valuation ahead of sale and that the Checkit acquisition is really just a free option to give Keith something to play with.
4) Auditors are unhappy with them. Its not 100% certain what the problem is but its stated that they don't like the 100% intangible write-down. They will "qualify" the accounts. I speculate whether this a bigger falling out and perhaps discomfort with other things like 1 above
I think Checkit and Keith have many fans....interested in why things are good?
hi Mojo
Can't complain about Checkit (LON:CKT) as a medium term shareholder. They did very well with their asset sale of Bulgin and have a strong track record of shareholder value creation rather than the many "shareholder destructive" companies out there. I am happy that Keith Daley holds over 20% as ultimate manager of the business so I still own some. I don't get the sense this is just a toy for him. I think he genuinely believes in it and given the types of agreements he had signed pre covid with the likes of BP he is clearly onto something. Obviously he still has to make it work though. He came on board Checkit as an activist investor and then as a director. He is credited with growing the business 10 fold over a few years which is why he has a following.
Cash makes up almost all of the market cap, though obviously still loss making currently so cash burn needs to be watched. Interesting that they wrote off intangibles. Almost certainly kitchen sinking I'd say. Not entirely sure how I feel about it. Auditors obviously feel as though it is too aggressive and there remains proper value in the business.
Happy to stick with it here and see where business goes post covid.
Jim Cramer pointed out that the public may be reluctant to use public transport. He therefore thinks that there could be pent-up demand for cars.
Whenever I find myself agreeing with Cramer I have to go lie down for a while to calm myself. However ... I think he's right, although most likely it'll be second hand cars that people choose. My preferred play here is Auto Trader (LON:AUTO) which provides exposure to the market but carries none of the capital overheads or, in fact, any need to actually go anywhere near the cars in question.
On the point about liabilities backing up and not appearing on balance sheets that's also a valid concern. I've been steering clear of companies that have taken government support because I can't figure out the impact - although there are plenty of other reasons for that given the sectors that they're in. A lot, although not all, of that support comes with strings attached as well - larger, longer term UK loans mean dividends, buybacks and bonuses are banned until repaid.
At the moment markets are such a mess it's hard to discern the signal in the noise but anything reporting growth is being bid up remarkably, even where the odds were stacked in their favour - Cmc Markets (LON:CMCX) and Best Of The Best (LON:BOTB) are the two most recent examples of companies whose prices have shot up after reporting an entirely predictable surge in earnings.
To me this looks like a two tier market - those companies mainly based online are continuing to do OK while those in the real world are largely struggling. Yet most of the action is around the latter - if I didn't know any better I'd say we're seeing a lot of investors suffering from familiarity bias.
But who knows? Investing in current markets is like picking your way through a minefield - it's possible, but one wrong step and the whole damn thing blows up.
timarr
Thanks for the reminder. Been meaning to add AUTO. Hope it doesn't now send the stock down
If you like AUTO look at $CARG - a bit more volatile but more growth potential
Timarr..Auto..Do you know if the directors inc chairman are invested to a significant level in the business as it appears difficult to find this info and you with a holding probably know this as I agree with you as Auto is a great way to get new and used exposure to the car market which surely is going to have a new scrap page scheme in the July budget..Thanks
Hi Tonysaparito
Autotrader director shareholding here: https://www.sharesmagazine.co....
As you can see the Chairman and a CEO have large financial stakes, although compared to the market cap they're not really significant. With companies this large I never worry overmuch about director holdings - they'll be handsomely rewarded anyway. Smaller cap director shareholdings are much more important, IMV.
I think you're right, there has to be some support for the industry to try and boost new car sales. Not sure that will benefit Auto Trader (LON:AUTO) directly but it's such a well run company that I don't think it matters. I really liked the proactive way they immediately raised money as soon as the crisis hit and then dropped fees for all of their customers in April and May. There was no magical thinking going on, they assessed the situation and responded accordingly.
timarr
Thank you timarr, much appreciated..Tony...PS.You are like another Paul
I think you are right about the car market. However, I also think people will be cautious with money. On that basis I think relatively cheap, nearly new cars will be in demand. I have invested in Motorpoint (LON:MOTR)
In terms of demand stimulated by not wanting to commute I personally think this is limited by parking and more people working from home.
There are some interesting TR-1’s also with heavyweight and successful investors holding quite large positions in Motorpoint. I am up 30% already and will hold.
To counter that many people will get more years of use out of their car without all the commuting miles. Family members have said they now expect to hold on to their cars for two or three years longer. Why pay out for a nice car on the drive that hardly goes anywhere?
For those who do want a new car this is a genuine a once in a lifetime opportunity to find a deal.
Let’s see. It will be interesting to track the performance of Vertu and Motorpoint. My money is on Motorpoint.
I loved the "damp squid" but have never really enjoyed that many dried ones. Far too chewy.
My guess is that the reason the signs of any turnaround are disappointing has much to do with two matters. First, there is, as far as I can tell from my own life and contacts, no real belief that we are coming out of the crisis, whatever anyone who has a financial axe to grind likes to say to us. We are waiting for the second wave, just as we always expect a dead cat bounce. The height and rate of rise of that wave will dictate to future confidence. It seems as if the government are gambling and only time will tell if they get lucky.
Possibly as importantly, it is increasingly hard to find anyone I chat with who can now trust the government about anything. Far too many opportunities to resolve issues of trust have been mismanaged.
I loved the "damp squid" but have never really enjoyed that many dried ones. Far too chewy.
Glad you enjoyed my little joke! ;-)
Hello Paul,
I certainly think that this is going to be part of the 'new normal' going forward. I work in an office in central London (Victoria) which previously had around 80 or so staff coming in every day. Because I live quite locally (Paddington) and have a relatively easy commute, I have been one of a handful of staff - about 10 of us - who have continued to work from the office throughout the pandemic whilst the majority have been working from home.
When the 'work from home' thing began towards the end of March, shortly before the government lock down, there was much jollity and a general mood of "see you all in a few weeks then". It is now apparent that most colleagues have realised that there is no point in commuting into the office every day and that they will continue to work from home even when the lock down finishes.
I can see this probably having consequences for the likes of Starbucks and Pret who tend to rely on hurried office workers popping in for their morning coffees or lunchtime sandwiches to consume at their desks. Also the likes of Waterstones and Holland and Barrett. Victoria Street is hardly a 'destination' shopping area so people working from home in the suburbs will probably either shop locally or buy their books and vitamins online. And why have the expense of an office that can accommodate 80 staff if only a fraction of that number are going to be working there?
I suspect that commercial areas in town centres are going to look very different in future.*
Gostevie
* Not that it will affect me that much because from September I shall be finishing with the wage-slavery and going into semi-retirement / full time investor mode with perhaps the odd bit of consultancy if it becomes available and if I fancy doing it. :-)
One more single data point:
My office is in Farringdon and like Gostevie above we had a sort of end-of-term feel to the start of lockdown, with everyone expecting to be back before too long. Two weeks ago my wife and I gave notice on our Camden flat and are moving to Norwich for a year to see if we like it; I'm happy to work from home if my 'home' morphs from a one-bed flat into a 4-bed house and I REDUCE my monthly bills. I think house prices within a two-hour commute from London might be in for a bump.
Does anyone know why the ongoing (and historical) Net Profits at Synectics (LON:SNX) are so meagre, given their not insubstantial Revenue?
Checkit (LON:CKT) is not THAT bad - still, even at these lower prices, 18 million market cap for a company with 10 million revenues, and annual revenue growth maybe 20% feels a bit rich to me. The situation is a bit confused by the purchase of Next Control Systems - didn't make sense to me. I don't hold, but it is one to watch.
ED say this today about Checkit (LON:CKT) "In line with the company announcement on guidance we suspend forecasts, whilst noting a current enterprise valuation which stands at a 41% discount to FY20 revenue and 34% discount to the purchase price of Checkit UK Limited." (their emphasis).
I hold, largely because Keith Daley is chairman and holds 21%.
Checkit (LON:CKT) cash is £13m so strip that out and the business is actually being valued at £5m which actually appears relatively cheap for a £10m revenue business with some blue chip clients etc.
Daley made investors around 10* their money up to selling the Bulgin business, so plenty of shareholders happy to see him take the reigns and own 21% of the stock given owner led businesses tend to outperform.
Well that's all good then...no need to checkit what they are doing now :)
The cash is not much different from say a mid stage biotech seeking to commercialise a product - it is funding not safety. How will you look upon an equity raise in 18 mths time to commercialise the product more? Don't know if that is what happens but not sure why Bulgin history counts for very much...and whats with the odd accounting?
Remember this business was called Elektron (same management): The Bulgin history matters because at the time Daley recognised the potential of Elektron and the Bulgin brand and delivered for shareholders. In the course of that evolution they also built the Checkit product. Eventually decided that the new business had more significant potential than Bulgin. They sold the Bulgin brand for a good premium and returned most cash to shareholders, retaining a significant chunk to grow the remaining business.
Why does that matter (1) because they have a ready to go customer list given the extensive relationships they had within Bulgin and will have done extensive customer feedback and (2) have a track record of winning business and growing margins; cite BP deal and (3) have a strong track record of enhancing shareholder value over time. So it matters quite a bit.
Your comments on an equity raise look spurious. Feels like you're scrabbling around for something contentious. They have £13m in the bank and will only use about £5m of that in the next 18 months so there's enormous headroom for any delays to profitability due to the Covid situation. (note they used £1.3m in the first 4 months so around £300k p/m outflow if they don't grow revenues at all). Daley owns 21% so I doubt he will be keen to dilute either unless maybe he wants to buy another bolt on business, but as ever I will assess the rationale if or when it occurs and not try to second guess it arbitrarily.
At present the EV of the business generating £10m+ of revenues is £5m or 0.5* sales. For a tech business with Skas model that is too cheap in my opinion so happy to own for now.
I don't know why the rather aggressive approach to intangible write offs. I would like to find out more on the rationale for that. I suspect opportunistic tho.
David, Do you know whether there's a management incentive scheme and, if there is, what the KPIs are?
David
Thanks for your points. I put up my low knowledge negatives as I was interested in understanding a little more as clearly a situation that could interesting due opacity and an owner with track record. Some responses to you:
Equity raise point is matter of fact. The've got overheads over their revenue. They need to invest more including scaling customer handling ahead of growth given the focus on premium/big customers. In addition, they wrote down all their acquired assets to zero....that should be read as a problem. C19 isn't a good excuse for it as the reasonable assumption is that the world has not ended.
I think it probable that cashflows benefit from C19 interruption at the moment as it allows for hard cost cut.
Daley has his money and this is his net fun project. He's not that sensitive to when or how it works.
It remains quite a dangerous if interesting situation and the prior Bulgin record is not a safety blanket I would hold on to...I'm very willing to rate people and don't know Daley and so may be missing the point. I do own outwardly flaky businesses as I think mgt are good plus dynamics not understood enough.
My hunch is that I will get a chance on Checkit (LON:CKT) at a lower price. The share price rise today on what was not a good report suggests over optimism short term
On the 'robinhood' effect
Having read the articles on FTAV on Hertz where it is noted that the company is in Ch11 and all equity is likely to be wiped out,
I suspect it is a means of transferring money from retail punters to more skilled traders
I think that the one of the challenges of someone who is not a full time trader and doing this around work, schooling children (who look like being at home until at least September now) and wondering how to deal with work if we are called back into the office or the boss is a little less forgiving for the constant interruptions when on calls, or that a lot of the work is done at 05:00 or 21:00 each day. Not to forget supporting three sets of parents with very different levels of demands depending on the minute, hour or day, is managing the emotion of it all.
Trying to continue learning from what felt like previous mistakes I stop loss'd out of a number of positions last week, "tick" protect the capital that I am trying to grow to be able to help fund University Fees, House Deposits and hopefully our retirement. So whilst it was ouch, and why did I not sell two days ago??? Felt within that it was the right thing especially when the DOW went down too.
Then within less than a week a number of the positions have bounced back above where they were before they had even started going down - having created a did I do it right with the stop loss portfolio. Massive FOMO this morning and why did I do that you numpty!
Addition to the original thoughts, obviously the stop loss positions have stayed in cash...so have the capital but miss the bounce hence the FOMO!
Is it just me kicking myself massively?
I went in and then out of Tupperware Brands right before the recent price spike, missing out on a movement that would have increased the size of my ISA by c.25%. You can't time the market old chap, just be reasonably happy if you make it through all this volatility with your shirt intact.
I sympathise, that is the problem with stop losses. Consider this - if you didn't have a stop and several of your favourite shares dropped 5% along with the rest of the market, would you rush to sell them? Possibly not. With a stop on, you don't have a choice in the matter (other than to take it off quick). You have to use stops very carefully to avoid just what happened to you (and me in the past).
But I bet you slept easier knowing x amount of your portfolio was ring fenced.
I do the same and unless I really like the company, remove it instantly from your portfolio screen and don't check the price again for months, it always appears to go up, but a lot of them bounce like cats.
There's always another bus coming, just don't jump on the first one and wait until you see Paul in the driving seat
Many of us have been there. About 20 years ago I had a stop loss got kicked out on a down spike which was literally a few seconds. That was a 20% stop loss and then the shares rocketted.. Cured me, I dont know about the validity of rumour of market makers fishing for stops. It certainly seems like it sometimes. Pros and cons to everything. The main concern is in a crash its doubtful they would work anyway. Do you set a minimum price to sell at or a sell at any price? If you set a minimum price and they can't sell, then they just carry on falling. I dont know if its changed now, but am sure someone will correct me if I'm wrong. A good discussion though.
If any of us could trade without ever making an error we could own half the world by Christmas. Everyone gets things wrong all the time so don't hold yourself to an unrealistic standard of perfection, especially so now.
But trading while stressed is not good. I would step back and take a rest and deal with all the other challenges at the moment. You need to let that regret and emotion subside before getting back in.
At times like this I usually go back to my investing books. "Come Into My Trading Room" by Elder or "Reminiscences of A Stock Operator" by Jesse Livermore come to mind.
I'll probably get shot down for this, and I'd certainly welcome feedback telling me why I'm wrong, but I'm not sure that stops are appropriate in such volatile market conditions? Every guide I've read by experienced traders says to use stops and I'm definitely still very much learning, but it seems to me that every time I have set a stop it has ended up costing me money. If I set stops at all now its at least 20-25% below current price. Maybe stops are more appropriate for traders than investors? I'm generally looking for stocks that I'm willing to hold long term and in that case I don't think it makes sense to get stopped out every time there is some bad macro news and the whole market dips. The exception for me is if I want to lock in profits of a stock which has risen significantly but don't want to miss out on further rises by selling.
Painful lessons ..personally I don’t set automatic stop losses as you are then a sitting duck for the infamous tree shake. Just set an alert here and then use your own judgment if it’s a genuine drop or not.
Best of luck !
.
“ Plus some of the women have voices like an angle-grinder running at maximum rpm. And don’t even get me on to Jim Cramer”
And I thought it was just me! Actually, I don’t mind Cramer, Kerman’s way of asking questions is very annoying. As for angle grinders running at maximum, I had more of an image of a perpetual motion machine dragging finger nails down a blackboard! Really strange how some voices are irrationally irritating.
So, I shall offer a prize for the best description of an irritating voice. The initial money is saying Robert Peston may be the subject of the description, but you may know differently.
Prize to be paid in a worthless cryptocurrency I have just invented, hereinafter to be known as Scottcoins, or should that be Screechcoins?
I always think of Kermit the frog when Cramer speaks!
'It was, what I can only describe as, a damp squid'
Think you mean squib. One of the most common mistakes apparently. :-)
Ah, but do our friends know what a squib is and what happens to it when it gets damp? Takes me back.
Reminded me of the IT Crowd sketch on damp squid/b
Hilarious clip, I absolutely love The IT Crowd. That must have been where I got the joke from!
It's just my little joke!
I wonder what a squib is -maybe a squid that's evolved to live on land lol
Thoughts from Mr Brumby this morning on the future of online gambling and potential future legislation.
Some 50 MPs have called for a ban on all gambling advertising and a cut to £2 in the maximum stake allowed online. The All Party Parliamentary Group for Gambling Related Harm said today that UK gambling regulation needed a “complete overhaul” and added that Covid-19 had exacerbated the need for better protection for vulnerable people. The report says ‘we cannot continue with the current lack of regulation for the online industry. We have an industry that is profiteering from vulnerable people gambling more than they can afford.’ Iain Duncan Smith is the vice chair.
I saw an interesting stat on CNBC yesterday showing a surge in buying activity from Robinhood traders when the market tanked in March. Feels like a win for the little guy. I wonder if they will go back to sports betting when that is available again. Interestingly I also hear that the Robinhood app will be available soon in the UK, interesting potential new competitor for the likes of £IG and £CMC etc. There is already an app available in the UK where you can trade for £0 commissions I use called freetrade, very useful for buying US stocks without the ridiculous FX and commission costs.
John Authers, in his excellent daily email, today discusses the impact (largely new) RobinHood traders have been having on the markets, and their excellent timing (so far).
Yes was going to mention this newsletter on the topic of Robin Hood traders. Excellent as always from John Auther, it would be good to have something similar from a UK markets perspective. The link in the newsletter to a piece by one of his colleagues at Bloomberg was also an interesting and humorous take on the situation. Here it is if the link works!
https://www.bloomberg.com/opin...
"There is already an app available in the UK where you can trade for £0 commissions I use called freetrade, very useful for buying US stocks without the ridiculous FX and commission costs".
I don't see how you can avoid these costs - I think you'll find they're just hiding them in the spread.
They don't set the spread with regular stock purchases. The business model depends on revenue from elsewhere (ISAs with Freetrade, CFDs with Trading 212 - see below).
Trading 212 has better FX charges for US stocks than Freetrade (and a bigger stock universe).
Nice article here on the Robin Hood business model:
Around 40% revenue made from routing trades to high frequency brokers
Other mainstream brokers also use this approach
Net interest margin on average of 10% cash account deposits
Other brokers eg Etrade, TD Ameritrade make around half their revenue this way
Robin Hood Gold subscription $5 a month has Level 2 and margin trading.
RH also seems to have some lending stock activity.
Overall, the RH model seems to be low price / high volume and not very different from other brokers.
https://blockworksgroup.io/blog/robinhood-sells-your-data-but-does-that-matter
On the subject of execution only brokers: I have been really impressed with A J Bell throughout the pandemic. Often, when there is no online price available for the trade I want, they have filled a limit bid within minutes at a price inside the spread. That's worth their £4.95 or £9.95 commission, to me.
Agree on the costs etc and in the case of say Robinhood they get paid for order flow, mainly from high frequency trading firms (you can guess what the HFT does with that ) and that's another reason why when the names Robinhooders are involved in the momentum increases significantly. Robinhood SEC Rule 606 Report disclosure Q4 19
interesting r.e free trade. I’ll take a look. I wonder if the spreads are much wider thus compensating for lack of fees?
dread to think what my HL dealing fees are from being essentially a day trader from March-June.
I think many Robin Hood traders used their “stimulus checks” to fund their accounts so their timing was driven by the stimulus timing rather more than market judgement.
The big question is whether the US government will load up the helicopters with more money or not.
”a damp squid”. I can see that phrase catching on.
memories of Fools and Horses " The world is your lobster". Thanks for your thoughts on this "opportunity" Paul.
Anecdotal story on potential demand for office space. My son works in New York City. His firm has been “working from home” for three months. Yesterday, the CFO informed all employees (around 100) that the firm, after reviewing efficiency over the pandemic, had given notice on the office lease and home working would now be the firm’s ongoing method of working. Perhaps his employers’ situation is exceptional (IT development firm, loss-making and with offices in Manhattan - so presumably not cheap)...
Thanks for the Bumby tip Paul, was part of daily life 5 years ago so I welcome this addition to the wealth of free content private investors can access these days.
If you enjoy the where does it all end debate, check The Grant Williams podcasts. Grant and Luke Growmen are also on We Study Billionaires this week which is good listening.
Fed comments yesterday reversed $ strength and its back at a critical level... good for markets. Watch US Treas today for follow through... they weakened a little yesterday ie Yields ticked up. These moves are ok for the market....for now.
Retail: short blog from Richard Hyman about yesterday's reopening: http://www.richardtalksretail....
Small data point. An outdoor market which is run by a company in which I am invested reopened on Saturday 13th. Stall rents reduced and only half the usual number of stalls, so less than half the usual income but increased costs. OTOH a reasonable turnout of customers and one stallholder sold out.
My view is that many retailers will survive with smaller estates and new approaches to merchandise ranges, store layouts, and the relationship of online to physical stores. But the number of stores and the overall square footage of retail space will decline, especially in centres where a significant percentage of customers used to arrive by bus (or in some cases train) if the 20% capacity rule continues. I also think the demand for office space will reduce. There's no sign of a permanent end to business rates or even a revaluation, and other costs are rising not falling. So if there is a reduced demand for space it has to be the rents and hence property values that take the strain. We might see the long-foretold end of the long Institutional FRI (full repairing and insuring) lease with upward-only rent reviews. Commercial property landlords may have to accept lower rents on easy-in/easy-out leases and do the repairs themselves. If I am right this will hit pension funds hard. The warehouse REITS are a special case.
On a broader point, yesterday was the deadline for businesses with >99 employees to enter the 45 day redundancy consultation period and complete the process before the furlough payments reduce. Only one large announcement (Travis Perkins (LON:TPK)). I expected more.
Thanks for the Richard Hyman link. He forecasts that clothing shops will suffer from more returns because changing rooms are closed, which led me to wonder about on-line clothing retailers like Boohoo (LON:BOO) and whether they have said how they will handle returns now. Does their business model depend on people ordering multiple items and returning many of them?
I would call it a feature of all online clothing companies. Clearly they would be better off if there were zero returns but around 50% of items get returned. SOS were trumpeting a reduction to 30% from introducing less fitted items. I expect BooHoo customers habitually order multiple items and return the ones that don't fit or appeal. Just like taking multiple items to the store fitting rooms. The reverse logistics chain is key to cost management for online companies.
I can't remember which company, but my sister told me she was actively encouraged to do that by one site she was shopping on at the weekend.
"Not sure which size to go for? Buy both and return the one that doesn't fit".
I did just look on the BooHoo website and saw updated information about deliveries but nothing Covid specific about returns.
Checkit (LON:CKT) if possible Paul. A radical change is in progress and the opportunities look significant. I’d welcome your accountant’s sceptical view.
The Checkit (LON:CKT) StockReport looks dreadful so I wonder what Paul could find attractive there. If it’s a transformation then I guess it must be a bet on the future potential rather than the historical figures. What do you find attractive in their new direction?
RE: £CKT
"Its products use Internet of Things (IoT) software applications, smart sensors and cloud analytics."
It's a full house on my speculative tech bingo card!
My morning smallcap tweet: 17 RNSs covered.
PureTech Health (LON:PRTC) £TM17 U and I (LON:UAI) 4imprint (LON:FOUR) Clipper Logistics (LON:CLG) Yourgene Health (LON:YGEN) Amiad Water Systems (LON:AFS) ClearStar Inc (LON:CLSU) De La Rue (LON:DLAR) Joules (LON:JOUL) Bidstack (LON:BIDS) Dialight (LON:DIA) ValiRx (LON:VAL) Synectics (LON:SNX) Epwin (LON:EPWN) Ilika (LON:IKA) Science (LON:SAG)
PureTech (PRTC) get FDA clearance for clearance for it's non-drug EndeavorRxTM as a prescription treatment for children with ADHD. Uses a video game experience.
Team17 (TM17) has started to see the unusually high levels of demand during April and May returning to a more normal level. New consoles and new IP launches across H2 creates a more unpredictable backdrop. No FY guidance.
U and I (UAI) gets planning permission at Landmark Court, a £240m Public Private Partnership scheme, subject to the standard six week procedural and s106 process. Expects c.£10-15m development and trading profit over 5 years.
4imprint (FOUR) order counts have steadily increased towards 50% of 2019 level, from 20%. Net cash $28.1m after $9.4m pension fund payment.
Clipper Logistics (CLG) advanced discussions with Arcadia Group for a transportation contract.
Yourgene (YGEN) covid testing and 'passport' collaboration agreement with payments company Caxton and immunity passport app Prova. Caxton will offer tests to its extensive network of corporate clients and their employees. Co will provide sample collection kits, training and running the test. Not clear how significant this is.
Amiad Water Systems (AFS) 5 year global distribution agreement with Netafim for disc filtration products for the irrigation market. No numbers.
ClearStar (CLSU) has not yet returned to our pre-covid revenue run rate but increase in sales so far is extremely encouraging. Optimistic that FY will not be as bad as feared.
De La Rue (DLAR) SFO has decided to discontinue its 11 month investigation.
Joules (JOUL) guides FY(May) in line with rev down 12%, pretax -£2m to 3m. E-commerce demand from start of lockdown to the end FY(May) up over 40%, significantly ahead of expectations. Collection of wholesale receivables was better than anticipated. Inventory position marginally lower than the prior year. C/F has been ahead of its covid base case scenario and significantly ahead of downside scenario.
Bidstack (BIDS) gets Internet Advertising Bureau's Gold Standard certificate 1.1, the first multi-device in-game advertising platform to do so, though it's a year since the 1.1 standard was published.
Direshite (DIA) improving, but volatile, order intake, especially in the US. "Due to the temporary closure of our facilities in April our order book is higher than we had expected, but we are increasing deliveries to customers week-on-week and have reduced the overdues backlog." Guides net debt at FY 2020 broadly flat YoY. No FY(Dec) guidance except it will be H2 weighted.
ValiRx (VAL) basic remuneration for Board, employees and consultants (pro forma)c. £300k cf £900k in FY18. Trying to dispose of its licence in GeneICE but no sale yet. Will therefore terminate licence due to high patent costs. SP down 99.6% in 5 years.
Synectics (SNX) wins £1m contract to provide surveillance systems for a major offshore oilfield development in the Middle East. Will be delivered mostly in this FY.
Epwin (EPWN) All sites are operational to some degree. Demand is returning, albeit at significantly lower levels than normal. Available cash and facility headroom remains at c.£45m.
Ilika (IKA) no order cancellations and expectations for FY21 remain unchanged.
Science Group (SAG) guides H1 adj op profit up 50%. Market share has been maintained.
"Direshite (DIA) improving, but volatile".
Am unsure whether this is a comment on a company or the British economy.
Once again Mr Contrarian you are really pulling out the stops to summarise these company results so quickly. Thanks for your hard work! I rather enjoyed "Direshite" too!
Mr Contrarian - Interesting pseudonym you have for Dialight this morning!!!!!
Pleased with ECK's results. Maybe only market expectations but double digits and profits surge are most welcome in this environment.
I wasjust looking at mortgage backed REITs, most are paying a yield of 13%. either they contain some high interest mortgages or someone has lost a lot of money.
Also has anyone done any research on CLOs, theyre meant to be ground zero of the next debt crisis.
More on topic to Pauls intro, (thank you Paul as always), Oxford Streets re opened yesterday and footfall was 80% down on this time last year (according to channel 4 news)
Oxford Street is reliant on tourists. It won’t be back to normal while we have 14 day quarantines on people flying in.
Similarly for Bournemouth. I don’t know it very well but I remember a lot of language students, Uni students, etc. Don’t the locals shop at Castlepoint rather than in the town centre?
I did some passing research on CLOs at the weekend after reading the Atlantic article.
I delved into the BIS report referenced in that article and this paragraph is somewhat alarming:
Default risk and losses-given-default depend on the quality of the underlying assets. For both CDOs and CLOs, strong investor demand led to a deterioration in underwriting standards. For example, US subprime mortgages without full documentation of borrowers’ income increased from about 28% in 2001 to more than 50% in 2006. Likewise, leveraged loans without maintenance covenants increased from 20% in 2012 to 80% in 2018
I then read the Financial Stability Board report into CLOs and found this choice nugget in the appendix explaining how a CLO is rated as AAA, BB, whatever:
As the actual CLO collateral is generally not fully identified until after the rating is issued, and because the collateral may be traded during the life of the CLO, evaluation of the underlying collateral is complex and may be based on hypothetical portfolios which are modelled under a variety of stress scenarios.
Essentially the ratings agencies don’t or can’t rate the CLOs because they don’t really know what is inside them, so they issue a rating based on a framework which the CLO manager pinky-swears not to deviate from.
I don’t think either of these things are very good.
However, no sign of synthetic CLOs like last time, and banks are generally much better capitalised. On the flip-side, companies have never had so much debt so quite a bit more scope for defaults.
I work in the CLO industry and I worked in subprime as well during its heyday and some less controversial stuff in between. The Atlantic article on CLOs was genuinely one of the worst I've ever read on any topic in my career. the author seems like a nice chap but it made a horrible mess of the topic.
to understand CLOs it makes sense to first think about a normal fund that buys leveraged loans. investors buy a participation in the find and get the asset return net of fess. Leveraged loans are typically non-investment grade and pay something like Euribor + 350-450. There have been a few cycles at this point and net return has been ok (I believe)
CLOs flip the liabilities onto their sides. the manager buys the loans as per usual but this time there are different tranches which the most senior receiving a much lower spread but this is typically rated and is far more risk remote from a credit perspective (in terms of suffering a loss). the tranche below is typical AA and pays a little more and there's A below that etc etc until you have an equity tranche which can pay up to 20% depending on loan scenarios.
there are broadly two systemic risks from CLOs. one, losses in the deals can destabilise the fin system like in 08 and the second is that CLOs disappear and you have a credit crunch due to a loss of credit provision.
The first one is unlikely in this instance because the owners on the more-at-risk tranches equity and B/BB-rated tranches are typically specialist Hedge Funds and Asset Managers. losses in their books pose little systemic issue outside losses in repo etc. banks and insurance do participate but only in the higher rated tranches. for what its worth, the chances of the top part taking losses are extremely remote. I can delve into why but its equivalent to a default cycle that would hobble every bank in the land..
the second risk - permanent loss of credit - has been somewhat assuaged by Fed actions and the market here is coming back to life. there are aspects to the CLO and Loan market that rightly attract criticism but it is *NOT* going to be the epicentre of some 08 type financial meltdown
Cheers for the follow-up Jimbo. I had come to a similar conclusion i.e. 'it'll be probably be fine', but good to hear a voice from the inside.
I'm sure you are a good chap Jimbonambo41, and work hard at what you, do but your post inadvertently explains much of what is wrong with the financial world these days. I'll be happy to explain what I mean if you wish, but please ask on tomorrow's board.
Interesting article in the Wall Street Journal. Cites some risk for insurers if downgrades force requiement for extra capital. No firm conclusion either way.
happy to hear your thoughts.. I dont know if you see this reply or not... I am a much bigger fan of small cap equity than exotic debt instruments so I may surprise you :)
I was in Fitzrovia yesterday and was going for a walk around the neighbourhood. Although stores had opened, it felt very dead. Took a taxi back and the driver was talking about how busy it was and that everyone was out again. Maybe Fitzrovia is just always a bit sleepy...
I live in Hackney and it's been getting busier here by the day. Every pub that does take away beers have long queues and people sitting on the sidewalk drinking. Most places seem to be open for take away food and seem to be doing fairly well.
I saw a video from Paris yesterday, looks like all the restaurants there are already packed! The question is, how long will that last?
I had no idea that only interest-bearing debt would be included in net debt figures, that's a shocker! Where is the FRC when you need them?
Agree with all that,the govt scrapping scheme if it comes could play a very interesting role have a good day