Small Cap Value Report (Tue 2 Apr 2019) - IGP, BON, HSW, WIN, SDRY, G4M

Good morning, it's Paul here.
I got up early to finish yesterday's report, so a new section on Instem (LON:INS) is now up. Unfortunately, the section on Low & Bonar (LON:LWB) vanished when technical gremlins struck, so I'll reconstitute that once we've got some of today's news up in this report. Although to be honest, I don't think you're missing out much if you ignore LWB.
Please see the header for announcements which I'll cover today. Plus anything else that crops up which looks interesting.
Intercede (LON:IGP)
Share price: 23.0p (up 39% today, at 08:09)
No. shares: 50.5m
Market cap: £11.6m
(at the time of writing, I hold a long position in this share)
Today's update covers the year to 31 March 2019.
Intercede is a cybersecurity company specialising in digital identities, derived credentials and access control, enabling digital trust in a mobile world.
I was fearing a profit warning here, because the share price has been drifting down (albeit on negligible volume). However, I'm delighted to read this morning's trading update, where the company has achieved a big last-minute success, namely a major contract win on the last working day of the financial year - talk about cutting it fine!
... pleased to announce that a large US Federal Government order totaling $4.3m was received on 29 March 2019.
The order includes software licenses and annual support & maintenance; $2.05m (£1.57m) of which will be recognised in the financial year ended 31 March 2019.
As a result, revenues are now ahead of expectations;
Subject to the completion of the year end audit, revenues for the year ended 31 March 2019 are expected to be in excess of £10.0m, which is ahead of market expectations and approximately 10% higher than the previous financial year.
This reflects the impact of follow on orders from existing customers plus new contract wins via partners in the US, Europe and SE Asia.
The establishment and further development of these and other partner relationships is critical for the Group's future growth prospects.
Note that in H1 the company reported revenues of £4.17m. Therefore H2 must be over £5.83m - a 40% growth rate from H1 to H2 sequentially. Impressive stuff.
Profitability - a major turnaround (for a small company) has been achieved here. This is very significant, in my opinion;
The combined effect of increased revenues and action taken to reduce the cost base, is expected to result in a return to profitability at both operating profit level (2018: £4.5m operating loss) and after interest and tax (2018: £3.8m loss for the year).
Note that in H1, the company reported a £589k operating loss. Therefore H2 must have been a positive figure of above £589k profit. Very encouraging indeed. Does it matter that the figures were saved by a last-minute contract win? Not really, a contract's a contract. However, it does reinforce how lumpy business can be for a small company like this, dealing with big organisations, for big contracts.
I think today's major contract win demonstrates how remarkable Interecede's client base is - some of the world's largest companies, and Governments, use its software. That's astonishing, for an AIM company worth just over £10m! It says to me that there could be very substantial latent value in this company - that's the reason I own shares in it personally. High risk, but potentially very high reward. The poor track record under previous management is another reason why the market cap is so low.
Net cash - note that gross cash has risen, so the company looks fine (no need for a fundraising);
As at 31 March 2019, gross cash balances totalled £3.2m (2018: £2.3m).
Important note - the company has outstanding convertible loan notes. I gave the details on that here, in Dec 2017. In a nutshell, the debt will need to be repaid by Dec 2021. If the share price gets above 68.8125p, then holders would be more likely to convert the loans into shares (as opposed to requiring repayment in cash). It's conceivable that loan note holders might convert into equity, even if the share price were to be somewhat lower than 68.8125p, because it wouldn't be possible to buy in size in the open market for the shares. They hardly trade at all.
With the share price currently around 20p, conversion isn't an issue.
The Dec 2021 repayment date for the loan notes is sufficiently far out in the future, that it doesn't concern me at this stage. It would be more of a concern once we get to early 2021, if the company has not grown profits further from the current level.
My opinion - this company is really making good progress under new management. The market cap is peanuts, for a company with software that is being sold in multi-million deals to huge international groups & Governments.
It doesn't need to raise cash for now. It's moved into profits. Sequential growth is strong, and existing customers are placing follow-on orders. All of which suggests to me that the product must be world-class. Yet the market cap is tiny.
It's risky, because orders are so lumpy. Without the major order signed last week, we would have been looking at a profit warning today. So I'd like to buy the sales team a beer or two, for pulling off a major result, on the last day!
Bottom line, I'm a very happy holder here. If more big orders flow, then I could foresee this being a multibagger from this level. That's the uncertainty though, we have no way of knowing how future orders will pan out, good or bad. It's just educated guesswork from a shareholder perspective, as is usually the case with most investments - we're trying to predict the future, which nobody can do with certainty, for any share.
Intercede shares are extremely illiquid. On a day like today, stale bulls might use the buying interest to offload, perhaps? With the bull case starting to come good, I'll be sitting tight on mine.
EDIT - note that there's a single page broker update from FinnCap out this morning, available on Research Tree.
Broker update - there are some important points in today's broker update;
- Gross cash of £3.2m as at 31 Mar 2019 excludes any monies from the recent big $4.3m contract win. Therefore, the cash pile should increase further.
- All development spending is expensed through the P&L, so EBITDA is a meaningful number, unlike many software companies. I've double-checked, and there are no intangible assets on the balance sheet - confirming the very conservative accounting.
- Note that Intercede benefits from substantial UK R&D tax credits.
- Substantial upgrade in Mar 2019 estimates: EBITDA Old: negative £1.8m, New: positive £0.4m.
Taking into account all those points, it seems to me that today's 7p rise in share price doesn't come anywhere near to reflecting how positive today's news actually is.
BonMarche
Thanks to Gus, who has flagged in the comments section below, a mandatory takeover bid for this struggling womenswear chain.
Spectre Holdings (a Dubai company, owned by Philip Day, retail billionaire) has increased its holding to 52.4%, at 11.445p per share, triggering a mandatory bid at the same price.
I've not yet seen any response from the Board of BON, so it's not clear whether this is an agreed bid, or not. Frankly, they've run the company into the ground, so existing management now has zero credibility.
My opinion - it's staggering how quickly BON unravelled in the last 6 months. Prior to that, it looked well-funded, and likely to survive if not prosper. However, a bit like QUIZ (LON:QUIZ) , it seems to have run into absolutely dire trading conditions more recently. I think both chains are weak brands, and have just got the product wrong.
Sadly, we need to see a thinning out of the High Street, to allow the stronger competition to gain market share from weaker also-rans.
Graham and I have been increasingly strongly warning readers away from this share here, for a while now. Therefore I hope none of our readers got caught out on this one.
Anyway, it's game over, and I would say shareholders should count themselves lucky to be getting anything. Therefore the only logical course of action is to accept the takeover offer. Given that the bidder already owns over 50% of the company, then the chances of a higher competing offer coming along look very slim.
Hostelworld (LON:HSW)
Share price: 193p (up 5% today, at 10:56)
No. shares: 95.6m
Market cap: £184.5m
Hostelworld, the global hostel-focussed online booking platform, is pleased to announce its preliminary results for the year ended 31 December 2018.
I've had a quick skim of the results, but can't see anything much of interest here.
Internet businesses are only of interest to me, if they are generating big organic growth. The problem with HSW is that it's gone ex-growth. Its non-core businesses seem to be a dead loss, with bookings down 47% to only 0.28m in the year. The core business only managed a 4% increase in bookings, to 7.7m. The average booking is for E11.89 (up 6% in constant currency).
As HSW mentions in today's commentary, it operates in a competitive space.
On the upside, it's still a highly profitable, and cash generative business.
Cashflow statement - looks good. It generates tons of cash, and pays out most of it in divis.
Balance sheet - looks strong, no issues here.
Valuation - as the company has gone ex-growth, then it's no longer valued like an internet company, but more as a value share;
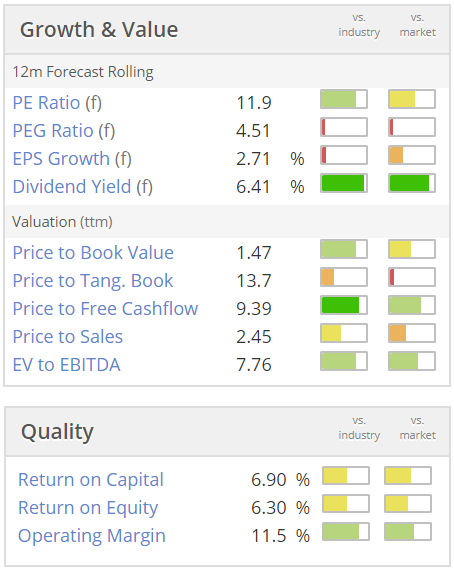
The trouble is that earnings are now declining, as are dividends.
Outlook - sounds OK;
Hostelworld is operating in a highly competitive market, which is growing. We have a very relevant brand which is trusted by a loyal and engaged customer base.
Trading in the first quarter of 2019 is in line with the Board's expectations. We remain committed to delivering value to shareholders and continue to assess our capital allocation approach in line with investment choices and priorities.
My opinion - the newish CEO (from July 2018) has done a review, and is trying various things to stimulate growth. If he succeeds, then this share could be re-rated back up to a growth stock, which would be lovely for shareholders.
On the downside, how likely is such a meaningful resumption of growth, given that there are many, some larger, competitors? The risk is that HSW could end up an also-ran, crushed by giant competitors.
On balance, I think the current share price looks about right. I don't know whether the growth strategy will work or not, hence it's not something I would invest in. If however signs of stronger growth began to percolate through in future trading updates, then I'd sit up and pay attention.
Wincanton (LON:WIN)
Share price: 230p (unchanged today)
No. shares: 123.9m
Market cap: £285.0m
Wincanton, the largest British third party logistics company, today issues the following trading update ahead of announcing its preliminary results for the year ended 31 March 2019.
- Positive H2 performance
- Substantial contract wins - but too late in the year to mitigate lost contracts
- Loss of low margin contracts
Outlook - sounds OK;
The Group's performance was further supported by a strong level of contract renewals in the second half with customers such as Asda, Valero and Marley, which together with the new business wins, positions Wincanton well to deliver revenue growth in the year ahead.
Net debt;
The Group's closing net debt is expected to be approximately £20m.
That sounds harmless, but see below.
Balance sheet - is horrendous still. NTAV is negative, at -£175m as last reported on 30 Sept 2018. The main cause of this deficit, is that working capital is heavily negative - i.e. the business has hidden debt, in that it's receiving cash up-front from customers. There's a large deficit of working capital - net current assets are negative £119.6m. I don't care what anyone says, to me that is a precarious & potentially dangerous position.
Note that the apparently small pension deficit is an iceberg - i.e. only -£28.9m deficit on the balance sheet, but in reality it's a huge scheme, with over £1bn in both assets and liabilities. Deficit recovery payments are large, e.g. from the last interim report;
The Company reached an agreement with the Trustee on the 2017 triennial valuation and recovery plan in the period. The net annual deficit contributions have been agreed at £17.3m per annum increasing by RPI over the three years to March 2021 and £24.3m per annum increasing by RPI from April 2022 to March 2027...
[excerpt from RNS dated 08 Nov 2018]
Checking the cashflow statement, this means that the pension scheme is getting more cash than shareholders receive in divis.
My opinion - the PER here is low for a good reason - because a lot of the cashflow goes into funding the pension deficit, and because the balance sheet is so weak.
Also, why would anyone want to invest in a lowish margin logistics business? That said, WIN does have a great client list, and must be good at what it does, to generate fairly reliable profits in a competitive market.
There doesn't seem to be much earnings growth happening either.
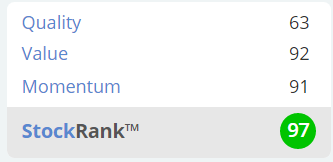
Stockopedia computers like it a lot - but I don't think they focus on pension deficits, or balance sheet strength as much as I do;
** BREAKING NEWS! **
Superdry (LON:SDRY)
The founder, Mr Dunkerton, has succeeded in his EGM to join the Board, and in time replace the existing Board.
In a vote closer than Brexit, Dunkerton achieved: For 51.15%, Against 48.85%.
As the existing (now presumably outgoing Board points out);
Peter Bamford, Chairman of Superdry, said:
"Whilst the Board was unanimous in its view that the resolutions should be rejected and 74% of shareholders other than Julian and James have voted against, there was a narrow overall majority in favour and we accept that outcome."
Therefore this cannot be seen as a vote of confidence in Mr Dunkerton - he only managed to persuade 1 in 4 outside shareholders to put him back in charge. Therefore, his winning the EGM largely on the strength of his own large shareholding, presumably is not going to be viewed positively by most outside shareholders who voted against him. Hence I suppose why the shares are currently (at 14:38 today) down 5% to 520p.
To my mind, the suits have made a mess of running this company, so bringing back the founder seems eminently sensible to me.
Gear4Music
Share price: 205p (down 5% today, at 14:32)
No. shares: 20.9m
Market cap: £42.8m
(at the time of writing, I have a long position in this share)
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces a trading update for the 13 months from 1 March 2018 to 31 March 2019 ("the Period").
My initial reading of this update, first thing this morning, was quite reassuring. We already knew that the company was suffering margin pressure, which is why the share price has been smashed down from a peak of c.£7-8, to barely a quarter of that now. However, strong organic growth is continuing, and today's update explains what they're doing to fix things, and that the push for improved margins is working. That sounds fine to me.
So imagine my surprise, when my broker messaged me before 8am, to say it was indicated to open 15% down! This seemed to be because people initially focus on anything that sounds negative, and ignore the positives. That's the kind of market we're in right now for small caps - shoot first, and ask questions later.
I'm split this into positives & negatives
Bull points
Very strong organic sales growth continues (
Bear points
(Ran out of mental bandwidth, sorry - that's that)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Intercede (LON:IGP) The logos of the following companies (and more) scroll across the bottom of their website pages. I cannot see what relationship they have with them. If they are customers why isn't IGP profitable ? If they are not customers what point is IGP trying to make?
Wells Fargo, Airbus, Department of Homeland Security, Boeing, Deutsche Telekom, Lockheed Martin, USA Social Security Adminisration
From IGP website:
"However, whilst PKI offered a robust process the organisation needed the means to connect PKI on-site within their server environment and the software necessary to issue and lifecycle manage credentials provided to the third-party companies and governmental organisations requiring access to their data."
That's one red flag !
Superdry (LON:SDRY)
Well I guess the one thing you can guarantee is they'll kitchen-sink the year end accounts.
Plus, are the guys leaving really "suits" ?
Interesting to see how this plays out, but I for one would not rule out it getting worse.
Phil
No position
Just saw how Reuters reported a 5% move .... apart from being arrant nonsense as d4t4 has dropped 30% in a day as recently as 2017, it is the kind of sensationalist clap-trap that nudges itchy fingers. I could append that it went on to "plunge" to -8% before "soaring" back to close down a "mere" 0.8%
TBH, was surprised by the initial reaction this am : reckon it is the prevailing market where an FD leaving has presaged pretty grim outcomes. I have been long for a couple of years so very much in profit and still adverse to selling, £d4t4 rode out the pre-Christmas sell-off with impressive strength and hasn't been below its 200 MA since July 2018 when it was at 130p. Its uptrend has been intact since April '18 which is a rare thing in recent markets
Celebrus, their Customer Data Platform, is a very compelling offering given media fragmentation and martech madness. d4t4 has great fundamentals, technicals, a real differentiated and IP protected product in a market that is growing ( and getting more complex for customers). Teradata is a channel partner as is SAS and Dell. Stocko scores it 82 to boot. Institutions have been adding , up 6% in the past 3 months across a few instis. No reported open interest. If anything, it is still under the radar and arguably still in accumulation before it "storifies" as it has great AI and ML credentials as well.
As for the initial sell-off today , that has reversed intraday: will wait to see if that was part of the share buyback operation but if not, it's an impressive reversal and in itself bullish. Did I mention I was long ;P
Superdry (LON:SDRY) - Dunkerton wins back his board seat (at 50.75% of the vote, which is perfectly fine even though he thinks 52% is unacceptable and requires a second vote.. arf!)
price down 7%, so the markets don't like having him back.
Superdry (LON:SDRY) the markets are schizophrenic! The share price was rocketing when he was rumoured to be coming back as investors cheered the move. It falls once he is confirmed :) Another case of buy the rumour, sell the fact I guess.
I think on balance it is a good thing. The two of them own circa 30% of the company so will be highly incentivised / aligned with shareholders. I suspect the board compensation will be dramatically reduced too. Hopefully re-invigorates employees outside of board/snr mgmt as they focus on brand. Will be interesting to see what board resignations occur overnight.
Re: Superdry (LON:SDRY)
They've already happened. Most of the board has gone today and the remaining four go in three months.
https://www.londonstockexchange.com/exchange/news/market-news/market-news-detail/SDRY/14026124.html
Fast work
EDIT
And the two brokers have resigned too.
Missed that - thanks fwyburd. Was fast indeed.
Well, holders now have an owner run business again I guess. Now let's see what they do!
Intercede (LON:IGP)
I've had a quick look at their website - I can't see what the fuss is about? There's already better solutions out there, and their's doesn't outwardly appear to provide Single Sign On capability.
The TSA solution highlighted on their website relies on smartcards - my company did away with these years ago, and so did most of the banks and other secure environments I've worked at.
Ultimately I think that Identity is going to be handled by the big players, and these guys are too small. Happy to be proved wrong but it's not for me.
Re Intercede, If there are better solutions out there for ID security, can you name one. I am sure the US government has done their homework and chosen what they consider best in the field, for the budget available!
Sure, there are plenty of identity providers, Microsoft, Google and Facebook for a start. I can't remember if it's Mastercard or Visa that are investing heavily in this area too, to provide secure identities for everyone, not just corporates..
Whilst I still have a "badge" to get me into our secure buildings, all my identity verification for data services is multi factor. I can sign in securely from any machine or device and my experience is altered depending on what device I am on. For example, if I am on an unknown PC I can only access webmail and my rights to copy data or save emails is severely restricted. If I am on my work PC I can do pretty much whatever I want, when I go to company webpages it knows who I am automatically and logs me in to the site. None of it requires me to have my badge, and if I was on my phone, where would I plug my badge into anyway?
This might be one of those instances where you can have too much knowledge which makes you miss something. But I'm wary of getting into small companies that solve problems massive companies have already tackled / are tackling. Is also why I'm avoiding cloudcall.
IGotPoesjacket, the reason IGP is in the rather unique position it is in ie supplier of highest quality kit to the likes of Boeing, Lockhead, Airbus, Gruman, highest priority US, UK govt depts, large banks etc etc, is because it was in at the start of the ID revolution. That is why ARM, Microsoft, Intel and others have worked with them. Their kit is of the highest quality, always has been multi factor (!) and they don't lose contracts once they are in. The problem has been a lack of sales drive to more commercial sectors. Hopefully that is what the new management are tackling.
I am left wondering whether the Intercede solution for ID identity, is more universal and less restrictive. If as you say you sign in on an unknown computer, your access is greatly restricted. Perhaps IGP have a solution which solves the problem for staff on the move, that need high level access to data. A much more difficult security problem to solve, then one for office staff using their work pc.
Intercede state that "The order includes software licenses and annual support & maintenance; $2.05m (£1.57m) of which will be recognised in the financial year ended 31 March 2019." I don't want to be a party pooper (hard anyway given a 70% share price increase) but doesn't this smack of front end loading? They only won the contract on 29th March so there has been no opportunity to deliver goods or services upon which profits could be realised before the year end.
David, it's not a new contract and the US Govt is always a late payer. That is the reason why it was not included in the broker forecast, having caused much angst over the years as to whether or not they would pay up before the 31/03 y/e.
I agree with David Bagley and his concern with Intercede booking profits up front. The order was only won on the 29th March, and it concerns me that if this is their norm, what confidence can one have in their accounts. Quindell got away with this for years, and look what happened there. Surely a profit is only a profit when the services have been delivered and paid for?
Now a mudslinging Board fight is breaking out in the nil premium takeover fight between Woodford/Invesco controlled Non-Standard Finance (LON:NSF) (combined 65.6% share at 31/1/19 on NSF website) and the Woodford/Invesco/Marathon) controlled (combined 49.4% share) Provident Financial (LON:PFG) (!!!).
Woodford/Invesco/Marathon have already declared for the NSF plan which basically sacks the PFG and replaces them with the NSF Board and merges the 2 operations (selling off 2 "non-core" businesses
Provident Financial (LON:PFG) challenges NSF about several (technical) issues especially relating to the right of NSF to have paid dividends over the last couple of years:
https://otp.tools.investis.com/clients/uk/nonstandard_finance_plc2/rns/regulatory-story.aspx?cid=993&newsid=1244756
NSF has responded re-iterating the benefits of its plan but not directly addressed the points raised. From what I can see the amounts are small and thus more a smear campaign against NSF - who have previously labelled the PFG Directors personally as poor managers still carrying out sharp practices and with poor relations with the FCA etc. (ie PFG's claims may be true and breaches of the law (I cannot judge and not good if true!) but don't seem to me to be worth derailing a decision - in an audit if found (and to my knowledge they were not raised), they would be highlighted but it would not be a big deal.
Frankly, I like the inference that NSF are straining every sinew to give me dividends since I see the underlying business progressing very well on an operational basis - which is why I supported NSF's plan to "takeover" much bigger PFG. However, getting involved in a personal slanging match is not good and will leave a bad taste in regulatory mouths even if it does not stop the takeover.
i ) Does anyone have insight into whether PFG's (mis-) accounting claims make sense
ii) If true, do have any serious implications for NSF's bid ???
Disclosure: I hold NSF I preferred it when they were running solo but now they have made a bid for PFG, I agree the tie up makes sense with lots of synergies. Indeed I had thought PFG might bid for NSF !
To be honest, if these claims have any basis, then I would suggest the auditors would have some serious questions to answer.
They do assess free from material mis-statement (expectation gap as it may create) and compliance with Companies Act 2006.
Playing fast and loose with the term interesting, but this could be interesting to look into in more depth. Not sure I will as seems quite a complicated matter and I don't have time or position! Would love it if someone else did!
#Freeriding #nothumbsdown
I sincerely hope GT are not their auditors - for their sake!
I see Superdry shareholders have voted to return their founder.
IGP seem to have a cap on share price at around 28p to 30p. Clear sellers in there.
Still trying to work out how FCCN will be worth more than 50p in this climate. Asset value from B/S mid 30s. Industry dire.
HI Cantab
Re: Intercede (LON:IGP) SP: it broke through the key resistance of 24 pretty easily and doesn't seem to find 27 much of a barrier either. After that 32 (where it was last December) should get tested soon and certainly in the event of more positive news IMO.
Cheers
Francis
Re Intercede (LON:IGP)
Many thanks Paul for the analysis. Worth noting that Finncap reiterate their target price of 80p which would be a £40m market cap. I can't find a 2020 broker forecast to see how realistic this is - do you know what it is?
I hold (a rare piece of sunshine in my year so far!)
Cheers
Francis
Re £G4M (Gear4music)
I wonder if someone can explain the difference between Gross Margin (GM) and Product Margin (PM). I presume certain costs are excluded from the PM calculations.
I only ask, as G4M state today :
"Due to our targeted operational improvements we have made progress in returning towards historic product margin levels, improving from 27.5% during H1, to 28.6% during the six months to 28 February 2019."
Their Gross Margin in H1 was 22.7%, so 4.8% below the PM.
If H2 GM is also 4.8% less at 23.8%, this would give a YE GM of 23.4% to show a Gross Profit of £27.7m.
Admin costs would therefore need to increase from £18.4m last year to £27.5m this year to get the EBITDA to just above £2m. Quite a rise in costs at 50% over last year !
Apologies if I'm treading on Paul's toes, and he's already working on all the above :o)
Re D4T4
one of my favourites too, but combine the upcoming trading statement and the CFO leaving then you are bound to get an adverse
market reaction. I have taken a small profit and will act accordingly after the T/S.
Yes I am interested in the £D4T4 bear case too? On one of my favorite screens, D4T4 passes with flying colours as excellent Value and Quality and Momentum (EV/FCF <10 and ROIC 53% and Momentum score 91).
Paul, would appreciate your assessment of Belvoir Lettings (LON:BLV) finals. They look ok, but I made a recent initial purchase and am still coming to grips with what seems quite a complicated estate agency. The Stocko description says "Its property franchise group manages approximately 58,000 properties in Grantham, Lincolnshire.", a surprising number for a small town, unless I misunderstand it.
Richard
Hi Richard - You've misunderstood.
Belvoir has circa 300 offices under 3 brands for property - Belvoir, Newton Fallowell & Northwood.
They then have 65 offices for financial services.
You can discover more through their presentation about today's results : http://www.belvoirlettingsplc.com/files/4615/5419/6037/01.04.19_BLV_prelims_presentation_FINAL.pdf
Thank you. That clarifies Belvoir Lettings (LON:BLV) a bit.
Richard Belvoir Lettings (LON:BLV) are based in Grantham - they don't run the town! As I understand it the 58,000 properties are managed property portfolios held by investor landlords across their brands (and across the country) which deliver a chunk of their Management Service Fee income. They are actively encouraging and assisting franchisees to increase this part of the business with 'assisted acquisitions'. Probably loans to you and I.
Taptica International (LON:TAP)
so the merger has finalised but RhythmOne (LON:RTHM) were trading below expectations for the year, which I think some of us suspected may have been the case. Doesn't use the word "material" so presumably it is a few % miss but one can't be certain.
The $15m buy back has begun and it seems Taptica International (LON:TAP) is trading as expected. The new CEO is Mr Druker, who founded Matomy Media and built up to a $275m+ revenue business, so he should have the right credentials. As previous head of Tremor Video I assume he is also US based, which may help from a repetitional perspective. Anyone here got any views/experience of him?
Interestingly the shares opened 23p down and now trade flat on the day. I suspect RhythmOne (LON:RTHM) holders will be somewhat relieved with the merger and creation of scale given trading.
Full realisation of the buy back should put any concerns around cash balances to bed so I am personally watching how this element plays out like a hawk.
I have "um'd and ah'd" on Taptica International (LON:TAP) for a while now but keep coming back to the free cashflow and low valuation so remain long.
EDIT - There is a good comprehensive piece on Research Tree I've just discovered. Haven't read it through yet so just fyi.
Any thoughts re Bonmarche Holdings (LON:BON) offer – I had commented negatively it before previously as I thought it had a dowdy but slowly product range which was crucially dependent on an old (65+), downmarket customer base buying on price with low internet penetration. Its key asset was (and is) its loyal shopper base and loyalty card user database. Essentially, I saw it as improving but doomed under Helen Connolly, the CEO of last couple of years.
However, on a balance sheet basis, it always looked to have some value to my untutored eye with (I thought) short and flexible leases (ave. 3.6yrs in Nov 18) and large cash/inventory stock balances especially since I thought it had been scrubbed of underperforming stores last time went under in 2012, prior to rescue and rebirth/IPO as an independent chain. “stores experienced challenges, yet almost all remain profitable. Short lease terms provide flexibility” from Nov 18 interims)
Does this also say anything about the wider (physical) retail sector or was this private equity simply moving on to avoid being dragged into operational trench warfare (having made good money in re-floating at IPO)? Conversely, an opportunistic buy on the back of tough conditions and weak Aut/Winter range.
I would appreciate and learn from your ‘balance sheet’ interogations to support entity value analysis – I hold some French Connection (LON:FCCN) and some other retail and fashion stocks on this basis because I believe the underlying consumer need/desire for clothing/goods etc remains largely undimmed. I think some companies using the physical retail channel are now undervalued in places where there is a consumer rationale for stores to exist (eg Pets@Home instore vets, Next nationwide returns network).
Part of this is confidence in being able to extract some value from stock liquidation and running down excess stores. But the very low price achieved for Bonmarche unnerves me a bit about trying to play in smaller chains.
I can certainly see why Bonmarche Holdings (LON:BON) will work better as a private company under a Philip Day character/organization. Bigger scale in buying and landlord negotiations; elimination of independent support functions; maybe some rebranding/conversion/concessions of stores within a bigger group.
I still, ill advisedly, have a small holding in Bonmarche Holdings (LON:BON) and there is something about this offer that is hard to understand. The mandatory offer is described in the offer document as such price being no less than the highest price paid by Spectre (or any persons acting in concert with it) ...during the 12 months prior to the date of this announcement. Afraid I'm really naive, but how did Mr Day obtain all those shares at this knock down price? Or, put it another way, why should Artemis or whoever pass their holding to Mr Day for peanuts when the market price has always been well above that. Of course to shift a small co's shares in huge quantity you need to take a haircut (so I am told, having not needed one for many years) but third-degree scalping?
Smells.
Re. Bonmarche Holdings (LON:BON) , there was a single shareholder (BM Holdings) on the register with the 50+% that has been acquired by today’s bidder so it’s readily plausible that shares have only been purchased at this knock down price.
http://bonmarcheplc.co.uk/investors/shareholder-information/major-shareholders/
Definitely looks like a fire sale by an insider suggesting Bonmarche Holdings (LON:BON) is sicker than apparent from published accounts and statements.
Gus.
Bonmarche Holdings (LON:BON)
It was actually BM Holdings S.A.R.L and yes it could be the case that if BM were looking to exit at some point anyway they may have recognised that in the current market the best they could do would be to take significant haircut.
It is also possible that they know more than us and that the company is in worse shape than thus far disclosed - that should NOT be the case otherwise there would have been an obligation for Bonmarche Holdings (LON:BON) to have gone public with that information.
Philip Day declares that he knows no more than the public information as to the state of the company. "Spectre has not undertaken any non-public due diligence to date. "
As to anything more 'murky' - I have no idea who BM Holdings are but there are no disclosed links between them and the Philip Day empire.
Like yourself, I have a small rump holding (as part of a small factors based portfolio).
It's almost entirely immaterial, but FWIW I will be doing nothing for now. I agree with Paul that there is little chance of a competitive bid coming in, but given that we have only exchanged one majority owner for another, it remains to be seen whether Spectre can gain the 50% of the remaining shares that they would need to be able to de-list.
Big insti's may take a similar view as BM that this is the only exit available currently or equally they may decide to sit in for the ride / hold out for a higher price.
Crusty - having bought a holding of 30+% the purchaser is required to make an offer of a minimum of the highest price/share that they have paid in the last 12 months whether they want to or not.
In the case of Bonmarche Holdings (LON:BON) the new holder has in excess of 50% so will already control the board. If Artemis et al decide that they don't want to accept the price on offer then the company will remain listed in the hope that the new management will turn it round. It is only when Spectre reach 75% that things will change.
Note that Sun is the ultimate seller and this is their retail portfolio suggesting (as have others on this board) that they have just given up on Bonmarche:
https://suneuropeanpartners.co...
Of these SCS (LON:SCS) is listed and they own 40.25% of that.
I am seconding the request for TP (LON:TPG) having been a holder for a while; significant progress seems to have been made overall. On a pre-adjusted basis, operating profit is £4m +85% and the eps is 0.524p equating to a current per of less than 12. The only metric I don't understand is that order book is up 16% but order intake is £43.2m vs £44.7m... perhaps I don't understand what order intake is, please can someone elaborate?
Morning all,
Just seconding Belvoir Lettings (LON:BLV). Positive news on Intercede (LON:IGP) Paul - is this still one of yours? Happy to wait for the actual results. This (former?) serial disappointer is coming good and the SP has been weak of late?
My morning smallcap tweet: Gear4music still in low ratio.
Bonmarche Holdings (LON:BON), £G4M, Intercede (LON:IGP), Kingswood Holdings (LON:KWG), Eden Research (LON:EDEN), £D4T4, Taptica International (LON:TAP)
Bonmarch (BON) mandatory cash offer at 11.445p by Spectre Holdings (a Philip Day. vehicle) which has just bought 52%. Offer is a 36% discount.
Gear4music (G4M) warns again, guides FY (13 months) EBITDA >=£2m. Prev guidance 'slightly below' FY18 (£3.5m). Blames additional distribution costs, short-term courier cost inflation and a clean-up of overstocked and slower moving inventory. FY rev up 36%
Intercede Group (IGP) guides FY rev at least £10m, above mkt expectation due to last minute $4.3m order. $2.05m recognised in the FY. I hold.
Kingswood Holdings (KWG) guides FY revenue and gross profit margin broadly in line with expectations, adjusted and reported pretax below previous expectations. Blames additional investment expenditure incurred across the Group to restructure and strengthen the Kingswood platform.
Eden Research (EDEN) FY rev £2.8m in line with prev guidance. Pretax -£0.5m much better than -£1m guided. Going concern stmt.
D4T4 Solutions (D4T4) CFO resigns, will work 3 month notice. She is thanked. I'm short.
Taptica (TAP) Following completion of the acquisition of RhythmOne, RhythmOne's FY trading was below market expectations. "still strongly believe that, taking into account RhythmOne's trading performance to date, the merger is in the best interest of the shareholders of Taptica." Will buy back up to $15m. I hold.
hi MrContrarian - on £D4T4 why are you short out of interest?
Cash is 15% of market cap, circa 36p. EPS for year should be circa 15-16p so trading on cash adjusted PE of 12.5, which isn't expensive for this type of business. Lots of contract wins recently underpinning next year revenues too.
CFO leaving never ideal but isn't departing immediately and will hand over. She has a tenure of 4 years so within general bounds of standard career progression for a "non owner director".
I am long and thus interested to hear the bear case to offset my natural confirmation bias.
Bonmarche Holdings (LON:BON) bought by UK billionaire Philip Day
Belvoir Lettings (LON:BLV) Finals. Looks good but what do I know.
Belvoir Lettings (LON:BLV) appears cash generative and offers great dividend yield @ 7%+, Stockopedia rankings like it too. Downsides: Balance Sheet in negative tangible asset territory, assets nearly all intangibles (!) but guess that down to Franchise business model and recent acquisitions, and significant gearing. Also in background is negative sentiment around property market/buy to let sector. Probably still worth holding (as I do) for yield if not significant capital growth.
Could you take a look at TP Group please, Paul. TPG. Looks to have turned around after a very torrid time. Revenue and operating profit ahead of forecast.
Copied across as its “today’s” news ...
—————
Mandatory bid triggered for troubled retailer Bonmarche Holdings (LON:BON) this morning as the prospective buyer has acquired over 50% of the shares from a bloc purchase from another holder.
https://www.investegate.co.uk/spectre-holdings-ltd/rns/mandatory-cash-offer-for-bonmarch--holdings-plc/201904020700177624U/
Put the bunting away, the offer is at 11.455p per share, about 37% below last night’s close. If successful, company will be delisted. Rock and a hard place for any residual holders of this former “Super Stock”.*
Gus.
* http://reports.stockopedia.co.uk/144280696/Bonmarche_Holdings_LSE_144280696_20180203.pdf
The RNS doesn't say it but must be private equity investor Sun Capital that sold the block in Bonmarche Holdings (LON:BON) - that's quite a signal.