Small Cap Value Report (Tue 21 Sep 2021) - COG, SIG, APP, SAA

Good morning, it's Paul & Roland here with Tuesday's SCVR.
Agenda -
Paul's section:
Cambridge Cognition Holdings (LON:COG) (I hold) - interim results are strong, with revenues up 50%, and breakeven reached. Numbers are all as expected, from Aug 2021 trading update. This is an excellent GARP share, in my personal opinion. £44m market cap seems low, considering the progress made, the record order book, 80% gross margins, and industry tailwinds.
M&c Saatchi (LON:SAA) - complicated accounts, but there's good news today on trading. I need to do more research on this one, but for the moment reckon it's potentially interesting & worth a closer look.
Roland's section:
Sig (LON:SHI) : This construction material group is trading well, but facing the usual cocktail of rising costs. In my view, the valuation is probably up with events given the uncertain outlook.
Appreciate (LON:APP) : An upbeat trading update from this gift voucher specialist, suggesting that trading levels are returning to pre-pandemic levels. I’m attracted to the financial performance of this business, but have some lingering concerns about its growth potential.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s section
Cambridge Cognition Holdings (LON:COG) (I hold)
140p (last night’s close) - mkt cap £44m
Cambridge Cognition Holdings Plc (AIM: COG), which develops and markets digital solutions to assess brain health, is pleased to announce its unaudited interim results for the six months ended 30 June 2021.
Greatly improved interim results are out today, with the figures being in line with those which we were given in the last trading update on 3 Aug 2021, which I reviewed here in a fair bit of detail.
There’s actually not a lot to add to that, since the numbers today are the same. Finncap upped its forecast revenues for 2021 by 19% after the last update, and that stands at £10.1m, with a small adj profit before tax of £0.2m forecast for FY 12/2021. Everything seems on track, with key H1 numbers being -
Revenues £4.5m
- Gross margin of 80% gives tremendous operational gearing, which could be very positive if strong revenue growth continues.
- Profit before tax of £81k in H1
- Orders won in H1 of £8.6m, substantially more than revenues, so the order book is growing strongly, giving improving visibility.
- Contracted order book £15.2m at end June 2021 - more than doubled in the last year.
Balance sheet is small, with only £262k NAV. NTAV is £(114)k. As there are hardly any fixed assets, and customers pay some up-front, then the overall financial position is absolutely fine, with £4.2m in net cash - so no need for any more placings.
Outlook - includes a section about overall market growth, which is estimated at 15% p.a., and substantial, at >$1bn p.a. So there’s plenty for COG to go for.
The Company remains firmly on track and we continue to trade in line with market expectations. We continue to see potential for growth for both clinic-based and virtual assessments for cognition, whether for recognised solutions such as CANTAB™, or for newer high-frequency digital or voice-based assessments and for electronic Clinical Outcomes Assessment solutions for CNS disorders in clinical trials.
With increasing investment in commercial activities, continued product development, a rising cash balance and supportive shareholder base, the Company is well positioned for further revenue growth. We remain excited about the potential for the future.
My opinion - I remain very bullish on the long-term opportunity here. COG has reached breakeven, and has a very strong contracted order book. So it’s passed that lovely inflection point where jam tomorrow companies become a viable business.
There’s a very good industry tailwind - the pandemic has triggered big pharmas moving to virtual clinical trials, doing things digitally rather than in person. That plays right into COG’s area of expertise.
Competition is limited, because COG benefits from decades of experience & data, difficult & time-consuming to replicate. Therefore it does seem to have a moat - the evidence is also in the figures, with an 80% gross margin.
COG has relationships with all the big pharmas, and a lot of its orders are repeat business.
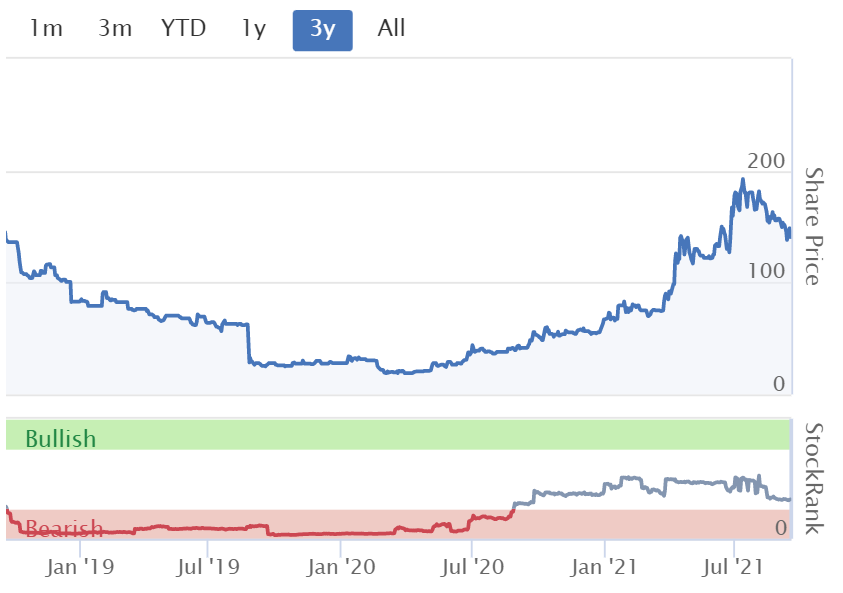
There’s so much to like here, that I’m puzzled why the market cap is only £44m? That seems too low to me, given the likelihood of a bright future. Maybe investors might be anchoring in the short term, looking at how the price has tripled, and baulking at paying more? That seems short-sighted to me. £44m is nothing these days, for a promising growth company.
Obviously the bull case relies on the company being able to continue winning more business. Given the industry tailwinds, I don’t see why we would see growth stall.
It’s not really a value share, but I certainly see this as a good GARP (growth at reasonable price) share. These interim numbers reinforce my bullish stance, so I'll be happy to keep holding for the foreseeable future (and probably buying more on the dips, when funds permit).
.
.
M&c Saatchi (LON:SAA)
150p (up 2% at 09:08) - mkt cap £182m
This is an advertising & marketing group.
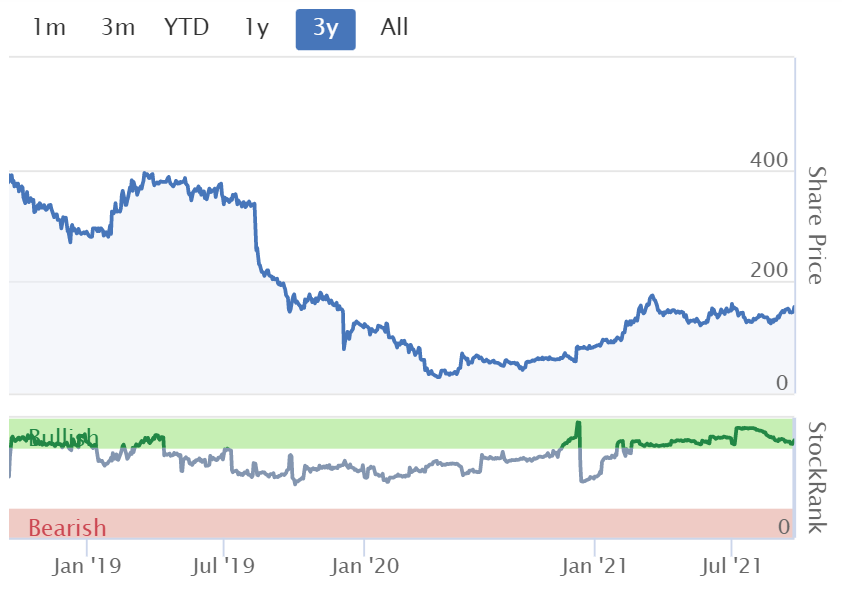
I’ve tended to steer clear of this share, because it’s had various accounting issues, including a potential very dilutive ill-considered options scheme relating to takeovers. Although I think most of the issues have since been mostly resolved.
It looks as if trading has been good in H1 (Jan-Jun 2021) -
A strong first half performance, results ahead of management's initial expectations and profits ahead of H1 2019 pre-pandemic levels...
Full year profit before tax and earnings expected to be substantially ahead of consensus
Options scheme - this sounds really good news, as this potentially large dilution was a big issue when the share price was in the doldrums -
Strong financial governance has enabled Board decision (post period end), to settle put options in cash rather than shares. Eliminates risk of continued substantial share dilution and represents a key turning point for the Group
Outlook - ahead of expectations -
Full year profit before tax and earnings expected to be substantially ahead of consensus…
Momentum from H1 has continued into H2 with important client retentions and new wins
2019 comparisons - a lot of companies are recognising that 2020 comparatives are not very useful, given that they were so widely impacted by the original, most severe lockdown 1. Therefore I very much like it when companies present H1 2021 numbers with both 2020 and 2019 comparatives, so we can see both the extent of recovery from the lows last year, but also how performance is versus pre-pandemic levels.
I can’t see any 2019 comps in the financial highlights for SAA’s results (but they are mentioned in the commentary), so I checked back myself, and it looks fine -
H1 2019: Revenues £117.9m Headline PBT £3.4m
H1 2020: Revenues £103.4m Headline PBT £2.0m
H1 2021: Revenues £118.1m Headline PBT £10.5m
As you can see, performance this year trounces both pandemic, and pre-pandemic levels of profit. That's assuming you’re happy with the adjustments made. Remember that PR companies can’t help but massage up the story to within an inch of its life, which after all is their job!
In 2020, the Group embarked on a large-scale, global restructuring programme, closing or merging 20 operating entities. This has had a strong favourable impact on H1 2021 results. We expect the revenue and operating profit benefits from the 2020 disposal programme to continue to positively impact the second half of the year.
Although further down in the commentary it refers to a different headline PBT for 2021. It looks as if one figure is adjusted, and the other isn’t. Confusing!
H1 2021 Headline PBT is £7.1m or 209% ahead of the pre-pandemic H1 2019 outcome.
Restructuring - as with many companies, the shock of the pandemic triggered a restructuring that has enhanced profitability.
Although with a people business, we should bear in mind that when profits rise strongly, the staff want a slice of the action, understandably. So wage inflation could become an issue in future. SAA neatly flips this around and turns this into a positive - very clever, and it might fool some readers!
The war for talent: In what has been called the Great Reappraisal by HR experts, there is a post-Covid fight for talent. Employees are re-assessing their vocational criteria, and the evidence strongly suggests that strong brands with a clear, noble purpose will become employers of choice.
Net revenue is £118.1m, with the largest cost (staff) devouring most of this, at £85.5m. Hence this is very much a people business.
Balance sheet - is a bit complicated, but looks OK overall, with about £10m NTAV.
There’s a large £73.6m cash pile, offset partially with borrowings of £41.8m, so net cash of a robust £31.8m.
The commentary says net cash improved post period end to £41.4m at 31 Aug 2021.
Hence it looks reasonably healthy overall. Much of this cash will be needed to settle the problematic put options, the latest comments being -
We expect to pay no more than £9.0million in cash in the next few weeks to settle the most immediate (2021) batch of put options. Thereafter, we expect the total liability for the remaining four years, 2022 to 2025, to be £27.4million. Based on our medium-term profit and cash forecast, we now expect to be able to settle the options in cash as they fall due.
That looks manageable in the context of the cash pile, and (hopefully) future ongoing cash generation. Eradicating potentially large dilution is a very positive thing in my view.
Receivables look very high, and have increased considerably, consuming most of H1’s cash generation. That’s probably due to revenues rising, thus receivables also rise. It looks as if receivables probably includes some pass-through revenues, hence why receivables are so large relative to revenues.
My opinion - it’s taken me a while just to review the numbers, but more work is needed, as this is quite complicated for a small cap.
However, on a first glance, I think there’s enough here that seems positive, to make me want to dig deeper at a later date. For now though, it goes into my “potentially interesting, more research needed” tray.
.
.
Roland’s section
Sig (LON:SHI)
Share price: 50p (pre-open)
Shares in issue: 1,182m
Market cap: £589m
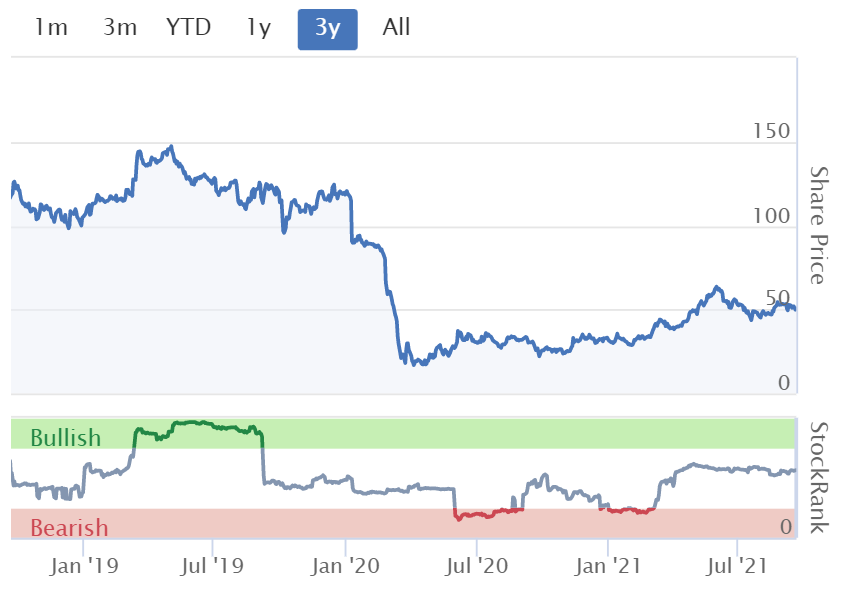
Construction materials group Sig (LON:SHI) reports half-year results today. Jack covered this turnaround situation in July and today’s numbers appear to contain more good news. Like-for-like sales are 33% ahead of H1 2020 and 1% ahead of the same period in 2019. Profit guidance for the full-year has been upgraded.
“Trading in July/August remained solid, strengthening the Board's confidence in full year outlook despite caution over ongoing impact of material shortages and cost price inflation”
“Continued profit improvement expected in H2 2021 and full year underlying operating profit anticipated to be ahead of prior expectations”
Financial highlights: SIG operates in the UK and Europe, but has been facing particular problems in its UK distribution business. This division is now said to be back on track but has been a significant drag during the half year.
Here are some of the main financial highlights. I’ve provided a comparison with H1 2019 as the first half of last year was something of a washout due to the initial disruption from Covid-19.
- Revenue +3.4% to £1,108.2m (H1 2019: £1,071.5m)
- Like-for-like sales +1% vs H1 2019 (LFL +8% excluding UK distribution)
- Gross margin: 25.9% (H1 2019: 25.3%)
- Operating profit -36% to £9.0m (H1 2019: £14.2m)
- Net debt excl. lease liabilities: £57.5m (H1 2019: £158.2m)
Gross margins and sales have improved against 2019 levels, but operating profit is still significantly lower. This reflects a sharp increase in underlying operating costs, which rose by 8.5% to £273.4m compared to H1 2020.
Unsurprisingly, SIG says this primarily reflects increases in freight and other handling costs.
What this implies is that SIG is only partially passing on cost increases to its customers, and is absorbing the remainder itself.
Balance sheet: Shareholders got diluted last year when SIG carried out a £165m placing that doubled its share count.
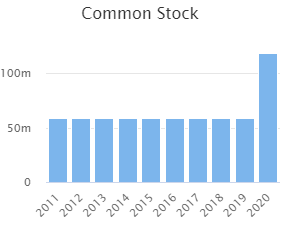
In fairness, it was the first time the company had issued shares for at least 10 years - in quite extreme circumstances: But the placing was driven by a need to reduce debt, which I’d argue was a little too high before the pandemic.
I have no such worries now. Net debt (excl. leases) is down to £57.5m from £162.8m at the end of 2019, which looks manageable to me. Lease liabilities are quite hefty, at £258m, but with the company trading profitably I don’t expect these to be an issue at present.
Outlook: SIG is clearly enjoying good demand for its products, but facing significant higher costs. How will these competing forces balance out?
CEO Steve Francis is taking a fairly optimistic stance. He says that trading in July and August was “solid” and expects to see
“continued profit improvement through H2 despite the ongoing impact of material shortages and cost price inflation” (my emphasis).
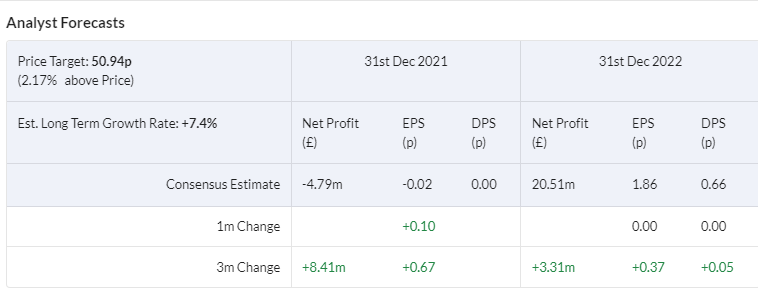
However, it’s worth remembering that prior to today, SIG was expected to report a loss this year. So any upgrade may be little more than breakeven - we don’t know yet.
My view: In the commodity sector, they say that the best cure for high prices, is high prices.
I’m starting to wonder where the tipping point is in this situation. At what point will rising prices and transport problems cause demand for SIG’s goods to level out or fall? We don’t seem to be there yet. The company clearly traded well over the summer.
But it’s a general truth that if prices rise too far, people will find a way to use less. We’re already starting to see the impact of soaring gas prices in the UK, with industrial customers such as fertiliser producers switching off production.
If the cost of building materials and road transport continues to rise, will we see a slowdown in building activity, for example?
I don’t know the answers, but with SIG shares now trading on 27 times 2022 forecast earnings, I would argue that the valuation of this low-margin business is probably up with events.
SIG’s turnaround appears to be going well, but I’m not convinced the balance of risk and reward is favourable at this point.
.
Appreciate (LON:APP)
Share price: 29.9p (+8% at 08:42)
Shares in issue: 186.3m
Market cap: £51m
AGM statement & Chair to step down
Appreciate Group runs gift voucher schemes such as Love2Shop, highstreetvouchers.com and the Park Christmas Savings scheme. The firm also runs reward schemes and provides VIP experiences for corporate customers.
The last trading update in June was fairly downbeat, as Jack reported here.
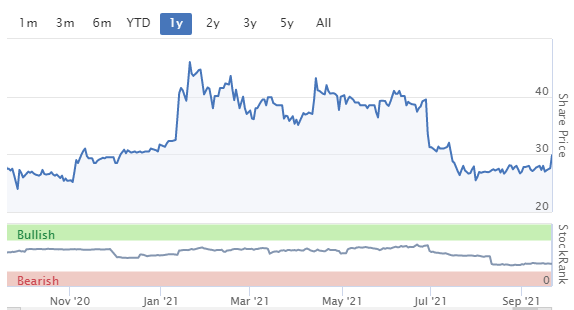
Today’s statement covers the period from April to September and is much more upbeat. Appreciate’s share price is up by 8% as I write.
“Q2 improvement in trading - now ahead of both FY20 and FY21 for year to date”
- Corporate and Gifting billings of £40.7m in Q2 were 14.6% ahead of the same period in FY20 (the last pre-pandemic period)
- YTD (April-September) billings of £79.7m are up by 3.6% versus FY20, reversing the fall of 6% seen in Q1
The improvement is being driven by growth in the corporate business, which is currently up by 6.8% YTD against FY20.
Appreciate’s Corporate business had a record Christmas last year as employers spent money on gifts for staff rather than Christmas parties. Revenue was also boosted by the company’s involvement in the free school meals initiative, which is now starting to taper.
The company is focusing on corporate growth, but it remains to be seen how much of last year’s gain can be retained as life returns to normal.
In contrast, Gifting billings (High Street vouchers, etc) are down by 12.1% so far this year, compared to the same period in FY20. In part, this reflects a backlog in redemptions from last year’s lockdown periods. The company says redemptions are now starting to improve, driving deferred revenue into the business.
In a similar vein, the Park Christmas Savings has been held back by £6.4m of unspent paper vouchers (as of June 2021) from Christmas 2020. In today’s update, the company confirms previous guidance that the Christmas Savings business will be down 14% on last year. The Christmas order book is now said to be complete, so the focus has now switched to reinvigorating this business for Christmas 2022.
Growth opportunities: Appreciate recently partnered with retail payment group PayPoint (disclosure: I hold) to offer the group’s gifting products at PayPoint’s network of 28,000 outlets. The business is still working to “build awareness and availability of our products” with PayPoint’s retailers but describes this as “an exciting opportunity”.
I’d imagine Appreciate’s client base should be a good demographic fit with PayPoint’s, so I can see some potential here.
The group is also expanding the range of redemption options available on its gift vouchers to include dining out and experiences, rather than just retail. Recent additions include All Bar One, Toby Carvery, Canvas Holidays and Merlin Entertainments (Legoland, Madame Tussauds). New retailers have also been added.
Board change: Appreciate’s chairman Laura Carstensen has announced her intention to step down today. This appears to be an orderly transition and Ms Carstensen will remain until a replacement is appointed. I don’t see anything to be concerned about here - she’s been on the board for eight years. With the company’s turnaround nearing completion, now seems a logical time to move on.
My view: House broker Liberum has left FY22 profit forecasts unchanged after today’s update. This is broadly in line with my own view. Although growth in billings is encouraging, there was some cost inflation last year and we don’t yet know how well the company will trade in the Q3 peak trading period (Oct-Dec).
More broadly, I have some concerns about the long-term growth potential of this business.
I’m encouraged by progress in the corporate division. But I wonder if the consumer gifting and Christmas businesses will ultimately struggle to make the shift to digital. Can they attract a loyal cohort of younger shoppers and families who expect hybrid online/offline services and more seamless payment processes?
Despite this concern, my overall view remains favourable. I’m also attracted to the financial characteristics of this business, which has been extremely profitable and cash generative in the past:
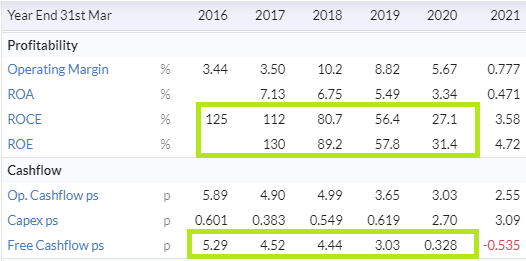
If Appreciate can deliver on current forecasts, then I think the shares could be very cheap at current levels:

I’ve been following this turnaround situation with interest and the shares are on my watchlist as a potential buy.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Ten Entertainment (LON:TEG)
Very solid update from Ten Entertainment - positively dripping with confidence (almost).
It looks like next year they are on track to be well ahead of the 2019 year that was PL (pre lockdown). So roll on a great PL (post lockdown) era. Hmmm not sure those acronyms will catch on - pre covid and post covid ? - err nope.
Anyway quick summary of where we are.
There was a minor early fundraising last year so share count has gone up 5% that is tolerable. Really i should have bought on the dip but i was too scared to push extra funds into a business so covid vulnerable.
They have proved me wrong in that i thought they might struggle with ongoing ask rules and the like - masks and minglingrisks dont seem to have put anyone off.
Overall covid could almost be seen as a benefit as they have transformed to a more digital way of doing things (2/3 of bookings online) i am guesing that is efficient , easy for the youth of today and makes direct trageeted marketing easy peasy. Customer database up 25%.
for 2022 they are targetting double digit sales growth compared to 2019 - i would neeed to do eexact comparative venue count but i am guessing new venues will provide decent contributionto that number - ie not all organic? - four new centres planned in 2022.
What about the debt - bank net debt is just under £11 mill - down from £12.6 mill 27/12/2020. With expectations of net profit of over £12 mill in 2022 they are in a hunky dory position of you "presume" there will be no more lockdowns. If there are aditional new extended lockdowns then the debt will deffo be a consideration - so not without risks if one takes the plunge here.
If we say they will beat the "current" stocky target for next year by 10% they could be on for EPS of 18p at 250p thats pe of just shy of 14. For self funding rollout for quality operator that seems cheap in a no covid world. Factor in covid and the debt combo and the shareprice is probably only mildly cheap and not without risks. When i bought this share pre covid it was a bit of a punt - i suspected Hollywood Bowl may have been the better business and there was slight worries about shareholder base. However operationally speaking i think management have delivered - not sure its up to the quality metrics of bowl yet but they are doing just fine compoared to where they were. Since i have held in March 2019 shares are up 22% compared to 11% of bowl - but i was lucky enough to buy on spike down at that time due to large seller - so i suspect the two companies are possible performing very equally with regard to shareholder returns generally speaking.
<posted instead of replied>
The bid for Entain (LON:ENT) is no surprise but exciting none the less. I have been invested in Entain (LON:ENT) since Sept 2016 and despite a top slice in June it is my best holding in terms of profit to date.
As davidjhill says it could get very interesting if MGM make a counter bid.
M&c Saatchi (LON:SAA) (I don’t hold - yet)
The well regarded tech investor Vin Murrya is now Deputy Chairman here and has 12+% of the equity. If Saatchi can in any way replicate what Martin Sorrell has done with S4 Capital (LON:SFOR) then this could be very interesting.
Looks like a £25 p/share bid from Draft Kings for Entain (LON:ENT) for anyone interested according to the press in the US. Was a CNBC report I believe. No update from the company yet though. Wonder if MGM will counter given their JV and original bid at £18. Could be an interesting one.
I'm long - have held this one for what seems like forever (from about £2). My fag packet take out target was £25 up to £30 so suspect this one paves the way for a successful takeout.
Mental health services provider £KOO announced results today. I hold a speculative position . It made a tiny profit and paid back it's debt using IPO cash but increased headcount by 40+ (15%) and so it's admin costs eat pretty much all profit - it needs to start growing sales without increasing these costs too much but comparing like for like it's 40% of revenue last year to 36% this and for a product that's online I'd be wanting to see a much improved figure. Def an interesting company and product but looking expensive and these figures don't make me think it's going to multibag anytime soon.
Hi Leebod,
Funnily enough, I've just been reading the interim results from Kooth (LON:KOO) and it struck me that conceptually, it's quite similar to Cambridge Cognition Holdings (LON:COG) (I hold). Both growing (although COG growing faster), both near breakeven (COG slightly above, KOO slightly below), both with cash on the balance sheet (KOO has about double COG), and both operating in different niches in digital cognition/mental health area.
What is most striking is the valuation gulf - KOO mkt cap almost £130m, whereas COG is under £50m.
I'd say COG is the much better business, with a far greater moat, and growing faster. Yet it's under half the price of KOO, which arguably still has a "newness" valuation. Whereas COG has arguably gone stale after years of false dawns.
So perhaps it might take time for investors to trust COG, and overcome scepticism over its previous lacklustre performance?
Don't get me wrong, I quite like the concept of KOO, and did (briefly) hold the stock, although chucked it out in a routine portfolio cull on margin calls a while ago (not a bad discipline actually).
But on a valuation comparison, there's no contest, COG is much better value, hence I think has better % upside. Could be wrong of course, as none of us knows what the future holds.
Regards, Paul.
Many thanks for your thoughts Paul.
Augean (LON:AUG) takeover auction being conducted tomorrow and price is nudging up. Be interesting to see what the resultant price is. Current level is a far cry from the 280p initially accepted by the board!!
Litigation Capital Management (LON:LIT) (I hold)
Following today's results I remain a fan.
Some positive points:
1. a) - Growing Gross Margins and Gross Profit
(more important than the revenue figure in my opinion)
---
1. b) - Note the $51.8m of investments directly held at cost last year.
$10m of this generated the $26.1m Gross Profit depicted above.
---
2 - Relatively Stable OPEX costs
(unlike Burford Capital (LON:BUR) which seems to be constantly rising)
---
3 - PBT would have been higher without the loss on funds
(which hopefully will generate high returns in the future)
---
And now for some Negative Points:
1 - As someone pointed out the newly available debt facility is very expensive, but "luckily" it is capped at 13%.
As someone quite averse to debt, this seems very high.
2 - The below shows changes in the company's current investment. So at the moment $135m has been deployed to fund various litigations.
I have no idea what this $5.5m is. I will be querying it, but I would have hoped for a better explanation for such a large figure.
3- One customer generated 67% of revenues this year, up from 36% last year, 19% the year before, and 14% the year before that. Is there a risk here?
Cheers
A
deleted
Appreciate this is not a small cap but it is a new IPO that has struggled to get traction but looks to be a very interesting business to the semi-conductor industry
Alphawave Ip (LON:AWE) half year out today and the growth numbers are staggering. On the face of it a £2.5bn business generating just $27m in revenues and $2.7m PAT looks a tad expensive but then you look into what's coming.....
H2 will double again to $50m revenues and bookings moving up to $230m (+500%) and above guidance at IPO by more than 25%!
This business has a gross margin of 95%.....wow!!
$519m in the bank as cash
Has anyone else looked at it? I picked some up at 380p as a medium position on the rational that with 95% gross margins and growth at 100%+ I can see it easily getting to $150m+ profit in the next 12-24 months and as an IP company (eg ARM etc) will probably be rated at 40* so maybe double from here. Perhaps I'm smoking something. Still 10p below IPO price as well.
I hold a good number of semiconductor stocks and was quite excited by the Alphawave Ip (LON:AWE) IPO. The team is very experienced and they have an early mover advantage in one of the fastest growing segments of the semi marketplace, high speed infrastructure connectivity. I have been building steadily as the price wobbled around and now have a full position.
On an FY23 EV/EBITDA ~25x after today’s spike, shares trade on a par with AMD and half the price of NVDA for >5x the growth. The TAM is massive so it's all about the execution, not the opportunity. but so far very satisfactory. I've put a note through to my bank's tech analyst to see if he wants to take a look at the name. If the numbers are good enough to get his attention I will increase the position to oversized.
Thanks BnB - good to get some similar thoughts. I nearly bought down at 290p but missed the initial rally but still in at a 10% discount to the IPO. I might well add to the position myself. It looks like a very high quality business with massive demand. Good to see the R&D being ramped up as this should keep them ahead of the game and cement their market leading position. Despite this ramp up operating costs are relatively small so much of the growing revenue drops straight to the bottom line which I love to see in a share, especially when the market opportunity is many billions.
Analyst at my bank has come back real quick. He's sufficiently impressed with the numbers to set up a meet with Alphawave's CFO in the next few days. This would be with a view to putting AWE on a watchlist for eventual full coverage. This analyst is very strong (and very bullish) on semis and the bank's focus is almost exclusively large cap, so small cap high growth is an interesting diversionary activity for him. If other houses start to initiate coverage this is sure to heighten awareness of the name. I'm invited to the meeting myself so will share any new thoughts in due course.
Alphawave Ip (LON:AWE)
Thanks for flagging this one up i have added this into my watchlist to have a butchers when i get time - nice to see some fast growing stocks actually listing in the UK rather than the us (Made.com being another example) - my sipp is kinda chokka full of US stuff as its a right pain buying US stocks in an ISA. As you say pe of 20 on next years figures looks very interesting. Lets hope they aren't totally china reliant to earn their crust. Hmmm mention of agreement with the company below
· All definitive agreements from China Product Partnership ("CPP") executed with first revenues expected to be recognised in H2 2021
Ref china in principle i have no problems on them dealing with China whatsoever on the supply side of things - however if they are reliant on China based companies to drive a high proportion of their income streams i would be slightly wary that they could be getting pimped short term by their customers. Certainly an interesting company.
Anyway one to look into when i get time cheers - the only worry with the less established companies is that they may be getting pimped out by their largest customers short term whilst they develop similar in house or ata later date move to cheaper (china based) competitor. The other one would be are the revenues repeatable in future years at the level thye are expecting this year and next.
Presumably at p/e of 20 the market is reasonably neutral with regard to the future past 2022 - it does seem cheaper than i would expect based simply on the trend from 2021 to 2022 must have a look at the listing documentation to see whats what.
yep - I need to unpick the CPP as there is no value attributed to this partnership but I haven't looked at it in any detail.
I believe revenues should be growing heavily. Total bookings (order book) are up to $230m (+500% growth YoY) so that supports the $50m in H2 and $180m of future years before any new sales. or repeat orders.
The more I look at this the more interesting it gets. I need to allow this to percolate more though before I buy any more as it would be folly to get too carried away.
As you say sales to China always concern me a little just in case there is IP leakage but to be fair the Chinese semi-conductor industry is a big part of the global manufacture so it can't really be avoided.
Hi David,
I was watching the Alphawave Ip (LON:AWE) earnings presentation this morning and they reported 50% adjusted EBITDA with guidance to 55% in the second half.
They do say they are transitioning from selling one off licenses to a subscription model that has extremely high margins so perhaps that's where the 95% margin number comes from? Or perhaps it's just that as an IP business they have no physical purchases but they do have significant R+D spend and other expenses? Gross margin of 95% sounds great but it doesn't all drop through by any means.
Edit - having mulled it over I decided to buy a starter position. The growth is really outstanding.
hi John
comes from the report " We maintained our gross margins at 95% and achieved strong profitability with an adjusted EBITDA of US$13.9m and adjusted EBITDA margin of 50%"
So I anticipate that the difference is the central and R&D costs. They are almost doubling the R&D team so it makes sense that EBIT only goes from 50 to 55% in H2 on doubled revenue. But assuming the R&D team then stabilises next years growth should increase EBIT %ages further still.
I first heard of Alphawave Ip (LON:AWE) (I hold) when the fund manager of Amati was interviewed by Tamzin at PI World (it's on YouTube). Intriguing company and looks good value considering the growth (and the fact they are already profitable).
Whilst semiconductors have traditionally been cyclical, my view is that there is a secular tailwind and a massive/growing TAM due to the digital revolution - big data, cloud, 5G, etc.
They are only a £2-3bn company currently so very small and probably a takeover target from one of the goliaths.
Why do you think 2 funds have had the confidence to short a high-growth IPO out the gates?
Short Interest Tracker - Alphawave IP Group PLC (shorttracker.co.uk)
don't know and it was a question I was asking myself when they did it but remember that not all shorts are naked shorts. They may be pairs where they take one position relative to another.
Also interesting in the analyst call this morning that when they did the IPO rounds and said they would do 100% revenue growth YoY a number of funds didn't believe them. Said they were way too aggressive growth numbers. They may have shorted on that but of course Alphawave Ip (LON:AWE) did 125% instead so that will be hurting if they did.
Worth watching the analyst presentation JohnEustace posted link to from this morning. It's illuminating if you're interested.
Alphawave Ip (LON:AWE)
Why do you think 2 funds have had the confidence to short a high-growth IPO out the gates?
Who knows - 2.5% doesnt really strike me as being a number to worry about though particularly.
- on the notified shareholder list it looks like Blackrock ended up with 9% shareholding after notification in May. I am kinda guessing they are no mugs presuming they are still hanging around now.
Morning Both, I'd appreciate your view on £LCM prelims. As Nebraska1977 has pointed out the claims of 78% IRR over the last 10 years should have pointed to a better SP performance, although I'd guess that the company would say that they are reinvesting the returns into further claims in order to achieve growth in the balance sheet and fund management (75/25 investment split) investments.
A notable omission seems to be that they have not mentioned the percentage fo claims they have taken up, which they do historically from memory.
This will (in my view) either be a great long-term performer once the pipeline of claims start to mature, or a serial disappointer
Also, the debt could be an issue in the short term.
Regards,
Dave
Amusing that Litigation Capital Management (LON:LIT) are claiming today that they have delivered a 78% IRR on their investments over the last 10-years. A 78% IRR equates to a 300-bagger over 10 years!! A quick look at their financials shows they have not delivered anything like that performance! At the same time they also announce that they are not paying a dividend this year, which follows them having to take on very expensive debt earlier in the year. If they were delivering 78% IRRs surely they would be drowning in cash! One to avoid, along with other litigation finance firms.
not really. Litigation Capital Management (LON:LIT) have one of the cleanest accounts out there. They were about the only litigation financing house to not include any case at fair value. Everything is shown in the accounts at cost.
Note it is a "portfolio cumulative" IRR of 73% over 10 years not an annualised return. The better measure is 153% on ROIC. What that tells you is that with $118m AUD of current investment an investor can expect worth circa $180m. Then there is $16m of net cash so it's trading around TNAV at current level.
Not factored into this is the asset management business which has around $250m AUD in it now. That should translate to at least $4m p/a of fees and probably adds £25-35m of corporate value.
So on a liquidation fair value approach it looks like 125p is closer to the mark in terms of asset value or a 40% upside to todays prices. Brokers are valuing at 140p so obviously adding some future value to their estimates.
People may remember I was heavily critical of most of the litigation financing companies at the heights of their popularity, questioning the appropriateness of fair value accounting and the 4-6* NAV attributed to them. Litigation Capital Management (LON:LIT) was the only one I felt was valued appropriately based on its conservative accounting methodology.
These figures represent the returns generated by the cases, it doesn't represent the company's actual return on equity. They are scaling up the business and most of those returns are being invested in new cases (hence the lack of cash generation and dividend so far) , but would expect the company to start delivering strong earnings growth over the next couple of years. It's also a nicely counter cyclical asset class which could do very well if we see an economic downturn.
Good morning Paul/Roland,
In light of comments in Friday's SCVR re. Electra ( LON:ELTA ) this article is in today's Retail Bulletin and demonstrates Hotter further embracing the "on line department store" concept.
"Comfort footwear brand, Hotter Shoes, will next month (October) begin to sell its products via John Lewis online as part of its strategy to reach even more consumers within its core demographic of 55+.
Hotter, which sells 1.3 million pairs of shoes worldwide, has struck up its latest partnership as it expands and responds to changing consumer trends. The brand, which currently reaches 29% of the female population 55+, has heavily focused on digital transformation in the last 18 months and is seeking to underpin further growth by securing strategic partnerships with well-known complementary brands.
A curated selection of women’s and men’s Hotter shoes will be available on John Lewis online as both brands seek to offer wider product sets to customers. Hotter’s product strategy is driven by its unique proposition of customised comfort, precision fit and stability.
The prestigious partnership with retailer John Lewis is the third collaboration for Hotter in the last three months. In July, the business re-launched a selected product range on Debenhams.com, after the retailer was acquired by Boohoo earlier in the year. This month (September), Hotter has launched a partnership with online marketplace Zalando, one of the largest global online marketplaces, focused on European and UK markets."....ends with some meaningless blurb from CCO which I have omiitted.
Enjoy the sunshine Paul!
Thanks. I've used the recent erratic drop in share price to pick up some more Electra Private Equity (LON:ELTA) actually. It's funny how the recent wobble in US markets has caused lots of UK stocks to almost randomly spike down. Could be some buying opps there, but of course you have to hold some cash on the sidelines to take advantage.
I've also topped up on Joules (LON:JOUL) and note some Director buying today, in a rather confusing RNS that seems to give 2 different figures for how many shares the founder has bought in the market. It's not a meaningful amount, given his existing holding, so I think this is what I call a demonstrative purchase - i.e. the founder saying, OK the share price is too low now, I want to send a signal by buying some.
Others? Volex (LON:VLX) (I hold) looks interesting, and is bouncing today.
Anyone else spotted any good bargains in the value/GARP space in recent sell-off?
Regards, Paul.
Tremor International (LON:TRMR) looks like the wrong price to me. Trading at what looks like 8* EV/EBITDA growing faster than competitors and trading at less than half their valuations.
"Anyone else spotted any good bargains in the value/GARP space in recent sell-off?"
I think Vertu Motors (LON:VTU) (I hold) continues to look undervalued and is down 13% from its recent high. Mkt cap backed by tangible assets.
Smiths News (LON:SNWS) bouncing a little today but again well down from recent highs on no news. I hold.
Both seemed decent value (to me, at least) at their highs and seem even better now.
Luceco (LON:LUCE) is looking tempting now it has fallen back 1/3 from it's recent peak but there could be cost and supply issues. Yes Joules (LON:JOUL) I have been watching.
Halfords (LON:HFD) could be worth a look also.
The problem is in this market is working out who will be affected by supply and cost issues. There are other issues such as shortage of HGV drivers, now CO2 and soaring energy costs. I'm surprised Wynnstay (LON:WYN) has not fallen back more, 2 fertiliser plants have closed down due to energy costs, hence the CO2 shortage which will affect some food supplies.
Supreme (LON:SUP) had a massive drop yesterday, but it's quickly bouncing back to the £2 level.
Why on earth has my post in reply to Paul Scott with a selection of shares worth checking out, been removed for review? I took ages preparing it and the content is not controversial. I was simply replying to Paul’s question whether anyone had spotted any good value/GARP bargains.
Maybe the Joules (LON:JOUL) director is a chartist Paul?
Nice level to buy at, has been significant a few times in the past, looks like a retest of a key level to me... with nice confluence on the rising 50 period weekly MA.
I may dip a toe in as well...
The other half visited the TGI Fridays in darkest Essex to meet some old work colleagues on Friday afternoon (admittedly a dead time for restaurants). She said it was horrendous - menu straight out of the early 90's, shocking service, terrible food. She didn't want to drink so asked for tea but was told they had none (there is an asda next door). Anecdotal I know...oh and although the retail park its located at was pretty much full there were only two tables in use including their gang of 5.
Both Hotter Shoes and TGI Friday's are very average, unfashionable brands and I think this will become clearer as we are allowed to learn more...and will NOT be well received by market. Electra Private Equity (LON:ELTA)
I hold Electra Private Equity (LON:ELTA) and prefer to focus on the numbers than anecdotes, but I'll counter this deep dark Essex review with one of my own, especially as there have been a few like this on here lately. I twice have been to a Fridays lately - in Basildon - and have been pretty impressed both times. This type of American dining resturant hasnt been my thing really for years but I found Fridays quite enjoyable when I went for a birthday. It was 4pm on a Saturday - so pretty early - and the place was full up. I thought the service was good - much better than you get in most chain restaurants these days - and the food was good. I again went a month later on a Friday lunchtime - obviously not as busy that time but a good few people in there. I also went up to Wembley during the Euros and there is a Fridays just outside the ground. That was full up when I was up there - I guess you'd expect that to be fair - but any of my experiences with a Fridays lately have been that business is doing well, the staff are decent and the food is pretty good too. Anecdotal I know but felt the need to counter all the negatives on here lately.
Is that the TGI Friday's @ Bas Vegas per chance? :)
Only one I know of in Basildon.
Breakout Trader - Yep, that's the one!
It was Basildon the other half went to funnily enough!
Opg Power Ventures (LON:OPG) - must be worth a mention as a value share - with a forward PE of 6.25, nearly debt-free (eta next year hopefully) and a quite decent cashflow - 5p/share, price is 11.5p.
its not for the ESG fanatics, sure, but coal power is not going away anytime soon even in the UK, let alone India. One to tuck away as a 5-10 year turnaround maybe.
Qualityrank - 86
Valuerank - 99
SR - 78
price to book - 0.27
Hi Antehelion,
Coal power being used to generate electricity in the UK is going away very soon, in 3 years. So does this investment case rely entirely on India? Genuine question.
Thanks
Chris
They land fill numerous broken wind blades.
Royal Dutch Shell (LON:RDSA) - climate activists overlook the flaw in the green agenda: whenever one oil major is forced to pivot towards renewable energy, another will be there to pick up its dirtier assets. In recent months European companies like Shell have increasingly diverged from their US rivals, who continue to bet big on oil and gas.
Someone needs to keep the lights on and it won't be the politicians.
yes, is the simple answer, it's an Indian power company.
my note on the UK was more just to call out that even here where we might think we are clean and progressive compared to some developing economies, we still really on coal power even in the UK.
The three largest carbon emitters are China, the US & India.
Time will tell how individual country targets to reduce carbon footprints will impact coal consumption.
Interestingly, there are EIGHT US States that rely on coal to produce the majority of their respective electricity generation (incl. West Virginia 93%, Wyoming 79% & Missouri 78%). Biden will have a tough job convincing the States to switch to more expensive forms of fuel.
NB In the UK, coal now generates just 4% of domestic electricity generation. The government plans to reduce this to 0% over the next three years.
Is solar not cheaper in the states than coal?
Why is the US importing bitcoin mining from China?
China is planning to build 43 more coal powered power stations and 18 blast furnaces.
nice graphs, thanks :)
yes, I'm fully onboard that at some point there will be reductions in appetite for coal in India. In the short to medium term, there is a sweet (and highly profitable - 43% FCF/MCAP TTM according to stocko) spot perhaps.
About 70% of India's energy needs are met by the combustion of coal. This share may fall in future but the fossil fuel is set to remain the dominant source of power demand growth, and this would rise by 4.4% from 2020 through to 2030, according to Roman Kramarchuk, S&P Global Platts Analytics head of Future Energy Analytics
https://www.spglobal.com/platt...
Paul.
I posted a reply in response to your request covering these 10 shares:-
Aviva (LON:AV.) M&g (LON:MNG) Boohoo (LON:BOO) Cenkos Securities (LON:CNKS) Capita (LON:CPI) Intercede (LON:IGP) Newriver Reit (LON:NRR) Revolution Bars (LON:RBG) Tp Icap (LON:TCAP) and £GSK. I also meant to include Smiths News (LON:SNWS) but forgot.
For some reason I can’t fathom Stockopedia have removed my post! I simply covered a few points supporting the investment case for each share and it took a good while to prepare too . I won’t bother posting on Stockopedia again unless getting an acceptable explanation.
Perhaps the few who saw my reply can suggest reasons why the post was removed because I haven’t a clue why!
I’ve asked Stockopedia to explain. They’ve asked me to send them the content but I didn’t save it because I didn’t think for a moment my post would be removed, and now it seems they can’t even find it!
Final words on this mysterious removal of my post. It seems nobody at Stockopedia saw it or removed it so how my post was removed and replaced with a “this post is under review” warning in red is a mystery.
I might post it again tomorrow as it did get several quick recommendations before it’s mystifying removal, so a bit on value shares at bargain prices might generate a bit of interest and useful follow up comment,
Why not post it as a stand alone thread Ken?
Hey Ken
Please don't give up on one lost post.
We all have days when things do not go our way, I mean how many lost internet connection, restarting your computer, Microsoft Blue Screen of Death (showing my age here), computer totally frozen just unplug, hold the button down for a minute and go get a coffee and hope that autosave worked
Waffle over.
Thanks
Tommy
Ps. I hold!
Thanks Graham and TommyH
Stockopedia replies to my complaint about the removal of my post reveal that no one seems to have removed it, or indeed had seen it! So how and why it was removed /targeted for moderation is a mystery. But since it’s removal was not because of the (harmless!) content it’s just one of those things and so no longer a reason to be so angry about it, . Weird how this can happen though.
Hi Ken, I saw your write up earlier today and can see no reason why it was removed. There was certainly nothing contentious that would justify a removal.
Appreciate (LON:APP) seems too be quietly firing on all cylinders.
Acceleration of Billings (ie selling gift cards and vouchers) in Q2, higher than last year and also pre covid. This bodes well for future revenue, its the equivalent of "concrete order book"
Acceleration of redemptions in Q2 (ie consumers spending the balances), which is what is recognised as revenues and profits.
Anyone have access to the broker note on Research Tree? Any EPS upgrades?
Currently just below 30p but no reason why it can't be above 40p within a few weeks given the chart, momentum, and low PE at the moment.
(I hold)
Hi dahokolomoki
Appreciate (LON:APP). The broker note from Liberum hasn't given any EPS upgrades but maintains it's target price at 66p saying 'with CY22E PE of 7.1 x with a dividend yield of 7.9% offers deep value.'
At a time when i am finding it hard to find any value buys at present Appreciate is one of the few standing out to me currently. I cant add much more to Roland's excellent article or some interesting points raised by dahokolomoki that you can see on the discussion thread. The only thing i can say and what has persuaded me to take up a a position today is that i noticed a real change of tone from management in today's statement compared to previous updates.
Looks cheap to me!
Cambridge Cognition (LON:COG)
Interims confirm excellent TU of 5th August
Highest order intake in 6 months period
Rev 50% ahead of previous year, profitable
80% gross margin
There is company presentation at 5.30 today which was mentioned in the update of 5th August but not in today's RNS.
Anyone interested can attend by emailing cog@investor-focus.co.uk
I hold
Here's the link to register for Cambridge Cognition Holdings (LON:COG) (I hold) Zoom at 17:30 today -
https://us02web.zoom.us/webina...
Thanks for posting the link, which I’ll pick up tonight. My initial reaction to your enthusiasm was that I can see COG’s operational gearing coming into play but the guided revenue growth at 8% is anaemic to say the least for such a buoyant sector. How does your thesis accommodate this possible frailty on the top-line?
I asked this question at the earnings presentation this evening. The reply from the CFO was a little forced and amounted to "we're probably being a little bit conservative with guidance but we did some big deals this and last financial year the momentum of which we can't guarantee will persist into the next year so we'd rather be cautious and accept that demand might take a breather". I don't have a problem with prudent forecasting and they see their TAM growing for some years at 15% pa, half of which they are happy to commit to.
I'm going to miss this unfortunately. Do you know if it's going to be made available for later viewing?
I asked the IR and no they don't record these sessions.
M&c Saatchi (LON:SAA) looks like they are getting their ducks in a row but the Put options yet to be exercised or purchased back are a massive overhang. What do people think of the taking back in-house of S&S Hong Kong and China? With the current political climate this could be a total drain? I get the impression they have a great digital strategy going forward, it’s a hard one to assess. The market doesn’t seem sure either. I hold.
Personal Group (LON:PGH) H1 results, in line with expectations. Revenue up 12%, although profit down reflecting the CV19 hit. They are confident of FY trade, good performance continues since H1 with a healthy new business opportunity pipeline across all divisions. Hear management present at a webcast followed by Q&A on Friday 24th September 2pm. Register here.
Litigation Capital Management (LON:LIT) FY21 results today. Total assets under management $336m. 10 yr IRR 78%. Cumulative ROIC 153%. Here is an overview by Patrick Moloney, CEO video & podcast. Management will give a full presentation with Q&A tomorrow 22.9.21, 9am. Register here.
Time Finance (LON:TIME) While business volumes and revenue were hit by the pandemic slowdown, TIME stayed profitable (unlike many other lenders) with cost cutting measures actually boosting margins, and the balance sheet remaining strong. We think the business is undervalued. Our core value is 50p per share, almost double the current share price. Moreover, its market-to-book ratio is 0.41 compared to a peer median of 1.36. Read the note here https://www.equitydevelopment....
Time Finance (LON:TIME) struggling to build lending volumes back to pre covid levels. Outlook statement doesn't sound very confident this will happen in the next 6 months.
Overall I think either they've gotten weaker during covid, or the market is way too competitive at the moment. Exacerbated by easy access to covid funds from small businesses.
One to file in a long term watchlist and revisit in a few months time IMO.
COG please results out this morning turning a profit for first time if small. I hold at an 18% loss currently. Thank you
Also Learning Technologies (LON:LTG) in line.
Know the comments here are more slanted towards retail / financials, but decent interims today from Alliance Pharma (LON:APH):
· The Group traded strongly in the Period with an excellent performance from Kelo-cote™, an uplift in revenue from Prescription Medicines and a significant contribution from recently acquired Amberen™
· See-through revenue in total up 24% (+28% on a constant currency basis ("CCY")) to £80.9m; like-for-like ("LFL") see-through revenue, which excludes Amberen, up 9% (+12% CCY); statutory revenue up 27% to £78.6m (H1 2020 £61.7m)
o Strong performance from Consumer Healthcare brands, with see-through revenue up 30% overall (+35% CCY) / Kelo-cote revenue up 54% (+62% CCY) / LFL Consumer Healthcare revenue up 8% (+12% CCY) / Prescription Medicines revenue up 12% (+12% CCY)
· Underlying gross margin up 4.7 % to 63.8% of see-through revenue (H1 2020: 59.1%), reflecting favourable changes in product mix; statutory gross margin up 3.1% to 65.6% (H1 2020: 62.5%)
· Underlying profit before tax up 24% to £20.1m (H1 2020: £16.3m); reported profit before tax £16.5m (H1 2020: £0.6m)
· Free cash flow £6.5m (H1 2020: £10.5m), reflecting the expected reversal of favourable working capital movements in Q4 2020 and the timing of sales within the Period
· Leverage reduced to 2.21 times from 2.43 times at December 2020 and expected to fall below 2.0 times by the end of the year
Alliance Pharma (LON:APH) (no position)
Thanks Cisk
I liked the results today too and I have a feeling that H2 will be stronger as society returns to "normal."
Whilst operating profits were good, I thought it might be better to wait for cash generation to come back up.
By my rough calculations free cash flow (for which I mainly exclude working capital movements) was c£17m for the 6 month period.
I'm hoping that this bumps up to £40m for the full year.
It might still be a little expensive for me at that price (a multiple of cx18 for an EV of £660m if leverage drops below x2), but given the core stable revenues + growing consumer healthcare brands, it might be worth paying up for this elevated multiple.
I would also hope that share dilution slows down as the company becomes more cash generative and is able to fund acquisitions using its own resources.
For now, I'll continue to keep it on the watch list and observe the share price as it undoubtedly continues to climb.
Cheers
A
Abtan, agree with your points, Amberen will be a key ingredient to drive growth and so far, so good. I hope (and expect) them to exceed leverage below 2.0, as I'm sure they are already looking at the next acquisition (although probably not as large as Biogix).
Hi
Hope someone can advise on the following! I asked on the Tharisa board but it’s quiet there at the moment.
Non-Controlling-interests
Just looking through the interim report and am struggling with reconciling the profit back to the EPS
Profit for the year attributable to:
Owners of the company $m57 439
Non-controlling interest $m18 224
Total $m75 663
The EPS is only calculated based on the owners of the company 57439000/268000000 = 21.4 cents per share
Why is the non controlling interest not part of the EPS ie 75663000/268000000 = 28.2 cents per shares
In reality as shareholders is the 28.2 cents the more relevant figure when working out the PER?
Cheers
El
Re Tharisa (LON:THS)
I am not aware of the context of this case - but accounting for non-controlling interests normally occurs where there is a subsidiary with a minority ownership other than the controlling company. Because the controlling company consolidates the accounts the minority interest is subtracted to arrive at the profit due to the controlling company - hope that helps?
cheers
In South Africa there is a requirement for 26% local ownership of mining companies, which often seems to be an ANC politician. The legal requirement is only for miners, so often the companies are structured so processing is carried out by a 100% owned subsidiary and mining by a 74% owned subsidiary. When you dig into the details for Tharisa (LON:THS) it'll probably be that.
Buy rec for Tandem (LON:TND) from Tempus, second share down. Much smaller than most companies it covers.
https://www.thetimes.co.uk/art...