Small Cap Value Report (Tue 23 July 2024) - EYE, STEM, YU, LUCE, HAT

Good morning, Roland and Graham with you today.
SThree (LON:STEM) Q&A: Graham is interviewing management at recruiter SThree at 10.20 this morning - if you have any questions you'd like him to ask management, please drop them in the comments below!
Update at 12.30: today's report is now finished, see you tomorrow!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
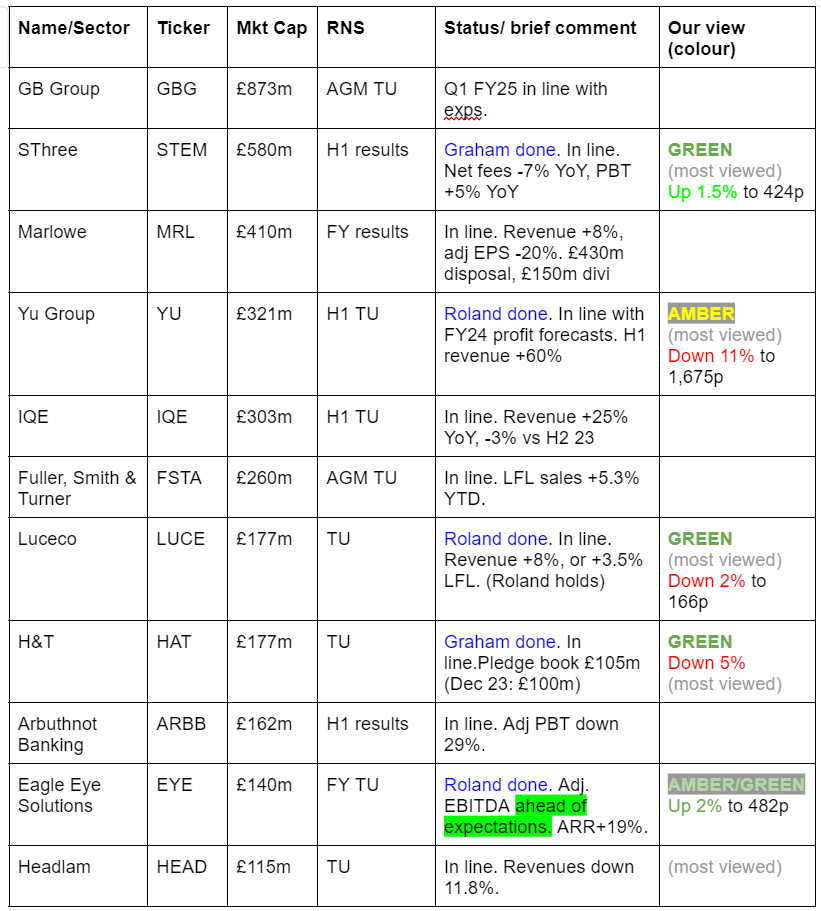
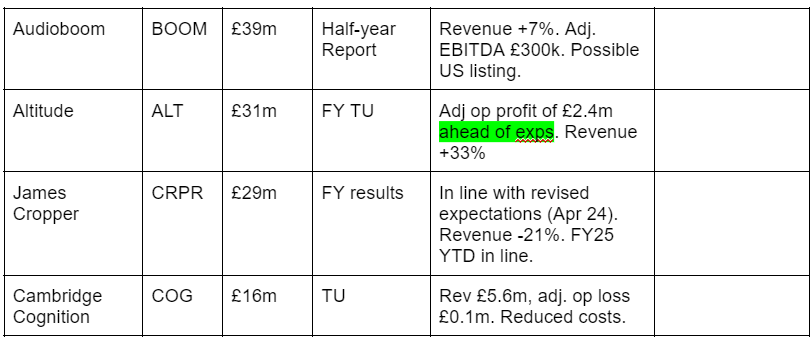
Summaries
Eagle Eye Solutions (LON:EYE) - up 2% to 482p (£141m) - FY trading update - Roland - AMBER/GREEN
FY24 adjusted EBITDA is ahead of expectations, despite revenue missing forecasts. Company says costs are well controlled. Mgt reports a number of contract wins late in FY24 and early in FY25. No specific guidance for FY25 yet. The shares aren't especially cheap, but I remain broadly positive ahead of September's results.
SThree (LON:STEM) - up 2.5% to 429p (£595m) - Half Year Results - Graham - GREEN
Expectations for FY24 remain in line despite ongoing difficult market conditions. Net fees are shrinking but the company has still managed to squeeze out an increase in profits, with some help from higher interest on its cash pile. There is still lots to like here in my view.
Yu (LON:YU.) - down 11% to 1,675p (£284m) - HY trading update - Roland - AMBER
Today’s half-year update from this energy supplier leaves expectations unchanged, but warns that mild weather resulted in lower consumption earlier this year. This weakness appears to have been offset by strong growth in new supply deals and good cash collection. I’m neutral, for now.
Luceco (LON:LUCE) (Roland holds) - down 2% to 166p (£265m) - HY trading update - Roland - GREEN
Like-for-like sales rose by 3.5% during the half-year and revenue was further lifted by acquisitions. Improve margins helped to lift operating profit by c.15%. Rising shipping costs are a possible risk, but I remain positive ahead of the half-year results.
H & T (LON:HAT) - down 5% to 386p (£166m) - Trading Update - Graham - GREEN
An in line update but it could be seen as a semi-profit warning as FY24 forecasts will be more difficult to hit, after a high rate of loan redemptions lasted longer than expected. Overall situation remains stable and as expected, so I’m happy maintaining my positive stance.
Graham's section
SThree (LON:STEM)
Up 2.5% to 429p (£595m) - Half Year Results - Graham - GREEN
As noted by Roland, I’ll be interviewing management here later this morning.
But before that, let’s get an overview of the H1 results from this international recruitment company.
Please note that I covered the relevant H1 trading update last month.
Today’s overview table:
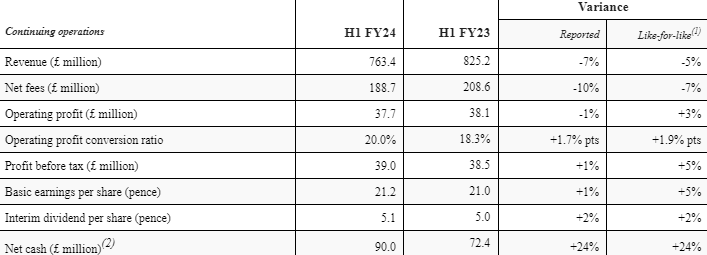
Key points:
Like-for-like net fees down 7% (please note that “like-for-like” means using constant exchange rates).
Like-for-like operating profit +3%.
Interim dividend gets a small raise (+2%).
Net cash goes up to £90m from £72.4m.
Commentary: there is an “ongoing challenging backdrop”. As we’ve seen before, Life Sciences (down 16%) is the worst-performing sector, while Engineering (including Energy) is the best-performing sector.
Contract, as opposed to Permanent recruitment, now accounts for 84% of fees.
Order book is down 2% to £182m, which is still “sector-leading visibility with the equivalent of circa four months’ net fees”.
PBT up 5% helped by “tight cost control and the benefit of higher interest income”.
Outlook is in line for FY November 2024:
Contract extensions remain strong whilst new business activity continues to be subdued.
Whilst market conditions have remained challenging for longer than anticipated, performance for FY24 currently expected to be in line with market expectations.
Continued focus on investment and sequenced roll-out of the TIP [Technology Improvement Programme] across rest of the Group, strengthening the Group's position for long-term growth.
Graham’s view
I’ve read the CEO report here and see little reason for anyone to change their view on SThree. There is an interesting note on market share: they have an average share of 3% across their different geographies, with the highest being 6% in the Netherlands.
There are probably natural upper limits to what can be achieved in market share, as recruitment always tends to be a fragmented industry, but perhaps they can make a push towards 6% in a few more places?
I remain comfortable with this being my favourite recruitment stock - net fee growth vs. FY 2019 remains ahead of their peer group in all core geographies.
And the profit margin is large and healthy: they want an operating profit of over 21%, although they haven’t quite reached it yet (20%).
The enormous cash balance gives added comfort that they can afford to pay a helpful yield, but the dividend is well-covered by earnings too. The target dividend cover is 2.5x to 3x.
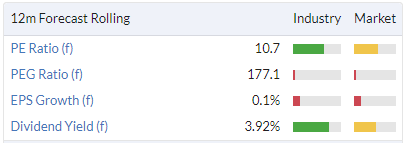
So again, I struggle to find any reasons not to like this stock. The focus on STEM contract recruitment has paid off in the form of several years of good profitability, and I share the company’s optimism for the future. The lack of growth in the short-term has been a disappointment, but SThree is not alone in having been affected by sluggish conditions in the recruitment industry.
On the income statement, I note that finance income increased in H1 2024 to £1.8m (from £0.7m). Without that increase, there wouldn’t have been any increase in pre-tax profits. But having so much cash on hand that your interest income becomes an important source of profits: that’s a nice problem to have!
H & T (LON:HAT)
Down 5% to 386p (£166m) - Trading Update - Graham - GREEN
We have a short H1 trading update from H&T today. Key message: trading is in line.
With the share price down 5%, and judging by reader comments today, investors were expecting a little better.
Here’s the company commentary:
Availability of small sum credit continues to be constrained generally for consumers and demand for our pawnbroking offer has been robust. Redemptions have taken a little longer to moderate than we anticipated, following the pickup of redemptions in Spring but they have moderated through June and into July.
The point about redemptions was raised in May when the company said:
Consistent with last year, redemptions in March and April were higher than average as customers chose to collect their items, often to wear them at religious and family celebrations. This is expected to reverse in the coming months.
So the company has been a little surprised by the pace of redemptions, though it adds that “all key pledge book metrics remain in line with redemptions”.
The pledge book is now £105m (end of June), vs. £101m at the end of Dec 2023.
Unfortunately, this isn’t a like-for-like comparison. H&T acquired a £6m book in February, discussed here.
So if you subtract the acquired book, we have a small decline during H1.
Retail sales, foreign currency revenues and gold purchasing for scrap gold margins are all performing as expected.
Graham’s view
I’ve been consistently positive on this one, most recently in May. This is a stock I’ve been a fan of long-term. But I acknowledge that the share price has struggled to gain traction in recent years (two-year chart):
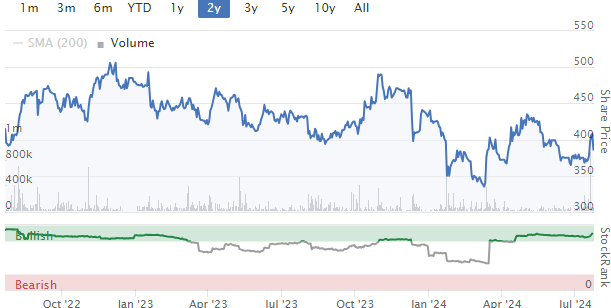
Checking the estimates from Shore Capital, it looks like the company may now face a challenge to hit forecasts for 2024, due to the unexpectedly high redemptions during H1. They say that the pledge book growth needed in H2 for H&T to hit full-year forecasts (8%-9%) is “stretching but achievable”.
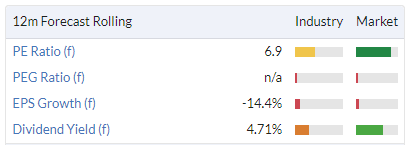
My own view is that even if the company doesn’t quite manage to hit forecasts, this uncertainty has already been priced in by the low valuation, with a PER of only about 7x:
It is a disappointment that the pledge book hasn’t maintained its momentum of course, but I’d also point out that this book is far larger than it was a few short years ago, even if you ignore the impact of the Maxcroft acquisition.
And despite an unexpectedly high rate of redemptions, the pledge book is unchanged vs. May 2024 when the AGM update was released.
Please note that the numbers released in these updates are the “capital value, excluding accrued interest and provisions”. These numbers are much smaller than the “net pledge book” figures in the annual reports, which includes accrued interest.
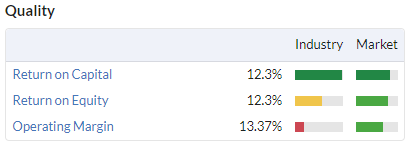
In conclusion, I still view this one as being quite unloved and deserving of a higher rating than the market is giving it. It qualifies for Ben Graham’s Deep Value Checklist according to Stockopedia, and it generates ROE/ROCE that is highly attractive compared to what you get from mainstream lenders.
I’m a broken clock when it comes to H&T, but I still like it!
Roland's section
Eagle Eye Solutions (LON:EYE)
+2% to 482p (£141m) - FY24 trading update - Roland [ahead] - AMBER/GREEN
“19% ARR growth and strong EBITDA performance, ahead of expectations”
Eagle Eye is a software business that enables companies to deliver personalised, real-time marketing to their customers. The company has an impressive-looking customer roster and says its loyalty personalisation platform delivers over 850m personalised offers each week.
Checking back in the archives, we last covered Eagle Eye in April when Paul commented on a promising-sounding contract win with Tesco Clubcard.
Today’s update covers the financial year ending 30 June 2024 and shows profits ahead of expectation, at least at adjusted EBITDA level. Let’s take a look.
Financial summary: today’s RNS is a trading update only, so we don’t get full details of profits or earnings, only revenue and adjusted EBITDA. Here’s the summary:
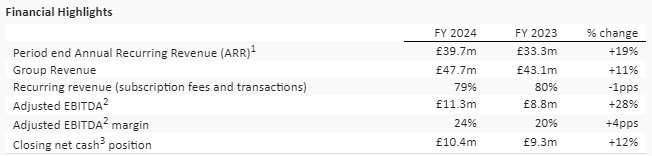
Strong annual recurring revenue (ARR) growth of 19% is encouraging, but the company says the proportion of its revenue generated from recurring charges actually fell slightly last year, to 79% (FY23: 80%). This is still an attractive figure, in my view, but I’d prefer to see it rising.
Group revenue growth of 11% to £47.7m also appears to be slightly below the consensus figure of £50m shown on Stockopedia. This is confirmed in an updated note from house broker Shore Capital this morning available on Research Tree – many thanks.
Despite this, strong cost control is said to have helped to lift the group’s EBITDA margin to 24% (FY23: 20%), resulting in a full-year adjusted EBITDA figure up 28% at £11.3m. That’s 5% ahead of Shore’s previous estimate of £10.8m.
Adjusted EBITDA isn’t my favourite measure of profit, as depreciation and amortisation charges can be real and significant costs for many businesses. However, today’s update confirms that Eagle Eye was cash generative over the last year, with net cash rising 12% to £10.4m. That’s a positive for me.
Consensus forecasts on Stockopedia ahead of today showed earnings of 11.4p per share for the year just ended. Today’s Shore note suggests adjusted earnings of 14.2p per share for the FY24 year.
Shore’s 16.4p forecast for FY25 has been left unchanged pending further guidance with September’s results.
These forecasts price the stock on FY24 P/E of 35, falling 30 for FY25.
Trading update - recent contract wins: Eagle Eye seems to have secured a number of new contracts close to the year-end (my emphasis):
The Group exited the Year with strong ARR, up 19% year on year, with the majority of revenue from the wins in Q4 FY 2024 to be recognised from FY 2025 onwards
New international customers flagged up in today’s update include Central Retail Vietnam, Z Energy in New Zealand (a fuel/convenience retailer) and French retailers Picard Surgeles and Chronodrive.
Wins so far in the 24/25 financial year have included Waterstones in the UK and RONA in Canada (a DIY chain).
Outlook: the company says its new AI-based offerings are helping to provide the business with “increasing opportunities”.
Chief executive Tim Mason reports a “significant sales pipeline” to support further growth through FY25 into FY26. However, there is no specific new guidance in today’s update, which is less than two months into the new financial year.
I’d imagine a more detailed outlook statement will be provided when the group’s results are published on 18 September 2024.
Roland’s view
I’m encouraged by Eagle Eye’s improved margins and evidence of cash generation this year.
However, I’m wary of the group’s historically poor performance on statutory profitability. Historically, the group has reported an operating loss in four of the last six years:
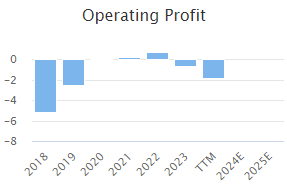
Looking ahead, I think it’s possible this business could reach an inflection point in terms of profitability and margins.
Last year’s (FY23) accounts show an impressive gross margin of 95%. The incremental cost of delivering services appears to be minimal.
If Eagle Eye can control its broader operating costs, while maintaining strong revenue growth, the extra revenue could drop through rapidly to profits, resulting in improved margins.
A forward P/E of 30 isn’t obviously cheap, but I am inclined to remain positive here, given progress with new customer wins and improved margins.
I’m going to go AMBER/GREEN on Eagle Eye, ahead of the publication of the full-year results in September.
Yu (LON:YU.)
Down 11% to 1,675p - HY trading update - Roland - AMBER
This morning’s update from this fast-growing business energy supplier and meter installer/owner is said to be in line with expectations. But it’s met with a poor reception from investors. Yü stock is down by around 11% as I write. Let’s try and understand why.
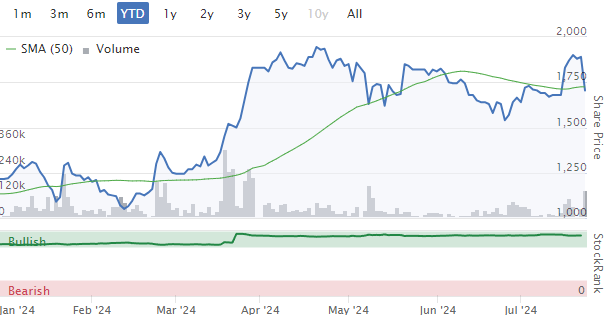
Today’s update covers the six months ended 30 June 2024, so it includes the key winter trading period when electricity and gas usage is expected to be seasonally higher.
The company makes numerous mentions of mild Spring temperatures but has left full-year guidance unchanged:
On track to deliver EBITDA and EBIT margins and therefore profitability for FY24 in-line with current market expectations, against a backdrop of lower commodity pricing and the impact of the mild temperatures in H1 24.
H1 highlights: Yü flags up some strong growth metrics in today’s update, but does not provide any indication of the like-for-like impact on consumption volumes of this year’s mild winter/spring.
Half-year revenue up c.60% to approximately £310m (H123: £195m), “despite mild Spring temperatures reducing consumption”
Monthly average [energy supply] bookings at £46.9m (H1 23: £51.3m) reflecting lower commodity prices
35% increase in supplied meter points in H1 24, closing at 72,300 meters (FY23: 53,400), driving higher total volumes despite reduced per-customer consumption
As far as I can see, the story is that continued growth in the number of customers supplied is offsetting any fall in consumption caused by mild weather.
The other strand to the business is its smart meter installation, Yü Smart. This generated less than 1% of operating profit last year but is growing and has the potential to provide an annuity-like income over time (my emphasis):
Yü Smart continues to scale, with meter installations in the period up 125% on the same period in 2023 (H1 24: 9,000; H1 23: 4,000), leading to 13,100 cumulative meters financed, providing a £0.6m forward annualised, indexed annuity income. Engineering field force headcount increased to 101 (FY23: 50).
Cash position: Yü ended the half-year with £86.8m of net cash, benefiting from the return of cash collateral relating to hedging contracts and “consistent customer collections”. Perhaps this means bad debt levels have fallen slightly? A small change can have a big impact on profits in this business, perhaps helping to offset lower consumption.
However, the company has a £33.2m annual ROC (Renewables Obligation Certificates) liability due in August.
Today’s update only includes guidance for “a significant net cash balance … at the end of 2024”, without being more specific.
However, I expect the cash figure to remain high, not least because I believe Yü needs strong liquidity to be able to manage commodity price hedging collateral requirements.
Share premium cancellation/dividends: the other notable update for shareholders is that Yü has now cancelled its share premium account, providing a further £12.3m in additional distributable reserves. This is expected to support increased distributions to shareholders, reflecting underlying cash generation.
Outlook: Yü’s statement on forward guidance seems carefully worded to me, again mentioning lower energy prices and mild temperatures:
“On track to deliver EBITDA and EBIT margins and therefore profitability for FY24 in-line with current market expectations, against a backdrop of lower commodity pricing and the impact of the mild temperatures in H1 24.”
The number of meter points supplied and the number of meters installed are both expected to continue rising, building in future revenue potential.
Sadly, the company has not included details of current market expectations for profits in today’s update. Stockopedia’s consensus earnings figure of 192p per share sits between unchanged estimates from brokers SPAngel (197.8p) and Panmure Liberum (185.9p) - many thanks to both.
Taking Stocko’s figure as a consensus estimate, the shares trading on a modest 8.8 times forecast earnings after today’s price drop.
Roland’s view
Yu shareholders have perhaps become used to the company beating expectations on a regular basis. Stockopedia’s broker analyst consensus chart shows multiple upgrades over the last 12 months:
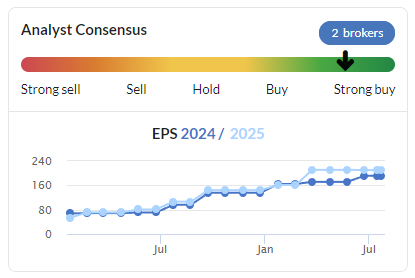
This run of upgrades now seems to have come to an end, despite continued strong underlying growth.
In this review of last year’s results, Paul commented that he was unsure if elevated profit margins can be maintained. That’s very much my view, as well.
My reading of today’s update is that the company is banking on strong growth to offset weaker consumption and the impact of lower commodity prices.
I would argue that today’s update has (slightly) increased the chance of a slight downgrade at some point, depending on trading conditions over the remainder of the year.
I remain encouraged by the strong growth of this business, which appears to have a compelling offer for its target corporate customers and a solid balance sheet. However, this isn't a stock I'd want to pay a premium price for.
Pending the release of the half-year accounts, I’m going to leave our previous view unchanged at AMBER.
Luceco (LON:LUCE) (Roland holds)
Down 2% to 166p (£265m) - HY trading update - Roland - GREEN
Luceco performed strongly in the first half against a challenging market backdrop. The Group's diverse portfolio and channels have ensured that we continue to deliver progress, with adjusted operating profit up around 15% in H1 2024.
Shares in this supplier of wiring accessories, lighting, power products and EV chargers are down slightly this morning after the company warned of a significant recent increase in container shipping costs.
Luceco depends heavily on manufacturing in China, so is unavoidably exposed to shipping costs.
Apart from this possible risk to margins, trading for the half-year to 30 June appears to have been reasonable.
Half-year summary: Luceco’s revenue rose by 8% to c.£109m in H1, albeit only 3.5% of this was like-for-like.
The acquisition of D-Line in February is expected to add c.£15m of sales this year, so presumably contributed much of the remaining increase in H1 revenue.
Adjusted operating profit for the half year is expected to be up by c.15% to approximately £12.5m. This performance was aided by a 0.8% improvement in adjusted operating margin to c.11.5%.
Leverage remains comfortable at 1.2x EBITDA, providing the option for further acquisitive growth.
Outlook: Performance so far is said to be in line with market expectations for the full year.
Unfortunately, “key industry metrics remain weak”, but management is confident “growth in our core markets will return in the not too distant future”.
The update doesn’t include any guidance on market expectations, but Stockopedia’s data suggest full-year adjusted earnings of 11.9p per share, up 7% from the FY23 figure of 11.1p.
These estimates appear unchanged today and price the stock on 14 times FY24 forecast earnings.
Roland’s view
Today’s update seems broadly reassuring to me. The improvement in operating margins suggests to me that Luceco is performing well in areas it can control.
Higher shipping costs are not fully within the group’s control, but if these persist I imagine Luceco would attempt to push price rises through to customers to cover some of the extra expense.
We’ve been positive on Luceco here in recent months. Given the group’s strong history of growth, I am happy to maintain a GREEN view ahead of the half-year results in September.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

103 comments
Although it is always a bit disappointing to see another good company getting snapped up, at least this afternoon’s bid for Ascential (LON:ASCL) by Informa (LON:INF) is an all UK deal at a good cash premium ( if it is agreed)
Some Australian billionaire called Brett Blundy has bought the Cardfactory stake.
Even sounds like a billionaire:)
He would appear to be an Aussie ‘poor man’s Mike Ashley’…the mind boggles!
TheOx, asked my little AI friend about him. Cattle empire to bras is good diversification
Brett Blundy, the founder of BBRC, has diversified his wealth across several sectors:
In summary, Blundy’s diverse portfolio spans retail, property, agribusiness, and technology, showcasing his entrepreneurial acumen and strategic investments
Hi Wolf
The research suggests that Mr Blundy has bought the Card Factory (LON:CARD) holding on the basis of the value on offer and will be supportive of the company and its aspirations. From memory I think that the company has some Partnership arrangement in Australia.
If this is the case and I can't think of a more plausible scenario I would expect the share price to continue to re-rate, albeit it may take a little time.
It would be interesting to know what he paid for the shares, but I don't expect we will ever find out.
Live on VOX Markets at 2pm Thursday 25th July, I will be interviewing top notch smallcap investor, analyst & commentator Paul Scott of Stockopedia.
It's sure to be another masterclass in all things stock picking - including lots of fascinating stock ideas such as: #CPI #HTG #GMS #HAT #IGP #JDW #JET2 #MACF #MEGP #NXR #POS #SYS1 #VLX #WTB #ZTF & many more.
Alongside of course, trying to answer any questions that you might have.
So please feel free join us here on Youtube. Everyone is welcome.
MJ GLEESON (LON:GLE) Harwood Capital buys an initial holding of 10.88%. Interesting as I thought they typically buy struggling companies to implement a turnaround strategy?
MJ GLEESON (LON:GLE) This is actually notification of a sale by Harwood - they have reduced from 6.6m to 6.355m. The RNS - like so many - is badly constructed
My bad - thanks for the correction mammyoko.
Auto: I thought Harwood had been significant shareholders in MJ GLEESON (LON:GLE) for some time. Would need to check an old Annual Report. Could be wrong
Silver Bullet Data Services (LON:SBDS) . For a tiddler to have Global brands on their books is quite appealing to me. A recent case study with AXA https://wearesilverbullet.com/...
Ian James: Google’s Decision is Positive for SilverBullet
Silver Bullet Data Services (LON:SBDS)
They will definitely need a fundraise (I have said it before anyway).
These global brands you are talking are not spending anything material on Silver Bullet Data Services (LON:SBDS) .
All the best
Silver Bullet Data Services (LON:SBDS)
I take a slightly contrarian view Yiannos
The revenue growth is pretty impressive - it will be a profitable (inc cash flow) business this coming year. I’ve followed this for a while and I like the job management are doing in growing clients. Lot of operating gearing about to come through I think.
Is the balance sheet stretched, yes. Does that necessarily mean they will need to raise money - no. They’ve had a history of avoiding dilution and the recent facility helps avoid that further.
I certainly wouldn’t rule out a small raise but I suspect that if they do it won’t be large - I’d prefer to have a half position now and take advantage of any raise where available to build a full position as I suspect it would be at a minimal discount anyway.
Hi David
You have a contrarian view BUT you wouldn’t rule out a small raise and you have a half position to take any advantage of a new share issue.
Must be or must have been a politician :-)
All the best
Haha - quite right Yiannos :-) that was a bit of a politicians view
I guess I have a hunch from watching Silver Bullet Data Services (LON:SBDS) management over time that they are keen to avoid dilution and thus are very focused on positive cash generation which, I understand, is anytime now. So I can certainly see a world where they avoid the need for a raise. But as you and Paul quite correctly point out the balance sheet is not exactly swimming with net cash either so I can’t completely rule it out.
But I do like the business and can see it doing well.
Looks like Cathal Friel out of hVIVO (LON:HVO)?
Edit: Id say definitely having seen the trades. He had 21,159,177 in Feb. Be interesting to see who bought them.
Wonder how that will affect the hVIVO (LON:HVO) price. Will soon see
hVIVO (LON:HVO) Unlike Telios & CARD and some secondary placings it has been well managed as no price movement today ... so far. Getting ahead of possible changes to capital gains tax?
Cathal loves Open Orphan - hVIVO (LON:HVO) - He always said he would be careful not to harm the company or share price when it was time to sell.
Rare to have someone deliver on their promises like that, respect!
hVIVO (LON:HVO) - hang on - that was 5 months ago - 14th February - and Friel is still today shown as Chairman and now has a holding of 3.11% Meanwhile there are a number of Funds which have significantly increased their holding - far more than the shares sold by Friel.
Directors are under a 12 month lock up at hVIVO (LON:HVO) unless Cavendish and Peel Hunt authorise differently - which either means they have an institution buyer who wants to replace Cathal as a long term shareholder at 29p or it is a different block of shares.
Octopus investments has been stake building and recently were above 4%
Either way it’s bullish for me. I’m not bothered about Cathal’s holding - he is an entrepreneur and is usually looking for the next opportunity - he doesn’t tend to stay involved with companies once the story starts to play out and I don’t believe he has been particularly “active” in the business for quite a while. You only have to see what happened with Amryt Pharma to understand the philosophy. After he sold it became a billion $ company.
I care much more about the quality of management running the business and whether they deliver on expectations. Mo ticks those boxes for me so I would care if he left and not if Cathal sells out.
The fact that institutions now see this as investment worthy at these levels also demonstrates the value on offer imo.
And now we know - a bunch of institutions attended the CMD and offered to buy all of Cathals shares at 29p.
Market reacting negatively but I’ve no idea why - it’s a good thing for me. Can only think some of Cathal disciples bailing out??
hVIVO plc (AIM & Euronext: HVO), a fast-growing specialist contract research organisation (CRO) and world leader in testing infectious and respiratory disease products using human challenge clinical trials, has been notified that Cathal Friel, Chairman, sold 21,159,177 ordinary shares in the Company earlier today at 29p each ("the Sale") to satisfy institutional demand post the Company's recent capital markets event.
https://newsfile.refinitiv.com...
It’s a great pity to see a director selling their entire stake while the company appears to be doing well. While I completely understand needing to take some money off the table, (and his loss may well be others’ gain) for me personally I like to see confidence from management, and selling down every last share does not speak to his confidence in the mid term growth story. I have now sold mine.
Jon - I think you misunderstand the situation and Cathal.
As I have said before Cathal is primarily a deal maker. He invests, buys, promotes and moves on. Usually he is quite good at spotting opportunities that can create those special situations . Cathal is not a BAU type guy. He is not running hVIVO (LON:HVO) - that ship sailed long ago. Mo Khan is in charge and knows what he is doing. I own hVIVO (LON:HVO) because of Mo and certainly not Cathal.
Cathal has a history of exactly this. With Amryt Pharma he also sold out early and it went on to seriously outperform. Its the psyche of a serial entrepreneur - so I would always be interested in backing him early but then if I don’t like the new management that are actually going to run the company I’d get out whilst it was still being promoted.
Cathal getting out doesn’t speak to anything about his mid term confidence in the business.
Thanks David, I understand that, but as someone who knows the business intimately and presumably the market opportunity, it’s always disturbing to see a total exit. In the short term it puts a lid on the share price, and longer term it poses questions about the growth opportunity. You can rationalise it however you like, he knows the business and has sold every last share. I’ve left good businesses and been happy to remain an investor!
Hi Jon - yes, the point is that Cathal doesn’t work like that. He is always recycling and at the moment he is buying Poolbeg Pharma (LON:POLB) and European Green Transition (LON:EGT) that’s just the psyche of the individual.
Check out Amryt Pharma - look at his exit and the resulting share price…..you will see what I mean.
Will be interesting to see what Cathal Friel does - his last hVIVO (LON:HVO) sale was followed by a Poolbeg Pharma (LON:POLB) purchase. I hold both.
I was thinking just the same thing James. Might be worth popping into Poolbeg Pharma (LON:POLB) , at least as a short term trade.
Since Cathal Friel is very popular today I will suggest to book on the 7th September the Sharestock day out. He will be there as a speaker and you can all meet him and ask him any questions you might have.
All the best
I will be moving overseas for work so won't get the opportunity to attend any live events in the UK in the next couple of years. Which is a ahame as its something id like to do more often. Thanks for the heads up though Yiannos.
On 24th of June Cathal purchased 7% in European Green Transition (LON:EGT) he might have mentioned selling some hVIVO (LON:HVO) on a Mello Monday in order to take advantage of this new opportunity
"Google Moves Away From Plan to Drop Ad Cookies for Chrome Users
Alphabet Inc.’s Google said it plans to give people who use its Chrome web browser the option to choose a more privacy-sensitive experience, rather than phasing out cookies, the software that lets marketers track users.
In a blog post, the company said it had made the decision after considering the impact that eliminating cookies would have on publishers, advertisers and others involved in the sprawling digital ad business.
“We are proposing an updated approach that elevates user choice,” Anthony Chavez, a vice president at Google, wrote Monday in the blog post.
“Instead of deprecating third-party cookies, we would introduce a new experience in Chrome that lets people make an informed choice that applies across their web browsing, and they’d be able to adjust that choice at any time.”"
Source: Bloomberg https://www.bloomberg.com/news...
A subscription site but I believe there are three free article views per month.
Google circumventing their privacy and GDPR obligations. Apple and others have already removed cookies. Let's see what the UK CMA thinks of the announcement. I remain positive on platforms providing alternative to cookies.
Problem is Grumpy if you think the US will descend into civil war ( I don't) you can be pretty sure AIM would be marmalised. No chance private investors seeing daily armed warfare across America on every news bulletin would think "I'll buy some Portmeirion (LON:PMP) this morning"
Personally I think the US may be in the last 1/4 of the current cycle. Everyone seems to have forgotten interest rates were raised very quickly, bound to be a lag effect and the US economy is starting to slow now from what I can see. Now I could be completely wrong and its smooth sailing, that's what Goldman Sachs thinks when it comes to forward earnings, but its common sense I think to watch for early signs.
Card Factory (LON:CARD) gone up heavily on no news in the past 2 days. Hopefully some positive news coming!
RNS yesterday afternoon highlighted the overhang from Teleios is now clear.
There was an RNS on Teleios voting yesterday but it's beyond my ability to work out the link of cause-effect...
US is historically overvalued but it deserves to be at a significant premium to international equities imo as the chart shows. Europe is a deindustrialising, Tech backwater. China is uninvestable. Japan is a ticking debt bomb.
As the US treasury guy put it "Europe is a museum, Japan is a nursing home, China is a jail"
I don’t think that the present situation in the US is entirely analogous to the dot com boom since companies such as Nvidia Microsoft and Apple are making huge profits. Nonetheless I think that AI is probably overhyped and there will be a crash in AI related shares at some time, it’s anyone’s guess when.
Wolf of SS - but then again most Americans haven't ever travelled abroad, so what do they know?
Even Kamala Harris said she's never been to Europe in 2021. Maybe she has now? Or maybe not?
Harris defends not going to border: ‘And I haven’t been to Europe’ (thehill.com)
I am currently in the US, and wonder if that premium can be sustained if it descends into civil war after the election. I was talking to a (commercially successful, apparently sane) chap yesterday who fervently believes that will happen. He has two full gun safes and 50k rounds at home, and is ready for action. There are many more like him. If the USA descends into civil strife, their risk premium will go through the roof, and we face global recession.
You do name yourself grumpy afterall.
Are you for real?
Less than likely if Trump wins the presidency, more than if he loses.
if it descends into civil war after the election
I was talking to a (commercially successful, apparently sane) chap yesterday who fervently believes that will happen
is the clue here "apparently"?
surely the american army could quell any civil insurrection that stars bfore it gets to war footing - do really think more than 1% of people are happy to participate in a civil war - probably not more than 0.01%?
I would say never but would be happy to take a bet there will be no civil war here.
In some respects the more civil unrest takes place the more i would expect the sensible people would rally to ensure order is maintained - eg enlist to ensure order is kept.
I thought that most americans beleive in their process and the rule of law despite whatever fiction the media tries to concocts.
That made me chuckle Wolf. Maybe a fair overview from a distance and as others have already commented like many Americans the Treasury guy may not even have a Passport!
Had quarterly review with an investment specialist yesterday. Their take is yes US is slowing down but will hopefully avoid recession, or only have a mild technical one like us. Interest rates to come down 1% over the next 12 months but won't go much lower after that, there or here. 'Flattening out' is their description. Mag 7 driving much higher level of profitability in Tech sector than in Dotcom boom and bust provides greater reassurance. Still expect that to come off the boil at some point,.
EU and UK looking good value overall and especially in the Smaller Co arena. Nothing we didn't know but useful to get the reiteration from another source. Suggesting some positioning in Value rather than fully on for Growth is prudent. They are slightly underweight USA as a result.
Also savings rate in EU/UK holding up surprisingly well. The US in contrast have been burning through any Covid savings built up at a rate. This is partly what has funded their growth over the last 12 months. Only Joe's ironically named 'Inflation Reduction Act' providing new kindling.
Performance over the last 12 months has been good so I'm happy to let them run with a 'sleep at night' part of my portfolio. Stops me inflicting too much damage on myself if I get carried away.
Also savings rate in EU/UK holding up surprisingly well. The US in contrast have been burning through any Covid savings built up at a rate. This is partly what has funded their growth over the last 12 months. Only Joe's ironically named 'Inflation Reduction Act' providing new kindling.
In addition to this the majority of small businesses who took out their covid loans in 2020 and 2021 - can now see the end in sight with regard to the end some somewhat crippling monthly payments - practicably speaking most of these loans were so one of in nature i doubt many will be going sraight out to get new loan when settled, I think standar term was 6 years on original batch (with ability to extend) so many now counting down months till payments end in may or june 2026 . this is dead cashoutflow not helping the economy that will hopefully be replaced by usaeful cash outflow (people spending again and keeping others in buisness!) - massive shoutout to those that have stuggled with this noose around their necks for the last 5 years ensuring that loans are for the most part being repaid. Hopefully the excess of bad debt over interest charged at the end of the day small beer and will be money well spent even if it is annoying that a small % of shysters will probably have gotten away with dubious antics due to lax controls at the start. I am talking about really basic stuff here evidencing business did have turnover and ensuring money didnt depart the "business immediately" for personal gain! - a few more basic controls ref use of funds lent would have ben sensible - so easy to say that with benefit of hindsight.
Very good Wolf, but he missed out India, that would be my top down regional play over the next couple of decades.
Morning Paul and Graham
Diaceutics (LON:DXRX) provided an inline H1 trading update this morning which I think is worth mentioning showing revs up 24% YoY and 28% on a CC basis. Following last year's 22% rev growth and 40% in 2022 when other companies in the sector are struggling to maintain revs and needing to raise cash, is of note.
Not far from a family biz, Diaceutics (LON:DXRX) is a 'technology and solutions provider to pharma and biotech companies' and has been on a 2 year investment program spending £7m of its own cash which finishes this calendar year. Cash hasn't moved much over that period - net cash end June 2024 was £16.7m (no debt).
Diaceutics (LON:DXRX) is a precision medicine platform which helps pharma get the right drugs to the right patients quickly. Margins are around 85%. This is really good for patients and also helps pharma pinpoint the right patients for their drugs and increases revs significantly. Management say no other company has a platform which provides daily notification or provides the scope of services, so feel they are in a sweet spot, hence the increased investment. Strong increase in revenue and profit is forecast.
Recurring revs are now 55% (35% in 2022) and expected to be 60% by year end, inline update and strong order book and pipeline bodes well. US sales force has been doubled in 2024 and a partnership with KPMG in the US should be supportive of driving sales which were previously mainly word of mouth. Almost all the large pharma companies are clients but siloed, so lots of opportunity. Further partnerships are expected.
Management are impressive and also heavily invested both in passion and shares (about 25%). I have been invested for approaching 2 years during which time management have stewarded the company well through turbulent times and always done what they promised.
Historically, there has always been a 40%/60% H1 /H2 weighting as much biz comes from the US where pharma budgets are finalised in December.
Quite a scary chart:
What’s the scary thing about this chart?
You are concerned about mean reversion.
I think that yes come the fall of civilisation, the value of all equities will revert to 0. Probably not in my lifetime.
The US is currently an almost blessed place. It's a rich country that is not full of pensioners like Germany. Energy is cheap unlike most of the developed world. Lots of natural resources unlike most of europe. Most trade is internal unlike the uk. Good legal system. Clear rules on ownership of things. Self sufficient on food. Cheap labour in south Mexico.
I don't see things changing for some time. There is a case to be made that the us is a different class of country compared to the rest of the first world.
One set of stats about America (if you believe it) Not an almost blessed place for many
Wealth inequality is higher in the United States than in almost any other developed country and has risen for much of the past 60 years. https://apps.urban.org/feature...
You are right. I prefer living in the UK with its NHS and sclerotic economy. And the rain. And that shade of green you get in spring that you will not find anywhere else.
...and the USA has the worst health outcomes achieved at the highest per capita cost in the developed world. My sister-in-law is a cancer surgeon in Utah. As she says: "God help you if you are poor and have cancer in the US".
I note Card Factory (LON:CARD) is up again today, threatening to escape from its 2023/24 holding pattern, after Telios disposed of the last of the previously 20% holding.
I can’t recall a better example of a share overhang limiting the upside share price than this. Every time Card Factory (LON:CARD) got up to around 110p it ended up sliding back to 90p or so, like some annoying game of snakes and ladders.
Another sign of government commitment to NHS investment - Galliford Try Holdings (LON:GFRD) announce today that they have secured a place in the North of England £835m spend over the next five years. They don't specify what proportion will actually come their way - but I guess even a small share will be significant.
https://www.stockopedia.com/sh...
CARD Factory (Lon:CARD) I hold
Up 5.6% this morning. Announced yesterday:-
Card Factory PLC has announced a notification of major holdings, revealing that Teleios Capital Partners LLC has disposed of its entire 9.92% voting rights. The Swiss-based investment firm reached this position on July 18, 2024, and notified the UK-based greeting card and gift retailer by July 22, 2024. No further voting rights are held by Teleios Capital Partners through shares or financial instruments in Card Factory PLC.
I doubled my position in Card Factory (LON:CARD) as a result of the announcement yesterday. I was hoping for more of a pickup, but will hold on for a while, but, profit is profit (I sold Avingtrans (LON:AVG) ) to purchase, so that's a buy signal to everyone I bet suddenly there is news about it..!
Results from SThree (LON:STEM) in stark contrast to other listed recruiters. Same general market conditions, different result. The key is in the establishment of a large base of installed contractors whose skills are irreplaceable and essential to customers objectives. For that you need to be in structurally compromised segments of the employment market where demand exceeds supply, even in hard times. STEM makes bold claims about being the only global specialist in the fields in which it operates. These claims are complete nonsense. But they are the only UK listed recruiter to meet that description. What I’m also pleased about is the management of headcount to drive a higher profit figure. Large recruiters cannot count on employing a high proportion of high-quality consultants, since these tend to flourish better in more focused boutiques. Instead, they need to constantly revolve headcount to keep quality of consultant “good enough “. When times are tough this willingness to usher poor performers out of the door pays off.
A very good report, I thought, given the circumstances.
Would be interesting to know what SThree (LON:STEM) are hearing from their clients about how ChatGPT / GenAI is changing the way that tech roles are done, and what implications that has for hiring and for their business. How are they adapting to the changing landscape?
SThree (LON:STEM)
i gave chat gpt a run yesterday ref bread and butter tax question - it got the answer completely wrong , strangely when i told it was wrong with some basic extra info (that shouldnt have been needed in the fisrt place) it did concede the fact it was wrong , so unlike me it at least its accepts it when it is wrong . Deffo though still a work in progress - albeit i would say the progress made by stuff like this is pretty amazing in sucha short piece of time. IMHO with stuff like this people who can think logicaly are nore important than ever as the dangers of letting computers make decisions they should make is pretty obvious (do humans do any better cloudfare?).
Ref stem i would say a pretty admirable set of numbers here - very well run business even if things are clearly in reverse at present. I think they may need to face reality that current numbers for 2025 look pretty ambitious. This wasnt high conviction purchase when i bought due to the sector it is in but management have impressed me enough that i am happy to stick around despite the fact the shareprice is up decently anfuture prospects are down since i bought - that is normally easy decision to say one got lucky and take the profit and run.
Agree it could be dangerous to let this type of tech completely off the leash, but, ChatGPT (or similar tech) can often generate working software code much faster than a typical programmer. It might not be right every time but it can make human coders much more efficient as long as they don't take their eye off the ball and accept that they will need to test and sometimes modify the output code or reword the question they are asking to ChatGPT.
Science (LON:SAG) Interim results to end June 2024
Nothing too exciting, solid progress made with integration of TP Group. The consultancy division took one step backwards with reduced activity in medical and industrial markets and rundown of low margin defence contracts acquired with TP Group. Turnaround of audio chip designer Frontier progressed to breakeven as destocking normalises. The highlight being continued turnaround of the submarine environmental business CSM2 which grew revenue and profits strongly. R&D collaboration with consultancy group resulted in filing of 12 patents with improving visibility over long term contracts and opportunities.
Revenue £53.686m -4%
Adj op profit £10.989 +5.5%
Adj Op Mgn 20.5%
Eps 12.9p +8.4%
Adj Eps 18.1p +10%
cashflow £10.726m +50% (above cashflow for FY23)
net cash £26.4m
Profit is in-line with full year expectations, with forecast adj eps up 65% for FY24, though revenue now looks to be H2 weighted and I would not be surprised by an FY with revenue slightly down on forecasts.
With cash burning a hole in the pocket and further cash flow generated from an H2 outlook broadly the same as H1 - increased share buyback to £5m. Still on the lookout for suitable acquisitions - but plenty of scope for improving the consuitancy division and continued improvement in Frontier in the meantime.
Note the £1m expense of treasury shares issued to satisfy exercise of options in H1. Though in this case of of the 317,500 shares issued only 70k were issued to 3 directors. Options were also granted over 330k shares - to 43 employees with only 65k to three directors. The executive chairman and largest shareholder (21%) was not a participant in any of these awards. That seems to me as a shareholder to be a well run performance incentive plan?
share price (before opening)415p is 12x forward 12month profits - not expensive for a company already delivering adj operating margins of 20%+ and forecast adj eps growth of 65% for the full year? Share buyback increased - makes sense - assuming that cash and cash generation is more than enough for any upcoming M&A.
I do like it when turnarounds start to gush cash. Given the accounting rules it can be a predictor of future gushing profits?
cheers
Mark
Science (LON:SAG) . Good quality company with high margins for a (largely) consultancy business trading on a cash adjusted PE of around 10. Modest single digit EPS growth (not 65%!)in forecasts but they look set to beat for the full year, and more to come from economic recovery and an improvement in the breakeven Frontier business as destocking ends. Good operational management with a disappointing contempt for outside shareholders , and no interest in investor relations whatsoever. Big cash pile provides an opportunity for another acquisition, where management have a good track record of vulturing underperforming businesses
Science (LON:SAG)
Jesseowens
Generally agree with you. Though I left out a lot of my detailed thinking in attempting to be brief.
The history of Science Group aka Sagentia is as an IP development group. If you adjust thinking from consultancy hire to IP development then management strategy and margins make more sense? Hence the focus upon CMS2 building IP and Frontier reverting to pure IP development? Of course I may be mistaken here.
I prefer good operational management with 'disappointing contempt' for outside shareholders to good shareholder relations with disappointing contempt for operational management. Just my thing, Also surprises me how often shareholder value shareholder relations above operational management? But then my background is in operational and executive management of aerospace/defence companies so I'm biased. I think it can help give me an edge, though not without added risk.
I referred to adjusted eps forecasts. Stockopedia quote adj (normalised) FY23 eps as 20.2p and FY24 forecast as 33.6p for 66% growth?
cheers
Mark
The Stockopedia data provider sometimes mixes up normalised and adjusted figures for previous years and can't be relied on for small companies. The correct figures per house broker for Science (LON:SAG) are fully diluted EPS of 32.9p for 2023 and forecast of 33.3p for this year. With a first half EPS of 18.1p in the bag this looks very beatable. Agree about non promotional management but they refuse to even answer basic questions by email in my experience . It's so easy now to do a webinar once a year and I think the actual owners of the company deserve to be better informed and ask questions of management
Anyone ever invested in AFC Energy (LON:AFC) wont be surprised Adam Bond has completed his last fundraise and is off back to Australia
Still no viable business, but he's made a lot of money.
I don't think ukgov should put any more money into hydrogen based projects, they are just a money pit. Hydrogen just doesn't make sense, expensive to produce and not a good store of energy
Hydrogen is expensive to produce if you electrolyse water for sure, but there are also large reserves of hydrogen worthy of extraction. Electrolysis of water to produce hydrogen is best viewed as part of a smart grid where excess cheap energy that would otherwise go to waste, is used to electrolyse water. This is how some hydro stations work using cheap energy to pump the water back up. You can make a successful argument that vanadium flow batteries do the same job cheaper.
As far as hydrogen being a poor store of energy, that depends on what you are comparing it to. The enthalpy of combustion of hydrogen is - 285 kJmol−1 compared to -890kJmol−1 for methane (natural gas). However, the combustion of 1 mol of methane produces one mol of carbon dioxide, whereas the combustion of hydrogen produces no carbon dioxide.
All the green alternatives to hydrocarbons, except for nuclear, are less efficient and less energy dense. We will pay a high price for our withdrawal from hydrocarbons, but speaking as a chemist, hydrogen has a role to play in the mix, and especially for heavy transport and logistics,
All good points James and they may make a quantum leap at some point but I have yet to see a commercially viable Hydrogen product that can stand on its own two feet, large or small.
After IEH, PHE, and AFC I certainly won't go anywhere near a blue sky hydrogen company again.
I have to admit newinvestor1972, I hold no hydrogen investments and have no intention of entering any either for similar reasons.
I don't think there is a quantum leap (nice choice of words!) to be made in its production; Gibb's Free Energy says not although there are lots of opportunities to improve the storage of hydrogen. We have a saying in Chemistry ... "the leading edge is often the bleeding edge", or as Paul would say ... steer clear of jam tomorrow shares.
I think we will be burning hydrocarbons for some time to come and, for the life of me, cannot fathom the current governments' obsession with closing the exploitation of our own reserves in the North Sea. I sold all my North Sea O&G investments as I feared what a future Labour government would do ... and here we are.
I have kept an eye on hydrogen / fuel cells ever since I worked for a majorJapanese utility several decades ago. The Japanese have had viable hydrogen cars for years - in fact James May has owned a couple of them.
Problem is that commercial traction has always seemed just over the horizon.
What I've picked up along the way is that the engineering challenges of hydrogen are much greater than they may first appear, for very boring reasons. It is a difficult gas to handle - a small molecule gas needs to be stored at very high pressures to get the required energy density, which makes leaks (and car prangs) a major headache. Or you turn in into a liquid....at a mere -250c..... Stuff like interstitial hydrides for solid state storage never really got near commercial viability.
In most cases you can't just repurpose natural gas infrastructure.
It remains a live prospect in heavy transport, but for light road vehicles batteries have had more investment and are ahead in the race, for better or worse.
And that is all before the green/grey hydrogen considerations.
NewInvestor Riversimple have had a hydrogen car driving around the UK and Europe for a couple of years. Gearing up for production on a monthly sub which will include all fuel and repairs. I hold a small amount via crowdfunding. There are hydrogen buses. I am quite interested in the sector- have an (showing loss) exposure through an Investment trust Hydrogenone Capital Growth (LON:HGEN)
It is the use of ammonia to utilise hydrogen for large scale power production, not electrolysed water, where we are likely to achieve commercially viable use of hydrogen.
https://en.wikipedia.org/wiki/...
I agree that we are not there yet, but the many of these companies are securing larger contracts, while refining their products and reducing cash burn. None that I have in my watch list are forecast to make a profit in the next 3 years, but a growing base of reference users and improved reliability as well as efficiency could see things change quicker than some expect.
My only holding in this area is Ceres Power Holdings (LON:CWR), who are differentiated by both their solid oxide technology and their licencing/royalties model.
The problem with this route to product is that ammonia, NH3
is manufactured using the Haber process which fixes atmospheric diatomic Nitrogen and combines it under high temperature and pressure to form ammonia. The source of the H2 is natural gas, CH4, so this route remains dependent on the hydrocarbon industry. This route also competes with the global N-fertiliser industry for feedstocks.
This type of hydrogen is known as blue hydrogen being derived from natural gas. Green hydrogen is derived from electrolysis using surplus green energy that would otherwise be wasted, so the marginal cost of energy is close to zero. BTW, there are lots of other colours of hydrogen depending on its source,
In my view, Vanadium flow batteries are a better storage of surplus green energy that electrolysing water to form hydrogen which then creates storage issues; whereas Vanadium flow batteries can store and release the energy back into the grid when required.
I believe there will be a substantial hydrogen industry, but it will be based on traditional extraction. The technical knowledge, wellhead engineering and pipe infrastructure already exists to create a hydrogen industry. Toyota and several bus and lorry manufacturers are on board with the technology at the vehicle end. There are 5 trillion tonnes of Hydrogen worldwide and potentially a large and non-polluting industry. That is where I would be looking for investment opportunities.
Agree with comments around blue hydrogen though the green lobby argue that production of hydrogen from natural gas is just an excuse for the oil & gas companies to stay in business! For example BP (LON:BP.) have projects in green & blue hydrogen for industrial applications. Where blue hydrogen is produced via natural gas I believe the intention is to combine the production process with carbon capture and storage to remove the CO2 emissions. Not sure about the economics or practicalities of this approach but I'm sure if it can be done the major oil & gas companies have the skills/expertise to develop the process.
Re Vanadium flow batteries I did hold Bushveld Minerals (LON:BMN) to try and play that particular theme. Unfortunately the mining aspect and the uncertainties of operating in a South Africa proved a disaster and I lost virtually all my investment which was fortunately fairly small!. There may be better players out there but it seems a pretty speculative area.
AFC Energy (LON:AFC) A disgusting story i have been following for years. Floated 18 years ago, every year promising sales but none delivered, no viable product. Even appointed a highly paid sales director four years ago when there were no sales.
Total losses of £100m accumulated. But of course Adam Bond CEO has taken up to £1 million a year in salary and bonuses. But the biggest mystery is that they continue to raise money every year, £89m raised in last 5 years. Mainly from fund managers who should know better.
For me the main lesson is that many institutional investors have no clue what they are doing. How can they not see and understand the appalling track record.
Stocko class AFC Energy (LON:AFC) a sucker stock and the metrics say it all - it only scores on its story (momentum)
Positive AGM update from Fuller Smith & Turner (LON:FSTA). Net debt down to a very modest (by pub co standards) £92m and margins improving as cost pressures ease.
Hopefully a read across to Youngs, I hold the non-voting shares Young & Co's Brewery (LON:YNGN)
Altitude (LON:ALT) This morning RNS looks very positive. Not a company I know. Have been reading the StockReport and it’s not that highly ranked. The forecast dividend is high (is this reliable?). Would appreciate any insight from Roland or Graham. Thx.
Sadly, the dividend yield figures for Altitude (LON:ALT) on Stocko are nonsense. Div yield is nil. The earnings figure is a beat against forecast but revenue is about 9% light so it will be interesting to see what Graham or Roland think. Zeus have a brief note out this morning.
Alpha International (LON:ALPH) . TU out. Provides great info and comparisons. Completely different level of TU compared to the smoke and mirrors of an EQLS or FIN TU .
Whilst commendably thorough on many details, surprised Alpha International (LON:ALPH) didn't include a PBT figure to make life a little easier.
At 40% margin on £64m H1 revenue = £25.6m
+ £42m H1 interest income stated
Total H1 PBT = £67.6m.
Assuming they do the same in H2, and corp tax 25% then the PE is 9 (nearer 7.5 if include £180m cash) so plenty of upside imo
Yeah, the lack of any detail on profit or profit margin from Alpha International (LON:ALPH) made me suspicious, from a company that never makes me suspicious. But then I looked back to the trading update at the same time last year, and they said something equally vague about profit margins only - so same as usual then:
2023: Delivered strong operating margins whilst continuing with accelerated investment programme.
2024: Delivered strong underlying profit margins alongside continued strategic investment.
Slight change in wording from operating to underlying but I'm not sophisticated enough to know if this means anything.
Otherwise, rock solid trading update, with lower group revenue growth than the first six months last year (20% versus 16% this year), but higher (I think) than H2 last year.
Every time commentators talk about interest rates staying higher for longer, I think of Alpha International (LON:ALPH), the net treasury income is ridiculous.
Pleasing.
Chris
Filtronic
Headline grabbing 9m usd order from Space X .
Impossible to value right now so everyone just guessing but seems to be hesding further into orbit in the next 12 months .
Youd have to think why Space X dont just grt it bought, but I guess in a way thats what they have done with the warrants they have as part if the deal .
I'm unclear with Filtronic (LON:FTC) whether this order has already been accounted for, or not.
If Space X don't buy this soon (and I hope they don't), then other players might be using their tech in their products, (i.e. Bezos is in the game).
This "latest news" was on their own website 24th April 2024 https://filtronic.com/news-eve...
Same deal? - More of the same? Oh! April was the strategic agreement - This is a contract win under that deal
Cavendish put out a note this morning which I have just finished reading. The "new" order is not new, but is included within the original contract ... at least that is how I read it. The SP has reacted as if it is a new order.
I read it as a separate win. They first won to be on the Framework which was the April agreement, and then won a contract under that framework agreement.
Filtronic (LON:FTC) $9M contract win from Musk’s Starlink
Luceco (LON:LUCE) cautions on considerable increase in shipping rates.
Outlook
· The Board is encouraged by the strong start to the year with performance expectations for the full year in line with market expectations.
· We continue to closely monitor the cost of container shipping, which has recently increased significantly.
· Key industry metrics remain weak, however, we remain confident that growth in our core markets will return in the not too distant future.
https://www.investegate.co.uk/...
H & T Group, H & T (LON:HAT) has risen 10% in the week before this mornings "in line" announcement. Nothing to see here then? I HOLD
Given the strongly rising gold price, I think many were expecting some stellar results from H & T (LON:HAT) - today's update was a bit of a disappointment I guess.
Not sure what it's going to take for H & T (LON:HAT) to re-rate at least to a PE of 10 which is closer to their historical value. Just seems very unloved at the moment
I'd say H & T (LON:HAT) has already re-rated? Currently trading at 4.8x PE historic (FY23).
If you look at the historical graphs, pre-COVID in 2018 and 2019, it only ever traded at a high of 4-5x PE. Operating Margin, ROCE all look quite similar for FY23 vs FY18, FY19.
Why would one expect a higher PE valuation? Especially as Pre-COVID valuations had 0% interest rate environment...
I don't think expecting the market to value this at 10x in the next year or so is realistic... unless the growth prospect is high? But outlook today is quite muted? Certainly positive progress expected this year, but not bag loads?
Agreed. Sold out at the open H & T (LON:HAT). Gold price at record, they should be doing a lot better.
I don't think that historic PE chart is correct - I've followed H & T (LON:HAT) for years and never seen it trade on 4-5x PE. I'd say 8-12x has been more typical in the past, although I agree this sort of business unlikely to hit a 10x PE any time soon.
Just had another thought on H & T (LON:HAT) and the read-across to consumer budgets / spending.
Many H&T customers use their valuables like a credit card; they pledge them for cash, redeem them, and then repledge them, in a cycle way. I think I remember hearing this on a webinar from H&T before, that this is their consumer pattern.
So the fact that redemption rates were higher than usual since the end of Ramadan (Apr24), and a lack of repledging items, suggests that (for H&T's customers at least) they are seeing better household financials. Driven by the national wage increase in April maybe?
You could then infer, since H&T are struggling with the growth of their pledge book, and people have cash to redeem their items... that at least a subset of consumers in the UK are in a better financial position now, than they were pre-April.
Yu (LON:YU.) trading update out. £86.8m net cash against a mkt cap £317m!
Bobby Kalar, Chief Executive Officer, said:
"I'm proud to report a continued set of strong results; with revenue, meter points supplied energy, and meters installed increasing by c.60%, 82% and 125% respectively on the same period in 2023.
We continue to focus on delivery of our strategy, increasing market share through our unique Digital by Default offering and supported by our new agreement with Shell, and to deliver sustainable margins as we scale.
Cash generation is very strong and provides a good basis to support our progressive dividend policy and to invest in strategic initiatives.
I remain excited by the future and am fully committed to delivering shareholder value. I would like to thank my fantastic team for continuing to deliver our growth trajectory and enabling the Group to benefit from its position as a key challenger brand in a £50 billion market."
https://newsfile.refinitiv.com...