Small Cap Value Report (Tue 24 Dec 2019) - IQE, TND, TSLA

Good morning folks,
in today's news, IQE (LON:IQE) has promised to adjust its remuneration policy next year after 42.9% of shareholders voted against it at this year's AGM. More on this to follow.
Elsewhere, there is a holdings RNS from Tandem (LON:TND) (in which I have a long position). Jupiter has been reducing its 10% stake - I wonder is this for fundamental reasons?
Due to a lack of news flow, I can cover other topics for you - any requests? A roundup of Tesla might be fun, after the stock reached the fabled $420 level yesterday.
Timings: I will wrap this up at 12.30-13.00, as the market closes. Finished at 13.00.
IQE (LON:IQE)
- Share price: 45.46p (-3%)
- No. of shares: 793 million
- Market cap: £360 million
AGM LTIP resolution voting and proposed actions
LTIPs ("long-term incentive plans") are considered to be perfectly standard devices and respectable consultants are available to advise companies on how to structure them. But I think it's difficult to find any, in real life, which are structured well.
And since remuneration is a very boring topic, few investors give it much thought. So we miss out on an understanding of how company executives are incentivised.
Shareholder dissent
IQE has noticed that 42.9% of shareholders voted against its 2019 LTIP at the most recent AGM. This is a rare level of opposition to an LTIP.
The company says it "did not anticipate any significant dissent", i.e. that the vote came as a surprise to it.
On the other hand, it was aware that ISS (a respected advisory body used by fund managers) had recommended voting against the LTIP.
Let's scroll back for a minute. The AGM took place all the way back in June. Why has it taken so long for a response?
I note that 173 million votes went against the LTIP. This says to me that some of the funds on the shareholder register (Invesco/Oppenheimer, T Rowe Price, Schroders) must have voted against it, in line with the advice from ISS.
Only about half of the total share count voted at the meeting - this is not a surprise. Most of us (myself included) only very occasionally vote at shareholder meetings.
If you agree with what a company is doing, and if your vote won't make a difference anyway, then I think it's reasonable not to vote. But it's important to remember that you do have the right to vote, in case you might ever want to exercise it.
The details
ISS recommended voting against the LTIP for two principal reasons:
1. That the dilution limits sought under the plan exceeded the standard dilution limit expected by institutional investors of 10% in 10 years for all of the Company's share schemes; and,
2. That the plan permits the vesting of outstanding options to good leavers without a pro-rata reduction to vesting based on performance and the portion of the vesting period expired up to the time of the termination of employment.
Dilution of more than 10% is extreme, when we are talking about a large company.
I must admit here that I own shares in Creightons (LON:CRL), where dilution of 12% is possible over ten years, under an existing option scheme.
In my defense:
- the details of the scheme at CRL were announced after I had built a stake in the company
- CRL is a much smaller company than IQE, and so the management at CRL are arguably even more critical to the company's success
- I might end up selling out of CRL ealier than I otherwise would, due to the dilution risk.
But let's get back to IQE. IQE says that it can't get under the 10% dilution limit for now, due to options already granted, but it will do so over time. Fair enough, I suppose. If it gets down to 9.9% in a few years, that would still be an awful lot of remuneration.
With respect to the second point, it means that employees can leave early and get all their options, without any reference to their performance or how long they stayed at the company.
In response, IQE pledges that the LTIP plan will be amended so that entitlements for employees who leave will take account of how long they spent at the company.
But IQE does not pledge that entitlements will be performance-based.
I ought to have a moan about this, but I note that CRL's options do not have any performance conditions, either!
The Solution
Investors need to be aware that we are seen as piggy banks by companies. If we put up with things like this, this is what we will get! We need to vote with our wallets and have a strong preference for those companies with sensible remuneration schemes.
If it was up to me, I would try to do away with share options schemes, or at the very least, reduce their size and importance.
In a bull market, share options work well for employees and investors are getting richer anyway, so they don't mind too much.
The problem is that in a bear market, employees will want cash, not worthless share options.
So instead of risking the company's workforce on the continuation of a bull market in stocks, I prefer to see employees getting paid cash bonuses. That protects the integrity of the company's share count too, which in the long run will boost returns for equity holders.
The IQE share count has been rising for a long time, and I think that investors are right to query whether all of this stock issuance has been necessary, or has really benefited them.
Tesla ($TSLA)
- Share price: $419.22 (+3%)
- No. of shares: 180 million
- Market cap: $75.6 billion
On October 7th, as detailed in the SCVR, I closed my Tesla shorts:
I like to be as transparent as possible when it comes to my personal portfolio, so please note that I have today closed both my short position in Tesla and my long positions in the FTSE Index...
To be clear, this has not been driven by any change in my view of the merits of these trades. I still view them both as extremely attractive. The reason is that I am in the middle of a house-buying process, and need to use the collateral for the deposit and fees. The potential returns from a trading account must be swapped out for the certainty of home equity.
As you can see, I can't claim to have miraculously predicted the rise in Tesla's share price.
Instead, what happened was that I needed to free up some funds, and shutting down my spread betting account was the most responsible way to do it.
A reasonable question would be: out of all your positions to close, why choose Tesla?
My answer to this question was published elsewhere:
As a general principle, spread bet/CFD positions don’t have a positive expected return after trading costs; they rely on the investor betting correctly on market movements (and this is so unlikely and rare that most governments prefer to leave spread bet/CFD profits and losses outside of the tax system).
Physical shares, on the other hand, do have a positive expected return. If you buy and hold a share, and do nothing else, and ongoing charges are close to zero, then you should eventually make money, on average. Stock markets tend to go up, over time. Or as Kimbal Musk would say: stocks generally go up and to the right.
So from that very simple perspective, and despite my strong views on Tesla, I thought it was more responsible to liquidate my spread bet/CFD positions rather than selling any physical shares.
Hopefully that is a clear enough explanation. Making money on a short position requires more skill than making money on a long position, and there were no long positions which I was desperate to close, so I preferred to leave them open.
As recently as August, I had been shorting Tesla with a lot of conviction. The only problem with the short, I noted, was the $5 billion cash balance and the lack of a short-term catalyst for financial collapse.
It turns out that the simple reasoning which justified closing my short ended up saving me a lot of angst.
Tesla has more than doubled from its lows and increased by $190 per share versus where I closed my short, at $231.
Musk Triumphant
One of the great red flags for short-sellers is a stock-promoting CEO.
Twitter has been a gift in this regard. It provides a venue which stock-promoting CEOs can't resist, and where short-sellers can easily monitor their antics.
Musk has already been fined $40 million for what I believe was the largest and most blatant stock market fraud in the history of finance, when he tweeted about a fake go-private deal for Tesla last year.
The fake deal was supposed to happen at $420 - this number is a drug reference that Musk thought would impress his girlfriend.
Tesla had never actually traded at $420 before - until now. It reached that number yesterday.
And Musk wasn't unhappy about it:
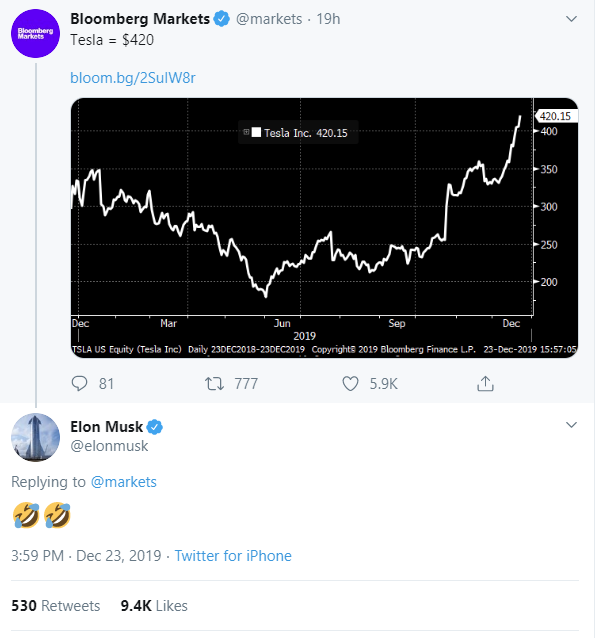
And:
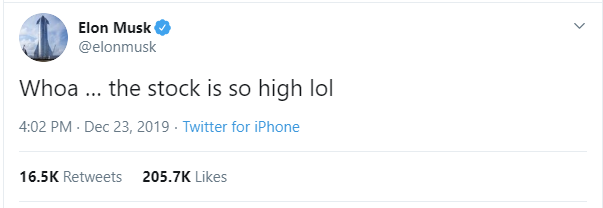
And:
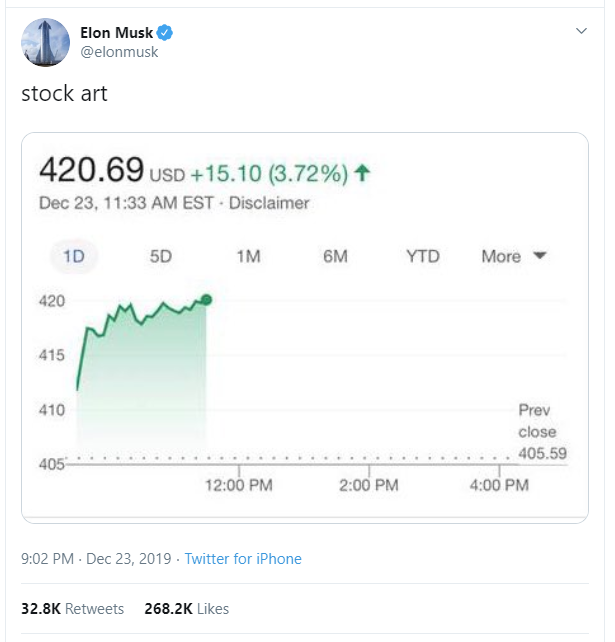
This is very foreign to those of us with a City background, where business people tend to behave in a "proper" sort of way, at least publicly!
But even by US standards, it's weird for a CEO to act like this.
If the person in charge of a tiddly small-cap, in any country, said "whoa... the stock is so high lol" about their own stock, it would be a good invitation for bears to look into it and see if there was something wrong with it.
When it's the CEO of a $75 billion company, on the other hand, it's scarcely believable. Except for the fact that this is Musk and Tesla, and we've seen this sort of thing from him before.
I feel bad for the shorts who are sitting on huge mark-to-market losses at present - because I still think their analysis is correct, even if their timing is off.
On the other hand, it's worth pointing out that if you compare Tesla to the index, it hasn't outperformed the NASDAQ by much or at all over the last few years.
In other words: we've been in a bull market, and most things have gone up. So if you've been shorting Tesla for a long-ish period of time, then your performance isn't that bad versus shorting other things.
But if you shorted Tesla in the last few months, then you might be sitting on a 100% notional loss (or more than 100%, if you used options).
That's the nightmare for short-sellers, and it's why short-selling is so dangerous. When you get it wrong, the problem gets bigger and bigger until you eventually get pushed out of the position.
Tesla short interest has declined to 25.5 million shares, versus 43.6 million shares last May.
According to Marketwatch, the number of Tesla shares sold short has not been less than 20 million since mid-2013.
It does feel like we are in the middle of a short squeeze, as shorts desperately close their positions in the midst of a stock rally, adding fuel to the rally's fire.
Musk has been obsessed with his short-sellers for some time. Only last month, he made fun of hedge fund manager David Einhorn with a juvenile letter, posted on Twitter (Einhorn responded, taking up the offer to engage further with Tesla, but nothing came of it).
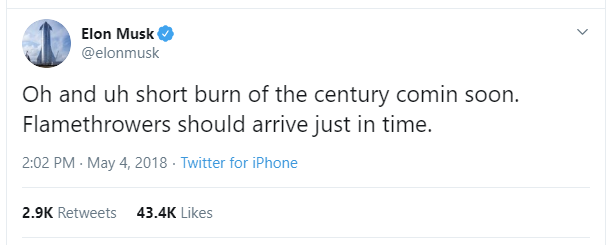
For now, Musk has won his battle with the short-sellers and may yet bring about the short burn of the century which he promised:
Miracle Profits & Chinese Dream
Allow me to quickly give you a recap of plausible reasons why Tesla stock has been roaring higher.
For Q3 2019, Tesla reported after-tax profits of $143 million.
Most of us were expecting it to post another loss.
The belief that Tesla might prove to be sustainably profitable and cash flow positive from now on has undoubtedly played a big part in the subsequent rally.
I remain deeply sceptical. I don't think the Q3 result was exactly as it first appeared.
Foreign Exchange gains
$143 million is not a large profit to begin with, and it was boosted by the fact that it included gains from foreign currency movements, while negative impacts from foreign currency movements were left out.
If you scroll down to "comprehensive income", you see that the real "bottom line" profits were a measly $29 million, which is negligible for a company of this size.
Accounts Receivable
David Einhorn (mentioned above) has been calling out Tesla's accounts receivable balance of $1.1 billion. Tesla's sales are predominantly for cash, so how does this work?
The company has suggested that it has to do with quarters which end on a weekend or bank transfers from European sales taking weeks to clear, but these explanations don't make a ton of sense.
Warranty Reserving
There has been some in-depth analysis (here and here) of whether Tesla is making sufficient provisions for its warranty liabilities.
It hasn't been proven beyond all reasonable doubt yet, but I do think that these are legitimate questions. Many customers can be found on twitter, with their messages following this template:
"I love the car, but [it has some terrible problem and I would really like somebody to fix it please.]"
When Tesla does fix cars, it has a tendency to call them "goodwill" rather than a warranty job.
The argument from bears is that this is a technique to avoid using up its warranty reserves a lot faster than it was supposed to. The argument goes that if it recognised all of these costs as warranties, then it would have to make a bigger provision for future warranties and its reported gross margins and profits would decline.
Cash flow games
Tesla proudly reported $371 million in free cash flow for Q3.
Again, the bears spotted a problem with this.
If you go to the cash flow statement on the 10-Q document, and read the notes, you find that the company classified $223 million dollars as "principal payments on finance leases".
These payments are to do with the purchase of equipment from Panasonic and are capex by another name, but their classification as lease payments removes them from the company's definition of free cash flow.
China et cetera
Tesla bulls are excited by many promises:
- manufacturing to commence at Tesla's Chinese plant in Shanghai
- a new factory to be built in Europe
- the release of a new affordable SUV, the model Y
- the release of autonomous driving capabilities, called FSD ("full self driving"), increasing the value all existing Teslas and creating a fleet of robotaxis
- the release of an electric Semi truck
- the release of the Cybertruck
- I've probably left something out!
From my point of view, it remains one of the most compelling shorts I've ever seen.
But timing is important in this game.
Maybe after a short squeeze, and as the company runs out of money again, will be the perfect timing to get back on this horse.
For now, it remains the purest entertainment.
That's it from me in this report for 2019.
I'll see you again in 2020. Have a wonderful Christmas and holiday season, and stay safe in the markets!
And thanks for all your wonderful comments, feedback and encouragement. We couldn't do it without you.
Best wishes
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
£TSLA
If you are a trader I can imagine TLSA is a fun stock to trade long and short in swings
If you are an investor, watch what the slower but large majors are doing. Toyota is huge and they say:
"we will be launching more than 10 battery electric vehicle models by the early 2020s. Our first target market will be China, after which we expect to roll them out to customers in Japan, India, the United States and Europe"
https://www.toyota-europe.com/world-of-toyota/feel/environment/better-air/electric-vehicle
It seems I angered the fan boys (&girls)
Play the ball not the man
They’re easily triggered.
I’m generally quite agnostic when it comes to Tesla. It’s just too difficult to put into a buy/sell category. I wonder if the cult-like defensive attitude of some of its fanboys and girls- even here- is a sign?
What is surprising reading the comments here is how many "investors" consider TSLA is "just an electric car company." If you're really into the stock for the long ride then much of TSLA's valuation should be based on it's potential as an energy stock (Tesla Megapack, Solar City, battery innovation, electric car charging etc) . I wonder how many of these same investors would (back in 1998) have assumed that AMZN was just a book seller...
yes nothing but positive news recently with Tesla, I wonder what it would take for some with a strong bias to change their minds or give them , even a slight bit of credit?
Thanks Graham for another excellent and very insightful report. I'm constantly impressed by how much analysis you and Paul are able to fit into a small space of time.
Regarding Tesla, one thing that's worth bearing in mind is their relentless ambition. They set themselves high targets, which can cause huge self-imposed headaches. However in working through these problems, they learn and improve, then repeat. Just look at their Model 3 production line issue with the 'tent'. They now have huge improvements in efficiencies & margins which they've been able to roll out in their China factory & will no doubt do so in Germany. There may be questions regarding their finances, but they are constantly innovating and carving out a huge competitive advantage when it comes to software, data & battery technology. Don't underestimate them!
who would buy a Tesla when the fragility of the business does not guarantee hassle free guarantees???
Hey ho; thanks to you both for the steady flow of stimulation across so many situations through 2019 and long May it continue
Happy times with your families through Christmas and into 2020
Many thanks and very best wishes to Paul, Graham, and all the contributors here. I owe you all a lot. Please enjoy the following:
https://www.youtube.com/watch?v=vsvOrtcrA5c
Thank you both for all the analysis this year its been truly useful, encouraging and educational!
On the note about Tesla what seems to be ignored is the network of super charges which makes Tesla one of the few global "utility" companies too. I do not have a long or a short just an interested in the company and what its building.
Elon Musk makes P.T. Barnum look like a clueless noob at the game of relieving people of their money.
Graham and Paul were stood together at the bar during Mello, one in a suit, one in a loud shirt, and I commented to my sister "No-one could ever accuse the boys of coming out of a cookie-cutter mould". What is consistent, in my opinion, is the level of value you both deliver, day after day.
I suspect the twin skills of analyzing accounts and writing entertaining prose are rarely found together in any individual, and we in the Stocko community are very lucky to have the pair of you. Long may you continue.
Best wishes for Xmas and the New Year.
Jon
Yes indeed the Lennon and McCartney of investments lol !!!
I can understand why Companies issue options, though it should not be a free lunch at the shareholders expense. The problem is that the Board of Directors if they are not paying any hard cash for their shares, it is too easy an ATM to use.
A company I was involved in issued options but also effectively covered them through share purchases an Employee Trust. The options were exercisable at a price by the employee, and then the company gives guidance to the trustees to issue the shares acquired, when the exercise occurs by the employee, rather than issuing new ones. That way there is more of a virtuous circle for other shareholders. The employee get a tax free sum up to £30K (too low in my view) and the Company pays NI on the award that is exercised over that amount.
It is not the cheapest way to structure a share option scheme, but it is fairer all around.
Thanks to Graham and Paul for their 2019 contributions. This is still one of the most interesting investing ideas platforms around.
Wishing Paul, Graham & all the team at Stocko along with all the contributors who post invaluable advice a merry Xmas & New Year.
Personally I would never short quality. Tesla has quality and Musk is a master of defeating the odds. He has done it time and time again. I'm not long Tesla but I dont see much of a case for being short other than it is trading at high multiples.
I haven't seen anything from other car makers to make me think otherwise either. Audi etc are too expensive and have a tarnished brand after the diesel scandal of fraudulently miss selling so called 'clean fuel' which turned out to be far worse.
Along with Apple, Tesla is now one of those sacred American brands which you are almost not American if you buy something else. I wouldn't underestimate that selling power.
Absolute nonsense. You’re not American if you buy something else? Where do you get that idea from?
It is a notion and one which is backed by their exponential sales.
Go to America and find someone who doesn't own an iPhone.
Go to America and ask someone what phone they will buy next. Tesla are gathering the same brand.
Ask an American what electric car they will buy. They will reply Tesla without hesitation.
But thank you for your brash ignorance.
Well, my ‘brash ignorance’ comes from living in America, in a city that is their biggest market, where there are Teslas on pretty much every corner nearby where I live.
So I don’t need to go there and ask them anything, I’m already living there.
I would be very careful in applying sweeping generalizations to support a wobbly investment thesis.
History has repeatedly shown that the first to market rarely end up being the market leader in the long term. Tesla may have been the pioneers in the field, but the others are catching up, and have already nailed the areas where Tesla trails, for example: quality, reliability and customer service.
There are a number of problems with battery-powered cars which are unlikely to be resolved in the near future. The batteries are heavy, have limited range and take a long time to recharge. The best model 3 Teslas have a quoted range of between 250 and 322 miles, wich is OK for day to day driving but not so good for a long journey when it takes 40 minutes to recharge to 80% capacity (assuming you can find a free Tesla supercharger). Several times a year I do a journey which is around 1000 miles door to door - waiting for recharges would add substantially to the journey time.
Then there is the problem that if everyone drove a battery-powered car the nation's electrical infrastructure would be unable to cope.
Finally, there is purchase cost - even a low-end petrol car is a very expensive purchase for the majority of people, and most people will always go for the cheapest transport option.
A number of major car manufacturers are beginning to acknowledge that electric cars are unlikely to be the future of motoring in the medium term, and both Toyota and Audi are currently developing cars powered by hydrogen fuel cells.
I don't think there are many people who drive more than 300 miles in one day and if they do I'm sure they wouldn't mind stopping for 45 minutes.
With that said, there are now Tesla fast chargers which charge 80% in 10 minutes, they will be rolling out in the next couple of years.
This is where Tesla is way ahead of other car makers.
Yes my family are American and live near DC, have a Tesla and only buy iPhones, my comment was one of fact about branding and has nothing to do with your own personal taste or where you live.
You may not agree on the power of their brand but even as Warren Buffet would say "they have a piece of consumers minds".
I wanted to purely talk about branding but I will make some further points after being attacked for my comment.
I was long Tesla at 190 because it was quite clear from their balance sheet that they would not run out of liquidity. Contrary to what several hedge funds were saying, something which Elon himself made fun of post Q3.
With his new factory in Germany, he has access to some of the best talent in car production and with Chinese incentives to go with his gigafactory 3 in Shanghai, Tesla will start to really compete on the big stage and they move at a much faster pace than the likes of BMW. BMW are so far behind that they dont even have an electric range announced. Only VW of the large car manufacturers do and it is underwhelming and more expensive than the Tesla Model 3.
Tesla chargers and their other units (home) are where they can really add value because they plan to integrate charging cars and homes all together and they have market leading home batteries and charging stations. Power wall 2 is by far the best and cheapest battery storage per kw for homes, with powerwall 3 likely to be released in 2020.
As I said before, 430 is a high price now so I wouldn't be long now but I dont see any reason to short Tesla with all of the points mentioned above and the current reasonable cashflow and working capital ratios. Not to mention the ease of raising funds, if they need to, but they won't again.
I would be more concerned that they weren't leading the market and were no longer innovating or their brand became tarnished - which was my original short version of my overall point.
“BMW are so far behind that they dont even have an electric range announced”
Oh dear. They’ve been making the i3 for years. And just about every model has a PHEV version. They just need to get their fleet co2 below the level that gets them fined by the EU and they have a strategy for that.
“Only VW of the large car manufacturers do and it is underwhelming and more expensive than the Tesla Model 3”
Someone better let Renault/Nissan, Jaguar, Mercedes, and Ford know they haven’t got electric ranges planned. 3 of those are already producing electric cars, and Ford release the Mach-E next autumn.
Personally I’m about to put a pre order in for a Mach-E looks much better engineered and classier than the Model 3.
Graham and Paul, a very happy christmas to you both. Many thanks for your extremely interesting insights and the transparency you give to us mere mortals. I shall raise a glass to you both over the period and I wish you a very prosperous 2020!!
Thanks camtab, have a good one!
Tesla
This must be one of the most divisive stocks around. It is love or hate. Arguably this is the great disruptor of the motor industry . I think Musk is the worst kind of charlatan and it will all come down like a deck of cards........ Once the motor manufacturers finally gear up for full scale electric car production prices will fall dramatically and Tesla will become the De Lorean of the 21st century . OK Scottish Mortgage Love Tesla.......
interested as to why you think he is a charlatan? Do you think his cars and space rockets aren’t real?
The stock is almost certainly overvalued right now but I still hope that the shorts get burnt because if they don’t then the rest of us will. We need to electrify transport (and heat) as fast as possible and Tesla is leading the charge. The science really is that conclusive and instead intelligent people such as some on these threads talk of nothing but how to make cash (which I have no problem with) at the expense of the environment.
Not so much that his cars and space rockets aren't real, I suspect, more his financial statements.
He’s the definition of a charlatan primarily because most of what comes out of his mouth is at best inaccurate and worst a bare faced lie. The only positive I can see from Tesla is that it gave the rest of the car industry a kick into developing their own technologies. There were electric cars before Tesla and there is nothing Tesla can do that no other manufacturer can not. The difference is that the traditional manufacturers realise it is incredibly difficult to make money selling electric cars and they are not prepared to saddle their companies with unmanageable amounts of debt. Yes electric cars are the future but to say they must replace ICE transport ASAP to help save the planet is a fallacy of the highest order. There is nothing environmentally friendly about mining and extracting billions of tonnes of copper, cobalt, aluminium, rare earths, gold etc etc
'there is nothing Tesla can do that no other manufacturer can not' LOL! not sure this guy actually has any understanding of just how difficult engineering is. I'm a Tesla owner. It's unreal how good it is.
The “only positive” that you point out is exactly what Musk said he wanted to achieve. So you contradicted the assertion you made in your first sentence, with your second sentence.
Other motor manufacturers perhaps can’t make electric vehicles at profit but that doesn’t mean Tesla (or a start up) can’t, it more likely means that pivoting the core of your manufacturing capability is unbelievably costly and will probably kill off a few of them, but then they are struggling to make profit on their ICE cars anyway. Or they can keep making ICE’s, but for how much longer?
As to you final point, how do you think we get the materials to manufacture ICE cars, perhaps a little mining?
I wonder if your negative sentiments are genuine, there are undoubtedly faults and concerns to raise with Tesla but you haven’t touched on any of them, instead its a repetition of disproven fallacies.
Personal thanks from me Graham. Especially for pointing me towards both Creightons (LON:CRL) and Cenkos Securities (LON:CNKS) both of which I'm up over 30% on this year. My portfolio is up 21% this year - I am sure others on here have far better returns than that and it's against the backdrop of a strong market this year, but, as a very part-time investor with a busy job, I'm thrilled with this result. Happy Christmas!
Well done Paraic. I only share ideas, it's up to you to research them and pull the trigger - and I'm glad you've had a good investing year!
Best wishes
Graham
Thanks Graham and Paul for all the wonderfully detailed reports...
...and a happy Christmas to everyone!!
I too just wanted to add my sincere thanks to Paul and Graham as well as Jack, Ben, Roland, Ed and the entire Stocko team not only for the excellent, insightful and educational commentary but for the immense effort and enthusiasm that has delivered the exceptional new platform this year. The fact that it was awesome at birth and just keeps on getting better with new features and updates added all the while is an incredible tribute to the skill and dedication of the team. Lastly thanks for all the considered and useful additions from the legions of below the line commentators too. Best wishes for a Happy Christmas and a successful New Year to all.
Thoughts on Tesla would be interesting. It must be really difficult to analyse its situation with very little hard evidence available until early 2020. Will it grow into its share rating? Volume sales don't look that encouraging in the USA in Q4 and apart from the Netherlands where there are large subsidies until the year end, other significant export markets are subdued. Surely it has to hit sales of 360,000 cars in 2019 and start selling in large volumes from its Chinese plant to keep its growth story going. And will the market believe its financial figures when they are released in January?
PS Thanks Graham and Paul for your really interesting commentaries.
Happy Christmas Graham, and thanks to you and Paul for your work this year.
Can I request your opinion on £WRKS? I don't think this has had any coverage as yet. I think the valuation is interesting, their balance sheet cleared of debt from the IPO but with so many stores they could end up failing.
Been in a few of their stores and not really sure what they specialise in, unlike others such as Shoe Zone (LON:SHOE)/Card Factory (LON:CARD) which have a specific focus. Don't know whether this opens up room for better performance, or will be their downfall in future.
Hey Snoo, you're welcome.
I'm afraid that I've never studied Works co uk (LON:WRKS).
Opening up its preliminaries from earlier this year, I note that margins are very low, LfLs are negative, and it now has 500 stores.
My initial impression is that it's another undifferentiated retailer with a grim future paying for its £114 million in IFRS 16 lease liabilities. But I've only just looked at it for the first time - maybe something we can cover in the new year? G
Sure thing Graham. I agree, the leases could fatal in the end - a downturn in trading would be fairly grim. Next trading update is 16 January, should be interesting reading.
Just a massive thank you to you both Graham and Paul for all of your hard work on our behalf throughout 2019. You are 'must reads' most days. As someone else has said Graham 'don't knock yourself out today, just pack it in and enjoy the break'. Have a good one both.
Charles
Thanks Charles.
I enjoy writing about Tesla and it's sort of a funny story, so I'm enjoying putting together a few thoughts on it before clocking out for the day.
Best wishes
Graham
Another vote for £TSLA here, surely there's an almighty short on at some point?! Merry Christmas both and thanks for all your hard work.
Merry Christmas Graham and Paul. Thank you for the SCVR. Read it everyday. It has been an interesting year!
I would second the request for your views on £TSLA I am not long or short but think it a fascinating company whose founder has single handily transformed the car industry.
Thanks to Graham and Paul for your sterling work this year. Find the challenge to my thinking ever valuable. It has very much contributed to the excellent investment year which I have enjoyed. Hope you have a very enjoyable Christmas and best wished for the New Year!
As its quiet a TSLA update would be good
Graham, Merry Xmas to you and yours. Very much appreciate the work you and Paul put in, day in day out. All the best for 2020.
Musings on Nmc Health (LON:NMC) would be appreciated (if you have any). No position, just an interested bystander.
Cheers Graham
A
Happy Christmas Graham,
I fully appreciate that this isn't your thing but Rockrose Energy would be an interesting company to hear your views on.
The share price hovers in the £17-19 range but they have £19-20/share worth of cash!
If this company fills you with horror, any of your "off-piste" write ups are always a great read.
James
James,
Thanks but I don't think I'll be able to add any value with respect to RockRose Energy (LON:RRE), since I've not studied it before. It does sound interesting. G
Hi James
One of the authors on Graeme’s own site covers this one...sorry for the cross plug.
Thanks
Tom
Thanks Tom,
Happy Christmas all
yes indeed and Gold membership of Cube Investments is worth every penny!
Also @Brilliantleader coverage of Rockrose Energy (LON:RRE) is always good.
Mark Brumby's free daily email (which I recommend) from Langton Capital says
The Institute of Directors has reported that business confidence in the British economy has leaped to its highest level for more than three years following the Conservatives’ general election victory.
• The IoD’s key confidence measure swung to positive 21% in December, up from minus 18% in November. The IoD cautions ‘our members’ confidence has proven sensitive to Brexit developments over the past few years, and this is likely to continue during negotiations in the year ahead.’
With Sterling back below $1.30, maybe we'll see further takeover activity in small caps in the next few months.
Graham, what are you expecting from the market in the New Year?
Regards
Martyn
Agree with Brookeda. You've both put a shift in this year. I'd like to add personally, your writing has been concise, helpful and a daily must read. Merry Xmas to both of you.
Would definitely like to hear your views on £TSLA Graham. Thank you and have a great Christmas!
Thanks mammyoko - Merry Christmas to you, too! I am compiling some thoughts on Tesla now. G
Thanks graham for your insights through the year. why don’t you knock it on the head today and take a well earned rest as it seems everyone else is in bed or the bar