Small Cap Value Report (Tue 26 Jan 2021) - Takeovers, SAGA, ANP, ZOO, EYE, ERGO, MANO

Good morning, it's Paul here with the SCVR for Tuesday.
Jack's busy today, but found the time to contribute an update on ERGO below, thanks to him for that.
.
Lord Lee/Sharesoc campaign re takeovers
Mello Monday, the popular online investor evening (fortnightly) was very interesting last night.
I thought Lord Lee gave an insightful talk about the shortcomings of the current rules of the takeover panel. He gave some examples where companies had failed to notify investors over an extended period, when takeover talks were actually underway.
I'm preparing a letter of my own to the Takeover Panel, to back up John's stance on this. My thoughts are along these lines;
1. Takeover bids are often revealed by the press. Companies are then forced to issue an RNS called e.g. "Response to press speculation", confirming that they are in takeover talks, or have had some approach. Surely this cannot be right? We need a proper system, with rules, for when shareholders should be told about possible bid talks. I appreciate that a preliminary, or speculative takeover approach, should not necessarily be announced to the market, but surely the owners (shareholders) of any company have a fundamental right to be told, if a serious bidder expresses interest & wants to engage with management about a possible bid?
2. False market - if the company is in bid talks (usually at a c.30-50% premium price), then that means the prevailing market price may be false, i.e. people selling their shares are not aware that a takeover bid might be in the pipeline, so they are selling at a price which is not reflecting undisclosed, price sensitive news. Buyers of the shares could be insider dealing, or tipped off about a potential bid, hence might be effectively stealing money from the sellers. As we all know, insider dealing is rarely caught or prosecuted, but is probably widespread, judging from share price movements that sometimes occur just before a takeover bid. Hence why price sensitive information must be promptly disclosed, which should include any credible takeover approaches.
3. It's a fine balance between what to disclose, and what not to disclose, so I feel tighter rules need to be put in place, rather than it seemingly being left to the discretion of companies, or the vagaries of press rumours, to decide what gets announced and when.
4. Can we always rely on company Directors to achieve the best price when they sell a company? In situations where Directors have immaterial personal shareholdings, maybe their own career interests could be their main priority, as opposed to achieving maximum shareholder value? It's not uncommon for Directors to recommend a bid, only for a higher competing bid to subsequently appear. Suggesting that Directors did not maximise value, or conduct a thorough sale process by exploring all options.
5. Sounding out of institutional investors - I recognise that companies might want to sound out their major shareholders, by taking them inside, to determine whether a takeover approach would be acceptable to them. This then locks in the institutions, who as insiders, are not then able to sell. However, they do have a major advantage, because being unable to sell, they are guaranteed to benefit from any takeover bid that does subsequently arise. Whereas private shareholders are left in the dark, hence might sell in the market, unaware of bid talks being underway, causing a financial loss. That is not fair. Clearly the market as a whole needs to be informed at a key trigger point where a bid looks credible and likely.
Possible tests to decide when a bid approach has to be announced;
1) Bidder is of a size, credibility, and financial strength to prove that it has funding available to progress a bid.
2) Major shareholders in the target company have been made insiders, and confirmed they would be supportive of the bid approach - at this point the whole market should be immediately informed.
3) If the market price moves up for no apparent reason, suggesting that information might have leaked.
That's all I can think of for now.
As an aside, I was disappointed with Stephen Clapham's (the next speaker) unjustified attack on Lord Lee's presentation - particularly as Stephen admitted he hadn't even heard the presentation! How can you say someone is talking rubbish, when you didn't hear what they said? Plus you won't win any friends by attacking a national treasure lol! So that was a mistake, but it was good to hear Stephen apologise at the end. Still we all get carried away sometimes, but it does generally pay to make 100% sure of your facts, before expressing a strident opinion!
Still, a little controversy has maybe heightened awareness of this issue.
.
Timing - quite a lot to cover today, so I'll leave it open ended for now. Update at 17:48 - that's all for today - today's report is now finished. I'll cover a few more bits from today in tomorrow's report.
Agenda -
Saga (LON:SAGA) (I hold) - Trading update
Anpario (LON:ANP) - Trading update - well ahead of expectations
Zoo Digital (LON:ZOO) - Trading update - ahead of expectations
Eagle Eye Solutions (LON:EYE) - H1 trading update - in line with expectations
Ergomed (LON:ERGO) - Trading update (this section contributed by Jack)
Manolete Partners (LON:MANO) - intra-day profit warning, down by a third. Looks bad to me.
.
Saga (LON:SAGA)
(I hold)
280p (up 1% at 08:27) - mkt cap £393m
Saga plc ("Saga" or "the Group"), the UK's specialist in products and services for people over 50, provides the following update on trading covering the period from 1 August 2020 to 25 January 2021.
This is a very detailed update, which reads positively to me.
SAGA’s share price is surprisingly volatile, which suggests to me that the market doesn’t really know how to value it at the moment, so it’s buffeted around by tides of sentiment going each way on a daily basis, re covid/vaccines mainly. To me that’s just background noise, but I tend to think longer term than many other market participants.
The financial year for SAGA ends 31 Jan 2021.
I’ll summarise the main points -
Key point - still profitable (underlying PBT) in FY 01/2021. It made an u/l PBT of £15.9m at the interims, so this implies H2 is (at worst) a loss of £(15.9)m, and hopefully better than that. Given that the travel division, including 2 new cruise ships, has been idle for most of the year, that’s impressive in my view. The attraction of this share, is that its profitable & cash generative insurance business is covering the losses & cash consumption of the travel division. Hence this share is a much lower risk way to back a recovery of the travel/holidays sector, than for example cash-haemorrhaging airlines or pure play cruise lines.
Liquidity - looks fine. It has £51m cash available as at 31 Dec 2020, plus an undrawn £100m RCF. Many investors seem to wrongly perceive that SAGA is financially distressed. It isn’t. The £150m equity fundraising a few months ago sorted out the issues. Now it has ample headroom, and the main debt is;
Bond of £250m repayable May 2024 (so not a worry), cheap: 3.375% fixed interest cost, and no covenants.
Ship loans - used to purchase 2 new cruise ships, currently anchored in Tilbury Docks, but guidance from the company is that they should generate £80m p.a. EBITDA once normal travel conditions return. From today’s update it sounds like the ship loans are £514m (calculated as £785m total net debt, less £271m net debt excluding the ship loans).
I really don’t see this ship debt as a problem. It’s just asset funding, and the company owns the assets, offsetting the debt. The lender is co-operative, having already waived covenants for Saga & other cruise line borrowers, given that the cruise ships are mothballed. The last thing a lender wants, is to repossess currently useless great lumps of steel! So it makes sense that the lender is being flexible.
The company is negotiating for further deferrals of ship loan repayments, and covenant easing. The lender & Saga’s interests are aligned, it has been co-operative & flexible to date, so I cannot see any reason as to why that would become more difficult now that a resumption of cruising is probably only months away. Hence unless something untoward were to happen, I’m not worried about the ship loans.
Covenants on the ship loans are;
- Trading EBITDA: Debt service must be above 1.2x.. Actual was 3.8x at 31 July 2020.
- Interest cover - trading EBITDA: net cash interest expenses must be above 2.0x. Actual was 5.4x at 31 July 2020.
Covenant waivers were previously secured, to 31 March 2021. It seems to me that the most likely outcome is an extended waiver on the ship loan covenants, until they can resume trading. But of course that cannot be guaranteed, so it is a potential risk, albeit not a big risk in my view.
Note that no dividends can be paid whilst the ship loans are in arrears, but none were planned anyway.
For more information, see page 207 of the refinancing prospectus from last year.
This is what SAGA says today about debt/covenants -
Whilst the Group has significant liquidity and headroom to the current covenants in short term bank facilities, given the backdrop of continued disruption to the Travel business, we are taking actions to further enhance financial flexibility.
We have commenced constructive discussions with lenders, who remain supportive. We are reviewing the covenants attached to our term loan and RCF, to increase flexibility ahead of the resumption of Travel.
As part of a package of measures available for the Cruise industry, separate discussions are underway in relation to a further debt deferral and covenant waiver for the two ship facilities. This could allow for deferral of up to £45m of principal payments due to be made from 1 April 2021 to 31 March 2022 and would be in addition to £32m already deferred, due in the period from 1 April 2020 to 31 March 2021. These are early stage discussions and we will provide an update with our full year results.
In a zero interest rate environment, lenders are generally being highly co-operative across the board, because that’s in their own interests. So I think we should be careful not to miss opportunities by being overly paranoid about debt. I missed out on a multibagger with Countrywide because the debt scared me off, for example. Given that hardly any listed companies are seeing lending facilities withdrawn, then maybe it’s time to be a little more gung-ho on this issue? The main risk is if lenders force a discounted placing, as happened at Revolution Bars (LON:RBG) (I hold) for example.
Insurance division - lots of detail given, which reads positively to me overall. described as “resilient in a highly competitive market”. It’s benefiting from reduced claims, as e.g. people use their cars less.
Travel division - planned to resume operations in May 2021. Requirement for customers to prove they’ve been fully vaccinated. This is where SAGA has an obvious advantage, since it specifically caters for the over-50s. They’ve done a lot of preparatory work on this, see the RNS for more details. It sounds well thought out, and includes frequent testing of crew, as well as numerous other measures.
We don’t yet know how/when the travel sector will resume, everyone has their own personal views on that.
Cash burn reduced to lower end of previously guided £6-8m per month for the travel division. Remember that the insurance division covers this cost, so unlike practically all other travel companies, SAGA’s financial position is not worsening. That’s one of the reasons I like this share so much. Strong potential upside, with far less downside risk than most investors seem to preconceive.
Travel bookings are good, reinforcing my view that habitual cruisers are itching to get going again. Remember that in the interims presentation, management repeatedly said, “Demand will not be a problem” when talking about their travel division. It all hinges on Govt restrictions being eased, then the coiled spring is released, in my opinion (and clearly Saga think the same thing too) -
Customer retention across both businesses remains high; the average proportion of Cruise guests who have re-booked rather than take a refund stands at an average of 69% through the travel suspension period, but rose to 86% more recently, showing the pent up demand for Cruise amongst our guests who will benefit from the first round of the vaccine roll out.
Customer deposits - remember that SAGA now ring-fences customer monies in a separate account. Unlike many other travel companies which use customer pre-payments to fund their operations. I imagine customers would find this very reassuring, in giving confidence to book early at SAGA. I think that’s a good example of where old-fashioned image & attitudes can be a positive thing.
Cruise bookings are 68% of capacity for 2021/22 (78% LY), and 28% for 2022/23 (6% LY) - given that the ships are currently mothballed, and nobody knows for sure when they can resume operations, those numbers strike me as remarkable. Clearly the customers want to get cruising again, which augurs well for the future, however long it takes, which doesn’t really matter because the insurance division covers the cash burn whilst we wait. An ideal business model really, in these uncertain times.
My opinion - that all sounds fine to me. My reason for investing is completely intact, namely;
- Insurance division profit/cashflow is funding the travel division losses
- Liquidity/debt looks fine, assuming covenants on ship loans waived/relaxed again (no reason to doubt this)
- Strong pent-up demand for cruise ships in particular, evidence by good forward bookings
- Should become highly profitable once travel resumes
- Medium-term benefits from return of Sir Roger de Haan (founder's son & long-standing CEO), and restoring the business, culture & image back to the original, before private equity & poor management damaged the business
- Longer-term - think about what could be done with a brand name this well-known, and catering for the segment of society that has most of the money & disposable income! Massive potential & brand value, I reckon. If they get it right, this could be a multibagger in my view.
My investing timescale on this one is 2-3 years. The opportunity is for a shorter term re-rating, as travel resumes. Then a longer-term re-rating from sorting out the fundamentals of the business. Time will tell, as always, nothing is guaranteed since the future is so inherently uncertain. Overall I see good risk:reward here, if you can cope with the share price volatility!
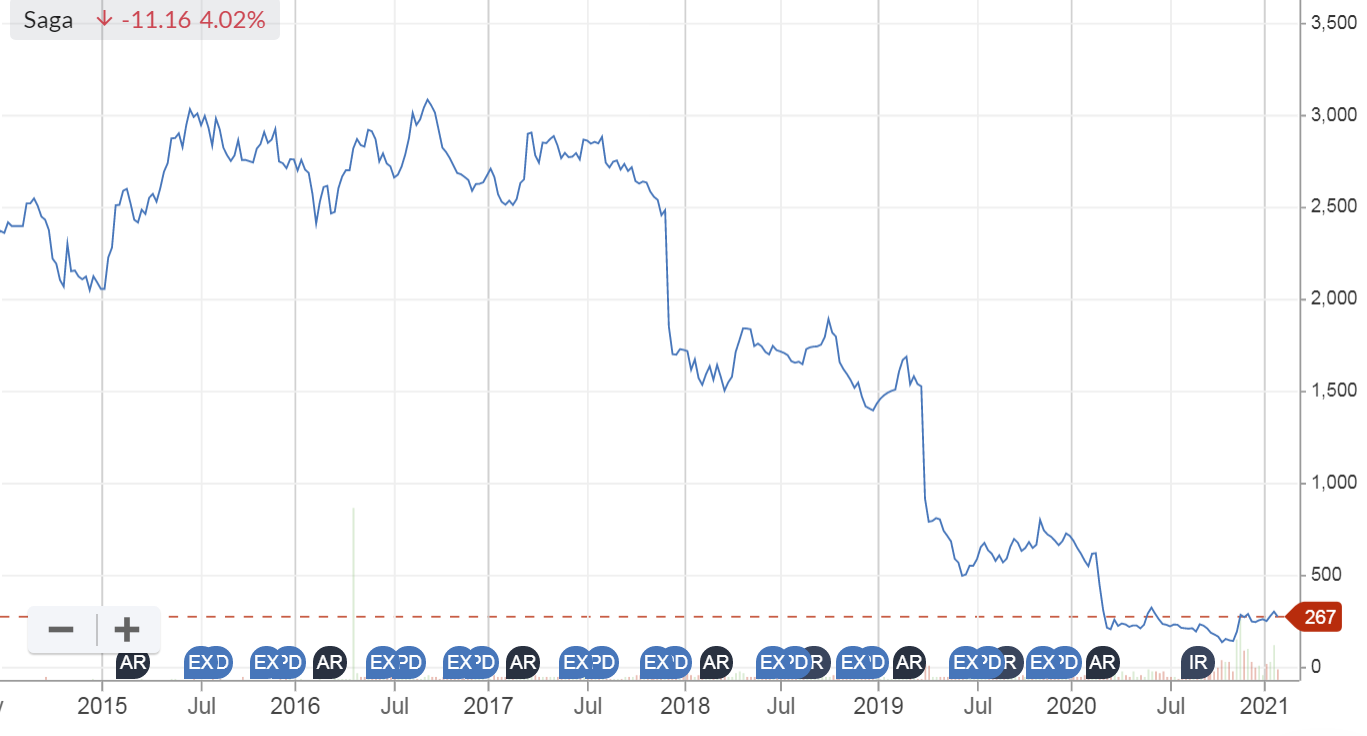
You can see from the long-term chart, that Saga was badly mismanaged under old management, destroying shareholder value. Then covid clobbered it again in the spring of 2020. Note also that the share count roughly doubled in the recent fundraising, so we need to adjust for that when looking at the upside. i.e. a recovery to 1500p would really be equivalent to 3000p on the chart. The chart has been adjusted for a 15:1 share consolidation, in case the numbers don't tie in with your recollection of the past.
.
.
Anpario (LON:ANP)
607p (unchanged at 10:21) - mkt cap £141m
This is one of many shares that is on my ever-growing, “I like the company, but it’s too expensive” list. Quite often though, companies on that list tend to out-perform market expectations, revealing the reason why they were expensive. Plus of course we’re in a roaring bull market for growth companies, where ratings are going through the roof in some cases, as investors prioritise momentum ahead of valuation. Risky stuff, as the music inevitably stops at some point! Nobody knows when, but the party’s in full swing right now, especially across the pond. Anyway, back to Anpario.
Anpario, the independent manufacturer of natural sustainable animal feed additives for health, nutrition and biosecurity, provides the following trading update for the year ended 31 December 2020.
It’s good to read a nice factual, numbers-based update here -
The Group has delivered a very strong operating performance despite a very difficult year around the world due to the pandemic. Full year sales are now expected to be not less than £30m and profit to be well ahead of expectations. This performance is reflected in the Group's strong cash generation with year-end cash balances of £15.8m (31 Dec 2019 £13.8m) after a £1m buyback programme and in addition to increased dividend distributions.
Diary date - FY 12/2020 results are due out on 17 March 2021.
Corporate video has been published, which is here:
.
Share price - hasn’t moved today, but there are only 17k shares (c.£100k) printed so far. The published spread is ridiculously wide, thus deterring both buyers & sellers, although the actual spread is often well inside the published prices, because of the antiquated pricing system we have in the UK for small caps. Putting a dummy trade into an online dealing platform, then cancelling it, is a good way to find out the real prices.
It’s still surprising for a price to not move, given that the company has just published a “profit well ahead of expectations” statement. Maybe it’s been anticipated by the recent price rise before today’s update?
My opinion - I can’t find any broker updates today, so haven’t really got anything accurate to work on. Stockopedia shows broker consensus of 18.0p EPS, so let’s guess at maybe close to 20p actual. That puts the PER about 30 - it’s difficult to see why the price is so high, when historic growth has been quite pedestrian. I’d need to see much more growth to get me interested at this valuation. The company's market share must be tiny, from the global animal feeds market. That could be an opportunity if sales take off (massive market size), but at the moment Anpario seems a niche also-ran. I'll keep an eye on it though, for signs of growth accelerating. In the meantime, it makes a very good profit margin, and has plenty of cash.
.

.
Zoo Digital (LON:ZOO)
98p (up 7% at 12:23 - mkt cap £73m
ZOO Digital Group plc, a world-leading provider of cloud-based localisation and media services to the global entertainment industry, today provides an update on current trading and outlook for the financial year ending March 2021.
This share got a boost from a weekend Sunday newspaper tip, and is up again today, so might be a nice point to take some profits perhaps? Buyers on newspaper tips are often beginners, who might have an attention span of about a fortnight before they sell up and move on to the next thing! That’s based on what I was like in the 1990s!
The company is having a good H2 (Oct 2020 - Mar 2021) -
… revenues for the full year are now expected to be at least $38 million (FY20: $29.8 million), an acceleration of growth in the second half over the first half of 35%. Based on this strong performance, the result for the year is anticipated to be ahead of market expectations.
I like the strong Y-on-Y growth, up 28%
Other points -
- More work from back catalogues, offsetting new productions “on hold” due to covid. This factor is not expected to continue as things normalise. It would have been useful to see a table of numbers, to put this into perspective.
- Positive industry trends - some new productions resumed, more content for streaming, rising consumer spending on entertainment content.
- Using the cloud has been an advantage for ZOO
- New customers added
- Claims technological leadership with its IT platform
Research update - there’s a new note out from Progressive, forecasting only $1.2m adj PBT for FY 03/2021 and $1.7m next year. That’s nowhere near enough to justify a £73m market cap, in my opinion.
My opinion - the current year PER is about 100x, falling to about 70x next year’s forecast EPS (from a note issued today). That looks a bonkers valuation, pricing in significant out-performance, for several years.
Historic performance has been lacklustre too, so if I held this share, I’d be cheerfully banking my recent profits at this price.
The only reason to buy or hold, is if you think it’s going to smash existing profit forecasts by a very large margin. Otherwise, the valuation doesn’t make sense. Dubbing & subtitling seems to be a very competitive, lowish margin sector, so not something that interests me at all.
.

.
Eagle Eye Solutions (LON:EYE)
421p (down 7% at 13:33) - mkt cap £108m
Eagle Eye, a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing through coupons, loyalty, apps, subscriptions and gift services, is pleased to provide an update on the Group's trading for the 6 months ended 31 December 2020 ("the Period").
The heading says -
Strong profit growth and new domestic and international customer wins
H1 revenue growth is +8% Y-on-Y - not madly impressive, and down from +11% in Q1 which I reported here on 17 Nov 2020. It previously indicated growth was expected to accelerate in the rest of the year, which hasn’t happened in Q2.
Adjusted EBITDA of £2.1m in H1 (up 62%). All very well, but LY the company capitalised £2.8m of development spending, which means that EBITDA here over-states real world profits.
Net cash only £0.1m, although that’s improved from £(2.2)m a year earlier. Undrawn £5m borrowing facility.
Last reported balance sheet was weak, with negative NTAV, although it does benefit from favourable working capital flows - customers paying up-front, and has little tangible fixed assets, so doesn’t particularly need a strong balance sheet.
Bull points -
- Very high gross margin of 94%, hence big operational gearing
- High levels of recurring/repeating revenues
- Low customer churn
- Amazing client list of major retailers
- International scope, so big market potential
- This type of tech/growth business is highly rated in the current stock market conditions
Bear points -
- Barely profitable, once capitalised R&D is expensed
- Slow, complex implementations of new client wins
- Sluggish growth rate
- Weak balance sheet - is this limiting growth perhaps?
- Expensive
Outlook -
COVID-19 may continue to cause new contract discussions to be extended, and is expected to continue to impact the Group's F&B and Non-Grocery customer segment, causing the Board to remain cautious in its outlook for this segment.
However, the careful management of the business, successful new wins in the first half of the year and growth of the existing customer base, mean profit for the financial year ending 30 June 2021 remains in line with the Board's expectations.
Never has digital engagement with consumers been of more relevance to the global retail sector. The Group's new business pipeline continues to grow at record levels internationally, including multiple enterprise level opportunities, providing the Board with confidence in the ongoing success of the business.
My opinion - the market cap of £108m seems too high to me (I seem to say that about many companies at the moment). Why would I want to pay up-front for several years’ more growth?
Here’s the progression of revenue growth in sequential half years.
H1 2018/19: £8.0m
H2 2018/19: £8.9m
H1 2019/20: £10.1m
H2 2019/20: £10.3m
H1 2020/21: £10.8m
Admittedly covid will have impacted the last 2 half years, but even so, it’s not madly exciting growth is it? For a £108m market cap company that only just makes a small profit, it’s not enough for me to want to pay up anything like the current share price of 421p. Would I be keen to buy at half that price? Not particularly. Looks a good time to bank profits, in my view. Like a lot of things, the price has got ahead of reality, in my opinion.
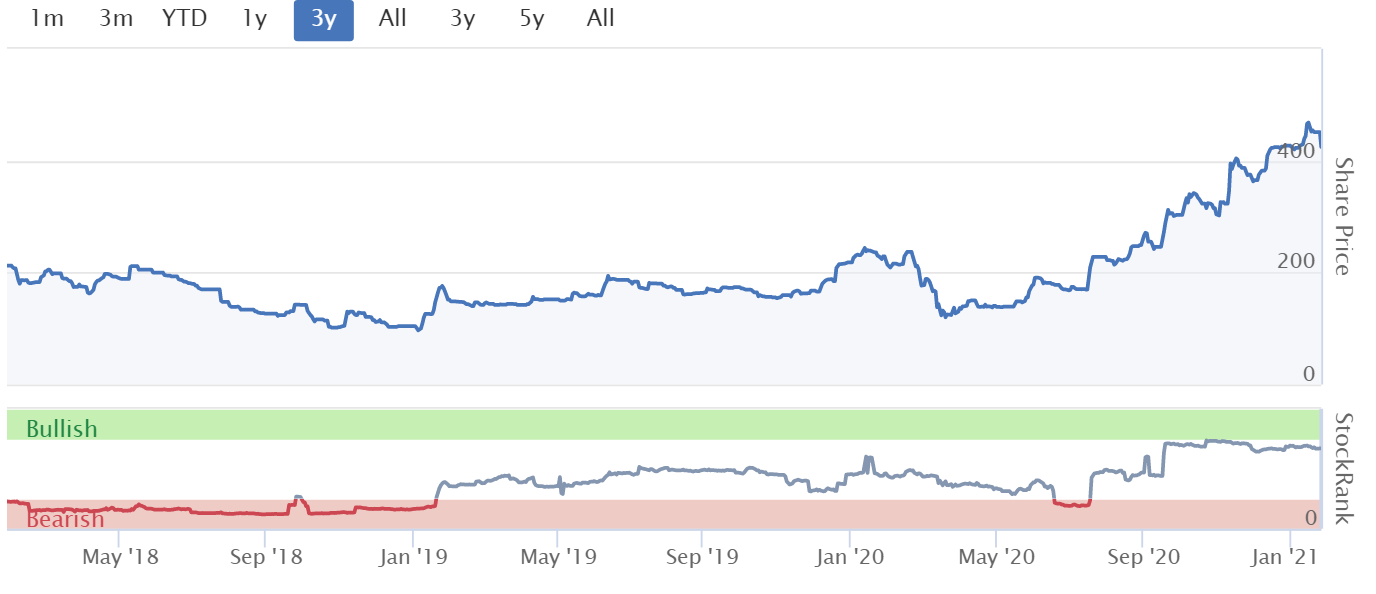
It's remarkable how many charts look similar to this one - sideways for a while, then 50-100% gain in the last c.4 months. They can't all be right. I think we're overdue a general correction, as too many things have had indiscriminate rises, despite only producing in line or slightly ahead of expectations trading updates.
.
.
Ergomed (LON:ERGO)
Share price: 1,100p (+12.24%)
Shares in issue: 48,719,526
Market cap: £536m
(Jack writing)
Ergomed (LON:ERGO) is focused on providing specialised services to the pharmaceutical industry. It’s in the Investment Club (you can find the original pitch here).
It provides outsourced expertise to the pharmaceutical industry - a high margin niche that has seen the group expand to a market cap of more than half a billion pounds, with operations in over 100 countries. Customers range from top 10 pharmaceutical and generics organizations to small and mid-sized drug development companies.
What’s more, it is still growing strongly and it looks like there are plenty of opportunities ahead.
The Ergomed group currently consists of three separate arms:
- Clinical Development Services - ERGO is a leader in the global clinical research (CRO) industry and has experience in planning, managing, monitoring, and reporting over 600 Phase I – IV trials. CRO revenues were broadly flat for 2020 at £31.3m (including £1.1m MedSource revenues) but were up 15.2% year-on-year in H2.
- Orphan Drug Development - This team is led by PSR Orphan Experts (PSR), Ergomed’s rare disease subsidiary. PSR is one of the few companies exclusively focused in orphan disease drug development.
- PrimeVigilance - This is a global pharmacovigilance (PV) service provider that supports companies in managing the global safety of their products from early clinical trial development through to full post-marketing activities. PV revenues increased by 56% overall to £55.1m and by 30% to £46.0m on a like for like basis (excluding the impact of Ashfield PV, which is now PrimeVigilance USA).
Full year Trading update
Growth continues apace at Ergomed:
- Adjusted EBITDA ahead of market expectations
- Total revenue growth 26.5% over 2019 (2020: £86.4 million vs 2019: £68.3 million)
- Strategic acquisitions in CRO and pharmacovigilance in the USA strengthen global specialist leadership
- Forward visibility underpinned by strong order book up 53%
On the whole, ERGO expects revenue for the year to be in line with expectations and for adjusted EBITDA to be ahead.
It ends the year with strong trading momentum and a promising forward-looking order book across both PV and CRO. The total combined order book at 31 December 2020 is expected to be up 53% to approximately £190m.
Conclusion
Given what occurred around the world in 2020, this is a remarkably resilient result. It’s testament to the group’s attractive CRO and PV-focused business model.
In fact, the acquisitions of Ashfield Pharmacovigilance in January 2020 and MS Clinical Services (MedSource) in December 2020, have strengthened its position in the USA - so ERGO has not just survived but thrived.
Admittedly, ERGO shares look expensive at 35.2x forecast earnings, but with growth this strong and a market this big, a high multiple can be justified. It’s not an obvious bargain at this price, but I don’t see why the group can’t continue its long track record of top line growth.

.
.
Manolete Partners (LON:MANO)
197p (down 35% at market close) - mkt cap £84m
(Paul writing this)
My commiserations to shareholders here, I know a few friends hold this one. It’s not a sector I would ever invest in (litigation financing), and it’s only been covered here once in July 2020, where I didn’t like the look of it at all.
Q3 Trading Update (profit warning)
A profit warning is bad enough, but one issued during market hours, at 14:47 today, is even worse. It gives an unfair advantage to market professionals, who can sell quickly, whereas your hapless private investor may not find out until later, when the damage is done.
Manolete Partners Plc (AIM: MANO), the leading listed insolvency litigation financing firm in the UK, announces record case completions and record completed case cash inflows but a continued low level of new case investments caused by the ongoing extraordinary UK Government economic support measures...
The company previously indicated on 10 Nov 2020 that new cases had begun to slow sharply. This has continued in Q3 and the start of Q4 (financial year end is 31 March 2021).
Negative impact on new cases expected to continue.
Completed cases look good, 108 to date, compared with 54 last year.
Gross settlement value of £23.9m, comfortably exceeding board expectations.
Lots more figures are given, but I don’t know enough about the company to draw any conclusions. Cutting to the chase, it says -
As a consequence of the above factors, the Board expects realised profits to be above, but unrealised profits to be significantly below, market expectations and therefore for the Company to be overall marginally EBIT profitable in H2.
Which sounds very poor.
Management comments suggest these problems are temporary.
My opinion - I wouldn’t want to waste any more time on this. It says insolvencies are artificially low. That’s true, but both Begbies Traynor (LON:BEG) (I hold) and Frp Advisory (LON:FRP) (I hold) seem to be managing fine. I know Manolete’s business is different, but why is it suffering when BEG & FRP are doing OK?
MANO made a £6.6m H1 EBIT profit. It’s saying H2 will be only just above breakeven. That seems to show a terrible lack of visibility to its business model.
It made 11.8p EPS in H1, and the consensus is for 23.9p FY 03/2021. It sounds like actual will be maybe 12.0p (assuming very little in H2), which is a big miss.
I would dump my shares, move on, and not look back, with a memo not to invest in this sector again. It’s a minefield, and companies like this have too many moving parts.
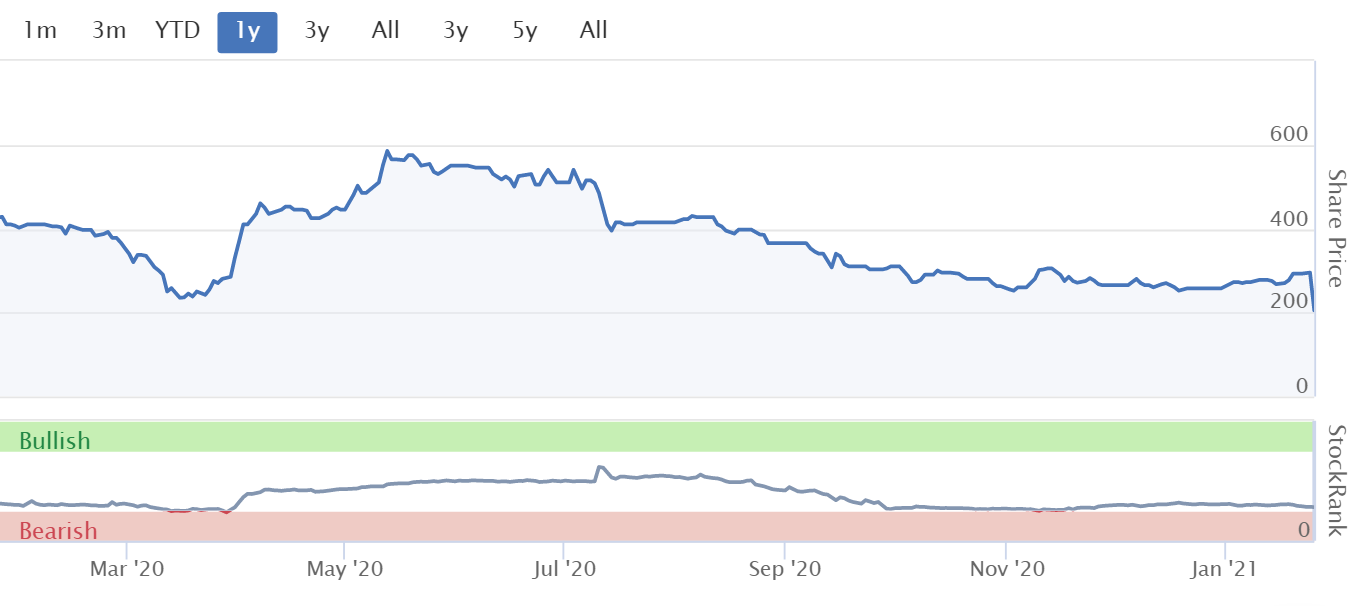
It's lost two thirds of the peak price back in May 2020 -
.
.
That's it for today. See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

107 comments
Manolete Partners (LON:MANO) (no position)
I asked the old CFO (Patrick Lineen) back in 2019 how '£3.54m of unrealised revenue relates to "New Cases Signed in the Period."'
His response:
"When we sign new cases, we normally ascribe a value to them but this tends to be a low value initially until we get to know the merits of the case better"
I didn't quite follow the rationale for recognising revenue simply for signing up a new case - and a part of me thinks it's wrong/bonkers - but presumably this accounting practice still holds and a lack of simply signing up new cases in the current depressed market will reduce their H2 revenue.
Cheers
A
Apologies to the Anti Technical investors here, but Paul comments on takeovers prompted me to do some digging and I couldn't help but share this screenshot of Signature Aviation (LON:SIG) in what blatantly looks like insider buyer right before a takeover announcement. As Anna Coulings books point out, there is not a lot you can do about hiding volume in the market.
See Yellow and red annotations indicating sustained buying before the announcement.
I hope your letter to the Takeover Panel gains some traction.
Re Heiq LSE:HEIQ
I guess todays in-line operating profit which what led to the brutal 23% fall. How much of this was due to IPO costs. Maybe a buying opportunity?
Over five years Zoo shares are up from 15p odd to around a pound if that is lacklustre then more please
Paul is only giving his opinion but seems it has done well for you.
Re Saga (LON:SAGA)
but a more general question about share valuation.
Those 2 ships that are parked up at Tilbury docks are depreciating say £30M per year between them. I get that they will have a 20 year life perhaps but if say SAGA had 20 ships and was replacing 1 a year we would be regarding this annual recurring 'expense' as material. When we talk of those 2 ships generating £80Mpa EBITDA ...eventually would it be more relevant to conceptualise that as £50Mpa EBIT or even less as EBT. Where do we draw the line.?
I note on several of Paul's prior reports that he is on the watch (rightly) for companies that capitalise too much opex and I think this is particularly the case with tech cos overcapitalising recurring development costs. But when is too much too much? and could there be a mechanism for factoring that into the PE thresholds for investment.
Just pondering over a glass of wine. I hold.....both
Re Manolete Partners (LON:MANO)
Long board meetings and trading updates sent out in the afternoon are never a good sign.
I had a small position sold out for a 30% loss fortunately not too much damage done as quite small position , I was convinced this it was a good investment !!!
I am trying to be more disciplined and sell at the first sign of trouble (can always buy back), I may live to regret it when it no doubts bounces tomorrow !!
(I hold MANO)
In the investor presentation yesterday they explained that they were advised to release the trading update immediately to avoid any issues of witholding information. My current feeling is that whilst the pandemic measures are still supressing case numbers there will be an upsurge when these measures lift. Don't understand the 10% drop today though - unless it is profit taking.
Thanks for the analysis and comments today Paul. Due to work and family commitments I'm never able to dial into the Mello sessions so I'm grateful for the sharing of what took place. With regard to mergers and insider trading, whilst it is perceived there is little/no successful prosecution I received evidence of at least one in my inbox this afternoon (quite a hefty repayment required of £3.9m):
Insider dealer faces paying £3.9m or more jail | Accountancy Daily
Late RNS from Manolete Partners (LON:MANO), stock drop +30%. a very poor show dropping this out late in the day
Manolete Partners (LON:MANO)
Intra-day Trading Update RNS at quarter to three. Doesn't look good - only breakeven in H2. Shares down 30%+.
Phil
I suppose 1.75x P/B may provide a floor for Manolete Partners (LON:MANO) (in line with Litigation Capital Management (LON:LIT))
Hi Paul, You thoughts on the afternoon £MANOupdate would be appreciated. 35% fall so far.
OK I'll take a look at Manolete Partners (LON:MANO)
Thanks for looking at this. I actually took the opposite action immediately after posting my request, even after considering stock's data on profit warnings. The value looked to good to miss as government assistance can only last so long. I hope I've got it right with a 2 to 3 year view, but hey ho. You can't help some people, eh?
How are you valuing Manolete Partners (LON:MANO) ? The profit figures seem to be built on fair value adjustments, which will now be negative i assume. The company doesn't ever seem to have been cash flow positive and yet it has quite a lot of cash on the balance sheet, presumably from debt and issuing shares. Not an encouraging investment case.
Up until now recoveries were being ploughed back into cases allowing the growth mentioned in the RNS. They use fair value but the cases only have an average 11 month duration and have been proven to be accurate if not slightly conservative. I'm unsure why you would assume fair value adjustments will now be negative? The work has dried up, albeit, one would assume, temporarily. Ongoing cases are not affected. With an easing of measures I expect a masssave ramp up in the number of available cases to choose from. It's worth noting that according to the company they only take on cases were there are abbundant easily attainable assets in the UK.
Manolete Partners (LON:MANO)
Scuba
Up until now recoveries were being ploughed back into cases
Looking at the the last 6 months figures there was negative cashflow before the investment in new cases !!! - so i would say practicably speaking they pimped working capital to invest in new cases! - as recoveries failed to cover tht other relevant expenses that existed. Looks like the prior 12 months was not disimilar. Not an expert in this company so i may have possibly got my cashflow knickers in a twist apologies if this is the case!
Maybe. I'm not an accountant, nor one of the more informed here. However, they have rapidly been scaling up the business year on year by investing in the acquisition of new cases. In the previous half year results they stated they had increased investments by 69%. On this they acheive a money multiple of 3.1. Everything was looking extremely promising until Covid and Rishi's prolonged interventions and they can't continue indefinitely. I'd suggest a glut of cases are likely once these are removed. Only a couple of weeks ago the company got not only the approval, but the presentation of the investment case by Kevin Taylor a couple of weeks back at the Mello Bash! He seems pretty shrewd and not easy please.
"I'm unsure why you would assume fair value adjustments will now be negative?"
I was taking that from the RNS which said unrealised profits would be significantly below market expectations. If they have settled more cases than they are working on, would that create a negative FV adjustment? I'm not sure.
Paul,
Re Saga (LON:SAGA)
The bond does have a number of covenants. They are in most part not particularly onerous, but the cross default one certainly means that other financing covenants are effectively present there too. So you have to presume that the most onerous covenants some of which might not be known on bank debt apply here.
Also, the negative pledge could come into play if they need to raise further debt finance or bank lending.
Also, with 3.5 years to maturity the recent example of AA highlights that refinancing will become front and centre in the not too distant future. If they tried to refi now, there would be a demand probably for some type of covenants and/or far more restrictive covenants. I would guess they would be issuing with a 6.5%-7% in the current market. As a point of reference Co-op Bank paid 9% for senior debt.
They're currently at a spread near G+600 which is not what I would term distressed in credit spread terms, rather elevated.
Regards
Paul
Hi Paul,
Where did you pick up your information on covenants on the Saga (LON:SAGA) bond? I didn't find any covenants mentioned in any of the Saga documents I looked at (Prospectus, Annual Report, etc), hence why I've got down in my notes that the bond doesn't have covenants. I'll happily correct the article if you can provide a reliable source to the contrary.
Mgt said in the last interims presentation that they expect to pay off the Bond from cashflows over the next few years, so refinancing it shouldn't be an issue, and it's way too early to worry about that anyway. Newish management strategy is to greatly reduce debt, so I don't think they'll be looking to refinance the bond at all.
Remember that in normal circumstances, when travel can operate again, Saga should be highly cash generative.
Regards, Paul.
Hi,
It's all in the prospectus under events of default.
Even if they do reduce debt greatly nobody knows if the bankers will demand they use the bond market going forwards. You can only ignore refi risk if you presume that they will be debt free in a few years.
Its often the case that an RCF is given or maybe in this case that ship finance is offered on the condition that the bond market is used to replace that finance. This is never public knowledge ahead of time. Hence you can only ignore refi risk if they are debt free by early 2024.
Unless they can be debt free and not need the bond market no management will dare upset bondholders. It doesn't end well for equity holders if they do. It's a backburner issue yes, but still an issue to contend with. Carnival had to pay 11.5% and offer the security of a number of ships last year. That would eat into any companies cashflow in an adverse scenario. I have no doubt that won't be lost on Saga as an entity and they will be out there talking to any bondholder who wants to know what's going on. Interestingly, there isn't an information covenant though.
Also, as covenants have been waived on the other finance management will know that the implications of the cross default are huge, so to an extent that is a substantial issue as there could possibly be a technical default if it gets messy. It's only a £250m issue but what if the ship finance isn't waived and an event of default is called on the bond as a result? They will be working hard to ensure that scenario doesn't play out & could result in an exchange to extend tenor and gain certainty.
I would imagine bondholders will be supportive but their kindness would not extend to equity holders if it gets messy.
Regards
Paul
Hi Paul,
Thanks for your helpful comments on £saga. Forgive what is doubtless a naive question, but why is is a good idea to defer debt repayments now (at a time of historically low interest rates) into the future when interest rates could be higher? Is your assumption that they'll rapidly be able to pay off any deferred debt is interest rates increase?
Grateful for any clarity on this - and apologies if I've completely missed the point.
Best, Pete
PeteB
Not Paul but isn’t it because Saga can’t afford to repay debt until their travel and cruise businesses are operating again and throwing off cash. For now they will be trying to preserve as much cash as possible and keep cash burn to a minimum.
Talking of take overs always reminds me of the extraordinary story of Raymarine from a few years ago. Then the leading marine electronics company. The company had denied any takeover interest and suggested the shares were likely worthless. Tipped off, a specialist yachting publication apparently threatened the company with a judicial review to get them to reveal that a number of approaches had been made. Which the company was forced to admit they had been and the company was later sold for $180 million...making punters who had bought at the lows a fortune.
There was speculation at the time that the directors had been hoping to buy the company back from the administrators for very little. I don't know the truth in that but I do know I struggle sometimes to believe what directors say in some instances where there is a potential "conflict of interest".
Surely there were a limited number of people in the know who were able to load up massively with cheap shares. Now wonder who was the broker?
Paul I watched Lord Lee on the Mello Investor Show last night and it reminded me of the takeover of Arm Holdings in July 2016.
I sold my shares a few todays before the announcement. I was very annoyed at the time and that is putting it mildly.
I too am drafting a letter to the Chairman of the Takeover Panel and I intend to send a copy to Lord Lee. I thought he was excellent as always.
The reason why Anpario (LON:ANP) share price has not moved is because it had already shot up following a weekend share tip in the Daily Mail.
MIDAS SHARE TIPS UPDATE: Healthy animal feed maker Anpario is flying high.
https://www.google.com/url?rct=j&sa=t&url=https://www.thisismoney.co.uk/money/investing/article-9179163/MIDAS-SHARE-TIPS-UPDATE-Feed-maker-Anpario-flying-high.html&ct=ga&cd=CAEYACoTMzM1MjI2MjU5OTQzNjExODc4MTIcNGFjMzlhNDhlZDYyMjU2Nzpjby51azplbjpHQg&usg=AFQjCNG3FpFS6wVQO4R2Y7n1WwodoHGTrA
I am a long-term Anpario (LON:ANP) shareholder and agree with Paul about the current high valuation given the slow growth in recent years. I have tended to buy when the p/e is in the high teens and sell when the p/e gets into the high 20s.
The City Pub Group Trading Statement out today
Paul's opinion on City Pub (LON:CPC) in July 2020:
"This must be one of the lowest risk ways to buy into the pubs sector. The share is basically a minimally geared property company, that also operates its freehold pubs portfolio.
Long-term, once we've got through covid, whenever that may be, this share could be usefully higher, perhaps. And in the meantime, it's not going bust, because of the value of the freeholds. So quite attractive risk:reward, I would say."
In today's trading statement, Clive Watson, Chairman of City Pub Group said:
"2020 has been a very challenging year, but decisions made since March 2020 with regards to the fundraising, cost control, streamlining of the business, and strengthening of the Board has resulted in a very strong balance sheet, good levels of liquidity, a strengthening of our business model, a more focussed proposition and most importantly, pure determination to go out there and do the business once the pubs reopen. We have the right people in the key roles, whether in the pubs or head office and a fantastic estate to trade from. I look forward to a time when I can announce to shareholders that we are on the acquisition trail again, but this will only be considered once we are hitting high levels of optimisation from our existing capacity."
Share price seems to be reacting favourably (I hold).
Talktalk Telecom (LON:TALK), Thank you Paul and Lord Lee for putting your views to the Take over panel.
An example Talktalk Telecom (LON:TALK) (I hold) They were offered a 135p /share bid by Tosca around July 2019, which was rejected by the board and not disclosed to shareholders at the time but only disclosed July 2020 after they accepted a 97p/share bid from Tosca.
IMO the boards of companies should have a fiduciary responsibility to disclose any offer received. They no doubt would argue of grey areas such as if the approach is not formal and say a "private discussion between parties" there is no need to disclose.
Alb
Transformational deal announcement from Getech (LON:GTC) this morning. Exclusive partnership with H2 Green and SNG to develop a network of large scale hydrogen generation, storage and refuelling hubs - to support transport fleets.
Getech will be involved in geospatial analytics to help H2 Green locate and build these hubs. They also have the option to buy H2 Green for £1m.
I had written off this investment for a few years (It has been in the bottom draw and forgotten about) so excited by the prospects, especially because it is in a 'hot'/interesting growth market.
I initially bought here as a value/turnaround situation, and liked the fact that the company was being valued at cash and freehold property. The upside potential now seems much greater.
Be interested to hear what other readers think of today's announcement.
All the Best,
Ben
@BenSharman
My reaction was bemusement. Building hydrogen hubs sounds expensive. Where's the money coming from? H2 Green was registered June 2020, and Getech have an option to buy it for £1m. That doesn't sound like a large organization to me.
There is a third party that you haven't mentioned - SGN https://www.sgn.co.uk/
Getech (LON:GTC)
-> long RNS but light on any near term tangibles.
H2 Green seems a concept company. It may be a good concept but £1m seems a drop in the ocean in terms of hydrogen infrastructure. It looks to me like Getech is an option on H2 Green which is an option on Luke Johnson's ability to secure contracts with meaningful players with the right permitting (the rns says that he has government and industry connections -> I know a lot of wheelerdealers with them!).
I know a little about Getech historically but not much and I've not updated myself any time recently. Can you explain why they are in uniquely good position to provide the geospatial logistics? Wouldn't a more established logistics company be better here...as this not about analysing geology to produce resources. This seems like H2 Green needed a partner and Luke Johnson's background in the oil and gas business means that he perhaps knows Getech guys.
What do Getech get?...some of that energy transition/ESG magic.
My feel on reading the rns was that it is a real spin document. Multi-million EBITDA from each site...and H2 Green are giving that away for one million max....there's some explanation needed there.
That said...Getech probably now at an elevated new base price for a period with volatility around that depending on how the can progress the partnership. The repositioning of existing assets sounds plausible...but why wouldn't SGN do that given they own them?
I'd guess that capital raised at the site level is going to come from specialist financiers. My experience of such deals is that the junior/equity interest in them is squeezed quite hard at the outset unless they are putting up a significant 'first loss' stake. That doesn't seem to be on offer from Getech/H2 Green so they will be very 'leveraged' to the finance deal (ie many scenarios that lead to zero or very little return and 'senior' partners getting more/all of assets). There's going to be high yield, PIKs, etc...and the equity is going to have to earn its return over the long run and/or with high growth. SGN need to be paid too before Getech/H2 on their assets.
I might not get it...but I think if I owned Getech I'd sell it today unless I can see other elements of value/turnaround....and then monitor and look to see if I should buy back if they actually prove something
Agree Mojo. - I know, pinching myself :) Just kidding!
Hydrogen (blue and green) are very promising but I can't help but feel that those with the biggest pockets will end up taking the spoils and many of the smaller companies are trying to build a story without the financial substance to deliver. Interesting to see BP talking a lot about getting heavily involved:
https://www.h2-view.com/story/...
Shell buy the UK's largest EV charging network and BP are talking about taking up share in hydrogen infrastructure.
Call me a cynic but I don't think they are doing it for solely ethical reasons but I didn't expect them to sit on the sidelines for long.
Sounds like it will be good for shareholders and terrible for consumers if they swallow up all the EV and hydrogen infrastructure - to go with all the existing fossil fuel infrastructure which they already have!
It’s a miracle Thornabian ;)
I’m not confident of my Getech (LON:GTC) view partly as it’s a while since I looked at it properly and partly as what was released today was hard to piece together ...but just trying to put together the pieces I can guess at.
Very interesting analysis of Saga. Many thanks
I had a call from a Saga (LON:SAGA) lady yesterday. I had called some time ago to ask some questions about what conditions would be required for the cruises to go ahead. She could only go so far at the time, but came back yesterday with more. I do follow Saga (LON:SAGA), am very positive to the company, having had several very enjoyable, great value land-based holidays with them, like their ships in principle (facilities etc, value for money).
However, I do believe that like a lot of travel companies (and yes, I know Saga have the insurance side too), I share a view from John Authers (Bloomberg Opinion) recently where he said that their SP has come back faster than it should. Too much future recovery was built in, in his humble opinion and mine too.
The info she gave me was that cruisers would have had to have had both jabs; and they would have had to have been symptom free for 2 weeks before boarding. How to check?
She was sure that they would make appropriate arrangements for the crew to offer a safe environment, but Im not sure how they could. Not specific at this time. Presumably the crew will not be in the age ranges covered by mid year!
On a cruise with Viking in the Caribbean in spring 2020, we had noticed that at virtually every port, the front of house and cabin staff were changing, based on the shorter contracts that seem to operate these days. She reassured me that of course Saga cruises operate from UK back to UK and their crews were principally Phillipino, and generally did not change within a cruise. Im still concerned about crew arrangements for vaccination and testing.
They are planning at least initially to have smaller numbers of passengers, which I already knew. 800 vs max near 1000. That's good.
As for visits to ports, she said that only controlled trips would be permitted. Makes sense, if of course passengers are allowed off at all (and for the early cruises shouldn't be a significant issue - local UK or European ports, but will all the latter play ball?)
I recognise that sooner or later (IMHO later), we will get to a stage where we accept a level of C-19 and get on with it, within controlled circumstances, which should be possible on a well run, very modern smaller cruise liner like Saga. When that stage will be reached is anyone's guess, but it isnt looking like soon. IMHO. In the meantime, I will await the shares falling further.
Intuitive6191 that was my experience in December big time. By speaking to £Saga
as I do every year, my Motor Insurance dropped from £800 to £406.
Because of Covid I only did 1,900 miles last year!
That’s interesting
I think it’s a wise move for SAGA to retain customers as there must be an element of cross-selling of the various SAGA products. To do this could mean that SAGA has to give up some of their margin on insurance.
I think that SAGA is an interesting situation but wouldn’t want to rely on the premise that insurance profits are likely to cover shortfalls elsewhere in the business.
SAGA - this sentence caught my eye.
Reduced claims frequency expected to have positive impact of at least 5ppts on current year loss ratio.
I suspect 5ppts or 5% is massive. Suppose the loss ratio was 95% ie for every £100 underwitten you receive £95 of claims. Improve that to 90% and you have doubled operating profits.
Can someone confirm my thinking and does anyone know what the SAGA's loss ratio last year was?
Don't know about the actual numbers but I had interpreted that syntax and using your numbers of 95 in 100 an improvement of 5% taking it to 94.75 in 100 ie 5% of the 5 which is the slice they keep after all. It seems unnecessarily opaque. It would have been more transparent if they had simply expressed it as £x on the bottom line in plain language. This is one of the reasons why DYOR is so hard for me. I should not need to be familiar with actuarial jargon to interpret a SAGA TU.
Saga (LON:SAGA)
I hold
I've not worked in personal lines insurance for 20 years but I can tell you that 5% is a big movement in loss ratioon home and motor, but this will even out a lot next year as the premiums fall. So, any increase in insurance profit will be exceptional rather than repeatable. You'd need to understand expense ratio and investment retruns to fully understand profit impact.
Thanks for the write up on SAGA Paul, excellent as always. Part of the reaction today could be due to the wording of the statement. They talk about a cash burn of £6m per month and no where do they specifically say that is only the Travel division and it is offset through other areas of the business. The below reads like the company burn rate is £6m per month, not just the travel division.
"In order to minimise the financial disruption during the period of travel suspension, significant savings have been achieved in both marketing and administrative costs which have reduced the cash burn rate. For the second half, on average, this is towards the lower end of our previous guidance of £6-£8m per month."
However they then go on to say that they have only burn £9m since 31st July. which does seem to imply that cash burn is much lower.
"Available cash balances have increased by £22m since 31 July 2020 due to the capital raise (£139m) and disposal proceeds (£12m), partially offset by repayment of the drawn portion of the RCF and half of the term loan (£120m in aggregate), and a net £9m of other trading items."
Maybe i missed it as I was reading it too fast but it does feel to me the company could have been clearer on this point?
Codemasters Group (LON:CDM) is one example of a company that had a takeover approach a considerable period before it advised the market of this. As it happened, I sold a fairly sizeable holding between these two dates... ...and certainly believe the company did not meet its obligations to keep the market properly informed.
Incidentally, this is also a situation where a non-exec had sizeable share options and the directors seem to have been lured into recommending the first bid by the excellent opportunities they were offered by the potential acquirer.
Obviously this is all IMHO.
A look at the Saga (LON:SAGA) chart. For the charting sceptics, look away now :)
I'd be looking at a break and daily close above 320p as a positive indication of upwards momentum. That would clear the recent DTL (downwards trend line) and the most recent high. Ideally accompanied by strong volume, indicative of institutional interest.
I would consider this a LTH as the Covid recovery plays out, so no specific price target.
A dip below 220p would be bearish in the short term.
Isn't it supposed to sink after hitting the iceberg :)
Was there a "too many moving parts" comment above about something.
I use SAGA for insurance and every year it’s usually a case of asking them to look at their quotation and sharpen their pencil. It s annoying to have to do this as a long term customer, but a ritual I had become used to.
Fast forward to the latest quotations and they are surprisingly competitive. I would guess from my own experience that they are working harder to keep insurance customers - but at a possible reduction of margin.
Re: Saga (LON:SAGA) the FCA is about to issue new rules on "price walking" following consultation paper CP20/19: "General insurance pricing practices" so I'd guess any change is a reflection of the fact that a change in practice is about to be forced on the industry.
The Investment Club should be pleased with the positive set of figures released by ERGO today.
Hi Paul,
As per some other comments earlier, would it be possible to add any views on Personal Group (I hold) following today's update. Based on Stockopedia there has been quite some community purchasing looking at the green bar.
A few comments from me:
Seems significantly undervalued.
The major part of the business is a niche insurance business. Whilst most insurers battle it out within the efficient market of price comparison sites, Personal has a niche direct to consumer model. Most insurers don't make any profit from their insurance business' and are reliant on the investment of the 'float' to generate poor returns on capital due to the low risk nature profile of their investments. Personal Group is not reliant on investments, their insurance business has generated excellent returns on assets for many years and continues to do so. For this reason, I believe it is one of the best insurance business models in the UK. Personal sell employee benefit packages to a wide range of business, including Royal Mail, at what seems to be a very competitive rate and then gain direct access to all their employees to sell their insurance products (no comparison sites).
Business is valued at £64.35m (market Cap):
Business has no debt
Cash confirmed today of £20m.
No impairment has been suffered on any parts of the business, leaving following areas of the business (the benefits side) valued as follows as a minimum based on acquisition costs:
Lets Connect: £12m
Innecto: £3m
Saas: £7.3m
Total: £42.3m
This leaves an insurance business valuation of £22m. The insurance business generated £8.3m ebitda in 2019 and whilst sales have been hit during covid due to not been able to sell face to face (although increased telesales capacity and improved retention rates), it is clear that the insurance business has not been hit as the market cap valuation would suggest.
Today's trading update states turnover, in line with 2019 at approx £70m and ebitda upwards of £9.5m (2019:£11m).
They state that insurance sales profitability will be hit in 2021. Even looking at worst cases, it would suggest the share price should be 50% higher. I believe this is an asymmetrical opportunity with a very limited downside on a proven business model with excellent fundamentals and a very strong balance sheet.
Paul XLM have results/ news out today. Any chance of a look?
Hello The skier re £XLM I think that the figures are awful. I have compared them with figures on Stocko in terms of turnover and they fall a long way short. I would be greateful for Paul's comments on the adjusted EBITDA of approximately $11.5 million (excluding transformation costs and share based payments). I still deal in real profit and real earnings, and heaven knows what Paul will be able to come up with having got through all this goo! I have had these shares on a number of occasions. They have promised so much, delivered so little time and time again.
Thanks ridavies. I have had mine for some time and should have sold when they hit great heights. But SCSW rate them and have them in their Growth Portfolio 3.
During this lockdown I came across a sheaf of five year old SCSW reports. Out of interest I drew up a spreadsheet of the main recommendation in each one and plotted the sp after one year and to date.
I stopped my subscription a few years ago and have no intention of renewing it.
RE £SAGA
The plan to resume cruising in May has to be in doubt given recent developments (mandatory hotel quarantine, delayed second jab rollout, prolonged general lockdown, issues over vaccine supply). Also there is no announcement for vaccine passports so customers will have to approach and pay GPs for evidence of vaccination.
The cash burn in the meantime is significant and banking covenants have yet to be renegotiated.
Saga (LON:SAGA) If they could sail holidays from lockdown, no ports just great food drink and entertainment and socialising with pre-sail quarantine procedures enforced there would be loads of people queuing up to have a change of scene and some semblance of normality and they’d clean up big time
Yes, on the face of it Saga (LON:SAGA) could offer a cruise to nowhere or a cruise round the UK. But that does then open up the question if they can do that because all the passengers are vaccinated (what about the crew by the way), then why shouldn’t other hospitality venues be allowed to do the same. e.g. Centerparcs?
But new variants of the virus are occurring all the time. It’s only going to take one a bit less susceptible to the current vaccines to take hold and we’re going to be ‘on hold’ again while the vaccines are modified.
Still all very uncertain. So, I’ve decided to sit these Covid dependent sectors out for now for this very reason. It just seems like guesswork about the future to do otherwise.
The difference between cruises and Centreparcs is people would cruise for a month happily - but the Centreparcs are a week or max two-week experience. Also, people would potentially sneak in and out of a parc, but once the ship has set sail you can guarantee no one is getting on and off illicitly. With staff and guests doing a 10 day quarantine before embarking instead of post cruise, it would be perfectly feasible.
I also think that the travel industry, when it can get going again, is going to be able to charge premium rates and not have to discount their fare at all. Think of all the shopping, drinking, and partying is pent up with everyone.
Not sure about this. Cruise holiday duration isn't dissimilar to other holidays i.e. 2-3 weeks, and almost all cruises stop at ports to allow passengers to disembark and explore. If they were to disallow disembarkation for the duration of the cruise, then a similar setup could be put in place at centre parcs i.e. once you're in, you can't drive out of the gates for the duration of the stay.
Yes, but some live out staff will be going in and out, there will be no seal which is the usp of the cruise ships. The government could give out licences to an operator like SAGA to start up earlier than the other travel industry players, as much as they will bitch and moan, because they are in this special position of being sealed if they don't make any port calls. Win win for SAGA and the government who will benefit in taxes and no furlough payments.
But new variants of the virus are occurring all the time. It’s only going to take one a bit less susceptible to the current vaccines to take hold and we’re going to be ‘on hold’ again while the vaccines are modified.
If a new variant makes existing vaccines ineffective then everyone will need revaccination, which will take months.
I agree, if people become careless after having the vaccine I think they will encourage the evolution of a vaccine resistant strain of the virus!
Deleted - silly post really.
Exactly right TStubbs. A lot of people just enjoy the cruise experience, with the stop-offs & excursions a nice to have, not essential. Take the fjord cruises for example - a lot of it is about soaking up the views, sipping cocktails on the top deck. Or inside.
If you said to the mayor of Bergen, or somewhere, we have a ship full of rich pensioners, all of whom have been covid vaccinated, would they really be turned away for excursions?
I think they'll find a way to get the ships moving again in the not-too-distant future, and people will be desperate to be released from imprisonment in their own homes, even if there are some restrictions on the ships.
Hi Paul - the really key point though as you described is the margin of safety given the Insurance division. From the statement today it looks like cash burn from travel is down to around £6m p/m and insurance should be generating more than this. Thus they should be able to maintain a small profitability and retain ample cash balances whilst we wait for the return to travel.
I notice a lot of chat about when the cruise ships might/might not be able to resume but timing isn't particularly important to the recovery of the shares. If they resume in May then great but if it is September then also fine. It defers the point at which profitability recovers but it doesn't really change the investment case at all so long as you have a time horizon of 2-3 years.
The deferred payment of principle doesn't concern me. All this does is change the cashflow profile, not the profitability and I suspect they will look to smooth this by elongating the payment profile once they are back up and running anyway.
There is an edge case where travel is pushed back for so long that the bonds come into play but I find that scenario really not very plausible. Populations will not permit governments to lock them up for any extended period - there would be a tipping point of serious unrest if that persisted. Vaccines will have to be tweaked every year, we know that already as the same happens with the flu jab, but it is not a complicated process to account for the mutations.
The number that caught my eye is deferred payment on principal of the covenants on ships. £32m at present, with Saga looking to defer a further £45m into mid-2022. Seems likely to be accepted given that who on Earth would repossess cruise ships right now, but that's £77m that has to be paid down along with normal covenants from mid-2022 onwards. Could be that profit from the ships will be minimal until deferred loans are paid from 2022 over 1 year, 2 years?
I sold out of Saga over xmas. I can see them being a successful company in 3-5 years, I just can't see how they get there.
IML, it seems like they will be servicing the interest not the capital. The capital repayments won’t impact on the profits but the increased interest over the life of the loan will. Year on year the difference will not be material. It is as though we are in limbo waiting for the start of year zero.
There is plenty of headroom in terms of cash and in the revolving credit facilities. They clearly want more headroom which I found interesting.
New variants are a concern. Whilst Saga are well focussed they w I’ll be subject to rules placed on the wider cruise industry. One bad breakout on board one ship could get the whole industry shut down.
I have a substantial holding and continue to hold. My time horizon is 2 years.
SAGA's cash burn is nothing. The insurance division more than covers the travel division cash burn. Hence it can tread water indefinitely. That's why the precise date of cruise resuming doesn't actually matter that much.
Roll things forward a few weeks, and the death rate (which lags infections) is likely to be drastically lower, and people will be clamouring for lockdowns to ease. You have to think forwards, not get bogged down in the situation today. That's where the opportunities lie.
Would the 500m odd ship loans not have to be repaid at some point? Even if they make 80m pa from the ships once things are up and running, that would still take at least 6 years to pay off. Or would they simply keep rolling over the debt?
Checking my notes from the prospectus last year, Saga's ship loans were set up in 2 stages, for each of the ships, in 2015 and 2017. Then drawn down when the ships were delivered new.
Repayments are due 6-monthly, over 144 months, so 12 years, in equal instalments, which I think is a combination of capital & interest.
It sounds like the amendments made due to covid will probably defer the repayments, shifting the repayments back by a year or two from what was originally planned, with higher interest charges to reflect that. I think that's right, although it's not specifically stated as such.
Paul, a comment further up the page stated that the £6m p.m. burn could be for the business overall. Do we know that the £6m p.m. burn is for the travel business and is covered by the insurance arm? Thanks.
Saga (LON:SAGA) put the comment on cash burn as a sub point under the heading "Travel business well positioned ...." and in the interims back in September they said "cash 'burn' for the Travel businesses to be in a range of £6m to £8m per month in the second half of the year"
I don't think they could have made it any clearer!
If Saga (LON:SAGA) cash burn is negligible then why is net debt up £139m since mid 2020?
Also there is a risk that proposed FCA insurance market regulation will hit insurance margins.
https://www.fca.org.uk/news/pr...
If Saga (LON:SAGA) cash burn is negligible then why is net debt up £139m since mid 2020?
Read the RNS again, more carefully! ;-)
It explains that they drew down the second ship loan, partially offset by the placing.
you get a little card when you get your first jab, saying what jab you had, your details and an appointment for your second jab, perhaps they're planning to give something out with second jab confirming the dates of jabs and all details ? I don't know just speculating, even if this isn't the case, surely there will be a central register of who has been vaccinated and you'd go there rather than to a gp ?
@Momoko
A small point. When I had my first vaccination last week I was given a card with the vaccine batch number, vaccination date and appointment date for my booster vaccination. It’s forgeable of course.
Did it have your full name on the card? As some people are reporting cards with no name or just your first name.
Full name except middle initial
I can't remember the name of the cruise ship that was quarantined at the beginning of the pandemic . The Worldometer very comprehensive covid stats site had it on its screen as if it were a country/state for quite a while. It registered as one of the most infected places on the planet.
I can't but wonder if enthusiasm for cruising has been dented as a result. I also have not read any analysis of why cruise ships were so badly afflicted - was it simply the very sociable setting or something more worrying such as shared air conditioning? I have no idea and no information. I would be grateful if anyone could guide me to a report on the subject.
Personal Group (LON:PGH) - O no fundraising / dilution took place in 2020 either.
Morning Paul.
If you have time please can you give your opinion.
#REAT Final results show a continuation in this tiny turnround.
Strong financial performance on all key metrics
Maiden full year profit
Rev up 44% all organic
Margin up 470 pts
Generating cash
1st 3 months of this year going well
I hold.
Investegate |React Group PLC Announcements | React Group PLC: Final Results and notice of AGM
I have held React (LON:REAT) for a while. Thinking the pandemic will require large scale deep cleaning of stadiums, aircraft and other places where crowds gather. I am a bit surprised by the price action this morning though. I see no negatives in the numbers out today so might need a month for some of the asset managers ( mIcrocap styles) to wake up and smell the coffee. I remain a happy holder. One day it might be large enough for PS to comment on.
I thought the numbers read well too. I think React has won contracts for Covid cleaning but it has also lost some due to Covid. The underlying business seems to be doing well excluding Covid. Maybe Covid will actually mean React win new clients for the post covid environment too. The new management team seem to be moving the business forward. It pleasing that all growth is organic. I am also a happy holder. I have spoken to Shaun Doak (CEO) who is passionate and newish to the role. A CEO with an active hands-on approach suits this type of industry well. He is also supported by the guidance of recently promoted and experienced Executive chair Mark Braund. It seems that the team are executing on their plan
Paul has commented before and I hope he will today but it is a tiny MCap.
Off-topic Personal Group (LON:PGH) - Rather strange gap down by the market makers in the morning. Given the SP was 399p in Jan 2020 and at yesterday's close 211p, I'd expected a gap up rather than down.
- New contracts and strategic partnerships
- 2020 Rev similar to 2019
- Cash has gone up by 3mn
- “Adjusted EBITDA to be upwards of £9.5m (2019: £11.0m) reflecting the change in revenue mix”
- No debt 2020 (2019 : nil)
- new virtual insurance sales solution has shown encouraging initial results. We have also expanded our policyholder base to capture contingent workers
- Sage Collaboration is encouraging
Personal Group (LON:PGH) 's Outlook: With further Government lockdowns ongoing, 2021 is expected to see a more significant financial impact on both income and profit as the ongoing restrictions reduce the ability to write new insurance sales and the historic impact from 2020 flows through. We also remain vigilant for the potential impact on the Group from any increase in claims. Notwithstanding, there are a number of clear strategic growth opportunities which underpin our confidence in the Group's prospects over the medium-term. New client wins will give Personal Group access to a significant number of employees when restrictions are lifted, all of whom will have the ability to apply for Group's insurance products, and the partnership with Sage represents an exciting, tangible opportunity to materially grow our target market for employee benefits.
Does not sound that bad to me!
Could we look at Quiz please Paul - lots of good sounding news my main worry is the online sales numbers would like your view on it thanks steve
same request please, I believe Paul was a holder previously, the lack of interest suggests he may have since sold ? I'd be interested to know why if so. I'm also a little concerned about the online sales
threeput,
I've got a huge list of things to look at, including Quiz (LON:QUIZ) (I hold) . I'll get to it when I get to it. Generally I'm trying to leave the less liquid stuff until the end. I've not sold, so please don't make things up, it's really annoying when people do that, leave that stuff to advfn. Thankyou.
Great results from React (LON:REAT) today, showing a maiden profit and a very upbeat outlook.
REACT are deep-cleaning specialists. They installed a new management team a couple of years ago and are reaping the benefits now, being in a happy place where both revenues and gross margins are improving rapidly.
Revenue rose by 41% to £4.36m. Of course, given its specialism, the company gained some business from COVID. However, even after backing out the £444k of COVID-specific business and notwithstanding the fact that COVID adversely affected some revenue streams, top line still grew 26% in the year.
Gross margin improved to 33.2%, up 470bp in a year and 1220bp over two years.
Having raised £1.16m net in June last year, REACT has a rock-solid balance sheet and, with £1.78m cash, it is well-placed to invest to fund further growth, possibly through acquisitions.
The outlook statement is very promising too:
The new financial year has begun well, with profit and cash generation stronger in the first quarter of FY 21 than the prior year.
Allenby is the corporate broker and the only one providing forecasts although, unfortunately they are not being captured by Stockopedia for some reason.
They are forecasting continuing revenue growth of 18% this year, to £5.15m and a further 124bp improvement in gross margin, leading to FY 2021 PBT of £505k, and label these projections as "prudent".
React (LON:REAT) are a tiddler (c. £8m market cap) but seem to be in a sweet spot at present and, in my opinion, offer tremendous upside potential.
(I hold)
Good resume. Agree with your thoughts. I hold too.
React (LON:REAT)
I did hold React seeing a turnaround. However, I think contrary to comment here relaying the positive comment from todays prelim and Allenby note, the turnaround looks a bit mired rather than accelerating. The price today says acceleration so that looks like disappointment coming down the pipe unless mgt pull some major good news rabbits out of their hat and explain their growth pathway (which they are being very slow to sketch out...we are beyond the stabilisation stage).
Why is the share price unimpressed today? Ans: They have it all to prove and their guidance is underwhelming to concerning
The above is likely leading to dissonance and disappointment for shareholders who have bought a rapid turnaround and growth narrative.
FY20 showed that competent and engaged management can make a decent established service business function well and in doing so firm up existing relationships and sales opps plus manage business costs better. This turns a simple business that shouldn't be loss making into one that breaks even.
However, the steps from here look harder and covid isn't a great excuse for moderate outlook as if the pickings are so rich for this better configured and operated group then the chance to pick up business from low base is high.
I wonder if untested CEO Shaun Doak is working out as a business leader rather than salesman? Maybe there's a surprise in this?
Its quite possible/probable that React sp could trade well below current levels as mgt prove themselves. At the moment is maybe deserves 1x sales and 20x earnings...so half current...for more they need to show and tell more
DYOR
mojo
mojomogoz,
It's useful to have a more bearish view on React (LON:REAT), although you do seem to be scraping the barrel for many of your bullet points. Comments on each below.
1. React is a very highly valued stock at near 2x revenues, and approx 40x earnings. Its got to show its motoring to maintain its valuation. For perspective, its a Boohoo (LON:BOO) -ish valuation without the proof that a boo shows on delivery.
Notwithstanding the fact that is manifestly absurd to benchmark a £7.5m contract cleaning company against a £4.4bn online clothing retailer, I will indulge you anyway. It is plainly foolish to look at REAT on a trailing PE basis when it has just transitioned to profitability. Its forward PE ratio is 15, compared to 34 for BOO. Your perspective seems to be skewed.
2. Guidance is a disappointment. FY20 saw 40% revenue growth 'despite covid' (they're only attributing c.£440k to covid and saying it lost them business in other areas). This implies that they would have had an even more block bluster year if covid hadn't come along...
“A disappointment” to whom? I’m happy with guidance, which is above my previous valuation projections and is described by the broker as “conservative”. If you are disappointed with the guidance, that is because you were unreasonably optimistic before,
3. ...so to state that FY21 to date is only stronger than this time last year is somewhere between underwhelming and a bit troubling. They did well in FY20 despite covid...so why isn't FY21 to date cracking, building operational momentum rather than just stronger? On back of 40% last year that's lukewarm for this year.
A conservative forecast of 18% revenue growth troubles me not at all. I also expect it has been set to be beaten.
4. 'Ad hoc' business is the leading edge indicator of React's ability to attract new business. Its their chance to impress new people. Take out the covid related work and then the 'ad hoc' revenue category is particularly concerning with only 20% growth (despite new team etc pushing the envelope). Covid business is unlikely to repeat. Contra to Allenby claims it probably provides low ability to impress new customers with what React can do as its an activity that is/will be clearly segmented off from future operating activities for companies and/or managed by new operating protocols driven by internal decontamination/cleaning protocols. They'll probably view money they paid for React to do covid decontamination etc as money down the drain!
Again, it makes no sense to take out COVID-related work from ad hoc. Given the yaer we have just had, it is perfectly obvious that most ad hoc opportunities would be related to COVID, and that is where the company would apply its limited ad hoc resource.
5. 'Contract reactive' business is a disappointment with YoY growth of less than 2%. Covid provides some excuse for this but outsiders/investors must feel unsure how much it explains. Idiots and undesirables still made toxic mess. This area has got to be a key reason to employ React. Why haven't they been able to find more new business here? Is it a lack of opportunity or a need to invest to capture the opp?
This is explained perfectly well in the results statement: “Specifically, we saw temporary reductions in activity in the judiciary and police sector, where we carry out a significant amount of deep cleaning to cells, courts, and transport vehicles, alongside a decline in the housing sector where we typically carry out void cleans, deep cleans and needle picks. We saw this business return in the late summer of 2020, only to reduce again post-year end as lockdown restrictions began to intensify. REACT operates on long-term framework agreements, which we continue to add to. We therefore anticipate this business will re-emerge and grow as the impact of restrictions eases in each of these sectors”.
6. 'Contract maintenance' grew lots....but this is less likely to be both differentiating and an area where margins can be kept up (probably also causes admin expense to increase)
2020 admin expenses for contract maintenance were 26% of the corresponding revenue, compared to 33% for 2019. Margins being kept up and admin expense ratio improving.
7. Is admin expense stable going forward giving operating leverage or does it need to rise with sales. Needs some explaining
Does this really need some explaining? Why wouldn’t this business benefit from operating leverage?
8. Something perhaps hidden below the surface is their reliance and engagement with external specialist cleaners. This is potential strength of the group and feeds ability to scale rapidly and efficiently as they act as a contracting and forwarding hub for these guys (like a logistics biz) and take a nice margin on top. There's probably something a bit chicken and egg re this sort of relationship and having the relationship with the specialist cleaner helps create growth opps. That they don't talk more about this makes me suspicious. Why aren't they talking it up as a growth driver? Are they struggling to build these relationships? Could that be that specialist cleaners aren't interested (have enough of their own business and most aren't going to hire more staff to grow)? Could it be that specialist cleaners don't want to share margin with React?
From the results statement: “To support our growth and develop the reach and range of our capability, we have grown our team of specialist operators. We also launched a partner programme aimed at developing a network of trained and authorised subcontractors, to help us to more rapidly scale to meet the often-demanding needs of nationwide coverage”.
9. What will they do with all that cash? There is no stated (re)investment plan for the group. A business on a growth rating needs a plan....
From the results statement: “Our strategy for growth is clear; we will continue to build a leading position across our business through fast-paced organic growth and if the right opportunities present themselves, via strategic acquisitions, to support our goal of becoming the country's most trusted name in the provision of specialist cleaning, decontamination, and hygiene services.
We continue to invest in sales and marketing to engage with the large addressable market for our services. This includes further developing our use of the right sales and marketing tools, especially during this period requiring a hybrid approach to customer engagement, i.e. where both face to face and virtual/electronic sales environments coexist”.
10. ...I suspect that plan is soon to be announced and it ain't that sexy...they simply need to invest in their people, equipment, training and more sales capability plus perhaps a pro CRM system to move them beyond spreadsheet lists and personal networks. That's all sensible...but its not 'we have take off' investment. It signals that they have stabilised the biz and now enter into a multi-year investment plan. I think this produces results over a 3-5 year horizon but its quite possibly slow to start with and will see cash balances go down.
I suspect that making deep cleaning “sexy” is a task beyond even the REAT management. The plan you suspect “is soon to be announced” seems to be pretty much the same as the one that has just been announced.
11. The Allenby note and forecast probably hint at a belief/hope that revenue growth will be back end weighted as it shows EBITDA near doubling but FCF from ops only moving up 20%. There's no working capital unwind from FY20 so the guidance is suggesting a negative working capital position into the year end which would be caused by business wins late in the year...
Making too much of too little here, I think. I’ll need to update my projections to get a better feel for this.
12. ...this also hints (again) that current business wins are disappointing
From the results statement: “The new financial year has begun well, with profit and cash generation stronger in the first quarter of FY 21 than the prior year”.
13. The presentation of this info by house broker may also hint at forthcoming capital raise?! Talking up lukewarm results is a classic game ahead of raise. React needs to have growth and inorganic is the easiest and the right acquisition probably improves their pathway to organic growth and certainly gives them more heft as a stock. Its not my instinct that React would acquire at the moment...but it would make sense for corporate ambitions to do so and fits with a new heavyweight (relative to company that is) chairman. This is likely not good for short term sp.
You seem unique among observers in considering the results lukewarm. As you pointed out earlier, the company seems to have ample cash. You may be right that the chairman has bigger ambitions for the business, but that is not apparent yet.
Thanks for your effortful response Effortless.
I might be wrong but my points are a bit better than you dismiss and the results and guidance are less good relative to implied expectations. You seem to believe React (LON:REAT) is an island in valuation and expectations terms as you like it and hold it...
It could go well. I like what they’ve done to date. But I’m pretty sure they need to step on it for this next interim or there’ll be disappointed holders disagreeing with your sanguine outlook.
It’s late so I’ll maybe respond more specifically tomorrow. If not, best wishes and good luck ...
Ciao for now
Hi Effortless Cool
Seeing as its React (LON:REAT) presentation tomorrow I thought I'd respond seeing as you found my detailed and considered points so useful before...even though they 'scrapped the barrel' and were 'absurd'....
I'm not one to say the share price never lies (as clearly price often misdirects) but I'd point out that since I wrote my note the price has fallen >15% (at this moment with 1.34 bid). That's not the normal way that a cheap stock welcomes stonkingly good news. Anyway:
Now I'll send my questions in for the meeting if I can get time to get round to it. I like what's happened at React and I'm interested. I just think this microcap is going to trade down short term (potentially quite meaningfully) unless it shows some covid-independent pzazz.
Peace out
Your mojo
Hey Effortless!
Today's React (LON:REAT) call was good...they handled and explained well.
We'll see how they update for H1 2021 in April. Whilst they say that Q1 is good (best yet) I still think the guidance they have left in the market is a bit lukewarm and at their size they need to show really quite strong top line growth (or transformative margin) to keep multiple up and a risk of H1 2021 not being good enough for current price and expectation remains real. They show good operating performance but not yet a motorway to growth...they're going to have to lay that out with time and comprehension of that is what can turn React into a more secure growth compounder IMO....my suspicion is that management are still looking to find that route out for themselves at the moment. So good work stabilising and turning round but still searching for the higher sustained gear IMO.
Paul can you take a look at £yu. if you get time probably to small forecasting above expectations for 2021 already.
Good morning. Any thoughts on the Sensyne Health (LON:SENS) interims last week? Minimal turnover, high cash burn and a Market Cap a little under £250m. Future prospects reliant on US regulatory product approval and NHS Trusts deciding to pay for products the company are currently providing foc for an initial 12 months. Interesting business model in a potentially high growth area (medical AI) - I've been in and out over the last couple of years (currently out). Many thanks.
I too have bought Sensyne Health (LON:SENS) in the past and no longer hold. What made me sell was the row between the CEO and the former CFO. The CEO paying himself an enormous fee in the IPO didn't help. However assuming all is sweetness and light in the boardroom these days, is it worth investing in? The figures are like an aggressive early stage tech company - in the next few years they will lose money even if they achieve their ambitious forecasts. They have two sides to the business; (1) making NHS health record data available to the pharm industry and (2) developing health apps. The second strikes me as moving into a highly competitive area and in any case it is the value of the NHS data that underpins those developments that might give them a competitive edge. Thus the success of the business model I think boils down to a single question - how much value will the pharm industry give to that sort of data? This is a really difficult question to answer. The data can surely help answer many interesting question, in particular what works and what doesn't. However I don't see the pharm industry wanting to pay a lot of money for this - finding out that their drug doesn't work is not one of their priorities. Sensyne are hoping synthetic control arms to drug trials will become more common. These are replacing the placebo arm of a trial with the identification of people who have already experienced the disease and a looking at the outcomes. This is fraught with methodological problems, so again I am not sure the speed it will be taken up by the industry. In short Sensyne Health (LON:SENS) is an interesting business, but it's success is too uncertain for me.
Morning Paul, would appreciate your thoughts on QUIZ update. Thanks.
Hey Paul, £Quiz published trading interims today. On a (very) brief look, seem ok but still a real loss for the period after £7m charge (which I assume are one time CVA charges?). If you don’t get time to have a look today, no worries. These retail recovery plays are sort of in suspended animation at the moment until we can get some clarity on CV19 anyway.
Quiz (LON:QUIZ) - Magical Profit after 72% fall in sales, Wow is that possible?
https://www.stockopedia.com/co...
My model up-dated.
BSV
Heiq (LON:HEIQ) update today looks rather skimpy. A great shame that they appeared on Mello last night rather than next time, as there would have been lots of questions asking them to flesh it out a bit. On back of last 2 Mello presentations management appear sound, and they operate in great business segments. I hold.
Agreed. Maybe as a new company they will get better at communicating. An update on cash would have been helpful.
My morning smallcap tweet:
Omega Diagnostics (LON:ODX) SimplyBiz (LON:SBIZ) Ideagen (LON:IDEA) City Pub (LON:CPC) Itaconix (LON:ITX) TP (LON:TPG) Yu (LON:YU.) Anpario (LON:ANP) XLMedia (LON:XLM) Zoo Digital (LON:ZOO) Getech (LON:GTC) Flowtech Fluidpower (LON:FLO) Personal Group (LON:PGH) Heiq (LON:HEIQ) Eagle Eye Solutions (LON:EYE), Abingdon Health (LON:ABDX), Centaur Media (LON:CAU)
Omega Diagnostics (ODX) launches covid antibody lab-based testing service. [SP=78 Cap=140m]
SimplyBiz (SBIZ) guides FY(Dec) rev £61m down £2m, adj EPS marginally above 11p ie in line. Final div will be 2p. [SP=180 Cap=174m]
Ideagen (IDEA) exec chmn and founder David Hornsby, to retire in May. He will be a very hard act to follow. [SP=286 Cap=721m]
City Pub Group (CPC) guides FY(Dec) rev down 57%. Ample liquidity into 2022. [SP=96 Cap=101m]
Itaconix (ITX) guides FY(Dec) rev and EBITDA slightly ahead of market expectations. [SP=6.06 Cap=26m]
TP Group (TPG) guides FY(Dec) rev flat at c. £58m and adj op profit c.£3.8m (£5.9m). Q4 'robust'. Order book £69.0m (£63.8m). [SP=6.92 Cap=54m]
Yü (YU.) expects to exceed FY(Dec) revenue, cash and profit market expectations. Also mgmt expectations for FY21 are now ahead of previous levels. "Legacy contracts have now completely 'washed out' of our book and have been replaced by good margin, high quality, segmentally diverse business." [SP=128.11 Cap=21m]
Anpario (ANP) guides FY(Dec) rev at least £30m and profit to be well ahead of expectations. "There were strong performances in the Americas, Europe and in China where sales showed a strong recovery as farmers restocked their pig operations and the ban on the use of anti-biotic growth promoters (AGPs) in animal feed benefited sales of Orego-Stim. The Middle East experienced continued weakness in the second half." [SP=600 Cap=139m]
XLMedia (XLM) guides FY(Dec) rev $54.5m down 32% but only gives a 20H1 comparative to make it look better. Adj EBITDA $11.5m. "We have now completed the core development work on all the rebuilt [casino] sites we will take forward and have commenced the submission process to Google for reconsideration." [SP=35.5 Cap=69m]
Zoo Digital (ZOO) guides FY(Mar) rev at least $38m ($29.8m) with H2 up 35% on H1, ahead of market expectations. SP up 47% in last two weeks, so who knew? [SP=91.55 Cap=68m]
GETECH (GTC) exclusive strategic partnership with H2 Green which is "focused on establishing a network of large-scale hydrogen generation, storage and refuelling hubs to support public and commercial transport fleets." GTC to help locate the hubs. Option to acquire H2 Green for up to £1m. GTC and H2 Green to also collaborate on new product ideas and optimisation services. [SP=13.98 Cap=5m]. I hold.
Flowtech Fluidpower (FLO) guides FY20 rev down 15%, thinks it's a modest increase in market share. Expects a small underlying profit. [SP=107.5 Cap=66m]
Personal Group (PGH) guides FY(Dec) rev £70m, broadly in line with FY19, and adjusted EBITDA at least £9.5m (£11.0m), down due to product mix. "With further Government lockdowns ongoing, 2021 is expected to see a more significant financial impact on both income and profit as the ongoing restrictions reduce the ability to write new insurance sales and the historic impact from 2020 flows through." [SP=211.45 Cap=66m]
HeiQ (HEIQ) guides FY(Dec) above market expectations. Cites particularly strong sales of antimicrobial technology HeiQ Viroblock. Guides op profit only in line due to record levels of investment. [SP=237 Cap=298m]
Eagle Eye Solutions (EYE) guides H1(Dec) rev up 8% and adj EBITDA up 62%. Net cash £0.1m, ahead of mgmt exp. Guides FY in line. [SP=445 Cap=115m]
In line: Abingdon Health (LON:ABDX) Centaur Media (LON:CAU)
Mr Contrarian, Sir, re GETECH (GTC), I tip my hat to your prescience.
I read your column, thought about the above, studied the news, (love that market - such a future)
and I bought.
Many thanks.
Paul, Would you have time to take a look at Centaur Media (LON:CAU)? The much respected managers of Gresham House Strategic bought a stake in it last year in support of the board's plans for the reconstruction of the company's business model.