Small Cap Value Report (Tue 29 Nov 2022) - SFE, ALT, REC, SUP, GBG, VP.

Good morning from Paul & Graham!
13.55. This report is now finished. Thank you for the comments and the feedback as always!
Agenda
Graham's Section:
Safestyle UK (LON:SFE) (£34m) - a profit warning from this double glazing company. October orders were too low, and November orders were too high! The November orders have helped to boost the order book to a very high low, but also have the effect of increasing costs without generating any revenues for the current year (FY 2022). Therefore, FY 2022 is now set to produce a loss. Estimates are slashed for the current year and despite the increased order book, both revenue and profit forecasts for next year have been cut, too. This company always seems to have problems and while it could make for an entertaining bet on the economy, I don’t see it as a stock that’s suitable for holding long-term.
Altitude (LON:ALT) (£23m) - interim results are in from this platform that provides services to suppliers and distributors of promotional products. We already had a trading update last week so there are few surprises in here, but it’s good to see confirmation that the company is trading close to breakeven and still has a net cash position, plus a small borrowing facility giving it some headroom. While the stock got overheated in 2019, the market might not be giving it enough credit now for its reasonable financial performance and the possibility of operational leverage in the years ahead.
Record (LON:REC) (£173m) - excellent interim results from this currency specialist. Performance fees are back, boosting the bottom line, and management fees are up too thanks to eighteen months of strong net inflows. The inflows aren’t showing up in AUME (“assets under management equivalent”) yet, due to negative market movements. But customers are clearly happy, as they continue to sign up for Record’s services. The company, and I, are excited to see what it can achieve with fund management and other currency-related products. To that end, a new fund has been launched in Luxembourg. The shares still don’t strike me as expensive even after recent strength.
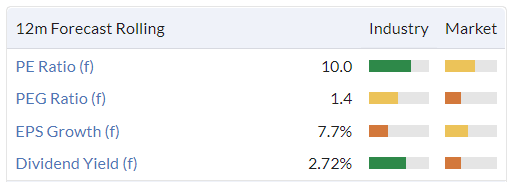
Supreme (LON:SUP) (£120m) - I attempt to make sense of the interim results at this fast-moving consumer goods business. The lighting division has seen its performance collapse due to retailer destocking and the revenue performance is only saved by strong growth in vaping. The company is confidently raising expectations for the full-year despite poor profitability in H1. Looking further ahead, there is no change to earnings expectations for FY 2024. It’s a really mixed bag and I’m left scratching my head: my instincts say that this business deserves to trade on a modest earnings multiple and I can only assume that the market is about right, pricing it on a PE ratio of 10x. In this uncertain economic climate, an improved balance sheet probably makes more sense for it than chunky shareholder dividends.
GB (LON:GBG) (£850m) (-4%) [no section below] - this stock is rarely covered in the SCVR, since it’s more of a mid-cap than a small-cap! In 2018, I noted a valuation multiple of nearly 40x and suggested that it was prohibitively expensive. The share price is down by one third since then, and valuation is more interesting at 16x earnings. Today’s results show a 3.4% growth in adjusted revenues at constant currencies, and a 1% increase in adjusted operating profit to £28m. The statutory numbers are much worse, however: operating profit falls to just £2.5m, largely due to the amortisation of acquired intangibles. The adjustments made by this company to its statutory numbers are both large and numerous.
More positively, the outlook statement tells us that H2 has started in line with expectations, and there is no change to forecasts. Net debt currently sits at around £118m. This is a large and reputable business providing advanced digital intelligence services to some of the world’s biggest businesses. However, there are many different moving parts to understand, and I perceive it as a black box type of investment. It is in my “too difficult” tray at this time. The StockRanks are also unconvinced, only awarding it a score of 26. [no section below]
VP (LON:VP.) (£277m) (+3%) [no section below] - this equipment rental group provides a wide range of products to sectors such as construction, engineering, rail, and oil & gas. Today’s interim results show revenue growth of 6% to £186.5m, adjusted PBT also +6% to £21.5m, and a return on capital employed of 14.4%. It’s reassuring to see ROIC listed so prominently at the top of the statement, to see it coming in at a very acceptable level, and to see that it has improved compared to last year! Statutory PBT comes out at £17.9m, so the level of earnings adjustment is modest.
Inflation has affected everything from transport to wages, and is being “actively managed”. I expect that VP should be able to pass on costs without too much difficulty or too much of a lag. Trading is in line with expectations. Net debt is currently around £149m: the company issued two private loans (total value £93m) to PGIM, maturing in January 2027. It also has a £90m RCF maturing in June 2024, and this will involve a floating interest rate. There are economic risks here that lie beyond VP’s control; arguably these have been priced in at a PE ratio of 8x and a yield of 6%, for what appears to be a successful and diversified rental business. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Safestyle UK (LON:SFE)
- Share price: 24.3p (-21%)
- Market cap: £34m
A profit warning from this “leading UK focused retailer and manufacturer of PVCu replacement windows and doors for the homeowner market”.
Orders in late September/early October were 7.6% below expectations, and 2.7% below the prior year. The costs of winning this business were higher than expected, too.
Why was trading so poor?
The Board attributes this to the well-reported political and economic news and events that have had a direct, adverse impact on consumer confidence.
Things picked up in November: order intake returned to expected levels (+30% year-on-year) and lead generation costs also returned to normal.
But since there is a lag between order intake and revenue generation, the November orders aren’t going to result in any revenues for FY 2022. In fact, the November orders only serve to increase costs for FY 2022.
Overall, therefore, these trends “will significantly impact FY 2022 profitability”. The only bright spot is an order book “that will close the year significantly ahead of our original expectations”.
Operational update: Safestyle is switching suppliers of PVCu profile, causing a small, temporary impact on manufacturing capacity. This will be completed by the end of the year. Installation capacity is unchanged.
Borrowing facility: new agreement in principle for a £7.5m replacement RCF with its existing lender Aurelius (not a mainstream lender).
Outlook: pre-tax profit for FY 2022 will be materially below expectations. Net cash will be lower than expected at c. £9m.
Looking ahead into 2023, there remains limited visibility on the strength of demand for next year, but the Board expects that the market will continue to be sensitive to negative sentiment. The Board reiterates that demand levels have improved recently and points to the fact that the Group operates in what has historically been a resilient and consistently-performing category despite previous challenging macroeconomic conditions.
Forecasts: the company’s broker has reduced the operating profit forecast for the current year from £2.1m to a loss of £3.4m. It has also reduced next year’s operating profit forecast from £10.1m to £4.6m, on reduced revenues.
My view
This company, in my experience, always seems to have problems.
A few of the challenges faced by the company, off the top of my head:
- Staff leaving to set up / join competitors.
- Cyber attack.
- Hot temperatures.
- Extremely sensitive to economic sentiment.
Today, we’ve learned that orders which arrive too late in the financial year have the effect of pushing up costs without generating any revenue: yet another factor affecting short-term profitability.
At least it is not currently using its borrowing facility, which would increase the risk profile considerably. Lender Aurelius says that it serves companies “who are unable to access the mainstream banking market for some or all of their capital requirements”.
I view this business as extremely high-risk and would certainly put it on a single-digit earnings multiple against the earnings that it makes in a “good” year. Possibly a low single-digit multiple.
The market had already priced it cheaply though, as it turns out, not cheaply enough:
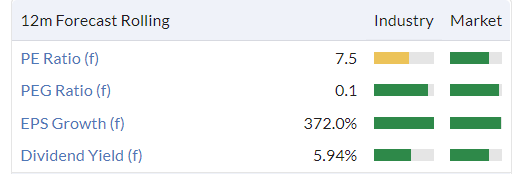
Since the stock is so sensitive to economic sentiment, it might be attractive to those with strong views on the economic outlook. But it’s not, in my opinion, something that can be a buy-and-hold candidate.
Altitude (LON:ALT)
- Share price: 32p (-6.6%)
- Market cap: £23m
I’ve taken a renewed interest in this stock lately: could it become a valuable “platform” business? A marketplace where buyers, suppliers and distributors of promotional products come together, generating valuable commissions for Altitude?
Company description:
Altitude is a technology company and has developed an industry specific marketplace which provides various design tools, applications, and web site pop-up stores for promotional product distributors and suppliers. We have developed a robust e-commerce enabled and scalable trading platform that facilitates the execution of both offline and online promotional product transactions.
The website for Altitude’s operating business, “AIM” (not the stock exchange) can be found here. Distributor membership at AIM has increased to 2,425 (last year: 2,200).
It has two revenue streams: “Services” (designed to help other companies sell their products) and “Merchanting” (sales made by Altitude itself, using affiliates).
Bullet points for today’s interim results:
- Revenues +29% to £7.7m
- Within this figure, “services” are up 36.5%, while “merchanting” is up 23%.
- Gross profit +39.5% to £3.9m
- Adj. operating profit increases from £0.5m to £0.76m.
In H1 last year, the company received an employee retention credit worth £0.5m. This was included in the “adjusted” numbers last year, even though it was clearly not going to be a permanent source of income.
If we deduct that item from last year’s result, we could argue that adj. operating profit has really moved from zero to £0.76m.
The elephant in the room, however, is currencies. This is predominantly a US business, and I think we need to see figures in dollars to fully understand what is happening (a point well made by mojomogoz in the comments). Perhaps the company should simply stop reporting in pounds and report in dollars instead?
Profits and cash flow: the statutory pre-tax loss is only £0.1m (last year: £0.4m). The total net cash outflow is just £0.2m. It’s comforting to see the company so close to breakeven but it would also be nice to see a bigger cash pile: balance sheet cash is just £800k. Additional headroom is provided by a £700k credit facility.
Outlook: no change to outlook (we already had a trading update last week, saying that the company was on track to meet expectations).
My view: I remain intrigued by the possibilities here. It’s certainly at the speculative end of the spectrum, but I’m encouraged by the decent revenue growth, the fact that it’s already trading around breakeven, and the possibility that operational leverage could kick in at some point.
The £23m market cap gives a P/S multiple of less than 1x if we use the FY March 2024 revenue forecast of £23.7m.
It’s not so easy to kick the tires when there’s a (mostly) US business, listed in the UK. So perhaps it deserves to trade at a discount, especially given the lack of clarity around its results at constant exchange rates. But I still think this share has plenty of potential at this market cap: it was overvalued in 2019, but it could be undervalued here.
Record (LON:REC)
- Share price: 87.3p (+8%)
- Market cap: £173m
This is a currency specialist where I’m a former shareholder.
Back in June, I noted that the company was branching out into fund management, after many years of suffering price erosion in currency services. Today, it announces interim results for the six months to September 2022.
Key points:
- Revenues +35% to £22.1m
- PBT +46% to £7.5m
- Assets under management equivalent falls slightly to $80.8 billion
- Operating profit margin 34%
I’ve been a fan of this company over the years due to its excellent cash generation, strong balance sheet, and high returns:
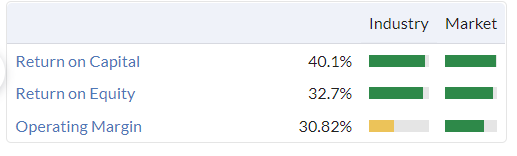
I eventually sold out due to a lack of growth, especially in its high-margin services.
But in good news for shareholders, it appears to have gained a second wind:
- Management fees and performance fees are up, with “strong performance across all product strands”. Performance fees of £2.8m (last year: £0.5m) are a big boost to the bottom line, but are hard to predict.
- Diversification into “higher revenue and more scalable products”.
- A licence to operate in Germany has been granted, and a range of funds have been launched in Luxembourg.
CEO statement - excerpt
Record is known as a traditional currency manager, and has built its reputation in that area. Therefore, while it is more interested in other higher-margin activities in future, it doesn’t want to leave its past completely high behind:
While a lot of our future growth might come from products other than pure currency, traditional currency products are and will remain a cornerstone of our brand and our reputation. Promisingly, we are seeing some growth in our traditional business and expect this to continue whilst mindful these are at lower fee rates than other areas of focus… While we are devoted to diversification as a source of growth and improved margins, we would not want our investors or stakeholders to forget our currency roots.
Fund management work “is starting to bear fruit and will begin to have a bigger impact on our bottom line in the coming year”. Record now has a team based in Zurich, Amsterdam and Dusseldorf.
Venture capital: Record has started investing in VC funds and even directly into start-up and early-stage companies. I’m not sure what to make of this - do they have the skillset to pull this off? I don’t know. They do have lots of spare cash but maybe they should give it back to shareholders instead of using it for VC investments?
The strategy is now a bit of everything:
It is crucial to remember that all the elements above are part of a plan to diversify Record and make us a meaningful asset management business, fit for the next generation, and well balanced between opportunity, risk and return. No single revenue line is ever intended to dominate, and we are always very much aware of the Board's measured approach to risk appetite in everything we do.
Market review - I recommend reading this section, if you want to see what currency experts think of recent macro developments.
AUME - it’s worth noting that while assets under management equivalent declined 2.8% in dollars, they rose 14.6% when measured in GBP. The company enjoyed net inflows of $8.6 billion.
This table demonstrates that market movements are responsible for the decline in AUME:

Over the last six quarters, Record has enjoyed net inflows of $11 billion to AUME. That’s a huge thumbs up from customers, even if there hasn’t been any progress in AUME. But the inflows do show up in increased management fees.
Costs are up 33%, with generous movements in personnel costs.
Also note that between 25% and 35% of operating profit (before bonuses) gets paid out in the form of a staff bonus. 33% of pre-Bonus operating profit was paid out in H1.
The company still earns very healthy margins for shareholders, so everybody is a winner.
Interim dividend increases to 2.05p (the final dividend and the interim dividend are usually the same). After today's share price increase, the yield here is probably around 5%.
My view
I have some regrets about not holding onto this share, but it was difficult to keep holding when it seemed to be making very little progress for quite a long time!
Under its reinvigorated strategy, I continue to think that prospects remain bright. What I’m really excited about is to see an increase in its fund management income, which I think could turn it into a very high-quality financial stock. The company's funds are still in their infancy, and so some more patience is required on that front.
I’m less enthused about the VC investments, and I’d like it if they decided to focus on 2-3 activities instead of trying to do too many things at once.
But I still don’t think these shares are expensive:

Remember that the founder Neil Record is still the Chairman and the largest shareholder (28%). With this stewardship at the top, I anticipate that it will keep doing well.
Supreme (LON:SUP)
- Share price: 103p (-5%)
- Market cap: £120m
This is “Europe’s leading manufacturer, brand owner and distributor of fast-moving staple products”. Among many other things, they own 88Vape.
Today’s interim results show a “credible trading performance”, in the words of the CEO.
Revenues are up 6% to £64.6m, within which there is a 47% increase in vaping (both organic and acquisition growth).
- Gross margin falls from 30% to 28% (we should not expect high margins on these products).
- Adj. PBT down 31% to £5.8m
- Actual PBT down 48% to £4.4m
- Net debt more than doubles to almost £20m
The lighting category appears to have been a disaster: revenues more than halved, “in line with the slowdown across the market”. I knew that the market for lightbulbs was volatile, but this takes the biscuit!
Gross profits in this category are down by 58%, as retailers unwind the overstocking they did over the past two years.
Dividend: the company declares an interim dividend of 0.8p. This looks like a very big cut compared to last year’s equivalent, although they don’t explicitly state this. They do say that their new policy is to pay out 25% of after-tax profits.
Debt: the company has a £25m RCF with HSBC, from which it has borrowed around £18m. The net debt to EBITDA multiple is around 1x, which is traditionally considered to be a modest leverage multiple.
Outlook
Positive start to H2 2023, with trading now ahead of market expectations for FY 2023
Vaping category expected to deliver a robust performance in H2 2023, reflecting positive impact of both organic and acquisitive growth
The business continues to navigate global trading challenges arising from raw material cost price increases, and inflationary increases to its overhead base
The company has been buying forward whey, to control the costs of its protein products, as an example of what it’s been doing to manage risk during a time of high inflation.
Investor presentation: Equity Development are hosting a presentation to investors today at 3pm: see here.
My view: I don’t have a strong view on this stock as it’s not one that I’ve studied in detail before.
Some of the key features are:
- Modest profit margins (goes with the territory)
- These margins are under pressure, as you might expect for a consumer-facing business during a cost-of-living crisis.
- My sense is that its brands probably do have good consumer awareness and recognition, but only very limited pricing power. They are very much in the “staple” category.
Given the volatility of demand in some categories, especially lighting, and the economic environment, perhaps it could have cancelled its dividend entirely, to ensure that its balance sheet is safe?
It’s also curious that the company is raising expectations for FY March 2023, and yet the share price is down today. I note that the analysts at Equity Development haven’t raised their outlook for FY 2024.
Overall, my instincts say that this stock should trade at cheap levels - perhaps the pricing is about right currently?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Graham - thanks for your write-up on Supreme (LON:SUP)
I hold and have followed this for some time so perhaps I may elaborate on one point:
"The lighting category appears to have been a disaster". It is important to understand the nature of this. Supreme hold exclusive licences for Eveready , JCB and Energiser. This means that apart from supplying small retailers from their own warehouse they supply the big boys by the containerload. They simply order from China and the container goes directly to the customer so profits go straight to the bottom line. It is no wonder that these customers stocked up in the period of uncertainty of getting containers from China to the UK (and then through the Tilbury bottleneck) and equally no surprise that now that has eased they are destocking. A good example of a big customer here is B+Q stocking 74 different Energiser bulbs: https://www.diy.com/search?ter...
In the last presentation there was a 14 minute section on lighting starting 7m 16s in here:
Much of this company depends on the entrepreneurial nature of Sandy Chadha, CEO and 57% shareholder. Watch this afternoon's presentation and form your own judgement!
£Vp. "The strong get stronger" (new research note on Vp plc) *** Today the company posted a “solid” set of H1’23 results, that was also in line with our FY’23 adjusted EBIT forecast of £45.75m. H1 sales rose +5.9% to £186.5m (vs £176.1m LY) - which alongside measured prices increases and internal efficiencies - drove ROCE up to 14.4% vs 13.5% LY, despite absorbing further input cost inflation.
Likewise, H1 adjusted PBT came in +6% higher at £21.5m (£20.2m LY), even after incurring higher interest charges, as net debt climbed 13% to £148.9m due to slightly longer debtor days and top line growth.
We also think that the UK construction market is now recovering on the back of a substantial backlog of future infrastructure work, especially in regulated areas such as roads, rail (CP6), water (AMP7) and electricity. And remember that Vp isn’t just a domestic group: TR (Australia) has returned to pre covid levels, whilst Airpac Rentals has benefitted from increased oil and gas demand and is diversifying into more downstream areas.
Vp trades on modest CY EV/EBITDA and EV/EBIT multiples of 4.5x and 9.0x respectively. Falling to 4.3x and 8.3x in the following year vs typical peer ratings of 6.0x & 10.4x. We reiterate our headline FY23 numbers and retained fair value of £11.30/share. Link to note: https://www.equitydevelopment....
I agree Edmonda VP (LON:VP.) looks good, with rentals into a number of different sectors de-risking this investment somewhat, and has gone onto my watch list. Nice margins being maintained they report by offsetting cost increases. RNS read well.
Construction is starting to look cheap but we are early in the recovery cycle I guess, so I'm holding out for a few months yet, as perhaps more value will come? I'm back up the food chain a little into mining for now.
Time will Tell
Not relevant to today discussion but it maybe of interest nevertheless: At the Mello (16-17 November) Graham reviewed a few undervalued companies which so far have proved spot on!
TTG. 151
MEGP. 103
IG DESIGN. 110
JUP 119
DISNEY. 95
Each of the above companies are undervalued for what appears to be good reasons. Graham argued that they are worth a punt!
Hi Paul and Graham, Have you got any thoughts on RE.? REA Holdings was one of Edwards 2022 NAPS - its now more than 44% down but the information in the company reports is very encouraging. Do you have any thoughts? I still hold RE. Thanks Pat
R E A Holdings (LON:RE.)
FWIW, and please ignore if your fully up to speed Pat.
Don't forget to look at Crude Palm Oil prices (Large Chart is last 12 months, small chart historic), which will tie quiet heavily into this companies SP, and from memory there has also been poor weather and export bans with a couple of these companies to add to the mix, that's without delving into this individual companies financial situation, which I no nothing of I'm afraid, some business in coal and stone, but at what levels I am unsure - at a decent mix could offset some price loss in Palm Oil?
Current Palm Oil Price has come up a bit of late to mid 2021 levels, but almost halved from its peak in Feb which was around the time of Russia's invasion.
I cant tell you where palm oil price is going I'm afraid as other than a passing interest, detail on individual commodities is not my thing.
All the Best
Paul
This is really helpful. Thanks
I would love to hear Graham's thoughts on Records progress. It is a company I have held for a few years now. I love the divi and the balance sheet. I also like that Neil Record is a significant holder. The CEO is an impressive lady. They have a growth story given they are trying to move from Exchange hedging into full fund management. Fixed Interest is a particular area of interest which is probably the area to be at present and therefore should give a filip to Record. They have good relationships in the industry having built it over many years. It looks a really nice developing story to me. They have an investor meeting at 9.30am tomorrow if anyone is interested. Investor Meet Company - Home
Hi Camtab, Record is covered now. Thanks for the comment. Wish I still held it, but can't hold everything! G
hi Graham
re Record (LON:REC) - I hold
Thanks for your summary. Whilst I share your positive thoughts, especially the progress in the higher margin asset management strategies, I do see some real risks here.
The new additional strategy of investing in venture capital is something of a surprise and I share your doubts as to whether they have the skill set to do this successfully. Funding is to come from unutilised spare cash which presumably spells the end of special dividends.
Also regarding the increased staff headcount, the high level of bonus payments at 33% of profits and the introduction of a new LTIP scheme (no details yet) all seem to point to staff rewards being of higher priority than shareholder returns. I know this is a sector wide issue but it does give some cause for thought.
At your last review in June I raised the issue of Executive rewards...............
The CEO, Leslie Hill received total remuneration of £2.395m (£724k fixed, £1.671m variable) whilst the CFO, Steve Cullen, received £258k (£153k fixed, £105k variable). So the CEO's total remuneration was a multiple of 9.3 times the CFO's. I find this quite staggering.
I wonder what the CFO thinks of this and what effect it might have on their working relationship?
In the company's defence the Remuneration Committee Chair states;
'The Group is in a three-year transitional phase where the current senior managers prepare to hand over to the next generation under our succession plans'
and
'To deliver the Group's three-year strategy, the Board believes that it is imperative that our current CEO, Leslie Hill, continues to drive this strategy. Our new Remuneration Policy for our CEO has therefore been designed to ensure that she is motivated and incentivised to deliver this three‑year
strategy'
Although Leslie Hill does appear to be doing a good job in this transitional phase the huge imbalance in total remuneration between CEO and CFO seems way out of kilter to me. I'd very much appreciate your views please.
Have you had an opportunity to consider this further?
regards
Snazzy
Snazzy, thanks for the input. I must admit that I've not studied the pay issue in detail at Record, so I appreciate you giving us some of the figures here.
If I had to defend the company, I would say that it does continue to earn very high profit margins for shareholders, even after increasing personnel costs. It is fundamentally a people business, and a financial business, and that is going to be reflected in salaries at the top.
Clearly, Neil Record thinks that Leslie Hall is "worth it"; she has been there for 30 years and could probably choose to retire now, if she was that way inclined. Mr. Record obviously wants her there and is happy for her to be handsomely rewarded. He owns more shares than anyone else and to be honest, I would be inclined to defer to his view on this.
Of course if the profit numbers went in reverse, I would hope and expect personnel costs to get trimmed. There is a risk that the fund management initiatives won't work out, and a very obvious risk that the VC deals will turn out to have been a waste of shareholders' funds. It would be good to see the detail on the LTIP.
Best regards
Graham
Many thanks Graham. I do find your insights extremely useful.
Looking at the VC funds and companies they name in their report - they're all in the crypto space, they had no need to go there.
Anyone know why LON:AVON is down by 10%+? I cant see any investor news - RNS or Co site, volumes don't look that exceptional, cant even find much on the share chat front. Also ex dividend is not a factor. Results were out last week so maybe a latent reaction but even they weren't terrible IMO (revenue up profit down).
Hi Berksbee
REf Avon Protection (LON:AVON) share price fall today ...... I have just spotted this snippet from Sharecast ........
Avon Protection was under the cosh on Tuesday after a share placing.
According to traders, JPMorgan placed 1.8m shares for an undisclosed institutional seller at between 1,061p and 1,100p.
At 1110 GMT, the shares were down 12% at 1,036p.
Avon specialises in the engineering and manufacturing of respiratory protection equipment for military, law enforcement and fire personnel.
I hold sadly (but not too much).
Regards
Howard
Thanks Howard. I also hold and am happy to. A lot of upside from here IMO but maybe not everyone agrees. That said there can be all sorts of reasons for an undisclosed institutional sell. Guess the SP will be subdued until the full amount is sold as it is more than 5% of the market cap!
Hi Berksbee
Yes I agree I used the dip to add to the cost pound averaging stance I am taking with Avon Protection (LON:AVON) as I think some factors are pushing it in favourable direction are falling into place.
Regards
Howard
I've just had a quick skim of the Safestyle UK (LON:SFE) trading update, and my word - there's quite a bunch of red flags on weak management, IMO.
- Switching to new supplier, disruptions. Surely they should have planned and flagged in advance
- Lots of "bad luck" events, but maybe that shows management isn't that resilient? All companies get a whole bunch of headwinds, but they mitigate them well and deal with it. Cyber attack, factory too hot (maybe will be too cold this winter?), flip-flopping consumer demand, consumer acquisition costs out of its control.
- RCF renewed - but why with an unknown name? Surely if they were solid for the credit, they could get from a regular high street bank? I note that Aurelius has been giving them an RCF from 2018, when their share price plummeted - were they the lenders of last resort during a crisis back then? This is the first time I've looked at SFE.
The silver lining is that they have net cash, and they also have a good order book that should unwind in the next few months. The new supplier, presume it offers them some advantage - better product or higher margins? So there might be some positives to come in the very short term, which will be a catalyst for re-rating.
Also I strongly believe that as people start seeing bill shock from their winter energy bills, which will be in the Dec-Feb period, householders might clamour to make their homes more energy efficient. For example, replacing old drafty windows with new PVC double glazing. In addition, landlords are being pressured to up either EPCs to Grade C or higher by 2024/2025? Which should also drive some window replacement volumes. Food for thought.
I know the infastructure and it's associated maintenance might be dull but Renew Holdings (LON:RNWH) keeps moving ahead with it's model, operating in all areas of infrastructure maintenance. With net cash excluding leases and a receptive government spending programme it can move forward hoovering up small acquisitions along the way. Dull and not expensive, this company seems to be in a sweet spot just now and largely unappreciated.
Would Paul or Graham care to comment today's FY record results
I hold
Good summary, Steves cups, and I would also be interested in discussion on Renew Holdings (LON:RNWH) as it is on my watchlist. I have held it in the past and would like to get back in at a decent price - I am reliant on Stocko metrics for that (still working through 'Accounts Demystified'), so would be glad to have someone who understands accounts take a look. There's a pension question they seem happy that they have resolved.
Thanks Indie - sorry about the SP move but
WOW the SP on RNWH have really shot up since i first read the RNS this am. It was about 3.3%: now over 7% up. More late risers like me now appreciative or just following momentum
EDIT
Must have been a Stocko aberration not 7% just as stated 3% ish
Ah well, you snooze you lose. I’m still watching it.
Very happy for them.
Treatt (LON:TET) revenue up but profits down.
How about a look at GB (LON:GBG)?
Highly regarded tech firm on a (for tech) GARP-y valuation which has just come down to SCVR size after a takeover - at twice the price - fell through while earnings have hit a recessionary roadblock. Levered to e-commerce growth and in the attractive and legally-mandated field of fraud prevention, revenues are well diversified globally. I like the long term prospects here and I know there are other holders. Valuation is not demanding at a FCF yield of 6x.
Would be grateful if you've got time to look at GB (LON:GBG) please gents. Has taken on some debt for acquisitions at the same time as Crypto customer verification work has dried up. The market understandably doesn't seem happy with this double whammy but the company supports many blue chip clients in what is arguably a critically necessary area nowerdays.
Would be grateful if you've got time to look at GB (LON:GBG) please gents. Has taken on some debt for acquisitions at the same time as Crypto customer verification work has dried up. The market understandably doesn't seem happy with this double whammy but the company supports many blue chip clients in what is arguably a critically necessary area nowerdays.
I admit I'd never looked at GB (LON:GBG) before and now I can see why. If the technology is so great, I don't understand why the ROCE and other profitability metrics are so poor for a software company? At first glance, that looks like a company in a crowded market with no significant edge over the competition. Thanks for bringing it up. I will dig a little deeper but an initial scan of the SR does not exactly fill me with hope, especially when you take into account the share dilution over the years.
All the best, Si
GB (LON:GBG)
I think you’re jumping the gun with your assumptions. The name isn’t a software company in the manner of Adobe or Intuit. Its revenues are more usage-based, like a PayPal. And payment companies are experiencing tough markets in 2022. As for having no edge, Liberum likes “GBG because it is the pure-play leader in ID verification, a good growth market, supported by regulation (AML, KYC), the growth of digital interactions in society and shift from physical to on-line crime (US ID theft doubled in 2Y)”
I think you’re jumping the gun with your assumptions. The name isn’t a software company in the manner of Adobe or Intuit. Its revenues are more usage-based, like a PayPal. And payment companies are experiencing tough markets in 2022. As for having no edge, Liberum likes “GBG because it is the pure-play leader in ID verification, a good growth market, supported by regulation (AML, KYC), the growth of digital interactions in society and shift from physical to on-line crime (US ID theft doubled in 2Y)”
To be fair, I made it quite clear I didn't know the company, so jumping the gun is entirely possible. However, half an hour digging around reading RNS and the company website has not really changed my opinion and it's easy to see why it's never appeared on any of my quality screens. I just don't understand why ROCE and margins are so poor for a technology company that is a "pure-play leader" in a growth industry? There seem to be a few companies in this area (ID & Verification), including Experian (LON:EXPN) which seems an all together better longer term bet, although it not a pure play on the sector.
Good luck with it anyway. Si
Good to have some discussion on the name. I certainly agree on the ROCE disappointments but FCF growth has been strong for a decade. I suspect this challenging year is a victim of pandemic liquidity withdrawal and expect GB (LON:GBG) to resume growth on the back of its attractive markets. And I would not be surprised by another bid in due course, perhaps even from an Experian (LON:EXPN). Then again, who knows?
GB (LON:GBG)
I just don't understand why ROCE and margins are so poor for a technology company that is a "pure-play leader" in a growth industry?
Digging into the numbers and adjusting for cash and provisions gives an average return on operating capital around 30% for the last decade. Admittedly the trend is downwards but that’s hardly shabby and certainly well clear of the cost of capital. Gross and operating margins have both expanded by large increments over the same period and sit at respectable levels of 71% and 25%. Are we looking at the same numbers?
Perhaps the yo-yo-ing price action today encapsulates the divergence of possible views!
Digging into the numbers and adjusting for cash and provisions gives an average return on operating capital around 30% for the last decade. Admittedly the trend is downwards but that’s hardly shabby and certainly well clear of the cost of capital. Gross and operating margins have both expanded by large increments over the same period and sit at respectable levels of 71% and 25%. Are we looking at the same numbers?
I was looking at the StockReport ROCE numbers for FY17-22. It really depends on your feelings about the EBIT adjustments, as ever. I'm really quite conservative when it comes to such things, as I presume is Stocko. For instance, of the £28m adjusted EBIT reported today, £2.7m is share based payments and a rather large £21.3m in amortisation. Without these adjustments, reported EBIT was a meagre £2.5m. ROCE and EBIT Margin numbers are reliant on how you want to treat the EBIT adjustments. As I said, good luck with it; doesn't float my boat and so I no longer wish to discuss this company.
All the best, Si
GB (LON:GBG)
GB Group PLC
Thanks for flagging up BnB - not particulalry a company i have loked at in detail before.
Certainly seems to have come crashing down in price - is there any growth here though ? - forecasts seem to have been dropping - growth seems all related to an acquisition and that acquisition doesnt seem to be performing too well (not a great start). I would accept that curent market conditions could be hiding underlying potential here - if they are blaming slowdown in crypto related business then i would say the near term outlook in that area must be bleak perhap? - did they buy acuant based on prospects that are turning out to be pants ?
Having said that even on current forecasts show that expected profits look pretty decent and its a decent sector to have exposure to so certainly would be nice to see some comments on the financials?
Is this potentially another uk company possibly failing when trying to conquer the all so difficult us market?
hmmm guessing this company may be ripe for a name change too?
I calculate Free Cash Flow for H1 FY23 to be £7.3m against full year FY23 analyst forecasts of £53.4m. Even after taking account of £8m working capital investment they seem off track for getting to 6x for the FY23.
Notably both Berenberg and Barclays have cut their price targets this morning from 850p to 515p and 700p to 570p respectively. A big cut but still significantly above the current share price which may be why the shares have recovered from being down 10% earlier today.
It's not clear if the target price cut was analysts catching up with multiple re-rating or, like me, they were disappointed with operating profit growth and cash generation.
Today's opening price of 350p was down from last weeks 365p to 385p price range so perhaps someone knew something. Then again it could simply be selling down following the recent takeover bid falling through.
Whilst management stated they were confident in the long term prospects of the business the outlook for H2 FY23 was, in my opinion, less inspiring:
"We expect to deliver mid-single digit pro forma constant currency revenue growth for the second half of the year, in-line with expectations".
Last year's growth benefit from crypto has gone and is expected to make up only 2% of H2 FY23 revenue.
Overall, for me, the prospects for future profit growth and cash generation are not obvious enough to continue to hold.
Re all the comments on GB (LON:GBG) the accounts are complex but it helps to watch the company's presentation here: https://www.gbgplc.com/en/inve... . There has clearly been negative impacts from declines in cryptocurrency and internet companies generally but I am not as negative as others about prospects. A lot of the issues are one-offs and judging a company on one half-years results is not wise in my view. I am a long-term holder and am likely to remain so.
A bit of travel and arrive from John Wood (LON:WG.)
Although today is disappointing on 2 levels - firstly they are cautious on costs and therefore margins going into 23. Secondly no buyback announcement. I’m pretty positive on the space but the shares had run hard into this statement. A note from JPM flagged a buyback announcement that hasn’t arrived. Rating isn’t demanding though so the reaction looks a little harsh to me although oil price was also weak yesterday….
I think it’s one to pick up in Q1 now … with their big day today and nothing further to hang on for but depends if it gets silly or not.
I've looked at Altitude (LON:ALT) in the past thinking something could be interesting. I've always struggled to unpick the business though and feel this comes from a lack of clarity in how they report and describe themselves (...I have assumed this is partly an unsureness from them on how best to proceed to success! Not a positive).
Anyway, in the above lack of clarity vein, I feel that these results are reported as high growth by not clearly and persistently splitting out the impact of large GBPUSD move. As an example, in the financial review they are only clear on currency impact on costs and how it inflates that...but not so clear on the beneficial inflation on revenue, profits and cf in that regard...selective!
More generally, they do a lot yet don't monetise as much as you'd think...I find it confusing! For example they report c.2500 bespoke online shops for customers. Why not more money made from all that? And why not tell us how much they make from this 'valuable' bespoke activity? I can't help but think its unprofitable scrabbling about to make more revenue...but not necessarily high quality.
They've also made a decent bit of noise re their move into direct 'merchanting'. TBH I had expected high revenue growth from this low margin activity and was disappointed by what they achieved - at nominal 22.8% (ie with the forex tailwind) this was a disappointment and seems that peddle to the metal didn't quite ignite acceleration. I had interpreted their past comments on merchanting to mean that we should see a real acceleration here but the result is meh....so we're back to whether they can really grow the services and tech they have been offering for a while as merchanting is so low margin it only works if they have a route to really accelerating sales.
Anyway, I'd welcome clarification from anyone that knows the biz better. My banalysis is only drive-by rather than targeted and knowledgeable.
I feel the company is still searching for pay dirt...
Altitude (LON:ALT) do say at constant currency growth was 26% so looks like roughly half of the 50% growth came from the FX effect.
They do also say that the affiliate agreements signed add an extra $5m p/a that wasn't recognised in the period too, which I guess is where the high growth/lower margin merchandising revenue expectations for the next year is coming from.
Never quite sure what to make of them. Intuitively I feel they are onto something but can't figure out whether the lack of expected execution to date was wholly related to covid setting them back 2 years. I'll be interested to see whether they can maintain positive trajectory
Snap
And yes re the 26%...but they clearly chose not to be as clear and useful as they could be with it.
Re the $5m (do they say its $6m later by the way!)...I don't feel that's clear either. They can't have contracted for $5m of sales either...its wrong wording surely? They have taken on 3rd party distributors who might sell $5m based on their pitch etc?! Maybe I'm too cynical on this one. I'm being biased to thinking its hype speech
probably pays to be sceptical.
they do say
"An additional c. $6 million in new expected annualised revenue within the Group's core Merchanting programmes,...."
so presumably the $5m from affiliates is most of this $6m and it is expected, rather than contracted ? Agree wording could be somewhat clearer. The whole text is a bit convoluted to me. I'd prefer it to be better set out and articulated.
I have a hunch though that this company is no longer just hype, but thats literally just my gut feel so Im not sure any attention whatsoever should be paid to that!! I'd like to see another round of higher than expected growth come through.
My guess is they themselves are not sure what really works and scales for them yet
Vertu Motors (LON:VTU)
The last time VTU got a mention here was on 1 November following the acquisition of 3 motor cycle dealerships.
On 9 Nov VTU issued an RNS saying they were in advanced discussions regarding another possible acquisition. This article in Car Dealer Magazine explains it in more detail.
https://cardealermagazine.co.uk/publish/vertu-motors-in-advanced-discussions-to-acquire-helston-garages/274369
Separately there is more about the parties involved here:
https://www.auto-retail.co.uk/agenda/helston-garages-to-be-split-and-sold-to-vertu-yeomans-and-rybrook/
The involvement of 3 parties is logical given the potential size of the target. Helston has quite a large number of dealerships and bodyshops and turned over £626m for a pt profit of £30.4m in 2021 If this proceeds it could be a very significant step up for VTU and is definitely worth keeping an eye on IMO. If anyone else is following this story, it would be good to hear what they know or believe.
I’ve added to my existing holding in view of the potential.
Paul and Graham I would be interested in your thoughts on Record (LON:REC) as the interim results look to be tracking well above the forecasts on stockopedia. All metrics look to be improved although expenses increasing presumably staff costs. I am a happy holder.
G
Hi greyster, yes, I'm planning to take a look at Record. G
£SUP - "H1'23 results buoyed by strong performance from Vaping" - link to full note & audio summary (free and accessible): https://www.equitydevelopment....
For the six months to 30 September, Supreme reported revenue growth of 6%YoY to £64.6m, EBITDA (adj.) of £8.1m, -19%YoY and PBT (adj.) of £5.8m, -31%YoY. Revenue was underpinned by 47%YoY growth in the Vaping division, with, notably, 31%YoY organic growth. Interim revenue was 5% ahead of our outlook and EBITDA (adj.) 4% below. The Group notes that trading in the Lighting division, which had negatively impacted the FY23 outlook, is now recovering; Supreme notes that improved overall revenue momentum indicates that full year Group performance should be ahead of prior market expectations.
Interim operating cashflow was £4.9m (H1 22, £4.2m), with (adj.) net debt of £14.6m and cash of £5.4m (FY22, £3.9m). Reflecting a policy of 25% net profit pay-out, the Board has proposed an Interim dividend of 0.8p/share (payable: 13.01.2023). We have raised our FY23 revenue outlook by 7% from £129.5m to £138.3m, based principally on strong organic growth in Vaping, and raised our FY23 EBITDA (adj.) outlook from by 6% to £18.5m. For FY24, we have raised our revenue forecast by 6% from £142.2m to £150.5m. However, given continued uncertainties for the impact of inflation on consumer demand, input costs and pricing, we have maintained our FY24 EBITDA outlook at £22.2m. Our estimates indicate a FY24 EV/EBITDA of 5.6x. Our Fair Value remains 190p/share.
I don't understand why Supreme (LON:SUP) don't just focus on vaping. The rest of the biz looks like low value distribution with likely volatility in demand?
Or does the vape business need the access and relationship that comes with these other product line relationships to keep the doors open enough (as vape is a competitive commoditised biz)
mojomogoz - I believe that Supreme (LON:SUP) services a lot of smaller chains and individual corner shops so all the products piggy back on each other. You will see that a small but useful £448k of gross profit comes from branded products (at low margin) - from Persil to Cadburys - https://www.supremeoffers.co.u...
If you want to find out more there is a presentation at 3 p.m - https://www.equitydevelopment....
Supreme (LON:SUP) made an error in forecasting on the lighting division misinterpreting the overstocking effect in lighting. But in the absence of that type of black swan pandemic event both lighting and batteries businesses are low vol. and have historically made decent and consistent margins.
Part of the value of Supreme (LON:SUP) in my view though is the access into supermarkets / smaller chains and independents. Once you have that access you can sell other items as a trusted partner, which they have done with sports nutrition.
worth a listen to the presentation later. CEO is a pretty straightforward guy
Hi Mojo,
Old school BCG matrix analysis of Supreme (LON:SUP) business would likely categorise the battery distribution business as a 'cash cow' generating steady dependable profits which can be used to invest in emerging areas (BCG question marks) such as their vitamin manufacturing. Whilst their 'star' sector vaping goes from strength to strength.
What really perplexes (annoys :-)) me is why they don't raise their prices significantly.
88vape costs around 99p, whilst their competitors charge more than double. The vitamins they manufacture sell for £5 / year supply. This is so low, I believe it puts a lot of customers off as they think they must be sub standard.
However, when I raised this point to management at a recent Q&A, they didn't seem grasp the issue which was a tad frustrating..
Interesting. I don't know Supreme (LON:SUP) well at all (it very remotely overlaps with a holding of mine UP Global Sourcing Holdings (LON:UPGS) and I feel disinclined to add overlapping risk...bar extreme pricing/opportunity). I will listen this afternoon.
I get the CEO is a good mover and hustler...I don't have a feel for why he's got a winning plan. Strange he doesn't see your point re price points. I'd assume he does but doesn't want to currently or can't with his current customer base or product offering
And if you only buy a brand once a year you probably won’t even remember where you bought it from!
Fully agree on pricing. Being cheaper than the competition has it's merits but too cheap puts buyers off and given today's figures with revenues up but profits down and keeping in mind every FMCG company with any sort of brand strength is putting up prices, they really should wake-up here. I'd like to see higher prices and dividend restored. Currently I hold but having second thoughts now. I feel this company has great potential which they are not making the most of. Will see how I feel after today's presentation before deciding next steps.
Well, I asked the question in today's investor presentation about prices and the CEO seems remarkably reluctant to put them up. He seems worried it would reduce demand. Hard to believe given where they are relative to competition. For comparison, Greggs sausage rolls are up 15% this year. I am sure Supreme 88vape could match and demand would hold up.
Diversification to reduce risk. What are they gonna do if vaping gets banned?
that's a hilarious comment. Vaping gets banned???....hmmm....that plays well into Governments attempts to switch people away from cigarette products. The far more likely scenario is that taxes increase on vaping products - the one thing about vice is that Governments like it because it generates outsized tax they can't get elsewhere.
There is one distribution channel for all products so it does make sense to me to have multiple categories, albeit vaping is the vast majority of gross margin at the moment.