Small Cap Value Report (Tue June 5 2018) - GHH, QUIZ, CAR, GBG, ALT, VNET

Morning all.
Many results statements are out this morning, plus a few AGM updates.
The most interesting ones for me are:
- Gooch & Housego (LON:GHH)
- QUIZ (LON:QUIZ)
- Carclo (LON:CAR)
- GB (LON:GBG)
- Altitude (LON:ALT)
- Vianet (LON:VNET)
3pm edit: Substituted Vianet into the list, in response to reader requests. Cheers!
Graham
Gooch & Housego (LON:GHH)
- Share price: 1367.5p (+2%)
- No. of shares: 24.5 million
- Market cap: £335 million
This is a high-quality AIM stock which I haven't been paying enough attention to in the last couple of years. It tends to fly under the radar because it generally performs well, doesn't attract controversy and pushes out decent results year in and year out.
It's in the field of photonics - lasers for industrial purposes, fiber optics components, and other light-related technologies and applications.
Today's headline results are as follows: revenues up 6.6%, PBT up 11.6%. Expectations for the full year are in line with management expectations.
Some acquisitions contributed to the revenue growth; a quick back-of-the-envelope calculation by me says that the organic revenue growth was 1.4%.
The company's long-term progress is illustrated by its dividend stream. Aside from taking a break in 2009/2010, it has paid a beautifully rising stream of dividends all the way back to 1998.
One particular metric from today's report which really jumps out at me is that on a constant currency basis, the order book is up 36% compared to a year ago. Probably not all of that is organic growth but even so, it strikes me that the outlook must be a rosy one, with that sort of growth rate in orders.
Overall group strategy is based on R&D, Diversification and "Moving up the Value Chain":
G&H seeks to move up the value chain to more complex sub-assemblies and systems through leveraging its excellence in materials and components, and by providing photonic design and engineering solutions for our customers. This will enable G&H to transition from a components supplier to a solutions provider. A significant proportion of our business in the Aerospace & Defence market now comes from the sale of sub-systems rather than discrete components.
And:
...continued strong focus is being placed on acquisition opportunities that enhance the Company's ability to wrap electronics and software around core photonic products to yield system-level solutions.
All of this strikes me as cutting-edge, if not downright futuristic!
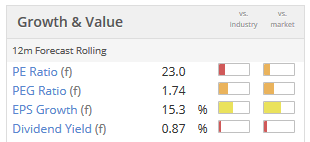
Once you dig into the numbers, you see that operating profit margin could be a little higher: it's 10.2% for the most recent period. Not bad, but not spectacular.
And if you examine the company's long-term quality metrics, you find that it usually earns more than 10% return on capital employed. Again, this is not spectacular, but it's good enough to produce a fine shareholder return over the long run. The share price has trebled since 2012, along with the rising dividends.
Putting it all together, I'm tempted to have a small nibble at this one, the next time I'm deploying some capital. One for the bottom drawer, perhaps.
QUIZ (LON:QUIZ)
- Share price: 168p (-5.6%)
- No. of shares: 124 million
- Market cap: £208 million
Preliminary Results - year ended 31 March 2018
Paraic makes another strong comment today, in the comment thread below:
What I like about QUIZ (LON:QUIZ) is it has great BooHoo style marketing to drive online traffic - at least in London; it's adverts are everywhere!
He's bang on the money there.
I noticed the same on my last trip to London, and took a snap of one instance of this:
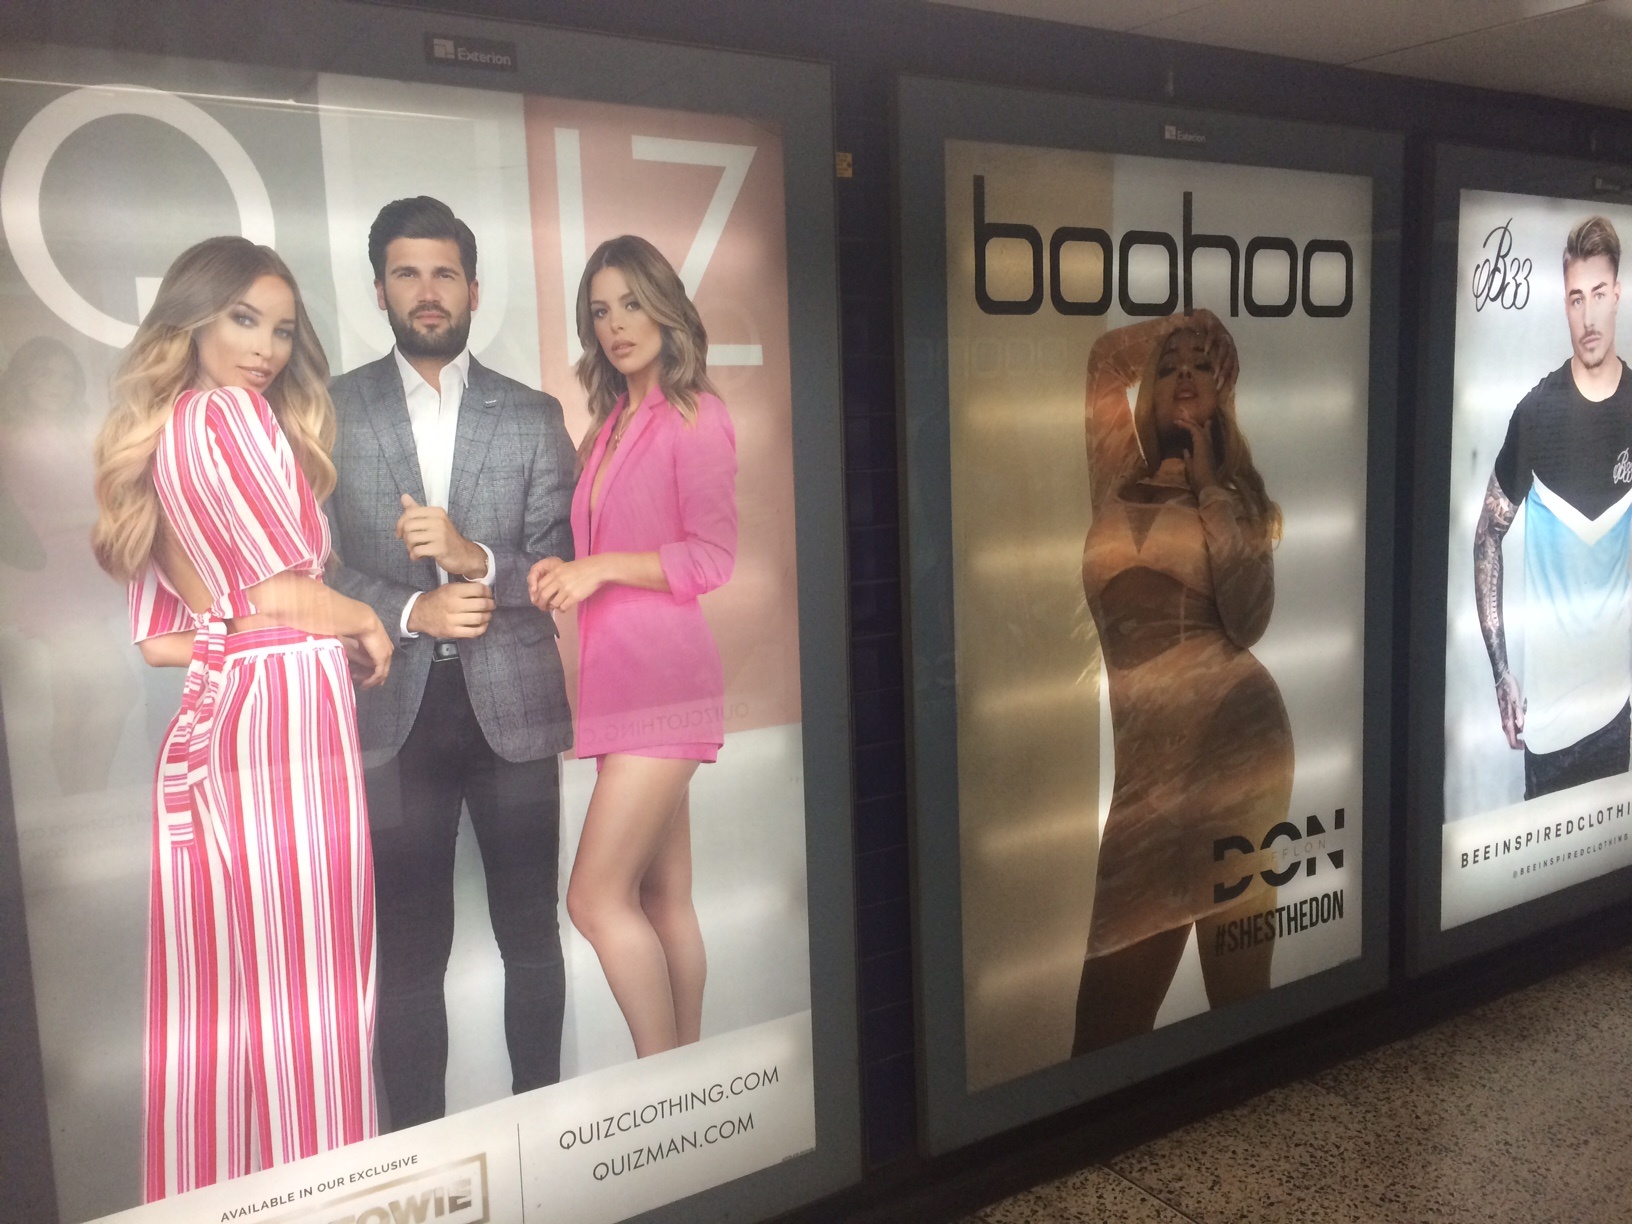
As you can see, QUIZ (LON:QUIZ) is competing for the exact same advertising space as Boohoo.Com (LON:BOO) on the underground.
On the same strip of adverts, we also can see the dark horse Bee Inspired, which describes itself as "the fastest growing streetwear brand in the UK". It can only be a matter of time before we are trading its shares, too!!
Anyway, back to Quiz.
Top-line growth is good (30%). Everything is pointing up:
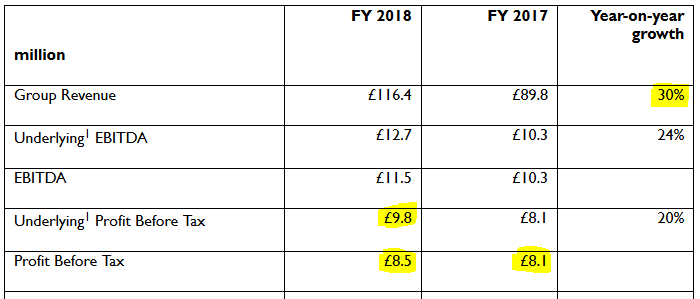
I suppose this table immediately leads to the question of why profit growth didn't improve by more. If revenues are up 30%, I'd like to see the profit measures improve by more than 30% (i.e. a positive impact from operating leverage).
The gross margin improved by 30 basis points to 63%, so there is no problem with that.
Quiz uses adjusted EBITDA margin as one its financial KPIs: this fell by 50bps.
If you scroll down to the Financial Review, you find that marketing spend increased by £1.5 million to £2.5 million, including digital spending and offline spending such as on the London Underground ads.
Distribution costs increased by a much larger amount, from £13.6 million to £21.4 million. Here's the explanation:
This increase reflects (i) the cost of carriage to stores, concessions and franchises as well as online customers and (ii) commission paid to third-parties who sell product on behalf of QUIZ. The uplift in these costs primarily reflects the higher commission costs incurred associated with a higher proportion of sales being made through third-parties which have a higher cost to serve than sales generated through our own websites.
This strikes me as important, because it's a key factor dragging on the operating/EBITDA margin and preventing a big uplift in profits during the year.
Depreciation and amortisation also increased faster than sales, but this is understandable given the recent capex spend.
The outlook for the full year is in line with expectations.
My opinion
An interesting stock, although I have to admit that I'm not too sure about the power of the brand. It says that its specialism is "occasion wear and dressy casual wear". Is it sufficiently unique to enjoy the same sort of cachet among consumers as the likes of Boohoo.Com (LON:BOO), which achieved sales 6x larger than QUIZ (LON:QUIZ) last year? At this stage, I can't tell.
The top-line numbers are all fine. Online sales jumped 158% and doubled as a percentage of total sales, reaching 26%.
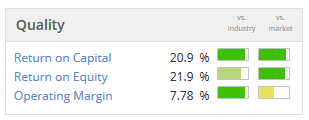
Overall, I see this as fairly priced at the moment (P/E ratio c. 22x). Despite having many positives, including the excellent quality metrics shown below, I think it's quite difficult to predict which of the "fast-fashion" stocks will be winners in the long-run. This is why I'm still holding Burberry (LON:BRBY), despite the P/E ratio approaching 27x, because I view it as (hopefully) an evergreen brand. Only time will tell!
Quiz quality metrics:
Carclo (LON:CAR)
- Share price: 87.5p (-3%)
- No. of shares: 73 million
- Market cap: £64 million
This manufacturing group had a nasty profit warning in January (covered here).
The Chairman describes these results as "disappointing". That's refreshing!
...delays in the placement of certain customer project awards and some weaknesses in operational performance, particularly within Carclo Technical Plastics ("CTP"), meant the Group did not achieve its profit targets.
Scrolling down to the CEO's report, he attributes the difficulties to labour shortages and increased resin prices not being immediately passed on to the customers of the plastics division.
All aspects of the plastics division have been reviewed. It sounds like the previous divisional management struggled to keep it working efficiently as revenues grew strongly over the past five years.
Notwithstanding these issues in FY 2018, Carclo still achieved a profit before tax of £8.2 million.
The balance sheet is a key issue: heavy capex has contributed to net debt increasing to £31.5 million. Headroom on the associated covenants was "comfortable" at March 2018.
There is also an accounting pension deficit of £24.7 million. (The pension position is heavily geared: £200 million in pre-tax liabilities versus £170 million in pre-tax assets.)
The shares are still a bit too risky for me, considering the balance sheet and the customer concentration. Excerpt from the 2017 annual report:
The proportion of revenues generated from the top five customers in the year was 47.5% (2016 – 47.4%). One medical customer accounted for 16.4% of revenues (2016 – 19.3%) and one supercar customer accounted for 14.7% of revenues (2016 – 14.5%). No other customer accounted for more than 10.0% of revenues in the year or prior year.
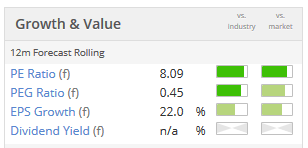
Investors who don't mind bearing these sorts of risks can buy the shares at 8x earnings, albeit without a dividend:
GB (LON:GBG)
- Share price: 518p (-0.4%)
- No. of shares: 152.7 million
- Market cap: £791 million
GB Group plc (AIM: GBG), the global identity data intelligence specialist, announces its annual results for the Year Ended 31 March 2018.
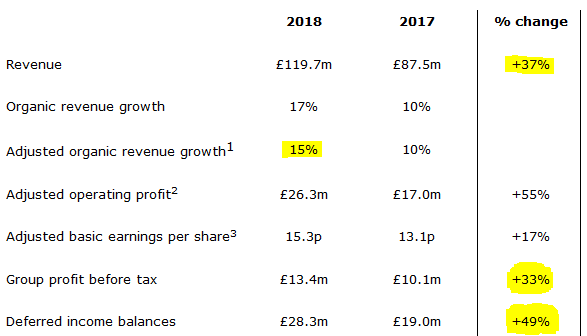
I have attempted to highlight the most important financial highlights for you in yellow below:
Outlook - the new financial year is trading in line with expectations.
Rather like the order book situation at Gooch & Housego (LON:GHH), I'm very impressed by the 49% growth in deferred income balances at GB (LON:GBG).
Deferred income is "the amount of invoiced business in excess of the amount recognised as revenue", i.e. the value of cash received from customers and outstanding trade receivables relating to work which hasn't been done yet (roughly speaking). This sort of metric, along with the order book, is often an excellent leading indicator for future revenue growth.
(Also note that GB has non-cancellable agreements with customers which haven't been invoiced yet, so GB's total sales visibility is larger than just its deferred income).
What it does
The company has a prestigious customer list and gives the impression that it is extremely busy, not least with GDPR-related work.
The two operating segments are:
Fraud, Risk & Compliance - which provides ID verification, ID Compliance and Fraud Solutions, ID trace & investigate and employment screening.
Customer & Location Intelligence - which provides ID Location Intelligence and ID engage solutions.
Reading through the specific definitions of each of the above lines of business, they are all engaged in helping companies keep track of the customers they are interacting with.
Here is an example of one of GBG's products. Some people might find this rather sinister:
GBG Connexus brings together the broadest range of identity data, all in one place. We have access to millions of records including names, addresses, dates of birth, telephone numbers, email addresses, 130 social networks to check for associated social IDs, and OSINT - our innovative Open Source Intelligence tool that aggregates social media data to provide you with valuable insights to aid your investigations.
All you need is a phone number or email address and you can build a profile on an individual. You can study their neighbours and cohabitees, too. I'm not surprised that big organisations are willing to pay up for tools like this, to develop detailed information on their customers, employees, etc.
Balance sheet
The balance sheet isn't too pretty, as GBG has grown via acquisition. There are £161 million of intangibles, mostly consisting of goodwill and customer relationships. And if you strip them out, the company is in negative equity. So there is no balance sheet value to fall back on in this case.
It does enjoy a net cash balance of £13.5 million, funded by customers paying in advance for GBG's products and services. So assuming continued profitability, it looks like it will probably be ok.
Conclusion - a very impressive company, growing strongly for many years.
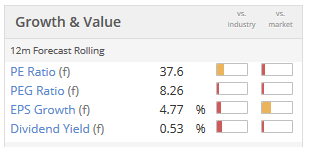
The valuation is sadly beyond the limits of where I could consider buying it, at nearly 40x forecast earnings:
Altitude (LON:ALT)
- Share price: 94p (+19%)
- No. of shares: 53 million
- Market cap: £50 million
Before I get into these results, bear in mind that they relate to the year ending December 2017. Very late.
Paul covered it last year, at the 2016 results, and called it "a complete punt".
It had a placing back then, for £2.5 million, and raised another £1.5 million this year.
The dilution hasn't been too awful - share count is up by 24% over the past five years.
Description of the company's technology services:
Altitude Group plc provide [sic] leading technology services, specialising in cloud and server based software that is catered to companies of any size and expertise. Whether you would like an end to end business management system to suit you [sic] company or access to product data from the industry’s most comprehensive sourcing portal, you’re in the right place.
The key focus for Altitude is something called the "AIMPro Tech Suite". I think this is its website. It serves US distributors (members of the "AIM Group") and as such, Altitude's new CEO will be US-based.
Altitude's e-commerce platform can be viewed at this link.
Results
Excluding the effects of an acquisition, revenues fell in 2017, from £4.3 million to £4 million.
The Chairman says he is pleased that PBT increased by 71.8% in 2017, but the increase was merely from £73k to £125k.
I'm not sure about how impressive this is:
AIMPro was formally launched to 200 attending AIM members at the national PPAI trade show in Las Vegas in January 2018 to an immediately positive reception. Indeed we are carefully managing demand within our current resources, as any marketing to the AIM members and suppliers prompts immediate response and excitement. Marketing email opening rates of 38.5% (industry average 14.2%), a click through rate of 8.9% (industry average 1.6%) and web site visits to the AIM info site doubled in May illustrating their enthusiasm for engagement.
My own mailing list is fairly small, but it's not very far from being the same size as the AIM Group membership. And my open rates are a lot higher than 38.5%!
The industry average open rates and click rates are more typical when you have mailing lists of commercial size, rather than tiny lists with less than 2,000 members.
I also find it a bit odd that investors should care very much that prospective clients are opening emails from Altitude.
Having said that, the opening levels of activity on AIMPro do seem encouraging:
More than 1.4 million items have been ordered through the platform on over 2,200 individual sales orders from the first 57 AIMPro members with total throughput of $2.8 million to date. 65% of active users have used the platform to place multiple orders.
I wonder how much revenue for Altitude is generated by $2.8 million of sales throughput on its platform? These are very early days.
Cash flow generation was ok, I'm happy to add back in the amortisation of intangible assets and depreciation so operating cash flow was somewhere around £550k for the period (from pre-existing publications and exhibitions businesses, plus six months of the new acquisition).
Conclusion: This is too early-stage for me. There are a few interesting things happening with it, but I don't see how it is worth more than its net book value or a modest earnings multiple, based on achievements to date.
It is trading at 5x 2018 forecast sales, and the StockRanks duly categorise it as Highly Speculative. As always, I'm happy to listen to arguments to the contrary!
Vianet (LON:VNET)
- Share price: 130p (+2%)
- No. of shares: 28 million
- Market cap: £37 million
If you go back in time, Vianet was known for providing vending solutions and performance management services for bars, petrol stations, gaming machines, etc.
It now describes itself as "having operated in the IoT enterprise level market since 1994". That's quite fair, I suppose!
Internet of Things (IoT) is a silly name but all it really means is that physical devices are able to communicate somehow (e.g. transmit to humans their location, condition, etc). Vianet has been in this space for a long time, before it became a huge investment theme.
Unlike blue-sky companies lacking in sales and profits, Vianet has stable revenues (£14.6 million in FY 2018, up from £14.3 million), a decent pre-tax profit margin of 14%, and pays an attractive dividend yield of 4.5%.
The older part of business, primarily in drinks monitoring, is in a slow decline. However, it is still generating cash and enabling Vianet to invest in infrastructure and technology, to explore new ways to implement its solutions.
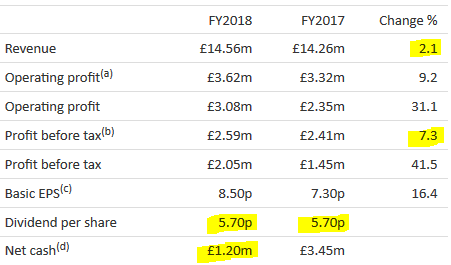
The numbers are all fine. Revenue is up only a little, but PBT improves 7%. The dividend is unchanged which looks prudent, as net cash has reduced following an acquisition:
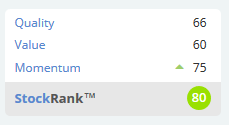
The StockRank is a very healthy 80, giving rise to classification as a Super Stock.
So overall, I think things are looking nice for shareholders, and I don't see any immediate cause for concern (by Sod's Law, I am probably jinxing it by saying this!)
I'm out of time for today. I hope you found a few interesting nuggets in today's report.
Best,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
We can get a reasonable indication from the financials provided previously by the company (see slide 13 here).
If I've done my maths right, $2.8m of sales throughput translates into c.$336k of revenue for Altitude. However the average order size of $1,278 actually experienced is more than twice the $500 assumed in their modelling, which if that continues means they could still have a very successful business even if take up is ultimately lower than the 5% market share they are targeting.
The biggest risk here is gaining traction with distributors and suppliers, so I thought the numbers disclosed today were quite promising given they were starting from scratch 6 months ago.
Based on the 462 distributors which they are actively engaging with, a simple pro rata implies those distributors could account for around $400m of revenues. If just 10% say of those revenues were channelled through Altitude's platform that would imply c.$48m of revenue for Altitude per annum, which compares to the current market cap of £40m.
Flex any combination of those assumptions even marginally upwards (no. of distributors, online penetration, gross margin, average order size, number of orders per annum...) and you rapidly get to potential revenue figures of multiples of the current market cap.
Yes it's still a story of deferred jam and it's high risk. But to me it seems misguided to write off Altitude as a jam tomorrow stock while focusing on the historic numbers reported today as the basis of valuation. The historic numbers are pretty meaningless at this point, other than to reassure that there are no cash burn issues like some jam tomorrow tech stocks out there.
Altitude (LON:ALT).
Please explain your maths to show how you got to that revenue figure given the guidance.
Also, as far as I understand they targetted the biggest fish first, so whilst the “average” order may be 2 1/2 times fore cast here and now, this will fall going forward surely?
Happy with my 65p buy and 94p sale. I still fear pump and dump butwould be interested again around 70p looking to scalp some mugs.
I agree. Many thanks for responding to requests for Vianet (LON:VNET) including mine and more broadly for the sheer breadth and depth of insightful analysis Paul and yourself relentlessly produce. One of the greatest services you provide is the reality checks that make it so much easier to avoid the myriad dross shares out there. I for one have been fishing in a smaller but richer pool of opportunities since I joined Stocko and in particular started following SCVR.
Thanks Graham for the brilliant write ups across the board today. I don't know how you and Paul manage to find out so much and then write in such high quality detail day after day. It must take many hours and you both provide a brilliant service as well as clear pointers on shares to avoid or check out further.
As for Altitude your analysis of the figures today confirms what I already thought...that so far it has been a lot of hype but little or no sign of real progress. BUT the reason I've added some to my previous small punt today is that there are now signs that the hype just might be justified. The appointment of Nichole Stella as Chief Executive looks a possible game changer with a chance of explosive growth in the US especially.
We probably won't know for sure until the next results. IF the hype proves justified then the share could rocket, but until more evidence showing fast growing revenues and profits Altitude remains a high risk punt. I rarely invest in blue sky type shares as they nearly all end in tears, but wonder if fairly soon we'll find Altitude is a rare exception?
Altitude (LON:ALT)
Sold these today based on the complete lack of progress. I fear pump and dump on the usual suspects bulletin boards so decided to take profit when I saw it.
A marketing company that generates 41 (yep 41) likes for its Facebook page (And Everything) in 6 months doesn’t get my pulse racing.
Graham,
Re: QUIZ (LON:QUIZ)
Whenever I see something along the lines of the quote from their RNS :
"The uplift in these costs primarily reflects the higher commission costs incurred associated with a higher proportion of sales being made through third-parties which have a higher cost to serve than sales generated through our own websites."
I immediately think of Amazon, so looked there and QUIZ have 143 separate items listed (excluding variations - Colour/Size etc.). Not many, but I haven't checked this against the items they have available on their own website.
I know from experience that Amazon have increased their fees over the past 1-2 years, have changed their Marketplace Seller T&Cs, and Sellers lose money and/or stock on refunds/returns. Amazon quite often refund a buyer (from the seller's funds) and allow the buyer keep the item as well - This has become so common, there are now blogs/threads informing buyers how to get away with this, and how to get items (not just clothing) for free. (Sorry, that started ok, but then turned into a rant ! lol)
Thanks for the insights re QUIZ (LON:QUIZ) and AMZN. Yet another argument for closing our eyes to the $800 billion valuation and buying AMZN, I guess!!
Am very pleased to see you are covering Altitude Graham. Until today hype but otherwise unimpressive. But since appointment of new Chief Executive there are now signs of real progress and perhaps very fast growing revenues and profits. Cash tight so maybe a placing ahead, unless revenues are going to be enough short term to make a placing unnecessary. Can’t fathom what it is they do, but it sounds as though whatever it is it is now in demand! Share up 15p today.
I mentioned my views on Carclo 6 months ago and the points made were poopooed by a number of other writers. I remain clear in my view it is a ? with some potential linked to a bunch of cash cows and does not offer any real synergies one part to the other. I'd avoid.
Hi Graham,
At the risk (certainty) of being a 'bit' curmudgeonly , I can't help but comment on the cutting edge / futuristic statement you highlight from Gooch & Housego (LON:GHH)
That is pure flim-flam imho.
I read :
I'm sure that there is much more to what they are doing than that, but it hardly sounds ground breaking to me.
I've no personal opinion on Gooch & Housego (LON:GHH) having not looked into it, but that's another of those examples where the language just turns me off in the first instance.
It's rather flowery language, I agree.
Gooch looks an interesting steady eddie with a long track record ( founded in 1948!) but optically forward PE of 23 look 50% too high - perhaps ? but definitely one for the watchlist.
RE: Gooch & Housego (LON:GHH) Putting it all together, I'm tempted to have a small nibble at this one, the next time I'm deploying some capital. One for the bottom drawer, perhaps.
Although operating in a slightly different niche of the electronics markets, I have no idea why anyone would choose Gooch & Housego (LON:GHH) over XP Power (LON:XPP) which just looks better on nearly every single metric you care to choose. Why is Gooch & Housego (LON:GHH) so expensive - is it one of those AIM shares beloved of the CGT crowd?
All the best, Si
Morning Graham. Please can I second the motion for you to run your rule over Vianet (LON:VNET) in which I have a small long position. I was impressed by the tone of the results statement today with plenty of optimism, impressive margins and a contract with a global coffee company. I know Paul has covered this company before and I tend to agree that there may be scope for a racier valuation if their transition into sexier IoT markets becomes better understood. The nice thing is that there is already some jam today whilst scope for more jam tomorrow does look highly plausible. In the meantime there is a pretty healthy dividend to collect. One hopes too that the appointment of the former "Chief Envisioning Officer" at Microsoft as NED can do no harm either. I'd be really keen to hear what you make of the numbers. Many thanks.
Hi John. "Chief Envisioning Officer" is a rather silly job title in my book but I do like what I see at Vianet (LON:VNET). It's been covered now. I agree with you - it's good to have some jam today, so we aren't completely dependent on jam tomorrow. Thank you for the suggestion. G
Another vote for Driver (LON:DRV) please - I see one of the brokers has upgraded earnings this morning by +13% for both 2018 and 2019. This is largely due to margin improvement from increased depute resolution. Thanks Ian
The statement today from GB (LON:GBG) repays detailed study. I hold the stock but cut my holding by a half earlier in the year (and missed a nice ramp up!).
The concerns I had are still visible behind a bullish statement that shows everything going up.
Taking just two starting points; well down in the statement we get to the end (the very end ) of the "Consolidated Statement of Comprehensive Income" and we see that "Total comprehensive income for the year attributable to equity holders of the parent" has gone from £14.4million in 2017 to £7.4million in 2018. Surely that is after an FX hit, tax, share based compensation and a non-cash write down of intangibles and do on, but none can really be considered out of the normal line of business.
In the light of the £7.4million for shareholders the £2.4million of Share based compensation, mostly for management, is worth keeping an eye on.
Much also is made of the increase in net cash but the cash flow has a lot of moving parts which include a £10.2million increase in trade payables against a £5.4million increase in receivables.
There is a lot to like in GB but I always get a bit uneasy when the management emphasizes all manner of EBITDA variations and KPI achievements and then award themselves a third of the profits that could be attributable to shareholders.
Because I think that the is a great business growing here I hope that someone can point out where I am going wrong with my concerns
Morning Graham,
Just a seconding for Fulcrum Utility Services (LON:FCRM) which I hold and Gama Aviation (LON:GMAA) which hit an alert for me this morning, having fallen.
Best,
Mark
Morning Graham - would welcome your comments on Driver (LON:DRV) and WYG (LON:WYG) results please! Thanks
Morning Sir... on a day with lots of news I will have to leave Driver (LON:DRV) and WYG (LON:WYG) to one side. They are quite a bit too labour intensive for my liking. But I know you are good at analysing this sector so would read anything you have to say about them! Thanks.
Graham's thoughts on Driver (LON:DRV) at the time of the trading statement can be read here:
https://www.stockopedia.com/content/small-cap-value-report-fri-23-feb-2018-drv-sgi-rmv-329328/?page=2#comments
Today's results show a continuation of the turnaround, including moving to net cash (there was a very bad year to 9/16 in which new management kitchen-sinked).
I bought after the February statement with the plus points including -
StockRank > 90
Keith Ashworth-Lord's Buffettology fund (for which I have some respect) increasing holding.
Explanation of what the company does (referenced by drvodkaquickstep in reply 7 to Graham's report) which can be seen here:
http://webcasting.brrmedia.co.uk/broadcast/5919d52d2fea63527a1ed6c2
Negatives -
Little forward visibility (but disputes will always be with us)
Illiquid
What I like about QUIZ (LON:QUIZ) is it has great BooHoo style marketing to drive online traffic - at least in London; it's adverts are everywhere! So I think the online side of things has great potential. Unfortunately in today's update we are given no indication as to what the "Board's expectations" are for FY19 and there is no data on like for like store sales - with a 12% rise in store revenue one imagines they shouldn't really have anything to hide. I also wish they'd stop using the annoying word 'omnichannel' when they just mean they sell stuff in stores and online like most other retail businesses! I hold.
Not a reporting small cap, but posting for general interest/discussion, a specialist Uranium investment company Yellow Cake has announced its intention to list on AIM. It received a bit of coverage in the weekend press and has lined up a reasonably high powered “great and the good” board (cynic in me usually sees this as a red flag).
https://www.investegate.co.uk/yellow-cake-plc/rns/intention-to-float/201806050700082675Q/
Concept is to raise funds (c.US$200m mooted) to buy and hold a substantial chunk of physical Uranium via a long term contract from one of the lowest cost global producers and sit on it (presumably with suitable lead shielding) until such time as the market price “normalises” (i.e. goes up based on imbalance of high cost unprofitable supply and growing future demand). The wider Uranium sector is a sea of red ink in terms of Stocko metrics due to low prevailing market price of the commodity and the speculative nature of several market companies as prospectors/developers (such as Berkeley Group (LON:BKG) ). I’ve been thinking of adding some “pure” Uranium risk to the wider investment portfolio as a supplement to holdings in other commodities and at face value this appears to fit the bill. Will probably hold fire on the IPO but watch with interest.
Gus.
Gus, Berkeley Group (LON:BKG) are a highly successful building company whose shares have been a very profitable investment over the last decade. Nothing to do with uranium. I assume you intended to refer to Berkeley Energia (LON:BKY).
Sorry John. My bad - fat thumb pulled up the wrong Berkeley. No Uranium under central London real estate so far as I’m aware.
Gus.
GB Group (LON:GBG) and Carlo (LON:CAR)
Graham,
I was wondering whether you could look at 2 companies releasing updates today
1. Fulcrum Utility Services Fulcrum Utility Services (LON:FCRM) (LON:FCRM) -you have been positive about this company in the past. Today's update seems reassuring with entry now into smart metering. Seems to be operating in all the latest areas of interest including change points for electric vehicles.
2. Gooch and Housego Gooch & Housego (LON:GHH) (LON:GHH) - another steady-as-she-goes update from the Lord Lee favourite. Record order book, no obvious red flags and seems valued appropriately.
I like Gooch & Housego (LON:GHH) and am considering buying.
One concern I have is the orderbook growth.
Since Mark Webster took over as CEO ghh always trumpets an impressive growth in orderbook but somehow, the corresponding growth in actual revenue that one would expect to follow on never materialises.
In the 2014 finals ghh said the orderbook was up 18%, in 2015 it was 11%, in 2016 it was 45%, and in 2017 it was 36.5%. Compare those sparkling figures to the actual revenue growth subsequently delivered - 12.5% in 2015, 9.3% in 2016, 18.7% in 2017, and 6.6% at the interim stage of 2018.
I accept there is probably a bit of currency effects and also the longer lead times associated with moving up the value chain but for me personally there is something not right about ghh's treatment of it's orderbook so I ignore it in my investment decision and assume 10% revenue growth in line with photonics industry trends.
I have noticed several other companies follow this pattern of massive increases in orderbook consistently failing to translate to auditable revenue. Stadium was a good example.
My morning smallcap tweet:
Gama Aviation (LON:GMAA), Imaginatik (LON:IMTK), Ten Entertainment (LON:TEG)
Gama Aviation (GMAA) AGM stmt: A warning? "Trading across both Air and Ground divisions has been broadly satisfactory although flat compared with last year, with conditions in Europe being somewhat challenging whilst conditions in the US are supporting strong growth." In March it said "Current trading in line with management expectations; company well placed to achieve its expectations for the current year." F/C is for 12% rev growth.
Imaginatik (IMTK) sale off, Chairman resigns and CEO booted out 'without compensation'. £225k loan notes convertible at 0.5p, a 55% discount issued to ex-chmn. Plan to cut £750k from cost PA.
Ten Entertainment (TEG) CEO to leave Dec 'for his own personal reasons'.
Morning Graham,
a litany of shoulda woulda couldas for me - requesting GB (LON:GBG) this morning please - profits up 55% but 'As we highlighted in the October 2017 trading update, the organic revenue growth includes £3.5m from the sale in September 2017 of a material perpetual licence to a leading European bank. Had this particular transaction been a fully delivered, 3-year agreement, payable in annual instalments then our revenue recognition policies would have resulted in an underlying organic growth rate of 15%.' A Naked Trader favourite, of course I sold my shares last year! https://www.investegate.co.uk/gb-group-plc--gbg-/rns/final-results/201806050700032624Q/
Also interesting is Vianet (LON:VNET) - IoT in vending machines etc. Basic EPS after tax was 6.55 pence compared to 3.77 pence in 2017. No position there either! :-( https://www.investegate.co.uk/vianet-group-plc--vnet-/rns/final-results/201806050700052643Q/
QUIZ (LON:QUIZ) too seems to be doing well - Underlying Basic EPS 6.48p from 5.33p last year, powered by online and international but also UK stores up 12%. Has been up off lows recently, leaky-leaky? 'We have further expanded the brand with the successful launches of our CURVE and Bridal ranges as well as the recent launch of QUIZMAN.com. More recently the QUIZ X TOWIE collection, our first male and female capsule collection has been very well received.' https://www.investegate.co.uk/quiz-plc--quiz-/rns/preliminary-results---year-ended-31-march-2018/201806050700052633Q/ Again, no position, I sold out halfway through the post-IPO slump :-(
Hi rtj, thanks for all those suggestions - 2 down, 1 to go! Cheers. G
Thanks for your hard work Graham! Yes the per of GB (LON:GBG) looked a bit high when I sold out at 290p too - guess I should have stuck with it. Evil govt Surveillance will not be going away, but that balance sheet...
IQE (LON:IQE) released an AGM statement yesterday. I missed it because it wasn't shown on investegate (and still isn't) so perhaps others missed it too. For such a long statement it manages to say virtually nothing. I am concerned about the lack of progress in finding a CFO. I feel the company is too academically focused and needs some more hard-headed financial thinking, and so for me the appointment of the Dr chairman as interim CFO concerns me.
http://www.londonstockexchange.com/exchange/news/market-news/market-news-detail/IQE/13664705.html
Leo, this was only an AGM update from IQE (LON:IQE) so not surprising that there wasn’t more information. We’ll need to wait for the interims for more detailed performance numbers.
But I do think it told us a lot in terms of confirming that everything is proceeding as planned with the new factory, new machines and replenishing of inventory for the wireless market. The stand out item is probably the fact that they are now doing qualification of their machines for a further 10 VCSEL manufacturers. A strong indication that the rapid adoption of VCSEL technology continues and they are at the centre of it.
With regard to replacing the CFO, yes it would be nice if they could find the right person immediately but consider the context. The previous one died in an accident only two months ago. Two months is a very short time frame to fill a senior position of this nature in this location when you had no inkling prior to that it was going to be necessary. I would far rather wait to find a good person than rush this process.
Graham D,
Seeing Machines (LON:SEE), "only an AGM update...not surprising that there wasn't more information"
Indeed, AGM statements are often only 1-2 sentences saying things are inline and when the next update will be. Whereas IQE's statement very long yet told me very little I was interested in beyond being inline and not having a proper CFO. This only reinforces what I perceive as a gulf between their interest in buying lots of shiny cool machines and my interest in making lots of money.
I do take your point that continuing investment should imply continuing orders and that they need the right CFO. If only I trusted them to align investment with firm orders and to have similar ideas of what kind of CFO is "right".
(I have a quite small position that I trade in and out of).