Small Cap Value Report (Wed 19 Dec 2018) - BEG, 888, COG, YU, MANO

Good morning!
Today is Fed decision day. President Trump has been tweeting unhappily about it, but it looks like US interest rates will increase toward 2.5%.
Away from macro, I have noticed the following RNS announcements:
- Begbies Traynor (LON:BEG) - half year report
- 888 (LON:888) - pre close trading update
- Cambridge Cognition Holdings (LON:COG) - trading update
- Yu (LON:YU.) - notice of appointment of FCA investigators
- Manolete Partners (LON:MANO) - maiden interim results are in line with expectations. What a relief - it has been listed since Friday!
Begbies Traynor (LON:BEG)
- Share price: 68.8p (pre-open)
- No. of shares: 110.5 million
- Market cap: £76 million
Begbies Traynor Group plc (the 'company' or the 'group'), the business recovery, financial advisory and property services consultancy, today announces its half year results for the six months ended 31 October 2018.
This company is useful as a barometer of financial distress in the economy.
The numbers show some modest progress against last year. There have been some acquisitions:
- revenue +£2 million to £28 million
- adjusted PBT +10% to £3.2 million
- after amortisation of acquired intangibles and transaction costs, actual PBT reduces from £1 million to £0.6 million (see the debate on my previous commentary)
- net down down, dividend up
Outlook
Careful wording: the company is "well placed to deliver up current market expectations for the full year". There is a second half weighting, relying on contingent fees and higher activity levels.
Insolvency Market
Corporate insolvencies are up 6% on a trailing 12-month basis, to September 2018.
After a couple of very lean years, this means that business looks to be getting back to normal for insolvency practitioners.
Begbies has been involved with the administrations of a music festival, an estate agency and a menswear retailer, and has advised House of Fraser landlords on the CVA process.
These individual cases give us a sense for how a full-blown consumer recession would (counter-cyclically) produce a boom in the demand for Begbies' services.
My view
For reasons previously discussed, this share doesn't interest me as a potential investment - I don't invest in professional services businesses.
Its announcements are useful, however, as confirmation of the state of the involvency market. It sounds like things are moving on that front, with momentum for continued growth in the demand for insolvency services. That's really healthy for the economy - freeing resources which have been tied up in failing businesses, so they can be allocated in a more rational way.
888 (LON:888)
- Share price: 182.6p (+7%)
- No. of shares: 364 million
- Market cap: £664 million
(Please note that I currently hold 888 shares.)
This international online gambling operator is a very recent addition to my portfolio.
It helps that I have played poker on 888 for a few years and also have some familiarity with its position in the US market - it is a smaller but highly-respected competitor against PokerStars.
Using its products is one of the best ways to deepen your understanding of any company - though you might want to be careful when it comes to gambling, tobacco, etc!
Poker has actually been one of the more difficult segments for 888. The other casino games tend to provide a much more straightforward route to profitability.
Today's update confirms that adjusted EBITDA will be in line with expectations.
888 shares have been massively de-rated over the past six months despite the prospect that US growth could be sparked through the legalisation of online sports betting and the spread of online poker to more and more States.
Investors have instead been focusing on the worrying situation in Europe, where the company has faced seemingly endless fines and legal problems.
The share price became overly pessimistic, in my view, since 888's broad geographic diversification means that it is likely to churn out decent results even if it continues to suffer bad luck in one or two jurisdictions.
It's a Gibraltar-registered company with Israeli roots, but is a truly international business.
For whatever it's worth, the Outlook comments today from the CEO are very positive.
888's forecast P/E ratio was 11x based on last night's close, with a forecast dividend yield of 7%.
It enjoys a Quality Rank of 87, thanks to the following metrics which are indicative of a successful online business:
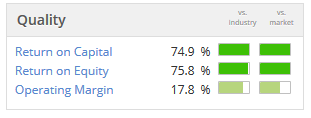
Where it falls down is in its Momentum, which is why Stockopedia classifies it as Contrarian.
I was brave enough to step in the way of the downtrend and buy some shares - I wouldn't be too upset if I had accidentally called the bottom. At the same, I also wouldn't mind continuing to accumulate them at cheap levels!
Cambridge Cognition Holdings (LON:COG)
- Share price: 81.5p (-19%)
- No. of shares: 21 million
- Market cap: £17 million
Trading Update and Notice of Results
I've been unpicking the logic in this trading update. Something strange is going on!
In a nutshell, the company is blaming IFRS 15 (the new accounting standard for revenue recognition) for a reduction in reported revenues this year.
That alone shouldn't cause a near-20% fall in the share price. Different accounting rules don't change the value of a business, after all! They only change how that value is presented to us.
So either investors are wrong to mark the shares down, or the company is wrong to blame IFRS 15 for its woes. I am leaning toward the latter.
Let's recap. In March, the company warned that IFRS 15 was coming. It said that this would result in smoother revenues through the life of its software contracts - revenues would be recognised over the life of a contract, rather than in a lumpy manner up front. The company seemed to be ok with that, at the time!
Very helpfully, we were given this table to show how the new rules would have changed historic revenue:
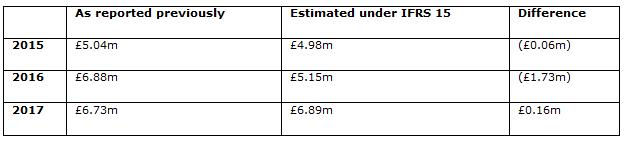
You can see that IFRS 15 revenue is smaller in the first two years, but is larger in the third year. Adding all years together (including 2018 and beyond), the total revenue should be unchanged. The only difference should be that some of the revenues are recognised later.
Which brings us to this morning. The key paragraph is:
For FY2018, the Company adopted IFRS15, the new financial standard on revenue recognition, which has had a short-term adverse impact on the financial performance of the Company. Under IFRS15, revenue for FY2018 is expected to be in the region of £6.0m. Had revenue been reported using the same standard adopted as in the year ending 31 December 2017 ("FY2017"), FY2018 revenue would have been approximately £7.0m. This compares with £6.7m in FY2017.
So the company is saying that under the old rules, it would have improved revenues from £6.7 million to £7 million in FY 2018.
But under the new rules, it is instead going to fall from £6.9 million (see the table above) to £6.0 million in FY 2018.
Stockopedia forecasts show that the consensus revenue forecast for FY 2018 was £6.9 million. I wonder is this under the new rules or the old rules? If it is under the new rules, then today's update represents a big sales miss, and it's unsurprising that the shares have fallen so much.
Whichever way you look at it - the new rules or the old rules - sales growth isn't growing terribly fast, at least not in FY 2018.
The company promises investors that marmalade will be coming soon:
Total sales order intake is expected to exceed £7.6m, compared with £5.1m in FY2017. In addition there are a number of materially significant contracts expected to be signed in Q1 2019. The order book is expected to be approximately £5.6m at 31 December 2018, an increase of 40% compared to the equivalent value of £4.0m at 31 December 2017.
Unfortunately, it has been around for quite a few years and hasn't yet made the big commercial breakthrough that would excite investors. Perhaps 2019 will be its year - but I would want to be very close to the story, to have the confidence to bet on that.
Yu (LON:YU.)
- Share price: 75p (-30%)
- No. of shares: 16 million
- Market cap: £12 million
Notice of Appointment of FCA Investigators
This company has suffered a shocking fall from grace, and in tandem with Patisserie Holdings, you might even go so far as to say that it has brought AIM into disrepute.
It launched at 200p in 2016 and reached a high at 1345p earlier this year, before admitting that its figures were, in a word, rubbish.
Income had been accrued (not invoiced) which would never be paid by customers. There were also significant additional amounts which had been invoiced but would never be paid by customers. The company was running at a loss instead of a large profit.
Today we learn:
The Financial Conduct Authority (the "FCA") has notified the Groupthat it intends to conduct an investigation into accuracy of the Group's announcements made between 6 March 2018 and 24 October 2018 and whether these announcements accurately reflected the Group's financial status.
I must be too simple-minded, but when a company admits that its accounts have "several areas of significant concern", resulting in £10 million of "adjustments" and a "substantial reduction in profitability", has it not already admitted that its announcements did not accurately reflect its financial status?
I wonder what the upshot of all this might be. It's not good for investor trust in AIM, that's for sure.
I studied Yu during its meteoric rise - I was impressed by its growth, but I did think that the share price had gotten ahead of itself by at least a few years.
A bit like Patisserie Holdings, it now turns out that the story was too good be true. It was surprising that a small gas and electricity supplier could do so well. On the other hand, it had peers who achieved similar success before it.
It now looks like the growth was a mirage. Hopefully, we will find out if there was a deliberate plot to mislead.
I wouldn't be tempted to buy shares in this company unless they were almost free.
Manolete Partners (LON:MANO)
- Share price: 195.5p (-0.3%)
- No. of shares: 43.6 million
- Market cap: £85 million
These are results to September 2018, i.e. for a period which had already ended long before its recent IPO.
Manolete is an insolvency litigation financing company, earning massive returns on its investments which would remind you of Burford Capital (LON:BUR).
These results, which are of course in line with expectations, show the success of the business model with an equity base of £8 - £10 million.
Its challenge now is to deploy NAV of £24 million, following a successful fundraise of almost £15 million, with a £20 million bank facility on top.
Returns
The "average money multiple" is 3.6x for cases completed during the period. How on earth can returns be so high?! It must be very painful for the customers (Insolvent Estates) to give away multiples like that to law firms. Although I suppose they don't have much of an alternative, and are better off than if they don't get the funding!
The pool of lawsuits seems to be reasonably well diversified, even before the fundraise: 76 live cases. I'd be curious to know how big were the top 5, as a percentage of the total value?
There is a big difference between the average case value (£180k) and the median case value (£60k). Mathematically, this hints at the existence of a small number of high-value cases.
One note of warning: about one third of recorded revenue for the period is to do with "unrealised gains on investments in cases". This must be tricky to measure. (Similarly, the true value of Burford's balance sheet is highly uncertain).
My view
I view this as a financial stock, trading at 3.5x book value - which might be justified, if the high returns continue to be achieved.
Perhaps I've been unduly sceptical towards this sector. My concern is simple enough: that it's impossible for an outsider to predict the outcome of legal cases with any certainty (so a concentrated set of legal cases would be dangerous). In addition, the extreme high returns make me suspicious that something strange is going on.
Good luck to anyone who is willing to give it a chance! I'll remain on the sidelines for now.
That's it from me this afternoon. Apologies for the slow production of this report - lots of preparations underway for Christmas. Life gets in the way sometimes!
Have a great evening.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
I also play poker online but do not on 888 as they insist one has to email them a photo ID to play on their sites
I wish to avoid putting a photo ID online. Maybe it is paranoia about online security and identity theft but the other poker sites I use do not insist on a photo ID so why take an unnecessary risk with 888 poker?
888 would not accept a posted photo ID which seemed to me poor customer services .
Are other stockopedia readers comfortable with their photo ID online on their computer?
I would also tell any sports betters out there that the GVC chain of bookmakers have an appalling altitude towards punters - closing down sports betters accounts no matter how small the punters stakes simply because they identify that a punter only bets with their sites when they are offering the best odds on an market
i.e GVC only wants mug punters and nobody else .Until recently it was the case that that the only gamblers who had accounts closed were high stakes winning gamblers.Now with GVC it is anyone who is not a mug.
Although Bilby's stock price never achieved the heights of Yu they are both looking very similar now! I wonder if father and son at Bilby (LON:BILB) knew about the MoD contract when they both sold out...?
Hi Graham,
Is 888 your preferred stock in the US betting sector? How would you rate GVC please? (LON:GVC)
Curious about 888 .Stocko says that it has negative net debt of 143.6 million pounds - ie net cash of that amount - which is over 20% of its market cap.However,Stocko also gives its price to tangible book as n/a - presumably indicating negative tangible book value ? That apparent contradiction could be explained by liabilities not included in net cash such as a pension deficiit.What is the explanation in 888's case ?
There is no contradiction
For 888 Holdings (LON:888) Total Liabilities are greater than Tangible Assets, hence the negative Tangible book value.
The reason for this is because 888 Holdings (LON:888) has huge Current Liabilities.
Check out their Balance Sheet: https://www.stockopedia.com/share-prices/888-holdings-LON:888/balance_sheet/
Cenkos Securities (LON:CNKS) Trading update:
The Board of Cenkos Securities plc is pleased to report that since the announcement of our interim results on 18 September 2018, revenues have improved. Accordingly, the profit before tax level for the year ended 31 December 2018 is expected to be in excess of the current market expectations.
YU - Last time I looked this was a holding in Octopus VCT - along a with a few other duds.
re Manolete Partners (LON:MANO), H1 2019 exceeded H1 2018 by 46% PAT, so applying the same uplift to FY would give PAT of £4.75m and therefore a 2019 PER of 13.3x ex-cash. (I think ex-cash of £16m is reasonable, as it added after the period end.) Three possible caveats -
1) Deploying the new funds and overdraft facilitywill take some time, then you have the approx. 12 months wait for settlement time. Maybe FY won't see the same growth.
2) There was slight seasonality last year: PAT H1 £1.69m, H2 £1.57m. Maybe not significant.
3) Regional offices, more staff will impact fixed costs, again suggesting 2019 H2 might fall short.
I hold a few, bought between 195p and 196p.
Hi Graham
I know I'm late but if you get the time can you have a brief look at FFI Holdings (LON:FFI).
On the up compared with last year's disaster.......
I hold
Steve
Hi Steve, thanks for the request but I'm out of time for today. Maybe will look at it another day if the RNS feed slows down, cheers. G
Thanks for your note Graham. Perhaps if nothing occurs in the next few days you could return to it. Sorry again for the late request
I raise a glass to your continued common sense approach. Seasons greetings to you and yours
Steve
The optimist's case for Cambridge Cognition Holdings (LON:COG) is put in:
https://www.investorschronicle.co.uk/comment/2018/12/19/cambridge-cognition-sales-shortfall/
I hold but that's perhaps because I can't figure out what's a fair price for a speculative business with a nice story. That said, thank you Graham and Paul - I've learnt a huge amount from your analysis.
Yu buggers
888 statement and USA sports betting deregulation etc. Thanks for views Graham!
In fact Washington DC voted to allow this late last night. That sets a real principle...if the capital will agree to it, who won't? Other USA states are certain to follow next year and the potential mkt is simply huge. My personal view is that this entire sector will be a star in 2019 and I see plenty of takeover activity. California will be the really big one; their turnover would be spectacular.
Been buying 888 and also hold GAN (who provide gaming software) and micro stock WEB (who own a racecourse in California and will thus be in a prime position when California votes). The latter is very volatile and often spikes heavily. It is majority owned by a well known billionaire and has not placed for over 5 years ...very unusual for a micro (I dont think he wants any dilution).
Morning Graham,
Not sure if you've noticed but the header/title says November instead of December!
Regards,
James
I see what he's up to - He's just about to call Superdry (LON:SDRY), Bonmarche Holdings (LON:BON) and ASOS (LON:ASC) profit warnings before the end of the year and no Santa Rally either ;)
Thanks James - fixed it. G
There’s an interview here with the Manolete CEO. https://youtu.be/87fPoNiP3dg
He says they aren’t cyclical during the year except maybe that retailers tend to go bust on quarter days when the rents are due.
I have bought an initial holding.
@JohnEustace
How did you manage to add Manolete Partners (LON:MANO) to your portfolio? I can't get Stockopedia to recognise the symbol properly. (Maybe Ed is too busy with his survey to get the recent IPOs on the system!)
@FREng
There seems to be some delay or error on the part of the data provider in getting Manolete Partners (LON:MANO) set up. I missed getting my usual news email alert from Investegate because I wasn't able to add it to my alerts list there, but then I could add it from the link on the interim announcement. I think it's an issue upstream of Stockopedia.
I've added it to my real world portfolio buying through HL.
Hi
I too just dipped into Manolete Partners (LON:MANO) through HL.
Interesting that the legal profession seems to be getting very keen to list.
I seemed to have acquired a mini legals portfolio. Now holding Burford Capital (LON:BUR) Keystone Law (LON:KEYS) Manolete Partners (LON:MANO) & Litigation Capital Management (LON:LIT). All very small holdings except Burford Capital (LON:BUR). I assume there are several others but I have not yet researched ideas from this angle, but might take a look out of curiosity.
Regards
Howard
Thanks. I managed to add it to my Stockopedia portfolio via the "add to portfolio" link on the (otherwise empty) Manolete Partners (LON:MANO) page.
I'd be interested in any comments on Manolete Partners (LON:MANO) as they seem on an undemanding rating if they can keep this performance up. I'm not sure how the two halves are weighted... but if they weren't at all this would mean a PER of around 18
On the day Ed has published the Stockopedia subscriber performance 2018, we have just published an interview with John Rosier, who discusses his performance this year. John writes a column for The Investor's Chronicle and has a trading diary blog: John'sInvestingChronicle.com Historically, John was a fund manager for large pension funds, so he's been through volatility many times before. It's helpful to hear his perspective on how he handles it.
https://www.piworld.co.uk/2018/12/19/john-rosier-reflections-on-2018-interview-by-tamzin-freeman/
A nasty profit warning from Gulf Marine Services (LON:GMS) today. Down about 58% at the moment - ouch! Looks like they're haemorrhaging margin, and thus steaming towards a covenant breach which won't be temporary, and which will require renegotiation. I've finally jumped ship - much too late - but the risk of it sinking completely now is very serious. If the banks allow it, they may be able to turn it around, but that falling knife may well end up at the bottom of the deep blue sea. Sorry for all the bad nautical metaphors, but I'm kicking myself here. I should have taken more note of the stock rank, which dropped sharply last summer.
Gulf Marine Services (LON:GMS) claim tangible assets of £800m, and liabilities at £445m. Even given the inevitable overstatement of assets, could somebody leap in here and tie it up? The outlook is very negative, and the sector as a whole is under the cosh again, but the banks have previously been very supportive.
while you jest on the Fed and Trump, reckon their language and relative dovishness may catalyse a rally assuming they are listening to the market noise on rate rise frequency and curve inversion fears. US price action has been tantrum-like of late so matches the Presidential disposition. Reckon we may be setting up for a very late rally : on a sidebar, this time last year the Fear Index was at 74 (Greed), today it is at 8 (Extreme Fear) : it doesn't get much worse and is so bad it is good
My morning smallcap tweet: Yu naughty boys?
FFI Holdings (LON:FFI), Hadrian's Wall Secured Investments (LON:HWSL), Cambridge Cognition Holdings (LON:COG), Yu (LON:YU.)
FFI Holdings (FFI) H1 rev up 91%. U/L EPS 3.0c (3.9c). Guides FY EBIT below previous expectations. Blames "delays in the timing of revenues from certain larger budget titles within the Completion Contracts business and of revenues associated with the Pandas Documentary within the Content Distribution business."
Hadrian's Wall (HWSL) revenue received from investments will be lower than expected in the short term.
Cambridge Cognition (COG) guides FY rev under newly adopted IFRS15 £6m. Would have been £7m up 5% under previous standard.. Guides pretax -£1.5m (-£0.3m) Guides order intake £7.6m (£5.1m) and a number of materially significant contracts expected to be signed in Q1 2019.
Yu Group (YU.) FCA to review the accuracy of announcements between 6 March (prelims before large placing) and 24 October 2018.
If frs15 takes the revenue down then presumably the order book rises commensurately? If this is the case then the increase in Cambridge Cognition Holdings (LON:COG) order book is very unimpressive. Is my logic correct?
Merry Christmas! Isn't it time we went to bed?
Well, surely we'd then miss the 'inevitable' Santa rally?
Couple of interesting announcements from the legal finance funders Burford Capital (LON:BUR) and Manolete Partners (LON:MANO) - the latter being their first interims, which at first glance look impressive. Burford Capital (LON:BUR) have raised $1.6 billion in funds including some from an unnamed sovereign wealth fund. Leaving aside the opaqueness of the business models they're an interesting play but I'd note that Burford is (surprisingly, at least to me) almost completely correlated with the wider market, but am beginning to wonder if this is an opportunity ...
... oh and Litigation Capital Management (LON:LIT) has also listed on AIM today. Almost like there's a theme emerging ...
Also FFI Holdings (LON:FFI) have announced interims. They look very good, although I'd still be concerned about the pace of acquisition.
timarr
"...but I'd note that Burford is (surprisingly, at least to me) almost completely correlated with the wider market, but am beginning to wonder if this is an opportunity..."
The share price of Burford Capital (LON:BUR) has reacted entirely in correlation with the wider market, but the performance of the company is uncorrelated with the what the wider business community is up to, and, to a lesser extent, the economy.
If the economy turns down, people sue each other. A business has less cash with which to finance, and has more management time to focus on, non-core issues such as litigation. Equally, poor economic prospects and political turmoil mean contracts for all sorts of things get cancelled, which leads to litigation.
The fallout from whichever type of Brexit we get (assuming we get one), will lead to litigation. Trumps policies over global trade will lead to litigation. There's always a loser in politics and in business, and that means there's always someone with a grudge worth following up on.
As you can probably tell, I like Burford Capital (LON:BUR) and I am a holder. I think now is a buying opportunity, but that there may be more buying opportunities over the next couple of months.
Interestingly, a member of the board of Litigation Capital Management (LON:LIT) (Nick Rowles-Davies) used to be CEO at Burford Capital (LON:BUR), so presumably knows what he's doing.
Ta
Chris
Merry Christmas! Isn't it time we went to bed?