Small Cap Value Report (Wed 2 August 2023) - BLTG, TPFG, IBST, XPP, SYS1, JHD

Good morning! It's Roland and Graham here with today's report.
It's a quieter day for news, so we're hoping to cover some backlog items (see list below). Please feel free to highlight any interesting situations or movers in the comments!
Today's report is now finished (10.30).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions
on them as possible candidates for further research if they interest
you. Our opinions will sometimes turn out to be right, and sometimes
wrong, because it's anybody's guess what direction market sentiment will
take & nobody can predict the future with certainty. We are
analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or
serious problems, so anyone looking at the share needs to be aware of
the high risk.
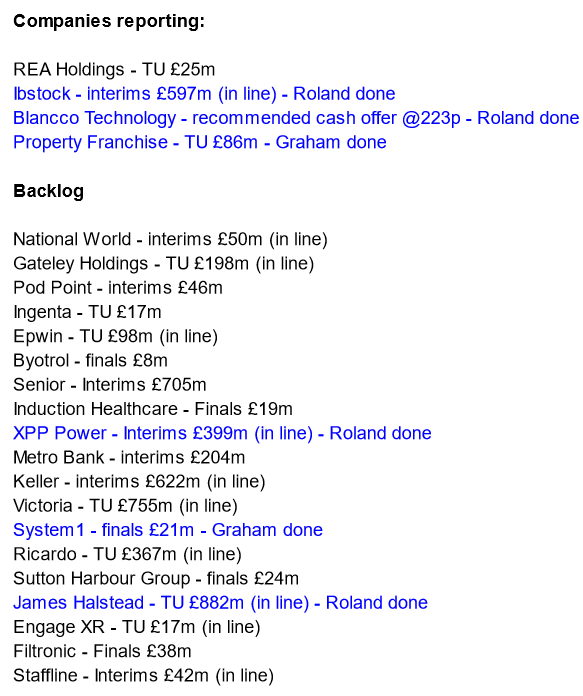
Summaries of main sections below
Property Franchise (LON:TPFG) - up 4% to 275.8p (£89m) - Half Year Trading Update - Graham - GREEN
An in line with expectations update from this property franchisor (the clue is in the name). Lettings revenue has risen thanks to more rental properties being managed at higher rents. I am a long-term fan of this business and I believe it offers excellent value at these levels.
System1 (LON:SYS1) - 177.5p (£22.5m) - Preliminary Results (in line) - Graham - AMBER
This “marketing decision-making platform” sees strong growth in platform revenues and is excited as it heads into FY 2024. Cash balance remains comfortable at nearly £6m. Existing management survived a shareholder vote. I’m neutral, waiting for meaningful profits.
Ibstock (LON:IBST) - up 5% to 160p (£618m) - Half-year results - Roland - AMBER/GREEN
The UK’s largest brick manufacturer says that trading remains in line with full-year expectations, but does inject a note of extra uncertainty into the outlook. Investment in modern new facilities continues. I can see some value here, despite macro risks.
XP Power (LON:XPP) - down 3% to 1,950p (£385m) - Half-year results - Roland - AMBER
This manufacturer of power controllers is going through a recovery process after a perfect storm of problems last year. I have some concerns about the risks posed by elevated debt. But on balance, I think the core attractions of the business are intact and the shares may offer value.
Quick comments (no sections below)
Blancco Technology (LON:BLTG) - 179p (pre-market) - recommended cash offer at 223p - Roland
Congratulations to holders of this data erasure software specialist, which has received a recommended cash offer of 223p per share - a premium of almost 25% to yesterday’s close and 45% above June’s lows. The buyer is Francisco Partners, a US private equity group.
This bid values the business at £175m, or roughly 22 times forecast earnings, for a business with an inconsistent record of profitability but recently improving momentum. I’m not especially familiar with Blancco, but it doesn’t seem an unreasonable offer to me. You can see Paul’s last comment here, when he took an AMBER view. If anyone has more insight into the business or the company’s market, then please let us know what you think in the comments.
James Halstead (LON:JHD) - 210p (unch) (£908m) - Trading update - GREEN - Roland
Just a quick comment on this excellent (in my opinion) family-controlled AIM firm, which specialises in high-quality vinyl flooring for non-residential purposes.
Halstead’s financial year ended on 30 June and Tuesday’s trading update confirmed that external conditions such as energy costs and shipping “greatly improved” in the latter part of the year.
Sales demand has been positive, “on the whole”, with increased demand in the UK, the Americas, Australia, Malaysia and New Zealand. Gross margins also improved, helped by a greater weighting towards commercial ranges, rather than heavy domestic.
The UK’s recent decision to join the CPTPP trade protocol will remove tariffs in many markets and is expected to be “good news” for the firm.
Stock levels have returned to more normal levels and cash balances have increased accordingly.
Halstead shares don’t look obviously cheap, on c.22x forecast earnings, with a 3.8% yield. But this business has consistently generated c.30% ROCE in recent years and has a net cash balance I estimate at over £40m. I think it’s a quality firm that is likely to be a sound long-term investment.
Graham's section
Property Franchise (LON:TPFG)
Share price: 275.8p (+4%)
Market cap: £89m
This H1 update is in line with expectations.
The Property Franchise Group PLC, the UK's largest property franchisor, is pleased to provide an update on trading ahead of publishing its interim results on Tuesday 12 September 2023.
As with Foxtons (LON:FOXT), TPFG is able to rely on lettings revenues even when property sales-related revenues are struggling.
Or in TPFG’s words, lettings provides “a growing and highly resilient revenue stream”.
Some highlights:
Total revenue +1% to £13.2m
Royalty income from franchisees +3% to £7.7m, of which 61% was lettings-related (GN note: this is the very high-quality revenue received by TPFG).
The company moves into net cash £0.7m.
We don’t get information about profitability in this update, but if the company is tracking in line with expectations then we should be on course for c. £8.3m of net income and EPS around 26p (using StockReport data).
Ewemove - this hybrid offering “continued to perform well”, with royalty income up 15%, although the number of new territories sold wasn’t quite as many as last year. The hybrid estate agency model looks like it’s here to stay for the long-term. Ewemove now has nearly 200 territories covered.
CEO comment:
"We are pleased with our performance in the first half of 2023. The benefits of operating a focused franchise model with multiple income streams are reflected in these results, as we continue to demonstrate considerable resilience in the face of an uncertain macroeconomic backdrop. Whilst the Board expects the macro-economic uncertainty to continue, it is confident that trading remains in line with expectations for the full year."
Graham’s view
I rarely have anything negative to say about this company, and was positive about it the last time I looked at it in April. For me, it’s a prime example of a successful franchise company.
Since I last covered the stock in April, the only real change is that we have confirmation of a slowdown in revenue growth. Although that expectation was already baked into forecasts for this (today’s update is not a profit warning).
If you treat this stock as being truly “ex growth”, then you might think that the current valuation multiples are fair:
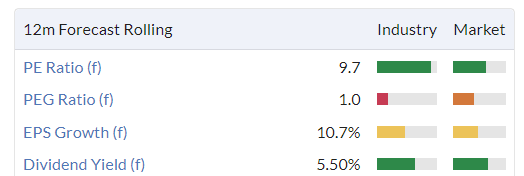
Personally, I don’t see it that way. I see it as a very high-quality business that’s currently in a quiet part of the cycle. I’m a former shareholder in this company and I’m open to the idea of buying back into it again at some point. The StockRank here is 95.
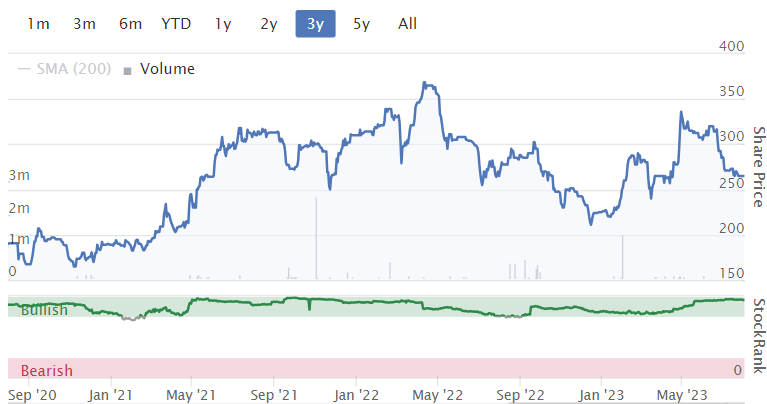
Even though the stock hasn’t moved far since 2021, its profits are up considerably since then: EPS was only 12p in 2021, versus 22.5p last year and 26p forecast this year. So in real terms this stock has been de-rated over the past couple of years:
System1 (LON:SYS1)
Share price: 177.5p
Market cap: £22.5m
When I covered this stock in April, shareholders were about to vote on whether or not to remove the Chairman and elect a new Executive Chairman (Stefan Barden, a 6% shareholder and former CEO of the company).
The resolutions were all defeated at a general meeting, but it was close: the failed resolutions received c. 40-43% of votes cast.
You can read the company’s detailed rebuttal to the arguments made in favour of the resolutions here.
This means that the company’s existing strategy continues.
And that brings us to yesterday’s full-year results for FY March 2023:
Revenue down 3% to £23.4m
Within this, “platform” revenue was up 40% to £17.4m (the other source of revenue, bespoke consultancy, is being allowed to decline)
Adjusted PBT £0.8m (prior year: £1m)
Net cash £5.7m
CEO comment:
"The business delivered a strong second half year and created momentum that has carried through into FY24 with profitable growth across our platform offering. We are relentlessly executing the plan outlined in the strategic review with a go-to-market strategy aimed at winning with the world's largest businesses; new product channels (digital and audio)
amplified by new partnerships, all spearheaded by a realigned executive team and John Kearon leading the charge on US growth."
John Kearon is the founder of Brainjuicer (now known as System1) and remains a 23% shareholder. On today’s Board, he is “Founder and President”.
The company argues that FY March 2023 was “a year of two halves”: H1 was all about “design and transition”, while H2 was about “relentless commercial execution”.
Financially, the company moved from year-on-year revenue decline in H1, to year-on-year revenue growth in H2.
Growth in “platform” revenue accelerated: from 34% in H1 to 45% in H2.
It’s worth mentioning that what the company calls “platform” revenue also includes “data-led consultancy”. A cynic might wonder if the quality of the revenue was improving all that much, if “bespoke consultancy” is being lost and then partially replaced with a different type of consultancy under a different name. The company would argue that the new category of consultancy work flows from its data-led ad testing service.
In its rebuttal to the resolutions put forward in April, this is what the company said (I’ve added the Bold):
In practice, we have found that ad testing is the best way to initiate a new relationship with a large business, because advertising is one of their largest and therefore most important annual investment. That's why Test Your Ad is the product we lead with, and then target to sell in Test Your Idea and Test Your Brand once we have won the relationship with the CMO and Head of Insight.
They also said:
We do not consider that Platform and creativity need to be mutually exclusive. We are selling predictions (product, feature) whilst at the same time selling the important benefit of creative confidence to our customers.
Outlook
FY March 2024 has started “promisingly”; the company is targeting revenue growth this year, has launched new “Test Your Ad” services for digital and audio ads, and the US commercial team is “making good progress”.
Canaccord Genuity made a slight upgrade to their FY 2024 adj. PBT estimate for the company yesterday, increasing it to £0.9m.
Net cash reduced from £8.7m to £5.7m during the year, so it’s still at a comfortable level.
A quick investigation of the cash flow statement shows me that the company spent £1.2m on “purchase of intangible assets” (last year, this was approximately zero). There is no mention of a change in accounting policy.
We always need to be careful when we find numbers like this. That £1.2m expense hasn’t shown up in P&L yet, but it will in future years, and it has already reduced the company’s cash pile.
Graham’s view
I remain unsure about this one. It has been years since meaningful profits were generated, although Covid was certainly an issue for some of those years:
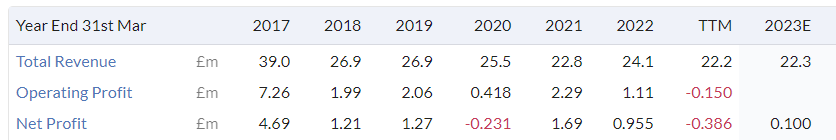
As someone who’s looking for a high-grade investment, I was interested in the tech-focused alternative strategy put forward by the resolutions in April. The current strategy is a mix of data products and data-led consultancy, and hopefully it will work out.
However, the PBT forecast for the current year is still less than £1m. Maybe the company will generate meaningful profits in FY 2025?
I don’t think this is a bad company by any means, but as an investment I’m not sure that it offers investors enough to get excited about right now. At a £22m market cap, minus a deduction for the cash balance, I think you need a lot of faith in the management team to want to get involved. Personally, I’m neutral.
Roland's section
Ibstock (LON:IBST)
Share price: 157p (+3% at 08.10)
Market cap: £610m
Today’s interim results from this brickmaker are in line and reiterate unchanged full-year expectations.
That’s an interesting contrast to Ibstock’s smaller rival Forterra (LON:FORT), which recently warned on profits.
Let’s take a look at what Ibstock has to say.
H1 highlights: the company says performance during the first half was “resliient” and “marginally ahead of the Board’s expectations”.
However, it’s worth noting that these expectations had already been scaled back to reflect more subdued conditions in residential markets.

Ibstock’s half-year numbers show a big drop in profitability and a rise in debt levels:
H1 revenue down 14% to £223m reflecting “a significant reduction in sales volumes”
Pre-tax profit down 42% to £30m
- Operating margin: 14.4% (H1 2022: 19.7%)
Earnings per share down 43% to 5.7p
Adjusted earnings per share down by 20% to 9.0p
Interim dividend up 3% to 3.4p per share
Net debt up £53m to £89m (H1 2022: £36m)
The main difference between adjusted and reported earnings appears to be the £11m cost of arising from a “potential clay site closure”. £1.5m of this is said to be a cash cost.
The increase in net debt reflects two factors. The first is a £39.5m working capital outflow to rebuild “inventory depleted since the pandemic”.
The second reason for the rise in debt was continued expenditure on growth projects, with £32.7m spent during the period. Developments underway include new brick slip manufacturing capacity and the redevelopment of a plant that will produce “the UK's first externally verified carbon neutral brick”.
Ibstock is also closing an older, higher-cost factory.
My sums suggest working capital outflows and growth capex totalled £72m during the period, versus a £53m increase in debt. This suggests to me that Ibstock’s operating business still generated underlying free cash flow of £19m during the half year.
Ibstock is already the UK’s largest brick manufacturer. Management seem to be hoping that they can invest through the downcycle and emerge as a larger, stronger, market leader.
If Ibstock’s view on future demand is correct and the firm’s balance sheet can take the strain, this could be a winning strategy – this is a profitable business. Operating margins were 14% during the first half of the year and Ibstock’s track record shows that it’s capable of generating consistent double-digit returns on capital employed:
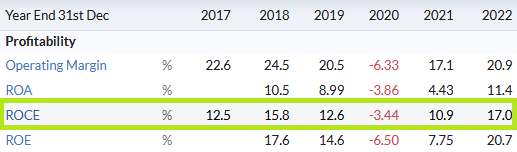
At present, management says that leverage is equivalent to 0.7x EBITDA, which does not appear concerning. However, it’s always worth remembering that this multiple can increase rapidly if EBITDA falls, even if net debt remains stable.
Outlook: today’s commentary leaves full-year expectations unchanged. However, management commentary does suggest some increased uncertainty to me:
While recent macroeconomic events have introduced greater uncertainty into the outlook, we remain confident in our ability to respond to market conditions and the Board's expectations for the full year are unchanged.
I can’t find any new broker notes today, but consensus forecasts on Stocko prior to today’s results suggested that Ibstock’s adjusted earnings would fall by 40% to 13.8p per share this year, before recovering to 15.3p per share in 2024.
For context, Ibstock generated adjusted earnings of 13.9p in 2021, so a repeat of this would not be a disaster.
The shares are up slightly as I write, pricing Ibstock on 11.5 times 2023 forecast earnings, with a 5.3% dividend yield.

Roland’s view
Ibstock floated on the London market in 2015, so the company hasn’t yet traded through a housing market downturn as a listed business.
My pick in this sector would be AIM-listed specialty firm Michelmersh Brick Holdings (LON:MBH) , which has a much longer track record as a plc and founder ownership.
However, I don’t see any major concerns with Ibstock and am encouraged by management’s ability to correctly guide expectations so far. Hopefully their view of H2 trading will not turn out to be over-optimistic (as happened at Forterra).
I think this is a decent enough business and I can see some potential value here. I’m going to take an AMBER/GREEN view, on the assumption that the housing downturn will be relatively short-lived.
However, I don’t know how accurate this assumption will turn out to be. If the downcycle becomes deeper or more protracted, Ibstock’s decision to draw down debt to fund growth capex could start to look much riskier.
This is very much a case of DYOR – I don’t think you can really take a view on housing-related stocks without also taking a macro view.
XP Power (LON:XPP)
Share price: 1,950p (-3% at 10.00)
Market cap: £385m
This is a backlog item from Tuesday, when this electronic power controller manufacturer published interim results.
XPP was a reliable performer (and a great investment) for many years, but it came off the rails last year.
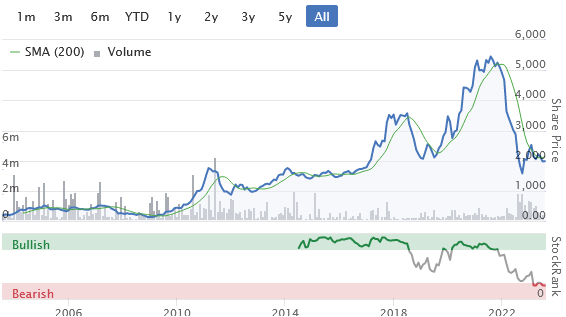
Graham covered this story in August 2022 and more recently in January this year.
In short, the company lost an expensive legal case and suffered badly from last year’s supply chain problems.
My feeling is that the underlying qualities of the business probably remain intact, so I’m interested to see if there’s any evidence of this in this week’s results.
Half-year highlights: XPP’s results cover the six months to 30 June 2023 and show the benefits of supply chain conditions returning to normal, with revenue and profits sharply higher.
Revenue up 30% to £160.2m
Gross margin up 1.6% to 41.8%
Adjusted pre-tax profit up 14% to £15.8m
Adjusted Operating Margin: 13.6% (H1 2022: 12.1%)
Adjusted earnings per share up 13% to 59.1p
However, order intake has softened, as customers destock and market conditions become weaker in some sectors.
- Order intake: £115.6m (H1 2022: £193.1m)
- Order book at period end: c£.250m (December 2022: £308.4m)
XPP’s backlog of orders remains elevated as a result of last year’s supply chain problems. So weaker order intake is not yet a concern for me, as the order book provides visibility through to next year.
Net debt/cash flow: the loss of a lawsuit in the US last year left XPP with net debt of £151m at the end of 2022.
Net debt fell to £148m during the first half, thanks to a modest working capital inflow.
The company says that on a covenant basis, leverage fell from 2.7x EBITDA to 2.3x during the first half of the year. Management expects this to fall below 2x by the end of the current year.
Operating cash flow was quite strong in H1, at £27.5m. However, cash generation for debt repayment was held back by other commitments:
Spending of £8.8m on relocating its US design centres and constructing a new plant in Malaysia
Debt interest payments of £7.6m (H1 2022: £1.0m)
Dividends payments of £11.2m
Rising interest rates mean this is an unfortunate time to be saddled with an unexpected rise in debt. Interest costs accounted for one third of adjusted operating profit in H1.
However, as the order book continues to unwind, I’d expect further cash to be released from working capital, aiding debt reduction.
XPP remains committed to its investment programme and expects to spend c.£30m on growth capex this year to support future US growth and reduce manufacturing dependence on China.
The dividend has also been maintained. XPP has a long and impressive record of shareholder payouts, so it’s clear this is important to the firm. But I wonder if it could start to be a headwind to deleveraging:

Outlook: trading has “much improved” over the last 12 months and the company expects this to continue into the second half of the year, despite macroeconomic risks.
Full-year expectations are unchanged and management reiterate plans to reduce financial leverage below 2x by year end – a more comfortable level. If this isn’t achieved, I think there’s a risk that a dividend cut will be needed.
Consensus estimates price the stock on around 12x forecast earnings, with a 4.8% yield.

Roland’s view
XPP isn’t out of the woods yet in my view, due to its elevated leverage. But I don’t see anything in these results to suggest that the company’s core franchise has weakened.
The company can’t escape macro headwinds, especially weaker demand in the semiconductor industry.
However, investments to support US growth and a more diverse manufacturing base make sense to me. I am also a fan of preserving the dividend, if possible.
I think the shares are probably cheap enough at current levels and could perform well if XPP can continue to deliver on its guidance.
I’m going to go AMBER on this share due to the risk posed by higher debt levels and external market conditions. But my overall impression is broadly positive.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Morgan Sindall (LON:MGNS) for some reason they released their interims @ 18:30.
I guess the danger is they (banks) will all look cheap when the times are "good" which they are now (when they aint bad they are good for banks imho) - amazing how things can go into reverse though quickly.
My only current banking one held is Virgin Money UK (LON:VMUK) - per stocky pe is 5.4 so probably the whole sector is in the same boat.
my logic for picking virgin money is pretty unscientific
they are not one of the big 4 - you dont have to do well to look good agsinst big 4.
they are amalgamating the different brands they came across into one , closing excess stores and concentrating on digital and employing their "Super Straightforward Efficiency plan" which sounds good to me (hopefully that term speaks for itself)
Thats not a recommendation for this company i must say - i suspect when it comes to banks we are all having a punt in thn hope that there is a hidden crisis about to unfold.
It looks like BurglarBill has uncovered some good news (thanks Bill!). The fact that the current tenants mothballed a while ago but continued paying rent (rather than doing a runner) suggested to me that they see value in the facility. Now having caught up with events (thanks to the ENDS Waste and Bioenergy site which has a number of articles about Hoddesdon), it is clear that the facility is under new ownership and they are looking to re-start generation in the next couple of months. This particular cloud hanging over Alternative Income REIT (LON:AIRE) appears to be moving on... sun on the way? Just hope the same happens on rather overcast holiday.
Character (LON:CCT) Has been drifting down for some time. Obvs "never catch a falling knife", but this is a share that has repeatedly had mini-boom and busts over the last 30 years. Many years ago (1993-ish) I had very good reports from the toy industry about the management at this company and have been following and sometimes participating since then. In December 2022 3 long-standing directors bought between them £210k shares @ £4.30. The current situation post-results is that a director (chair of audit committee) bought £20k shares @ £3.45 (director salary £40k, no options or other shares owned, has been a director for >2 years). Two directors have rejigged their shares into ISAs and family trusts. The guidance is for an improved 2nd half. I have decided to open a starter position today on the basis that the new Turtles film is getting very good reviews (so far) and the new Heroes of Goo Jit Zu toys are now in Argos. I had been waiting for a shock to the market so that I could pick some shares up on a spike down, but my hand has been forced. I'm really betting on the jockey(s) here and the market being a dog, so DYOR and size accordingly - nothing good happens below the 200 day moving average!
ME International (MEGP)
Hi Paul, I don't often post, but am an avid follower, thank you for all the good work that everyone at Stockpedia does on behalf of us, mere mortals. I am interested in your thoughts on ME International (MEGP) I hold. Serge Crasnianski who holds approximately 40% of the company through his investment vehicleTibergest PTE Ltd has announced a proposed share buyback of 10% of the company, presumably his intention will be to take his shareholding to over 50% and then "make an offer to the existing shareholders that they can't refuse" I know you have warned recently of investing in companies with dominant shareholders. I would be interested in your thoughts. Thank you.
ME International (LON:MEGP) In case you missed it, this was discussed yesterday on the SCVR. I don't think that is the intention at all, yes if the buyback happens in full, his share will go up to over 40%. From the RNS "Assuming utilisation of the full buyback authority, the Company's largest shareholder, Tibergest PTE Ltd, and persons acting in concert with it, may own up to 40.60 per cent of the voting rights in the Company. Therefore, the Independent Shareholders will be asked to waive an obligation on the Concert Party to make a general offer for the entire issued, and to be issued, share capital of the Company which may arise under Rule 9 of the Takeover Code as a result of the Company purchasing its Ordinary Shares."
My sense (for what it is worth) is that the previous bid was opportunistic in nature. The CEO considered there to be deep value unrecognised by the market and tried to take advantage.
today the stock is much more reasonably valued so I suspect that is much less likely even if a buy back takes him up over 50%.
however, if the stock were to drop down again for some reason other than a material deterioration in trading then I’d put low odds on him trying again so that’s probably worth keeping an eye out for.
ME International (MEGP) Hello Rusty, thank you for pointing that out to me, I was out yesterday afternoon and missed it. I've just read it and I noticed that you stated.
"But if the holding, goes over a certain %, does the holder not have to declare his intentions? Anyway, I can't see any failed bid attempts, which was my point."
Are you aware that In March 2022 Serge Crasnianski made an offer to acquire the remaining 63.5% stake in Photo-Me International plc (LSE:PHTM) for £180 million on January 21, 2022.
I was not aware, not holding at that time. Was that not just to comply with the take-over rules, so put in a low offer.
RE: ME International (LON:MEGP)
Are you aware that In March 2022 Serge Crasnianski made an offer to acquire the remaining 63.5% stake in Photo-Me International plc (LSE:PHTM) for £180 million on January 21, 2022.
It was a mandatory bid under the takeover rules when he went over 30%. The assumption at the time was the entirely desirory, no premium offer, was because he had no choice but had no wish to actually succeed.
The market agreed, with only 0.04% of holders accepting the offer.
timarr
ME International (LON:MEGP)
That was my recollection at the time Timarr as well.
https://www.londonstockexchang...
https://www.londonstockexchang...
ME International (LON:MEGP) That was my understanding, he had to make an offer.
I took yesterday’s RNS as the polar opposite of Serge trying to take over ME International (LON:MEGP) . The RNS and forthcoming GM are so the buyback can start without him having to make an offer & allow his shareholding to go over 40%
His previous offer (as others have said) was compulsory. Whilst he is a ‘mature’ age of CEO, both his children work in the business so I don’t see him as wanting to take the whole company over- rather I’d see his eventual exit as being a result of a chunky takeover by another company. As a shareholder I hope this doesn’t happen too soon
That's was what l was trying to say, sorry if it was not clear.
Excerpt from Paul's review of the profit warning issued by Headlam (LON:HEAD) on 27/7/23:
Outlook/Dividends - rather convoluted wording here. I think they’re trying to say that divis will be maintained, hence cover is reduced?
It’s not at all clear what that means. Badly worded.
It now looks like Paul's (and my initial) interpretation that the temporary lowering of dividend cover would prevent a need to cut dividends was wrong. Revised forecast dividend is now 9.13p which is a cut of 47.5% reducing the yield from nearly 8% to 4%. This puts a big dampener on the investment case.
Reducing dividend cover means they are paying out a higher proportion of their profit as dividends. In this case, profits down but dividend held. I've also seen it used when dividends are increased at a faster pace than profits. Agree, it's a somewhat confusing term and companies should find a clearer way of explaining their dividend policy.
Except in this case it doesn’t of course as the dividend expectations have also been slashed.
it looks like dividend has been cut but even at the cut level the dividend cover has reduced - ie they are paying a higher %age of profits out but less in nominal terms.
hi Bouden54
re Headlam (LON:HEAD)
I understand what you say and had interpreted the company's comments in the same way you had i.e. that the dividend payment would be held for FY '23.
However, the revised dividend forecasts contradict this interpretation with dividend forecasts of 9.13p, 11.3p and 13p for the next 3 years set against last year's dividend of 17.4p.
Both cannot be correct so it remains confusing at best.
Both can be correct. The RNS states that Headlam will reduce dividend cover to pre covid level. Per stockopedia stockreport page for Headlam the dividend cover was 1.57x in 2017 and 1.59x in 2018, dividend cover had risen to 2.31x last year (and been all over the place during covid). These forecasts reduce dividend cover back to 1.6x next year but due to the lower forecast profit level this also relates to a reduced absolute dividend.
I agree this slashes the investment case for Headlam, this is a new management team looking after a valuable brand. However the management teams at Halstead (different business model and exceptional, proven team) and Likewise (identical business model and proven team from Headlam days) would seem much safer choices at present.
SCS (LON:SCS) which I hold seems to be increasing in price. Not seen any news-other than a shareholder notification by Valentum. Been looking good value for a while now-Stock Rank 94, yield 7.74%. Has anyone seen a tip in the press?
Housebuilders again!
When the bad news ( from Nationwide on house prices and Taylor Wimpey on lower profit) on a down day like today, FTse down 110 so far, does not sink the housebuilders shares it is time to take note!
looking ahead , in two years time, when the inflation is around 2% and interest rate is a little higher than that, the value on the offer from the Housebuilders are outstanding.
Taylor Wimpey (LON:TW.) wasn’t bad news though. It was at the upper end of previously set expectations with a very healthy net cash balance that at current interest rates also adds a considerable amount to PBT.
However, I would say this does not necessarily translate to other house builders. I’d say Taylor Wimpey (LON:TW.) is both of higher quality than most and has a housing stock demographic that copes better in times of housing market pressure than others. With a 10p EPS (rather than forecast of 9) the 7.5% of NAV dividend is also covered which will have acted as a relief to the market.
All that said I agree that on a cyclical basis some of the house builders offer really good value. Unlike previous economic downturns where they were highly leveraged this time a number of them have very strong net cash positions and can both weather the storm, maintain profitability and pay 8% dividends. That sort of resilience “should” be rewarded by investors but patience will be needed.
Arbuthnot Banking (LON:ARBB) just saw a new house broker note out on Research Tree and seems like a lot of value in this business.
Whilst NIM will normalise RoTe back to mid teens by 2025 EPS is expected to stay around the 220p mark making this (on a 1 year forward basis) a 5% yield on a 4.5*PER with a conservative banking model and a TNAV of 1700p (so trading at a price to book of just 0.6).
Just looks like the wrong price surely?
ARBB,
I think the banking sector with current share prices are good value. lots of bad news are predicted and most likely there will be a recession and the unemployment will rise.
The banks however are well capitalised and have put aside some good provisions. Dividend on offer for income seekers is great.
Natwest (LON:NWG) - Interesting points re the banks.
I've just started looking at this particular share in a bit more detail today, on the initial broad investment theory that the Farage/account cancelling issue that seems to have caused the recent drops could be an overdone black swan event. There may be value in taking a shorter term position (than I usually invest) once support forms (around 230ish usually), back up to around the 275 levels its previously hit this year.
I am a big fan of HSBC. Really impressive 6 months results and £2 billion share buy back . Very good yield with expected “ special 24p “ bonus divided per share expected next year . Some may be put off by China issues but having lived most of my life in Hong Kong , this is a strength not weakness .
Agree Arbuthnot Banking (LON:ARBB) looks very interesting, although the wide spread has put me off and prevented me from taking a position so far. Just can't face taking an immediate 5% hit!
Haha - yes I hear you Bouden. It’s a ridiculous spread for investors to swallow. Assuming you are using a decent broker you should be able to get well inside that offer price though if you leave an order.
Well, markets were looking stable until yesterday!
Thank you to yiannos1 and Rusty2 for pointing out my error yesterday re National World (LON:NWOR) in relation to the shares held by Aberforth.You are spot on Rusty2 I did use the Stockopedia numbers but failed to realise, which was careless of me,that under the 19% figure was the breakdown of the 19% and as a result I added them all together.My apologies I will not make that mistake again!
Link from StockReports to holders
portugull - don't worry we've all made mistakes like that with Stocko's wierd and wonderful notations.
You did also make another more common mistake yesterday by writing "73.37% in institutional hands". Not so! When you press Stocko's Institutions View button that is not what you get - you get the top holders be they individuals or institutions. In microcaps with few large holders you sometimes see execution only brokers nominees there.
After a green button argument about an institutional holder with 5% being missing I found out that the list is limited to a maximum of 10 lines. This could be 10 holders but in this case with Aberforth taking up 3 lines you only get 8 holders!
Stocko info. is not always correct. I reported one about 5 months ago, which is still uncorrected.
It is a bit misleading, mixing institutions with individuals and calling them all institutions.
There is some astonishing value on offer at present in UK smaller companies but very few are interested.
Examples from my portfolio, so I am biased, are IG group (LON:IGG, oodles of cash, forward PE 7.5ish, yield close to 7%, this morning announced the start of further £250m buyback . The sole purpose being to reduce the share capital.
Also Palace Capital (LON:PCA) has just announced a further sale to add to those announced at the recent AGM update. A property in Maidenhead at close to 10% above March 23 book value. Its net debt on completion of will be £0.1m, yields 6%, recent NAV update of 304p versus a share price of 236p. It also just commenced a further buy back program of 1 million shares, having earlier this year bought back in excess of 1.8 million.
All seems crackers to me, but no one is interested. At some point the pendulum will swing back and the value on offer will be recognised. If one is standing on the side lines at the inflexion point whenever it happens it will be too late
I agree on Palace Capital (LON:PCA)
In reality the NAV as at end march of 304p is artificially deflated.
Most of their asset sales are about 10% higher than NAV and the buy backs at such a discount adds another 8-10p
So in essence I think real wind up value is circa 345p which gives me about 50% upside and should be completed in about 2 years I think. On that basis it should prove to be a good compound 2 year trade for the patient.
Interestingly net debt is now zero after current sale so no exposure to refinancing or cost of debt.
Agree Jonno- and Peter Gyllenhammar AB have a 11.55% stake.
In comparison to Home Reit (LON:HOME), Alternative Income REIT (LON:AIRE) results this morning look ok. Renewal of Pets at Home looks a good deal for the tenant but at least they're not doing a CVA. And a near 10% divi (Stocko figures for yield not correct unfortunately). SP up 2% at 8.30am
Regarding Alternative Income REIT (LON:AIRE) - what is your view on their power generation site Hoddesdon Energy? It's been idle for quite some time and is going to be mothballed by the operator. I'd think it would be hard to repurpose that and timely to rent again. I continue to have a tiny position only until there's some clarity.
RE Alternative Income REIT (LON:AIRE) & Hoddesdon Energy. According to https://www.endswasteandbioene... there is a new owner.
A little respect and huge congrats to the holders of the Data ERASURE software specialist (BLTG)
Blancco Technology (LON:BLTG)
Indeed jmallin, one I missed. For non IT people, when you delete a file on your phone or computer, to save time the file is left intact but only the entry in the directory is deleleted and the area of storage used is made available for re-use.
This is obviously a security risk and their software will ensure the file is over-written on deletion. A very useful addition to corporate security.
I missed this too; data erasure (and certification) just seemed dull! Wikipedia has a short overview giving its history.
https://en.wikipedia.org/wiki/...
Yesterday Ricardo (LON:RCDO) provided a trading update. I used to be a shareholder but had second thoughts and sold. The company grows through acquisitions and the successful ones flow through to earnings. The less successful are written off but the cost goes under the heading ‘specific adjusting item’ and not included in normalised earnings which the group regards as “a more useful indication of underlying performance and trends over time.”’ Over the last six years normalised earnings has always been higher than reported. The average EPS for normalised earnings has been 36p compared to 20p for reported. I suspect however that reported is a better indicator of value added by management.
Lookers (LON:LOOK) welcome news that Cinch have given an irrevocable undertaking on their 19.5% holding in Lookers to the 130p bid by Global Autos
This should edge the market price (currently 124.6p) a little nearer 130p as the bid now looks more likely to go through
My morning smallcap tweet: Two REITs don't make a wrong
Home Reit (LON:HOME) Target Healthcare Reit (LON:THRL) Blancco Technology (LON:BLTG) React (LON:REAT) Palace Capital (LON:PCA) CAP XX (LON:CPX) Evgen Pharma (LON:EVG) Cyanconnode Holdings (LON:CYAN) Oxford Biodynamics (LON:OBD), Property Franchise (LON:TPFG)
◄Home REIT (HOME)► two tenants make CVA. Was 12% total of rent income. This "unlocks the ability for the Company to re-tenant the properties or to carry out other asset management initiatives." [SP=38.05 Cap=301m]
◄Target Healthcare REIT (THRL)► EPRA NAV 104.5p/sh, up 1.1p from Mar. 99% rent collection reflecting improved trading and demand. [SP=73 Cap=453m]
◄Blancco Technology (BLTG)► rec offer of 223p, a 25% premium. [SP=178 Cap=136m]
◄React (REAT)► wins £1.8m 3 yr contact. £100k in this FY. [SP=1.54 Cap=16m]
◄Palace Capital (PCA)► sells Maidenhead office property for £9.6m, 10% above book. [SP=235 Cap=98m]
◄CAP-XX (CPX)► warns FY-June rev A$4m and adj EBITDA -A$1.2m. Cash at hand A$2.6m. Blames some orders slipping into Q1. "The sales pipeline reporting is being reviewed to improve the accuracy, reliability and insight of known opportunities." [SP=1.7 Cap=12m]
◄Evgen Pharma (EVG)► terminates Patent and Know-How License Agreement with Juvenescence for Evgen's Sulforadex. [SP=3.2 Cap=9m]
◄CyanConnode (CYAN)► gets another order for 300k modules under framework agreement for 3m. [SP=13.59 Cap=37m]
◄Oxford BioDynamics (OBD)► [last night] £5.6m placing at 11p, a 4% premium, to keep the lights on. [SP=10.4 Cap=15m]
In line: TPFG
"Two REITs don't make a wrong"