Small Cap Value Report (Wed 24 July 2024) - NICL, GNC, MEX, NXQ

Good morning! There are lots of updates to keep us occupied today. Hanging up the pen for today - hopefully we will have a chance for some catch-ups later in the week. Thanks!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
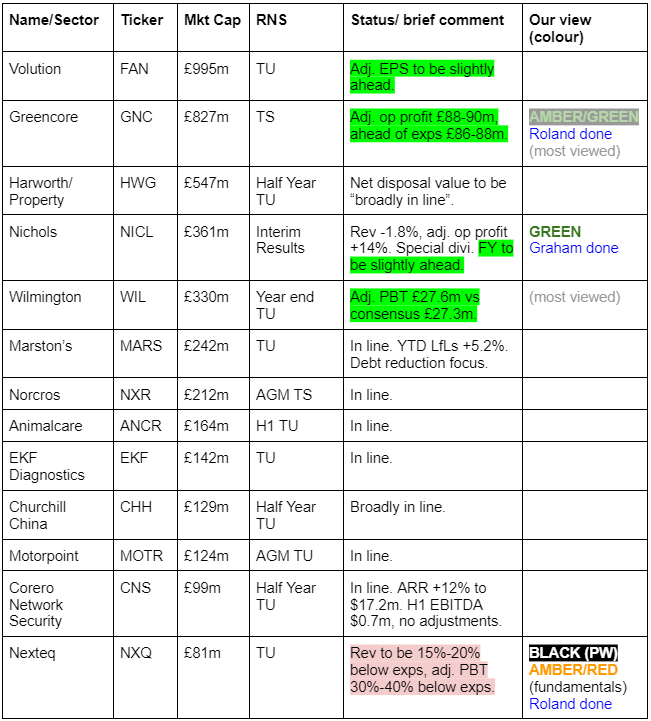
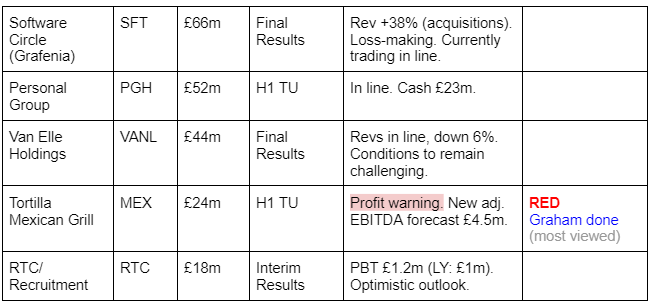
Graham's Section (No Summaries today due to time constraints)
Nichols (LON:NICL)
Up 7% to £10.68p (£390m) - Interim Results - Graham - GREEN
Soft drinks group Nichols has published a huge table of “key financials”, here are the best bits:
Revenue down 1.8% to £84m
Adj. PBT +18% to £14.5m
PBT +5.8% to £11.8m
Cash £70m (last year: £56m)
Given the strength of trading, and the growing cash pile, the company announces a one-off special dividend worth £20m, or 54.8p per share.
On top of regular dividends of about 30p p.a., that means a payout of c. 85p for shareholders this year.
This amount is not fully covered by this year’s earnings but it’s affordable in the circumstances and for me is a fresh indication of the company’s shareholder orientation. Nichols still very much looks and acts like a family business, even if times have moved on.
CEO comment:
Positive trading momentum in our UK Packaged business reflected further market share gains in squash and carbonates, driven by increased marketing investment, growth from innovation, and distribution gains. Our biggest ever UK promotional campaign was launched towards the end of the Period, and we are confident this will support the continued growth of the Vimto brand over the summer.
Whilst mindful of continued pressure on consumer spending, despite levels of inflation stabilising, our diversified business model and the enduring strength of the Vimto brand have enabled us to deliver a strong performance. As a result, we now expect full-year profitability to be slightly ahead of current market expectations and we remain confident that Nichols is well placed to deliver its strategic growth ambitions."
Estimates:
Checking the latest broker note from Singers, they have upgraded their EPS estimates by 4% for each year from 2024 to 2026, and they note that Nichols is trading at a discounted earnings multiple against its own historic average and against the buyout multiple given to Britvic (LON:BVIC) by Carlsberg.
Graham’s view
We have a lot to look at today so I’ll keep this brief. I’m delighted to see the investment thesis playing out here, as this is a stock I’ve backed on multiple occasions. Please see my comments in April. There is still a long way to go if Nichols will ever achieve its historic operating margins, but it’s moving in the right direction.
Strategic decisions to exit unprofitable contracts (at the cost of lower revenues) are proving to be the right ones. The company’s assurances that weak trading in Q1 was caused by temporary timing issues have proven to be accurate. And now they are rewarding patient shareholders with a large dividend, instead of embarking on risky and expensive projects as many AIM-listed companies would be tempted to do.
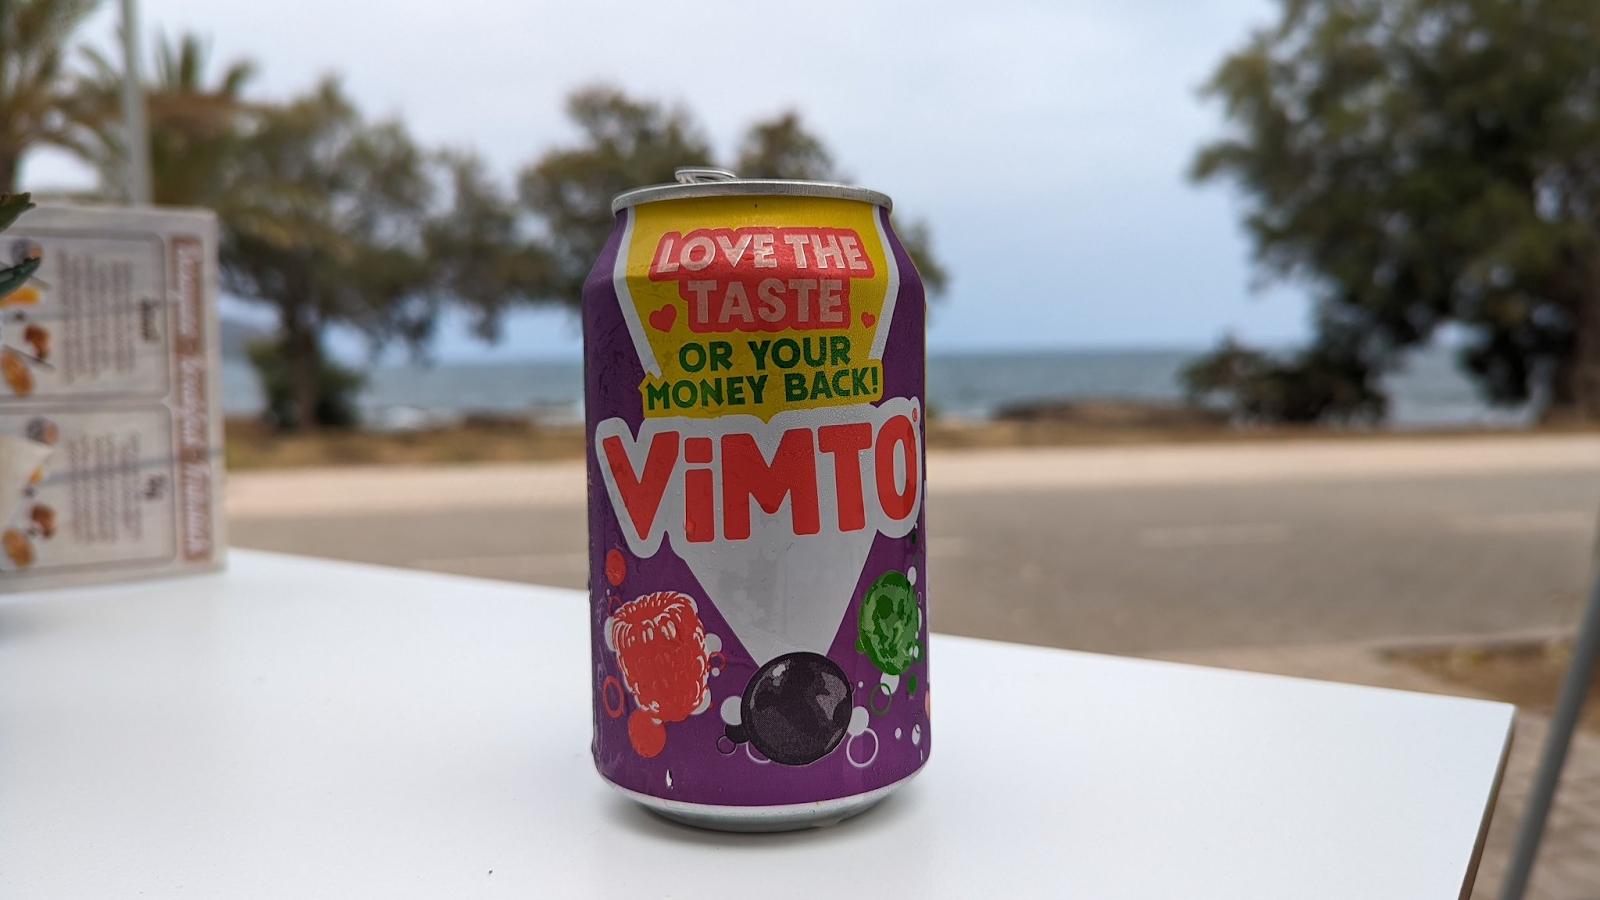
Before finishing, I should admit that I engaged in a bit of self dealing while on my recent holiday in Mallorca. It wasn’t the drink that I wanted the most, but I really wanted to help Nichols produce a good H1 result. So I bought several cans of the purple stuff. And I didn’t regret it: it was wonderfully refreshing every time.
Tortilla Mexican Grill (LON:MEX)
Down 20% to 50.3p (£19m) -H1 2024 Trading Update - Graham - RED
It’s bad news from this restaurant group, I’m afraid.
Key bullet points:
LfL revenues down 5.9% (GN note: this is despite MEX raising prices vs. last year)
Adj. EBITDA £1.8m, same as H1 last year.
Outlook: full-year adj. EBITDA £4.5m. Previous forecast from Panmure Liberum was £5.1m.
Net debt was £3.3m at the end of H1 and is forecast to increase to £7.5m at year-end.
CEO comment:
We are now seeing the positive implementation of our strategy across all five pillars as we continue to strengthen Tortilla's offering and position the business to capitalise on the long-term significant opportunities in our market as the dominant European market leader in fast-casual Mexican cuisine.
In the first half of 2024, we have significantly improved the quality of our food and are driving exciting innovation with our new Food Director, James Garland now onboard. We have accelerated the deployment of kiosk-ordering technology and will be launching our new loyalty platform at the beginning of August. Whilst the timing of these initiatives has been slower than planned, the early signs are positive, and we look forward to updating shareholders on progress in September."
Graham’s view
I’ve quoted several paragraphs of the CEO comment because I would like readers to be able to read the bullish argument, too, in addition to what I’m going to say about it.
In general, I’m not a fan of restaurant shares. So it’s true that I’m already biased against MEX, even before I read its profit warning.
Firstly, this is a sector where EBITDA is useless - the depreciation charge “D” is real. Fixtures and fittings need to be replaced every few years, and shareholders will have to pay for it one way or another. Expansion capex is a separate category of spending, but of course there is also greater uncertainty around the ultimate payoff for that spending. The bottom line is that I give zero credit to any restaurant company for having positive EBITDA.
Secondly, this is a sector where there is inherent leverage from leases, legal liabilities which used to sit off the balance sheet but which modern accounting rules require to go on the balance sheet, where shareholders can see them more easily.
The last set of full-year results from MEX showed lease liabilities with a present value of £35m.
MEX has combined this with financial leverage in the form of bank loans.
It has embraced this risk by making an acquisition in France (!) for €4m before the UK company has succeeded.
In terms of how the business is trading, the recent fall in LfL revenue is attributed by the company to the decision to use a “dual delivery platform to improve profit conversion and increase focus on in store revenue”.
If I was to describe what happened in plain English and perhaps in a more cynical way, I would say that they simply dropped Deliveroo (their 3rd major delivery partner) because they couldn’t afford Deliveroo’s commissions. That decision, combined with fewer visitors in store, explains their falling sales.
Net assets? The Dec 2023 balance sheet showed no tangible asset backing here.
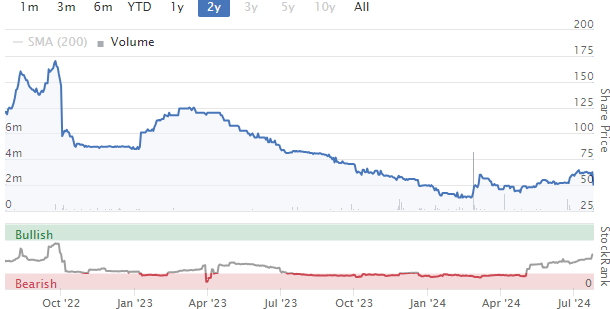
I’m afraid I do not see any attraction to this share, and I think it’s very risky, so I’m putting a RED on it.
Roland's Section
Greencore (LON:GNC)
Up 4% to 187p (£850m) - Q3 trading update [ahead] - Roland - AMBER/GREEN
Upgrading FY24 outlook of £88-90m Adjusted Operating Profit, ahead of prior guidance and current market expectations
Sandwich and convenience food producer Greencore has issued a positive Q3 trading update today including an upgrade to full-year guidance and confirmation that the company will restart dividend payments this year.
This is a fairly modest upgrade – the company helpfully cites its previous guidance for an adjusted operating profit of £86m-£88m. This has now been upgraded to £88m-£90m.
However, an upgrade is an upgrade – and in fairness, there were some headwinds during the quarter. Wet weather affected sales in some categories and a major salad recall due to E coli concerns was a further challenge.
Q3 highlights: chief executive Dalton Philips is focusing on profitability as well as volume. During the last financial year, he sold the Trilby Trading vegetable oil business and exited some low-margin contracts.
Largely as a result of these changes, Greencore’s reported revenue is down this year. However, rising profits and like-for-like sales growth in most categories suggest to me that Philips’ strategy is delivering results:
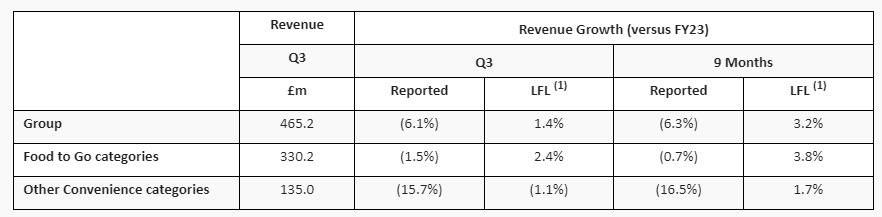
The company says performance in the sandwich category was broadly flat against a 1% market decline. Meanwhile, there were positive LFL volumes in chilled ready meals, sauces and sushi.
Cash conversion from profits is also said to be improving due to operational and cost initiatives. The company has restructured its soup business and launched a number of new premium food offerings during the period.
A £30m share buyback is underway and a dividend will be declared for the year to 30 September 2024.
Updated forecasts: a note from house broker Shore Capital today (with thanks) suggests a payout of 3.5p per share for FY24, supported by (unchanged) adjusted earnings of 10.5p per share.
Those estimates price the shares on a FY24e P/E of 17 with a 1.9% dividend yield.
Roland’s view
Greencore was hit hard during the pandemic due to its heavy dependence on out-of-home sales. But it’s delivered a series of improving results since 2021 and operating profits have now risen above pre-pandemic levels.
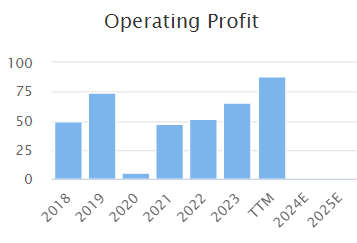
Greencore’s long-term share price history suggests brutal cyclicality. But investors who have bought at the right times have done well.
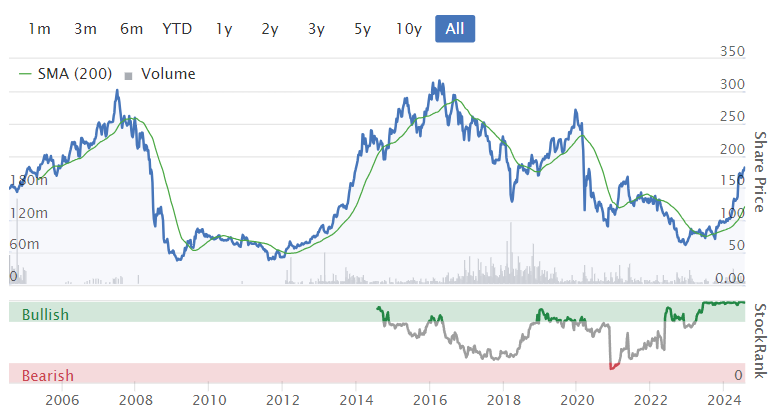
Today’s update suggests to me that the current cycle may have plenty of distance to run.
While the forecast P/E of 17 is not obviously cheap for a low-margin business, I can see a couple of catalysts for further gains:
Having made changes to exit low-margin businesses, Greencore is now better-positioned to focus on growth from higher-margin categories, including new ranges
This improving profitability could drive operating leverage (when profits rise faster than sales)
I’m positive on the outlook here and believe the fundamentals are improving. But this is still a low-margin business, and I think it’s probably fair to say that some of the good news is already priced in.
On balance, I’m happy to maintain our previous view of AMBER/GREEN on Greencore.
Nexteq (LON:NXQ)
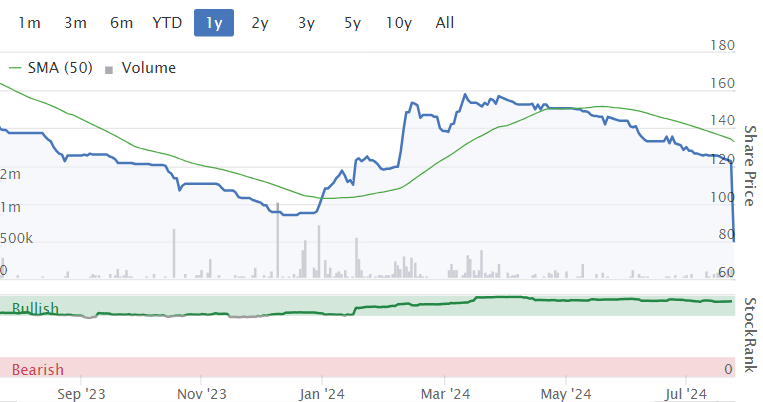
Down 35% to 80p (£53m) - Trading update [warning] & Board transition - Roland - BLACK (pw) / AMBER/RED (fundamentals)
It looks like something has gone wrong at technology firm Nexteq, which has issued a big profit warning and announced the departure of its chair, CEO and CFO.
This is a technology firm that produces software and hardware controls such as touchscreens. It has two core businesses, Densitron (industrial customers) and Quixant (casino/gaming). The company was renamed from Quixant to Nexteq in 2023.
H1 trading update/profit warning: the company says it has continued to see industry de-stocking during the first half of this year. In addition to this, some larger Quixant customers (gaming operators) have reported lower demand and have apparently decided to delay planned product launches/upgrades.
The impact on trading seems quite severe:
H1 revenue expected to be down 15% to $48.2m
Quixant H1 sales expected down 10% to $30.9m
Densitron H1 sales expected down 22% to $17.3m
There is some positive news on margins and cash generation:
Increased gross margin is expected to result in “double-digit adjusted profit before tax margins”
Net cash at 30 June 2024 of $36.9m (31 Dec 2023: $27.9m)
This net cash balance covers more than half the company’s market cap after today’s slump!
Full-year outlook: the company says its strategy is to diversify by targeting new customers in the Gaming and Broadcast sectors. An improvement in order intake was expected in H2, but this hasn’t happened yet.
Although we are still relatively early in the second half, it doesn’t sound like the company expects any recovery later during the period.
Nexteq has now cut its guidance for full-year revenue by 15%-20%:
As a result, H2 2024 revenues are expected to be broadly in line with H1, which would result in FY24 revenues 15%-20% below market expectations
Despite the strong margin performance mentioned above, the company expects a big hit to profits due to the reverse operating leverage impact of reduced sales (my emphasis):
expects adjusted profit before tax to be 30%-40% below market expectations, primarily driven by the lower revenues.
According to todays’ update, previous consensus expectations were for revenue of $115.4m and adjusted profit before tax of $14.9m.
Using the mid-points of today’s guidance, my sums suggest revised revenue expectations of c.$95m, with adjusted pre-tax profit of perhaps $9.6m.
Helpfully we have an updated broker note from Canaccord Genuity today.
CG has cut FY24 eps estimates by 40% to $0.11 per share. FY25 earnings estimates have also been cut by 40% to $0.12 per share.
These estimates potentially price the shares on less than 10 times forecast earnings, after today’s 35% slump. But I would not rule out the risk of further downgrades at this early stage, perhaps when new management takes charge.
The company sounds bullish about the outlook for 2025, for what it’s worth:
The Board expects to see an improvement to order intake in 2025 as key customers' buying patterns normalise and the Group benefits from the healthy pipeline of new customers across both Quixant and Densitron. The Group benefits from a robust operating platform and diversified product portfolio, and the Board continues to have confidence in the Group's organic growth opportunities in the medium term.
However, with both top execs due to leave, I would not attach too much weight to this view without further evidence of a turnaround.
Board transition: Commenter AstonGirl says it sounds like a night of long swords at Nexteq. I can’t disagree with this!
The CEO, CFO and non-executive chair have all announced plans to leave over the coming months, once successors have been identified.
Founder and Deputy Chair Nick Jarmany (16.9% shareholder) is fulsome in his thanks to each, and says that their decisions to leave have been “carefully considered over some time”.
It’s an unusual situation, in my experience. These three directors are responsible for setting and executing strategy and control all investment decisions. Apparently they are not leaving in disgrace, but they have all decided to resign at the same time.
My best guess at what lies behind this change might be that the top team is no longer in agreement with founder Mr Jarmany about the future direction for the business.
The company says it expects to appoint a new independent non-executive chair shortly.
I wonder also whether Mr Jarmany might consider taking a more active role again, perhaps as interim CEO.
Roland’s view
With hindsight, Paul spotted the warning signs on trading here when we last covered this company in March 2024:
The wobbly, over-PR'd outlook statement spoils it for me though, with a soft H1 in 2024 now seeming likely, and it dodged the question of meeting 2024 profit expectations, instead only confirming revenues - which strikes me as deceptive, and introducing doubt. Very odd to be raising broker forecast at the same time as giving a wobbly-sounding outlook
Back in March, Nexteq said it had a “confirmed order book covering five months of revenue”. However, revenue was expected to be weighted to H2.
It seems that order intake has fallen far below expectations. Without further research into the company and the wider sector, it’s not clear to me whether this reflects external conditions or company performance. Or both.
However, given the uncertain outlook for the business and the expected change of management, I have no choice but to take a cautious and somewhat sceptical view at this point.
Nexteq’s performance was inconsistent, even before the disruption of the pandemic:
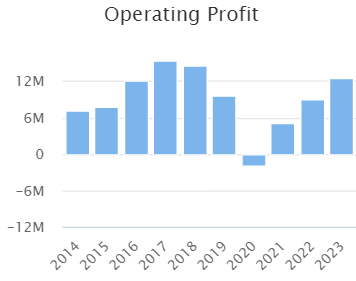
Perhaps the problems we’re seeing now are the culmination of decisions made a few years ago? I’m not sure.
The only saving grace of this situation is that Nexteq’s balance sheet appears to remain very strong, with net cash covering half the market cap and roughly one year’s operating expenses (based on FY23 results).
This pile gives the group breathing room and optionality – the benefits of this cannot be underestimated in a situation where things haven’t gone to plan.
The strong balance sheet means I’m not worried about an imminent collapse here. I think the equity looks safe for now. But the outlook is clearly uncertain, and in my view, today’s news raises questions over the group’s strategy and perhaps its product portfolio.
I’d need to do more in-depth research to understand these issues. For now, I’m going to adopt an AMBER/RED view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

109 comments
Tortilla Mexican Grill (LON:MEX)
Is it any good - make my day amigo
Cracking trading update fromLBG Media (LON:LBG) today. Not sure if anyone has mentioned it already, but I’m wondering if you think it might be worth having a look at Paul. I hold , surprise surprise!
Odd trade in Murray International Trust (LON:MYI) a short while ago
Quick question; looking at Stocko-generated metrics below
Is there a rule that can be applied to find companies where one of these metrics (such as stock rank) has moved up or down by a given amount (say 10%) over the last week, month, 3 months, 6 months?
Please share it with me when you find one! More to the point though I've recently set up another vitual portfolio which is comprised only of 80+ QVMSR/R shares, the monitoring of these may lead to fruitful decisions on my behalf. On any particular company Stock Report, next to the ADD TO PORTFOLIO tab you can click PRINT tab to check on past reports of that company. Time consuming though.
P.S. A qucker way is to click the performanc eline on the graph and running the cursor back and forth will show the price and stock rank on any day in the past.
hi Turbo. chk out the LEARN at the bottom lots of good stuff on the tools. https://www.stockopedia.com/le...
Paul Scott and Ed croft have done video's on playing with screeners and you can definitely do what you wanted above using rules.. . They are packed with gotcha tips. i didn't think I'd get much out of them but they are excellent and an easy watch.
in fact I highly recommend any subscriber, who hasn't perused the libary of Vlogs, to invest a few hours. you are missing out on a rich vein of "toolfullness" that comes with Stocko..
much as the SCVR (and also the discussion board) are my daily goto for stock knowledge, the articles that Roland, Mark, Edmund and others, in house, really useful insights into strategies and ideas.
if we're paying a fee, might as well explore all the nooks and crannies of the site.. it might even provide us with a wonderful opportunity...
good luck
.
Honestly this market baffles me sometimes, great trading update from easyJet (LON:EZJ) and it's only 4% up, less than the drop due to Ryan air's crappy results on Monday.
Oh well, as Benjamin Graham said — 'In the short run, the market is a voting machine but in the long run, it is a weighing machine......'
Hargreaves Services (LON:HSP) Results delayed till not later than the 6th Aug from the 31st July. They did the same last year, due to auditors needing more time for the German JSV. Still expecting results at least inline.
Hi All,
Can anyone please kindly breakdown how Tortilla Mexican Grill (LON:MEX) arrived at the £375-475k costs to open a new site. The Investor relations/management weren't interested in responding to my emails nor replying to my Investormeet question at the time.
Personally I just don't understand how it costs £375-475k to fit out a new site. Couple of years back I arranged to refurbish/fit out an entire house (all rooms), new kitchen, bathrooms, units, flooring, tiles, paint, even roof etc.. for a fraction of that. I doubt any of the food places we see opening up on the high streets are spending that much either.
Presumably I'm missing something....marketing costs?
Look forward to hearing from folks.
Thanks
I wouldn't compare a house to a restaurant fit out. The kitchen fit out alone could be well over £100,000. There are things that people don't always realise the cost. Like a good air con system could be £20k plus. A decent coffee machine can be over £5k. You want the place looking good and with all the correct equipment - it all adds up. £375k does sound a lot - what do the premises look like - are they looking very appealing and high end - or does it look like they are just wasting money? I have not eaten their food, or been to their premises and have no position. I strongly agree with Graham and his caution over depreciation, as it's often overlooked, but often ensures that many of these types of businesses never make any money. A large part of the tangible asset value can be a future liability as it will need maintaining and replacing - and usually its just to tread water and maintain revenues instead of growing the business.
Thanks
Comparison was for context purposes, not like for like.
I have been to a few of their shops. Quite like the product but only the veg/vegan options. The meat quality/mixture/texture I'm not keen on .
Some outlets look a bit more fancier then others with upstairs/downstairs, and sizes can vary but still seems like they are paying a lot as they aren't that big overall and 375k-475k is the range.
Here is what CHAT gpt had to say......
Certainly! Here's a more detailed breakdown of fit-out costs for a typical Tortilla restaurant in the UK. The Tortilla chain, which specializes in Mexican food, typically falls into the mid-range category for fit-outs, but I'll include a range of possible costs:
1. Shell Condition Preparation
2. Mechanical and Electrical (M&E)
3. Flooring
4. Walls and Ceilings
5. Furniture, Fixtures, and Equipment (FF&E)
6. Decor and Branding
7. Professional Fees
8. Permits and Licenses
9. Contingency
Total Estimated Costs
These estimates provide a broad range to accommodate different levels of quality and specific requirements. The actual cost for a Tortilla restaurant would likely fall somewhere in the mid-range given the chain's typical design and equipment standards.
Example Calculation for a 100 Square Meter Mid-Range Fit-Out:
Hi Buy100ozSilver,
Yes c.£400k is about right for the capex for a MEX casual dining restaurant.
It depends on the size, shape, and existing condition of the sites they take on.
Although remember that there would have been generous landlord contributions in capital costs and rent-free periods to partially offset some of the £400k capex, over the last few years.
Factor in a consumer recovery, with high gross margin (typically c.70-80%) sales up say 10-20%, and a lot of these sites could become highly profitable.
Meanwhile it's bumping along around breakeven, which in current market conditions is not too shabby - this is a very tough sector, with lots of indirect competition.
Regards, Paul.
Thanks Paul , maybe I need to visit some more trendier sites ~£400k seems a lot for the sites I've been to and not that big either. Perhaps commercial fit outs are more expensive
I've eaten at + used delivery options for tortilla quite a few times. I actually managed to get Large bowls/wraps for very cheap given the discounts this year. I think I got as low as £12 for 2 large including delivery which is seriously low.
Looks like they might be struggling for customers so desperately trying to boost revenues as fixed costs overall are quite high, and given that gross margins are high it makes sense to drive volumes via utilising discounts.
Every time I've visited an outlet in my local area especially in the past 12 months, there is often a delivery driver ready to take the order, but not too many eating at the site itself.
Unfortunately Tortilla in some sense haven't done themselves a favour when it comes to discounted delivery options - I now feel entitled to a substantial discount and sometimes get a delivery from elsewhere if I don't get that discount. I suspect others might be thinking in the same way.
Hoping for a strong Q1 update from CMC Markets (LON:CMCX) tomorrow. 40% of their trading volume is institutional now. eps fcst of 19.2(2025) followed by 21.7(2026). Mkt cap £870m, EV £676m.
Van Elle Holdings (LON:VANL)
Well don't you just love the short term approach of some 'investors'! Stockopedia shows forecast EPS for the year ended 30 April 2024 of 3.5p on revenue of £141m and operating margin of 3.7%.
Reported revenue came in at £139.5m but underlying basic EPS was on the money at 3.5p with basic EPS at 3.9p. Net funds are £5.5m, which turns into net debt of £1.2m if one includes IFRS16 property and leasing obligations. I tend to ignore IFRS16 which is offset in my view by rights of use.
Despite conditions remaining challenging, The order book is up 15% year on year to £35.1m, excluding framework agreements and preferred bidder positions. In addition orders in Housing are over 30% higher year on year.
I just can't see why the prelims deserve a near 10% wallop to the share price
I hold. Patience!
"Current trading and outlook
· Market conditions are expected to remain challenging throughout the remainder of calendar year 2024.
· Despite housebuilding volumes being anticipated to remain subdued in the immediate future, orders in Housing post year end are over 30% higher when compared to the equivalent prior year period.
· Strong customer relationships, national frameworks and significant investment programmes in UK and Canada infrastructure underpin the Board's confidence of medium-term growth.
· A broad range of capabilities and diverse exposure to multiple sectors, positions the Group well to benefit from improvements in the market.
· FY2025 will see the Group make further progress against its strategy and strategic financial targets.
· In Q1 FY2025 the Group acquired certain assets from Fussey Piling Ltd, strengthening its sheet piling and ground improvement capability.
· Order book at 30 April 2024 of £35.1m (£30.8m at 30 April 2023) excluding framework agreements and preferred bidder positions (estimated annual revenues of £30m-£40m subject to timing and allocation of workload)."
Voting machine vs weighing machine. Weighing machine will tell in the longer term. I hold.
Van Elle Holdings (LON:VANL)
did the company guide how the expectations for this year tally up with current broker forecasts or with their prior internal expectations.
I cant see anything useful which is very unhelpful if they are not telling us how they are doing
align that with the following comments
· Market conditions are expected to remain challenging throughout the remainder of calendar year 2024.
Oh dear - what are we meant to make of that if they are spelling it out to us clearly.
Everything about the update today that is likely to mov ethen needle is probably about how they are expected to do this year. In that regard i for one if i have missed nothing can sede why the price has been pumelled as they aint told us how they are doing.
you quote the order book being 35.1 mill - well thats down on the prior update which was £36.80 at 31/3. So the size of teh order book is not new god news.
Note on 22nd May update they said the following which suggested some sort of uptick coming soon ? for them now to turn that into Market conditions are expected to remain challenging throughout the remainder of calendar year 2024. to me sounds like they have actually gone into reverse since prior update
Per May update
Both the housing and infrastructure sectors are widely expected to recover in the near term, and whilst timing remains uncertain, the Group will benefit from increased volumes.
The Board remains conservative on the timing of a full recovery in the housing sector, but the Group is seeing early signs of progress with order intake and rig utilisation increasing over the last three months.
Ok i may have picked selective quotes here but please tell us you are on track if you are or not if you are not. I suggest if their first line of outlook had been we are on track to comfortabley meet current expectations for the new year then shareprice reactgion may not have been what it is.
are they on track to meet prior expectations or not - i no not?
For info, there's an Investor Meet Company presentation starting at 1530 on Van Elle Holdings (LON:VANL.)
Very little discussion of the Van Elle Holdings (LON:VANL) results this morning. It looks like investors were a little premature to “pile” in recently. But I like the share back at these levels- indeed I bought a “pile” based on the discount to NAV and tangible asset backing. With the optionality of an increase in house building and infrastructure spending of course.
Sorry. Couldn’t resist the puns. But they weren’t the entire point of my post.
As you might expect BnB I whole heartedly agree.
Van Elle Holdings (LON:VANL) will be first on site when it comes to house building and also has a foot in the door in the energy and waste sectors. There is a lot of potential upside in the shares at the current price, which is where I bought in.
What a lovely little share Volution (LON:FAN) has been. Not enough deviation from expectations to warrant special coverage from the team today. Although I know Graham is a “fan”. But a very resilient performance in difficult markets. Being a cyclical, and prone to market somersaults, I often think about trimming this one and then reproach myself - don’t be so stupid. This is a quality compounder with excellent returns on capital and high margins.
Card Factory (LON:CARD)
Late yesterday RNS suggested most of Teleios's 9.92% stake went to Brett Blundy (8.17%).
I know little about this Australian billionaire apart from what's on his Wiki page - which at least suggests retail is his thing.
https://en.wikipedia.org/wiki/...
Wondered if anyone had any more insights / thoughts on the new shareholder.
IMO Card Factory (LON:CARD) still looks very good value even after the current 20% rise should they continue to deliver on their strategy and am pondering topping up. Might wait until the interim TU due in a couple of weeks.
A.
(I Hold)
I used to hold Card Factory (LON:CARD) until earlier this year when I sold out as I just saw the price bouncing between 90p and 110p. I've maintained an interest in it since and felt a twinge of regret yesterday when I saw the price jump on the Teleios sale. However, as a fan of Peter Lynch's approach to investing, visits to their empty shops don't convince me that they have a significant high street presence. Other retailers are now selling cards at similar prices and as a self-confessed tight wad, I don't see much of a runway for the 'addtional' purchases at the tills Card Factory management are keen to highglight. Staff are always really friendly and helpful, but I do wonder when the share will realise its c. 150p fair value. I am frequently wrong, so this may be the start of the run!
Unless your site visits are properly coordinated in line with the business trading dynamics then imo they are next to useless as an indicator of performance. That’s not just for Card Factory (LON:CARD) but any major stores.
Have you been at different times of the day, different times of the year, key revenue driver event windows. Have you assessed the most and least profitable stores and made sure you’ve been to a representative sample? If not then all you’ve learnt is that a particular store on a particular high street is not selling much at a certain time of day……..means nothing.
But insights can be important - for example I was standing in a queue for a plane recently and there was a group of 16/17YOs behind me chatting - one of them complemented another on their outfit. She commented along the lines of guess where I got it? - to which the answer was Marks and Spencer (LON:MKS) followed by a series of oohs and aahs………now Marks and Spencer (LON:MKS) management would have me believe that their fashion is starting to resonate with more than just the 40+’s and this sort of insight gives me some anecdotal insight that this may just be correct, in which case I should be looking for clothing sales to be on the up. But if I visit a single M&S store at a certain time of day I get no real insight at all.
It’s all about context.
The 16-17 year olds certainly aren't shopping at Boohoo (LON:BOO) and Asos (LON:ASC) anymore!Although i wouldn't totally dismiss the younger 40+ range of shoppers coming back to a well known brand and purchasing/repeat purchasing the more updated m&s range.I certainly love the gear and early 40s, but i'm not sure i would call it fashionable.More quality, well made, nice modern takes of still fairly traditional designs i think (nothing too adventurous & fashionable mind) and great price points for the quality.Less Per Una (if anyone remembers that m&s own brand with its very garish prints)...... more traditional parisian chic for the ladies anyway!For the gents.. well modern day english gent ofcourse.
I think the same 'no real insight' challenge is true of single anecdotal conversations as of single store visits. Unless you know what proportion of clothing spend it represents for the individual, how representative of the buying base the teenager was and what price they paid, there is no context for understanding the conversation. Perhaps her parents are fashion managers in M&S who gave her 20 outfits for free of which she likes just this one? Even focus groups carefully selected to be constituted from a demographic you want to understand can mislead which is why FMCG companies will do a series of them to understand a single point.
As humans we love a story or narrative to help us make sense of the world, but would the anecdote have resonated if you did not also have the data somewhere in your mind that M&S fashion sales are starting to improve.
Depressingly, this probably means machines /AI with access to big data will be better than humans about investing quite soon. Encouragingly, probably not yet - or least enough humans still influence markets to leave them inefficient.
My local Card Factory (LON:CARD) is always seems busy and stands next to an always empty Clintons. So I am (an emotionally driven!) Card Factory (LON:CARD) buyer who hopes the data is also on my side :)
NICL Just a side-note from me. I bought NICL in, I dunno, maybe around the 2000 time-frame, but sold it a year a year or two later for a small profit, if memory serves. It then went on to do quite well. At the time, analysts were forecasting about 5% increase in profits, and I thought that was too dull to own. Its PE would have been quite cheap.
The share reminds me of the book by legendary value investor Bolton. He said that he was not a fan of the PEG ratio, and couldn't see much theoretical underpinning to it. He said that he would take a stock trading on a PE of 5 in which profits were expected to grow 5% over a PE 20 stock with an expected growth of 20%, every day of the week.
Re your comments about Nichols (LON:NICL) and the PEG ratio. To be fair to the late Jim Slater who popularised (perhaps invented?) the PEG ratio, I don't think he would suggest investing based on that ratio alone. Rather, it was a shorthand way of identifying companies where the likely growth rate and P/E were out of kilter in an age before sophisticated stock screening tools were available. Pace the equally admirable Anthony Bolton, there surely is a relationship between a company's likely rate of earnings growth and the appropriate multiple of today's earnings to pay but it is neither simple nor linear. I have tried unsuccessfully over many years to find a simple formula for this but it depends, among other factors, on how long that rate of earnings growth is projected to last and how much risk there is of a different (especially worse) outcome. There is also a need to factor in how much additional capital is required to fund that growth. There is a convincing argument that, if a company's ROIIC (return on incremental invested capital) is less than its cost of capital, growth adds no value (in fact reduces it), however high the growth rate (and so however low the PEG ratio). Of course, establishing cost of capital is hardly an exact science. Bolton is, however, surely right that, all other things being equal, it is better to count on a 5% growth rate than one of 20%. Unfortunately, all other things never are equal! It's the complexity of balancing such imponderables that make stockpicking such an interesting exercise. For those with less time for pondering the imponderable, Stockopedia's admirable Quality and Value ranks are a useful shortcut.
Completely agree with 5% > 20% growth idea.
5%: If inflation is 2.5% you only have to grow by 2.5%. Something goes wrong. Ship same number of units. Revenue up by 2.5%. You can usually find efficiencies and keep profits level.
20%: something goes wrong. Ship same number of units. Profits for the year are gone. SP not going up.
Resiliency.
He said that he would take a stock trading on a PE of 5 in which profits were expected to grow 5% over a PE 20 stock with an expected growth of 20%, every day of the week.
Good thing he avoided Alphabet and Microsoft then. Phew!
Interesting update from Atome (LON:ATOM), a developer of green fertiliser projects, this morning who have secured an offtake heads of terms for 100% of the production from the Villeta project, where construction is due to commence later this year. Several other projects underway too. Share price up 24% as I type (I hold).
There will be a presentation on Investor Meet Company tomorrow for anyone interested, link here.
https://www.investormeetcompany.com/atome-plc/register-investor
Sightly off topic. I have just read the Edison Group note on Filtronics and the big SpaceX order it received. It said - "As part of this agreement, SpaceX is entitled to warrants (exercise price 33p) in proportion to the value of orders placed over a five-year period, up to a maximum of 21,712,109 warrants across two tranches. For Tranche 1, 2,171,211 warrants vested as a result of this order, taking the cumulative number of warrants vested to 8,684,844, which equates to 4% of shares outstanding as at the date the agreement was signed (the maximum available in this tranche is 5%)". Does this mean that SpaceX has the right to buy millions of shares at 33p each? (I don't hold Filtronics. While its doing well it looks expensive and possibly too dependent on one customer.)
Nichols NICL never heard of it before this morning, never noticed Vimto before. Super write-up, will try the drink, possibly look at the company and share. Thanks.
Spoiler alert: it tastes like fizzy cough medicine. It's quite a love-it or hate-it kind of drink.
Nichols (LON:NICL) I think there could be a big youth market for an alcopop that tastes like Calpol. Two addictive drinks in one!
Like you, I had not heard of the firm until this weekend - although I am aware of Vimto - but opted to buy an opening position in A G Barr (LON:BAG) , based on the Stocko comparator, and that results were due this week. Obviously, disappointed to have missed out on today's rise but will monitor.
RTC (LON:RTC) …interims to 30th June out super quick and ahead of the date set for release. Good news travels faster and PBT up 20% and net assets up nearly 30% with confident outlook.
The eps at the halfway point is now 6p and I am expecting 15p or more for the full year if the stronger second half continues this momentum. The H2 is always the stronger half and last year delivered 5.2p first half and then 7.55p in the second. With no debt other than a lease and steady growth this really should be on a higher p/e rating than eight.
RTC Group Plc (AIM: RTC.L), the engineering and technical recruitment Group, is pleased to announce its unaudited results for the six months ended 30 June 2024.
Summary:
· Group revenue from continuing operations increased to £49.0m (2023: £45.6m);
· Contract revenues increased to £46.7m (2023: £43.0m);
· EBITDA increased to £1.9m (2023: £1.6m);
· Profit before tax increased to £1.2m (2023: £1.0m);
· Net assets grew to £8.7m (2023: £6.9m);
· Net cash inflow from operating activities £0.3m (2023 £2.1m);
· No term debt, and no borrowings other than lease liabilities; and
· Basic earnings per share 6.0p (2023: 5.20p) with little dilution.
For the benefit of the many here who probably would not be aware, might I humbly suggest that it would be fairer to disclose your interest here (owning in excess of 3% of the company may be material to your commentary). Thank you.
RTC (LON:RTC)
He has previously stated in detail why he owns this stock. Thank you.
Call me an old fashioned pedant but surely we should be transparent in such declarations when we own a share and post an opinion on it. We can all plainly forget or even delete such a note in error whilst making a post and I don't wish to pick on anyone who may have done so.
However I personally do not think having mentioned an interest sometime in the past, means you do not need to be open and frank EVERY TIME you express an option on a share held.
Surely it is how you behave when such an oversight occurs the matters, I am sure David did not mean to cause an issue with his post, but should we not TRY to be transparent at all times?
New members join Stocko all the time and there is no reason to believe they or any other member may be aware of a previous declaration and as such on this rare occasion I disagree with your post yiannos1 Thank you
There are such precedents - (Paul's latest example was from Monday)
PS - I am certainly NOT suggesting all MP's behave 100% correctly 100% of the time BTW
PPS - I do not hold RTC (LON:RTC)
Unless you work and get paid from Stockopedia or promoting a share that you get paid for (Paul Hill for example) ; you should NOT have to declare anything.
The gentleman in question has declared that he holds RTC (LON:RTC) in a previous post explaining the rationale behind his investment. If we start attacking people that try so hard to promote the UK small caps by even offering FREE passes here in this forum then I believe we Lost the plot.
People should pay more attention and do more research imo.
All the best
I don't recall that. I'm not religious about checking every SCVR post/comment every day. Nor should I be expected to be. If a person posts on a share that they hold, they should make it clear that this is the case. If they have a significant interest in a stock, I think it's fair we should know that too.
I obviously couldn't put it as succinctly !
I am certainly not trying to hide anything and I have previously stated that I have a notifiable holding and as it is one of my main holdings I like to watch it very closely and report back on how I see things developing
Open and transparent as the gentleman that you are David, Thank you
johnsmith, you are right that transparency is fairer but it's not obligatory. I for one base my trust on posters on how they "come across" are over a series of posts.
i don't know David personally, but have been aware of his contributions to stock boards since motley fool days. Although I appreciate you humbly reminding him of this helpful point, you'd be much better off engaging with him about the investment..
We'd all benefit a lot more from knowing his stock picks and reasons for why he's invested in a certain stock. (hint hint ;) )
i suspect he's one of the least likely people to hide an investment or his "skin in the game".. for some kind of benefit. He's spent his stock picking career providing his help and knowledge to the community.
FWIW i did assume he was a holder from the post as he states
"The eps at the halfway point is now 6p and I am expecting 15p or more for the full year"
just defending him, as for me, like Paulypilot (a.k.a paul scott) he should have 'national treasure' status in the stock-picking community
all the best
Very well said!
I think we are all fine. No names, no pack drill.
But ... it is still true that many poor, ignorant, deeply benighted, simple punters -- like me -- do not have any background knowledge/information on the credentials/backstories of other posters. So ... if person 'X' posts an especially positive comment on stock 'Y', it's kinda useful to know if they are holding it (or not) and especially useful to know that they hold a sizeable chunk of the company.
This wasn't some malicious ramping effort. Nobody was trying to influence others' behaviour for personal gain. It's not a very big deal. But it's a useful reminder that ... if you post a comment about a company ... you should say, at the same time, whether or not you hold it in your portfolio, and if you have a significant shareholding.
And where does it end this disclosure?
Do we have to disclose then that we have sold something that we have posted that we held at the time? And when do we have to disclose this? After or before we sell?
BnB , Rmillaree , Davidjhill , eParo , Boon , and other valuable contributors post several times a week about different stocks. Personally I do not expect them to disclose whether they hold or not a share. They offer their honest opinion for FREE.
It’s all about DYOR and be responsible for your actions.
Personally I always offer my honest views after extensive research.
All the best
Good luck with the report today chaps, I don't envy you :)
M P Evans (LON:MPE), Indonesian palm oil producer, issued a crop and production update today, which was basically "steady as she goes." What's more interesting is the long-term performance of the shares. Over 20 years, the share price has been compounding at about 9.4%pa. Its dividend would have been about 2.9% on average (a highly guesstimated figure on my part), for a total return of about 12.3%pa. That's a really good number.
By contrast, I estimated that the ULVR total return was about 10.9%pa. NICL (maker of Vimto) 13.7%pa.
My point is this. None of these companies are particularly exciting, but they all produced double digit total returns over 20 years. In my modest ambitions, that's a great performance.
You could of course argue that I'm cherry-picking all this, which is fair enough. I still think it illustrates the value of buying sensible companies at sensible prices, then holding for the long term. None of the companies mentioned have any sex appeal, but they are solid, and they did deliver double-digit returns.
There's an interesting post on Coffee Can Investing by Rational Investor here: https://newsletter.rationalwal...
I also recall reading somewhere that the original constituents of the S&P500 outperformed the S&P500 itself.
Nichols (LON:NICL) special divided with more to come I expect safe and boring company would still have £50million of cash
Nichols (LON:NICL) results look very encouraging. Love the quality metrics and dividend is reasonably good. Look forward to Graham covering this.
I just wonder why it has never recovered the operating margins and profit level it achieved pre-pandemic in 2018 and 2019? Has there been a permanent change to its ability to generate that level of profit hence the slide in share price from 2017/18 to now.
As a reader not a writer today, I have to say the table with quick summaries, up early, is incredibly useful in focusing my attention on what to look at. You guys did very well covering so much ground in a short space of time :-)
LOL. Paul. It’s apparent how much you enjoy this space. You can’t stay away! I totally agree with you about the summary. Very useful.
I agree the summary is very useful. I don’t always have the time to read every review in the mornings and so find the summary great for a quick glance at what is being reported. The SCVR has gone from strength to strength over the years and I for one am very grateful for all the hard work done by you Paul, Graham and Roland. Thank you, and keep up the amazing reporting you all do. I can not state enough how much this helps people like me and how much appreciated all the work you do, day in and day out.
EKF Diagnostics Holdings (LON:EKF)
Encouraging TU with improving numbers. (I hold)
Ricardo
EKF Diagnostics Holdings (LON:EKF) looks a decent update, surprised the shares are down so much today. I hold.
Morning team- I don’t envy you today with SO many results and updates, its like an avalanche
Those I read that I found interesting include the Nexteq (LON:NXQ) where it’s been a night of long swords from the look of things, Reckitt Benckiser (LON:RKT) for their plans going forward (definitely not a small cap but interesting all the same) & easyJet (LON:EZJ) where the strong growth in their holidays business continues (& it’s hard not to imagine they’re taking market share from competitors/other holiday companies)
Good luck
I doubt they will be taking market share from the excellent Jet2 (LON:JET2) !
Agreed on market share but easyJet holidays cover a lot of the same routes as Jet2 so this will probably hit their margins as it increases competition on certain routes. The trading team will have to discount to ensure the load factor is acceptable
easyJet (LON:EZJ holidays) can work on lower package margins as it's all incremental profit for them.
Pretty sure easyJet holidays will be eating On Beach group (LON:OTB) lunch in the short haul market, would help to explain OTB's pivot to long haul higher end product.
Thanks AG.... !
Reckitt Benckiser (LON:RKT) are looking to dispose of the (formerly) Mead Johnson nutrition business.
Buying that business has to go down as one of the worst corporate decision in recent years. They paid $18billion (C29 times earnings) in 2017, wrote it down by £5 billion three years later, and now they are looking to dispose of it. Call me cynical, but I don't think they'll get c£10 billion for it.
I don't hold.
Wilmington (LON:WIL) TU.
Group organic revenue growth is expected to be 9%, with reported revenues in the order of £126.0m (2023: £123.5m).
Adjusted* profit before tax (unaudited) is expected to be £27.6m (2023: £24.3m), up 13% on last year.
Cash conversion continued to be strong with Group net cash on 30 June 2024 at £67.8m (30 June 2023: £42.2m) after the completion of the sale of the MiExact and the Healthcare businesses and the acquisition of Astutis during the year.
Nexteq (LON:NXQ)
Today announce : Francis Small (Non-Executive Chair), Jon Jayal (Chief Executive Officer) and Johan Olivier (Chief Financial Officer) have informed the Board that they will step down from the Board and leave the Group in the coming months. Francis, Jon and Johan intend to continue in their roles until successors have been identified and to facilitate an orderly handover.
Inline results from #FRP but the numbers posted are very strong indeed. Not sure how I missed this one
Morning WTT,
Figures from Frp Advisory (LON:FRP) do indeed look excellent.
I covered its last positive trading update here with a GREEN on 17 May 2024, but much to my surprise, the shares have since fallen back about 10% since then.
Value metrics look good, and high quality scores too -
In the past, FRP shares had tended to attract a higher PER, often as high as 20-30x, so it seems unusually attractively priced right now at 12.5x forward earnings.
A net cash balance sheet looks healthy too. There's a decent dividend yield of over 4% too, twice covered by earnings.
I can't see the catch here, it looks good value to me.
Similar story with BEG - looks attractive at c.101p/share.
Disclosure: no personal holdings in either FRP or BEG.
Regards, Paul.
Do you think the green shoots of economic recovery weighs on them as they focus on insolvency?
I can’t help but think they will have a reputation problem at some stage also.
Some of their practices are a bit close to the wind.
I also thought this & I think they have certainly got a boost from restructuring business recently. However they have several other business segments that don't rely on a poor economic environment. I can't find all of the comments they make in their report, but here's one:
"As economic conditions in the UK began to stabilise and market sentiment improved through the year, our Corporate Finance team, which works on M&A, strategic advisory and valuation, financial due diligence, capital raising, special situations M&A and partial exits, became more active, particularly in the second half. There is cautious optimism and momentum continuing into financial year 2025."
I'm still getting to grips with the business, but it sounds like they have revenue streams for all economic environments. Maybe more so in poor times though, not sure. Cavendish upgraded their numbers for FY25 this morning, though not by much.
You can still have plenty of restructurings and insolvencies even in a period of economic growth - in fact, a healthy economy probably needs a certain number.
Hi Paul
Here’s my quick take on Frp Advisory (LON:FRP) - from a very brief run through the numbers and business lines. It looks a decent business with good returns and margins, with forecasts suggesting a major boost to cash flows. But I end up with more compelling bear points than bull.
Firstly, I think it’s dangerous to anchor to previous valuations. The multiple is in a declining trend that certainly reflects higher rates, but also might reflect a steady moderation of enthusiasm post IPO. Indeed, I recall K3 Capital, a reasonable point of comparison, trading on a single digit PER. Shares are still at the level of the post-IPO bounce. This suggests the company is still growing into its valuation, which may settle around a PER of only 10x, quite normal for this type of business.
Secondly, the business is widely perceived as a restructuring firm. Yes, there are pro-cyclical lines of business as well. But the majority of profits are being delivered currently from restructuring and insolvency work. Even if the M&A and corporate finance product lines are boosted by an improvement to the economic outlook, and notwithstanding the lagged demand for restructuring work into a recovery, will the market give the business credit during an upcycle for its “through the cycle” range of services?
Thirdly, profits growth is anaemic since 2018 against a background of much faster rising revenues. I haven’t researched sufficiently to explain why this is the case, but this negative operating leverage is unhelpful. Certainly, staff costs are the major variable for a knowledge businesses of this type and perhaps they have suffered inflation on this measure. But I’m guessing. At the very least, this observation points back to my first comment, where the valuation should reflect the disappearance of all the companies productive assets at 5 pm on every weekday.
It does look a very good business though, with a great balance sheet, and I welcome a constructive debate.
Frp Advisory (LON:FRP) some valid points, but don't think you're right about lack of growth - just went through broker reports and adjusted EPS is as follows for past few years. This shows annual EPS growth of around 8.5% since 2021.
2021 - 7.1p
2022 - 7.6p
2023 - 7.8p
2024 - 9.9p
I suspect you're looking at Stocko figures (not always accurate) which shows 11p EPS in 2018. This looks to be a rogue figure as the company only listed in 2020.
I suspect you're looking at Stocko figures (not always accurate) which shows 11p EPS in 2018
No, I’m looking at PBT, which is hardly higher today than it was in 2018. For balance, it’s a lot higher now than in recent years.
Are you looking at Stocko figures? Anything before 2020 is surely not accurate as the company only listed in 2020. If you really want 2018 figures you'd probably need to dig out the IPO docs which should have all the pre IPO profit numbers. Not looked at this but fairly sure FRP would grown since then. It's certianly grown nicely since listing in 2020.
Frp Advisory (LON:FRP) I’m looking at Sharepad data which habitually shows pre-IPO accounting numbers, in this case going back to 2017. Whether they can be trusted or not is another matter - as you say the company historical filings would be required to check. And if accurate, were the earlier profits massaged upwards in expectation of a forthcoming IPO? Probably well worth understanding before making an investment.
It still looks a good company. But I don’t see why it should be valued higher than K3 Capital was.
K3 Capital was mainly involved in business sales - they later added an insolvency division but still a smallish part of overall business. So not really directly comparable in my view. I can't remember what sort of multiple K3 was on, but seem to recall it was taken out at a decent premium.
K3 Capital was mainly involved in business sales - they later added an insolvency division but still a smallish part of overall business. So not really directly comparable in my view. I can't remember what sort of multiple K3 was on, but seem to recall it was taken out at a decent premium.
In what way is a business involved in M&A and insolvency not comparable to a business involved in M&A and insolvency? The multiple was low double digits if I remember correctly - which is by no means guaranteed..
K3 were mainly involved in selling businesses (eg on behalf of owners who wanted to exit) so were more of a cyclical business. FRP are mainly involved in restructurings so more counter cyclical. Quite different risk profiles in my view.
A final follow up on this - I checked out the original initiation note when FRP IPO'd and PAT in 2018 was £14m, PAT in 2024 was £25m - so we can safely say that growth is not flat I think what may have happened is there was a completely different company which used to have the FRP ticker and I think Stocko/Sharepad may have pulled in the data from that.
Thanks for that. Looking at the Sharepad numbers in more detail, the PAT is the same as the PBT for 2018, which casts some doubt on the numbers! It looks a lot better proposition now. But the question remains about the “right” valuation multiple for a company of this type. Elixirr International (LON:ELIX) has a similar valuation, but with more top line growth in prospect.
Hi WTT. Yes decent FY results from Frp Advisory (LON:FRP) . A stock I've only recently started following, so still getting to grips with the business. My checklist score is down from 42 to 38/50, due to declining forward growth estimates. I'm seeing this with a lot of stocks at the moment, especially ones across the pond. It could be what's holding the share price back for now?
They appear to be executing well with a decent market share in the UK & steady growth in partners & wider fee earners. Very acquisitive strategy, but it seems to be working.
It's a stock that's on my watchlist, looking to enter if it breaks through 150p. As Paul says, looking very good on a valuation basis as well for long term investors.
If you held on in Ascential (LON:ASCL) well done, a staggering premium... Informa (LON:INF) claim 11x post synergy EBITDA multiple. Some creativity there with only £12m of cost savings... Ascential (LON:ASCL) must be trading its socks off. Covers long term cost of capital in 2-3 years whatever that means. Anyway well done to holders... I sold because the rating was up with Informa (LON:INF) ....what an idiot.
Note: Actually that EBITDAx probably applies to a combination of acquisitions since they reference £600m of revenue. Looks to me like Informa (LON:INF) have paid at least 1 turn of revenue too much ... and another example of media cos overpaying for trophy assets.
I did continue to hold Ascential (LON:ASCL) through the recent reorganization and of course this morning I am pleased to have done so. But to maintain a proper sense of humility about how much of this investing is subject to the whims of chance (rather than brilliance) my morning excitement of being 16% up on Ascential is immediately doused by being 16% down on the bad news out of Learning Technologies (LON:LTG) , as their US subsidiary loses its ability to win government contracts - a classic arrival of a black swan !
Nexteq (LON:NXQ) warns
The business has continued to see persistent softer customer demand across both divisions through the first half of the year, in line with wider industry de-stocking, as initially highlighted at the time of the FY23 results release in March 2024. Furthermore, some specific larger key Quixant customers have recently indicated lower demand, partly reflecting the timing of new product releases and challenges in specific regional markets.
As a result, we expect to report Group Revenue for the six-month period down 15% to $48.2m (H1 2023: $56.3m). Within the Group's brands, we expect to report that Quixant revenue is down 10% to $30.9m (H1 2023: $34.3m) and Densitron revenue down 22% to $17.3m (H1 2023: $22.0m).
Net cash up to $36.9m
https://www.investegate.co.uk/...
Nexteq (LON:NXQ) guides down FY2024 revenue by 15-20% and adj PBT by 30-40%.
And Chair, CEO and CFO all announce today, they intend to leave “in the coming months.”
Nexteq (LON:NXQ) - it sounds to me like a boardroom disagreement, maybe with the founder:
Nick Jarmany, founding Director and Deputy Chair of Nexteq, commented:
"Whilst I am sorry to see Francis, Jon and Johan leave, I respect their decisions which have been carefully considered over some time and I am looking forward to welcoming new leadership to Nexteq to support our growth strategy.
Unfortunately, I had a small holding. Not great news but could well bounce when trading improves again. The shares will likely get hammered today.
Nexteq (LON:NXQ) I unusually got the timing right on this and sold for 151p.
Hi topvest, before I came across all the argy-bargy below I doubled-down after seeing the RNS. I've held Nexteq (LON:NXQ) since buying in at 223p, doubling-down at 100p last December. I suppose I might be doubling down until the cows come home but on the other hand I may escape yet wearing a shirt.
Would be great to get your thoughts on the trading update from Tortilla Mexican Grill (LON:MEX)
”The early results are encouraging, however, the benefits of these initiatives will be slower than originally anticipated, and this combined with an ongoing challenging trading environment, means the Board now expects Adjusted EBITDA (excluding the recent Fresh Burritos acquisition) to be £5.0m for 2024. A revised combined outlook, including Fresh Burritos, will now be Adjusted EBITDA of £4.5m and the year-end net debt position is expected to correspondingly increase to c.£7.5m”
Hi Aeon Flux,
There's a note out from Panmure Liberum this morning on Tortilla Mexican Grill (LON:MEX)
It's a mild profit warning, they reduce forecast for FY 12/2024 from £0.0m adj PBT, to £(0.3)m.
Annoyingly, the company focuses on the artificially high (since it ignores the large depreciation charge on fixed assets, and finance costs) EBITDA - which is reduced from £5.1m (old) to £4.5m (new). Although EBITDA does demonstrate that without any new store openings, MEX is decently cash generative.
I'm not keen on net debt forecast to be £7.5m by end 2024, and I wonder if they've bitten off more than they can chew with the European expansion?
All that said, it's still dirt cheap for a good-sized chain of branded quick service restaurants. I wonder if SSP (franchisee) might bid for it? The story is all about an operationally geared recovery to trading as consumers spend more. Also the big cost shocks might abate. But in the meantime trading looks quite tough.
At 08:05 it seems to be trading 18% down at 50/53p bid/offer.
Regards, Paul.
Tortilla Mexican Grill (LON:MEX)
Management need to roll their sleeves up and execute on their margin improvement strategy and integration of the French acquisition. If they achieve this then it should rise substantially from here, if they don't then it's potentially a take over target for somebody with deeper pockets. I think they will need 12 months, fortunately there are new shareholders on the register who will be cracking the whip.
These small turnarounds give me a headache, I wish I would stick to my quality compounders and not get involved with these special situations......
Morning Burnt Onions,
Tortilla Mexican Grill (LON:MEX) I did try and warn about this one. Very difficult to make money in this sector these days. The costs and competition involved in running these businesses are killing them.
All the best
Hi Yiannos, yes this is very true, your warning was noted but not heeded and now I'm eating a burrito stuffed with humble pie....
To be fair, Tortilla Mexican Grill (LON:MEX) has simply given up this year's previous gains. It's now flat YTD - hardly a disaster.
It's now forecast to make a very small loss in calendar 2024, c.£(0.3)m, which is far from a disaster (previous forecast was bang on breakeven).
In the absence of new store openings (which are discretionary of course) it's decently cash generative, due to a large physical depreciation charge.
The case for MEX shares was and still is very clear - tiny market cap, trading at around breakeven after an incredibly difficult macro backdrop, hence recovery potential over the next couple of years as consumers relax the purse strings now real wages are starting to rise again.
My main dislike with MEX is the balance sheet, which wasn't great even before the recent acquisition in France. That deal has now stretched the finances further than I'm personally comfortable with.
I also raise a question about product quality. I enjoy the chicken burritos, but tried a beef or pork one, and it was pretty grotty. Also sometimes the food seems to have been left out too long, and looks dried up. They don't have enough volume flowing through. I'm also not keen on the strategy to extend opening hours into the evening. I tried that out, and the side order of sweetcorn was dry, and stone cold - just not good enough.
So still some work to do, but it's a decent sized business with a good UK footprint, and successful & expanding franchise operations. So at only c.£20m market cap, there's a good opportunity here IMO.
Regards, Paul. (no current position, but it's one I've held before, and would consider buying again).
Re Tortila Mexican Grill (MEX)
"I also raise a question about product quality. I enjoy the chicken burritos, but tried a beef or pork one, and it was pretty grotty. Also sometimes the food seems to have been left out too long, and looks dried up"
No further analysis needed here. Why would anyone invest in a casual dining chain that serves food as described above?
Anyone here involved in web marketing? The MEX website looks in need of some attention. The manage cookies button didnt work for me on two different browsers. The menu button dose not actually give a menu? Not to mention the design which is rather distracting in my view.
Ok Yannis will pull me up as I probably missed something but easyJet (LON:EZJ) Q3 trading update looks great to me, especially after Ryan Air's disappointing trading update.
Graham - would be great to get your take on EZJ if you have time, I know it's not exactly small cap but I think it's a good opportunity. I hold.
Yes good number from easyJet (LON:EZJ) and in stark contrast to Ryanair. Jet2 (LON:JET2) has sold off sharply on the back of their Ryanair results so perhaps chance now for a reappraisal.
Annoying they don't explain the acronyms. What is CASK, CPS, and RPS?!
The package holiday numbers look good - and maybe one for us holders of On Beach group (LON:OTB) & Jet2 (LON:JET2) to keep an eye on.
A glossary of acronyms can be found within the FY23 Annual Report on Page 197, available on easyJet's corporate website.
Couldn't be bothered to hunt for it, so asked Mr Google for Acronym's. (They might mean)
CASK - Cost Available Seat / Kilometre
CPS - Cost Per Seat
RPS - Revenue Per Seat