Small Cap Value Report (Wed 24 May 2023) - MAB1, CRU, PCIP, CCR, ZTF

Good morning! It's Roland and Graham here with today's small-cap report.
Today's report is now finished (10.00).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
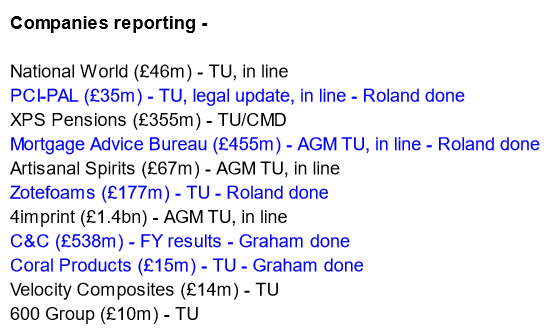
Summaries of main sections below:
Mortgage Advice Bureau (Holdings) (LON:MAB1) - 796p (pre-market) (£454m) - AGM TU, in line - Roland - GREEN
This mortgage broking business reports in line trading against a backdrop of more stable market conditions. MAB gained market share in a declining market in Q1, despite reducing headcount. I remain positive about this business, although it’s starting to look fully priced on a near-term view.
Coral Products (LON:CRU) - 16.75p (pre-market) (£15m) - TU, slightly ahead, forecasts slightly reduced - Graham - AMBER
This company’s broker estimates for FY 2024 are slightly reduced despite news that FY 2023 is ahead of expectations. I still remain impressed that Coral Products is able to digest four acquisitions at the same time. Shares are superficially cheap but perhaps priced right.
PCI- PAL (LON:PCIP), up 5% to 56.2p (£37m) - TU and legal update, trading in line - Roland - AMBER
This cloud-based secure card payment provider appears to be trading well, but faces potentially significant legal risks and has not included an update on cash performance in today’s statement. Too speculative for me, but potentially an interesting business.
C&C (LON:CCR) , 134.4p (-2%) (£522m/€602m) - FY results, profit warning - Graham - GREEN
This drinks/distribution business is trading in line except for a very costly, disruptive ERP upgrade. Leaving that to one side, its drink brands are thought to have seen improved market share. Balance sheet is improved. Dividend declared. Still seems too cheap for me.
Quick comments (no section below)
Zotefoams (LON:ZTF), up 3% to 375p (£184m) - TU, in line & chair succession - Roland - GREEN
This materials group has issued an AGM statement today. Trading during the four months to 30 April “was strong”, with sales up 15% and margins benefiting from pricing and other factors. Cost inflation is said to have eased.
Product volumes were mixed across the different parts of the business, but pricing appears to have been fairly strong across the board. Good cash generation has left leverage at 1.1x EBITDA, compared to 1.2x at the end of 2022.
The company confirms chair Steve Good will stand down at today’s AGM and be replaced by Dr Lynn Drummond, as previously announced.
Outlook: further sales growth is expected, mainly from the High-Performance Products portfolio (foam used in footwear). Market conditions for industrial customers are expected to remain “challenging everywhere except for North America”.
Overall expectations remain unchanged; consensus forecasts suggest earnings will fall by around 5% this year, before recovering strongly in 2024.
Roland’s view: this business seems to be in good health and performing well. Leverage is modest and cash generation appears good. The 2023 forecast P/E of 20 does not seem excessive to me and could prove good value if Zotefoams can deliver on FY24 forecasts. Overall, my impression is positive.
Graham's section
Coral Products (LON:CRU)
Share price: 16.75p (pre-market)
Market cap: £15m)
This is “a specialist in the design, manufacture and supply of plastic products based in Wythenshawe, Manchester”.
I covered their results back in December, and failed to find anything too worrisome. They were digesting a remarkable four acquisitions, which now accounted for the majority of their sales, but all four were said to be performing according to plan.
This morning brings us a trading update for the full year ending April 2023, and it’s good news: revenue is expected to be over £35m, “slightly” ahead of market expectations. As for profits, adjusted EBITDA will be not less than £3.5m, which is ahead of market expectations.
Executive Chairman comment: In spite of the challenging trading conditions in the second half of the year, we have had a successful year… This marks a significant step towards our objective of building a specialist UK plastics business of scale, targeting profitable, high-demand sectors".
Estimates: It would be helpful if the company included market expectations in its RNS, as other companies are increasingly doing. Today’s broker note from Cenkos outlines that their previous forecast was for revenues of £34.6m and adjusted EBITDA of £3.1m. So each of those numbers is beaten by £0.4m.
Looking ahead, the estimate for adjusted EBITDA in the current financial year FY April 2024 is reduced by a few percentage points to £3.9m.
Perhaps this is just a minor quibble, but wouldn’t it be more helpful if the RNS itself mentioned that the outlook for FY 2024 had slightly deteriorated?
The broker says that it is reducing its FY 2024 estimate due to the mention in the RNS of “challenging” trading conditions in H2, but the RNS itself says “in spite of the challenging trading conditions in the second half of the year, we have had a successful year”! If I was reading this RNS without access to the broker note, I could easily conclude that expectations for FY 2024 might have increased!
Graham’s view
Putting quibbles around estimates to one side, I continue to think this micro-cap looks to have some potential. I remain impressed that all four acquisitions, vastly increasing the scale of the group, continue to perform as hoped. Remember that the deals were done without diluting shareholders, but instead by leveraging up the balance sheet - a risky play, but with potentially high rewards if it works out.
I won’t be able to give the stock the thumbs up since net income is of course expected to come in quite a bit lower than adjusted EBITDA, around £1.6m, so the stock is cheap but not outrageously so in the current environment:
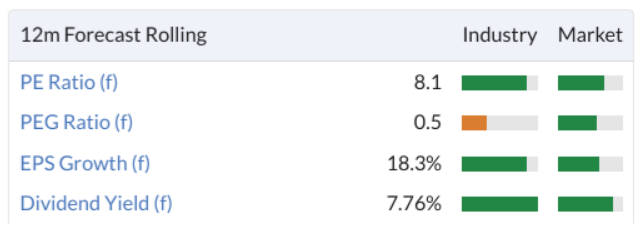
Due to the nature of the business - manufacturing and supplying plastic products - the gross margin is on the lower end of the spectrum at c. 27%. This is not the type of business that I am inclined to put in my personal portfolio, as I would be surprised if economic returns here proved to be significantly above average over the long-term. Let’s hope they can prove me wrong on that point.
On balance, I continue to view this as one of the more impressive little nano-caps that I’ve come across in recent months.
C&C (LON:CCR)
Share price: 134.4p (-2%)
Market cap: £522m (€602m)
C&C Group plc (‘C&C’ or the 'Group’), a leading, vertically integrated premium drinks company which manufactures, markets and distributes branded beer, cider, wine, spirits and soft drinks across the UK and Ireland announces results for the twelve months ended 28 February 2023 (‘FY2023’).
This stock has still failed to recover to the levels it reached prior to March 2020:
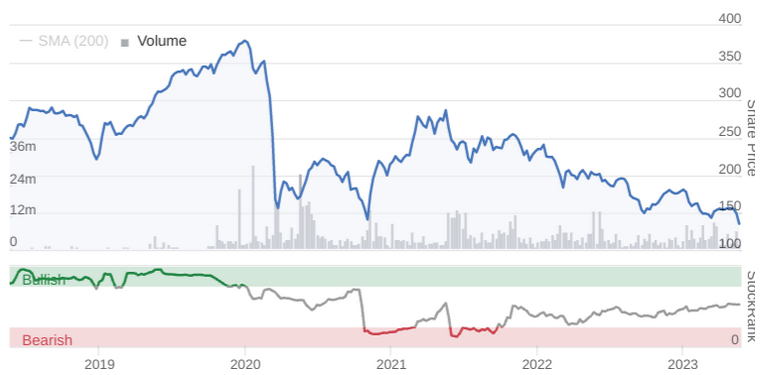
I wrote about its H1 results in October, providing an overview of the company’s post-Covid struggles, but thinking that the stock could be well-positioned for a recovery. Looking back now after another 6-7 months, the share price doesn’t agree with me yet!
Here are the full-year results for FY February 2023:
Net revenue +18% to €1.7 billion
Operating profit +75% to €84m
Operating margin increases to 5% (last year: 3.4%)
In further good news, the company declares a dividend for the first time since 2020.
Net debt fell during the year from €191m all the way to €79m. This progress was admittedly boosted by the €66m sale of the company’s stake in Admiral Taverns, but it makes for a radically improved balance sheet. The company’s net debt to adjusted EBITDA multiple is now below its medium-term target range of 1.5x - 2.0x.
Strategic highlights - both Tennent’s and Bulmers are said to have enjoyed increasing market share, but there are challenges for each of them.
Tennent’s has suffered from the ongoing trend for beer premiumisation. The news from it is slightly more positive today:
"Tennent’s performed strongly, with volumes up 4.8% in the year including 25.8% in the on-trade. Tennent’s continued to gain share in the Scottish on-trade during FY2023, with its share of total beer in Scotland up 1.8ppts to 29.6% in the twelve months ended February 2023… Amongst mainstream beer brands, Tennent’s represents 2 in every 3 pints poured in the On-Trade (68.9%), and across all Beer it represents 1 in every 2 pints poured in the on-trade”
For Bulmers, the cider category has weakened considerably, though C&C says that people are returning to apple cider.
Outlook is again very mixed:
Macroeconomic conditions continue to impact the trading environment which is expected to remain challenging in the near term, particularly in the GB market.
Additionally, the company has implemented an ERP system upgrade - these are so often costly and disruptive, but thought to be necessary! For the C&C distribution businesses, it has taken longer than expected and had a “material impact on service and profitability”. I hope customers haven’t been too put out! It’s a €25m hit to C&C.
Excluding this problem, trading is in line with expectations.
Graham’s view
It’s not easy (and perhaps not clever) being positive on this stock, when it seems to be facing an uphill battle to reach the level of profits it had back in 2018/2019.
However, despite the economy and despite the challenges faced by its key brands, it has still managed to earn a net income for FY February 2023 of c. €52m. And these figures turned out to be very clean, with less than €1m of “exceptional items”.
Next year’s figures will be less clean, thanks to the fiasco at the distribution division and its ERP upgrade. And when those figures are released, I will probably be inclined not to write off the ERP-related costs as being entirely exceptional.
Even so, I maintain reasons for optimism with this stock. The balance sheet is much improved, so they are well-placed to deal with the challenges they are facing. Market share within their respective categories remains high. And the declaration of a dividend is a sign from management that the crisis and the difficulties associated with Covid are fully in the past.
I’ll give this stock the thumbs up, as I do think it offers some significant brands at a reasonable price, so there is potentially some value to be had with this one.
Roland's section
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Share price: 796p (pre-open)
Market cap: £454m
This mortgage broker has a good track record and its results were well-reviewed by Graham back in March.
Trading summary: today’s AGM trading update does not contain any nasty surprises. Adviser numbers have stabilised as previously guided, and the company expects to see a return to growth later this year. Management reports a strong pipeline of new Appointed Representatives.
While the value of mortgage completions fell by 21% in the wider market in Q1, MAB’s total completions were broadly unchanged at £5.8bn, suggesting a gain in market share. The company says this is being achieved despite a reduction in advisers since Q4 2022.
MAB says market conditions are showing “early signs of increasing activity and mortgage approvals” after the disruption seen following the mini budget.
Performance remains in line with the Board’s expectations, “with further improvement expected in the second half of the year”.
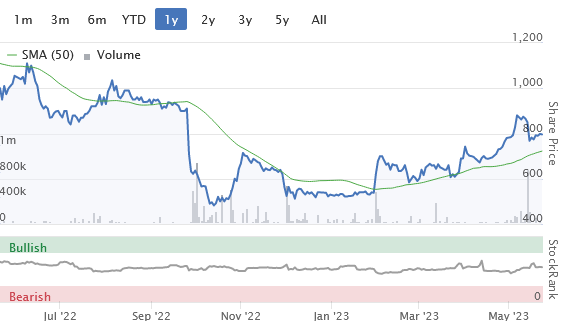
Roland’s opinion: this looks like a solid update from a management team that’s in control and has a clear strategy. MAB’s share price has continued to rise since March and the firm’s shares do not look especially cheap to me. But if growth resumes from next year as expected, then I think the stock could soon grow back into its valuation.
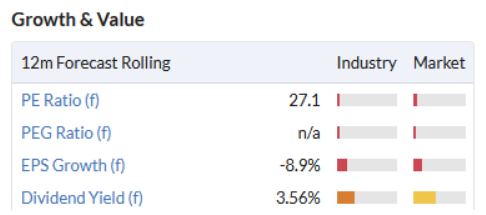
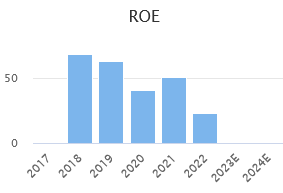
Consensus forecasts price the stock on 30x 2023 earnings, falling to a P/E of 24 in 2024. This may not be excessive if the business can return to generating 50%+ returns on equity as seen in the past.
A longer slowdown in the housing market could put pressure on profitability, but MAB’s commentary suggests to me that the group is able to scale its capacity effectively to reflect market conditions. I remain positive on this stock, although I might hope for a cheaper entry point.
PCI- PAL (LON:PCIP)
Share price: 56.2p (+5% at 09.20)
Market cap: £37m
Trading and Patent Case Updates
As a result of this momentum, the Board is confident that results for FY23 will be in line with management expectations.
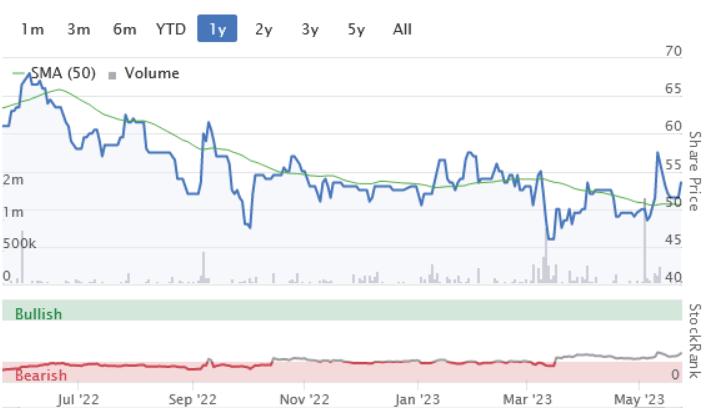
The growth outlook for this cloud-based secure payment provider is currently clouded by legal cases. But PCI-Pal’s market cap has risen from £29m to £37m since Graham wrote about this stock in March, so the market seems to have become more optimistic.
Today’s update covers both trading and legal issues, so let’s take a look at what has unfolded over the last two months.
Trading update: new sales seem to have accelerated during the second half of the year (y/e 30 June 2023).
PCI-Pal says that newly-won annualised recurring revenue for the year-to-date has risen to £3.4m, from £1.47m at the half-year mark. According to management, 86% of these new contracts have come through the company’s partner network, with £3.0m from new customers.
This represents a 34% increase in new business, compared to the same period last year.
Highlights are said to include “a number of enterprise deals in the US”, including a deal with a Fortune 50 healthcare provider and “one of the largest electronics companies in the world”.
PCI-Pal also reports the company’s largest contract to date in Australia, with “a well-known global insurer”.
Outlook: trading for the full year is said to remain in line with management expectations. Broker FinnCap reiterated its forecasts this morning, guiding for an adjusted loss of 2.8 pence per share this year (note available on Research Tree).
Stockopedia consensus forecasts suggest PCI-Pal could turn profitable next year.
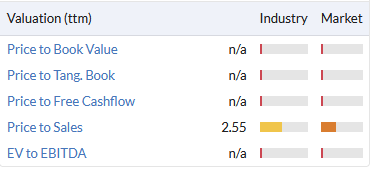
With a market cap of £37m, this business is currently valued at 2.5 times forecast sales for the year. That’s not necessarily an outlandish valuation for a tech stock. But I don’t think we can ignore the risks posed by the company’s ongoing legal dramas.
Patent Case update: PCI-Pal’s operational progress may not count for much if it loses in court.
The company is currently involved in legal cases relating to patent infringement claims brought by rival payment operator Sycurio Limited. PCI-Pal has also made counter claims alleging the invalidity of related Sycurio patents.
Since the last update in March, the two companies have swapped expert witness reports and held discussions regarding the case. However, there doesn’t seem to be much prospect of a settlement:
To date these discussions have not produced any sensible settlement options that the Board believes are in the best interests of the business. The Board continues to seek the best outcome for the business and is entirely prepared for trial on that basis.
A UK trial relating to these claims is scheduled for eight days from 12 June 2023. A ruling is expected up to four months after that time.
It’s worth noting that US court proceedings are also expected – in its March results, the company said these were yet to be set, but expected in late 2024.
Roland’s view: PCI-Pal appears to be trading well. Although I am not familiar with the firm’s competitors, I have no reason to doubt the quality of the company’s product or its growth potential.
I should also point out that the company says it has plans in place such that if it loses the patent cases, it can make changes to its products “to continue operating in a non-infringing manner”. This suggests that the firm could shrug off such a legal loss, but I suspect the reality could be more challenging.
Would customers and regulators remain supportive and accept the technical changes?
Would the changes affect the future development potential of the product?
We don’t know.
I think it would be easy for shareholders to underestimate the risks in this situation. Even if the legal issues can be resolved without any impact on trading or growth, I think there’s a risk the firm could still run short of cash.
In the half-year results, management said they were confident the company would reach monthly cash flow breakeven during the second half of the year.
This target was not mentioned today, nor was the current cash balance disclosed. The latest update we have is that cash stood at £3.4m at the end of February 2023. For contrast, cash burn during the first half of the year was £3m.
I haven’t looked into the funding arrangements for the company’s legal cases. But even if they have been fully funded externally, I think there remains a risk that the firm will need a further injection of cash to reach operating profitability.
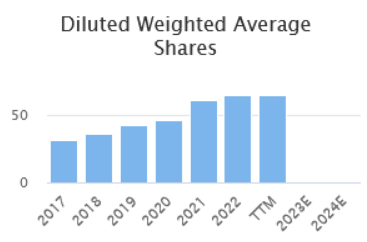
Shareholders have suffered significant dilution in the past – the share count has doubled since 2017:
In my view, this is an interesting business with decent growth potential. It could easily also become a takeover target.
However, while the legal situation remains uncertain and the business continues to lose money, I think it’s prudent to view this as a highly speculative situation.
I’m going to rate the shares as amber. It’s too risky and uncertain for me, but I think there could be an opportunity here, if the company can resolve its legal issues favourably.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Acounsell.
much appreciated.
rpannell.
Do you have the ticker symbols for index linked gilts.
They are on the London Stock Exchange web site.
https://www.londonstockexchang...
Can anyone give me the ticker symbol of the 2yr uk treasury bond.
TG25 for the June 2025 maturity according to London Stock exchange website.
Hi all, just to let you know Paul ( fresh with a new hair cut ) has a new excellent video with Paul Hill on Vox Markets. https://www.voxmarkets.co.uk/a...
A strong set of FY22 results and Q1 FY23 update from XP Factory (LON:XPF) yesterday.
“Trading in the first quarter of 2023 has been strong with the Group as a whole exceeding management expectations.”
The group’s divisions Boom Battle Bars and Escape Hunt are both performing strongly.
Owner operated Boom sites grew at 44% LFL with operating metrics as expected. FY23 revenue and profits should be boosted by a massive increase in site openings in Q3 and Q4 FY22. Not least from the Oxford Street premisses.
Escape Hunt grew at 34% where overall trading was “ahead of management expectations”.
New broker Singer has a price target of 37p. Compared to previous broker forecasts in January 23, revenue and EBITDA forecasts for FY23 are higher at £42.6m and £9.8m but FY23 forecast PBT and YE net cash are lower at £1.1m (versus £2.2m) and to £1.7m (versus £3.9m) respectively.
So far, so good. The share price initially rose over 10% yesterday but then closed pretty flat on the day.
One thing at the back of my mind is the ownership structure: Canaccord still owns 21% and there are a small number of large holders. Many of them took part in the 30p fund raise in November 2021 and may be wanting to reduce their exposure with the share price rising in recent weeks but still only around 20p.
This interested me from the chairman's statement: "....our challenge now is to optimise the pace of roll-out within the constraints of the capital we have available." i.e. they'd prefer to invest more but haven't got the cash.
Management dont seem to be out and about on the retail circuit either yesterday or today (no feedback yet from Paul’s interview) so I assume they're focussed on the institutional side.
Is there an overhang supply of shares from longer term shareholders? Are management sounding out investors for capital to re-accelerate growth and/or take up the option to purchase Flip Out?
I had a good look at the website yesterday to check availability slots at the various locations. London very busy. Other sites had lots of availability. We hear a lot about how busy their London site is. Anyone visited their now many other sites?
You missed two very very important points here :
1. The share count will increase by at least 40% in the next 2 years.
2. They are not generating any cash.
Thanks
XP Factory (LON:XPF) Would you be kind enough to expand on the share count change please Yiannos?
About 25m deferred for a recent acquisition, add to that about 20m for the well paid management, and finally they will need a new fundraise to expand further (supposedly).
Thanks
Hi yiannos1
1. Can you share your calculation for the share count increasing by at least 40% please? (I have 150m currently outstanding, 23.5m related to the Boom acquisition contingent settlement, plus 16.7m employee/management share options, so closer to 25% if options are exercised).
2. Operating cash flow is very positive. I think the key question is how much they spend on Capex and other investments.
Thanks
Operating cash flow is just part of the cash flow analysis ( and they do not generate any cash ).
As for the at least 40% increase in the share count , I am adding a further 20% increase in a fresh fundraise.
I prefer Ten Entertainment plc , no debt , a 5% dividend yield and real cash flows , about £27m at least this year. For its market cap this is indeed an undervalued growth company and a definite takeover target.
DYOR
Thanks
In agreement regarding Ten Entertainment (LON:TEG), way undervalued.
XP Factory (LON:XPF)
Hi Cuddlesticks
I don't know too much about the share count, but coincidentally I just looked at the recently released cash flow statement and it looked like they were burning through cash quite quickly.
2021 cash generation was slightly better, but it looks like this was driven by rent free periods on new leases.
So overall it looks like the company is losing money right now and will probably look at expansion as an attempt to change this.
A
They will look at expansion for an excuse to raise more money as they are loss making ( they have already mentioned this yesterday, in a rather hidden statement ).
Thanks
Hi
This is FY22. The key point being many of their large premises did not open until Q4. Their operating cash flow should be very positive now. You can see this from both broker forecasts and also how the net cash balance has stabilised /increased between 31/12 and 31/3. So I dont agree they necessarily need to raise.
For me the question is how much is available for further growth capex ie there is possibly tension between management looking to invest (which may require a raise) and investors who’d prefer focussing on the existing estate.
Good CEO interview now available on Q1 FY23 and FY22
https://www.directorstalkinter...
Increase in payables , a decrease in receivables an a one off landlord incentive does not make a company profitable in the long term.
Good luck to all holders
£4m cash at Apr 2023 vs £3.2m Dec 2022 suggests fundraise isn't imminent. I hope payables and receivables have unwound since then. Landlord incentives supported the significant growth in 2022. Of course their expansion is restricted by the amount of capital they have. Doesn't mean they'll do a 20m share placing.
£4m cash at April 2023 means nothing to me ( probably payables have increased more ). And yes , this company will need a new fundraise and this is crystal clear for me.
However, I haven’t said that this is imminent ( not tomorrow anyway ).
As I said before , good luck to all holders.
Thanks for posting the link. Really helpful, ta.
Interested in any views on Sondrel (Holdings) (LON:SND) ? Opaque as recent ipo and it’s also transforming from pure design to managing chip production runs (multiple years) and taking a modest clip of that high long duration value.
Working capital is tough to work out. Not got my head fully in it but significantly relates to design tools they much ‘lease’ from chip cos.
Good trading update today from Velocity Composites (LON:VEL) .
New US plant continues to ramp with revenues and profits on track to meet FY23 forecasts. Cenkos reiterates price target of 68p to 101p so a lot of upside even at 68p.
I think the broad price target range reflects the potential upside from securing further high value contracts. Management says there is a healthy contract pipeline but the nature of aerospace manufacturing means these contracts can take time to land, quality approve manufacturing processes and ramp.
Contracted revenue is worth £30m to £36m pa which should underpin profit forecasts over the next couple of years whilst management work to secure additional business in an area of focus (effective use of composite components) in a secular growing sector (aerospace, including defence).
I was impressed with how nimbly management managed costs and limited capital through the pandemic and have confidence now they have re-committed to FY23 targets.
Only £15m market cap but I think one for the patient investors to consider dabbling in.
Artisanal Spirits (LON:ART) - AGM statement confirms growth momentum (new note: https://www.equitydevelopment....)
Today’s Annual General Meeting trading update from The Artisanal Spirits Company (ASC) confirms that the positive underlying sales momentum enjoyed in FY2022 has continued into the current year. The group remains confident of delivering both sales growth and EBITDA in line with expectations. Moreover, sales growth is expected to be at least double digit % in the second quarter after a relatively flat Q1.
We base our 150p fair value/share, which implies a 4.9x FY2023 EV/sales ratio, on a relative valuation when compared with leading listed distilled spirits companies and luxury goods providers. ASC is simultaneously exposed to both these categories given its emphasis on ultra-premium-and-above Scotch malt whiskies.
Furthermore, the £493m updated notional retail value of the company’s maturing whisky stocks is currently over 6 times today’s market capitalisation.
April RPI = 11.4%. This is the important number for index linked gilt holders. It's down from the peak of 14.2% in October 22 or last month's 13.5% but it is still very high. I wonder how many investors in shares are achieving > 11.4% at the moment.
Interesting to note that AIM is only down by 0.25% this morning on the inflation data. By contrast the FTSE100, FTSE250 and FTSE All Share are all down by over 1%. Lets hope that AIM has bottomed out at this support level of around 800p and everyone left standing isn't too interested in selling anymore.
The market may also be nervous about the US debt ceiling. I am.
Potentially, although Wall Street futures are only down 0.2% on IG at the moment. With the debt ceiling its a weird limbo, the chance of it not being raised being is very small but with a potentially colossal impact. I personally think they will push their luck as close to the June 1st deadline as possible and then raise, or at least that's what I hope...
Nothing to see here...
The U.S. debt panto is one of their ritual performances, as American as apple pie or halloween. They always resolve it in the end.
All the European markets are down heavily too so don't think UK inflation is the main driver - rather the debt ceiling seems to be spooking markets.
Yet US markets are hardly down, in fact the Nasdaq was up yesterday.
Are you sure ? CNBC shows
Last | 05/23/23 EDT12,560.25
-160.53 (-1.26%)
Going by last nights close on Stockopedia.
Nasdaq Composite Index
$12,720.78 62.88+0.5%
think you are looking at futures.
Nasdaq is never correct on Stockopedia (no idea why) it was down 1.3% yesterday.
And so does Yahoo. -1.26%
Pleased to see a non-exec Director and Chair bought 55,000 shares in WJG yesterday. Not huge but he was a lot braver than I was when adding to our growing holding.
Watkin Jones (LON:WJG)
I looked at this company earlier this year and couldn't get comfortable with it.
For example, I couldn't quite match schemes in development with those forward sold and delivered:
A few points here:
I was under the impression that once a project was forward sold, someone somewhere would be paying for it, so there shouldn't really be any cancellations...or maybe I've misunderstood something?
---
I also couldn't quite get my head around whether the gross profits, where the margin seems to fluctuate quite a lot (between 10.4% and 23.3% looking over the last few years), would be enough to fund the administration costs.
Looking at the recent interim results, gross profits were £16m, barely enough to cover Corporate Admin (£11.7m), Accommodation Management Admin (£2.5m) and the Finance Costs (£1.7m).
---
I have a feeling that I'm overthinking things again, so any insight into my concerns above would be most appreciated.
A
Enwell Energy (LON:ENW) announced a 15p interim dividend this morning sp closed at 15.7p yesterday. Up 28% Today but still seems like free money to me...
Unless they actually meant 0.15p but the rns said £0.15
Stockopedia quotes a forward PER for Enwell Energy (LON:ENW) of 0.8. I was wondering if that might be a record, until I ran a screen and found 16 London companies with a PER of less than 1.5, some of them quite respectable outfits. Are we looking at peak gloom?
I'd be careful with Enwell Energy. I don't know much about the company but the major shareholder is a Ukrainian who the current govt consider a traitor (corruption, Russian ties etc.) and they're trying to take the company off him, freeze his assets, take gas producing licenses away from his company etc. Enwell can't find an auditor for all of business ops outside of Ukraine because of all the well known problems with the company, and they've been looking for over 6 months. The shares are due to be suspended end June if they can't find an auditor by then and they'll have another 6 months to find an auditor before delisting. If they haven't found an auditor in last 6 months then I wouldn't rate their chances of finding one in their 6 month suspension period very highly. They're paying such a huge dividend cos they've got £60m plus cash in bank and it's way for major shareholder to get his cash out of company before it's presumably game over so might be worth a punt but buyer beware. The current govt in Ukraine is all powerful and they're on a crusade against corruption & supposed fifth columnists.
Yes got a short term target for selling. I reckon the sp will evaporate completely when it goes xd
Not a small cap but good results from Marks and Spencer (LON:MKS) Shore Capital note, smashing it!.
"Marks & Spencer's ('M&S') FY23 results have positively smashed our expectations; CPTP of £482m (SC, £431m) driven by a major beat on Food, with strong progress in Clothing and Home and International. Good trading momentum but further cost headwinds characterise FY24 and so we upgrade CPTP by c14% to £475m, EPS of 16.1p (noting a materially higher tax rate). In good shape with more to come, including a modest dividend in FY24, M&S equity trades on a modest FY24 PER of 10.2x, a lowly EV/EBITDA multiple of just 4.9x, with rating expansion a strengthening possibility in our view; now should be a very attractive entry point"
CPI inflation 8.7%
Forecast was 8 2% though, probably why ftse is dropping in futures.
Going to take much longer than expected in my opinion to bring this down as it’s already now being baked into salary awards.
Another dismal day ahead for small caps no doubt!
Private sector awards are hovering around 6% average, so not really driving the current level. Food is probably the main driver, but coming down slowly, as is energy. Fingers crossed it will drop quicker and faster soon!?
And RPI at 11.4%! It will be interesting to hear later if BoE still maintaining that inflation will come down rapidly.
Personally, I find it quite shocking that, for all the analysts and experts, they keep getting the forecasting wrong (not even close).
Hi Rev8, highly recommend the book by Philip Tetlock if you havent heard already explaining why the experts are often wrong - a nice antidote to believing their opinions.Superforecasting: The Art and Science of Prediction: Amazon.co.uk: Tetlock, Philip, Gardner, Dan: 9781847947154: Books
Hi TGP20
I completely agree with your recommendation of the Superforecasting book.
It inspired a focus on being more disciplined with my stock sales, especially when I saw the story was changing and wasn't sure what to do.
I now try and assign %'s to outcomes and use those to make my decisions.
---
As an example, I recently sold one of my favourite holdings - Ivu Traffic Technologies AG (ETR:IVU) , (essentially a larger, German-based Tracsis (LON:TRCS) ) who coincidentally released their Q1 results this morning.
It's a fantastic company and in the long term I'm sure they'll continue to perform well. Results this morning were unsurprisingly excellent.
But the share price is already expensive and I can't see it moving much higher in the short-term, so I decided to sell and redeploy elsewhere.
I hope to buy back in one day and will continue to monitor for when I believe there is a greater chance of more near term upside.
My decision to sell might of course be wrong, but statistically I would hope that my overall returns will be greater by thinking like this.
A
Isn't it more shocking that there is a profession in forecasting. There are teams of economists that are making stuff up every day. If they were any good, why would they work for anyone. As Peter Lynch said: if you spend 15mins on economics, you've wasted 8mins (something along those lines)
Just remember that one of the reason for forecasts is to encourage action to avoid that forecast!
So inherently the forecast is going to be wrong because people, companies and govt's change what they do (and the forecast is based on) depending on what the forecast is!
Good point.
Only good news is energy prices are predicted to fall tomorrow and again in October. If the price cap does fall by £400 from £2,500, that will be quite significant.
BoE and Bailey have done a lousy job. Almost everyone said it wasn't transitional.