Small Cap Value Report (Wed 27 June 2018) - FJET, CRAW, XAR, TAM, LIO, ULS, OPM

Greetings - we have a bunch of exciting updates today, making the World Cup Group F games at 3pm pale into insignificance!
Stocks of interest today are:
- Tatton Asset Management (LON:TAM) - results
- ULS Technology (LON:ULS) - results
- Fastjet (LON:FJET) - funding update
- Crawshaw (LON:CRAW) - trading update
- Xaar (LON:XAR) - trading update
- 1pm (LON:OPM) - trading update
- IWG (LON:IWG) - trading update
- Liontrust Asset Management (LON:LIO) - results
Stories are presented below in order of the headline to this article!
Fastjet (LON:FJET)
- Share price: 4.95p (-68%)
- No. of shares: 522.4 million
- Market cap: £26 million
Mentioning this first as it is the simplest story today. A bad business in a bad sector, listed in London but based in Africa, is running out of money again.
This had many hallmarks of a stock to avoid. The most obvious and important one being that it repeatedly ran out of money.
And it was remarkable that a few City fund managers kept putting fresh funds into it. I only wish I could have been a fly on the wall to hear their conversations and rationale in advance of each placing.
Perhaps they are about to throw in the towel at last:
The Company is currently in active discussions with its major shareholders regarding a potential equity fundraising, in the absence of which the Group is at risk of not being able to continue trading as a going concern.
Fastjet would never have existed if stock market investors had not been found to throw money at it. I continue to believe that it is worth close to zero.
The algorithms appropriately identify it as a Sucker Stock.
Crawshaw (LON:CRAW)
- Share price: 5.25p (-25%)
- No. of shares: 113 million
- Market cap: £6 million
Today's trading update from this chain of butchers strikes familiar themes: high street shops doing poorly, factory shops doing well. The macro environment is blamed (lower footfall on the High Street) and like-for-like sales are very poor:
Group sales were at -1.6% for the first 20 weeks of the current financial year with like-for-like sales down 12.9% for the same period. The trading performance of our high street shops remains challenging and reflects the widely reported lower footfall and softer consumer sentiment. Our factory shop format continues to perform well in this environment.
I'm very curious to see Crawshaw's interim results (out in September), to check for evidence that its transition to the factory shop model is starting to yield financial benefits.
The results for the year ending January 2018 showed an EBITDA loss and further losses are anticipated in FY 2019.
According to the FY 2018 results, Crawshaw "should be able to operate within its cash reserves" during FY 2019, so it has not acknowledged any need to raise fresh equity yet.
The shares are still much too speculative for me, personally. But I am leaving it on my watchlist, to check for any signs of a turnaround.
The Stocko algorithms have a very suitable classification for this stock, too: Value Trap.
Xaar (LON:XAR)
- Share price: 237p (-14%)
- No. of shares: 78 million
- Market cap: £185 million
Another quick profit warning to cover today.
Xaar is a Cambridge-based manufacturer. It makes the high-tech printheads that get used in industrial printers for advanced or demanding applications like ceramics, wood, glass, 3d printing, etc. See here for a list of applications.
It's been a while since I've studied Xaar in any depth. It first appeared on my radar around 2014, when I thought it looked good value after some sustained share price weakness (unfortunately for me, it went on to have several nasty profit warnings).
It has a volatile track record, as these charts help to illustrate:
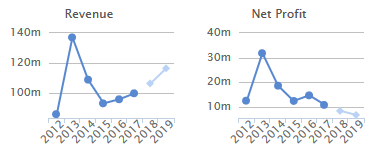
Overall, the trend in profitability is downward (see right-hand-side), and the share price is back around those 2014 lows.
This puts it firmly within the remit of a Small Cap report such as this.
Today's update again points to a lack of visibility in its end-markets, and volatile sales results:
Our strategy remains one of diversifying the business, introducing a broader range of products across a wider range of market sectors and developing partnerships to exploit the on-going analogue to inkjet conversion within print markets. We continue to make progress with this but the rate of market adoption remains difficult to predict.
We are guided toward the dreaded second-half weighting and guided for full-year profit to be in line with expectations, despite ceramics sales being below expectations.
Job losses are on the cards. Xaar employees have suffered too, from the company's volatile results. Back in 2014, 160 employees were let go in a single swoop (about a fifth of its entire workforce at the time).
I imagine that there is more pain to come, given the H2-guidance and the weak sales guidance.
Having said all of the above, I still have the belief that there is money to be made in this niche, and that Xaar is not a badly-run company.
It has always had a strong balance sheet, and nearly always been profitable (using the past 20 years as a guide).
If I perceived that shareholders had finally crossed the threshold into peak gloom, and the shares were sufficiently cheap, there is a level at which I'd be interested to buy into it again.
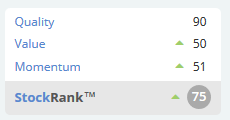
Stocko algorithms are picking up on a few positive characteristics, too:
Tatton Asset Management (LON:TAM)
- Share price: 233p (unch.)
- No. of shares: 56 million
- Market cap: £130 million
My first time looking at this stock - it has been listed only since last year.
It provides services to the mass affluent population via independent financial advisors. From its website:
Tatton Asset Management offers on-platform only discretionary fund management, regulatory, compliance and business consulting services, as well as a whole of market mortgage provision, to Directly Authorised financial advisers across the UK.
A strikingly positive headline for today's announcement. These are results for the year ending March 2018:
"Excellent debut - Strong growth across all businesses"
A few of the highlights:
- Tatton's discretionary assets under management ("AUM") increased 25.6% to £4.9bn
- Average AUM inflows of over £80m per month maintained
- Adjusted Operating profit1 up 44.7% to £6.5m
Tatton Investment Management Limited (TIML) is key to the story. It has over 300 adviser firms on board and almost 50,000 client accounts (average size: £100k, so nearly £5 billion under management).
This is what it does:
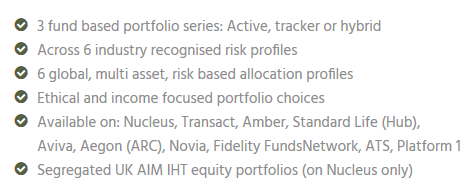
Route to market seems to be working, given the fast growth in AuM.
I like the overall strategy, organic growth being highlighted ahead of "selective acquisitions":
The Group's strategic objective remains focused on organic growth through the provision of all major products and services that an IFA requires to service its clients.
The full-year dividend is 6.6p. That makes for a helpful yield against the current share price.
Outlook statement is confident, as you would expect given the preceding tone.
My view
I'm still getting to grips with the details of what Tatton does, but my initial impressions are positive.
For context, it's important to realise that the FIML business is providing a service to IFAs and acting as a go-between for the fund management companies who are actually managing client assets, so its slice of total fees is relatively small.
As usual with recent IPOs, I will be more comfortable with it when it has a slightly longer record as a listed company.
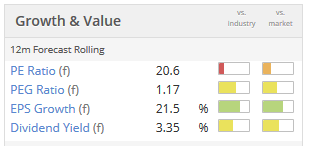
Stocko algorithms see little value at the current share price, and I am inclined to agree. It would need to continue growing at current rates to disprove this:
Liontrust Asset Management (LON:LIO)
- Share price: 608p (+3%)
- No. of shares: 50.5 million
- Market cap: £307 million
This is more like the type of asset management business that I would typically invest in: one that is actually running money and earning most of the fees.
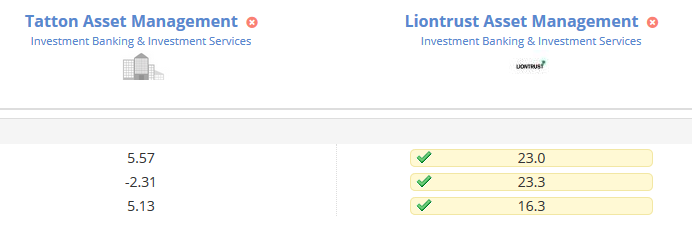
As Gus, suggested in the comments, Liontrust is doing better than Tatton according to several metrics.
I would have suspected that Liontrust would have good quality metrics: this is a general feature of fund management companies.
The Tatton numbers should improve, but there is no doubt that Liontrust is already doing very well. From top to bottom, this is Stocko's view of their Return on Capital, Return on Equity and Operating Margin:
Liontrust's results today are sparkling.
It has achieved large inflows, massive growth in AuM, bigger performance fees and substantial top and bottom line growth.
AuM analysis is as follows:
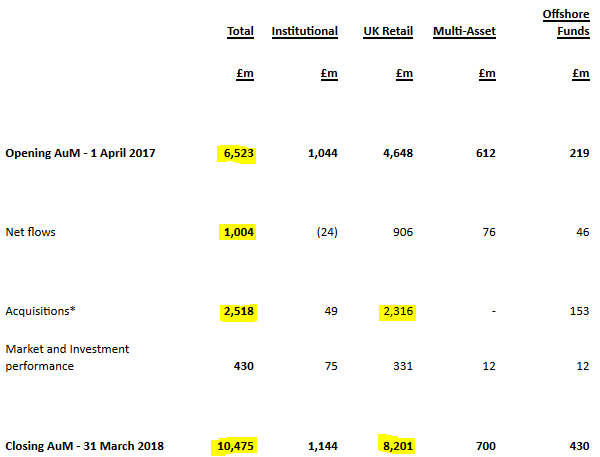
Organic growth from inflows (£1 billion) was 15% of the starting level (£6.5 billion) - pretty good.
If that was achieved every year, combined with decent performance, AuM would snowball to massive levels.
Acquisitions were nearly all UK retail-based, increasing that category as a percentage of the total. It's an attractive category, so there's nothing wrong with that. Liontrust bought out the investment management division of Alliance Trust (LON:ATST).
The team joining from Alliance Trust focuses on Sustainable Investments, similar to Impax Asset Management (LON:IPX) which we have covered in this report.
Environmentally-focused investing is extremely popular at the moment, and fund flows to this particular team of managers may have been suppressed by its association with Alliance Trust (which was the subject of a shareholder activist campaign).
The Sustainable Investments team now has £3 billion in AuM, up by half a billion during the year. It was an acquisition that worked out even better than expected:
Following the completion of the acquisition, the positive fundflows were significantly higher than initially expected. The perception of corporate instability surrounding AT Plc and to what extent it would suppress demand for ATI's retails funds had not been fully considered. Additionally management had not been fully aware of the increase in UK investment consumer demand for 'Sustainable' investments.
My view
I think there are a bunch of positive characteristics to this stock. See how it has been enjoying strong earnings momentum:
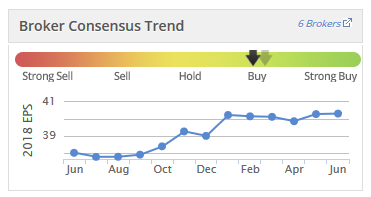
The forward P/E multiple is not too demanding (13.4x, according to Stocko) and the StockRank is an excellent 88.
So I think this is certainly worth a second look.
ULS Technology (LON:ULS)
- Share price: 135.5p (unch.)
- No. of shares: 64.8 million
- Market cap: £88 million
ULS Technology plc (AIM:ULS), the provider of online technology platforms for the UK conveyancing and financial intermediary markets, announces its Full Year results for the 12 month period to 31 March 2018.
This stock is new to me. Paul covered it once last year.
I need a simple explanation of what it does. From its website:
Customers use our service to compare conveyancing quotes based on price, location and service rating, made possible by the quality assured solicitor and licensed conveyancing firms with whom we partner.
FY 2018 is ULS' first full year of ownership of a company it acquired for £10.6 million (including earn-out), during the prior financial year.
I can't see what this acquired company ("Conveyancing Alliance") contributed to ULS's results in each year, but it was earning revenues of £4.4 million and PBT of almost £1 million as an independent company, back in 2015.
So the growth rates seen below will include a significant element of growth from the inclusion of CA for a full year:
- Revenue increased by 38% to £30.7m
- Underlying EBITDA1 increased 25% to £6.4m
- Underlying Profit Before Tax1 increased by 26% to £5.5m
The adjustments to PBT need to be treated with care.
For example, it excludes the amortisation of acquired intangibles.
These intangibles include customer relationships (which have been found to have a much shorter life than originally anticipated) and a technology platform which is assumed to have a useful life of 10 years.
I would think that the amortisation of these intangibles does need to be included in a reasonable PBT measure.
In addition, underlying PBT gets a £200k boost from the company capitalising more development spending than it amortises.
This use of intangibles ultimately makes the balance sheet less bullet-proof, and a quick inspection reveals that ULS's equity of £9.3 million is outmatched by nearly £18 million of intangibles.
Since its growth is not entirely organic and the balance sheet is weak, I've not seen enough to interest me in making an investment at this valuation, so will stop here.
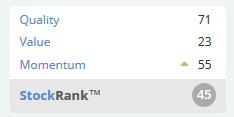
Stocko robots agree that it is fully priced:
1pm (LON:OPM)
- Share price: 46.5p (unch.)
- No. of shares: 86 million
- Market cap: £40 million
This is a rapidly growing SME finance house, acting as both a lender and a broker. I've neglected to include it within my own portfolio, preferring to invest in PCF (LON:PCF), whose banking licence is spurring it to growth. But I must admit that the momentum at 1pm (LON:OPM) looks excellent, and this share could be excused for feeling neglected by investors.
Despite not having a banking licence, 1PM's lending capacity has still shown tremendous growth, thanks to support from the wholesale markets:
The Group's raw material is cash. The Group is pleased to report continuing and increasing support from the providers of wholesale funding facilities and debt investors. As at 31 May 2018, total borrowing facilities stood in excess of £160 million (2017: £74.5 million), an increase of over 2 times.Its cost of borrowing has fallen to less than 4%, enabling it to increase net interest margin.
It is growing primarily by acquisition: the total lending portfolio is up 50%, but only 10% of this is organic. Revenue is up 75%, of which 30% is organic.
An emphasis on growth-by-acquisition is one reason for me to feel cautious toward this stock. Another reason is that reliance on the wholesale markets is much less secure over the entire business cycle than, for example, retail deposits.
Despite these negatives, I'd still be inclined to think that the market is being unnecessarily harsh in terms of the share price. According to Stocko, 1PM is trading at a 10% discount to book value and at a P/E ratio of just 6x.

All done for today!
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Just in case anyone missed it I wanted to point out the fall in Ramsdens today following bulky sales by Management. I like the company but not sure what to think.
A couple of observations on Liontrust Asset Management (LON:LIO) which I hold. They have done a good job of systematically diversifying away from a previous over reliance on Anthony Cross and team (though he still manages a very large proportion). While they are still overwhelmingly retail focused, they have and continue to make hires to beef up institutional. If they can attract institutional funds to their Sustainable Future funds then there could be a significant rise in AuM.
Last year the growth "story" was centred around the Sustainable Future funds which brought an additional pillar to the platform. This year it's the launch of Fixed Income with the hire (announced last August) of Roberts and Milburn from Kames. They launched 3 funds in early April (NB after the end of the financial year) that have gathered £214m. For context, Graham points out that total net inflows for 17/18 were a bit over £1bn and, of this, about £500m was Sustainable Future off a base of £2.5bn. So, if, after a few weeks, the three new fixed income funds alone have attracted 20% of last year's full year total maybe there's quite nice potential. When Liontrust announced they were joining, I checked Trustnet for which funds they managed at Kames. Alas, they had already been removed but, helpfully, Trustnet tells you how long a manager has been in place. The funds that changed a manager the day before Liontrust announced the hiring of Roberts and Milburn were Kames Strategic Global Bond ($638 AuM at the time according to Trustnet), Kames Strategic Bond (£320m), Kames High Yield Bond (£908m) and Kames Sterling Corporate Bond (£604m).
Hi,
I know David Roberts and Phil Milburn, as they used to be clients of mine. They are both good solid corporate bond guys who come with a good pedigree and are both long enough in the tooth and smart enough to know how to both perform and attract AuM. The problem they may face is one of timing. If rates do accelerate higher then selling bond funds, especially ones without a track record regardless of how good they are will be an uphill task.
However, if you look at the biggest retail fund out there run by Richard Woolnough at M&G, if they can attract even a fraction of that kind of inflows they will do extremely well. Twenty Four asset management funds are perhaps a good benchmark for what can be achieved from a standing start. I would suspect their focus will largely be higher yielding sterling credits to attract the yield hungry IFA driven flows. This brings another issue that I have no idea on, in that the need to be market it across the land will be substantial and could impact on their day to day portfolio management. Cheers.
Very interesting comments on the new arrivals at Liontrust Asset Management (LON:LIO) thanks.
I think I'd be pretty happy with somewhere north of £500m after a year or so in aggregate across the funds which doesn't seem out of the question given where they are at the moment and Twenty Four Corporate Bond.
Would Kames also be classed as retail or largely retail? The equivalent Kames funds have (in aggregate) lost some AuM since the Liontrust launch. I was hoping there might be a partially loyal institutional customer base that would follow them from Kames and be married with new Liontrust retail customers. But that may be wishful thinking.
PS There is always a problem with looking at % changes on ST recommendations. The price a PI will be able to buy at is usually quite a bit higher than the price that appears in print. He even advises waiting with his Bargain Shares because prices often fall back a bit after the initial rise.
I wouldn't want my mention of ST in my Crawshaw comment to be seen as a negative comment on him (and I wasn't following his tips with my duds). It is more a comment on the climate of positivity around some of those companies. ST has a lot of PI followers, so he is a prime target for someone with a story (justified or not) and shares he recommends will be more often bought by PIs than would have been the case without his support.
With Paul, we know what has happened - he comments on results that came out earlier in the day, and if he speaks to anyone (usually not) he mentions it; and his views can be positive, neutral or negative. And he still bought Conviviality and was taken in by the previous RBG management (but still likes the business). I doubt that anything appears in ST's column without phone calls having been made (part of his diligence) and there is a pressure to recommend buys (all his readers are interested in buys, only holders are interested in sells). And we don't know the journey his ideas have followed before they appear - could be 'information' from a contact, a recommendation by someone he knows, or something he found sniffing around the markets for his Bargain Share portfolio - and we don't know who he has spoken to. The important thing for PIs to understand is what he will have done (some diligence by phone, some surface analysis of the figures) and what he may (or may not) have done - deeper digging for things that might be wrong with the story or the figures.
A bit surprised at (the sometimes vague) negative comment about Simon Thompson, who used to be Companies Editor at Investors Chronicle and is now Associate Editor, with an excellent regular column along with frequent online updates. As with Paul and Graham here, the quality and depth of his comment is mind boggling and how they do it day after day beats me!
Of course Simon Thompson tips the odd dud, and makes other mistake including real howlers like tipping Chinese frauds Naibu (or whatever it was called) and Camkids. If he had read quality bb comment on sites like Motley Fool he would have realised the risk that they were complete frauds. Also suspect he doesn't subscribe to this site and he would be better still if he did. He is very balance sheet focused.
One big success is his annual bargain shares portfolio. I couldn't access his successful 2017 portfolio before writing this, but his 2016 portfolio of 10 bargain shares is currently up 47% overall and there is only one losing share (Walker Cripps down 16%) in it. The best in that 2016 list are Bioquell +144%. Volvere + 117% and Bowleven + 86%.
His latest 2018 portfolio is also doing very well with all 10 shares in profit. Average gain so far this year is 27%.
Here are the 10 shares:-
Parkmead +65%
PCF + 45%
Shore Capital +34%
MPAC + 32%
U and I + 24%
Titon + 24%
Sylvana Platinum + 17%
Conygar + 7%
Record +5.8%
Crystal Amber + 5/8%
My own investment record has improved substantially since subscribing to Stockopedia nearly 3 years ago, and even more so thanks to Paul Scott and more recently Graham too. They are so good at highlighting shares well worth checking as well as ones not worth a second look! Add their skills to the wealth of information on this site and it's a compelling package. BUT I also look for quality information elsewhere and Simon Thompson is certainly very high quality.
That does not apply to all tipping shares on Investors Chronicle. A lot of their tips are semi anonymous with just initial of first and surname hidden away, and a quick check sometimes shows the writer only just out of University or first job. Hence the very embarrassing Conviviality "tip of the week" just a day or so before it went bust. Many contributors to the comments threads here are likely to be much better informed than some of their writers. And presumably the same applies to newspaper tipsters who are journalists first. Sometimes their investment ignorance is very clear to see. . But lump Simon Thompson in that dud category? Never!
Yes, ST is the IC's famous Associate Editor.
I think that his problem is only partly the amount of space he has to fill (which inevitably means weak due diligence) but also that one of his strategies is to purvey from tips from people who have nudged him. If it looks OK on the surface he passes it on. Some of them are good and others aren't. I think he was one of those taken in by Globo. From PI point of view, I think it's just a question of doing deep due diligence yourself, (knowing that he hasn't) realising that the original story may have come from a convincing someone with an agenda and accepting that a recommendation from ST will inevitably have puffed the market price short term. btw, afaics he didn't recommend Crawshaw (LON:CRAW), though the IC's John Rosier seems to have done.
ST has given some good advice in the past but the problem now in my view is that he is trying to tip too many shares. Inevitably some of these will be successful and others will not. He tends to write follow up articles on the successful ones - less so though on the duds.
Even God allowed his prophets to be wrong sometimes - if only to keep them humble!
Simon Thompson is a journalist not a soothsayer. The Investors Chronicle has been around for decades - if it could make everybody rich it would have suceeded by now.
I regret to say we are the ones responsible for our own (mis)fortunes.
Bonitabeach
Xaar has always had a fundemental flaw, it is an innovator but sells into the Chinese market where its competitors steal all its ideas. It has some very good people but battling that sort of problem is beyond it.
It's just come to me -ST is the bloke who writes for the Chronic Investor. Simon Templar or something like that.
Problem for him is that he has too much space to fill so will invariably come up with duds.
wildshot -I'm also wondering about that. Maybe ST is Sunday Times?. Also what is post \\378204? Are posts numbered? Maybe this weather has addled my brain.
I may be wrong but I believe ST may be a well known investors chronicle columnist!
Hi
i thought ST was Sunday Times but now realise that it is Simon Thompson.
As to the \\378204. This will be the record value of this post in the Stockopedia relation database. So in table “SCVR Comments” or “All comments” depending on how they have set it up, the first field will be the index value of the entry and will be unique in that table and enables other tables/records to be linked to it. I think normally the value \\378204 is translated to another value being the post number for posts that day (so that it is easy to find/makes sense) but something must have gone wrong with the coding. I am sure Stockopedia will correct it soon.
“ I think normally the value \\378204 is translated to another value being the post number for posts that day (so that it is easy to find/makes sense) but something must have gone wrong with the coding. I am sure Stockopedia will correct it soon.”
Yes. This only seemed to go wrong recently. It is very frustrating not to be able to work out who a poster is replying to in a long thread.
Looking forward to it being sorted out soon hopefully.
Yes. This only seemed to go wrong recently. It is very frustrating not to be able to work out who a poster is replying to in a long thread.
Click on the link in the "in reply to post #" and it shows you the original message. It's a bit annoying, but hardly the end of the world. Stocko obviously have a few issues with a recent upgrade, but such is the nature of Agile development.
Back in my day we'd have specified it to death and got it right first (err, well, fifth) time. On the other hand, we'd have only upgraded once a year, and we'd still have a website that looked like AOL in 1998 ...
timarr
Thanks for your comments about Xaar. With an old market falling faster than expected and a new market difficult to forecast, it's hard to see how this will turn out. But could the Stockopedia team explain how a company where the share price has fallen from 500 in Nov 2017 to 233 today has a Momentum score of 51.
Hi Chris,
I was intrigued by this too. I drilled into the momentum ranking expansion and, under the geek section' it says "where the 50-day MA is much higher than the 200-day MA tend to perform better over the subsequent six months" or this case the 50-day MA is less bad than the 200-day so it's effectively starting to pull up from a dive. I do however suspect the numbers don't reflect today's fall so it should get worse when the numbers get crunched again. I'm not sure how frequently that happens on Stocko but would be interested to know.
I have no position in Xaar (LON:XAR)
cheers
Regarding Xaar (LON:XAR) 's Momentum rank, it gets boosted by the values for % 1m EPS Upgrade FY2 % 3m EPS Upgrade FY1 and EPS Surprise %, Last Interim.
Arguably this is a mixing up of two different factors into a single number. But for what it is worth this is the explanation for how it gets a Momentum Rank of 51 even though the "Price Momentum" figures are all low.
https://www.stockopedia.com/aj...
Xaar MomentumRank™ Components
MomentumRank™ Composite: 51/100
Hi Graham, I am very interested in your thoughts on opm; 1pm. Lat time you were going to look at them but ranout of time. The numbers look sound and the multiple is attractive. Operating margin in 20s but ROCE and ROE not so . Stock I have had on my watch list for a while as seems interesting but ……….. all the best
Crawshaw (LON:CRAW) has been an interesting learning experience for me. The were very popular with PIs when I moved heavily back into the market in 2015. I looked at them, and the metrics were OK(ish) but growth was good. but I thought 'butchers shops? what sort of magic dust can be spread on butchers shops?' I even went and looked at one locally, which was basically a permanent market stall, doing a bit of unappetising hot food (Greggs they weren't), more freezer pre-packs than normal, and a smaller meat range. I didn't buy anything and saw no magic dust. And the price kept on rising. Now we have an inkling that the magic dust was over the contracts and accounts and expansion, though I still don't understand how LFL can be so poor.
When I review my duds, I can see that they were all popular at the time, all tipped by ST, and all had my own little red flags I should have acted on at the time. My own 'errors' where the price fell heavily were all a case of getting in too soon and came right in the end (often with me putting more in at the bottom). Teach me to stick to my last!
I don't know if ST recommended Crawshaw (LON:CRAW), and can't check because the site is down for 'maintenance'.
Excuse my ignorance but you say "all tipped by ST", who or what is ST please?
Simon Thompson of the investors chronicle....
Simon Thompson at the Investors Chronicle...or IC ..
That'll probably be Simon Thompson of the Investors Chronicle
Morning Graham.
I see you’re looking to cover asset manager Tatton Asset Management (LON:TAM) in today’s SCVR. Reference my earlier post #1, although they are both High Flyers, at face value the Stocko algos suggest it is some way behind Liontrust Asset Management (LON:LIO) on most metrics which also reported today. Interesting to compare the two directly although clearly providing different services in their respective spheres.
Gus.
https://www.stockopedia.com/compare/?tickers=LON%3ATAM%2C+LON%3ALIO%2C+
re: Tatton Asset Management (LON:TAM) / Liontrust Asset Management (LON:LIO)
Thanks Gus!
test-please ignore
A second request for ULS Technology (LON:ULS) whose March 2018 final results are out today. Yet another example of their preferred EBITDA and adjusted EPS measures all looking good. If you have the perseverance to read down to the p&l (maybe 20 pages in) pbt has reduced because of a large increase in an expected deferred consideration for an acquisition. But if acquisitions bring in additional revenues and profits then the cost of those acquisitions should be counted too.
And most of their prior year numbers are reported as 2016, while some are reported as 2017. Is this just poor proof reading are a sign of lack of attention to detail?
I don’t hold but the story is interesting
Cerillion (LON:CER) presentation by CEO & CFO at MelloSouth, just published
http://www.piworld.co.uk/2018/...
Also, worth looking at this with the write up by Graham back in May, when he interviewed management.
Graham, would you look at ULS Technology please? Underlying EPS of 7.2p apparently beats forecast in Stocko of 6.5p but shares down about 3%. Small dividend increase. Borrowings plus trade and other a/c payable looks high.
HI Graham,
Walker Greenbank (LON:WGB) gave an AGM update today which I'd appreciate your views about.
Weak first half with optimism for the second. Not sure what to make of this but on balance not as bad as it could have been? Or was the SP fall yesterday an indication that that part of the market who was in the know doesn't like it?
Anyone else have views?
cheers
Francis
My morning smallcap tweet: Brace, brace, brace! Farcejet flameout.
Fastjet (LON:FJET), Crawshaw (LON:CRAW), ST Ives (LON:SIV), 1pm (LON:OPM)
Farcejet (FJET) Despite the new loan agreements of 5 June it's critically short of cash. Discussing equity fundraising, in the absence of which the Group is at risk of not being able to continue trading as a going concern. If the fundraise is not successful the annual results won't be published and shares will be suspended.
Crawshaw Group (CRAW) High St trading still dire. Group LFL -13%. "There are numerous key sales-driving and cost-saving initiatives currently being undertaken." Should butcher that dead horse instead of flogging it. Factory shop format continues to perform well.
St. Ives (SIV) A J to replace the CEO who leaves in August. J Schwan, who has been with the Group for three years. "J began his career in Accenture's emerging technologies lab." So his first name is J!
1PM (OPM) guides FY rev slightly ahead of market expectations with profits in line following further investment in operations.
Reference St. Ives. This is a classic case of J walking, attracts a prison sentence in some American states ..
Farcejet - very good, MrC. Very good.
test please ignore
test - please ignore
OPM FY trading update interview with Ian Smith, CEO talking through today's RNS
http://www.piworld.co.uk/2018/06/27/1pm-opm-full-year-2018-trading-update/
What’s behind the improved revenue and EPS? – 00:28
The market – 01:27
What does ‘50% of current year revenue being held in unearned income’ mean? – 02:12
Costs? – 03:04
Borrow facilities and cost? – 03:55
Integration of acquisitions – 04:54
Outlook –
Full year results out from specialist fund manager Liontrust Asset Management (LON:LIO) this morning.
https://www.investegate.co.uk/liontrust-ass-manplc--lio-/rns/final-results/201806270700036705S/
Strong growth in revenues and profit with AUM up 61% YoY. Decent increase in the dividend announced. High Q and M factors but starting to look fully valued.
Gus.