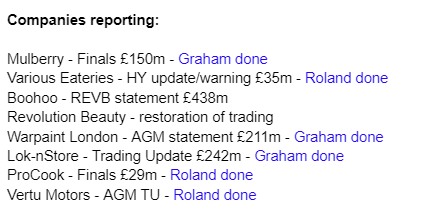
Small Cap Value Report (Wed 28 June 2023) - MUL, PROC, W7L, VARE, LOK, VTU, REVB

Good morning, it's Graham and Roland here with today's report. Paul is back tomorrow from his mini-break!
11.20am: today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Quick comment
Revolution Beauty (LON:REVB) - there has been boardroom drama at Revolution Beauty, whose shares were unsuspended today and are up 56% at the time of typing this (market cap £92 million).
At yesterday's AGM, which REVB unsuccessfully attempted to adjourn, the company's largest shareholder Boohoo (LON:BOO) used its voting power to remove the CEO, the CFO and the Chair.
REVB was left with only one Director on its Board.
After the AGM, that Director then decided to reappoint all three individuals, who had just been booted out, to their former positions! And he also brought in two other NEDs.
Boohoo describes what happened as "self-serving" and an "abuse of process".
REVB says that the company needed to reappoint its Board members in order for the shares to be unsuspended, and has promised that it will allow a fresh vote in late July or early August.
Graham's view - this is hardly a controversial take, but I think that when shareholders vote against the re-election of directors, the remaining directors should not unilaterally reappoint those individuals!
Therefore, I think that the remaining director at REVB should have taken no action and should have allowed the shares to remain suspended. The restoration of trading is not the most important thing, and it could have happened at a later date. Respecting shareholder votes is far more important, in my view.
I also note that REVB has used the restoration to grant millions of options to the CEO, CFO and other members of the management team, diluting existing shareholders by 3.4%.
REVB says "the options awarded are fully vested, but shares will be subject to a 12-month holding period".
If I am reading this right, it means that the individuals receiving these options do not need to achieve anything further in order to reap the benefits of these option awards. They will have the right to cash out after 12 months.
Furthermore, these are nominal cost options, so there is not even a challenging hurdle that the share price needs to achieve.
The CEO gets 5.6 million nominal cost options (5.6 million shares are currently worth £1.9 million).
The CFO gets 2.8 million nominal cost options (2.8 million shares are currently worth nearly £1 million).
I am open to any counter-arguments, but this strikes me as disgraceful behaviour by a company, to grant such bonuses to directors who just lost a shareholder vote.
There is a long backstory at REVB but purely on the basis of today's news, I would give these shares the thumbs down. I would never want to invest in a company that behaved like this.
Summaries
Mulberry (LON:MUL) - up 3% to 260p (£156m) - Finals - Graham - GREEN
The performance of this luxury goods company remains something of a mixed bag. Revenues are doing ok, but profits for FY 2023 were only saved by closing an impaired London store. I continue to believe in the possible undervaluation of the stock.
PROCOOK (LON:PROC) - down 10% to 23p (£25m) - Finals - Roland - RED
Like-for-like sales at this cookware business fell by 10.7% last year and are down by 7.9% so far this year. Low margins and high fixed costs are making life difficult and the company has warned of going concern problems if trading continues to worsen. Too risky for me.
Warpaint London (LON:W7L) - up 1% to 277.25p (£213m) - AGM Statement - Graham - GREEN
This share has had a pleasant rise and cannot be considered a “value” share at this point, but it does still have nice earnings momentum. Today’s AGM statement reveals strong trading in recent months and an imminent expansion into Superdrug. I’ll stay positive.
Various Eateries (LON:VARE) - down 15% to 34p (£29m) - Interims/warning - Roland - RED
This restaurant chain has seen profit margins slump in the face of rising costs. H1 cash flow was heavily negative, while insider ownership and loan arrangements suggest delisting and refinancing risks, too. I think there are far better options available elsewhere in this sector.
Vertu Motors (LON:VTU) - down 1.5% to 68p (£239m) - AGM Statement - Roland - GREEN
A solid quarterly update from this car dealership group. New vehicle supply is said to be improving and Vertu’s profit margins have remained stable. Full-year results are expected to be in line with current forecasts. I think the shares look reasonably priced.
Lok'n Store (LON:LOK) - up 2% to 820p (£267m) - Trading update - Graham - AMBER
This self-storage business remains in an impressive growth trend with stores opening, under construction and in planning. I continue to view this as an excellent business but it’s arguably too expensive relative to NAV and the earnings multiple is also far from cheap at 27x.
Graham's Section
Mulberry (LON:MUL)
- Share price: 252p (pre-market)
- Market cap: £151m
I should try to keep these comments brief as this stock, despite a market cap of £150m, is not liquid: over 90% of it is owned by the Malaysian Ong family and by Frasers Group.
For more of the background, check out my comments from April.
Here are the highlights from today’s full-year results for the financial year ending April 1st, 2023:
Revenue +4% to £159m (this is ahead of the revenue estimate shown in the StockReport, £155m). Revenue has been boosted by Mulberry taking over some stores in Sweden and Australia that were previously run by franchisees.
The core UK and Asia Pacific regions are not doing as well as “international” markets.
Gross margin is still excellent at 71.2% (last year: 71.7%).
Underlying PBT of only £2.5m, after spending £4m on “SaaS costs and additional investment in the Group”. The net income estimate on the StockReport was better than this at £6m.
Current trading / outlook
Revenue in the first 12 weeks of the financial year is up 6%.
Retail revenue +15% (with the help of the newly acquired stores), offset by a possible decline in total franchise/wholesale revenue.
As of yesterday, Mulberry now has full ownership of Mulberry Japan Co. Limited.
Dividend cut: only a 1p final dividend (last year: 3p). The Chairman refers to “the external environment and ongoing sector headwinds”, but the harsh truth is that Mulberry used up £25m of cash during the year, and generated very little profit.
Speaking of which, let’s see where all the cash went!
Net cash outflow from investing activities: £14m (£3m on acquisitions, £7m on capex, £4m on intangible assets).
Then there were £10m on lease payments and £2m of dividends, offset by a small cash inflow from operating activities.
The company insists that all of the spending will help to underpin its future success, with new digital platforms, new back-office systems, new stores, etc.
Reported PBT: while some aspects of today’s numbers are disappointing, reported PBT was actually quite good at £13m. Mulberry gained £11m from the reversal of impairment charges, after it closed its store on London’s Bond Street.
Graham’s view
I’ve previously given this one the thumbs up, on the grounds that its price to sales multiple is simply too low at 1x, compared to other luxury brands. Burberry (LON:BRBY) (in which I have a long position) earns lower gross margins than Mulberry, but Burberry trades at a P/S multiple of 2.6x. Kering trades at 3x, and LVMH trades at 5x.
The one small problem that Mulberry has is that it doesn’t generate much profit (!). However, I continue to believe that this problem can be fixed at some point, either by Mulberry itself or by a larger competitor that takes it out and eliminates duplicate costs. I haven’t got a great deal of conviction and I don’t know when it will improve, but I’m going to leave my positive view here unchanged.
I’ve never owned these shares but if I had known back in 2012 or 2015 that they would be available at £2.50 in a few years, I’d have been very excited about the prospect of picking some up at this much lower level!
Warpaint London (LON:W7L)
- Share price: 277.25p (+1%)
- Market cap: £213m
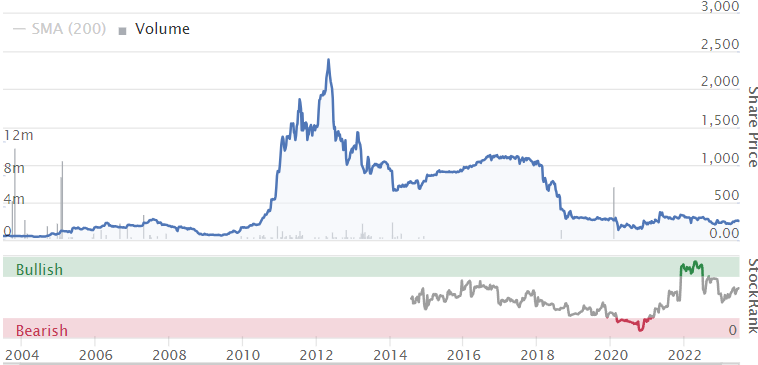
This was a hot share at the recent Mello conference. Many investors must be sitting on nice gains after the recent run-up in the share price:

Today we have an AGM statement:
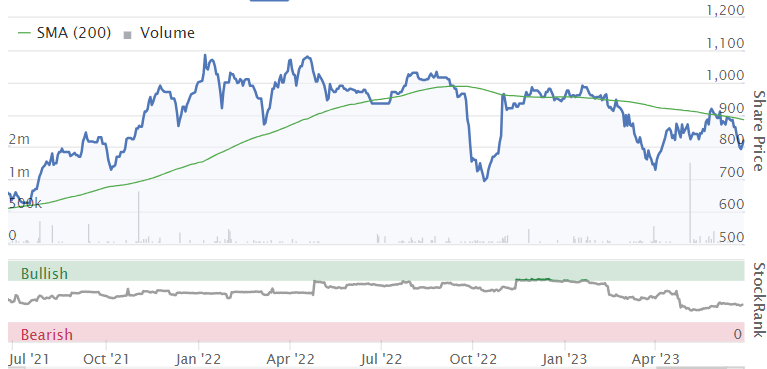
"The Group continues to trade strongly with sales for the six months to 30 June 2023 anticipated to be in excess of £36 million (six months to 30 June 2022: £25.2 million), with margins continuing to be robust and ahead of those achieved in 2022.
In further good news, the W7 brand is launching in “an initial 73 Superdrug stores” in September, and there are “active discussions” with other retailers.
Graham’s view
Damian Cannon presented this at the Mello BASH, and I also attended a presentation by the CEO. Based on what I heard then, I could think of few major issues with the investment thesis here. Yes, it’s a “copycat” business model, and it won’t ever have the prestige of other brands. But that won’t necessarily stop it from being an effective provider of core cosmetic products and cheap alternatives to the prestige brands.
The gross profit margin last year was 36.4% - not what you’d want to see from brands at the other end of the price spectrum, but still impressive for what are considered to be cheap products (e.g. lipstick for £3.95).
At December 2022, the company reported having cash of nearly £6m and no debt.
The shares themselves are a little pricey (ValueRank of only 18 and a PER of 18x). However, it has the tailwind of earnings momentum behind it and in the spirit of letting winners run, I’ll maintain a positive view on this for the time being.

Lok'n Store (LON:LOK)
- Share price: 820p (+2%)
- Market cap: £267m
This successful self-storage company issues a trading update. I most recently commented on it here.
The roll-out expansion continues:
A new store has just opened in Peterborough. £7.5m cost, 46,000 square feet.
Three further stores under construction or being fitted out. These will bring an extra 162,000 square feet of capacity.
Two other huge stores are in the planning phase.
Momentum remains good:
Our total secured pipeline of 10 new stores will result in the Group operating 52 stores when fully developed, increasing the owned store trading space by 37.7%.
Trading continues to be buoyant with H2 stores' revenue expected to be up c.10.5% year on year.
Graham’s view
I think this is an excellent business: founder-led (Chairman Andrew Jacobs owns 17%), conservatively geared, with a proven process, and operating in a niche with excellent secular growth.
Valuation remains a niggle for me: the shares are trading below “adjusted” NAV, but about 27% above my own calculation of “actual” NAV. For property-related businesses I do struggle to pay a premium to book value. Perhaps I’d make an exception for this one, but I’ll stick with a neutral view for now. Around 700p I would be more interested.
Roland's Section
PROCOOK (LON:PROC)
- Share price: 26p (pre-market)
- Market cap: £29m
Preliminary results for 52 weeks to 2 April 2023
In April, I looked at Procook’s year-end trading update and said that while I liked the products as a customer, the company’s financial situation looked somewhat uncertain to me.
Today’s results provide us with a chance to see more detail on the group’s financial performance last year and gain fresh insight on current trading.
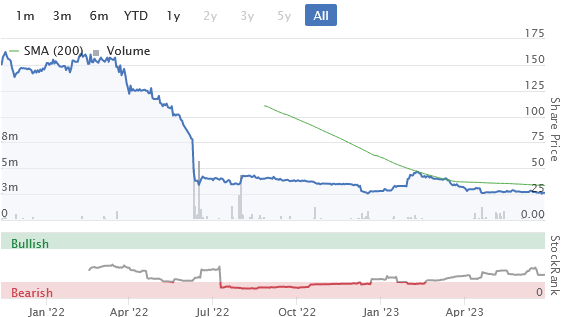
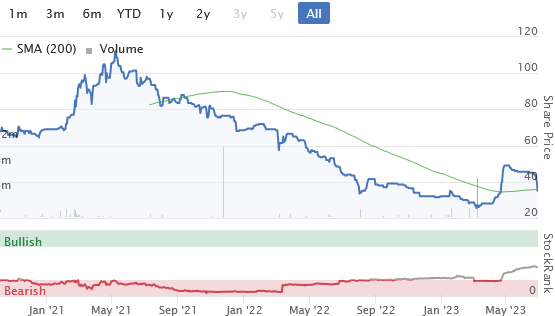
Let’s start with a quick reminder of what a disastrous IPO this has been – the shares are down by c.85% from October 2021 listing price. If Procook can turnaround, this might be an interesting situation, but the market is clearly pricing in significant risk:
Financial summary: Procook’s full-year update in April guided for revenue of £62.3m, with profits at “approximately breakeven”, on an underlying basis.
Today’s results are in line with these numbers:
Revenue down 9.9% to £62.3m
Ecommerce like-for-like revenue down 11.0%
Retail (store) LFL revenue down 10.4%
Gross margin: 61.5% (FY22: 65.1%)
Underlying pre-tax loss: £0.2m
Reported pre-tax loss: £6.5m
Net debt exc. lease liabilities: £2.8m (FY22: £1.8m)
The big problem for Procook seems to be that the expected post-pandemic decline in ecommerce sales has not been offset by a corresponding increase in store sales.
The revenue decline has been made worse by the company’s decision to exit low-margin Amazon sales channels. But even if this is stripped out, sales still fell by 5% last year. That’s a big decline against a backdrop of c.10% inflation, implying a sizeable reduction in volumes.
Today’s reported loss includes £4.4m of impairment charges. £3.3m of impairment has been applied to the group’s stores, with the remaining £1.1m applied to head office/distribution sites. I guess this may reflect lower future expectations from ecommerce as well as in-store trading.
Cash flow/balance sheet: operating cash flow of £9.4m was converted into a free cash outflow of £0.5m last year. However, this result was boosted by a £5.2m reduction in inventories. I wouldn’t expect this to be repeated, as supply chain conditions are now normalising.
Net debt rose to £2.8m during the year (FY22: £1.8m), leaving borrowing headroom of £13.2m.
This may sound relatively comfortable, but it’s worth remembering that Procook also has £29m of lease liabilities that required payments of £4.4m last year.
Trading commentary: founder and CEO Daniel O’Neill is keen to emphasise that Procook’s offer is continuing to resonate with customers.
The number of active customers over the last 12 months rose by 1.8% to 991,000, while the 12-months repeat purchase rate was relatively stable, at 23.6%. However, new customer numbers were lower, at 692k (FY22: 723k).
I don’t think this is a bad result, operationally, given the conflicting pressures on consumer spending (and the return to holiday travel) after the pandemic.
Current trading: this doesn’t look good to me. Procook says that trading during the quarter to 26 June 2023 has been challenging, with revenue down by 7.9% on a LFL basis due to “the warm weather and soft homewares market in May and June”.
The company reckons its share of the market has remained flat, versus last year.
Outlook: there’s no clear financial guidance today, but the outlook sentiment strikes a very cautious note:
The outlook remains challenging and much is uncertain. While there are indications that inflationary pressures will ease over the months ahead, UK consumers have suffered a significant adverse impact on disposable incomes and discretionary spending power.
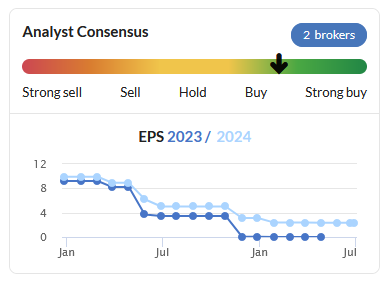
Consensus forecasts on Stockopedia suggest that revenue could rise by 10% to £68m this year, generating earnings of 2.4p per share. These forecasts seem optimistic to me. I suspect that they’ll be revised down (again) after today’s results, although I haven’t been able to find an updated broker note yet.
Going concern risk: in yesterday’s report I commented on how operational gearing had boosted profits at CML Microsystems. Procook’s declining revenue and substantial fixed cost base means the group is now suffering operating leverage in reverse.
It seems that this could lead to some uncertainty over the group’s going concern status, if trading worsens.
The company’s severe but plausible downside scenario modelled a further 5% LFL decline in revenue in addition to that seen already (YTD: -7.9% LFL). I don’t know how likely this is, but in this scenario the company believes it would breach the fixed charge covenant on its main borrowing facility.
Essentially, this means that the group’s EBITDA would not provide sufficient cover for its rent, lease and interest payments.
A breach might not stop the business operating normally, but it would require a covenant waiver from lender HSBC. In fact, today’s results reveal that HSBC has already relaxed the fixed charge covenant once, in May this year, to prevent a breach.
Roland’s view: I don’t know how Procook will perform over the remainder of this year. But I don’t see any obvious reasons why sales should suddenly improve, after such a weak start to the year.
I think there’s some risk that Procook will need to carry out a placing to strengthen its balance sheet. Existing shareholders could face significant dilution.
In addition, I think it may also be worth remembering that the founding O’Neill family control more than 65% of the stock. So there might be some risk that the business will be delisted and taken private if it needs refinancing.
On balance, my negative view remains unchanged from April. Even at the best of times, this is a low-margin business with fairly high fixed costs. This isn’t a good place to be right now and I can see some risk to equity holders.
Various Eateries (LON:VARE)
- Share price: 34p (-15% at 09.00)
- Market cap: £29m
Half-year results & trading update (profit warning)
“the Company anticipates that net EBITDA margins as a percentage of sales will be significantly lower than previously expected.”
Various Eateries operates 17 locations under the Coppa Club, Tavolino and Noci brands.
In August 2022, Paul commented that this chain of bars/eateries looked “unproven” and perhaps not very financially robust. Today’s half-year results and profit warning suggest he was probably right to be cautious.
Trading update/profit warning: the company says it has been prioritising sales over margins.
While full-year revenue is expected to be “broadly in line with market expectations”, EBITDA margins are now likely to be “significantly lower than previously expected”.
Management says that as a result of rising food, labour and variable costs, EBITDA margins for the full year to September 2023 are expected to be between 5% and 7%.
Various Eateries’ EBITDA margin was 8.6% last year, on an adjusted basis. So this represents a material worsening of profitability. While I understand the importance of trying to maintain price positioning in the market, I wonder if this approach is really sustainable.
For contrast, rival Loungers (LON:LGRS) reported an EBITDA margin of 15.8% for the half-year to October 2022 and recently confirmed trading in line with expectations.
For what it’s worth, Various Eateries says that the performance of new openings “has been encouraging”. New sites in prime locations at reduced rents continue to become available – but can the business really afford to be expanding? I’m not sure.
Half-year results: these numbers cover the 26 weeks to 2 April 2023 and provide additional context for today’s profit warning. We can see that while revenue is rising, all measures of profit have fallen sharply:
Revenue up 16% to £20.6m
Gross profit down 63% to £565m
Gross margin: 2.8% (H1 2022: 8.6%)
Adjusted EBITDA loss of £29k (H1 2022: +£1.7m)
Operating loss increased to £3.2m (H1 2022: £1.6m)
Net debt exc. lease liabilities increased to £9.8m (H1 2022: net cash of £1.9m)
My sums suggest the business suffered a cash outflow of £6.3m during the half-year reporting period. Presumably this is continuing into the second half of the year.
However, the H1 EBITDA loss seems to suggest that some improvement in profitability is expected over the summer period, in order to achieve the guided 5%-7% EBITDA margin.
Roland’s view: As with Procook, Various Eateries’ profitability looks challenging for the near future. The financial situation here is also complicated by a dominant shareholder and related-party loans.
I haven’t researched this business in any detail. But Various Eateries’ low margins suggest to me that some of its sites may be tied into expensive leases. Alternatively, perhaps the pricing power of its brands and locations are not as strong as some rival chains.
In addition to the risk of an equity placing, I would argue that there’s a risk this business could be taken private for refinancing, perhaps before being refloated or sold in more advantageous market conditions.
This isn’t something I would want to spend anymore time on. It looks high risk and speculative to me at present, so I’m going to stop there.
Vertu Motors (LON:VTU)
- Share price: 68p (-1.5% at 09.40)
- Market cap: £239m
“The Board anticipates that full year results for FY24 will be in line with current market expectations.”
Today’s update from this car dealership group seems fairly reassuring to me. Although management does comment on “uncertainty of consumer demand”, the remaining commentary is fairly positive and suggests industry supply conditions are improving.
Trading highlights: trading (adjusted operating) profit for the three months to 31 May has been “above prior year levels”, aided by the acquisition of the Helston Garages last year.
New car retail and Motability volumes up 10.8%
Like-for-like (LFL) new vehicle margins stable at 7.9% (8.0% last year)
Fleet and commercial volumes up 1.0%
Used vehicle LFL volumes down 5.9%, due to supply constraints
LFL gross profit per used unit sold stable at £1,648 (last year: £1,652)
Operating costs have risen slightly as a proportion of revenue due to energy, pay, IT, etc.
Updates from car dealership groups often provide interesting insight on market conditions across the sector.
Today’s update shares that SMMT (industry trade body) forecasts for the new vehicle registrations this year were increased by 2% to 1.83m in April, to reflect stronger fleet sales.
This is said to reflect a return to more normal supply conditions, with UK fleet and commercial vehicle registrations rising by 30.9%, especially in the rental sector.
Vertu isn’t a major supplier to the “low margin rental sectors”, so the group’s volumes lagged the wider UK market.
However, Vertu says that its new car retail and Motability volume growth of 10.8% compared favourably to a UK-wide figure of 8%. This implies Vertu has gained market share in this segment.
Outlook: the company strikes a positive tone:
“New vehicle supply continues to improve whilst constraints in used vehicle supply in the UK are likely to persist, helping to underpin used vehicle values and gross profit.”
However, higher interest rates and inflationary pressures may act as a headwind to consumer demand.
Results for the year to 28 February 2024 are expected to be in line with current expectations.
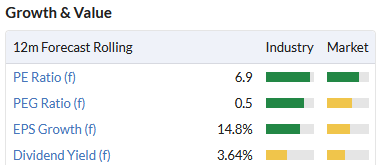
Stockopedia’s consensus forecasts suggest earnings of 9.9p per share, with a 2.5p dividend. That prices the stock on a P/E of 7, with a 3.6% yield:
Roland’s view: Vertu has plenty of freehold property and the shares continue to trade just above tangible net asset value.
However, I suspect that consumer demand could still be held back later this year by the impact of higher interest rates on both mortgages and car finance costs.
On balance, I think Vertu shares look reasonably valued at current levels, but perhaps not quite as cheap as they might seem.
However, given the strength of the balance sheet and the group’s current stable performance, I’m happy to go green on this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Revolution Beauty (LON:REVB) I actually think graham's view is fairly controversial for revb holders like me.
Boohoo are trying to take control of the company without actually paying a penny. If they want control tbey should make an offer.
As a retail investor i fail to see how i would benefit from boohoo taking control given their track record of distressed acquisitions and the state of the boohoo business.
Am i happy that revb just diluted, no. But I much prefer this to boohoo and their management who are entirely discredited taking over.
If boohoo want control of the board then they should make.an offer.
RBG and Revolution Beauty
As PI no need to engage with types of companies that are run by the self serving and self entitled dross management that is a stain on AIM Market .
RBG showed its colours before and it was obvious this was one to avoid like the plague when the FD was given huge share options at zero cost with no hurdle . Some readers on here seem happy to accept this as “the way it is” or “good to reward management “.
The only credible action for PI is to run a mile and tell these clowns to “do one” as we say in Sheffield .
With thousands of companies to consider just no need to dance with the self entitled devil .
Revolution beauty what a total disgrace of a board I remember listening to Paul Hill / Equity development bang the drum for them (paid to bang of course) when the CEO was claiming to target 1 billion in sales and I knew at that moment it was total bullshit and hype management pump and dump bill market dross .
Hope we all learn the lessons and see the signs in future but what a shower of dross stealing shareholder value and stuffing it in their pockets .
Suffice to say I am not a fan.
Such interesting commentary on Revolution Beauty (LON:REVB) !
I was under the impression that the current board had brought it back from the brink and just as they were about to potentially start reaping the rewards, BOO are trying to throw a spanner in the works for their own benefit (did they expect to take it out of administration on the cheap? were they keen not to see it re list?)
Couple of things I can't understand?
Why did BOO vote for the reappointment of Scwartz? Were they in cahoots? Did Schwartz do the double cross?!!
And then why were there so few votes cast? 120m out of 280m? The votes against re election appear to be almost entirely BOO? How does a 26% shareholding afford BOO the luxury of a board coup?
Having seen Bob Holt at Mears and Sureserve, I get the impression REVB stands a decent chance under his stewardship- the words boring, sensible, experienced come to mind. BOO would appear to have enough on their hands turning their own fortunes around?
I agree
If boohoo want control they need put an offer on the table.
I can't see what it's in any PIs interest for boohoo to take control and potentially run it into the ground to snap the assets for next to nothing
If the Revolution Beauty (LON:REVB) board had any credibility they blew it yesterday, as they moved to shovel as much of the company's cash into their pockets as they thought they could, after they had been removed as directors by the meeting. https://www.investegate.co.uk/...
PROCOOK (LON:PROC) update 28/06/23: Procook's PR team has helpfully forwarded me two updated broker notes which both show forecasts unchanged for the current year, contrary to my expectation that they might be cut.
Averaging the two forecasts provided gives an estimate of 2.8p, in line with the consensus shown in Stockopedia. That's equivalent to a forecast P/E of 11.
While I have concerns about the outlook, I like this business and I'm a fan of the products, so I'll keep watching with interest for signs that trading is stabilising.
RBG Holdings (LON:RBGP) is a holding I should have sold a long time ago.
If I had sold on 31 January the day an RNS hit the market stating that the CEO had been sacked I could have got out at 58p. I paid 145p in Sept 2021.
My holding today is worth just £1,875. Now the CFO takes a 6 month sabbatical, always a bad sig. I feel that I might as well hang on but I do so without much confidence that the Board can turn things round.
It looks like the sale of the Litigation Finance business Lionfish is becoming very protracted with no positive news. I can understand why Paul Scott does not like to invest in this type of business.
Lawyers will always put their interests first.
RBG Holdings (LON:RBGP) the time to sell would have been when they divulged the lion fish losses. This was probably a trigger for foulston going as she had appeared competent until then.
I have held on as I believe in the core business and if one believes the latest reports they are trading in line.
As an aside of idle speculation it could be the foulston is making life difficult for rosenblatt as I understand his shares are now acting as security for bank indebtedness.
I may add more but it could go lower that’s the market
I sold some time before that as was very unhappy with the massive £1m share award to the then CFO. I think that was around 18 months ago and saw it as a really bad sign. The share price has been pretty much all downhill since.
Hi Roland ,
A £240m market cap , a decent 4-5% dividend yield , another 4% return to shareholders through buybacks , at least £50m yearly PBT , growing revenues , yearly free cash flow of over £30m and with management regarded one of the best in the industry.
I think reasonably priced is a bit unfair!
Vertu Motors (LON:VTU) ?
Yes indeed
The share prices of many companies are beaten up at the moment. I have a number is my portfolio. The price drops feel uncomfortable leading to more selling and even lower prices, so self-perpetuating. With the exception of Odey, the sellers are mainly retail which tells a story. The selling is driven by fear of prices falling further rather than fundamentals. Unless you think there is going to be a full-blown economic crisis, many small companies are very cheap. This is potentially a great opportunity for well informed private investors like us who realise the health of a company and its share price fluctuate independently.
It is interesting that it can be harder to buy when share prices drop and easier when prices are climbing but important to remember these are the same companies, just available at a cheaper price. The drop in share price does not necessarily represent bad company performance.
Peter Lynch goes to the golf course when the stock market is falling. He likes falling share prices because it means he can buy companies he likes more cheaply.
Warren Buffet says 'Be greedy when others are fearful."
It is very rare to buy shares in a company at the lowest point. As long as you are not a forced seller, it does not matter if the price goes down after your buy.
Couldn't agree more Michael. If you know where to look there are some very good UK small companies trading at very attractive prices. The sale goes on.
I would add Howard Mark's wise words to those of Warren Buffet and Peter Lynch. To paraphrase the former, if after having confirmed one's thesis that the stock is cheap and trading below intrinsic value, buy it. He asserts that it is a mistake trying to pick the bottom and if after buying, the price falls further, buy more, provided one's original reasons for buying continue to stack up.
As the very erudite Mr Marks says, the stock market swings between hopeless and flawless. The time to buy is when the former prevails.
All the best
LIKE.
Please share with the community here when you spot the next Coca Cola or the next Apple that’s listed in the small cap sector in the UK.
It has happened - ARM was spun out of UK small cap Acorn.
Has happened doesn’t make you money but I don’t think you understood my point.
On Buying Shares When Their Prices Are Falling
I have sympathy with much of what you are saying, Michael, but I would like to sound a note of caution in two regards. It can be very dangerous, but also very tempting, to carry on accumulating grossly over-sized positions in companies one thinks look good, but the market thinks otherwise, in an effort to minimise the percentage by which the position is in the red. It's easy to get caught up in doing so, only to realise later that most of the money poured into what, by stages, became a dangerously over-sized proportion of one's entire wealth has evaporated, temporarily or permanently, who knows - perhaps the market does know better?
The second, related, point is that when such calamitous and prolonged share-price collapses occur, such companies are vulnerable to opportunistic low-bid buy-outs while the share price is near its nadir, except where large share holders, such as foundrrs or founding families can protect against it by blocking. Small-caps are all too vulnerable to this - time and again private equity seizes the recovery profits away from existing share holders. Continuing to hold heavily-underwater positions, even in sound companies, and waiting for share-price recovery is still a bit of a lottery if its share-holder base lacks large long-term or controlling share holders. I remember David Paul of VectorVest (he started out as a short-term share trader) remarking during a presentation to Mello last year that "betting against the market is the worst thing an investor can do". Please folks, stupidly I've learned the hard way, so if you're going to continue buying after a share price falls, averaging down, do at least be very disciplined about sticking to pre-decided maximum position sizes; and I suggest you wait for the establishment of a convincing new uptrend before increasing your exposuee to something of which the market is taking a dim view.
I agree 100% with "I suggest you wait for the establishment of a convincing new uptrend before increasing your exposure to something of which the market is taking a dim view." Never catch a falling knife! I believe that it does matter when the price falls after a purchase. The loss is real. If one continues to hold the falling share then the loss has not been crystalised, However, the loss is still a real loss, and worse still, it is likely to be an increasing and real loss!
Hi Ed Miller
I wrote my post here as the readers are mainly experienced investors.
Everyone should invest according to what they feel comfortable with.
I agree, when averaging down, one needs to feel very sure.
Position sizing is a personal decision, of course it is possible to be caught out.
When I average down, it is not because my position is in the red, it is because I feel confident in the company's prospects.
The positions I have been adding to are not in the red. They are mainly long term holdings which I know well.
As with all investors, some investments go well and some don't, If the business stops performing as I expect, I sell.
If the share price drops but the company continues to perform well, I may add to my position.
Very wise ed_miller, I am that injured soldier too.
JASVFS
Sorry to hear that.
Hope your injuries are healing.
I do not want my comments to put anyone in jeopardy.
There is a long backstory at REVB but purely on the basis of today's news, I would give these shares the thumbs down. I would never want to invest in a company that behaved like this.
With a choice between the current directors and Boohoo, Revolution Beauty (LON:REVB) shareholders really are between a rock and a hard place!
Anyone up to date on the soap opera at RBG Holdings (LON:RBGP) ?
From what I can see - Former CEO makes (allegedly) racist comment in front of a black employee, he sues Foulston?Rosenblatt/RBG, Foulston is sacked, RBG board changes, Foulston sues for unfair dismissal, RBG counterclaim, CFO abruptly quits, says she'll be back in January.
Labour have returned a £16,000 donation from Ian Rosenblatt because of the firms involvement representing a Russian state owned bank... mostly it seems around the UK-based restructuring firm Teneo. He'd previously donanted £200k when Milliband was in charge. Now says Labour threw him under the bus :)
Anyone know the ins and outs here, it looks a pr car crash. Foulston selling her shares causing the sell off or investors just running for the hills?
RBG Holdings (LON:RBGP) I stopped following it as decided it was uninvestable some time ago - I had concerns over governance and culture for a while and sold out around 18 months ago - things seem to have got a lot worse since I last looked at it. Why get involved when there are so many good quality stocks out there on very cheap valuations?
RBG Holdings (LON:RBGP) is indeed a PR car crash but as all of the above is in the public domain, I believe it is priced in. I think the core business is operating very profitably and at a forward PER of 3.5 it looks rather attractive - surely significantly more upside than downside. Its share price is 20% of what it was 2 years ago. I think it’s a case of riding it out - letting Foulston sell her large shareholding and for sentiment to improve.
https://www.lawgazette.co.uk/n... Foulson claiming unfair dismissal and RMGP claiming breach of contract...the only winners will be the lawyers
Its a mess for sure. I sold out today because there just seems to be no end to the selling and scandals.
Thought it might be worth sharing something. Are any investors here sitting on high cash balances in their ISAs or trading accounts, and only earning 2-3% interest? I was. I've just switched a chunk into very short dated UK government gilts (e.g. TN24 with 7m to go) and others. Low risk and have redemption yields of c5% after trading costs of 0.1% or so. Seems a no-brainer to me as you have easy access to either await redemption or sell when you need the money to invest in small caps. I had missed this, but someone pointed this out to me yesterday. Of course, if you are a dividend investor like me, it makes you think hard about deploying cash when you get 5% for no risk......... particularly when the yield curve has now been heavily inverted for 1 year on 5 July...a very solid indicator of an impending recession.
Very sound idea have done several .No capital gains charged on UK gilts
That's what I'm doing too. Better returns than a savings account, and you can sell whenever you want, unlike a savings account where you'll be lo locked in for at least a year if you want a good rate.
But don't you have to wait until the redemption at expiry to get the return?
Can get 3.9% instant access now. No costs either.
As a bond moves closer to redemption its price should move closer to par - hypothetically take a bond trading at 95p and due to mature in 2 years - after one year it might move to say 97p and a few months before redemption it might trade at 99.5p. So if you sell early you should still pocket some gains.
Thanks for sharing. Please excuse my ignorance but how do you buy/sell UK government gilts?
Hi Gudge58 it depends on which platform you are using, some you can trade directly others you have to find products. Tommy
Hi Gudge58,
A J Bell say: How to invest in bonds
To buy and sell bonds directly, call our dealing services team on 0345 54 32 600.
The dealing charge for bonds is £9.95.
You can’t currently buy and sell bonds on our website or app.
(They also mention the option of ETFs)
Interesting statement by Golden Metal Resources (LON:GMET) today. future of take agreement, ok won't interest many on here by that's a big partner to deal with.
Personally always happy to see metals miners, and drillers noted.
Aferian (LON:AFRN) interims out today, last covered by Paul on May 17th.
Outlook "in-line", but whatever they are in-line with is miles away from the expectations showing in Stocko. Not a chance of full yr revenues ending up anywhere near $90m. H1 23 was $23.1m vs $44.5m H1 22. Progressive had a "research" note out after 31st May update that simply parroted the RNS & contained no forecasts at all, so I suspect very stale numbers feeding through.
Good news is that debt remains at previously anticipated $13m. No further mention of shareholder loan, or plans to replace undrawn element by 31st July. Bad news is that sales on the Amino side were not just down, but off a cliff (-71%). Inventory of $8.6m expected to decline, paying down the debt, but you've got to wonder if the precipitous drop in device sales is down to the devices rather than the "wider macro" blamed in the 31st May update.
"The Amino division, which connects Pay TV to streaming services, will now focus on higher quality, higher margin streaming devices"
Does that mean they were previously focusing on lower quality, lower margin devices that are now obsolete?
The 24i dvision they acquired appears to have a future, but the growth is hardly knocking the lights out.
re Aferian (LON:AFRN) It is in line with the previous release of the bad news.
"The Amino division, which connects Pay TV to streaming services, will now focus on higher quality, higher margin streaming devices"
Does that mean they were previously focusing on lower quality, lower margin devices that are now obsolete?
You have to sell what your customers ask for. Their market is seeing a shift from Pay TV to streaming, so obsolescence will be a factor in the revenue collapse. In fairness to management, they have been warning of the trend for some time, it is the suddenness of the drop in sales that seems to have caught them, and their customers, by surprise.
I see Aferian (LON:AFRN) as essentially a software company. It is the gross profit that is the meaningful figure for revenue from devices.
I should perhaps make my sarcasm a little more obvious. The big question is whether the elevated inventory can be sold off to reduce the debt, or whether that is wishful thinking and we will instead see write-downs of devices they can't ship at the price they expected.
Management have clearly been caught out, to the degree that you have to wonder about competence....doubling up your inventories to avoid supply chain disruption just as demand collapses by 71% is a particulary unfortunate state of affairs when viewed alongside a major acquisition that risked the balance sheet.
Or they may just be very unlucky - I seem to recall Pace (or Pace Micro) being a UK company that also struggled on the inventory side with set-top boxes in the Pay TV market. Seems to be a miserable sector to be a supplier in, and I wonder how that changes in the transition across to software/streaming.
Gosh! The Revolution Beauty (LON:REVB) AGM reads like an episode of HBO Succession series. 50% rise on lifting of suspension this morning, so market must agree with the last remaining board member, that he did the right thing with reinstating the other board members rather than going with the people Boohoo (LON:BOO) wanted in those roles
It looks like the board done what they could do, until the next general meeting where a vote will be made and in all probability, they'll be gone unless they can convince other share holders that they should remain, which I think is unlikely given that Boohoo with the other two ex directors will have the majority. To me, the market is looking forward to the take over and new management. Interesting.
It also looks as though the existing (and "restored") Revolution Beauty (LON:REVB) board are determined to put as much cash into their pockets as possible while they still can!
Thanks Peter G - I've added a comment on REVB to the report. Incredible stuff! G
Re: REVB vs BOO Wars
Graham, I haven't all the back story on REVB's woes, but bear in mind that the directors of REVB think that BOO is trying to gain control of it despite only having a minority holding of 26.6%. They further state that the current crop of REVB directors are not responsible for its historical woes and they have all the skills and experience to improve REVB's fortunes. They wanted to adjourn the AGM and delay long enough to galvanise the rest of the share holders and win them round. MarkB above states that two ex-directors side with BOO and together they do actually have a majority holding, if so, it seems current directors of REVB are likely to lose their boardroom battle and be comprehensively ousted when a general meeting is convened in July or August.
I agree with your comments on the REVB directors stuffing their pockets full of nil-cost options, diluting existing share holders.
(Disclosure: I have no position in REVB; I hold BOO, unfortunately.)
Boohoo (LON:BOO) very tentatively looking to make a base here after the large volume day on the 19th. Hasn't fallen with the general market last 7 days. Largest days volume since 2017 I think. Indecisive looking right now.
Shorts closing
RSI divergence. Its not a slam dunk but is starting to look interesting now at least
Morning all,
I was wondering - does Stockopedia have the potential to notify you when someone directly comments on one of your posts? I have found a couple of times that people have left really good insight on a comment or question I have made, but because it has been made towards the end of the day I nearly miss it. I am sure there at times where I will have missed comments if I don't revisit the page.
If this can't be done, another possibility would be that you can tag a response @ a person in a similar way to what we do with stocks, when that happens they get notified.
Not sure if anyone else would find this a useful addition.
Ben
Hi Ben, add it to the green button at the bottom right feedback!
I concur as I often read late in the evening, so comment after most peoples days have completed, currently waiting for a meeting to start as folks running late, so quick check.
Good luck
Tommy
Agreed. This would save time not having to look back to check for a response. ADVFN manages to do it - although that does result in being also notified that all the numpties (and we don't get those here) have also posted comments.
I'm now wondering how many readers are calling me a numpty. No need to comment on that thank you.
Roger, you are a Roger!
Morning all,
Warpaint London (LON:W7L) positive trading update, going very well!
Looks like Stocko forecasts are too low to me.
There’s something to be said for forecasts being suitably set to beat though
Ahead of expectations TU’s in shares I own are always welcome ;)
Yes but they will have to keep on doing it, otherwise the share price will crash. I do hold some Warpaint London (LON:W7L) one of the better performing UK stocks, this year.
It's now in the report, John! G
My morning smallcap tweet: One Thousand and One Fights
Revolution Beauty (LON:REVB) Lok'n Store (LON:LOK) Nanoco (LON:NANO) Woodbois (LON:WBI) Molecular Energies (LON:MEN) Newriver Reit (LON:NRR) hVIVO (LON:HVO) Location Sciences (LON:LSAI) PROCOOK (LON:PROC), Aferian (LON:AFRN), Vertu Motors (LON:VTU)
◄Revolution Beauty (REVB)► unsuspended. Boohoo attack's board conduct at and after AGM at which 3 dirs removed. Remaining dir then re-appointed them. [SP=8.25 Cap=26m]
◄Lok'nStore (LOK)► guides store revenue up c.10.5% in H2. In line? [SP=797.9 Cap=240m]
◄Nanoco (NANO)► GM requisitioned to remove all directors. "The Requisition follows the receipt of two letters from Mr Hamoodi." [SP=19.1 Cap=62m]. I hold.
◄Woodbois (WBI)► bail-out £6m placing at 0.5p, a 16% discount, to replace $6m working capital facility was withdrawn by Sydbank. Also d4f and warrants. CEO going. [SP=0.6 Cap=15m]
◄Molecular Energies (MEN)► proposes spin out and IPO its Green House Capital alternative energies division. [SP=127.36 Cap=13m]
◄NewRiver REIT (NRR)► completion of the disposal of Retail Parks £62.6m. NRR owns half. [SP=89.3 Cap=277m]
◄hVIVO (HVO)► developing a human metapneumovirus (hMPV) challenge model for a North American biopharmaceutical co. [SP=15 Cap=102m]
◄Location Sciences (LSAI)► proposed RTO. Agreement to lend £2.6m (max) to Sorted Holdings. Also non-binding heads of terms to buy Sorted for £1 (sic); will assume approximately £4.0m of Sorted's outstanding debt. Shares suspended. [SP=0.13 Cap=4m]
◄ProCook (PROC)► FY-Apr. Rev down 10%. Recent trading: LFL rev down 8%. "The outlook remains challenging and much is uncertain. " [SP=25.1 Cap=27m]
In line: AFRN, VTU