Small Cap Value Report (Wed 28 Nov 2018) - OTB, VCP, TENG

Good morning, it's Paul here.
It was a huge pleasure to meet & chat to the many Stockopedia subscribers who attended Mello London. The whole event was a terrific success. Mello has become a community of friends, and I really enjoy the gathering of the clan at each event. Congratulations to David Stredder, Georgina, and the rest of the team, for organising another excellent event.
I lost count of the number of people who thanked me & Graham in person for our work in producing these reports. It's very rewarding to receive such positive feedback, so thank you to everyone who took the trouble to speak to me. So much positive energy, I feel like a fully charged battery now!
Right, on to today's news.
OnTheBeach (LON:OTB)
Share price: 416p (up 3.5% today, at 08:06)
No. shares: 131.0m
Market cap: £545m
This is an online travel agent. It's reporting today on the year ended 30 Sept 2018.
So far, so good - the market has reacted positively this morning in early trades, share price up about 4%.
Revenues - up 24.5% to £104.1m. As disclosed in a footnote, the bulk of this increase is due to a recent acquisition (called "Classic"). The more meaningful number is that core business revenues were up 9% to £89.3m.
Marketing costs - many online businesses have marketing costs as their largest variable cost. This is a very attractive feature, since marketing spend can be dialed up or down, to suit market conditions. In a recession, it would be a major advantage over bricks & mortar competitors, which are stuck with largely fixed costs. Marketing spend here is huge, at 41.8% of revenues (down from 45.2% last year).
International - the growth in Scandinavia has stalled. Doesn't seem to be working yet, with a £2.2m EBITDA loss. Warm summer & discounting by competitors are given as reasons. To reiterate the point above about marketing spend, this was slashed to a background level.
Adjusted profit before tax - the key number for me, is £33.6m, up an impressive 17.9%. Let me check that the adjustments are sensible. Footnote 3 explains the adjustments as follows;
(3) Group adjusted profit before tax is profit before tax,
amortisation of acquired intangibles of £4.6m (FY17: £4.3m),
share based payments £1.4m (FY17: £0.5m),
exceptional costs of £0.6m (FY17: £2.7m) and
one-off property and litigation costs of £0.9m (FY17: nil)
The only big one there is reversing the amortisation of goodwill & similar, which is fine by me. I always reverse out that item anyway, as it shouldn't have any bearing on how we value any company.
The other adjustments are small in the context of £33.6m profit, so I can live with these adjustments. Share based payments is the one I grumble about usually. However, a friend pointed out that if we use fully diluted, adjusted EPS, then the potential dilution from options is already factored in.
Adjusted EPS - up an impressive 20.5% to 21.2p - giving a PER of 19.6
Dividends - for the full year total 3.3p - this is increased by 18% Y-on-Y, but seems a very low payout, yielding only 0.8%. I'm wondering why the company isn't more generous, and this steers me towards looking more closely at how cash generative (or not) it is.
Balance sheet - the key metrics for me, as usual, are these;
NAV: £117.9m, less intangibles of £88.1m, gives;
NTAV: £29.8m. That looks adequate, but not especially strong. Being an online business, it's a capex-light business model, so doesn't need a lot of net assets.
Working capital: current assets of £158.1m includes £85.7m of cash. Current liabilities total £126.4m, note this is all trade creditors - there's no bank debt. Travel companies usually receive cash up-front from customers, before having to pay suppliers, and OTB's balance sheet looks consistent with that.
I imagine that the 30 Sep 2018 year end is probably when the cash pile would be a seasonal high - companies usually choose the year end date that shows the most flattering cash position. So it's safe to work on the assumption that the cash pile could be much lower at other points in the year. This is why I see enterprise value as being quite a flawed concept. It should be based on average cash throughout the year (which of course we're not told), rather than the year end snapshot cash balance.
Cashflow statement - looks fine to me, the company seems genuinely cash generative, and has considerable scope to increase future dividends.
Note that £3.8m of development costs were capitalised. There's nothing wrong about that, but I always flag it because it renders EBITDA meaningless.
Outlook - this sounds encouraging. In the context of profit warnings from heavily indebted Thomas Cook (LON:TCG) , it's clear that OTB must be taking market share from more traditional operators.
The first quarter of our financial year (calendar Q4) is historically the quietest trading period for the Group. We are pleased to report a strong early trading performance, supported by a slightly earlier release of summer capacity by major low cost carriers, lower YOY seat prices for winter departures and a continued efficiency in marketing spend.
This current performance is in line with our expectations and the Board believes the business is well positioned for the key trading period that commences in late December and continues into Q1 2019.
Whilst the consumer environment continues to be challenging, we remain confident in the resilience and flexibility of our business model. The Board will also continue to evaluate acquisition opportunities that will both increase scale and deliver value for shareholders.
That's resolved my query about why the dividend yield is so low - the company looks to be hoarding cash for acquisitions.
My opinion - is positive. These seem to be good results & outlook, in a tough market.
The valuation strikes me as reasonable, and this is going onto my watchlist as a potential future purchase.
My only reservation is that a couple of friends bought holidays through OTB, but were not impressed. That could mean the company needs to constantly spend heavily on marketing, to attract new customers, but may not be getting repeat business as much, possibly? Therefore a key statistic I would like find out, is what level of repeat business is being achieved from active customers?
The company says repeat business is up 14%, but not what the actual level is. It also says this;
We have increased our investment to multi-skill our customer-facing staff to ensure that we can provide an even higher level of customer support for all of our valued customers and support the sale of package holidays post the implementation of the new PTRs on 1 July 2018. We are delighted to have maintained our excellent Net Promoter Scores and our repeat purchase rates have increased significantly through FY18.
I'd still like more information on this vitally important KPI of repeat customer orders.
EDIT - Many thanks to "Reacher", who added a comment below, giving a link to the company's results presentation slides (which I was not aware had been published, are here). This provides a lot of very useful additional detail.
Incidentally, I've just emailed Rob at Research Tree, to ask if they could include links to company presentations as part of their service, which would make them visible to more investors.
In particular, a graph shows that repeat business for OTB is building nicely, and is at a decent level;
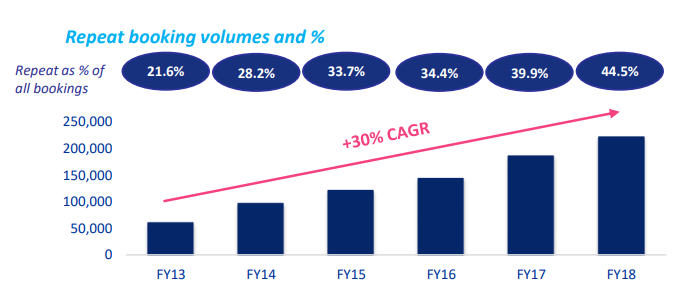
That answers my question on repeat bookings. I don't know what the industry average is, for repeat bookings, but 44.5% seems a decent level. The trend is also positive.
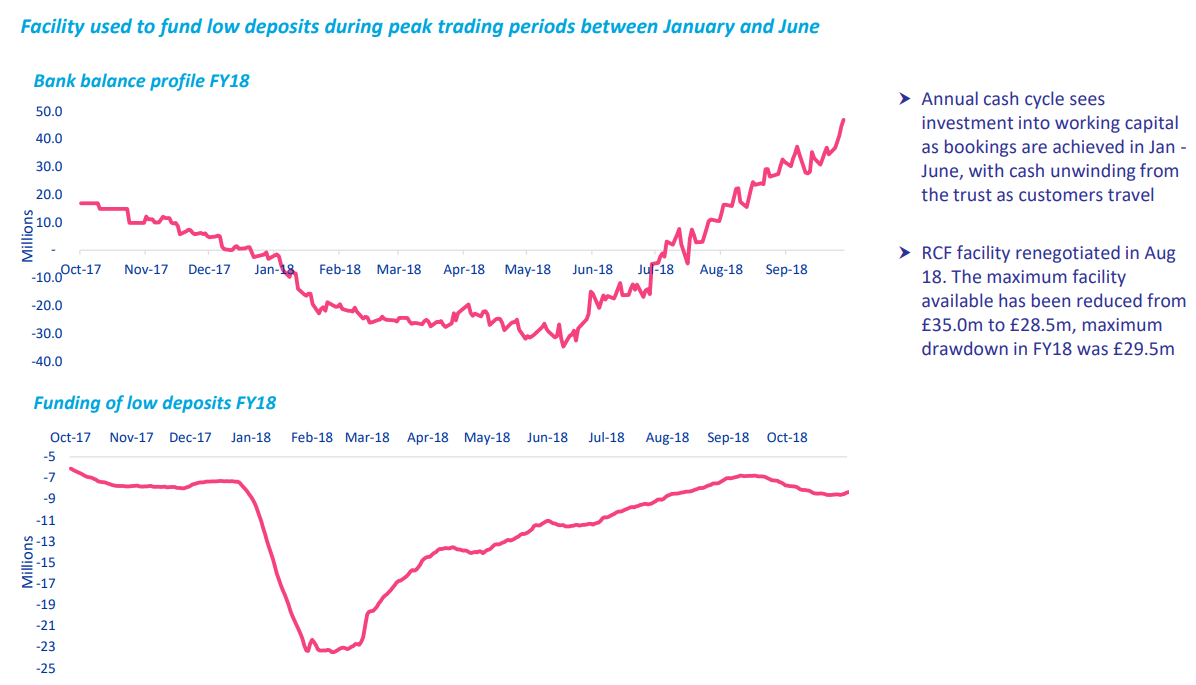
Slide 9 of the presentation discloses that;
All customer monies are paid into a trust account which isThis confirms my hunch that the year end cash figure is favourable (at a seasonal high). At other times of the year, there could be net debt (otherwise why have a RCF).
effectively a debtor to the business
Seasonal cash flow requirements are covered by a revolving
credit facility which is drawn down as required. This is not
utilised at year end
Year end cash of £85.7m is split down into its constituent parts;
Company cash: £47.3m
Trust a/c (customer cash): £38.4m
Cash profile - hoorah, another of my queries has been resolved. Slide 26 shows the average cash/debt position throughout the year, which confirms my hunch about Sept being a seasonal peak for cash. Well done to the company for being so transparent with this helpful info.;
End of edit
As an aside, one of the reasons I like Sosandar (LON:SOS) so much, is that it has cost-effective marketing to attract new customers, who then become very sticky customers - repeat orders were 43% of total orders in SOS's recent interims - which is astonishing, given how fast they are growing. It's creating a snowballing effect in revenue growth. Combine that snowballing effect with high gross margins, and the operational gearing at SOS could be astounding, in time. That's why the valuation is high.
I'm not sure whether OTB is achieving enough customer loyalty & repeat business? Although looking at reviews on feefo, they seem generally good. The danger with any holiday booking service, is that customers will leave bad reviews if something goes wrong on their holiday which is not necessarily the fault of the booking service.
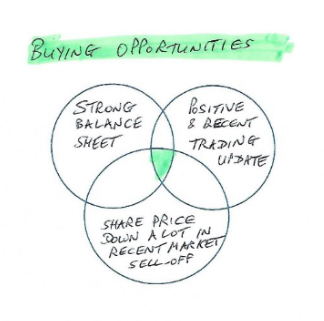
The more I look at OTB, the more I like it. It seems a good GARP share, and falls into the sweet spot of what I'm looking for at the moment:
Victoria (LON:VCP)
Share price: 480p
No. shares: 125.4m
Market cap: £601.9m
Graham wrote a section yesterday here, on interim results from this floor coverings buy & build group. I met the Executive Chairman a few weeks ago, when the aborted bond issue caused a lot of confusion in the market.
As a follow-up to that report, I note today that there has been meaningful-sized Director buying, as follows;
Alexander Anton (NED): bought £243k
Andrew Harrison (NED): bought £50k
Geoff Wilding (Exec.Chmn): bought £5m (at 491p)
I tend to sit up and take notice, when Directors buy a serious size share purchase in the open market. A purchase of £5m from the Chairman does reassure me that things could be getting back on track.
Although this also needs to be seen in the context of the Chairman having banked £41.35m just 3 months ago, selling at a much higher price (827p).
Ten Lifestyle (LON:TENG)
Share price: 36p (down 42% today, at 13:04)
No. shares: 80.7m
Market cap: £29.1m
Preliminary results & trading update (profit warning)
Ten Lifestyle Group plc (AIM: TENG), a leading technology-enabled lifestyle and travel platform for the world's wealthy and mass affluent, announces its Preliminary Results for the year ended 31 August 2018 (the "Year") and provides a Trading Update for FY 2019.
It seems to be some kind of online concierge service, with some impressive sounding clients -e.g. HSBC & other banks. This share listed on AIM in Nov 2017.
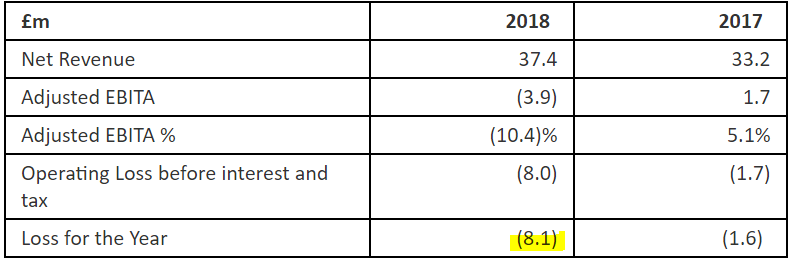
The problem is, it's not growing revenue very quickly, and is generating heavy losses;
The last trading update here on 11 Sep 2018 sounded quite upbeat.
The tone is less optimistic today;
Net Revenue for the financial year ending 31 August 2019 is expected to show continued growth, materially above the 13% growth in Net Revenue that the Group achieved in the year ending 31 August 2018, but materially below previous expectations.
Cash position - still healthy, with £20.7m net cash at 31 Aug 2018.
Looking at the cashflow statement, it burned through £8.5m cash in the year. It raised a net (after repayment of existing shareholder loans, etc) £21.3m in the IPO.
Therefore, despite under-performance, the business looks fully funded for another 2 years. At least that gives management time to attempt to turn around performance.
My opinion - it's not a startup, but has been around for 20 years, so there must be some substance to the business.
Looking at its website, membership "starts from £130 per month", and gives unlimited use of a concierge service to book restaurants, events tickets, and travel. It claims to offer special perks for members.
There are some interesting reviews from employees here at glassdoor - a good website to see what employees past and present, think (anonymously) about the company. Obviously, as with all review sites, these should be treated with a healthy dose of scepticism. It sounds as if there are cultural & management problems at this company.
Overall, this share doesn't interest me at all. Consistently loss-making businesses, that are hoping to increase sales considerably, in order to reach breakeven, are generally best avoided. The only exceptions I'll make, is where growth is stellar, and operational gearing is high.
The growth at TENG has slowed down, so for me that eliminates any reason to buy the share. Therefore, it gets a firm thumbs down for me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Re reader requests above for Ramsdens Holdings (LON:RFX) - I've never looked at this company before, but Graham has covered it loads of times. Graham is writing Thu & Fri reports this week, so perhaps you could ask him to take a look at it?
Yours with sloping shoulders, ;-)
Paul.
Just (4.30) had a “nudge” from my account at IG saying the oft discussed stock IQE (LON:IQE) is up 15% on the day. Can’t see any obvious news, and Stocko is showing rise of about 9% at the moment, but either way seems to be a reasonable move. Anything heard on the grapevine?
Gus.
Interesting Gus,
I notice that the open short positions on them have reduced too!
Less downside opportunity at these levels for the shorts, after the recent TU, so it is not surprising some have been closing out. I don't think the bounce tells us much - IQE is historically very volatile.
Thanks Paul,
Great analysis as ever, easy to understand and gets to the heart of the main metrics that helps newbies like me learn how to value a share/company. Thanks also for the hand drawn diagram!!
I don't know if you've any interest in Safecharge but if you do perhaps a quick look at their trading update?
Cheers,
Nick
Re Smartspace Software (LON:SMRT)
I attended their presentation and came away underwhelmed. I used to work in this space a few years ago and know how customers buy technologies like this.
The supply chain is complex, with manufacturers of hardware and software at one end, distributors and resellers in the middle and system integrators/consultants and architects at the other end selling/advising the customer. Companies fitting out offices tend to use large national or local suppliers to help them muddle through the complex array of technologies available which is why distribution is key for software and hardware vendors. I asked Frank about this and he was adamant direct selling was best. I completely disagree. I don't think he necessarily should go through resellers but he certainly should work with the systems integrator/consultant community all of whom have enormous influence on what the customer specifies.
Secondly, these technologies have been around for years (although apps on smart phones are clearly new) and they all suffer one major problem: they fall into the category of groupware. Post purchase issues are common place which is why the customer experience of Groupware needs careful management and lots of support in order to get technologies adopted and used properly. Whilst their UBM case-study is great, I wonder why UBM (now part of Infoma) haven't rolled this out across the world? I suspect FM professionals are sceptical because they know the problems of getting adoption - after all this is not a new way of managing people and space.
And thirdly, they are not the only ones offering such technologies and so have no real moat. Yes they have a deal with Phillips and Evoko to integrate SMART software with their hardware but it's a big world out there with many, many competing hardware and software players.
Hope that helps
Francis
Smartspace Software (LON:SMRT)
Thanks to those that commented. That was useful. I will wait and view the presentation from Mello on video as well I think then. Seems I need to wait for some more evidence of successful strategy execution on this then. The Swiped on acquisition could be interesting if it continues current levels of growth. I think wimbledonsprinter is right though that the £4.5m cash cost needs to come off, so cash is circa £10m or half market cap.
The last time I looked at significant board purchases, it was for £UPG and in due course it headed for a profit warning.
Noting from Paul's comment that there have been significant purchases by Victoria (LON:VCP) directors looks interesting. But for me the way they announced previous sales by the Exec Chairman ( and main man) in such a low key fashion, seems to me to smack of a selective approach to announcements.
As Paul points out the amount purchased represents relative chump change for the Exec Chairman on his share sales, not taking into account the fact that he also pledged his shares for a massive loan.
I guess they could be just taking advantage of a significant share price fall, but as Graham pointed out the share price is quite well valued at the current level.
Its odd isn't it. On the one hand shareholders commentate on the over-remuneration of execs, and their preference for alignment with shareholder interests, but on the other when the Exec chairman takes nominal remuneration, as he does here, but who then habitually sells or pledges his shares for massive amounts, it still makes one feel queasy.
I guess its the worry that being wholly share focused creates a traders mindset, where bad news or negative connotations are fudged (remember the highly technical announcement that was really a profit warning).
Maybe I am over analysing, but this arguably selective approach to announcements worries me.
Hi Trident,
Your comment above on Victoria (LON:VCP) reminded me of a question I asked the Chairman at a meeting recently. I asked him about the shares he pledged for an enormous personal loan, and was there a risk he would become a forced seller, on a margin call.
He replied that he's not drawn down anything on that facility, it was just "for a rainy day"!
Regards, Paul.
I wasn't able to attend Mello, but definitely wouild like to join in the thanks to Paul and Graham for their reports which are always highly informative.
Hi Paul,
Maybe this is too obvious, but in case anyone is confused.
In the On The Beach (LON:OTB) section, the reference to Telit Communications (LON:TCM) should be to Thomas Cook (LON:TCG).
Hi nigelo,
Yes you're correct, apologies for my ticker error.
I spotted it myself first thing this morning, and have corrected it.
Best wishes, Paul.
P.S. Memo to self - must check tickers and not rely on my memory!
Hi Paul. Is there any chance, time permitting, you could cast your eyes over the results from QUIZ (LON:QUIZ) yesterday? They looked reasonable to me and the share seems way oversold. Thanks.
There was a discussion about Restaurant (LON:RTN) in Paul's SCVR here.
Today the EGM has approved the purchase of Wagamama and the rights issue by roughly 60% to 40%.
Peel H said earlier this week that "The possibility that shareholders will vote down the deal is supporting the share price" and were they right - down 14% at the moment to a new 8 year low (goes xr tomorrow). The threat of institutions to vote against has caused, in the words of today's announcement, "We have engaged extensively with investors", which means management time spent on that rather than turning round the existing business.
I find this very sad having bought at 51p in 2000 and (being a buy and hold type) watched Alan Jackson (to May 16) and Andrew Page (to August 2014) build the group with the share price responding to over 700p. Mercifully I got out in a number of tranches with the last earlier this year.
I see ST of IC has just written a very positive review of Ramsdens Holdings (LON:RFX)
Paul, Victoria I think the fact he was able to sell at £8.27 and buy back in at this level actually gives me some confidence in the Chair.
Smartspace Software (LON:SMRT)
Anyone else looking at this? Announced a minimum 5Y contract with leading international bank this morning, that feels material in terms of revenue (though unhelpfully no numbers were given!!).
I am drawn to the fact that they have £15m of cash (inc £2m deferred), which is 75% of their market cap. Strip this out and the business is worth £5m....hmm feels to me like this is potentially very undervalued.
Anyone know the business well - thoughts?
David
Smartspace Software (LON:SMRT) I can’t claim to know the business well - but I did own the shares earlier this year - when it was still Redstone. It is on my “watch” list. The current cash position is more like £10m I think (£13m reported at end-July minus £4m for purchase of Swiped On plus maybe £2m from repaid WC from Redstone sale), DYOR. I think it optically looks cheap and if management can deliver then it could be a great buy. The reason I am not buying and am feeling cooler rather than warmer include:
1). I am not convinced by the Swiped On purchase. Managing a business in NZ cannot be easy, if problems arise.
2). The strategy is to build a SaaS business. From the July results, there seemed a low level of SaaS business. The new contract announced today (while encouraging) seemed to be on a licence sale basis not a SaaS basis.
3). The July results also did not indicate any momentum in the business (admittedly during a 6 month time period when management focus was elsewhere - selling Redstone).
4). Historically the group has had numerous issues and profit and EBITDA have rarely been transformed into positive cash flow.
5). Frank Beechinor has come out of semi retirement (from executive roles) to be CEO. He had been Chair of Smartspace/ Redstone for around 3 years before that. He is also chair of dotDigital (LON:DOTD) and maybe can take credit from its success. But he needs to show that he still has what it takes to be a CEO.
6). Company has just appointed a new CFO and NOMAD (Singer N+1 from Canter). I don’t see a cause for concern - but still it poses a question mark.
Company presented at Mello on Tuesday - and I think it was videoed by PI World - If you were not there, maybe in due course it will be on the PI website.
I was intending to speak to Smartspace Software, but unfortunately there was a more interesting presentation clashing with theirs.
They seem to be making a strategic move towards space management, particularly those smart meeting room booking facilities. My former employer adopted such a system and one advantage is that it cancels meeting bookings if no one turns up, so it's very good for improving meeting room availability without the capex to extend the building.
However, that system was made by a competitor.
I did some research on google and gave up after quickly finding at least 10 companies offering such a system
My number 1 question would have been about the competition in the field & how do they expect to deal with this.
Smartspace Software (LON:SMRT) presentation at Mello will be available in due course
Paul
With regards to repeat bookings for On The Beach (LON:OTB) there is a separate results presentation located on their website which shows the stat for repeat bookings as a percentage of total bookings (p 16/26). In FY18 this was 44.5%. This has been increasing over time.
https://www.onthebeachgroupplc.com/~/media/Files/O/On-The-Beach/investor-docs/results-and-presentations/preliminary-results-presentation-2018.pdf
Re On The Beach (LON:OTB) and Paul's review, anecdotal information I know,.... but my daughter's family was part of a group trip to Spain this year. There were some issues, and On The Beach (LON:OTB) staff didnt want to know. Its all very well being a low cost supplier of so-called value holidays, but nothing is good value / cheap if it doesnt work. None of that big group - about 25 people - will be using this company again and will be warning their friends NEVER to use them, rather than singing their praises and building up that repeat purchase pattern and consumer recommendation that all successful businesses seek.
Hi Reacher,
Thank you very much for flagging up the On The Beach (LON:OTB) results presentation slides, that was incredibly helpful of you! :-)
I've looked through the slides, and they answer my main queries on seasonality of bank balances, and extent of customer repeat orders. So I've edited the main article to include this new info.
Thanks again, much appreciated.
Best wishes, Paul.
I hold RFX as a kind of hedge on the price of gold. Undeniably cheap at the moment, although the obvious question is whether they might get cheaper.
I do wonder if the modest growth might start them being a bit more ambitious. They and H&T seem to have shied away from competition with each other, with Ramsdens very much in the North. There surely must be quite a few locations which might support a store, particularly if the economy gets a bit worse.
https://ritholtz.com/2018/11/the-giant-has-been-awoken/?utm_source=dlvr.it&utm_medium=twitter
Some staggering projections for Amazon as a future advertising giant from Barry Ritholz. It will probably sharpen the cry for Trust busting laws from the likes of Pres. Trump, and others.
Ramsdens Holdings (LON:RFX) CEO commentary re the interims https://www.youtube.com/watch?v=KER_pazlX84 and associated presentation can be found here
Ramsdens Holdings (LON:RFX)
This share does seem to be coming into bargain basement territory here, i am trying to stay away from value shares where future earnings may be on a long term downward spiral however this one sort of looks on the up.
My worry here would be with regard to the long term risk that currency exchange in shops may be a terminally declining market with the advent of Revolut type multiple currency cards and other online transfer methods.
£7 mill out of £32 mill seems modest but it has to be the easiest type of profit for them.
Hey ho they do have online expansion and it looks like the tangible net asset value of about 90p a share seems to offer a nice buffer to the worst case scenario that without the core £7 mill easy cash profit they could be struggling slightly.
Finally they are forecasting increase in earnings for current year so it does seem to pretty much tick all of the boxes from value type punt perspective, although i guess a pe of 9 could just as easily become a pe of 8 or 7 with the shareprice still being above the book value and the way other shares seem to be drifting on a slow downward spiral.
A request: did anyone go to the TClarke presentation at Mello, and was there anything important said?
piworld filmed T Clarke, so you can catch up in full ... when it's edited! Give us a bit of time.
I'm confused about Ten Lifestyle Group (TENG), it's down 63% but the narrative does not justify that drop, what I'm I missing
Good morning Paul
I was sorry not to meet you at Mello (what a great event it was) but enjoyed your talk on Monday and Graham's on Tuesday. I also had a slot yesterday where I presented the findings from my 2018 Investor Sentiment survey.
For your readers who couldn't make it, I promised to provide them with the findings which they can see here: https://www.stockopedia.com/content/2018-investor-sentiment-report-422163/
Cheers
Francis
Thank you fwyburd for publishing the results. It is shame that more of the thousands that read the SCVR everyday could not spend the couple of minutes it took to complete the survey to give a more broader indication of sentiment.
It is like the “Do you like this post?” button on the SCVR, which only ever gets 50 or so clicks when thousands read it. It would be nice if people could show there appreciation of Paul and Graham’s efforts each day by not just reading it but giving it the thumbs up. I always give it the thumbs up even if I dont agree with what Paul or Graham write. I am always educated by what they write.
I am embarrassed to admit that in several years of using the site I had never even noticed the “Do you like this post?” button and only now, following your post,I have gone looking for it. Not hard to see if have not mentally tuned out social media shares alongside it.
I will pay attention to it in future- thank you
Thank you purpleski, much appreciated.
167 responses is still pretty good and statistically ok with the exceptions I note in the report. And the Stockopedia audience is particularly responsive (about 66% of responses, mostly within minutes of me posting the link to the survey).
But I agree with you about 'likes' as it's the only feedback we get. However I think one of the problems is that the placement of the thumbs up for the poster (as opposed in the comments) is too recessive. Perhaps Stockopedia should highlight it better and give it more prominence?
cheers
Francis
Thumbs buttons don’t work on iPhone, for me at least they don’t.
It is like the “Do you like this post?” button on the SCVR, which only ever gets 50 or so clicks when thousands read it. It would be nice if people could show there appreciation of Paul and Graham’s efforts each day by not just reading it but giving it the thumbs up. I always give it the thumbs up even if I dont agree with what Paul or Graham write. I am always educated by what they write.
purpleski,
This has caused me something an existential crisis... does this mean I have to give a thumbs up to your post! :-) I normally give a thumbs up to the SCVR but more often than not forget, so I can only apologise to Graham and Paul. It is just a lack of discipline and nothing personal!
On the survey... I absolutely never take part in surveys since reading the Cialdini book, so hope no-one takes it personally. Having said that, I'm not sure the results tell me much? For a start, I'd have to care about the sentiment of other private investors (sorry I don't) and in terms of the results know what level of risk they were taking on in their portfolios? The survey will also be heavily skewed towards people responding who have had a good year as opposed to those who have not. Apart from anything else they'd have to be telling the truth and I'm not sure how credible the results look given the year we have seen up to mid October.
All the best, Si
Paul great to see you, and yes Mello London was superb. Yes, a great event by David with Georgina.
Fantastic to see so many investors, friends and familiar faces. Thank you for loads of positive piworld comments, too - as you say Paul, this wonderful feedback it means a lot. The company videos should be following thick and fast ... but give us a bit of time. (There's over 40 hours of editing to be done!) David/Mello will handle the keynote speakers, which will be available for Mello London delegates.
In the meantime, here's Codemasters Group (LON:CDM) interim results presentation, giving an overview of their H1's which were released 13.11.18. A really clear outline of what to expect in H2, and their overall strategy.
https://www.piworld.co.uk/2018/11/28/codemasters-cdm-h1-results-presentation-november-2018/
Further, at Mello we filmed Frontier Developments (LON:FDEV), once that is published we will have coverage of all the main video games companies, with the exception of £TM17 (for now!).
Tamzin
Any chance that any of the keynote presentations at Chiswick will be available to those of us who couldn't attend. I realise that it's not fair that those who didn't pay for tickets should get the same access as those that did but may all can have access after a reasonable period of time
Thanks
Leave it with us ....
Sorry to possibly be adding to your workload Tomps3, but will that include Volvere?
Thanks, Mark.
Another vote for Ramsdens Holdings (LON:RFX) please Paul. Also further transactions at Randall & Quilter Investment Holdings (LON:RQIH) that operates in the insurance and has recently undergone a significant restructuring, which may interest some readers..
Trading statement out from payments/tech company SafeCharge International (LON:SCH) this morning.
https://www.investegate.co.uk/safecharge-int-grp--sch-/rns/trading-statement/201811280700036837I/
Figures for revenue ahead of expectations, with EBITDA on market. Recent marked sell off in the shares since Graham covered it in September. Decent company outlook. Also a high and seemingly sustainable dividend yield of c.6%. Very strong Q metrics (97 score) but poor M and indifferent V make it a Falling Star, but possibly this report might prompt a market re-think.
Gus.
Ramsdens Holdings (LON:RFX) interims out this morning. Any comments??
Group Revenue up 10% to £23.9m but profit down 3% to £5.0m. associated with the absence of peak Easter holiday FX trading, the opening costs associated with new stores, and investment in the infrastructure and team to support growth. Seems legit.
Jewellery Retail revenue grew by 27% to £4.5m (H1 FY18: £3.5m) including online jewellery retail which itself increased by 126% year on year. This is where the excitement lies!
FY Forecasts showing Revenue of 42.5m and EPS 17p. Seems to me these forecasts are likely to be beaten even allowing for a softer H2
Ramsdens Holdings (LON:RFX)
Personally wasn't prepared for the fall in profitability - I don't think the TU gave any hint of this. That said the reasons do seem credible.
There is a detailed research note on research tree from Liberum - as far as I can see they are increasing their revenue forecasts but maintaining or reducing their profit forecasts - probably as Ramsdens Holdings (LON:RFX) has a very profit lite H2.
Initial reaction in the market not good and I feel overdone, but that is the current market.
Phil
Morning,
re Ramsdens Holdings (LON:RFX)
I think the market reaction seems harsh as they are clearly investing in growth (8 new stores) and the extra costs that come with that. The capex in the period looks to be £1.3m vs £0.3m last time. The weakness in FX is hardly a disaster when the reason is the glorious summer we had an an easter timing issue.
Also, the growth in the jewellery division particularly looks to be another positive. At an operating level cash flow positive and the balance sheet seems good with only £400k of intangibles.
So, I'm genuinely interested to see what I have missed to justify the price drop of c8% at the open.
Paul
Ps As ever, great presentations by Paul & Graham at Mello. Thank you!
Ramsdens Holdings (LON:RFX)
Same here - I am struggling to understand the early reaction, although seems to have recovered a little.
Strong balance sheet and cash generative - although margins are falling and impairments rising - probably not be a good sign and hitting gross margins - part of revenue increase is because pawn broking revenue now gross of impairment.
That said, with a yield on secured loan book at 55%, I would not think the (current) level of impairments is problematic.
Hold and very tempted to add given the dividend / valuation / quality scores and outlook.
Straw clutch - one would think with a bigger jewellery business and all these staycations, people might go away over winter - H2 would be more meaningful than before.
PS: Sadly I was not able to make Mello - but may I add my thanks to Graham and Paul for their great effort and analysis - hopefully I am also able to do it in person one day.
Re Ramsdens Holdings (LON:RFX), I'm still remembering the major sale of shares by directors at around 170p from memory. Never regained those levels. They obviously knew a good time to sell. Always worth following director actions, especially sell ones.
My morning smallcap tweet:
Smartspace Software (LON:SMRT), Ten Lifestyle (LON:TENG), WH Ireland (LON:WHI)
Smartspace Software (SMRT) wins contract from internatio al bank. Initially "includes desks and mobile users in one location, together with meeting rooms which cover a greater number of the client's locations...The five -year contract includes the option to expand the engagement to introduce additional services across the client's operations on country by country basis." No numbers.
Ten Lifestyle Group (TENG) FY (presumably as per Sept trading stmt) and 2019 trading. Guides FY19 EBITA below previous expectations, largely due to continued investment in the platform [did it not plan that?] and lower than expected Net Revenues.
W.H. Ireland (WHI) FD resigns but stays till April.