Small Cap Value Report (Wed 3 March 2021) - Budget day, NXR, GETB, SNWS

Good morning, it's Paul here with the SCVR for Wednesday.
Budget Day today, so I'll be focused on that from lunchtime.
I've also got Hotel Chocolat (LON:HOTC) to finish off from yesterday, and 5 more companies reporting today that I want to look at (Norcros, Getbusy first, then Smiths, Cambria Autos and Barkby, if there's time). That's the plan, so I'll get cracking now!
Agenda -
Norcros (LON:NXR) - positive trading update, with guidance raised 12% for FY 03/2021. Looks good.
Getbusy (LON:GETB) - FY 12/2020 Final results. An interesting software business, with 1 highly profitable product, which subsidises 2 newer, loss-making products.
Smiths News (LON:SNWS) - Deep value share. In line trading. Looks very cheap, but has a weak balance sheet.
.
Norcros (LON:NXR)
235p (pre market open) - market cap £190m
Norcros plc ("Norcros" or the "Group"), a market leading supplier of high quality and innovative bathroom and kitchen products, is today providing a trading update for the ten month period ended 7 February 2021.
A positive update here, ahead of expectations -
Norcros continues to win share in its two main geographical markets, reflecting the Group's strong competitive and financial position. The Board remains confident that the Group's leading market positions, established brands, broad distribution channels and experienced management team will deliver further growth, notwithstanding that economic conditions are likely to remain uncertain as our main markets continue to adjust to the impact of the pandemic.
Consequently, it is now expected that reported underlying profit for the year to 31 March 2021 will be no less than £28m on a post-IFRS 16 basis and ahead of current market expectations of circa £25m.
That’s presented in a very clear way, giving us both profit guidance, and the figure for market expectations. It’s so simple, why can’t everyone report like this?
Revenues - Norcros was already reporting an improving trend, with Q2 (July, Aug, Sept) already up on LY on a constant currency basis, slightly behind in reported currency (for the South African part of the business).
Q3 (Oct, Nov, Dec) and the first month of Q4 (Jan) combined saw group revenues up much more strongly, at +114% reported and +117% at constant currency versus LY.
10 month YTD figures are now down 8% on LY, reported, and -4% at constant currency.
In summary, the group has now caught up with most of the previously lost sales from the worst impact from covid/lockdown/supply chain, in Q1. I’m impressed with that.
Net debt - down to only £(5.7)m at 7 Feb 2021. It was £(36.4)m at the start of the financial year, beginning 1 April 2020. That’s a big reduction, and gives scope to fund more acquisitions in my view. So far, Norcros seems to have made a good job of acquisitions, picking off good quality, profitable, complementary businesses, at reasonable prices. This helps gradually dilute the big pension deficit, into a bigger business, so the strategy seems to be working well.
Dividends - good news here, with divis resuming.
Diary date - scheduled trading update 15 April 2021.
My opinion - the share price has been strongly recovering, so the question is how much of the good news is already baked into the improved share price?
South Africa political/economic risks, and the big pension deficit, are negative factors that need to be taken into account when valuing this share.
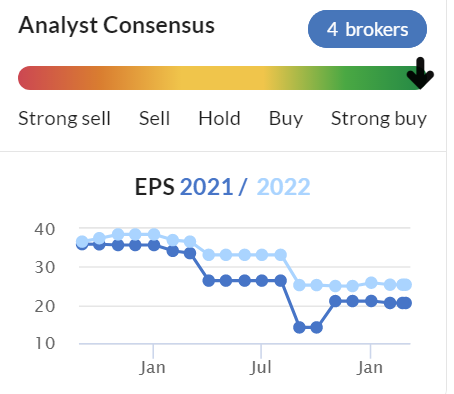
Existing broker consensus seems to be 20.5p, so if we assume actual is likely to be c.12% ahead of that, as implied by today’s update, then that’s a revised EPS of 23.0p. I can't see any revised broker notes yet.
At 235p per share, that’s a PER of 10.2 - sounds cheap, but Norcros is always cheap due to the huge pension scheme and its deficit. Therefore if history is any guide, there’s probably only limited scope for the PER to go higher than that. The StockReport graphs show that the PER range since 2015 has been between 4.4 and 12.6, averaging high single digits. Therefore the current valuation is probably about right. That said, I imagine this positive update today could inspire some buying, so maybe 10% upside on the share price might be reasonable in the short term.
Thinking longer term, if business can recover to pre-covid forecasts of c.35p, then a usefully higher share price could be justified. So this might be a decent longer-term value share to hold for a few years.
.
.
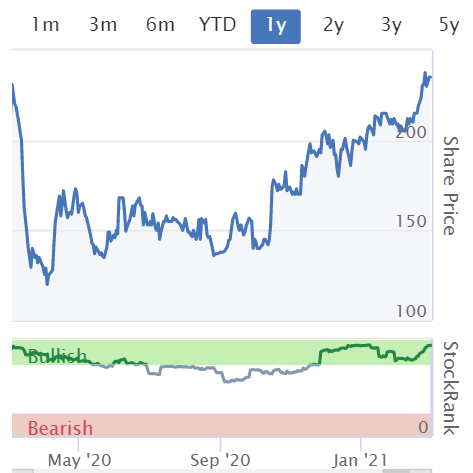
Note the high StockRank below the share price chart below. With broker upgrades feeding through in the next few days, this should remain high, currently 91.
.
Getbusy (LON:GETB)
107.5p (flat) - mkt cap £53m
GetBusy plc ("GetBusy", the "Company" or the "Group") (AIM: GETB), a leading developer of document management and task management software, announces its audited results for the year ended 31 December 2020.
"Our Group contains a combination of a proven, highly cash-generative market-leader [Paul: “Virtual Cabinet”], a rapidly and predictably scaling pure SaaS business in a large and valuable market [Paul: “Smart Vault”], and a new product [Paul: GetBusy] that solves increasingly relevant problems and that has the potential to open a significantly greater market.
There’s a lot of useful information in the highlights table -

Key points -
- Most revenues are recurring, giving good visibility & financial stability
- Modest overall loss, not a concern for a growth company
- Core business, Virtual Cabinet, is strongly profitable, but only 2% revenue growth
- Smart Vault business is growing strongly at +31% revenue, but losses increased to £(1.37)m
- Development spend is high, at £3.6m, mostly expensed - good, as it's R&D that drives progress, if spent wisely
- Lowish customer churn (see presentation slides for bridges)
- High gross margin, so more rapid growth would create excellent leveraged upside due to operational gearing
Results presentation slides are here (then click on “Download” under the third option, “Presentation”). These are useful for a quick introduction to the business & its 3 software products.
Slide 26 is particularly useful, in showing how the highly profitable product (Virtual Cabinet) funds the losses for the 2 loss-making products. Although I would personally take off the £1.5m central costs from Virtual Cabinet’s £3.9m profits, to arrive at £2.4m what I consider real world profits for Virtual Cabinet - still good though, and underpins a lot of the market cap.

The bull case is that we can value the shares on a multiple of Virtual Cabinet’s profits, then add in a speculative value for the 2 loss-making products. If the new products don’t work, then they could be jettisoned, leaving a nicely profitable core business that underpins the current market cap.
The bear case is that the loss-making products should be attributed a negative valuation, reducing the overall group value.
Balance sheet - is weak, unfortunately. NAV is negative at £(1.78)m. There’s only £0.8m in intangible assets, so NTAV is £(2.6)m. That’s not ideal, but for a subscription, recurring revenues company that gets paid a lot up-front, then it’s tolerable.
Remember that this group could move into profits & positive cashflow any time it wants, by curtailing the cash burn on the loss-making parts of the business. So it has flexibility, which is just as important as the actual numbers.
Also, I feel it is battle proven in 2020, being such a disrupted year, by covid/lockdowns.
Cashflow statement - a favourable £1,076k “income taxes received” stands out. Also £384k income from “forgiven PPP loan” helps.
My opinion - this looks an interesting little software business. It’s underpinned by a decently profitable core business. The profits & cash from that are being used to develop 2 new products - speculative upside if they work.
The share has done well recently, and the market cap has risen to £53m. Maybe that’s enough for the time being, based on fundamentals? But remember we’re in a roaring bull market for tech/growth companies, so bullish sentiment could take this share price up to higher levels, particularly if the newsflow is good this year.
Personally, I feel I’ve missed the boat, so probably won’t be buying any. Pity, as it caught my interest last year, but unfortunately (can’t remember why) I failed to buy any. It might have been lack of liquidity - I vaguely recall giving my broker a buy order, but we didn’t get filled. That’s the trouble with very small, tightly held small caps - it can be difficult to impossible to buy a meaningful stake, with similar problems when you want to exit if anything goes wrong.
Overall though, GetBusy gets a thumbs up from me. Well worth readers taking a closer look at it.
.

.
Smiths News (LON:SNWS)
29.2p (up 3% at 11:48) - mkt cap £71m
In April 2014 it changed name from Smiths News to the meaningless “Connect Group”, then recently in Nov 2020 reverted to the old name of “Smiths News plc”.
It’s a newspaper & magazines wholesaler.
Smiths News is pleased to report a robust operational and financial performance for the 26-week period to 27 February 2021, with profit and cash generation in line with market expectations…
The Company expects Adjusted EBITDA (excluding IFRS16 - leases)(1) to be £20.5m for H1 2021 and our Bank Net Debt(2) to be £71m at 27 February 2021, which would result in a Bank Net Debt to Adjusted EBITDA ratio of 1.9x.
Given the stable performance of the business in H1 2021, the Board continues to expect that full year financial performance will be in line with market expectations.
Bank facilities were a big worry, but were refinanced in Nov 2020, at a quite expensive rate of 5.5-6.0% over LIBOR.
Dividends - could be reinstated - update in May 2021. Personally I think it would be extremely unwise to resume divis, whilst its balance sheet is so ropey (negative NTAV). The group should be focused on debt reduction, and rebuilding its balance sheet. Surely the pandemic made that crystal clear, that companies need financial reserves to cope with unexpected events? Management here didn’t seem to get that memo. They sailed close to the wind in 2020, cutting it fine with getting the bank facilities renewed, but it worked out OK, so they were lucky.
Having said that, I've had a quick look at the FY 08/2020 results, which are surprisingly good, so management have justification for pointing out that the business is resilient.
My opinion - I was expecting to find something close to a basket case here, but not at all. It actually looks quite interesting at 29p per share. Obviously it’s always going to be cheap, because a newspaper & magazine wholesaler is a declining business. With the bank facilities sorted until late 2023, insolvency risk has probably gone for now, and shareholders didn’t get diluted in 2020.
Valuation metrics look attractive. I can’t see how a PER of 3.0 is justified! I’ve checked the figures, and it did 9.7p adj EPS for FY 08/2020, surprisingly good. So that PER of 3.0 is real, not an error or out-of-date forecast.
As a deep value share, this one looks worthy of a closer look by readers. I can see why it might be on a PER of say 5-6, but 3 is too low. I need to check the pension schemes more closely, but the last results seemed to show only small cash payments are necessary.
Dividends resuming, whilst I think that’s a mistake with a weak balance sheet, could provide a catalyst for buyers of the shares later this year. It’s quite tempting to have a nibble at these shares, even though it’s not a business I would normally want to invest in. The valuation does look quite compelling though, as you can see -
.

.
Have any readers looked into this one? If so, I'd be interested in your views. I'm writing this under time pressure, so am worried I might have missed something.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
if it wasn’t for the Newspaper declines this could be a very interesting . 55% market share and 24,000 customers 7 days a week plus nighttime collation of products represents a substantial moat. The PER is exceptionally low and the price to cash flow is modest. A number of relatively new appointments to the Board have taken place and some of them look very relevant.
It is not a complex business .
Key Questions - will independent retailers continue to decline - at what level?
Similarly will the newspaper continue to decline
What could a very valuable distribution be used for in the future ie can they replace papers with toys etc.
I think it could be very interesting
Remember as a young, bushy tailed and starry eyed auditor in the early 80's I had a chemical plant as a client. With Regional Development Grants, 100% first year allowances against C Tax and other stuff which I can't remember , the cost of capital investment was negligible .
But, even so, what caused them to "do" capital investment was demand for their products not how cheap it was.
The Government always seems to be on the wrong side of the equation. House building is a classic - this country needs more affordable supply not more demand - yet the distortion continues.
Bring back John Delorean!
Bring back John Delorean!
Did you see that recent documentary about him? It was fascinating! Highly recommended for anyone who hasn't seen it.
Hello, are you going to have time to do Hotel Chocolat (LON:HOTC)? It's a unique company, but intriguingly and consistently unprofitable for its reach and size.
I did. Fascinating story of Government folly and desperation policy. Governments love a "white knight" riding in offering jobs and enterprise.
Getbusy (LON:GETB) Take a closer look at this one.......
The earnings for ye2020 are from their software; Smart vault and Virtual Cabinet - this is specialist software that seems to be aimed at Accountants
They now have Get Busy which can be used by Businesses with Clients - a much larger market.
This type of business is very attractive - no raw materials or processing or transport issues or issues with regulators or etc
The income is sticky - much of their profits are from renewals!
The 'super deduction' (130% tax credit for capex) in the budget is really interesting and I wonder who will be the big gainers?
"In aggregate, the UK’s non-financial companies have been been building their cash holdings steadily since 2009-10—from 15% of GDP in that year to nearly 25% today.
The pandemic is unlike previous recessions in one key way. In all the past four recessions, firms have drawn down their cash buffers by an average of around £40 billion in current prices. In stark contrast, money holdings have increased in the four quarters since the onset of Covid-19 by around £118 billion.” - Resolution Foundation.
Not sure how much of the following will be UK based capex but to name a few companies and rough numbers of those which have relatively high capex:
BT up 7% on the news today and have a capex bill of over £4bn (total) per year. (has quite a big pension deficit)
Rolls Royce £700mio (total) capex, share price barely moved.
BAE £500mio (total) capex, share price didn't move. (has quite a big pension deficit)
IAG net capex c. £1bn (total), share price up 7% today.
THG has over £1bn (total) of capex expected, share price didn't move.
CRH over £1bn (total) capex, SP up 2%.
National Grid over £1bn UK capex, SP down 2%.
I've just put this together very quickly so the numbers are very rough and not completely accurate because companies don't usually give regional breakdowns on capex but it would be interesting to see some detailed analysis of this, probably a few companies which will benefit quite considerably.
An area that is perhaps missed in the first flush of analysis on the 130% super deduction is startup and early stage businesses.
There's a lot of PE, VC and angel money sloshing around in the UK. There is a tendency for this to find its way into asset light businesses (SaaS-y) as these business take less capital and VCs etc are happier funding things that asset light. I know there are many incentives around new businesses (tax credit etc) bu nevertheless this is probably net (very) positive at the more capital intense areas (whether exciting or mundane...probably more the latter which is also probably better for general employment)
In addition, vanilla bank lending to industrial activities just became a whole lot more attractive and less risky. Move away from sexy tech/healthcare/ etc related stuff that VC is happy to chase after and into mundane workshop in Hull and this is big news. The bank is important to them as their primary source of meaningful capital.
I can immediately think of two of my holdings that benefit:
Mercia Asset Management (LON:MERC) -> Early stage investor with a decent exposure to capital intensive technology, industrial and medtech businesses. 130% super deduction could have significant revaluation impact on these cos. This is both in their balance sheet investments and their 3rd party fund management portfolios.
K3 Capital (LON:K3C) -> Seems less obvious but this tax change could be a boost to number and value of corporate finance transactions
I'd then add a third very non-sexy:
Time Finance (LON:TIME) -> Asset based lending and small corporate lending is a significant part of their book of business. They are a sort of non-bank bank. Their niche is lending to businesses that are too high risk for the high street lenders. High risk is as much about scale or early stage (but mundane like a builder rather than a PhD activity) as credit risk....they lend in an area where the main banks find it impossible to apply their data based credit process and uneconomical to pay for real eyeballs and shoe leather based assessment.
I read pessimism from timarr re freeports and economic zones as mere shuffling deckchairs on the Titanic as we head into to non-EU oblivion as we are not part of mega economic zone like US, China or EU. The first two are out of reach...and of course we left the latter...but the economies and benefits of scale in the EU are much less than US or China and the complaint is irrelevant IMO...
The issue is what best for us to do. An industrial and investment policy would be a good thing...and this seems a first step. Change is not usually a net neutral economic activity when are talking physical rather than virtual assets. Anyhow, most growth we experience over time is a result of mundane change....but we have a misplaced narrative that its 'innovation'.
I need to read more carefully but my first impression is that this could be impactful. Its likely to attract capital to UK as well...and it tends to want to come here for many structural reasons even if there has been a recent hiatus.
A step I would like to see is the govt enacting policy that more directly liberates the somewhat frozen out bank balance sheets that has happened post 2008 crisis and subsequent austerity and bank capital adequacy reforms. Productivity and growth is linked inexorably to credit growth. We now need a decade of credit growth. I outline how the above will encourage it...I had hoped that the govt would also target credit growth through effectively a credit policy whereby it partially underwrites lending to targeted areas (eg renewables, deprived economic zones, etc).
Keen to get your thoughts on HOTC.
UK_Investor's (small) head is spinning.
What with a house move T-14 days, about 20 address notifications today, the day jobs, the budgie, the bug, my share disaster/ineptitude last week, everything else, its hard to keep up.
Funny enough, the one party I couldn't notify of my impending change of address is The HMRC Corporation Tax... because to change your HMRC company address, you have to change your declared Registered Office, and I can't prove my new Registered Office address yet, because I'm not there, and my anonymising mail service can't do this without the correct proofs. Fortunately, I think I've charmed my buyer into holding any important mail for me in the gap where I am homeless.
To shares...
XLMedia (LON:XLM) continues its surge, unchanged in the 43p to 47p range on 1,289,636 volume. Still no news.
International Personal Finance (LON:IPF) had Full Year Results today. I was up at 0750 to read them. Their Results read like a book of the bible in verbosity and detail, which I think is probably a good thing. There are clear explanations on each business unit, and each material factor affecting their enterprise. They also set out their Ethical agenda clearly:- to serve unserved clients, and to do so by building trust and relationships with their agents and end user clients.
The Accounts loss of H1 is nearly reversed with a Trading profit in H2, with some sensible cost reduction and right scaling. I'd say The Management are Talking a good Talk. There are reasons to be impressed and assured with their competence.
Dividend remains off for very sensible reasons but there is a stated intent to resume a progressive payout when its clear the global crisis abates. They expect to be (highly) cash generative by 2022.
International Personal Finance (LON:IPF) had a low of 79.65, a high of 91.3p and closed @ 89.8p on 1,520,904 volume. +8.59% on the day.
I say, sit this out. We are looking at a year timeframe to see a quality business return to good yield, growth, long term stability, and operating within the law and providing good service to its end user clients, with a global diversity.
I am still kicking myself about selling EVRAZ (LON:EVR) Central Asia Metals (LON:CAML) and Apax Global Alpha (LON:APAX) last week.
Seriously, don't leave me in charge of a goldfish let alone something of more importance.
I am pleased that IG Group (LON:IGG) continues to hold the range of 791 to 811p.
Plus500 (LON:PLUS) is slipping below 1299 at the close.
Centamin (LON:CEY) - you guys don't love it... but I like a loser!
I declared my milestone in December 2020 of breaking the £1M for the first time (with many thanks to Stockopedia's excellent algorithms and excellent editorial commentary).
Today, my shares under management plus the cash stupidly generated last week broke through £1.115M Gross before tax due. (I am not sure such selling prices are attainable without splitting share sells into small batches.)
The Reactor hellfire is continuing to be fed, though I'm at about 20% cash today and short by a small balancing amount on my house completion, though 1 month should fix that.
This idiot is so far up 10% in 3 months in spite of missing the shares I want to be in.
So many regrets at so many mistakes. Never done anything like this before. Wow.
You can get Royal Mail to redirect your post for a period.
From my experience it is worth doing for a few months as there will probably be someone you forgot to notify.
This isn't advfn
What's an advfn?
Any good reason for Finncap (LON:FCAP) to publish its 'ahead of expectation' trading update at 1.55pm?
Basic Stockopedia ranking question (I'm new, sorry) On Getbusy (LON:GETB) , how is it rated as a 'High Flyer' when it's not in the green on Quality or Momentum (or value for that matter)?
Hi Bullygig,
The rule of thumb is: provided the Quality Rank and the Momentum Rank are ranked 60 or above then the share qualifies as a 'High Flyer'.
Only when a ranking reaches 80 or above does the colour changes to green.
Value has to be under 50 otherwise it will be a Super Stock.
Thanks for taking the time to reply. I think I may have taken the graphical representations of the stockstyles a little too literally!
Hi Paul
Smiths News (LON:SNWS) was reviewed in the Mello Bash on 19th October. It was trading at around 26p at the time and pitched by Kevin Taylor, whose view was that one should 'back the truck up'. Kevin gives a very good review of the company's somewhat chequered history. Kevin took the view that it is simply too cheap. The overall consensus view was buy with some reservations.
Like Gromley I have a small position, which I will hold and look to add to, depending on how the situation evolves.
I hark back to the comment from Peter Lynch in his book 'One up on Wall Street' that companies in declining industries don't attract competition. It was the refinancing of the debt burden that eventually persuaded me to push the buy button.
All the best
Smiths News (LON:SNWS)
I'm very fond of investing in declining industries. There's always a risk that the decline will be faster than expected, but otherwise they're more profitable than most investors anticipate.
For me the key risk is a poorly managed diversification, which is all too common and which Smiths have already done once. The key issue is whether the management is technically competent enough to manage the decline; most companies don't have this - it requires the ability to plan and predict into the medium/long term and a lot of discipline and self-control.
The big plus is the ability to throw off cash (as long as they don't waste it), so I tend not to worry too much about a weak balance sheet - it's easy enough to do the sums to check whether it's too weak.
I believe Smiths is cheap. But I remain to be convinced by the management.
You make good points xcity.
In terms of Smiths News (LON:SNWS) though there are two points I would make :
I'm not up to date on budget (actually watched the Scottish stuff more in news today hoping charming smug dictatorial Nicky gets caught out).
My worry is austerity and/or real and rapid action to seek to pay down national debt (talking about it is fine...and to some extent Sunak may have got the balance right to show he cares but not do anything now).
The only way out is nominal growth at these levels of national debt (and national debt is much much better than it being loaded on people and cos!). All plans should aim at that and then a very long payback/real erosion of debt.
Austerity or payback quickly would be amazing self harm
From my reading of his budget speech Rushi 'Honest' Sunak agrees with you.
Re the Scottish woman, we can but hope.
A lot of UK national debt is QE money owed by the government to the Bank of England. It need never be repaid and is de facto not an a burden on the public purse.
I agree Mark L ....I was just avoiding the controversy...hopefully like Rishi and Boris are ;)
In think we should covertly embrace MMT...in fact many aspects of what John McDonnell proposed for the first election the dynamic duo fought and got close on re QE for the people and structural investment are timely...
On Getbusy (LON:GETB) -> I think Paul is too conservative on his cautious valuation of the business as SmartVault is a profitable business but they are investing at the most rapid rate they can in growth. So to be simplistic, I think you can take the Virtual Cabinet PBT of £3.9m as a conservative base as underlying profitability at SmartVault (assuming less aggressive growth investment) counteracts central costs...and this is likely an overly cautious perspective. IMO it would not be unlikely that 'growth adjusted adjusted' PBT (wow!) would be something near £5m. Table from accounts lays out the numbers a bit more and can see the extend to which investment in being shovelled into SmartVault and GetBusy task mgt inc on YoY basis (although some of the development work at SV was structural and upgrading so not pure growth investment....but nevertheless not probably reoccurring):
I'm surprised by the timing of GETB's sp movement. I feel that the 2nd half to 2020 was a moderate disappointment compared to resilient H1 and it seemed to me that they failed to capitalise on the growth investment as much as I would have liked (I guess there's a little but of internal disappointment there....of course 'long covid' hangovers etc so hard to make certain judgement). I suspect the perf in H2 2020 may have been aided by likes of Glasshalfull get on board with it (I didn't realise at the time but when I looked at GETB tweets today I saw that he stated a position in H2 around 70-80p area I think).
I think there's reason to see sp both higher or lower from here and there's quite a bit of mood music relying on H1 2021. Could be sticky as I think the reality of opening up will create lots of delays and disjointed corporate action/attention. That's not a bearish statement just that I'm cautious of the general tendency to straight line everything to the moon at the moment.
An interesting budget.
Spending like the Labour Party on steroids.
Saying the word 'honest' about 15 times(!).
An increase in Corporation Tax to 25% in two years but in the mean time the ability to claim for 130% of investment.
8 Free Ports in England, more to come in the 'nations'.
No significant change to personal tax rates, just the freezing of duties and of tax allowances.
Oh yes and opening an office of the Treasury in Darlington.
But anybody who believe the Corporation tax rate will actually increase to 25% just before a General Election is frighteningly naive. It will obviously be reduced to whatever level can be afforded just beforehand and presented as a result of good economic management. Even an increase to 22% could be presented as a triumph rather than deep disappontment.
And in the meantime, corporate tax rates are effectively being reduced from the current 19% for any company prepared to invest to grow.
I suspect other Governments will be increasing Corporation tax as well. Remember all Governments in the West these days are stuck on their mantras of 'fairness', this is one tax that works with that as it's the successful businesses that pay it. I think more likely that if it is seen to be successful at boosting investment (rather than just subsidising normal levels of investment) then he may well keep the super investment tax allowance (or whatever he called it).
But yes, you may well be right. Chancellors always like pulling rabbits out of hats. Going 'tada! Corporation Tax will go down to 23%' could easily be one, as you say a year before an election..
Anyway he didn't meddle much with CGT or other personal taxes, so that's ok with me.
Incentivising private enterprise to grow (130% capex credit) is precisely what we need to get out of this mess. Austerity (Lower fiscal expenditure) is all well and good for reducing the deficit but it destroys growth and business investment.
The UK had the lowest growth in the G7 for the past 10 years.
On top of this, UK companies are afraid to expand and grow because shareholders just want an old war horse which pays them an 80% cash payout ratio every year and why Apple is bigger than the entire FTSE 100 by market cap!
Free ports, economic zones for under-utilised regions and labour markets can provide a big boost to the constant decreasing levels of productivity that the UK has seen over the past 20 years.
The UK needs to learn to take some risk and be pro-business again, drive private enterprise and incentivise entrepreneurship for the long term rather than just relying on old large laggards of near dead industries like tobacco and oil. If we need to spend a bit to get there, then so be it.
It is much better than just increasing the welfare state and offshoring everything to a cheaper location so we feel a bit richer for a while; which seems to have been the policies of the Tony Blair and Cameron eras.
Incentivising private enterprise to grow (130% capex credit) is precisely what we need to get out of this mess.
Well, it'll help. But the woefully low prediction of future growth in the Budget show exactly how poor expections of productivity growth are, even with encouragement to invest. Free ports don't really help - they may revitalise targeted areas, but they move investment away from other areas so overall they tend to have a neutral effect.
If you want to turbocharge growth you need to start with investing in education and then incentives for school and university leavers to set up their own businesses - and then massive incentives and access to capital for them to grow them. Frankly old - or even middle aged - people rarely create exciting businesses. Sadly that's not a quick fix.
The UK's problem is that its internal market isn't big enough to support global champions - there's a reason most of the tech giants are from the US or China. Without tariff free access to large home markets growth is harder to achieve, and we end up seeing our most exciting businesses bought before they can grow.
But when the government actively cheers on purchases of our rare global champions such as ARM, then what else should we expect?
timarr
Hi Thornobian
For me the issue re the 130% capex credit is quite simple: does it increase investment or does it just subsidise existing investment? I have no idea what the answer will be. If it does significantly increase investment then I suspect that it will be retained.
Re the free ports I think those are good news and it will be interesting to see what their potential can realise. Clearly the Government are keen to move the stock market on from its current malaise. Of course I agree that the UK should incentivise entrepreneurship....who knows, one day it may happen. That said there is a record number of business start ups at present... so perhaps there is some hope.
I used to trade options on small company stocks which would normally cost around 10% of the stock price for a 3 month view, my old broker no longer does it, Spreadex are not opening new positions in the stocks that I want to trade does anyone know a broker who trades options in smaller companies still? Thanks Steve
Hi Cleeve, I used to market make options and have been trying to find an options broker too. It was a declining market before I finished in the U.K. unfortunately, it’s a bigger market in the U.S as retail punters can’t short stocks. I am half hoping IG Index will start to offer an options service having bought the American options business. Have you tried City of London?
Hi Cleeve and Delta neutral, I used to trade options with Saxo Bank a long time ago. Don't know if this is still possible, but worth an inquiry.
Hi Essex Pete, thanks for the heads up.....I think I looked there platform?? but found a he spreads too wide.
Hi Pete
tried them but spent ages holding only to be told by an automated service that my call could not be taken maybe there is a gap in the market here
Hi thanks not tried city of london is it a broker?
Hi Cleeve,
Spreadex are not opening new positions in the stocks that I want to trade
I'm surprised to hear you say that, because I've been opening lots of new long positions with Spreadex lately, in small caps, with no restrictions.
Also, Spreadex lowered their margin requirements on Saga (LON:SAGA) (I hold) this week, which is such a pity, as I was forced out of my IG SAGA position just days earlier.
I was asked by Spreadex to sign away my regulatory protections on my cash pile held with them last week, which I agreed to, because I know and trust the management, who are very conservative, and have strong financial backing, and a superb track record (they were bulletproof in 2008-9 financial crisis, as billionaire deep-pocketed shareholders provided liquidity when needed).
Spreadex's last accounts show balance sheet, as at 31 May 2020 showed NTAV of £82.4m, and profits of £23.4m (pre-tax) on revenues of £49.1m, so it's financially strong.
I'm told that Spreadex hedge some of their client positions via IG, but have relationships with other brokers too.
In summary therefore, for my account anyway, it's been completely business as normal with Spreadex. But my account is classified as professional, and I've signed away my rights over my cash pile. That makes it a more profitable account, and means Spreadex can use my cash within their pooled capital.
I've approached them, and asked if Spreadex want to do another interview with me, to discuss these topics, as there seem to be different experiences for different people at the moment.
Regards, Paul.
Hi Paul
Thanks for your thoughts - Spreadex would insist on me losing all protection as well however I mentioned 4 stocks to them and they said that I had no chance of opening positions in any of them with or without the protection. They are not stocks which will pass your tests I fear but maybe you could ask if you could open a position in #AAA or #DEV or even #ASLR would be most interested in your findings. Thanks Steve
Hi Paul,
I've looked at Smiths News (LON:SNWS) quite extensively in the past so I can add a little more colour.
One bit of history that I'm sure many will remember was that the 2014 rename was related to the acquisition of the parcel delivery firm Tunfells, the aim was essentially to diversify away from the declining newspaper business to build a broader logistics business.
It was in my view a good plan, however the reorganisation of Tufnells was a complete disaster (I could write a book on the subject) and having cost them millions they disposed of it on the cheap. That's the primary reason for the weak balance sheet.
Once the disposal was complete, they are essentially the same (somewhat boring) business that they were back in 2014.
When you described them as a wholesaler above I was going to correct you and point out that they are actually a distributor, but then I noticed that they describe themselves as a wholesaler in today's announcement.
Strictly speaking that is true because they bear the credit risk on the newsagents paying the bills (weekly!) but it does bear considering just how much of their "turnover" is essentially pass through to the publishers.
Why does that matter? Well for one thing it means for the service they actually provide (distribution) their operating margins are actually much better.
Whilst the balance sheet overall looks poor, the current account balance sheet is actually okay (last years figures look a bit odd because the debt that was due for renewal was all therefore all on the current account) and the cashflow is super reliable.
I only have a small position here at the moment as I think we will probably need to see some clean numbers before there is much possibility of a rerating.
There was also the matter of Pass My Parcel, which was owned and shut down by Connect Group. Not sure what costs were attached to that (2018 I think).
I returned an expensive but faulty laptop to Amazon via Pass My Parcel in late 2017 because the newsagent seemed more convenient. It never arrived and it took a long time for the refund to be issued by Amazon - my suspicion is that it was intercepted during the couple of days it sat in the back room at the shop (apparently there is a fraud which involves "label swapping"). Anyway, one problem doesn't mean anything by itself, but I wasn't surprised when both Pass My Parcel and the newsagents closed down the following year.
Hi Paul, I've held Smiths News for around 3 years. I agree the p/e is genuine. One factor worth considering are the advance payments received, that will shrink as turnover reduces and absorb free cashflow. I guess Covid has accelerated print decline, and there might be a temporary pause that would help. Now the business is stabilised, the bank debt can be reduced and hopefully the interest on debt will fall. Ultimately, it's a gamble on how quickly print revenues fall. I estimate anything less than 5% decline per annum will make this a very good investment, 7% should still be ok. The key question is whether print is ultimately going to zero, in which case it's probably one to avoid, as at some point well before then the business will be terminated. Another point to consider is whether management will follow their predecessors, and seek again to diversify. The main shareholders look pretty solid though (Aberforth etc), and would hopefully check out any such plans very carefully.
Here are my SCVR heat maps for today (prices as at ~11:40am).
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents
I have just heard the presentation by Rbg Holdings (LON:RBGP) (which describes itself as a professional services company, though to date most of its income has been from Rosenblatt Solicitors) on Investor meet Company this morning. For those who know the company, this presentation focussed on its new (May 2020) subsidiary Lionfish, which is a litigation funder. I know there have been (and may well remain) issues in this business space, but I think Lionfish appears to have a very clear approach that sidesteps those issues.
Additionally if you access their presentation, slide 6 sets out the potential returns from three cases that Rosenblatt are working on and have funded internally (so not related to Lionfish) and their potential returns (which it is claimed are likely in the next couple of years). The profits are potentially greater than the current EV of £89m...and these are 'not provided within our market forecasts nor marked up in our annual accounts'.
I have been most impressed with the CE Nicky Foulston, which led to my taking a holding. I am now also most impressed with Tets Iskikawa the Lionfish MD. There is a further subsidiary Convex Capital, that got clobbered by Covid related issues in 2020 but is also a source for further profitability. On my reading the current year PE of 14 could be substantially reduced in 2022; but as ever DYOR.
I believe Rbg Holdings (LON:RBGP) are also presenting to the next Mello.
Sorry to revert to Boohoo (LON:BOO) but wanted to draw people’s attention to an FT article that was more positive on the Boohoo US “thing”.
“It’s no laughing matter, but US is crying wolf over Boohoo import ban.”
https://www.ft.com/content/a96...
From the article:
“Yet the risk of Boohoo being locked out of its fastest-growing market appears vanishingly small.”
I hold.
Regards
Michael
Similar quote in the Guardian, re Boohoo (LON:BOO) this morning -
"Simon Bowler, an analyst at Numis, said: “Orders to prevent the import of product under these regulations look to be rare, and the nature of an investigation across a complicated supply chain that is in the process of being overhauled, for which no evidence of modern slavery has yet been found by current UK enforcement bodies, means that the direct risk arising from these letters feels remote.”
https://www.theguardian.com/bu...
Customs and Border Protection is also quoted as saying - "it could not comment on whether it was investigating any specific companies."
So the assertion that "(CBP) ...is understood to have found sufficient grounds for the investigation" remains unsubstantiated.
I'm quite happy holding
Thx Peterg.
Before all the budget chat kicks in :), I just had a quick query I was hoping someone could help with. A few weeks/months back there was a discussion on this board with regards to a company relating to product placement. It's an area I'm interested in investing in, (I've noticed this appearing more frequently in programmes), but I can't for the life of me find the company that was discussed. If anyone is able to help out please, it would be much appreciated.
Hi Ipreidster. I think it may well have been Mirriad Advertising (LON:MIRI)
Many thanks Johnsmith68. Time for the research to start!
Hi lpreidster
I invested a couple of times in Mirriad Advertising (LON:MIRI) and will do again when re-entry looks ok. I think it has real potential.
I found several rather interesting vids about Mirriad Advertising (LON:MIRI) through searching YouTube. You might want to take a look if you have not already done so.
Regards
Howard
Thanks Howard - looking at the fundamentals, they are not quite there yet. I will however keep this on my watchlist for an entry point, as I agree with you, it's an area I see real potential in. Adverts are at best annoying, but product placement sees to flow seamlessly in programmes (hopefully not too seamlessly though that you don't even notice it!)
I will have a look at the YouTube videos, many thanks for the pointer.
is Hotel Chocolat (LON:HOTC) in the supermarkets? If not they need to be as I dont have intention to go back to the high street even outside of Covid and im sure I'm not the only one. Not interested in ordering either individual or a lot of chocolate online either, just with my weekly shop or visit to home bargains. Maybe an M and S tie up would be good for HOTC
MattB52 - some HOTC sold on Ocado FWIW
My bet fwiw is that High St that still have some shops in will be crowded when/if we are 'unlocked' and the weather improves.
Yes I agree, though I do think we will even more rapidly move towards destination shopping. So Bath, Brighton, Guildford, Bond Street, etc (forgive my southern bias) will prosper while more mundane centres dwindle.
Funnily enough I ordered some on amazon of all places about three weeks ago - I usually go for chococo but was too late. They arrived the next day were really tasty and only £12 (oh and no palm oil! great) - I agree though, they would clear up in supermarkets where the most upmarket I can usually find are lindt or thorntons
my favourite fresh chocolates, for other chocolate fans is The Chocolate Society www.chocolate.co.uk fantastic service too - I heartily recommend
Thornton’s! Yuk.
Try Waitrose for a really good range of chocolate. I particularly like the Lily O’Brien brand but also Waitrose own brand Belgian milk chocolate bars are very nice and both are good value. They also have Green & Blacks, Guylain, Butlers, Divine and some other niche brands.
M&S chocolate is scrummy too and good value. Agree that Thornton's is gross, all sugar and little cocoa. Other half is fond of Hotel Chocolat (LON:HOTC) but other than nice packaging I can't see what the fuss is about.
Not in supermarkets. Hotel Chocolat (LON:HOTC) has two main strengths: its multi channel online depth, and its exposure to US and Japan (tiny, but hard to break into). Its financials are perplexing. Constantly low margins and never seems to achieve its potential. They are behind on the ethical side of cocoa sourcing, no matter how hard they talk about "happy cocoa farmers" etc. The chocolate itself is really not special. It's mostly made from Ghanaian "bulk" cocoa, ie standard beans. It's the chocolate equivalent of "supermarket wine" in that you can't tell anything about the grower or the grape variety. There are many handmade english artisan brands which make truly world class chocolate. Look at www.duffyschocolate.co.uk for example. Twice the price, but many times better. Once you taste bean-to-bar chocolate, it's hard to go back to industrial chocolate like Hotel Choc.
Norcros (LON:NXR)
Although it is correct to say Norcross has a huge pension scheme i do take comfort from the fact that the present value of scheme liabilities has a shown material and consistent decreases from 2017 onwards. I am not an expert in this area but to me this suggests they are well past the "peak liabilities" position and as such on a lfl basis one should expect the pension issue to see less wild swings going forward as the liability number decreases and the associated risk of yearly additional shortfalls also decreases on a lfl basis. The pension deficit was down to £31 mill in 2019 but increased sharply to £48 mil in 2020 down to poor equity performance - there is hope that that poor equities situation should be reversed compared to the lowpoint values used at 31/3/2020. Note at 31/3/2017 deficit was £61 mill so they had practicably speaking halved the deficit before last years "blip" due to deprssed equity prices.
If we look at the important scheme liabilities from 2017 on year by year basis they are as follows
2017 467 mill
2018 447 mill
2019 428 mill
2020 410 mill
A reasonably clear trend that the pension issue is trending very nicely towards being much less of a noose around their neck.
Note norcross is a different beast from even 2019 practicably speaking - so although the shareprice has traditionally been cheap there was reasons why that ws the case then that simply don't exist now - in 2019 the company had £47 mill of net debt compared to £6 mill now. Pension - scheme liabities of probably £35 mill+ more than now - and then they had newer acquisitions that were somewhat unproven.
So hopefully for current holders (who may wish to realise gains at some stage?) perhaps the days of the unloved p/e of 5 or 6 may be a distant memory - i did think that may also be the case last year when the price was 290p pre covid and i was wrong then so i may be wrong again in my hope that the future is reasonably sound.
Thank you rmillaree for that review of key elements of £NXR. Very helpful.
Norcros (LON:NXR) ; Is there an argument to buy companies with large pension deficits in the expectation that these will fall if gilt yields keep on rising?
Jim
My morning smallcap tweet:
£GTB Maestrano (LON:MNO) Sportech (LON:SPO) Barkby (OFEX:BARK) Cambria Automobiles (LON:CAMB) Norcros (LON:NXR) Argo Blockchain (LON:ARB) Gore Street Energy Storage Fund (LON:GSF), Smiths News (LON:SNWS)
GetBusy (GTB) FY(Dec) in line with Jan trading RNS. "We are able to see a path to a substantial business..." Marvellous what telescopes can do these days. [SP=NA Cap=NA]
Maestrano (MNO) £2m placing at 13p, a 9% discount, for marketing and technical staff, premises and manufacturing capacity expansion and working capital. [SP=14.4 Cap=22m]
Sportech (SPO) re Connecticut proposal to expand gaming, specifically sports wagering and iGaming in a deal with the Mohegan Tribe and the State Lottery. 15 venues will have a right to sub-license some of those locations to Sportech Venues. "Somewhat contrary to the previous statements from the Governor...seeking further clarification." [SP=30.5 Cap=58m]
Barkby (BARK) H1 trading: rev £7.9m, EBITDA loss £1.1m and 'net loss' £2m. Agrees sale of development at Saffron Walden for £2.85m and book gain of £1.8m. £1m expected in Summer. [SP=21.75 Cap=31m]
Cambria Automobiles (CAMB) recent five months new car sales down 14%, used down 31% but margin up 16%! Aftersales down 14%.THis is still up YoY. NO fwd guidance. [SP=62 Cap=62m]
Norcros (NXR) guides FY(Mar) U/L profit at least £28m cf F/C c. £25m. Will pay a final div. [SP=235 Cap=190m]. I hold.
Argo Blockchain (ARB) mined 129 Bitcoin in Feb (ARB). Co holds 599 BTC. CEO to be paid in BTC. Sounds like a gimmick. [SP=266 Cap=971m]
Gore Street Energy Storage Fund (GSF) now participating in the National Grid's new Dynamic Containment Service which provides very fast grid frequency stability. Co will have most of its operational portfolio participating from 1 April. Since October 2020, "Dynamic Containment has paid an average of £17.0 MW/hr, well above the recent average Fast Frequency Response prices, of £6.5 MW/hr." Current prices may result in a material uplift in rev in 2021. [SP=104.8 Cap=151m]
In line: Smiths News (LON:SNWS) I hold.
Dear Mr C, I really appreciate your update each morning and often witty opinions - thanks. Please keep going along with Paul and Jack's sterling efforts and insights. Cheers all and have a good day
"Marvellous what telescopes can do these days"
Wonderful Mr C! :-)
"Marvellous what telescopes can do these days"
I have heard a rumour that cloudcall have invented a telescope that can see 5 years into the future - i guess we will find out if thats the case in 5 years time.
I have heard a rumour that cloudcall have invented a telescope that can see 5 years into the future - i guess we will find out if thats the case in 5 years time.
Ah - But how many fund raisings does a 5 year telescope project require ?
My own telescope seems to have a blind spot in it.
RE: Argo Blockchain (LON:ARB)
I'm guessing the CEO is hoping for a price increases then or he could be paid +/- 20% depeding on the day he turns them into cash
Norcros (LON:NXR)
Strong ahead of expectations update today - upping underlying profit estimates from 25 mill to 28 mill ye 31/3/21 - not bad for a £190 mill market cap business. Net debt down again to under £6 mill compared to £36 mill at the start of the year !! Not much reduction since prior update but stonkingly good progress for the year as a whole.
Yes, but you also have to take into account the one-off tailwind in the UK for Norcros (LON:NXR), from more DIY during COVID as well as a housing transaction boom. Bathrooms are notoriously messy to renovate, plus out of commission when you do so. The best time is of course when you're not living in it - i.e just bought.
That is why the likes of Topps Tiles (LON:TPT) has also been doing extremely well, along with Howdens.
Agreed. I bought (more) Topps Tiles (LON:TPT) today on the back of the Norcros (LON:NXR) report. Topps last updated the market for the 13 weeks to 26 Dec 2020 (ie upto the current lockdown) with LfL retail sales up almost 20% on same quarter 2019. Norcros today reported UK revenues up 15% in the 4 months to 7 Feb and with the profit upgrade today I think that it is safe to assume that similar growth has continued into the start of March.
It is difficult to see a scenario where Nocros’s UK business is performing well but Topp’s retails business is not. So I have more confidence in a positive next trading update from Topps Tiles (LON:TPT) (due 31 March)
although Howdens is trade only.