Small Cap Value Report (Wed 4 Apr 2018) - TPT, OTMP, MTC

Good morning, it's Paul here!
I'm still jet-lagged, so am waking & sleeping at very odd times - no change there, I hear you cry! Anyway, I've been up since 4am today, and have finished yesterday's report , adding a new section on the trading update from Hornby (LON:HRN) . Quite an interesting special situation actually, but not one I'm tempted to buy.
Market comments
Small caps seem to be in a terrible patch at the moment, so my portfolio is really suffering. Still, it's a marathon, not a sprint, and this type of gloomy market is when (selectively) we can find some bargains. Also, I feel that 2017 was so ridiculously good, that many small caps became over-valued. So a correction to more sensible valuations was inevitable at some point.
Graham and I began to sound like a stuck record last year - concluding our reviews on many stocks, with - nice company, but the shares look too expensive. With valuations now generally having corrected downwards, hopefully we can unearth some more sensible buying opportunities this year. After all, the time to catch the bargains is when other people are too fearful to buy on good news.
I don't see any reason at all to expect a sustained bear market. We have good growth in the world economy, in all main regions. UK consumer confidence is fairly weak, but the outlook seems quite encouraging to me - inflation has peaked, and is now falling. We have full employment, wages are rising, and look set to soon overtake inflation - meaning that the pinch on disposable incomes is coming to an end.
Very unusual weather in the UK has also had an impact this year to date. Winter weather carried on through until the end of March. Therefore retailers & hospitality companies have seen lower footfall. There seems to have been a shift from consumer spending away from things, towards experiences - e.g. I read yesterday that holiday bookings are bucking the trend - surprisingly, at a time of weak sterling.
However, I think it's important to remember that, when we buy a share, we're not just buying this year's earnings, we're buying all earnings in perpetuity. So if prices are marked down because this year's earnings have been hit by one-off factors (such as poor weather), then that can, selectively, provide a buying opportunity.
Mind you, we have to be very careful to avoid companies that are in structural decline. I feel, given that retail is my specialist sector, embarrassed that to a certain extent I've been asleep at the wheel - not anticipating the dramatic decline of shares in Debenhams (LON:DEB) , Mothercare (LON:MTC) or Carpetright (LON:CPR) for example. Although I saw enough to realise that all of those (and others) were best avoided.
It seems to me that a wave of CVAs is now the only solution for many old-school High Street (and out of town park) retailers. Something has to give, after their profits have been decimated by high rent & rates, rising import costs, higher wages due to living wage, pensions, etc, plus a certain amount of business leaking away to the internet every year.
There is only one thing that can release the pressure - namely rents, which have to fall dramatically. The only quick way to do that, is via a CVA. So I think retail landlords are going to be the really big losers in the next few years. Hence I would avoid any REIT which owns properties that are let out to retailers. I'm toying with the idea of shorting Land Securities (LON:LAND) , Intu Properties (LON:INTU) , or Capital & Regional (LON:CAL) - which own a lot of shopping centres. Although that ship might have already sailed, as I see all are already trading well below book value. Also the cost of shorting could be prohibitive, due to having to fund the dividends to the other side of the trade.
The other thing to look out for, is the impact of interest rates being too low, for too long. This has led to over-investment in many sectors (i.e. mis-allocated capital). Hospitality has seen a c.40% increase in casual dining outlets in the last 10 years. The sector is now in a disastrous over-capacity situation, where many PE-backed chains are struggling to survive. The only way out from over-rented sites, is a CVA.
There's a similar situation with retailers - there are too many malls, with excessive rents, many of which are white elephants now. All of this is great for consumers of course - bargains abound, with most chains discounting heavily, so look out for the deals - nobody needs to pay full price any more when eating out. That's another reason why we should not fear the return of inflation, in my view. Retailers' pain is the consumer's gain, as customers resist price rises, and shop elsewhere if retailers try to impose price rises.
Equally, with the internet, there are numerous companies battling for our business, cutting prices to the bone. Many are operating at a loss, or at best a negligible profit margin, in order to gain market share. Again, great for consumers. Not so good for long-term choice though, as independent retailers are being squeezed out of existence.
Overall, I think the marvellous stock market conditions of 2017, where we could look forward to almost everything in our portfolios going up almost every day, are now long gone. This is now a much tougher market, where only good stock picks are likely to give decent returns. To my mind, it feels like a long-overdue correction in a bull market, rather than the start of a bear market. But I reserve the right to revise that opinion in future, if the facts change!
Topps Tiles (LON:TPT)
Share price: 72.85p (down 9.5% today, at 10:01)
No. shares: 193.5m
Market cap: £141.0m
Topps Tiles Plc (the "Group"), the UK's largest tile specialist, announces a trading update for the 26 week period ending 31 March 2018. The Board will announce interim results for the period on 22 May 2018.
LFL sales in H1 look pretty sound, at +0.6%.
However, the trend shows a deterioration, since the split is as follows;
Q1 +3.4% LFL sales
Q2 -2.2% LFL sales
Obviously very bad Feb & Mar weather is bound to have had some impact, which the company helpfully tries to estimate;
While we estimate that short term weather factors in late February and March, and the timing of an earlier Easter, account for around 1.6% of the second quarter like-for-like sales reduction, it is also clear that that there has been a softening of the underlying market.
I like these comments - the company is telling it like it is, not trying to sugar-coat the baddish news.
There is additional commentary, within which this caught my eye, as potentially providing good future upside;
Commercial - we are investing in our Parkside business with an ambition to develop this into a leading brand in the commercial tile market. We have launched a new website, parkside.co.uk, and are very encouraged by the response we have received in our drive to build a talented sales team.
Range - we are seeing encouraging signs that we can leverage our buying scale and range advantage into the commercial segment, effectively almost doubling the size of our addressable market while staying within our specialism of tiles.
That phrase "almost doubling the size of our addressable market..." is the sort of thing that you don't see very often, and certainly makes me sit up and take notice. Doubling your market size, on static fixed costs, could prove lucrative, longer term.
Outlook comments from the CEO sound realistic;
Matthew Williams, Chief Executive Officer, said: "After a strong start to the year, market conditions have become more challenging over the second quarter. While the business has responded well with a performance ahead of the overall tile market, we are retaining a cautious view of market conditions for the remainder of the year."
I think this is warming us up to a probable trimming of earnings forecasts for the full year, but it doesn't sound of particular worry - everyone already knew that this year was likely to be tough for all retailers, whatever they're selling.
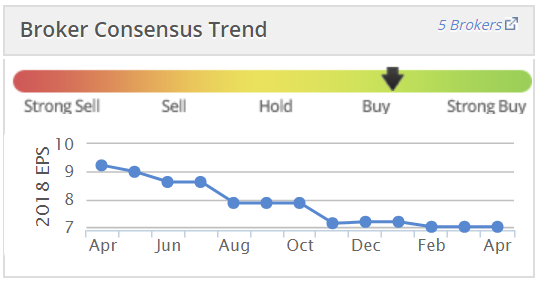
As you can see from the Stockopedia graph on broker forecasts, these have already come down quite a lot in the last year;
My opinion - this is one of the very few retailers that I would consider investing in right now.
I think this company is likely to be a structural winner, in the long term. The trouble is, why buy it now, given that earnings forecasts are steadily falling?
This is a classic glass half full, or half empty share. At some point, the market is likely to become optimistic, anticipating future recovery in earnings & growth from the new addressable market. We just don't know when. So the risk of buying/holding now, is that the market might continue to see things negatively for some time. Nobody knows.
It's on my watchlist already, as I like the company, and took a small opening position a little while ago. However, that didn't survive my recent portfolio pruning. I could definitely see myself buying back into this share at some point. The only question is the timing - which depends on macro factors such as consumer confidence readings, inflation & wage growth figures, which I tend to monitor monthly to drive some decision-making, on at least the timing of buys & sells. It's a fundamentally good company though, in my view.
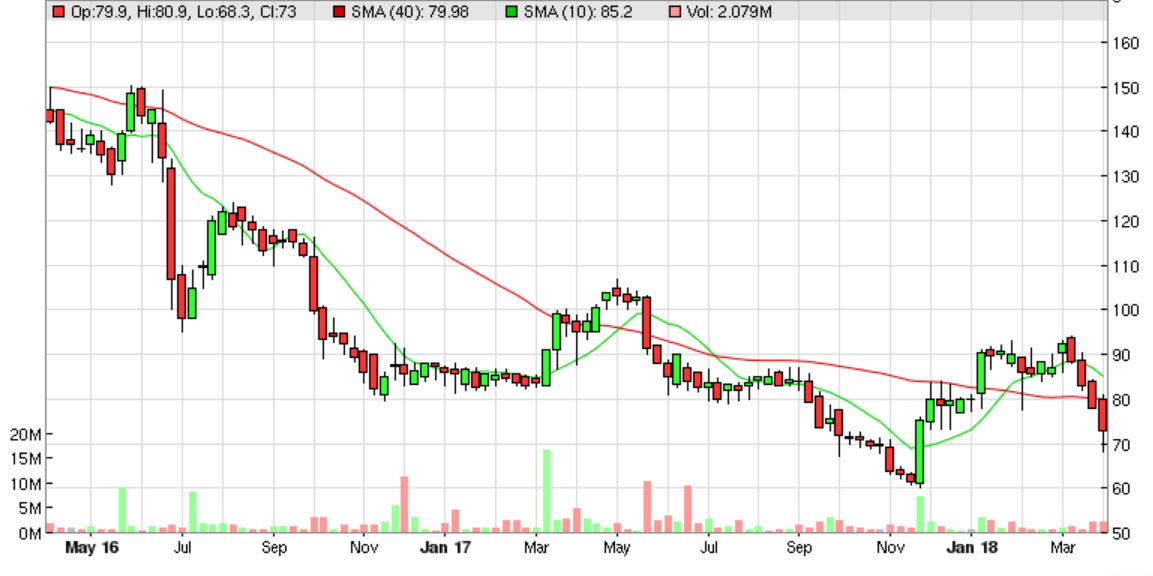
Looking at the chart, 60p is looking an interesting potential future buy point, maybe?
Conviviality
The final chapter here is that an announcement today from C&C (LON:CCR) that it is buying the best bits of Conviviality group (Matthew Clark, and Bibendum) for a nominal sum, and assuming some or all of the bank debt. That's to be expected, since Conviviality shareholders declined to refinance the business, so are wiped out.
The market has added about £100m to the market cap of CCR today, which indicates the lost opportunity for Conviviality shareholders. This business could & should have been saved, and new management brought in, but it's too late now. Instead the upside goes to CCR.
It's such a pity, as the whole collapse of Conviviality could have been avoided, if it had just raised an additional, say £50m in one of the previous placings to make acquisitions.
This was certainly a shocking example of how weak management, going on a big acquisitions spree, can have calamitous results. I don't think anyone saw this coming, either, in terms of Conviviality actually collapsing to 0p. When I've got time, I'll revisit the numbers, and see if there were any warning signs in the previous figures. But seeing as management couldn't actually count, and the figures were clearly wrong, maybe that would be a pointless exercise?!
Mothercare (LON:MTC)
Change of CEO - Mark Newton-Jones' 4 year tenure as turnaround CEO at this distressed retailer has come to an end. In comes a new turnaround CEO, David Wood, who sounds a credible new pair of hands.
As I reported recently here, it's impossible to value MTC shares. They're probably worth little to nothing, but that depends on what type of restructuring & fundraising the company undertakes. I cannot see why investors would want to pour in more money, just to see it frittered away, paying off landlords to exit loss-making shops.
It's anybody's guess how existing shareholders will be treated, we just don't know. Hence this share is univestable, and only for gamblers right now.
Onthemarket (LON:OTMP)
Share price: 112.5p (up 2.7% today, at 12:12)
No. shares: 60.5m
Market cap: £68.1m
I wouldn't normally comment on this type of announcement, but I'm intrigued by this share, and am watching its progress.
This company is the UK's 3rd-largest online property website, behind Rightmove & Zoopla. I wrote a review of it a couple of months ago, here.
Today it says;
OnTheMarket plc (AIM: OTMP), the agent-backed company which operates the OnTheMarket.com property portal, is pleased to announce that traffic to the OnTheMarket property portal reached c. 12 million visits* during March 2018, the first full month since Admission to AIM. This is more than double the visits compared with February 2018 and compared with March 2017.
While this is only a month of data and is therefore early days post-Admission in the Company's steps to drive site traffic, the Directors consider this growth to be very encouraging and expect momentum to continue over the coming months through a combination of the increase in marketing and the traffic generated by increases in branches signing up and listing properties. The Company will provide a further update on visits in connection with the results for the year ending January 2018....
My opinion - this is basically a second attempt, after the initial business plan didn't work very well. The IPO raised a chunk of new money, to spend on marketing.
On balance, I reckon the chances of success are pretty slim. However, if it does succeed, then the upside on the share price could be considerable. So it's worth keeping on the watchlist, in my view.
I'll leave it there for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Hi Paul,
What does CVA mean?
Thanks for the insightful article.
Regards, Daphne
To save Paul and my blushes - I always like to Google the answer and in this case wikipedia gives you LOADS of options https://en.wikipedia.org/wiki/...
and under Economics the options are-
Collateral Valuation Adjustment, a concept in debt restructuring
Credit Value Adjustment, a credit component of FAS 157 Fair Valuation - see Mark-to-market accounting#FAS 157
Credit Valuation Adjustment, the market value of counterparty credit risk
Certified Valuation Analyst, a specialist in business valuation standards
Company voluntary arrangement, for companies in insolvency
Last one looks the likely culprit
I feel like any commentary on the market is amiss if not considering the change in direction of the US Fed. Rates are now on a rising path and 'quantitve tightening' is planned. They exact opposite of policies which have given us such a buyoant and un-volatile market for the last 10 years. A lot of people would argue this has been THE driving force in markets for the past decade.
Maybe i'm too eager to seethe disaster around the corner but i'm not positive about the general market. I felt similar a year ago though too.
As usual, very insightful macro analysis. Thanks.
I was interested in Onthemarket (LON:OTMP) but when you think about it their whole concept is to save agents money compared to the big two. But the problem is because of the dominant market share from the other two the agent would still have to pay for them two as well as Onthemarket (LON:OTMP), essentially costing the agent more. It's better off signing agents up for free and maybe use an affiliate / pay per click model.
The solution for REITS
Paul - you are right the CVA is the short term solution for all these retail businesses who sign up for 5-20 year leases with no visibility on their revenue. I am confident this will induce a change in the property law rather like we had it in 1986 in residential property with the assured shorthold tenancy when there is no tenants rights but they can walk away quickly. No such thing exists in commercial property law. In residential it caused the buy to let boom when private rented went from 3% of the housing stock to 20%.
I think the same will now happen in commercial property. Which would be the turning point for Intu and Hammerson as they own the retail stock. Then the tenants can have a go at low risk and we get more vibrant pop up retail space. And just maybe the REITS will trade nearer NAV.
Just in case you want to go short that may be the reason that could be wrong. But it may take a long time I guess.
While I agree that the retail landlords will have problems, I do think that much of this (if not more), is already in the price for many REITS. Looking at Land Securities, for example, it reail properties are valued (in the NAV) at an equivalent yield of c4.5% (a wide spread to gilts). On top of this, the stock is trading at a 35% discount to NAV and remembering that London offices make up nearly half of the portfolio - so there is a significant fall in the retail part of the portfolio that is priced in. Also LTVs (leverage) remain relatively modest.
Mothercare new CEO stating he needs to put the company on a "secure financial footing". with debt of £50m and market cap of only £30m how does that work? that is before structural revenue decline, too many high rent stores and cash outflows to fund refurbs and closures. probably need to raise best part of £100m cash. even then probably won't work.
Thanks, Paul. Another high quality report.
They have helped me enormously over the past couple of years.
BB
Having bought tiles recently one thing I'd caution against Topps Tiles (LON:TPT) is the amount of online competition. Topps Tiles (LON:TPT) is a well-known brand and its samples are cheap (a useful way of enticing customers), but some of the online competitors are undercutting it or are similar on price. Plus you can order other bathroom or kitchen furniture from some of its competitors (e.g. Victorian Plumbing) which is convenient for doing one big order or for reducing the overall cost of delivery (which can be quite expensive on bulky bathroom stuff). I also wonder why you need physical stores for tiles, at least for ordinary customers, as it's easy to get samples through the post so perhaps they will be disadvantaged against some of the online-only competition. In the end I bought my tiles from other competitors for reasons of price and style.
The Topps Tiles (LON:TPT) website is very easy and intuitive to use though. I like the sound of other opportunities in the commercial segment so, despite the comments above, I've added it to my own watchlist and may do further research at some point.
Thanks Paul, interesting comments on Topps Tiles (LON:TPT).
I largely agree with your sentiments regarding Topps Tiles (LON:TPT) being a well structured company with a long term profitability. Particularly interested in the trade focus that they are adopting. As for retail they have a great online presence and the stores well positioned as a 'one stop shop/up selling ' for all tiling products. I can't help but think this company will kick on with the uptake in general house building and planning relaxations.
One to watch (I don't currently hold, got stopped out at 83p last week) with the right conditions.
Hi Paul,
Thanks for the great Topps Tiles (LON:TPT) update, just wondering as it wasn't mentioned (or I missed) - Do you believe the Dividend to be sustainable?
Hi Matylda,
Do you believe the Dividend to be sustainable?
This question relates to Topps Tiles (LON:TPT) .
I note that the divi last year was slightly reduced, from 3.5p to 3.4p, so that does raise a question mark over future divis.
Brokers are forecasting divis this year & next, and they get their steer from the company.
You would need to trawl through the previous results updates & trading updates, doing a CTRL+F search for the word "dividend", and see what it throws up, in terms of comments.
Looking at the numbers, I can't see any particular reason why the company would need to stop paying divis. Its balance sheet looks OK, although it has some debt, but that doesn't look excessive compared with profits.
Regards, Paul.
Thanks Paul re: Topps Tiles (LON:TPT).
Yes, I noticed the reduction there too which seems to have been a precursor to the revisions today (Liberium note) which are down about 8% or so to 3.1p, 3.2p and 3.4p for 2018/19/20. Seems coverage is around 2x so hopefully they can be sustained around these levels.
Thanks again for the coverage, the response and the macro note (most useful all round).
Concurrent Technologies (CNC.L) announced its final results for the year ended 31 December 2017 today, that its reported revenue stood at £16.2 million, compared to £16.4 million in the preceding year.
Profit after tax was £2.8 million compared to £2.8 million.
The company’s diluted earnings per share was 3.79p, compared to 3.90p.
The company declared a final dividend of 2.20p per share compared to 2.10p in the comparable period.
The shares are down 7% presently for in-line results.
Paul could you have a look at this solid company that produces up market computer boards, which recently announced a number of new products as well.
C&C Group are to acquire a chunk of Conviviality for a nominal sum. It looks like they are taking on a substantial portion of the debt as well.
https://www.investegate.co.uk/c--38-c-group-plc--ccr-/bus/acquisition/20180404081200Z4268/
Any stocks trading below book value as with both most high street retailers & commercial rental landlords could be the big surprise winners over the next few years as book value as a value criteria has underperformed for years and mean reversion suggests book value is due a bull market
With regard to the market direction generally, I took a look at the Earnings Upgrade Momentum Screen this morning. There are only 19 qualifying stocks, 3 of which are incarnations of John Laing.
I don’t know how many stocks this screen typically finds and broker forecasts can be lagging, but it strikes me that just 19 qualifiers suggests that there is quite some way to go before market sentiment generally turns more positive.
Although I'm bearish based on market zigs and zags, for this screen the answer to your 'typical' is 12-13, shown to the right of the chart.
So if anything 19 is bullish, although with such small average numbers statistically I doubt there is a real difference.
Thanks for that. I hadn’t spotted that the average number of holdings is stated on the screens.
Paul, you are right in saying "I don't see any reason at all to expect a sustained bear market. We have good growth in the world economy, in all main regions. UK consumer confidence is fairly weak, but the outlook seems quite encouraging to me"
I think the problem is more Trump and the ripples he is causing affecting US indices and in turn affecting ours.
If we get sensible negotiations taking place with US- China I think you will see a reversal of trend in the indices in USA and subsequently here.
Thanks for the interesting intro, Paul!
In some ways a similar story with Filtronic (LON:FTC) which makes mobile phone network antennae etc.
Similar to Image Scan Holdings (LON:IGE) this company is riding a megatrend - in this case mobile phone network roll outs and particularly the upcoming 5G revolution. Revenues here are very lumpy due to small number of customers. They enjoyed an exceptional H1 last year, but business returned to more normal levels in H2 and H1 this and at the end of January they reported "progress toward production volume orders has been slower than anticipated." and "further growth being pushed into FY2019."
As a result, shares have been trading at a near 50% discount to the late 2017 highs.
A promising announcement this morning of a massive MIMO antenna development with Nokia
I should point out that "massive MIMO" is "a thing", there is no indication whatsoever that the deal itself is massive - in fact no indications at all on timescales or scale.
To some degree or another it must be good news, but I would say good news that should have been expected so the 4% increase in the share price this morning is probably neither too bullish nor too conservative.
A short but sweetish trading update this morning from Image Scan Holdings (LON:IGE) .
(Price up around 8% at market open)
The story so far :
• Image Scan Holdings (LON:IGE) manufactures and sells portable X-ray machines for use in security and industrial processes.
• The price had risen from around 5p / share in early 2017 to c. 12.5p prior to the announcement of FY results in December 17.
• The December statement included some amber flags in the outlook (although I’m not sure that the full significance was generally understood at the time). In particular “robust orderbook, although we need to finalise the extended delivery dates on a proportion of those orders.”
• The significance of this phrase became clearer in a 1-feb update – a £1m order (FY 2017 revenues only £5m) was not likely to go ahead and cancellation terms were being negotiated. FY 18 to be materially below expectations.
• Further clarity on 27th Feb – cancellation negotiations hoped to be completed by end of March; some of the units had been “repackaged” for other customers. Performance to be H2 weighted, profitable for the full year but a small loss in H1.
At this stage I was quite sceptical : what does “repackaged” mean? How much visibility of H2 return to normality?
Today’s announcement gives a little more confidence imho :
• Order cancellation terms have been agreed (on time therefore).
• “all the portable X-ray units from this order have been repackaged and sold”
It seems clear though from this that the cancellation fees they have extracted in relation to this order, do not fully cover the cost of repackaging and probably extra discounting as “expects the Company to perform at close to break even for the first half of FY18.” – Splitting hairs possibly, but I take this to be a small improvement on “report a small loss for H1” from the previous update.
There are also some warmish (although perhaps not as bullish as some statements last year) about levels on “interest” and levels of “orders”.
I’m somewhat warmed by this statement and particularly the fact that they have “put the cancelled portable X-ray order behind us”– I was tempted to take a small position here, but on reflection whilst the outlook statements do sound promising they are not quite sufficiently concrete for me yet, so sitting on my hands for now.
However I also think that there are a couple of learning points here : (1) even companies riding a broader “megatrend” (security in this case) can come unstuck, particularly if there is a reliance on a small number of major customers, (2) do pay attention even seemingly innocuous changes in the tone of company announcements as chances are they may well be deliberate flags.
Grateful as ever for views from others.
Looking forward to hearing your thoughts on Image Scan Holdings (LON:IGE) Paul!
There was a recent article in Shares Magazine that kind-of recommended buying the REITS you mention.
What do you & others think will happen with interest rates rising? Are we likely to see borrowing collapse and a flight to savings again? Will house prices continue to underperform (I think the opportunity to short PURP has probably sailed...)
My morning smallcap tweet: Rhyl till chill thrill.
Collagen Solutions (LON:COS), Mountfield (LON:MOGP), Intercede (LON:IGP), ULS Technology (LON:ULS), Topps Tiles (LON:TPT), Ediston Property Investment (LON:EPIC)
Collagen Solutions (COS) warns on FY as it fails to land a large contract. Gu9des rev £3.5m (£3.9m).
Mountfield Group (MOGP) wins £1.2m contract. 2016 rev was £9.6m.
Intercede Group (IGP) wins eleventh hour deal on 28 March worth $4.0m. $2.05m (£1.46m) will be recognised in the financial year ended 31 March 2018. Guides FY rev in line.
ULS Technology (ULS) CEO resigns to join Mortgage Advice Bureau. MD become CEO today.
Topps Tiles (TPT) trading: Q2 LFL down 2.2%. "While we estimate that short term weather factors blah blah blah account for around 1.6%...there has been a softening of the underlying market."
Ediston Property Investment Company (EPIC) leases unit to Iceland at Clwyd Retail Park in Rhyl. Great news for the hard of seeing in that sadly run down resort of my childhood as they peruse the frozen blocks of congealed hydrogenated vegetable oil, sugar and salt with giant £1, £2... price labels.
Hi Paul. Thanks very much for such a great intro. I really enjoy these as I'm more of a mid and large cap investor these days. Having said that I have certainly gained much from your reports over the years.
I think the market is at a critical point. The short term falls in the market should be getting close to running out of steam. Personally I think it is likely that we will see a significant jump in the next few days. However if we see a muted jump and then a return to declines then that could suggest we are in a more pronounced bear market. Certainly a more difficult market than last year!