Small Cap Value Report (Wed 6 June 2018) - RDL, TCN, CPR, MSI, AMO, HVN

Morning folks.
These are the stocks which have caught my eye today:
- Ranger Direct Lending Fund (LON:RDL)
- Tricorn (LON:TCN)
- Carpetright (LON:CPR)
- MS International (LON:MSI)
- Amino Technologies (LON:AMO)
- Harvey Nash (LON:HVN)
1pm edit: Lots of interest in Amino Technologies (LON:AMO), so I'll be taking a look at this, too.
Cheers,
Graham
Ranger Direct Lending Fund (LON:RDL)
- Share price: 797p (unch.)
- No. of shares: 16.1 million
- Market cap: £128 million
Oaktree releases open letter to Ranger shareholders
Some (most?) of you are probably familiar with Howard Marks of Oaktree Capital. He runs an alternative investment firm with particular expertise in high-yield bonds, distressed debt, etc.
Marks has become well-known through his published memos (available here), containing a great deal of investment wisdom.
His memos have also been published in book form: The Most Important Thing: Uncommon Sense for the Thoughtful Investor, which I enjoy reading and am happy to recommend. His value-oriented philosophy can be applied to pretty much any asset class.
So I was intrigued to discover recently that Marks' firm has been engaging in some activism in relation to a small British investment vehicle: Ranger Direct Lending Fund (LON:RDL). (Note that Marks himself is unlikely to be heavily involved in this project.)
Oaktree has bought up 19% of Ranger and is now pressing for Board representation, with the view that a wind-down would be in the best interests of all shareholders.
What went wrong
Ranger's strategy has been to invest in a portfolio of debt obligations issued by direct lending platforms, and distribute quarterly dividends to shareholders.
In USD terms, the returns generated by Ranger on capital deployed over the last three years is as follows:
- 2015: 9.36%
- 2016: 5.53%
- 2017: -2.95%
One particular investment has gone very badly, the "Princeton Alternative Income Fund LP".
This was unfortunately a very large investment relative to the size of the fund as a whole. $55 million was originally invested in it, and it is currently (Dec 2017 valuation) in the books valued at $29.3 million (although a $29.6 million figure is also mentioned).
The auditors issued a "qualified opinion" in relation to what Ranger's holding in Princeton is worth. The case is currently going through the bankruptcy courts in the US. This makes it extremely hard to value. Apparently, Princeton is only communicating with Ranger through its lawyers.
From the most recent annual report:
As described in note 3, the directors have been unable to provide us with sufficient appropriate audit evidence in relation to the investment in Princeton recorded at a value of USD 29.6 million. We were unable to obtain sufficient appropriate audit evidence regarding this investment by using other audit procedures.
The opportunity
The NAV for a Ranger share at March 2018 was 938p, including the dodgy Princeton holding. Total value on the books was recorded at $212 million (see here).
So there is a discount to recorded book value available, and a very active and successful shareholder seeking to make changes.
I haven't been able to convince myself to buy it yet, but I thought I'd leave it here in case anybody else would be interested to research it for themselves.
Incidentally, my request for a quote this morning was prevented from being served, thanks to EU regulations. I was met with the following error message:
You have not confirmed that you have read the Key Investor Information Document for this fund.
Thankfully, Ranger Direct Lending Fund (LON:RDL) does have a KIID on its website. So I should be able to buy Ranger shares by calling up my broker and confirming that I've read it.
This has not been the case with Volvere (LON:VLE), in which I do have a long position. According to the bulletin boards, some brokers have prevented investors from buying it because it has no KIID - and there is no way for them to buy it, unless they can find a different broker, who will allow it!
Tricorn (LON:TCN)
- Share price: 34.5p (+11%)
- No. of shares: 34 million
- Market cap: £12 million
Tricorn Group plc ('Tricorn' or the 'Group'), (TCN.L) the AIM quoted tube manipulation specialist, announces its audited final results for the year ended 31 March 2018.
Some great financial progress from this engineering company based in Malvern.
Revenues are up 20% and underlying PBT has more than trebled:
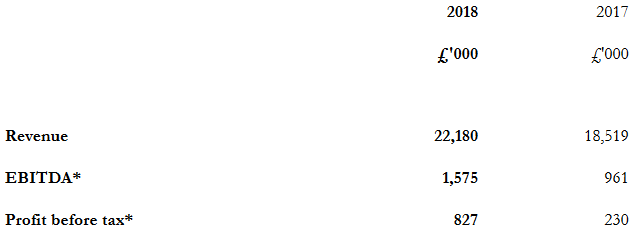
The adjustments made to PBT this year weren't too dramatic, so the actual PBT was £600k.
Tricorn hasn't paid a dividend since 2014, as it has been carrying between £3 and £4 million of net debt.
Net debt has been reduced back now to £3 million (£0.7 million of cash offset by £3.7 million of gross borrowings).
Despite the improvement, I don't think I'd be entirely comfortable with this balance sheet.
Net debt/adjusted EBITDA is about 2x, which is within a normal range.
But if you use a more conservative measure than adjusted EBITDA, e.g. actual EBIT (including joint venture income), then you get a debt multiple of 3.6x (£3 million of net debt divided by £830k of EBIT).
It's not distressed but it's at the upper end of what I would be comfortable with.
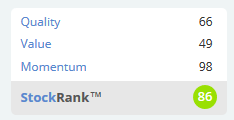
In terms of quality, I've just quickly tried calculating Tricorn's return on tangible capital for FY 2018, and got an answer of 15% - not bad.
So I think its quality score might possibly be set to improve:
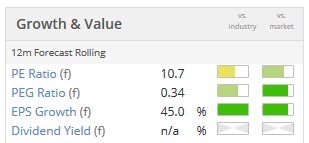
Its value score would also improve if it elected to pay a dividend, but this is not on the cards in the short-term. Other value metrics are good:
Conclusion
A decent stock with an acceptable result this year, although the track record is a bit patchy and the debt load is possibly on the high side. I'm inclined to think there is more upside available for shareholders here - worth looking into, IMHO.
Carpetright (LON:CPR)
- Share price: 34p (-2%)
- No. of shares: 71 million
- Market cap: £24 million
Result of Placing and Open Offer
The carpet retailer has seen strong support from shareholders under its open offer at 28p, with a 92% acceptance rate.
The share count is going to be about 304 million by my reckoning, so the implied market cap at today's share price is c. £103 million. The new shares will start trading on Friday.
The CVA now goes ahead. Recall the key element of the CVA proposal:
A comprehensive review of the Company's property portfolio has identified 205 sites in the UK that are underperforming and/or on unfavourable lease terms, or, in certain cases, not expected to have significant strategic value to the Company going forward. Of these, 92 sites have been identified for closure in the short term under the CVA Proposal, with the balance of 113 sites being subject to a reduction in rental costs and revised lease terms.
The entire estate had about 420 sites late last year, so we should expect a significant trading improvement now that the worst half of them will either be closed or see their rents reduce.
The big cash injection is also great news for the company, of course.
Carpetright's earnings multiple might end up looking very cheap for a year or two, if the planned-for cost savings do materialise, but I think we have to note that carpet retailers are among those retail stocks trading at very cheap valuations at the moment.
Another holding of mine, United Carpets (LON:UCG), is trading at an earnings multiple of 5.1x and an EV/EBITDA multiple of less than 3x (using Stocko data). Investors are extraordinarily sceptical.
In the case of Carpetright, it has been struggling against the competition and in the face of a difficult consumer market, which has led to the need for a recapitalisation.
Speaking generally, it's hard for these companies to build and sustain a competitive advantage. They can do really well for a period of time, but eventually they tend to run into serious difficulties.
So I wouldn't mind holding Carpetright shares for a limited period of time. I think both CPR and UCG could have a nice re-rating higher if they trade well for a couple of years. But I'd probably be very scared to keep them in a buy-and-forget type of portfolio!
MS International (LON:MSI)
- Share price: 236p (+13%)
- No. of shares: 16.7 million
- Market cap: £39 million
It has been a couple of years since I last looked at this stock. At the time, I noted heavy insider ownership, and that remains the case today. The Chairman owns 29% of shares, with another non-exec owning 11%.
It has a very basic website, which is comforting in a way - the company is not at all promotional when it comes to investor relations.
Its operating divisions are: 'Defence'; 'Forgings', 'Petrol Station Superstructures' and 'Petrol Station Branding'. The company produces defence equipment, fork-arms for fork-lift trucks, petrol station superstructures and petrol station branding.
Defense sales are primarily to the export market, as UK defense spending is constrained. I presume that this will remain the case for the foreseeable future.
In petrol stations, the market is changing as ownership passes from oil producers to independent operators such as Applegreen (LON:APGN). This has affected the demand for MSI's services but the company reckons that demand will pick up again once transaction activity slows down.
Petrol station branding is doing better because as petrol station ownership changes, the forecourts must be swiftly rebranded.
The company is pleased with the outcome of its R&D spending:
A key feature is sustaining our creative and innovative product development programmes across the Group, which also results in us owning, unquestionably, the intellectual property rights of products we develop, particularly important in the defence sector.
The outlook statement is positive and dividend is marginally increased.
Conclusion
I like the company's style of corporate governance, with heavy insider ownership and an understated approach to its shareholder communications.
It also has a nice track record of profitability. It has been profitable every year since 2002.
It is a little bit too "heavy" for my liking, in terms of the amount of capital it has had to use to generate these returns. You can see that the quality metrics are a bit weak:
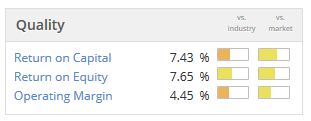
It used to earn really strong returns on capital, but I'm guessing that was when UK defense spending was more abundant and when the petrol station market was more predictable, too.
It's possible that those conditions could return at some point, though I don't know when. For now, I'm happy to keep this one on the watchlist.
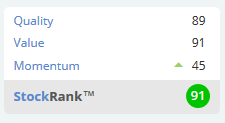
The StockRanks like it a little bit more than I do - perhaps I am missing something!
Amino Technologies (LON:AMO)
- Share price: 200p (-3.6%)
- No. of shares: 72.7 million
- Market cap: £145 million
Amino Technologies plc (LSE: AMO), the global media and entertainment technology solutions provider, provides the following trading update for the six months ended 31 May 2018 ("H1 2018").
I haven't covered this one before. Today's update says that expectations for the full year remain unchanged.
H1 revenues are lower by almost 20% to $41 million, but H1 orders are up by 40%, as seasonality with a second-half weighting is guided.
The Chairman is positive for the full year result:
"As operators transform their services to IP delivery to meet consumer demand for entertainment 24/7 on any device we are seeing good traction for our three clear market opportunities - upcycling, the transition from cable to IPTV, and Android TV. Good visibility provided by our order backlog and pipeline underpins the Board's confidence in full year expectations."
I have been trying to familiarise myself with what Amino actually does:
Amino is a global leader in innovative Internet Protocol (IP) solutions that enable service providers to connect with consumers.
It's providing software, set-top boxes and the like, so that TV services can be delivered digitally.
It has been seeking to increase its recurring revenues, still rather small as a proportion of the total:
Exit annual run rate recurring revenues increased in the period to circa $5 million (H1 2017: $3.7 million).
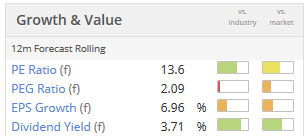
The historical financials look great and the Stocko algorithms are convinced, too, awarding it a StockRank of over 90.
Valuation is not stretched at all:
I would need to read more about it to really understand its products and services.
Some people might be worried about the second-half weighting but I think this is mitigated, more or less, by the increase in orders.
Overall, it's hard to argue with the numbers. I wouldn't mind including a few shares of this in a StockRank-derived portfolio.
Harvey Nash (LON:HVN)
- Share price: 114p (+7.5%)
- No. of shares: 73.5 million
- Market cap: £84 million
This recruiter's share price was around 87p when I covered it in March, the same level it was at when I covered it the previous September.
It was trading near its historic low in P/E terms then, and is still rated quite cheaply in historic terms (despite the recent share price gains).
It has a January year-end; for the Q1 period ending April, gross profits are up 7%.
The UK & Ireland region has been outpacing Mainland Europe and the Rest of the World in gross profit growth, and that trend continued in Q1.
UK & Ireland is up 20% while the Rest of the World segment continues to suffer, down 23%. This is blamed on difficult comparatives.
Overall, Harvey Nash is doing better than planned:
"I am very pleased to report that the strong organic growth reported in the second half of last year has continued into the current year and the first quarter is tracking ahead of budget. The Group has a clear growth strategy, and with the additional contribution from the annualised effect of the acquired businesses and of the transformation programme, we are confident of continuing to make significant progress in 2018."
My opinion
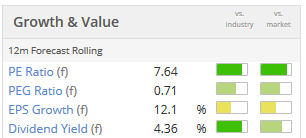
I like this stock and I reckon it makes for a decent investment at the low earnings multiples typically assigned to it by the market. It's hard for recruiters to differentiate themselves much from the competition, but they can and often do generate acceptable returns for shareholders. I'd buy it for the yield, not expecting too much capital growth:
All done for today! Thanks for dropping by.
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Amino Technologies (LON:AMO) not sure I would trust them after what happened in 2015, interims results were good: Adjusted operating profit up 56% to £2.8m (H1 2014: £1.8m) before exceptional items. The outlook was very promising:
"Today's results mark a real turning point for Amino. Following a significant amount of hard work, and thanks to a clear and well thought-out strategy, our business has reignited its organic revenue growth, extended its margins and profitability, and begun to put in place some very exciting building blocks for the future."
3 months later issued a profit warning.
If I was a holder I would sell and watch.
I enjoy reading these articles and comments but sometimes I get a bit grumpy, especially about spelling. So this is a special request to Graham to spell it as "defence". Even though I share Graham's nationality, I'm a traditionalist regarding English usage; hence "licence" (noun), "license" (verb) etc. (I'm sure Graham has fond memories of the Irish Leaving Certificate exams - which started today with English.)
Bezhe, I have granted your request. Typo's and misspelings annoy me too, so please feel free to let us know if you spot any more. Thanks :)
Shouldn't that be - typos?
And "misspelings" is actually a misspelling.
You seem to have missed Graham's tongue being clearly in cheek there...
Well yes, I too like correct spelling but I think you have to allow some leeway. He accomplishes an awful lot in a short time and spellcheck doesn't always pick up everything.
Full proofreading and editing would only result in long delays and I think most on here appreciate reading comments on today's announcements today rather than some day in the future.
I sold out of AMO first thing this morning on the back of the trading statement. Would have liked more guidance on what the Directors' expectations are. Seemed a bit lukewarm to me and I'm happy to bank a small profit and move on.
EMIS
Just used their updated Patient Access App for the first time.
Definitely not as good as before.
Mrken
Thanks for your comments on Ranger Direct Lending Fund (LON:RDL), Graham. I see it as a stock with little downside risk (from current price), good ongoing dividend yield (c.100p a year on 800p price) and a 10% capital upside if they sort out the current mess. The rest of the portfolio (ex Princeton) is in decent shape and delivering ROA of 12-14%, which in turn "spits out" 8% divis on NAV after taking into account fees etc. Never going to be a five bagger, but certainly a strong risk reward (relative to cash in a 2-year duration, high interest bank account). I hold.
Cheers Mark. That sounds like a useful synopsis you've given. Good luck. G
A lot of interest in Amino Technologies, so I'll take a look at it! G
I really think Amino Technologies (LON:AMO) could have done a better job with their trading update today, in providing more concrete evidence of why they think H2 would come good. This poor communication is definitely not going to help the SP next few months.
I still think that this share is a great macro play. All telco and media players are getting pressure now to invest in nextgen hardware for their customers, which has been enabled by faster broadband speeds. Also customers will be demanding UHD and 4K content increasingly, now that TVs support it as standard. This can only be delivered over IPTV.
The key risk with Amino is that revenues will always be lumpy, due to the B2B nature of the business.
MS International (LON:MSI)
This is an interesting if mildly dull play.
EPS of 20.5p so trading on 10* PE but they have £15m net cash in the bank equating to around 100p. Strip that out and the PE is 5 !
Net tangible assets are circa £35m = market cap so only trading at book value.
Dividend is 4%
Cash was up 600k in the year after paying dividends and investing in tangible assets. Small increase in Inventories.
Kind of feel this should be trading at 1.3 - 1.5* book or 8* earnings adjusted for cash = 260-280p
There is upside as a number of markets they operate in have a reasonable chance of seeing an upturn too.
hmm
I looked at MS International (LON:MSI) several years ago now and came away with the impression that it was being used as a director's piggy bank. Their salaries were totally out of whack with what should be expected for a business of the size it was at the time.
I don't know if that is still the case...
Harvey Nash (LON:HVN) please, positive trading update this AM overall profits 7% up mainly through strong results in UK & IE (20%) although ROW 23% down LFL and reasons of exceptional USA results the year previous hmmmmm. They do seem to be on the up overall but would welcome comments from the gang here on the recent acquisitions and future prospects with Brexit and other macro uncertainty.
All the best, CID
Morning Graham, I’d welcome your comments on Amino Technologies (LON:AMO) please.
Thanks
Newbie
I'd also value your thoughts on Amino Technologies (LON:AMO) trading statement Graham please. Interesting comment about H1 revenue fall...
I am also interested in Amino Technologies (LON:AMO) where we have the dreaded "H2 weighted" statement but they say last year was exceptional so I have checked:
Year to Nov. / H1 / Full year / H1%
2014 16.4 36.2 45.3
2015 17.9 41.7 42.9
2016 33.0 75.2 43.9
2017 39.9 75.3 53.0
So yes, that was true but for this year if £30m in H1 and forecast £79.2 for full year H1 would be 37.9% which is lower than the 2014/6 range.
The order book sounds promising but will the market be convinced?
Amino Technologies (LON:AMO)
Another way of looking at your figures, and what concerns me, is:-
H2 2016 £42.2
H1 2017 £39.9
H2 2017 £35.4
H1 2018 £30.0
I think Amino is asking for more trust than normal in an H2 weighting trading statement. Lets hope they are correct.
Phil
I agree.However,they are cheap in relation to the rest of the market,so I am holding.
Hi Newbie, I've had a go at Amino Technologies (LON:AMO) although it's my first time looking at it so apologies if my review of it was a bit basic. On balance, I would give management the benefit of the doubt re: the second half weighting. A judgement call, though.
Thank you Graham.
As is always the case, it’s about the level of trust one has in the management team and their ability to correctly and honestly tell us the situation re. H1/H2 weighting. Lets hope for the holders out their, including myself, that they are correct.
As is always the case, it’s about the level of trust one has in the management team and their ability to correctly and honestly tell us the situation re. H1/H2 weighting. Lets hope for the holders out their, including myself, that they are correct.
As a former holder of Amino Technologies (LON:AMO) I would actually trust the management "current expectations", even though the TU was not the best worded statement you'll ever read. IMO they have executed well enough over the past few years (despite a sales blip) to earn my trust.
It's quite possible they will have a blow out H2 (£50m revenue) to meet current estimates for the full year, but at the same time the risk is now much increased that they won't. Who's to say the major customer won't "re-phase" product delivery again? I like the company, and the market they operate in, but I sold first thing yesterday and will wait to see what they say at the interims in July.
All the best, Si
Alpha Financial Markets Consulting (LON:AFM) reported full year results today. They offer consulting services focused on the asset management industry. Forecast growth looks modest given reported results. They've launched new practice areas (Digital, Data Solutions, Investment Guidelines and Regulatory Compliance), made an acquisition (Track Two in Germany to form Data Solutions practice) and opened new offices (Singapore and Switzerland, at the request of clients). They've also secured 25 new clients during the year. There's pretty significant overlap between the list of customers and the list of shareholders which, for me, acts as a third party endorsement of their capability.
MS International (LON:MSI) reports EPS up from 9.1p to 20.5p. Any views? I hold.
Some good looking results from Tricorn (Tricorn (LON:TCN) )..should lead to upgrades. Worth a look.
Hi Graham - sorry to hog the comments this week but I agree with hayashai22 - Tricorn (LON:TCN) is looking interesting. It seems to be turning around as a business, growing revenues and profitability, but is on a low forward PE of 10.7. Its margins are not that great as a business and the management have made it a priority to change that which seems to be beginning to work. However, the balance sheet doesn't look ideal to me (although as an amateur I don't know if I should be more forgiving of a capital intensive business?), it is a very illiquid share, and one wonders why the management haven't managed to do something about that before.
I did hold. BUT then I sold last week. Why? Because if you search its annual reports the company says it is heavily exposed to the steel price. It is therefore hard to see how the recent Trump announcement (and possible EU retaliation) to impose tariffs on steel imports will help the company with its drive to improve margins. I am slightly struggling to find out how directly it will be hit by the Trump announcement but I am guessing the steel price will not benefit thanks to Trump. It manufactures its products in different countries including the US.
It's disappointing there is nothing in its results this morning mentioning the tariffs.
Hi Paraic, no worries about hogging the comments!
Yes, the company said nothing about steel today. In the outlook, it guided for "further significant progress." Maybe it's not affected by tariffs? Good question, though.
I was at the Billington Holdings (LON:BILN) AGM on Monday & we discussed steel / trump etc..for the record they had no concerns..steel prices in the UK are not likely to see an impact , they thought that given the constraints on US steel production..big users will simply pay the tariffs ...steel prices in the U.K. are likely to be stable as continental steel uses a higher component of scrap for legislation reasons than UK steel producers so U.K. steel is more niche & higher up the value chain. Useful research here http://www.nass.org.uk/Publications/Publication4410/Atradius_Economic_Research_Trump_tariffs_Mar_2018_ern032202en.pdf
Thanks - yep, I will take a look at Tricorn (LON:TCN).
My morning smallcap tweet: The curse of H2 weighting.
Autins (LON:AUTG), Microsaic Systems (LON:MSYS), Minoan (LON:MIN), Hornby (LON:HRN), Harvey Nash (LON:HVN)
Autins Group (AUTG) The curse of H2 weighting: H2 refuses to meet guidance, no better than H1. "FY2018 revenues will be behind market expectations and profitability will be significantly below market expectations." Good news is it has now secured technical approval for its Neptune materials with key strategic European OEMs.
Microsaic Systems (MSYS) raises £5.5m at 2p, an 11% discount.
Minoan Group (MIN) sale of its travel business is proceeding, but more slowly than previously envisaged.
Hornby (HRN) replaces £6m facility with two totalling £18m. The smaller loan is from its largest shareholder, Rate for larger one is 2.5-3% over LIBOR plus non-utilisation fee of 0.75% of undrawn funds. What a chuffing liberty! The shareholder loan is even worse, 5% and 1%. "Whilst the Board believes it is unlikely that we will need to draw down on the entire availability, the Board is of the opinion that having a robust balance sheet is important to give our customers, suppliers and retail partners full confidence." Owing a lot of money if not a 'robust balance sheet'.
Harvey Nash Group (HVN) Q1 ahead of budget with gross profit growth 7%.
Morning all, on a seemingly-slow day, Flowtech Fluidpower (LON:FLO) 's agm statement sounds interesting - 'Following significant refurbishment at the Skelmersdale site, which was largely complete towards the end of 2017, the Group created a Shared Logistics Centre to support all subsidiaries, streamline logistics operations and identify greater product synergies for the Group. In addition, the acquisition of Beaumanor in March of this year immediately increased the Group's market share within the maintenance, repair and operation (MRO) market and gave access to a second warehouse based in the Midlands.' Normally 'consolidation' means a break in profit growth as with £G4M recently, right, only for it to bounce back loads if that consolidation actually works? Don't know anything about the sector but I'd be interested in reading people's views on this 'Super stock.' Cheers.
I like the update today. No change from strategy and plan from last update, things progressing well.
We won't see the benefits in this year's financial results, but next year should be pleasing.