Small Cap Value Report (Weds 12 Aug 2020) - WGB, BOO, HSW, APP

Good morning, it's Paul here. I'm late with the placeholder, as my alarm didn't go off. Apologies for the inconvenience.
Superb reports from Jack on Mon & especially Tuesday, covering a lot of ground. The only additional share I want to flag from yesterday, is a trading update from upmarket wallpaper & furnishings group, Walker Greenbank.
Today's report is now finished.
.
Walker Greenbank (LON:WGB)
Share price: 45p
No. shares: 71.0m
Market cap: £32.0m
(I'm long)
Walker Greenbank PLC (AIM: WGB), the luxury interior furnishings group, announces its half year trading update for the six months ended 31 July 2020.
Note the unusual H1 period end, 31 July. The next year end is 31 Jan 2021.
- Covid - significant impact in H1 (as already reported, so no surprise there)
- Improving trend since April, gaining momentum
- H1 sales down 28% on LY (strikes me as not too bad, in the circumstances)
- Core licensing revenues down 10% (OK)
- Third party order book good, and demand growing
- "Robust" liquidity - £19.5m headroom, including bank facilities (that's good, but it is not disclosed how much creditors have been stretched (e.g. VAT, payroll taxes)
- Outlook for H2 uncertain
- H1 results to be published in Oct 2020
My opinion - I think that's satisfactory. We all know H1 will be a write-off, due to lockdown, for this and many other companies,. Therefore the focus should now be on how well companies are recovering. WGB sounds as if things are improving, but the company has withheld the figures (e.g. it could have told us the month on month trend of performance, but decided not to).
All in all then, this is a bit of a nothing update, as a reader commented yesterday. Nothing much of concern, but inadequate information to properly ascertain how the company is performing. I'm not very happy about that.
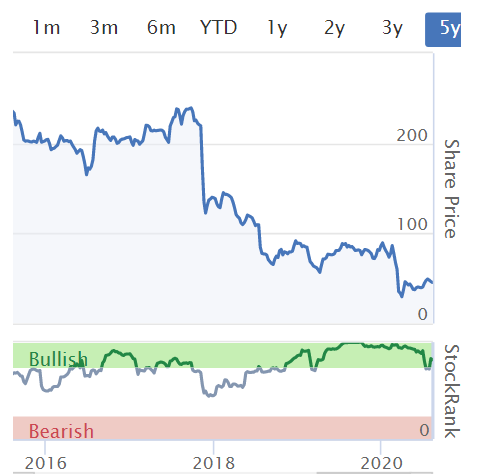
Overall, I don't think this update makes me want to buy more, or sell any. I'm happy to hold for hopefully further recovery. A few years back, this share settled around 200p, and seemed rock solid at that level. It's now under a quarter of that level, after a few mishaps. £32m mkt cap seems very low for a nice collection of brands, with great heritage, and licensing revenues from the historic back catalogue of e.g. William Morris famous designs. I wonder if it could be a bid target, at the currently bombed out valuation?
.
.
Boohoo (LON:BOO)
(I'm long)
Ethical funds
This has, so far, been one of this year's best trades. First there was a botched shorting attack from Shadowfall, which was largely nonsense, just regurgitating already-known points about family interests, etc.. Anyone paying attention would have already known that BOO is a family business with a listing, and yes there are some related party transactions, etc, all disclosed in the accounts. Attempts to sensationalise these issues haven't worked, as people already knew about them, and didn't care. What matters more to investors here, is that earnings have gone up about 10-fold in recent years.
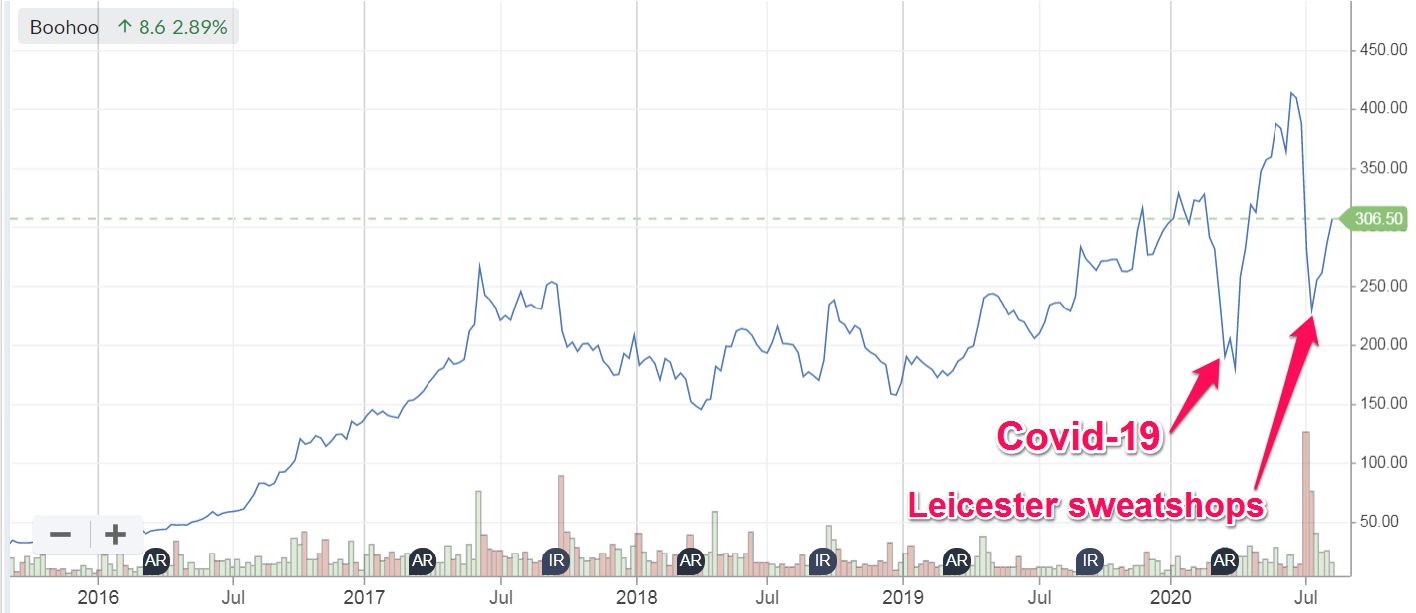
More recently though, the share price halved on renewed allegations of malpractice in BOO's Leicester supply chain. Something similar was reported a couple of years ago, yet the first time it had hardly any impact on the share price. This time it halved the share price. How come?
The reason is possibly that fund managers are more focused on ethical investing, with ESG (Environmental, Social & corporate Governance) being the latest thing. Those are fine things, and I very much like the focus on urging companies to improve the way they behave.
I've read that BOO's share price plunge recently was down to ethical funds dumping the shares at any price, since they didn't want the scandal-hit company on their list of investments. But why were BOO shares in an ethical fund to begin with ? Even some very basic research would have revealed that the fast fashion sector is ethically questionable - because throwaway fashion hurts the environment in various ways (fabric is wasteful to produce, then landfill is brimming with discarded clothes). Plus the rag trade generally (from top brands all the way down to Primark) is regularly dogged with allegations of sweatshop conditions for workers. As I've mentioned before, it's almost impossible for retailers to police how their product is made, because the supply chains go all around the world, and sub-contracting out work to unknown factories is widespread.
The end result of this, is that these ethical funds which were dumping BOO shares as low as 200p shouldn't have been in the stock to begin with, and they handed a lucrative slice of their clients' funds to other investors, on a plate. I filled my boots, as reported here at the time, at 209p upwards, and it's now 312p at the time of writing, as the hoo-haa subsided.
If I were an investor in an ethical fund, I'd be asking the fund manager serious questions about this. Why did he invest in a sector with widely known issues? And why did he dump BOO shares at half price, handing Stockopedia blog readers a fabulously profitable trade? I'm very grateful for how things panned out, but wouldn't be very happy if I'd entrusted a fund manager with my money, and he'd handled it this badly.
This issue could resurface of course, because there's a full, independent investigation underway at BOO. Although I suspect it would just move production to even lower cost factories, abroad. BOO is also planning on opening its own, model factory in the UK, to showcase what standards it supposedly wants from its suppliers. This is a really clever solution, because cutting out the wholesaler's margin (usually about 20-30%) means that BOO would be able to pay its workers minimum wage without any impact on margins. There's never been any issue with people directly employed by BOO by the way.
All in all then, I think if people are going to set up ethical funds, they should take a lot more care in checking out the sectors & companies they invest other peoples' money in, to avoid squandering client funds, as in this case. I do hope that readers took full advantage of this wonderful opportunity to be given some free money! One reader I'm corresponding with, put about 50% of his portfolio into BOO near the lows. So he's a lot happier with his YTD performance now. Let's hope he top slices, to reduce portfolio risk.
.
.
EDIT: I enjoyed the reader comments below about this. In particular, Pangit's daughter's short-lived boycott of BooHoo! Hilarious!
Hostelworld (LON:HSW)
Share price: 62p (down 1% today, at 09:45)
No. shares: 114.7m
Market cap: £71.1m
Hostelworld, a leading global OTA focused on the hostel market, is pleased to announce its interim results for the period ended 30 June 2020 [Paul: 6 months, H1]
They've given it one of those summary headers, which says;
H1 2020 in line with expectations; modest increase in bookings in recent weeks in line with the easing of travel restrictions. Accelerated delivery of Roadmap for Growth initiatives
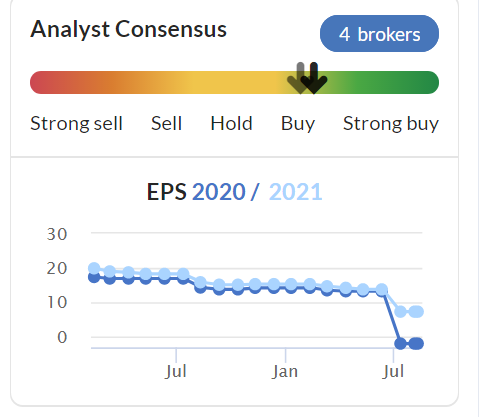
In line with expectations doesn't mean much, since expectations were slashed (darker line is the current year), now forecasting a loss of c.2p EPS this year;
Given what's happened with lockdown, it's probably not worth me poring through the detail of these interim results. All that matters are: strength of balance sheet, and outlook/current trading comments, so I'm generally focusing on that at the moment. Figures are massively distorted by covid, income from furlough, etc..
Refreshing my memory, I last looked at HSW here on 27 Mar 2020, concluding that its flexible cost business model meant that it should survive the covid crisis intact. In particular, large marketing spending can be easily reduced or switched off altogether, to conserve cash.
- H1 revenues down 69% to E12.0m
- Marketing costs slashed to E7.5m, down 54% on H1 LY - see what I mean about flexible costs? This is a huge advantage over travel agents with physical stores, which have limited scope to downsize costs in a crisis
- Hefty loss at EBITDA level of E8.3m (vs a profit of E8.9m H1 LY), but it says this is in line with guidance
Balance sheet - raised E15.2m (gross) in a June 2020 placing
Cash position looks very strong;
Closing cash position €32.9m (H1 2019 €25.4m) includes cash on hand of €29.4m and a €3.5m short-term financing facility
Although the balance sheet overall isn't as strong as I expected. I've reviewed the balance sheet & cashflow, and note that trade and other payables have risen to E18.0m (up from E11.1m 6 months earlier), which looks like it has perhaps stretched creditors? That's only a short-term benefit, and is likely to reverse in 2021, which together with ongoing cash burn, could mean the underlying cash position is not as strong as it looks.
Going concern note - worth reading. It concludes that the group has sufficient cash headroom for the foreseeable future.
Dividends - no cash divi, but a scrip (bonus issue of shares) divi is being paid. Why? I cannot see the point in this, as everyone's % shareholding remains the same. Maybe it wants to stay on the dividend list for some technical reason, who knows?
Current trading -
In recent weeks we have seen an increase in demand as travel restrictions have eased, and we are tracking slightly ahead of our Base Case scenario. This recovery started with very modest growth in domestic bookings in June, and more recently has progressed to very modest growth in domestic and short-haul bookings into Europe. Overall, we expect the pace of recovery to mirror changes in travel guidance in individual markets over the coming months, both positive and negative. Elsewhere, source markets in the Americas, Asia and Oceania continue to remain very depressed.
The obvious point is that fresh outbreaks of covid are happening all over the place, so nobody really knows when the travel sector will get back to normal. Also, are customers likely to want to stay in hostels, where social distancing is surely more difficult than in hotels? (e.g. multiple occupancy rooms, etc). Or are younger people more prepared to take the (minimal, to them) risk?
Overall, we are encouraged that our travellers are continuing to book Dorms in the majority of cases - with only a slight shift to date in accommodation mix towards Private rooms versus Dorm accommodation across markets.
H2 outlook - not good, for reasons outside their control;
Overall while bookings continue to trend well below normalised patterns, and assuming a gradual improvement in the macro travel environment, we expect the recovery to improve further in Q3 and Q4 2020, albeit net bookings will remain at significantly reduced levels when compared to 2019. Whilst this recovery is likely to take some time and the consumer environment will continue to be uncertain and challenging, the Board remains confident in the resilience and flexibility of our business model...
No full year guidance is given.
My opinion - this is the type of share that has been really whacked by covid, and buying/holding this share is really taking a view that covid will be defeated, and the travel sector returns to normal. that's obviously going to happen at some point, but the timing is uncertain. Meanwhile travel companies burn through cash. I prefer the online model here, to a physical travel agent.
HSW was a decently profitable business pre-covid, but was facing stiff competition. Therefore my worry is that it might be an also-ran in a sector dominated by e.g. Booking.com
It might be worth spending some time looking at HSW's growth plans, as there could be good value here, if it is able to become a growth stock again. Overall, I'm not convinced, so cannot see any reason to rush out and buy this share at the moment.
.
Appreciate (LON:APP)
Share price: 35p (down 13% today, at 11:51)
No. shares: 186.3m
Market cap: £65.2m
Appreciate Group (the 'Group'), the UK's leading multi-retailer redemption product provider to corporate and consumer markets, today announces its final results for the financial year ended 31 March 2020, and provides an update on current trading for the new financial year to date.
Subscriber markmac has asked me to look at this, and it appeared on my radar recently when Lord Lee wanted to chat to me about a share he likes, Air Partner (LON:AIR) , and he also mentioned Appreciate, my notes from our conversation are (this was in early July);
- Used to be called Park Group
- Hopeless acquisitions
- New CEO, with impressive strategy to focus on digitalising for smartphones
- Company seemed confident about the future, pre-covid
- Passed divi
- Encouraging trading update (in July)
Results for FY 03/2020 - impacted by covid in the final month, but in line with expectations in previous 11 months.
Profit before tax & exceptionals of £11.4m (down 9% on LY)
No divis, but will resume when prudent
Current trading/outlook -
Total billings* have progressively recovered as lockdown eases; 48 per cent down as at the end of Q1 in the new financial year compared to Q1 in the prior year.... Our continued investment in transformation, with changes to logistics and operations completed, is already showing significant benefits. Whilst our performance has been interrupted by the lockdown, we have seen trading start to recover and expect the resumption of growth founded on the more robust and scalable business model. "We are confident that delivery of the strategic business plan will be the bedrock of strong and sustained future growth."
Pension schemes - look fine;
No further contributions to either scheme are currently required. The next triannual valuation will be undertaken as at 31 March 2022 when the positions will be reassessed.
Pension deficits are getting worse in some cases, because of the move to near-zero interest rates. Offsetting that could be rise in asset values. But if the schemes are currently fully funded, then I imagine any possibly future funding requirement would be likely to be small, if at all. Although it's always worth checking the last Annual Report before buying any share with a pension scheme.
Forecasting/stress testing - there's useful information provided about this in the going concern section. In particular;
The actual results for quarter one are slightly ahead of the base case, with overall corporate and HSV billings decreasing by 48 per cent compared to the 60 per cent assumed. In addition, July trading is ahead of forecast. This gives the Group confidence that the base case scenario is currently the best estimate and minimises the likelihood of any downside risks modelled within the other scenarios.
From a going concern perspective, the monthly forecasting of the Group's free cash balance in this scenario is the key area for consideration, as liquidity is the principal going concern risk. The base case, before usage of the RCF, shows a negative free cash balance in July 2021, recovering by September 2021.
A further downside scenario results in negative free cash balance a month earlier, in June 2021. If cost savings were implemented, then the cash balance turns negative in Aug 2021.
Bank facilities are in place to handle these scenarios, so it doesn't sound a problem -
New financing
The Group has access to a recently agreed committed RCF of £15m, with an additional uncommitted accordion of £10m.
With the RCF in place, and having cancelled the final dividend payment, the directors consider that sufficient headroom exists to cover any negative sensitivities of COVID-19 in both the base case and downside scenario.
The bank covenants are then explained, good transparency there.
This is the most important bit, and sounds OK;
With the RCF in place, in line with the base case forecast, it is not envisaged that the Group will draw down on the facility until July 2021. The Group is forecast to be in full compliance with the three covenants throughout the twelve month period from the signing of the annual report and accounts, with sufficient headroom in place in both the base case and downside scenarios.
That all sounds OK to me.
Balance sheet - the most striking number is £102.7m cash, "Monies held in trust" - customer prepayments presumably. There are large creditors, presumably relating to the other side of the double entry of this customer cash.
It's not a brilliant balance sheet. The current ratio is only 1.05 for example.
NAV is £18.3m, but by the time we take off £5.6m intangible assets, and the £4.2m pension asset, then NTAV is quite modest, at £8.5m.
I would have preferred to see more asset backing here.
My opinion - I don't know enough about this business to form a view overall.
I'd prefer the balance sheet to be stronger - i.e. it might be better to keep divis low for a couple of years, to allow the balance sheet strength to build from retained profits.
I'll do some more research on the products & strategy, and we can look at it again when the next trading update comes out.
Here is the results video presentation, courtesy of our friends at PIWorld.
.
I'll leave it there for today, as the other things reporting today are very small, and don't interest me.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Air Partner (LON:AIR) (I hold)
For any interested parties, I draw your attention to the following paragraph in a recently published interview:
"When travel restrictions in Europe began to ease, Air Partner saw a boom in private jet travel demand as people regained appetite for travel.
Initially, it saw a 210 per cent increase in private jet requests for future flight bookings compared to last year. This grew to 321 per cent by June."
The 321% figure has not previously been disclosed by the company as far as I am aware, though a note of caution - in the last update (dated July 15th), the company said the Private Jet business was returning to pre-pandemic levels, so that's quite a contrast to the 321% figure from just a month earlier.
Cheers
A
SOURCE: https://www.mailonsunday.co.uk/money/holidays/article-8643455/How-does-cost-charter-private-jet-UK.html
abtan -
Thanks for that (I also hold). You say 'recent interview' but a google shows the information was given to the press on July 3rd see -
https://www.evaint.com/european-private-jet-travel-enquiries-up-321-this-june/
or even https://aviachartertour.ru/air-partner-soobshhaet-ob-rekordnom-kolichestve-zaprosov/ !!!
That was 12 days before the AGM trading statement to which you refer.
So probably the more significant event is that they didn't put out an early August press release boasting of the % increase in July cf previous year. That absence would fit with the 15/7 statement.
Shares in Walker Greenbank have ticked up over 25% since the trading update on 11 August, which I am sure will not have gone unnoticed by other Stocko subscribers. As to why I have no idea.
It is likely to be the meanderings of Mr Market. Alternatively it may be that investors have started to come round to the view, which I subscribe to, that the share price fails to reflect the value of the company's brands and archives, or that trading is perceived to have improved, or perhaps that Messrs Farrow and Ball or other parties have been having a conversation with management.
Who knows...answers on a postcard please!
Appreciate (LON:APP) appears to thrive when the economy is booming, in particular, when the interest rates are high, they milk the customer's money by earning interest from it. Current climate, no milking I'm afraid!
Hi maxistaxis,
Good point, thanks. I've just watched the APP results video. Another point this flagged re cash, is that the move from paper-based, to card-based and digital products, is absorbing cash, because the new (higher margin) products are regulated, whereas the old paper-based versions were not regulated. Hence why they needed to put the £15m (unsecured) RCF in place. That must surely restrict the ability to pay future divis somewhat?
I'd rather invest in companies that are throwing off free cash, not absorbing it.
Overall, I've decided against buying any Appreciate (LON:APP) for now, but will keep it on my watch list & report progress here in future SCVRs.
I think I'm correct in saying that voucher businesses benefit from some vouchers never being redeemed. People lose them, forget them, or just can't be bothered to go through the pallava of redeeming them.
The ONS recently picked me to randomly participate in a survey, and the letter included a £10 Love2Shop card. I spotted that this is a Appreciate company, so registered the voucher, which I have to say was not particularly easy, and I disliked having to provide my address & phone number. So presumably I'm now on a database, that Appreciate can monetise in some way?
Regards, Paul.
£ASOS has been one of the trades of the year, April 3rd at 1000, now over 4500. Only a few like SEA Ltd and Tesla have beat that share price increase this year.
I almost bought it at this time and instead went for Just Eat Takeaway.com Nv (LON:JET) which is doing very well too but the share price hasn't rallied quite so much, although, it never really had a depressed period like £ASOS and the risk:reward was better with £JET.
Hindsight can be a dangerous thing.
Re the Farrow & Ball gross Margins being part of their brand moat
You would be surprised how many people have confided in me that they get the F&B Colour chart then go to the local B&Q (other DIY Stores are available with the same service) to have it mixed to order. You can apparently take your favourite jumper and they will get you the paint to match
https://www.diy.com/ideas-advice/how-to-use-the-valspar-paint-mixing-service/CC_npcart_2100010.art
I live in the South of Spain and you can go into paint supply shops and get them to mix the F & B colours by name. They are already in their machine's database.
F & B paint haves very flat finish compared to other paints, but do not take knock or scrapes very well, yes you can get other paints mixed to match and not pay the premium in price.
Haha that's what I do!
Just published Empresaria (LON:EMR) H1 2020 results with Rhona Driggs, CEO & Tim Anderson, CFO. EMR is an international recruitment & staffing company across diverse sectors. The interview covers the operational & financial highlights and outlook.
Video or podcast
Also, Appreciate (LON:APP) FY20 results presentation with Ian O’Doherty, CEO & Tim Clancy, CFO. Although performance interrupted by CV19, trading has started to recover. Update on strategy, including the adaptation of the business to digital products & delivery.
Video or podcast
Separately, we have a Creightons (LON:CRL) webinar coming up on Wednesday 26th August at 11am. Bernard Johnson, Group Managing Director, Pippa Clark, Joint Deputy Managing Director & Paul Forster, Group Finance and Commercial Director, will present results followed by a Q&A. Register here.
Thank you for you take on Paul.
I sold my original holding back in Feb/March (mistake) at an average price of 231p. Never expecting to be able to re-enter but have now managed re-build my holding to the same number of shares at an average of 275p (including a top up today). I have expectations of 400p to 450p By the end of he year.
The only thing I would say on the ethical issue is that the same manager that dumped Boohoo (LON:BOO) also holds British American Tobacco Corporate Debt. Figure that one out.
Regards
Michael.
Good point Mike. These managers' actions re Boohoo (LON:BOO) appear to be show off rather than anything else.
Hello Paul...when you late last year and early this year started covering Boohoo Boohoo (LON:BOO), I foolishly thought.' I do not wish to invest in the rag trade, as I know nothing about it' however, your coverage following the 'ethics issue and alleged working practices' ..made me get off my biased backside and research the company...after, some time on research and a director link to Avacta £AVCT..in which I am long, I started buying into Boohoo (LON:BOO), and today it is the largest holding in my SIPP...I am pleased to report it is not the most profitable to date but the fundamentals of the business, especially ROA, ROCE & ROE, has made me realise that in future, I should not be so biased or so short-sighted about any share, as now I truly believe, Boohoo (LON:BOO) could be an outstanding long term holding..
Moreover, along with my wife, I looked in detail at all the brands on Boohoo (LON:BOO) s website and even though I know many here have quoted from their younger children, I spoke to my daughter who works for HL..and she told me she bought clothes from Boohoo (LON:BOO) and ASOS ...but the issue surrounding Boohoo (LON:BOO) made it one of the biggest hot topics amongst HL staff...and investors were piling into the company at the recent lows.
Finally, if anyone here thinks Boohoo (LON:BOO) is all about selling dresses for £6 to 16-24-year-olds, I suggest you look at the beautiful large ladies in the lingerie section on the Boohoo (LON:BOO) platform.....you will soon realise the guys and girls behind Boohoo (LON:BOO) are far far smarter than most people believe them to be..Thanks again and if you only give one similar write up once a year, it makes my subscription to stocko an absolute steal..I know you know this but I still do not think you get the credit you deserve, from some of the guys on here..I think you should be able to send one real good GET STUFFED message every week, as part of your effort here..Best.Tony
WGB Walker Greenbank
Worth comparing Farrow & Balls performance. Owned by private equity.
https://www.bournemouthecho.co.uk/news/18644712.farrow-ball-reveals-record-sales-coronavirus-lockdown/
and the accounts.....
https://beta.companieshouse.gov.uk/company/00999927/filing-history
How interesting, thanks. Farrow & Balls seems to make a far higher profit margin than Walker Greenbank (LON:WGB)
Looks like this could be a potential buyer of WGB perhaps? Strip out duplicated costs, provide more outlets for WGB's products, etc? Its accounts make WGB look rather sleepy.
Thanks for posting, useful comparative info.
Not sure. I would have thought paint was a rather different business to Walker Greenbank (LON:WGB) 's wallpaper and fabrics.
As I understand it, a lot of £WGB's sales go to trade outlets - many of which have been closed for some time. They could be in line for a stronger than expected rebound as these re-open. I don't hold, but thanks for your commentary Paul, I feel these are looking interesting.
Interesting spot re the comparison between Farrow & Balls and Walker Greenbank (LON:WGB) tufty.
F&B's Annual Report is more detailed than many you see for unlisted companies.
F&B describe themselves as making and selling paint and wallpaper, whereas WGB are wallpaper, fabrics and paint (but the don't seem to talk about the paint much) - but close enough a match to be interesting.
F&B's FY had only one week of lockdown in it, although they do say (credibly) that they were seeing impacts in the prior week.
They are not totally forthcoming with how they have traded through the lockdown (neither are the obliged to be), but they do say they have seen year on year growth in the "post balance sheet event review period" - which I take to mean from April to early July. This contrasts with WB being down by my estimate 60-70% during the full lockdown improving to -15% during July.
It looks like before the crisis WGB were doing less well than F&B, that was probably reflected in the pre crisis share price in the 70s-80s. WGB though had largely blamed the tough retail environment, which was credible, but F&B's figures suggest that it was a market in which it was possible to prosper.
It appears also that F&B have performed better during and coming out of the crisis.
We briefly touched yesterday on the fact that WGB's year on year numbers seemed to still be negative. I think a lot of this has to be out channels to market, WGB are accelerating their digital effort whereas it looks like F&B have already nailed it. Mention was also made in this thread of the point that a lot of WGB sales are through trade outlets that may have been closed during the crisis. I have also read conjecture that a significant portion of WGB products are deployed by decorators rather than DIYers (don't know if that is true or not, but it seems credible). Even now we are out of lockdown I think many people are still reluctant to have "trades" in their house.
I am encouraged to see that F&B seem to be seeing positives post the lockdown, even if WGB look set to lag that trend. It is also interesting to see that WGB's recent lack-lustre performance may have been more about the company than the wider market - but as I say that was probably already in the price, and when I say lacklustre I could have been kinder and said sluggish but resilient - I don't know when (even if) WGB last failed to make a profit - they certainly traded profitably through the GFC.
So whilst the comparison with F&B isn't flattering to WGB; I am actually encouraged rather than discouraged by what I read here. Maybe "read-across" is the reason for today's 9% rise for WGB?
As a bit of an aside it is interesting to read some of the comments suggesting that maybe F&B's products are not all they are cracked up to be at that there are ways to get better and cheaper. If so, you have to applaud their brand management, that they look to be growing nicely - they seem to have mobilised the "you get what you pay for" buyer mentality.
Anyway, for the record, I still hold WGB - but would be tempted by F&B if they were on the market.
Or maybe today's rise for Walker Greenbank (LON:WGB) , rather than being read-across from F&B was as a result of a positive note from Edison . It is actually a pretty poor analysis IMHO it hints at having a greater degree of insight into the situation, which may be true given they have access to management. But then completely misses the fact that the July number was improved by a major contract completion in the month, which I surmised yesterday is probably of the order of £1.5m revenue.
Hi All
what is the community’s take on Appreciate Appreciate (LON:APP)? Which seems to be well liked by John Lee
I'm looking at this one next!
Lucky you Paul needing an alarm to wake you up! That’s one problem you won’t have when you get to my age !! Agree with you on BooHoo and like you bought plenty at close to 200. Can only see further upside for this brilliant company and will certainly buy more on any weakness .
On Boohoo (LON:BOO) I was considering taking a position when the stock crashed. To test the water, I asked the opinion of my 22 year old daughter who was a regular user of Boohoo. She said that she would never use them again because of the slave labour issue. So I ended up buying a smaller position than I originally intended. Two weeks later, the postman is at the door with a Boohoo parcel for my daughter. I asked why she had used Boohoo after stating she would never use them again. “But their stuff is so pretty and cheap ......”
Pangit
that is the Boohoo trade in a nutshell
Re Boohoo (LON:BOO) - they're all doing it!
Just heard ad on the radio for Aldi. Back to school uniforms:- 2 x Polo Shirts plus 1 x Sweatshirt plus 1 x Pleated Skirt or pair of trousers all for £4.
OK, maybe there's a certain element of this being a loss leader but even so.
AND the mindset of the young !
Paul, I understand too big strictly, but in one of your favourite areas, Asos (ASOS:LON) FY guidance of revenue +17-19% and PBT £130-150m implies operating margins again above 4.0% and last quarter revenue up low/mid 20s. Well ahead of guidance and surely broker upgrades to follow. Margins up due to lower returns profile due to mix and customer behaviour
Naughty Paul, but understandable! It's so hot that it's hard to fall asleep at night, and hard to wake up in the morning... Seems like these spells of 35 degree days and tropical nights are getting more and more common!
Indeed. I took delivery of an industrial fan yesterday, and today a small portable aircon unit is arriving. Just in time for the thunderstorms! :-)
Good morning Paul. I wonder if you might have time to cast your eye over Checkit (LON:CKT) trading update this morning. My take is one of cautious optimism. Recurring revenues inched ahead from £1.1m (Q1) to £1.2m (Q2) which appears reasonable for May - July of the current crisis. Non-recurring revenue over the same timeframe declined which seems reasonable too given that installation and project based revenues would understandably be hit by the shutdowns.
I'm happy that "..the Board is continuing to rely on its recurring revenue as its base case for internal planning purposes." This seems to strike a suitably conservative approach whereas in reality, one might expect that as businesses slowly return to some kind of normal, there may be some pent up demand for Checkit's services.
Like many holders here, I too am in this for my strong conviction in Keith Daley who is very much aligned with my interests having a 23% holding which he increased in July this year.
A dilution looks unlikely for the foreseeable with cash at 31 July 2020 standing at £13.4m down from £14.3m at the end of January albeit with a £0.5m uplift from a loan repayment.
I'd be interested to hear if anyone has knowledge or experience of using Checkit's services?
Hi johnsmith68,
I've had a quick look at Checkit (LON:CKT) trading update, and unfortunately there's not really anything much in it that I can interpret. It just tells us detailed sales figures for Q1, and Q2, and says covid impacted performance. The stand out feature is the cash pile, which looks large relative to market cap.
There's not anything more I can add.
Regards, Paul.
Thanks for looking at it Paul and thanks again for another sterling effort today on the SCVR.
We are organising a webinar for £dgoc today at 4pm. HY results on Monday were well received. Ask your questions to management
- how is decommissioning managed
- how are costs kept so low
- what plans for further dividend growth
- whats the potential for more M&A
https://us02web.zoom.us/webinar/register/4815957753589/WN_qT9gtei1SVOy4CQVQafkTw
Increasingly I feel I am living in a world where people are reading two newspapers to me at the same time - one is all doom and gloom. The other is the business pages where large swathes of the business world are reporting better than expected results - some even better than pre lock down.
For example this morning one side is all about recession and unemployment, offset by the news that the housing market is buzzing upwards, and the majority of company results are seemingly positive.
I am finding it very difficult to know what the medium term is going to be.
Agreed and I think the agenda on one side is to promote the doom and clue. The other is the human instinct for growth and recovery. It depends on which side of the fence you sit. Im glass half full although I know its hard to be positive what else is there? We are being presented with investment opportunities that are generational in their rarity.
I think it's a question of weighting the news by employee significance.
UK construction (including housebuilding) ought to continue to enjoy growth especially if the government sponsors an Infrastructure Plan.
However construction employs less than 5% of the total UK workforce.
By contrast, retail/wholesale/food service & hotels employ in excess of 22% of the UK workforce. These sectors are likely to experience the largest reductions in employment as the furlough scheme is tapered in the next two months.
Data from the ONS
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
Hi HollandSmith,
Formatting of your announcements is excellent now - well done!
Hi HollandSmith,
Fantastic, this is really helpful (along with MrC's long-running quickfire summaries). Sorry the placeholder was late today. I remembered to plug in my phone for a recharge last night, but didn't notice it was switched off, doh!
Regards, Paul.
many thanks HollandSmith-a very valuable summary each day-much appreciated.
Good morning Paul
Views on Northbridge Industrial Services would be interesting to hear. Promising update, impacted by covid but moving in the right direction. Competent management who have experienced tough trading before. All in all moving in the right direction. I hold and will look to add.
Jonno: Northbridge Industrial Services: LON(NBI)
Be very wary about being caught on the hook by this one. There are many from the Longville days who would dispute the use of the word competent. When did this business last declare a profit?
A really key component of running a successful business in the rental sector is having up to date and reliable equipment to rent to customers.
At 31 December 2014 NBI plant was 27% depreciated - at 31 December 2019 it was 57% depreciated: indicating an aged and increasingly decrepit rental fleet.
An old dog up to his old tricks.
Bonitabeach
No position.
Hostelworld (LON:HSW) announces this morning that instead of a dividend it will 'issue new ordinary shares, by way of bonus issue, to shareholders based on a value of 1.0 € cent per share and subject to shareholder approval.'
I'm a bit of a novice still but isn't this a bit of a gimmick as it will just mean I hold more shares but with the same total value given everyone will be in the same position?! I'm keen to know if I've misunderstood.
Sounds like a scrip dividend to me. And yes, I agree.
But the shares should go up because of the cash 'saved' by not making a distribution. They then reinvest the cash in the business for higher return. A fallacy is that most returns from shares comes from reinvestment of dividends. They come from reinvestment of retained earnings and hence capital growth. Terry Smith explains this better than me on the Fundsmith website.
But the shares should go up because of the cash 'saved' by not making a distribution.
But as there will be more shares in issue there should be no effect on SP on average, other than in some special situations, perhaps, where the cash can be seen to have a clear use that will disproportionately improve profits.
If a shareholder believes they can make more money by investing their money in different shares, why are they holding the stock in the first place?
If a shareholder believes they can make more money by investing their money in different shares, why are they holding the stock in the first place?
That's moving away from the point I was responding to (which was the short term impact of a scrip only div on the SP), but following that through would suggest that you shouldn't invest in shares that pay dividends at all, which is a subject in itself. There are shares I hold that I would be very unhappy to see paying out cash, as they need/have good uses for it . But I hold others, generaly more mature, that I'm very happy to accept cash from as dividends.
Regarding bonus shares in lieu of dividends - no, you have not misunderstood - everyone ends up with the same percentage stake in the company. Bloomsbury Publishing (LON:BMY) also did this recently and the reason is pure vanity - the company thinks that they can label this a dividend so that in years to come they can proclaim to the faithful that they never cut the dividend, not even through the pandemic of 2020/21.
Who gains? the advisers, lawyers and registrars with extra fees
Who loses? Small shareholders like you and me with an odd number of shares meaning that if we are entitled to some fraction of a share we lose out. In the case of Bloomsbury I am entitled to X.95 shares which means I effectively lose 190p with the shares at 200p.
My morning smallcap tweet:
Wameja (LON:WJA) Hawkwing (LON:HNG) Impact Healthcare REIT (LON:IHR) Accsys Technologies (LON:AXS) £7DIG Checkit (LON:CKT) Northbridge Industrial Services (LON:NBI) Grafenia (LON:GRA), Hostelworld (LON:HSW)
Wameja (WJA) Homesend pays back €2.5m loan to WJA. [SP=5 Cap=97m]
Hawkwing (HNG) expects move from AIM to main list on 26 Aug. [SP=0.4 Cap=1m]
Impact Healthcare REIT (IHR) sells The Shrubbery care home in Worcester to a developer for alternative use for 24% over book. Have all the Knights Who Say "Ni!" died now? [SP=103.5 Cap=330m]. I hold.
Accsys (AXS) forms JV to construct and operate an Accoya® wood production plant to serve the North American market. Accsys' share of the initial engineering and design costs c. €1.5m. [SP=90 Cap=148m]
7digital (7DIG) contract with Triller "to power the world's fastest growing social music video app with its Music Platform-as-a-Service offering...Triller is an AI-powered app that allows users to choose their favourite music to create auto-edited, professional-quality videos which can be published on the app or shared via social media channels." [SP=0.59 Cap=15m]
Checkit (CKT) guides H1(July) rev up 2.3% normalised (as if Checkit UK had been owned in prior period). Recurring rev up 23%. [SP=37.61 Cap=23m]. I hold.
Northbridge Industrial Services (NBI) guides H1(June) rev down 5%. Fall mostly offset by a reduction in operating costs and around £0.2m of gov't support so expect the overall trading result similar to 2019. [SP=85.75 Cap=24m]
Grafenia (GRA) FY. Outlook "With the restructuring activity undertaken in this financial year, and the financial support secured through the bond issue and CBILS loan, we believe we have secured the financial future of the business and have the resources to execute our expansion plans. Accordingly, the Directors continue to adopt the going concern basis." [SP=6.5 Cap=9m]
In line: Hostelworld (LON:HSW)