Small Cap Value Report (Weds 21 Nov 2018) - SOS, BON, IMO, ECK, SRT, SOLI, CRL, JDG, MAI, GMD

Good morning, it's Paul here.
Today's report is a mixture of backlog from yesterday, and reports published today. Some was written last night, and some today, so that's why it might sound a bit confusing in places.
Sosandar (LON:SOS)
Share price: 37.0p (up 8.8% today)
No. shares: 116.2m
Market cap: £43.0m
(this is my largest personal shareholding)
My main focus on Weds morning will be interim results from Sosandar (LON:SOS) (which is my largest personal shareholding). We already know from the 10 October 2018 trading update what to expect, in terms of H1 revenues (£1.84m, organic growth of a stunning 407% Y-on-Y), and an excellent gross margin of 55%.
However, it's the most recent outlook & current trading comments which will be key. I'm anticipating strong current trading, for 2 reasons;
1) In the last update, it said that September 2018 had seen record sales. That is when new season autumn/winter stock hits the website. So if the initial sales are strong, then you can be sure of a successful season overall (to early January), because the product designs have hit the nail on the head. Fashion retail is mainly about the product. This tiny company is producing better womenswear ranges than Marks & Spencer. Think about that for a moment.
EDIT: results confirmed in the narrative, that October was a new consecutive record sales month. As you would expect for a rapid growth company. End of edit.
2) I monitor the Sosandar website every day. A lot of "new in" styles are selling out (in some sizes) within days of hitting the website - which augurs well for current trading. Social media followers are small, but growing fast on the key ones - Instagram & Facebook.
I wrote the above last night.
For anyone interested, here is my initial take on the interim results this morning. More later;
Figures and current trading are in line with management expectations. I queried on a phone call this morning if management and market (i.e. house broker forecast) expectations are the same thing? Yes they are.
In my opinion, they should beat the full year (FY 03/2019) revenue forecast of £3.9m (Shore Capital), because Oct-Dec is a huge seasonal peak in womenswear. EDIT: Shore Capital has today upgraded revenue forecast for this year by 6% to £4.15m. That still looks conservative to me. Shore has also increased its admin costs forecast from £5.6m to £5.8m, which overall leaves the forecast loss for this year unchanged at £3.5m.
Forecast for next year (ending 03/2020) is revenue of £9.5m, and a loss of £1.6m.
Then 03/2021 the forecast revenue is £19.5m, and a maiden profit of £2.1m. I'm working on the basis that this is just the start, of what could become a very much larger business longer term.
H1 revenue is already £1.84m, which included quieter summer months when it was too hot.
So broker forecast implies only £2.06m revs in H2, which is crazily low given that Oct-Dec should show a massive uplift. By my calculations, revenues should be £4.5m to £5m for the full year. At 55% margins, that's excellent operational gearing. Then you're probably looking at £10m+ next year, and breakeven-ish.
Roll the numbers forwards, with triple-digit % revenue growth, and 55% gross margins, and you arrive at startling profitability in 2-3 years. There's no guarantee that will happen of course, but the company is off to an excellent start (it's only been trading for 2 years, remember).
Very encouraging commentary today from Sosandar, including positive noises about sales of current season styles. That augurs very well for peak seasonal trading this autumn/winter.
Gross margin of 55% is astonishingly high for such a small business.
When it IPO'd, I questioned management on how realistic it was to target £3m revenues this year (original forecast), which looked a tall order. They said they were confident it could be done. Now we're heading for a substantial beat against the original forecasts.
It's all going extremely well. I'm glad they did £3m placing now, as it removes any concerns about running out of cash.
I don't think there's much more to add about Sosandar. I've had a quick chat with management this morning, and I'm happy with everything.
The numbers & commentary in today's RNS are self-explanatory, and well worth reading. In my view this stock is likely to be a multi-bagger, taking a long-term view. It's all about backing a highly competent, experienced, and hard-working management team.
Firstly, here are some additional company updates from yesterday:
Bonmarche Holdings (LON:BON)
Share price: 84p (up 3% yesterday)
No. shares: 50.0m
Market cap: £42.0m
Bonmarché is one of the UK's largest women's value retailers, focused on selling stylish, affordable, quality clothing and accessories in a wide range of sizes, via its own store portfolio and online.
Here are the financial highlights, with my commentary on the yellow items below;
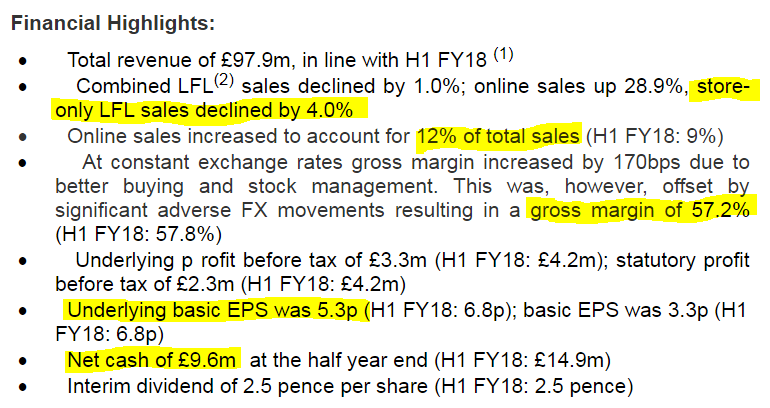
I like the disclosure of store LFL sales, online, and the blended total. That's useful information, in a good format, which I hope become the norm for other retailers reporting.
Online sales at only 12% of the total, is much too low, in my opinion. Although it is growing. The best retailers should be achieving nearer to half their sales online.
Store revenues down 4% LFL is not good, because as we know, many store costs are rising (especially staff wages). The key to retailers surviving, is cost flexibility - in particular property leases being short, hence allowing the retailer to walk away from loss-making, over-rented sites. BON is in a favourable position;
Following the major restructuring of the store estate in 2012, including the rebasing of rents, we have continued to maintain a tight control over property costs.
Twenty four stores had lease renewals or rent reviews completed during the period, for which we secured an average rent reduction of 15% plus an incentive with a cash equivalent value of £13k.
The average term to expiry (or the next break) is 3.6 years, which therefore allows us to retain flexibility across the store estate.
The worry for most retailers, is that over time, store sales gradually reduce, to a point where ultimately hardly any stores might end up being viable. What happens then?
Gross margin of 57.2%, despite forex headwinds, is good.
Seasonality - last year H1 & H2 were about the same for profits. Therefore achieving underlying EPS of 5.3p in H1 suggests that it might do c.10p EPS for the full year, ending 31 Mar 2019. That's above the 8.5p broker consensus forecast shown on Stockopedia.
Outlook - the company helpfully gives profit guidance for the full year (I so wish all companies would do this, it would make life much easier for investors);
Whilst online sales have continued to show strong year on year growth, as reported, store LFLs have remained weak, and traditional autumn/winter categories have had a slow start to the season. Providing that sales during the key Black Friday through to Christmas trading period meet expectations, the Board maintains the guidance published in September, being that the underlying PBT for the Group for FY19 will be approximately £5.5m.
(by my calculations, £5.5m adj PBT equates to about 9.0p EPS)
A slow start to the autumn/winter season is bad news. That suggests the product ranges have not sufficiently appealed to customers, which usually leads to a slow Xmas season & increased discounting, hence lower margins, to clear slow-moving lines. Therefore I imagine the next trading update is likely to be subdued.
This is reinforced by a much higher inventories figure of £28.2m at 29 Sept 2018, up from £23.5m a year earlier - which suggests there could be a lot of slow-moving stock in the shops.
Net cash - of £9.6m is healthy, but down quite a bit on a year earlier (£14.9m) - increased inventories looks to be the main culprit.
Balance sheet - is healthy, so no solvency issues.
Cash generation - is still good. Remember that retailers have quite large depreciation charges, so add that back, and EBITDA is not bad.
Dividends - the interim divi of 2.5p is maintained. The forecast yield of 9.5% is telling us that the market thinks the big divis are not likely to continue for much longer.
My opinion - although profits are down, as noted above, the company should deliver about 9.0p EPS for FY 03/2019. I make that a PER of 9.3 - not bad considering the balance sheet is also strong, with net cash.
The big problem here, as with almost all retailers, is the direction of travel. Store costs are rising, which need to be offset with rent reductions. BON looks OK in that regard. However, store LFL sales are likely to keep falling, relentlessly. This is a terrible headwind for retailers, as more business leaks away to online competition. BON's 12% of total sales online just isn't enough, although it is rising.
The slow start to autumn/winter season, and much higher inventories, suggests to me that there could be a profit warning in the next couple of months, as Xmas sales seem to be set up to disappoint.
BON is likely to be a survivor on the High Street, as it's still decently cash generative, and has sound finances. So its best hope is to pick up business from competitors going bust. If that can be combined with ditching loss-making shops on lease expiry, and canny negotiation on new, cheap & short leases, then I could see BON continuing to exist.
Whether it will remain cash generative enough to continue paying such generous divis, is doubtful.
Overall, I cannot see why anyone would want to buy this share in preference to the much higher quality, but only slightly more expensive (on a PER basis) shares in Next (LON:NXT) .
IMImobile (LON:IMO)
Share price: 291p (down 0.7% yesterday)
No. shares: 65.3m
Market cap: £190.0m
IMImobile PLC, a cloud communications software and solutions provider,today announces its consolidated interim results for the six months ended 30 September 2018.
Interim results look good, at the adjusted level. Statutory profit is modest, as it's weighed down by acquisition-related costs. Basic EPS is a small loss, of -0.2p, but adjusted EPS is positive at 6.6p (fully diluted) for H1.
Outlook - solid;
We have had a strong start to the second half and remain confident about the Group's prospects for the full year. We expect full year results to be in line with management expectations."
Balance sheet - I'm not keen on this. As with a lot of acquisitive groups, the balance sheet is becoming top heavy with intangibles. So NAV of £56.2m becomes NTAV of negative -£16.3m. That's a deal-breaker for me, as I rarely invest in companies with negative NTAV.
My opinion - I've met management of IMO twice in recent years, and was very impressed both times. The client list is very impressive too - big companies, which rely on IMO for important IT services.
I'm less than keen on the weak balance sheet. Also, a forward PER of almost 20 looks fully priced. I don't have the knowledge to predict how this company might perform in future. IT can be very fast-moving, and I don't have the skills to analyse it further, hence will pass on this one.
Quick comments from yesterday's announcements, to finish off;
Eckoh (LON:ECK)
Interims to 30 Sept 2018.
Revenue actually down 2%, and adjusted EBITDA down 15% to £1.6m in H1.
Company says this poor performance is in line with Board expectations. IFRS 15 accounting rule changes have had an impact. Business has a pro-H2 seasonality.
Lots of upbeat comments about order intake & outlook. "Record visibility for second half".
My opinion - I struggle to see how this company is worth £94m.
The valuation hinges on expectations of future growth, rather than its unimpressive historic track record of low profitability.
SRT Marine Systems (LON:SRT)
Half year report
More of the same - poor interims, and promises of jam tomorrow.
Shareholders have been extraordinarily patient here.
The company seems to inherently have almost no visibility on sales & profits.
Solid State (LON:SOLI)
Interim results
Look OK - revenue up 4%, adjusted PBT up 6%.
Divi yield is about 3.8%, and interim divi up 5%, well covered by earnings.
Most noteworthy is the strong order book - up 46% to £29.4m at 31/10/2018.
The Board is confident that the prospects for the remainder of the year are positive and it expects the Group to deliver a strong performance in the second half of the year.
In addition, it believes the Group is well positioned for future growth and to deliver enhanced value for the Company and its shareholders.
Balance sheet is strong.
My opinion - worth a closer look. This looks to be a modestly-valued company, which is performing well.
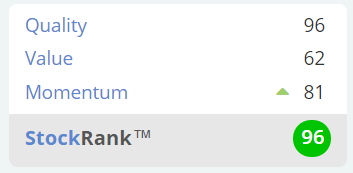
Stockopedia approves too, with a "Super Stock" classification, and excellent StockRank;
That concludes yesterday's updates. On to Weds company updates below;
Creightons (LON:CRL)
Share price: 31.0p (up 14.8% today)
No. shares: 62.4m
Market cap: £19.3m
Creightons is a manufacturer & distributor of toiletries & fragrances.
These interim figures look good to me;
- Strong revenue growth - up 34% to £22.3m
- Profit before tax up 44.4% to £1.38m in H1
- Diluted EPS is up an even higher percentage, up 65% to 1.8p - this is flattered by a reduced tax charge
- Modest divis, unchanged on last year
Balance sheet - overall looks OK to me.
NAV is £10.8m. Only £0.7m intangibles, so NTAV looks sound at £10.1m.
Working capital - current assets of £17.7m, less current liabilities of £9.6m, gives a current ratio of 1.84, which is healthy. There are no long-term liabilities, which is excellent.
Net debt of £1.96m is worse than last year - the reason being significant increases in working capital - i.e. inventories & receivables. That's inevitable when revenues rise considerably, as they have. So I don't see this is a problem. When a business grows its revenues, the balance sheet effect can be negative. This is because two assets rise, namely inventories & receivables, but only one liability rises - trade creditors. Therefore a growing business will usually see cashflow tighten during the growth phase, requiring additional drawings on bank facilities.
Outlook - I may have missed it, but cannot seen any reference to the outlook for the full year.
The commentary sounds positive in tone, and includes this comment;
The Board and I believe that this half year's results including investments in resources and capabilities places the Group in an excellent position to take advantage of any opportunities that may arise.
My opinion - it's difficult to value this share, because I can't find any broker forecasts.
Taking a broad range, if current year EPS comes out between 3-4p, which seems likely, then at 31p share price the range would be PER of 7.8 to 10.3 - that looks good value for a well-financed company, achieving impressive uplift in sales & profit.
It's a similar valuation to Swallowfield (LON:SWL) which I also wrote about here recently. SWL is about double the size & market cap of CRL, so will be more liquid. Also it pays a better divi yield. However, CRL is growing faster. So I can see attractions to both shares.
Judges Scientific (LON:JDG)
Share price: 2,330p (up 7.4% today, at 12:50)
No. shares: 6.19m
Market cap: £144.2m
The Board of Judges Scientific, a group involved in the buy and build of scientific instrument businesses, updates shareholders and the market on the Group's trading performance in the financial year ending 31 December 2018.
We don't see many of these at the moment - out-performing expectations;
Trading has remained strong since the publication of the interim results and the healthy order intake communicated at the time of the results has continued since the beginning of the second half.
As a result, the Board expects Earnings per Share for the full year ending 31 December 2018 to exceed current market expectations as increased in September.
The trend on broker consensus forecast EPS has been smashing this year, and it will be going up again after today's update;
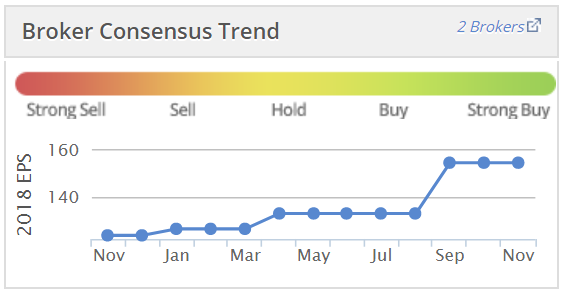
There's a broker update on Research Tree, which shows a 12% increase to 172p adj. EPS this year. The PER is 13.5 - that looks excellent value, for a nice quality group of businesses.
Balance sheet - I've quickly checked the most recent one, and it's fine.
My opinion - what I pity I don't have any spare cash, as I'd be tempted to buy today if I did.
The recent market sell-off is throwing up some good opportunities, and I reckon this could be one of them. DYOR as usual please!
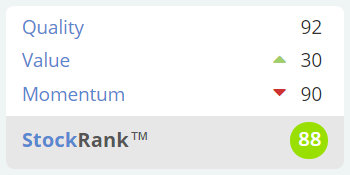
Stockopedia likes it too - a high StockRank, and "High Flyer" status;
Maintel Holdings (LON:MAI)
Share price: 455p (down 25% today, at 14:04)
No. shares: 14.2m
Market cap: £64.6m
This seems to be an IT and telecoms services provider. We had a profit warning yesterday from another company in that sector, KCOM (LON:KCOM) - so I wonder if this is a general sector slowdown?
What's gone wrong?
- The sales mix has shifted towards longer term, recurring revenue projects. Away from shorter term projects where profit would have been recognised faster
- Projects delayed, now completing in 2019, not H2 2018 as anticipated
Quantifying the problem - this is very helpful in giving market guidance;
As a result,the Board now expects Adjusted* EBITDA for the year ended 31 December 2018 to be in the range of £12m to £12.5m (2017 £10.9m).
I'm really not a fan of adjusted EBITDA. Adjusted profit is the figure I much prefer. Adjusted EPS is better still as it's then quick & easy to work out the revised PER.
There's a broker update available today, which has revised down 2018 adjusted PBT by 24% - quite a hefty downgrade at this late stage in the year. Next year's forecast comes down by 21% too.
Adjusted EPS forecast for 2018 is now 63.2p - a PER of 7.2 - apparently cheap. The catch is;
Balance sheet - it's horrible. Too much debt, and NTAV is heavily negative, at -£43.3m - that's a deal-breaker for me.
Liquidity - I thought there must be a data error when I saw that the quoted market price is 410p Bid, and 500p Offer! Our of curiosity, I asked my broker for the real prices, which are 435p Bid (in size of only 1,500 shares), and 475p Offer (in only 250 shares size). What's the point in having a listing, if the liquidity is so bad?
My opinion - the balance sheet weakness rules out this one for me.
I wouldn't invest in this sector either. So definitely not for me.
GAME Digital (LON:GMD)
Share price: 27.3p
No. shares: 172.9m
Market cap: £47.2m
(at the time of writing, I hold a long position in this share)
GAME Digital plc ("GAME" or the "Group") today announces its final results for the 52 week period ended 28 July 2018 (the "period").
This company operates the "GAME" retail stores in the UK & Spain, which sell computer games, consoles, and accessories. The business model is also transitioning into a roll-out (JV with Sports Direct) of the "BELONG" social computer gaming, where customers pay per hour to play computer games, sometimes competitively, in competitive leagues, etc.
A key point to think about with this share, is that the bulk of its retail leases expire or have expired in 2018. Therefore a large scale closure/relocation/renegotiation of retail sites is in progress. This presents both opportunities, but also risks.
The main reason why this share appears to be so cheap, is that the stock market is discounting a possible short lifetime of the business. Are downloads going to take over from selling physical gaming discs, rendering GAME shops redundant, in the long run? The jury's out on that, but there still seems to be a lot of business available in selling new & secondhand computer games.
Looking first at the P&L;
Statutory results -
- Revenues of £782m (flat against LY) - still a substantial business, even though market cap is only £47m
- Loss before tax of £-7.4m (improved from £-10.0m in prior year)
- Basic loss per share of -6.0p (prior year: -7.1p loss)
- Net cash £58.7m (up from £47.2m a year earlier) - NB. the net cash balance is higher than the market cap, very unusual
Adjusted results -
- Adjusted EBITDA positive at £10.1m (up 26% vs LY)
- Core retail EBITDA fell from £14.0m to £12.2m. The reason total EBITDA rose, was due to eliminating £3.9m of prior year losses in the non-core eSports division. Note that Spain generates nearly all the EBITDA, with UK around breakeven.
- Adjusted loss before tax of £-3.5m (improved a bit compared with prior year of £-4.3m)
My interpretation of the above is that it seems surprisingly resilient, given how bombed out the share price is.
Current trading - again, surprisingly resilient;
Though early in the year, the Board remains cautiously optimistic with the prospects of the Group in the future.
Trading for the first 14 weeks of the year has been ahead of the prior year, with Group Retail GTV up 4.5%. GTV in both UK and Spain are up on last year 6.6% and 1.7% respectively in local currencies reflecting the benefits of a stronger performance from new game releases this year.
BELONG pay-to-play performance has been encouraging for the first 14 weeks, up 50% year-on-year (excluding the two new arenas).
A 6.6% growth in transaction value in the UK seems remarkably good, given that the stock market has pretty much written off the prospects of this company, valuing it below its own net cash. BELONG up 50% is also very encouraging.
Cost savings - seem to be keeping pace with the reduced gross profit - note that whilst revenue held up, gross profit fell from £205.1m last year, to £196.2m this year. Offset by cost savings;
During the period the UK retail business delivered cost savings of £11.4 million, as we continue to take advantage of our flexible lease profile to renegotiate leases, relocate or close stores.
In addition, store operating efficiencies, procurement benefits and a reorganisation of our head office have also realised further savings this year.
It's clear that the lease expiries are absolutely key here. If the company did not have this flexibility, then I imagine it would be heading quickly towards insolvency - a CVA or a pre-pack. As the leases are mostly coming up for expiry or break (average 0.9 years), that's not necessary here, a key advantage;
Our UK business has an average lease length to break of 0.9 years and we have over 200 potential lease events by the end of 2019.
We have achieved savings of 42% from leases renegotiated in the year and, as at the year end date, we have a total of 25 stores on zero rent and 99 stores on flexible arrangements, usually a three-month rolling break option.
The store estate in Spain is continually reviewed and a low average lease exit period of one year gives flexibility to move to better stores in existing locations and to open in new locations.
BELONG update - at the moment, the stock market seems to be attributing little value to the potential for the new format BELONG stores - which combine the traditional GAME store, with a basement or mezzanine level gaming arena;
"BELONG, the Group's esports and experience-based gaming proposition, remains core to our transformation strategy and we continue to expand the business through the opening of larger BELONG gaming arenas while improving our GAME Retail offer to fully capitalise on the strong growth potential in the esports market.
The first of these larger BELONG arenas has opened and trading results to date are promising. Planning for the further rollout of arena locations is well advanced."
The only issue I can see is that Sports Direct has its hands full currently, dealing with House of Fraser. So I'm not sure whether BELONG will be much of a priority for SD?
Cashflow - was positive £11.7m. Note this came from disposal proceeds of £14.9m + £3.2m, which are obviously one-offs. Taking into account future capex, the group probably is not going to be generating any more positive free cashflow any time soon.
Debt facilities - despite having net cash of £58.7m at the balance sheet date, the group also had undrawn borrowing facilities of £169m. This suggests there must be large cash drawdowns at peak trading periods, e.g. to buy all the stock needed for busy Xmas trading.
Dividends - have stopped, as it's prioritising growth capex for the new BELONG sites.
Going concern - says that the group has adequate finances to continue trading for 12 months, as is usual in these statements. There is also a "Viability statement" which confirms that the group should be able to continue trading for 3 years. This is something new to me. It looks like a new regulatory requirement.
I've googled it, and this regulatory reference is to the UK Corporate Governance Code. Some bedtime reading there for anyone who likes reading up on rules & regulations.
Balance sheet - looks healthy to me.
NAV: £98.5m, less intangibles of £24.0m, gives
NTAV: £74.5m, well above the £47.2m market cap.
There are negligible long term creditors.
Working capital - a current ratio of 1.61 is very good.
Overall, there looks to be no issue at all with solvency - the group is well financed. Borrowing facilities are only for peak trading, and are undrawn at year end. Banks love that type of lending, as it's very low risk.
My opinion - I like this. The legacy business is holding its own, and has unique flexibility to vacate loss-making sites, due to very short leases.
BELONG seems to have promise, and could become a decent format, ultimately rebuilding profits, if it works out.
The valuation is extraordinarily cheap, and more than backed by net cash.
Yet investors are showing absolutely no interest in the company whatsoever. Sports Direct is probably too busy to think about buying it out completely.
Maybe the share price will just continue to languish? Yet I remain of the view that there's interesting potential value in this share, longer term, if BELONG works.
All done for today! I'm handing over now to Graham for Thurs & Friday.
I hope to see lots of you at Mello London on Monday & Tuesday :-
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Maintel Holdings (LON:MAI)
This share taught me about liquidity, when I realized that my trading alone was setting the price. I now add capitalization, spread and volume to my filters to remove the illiquid from my consideration.
Interesting Sosandar investor presentation here by Julie Lavington and someone from the Finance team - https://www.youtube.com/watch?...
Re Sosandar (LON:SOS) "high" level of returns, I remember it previously being stated that every retailer has a slightly different approach to the sizing of women's clothing. Hence, for new customers, of which Sosandar (LON:SOS) will have a high proportion given their strong sales growth, the level of returns is relatively high... ...declining once customers get used to the sizing.
Having listened to the live Web cast for Creightons (LON:CRL) today at PiWorld I am as impressed as I was after the FY results. The 3 presenters especially Pippa answered all questions with an abundance of frankness. It refreshing to see a company giving share option and bonuses to ALL staff. Finance questions aside I liked the way that management responded by saying that they had the flexibility to deal with differing situations and that they are still capable of large volume increases given their investment in new manufacturing lines (some still to be started up), their shift patterns and their newly engaged production management.
Note she said there was little seasonality (?)
I hold and will probably increase when SP recedes a bit. A worry is the large spread and lack of FY forecasts (maybe 4p). At current SP PE looks under 10 with a PEG as low as ......
As always DYOR
Steve
I sold my Eckoh a month or two ago specifically because the adoption of IFRS15 (wasn't it?) was going to have a very negative affect on published revenues and profits in the s-t. This was clearly signalled by the company in the most recent annual report. In the event I thought, after a quick look, that the impact seemed less than I had expected, implying to me that the underlying business was actually rather good. It will take a year or two for the earnings pattern to stabilise but I do think this is worth keeping in mind as a potential winner.
As for Bonmarche, another one I held some time ago, I have a slight inside track - one of my acquaintances works there. She is of the opinion that the retail software they are using is neanderthal and as a one time visitor to a store I was not much impressed by the ranges and displays though they are pretty cheap.
I just think Sosandar is much too expensive and speculative so haven't bought despite some friends urging me so to do. I suppose I wish I had done so but it really is against all the rules of smart investing, isn't it? More than one way to skin a cat but surely couldn't be a major portfolio holding candidate.
DAK why Sosander's admin expenses more than doubled? I couldn't find an explanation in the report - more employees perhaps?
I don't quite understand why nobody has mentioned the return rate of 50%+, it's normal or is Sosandar (LON:SOS) an exception to the rule perhaps ?
I've seen figures between 20% and 40% quoted for returns of fashion items ordered online so 50% does seem high at Sosandar (LON:SOS). But they are selling only to ladies and they return a higher percentage than the gents.
I've heard Carol Kane at Boohoo describe it in terms of the customer's bedroom being their equivalent of the instore changing room. You wouldn't expect people to buy everything they try on in a shop.
The business model has to work if the customer orders four items, keeps two, and returns two. The returns process has to be pain free so they are happy to order again. And the reverse logistics process for handling the returns is as important as the outbound shipping.
Further to note 40 and from the Sosandar (LON:SOS) interim results themselves :
"Returns levels have increased during the period (my insert: from 44% to 52%) for two principal reasons: higher than anticipated levels of customer acquisition, as new customers find their correct fit; and a particularly high demand for dresses during the Spring/Summer period. Dresses have higher return rates due to a more complex body fit. Management expects the returns rate will be lower at the full year, reflecting the different product mix in Autumn/Winter."
Good test to see if Mgt do understand their business!
My question to accountants is: how are returns handled in the accounts? Is the revenue reversed out of the topline if 3 dresses are shipped but only 1 retained and where does the re-sorting cost get charged - is this a below the Gross Profit in Admin expenses?
Ths Sosandar Annual Report http://www.sosandar-ir.com/arc... reveals how they account for revenue. From page 48:
"Revenue represents net invoiced sales of goods including posting and packing receipts, excluding value added tax. Revenue from the sale is recognised when the company has transferred the goods to the buyer on dispatch from the warehouse, less actual returns and provision for expected returns."
So the reported revenue number is net of returns.
I'd guess that they need to make a "provision for expected returns" for sales made at period ends.
Regret to say the accounts of Sosandar look very unimpressive to me. It's easy to grow a business in revenue terms if you spend enough, and with large negative profits and cash flow that's what it looks like. But there is no point in revenue growth unless it is profitable sooner or later. It will certainly be interesting to get Graham's view.
But having held both ECK and SRT in the past I totally agree with Paul's comments. Jam tomorrow in both cases.
Re Sosandar.
Roger,
I think Sosandar’s business model is certainly scaleable though and the increase in costs looks measured. I don’t think it would make sense for them to try and target breakeven too early. Having said that though they don’t want to forever delay profits and I appreciate there’s a lot of uncertainty over the level to which they can scale, especially given an increasingly competitive online market.
Regards
Andrew
This maybe a technical question or I'm loosing the plot - Sosandar (LON:SOS) has only been trading for a couple of years but the stockopedia chart starts back in 2006.. is this a glitch in the system?
Almost certainly a reverse takeover then ... and a quick Google confirms this - AIM cash shell Orogen acquired Thread 35 in 2017, who were Sosander's parent at the time.
timarr
Hi Paul, appreciate all the hours you put into these reports and appreciate the Sosandar commentary, I hold. Like you, I’m impressed with what they’ve done to date and believe the business model is very scaleable so I want to stay with them and see what they can do.
I wondered if you would be interested in perhaps holding and recording a call with management after the full year results and perhaps putting a few reader questions to them as well? I’d find that really valuable.
Thanks,
Andrew
Hi Andrew,
I wondered if you would be interested in perhaps holding and recording a call with management after the full year results and perhaps putting a few reader questions to them as well? I’d find that really valuable.
It's funny you should mention that (re Sosandar (LON:SOS) ) as I've had that exact conversation with the company today. They like the idea, and hopefully I'll be able to publish an audio interview with SOS management before Xmas.
As usual, I'll do it for free (so am not conflicted), and will crowd-source the questions from you, the readers here, in due course. Don't send questions to me yet though, but by all means start thinking about what you'd like me to ask them.
Regards, Paul.
Re Sosandar, chat with management.
Thanks Paul, that would be superb. I’ll put my thinking cap on in readiness.
You’re extremely helpful to us all!
Best wishes,
Andrew
Just further on Sosandar, they’re also getting very decent gross margin on their sales so they’re not flogging clothes dirt cheap to build the revenue line. I think that level of gross margin is encouraging and suggests that they have product that is desireable at a fair price. They may take lower margin to go wider in the future but I think their reported gross margin is encouraging.
I think the speed at which they have grown and the publicity traction they’re getting as well as qualitative things like the management of their Instagram site and the quality of the photography of the clothes and models marks them out for me as having very good potential. I also think the CEOs’ background is very good for building a digital business.
Regards
Andrew
Thumbs up from me for the interview with Sosandar (LON:SOS) management Paul.
Regards.
Hi Paul. I would be interested on your views of the latest developments with Flybe (LON:FLYB) and their sale and leaseback of hangar at Exeter airport and the release of funds secured against an aircraft. Cheers
I've covered Flybe (LON:FLYB) in the past so I'll weigh in here.
Flybe (LON:FLYB) are in very serious trouble. With current liabilities exceeding current assets at 30th September, weaker than expected winter trading and December/January being the seasonal low for cash balances, if they hadn't done anything they were bust IMO. The credit card acquirers seeing the risk and demanding more collateral doesn't help of course.
By handing back the excess planes and rationalisation routes the company is finally starting to get the sort of load factors that they need to. However the cost saving per seat are only really starting to come in, and is too little too late. If they did this 2 years ago they would have the balance sheet strength to trade through current weakness. The lack of management grip on costs is a major failing here IMO.
The aircraft funding is mildly positive for the company though. Primarily because someone was willing to lend 80% of the value of a Q400. It shows that the value of the aircraft on the balance sheet isn't totally crazy, and it is the discount to NTAV that will attract any acquirer.
With £286.8m aircraft assets & £152.7m combined long-term and short term debt at 30th September, if they could borrow up to 80% then that would move £77m from short-term to long-term debt and their short-term outlook would look a lot better. It really depends on what existing lending covenants are to see if they can actually access further long-term debt form this source. £5m for a hangar and $5m is unlikely to cut it though so they need something else to survive IMO.
Although the aircraft funding deal is positive both from the ability to still access long-term debt and the read through to aircraft asset valuation, this is very much a punt not an investment at the moment given the risk of a total loss.
One thing that is interesting for those who do like a flutter though is that last time I looked IG were still offering controlled risk spread bets on Flybe (LON:FLYB) !
HTH.
Virgin interested in Flybe (LON:FLYB) according to Sky News:
https://news.sky.com/story/virgin-atlantic-in-surprise-bid-to-take-off-with-flybe-11560548
Still no firm offer form anyone but having multiple bidders is key to getting any real premium so would seem to be a mildly positive development.
I have owned Creightons shares for several years and am pleased to continue doing so. After having looked at their H1 reports webinar, I remain impressed by the directors' optimistic tone. Incidentally, if you had watched these webinars you would perhaps not have been so surprised by last year's profit warning, as the pressures resulting from sales growth were flagged up beforehand. In this regard, the bottom line increases just announced can be seen in part as playing catch up after the margin decline that resulted last year by temporary outsourcing of manufacturing when demand exceeded capacity.
The company's aspirations by which they have invited us to measure them include the following by 31 March 2021 (end of 2020-21 year):
It was expressly stated that the intention is to achieve these goals by organic growth (no acquisition). Some of the positives I have taken from the webinar are:
As a shareholder, continued performance at these levels will certainly take care of my wishes. We shall see. I am sure that the webinar will appear soon on www.piworld.co.uk
Repeat of my ADVFN post:
Hi Paul,
FWIW
I spent half a day with a friend and target customer of SOS, who she wasn't aware of. We looked through their catalogue and compared SOS with five competitors.
She was impressed and her main queries were about quality - she is a big spender.
To me the smaller outfits (should've made notes!) didn't look in any position to compete.
We also looked in some detail at the social media sites, and again SOS was very impressive.
I also found, on a social media site, the view (from a customer) that SOS had moved upmarket in the last year.
I also note that with SOS a customer 'enters' a brand - not a shop where one chooses between brands.
This powerful point seemed to have evaded the tintin,s until Carol Kane confirmed it at a recent BOO presentation.
Thanks for your analysis.
apad
My problem with Creightons (LON:CRL) is that revenue seems to be a bit lumpy and unpredictable - I don't know if there's a good reason for this or not? This puts me off investing because it's difficult to have much visibility about the future. For example, previous results to today showed:
H1 16/17
16/17
H1 17/18
17/18
Rev % inc
45.1%
45.7%
7%
13.8%
WH Ireland upgrade Judges Scientific (LON:JDG) full year adjusted profit to £13.4 million. The vast majority of adjustments pertain to amortisation of intangible assets arising from acquisition which seems perfectly reasonable (hence Judges excellent record of converting adjusted profits into cash). Judges will have also moved into a net cash position by the end of the year, with £35 million in undrawn bank facilities available to make acquisitions. IMO a fantastic buying opportunity that is well insulated from any Brexit worries, as a weak pound increases its competitiveness in its global markets
Thanks for the review of Imimobile IMImobile (LON:IMO) Paul. Not sure where you get your P/E ratio from though!
Whitman Howard as of yesterday forecast 17.3p EPS this year, rising to 21.5p EPS next year. At 276p that's a P/E of only 15.9 falling to 12.8 - not bad for a business showing 40% adjusted PAT growth.
IMO have confirmed that they expect full year results to be in line with expectations.
I also note that the 3rd July acquisition of Impact Mobile is expected to be "immediately significantly earnings enhancing".
And there's been another acquisition this week which wasn't formally announced on RNS - IMO paid $1.5m for "the trade and assets of Express Pigeon, a US-based email marketing platform provider".
I too have met the management and been equally impressed.
I think we all understand the potential biases that we have regarding commenting on shares. At least Sosandar (LON:SOS) appear to be hitting some and possibly all of its targets, so that provides momentum for a positive commentary, though actual valuation multiples is always a matter of personal taste it seems.
The only worrying signs is despite when a share punches you on the nose, like abuse, its not always right to accommodate its right to abuse you, by making excuses for it. That's a potential sign of the Stockholm syndrome, or anchoring or whatever.
I personally value Paul's insight highly, but being a weak individual I panicked and sold my Sosandar (LON:SOS) during the brief market meltdown and made a profit, thanks entirely to him, not my own deeply buried genius. So, obviously like all grown ups, we have to accept our own part in accepting or rejecting a narrative at the end of the day.
Just a quick response to Paul's comments on Eckoh (LON:ECK) from yesterday. I don't dispute the contention that the valuation of Eckoh is a bit rich at present but it is a little simplistic to say that revenues are down and H1 numbers disappointing. The new business wins here are impressive, with new business in this half year almost exceeding the whole of last year. IFRS 15 prevents revenues being recognised yet on these contracts but numbers going forward are well underpinned.
Eckoh has net cash and a large US opportunity. One to keep an eye on if further contracts emerge of similar scale to recent deals.
sparkler,
it is a little simplistic to say that revenues are down and H1 numbers disappointing. The new business wins here are impressive
I think you'll find that's exactly what I wrote about Eckoh (LON:ECK) ! That H1 figures are poor (a statement of fact), but that the valuation rests on the positive outlook & contract wins.
Surely we're in agreement then?
Regards, Paul.
I think my point is that the revenue growth is actually occurring now with signed contracts (as opposed to a 'pipeline of prospects'), but you won't see that reflected in numbers until year 2 or 3. The business trades on an EV/Sales multiple of about 3x which is in line with mid/high growth software stocks. If you believe the US opportunity will come through (and recent contract wins are supportive) then Eckoh (LON:ECK) is reasonable value.
I've got a speculative position in Sosandar, but I do wonder about the long-term viability of it all. Looking at the figures, I do agree with Paul that £10m+ might be around the figures where break-even comes. At what point would they need to upgrade their logistics?
Their USP appears to be that the two co-CEO's have some kind of unique take on the womens fashion market, using their knowledge to bring pieces to market that are appreciated. Fine, but can this be maintained, and why can't other firms replicate it? After all, there are probably millions of 50+ women who have bought clothes.
Looking at the stuff that sells out, I do wonder if there is a risk of confusing quality for mass-market appeal. For instance, they are leaning towards celebrities. Someone like Darcy Bussell could wear a bin liner and it would end up selling out on whichever website chose to sell it.
I would like to enquire with Paul about intellectual property in this area. We saw Next settle with Scamp and Dude, but Sosandar designs seem rather less distinctive....if SOS end up becoming really popular what would stop the same happening?
"At what point would they need to upgrade their logistics?"
Sosandar is an asset-light platform company.
It neither manufactures nor distributes the clothes it retails.
So large infrastructure investments appear unlikely.
Your comments on M&S are interesting & do not surprise me at all.
I'm just past 50 and should be an M&S target customer, but absolutely none of their casual wear is suitable (even for a less demanding male customer).
Many apparel retailers make obvious errors such as designing pockets which are simply not long enough to accommodate a modern mobile phone. So a sale is lost for about 2 pence worth of fabric.
Absolutely none of them do trousers with 3 pockets on the front, for wallet, phone and keys.
Finally even high flying growth retailers can make dumb errors. Take Uniqlo (Fast Retail, Japan). For almost all of this year, they have had their main jeans line in 34" inside leg and nothing else. Maybe having jeans that are too long is fashionable, but they simply exclude the more practical customers with such stupidity.
The above examples are just common sense. If retailers cannot get that right, how can they get the more difficult fashion element right ? No wonder old apparel retailers tend to die.
There is a long list of them and there is zero chance of me purchasing M&S shares any time in the near future.
As for the better candidates, I suppose the trick is to figure out how to decide when retailers move from the H&M growth bucket to the C&A bucket.
Incidentally, I presume google would be selling data about footfall in stores to the major fund managers and presumably also selling data about search results & clicks as well. So for anything other than the small caps, we may be at a disadvantage.
Very happy to have Graham's view as well but would hate to see Paul tone down his enthusiasm on shares he is really keen on and/or has large investments in. That's one of his big plus points. He says it whether( good or bad) exactly as he sees it. A lot of people have benefited., me included, when Paul has been very enthusiastic about a Company (e.g BOO from 35p). And we can all check out figures etc for ourselves from Stockopedia.
I'm not keen on the idea of the one not holding a large stake being the only one who should comment. What if Paul or Graham is far less clued up on that share and has not followed closely? It makes no sense, be it Graham or Paul to be put int that situation. It would mean a lot of unnecessary research work for the less clued up of the two. And inferior information for all of us.
Hi Paul
As you are “in deep” on Sosandar (LON:SOS), would it be an idea to get Graham N’s thoughts on it additionally or instead?
I’m sure that you and Graham do your level best to stay objective when commenting on the stocks that you are investing in. However, when the holding is relatively large we all have a tendency to subconscious bias I would think. So, as a matter of principle, might it be better whenever you have this situation for both of you to provide comment, or if not possible for both to comment, just the one without the large personal stake?
Hmm I can see your point, however I wouldn't want to lose Paul's view. Some of my best trades have come from Paul's conviction ideas Avseco & Boohoo for instance. You would also loose the deep dive he is doing - Graham wouldn't be looking at their website daily.
Hi Graham,
Re: Sosandar (LON:SOS)
Graham Neary has already made his thoughts known on the 10th October SCVR
Paul on the other hand is a retail fashion expert and knows this business intimately. So whilst I value both their opinions, whatever biases they might have, in this instance I doubt Graham would add very much to what he has already said.
cheers
Francis
Hi GrahamFord,
Our Graham (Neary) has complete freedom to write whatever he likes about any share, as indeed do I.
So if you'd like Graham Neary to comment on Sosandar (LON:SOS) for a (probably) less enthusiastic opinion than mine, then feel free to ask him - he's writing tomorrow & Friday's reports! :-) I'll message him now to ask if he'd give a view on it at some point.
I'm happy to listen to all views. Although I won't be toning down my own opinions here - if I think a company has fantastic potential (as I do with SOS) then I'll shout it from the rooftops! Equally, if something looks terrible, I'll shout that from the rooftops too! That's what's different about these reports - no sanitised views, just honest opinions from writers with a track record of getting more right than we get wrong.
Regards, Paul.
Paul
I haven’t asked you to change what you write, so I am at a loss to understand why you reply as if I had.
GrahamFord,
I was just doing a catch-all reply to the discussion, in which your reply was one.
No harm done, it's not a problem. I'm relaxed about everyone airing their views here.
Regards, Paul.
Creightons (LON:CRL) 's cashflow looks very concerning to me. They seem to have particularly bad working capital dynamics and it is unclear to what extent the investment in plant is typical. I don't understand why they are paying a dividend - on the face of it they need to issue more shares if they are continue growing. On the plus side growth is impressive and operational gearing on their side for the moment. I'm not really sure what to make of them - any thoughts welcome.
Edit: Some figures below :)
PBT: £1,380,000
BUT:
Operating cashflow: (£1,350,000)
Investment cashflow: (£738,000
Creightons (LON:CRL) have/are renewing all the production equipment over a 12 month period. The bottling equipment is done and in full production, the tube filling will be concluded by December. This is increasing capacity by 20-25% and is a one off required because of excessive demand from their customers and increases in their own label sales. I suggest the new gear should last for a decade maybe although always possible may need upgrading again in say five years if technology improves?
Creightons are by far my largest holding being twice the size of my No2 stock.
There is a live webcast at 2pm today available to PI's but you have to contact Tamzin at PI World for a personal login code.
Hi Dave
I am impressed by your conviction holding in Creightons (LON:CRL). I retain a relatively modest holding and added at the time of the profit warning in February and may do so again, once I have re-read today's results. Some interesting and informed comments this morning and as Ramridge notes, Graham Neary is a holder and has previously given a good analysis of the company.
Given your high conviction I would be interested on your thoughts for the future of Creightons (LON:CRL). The most obvious I suppose is that it is eventually acquired. It would I think be a natural fit for Swallowfield (LON:SWL), but I suspect would be too large an acquisition given the relative market caps of the two companies.
All the best
Jonno
Hi Jonno,
I believe Creightons (LON:CRL) has a lot further to go. The new production capacity is far from fully utilsed as the tube facility will only be in production for the final 3 months of FY3/19. They also have ideas to add extra shifts once whole of upgrade completed.
The net margin is improving- they are relinqushing lower profit margin customers; they help design/formulate some customers products so they are not merely a manufacturer to many labels; they are increasing own label and direct sales which provides higher margins;
So I expect they will want to remain independent for at least the next 2-3 years. I am no analyst but I expect the sp to reach 45-50p by YE 3/20 results if not before but please DYOR.
Don't forget live webcast 2pm link code via email toTasmin at PI World.
Cheers, Dave
Hi leoleo73 - re. Creightons (LON:CRL)
Graham gave an excellent analysis of this share at the last FY results here .
He liked what he saw and bought some shares. Graham is a very cautious man. If Graham buys, I sit up and take note. The accounts had a similar profile at that time with respect to cash flows.
Today's HY results are really good. From what I can make out, the forecast eps for the full year is likely to be 3.2p (my number), There is a small bias towards the H1, i.e. H2 eps has been lower historically and I have made an adjustment to come up with 3.2.
So with today's sp 31p, that gives forecast PE of around 10. Taking into account that eps growth at HY is 73%, that looks very enticing.
I took a small stake this morning. I was also influenced by the fact that the sp has been fairly resilient over the last few months, and it has stood up to the market battering reasonably well.
As ever, all IMO and PDYOR
My morning smallcap tweet:
Augean (LON:AUG), HSS Hire (LON:HSS), Judges Scientific (LON:JDG)
Augean (AUG) guides adj pretax materially ahead of market expectation.
HSS Hire Group (HSS) good Q3. Guides FY EBITDA to be marginally ahead of market expectations
Judges Scientific (JDG) guides FY EPS ahead of market expectations as increased in September.
Creightons (LON:CRL) Creightons PLC – Half – year Report
Impressive results reported today.
Revenue increased by 33.5% to £22.3m. (2017: £16.7m)
Profit before tax increased by 44.4% to £1,380,000 (2017:
£956,000)
Operating profit margin of 6.3% (2017 5.8%)
Diluted EPS 1.80p (2017: 1.09p)
Worthy of analysis.
I hold.
Hi mercury61,
Thanks for flagging, those numbers do look interesting from Creightons (LON:CRL)
You have got me interested, I'll take a closer look later today.
I much prefer it when readers give some facts & figures, and why you think results/trading update look interesting, rather than just asking me to do all the work! So many thanks for that.
Regards, Paul.