Stock in Focus: DX (Group) could deliver for investors

Delivery firm DX (Group) has delivered a remarkable double-digit gain for shareholders over the last month. The shares have recovered from August’s market correction and surged to around 90p, a level not seen since February. The big gains started on 23 September, two days after DX published its full-year results.
Small-cap editor Paul Scott described these figures as “quite good” and they’ve prompted a modest broker upgrade for the current year:
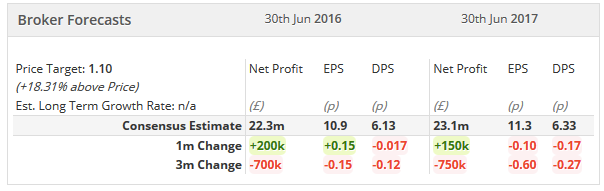
This combination of factors has made DX Group the biggest StockRank riser over the last month. As I write, the firm’s StockRank is 98 -- a whopping 47 points higher than it was 30 days ago.
There’s only one potential problem. Even after their recent gains, DX shares are valued on just 8.5 times rolling forecast earnings and boast a forecast dividend yield of 6.7%. As Paul explained: “There's only one reason stocks are that cheap - because the market doesn't believe profits are sustainable.”
Is this an opportunity?
 DX (Group) offers a mixture of parcel, mail and logistics services, but isn’t simply a direct competitor to mainstream couriers such as Yodel or Parcelforce. Instead, DX offers a range of more specialist delivery services. These include delivering irregular items that are unsuitable for automated handling, 2-man home deliveries, and secure parcel and packet services.
Among the firm’s more interesting customers are the passport office, for whom DX delivers all passports, and a number of banks and credit card companies.
DX also has a legacy business, DX Exchange, whose customers are mainly legal and financial firms which need secure overnight document delivery. This business is being steadily eroded by email, as you’d expect, but remains important to DX.
Focusing on specialist areas of service makes good sense to me, as these presumably attract a slight price premium. Competing with firms such as Yodel and Hermes in a race to the bottom to offer the cheapest home delivery service makes no sense.
Yet as Paul highlighted in his review of last year’s results, DX’s 8.5% operating margin is exceptionally high for a business of this type. How sustainable are these profits? Are slim margins on parcel work being subsidised by fatter margins at the declining DX Exchange business?
DX (Group) doesn’t break down its profits in its results, so investors are left guessing at the answers to these questions.
However, DX’s quality, value and momentum ratios look so attractive to me that I think this stock may be worth a closer look, despite this risk.
Good value?
DX was in private equity hands until February 2014, when it was floated back onto the AIM market. The resulting financial restructuring means that investors don’t have much in the way of comparable figures for historic performance.
However, the pro-forma figures provided at the time of the IPO suggest steady progress over the last few years. This has been aided by the acquisition of former large item delivery specialist Nightfreight in 2012. DX also claims to have acquired more than £10m of annualised business from former City Link customers.
A ValueRank of 95 highlights how attractive DX’s valuation is, if last year’s performance can be sustained. At 91p, DX shares trade on just 10 times free cash flow and on 9.4 times trailing earnings per share.
The trailing dividend yield of 6.5% was covered by free cash flow and earnings last year. One of my favourite metrics, the earnings yield (EBIT/EV), is also strong at 13.5%.
Overall, for traditional value investors who focus on historic performance, DX looks very attractive.
A closer look at QualityRank
DX’s value appeal is complemented by a QualityRank of 86, but this is one of those rare cases where the data input to Stockopedia’s algorithms may be producing a spurious result.
It’s always worth looking at the components of each rank for yourself. (This is easy to do by looking on the sector page for a company, clicking the Ranks tab and then clicking on the individual Rank you are interested in.)
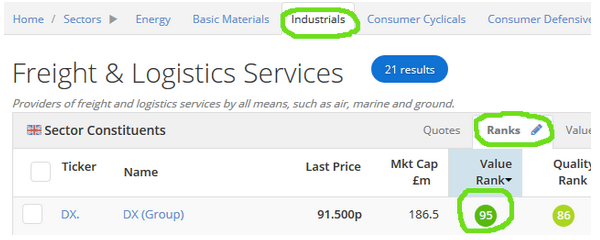
For example, Stockopedia gives DX a five-year average net (post-tax) profit margin of 15.3%. This sounds great until you realise it’s almost impossible. Last year’s operating margin (pre-tax) was just 8.5%.
The problem seems to be that the StockReport shows an operating margin of 118% in 2011, thanks to a net profit of £151m on revenue of £149m:
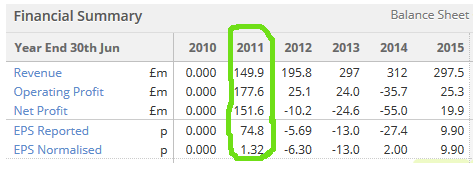
Although there’s a legitimate explanation for this exceptional gain, it doesn’t represent the firm’s underlying performance, so this is worth noting.
Despite this, I’d say that DX does deserve a high QualityRank. The firm’s Piotroski F-Score of 7 is both impressive and a far more realistic indicator of the firm’s financial health and profitability. The F-Score highlights falling debt, strong cash generation and rising profit margins.
Rising momentum
DX shares fell by 37% during the first year after its IPO. Private equity sales tend to be overvalued and perhaps expectations were a little high.
However, the picture is now changing. DX’s MomentumRank has risen sharply over the last month as the shares have surged higher. One factor that may have helped is that one of the firm’s institutional shareholders, River and Mercantile Asset Management, added 2.3m shares to its holding, which is now more than 6%.
Incidentally, it’s worth noting that DX is very strongly backed by institutions. Shareholders holding more than 3% of the firm’s stock account control 80% of the shares in issue. The list of major shareholders includes respected names like Miton and Hargreave Hale and is worth a look.
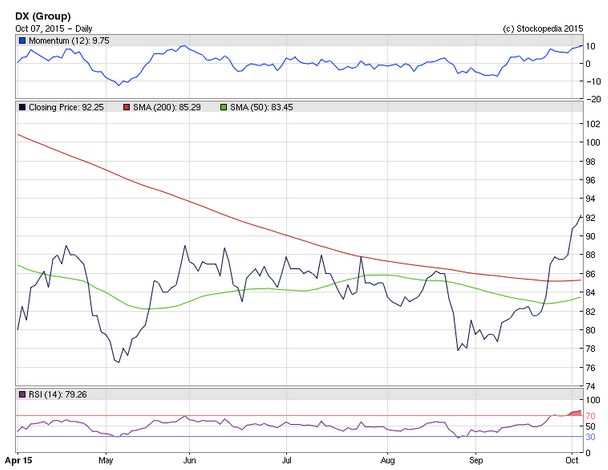
Returning to DX’s momentum credentials, both price and earnings momentum are improving. The shares are now just 13.5% below their 52-week high and the recent results delivered a modest earnings surprise.
Relative strength and chart momentum readings are also encouraging, although it is probably too early to say if the recent gains will convert into a long-term uptrend:
Does DX have potential?
I share Paul Scott’s view that DX’s reluctance to provide a break down of its profits is a concern.
Despite this, I’m a little more optimistic than Paul about the outlook for the firm. I think that DX’s focus on a range of niche areas could help protect profits as the DX Exchange service continues to decline.
On a fundamental level, I’m also impressed by DX’s strong cash generation and generous yield. The firm’s StockRank profile suggests it could be a contrarian play with the potential to become a super stock.
I think that DX is possibly interesting, and could provide attractive returns at its current valuation. That said, as DX is an AIM-listed small-cap stock, careful position sizing and DYOR are even more important than usual.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Dear Roland,
Thanks for this interesting article, which I found very informative and useful. I have held £DX for about a year, buying at around the current price at the end of 2014. I liked the fundamentals but bought mainly as an income stock. What really attracted me to the company was the incredible list of shareholders, which reads like a whos who of fund managers. It looks as though they are exiting 'commercially unattractive contracts' and winning some new customers - hopefully this strategy will result in margins increasing? A big positive is the cash generation and the reduction in debt (from £12.2m in 2014 to £1.8m). There is quite a lot of change going on in the business and they are instigating a 'OneDX integration and development plan'. Despite holding DX (Group) (LON:DX.) my feelings are quite neutral on their prospects - I don't see anything to get me excited and growth looks to be quite slow in a market, which is very competitive and difficult. However I do like the cash generation and the income that this stock generates. I'd be happy with a 6% yield and 2-5% capital growth per year!
I would really like to hear what other people think about DX (Group) (LON:DX.)