Stock in Focus: Is Norcros about to turn on the taps?

Value and momentum are usually seen as opposite investing disciplines. In theory, a screen focusing on strong value and momentum should highlight cheap stocks with the potential for big gains.I’ve selected shower and bathroom fitting supplier Norcros in order to try and test this hypothesis.
This company has as Value-Momentum Rank (VM Rank) of 98. This suggests that it combines the characteristics of a value buy with those of an upwardly-mobile momentum stock.This combination of value and momentum is also the classic profile of a turnaround that’s starting to come good.
Stockopedia’s computers like Norcros, giving it a StockRank of 96. Norcros is also a Paul Scott favourite and has cropped up on my own value screens more than once.
Late to the party?
Housing stocks and related businesses such as Epwin have put in strong performances over the last few years. It’s not immediately obvious why Norcros has lagged behind.
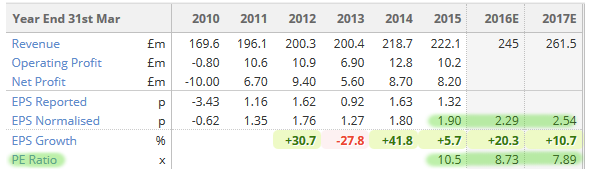
2015 wasn’t a great year, but forecasts for 2016/17 are strong and the shares look cheap.
One possibility might be that demand for the firm’s products lags house sales, as people tend to do up homes after they’ve moved. That doesn’t explain the apparent lack of demand growth from housebuilders, though.
Another possibility could simply be that Norcros doesn’t have the right products. The firm reported sluggish UK trading in its Q1 update and UK sales for the year to 31 March 2015 were flat on the previous year.
I specify UK sales because Norcros also has a South African business, which accounts for around a third of sales and about 20% of operating profit. Norcros appears to be doing better in South Africa. Last year saw sales rise by 3% and underlying operating profit rise by a whopping 68%.
However, the bottom line is that Norcros currently expects to meet market expectations for the full year. These currently suggest that earnings per share could rise by 20% to 2.3p, putting Norcros on a forecast P/E for the current year of just 8.8.
Looking further ahead, the firm’s target is to double revenue to £420m by 2018, using acquisitions to drive growth. Even a partial success here could deliver a big re-rating of the firm’s shares, in my view.
Given that Norcros also has a MomentumRank of 96, I think it’s worth a closer look.
Simple value
Norcros has a solid ValueRank of 76, which suggests few serious concerns.
The shares look reasonably priced, on 10.5 times trailing earnings and 16.5 times free cash flow. An earnings yield of 7.5% isn’t too bad for a mid-market volume manufacturer, and the shares’ 2.8% dividend yield is quite decent for a small cap.
Norcros has no obvious value weaknesses other than a fairly high price-to-book ratio of 2.3 and a price-to-tangible book ratio of 4.7.
This firm clearly isn’t an asset play, although mid-market brands such as Triton Showers have reasonable brand recognition.
Quality ok
Norcros products are fairly mid-range, based on my limited experience, and so is the group’s financial performance.
Last year’s return on capital (ROCE) of 8.5% was down from 10.3% in 2014, but slightly ahead of the long-run average of 6.9%. Similarly, the firm’s operating margin of 4.6% is decidedly ordinary.
However, management have taken steps to strengthen the balance sheet and improve geographic focus over the last year. A series of disposals and property sales generated cash proceeds of £10.3m. This enabled the group to reduce net debt by 48% to just £14.2m.
These disposals were paired with a solid operating performance and give Norcros a Piotroski F-score of 6 (out of a possible 9). No serious concerns are highlighted, and a QualityRank in the mid-60s seems appropriate.
Norcros’s balance sheet appears strong enough to support acquisition-led growth. The group also took advantage of low interest rates to arrange a new £70m borrowing facility.
The only possible caveat that the firm’s £35m pension deficit doubled last year. If this trend continues, the scheme’s trustees might demand additional payments.
Momentum: it’s happening!
This is where the magic is starting to happen -- at least that’s the theory. A Momentum Rank of 96 indicates strong price and earnings momentum:
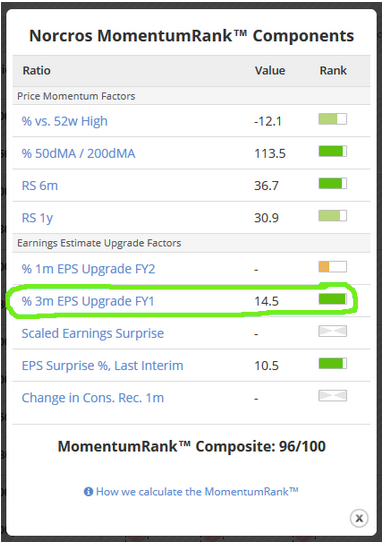
Norcros stock currently trades on a rolling 2-year forecast P/E of just 8.3. The share price doesn’t seem to have kept up with recent earnings upgrades. 2016/17 forecast earnings per share have risen by nearly 15% over the last three months.
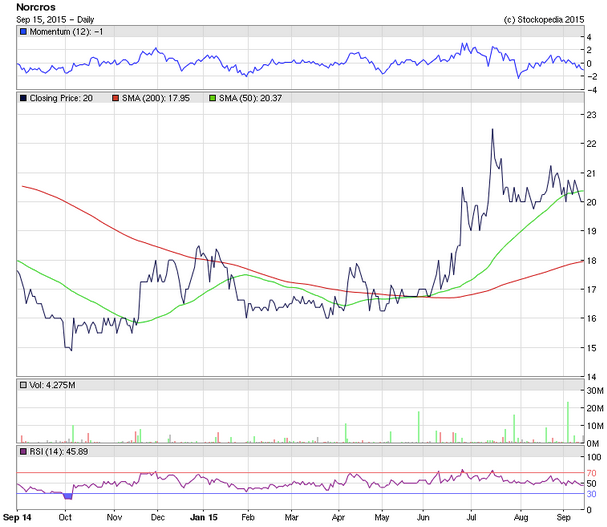
Norcros shares appear to have formed a strong base at around 16p earlier this year, and have since formed a new uptrend with a 52-week high in July. Although price momentum seems to have stalled recently, it’s worth noting that average volumes seem to have increased over the summer.
A relative strength index (RSI) in the mid-40s and a price close to the 52-week high suggests to me that we could be seeing a period of consolidation, ahead of further gains.
If this momentum continues and is backed by a strong set of interim results in November, it’s not hard to see the shares rising.
Outlook
Norcros’s modest valuation, cash-backed yield and low gearing should provide a good margin of safety if growth is slower than expected. Arguably, the shares are priced for minimal growth at the moment.
On the upside, if Norcros delivers forecast growth this year I suspect market sentiment will improve. A substantial re-rating could be possible.
There are risks, of course. Although Norcros does have a decent record of integrating acquisitions, aiming to double sales in three years through acquisitions is a demanding target. Some might say that it’s risky, and may encourage management to make poor choices.
I’m willing to give chief executive Nick Kelsall the benefit of the doubt until proven wrong. Norcros has solid institutional backing, and Mr Kelsall owns almost 8m shares himself, in addition to unvested options.
However, please DYOR as always -- and feel free to share your view on this interesting stock in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
Hi Roland, another very interesting article, thank you!
As a general question - how do you access the Rank Components? I've seen you use these a few times but am struggling to figure out how to get to them? E.g. in your article the "MomentumRank Components" for Norcros.
Thanks in advance,
James
Hi James, thanks very much for your feedback.
Accessing the rank components is easy if you know where to look! The simplest way is this:
1. Go to the sector page for the company, by clicking on the sector name at the top left of the Stock Report screen.
2. Click on the 'Ranks' tab.
3. You'll see the ranks listed for each company in that sector. To see the breakdown of the rank components, just click on any of the rank numbers.
You're probably thinking that it would be great if you could click on the rank numbers in the StockReport to access this information. I agree -- hopefully this feature will be added soon!
Regards, Roland
I see the 1 for 10 Consolidation occurred today - for a moment I thought I was a millionaire :)
I'm long. I like the products. The market is likely to grow as people have more free cash. There's good brand recognition and the shares are cheap and pay a decent divi.
What makes you think people are going to have more free cash? I see the opposite. Rising interest rates, fuel costs that can only go north, and a prospective return of inflation don't bode well for this stock. After all, if it produces a fairly lacklustre performance now when it's had a fairly generous environment to grow, why should it get any better in the future when conditions are worse?
I found the research interesting and useful for future investigation.
Not a bad review of the figures. Although I think we need to distinguish between companies which are getting earnings upgrades because they are making bolt-on acquisitions (as NXR is doing), and companies which are getting upgrades based on strong organic growth - there's two very different things, and have dramatically different consequences for valuation.
So whilst I agree NXR is cheap (it's one I've held since about 10p), we shouldn't get too carried away with growth fuelled with debt. That said, the acquisitions so far have been good - reasonably-priced, good quality companies. There might be some synergies too.
Numis reckons the shares are worth 30p, and that looks a sensible price target to me. It could re-rate very suddenly in my view, as I think there's been a long-term selling overhang in the market, suppressing the price. The good thing is that the seller stops at 16p, as you pointed out, so the downside is about 3.5p from here, and the upside is about 10.5p, so to my mind that is a positive risk:reward play. We get paid divis whilst we wait too.
Regards, Paul.
Paul,
Thanks for your comments.
I agree about organic vs. acquisition-led growth. As I mentioned, my concern is that while the firm has been decently successful at acquiring growth in the past, setting an explicit target of doubling revenue could incentivize management to take too much risk in this area.
We'll have to see -- at the moment it seems reasonable to give the board the benefit of the doubt.
Regards, Roland